

Key Highlights
- The Now Fund provides liquidity for the first 1-3 years of retirement, covering essential expenses without needing to liquidate investments during downturns.
- Average yearly retirement expenses for households led by individuals aged 65 and older are approximately $61,432, emphasising the need for cash reserves.
- The Soon Fund helps families manage expected costs in the next 3-10 years, using fixed-income investments for stability and growth.
- Families face an average cost of raising a child of about $303,418, with education expenses being a significant portion.
- The Later Bucket focuses on long-term growth through equities, helping families prepare for future educational costs and financial goals.
- 529 college savings plans have seen total assets reach $525.1 billion, reflecting a growing trend in tax-advantaged education savings.
- The 3 bucket strategy allows for flexible withdrawals, helping families adapt to market conditions and maintain their lifestyle.
- Effective asset allocation across the three buckets ensures families balance immediate needs with long-term goals.
- The strategy reduces financial anxiety by providing a clear method for managing retirement income and expenses.
- Integrating the bucket strategy with comprehensive financial planning enhances overall financial security and aligns investments with family goals.
Introduction
Imagine feeling free from financial worries, allowing your family to cherish every moment together. The 3 Bucket Retirement Income Strategy provides a structured approach to managing retirement funds, ensuring immediate needs are met while also planning for future expenses. Many families feel overwhelmed and anxious, unsure of how to secure their future amidst the complexities of retirement planning and market volatility. How can they navigate these challenges to secure a stable financial future? In this article, we’ll explore ten key benefits of the 3 Bucket Strategy, showing how it can help families find peace of mind and thrive in retirement.
Ensure Immediate Financial Security with the Now Bucket
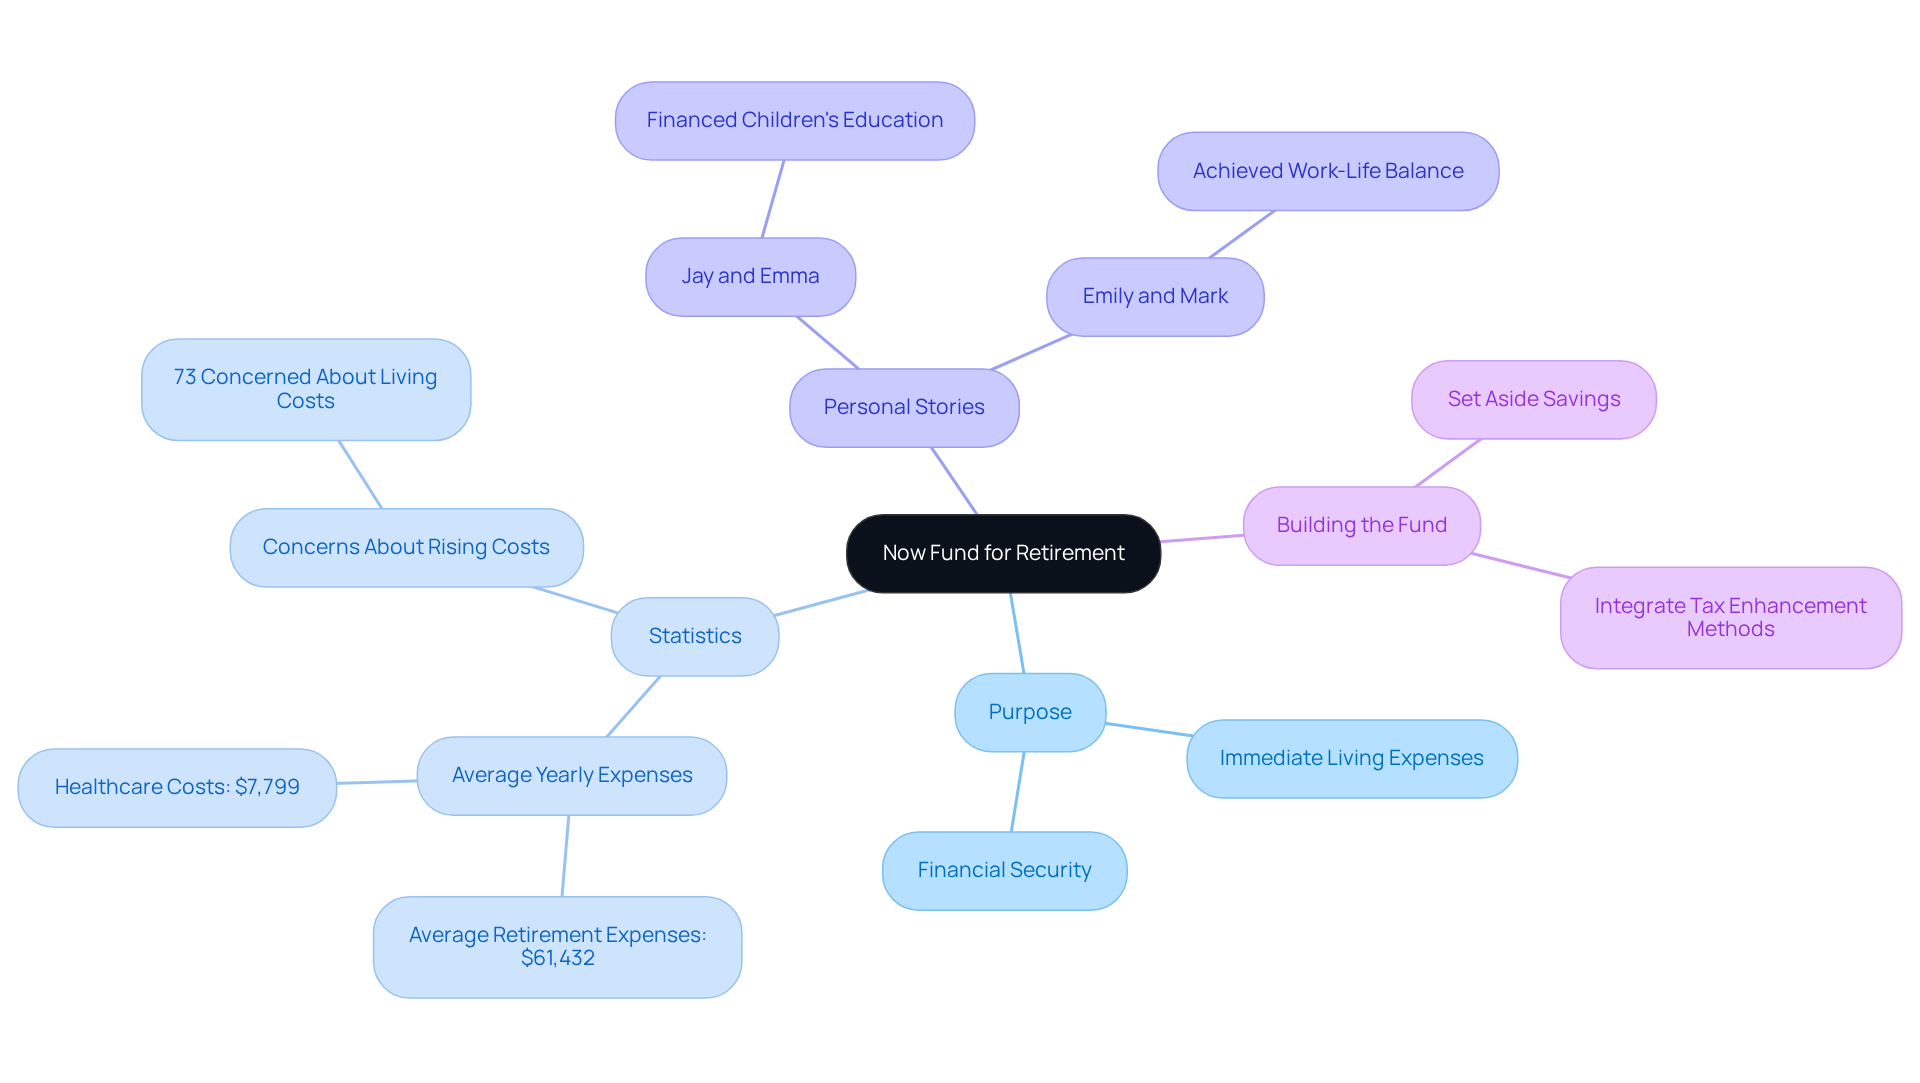
Imagine stepping into retirement with the peace of mind that your immediate living expenses are covered, allowing you to focus on what truly matters – your family. The Now Fund is designed to help you manage those crucial first 1-3 years of retirement, filled with cash or cash equivalents for quick access. This way, you won’t have to worry about liquidating investments during market downturns. For households, having this liquidity is vital for handling daily expenses like mortgage payments, groceries, and healthcare costs, easing financial pressure and letting you enjoy this new chapter of life.
Many families, just like yours, often find it tough to keep enough cash reserves for a comfortable retirement. Current statistics show that the average yearly retirement expenses for households led by individuals aged 65 and older is around $61,432. This highlights just how important it is to have a fund that can effectively manage these costs. Plus, with 73% of individuals concerned that rising living costs could impact their retirement plans, the need for immediate financial security strategies becomes even clearer.
Consider the stories of retirees who’ve embraced the Now Fund; they’ve found themselves better equipped to handle unexpected expenses, like healthcare costs that can average around $7,799 a year. Take Jay and Emma, for example. With two children, they successfully created their Now Fund with the guidance of Bright Advisers, allowing them to finance their children’s education while preparing for retirement. Similarly, Emily and Mark, both busy professionals, discovered that having a solid Now Plan gave them the freedom to make career decisions based on their desired work-life balance. This approach not only helps households meet their essential needs but also enhances their overall retirement experience.
To start building your Now Fund, think about setting aside a portion of your savings in easily accessible accounts. This way, you’ll be ready for any urgent monetary needs that may arise. Additionally, integrating tax enhancement methods can further boost the effectiveness of your Now approach, helping you make the most of your financial resources. Remember, we’re here for you, and together, we can navigate this journey toward a secure and fulfilling retirement.
Manage Short-Term Expenses with the Soon Bucket
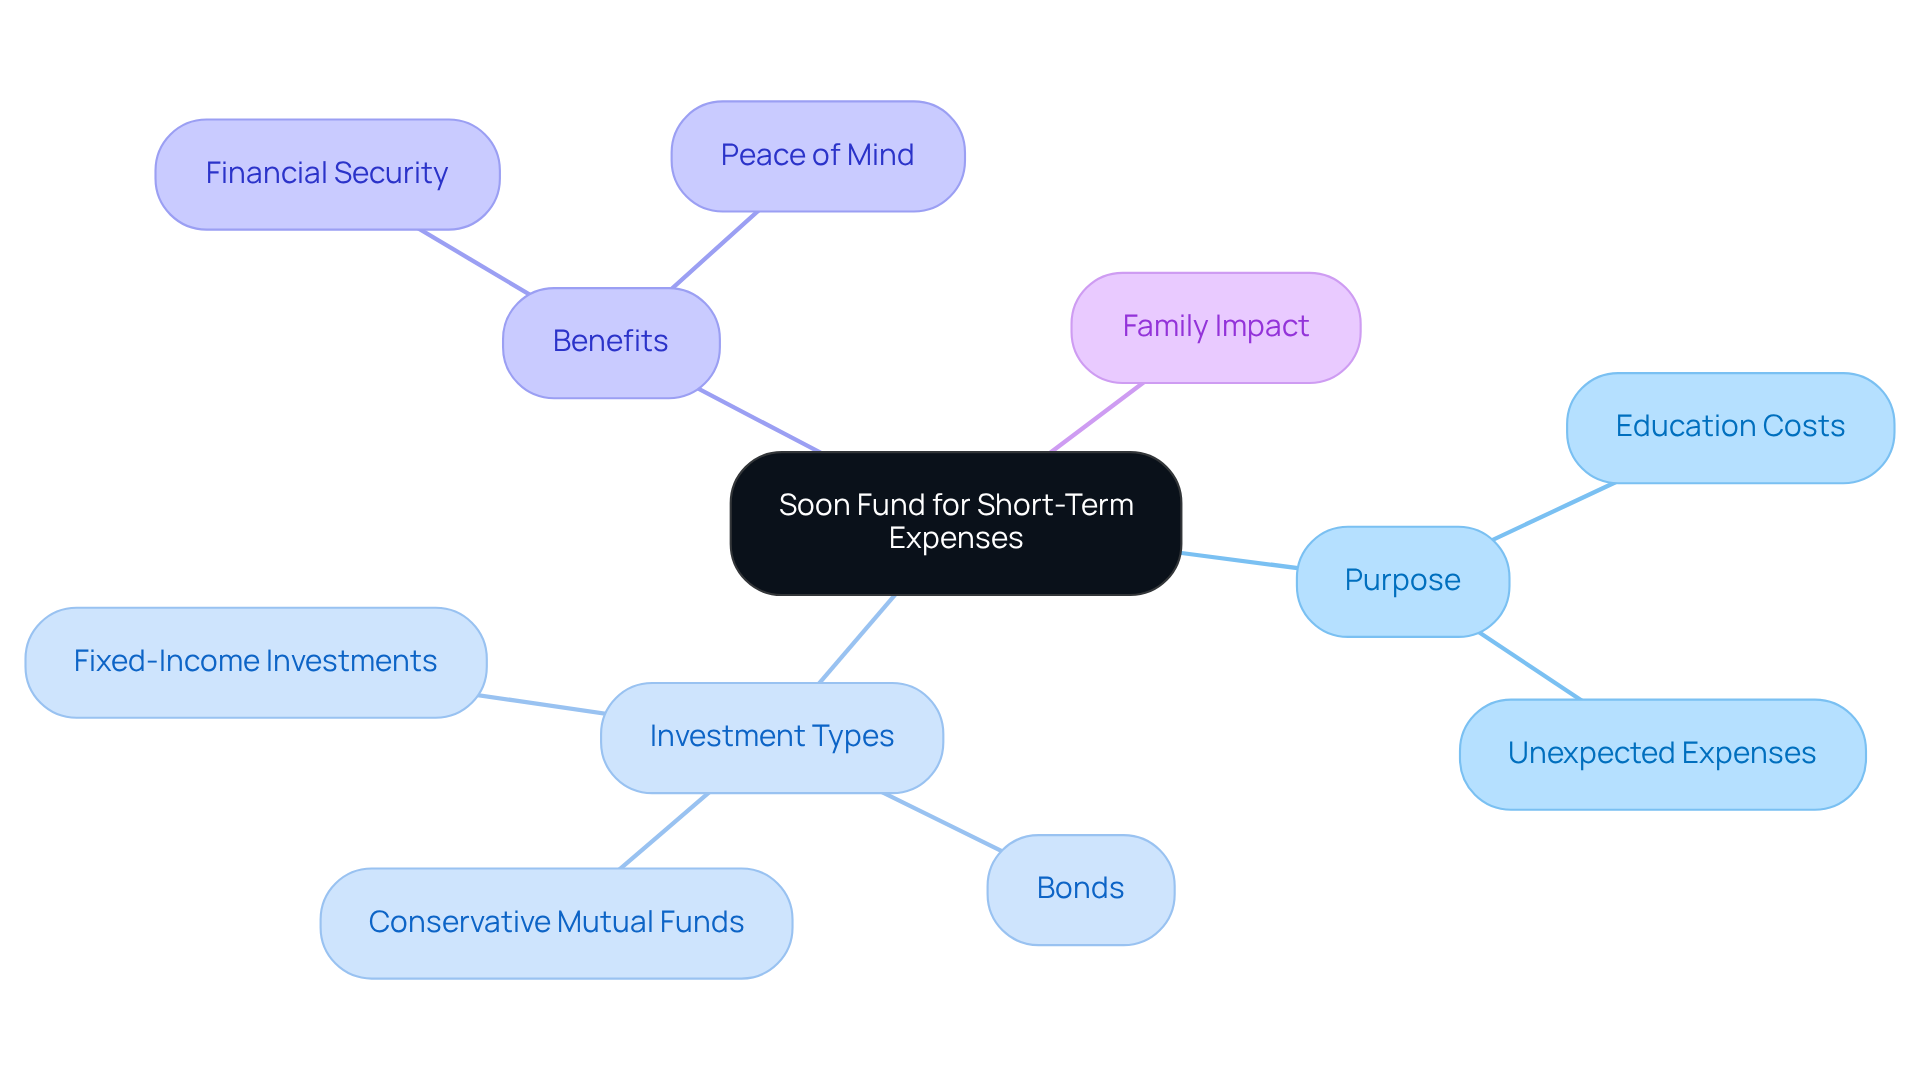
Imagine the relief of knowing you’re prepared for your child’s education and other significant expenses in the coming years. The Soon Fund is here to help you cover those costs expected in the next 3-10 years, making it a vital part of your financial planning. This fund typically includes fixed-income investments, like bonds or conservative mutual funds, which balance growth and stability. By putting resources into the Soon Fund, you can ensure you have what you need to cover these upcoming costs without disrupting your long-term investment strategy.
Think about families who are worried about rising education costs; they can find peace of mind with this approach. The average cost of raising a child over 18 years has reached approximately $303,418, with education expenses being a significant portion of this figure. By strategically allocating resources in the Soon Fund, families can prepare for tuition and related expenses, reducing financial pressure when these costs arise.
Additionally, the Soon Fund can help manage unexpected expenses, like home repairs or medical bills, ensuring that you stay financially secure while pursuing your long-term goals. Bright Advisers’ innovative in-house technology allows for the construction of hyper-personalized portfolios, utilizing strategies like smart beta and factor investing to enhance efficiency and avoid the need for expensive mutual funds and ETFs. This proactive financial planning approach not only addresses immediate needs but also strengthens your overall financial well-being, enabling you to focus on what truly matters – creating cherished memories with your family without the weight of financial stress.
Achieve Long-Term Growth with the Later Bucket
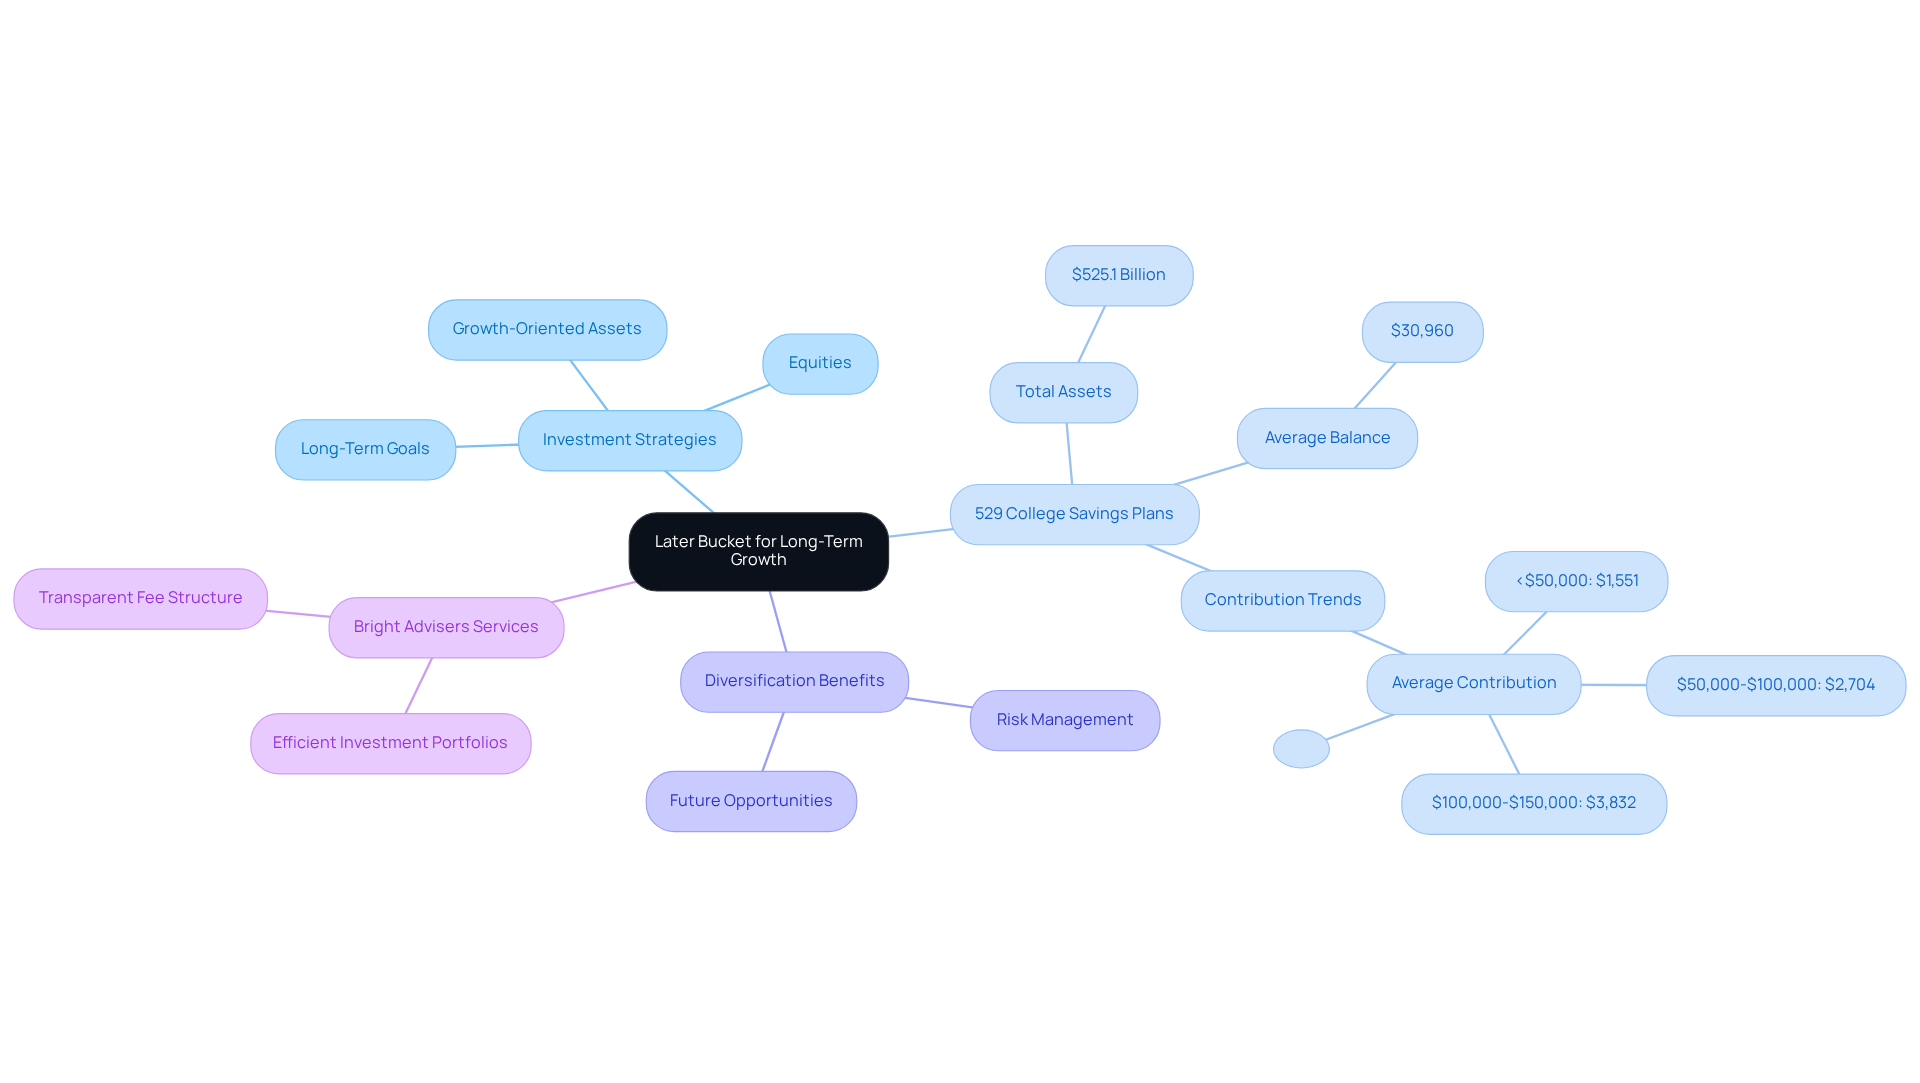
Imagine the peace of mind that comes from knowing your child’s future is secure, even if it feels overwhelming right now. The Later Bucket focuses on long-term growth, investing in equities or other growth-oriented assets. This bucket is all about investing in your child’s future, with funds set aside for at least a decade. By doing this, families can potentially achieve higher returns through market appreciation, paving the way for their children’s education and other long-term financial goals.
More and more families are realizing how crucial 529 college savings plans can be for their children’s education. As of December 2024, total assets in these plans reached an impressive $525.1 billion, with the average balance reported at $30,960. This shows a growing trend in utilizing tax-advantaged savings for education. In 2025, parents of young children contributed an average of $1,551 to college education from savings plans, reflecting a more current perspective on savings trends compared to previous years.
When families choose a diversified investment strategy, they’re not just managing risk; they’re opening doors to future opportunities for their kids. For instance, families using 529 plans can select from various investment strategies, aligning their risk tolerance with their long-term goals. This organized method not only aids their children’s education but also promotes a culture of money management, teaching children the significance of saving and investing from an early age.
Bright Advisers’ innovative in-house technology has made costly mutual funds and ETFs practically outdated, leading to significantly more efficient investment portfolios and greater chances of achieving monetary goals. Plus, Bright Advisers offers a transparent, all-inclusive fee structure with no hidden fees, commissions, or trade fees. This way, families can focus on their financial goals without unexpected costs. By investing wisely today, you’re not just saving for college; you’re building a brighter future for your family.
Enhance Flexibility in Withdrawals with the Bucket Strategy
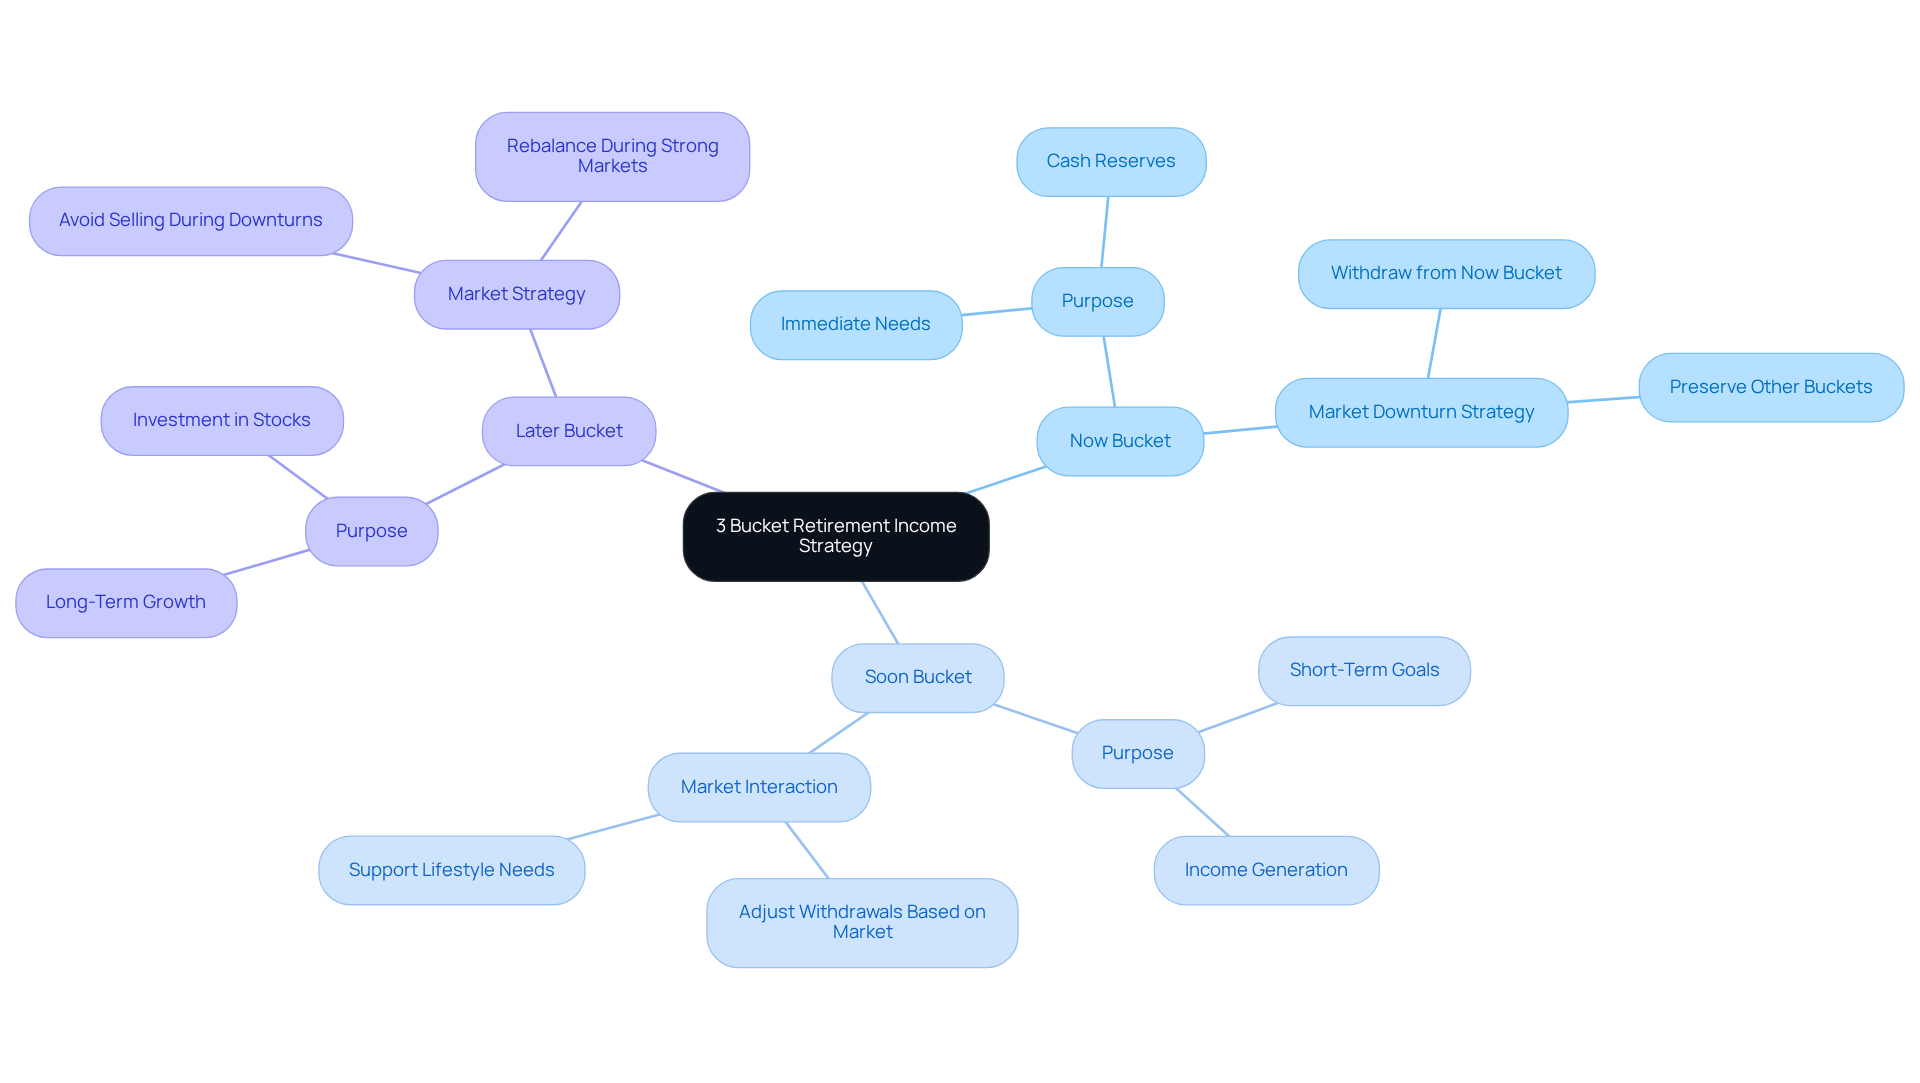
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in uncertain times. One of the main advantages of the 3 bucket retirement income strategy is the flexibility it provides in withdrawals. Families can draw from the Now Bucket during market downturns as part of the 3 bucket retirement income strategy, preserving the value of their investments in the Soon and Later Buckets. This approach lets families adapt their withdrawal plans based on market conditions and their own financial needs, ensuring they can sustain their lifestyle without needing to liquidate investments at a loss.
Many retirees find that adjusting their withdrawal plans during tough times helps them keep their savings intact and their income steady. By utilizing a 3 bucket retirement income strategy, households can navigate monetary uncertainties with greater ease. For example, imagine a retiree with a $1,000,000 portfolio who withdraws $50,000 each year. If they experience a 20% market drop in the first year, a flexible withdrawal approach allows them to make adjustments that improve long-term viability.
This organized method not only reduces the effects of market fluctuations but also empowers families to make informed choices regarding their financial future. With a flexible withdrawal strategy, you can confidently navigate market ups and downs, ensuring your family’s needs are met without sacrificing your investments.
Mitigate Market Volatility Risks with the Bucket Approach
Imagine feeling secure about your family’s financial future, even when the market feels uncertain. The 3 bucket retirement income strategy can help you achieve that peace of mind by organizing your assets based on what you need them for. By allocating your Now Bucket to cash or cash equivalents, you can avoid the stress of selling investments during market downturns, allowing your portfolio to grow over time.
Many families, just like yours, are feeling anxious about the recent ups and downs in the stock market, with a significant number worried about what lies ahead. This strategy, known as the 3 bucket retirement income strategy, not only helps you maintain a steady income flow during market changes but also promotes a sense of economic stability.
It’s essential to remember that maintaining a diversified portfolio – mixing stocks, bonds, and cash – can protect your family’s wealth during downturns. Different asset classes respond differently to market conditions, and this diversity can be your safety net. Regularly assessing your investment approach ensures that you stay aligned with your family’s financial goals, even as the economic landscape shifts.
At Bright Advisers, we focus on creating personalized investment strategies that truly reflect your family’s needs, steering clear of costly mutual funds and ETFs that can complicate your journey. Many families have found comfort in our strategies, like smart beta and factor investing, which help alleviate monetary anxiety while securing their futures.
By taking proactive steps today, you can create a brighter tomorrow for your family, no matter what the market throws your way.
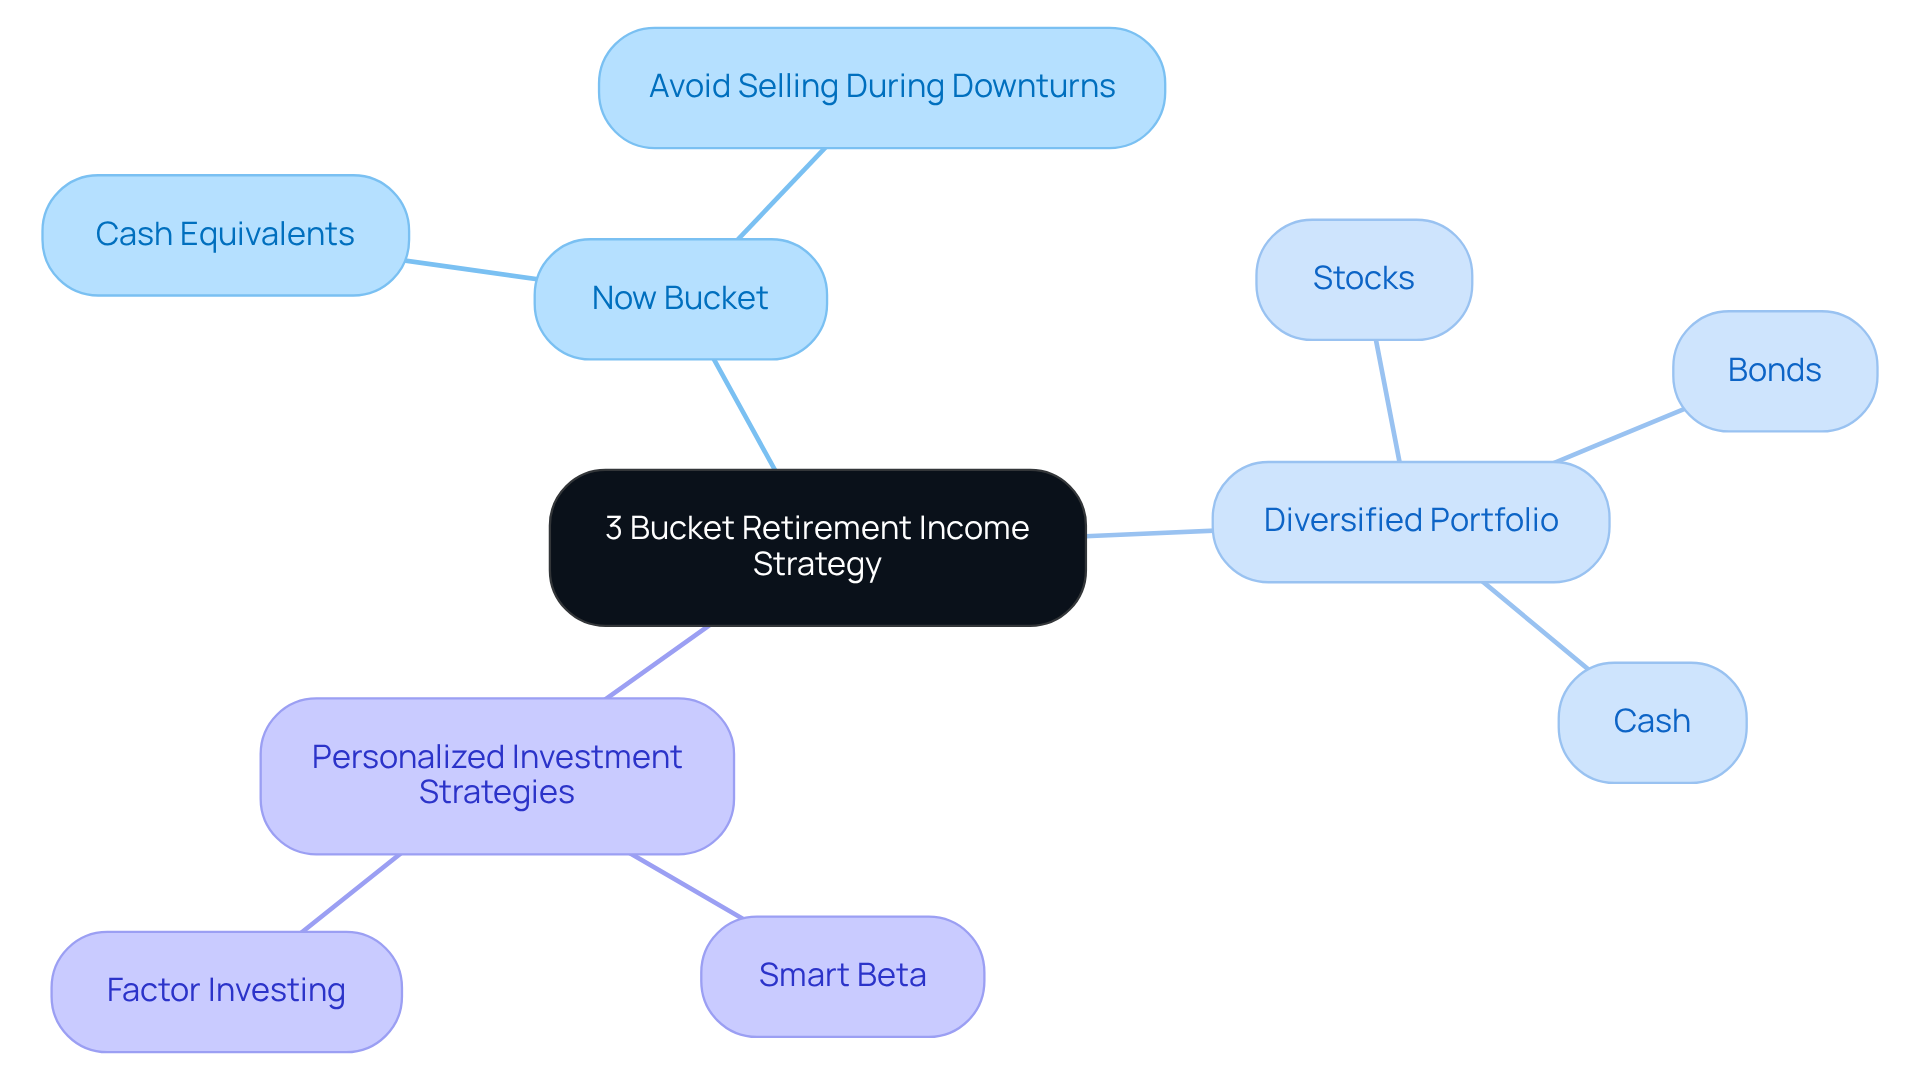
Optimize Asset Allocation Across the Three Buckets
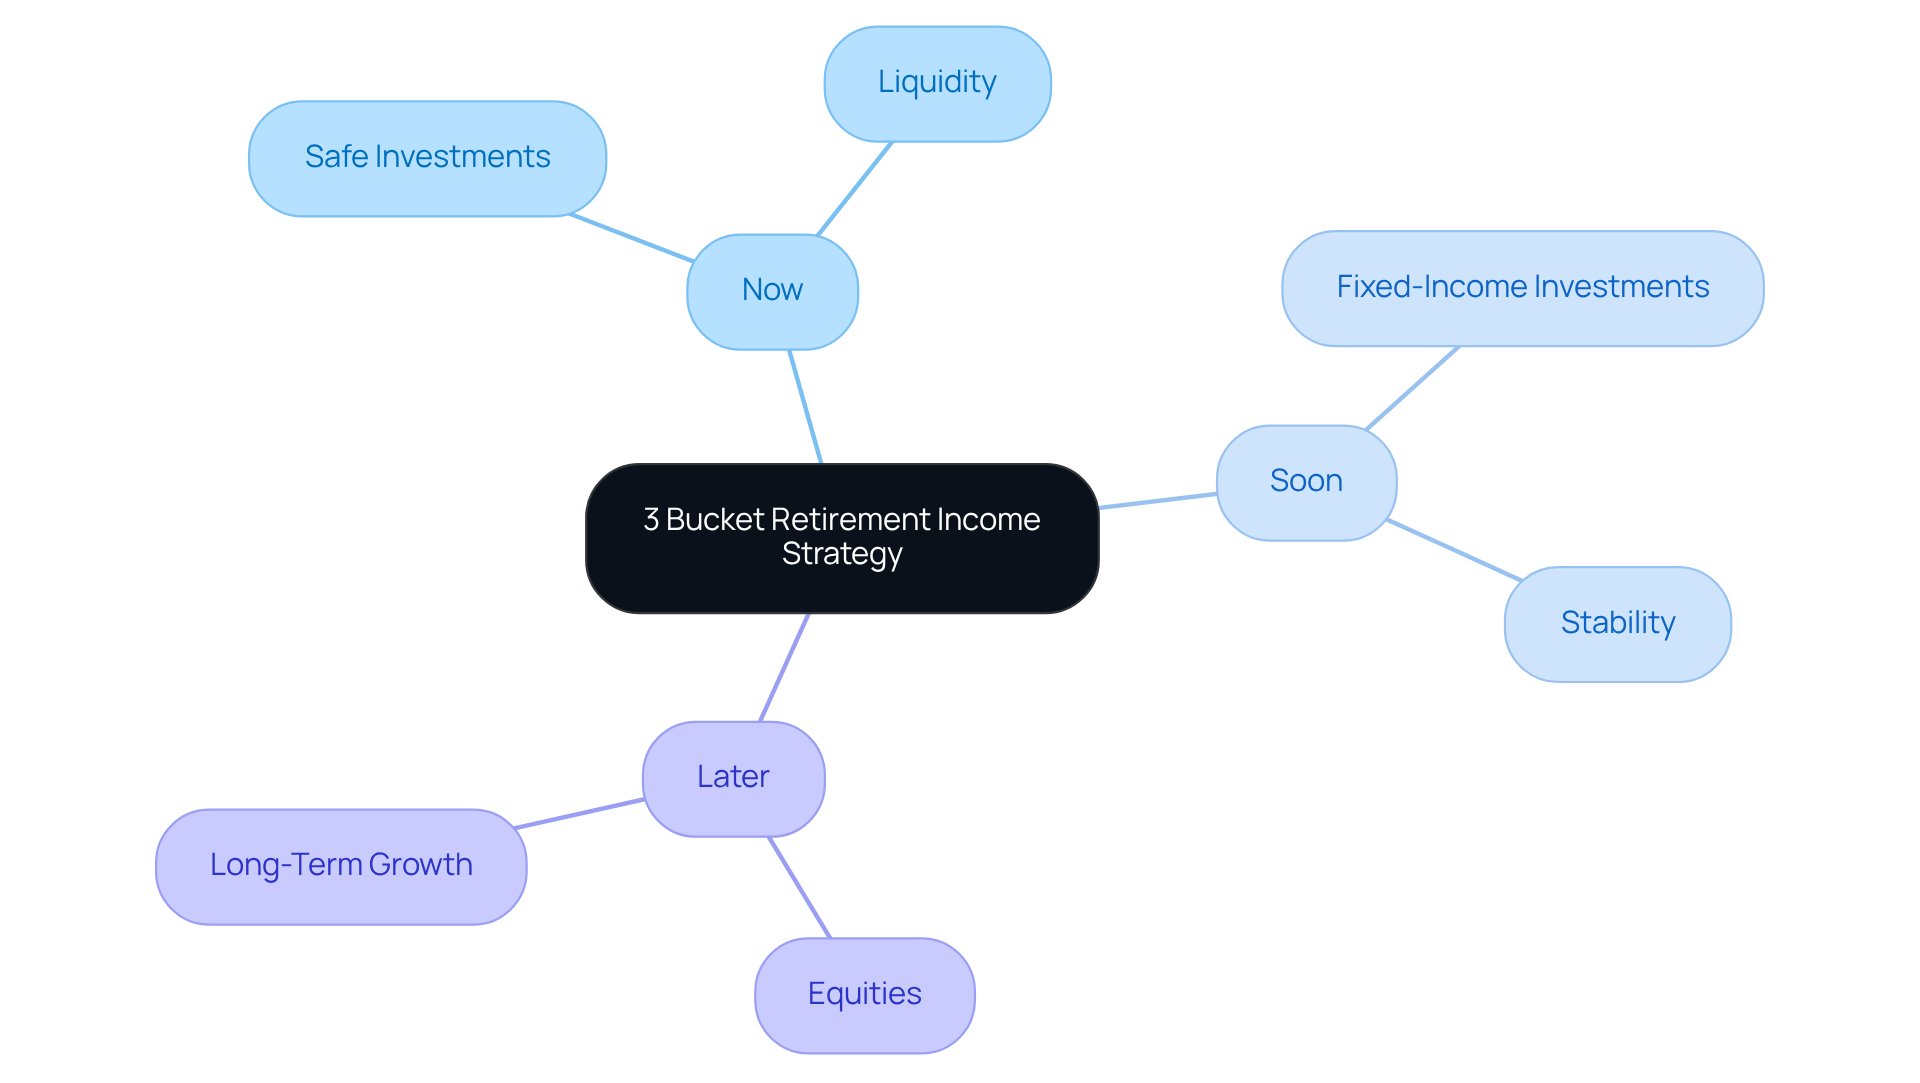
Imagine feeling secure about your family’s financial future while balancing your immediate needs and long-term goals. Effective asset allocation can help you achieve this balance through the 3 bucket retirement income strategy, which includes three important buckets: Now, Soon, and Later. It’s important to understand your family’s unique situation, including your comfort with risk and your financial aspirations, to guide your asset allocation decisions.
For instance, the Now Fund should focus on safe investments to ensure you have the liquidity for immediate needs. The Soon Container can blend fixed-income investments, providing stability while allowing for some growth. In contrast, the Later Bucket of the 3 bucket retirement income strategy can take a more aggressive approach, focusing on equities to capitalize on long-term growth potential.
Regularly checking in on your financial plan can help ensure it stays aligned with your family’s evolving needs and the market’s ups and downs. Consider gathering as a family each year to discuss your investment goals and risk preferences. These conversations can strengthen your family bonds and promote open dialogue about finances. By having these conversations, you not only work towards your financial goals but also teach your children valuable lessons about managing money responsibly. Together, you can create a financial plan that nurtures your family’s future.
Reduce Financial Anxiety with the Three-Bucket Strategy
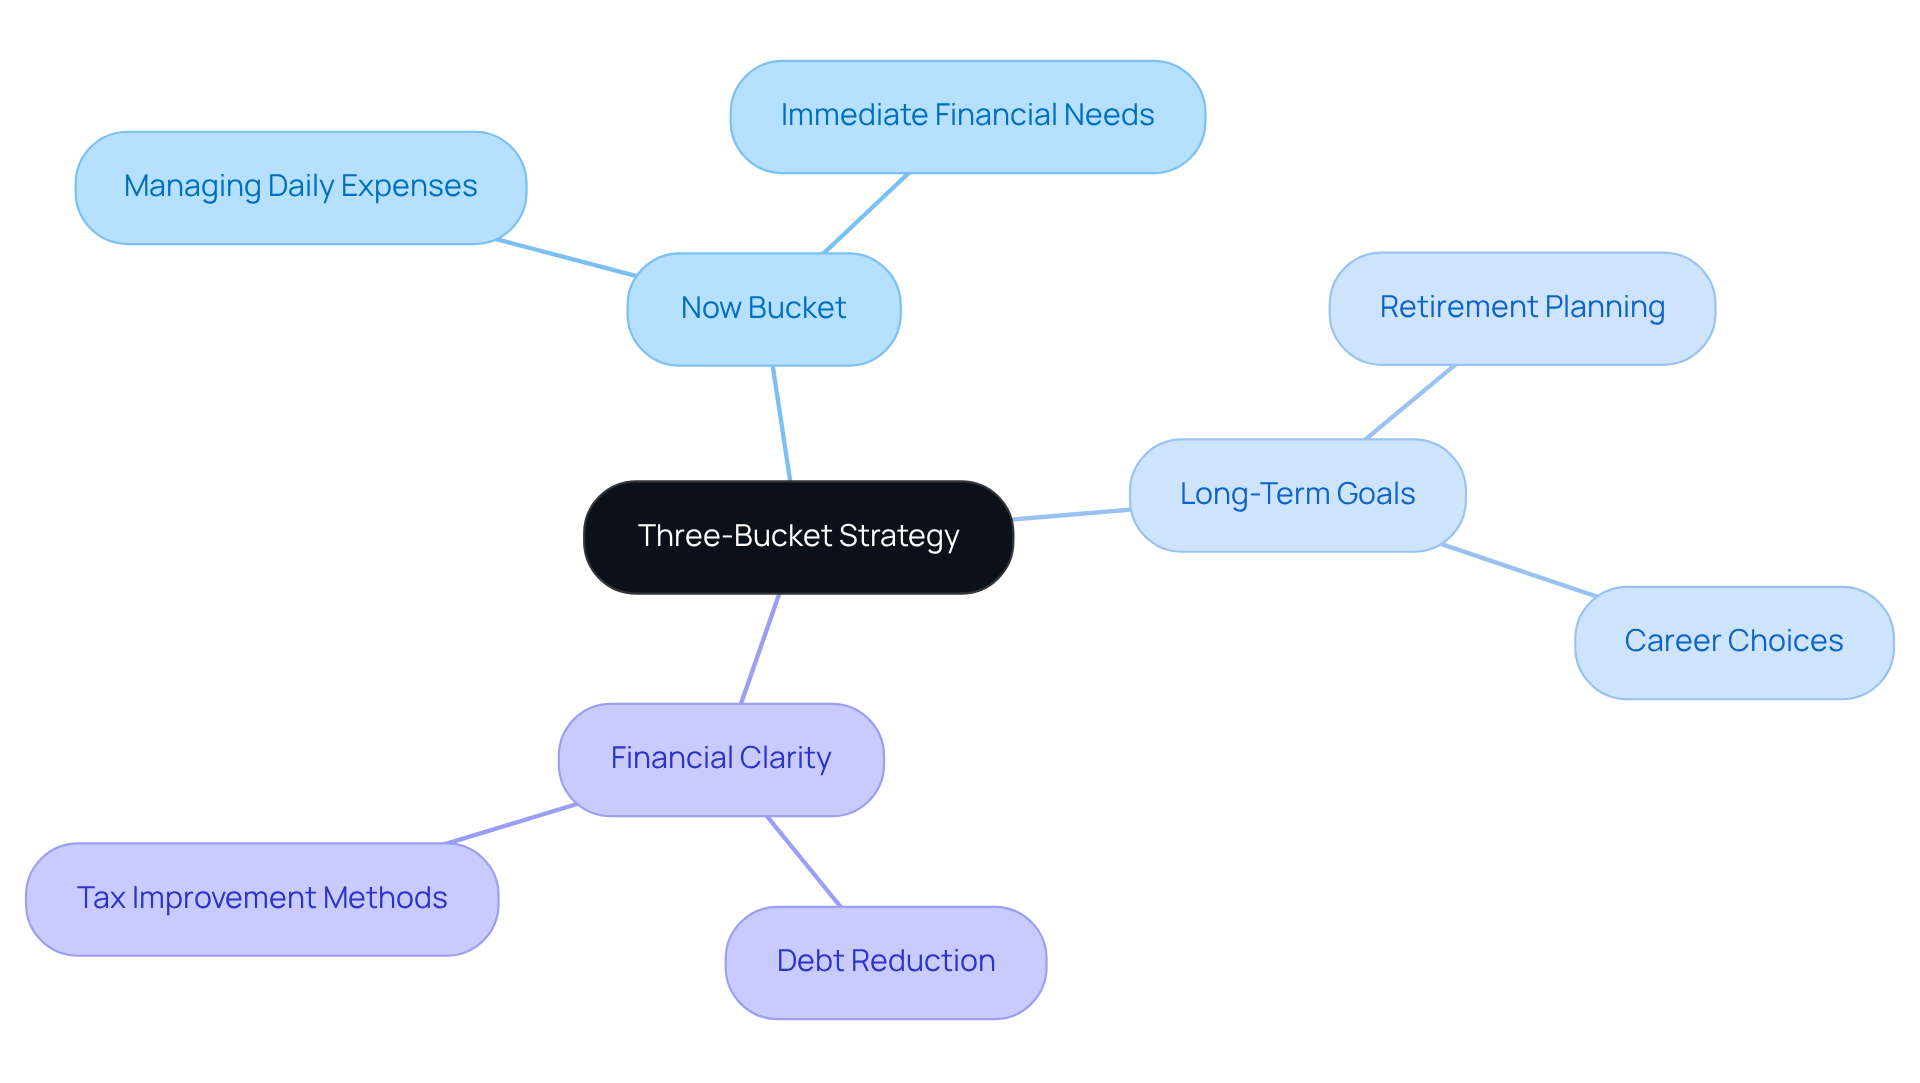
Many families feel overwhelmed by the constant pressure of managing daily expenses, especially when planning for the future. The 3 bucket retirement income strategy can greatly alleviate monetary stress for households by providing a clear and organized method for managing retirement income. When families manage their immediate costs with the Now Bucket, they can focus on long-term goals without worrying about daily financial pressures. This feeling of security is incredibly valuable, especially for families with young children who often face unexpected costs.
With the help of Bright Advisers, families like Emily and Mark found clarity in their finances and developed a thoughtful plan using the 3 bucket retirement income strategy. This plan focused on managing their cash flow, reducing debt, and implementing tax improvement methods, ultimately granting them the freedom to make career choices based on their desired work-life balance.
With a clearly outlined plan established, families can approach retirement with confidence, knowing they have a method to address their monetary needs and fulfill their goals. With the right support, families can confidently navigate their financial journey, ensuring a brighter future for their loved ones.
Empower Yourself with Knowledge of the Bucket Strategy
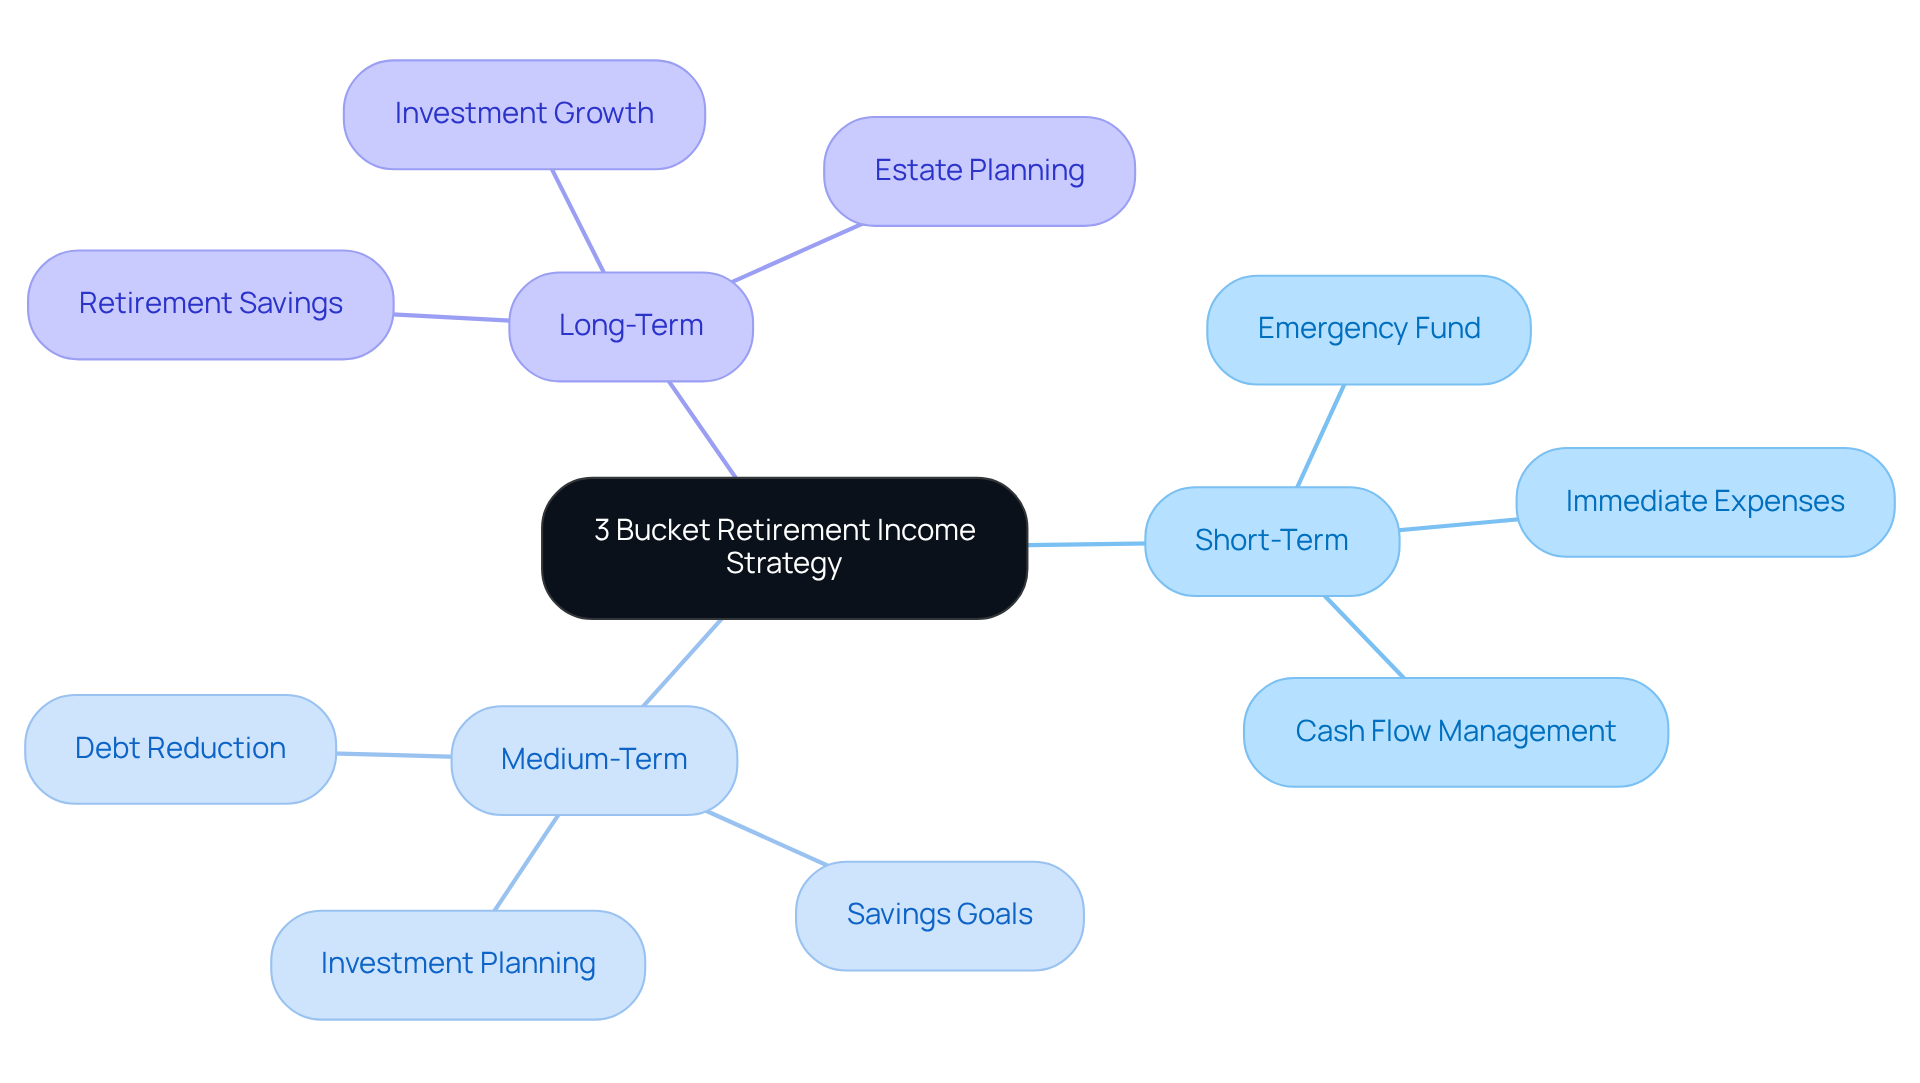
Imagine feeling empowered to take charge of your family’s financial future with confidence and clarity. Understanding the 3 bucket retirement income strategy helps families learn how to distribute their assets across three categories: short-term, medium-term, and long-term. This approach allows families to make informed choices that align with their financial goals. Not only does it enhance money management skills, but it also builds confidence in handling investments and withdrawals. When families engage in conversations about budgeting, it fosters openness and ensures everyone is aligned, working towards shared goals.
It’s concerning to know that many young parents feel uncertain about managing their finances, with only 14% able to answer key questions correctly. This highlights the importance of prioritizing financial education in households. By learning about the 3 bucket retirement income strategy, families can navigate their financial landscape with greater confidence, leading to improved economic well-being.
Families who embrace the bucket strategy often share stories of newfound security and understanding in their financial choices. Take Emily and Mark, for instance. This couple in their mid-30s worked with Bright Advisers to create a personalized plan that gave them the flexibility to decide whether to continue working. Through tailored strategies to reduce debt, manage cash flow, and invest wisely, they found the freedom to make career choices that suited their desired work-life balance. Families that actively participate in financial discussions and planning are better equipped to manage their resources effectively, reducing stress and enhancing their overall economic health. As educator John W. Rogers, Jr. wisely states, “Money management knowledge is just as important in life as the other basics.” By utilizing the 3 bucket retirement income strategy, families can create a roadmap for their future, ensuring they are prepared for both expected and unexpected expenses.
At Bright Advisers, we are committed to transparent pricing and low fund fees, so families can access the guidance they need without hidden costs. Remember, all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and all investments carry risk. By embracing the 3 bucket retirement income strategy, you can pave the way for a secure financial future, prepared for whatever life throws your way.
Enhance Tax Efficiency with the Three-Bucket Approach
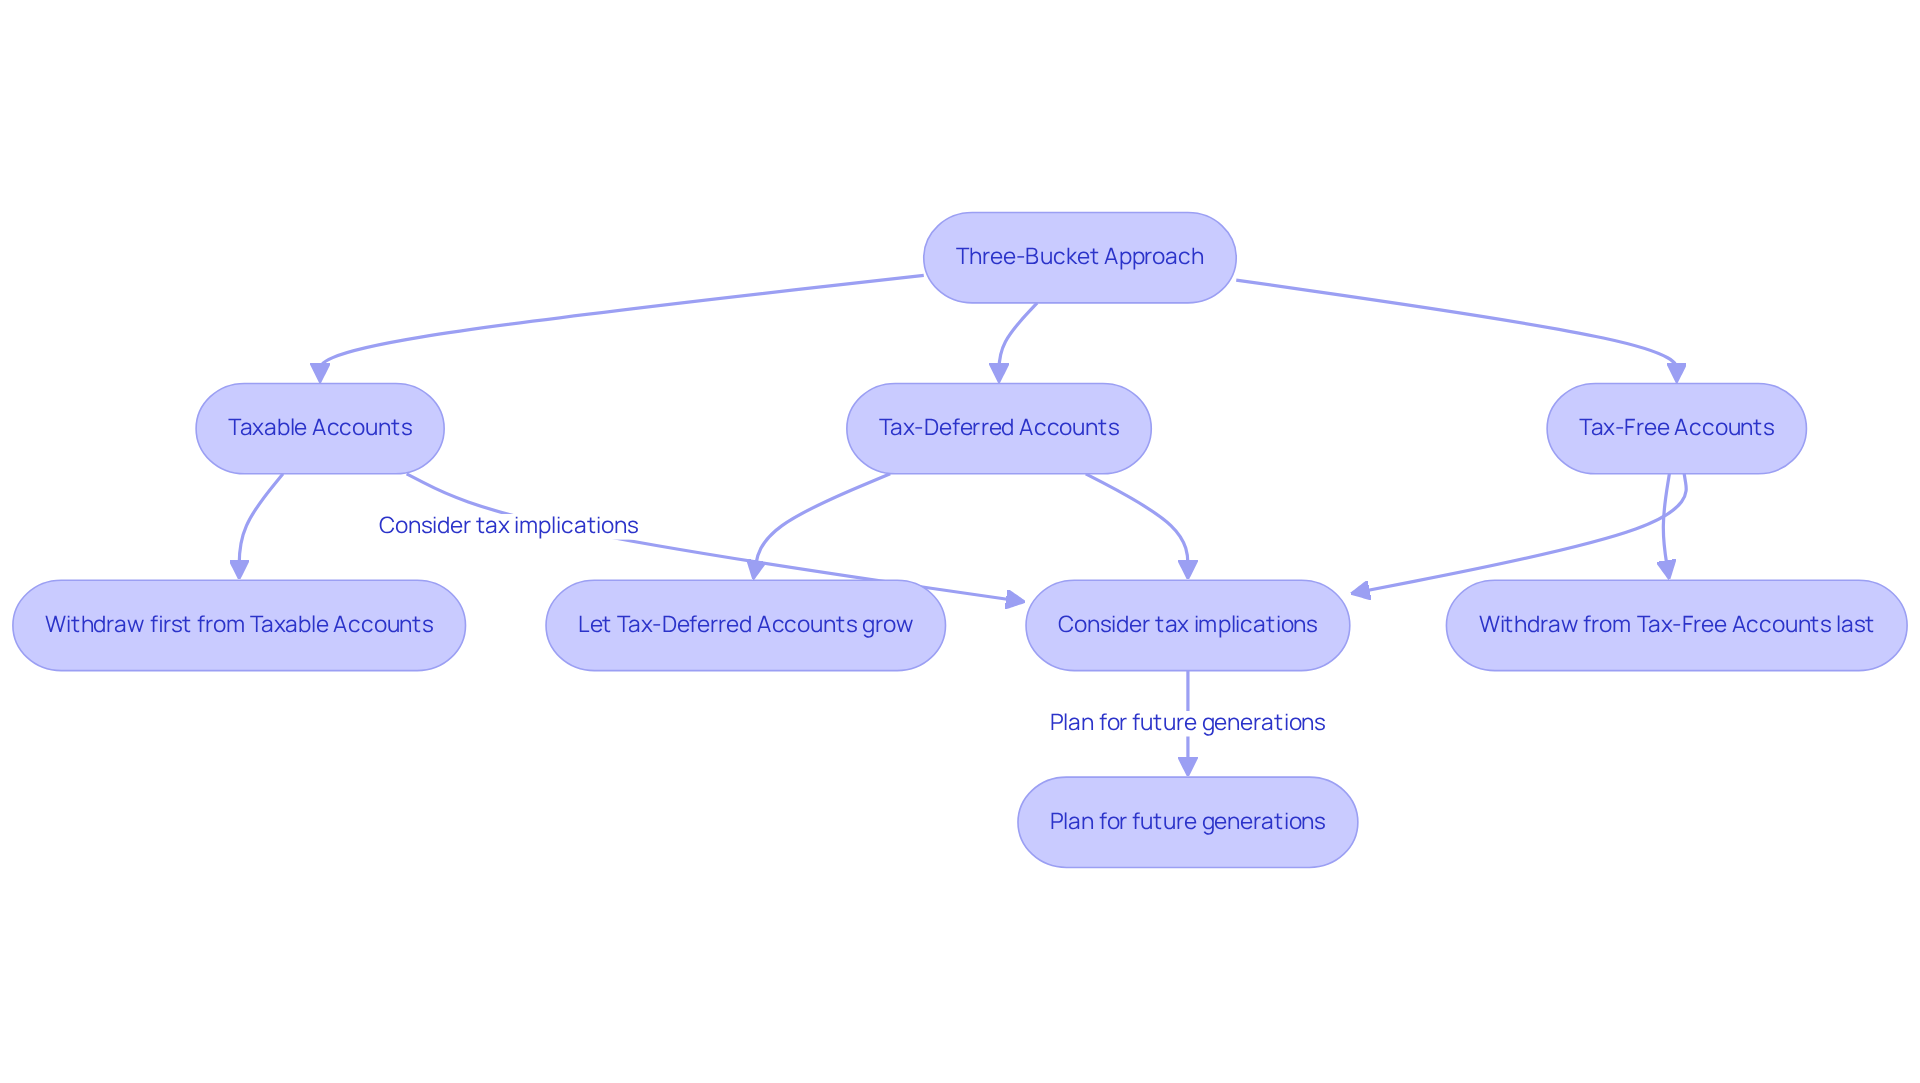
Imagine feeling confident about your family’s financial future, knowing you’re making the most of your hard-earned money. The 3 bucket retirement income strategy can help families feel more secure by managing withdrawals in a way that maximizes their money. By prioritizing withdrawals from taxable accounts first, families can let their tax-deferred accounts continue to grow. This method minimizes the tax impact on retirement income and helps families stay within lower tax brackets, ultimately preserving more wealth for future generations.
For example, consider Allison and Brian, a couple just like you, who turned to Bright Advisers for help with their tax planning journey. Even with good incomes, they felt lost about the financial opportunities slipping through their fingers because of their tax plans. By using the 3 bucket retirement income strategy as a tax-efficient withdrawal method, they saved approximately $40,000 in federal taxes and increased their after-tax inheritance value by $120,000 compared to conventional methods. This thoughtful strategy not only improved their tax situation but also helped secure their children’s education and gave them the chance to retire earlier.
It’s important to understand the tax consequences of withdrawals for families aiming to enhance their income. As Roger Young, a CERTIFIED FINANCIAL PLANNER professional, shares, “Instead of the conventional approach-taking from taxable accounts first, then traditional accounts, then Roth-years of research on tax efficiency and withdrawal sequencing show that tailoring withdrawals to your circumstances can save thousands in taxes.” This proactive strategy for tax planning not only addresses current monetary needs but also lays the groundwork for future generations to benefit from their wealth. By embracing a thoughtful tax strategy, you can create a lasting legacy for your loved ones, ensuring they thrive in the years to come.
Integrate Comprehensive Financial Planning with the Bucket Strategy
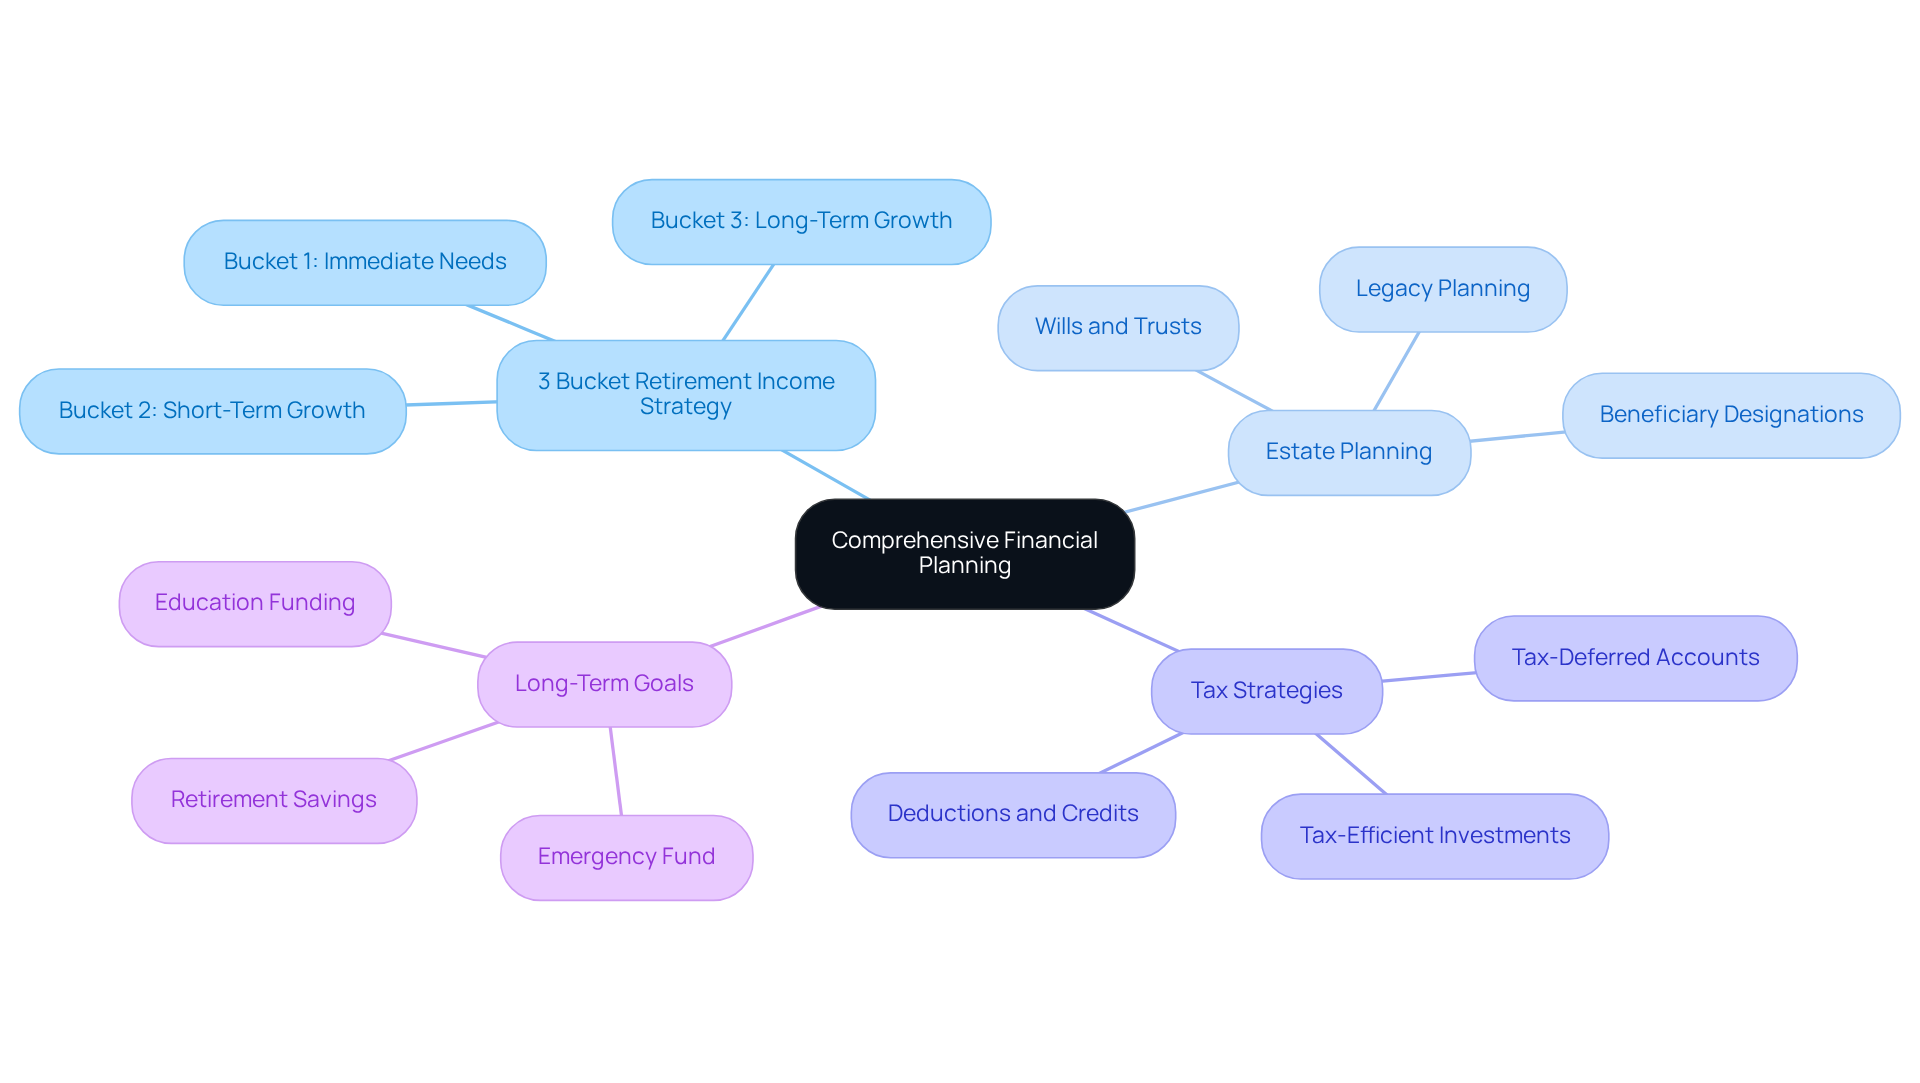
Imagine the peace of mind that comes from knowing your family’s financial future is secure and well-planned. When you blend the 3 bucket retirement income strategy with thoughtful financial planning, you can truly align your investments with what matters most to your family. This method takes into account essential aspects like estate planning, tax strategies, and long-term goals. By viewing the 3 bucket retirement income strategy as part of a broader financial framework, you can ensure that your investments support your dreams, whether that’s funding education or leaving a legacy. This integration fosters a cohesive strategy that adapts to changing circumstances, giving you the resources you need to navigate your financial future effectively.
Did you know that nearly 9 out of 10 comprehensive planners have a clear retirement strategy? It shows just how vital it is to have a solid financial plan in place. Additionally, 85% of these planners keep at least three months of emergency savings, demonstrating their readiness for unexpected expenses. In contrast, families without a budget often find themselves struggling with money management, with 92% of non-planners lacking specific savings goals.
Families who work with financial professionals – about 19% of households – often find themselves feeling more secure, with 67% of them seeking guidance that truly puts their family’s needs first. This professional support is linked to better financial outcomes, highlighting the importance of combining thorough planning with investment strategies. For instance, Emily and Mark, a couple in their mid-30s, partnered with Bright Advisers to gain clarity on their financial situation. Through a comprehensive evaluation, they crafted a plan focused on reducing debt, managing cash flow, and implementing tax improvement strategies. This empowered them to align their financial strategies with their personal aspirations, showcasing the transformative power of effective planning.
As Kevin R. Keller, CEO of the CFP Board, states, “This research reaffirms the importance of planning for all households and also the value of receiving assistance from a professional who always prioritizes the families’ best interest first and adheres to a fiduciary standard of care.” By adopting this integrated approach, families can enhance their financial confidence and satisfaction, ultimately leading to a more secure financial future. With the right support, you can turn your financial dreams into reality, ensuring a brighter future for your family.
Conclusion
Imagine navigating your family’s financial future with confidence and clarity. The 3 bucket retirement income strategy offers families a structured approach to managing their financial future, ensuring that immediate, short-term, and long-term needs are met with assurance. Dividing your assets into three buckets – Now, Soon, and Later – helps your family navigate retirement with a clear plan. This approach addresses your current expenses while also focusing on future goals, bringing you peace of mind.
Throughout this article, we’ve highlighted key benefits of this strategy. You can manage immediate living expenses, prepare for upcoming costs like education, and invest for long-term growth. The flexibility in withdrawal strategies allows families to adapt to market conditions, reducing risks associated with market volatility. Plus, integrating tax-efficient withdrawal methods enhances your overall financial well-being, ensuring that you can preserve your wealth for future generations.
Using the 3 bucket retirement income strategy can be a game-changer for families looking to reach their financial dreams. By prioritizing education and having open discussions about budgeting, you can empower your family to make informed decisions that align with your values and goals. Embracing this strategy not only alleviates financial anxiety but also paves the way for a secure and prosperous future. We encourage you to explore this approach further and consider seeking guidance from Bright Advisers to tailor a plan that meets your unique needs and aspirations. Taking this step today can transform your family’s financial journey into one filled with hope and security.
Frequently Asked Questions
What is the Now Fund and how does it help retirees?
The Now Fund is designed to cover immediate living expenses during the first 1-3 years of retirement, providing cash or cash equivalents for quick access. This helps retirees avoid liquidating investments during market downturns and ensures they can manage daily expenses like mortgage payments, groceries, and healthcare costs.
Why is it important to have a cash reserve for retirement?
Having a cash reserve is vital for managing the average yearly retirement expenses, which for households led by individuals aged 65 and older is around $61,432. It helps alleviate financial pressure and allows retirees to focus on their families and enjoy retirement.
How can families prepare for unexpected expenses in retirement?
Families can prepare for unexpected expenses by creating a Now Fund, which provides liquidity for urgent monetary needs. This fund can help cover costs such as healthcare, which averages around $7,799 a year.
What is the Soon Fund and what expenses does it cover?
The Soon Fund is designed to manage short-term expenses expected in the next 3-10 years, such as education costs and significant expenses like home repairs or medical bills. It typically includes fixed-income investments, balancing growth and stability.
How can families benefit from the Soon Fund in terms of education costs?
The Soon Fund helps families prepare for rising education costs, which contribute to the average cost of raising a child over 18 years, estimated at approximately $303,418. By allocating resources to this fund, families can reduce financial pressure when these costs arise.
What investment strategies are used in the Soon Fund?
The Soon Fund utilizes fixed-income investments like bonds or conservative mutual funds, and Bright Advisers employs innovative technology to create hyper-personalized portfolios, enhancing efficiency and avoiding expensive mutual funds and ETFs.
What is the Later Bucket and its purpose?
The Later Bucket focuses on long-term growth by investing in equities or other growth-oriented assets, with funds set aside for at least a decade. It aims to secure a child’s future and achieve higher returns through market appreciation.
How do 529 college savings plans relate to the Later Bucket?
529 college savings plans are crucial for funding children’s education, with total assets reaching $525.1 billion as of December 2024. These plans allow families to utilize tax-advantaged savings for education, promoting a culture of money management.
What advantages does Bright Advisers offer for investment portfolios?
Bright Advisers provides a transparent, all-inclusive fee structure with no hidden fees, commissions, or trade fees. Their innovative technology leads to more efficient investment portfolios, increasing the chances of achieving financial goals.
How can families start building their Now Fund?
Families can begin building their Now Fund by setting aside a portion of their savings in easily accessible accounts, ensuring they are prepared for any urgent monetary needs that may arise.
List of Sources
- Ensure Immediate Financial Security with the Now Bucket
- 14 Must-Know Retirement Stats For 2026 – Carry (https://carry.com/learn/retirement-stats)
- 44 Retirement Statistics That Might Change Your Plan [2026] (https://getamplifylife.com/learn/blog/retirement-statistics)
- The Average Retirement Savings by Age (https://kiplinger.com/retirement/retirement-planning/average-retirement-savings-by-age)
- Here’s How Much Americans Save for Retirement: How Do You Compare? (https://investopedia.com/average-retirement-savings-by-age-8740967)
- Retirement Cost of Living Guide: Insights & Considerations (https://westernsouthern.com/retirement/retirement-cost-of-living)
- Manage Short-Term Expenses with the Soon Bucket
- Trends in College Pricing Highlights – College Board Research (https://research.collegeboard.org/trends/college-pricing/highlights)
- Retirement Income: The Bucket Strategy (https://americancentury.com/insights/retirement-income-the-bucket-strategy)
- The Bucket Plan® Philosophy | Prosperity Capital Advisors (https://prosperitycapitaladvisors.com/services/bucket-plan-philosophy)
- It Costs an Additional $303,418 to Raise a Child Over 18 Years, Up 1.9% (https://lendingtree.com/debt-consolidation/raising-a-child-study)
- Average Cost of College [2026]: Yearly Tuition + Expenses (https://educationdata.org/average-cost-of-college)
- Achieve Long-Term Growth with the Later Bucket
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2026]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- 5 Amazing Investing Quotes To Share With Your Kids (https://bluetreesavings.com/post/5-amazing-investing-quotes)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- Enhance Flexibility in Withdrawals with the Bucket Strategy
- Retiring in a Down Market: 7 Smart Strategies for 2026 | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/retiring-in-a-down-market)
- Managing Withdrawals During Market Downturns – Fullerton Financial Planning (https://fullertonfp.com/blog/managing-withdrawals-during-market-downturns)
- The Impact of Guaranteed Income and Dynamic Withdrawals on Safe Initial Withdrawal Rates (https://financialplanningassociation.org/article/journal/APR17-impact-guaranteed-income-and-dynamic-withdrawals-safe-initial-withdrawal-rates)
- Retiring into a down market: How to make your savings last (https://troweprice.com/personal-investing/resources/insights/how-to-make-your-savings-last-when-retiring-into-a-down-market.html)
- Protecting Retirement Accounts During Market Volatility – Olsen Thielen CPAs & Advisors (https://otcpas.com/market-volatility)
- Mitigate Market Volatility Risks with the Bucket Approach
- How to Prepare for a Recession: 7 Smart Tips (https://schwab.com/learn/story/5-tips-weathering-recession)
- How to Handle Market Volatility | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/how-to-handle-market-volatility.html)
- U.S. Investors Braced for More Market Volatility (https://news.gallup.com/poll/692309/investors-braced-market-volatility.aspx)
- How to Protect Your Wealth During Market Downturns (https://realinvestmentadvice.com/resources/blog/how-to-protect-your-wealth-during-market-downturns)
- Optimize Asset Allocation Across the Three Buckets
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- A Simple guide to asset allocation for family (https://andsimple.co/guides/family-office-asset-allocation)
- Retirement Portfolio Assets: Allocation by Age (https://schwab.com/learn/story/retirement-portfolio-assets-allocation-by-age)
- How to Account for Different Levels of Family Risk Tolerance (https://thefopro.com/how-to-account-for-different-levels-of-family-risk-tolerance)
- Asset allocation: What it is and how to choose yours | Fidelity (https://fidelity.com/learning-center/trading-investing/asset-allocation)
- Reduce Financial Anxiety with the Three-Bucket Strategy
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- 14 Quotes About Financial Planning to Share With Clients | Blueleaf (https://blueleaf.com/blog/14-quotes-about-financial-planning-to-share-with-clients)
- As Costs Rise, Families With Young Children Are Feeling the Strain (https://the74million.org/zero2eight/as-costs-rise-families-with-young-children-are-feeling-the-strain)
- How Financial Planning Can Reduce Stress (https://avaii.com/blog/how-financial-planning-can-reduce-stress)
- Famous Quotes on Financial Stability and Well-Being – Center for the Advancement of Well-Being (https://wellbeing.gmu.edu/famous-quotes-on-financial-stability-and-well-being)
- Empower Yourself with Knowledge of the Bucket Strategy
- Financial Literacy Data Insights (https://ifdm.stanford.edu/data-financial-literacy)
- Financial Education Quotes (https://financialeducatorscouncil.org/financial-education-quotes)
- 40 Financial Literacy Statistics in the United States – Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/financial-literacy-statistics)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)
- Enhance Tax Efficiency with the Three-Bucket Approach
- Tax-Efficient Withdrawal Strategies During Retirement (https://ireap.naifa.org/blog/tax-efficient-withdrawal-strategies-during-retirement)
- 3 Tax-Efficient Strategies for Retirement | SecurityPlus FCU (https://securityplusfcu.org/learn/education/prosperity-pulse/september-2025/3-tax-efficient-strategies-for-retirement-withdrawals)
- Want your retirement savings to go further? Learn more about tax-efficient strategies (https://troweprice.com/personal-investing/resources/insights/tax-efficient-retirement-withdrawal-strategies.html)
- Savvy tax withdrawals | Fidelity (https://fidelity.com/viewpoints/retirement/tax-savvy-withdrawals)
- Maximize your savings: Tax-efficient retirement withdrawal strategies (https://ubs.com/us/en/wealth-management/our-solutions/planning/retire-planning/articles/maximize-savings-tax-efficient-withdrawals.html)
- Integrate Comprehensive Financial Planning with the Bucket Strategy
- Article – New Research Shows Most American Households Do Financial Planning, But the Extent of This Planning Varies Greatly | Consumer Federation of America (https://consumerfed.org/news/press-releases/new-research-shows-most-american-households-do-financial-planning-but-the-extent-of-this-planning-varies-greatly)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Cerulli Associates | 53% of Households Believe in the Importance of a… (https://cerulli.com/press-releases/53-of-households-believe-in-the-importance-of-a-financial-plan)
- What Is a Financial Plan and Why Do I Need One? | Morgan Stanley (https://morganstanley.com/insights/articles/what-is-a-financial-plan)
- Morgan Stanley Financial Planning Survey | Morgan Stanley (https://morganstanley.com/press-releases/morgan-stanley-financial-planning-survey)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading