

Key Highlights
- Many young parents overlook the vesting schedule of Incentive Stock Options (ISOs), which can lead to financial losses if options are not exercised in time.
- Families should set calendar reminders for important ISO deadlines to avoid expiration planning mistakes.
- Exercising ISOs can lead to unexpected financial strain due to cash flow needs and potential tax liabilities, particularly from the Alternative Minimum Tax (AMT).
- Understanding the tax implications of exercising ISOs is crucial, as families may face significant AMT liabilities without proper planning.
- Market conditions and company status, such as potential IPOs, can impact the timing of exercising stock options, making it essential for families to stay informed.
- Personal risk tolerance should guide decisions regarding ISOs to align investments with family financial goals and reduce stress.
- Accurate record-keeping of ISOs is vital to avoid missing tax benefits and managing options effectively.
- Professional guidance from Bright Advisers can help families navigate ISO complexities and align their financial strategies with their goals.
Introduction
Imagine feeling overwhelmed by the complexities of Incentive Stock Options (ISOs) while trying to secure your family’s financial future. Many families find themselves facing challenges in ISO expiration planning that can lead to missed opportunities and unexpected financial burdens. In this article, we’ll gently guide you through ten common challenges parents face, offering insights and strategies to help you avoid these costly errors.
How can you, as a parent, feel confident in making informed decisions about your ISOs while balancing the demands of parenthood and financial planning?
Neglecting the Vesting Schedule of ISOs
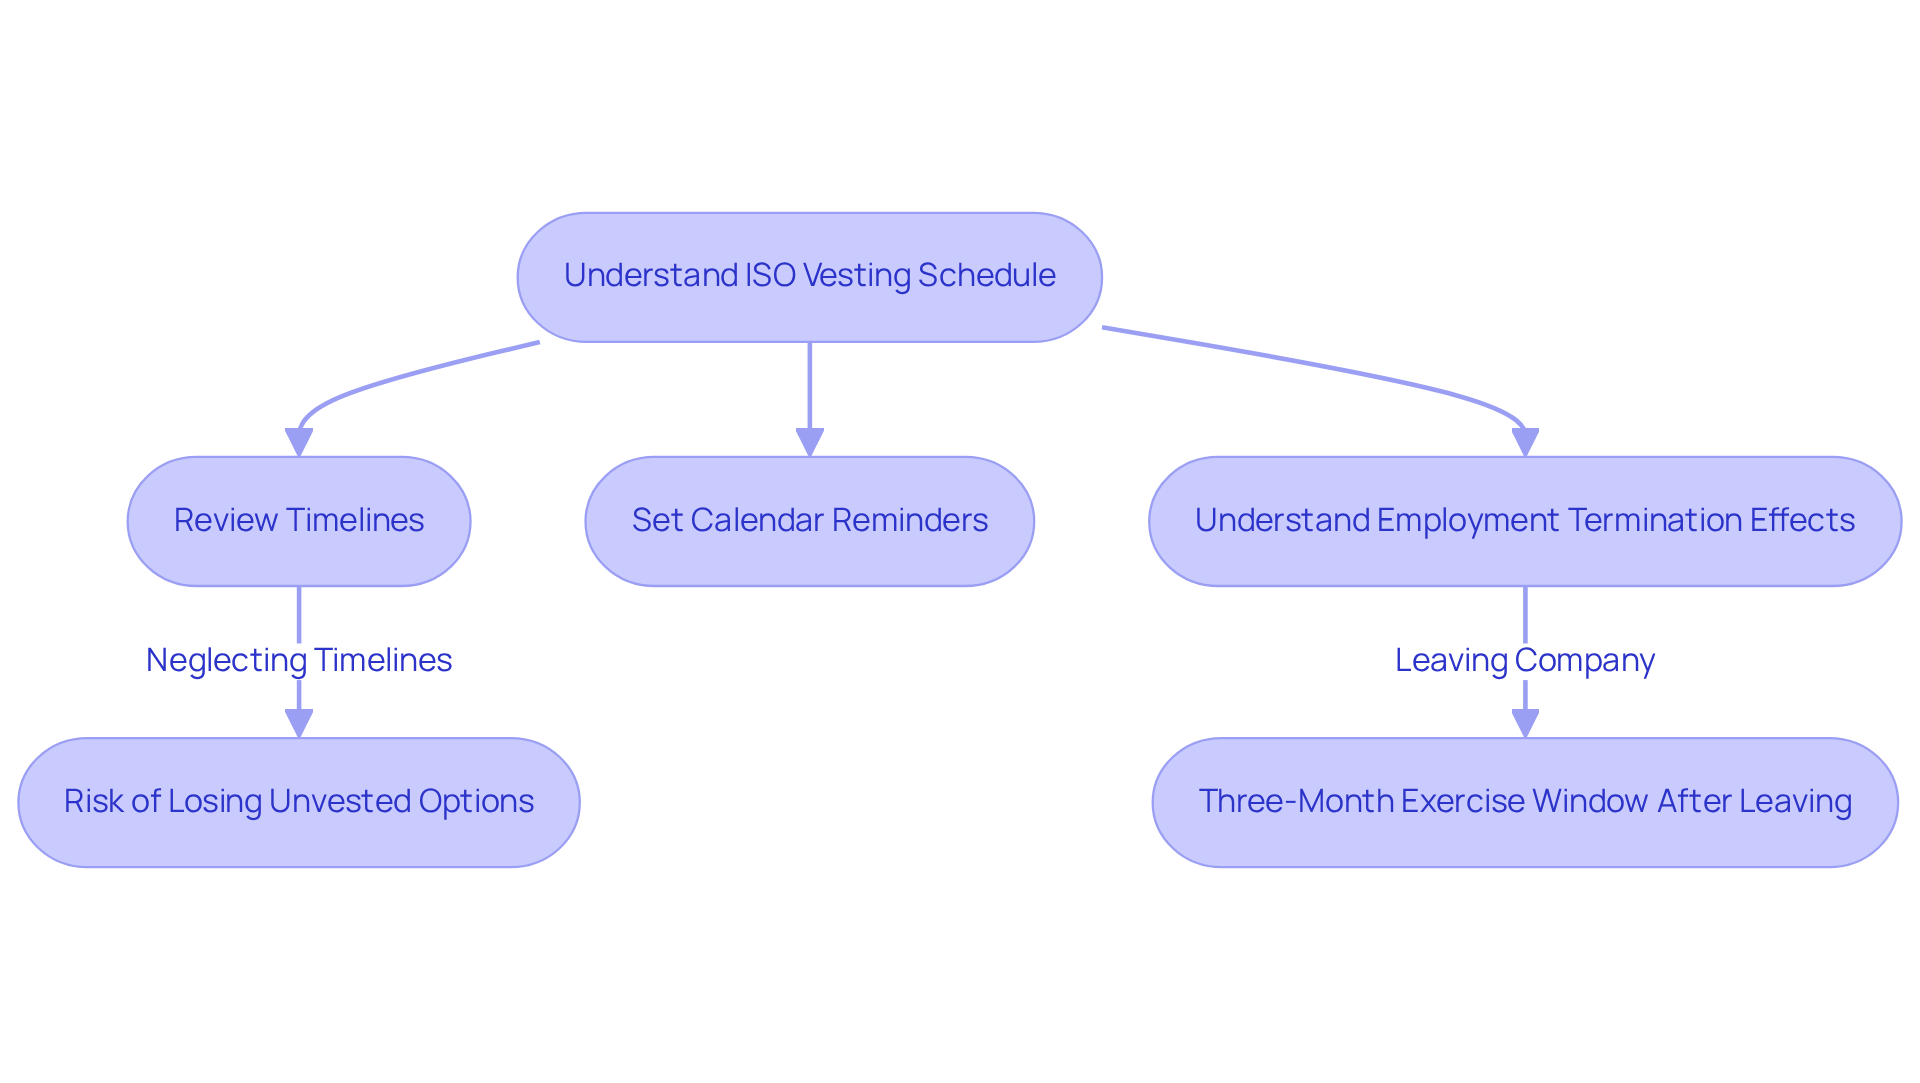
Imagine missing out on a financial opportunity simply due to an ISO expiration planning mistake related to the timeline for your Incentive Stock Options. Many young parents often overlook the vesting schedule, which is essential for knowing when they can exercise their options. It’s important to understand that an ISO expiration planning mistake by missing these timelines could mean losing out on valuable financial opportunities for your family. Typically, ISOs vest over four years, with a one-year cliff. This means no options vest until you’ve been with the company for a year, after which they gradually become available.
Taking the time to review these timelines can help your family make the most of your financial opportunities. If you leave the company before your options are fully vested, you risk losing unvested options, potentially resulting in an ISO expiration planning mistake that can significantly impact your financial planning. Bright Advisers recommends setting up calendar reminders to track these important dates and deadlines to prevent an ISO expiration planning mistake when exercising your options.
It’s also crucial to understand how employment termination affects your stock options. Generally, you have about three months to exercise any vested options after leaving. This means that taking action now can help secure your family’s financial future. Incorporating stock options into your estate planning is vital, as heirs typically have one year from the date of passing to exercise any vested but unexercised options.
By staying informed and proactive, you can ensure your family’s financial future is secure and bright. Bright Advisers offers customized planning strategies to help you effectively manage your stock options and integrate them into your overall wealth management approach.
Overlooking Financial Implications of Exercising ISOs
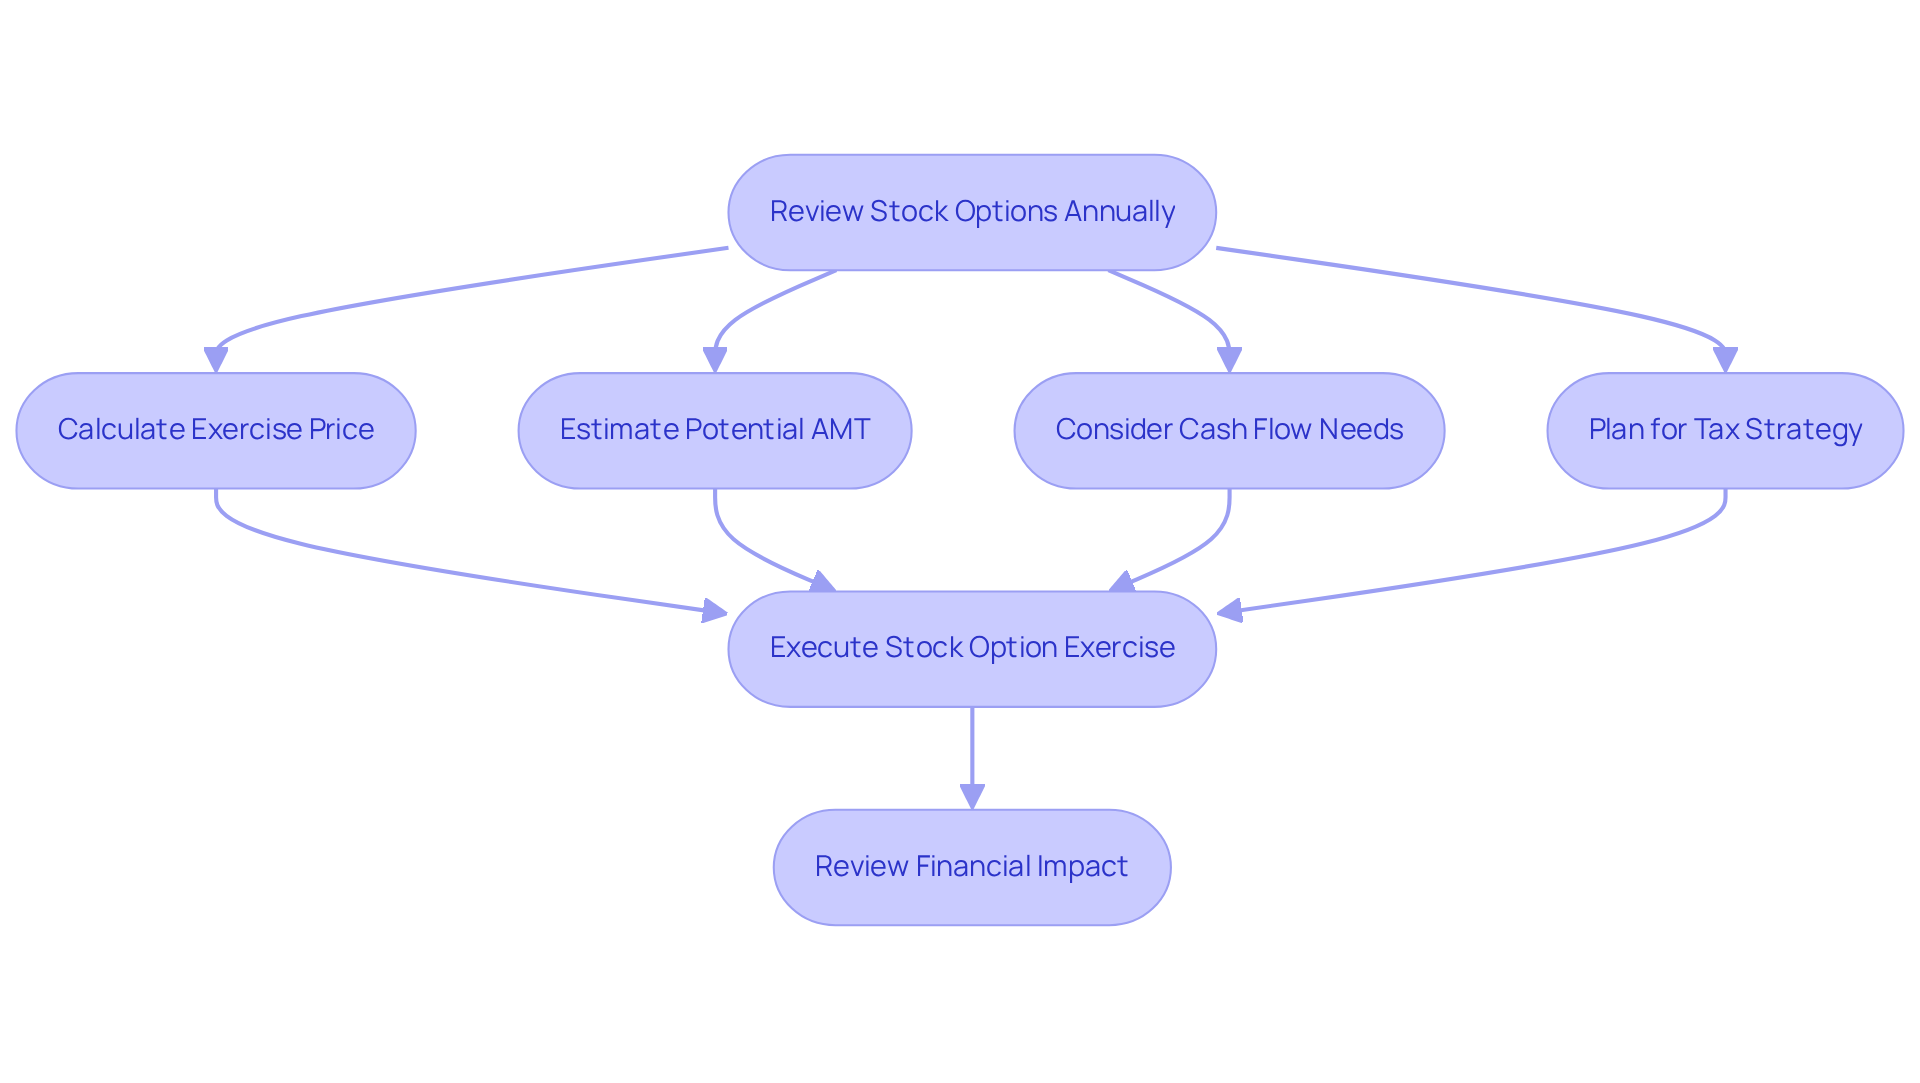
Imagine the surprise of discovering that exercising your stock options could lead to unexpected financial strain on your family. Many parents underestimate the cash needed to cover the exercise price, which can create stress when juggling bills. Plus, potential tax liabilities can arise, especially if the Alternative Minimum Tax (AMT) is triggered. For instance, if you exercise stock options with a strike price of $50 per share when the fair market value is $100, that $50 spread gets added to your income for AMT calculations, possibly leading to a hefty tax bill.
It’s important to think about the total cost of exercising your options, including any taxes that might come up. A common ISO expiration planning mistake is not accounting for the cash flow needed not just for the exercise price but also for potential AMT payments and regular living expenses during the holding period. Imagine exercising 10,000 stock options at a strike price of $50, with a fair market value of $500. You could face a phantom gain of $4,500,000 for AMT purposes, even though you haven’t sold any shares yet.
To avoid surprises, families should take a moment each year to review their stock options and understand their value. This proactive approach can help you plan exercises for the upcoming year while coordinating with your overall tax strategy. By understanding the financial implications and planning ahead, families can navigate the complexities of ISOs more effectively and avoid costly mistakes.
Take Allison and Brian, for instance. They reached out to Bright Advisers, hoping to unlock their financial potential through thoughtful tax planning. Despite their significant incomes, they were unaware of the opportunities they were missing due to insufficient tax strategies. With Bright Advisers’ help, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. This collaboration shows how strategic tax planning can enhance financial security for families, allowing them to enjoy more quality time with their loved ones.
Ignoring Tax Consequences of ISO Exercise
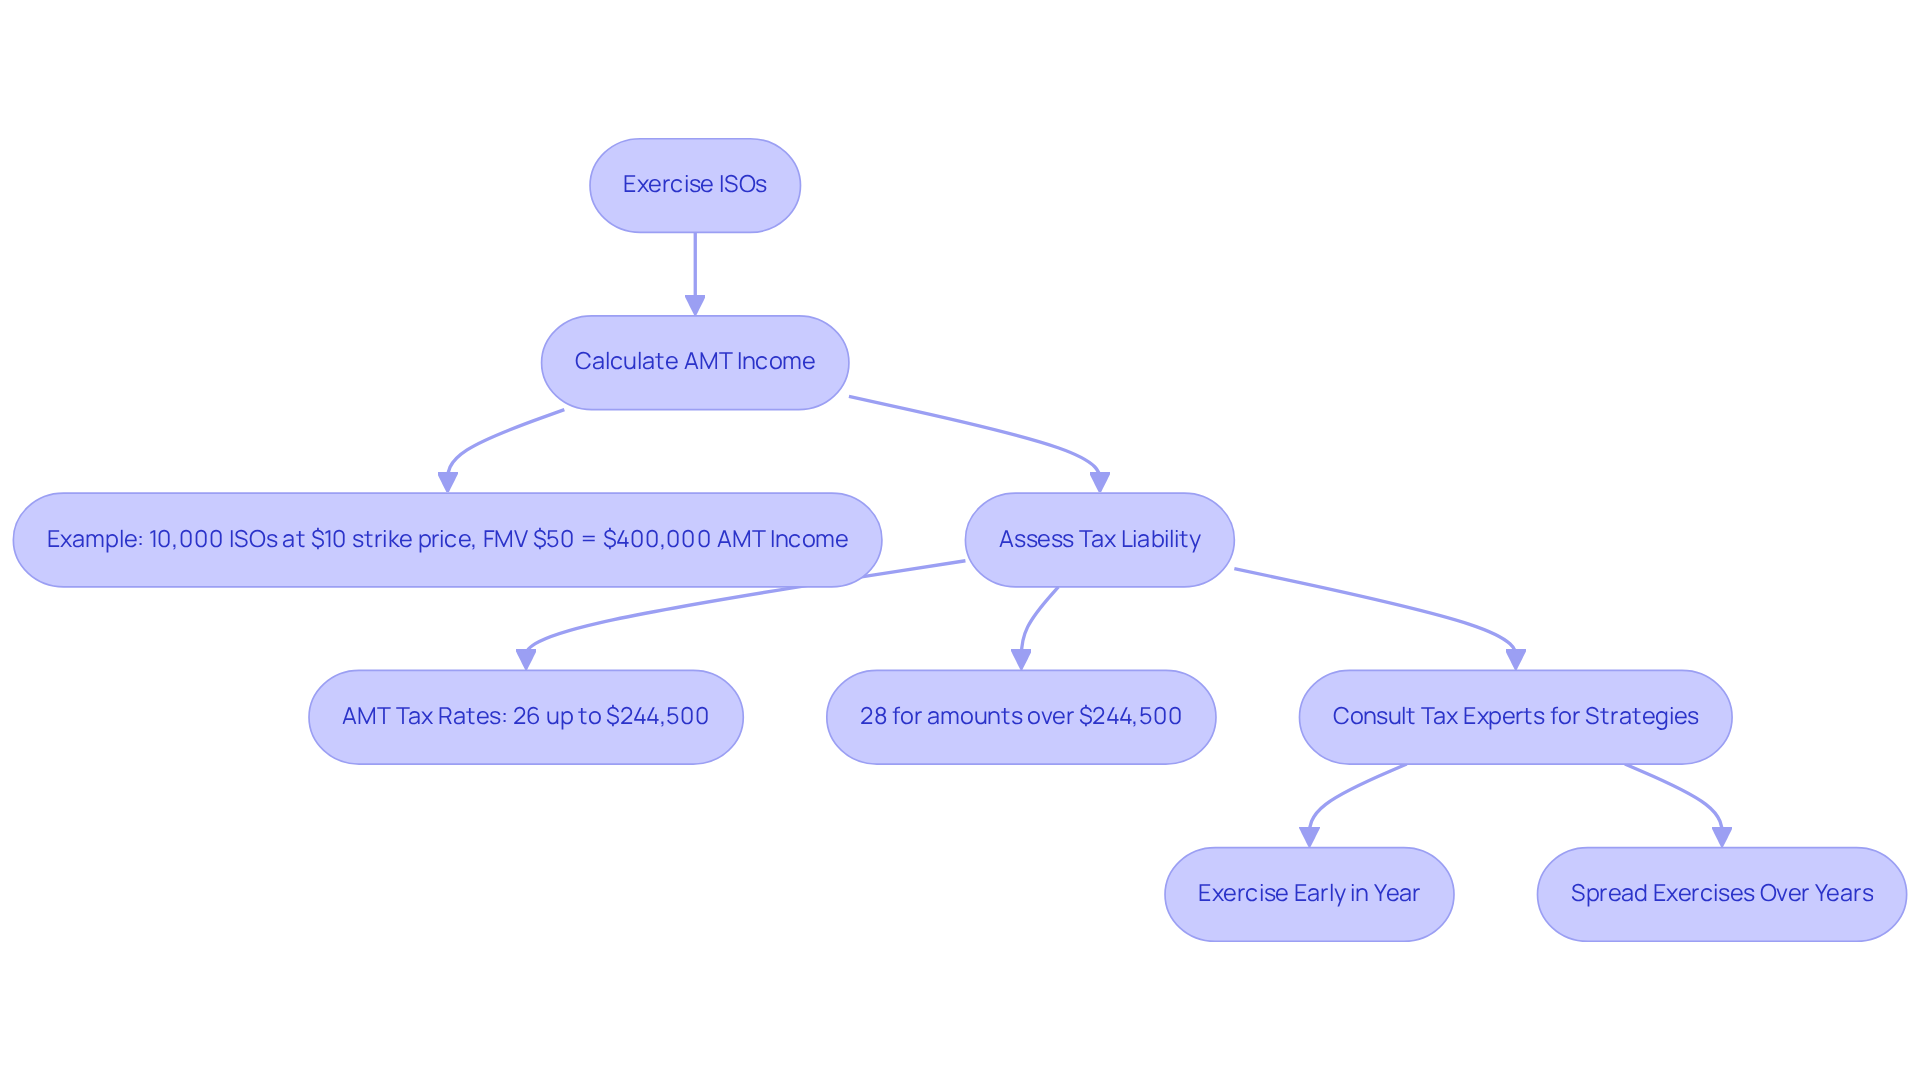
Imagine facing unexpected tax bills just when you thought you were making progress with your finances. Many parents might not realize that exercising stock options can lead to unexpected AMT liabilities. For example, if a household exercises 10,000 ISOs at a $10 strike price when the fair market value is $50, they could incur an AMT income of $400,000. This situation can lead to an additional AMT tax liability of $20,000, even if there’s no cash gain at that moment. It’s crucial to understand how AMT can impact your family’s overall tax situation.
By 2026, families earning over $1,000,000 will find their AMT exemptions reduced, which could lead to higher tax bills. The AMT tax rates start at 26% for alternative minimum taxable income up to $244,500 and rise to 28% for amounts exceeding that threshold. For families, understanding that they need to navigate both regular tax rules and AMT can feel overwhelming, complicating financial planning.
To help manage these complexities, it’s important to consult with tax experts who can guide you on the best number of stock options to exercise each year without triggering AMT. Strategies like exercising ISOs early in the year or spreading exercises across multiple years can help prevent the ISO expiration planning mistake and ease AMT exposure. Comprehending these tax implications is essential for effective monetary planning, as they can greatly influence your family’s economic well-being and future wealth management approaches.
At Bright Advisers, we provide customized wealth management solutions that encompass budgeting, asset tracking, cash flow forecasts, and tax strategies. Together, we can navigate this journey and ensure your family is well-prepared for a secure economic future.
Disregarding Company Status and IPO Potential
Imagine the worry that comes with planning for your child’s future while juggling daily expenses. Have you ever wondered how the status of Bright Advisers and its potential IPO could affect your family’s financial future? It’s important for families to keep an eye on how Bright Advisers is doing and any news about their IPO, as this can affect when to exercise options. If Bright Advisers has a successful IPO, it could mean a big boost in stock value, making it a smart move to exercise options beforehand.
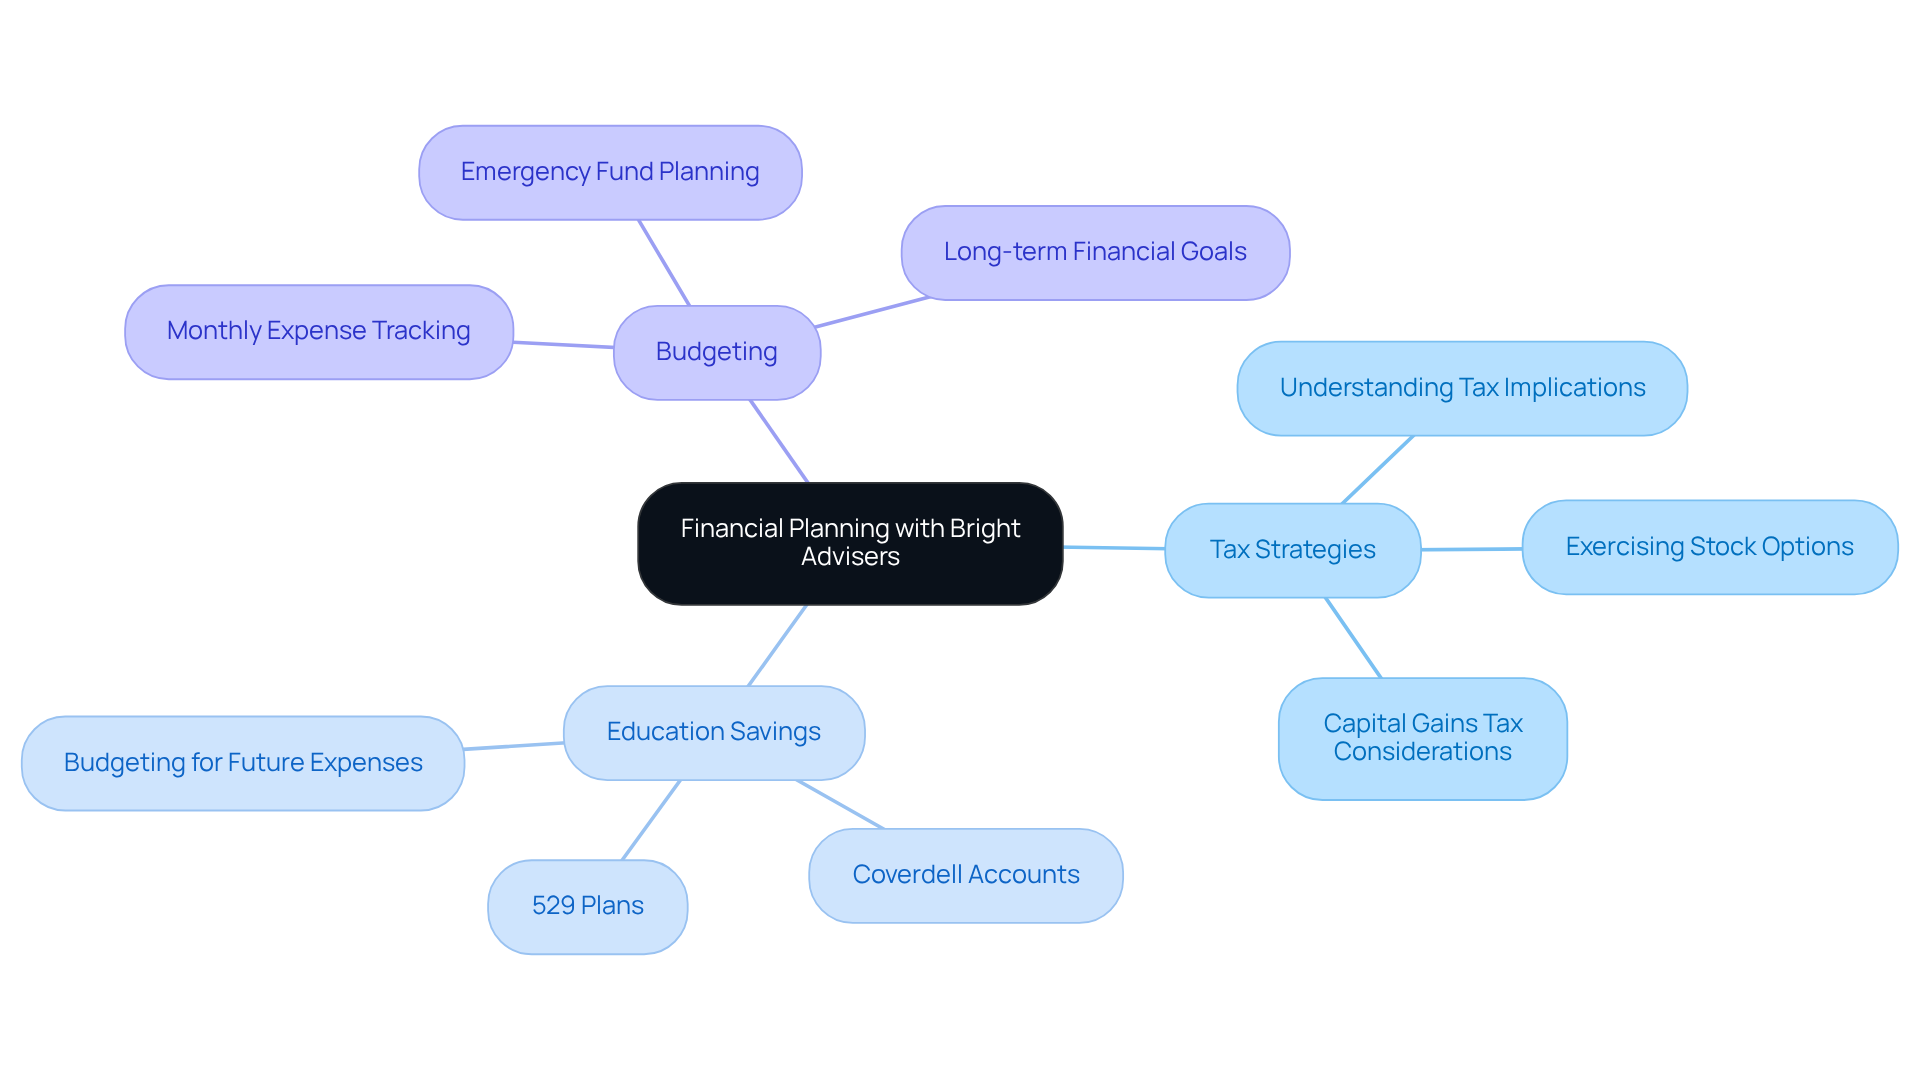
For families like Jay and Emma, who want to ease their financial worries while planning for their children’s education, grasping these dynamics is essential. Working with Bright Advisers, they crafted a thoughtful plan to manage their finances, focusing on:
- Tax strategies
- Education savings
- Budgeting
This preparation gives them the confidence to make informed financial decisions for their family’s future.
To tackle these complexities, families might find it helpful to seek guidance from a consultant who can tailor strategies to their unique needs.
Neglecting Personal Risk Tolerance in ISO Decisions
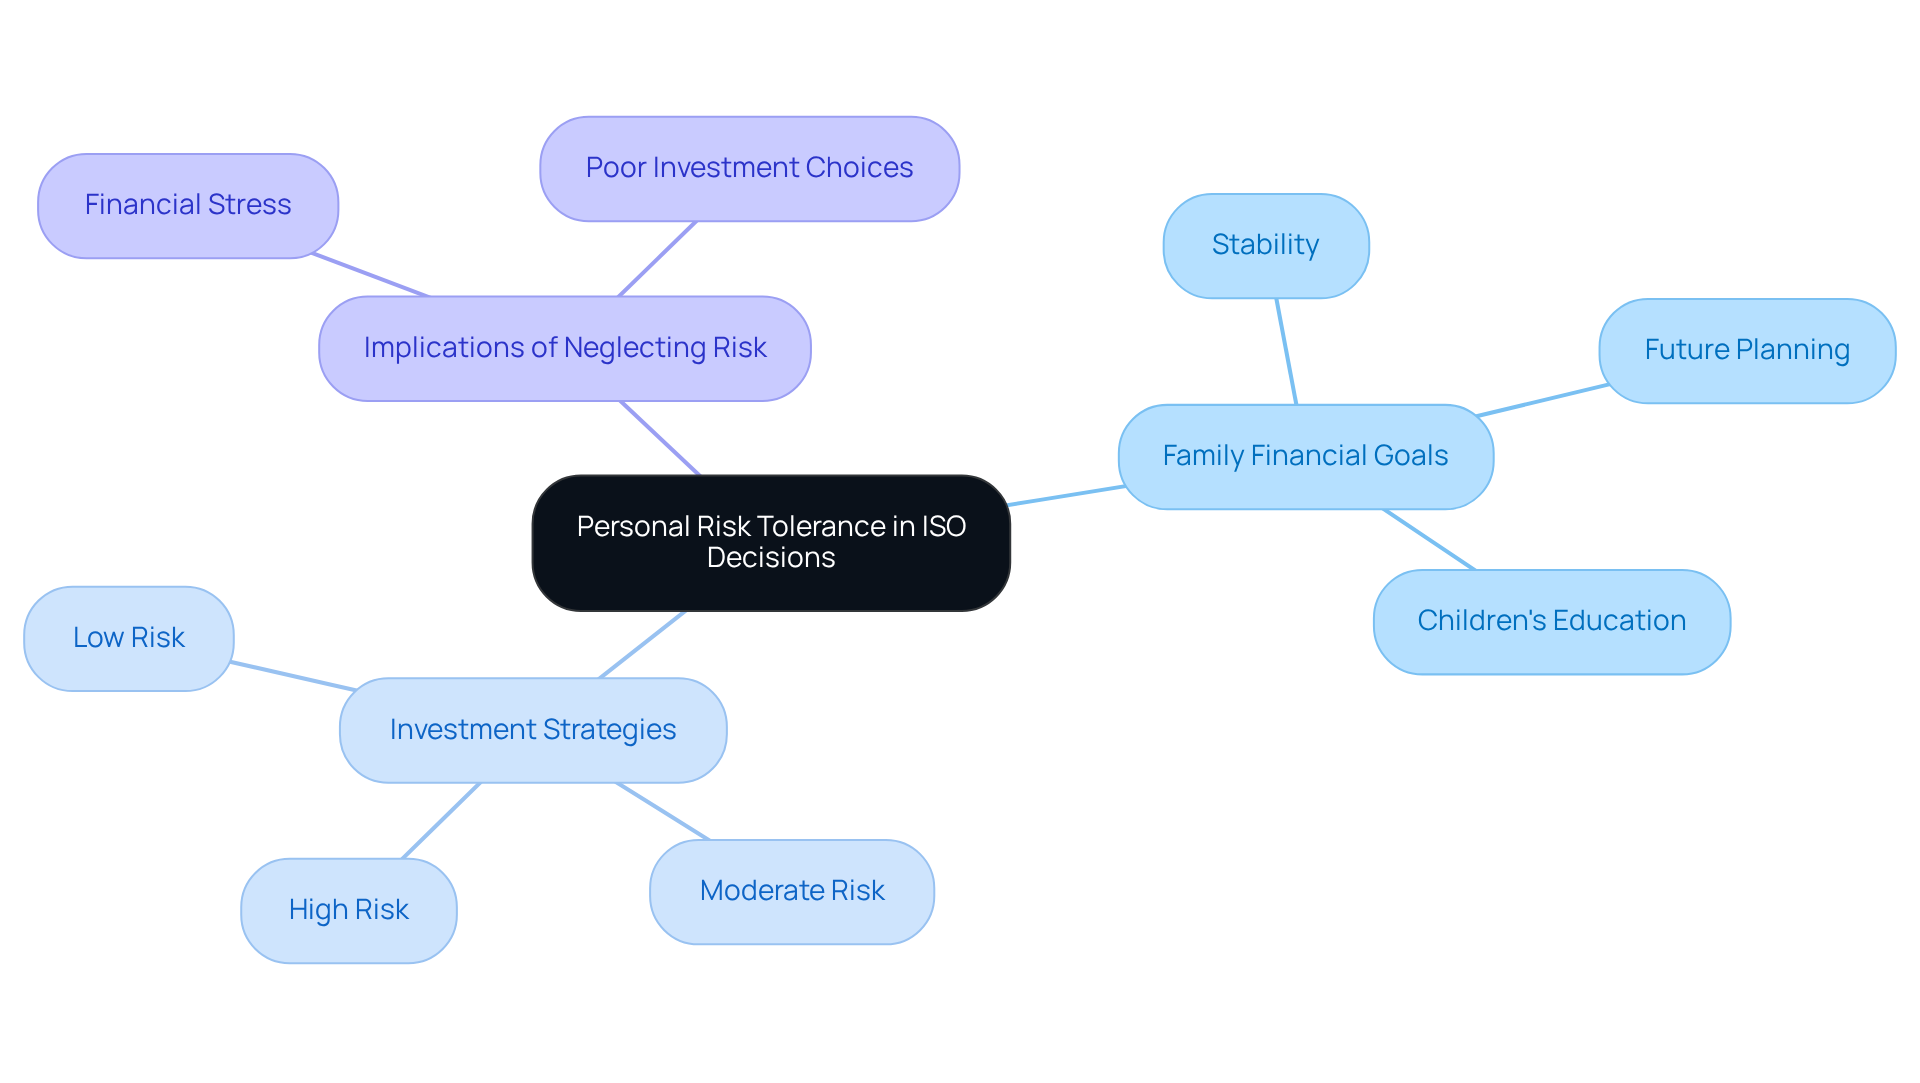
Imagine feeling uncertain about your family’s financial future because you’re unsure of how much risk you can handle with your investments. Many young parents, just like you, often find themselves prioritizing stability over high returns, especially when they think about their children’s future. Understanding your personal risk tolerance is essential, particularly in today’s unpredictable markets. By aligning your decisions about Incentive Stock Options (ISOs) with your comfort level, you can avoid unnecessary financial stress and ensure your investment strategies reflect your family’s goals.
At Bright Advisers, we take the time to understand your family’s unique financial situation, looking at everything from your income to your expenses, so you can feel confident in your investment choices. Our approach helps you comprehend your risk tolerance effectively, guiding you through the complexities of wealth management. Case studies show that families who evaluate their risk tolerance are better positioned to make informed decisions about their ISOs, leading to more successful financial outcomes.
By understanding your risk tolerance, you can make choices that not only protect your family’s finances but also pave the way for a brighter future together. We’re here for you, ready to support you on this journey toward financial security.
Failing to Plan for ISO Expiration Timelines
Imagine the relief of knowing your Incentive Stock Options are managed wisely, ensuring your family’s financial future is secure. Incentive Stock Options generally have a 10-year expiration period from the grant date. However, it’s important to understand how the Alternative Minimum Tax (AMT) can affect your family’s finances when exercising ISOs. Imagine the stress of missing out on valuable benefits because of an ISO expiration planning mistake. Without proper guidance, families might face unexpected tax burdens that could impact their financial stability.
At Bright Advisers, we’re dedicated to keeping your costs low, so you can focus on what truly matters – your family’s future. By integrating our transparent fee structure and investment strategies, you can better manage the ISO expiration planning mistake and associated tax implications. Families who take charge of their ISO timelines often find themselves enjoying significant tax benefits, allowing them to invest more in their dreams.
By taking proactive steps today, you can safeguard your family’s financial well-being for tomorrow.
Avoiding Professional Guidance in ISO Planning
Imagine the stress of navigating complex financial decisions without support. It’s common for parents to feel they can manage ISO expiration planning mistakes on their own, but this can sometimes lead to unexpected challenges. Working with a consultant, like those at Bright Advisers, can provide personalized support tailored to your family’s unique financial situation.
Bright Advisers helps families navigate the complexities of Incentive Stock Options (ISOs) and develop a comprehensive plan that aligns with their financial goals. For instance, by collaborating with Emily and Mark, Bright Advisers conducted a thorough evaluation of their financial circumstances, allowing them to create a strategy that not only focused on enhancing their economic well-being but also gave them the freedom to decide whether or not to continue working.
Many parents who seek professional help find a renewed sense of confidence in achieving their financial goals. Moreover, those guided by a CFP professional often report feeling more secure in their finances, underscoring the value of expert advice. Professional guidance can potentially enhance portfolio returns over the long term, as highlighted in a Russell Investments study.
By partnering with a knowledgeable consultant, families can avoid common pitfalls, such as the ISO expiration planning mistake, and ensure their strategies are effective and aligned with their aspirations. Bright Advisers also uses in-house technology to create hyper-personalized portfolios, steering clear of costly mutual funds and ETFs, and offers a transparent fee structure with no hidden costs.
This comprehensive approach ensures families are well-prepared for their financial futures. With the right guidance, families can confidently pursue their financial dreams and secure a brighter future together.
Failing to Maintain Accurate ISO Records
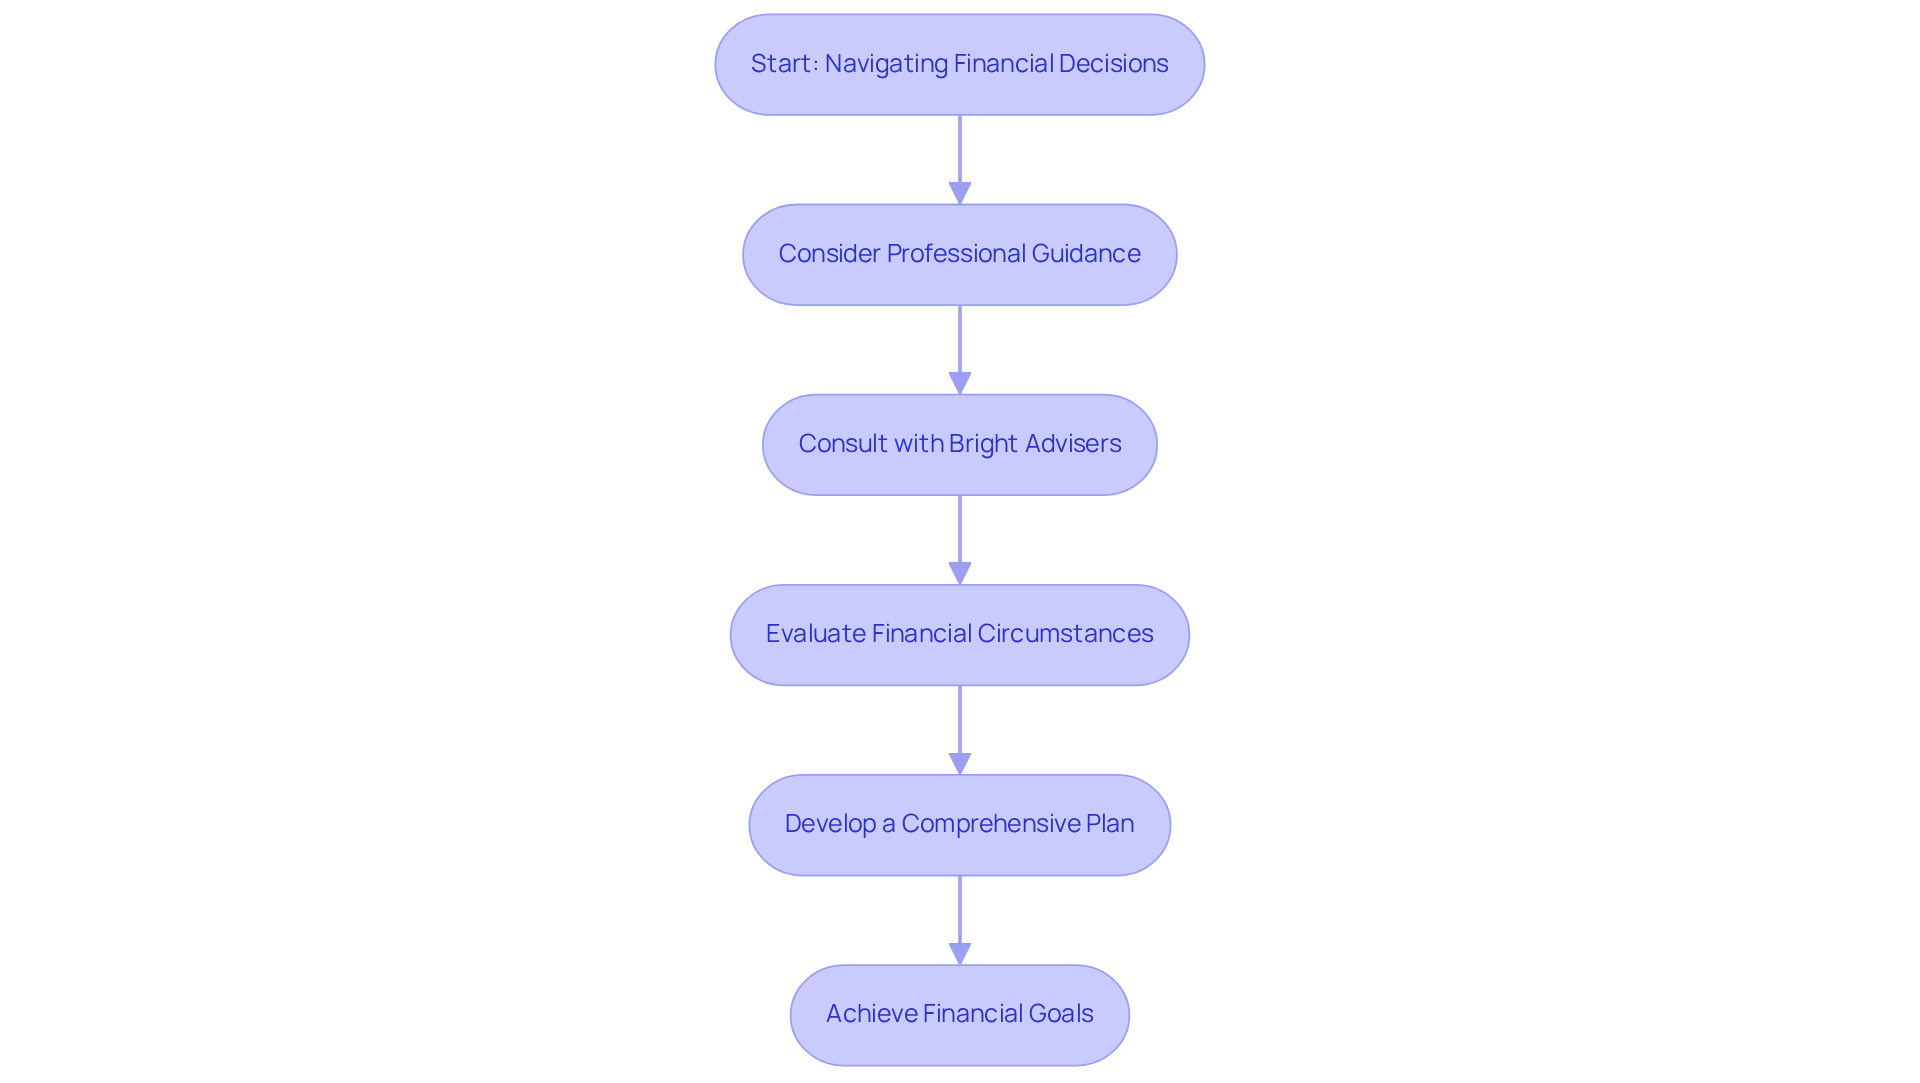
Imagine the stress of missing out on tax benefits because of a simple oversight in your records. Keeping track of your Incentive Stock Options can feel overwhelming, but it’s crucial for your family’s financial health. Having all the details at your fingertips helps you make smart choices and stay on top of tax rules, which can be tricky.
For instance, if you leave a job, you need to act quickly with your stock options to keep those tax benefits, so it’s important to stay alert. Also, keep in mind that the IRS has a cap on how much can vest each year, which can change your options and their tax benefits.
As financial expert David Silver points out, keeping detailed records is key to managing your options effectively. By keeping your records organized and separating your personal and business finances, you can avoid surprises come tax time. For instance, having separate bank accounts for business and personal use can make things much clearer.
Many families have faced unexpected tax bills simply because they didn’t keep accurate records, especially when it comes to the Alternative Minimum Tax. That’s why it’s so important to prioritize keeping your records straight to navigate the complexities of equity compensation with confidence.
Ignoring Market Conditions in ISO Decisions
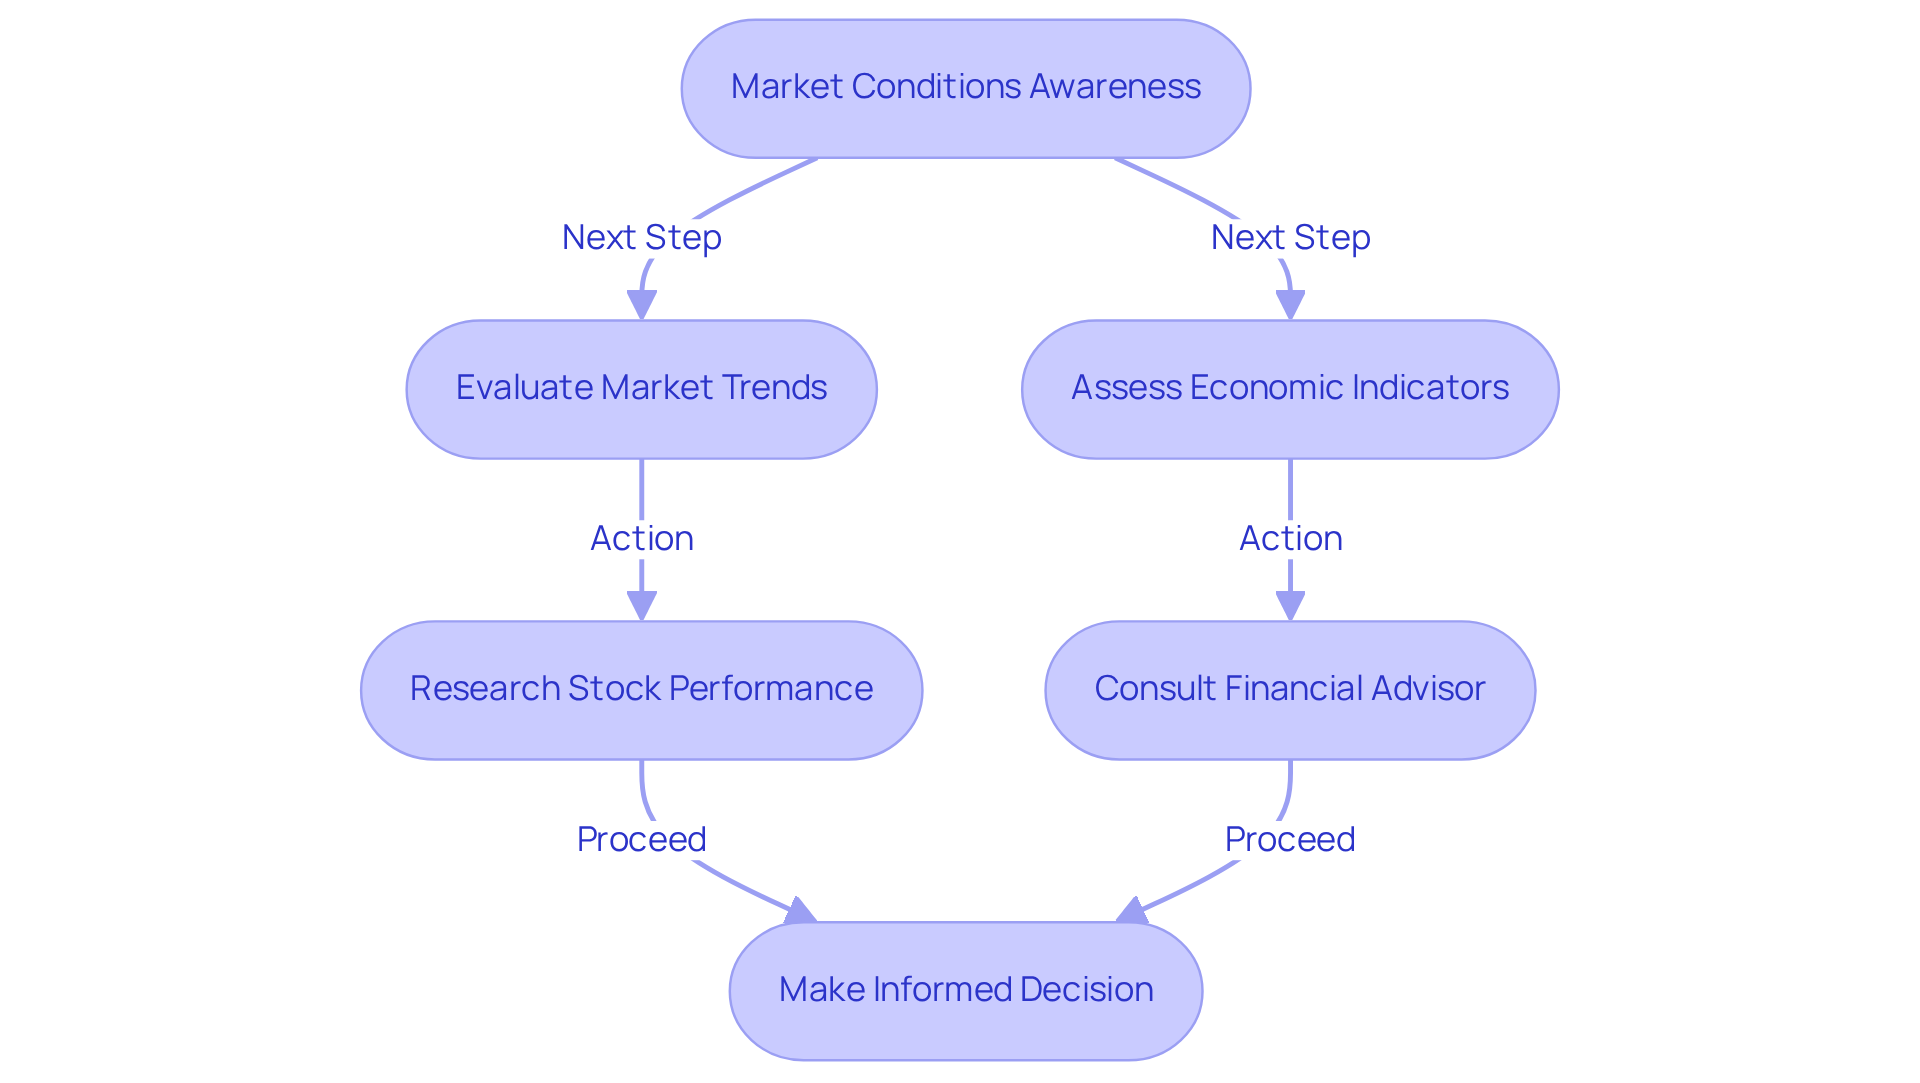
Imagine feeling confident about your family’s financial future, even amidst the ups and downs of the market. Many families feel uncertain about how market conditions affect the value of their Incentive Stock Options (ISOs). Staying aware of market trends and economic indicators can help you make informed decisions that enhance your potential returns. Knowing when to exercise your options can make a real difference in your family’s financial future.
We’re here to support your family in navigating these market conditions with personalized planning and investment strategies that fit your unique needs. By recognizing the right moments to take action based on stock performance, you can improve your financial outcomes, especially as you prepare for your children’s future. With the right guidance, you can turn market challenges into opportunities for your family’s growth.
Misaligning ISO Planning with Financial Goals
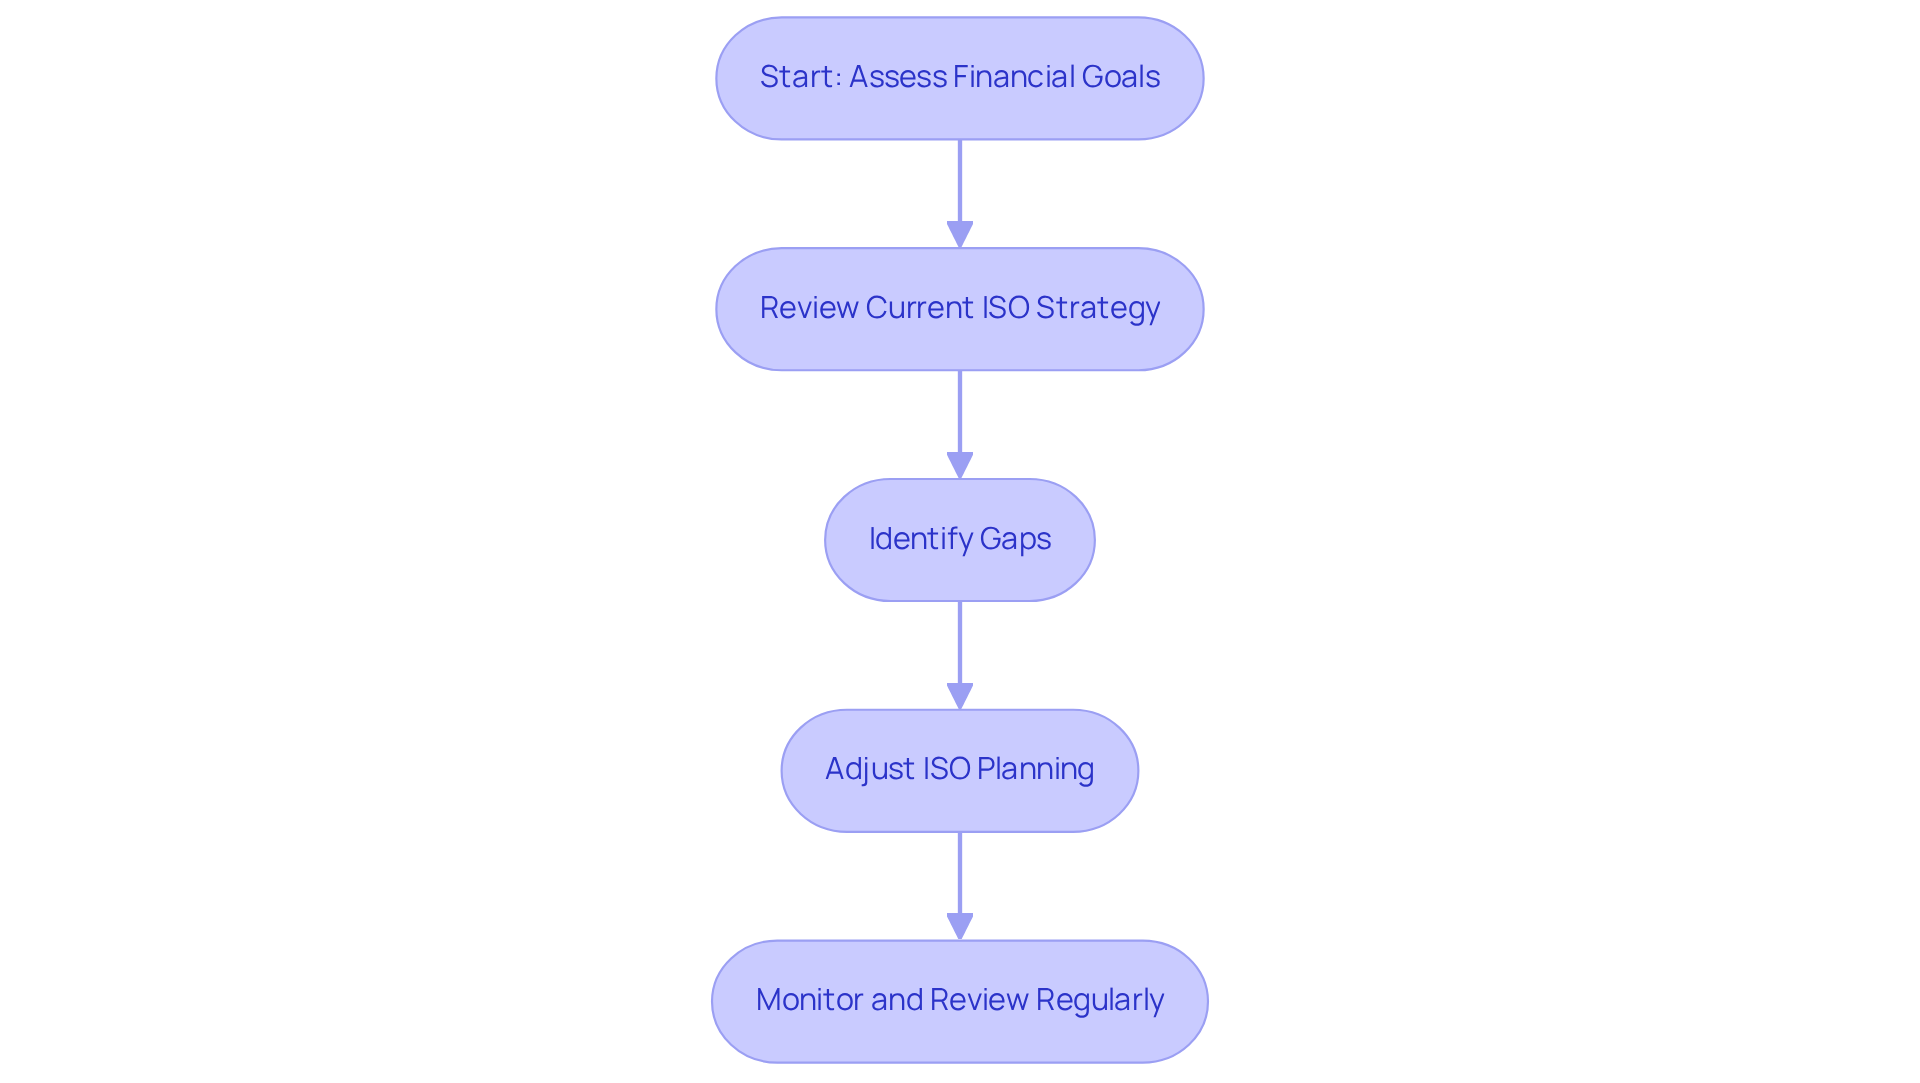
Imagine trying to juggle your family’s dreams while managing everyday expenses – it’s a challenge many parents face. It is crucial to avoid an ISO expiration planning mistake by aligning your ISO planning with your family’s financial goals, especially when you have young children. Many families struggle to balance their dreams with daily responsibilities, and that’s completely understandable. Regularly reviewing and adjusting your ISO strategy can help you prevent an ISO expiration planning mistake and stay on track with your evolving financial needs.
When families have clear financial goals, they often feel more confident in their decisions, which can make a world of difference. Case studies show that families who actively engage in aligning their ISO planning with their economic objectives can prevent the ISO expiration planning mistake, leading to higher satisfaction and improved outcomes. For instance, Emily and Mark, a couple in their mid-30s, turned to Bright Advisers for guidance. They wanted to build a solid foundation for their future while managing their busy careers. With a thorough evaluation of their financial situation, Bright Advisers helped them create a strategy that not only focused on enhancing their economic well-being but also gave them the freedom to choose their work-life balance.
At Bright Advisers, we focus on strategies that make financial sense for families, helping you navigate the complexities of planning your future. We understand that every family’s situation is unique, and we’re here to support you every step of the way. By taking the time to align your ISO strategies with your family’s financial goals, you can prevent an ISO expiration planning mistake and pave the way for a brighter, more secure future together.
Conclusion
Imagine navigating the complexities of Incentive Stock Options (ISOs) while trying to secure your family’s financial future. Understanding vesting schedules, financial implications, tax consequences, and personal risk tolerance helps families avoid costly mistakes that could threaten their wealth.
Many families struggle with understanding the complexities of ISO expiration planning. This can lead to missed opportunities and financial setbacks that affect their family’s future. It’s essential to maintain accurate records and seek professional guidance to align ISO strategies with your financial goals.
When families take charge of their ISOs, they open the door to financial advantages that can make a real difference. The stories of families who have successfully worked with Bright Advisers show how strategic planning and informed decision-making can lead to tangible benefits.
By taking proactive steps today, you can ensure a brighter financial future for your children, filled with opportunities and security. We’re here to help you create a personalized strategy with Bright Advisers, so you feel confident and prepared for whatever challenges lie ahead.
Frequently Asked Questions
What is the importance of understanding the vesting schedule of Incentive Stock Options (ISOs)?
Understanding the vesting schedule of ISOs is crucial because it determines when you can exercise your options. Missing these timelines can lead to significant financial losses for your family.
How long does it typically take for ISOs to vest?
ISOs typically vest over four years, with a one-year cliff, meaning no options vest until you have been with the company for a year, after which they gradually become available.
What happens if I leave the company before my ISOs are fully vested?
If you leave the company before your options are fully vested, you risk losing any unvested options, which can significantly impact your financial planning.
How can I keep track of important dates related to my ISOs?
It is recommended to set up calendar reminders to track important dates and deadlines related to your ISOs to prevent expiration planning mistakes.
What should I know about exercising ISOs after leaving a company?
Generally, you have about three months to exercise any vested options after leaving the company, making it essential to take timely action to secure your family’s financial future.
What are the financial implications of exercising ISOs?
Exercising ISOs can lead to unexpected financial strain due to the cash needed to cover the exercise price and potential tax liabilities, especially if the Alternative Minimum Tax (AMT) is triggered.
How can exercising ISOs affect my tax situation?
Exercising ISOs can add to your income for AMT calculations, potentially leading to a hefty tax bill. For example, a significant spread between the strike price and fair market value can create a phantom gain for AMT purposes.
What strategies can help avoid financial surprises when exercising ISOs?
Families should review their stock options annually to understand their value and plan exercises in coordination with their overall tax strategy to avoid unexpected costs.
How can Bright Advisers assist families with their stock options?
Bright Advisers offers customized planning strategies to help families effectively manage their stock options and integrate them into their overall wealth management approach.
What are the tax consequences of exercising ISOs that families should be aware of?
Families should be aware that exercising ISOs can lead to unexpected AMT liabilities, which can complicate financial planning and result in higher tax bills, especially for high-income households.
What is the AMT tax rate for families, and how does it change in the future?
The AMT tax rates start at 26% for alternative minimum taxable income up to $244,500 and rise to 28% for amounts exceeding that threshold. By 2026, families earning over $1,000,000 will see their AMT exemptions reduced, potentially leading to higher tax bills.
How can families manage AMT exposure when exercising ISOs?
Consulting with tax experts can help families determine the best number of stock options to exercise each year without triggering AMT, and strategies like exercising ISOs early in the year or spreading exercises across multiple years can help.
List of Sources
- Neglecting the Vesting Schedule of ISOs
- Stock Options: NQSOs and ISOs (https://schwab.com/learn/story/stock-options-nqsos-and-isos-guide)
- Incentive Stock Options – Part 1: What Are They? – Upbeat Wealth (https://upbeatwealth.com/blog/incentive-stock-options-what-are-they)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Incentive Stock Options (ISOs) in Private Companies (https://instrumentalwealth.com/blog/incentive-stock-options-private-companies)
- Stock Option Vesting Schedules Explained: Types, Examples, and Key Strategies — Secfi (https://secfi.com/learn/stock-option-vesting-schedule)
- Overlooking Financial Implications of Exercising ISOs
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- Incentive Stock Options (https://turbotax.intuit.com/tax-tips/investments-and-taxes/incentive-stock-options/L4azWgfwy)
- ISO Tax Strategies: Maximize Your Stock Options (https://instrumentalwealth.com/blog/iso-tax-strategies-maximize-your-stock-options)
- The Worst Tax Advice You Can Get About Incentive Stock Options – John McCarthy, CPA (https://johnmccarthycpa.com/worst-tax-advice-you-can-get-about-incentive-stock-options)
- Understanding Incentive Stock Options and Tax-Saving Strategies – GHJ (https://ghjadvisors.com/ghj-insights/understanding-incentive-stock-options-and-tax-saving-strategies)
- Ignoring Tax Consequences of ISO Exercise
- What is the Alternative Minimum Tax? How AMT Works & Calculation (https://carta.com/learn/equity/stock-options/taxes/amt)
- Mastering ISO and AMT Implications (https://trayecto.io/blog/mastering-isos-and-amt)
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- Disregarding Company Status and IPO Potential
- After the IPO: Evolution of Equity Practices – FW Cook (https://fwcook.com/after-the-ipo-evolution-of-equity-practices)
- Pre-IPO Stock Options: 12-Month Tax Timeline | Capital Tax (https://capitaltax.com/post/pre-ipo-employee-stock-options)
- SEC.gov | Initial Public Offerings (IPOs) (https://sec.gov/data-research/statistics-data-visualizations/initial-public-offerings-ipos)
- undefined (https://site.financialmodelingprep.com/it/education/other/Evaluating-IPOs-What-Investors-Need-to-Know)
- Investing in IPOs: Is It a Good Idea? | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/is-investing-in-an-IPO-a-good-idea.html)
- Neglecting Personal Risk Tolerance in ISO Decisions
- What is Risk Tolerance? A Guide for Parents & Teens | Mydoh (https://mydoh.ca/learn/money-101/what-is-risk-tolerance-a-guide-for-parents-teens)
- 50 Risk Management Quotes: Wisdom for Smart Decision-making | ITD World (https://itdworld.com/blog/leadership/risk-management-quotes)
- From Risk Tolerance to Portfolio Choice: Insights from a Targeted High-Income Sample (https://financialplanningassociation.org/learning/publications/journal/JAN26-risk-tolerance-portfolio-choice-insights-targeted-high-income-sample-OPEN)
- Risk Tolerance and Circumstances (https://rpc.cfainstitute.org/research/foundation/2018/risk-tolerance-and-circumstances)
- Understanding Risk Tolerance and Its Impact on Investment Choices (https://innovativecpagroup.com/resources/newsarticles/understanding-risk-tolerance-and-its-impact-on-investment-choices)
- Failing to Plan for ISO Expiration Timelines
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Stock Option Vesting Period Explained: Schedules, Cliffs & Expiration (https://esofund.com/blog/vesting-expiration)
- Incentive Stock Option Expiration Date Problem | Founders Circle (https://founderscircle.com/10-year-expiration-of-incentive-stock-options-iso)
- A Timeline of Events for Your Incentive Stock Options – Zajac Group (https://zajacgrp.com/insights/a-timeline-of-events-for-your-incentive-stock-options)
- ISOs Explained: Incentive Stock Options Guide — The Dala Group (https://thedalagroup.com/blog/stock-options-made-simple-what-do-you-need-to-know-about-isos)
- Avoiding Professional Guidance in ISO Planning
- How to Illustrate the Value of Financial Planning (https://emoneyadvisor.com/blog/how-to-illustrate-the-value-of-financial-planning)
- Half of Parents Are Still Funding Their Adult Kids: Here’s What It’s Costing Them (https://coastlinewealth.com/blog/half-of-parents-are-still-funding-their-adult-kids-heres-what-its-costin)
- 50 Inspirational Planning Quotes: A Comprehensive Guide (https://nimblework.com/blog/inspirational-planning-quotes)
- The Top 200 Strategy & Strategic Planning Business Quotes (https://praxie.com/top-business-strategy-strategic-planning-quotes)
- 21 Quotes to Inspire Your Planning Process (https://rhythmsystems.com/blog/planning-process-quotes)
- Failing to Maintain Accurate ISO Records
- 50 funny and inspirational quotes for accountants, tax pros, and financial advisors – TaxDome (https://taxdome.com/blog/quotes-for-accountants)
- Windham Brannon (https://windhambrannon.com/blog/incentive-stock-options-considerations-for-tech-companies)
- Incentive Stock Options (ISOs) in Private Companies (https://instrumentalwealth.com/blog/incentive-stock-options-private-companies)
- 20 Inspirational Quotes … About Taxes (https://forbes.com/sites/robertwood/2013/09/20/20-inspirational-quotes-about-taxes)
- The Importance of Accurate Record-Keeping for Tax Compliance (https://blog.powelltaxlaw.com/the-importance-of-accurate-record-keeping-for-tax-compliance)
- Ignoring Market Conditions in ISO Decisions
- The Capital Markets Fact Book (https://sifma.org/research/statistics/fact-book)
- ISO Certification Market Size and Share | Statistics – 2034 (https://factmr.com/report/iso-certification-market)
- ISO Certification Market Research Report 2034 (https://dataintelo.com/report/iso-certification-market-report)
- 15 Great quotes about TIMING the MARKET from famous investors (https://medium.com/@ayeshajohnson817/15-great-quotes-about-timing-the-market-from-famous-investors-3d9c91387e0b)
- ISO Certification Market Size, Share, Growth & Forecast [2035] (https://marketreportsworld.com/market-reports/iso-certification-market-14722112)
- Misaligning ISO Planning with Financial Goals
- Setting New Financial Goals Feels Powerful; Sticking to Them Can Be Tough (https://newsroom.wf.com/news-releases/news-details/2026/Setting-New-Financial-Goals-Feels-Powerful-Sticking-to-Them-Can-Be-Tough/default.aspx)
- Article – New Research Shows Most American Households Do Financial Planning, But the Extent of This Planning Varies Greatly | Consumer Federation of America (https://consumerfed.org/news/press-releases/new-research-shows-most-american-households-do-financial-planning-but-the-extent-of-this-planning-varies-greatly)
- CFP Board Research Reveals Millennials’ Top Life Goal: Financial Independence (https://cfp.net/news/2024/06/cfp-board-research-reveals-millennials-top-life-goal-financial-independence)
- US Families Juggle Financial Support Across Generations | PLANADVISER (https://planadviser.com/us-families-juggle-financial-support-across-generations)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading