

Overview
This article presents ten effective strategies designed specifically for young families aiming to lower their Adjusted Gross Income (AGI). Imagine maximizing your contributions to retirement accounts, utilizing Health Savings Accounts (HSAs), and taking full advantage of education credits. Each method is supported by practical examples and financial reasoning, showing how these strategies can significantly reduce tax liabilities and enhance your family’s overall financial well-being.
As you explore these strategies, consider the positive impact they can have on your family’s future. By implementing these approaches, you’ll not only ease your financial burden but also create a foundation for lasting security and peace of mind. We understand that navigating financial matters can feel overwhelming, but together, we can make this journey manageable.
Each of these strategies is designed with your family values in mind, ensuring that you can prioritize what truly matters. From saving for your children’s education to securing your retirement, these methods are tailored to support your unique needs. Remember, we’re here for you every step of the way.
Take a moment to reflect on how these strategies could transform your financial landscape. It’s important to understand that by taking action now, you are investing in your family’s future. Let’s navigate this journey together, ensuring that your financial choices align with your family’s aspirations.
Key Highlights:
- Bright Advisers offers customised financial strategies to help families lower their AGI.
- Key methods include maximising contributions to retirement accounts, such as 401(k)s and HSAs, which provide tax benefits.
- Health Savings Accounts (HSAs) allow families to save pre-tax funds for medical expenses, reducing AGI.
- Pre-tax 401(k) contributions can lower AGI while building retirement savings, with potential employer matching contributions.
- Deductible Traditional IRAs enable families to save for retirement while potentially lowering AGI through tax deductions.
- Tax-loss harvesting helps offset gains by selling underperforming investments, improving overall tax efficiency.
- Education credits like the American Opportunity Tax Credit (AOTC) and Lifetime Learning Credit (LLC) can significantly reduce tax obligations for families with students.
- Strategically managing capital gains by holding investments longer can lower AGI due to reduced tax rates on long-term gains.
- Required Minimum Distributions (RMDs) must be planned to avoid increasing AGI; strategies include converting to Roth IRAs and utilising Qualified Charitable Distributions (QCDs).
- Municipal bonds provide tax-exempt interest income, making them a favourable investment for lowering AGI.
- Families should regularly assess their financial situations and adjust withholding allowances to avoid common pitfalls that can increase AGI.
Introduction
Lowering Adjusted Gross Income (AGI) is an essential financial strategy for young families seeking to enhance their economic stability and tax efficiency. Imagine if you could take control of your finances and create a brighter future for your loved ones. By exploring tailored approaches, families can discover effective methods to reduce their AGI, ultimately leading to significant savings and improved financial health.
However, with so many options available, it’s important to navigate these strategies carefully. How can families ensure they are maximizing their benefits while avoiding common pitfalls? This article delves into ten impactful ways to lower AGI, providing insights that empower families to take charge of their financial journey.
Together, we can explore these strategies, ensuring that your family’s values and priorities are at the forefront of every decision. We’re here for you, guiding you through each step of this process, so you can focus on what truly matters—your family.
Bright Advisers: Tailored Financial Planning to Lower AGI
At Bright Advisers, we understand that every family has unique financial needs. Our client-first approach is designed to create customized monetary strategies that offer ways to lower AGI for households. Imagine navigating the complex world of finances with a trusted partner by your side. By utilizing cutting-edge technology alongside tailored strategies, we empower families to traverse intricate economic environments with confidence.
This journey begins with a thorough evaluation of your income sources, potential deductions, and tax-efficient investment options. Our goal is to help you prioritize your financial objectives while ensuring a secure future for your children. For instance, contributions to retirement accounts like 401(k)s and Health Savings Accounts (HSAs) are among the best ways to lower AGI, allowing families to optimize their tax benefits.
We believe that education is a vital part of financial literacy. That’s why Bright Advisers offers a wealth of educational materials, including 30 on-demand interactive lessons. These resources are designed to teach your children about money management and wise financial choices, fostering a culture of financial literacy at home.
Our commitment to transparency and accessibility simplifies the implementation of these strategies. We want you to make informed decisions that align with your long-term monetary goals. As financial advisors often emphasize, understanding ways to lower AGI is crucial for families striving to improve their tax situations and overall financial well-being. Remember, we’re here for you, and together, we can navigate this journey toward a brighter financial future.
Health Savings Account (HSA): Maximize Contributions for AGI Reduction
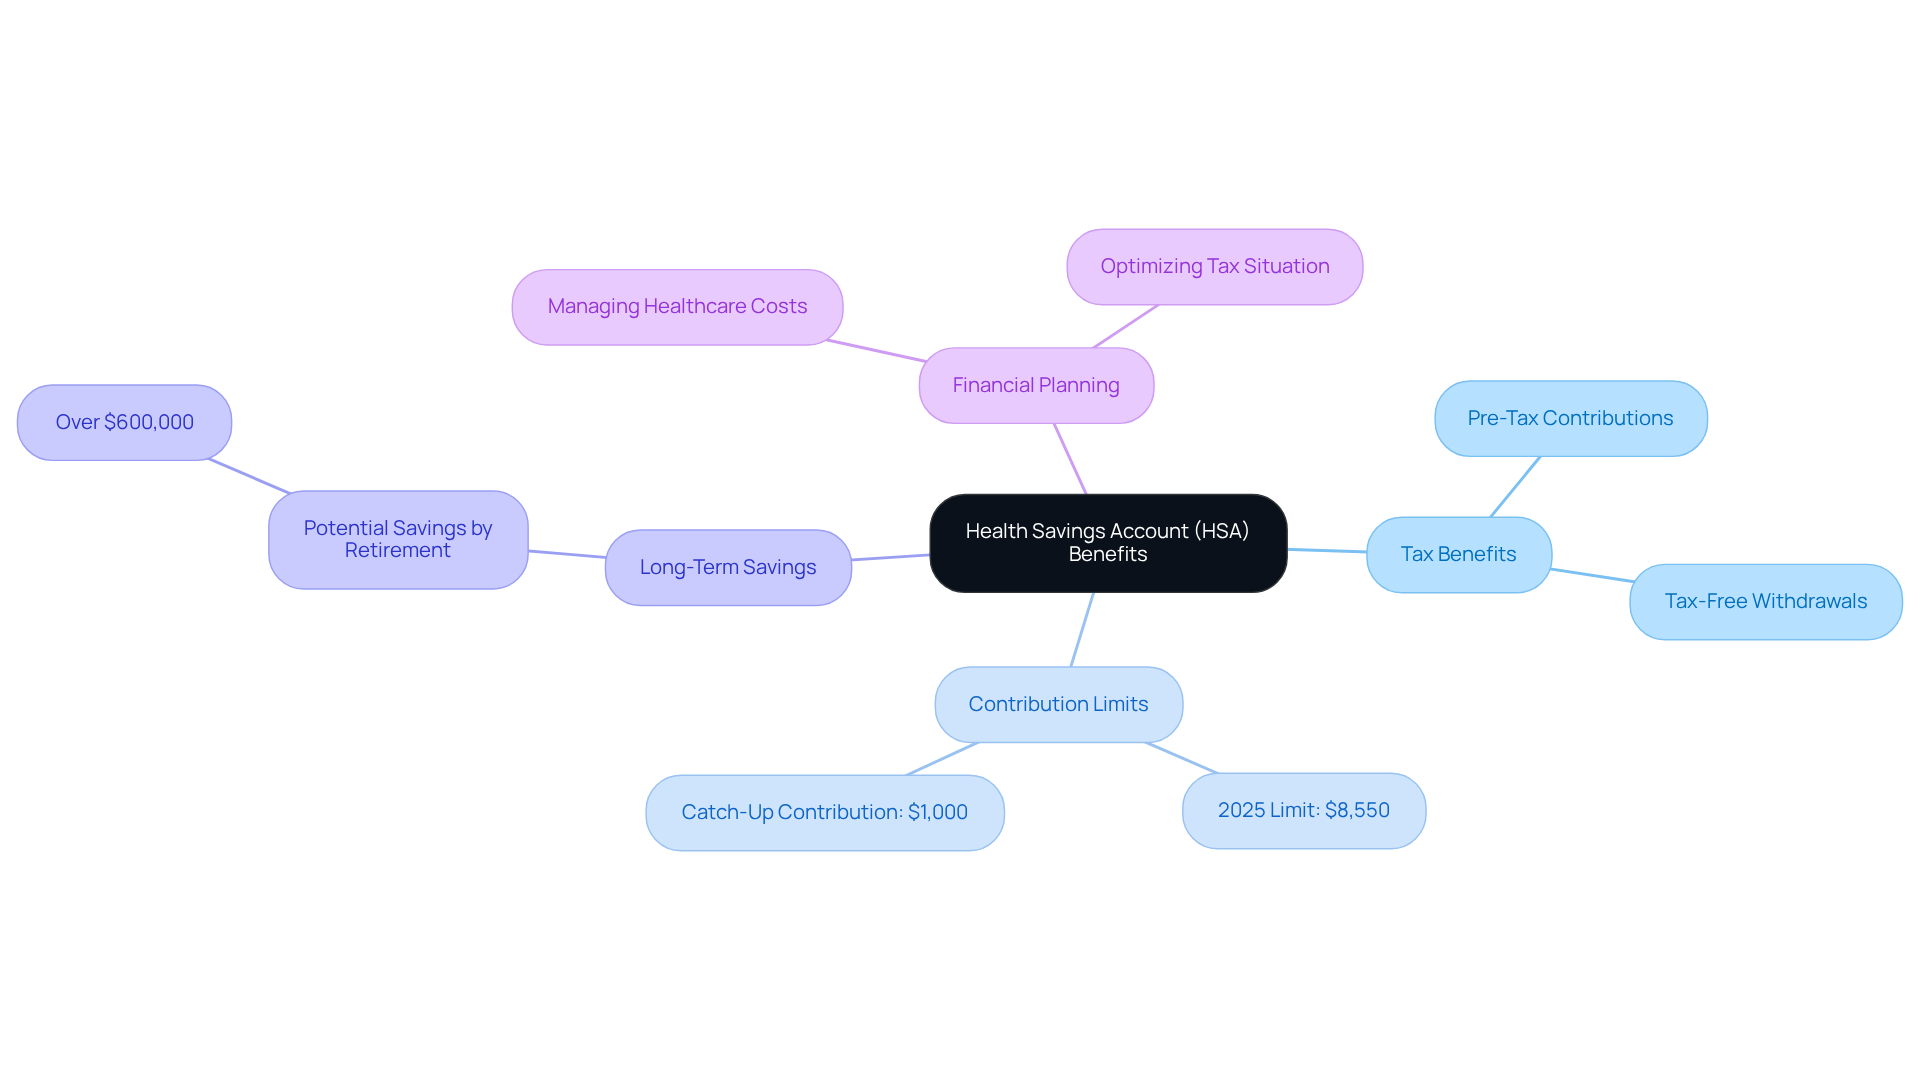
Health Savings Accounts (HSAs) offer a caring solution for families looking to manage their medical expenses wisely. By allowing households to set aside pre-tax funds, HSAs present effective ways to lower AGI, making it easier to navigate financial responsibilities. In 2025, families with a high-deductible health plan can contribute up to $8,550, which includes an extra $1,000 catch-up contribution for individuals aged 55 and older. This means that not only are contributions tax-deductible, but withdrawals for qualified medical expenses are tax-free, creating a wonderful dual-benefit opportunity.
Imagine a family that maximizes its HSA contributions. They can lower their taxable income while building a safety net for future healthcare costs. This approach not only alleviates immediate financial pressures but also offers ways to lower AGI by preparing families for potential medical expenses down the road.
Tax experts emphasize the unique advantages of HSAs, highlighting how they allow individuals to manage healthcare costs while optimizing their tax situation. By embracing HSAs, families can tackle the complexities of healthcare expenses with confidence, ensuring they prioritize both their financial well-being and the health of their loved ones.
Furthermore, HSAs can have a lasting impact on a family’s financial landscape. Consider a couple in their 40s who consistently contributes to their HSA; they could save over $600,000 for healthcare by the time they retire. This potential for long-term savings underscores the importance of HSAs as a vital part of a comprehensive financial plan for young families.
Together, we can navigate this journey toward financial security, ensuring that your family’s future is as bright as possible.
Pre-Tax 401(k) Contributions: A Strategic Move to Lower AGI
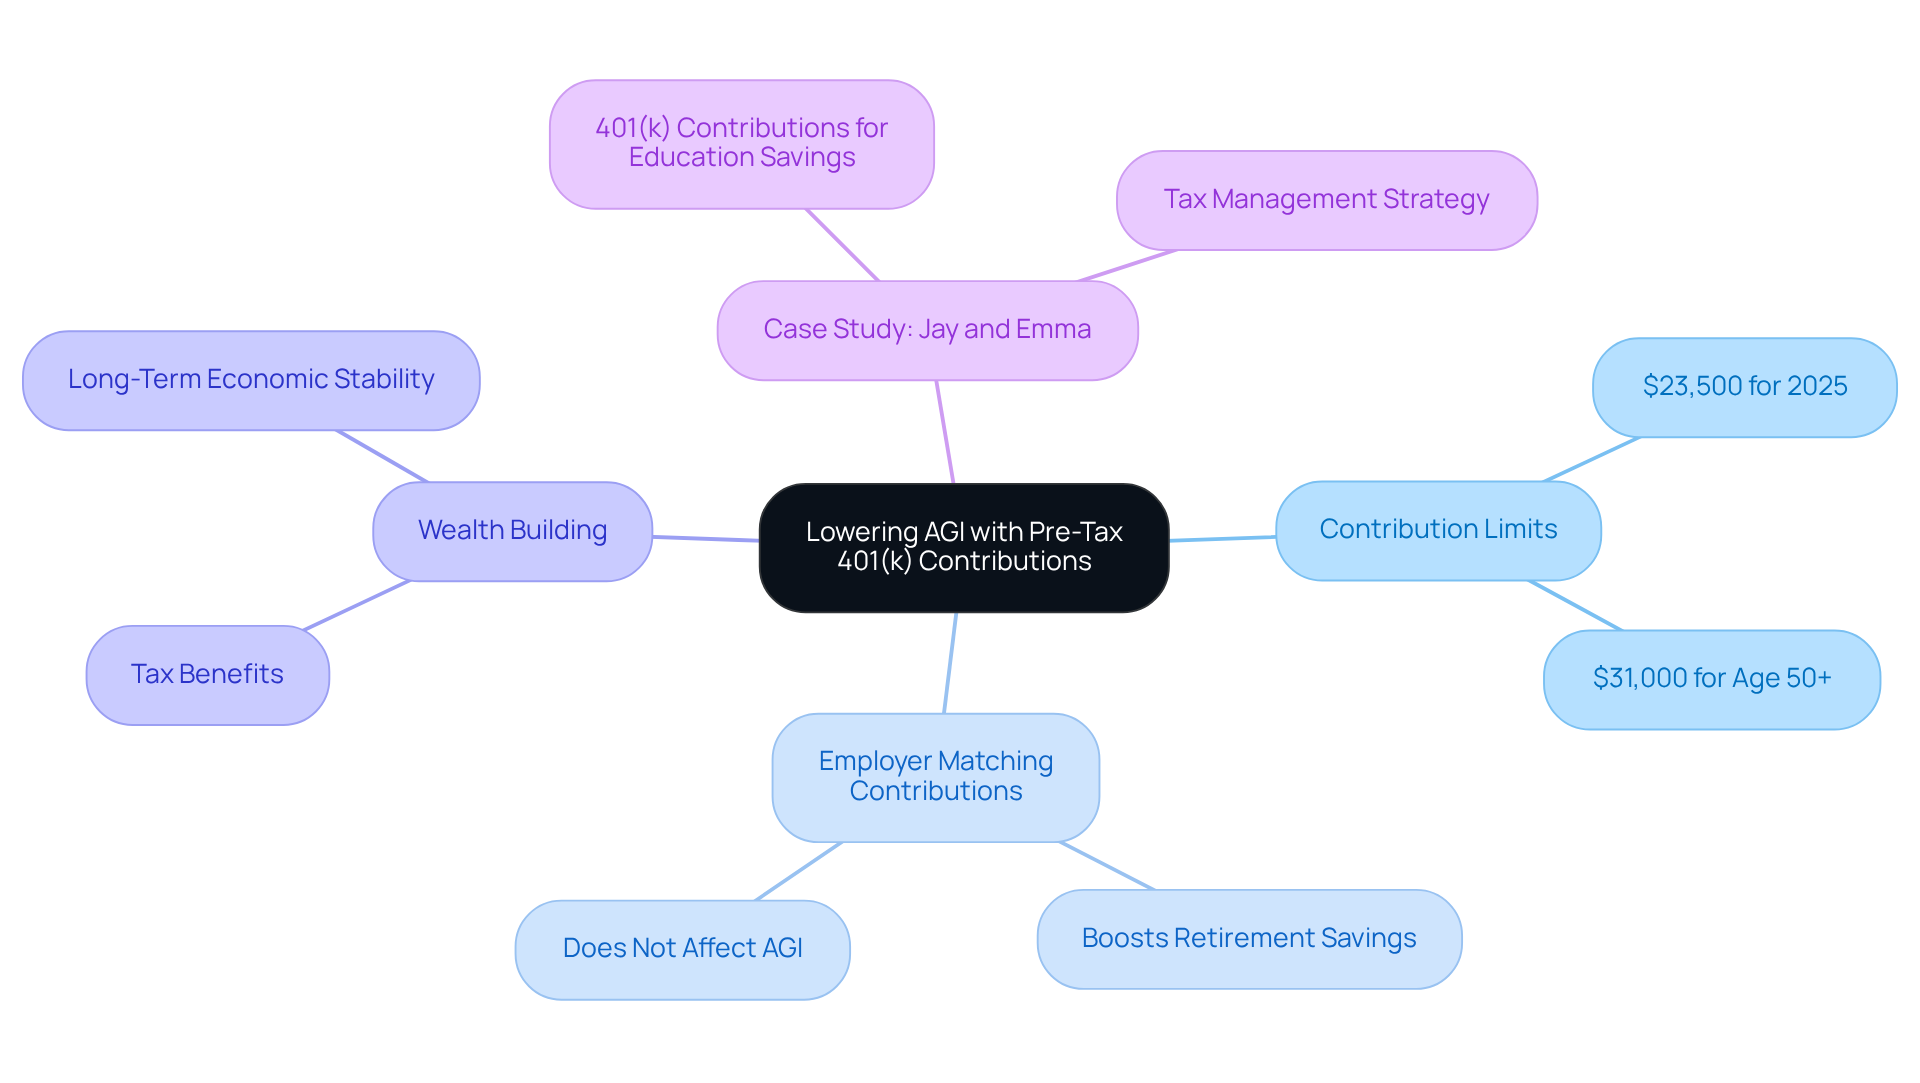
Contributing to a pre-tax 401(k) is one of the best ways to lower AGI for young households while building wealth for the future. Imagine being able to contribute up to $23,500 in 2025, or even $31,000 if you’re aged 50 or older. These contributions not only reduce your taxable income but also allow you to save for retirement while enjoying immediate tax benefits.
Many employers are there for you too, offering matching contributions that can significantly boost your retirement savings without affecting your AGI. This dual benefit can enhance your long-term economic stability and help you optimize your tax efficiency.
Consider Jay and Emma, who used their 401(k) contributions as part of a broader financial strategy that included saving for their children’s education. They effectively managed their tax responsibilities while preparing for their kids’ future needs.
As retirement planning specialists often emphasize, understanding the ways to lower AGI through 401(k) contributions is crucial for families aiming to achieve financial stability and pursue long-term goals. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.
Deductible Traditional IRA: Enhance Retirement Savings While Lowering AGI
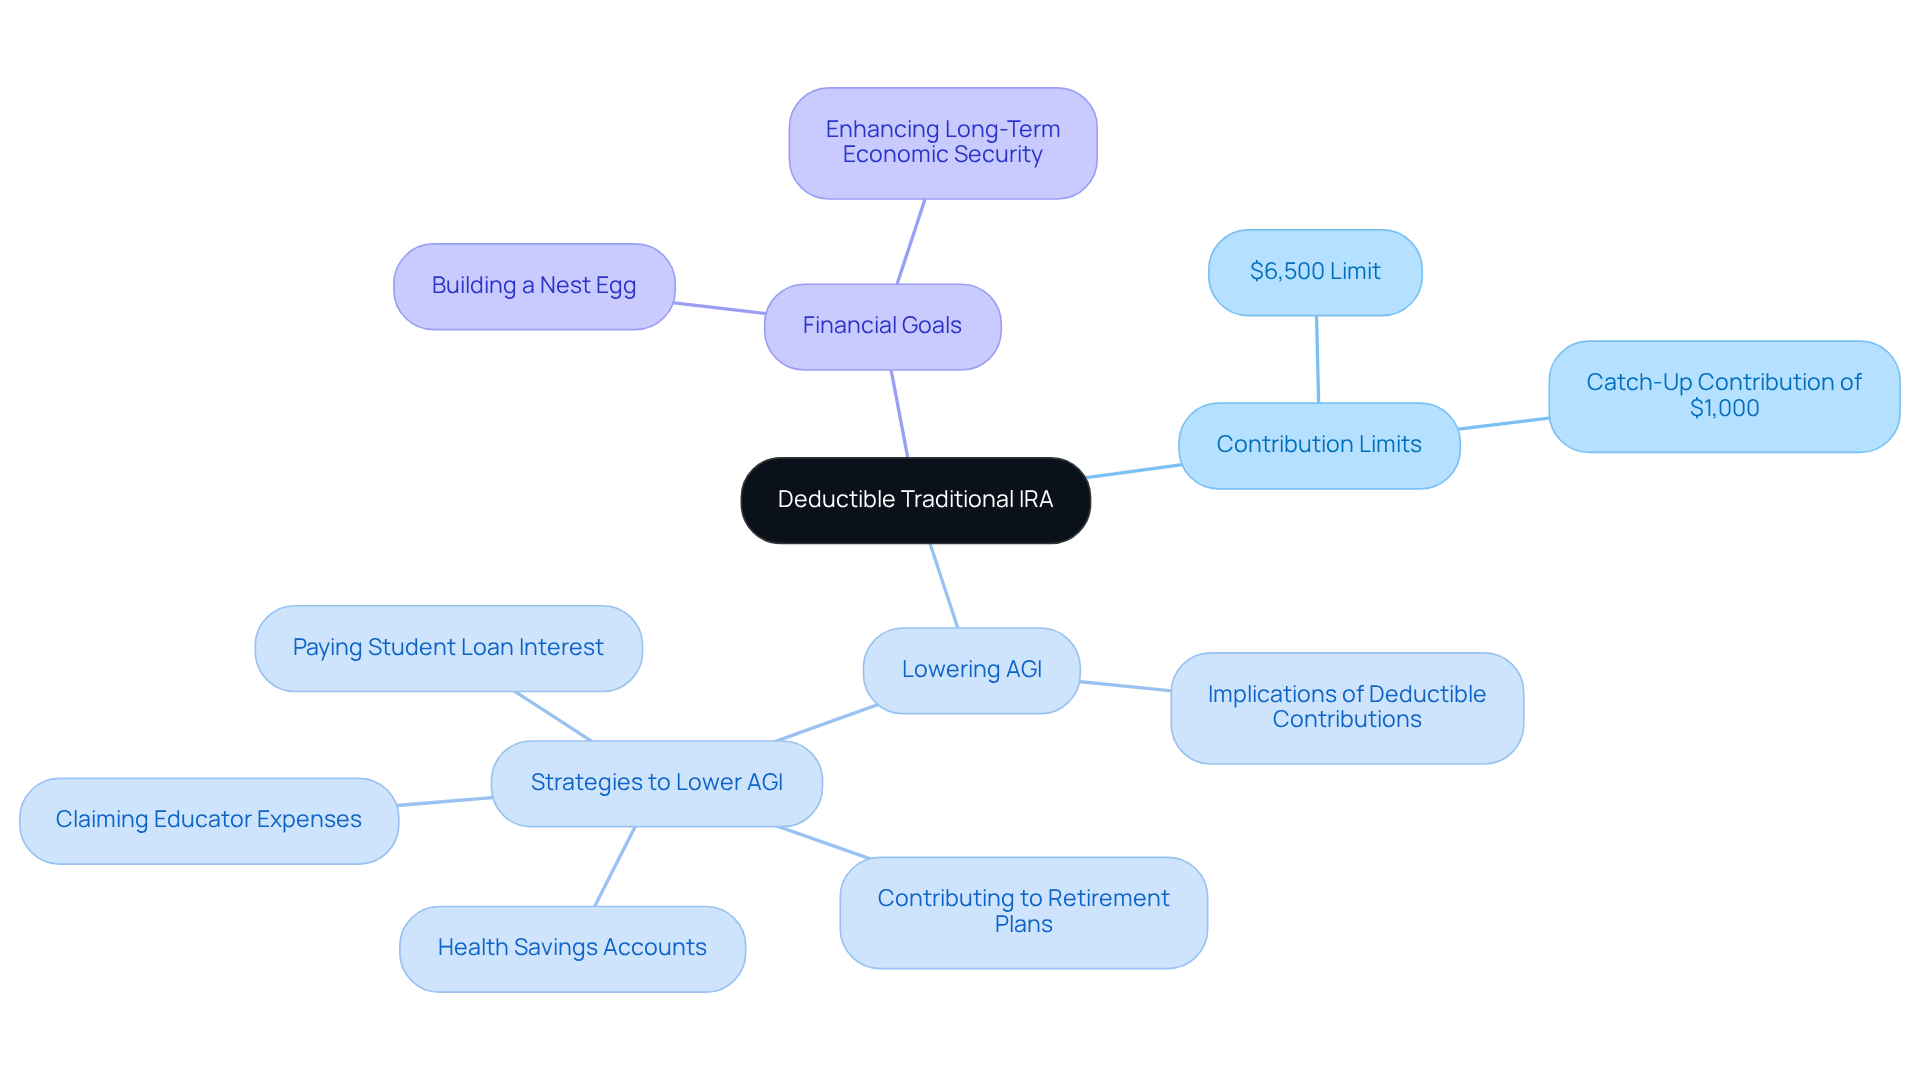
In 2025, households have the opportunity to contribute up to $6,500 per person to a Deductible Traditional IRA. For those aged 50 and older, there’s an additional catch-up contribution of $1,000. Depending on your income levels and whether you participate in employer-sponsored retirement plans, these contributions might be fully or partially deductible.
Imagine if you could discover ways to lower AGI and simultaneously build a significant nest egg for your family’s future. Using a Traditional IRA offers this dual advantage, presenting families with effective ways to lower AGI and enhance their long-term economic security.
It’s heartening to note that many households are turning to Deductible Traditional IRAs to boost their retirement savings. This trend highlights the effectiveness of this approach in achieving financial goals. Together, we can navigate this journey towards a more secure future for your family.
Tax-Loss Harvesting: Offset Gains to Reduce AGI
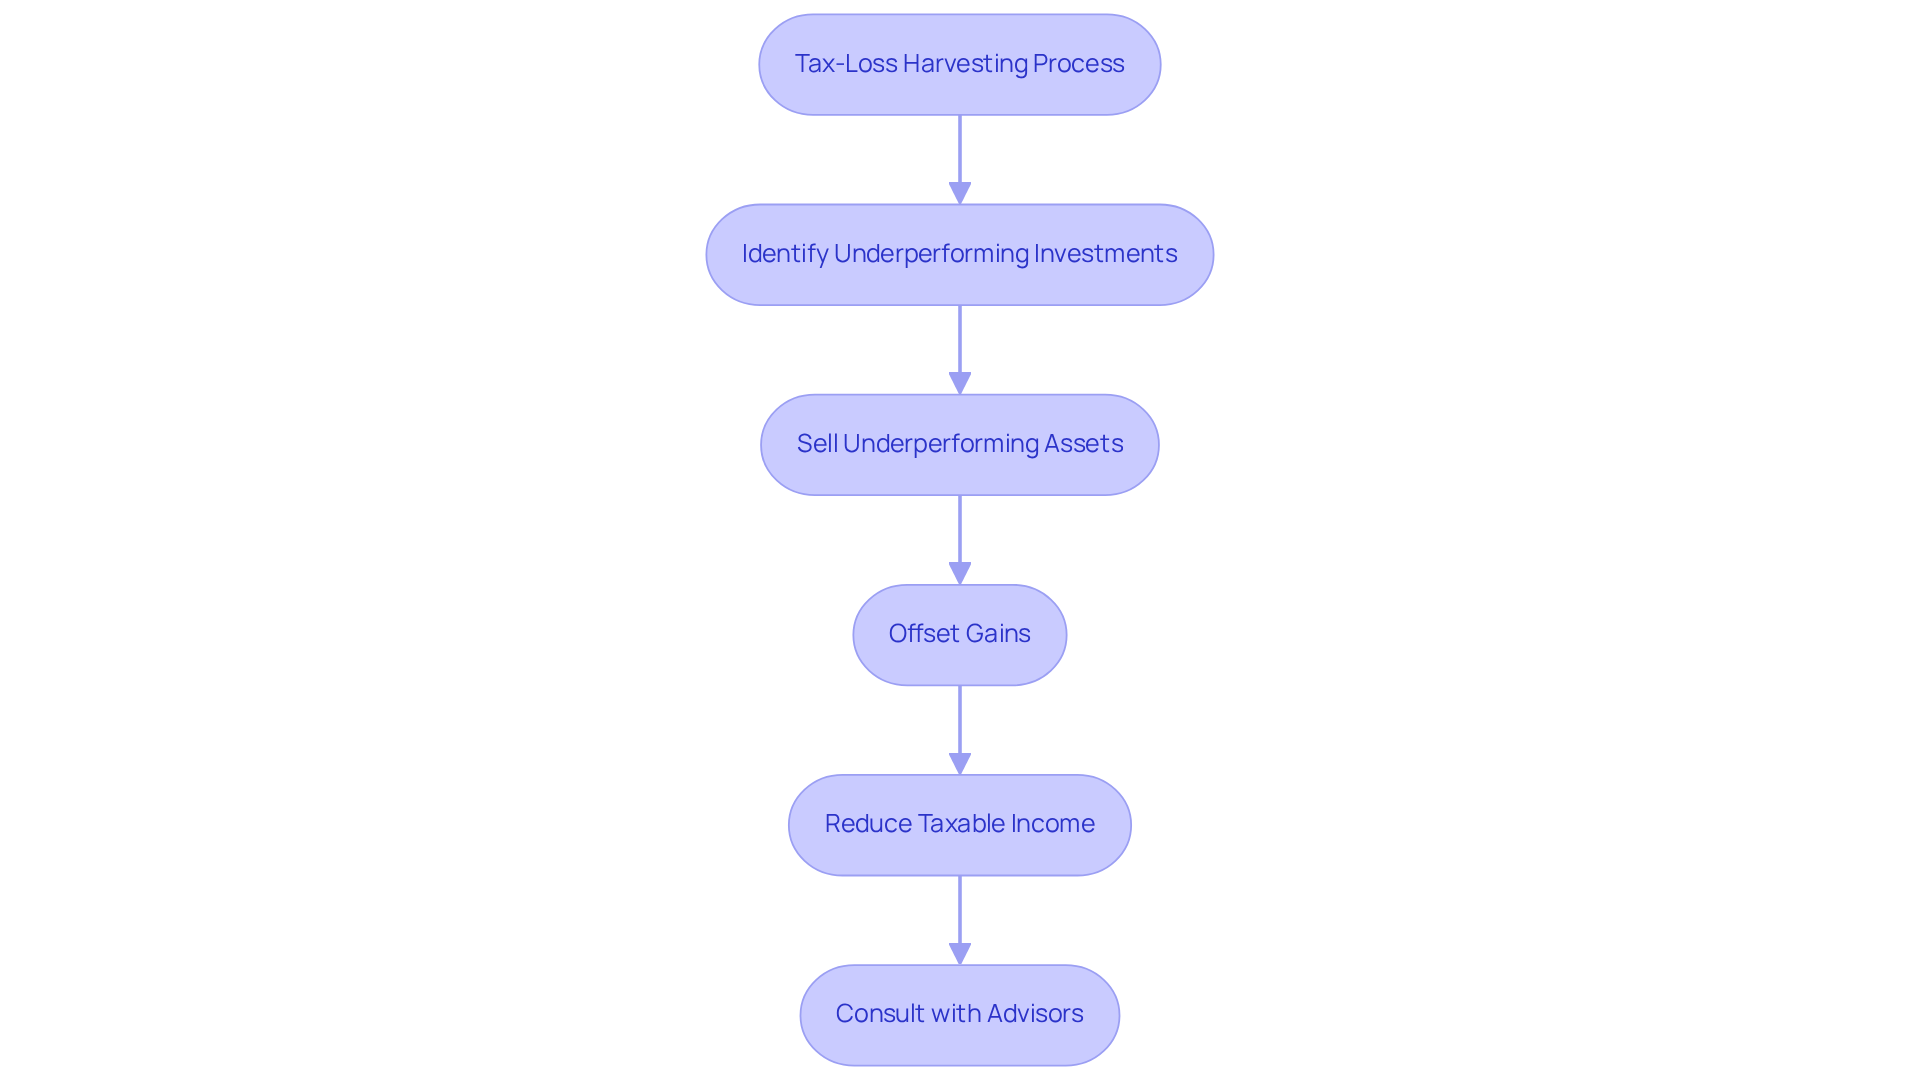
Tax-loss harvesting is a thoughtful strategy that involves selling underperforming investments to offset gains from profitable ones, providing effective ways to lower AGI and reduce taxable income. For families like Allison and Brian, who sought guidance from Bright Advisers to enhance their financial potential, this method can be particularly beneficial, especially during times of market fluctuation. By consistently examining their investment portfolios, families can identify potential losses that can be used to offset gains, thereby improving overall tax efficiency.
Imagine a family that has realized gains of $200,000 from one investment but also holds losses of $150,000 from another. By selling the underperforming asset, they can offset a significant portion of their gains, which helps reduce their taxable income and overall tax liability. This proactive management not only protects their wealth but also aligns with long-term financial goals, as seen in Allison and Brian’s case, where they optimized their tax situation and secured their children’s future through education funding.
In their partnership with Bright Advisers, Allison and Brian embraced specific strategies like regularly assessing their investment performance and timing the sale of assets to maximize tax benefits. Investment advisors emphasize the importance of incorporating tax-loss harvesting into a broader financial strategy. As one advisor shared, “Tax-loss harvesting is just one part of a comprehensive strategy to reduce tax liability and grow your wealth.” This highlights the significance of a holistic approach to financial planning, especially for families aiming to ensure their financial future.
On average, families utilizing tax-loss harvesting can save meaningful amounts on their tax bills. For instance, a household in a higher tax bracket could potentially save thousands each year by effectively managing their investment losses. By understanding and applying this strategy, families can explore various ways to lower AGI, significantly enhancing their after-tax returns and maintaining a more favorable financial situation. Additionally, it’s crucial for families to be aware of the Wash Sale Rule, which prohibits claiming a loss if a substantially identical security is repurchased within 30 days. By grasping and implementing this strategy, households can greatly improve their after-tax returns and sustain a more advantageous economic position. To embark on this journey, families should seek guidance from an investment consultant to explore how tax-loss harvesting can fit into their overall investment approach.
Education Credits and Deductions: Financial Relief for Families
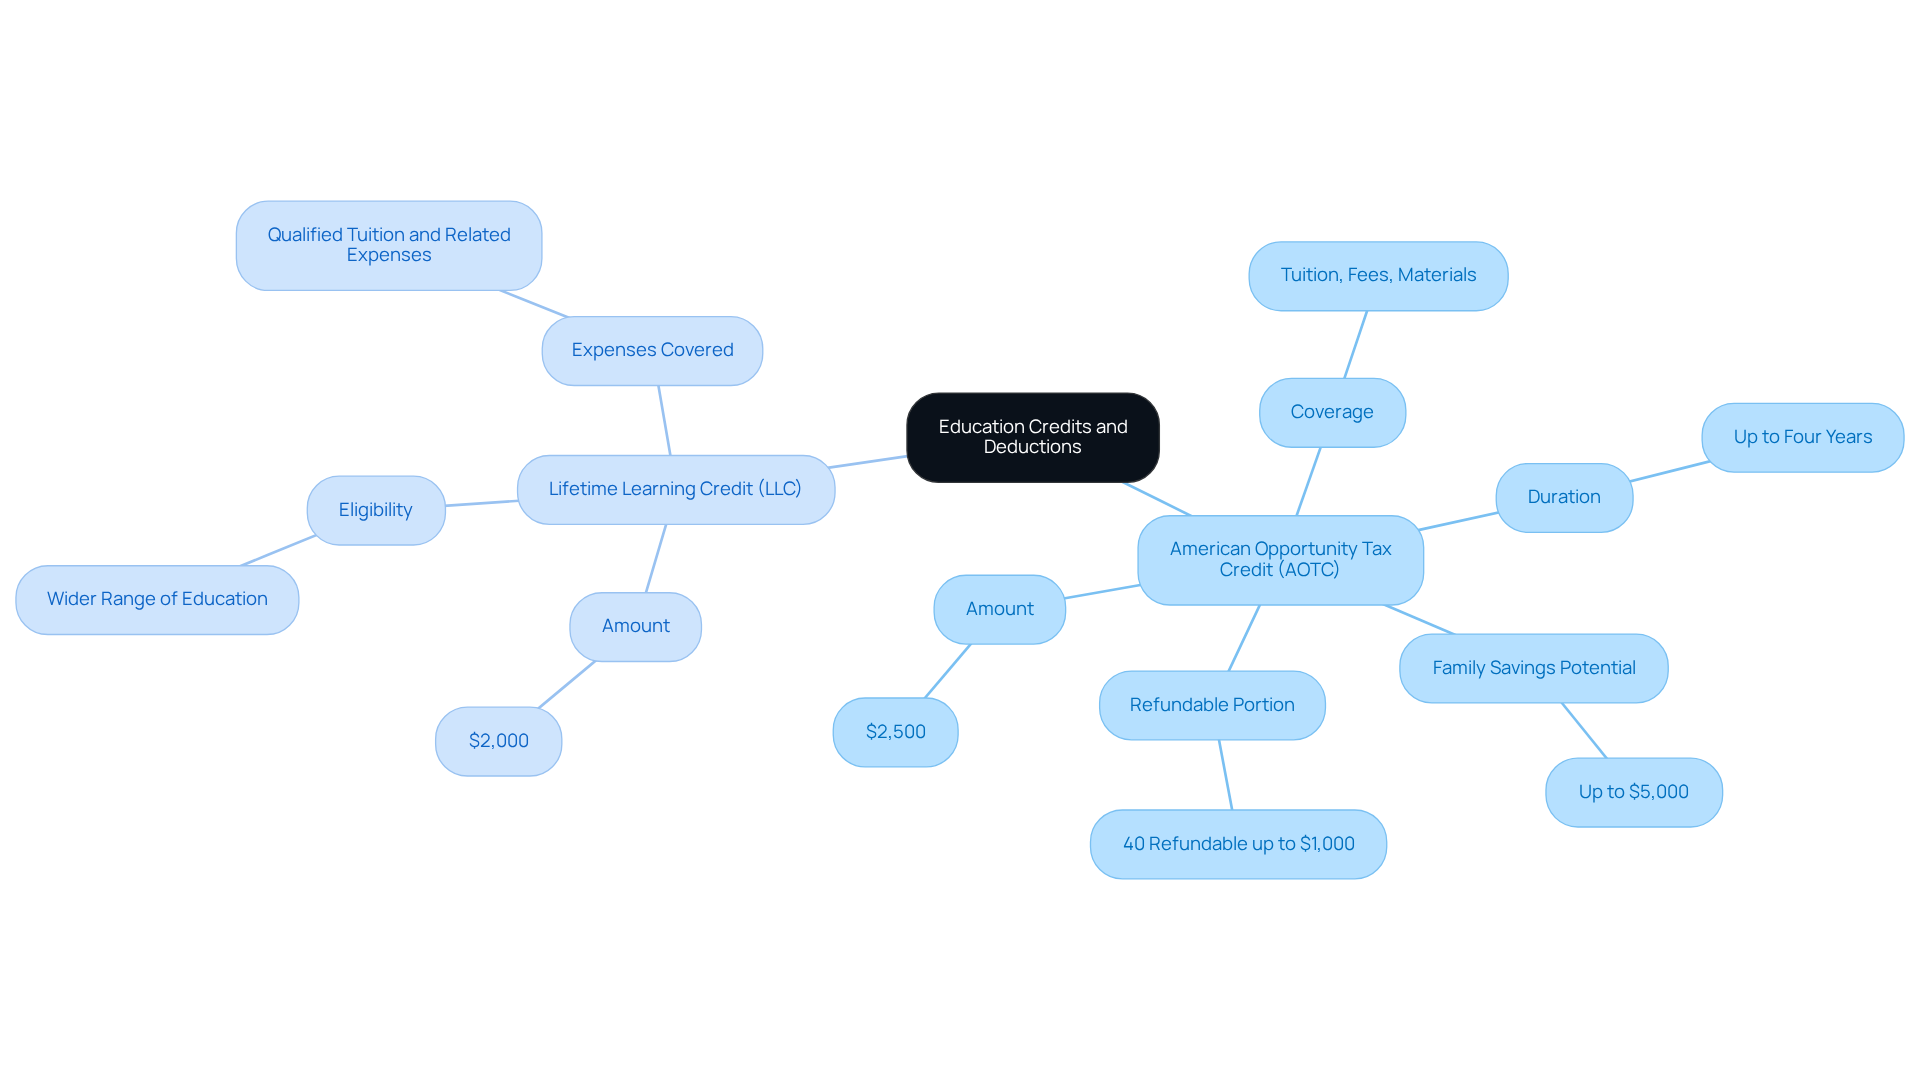
Families have the opportunity to ease their economic burdens and enhance their overall well-being through education credits and deductions, like the American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC). Imagine being able to claim up to $2,500 for the first four years of higher education with the AOTC. This credit covers tuition, fees, and course materials, and it’s available for up to four tax years if your student hasn’t yet completed their first four years of college.
In contrast, the LLC offers up to $2,000 for qualified tuition and related expenses, applicable to a wider range of educational pursuits, including graduate studies. By strategically claiming these credits, households can significantly decrease their tax obligations, which are among the best ways to lower AGI. For example, consider a household with two qualified students—this family could potentially save as much as $5,000 through the AOTC alone, providing crucial support during those essential educational years.
Furthermore, it’s comforting to know that 40% of the AOTC credit that exceeds the tax due can be reimbursed, up to $1,000. This highlights the economic advantages available to families. Tax experts emphasize the importance of maximizing benefits and exploring ways to lower AGI through careful planning and accurate documentation. Remember, students need to receive a Form 1098-T to claim an education credit.
As families navigate the complexities of education expenses, understanding and utilizing these credits—while seeking professional guidance—can play a pivotal role in securing their financial future. Together, we can navigate this journey and ensure that your family’s educational goals are within reach.
Capital Gains Management: Control Your AGI Impact
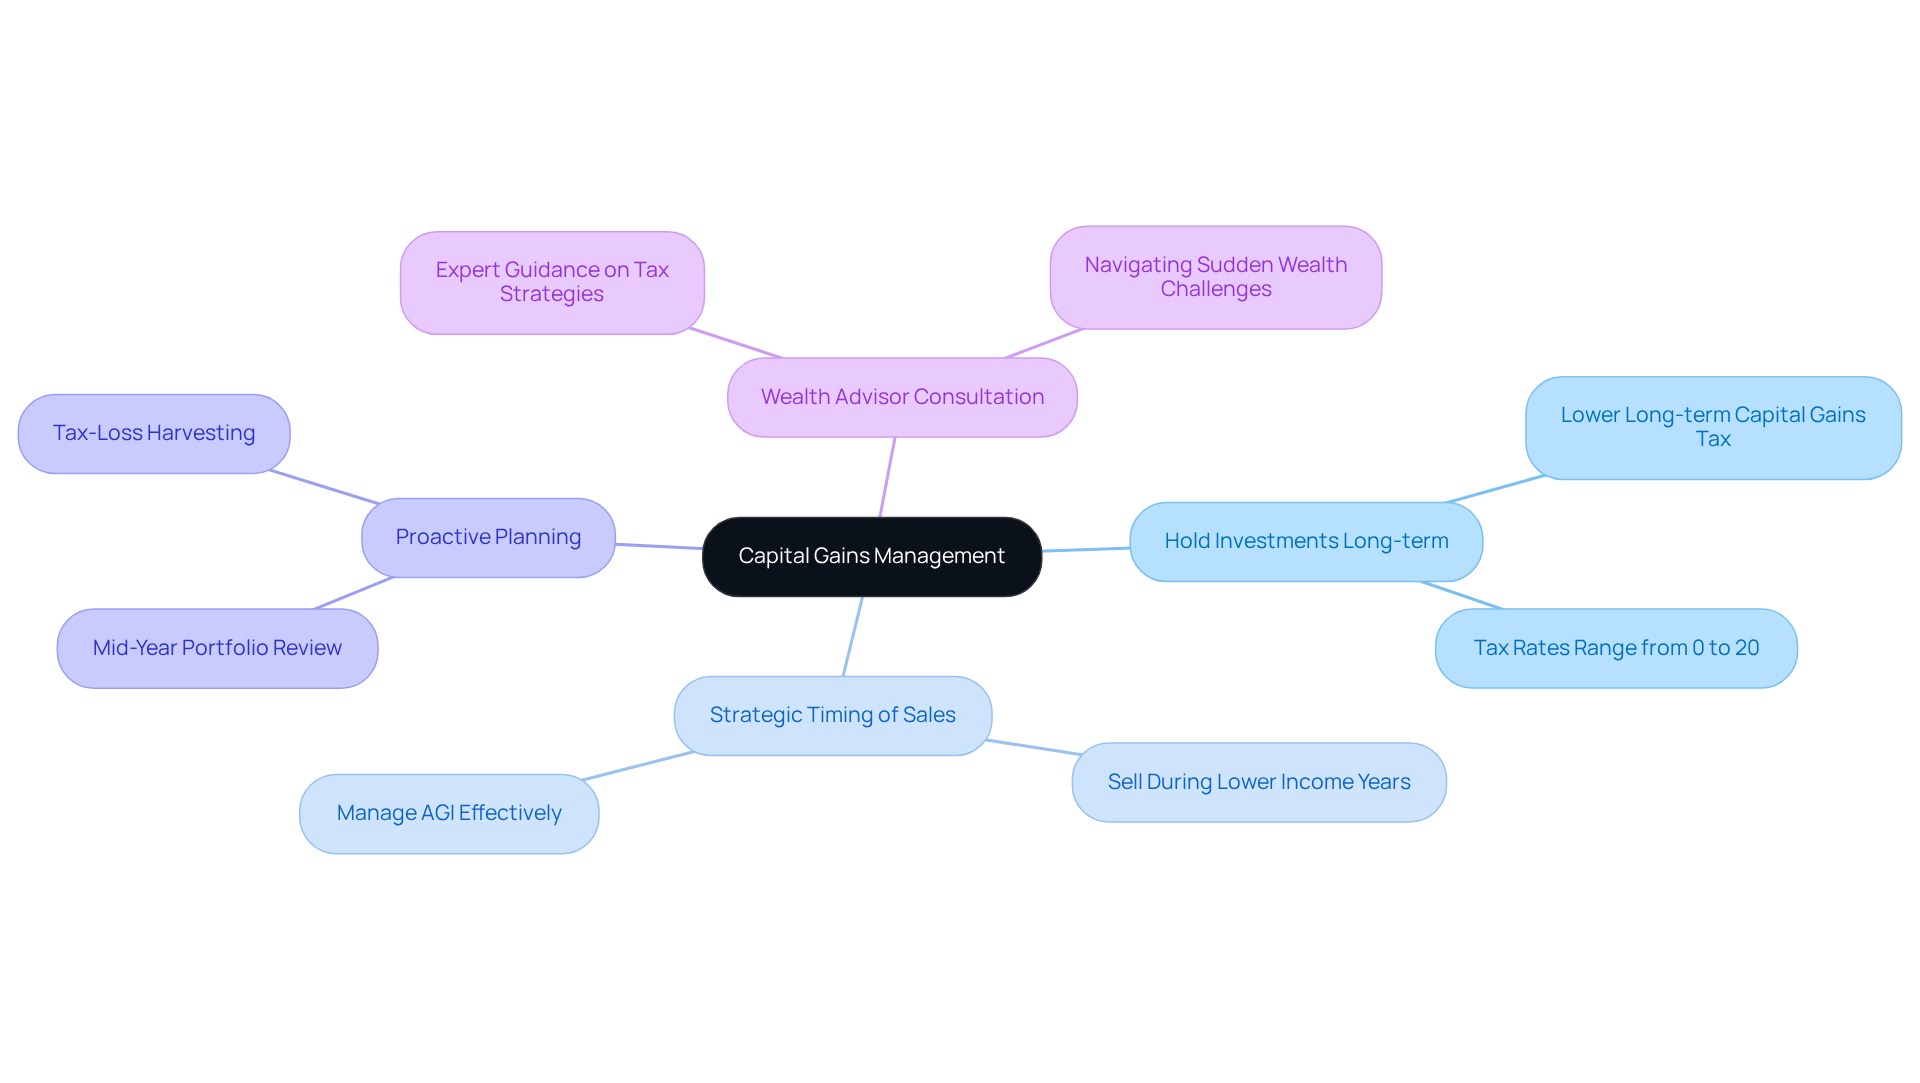
It’s crucial for families to explore ways to lower AGI, as capital gains can significantly affect their Adjusted Gross Income (AGI) when selling investments. Imagine if you could ease this burden by holding onto your investments for over a year. By doing so, you can benefit from significantly lower long-term capital gains tax rates, which can range from 0% to 20%.
Consider this: if you strategically time the sale of your investments during years when your income is lower, you can discover ways to lower AGI and potentially lighten your overall tax load. Real-life stories show that families who sold investments in a year with reduced income successfully improved their tax situations. This highlights the importance of proactive planning in your financial journey.
Wealth advisors emphasize that by employing these ways to lower AGI, you can manage your capital gains effectively, allowing you to preserve more of your hard-earned wealth while securing your family’s economic future. This thoughtful planning not only aids in optimizing taxes but also fosters long-term financial stability for your household. Remember, together, we can navigate this journey and ensure a brighter future for your family.
Required Minimum Distributions (RMDs): Plan Ahead to Manage AGI
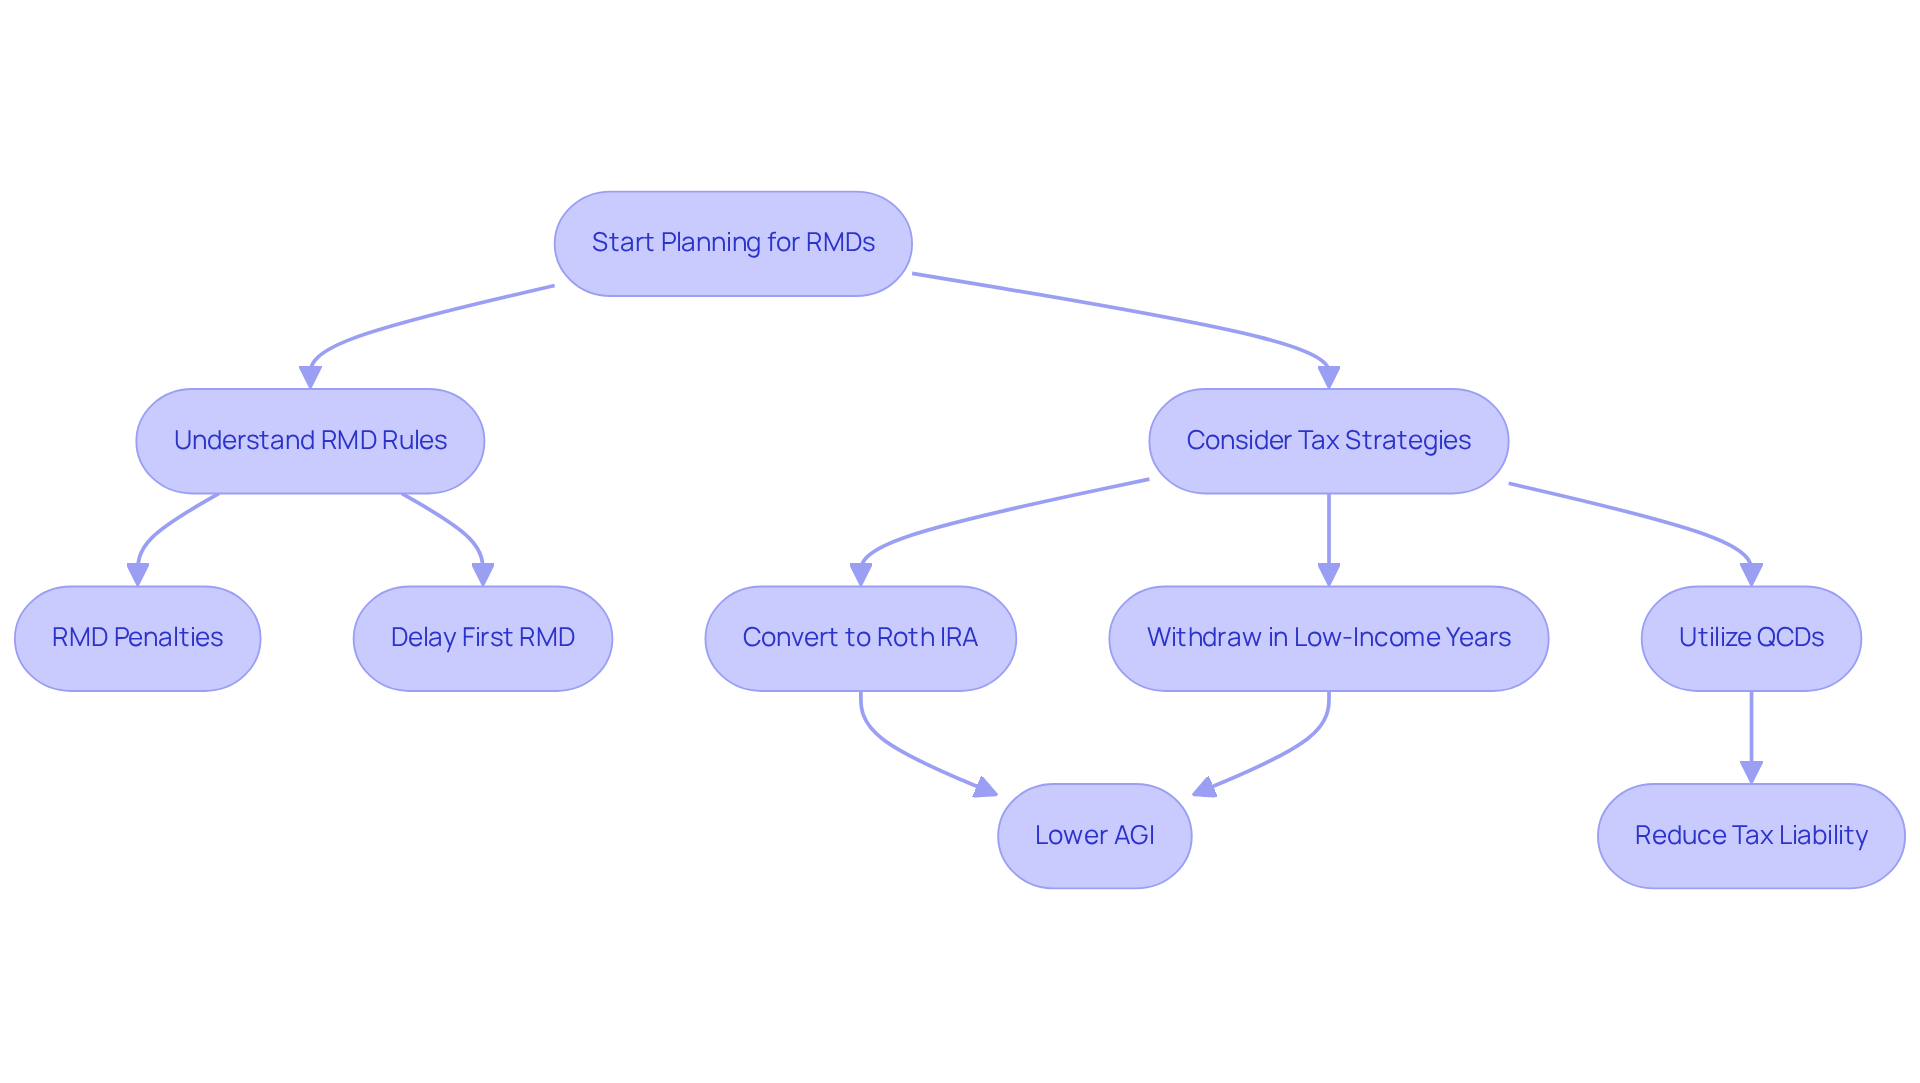
Navigating the world of retirement planning can feel overwhelming, especially for young parents who are juggling so many responsibilities. Required Minimum Distributions (RMDs) are a crucial aspect to understand, as they are mandatory withdrawals from traditional IRAs and 401(k)s that begin at age 73, according to the SECURE Act 2.0. These distributions are considered taxable income and can significantly increase an individual’s Adjusted Gross Income (AGI). For example, imagine a household with a $2 million IRA facing an RMD of approximately $81,301. This could push them into a higher tax bracket, impacting their overall tax liability and potentially increasing their Medicare premiums.
To ease the burden of RMDs and lessen their tax impact, families can consider several ways to lower AGI through thoughtful strategies. One effective approach is converting traditional IRAs to Roth IRAs during lower-income years. This not only allows for tax-free withdrawals later but also reduces future RMD amounts. Additionally, families can consider ways to lower AGI by planning to withdraw funds in years when their income is lower, helping to keep their AGI within a more favorable tax bracket.
It’s important to emphasize the value of planning ahead and seeking professional guidance to navigate these complexities. For instance, utilizing Qualified Charitable Distributions (QCDs) can be a wonderful option for individuals aged 70½ and older. This allows them to donate directly from their IRAs to charity, satisfying part or all of their RMDs and providing ways to lower AGI. This strategy not only supports charitable causes but also helps lower taxable income, creating a win-win situation.
Real-world examples can illustrate the effectiveness of these strategies. Take families like Allison and Brian, who proactively plan their RMDs. They often discover ways to lower AGI, ensuring they maintain financial stability while fulfilling their retirement obligations. By understanding the tax implications of RMDs and implementing thoughtful withdrawal strategies, families can navigate the complexities of retirement planning more effectively.
It’s also crucial to remember that missing an RMD incurs a steep penalty of 25% on the amount not withdrawn. This highlights the importance of compliance with RMD rules. Furthermore, the first RMD can be delayed until April 1 of the year following the year the individual turns 73. However, this may lead to taking two RMDs in one year, significantly increasing taxable income.
Together, we can navigate this journey, ensuring that your family’s financial future remains bright and secure.
Municipal Bond Income: A Tax-Advantaged Investment for Lower AGI
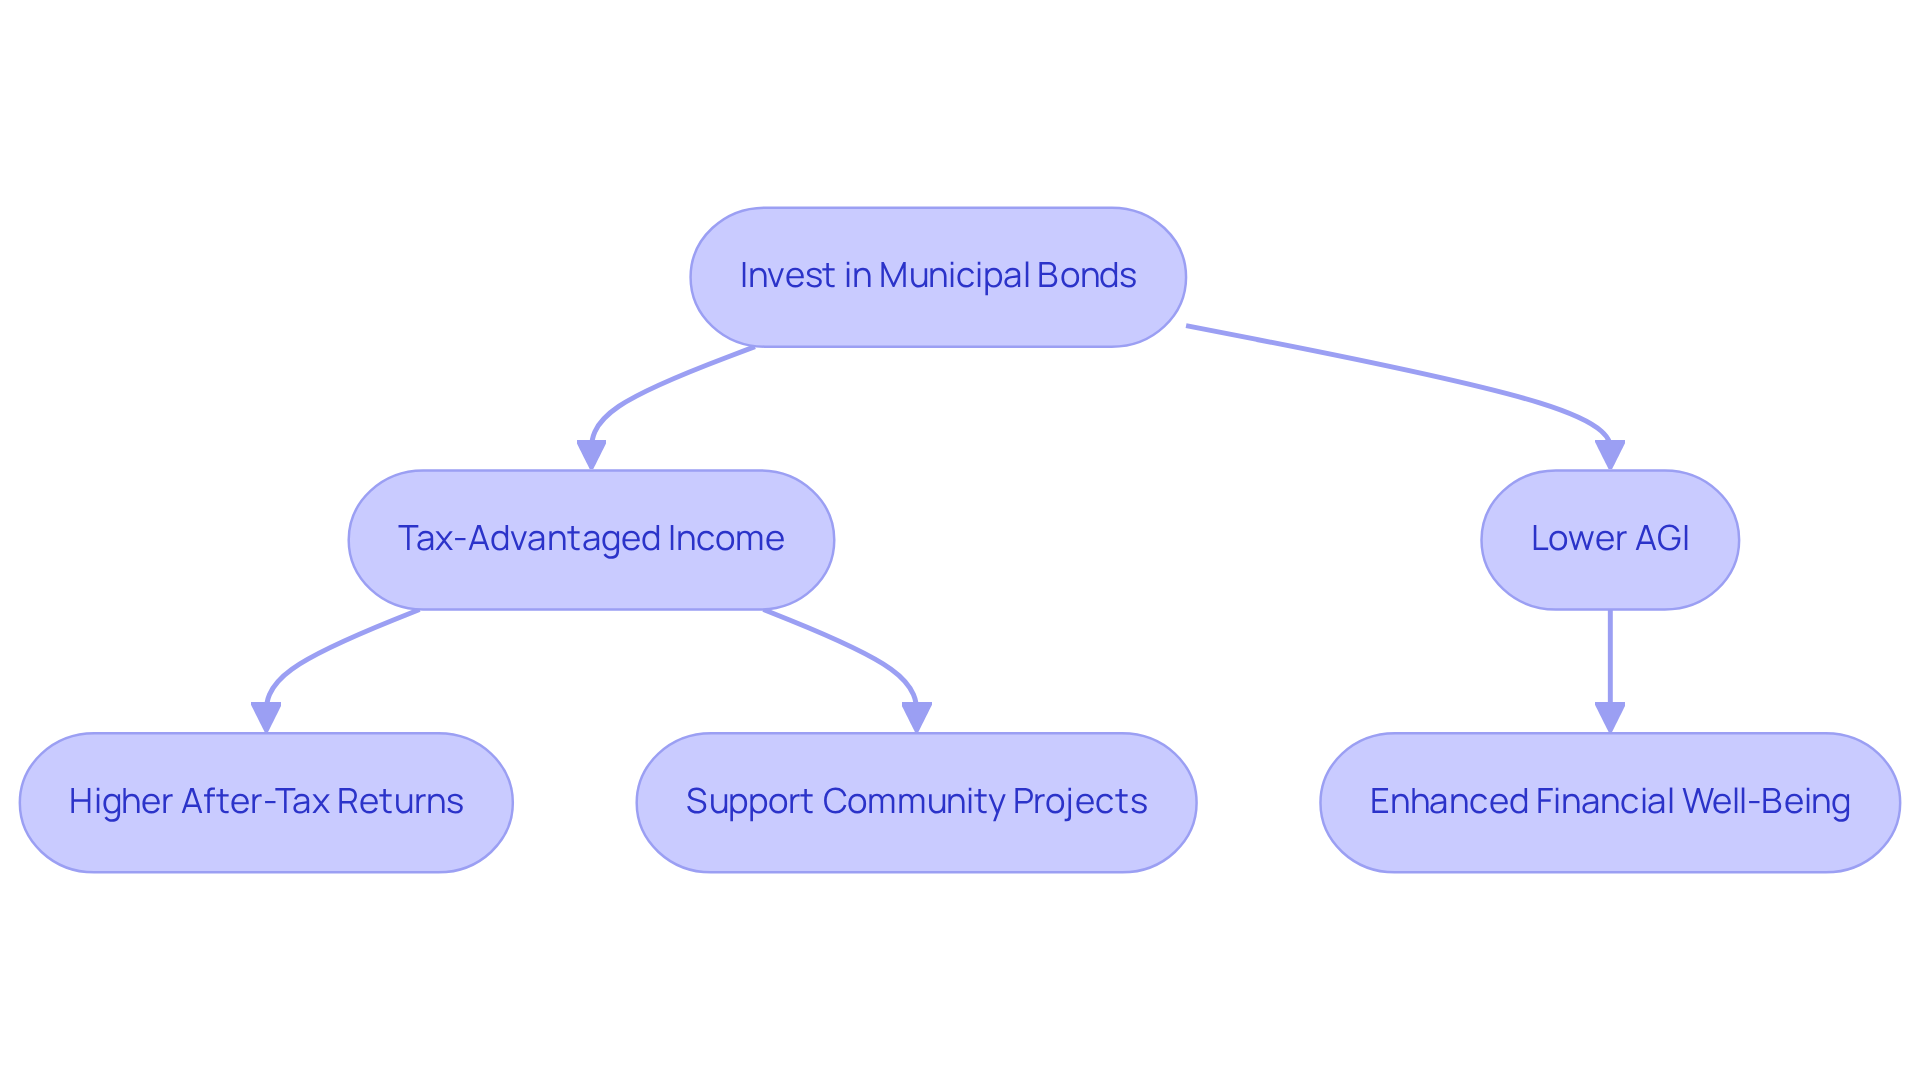
Municipal bonds, issued by state and local governments, present a wonderful opportunity for families looking to ease their tax burden. The interest income generated from these bonds is typically exempt from federal income tax and often from state and local taxes, meaning it does not affect your Adjusted Gross Income (AGI). This tax advantage makes municipal bonds particularly appealing for households striving to enhance their financial strategies.
Imagine a family that invests in municipal bonds yielding 4% while living in a high-tax state. The tax-equivalent yield can significantly boost their after-tax returns compared to taxable bonds or stock investments. For families in high-income brackets, like Allison and Brian, who are eager to maximize their financial potential through thoughtful tax planning, the effective tax rate on municipal bond income can be considerably lower than that on ordinary income, allowing them to retain more of their hard-earned money.
Real-life stories illustrate how municipal bonds can positively impact families’ financial situations. Consider a couple in Illinois with a combined income of $800,000 who chose to invest in state municipal bonds to save for a home down payment. They found that their investment in Illinois Municipal Bonds yielded a net income of $14,888 after taxes, surpassing other options like corporate bonds and U.S. Treasury Notes.
Investment professionals stress the value of tax-advantaged investments like municipal bonds. As Paul Malloy from Vanguard wisely noted, “Investors can still earn significantly more income by moving into longer maturities, especially in high-quality bonds.” This highlights the strategic benefits of including municipal bonds in your investment portfolio as one of the ways to lower AGI, while also supporting community projects and optimizing tax efficiency.
By incorporating municipal bonds into your financial planning, you can find ways to lower AGI, thus reducing your overall tax burden and enhancing your family’s economic well-being. Bright Advisers is here to provide personalized strategies to help families navigate these investment opportunities, ensuring you make informed decisions that align with your long-term financial goals. Together, we can navigate this journey towards a brighter financial future.
Avoid Common Pitfalls: Strategies to Prevent AGI Increase
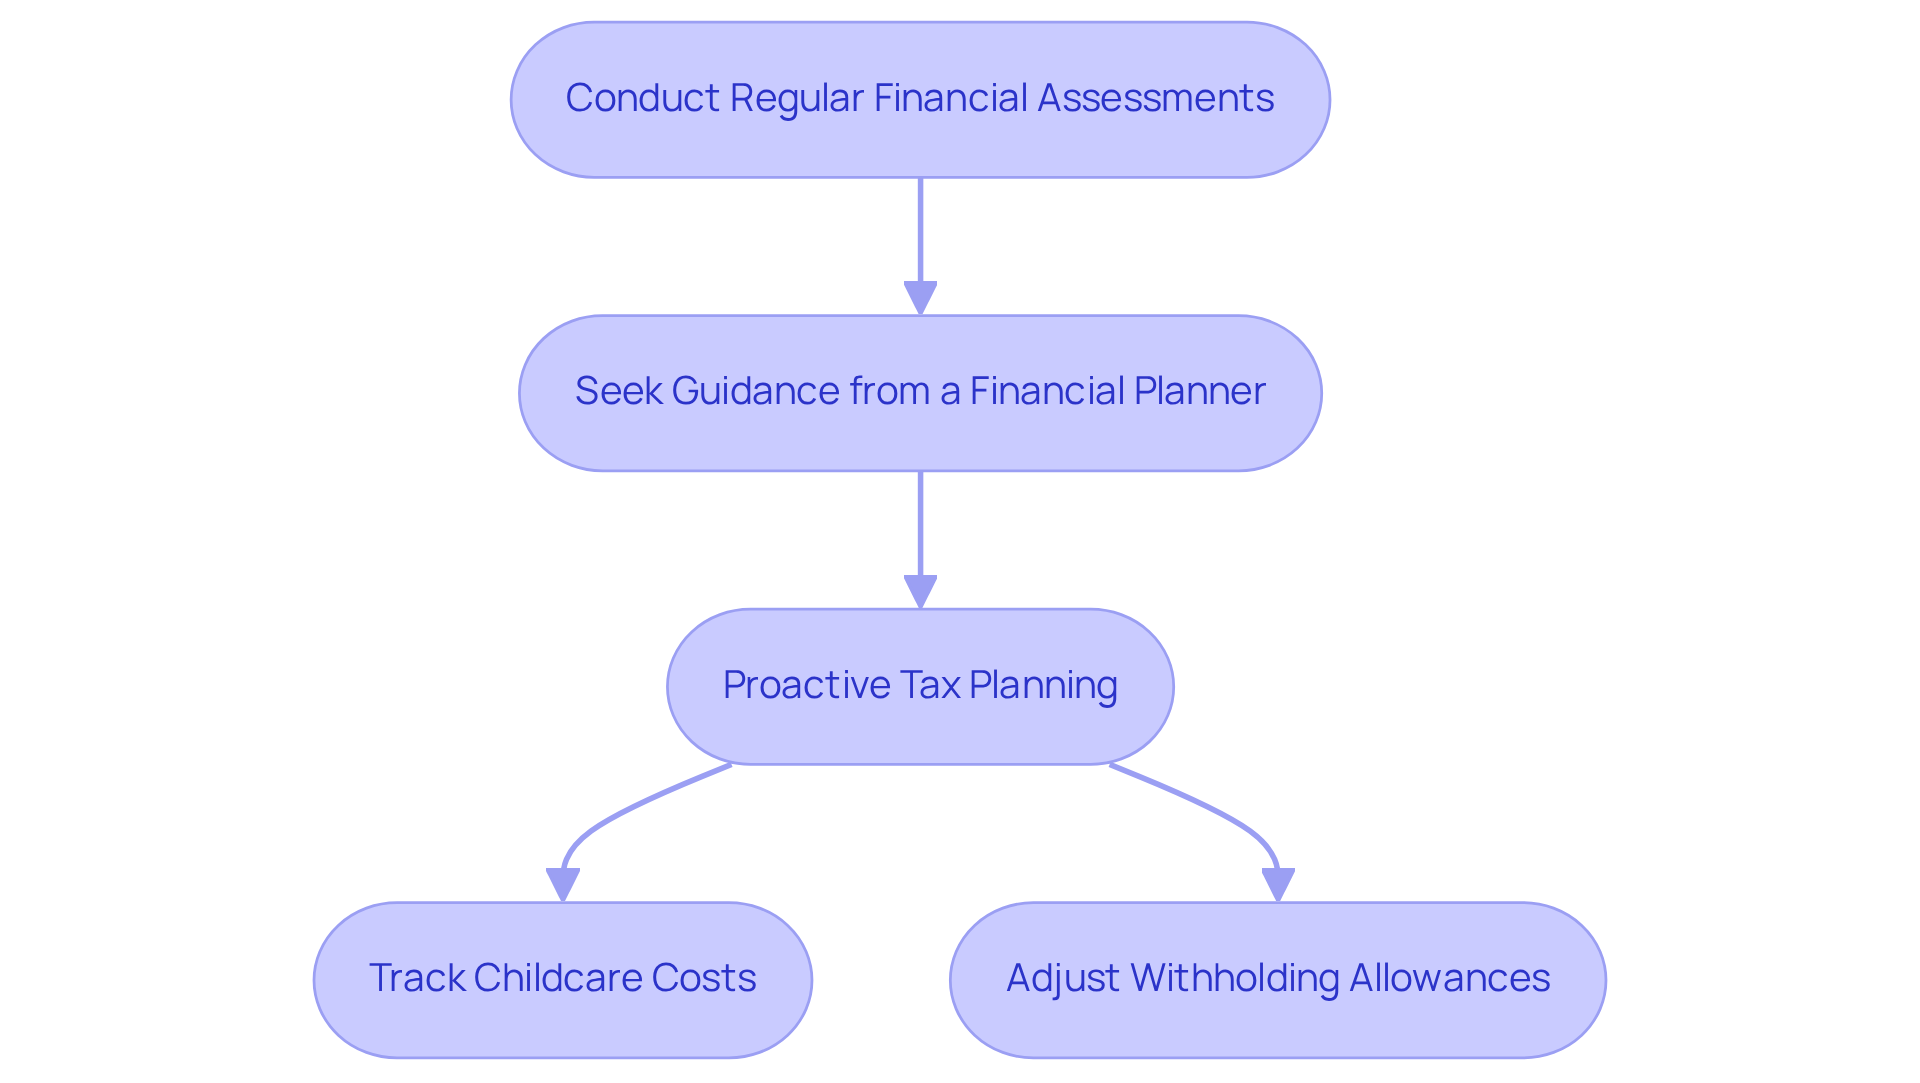
Families often face challenges that can unintentionally obstruct their efforts to find ways to lower AGI. Imagine navigating the complexities of deductible expenses while juggling the demands of everyday life. It’s easy to overlook the need to adjust withholding allowances as personal situations evolve.
To help you avoid these pitfalls, consider conducting regular assessments of your financial situation. Seeking guidance from a financial planner can provide the support you need. Proactive tax planning throughout the year, rather than waiting until tax season, can help you sidestep unexpected tax liabilities and explore ways to lower AGI.
For instance, families who consistently track their childcare costs and adjust their tax withholding accordingly have discovered effective ways to lower AGI. This means more savings to allocate toward essential household needs, allowing you to focus on what truly matters.
Financial planners emphasize the importance of staying organized and informed about available deductions and credits. By implementing these strategies, you can create a more stable financial foundation for your family. Remember, we’re here for you—together, we can navigate this journey toward enhanced financial well-being.
Conclusion
Lowering Adjusted Gross Income (AGI) is an important step for young families striving to enhance their financial stability and lessen tax burdens. Imagine being able to improve not just your current financial situation, but also secure a brighter future for your loved ones. This article shares effective methods to help you achieve this goal, highlighting the significance of personalized financial planning and proactive management.
Consider strategies like maximizing contributions to Health Savings Accounts (HSAs) and pre-tax 401(k) plans. These actions can significantly lower your AGI while promoting long-term financial health. Additionally, utilizing tax-loss harvesting to offset gains and taking advantage of education credits and deductions can provide unique benefits tailored to your family’s needs. Understanding the implications of capital gains and Required Minimum Distributions (RMDs) can further empower you to make informed decisions that align with your financial objectives.
As you embark on this journey to lower your AGI, remember that it is a multifaceted process requiring thoughtful planning and execution. By actively engaging in these strategies and seeking guidance from financial professionals, you can confidently navigate the complexities of your financial landscape. Embracing these practices not only alleviates current financial pressures but also lays the groundwork for a secure and thriving future.
Taking the first steps today can lead to lasting benefits, ensuring that you achieve your financial goals while fostering a culture of financial literacy for generations to come. Together, we can navigate this journey, and we’re here to support you every step of the way.
Frequently Asked Questions
What is the main focus of Bright Advisers?
Bright Advisers focuses on tailored financial planning to help families lower their Adjusted Gross Income (AGI) through customized strategies and a client-first approach.
How does Bright Advisers help families lower their AGI?
They evaluate income sources, potential deductions, and tax-efficient investment options, such as contributions to retirement accounts like 401(k)s and Health Savings Accounts (HSAs).
What educational resources does Bright Advisers provide?
Bright Advisers offers 30 on-demand interactive lessons aimed at teaching children about money management and financial literacy.
What are Health Savings Accounts (HSAs) and how do they help in lowering AGI?
HSAs allow families to set aside pre-tax funds for medical expenses, which can lower AGI. Contributions are tax-deductible, and withdrawals for qualified medical expenses are tax-free.
What are the contribution limits for HSAs in 2025?
Families with a high-deductible health plan can contribute up to $8,550, with an additional $1,000 catch-up contribution for individuals aged 55 and older.
How can contributing to a pre-tax 401(k) benefit families?
Contributing to a pre-tax 401(k) can lower AGI, as individuals can contribute up to $23,500 in 2025 or $31,000 if aged 50 or older, while also saving for retirement and receiving immediate tax benefits.
What role do employer matching contributions play in 401(k) plans?
Employer matching contributions can significantly boost retirement savings without affecting AGI, enhancing long-term economic stability.
How can families effectively manage their financial responsibilities using these strategies?
By utilizing strategies like HSAs and 401(k) contributions, families can lower their taxable income, prepare for future expenses, and achieve financial stability while planning for long-term goals.
List of Sources
- Bright Advisers: Tailored Financial Planning to Lower AGI
- Effective Strategies: How to Reduce MAGI for High Earners and Lower Premiums – IRMAA Certified Planner (https://irmaacertifiedplanner.com/how-to-reduce-magi)
- How to Lower AGI – Benefits of Tax Planning Strategies – Arnold Mote Wealth Management (https://arnoldmotewealthmanagement.com/how-to-lower-your-agi-or-magi-benefits)
- How to Take Control of Your Adjusted Gross Income and Reduce Your Retirement Tax Bill (https://gudorffinancial.com/blog/how-to-take-control-of-your-adjusted-gross-income-and-reduce-your-retirement-tax-bill)
- Lowering AGI this year can help taxpayers when they file next year | Internal Revenue Service (https://irs.gov/newsroom/lowering-agi-this-year-can-help-taxpayers-when-they-file-next-year)
- Health Savings Account (HSA): Maximize Contributions for AGI Reduction
- Health Savings Account (HSA) Benefits and Details Explained (https://ml.com/articles/health-savings-accounts-explained.html)
- Health Savings Accounts (HSAs) (https://congress.gov/crs-product/R45277)
- HSA contribution limits 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- Pre-Tax 401(k) Contributions: A Strategic Move to Lower AGI
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Effective Strategies: How to Reduce MAGI for High Earners and Lower Premiums – IRMAA Certified Planner (https://irmaacertifiedplanner.com/how-to-reduce-magi)
- 401(k) Tax Rules: Withdrawals, Deductions & More (https://smartasset.com/retirement/401k-tax)
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)
- Deductible Traditional IRA: Enhance Retirement Savings While Lowering AGI
- Retirement topics – IRA contribution limits | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-ira-contribution-limits)
- Case Study: Retirees – Mariaca Wealth Management (https://mariacawealth.com/case_studies/retirees)
- Case Studies – Financial Engineer (https://thefinangineer.com/category/case_studies)
- Lowering AGI this year can help taxpayers when they file next year | Internal Revenue Service (https://irs.gov/newsroom/lowering-agi-this-year-can-help-taxpayers-when-they-file-next-year)
- Tax-Loss Harvesting: Offset Gains to Reduce AGI
- Maximize Your Savings With Tax-Loss Harvesting (https://creativeplanning.com/insights/financial-planning/tax-loss-harvesting)
- Current market conditions present opportunities for tax-loss harvesting (https://wolterskluwer.com/en/expert-insights/current-market-conditions-present-opportunities-for-tax-loss-harvesting)
- The economics of tax-loss harvesting (https://thetaxadviser.com/issues/2023/sep/the-economics-of-tax-loss-harvesting)
- From the Experts: Tax Loss Harvesting (https://annuity.org/2022/11/14/tax-loss-harvesting)
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Education Credits and Deductions: Financial Relief for Families
- Congress Enacts First-Ever Federal Tax Credit for Education Scholarships (https://edchoice.org/2025-congress-enacts-first-ever-federal-tax-credit-for-education-scholarships)
- Education credits: Questions and answers | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/education-credits-questions-and-answers)
- Republicans in Congress want to kill two education tax credits worth billions to U.S. students. If you’re a college student, it could impact you. | Fortune (https://fortune.com/article/gop-congress-budget-would-end-education-tax-credits-llc-aotc)
- 14 Education Tax Credits and Deductions to Know (https://kiplinger.com/slideshow/taxes/t054-s001-tax-deductions-and-credits-to-help-pay-for-college)
- Capital Gains Management: Control Your AGI Impact
- Smart Strategies for Navigating Capital Gains Tax on Sudden Wealth (https://thirdactretirement.com/blog/smart-strategies-for-navigating-capital-gains-tax-on-sudden-wealth)
- Strategic Tax Plan: Timing Investment Gains to Reduce Tax Liability (https://commercetrustcompany.com/research-and-insights/articles/6-strategies-to-lower-capital-gains-taxes-on-investment-returns)
- CharitablePlanning.com (https://charitableplanning.com/case_studies)
- 6 Mid-Year Planning Tips to Get Ahead of Capital Gains Taxes | Poinciana Advisors Group, LLC (https://poincianagroup.com/blog-01/6-mid-year-planning-tips-get-ahead-capital-gains-taxes)
- Selling Stocks and Bonds: How to Avoid Capital Gains Taxes (https://ml.com/articles/selling-high-performing-stocks-3-ideas-to-help-minimize-capital-gains-taxes.html)
- Required Minimum Distributions (RMDs): Plan Ahead to Manage AGI
- These are smart moves for required withdrawals in retirement when you don’t need the money (https://cnbc.com/2025/08/12/required-minimum-distributions.html)
- Tips to Reduce the Tax Impact of RMDs on Retirement Income (https://brandywineoak.com/reduce-tax-impact-of-rmds-on-retirement-income)
- 6 Tips for Strategically Timing RMDs (https://cgnadvisors.com/rethinking-when-to-take-your-rmds)
- Taxation of required minimum distributions | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/taxation-of-required-minimum-distributions)
- Required Minimum Distributions: What’s New in 2025 (https://schwab.com/learn/story/required-minimum-distributions-what-you-should-know)
- Municipal Bond Income: A Tax-Advantaged Investment for Lower AGI
- Municipal bond yields offer attractive returns for individual investors. Could Congress kill their tax advantage? | CNN Business (https://cnn.com/2025/05/05/business/municipal-bond-yields-tax-advantage)
- Tax-efficient fund placement – Bogleheads (https://bogleheads.org/wiki/Tax-efficient_fund_placement)
- Why longer municipal strategies make sense now | Fortune (https://fortune.com/2025/10/04/why-longer-municipal-strategies-make-sense-now)
- Protecting Tax Exemption for Municipal Bonds – United States Conference of Mayors (https://usmayors.org/issues/protecting-tax-exemption-for-municipal-bonds)
- Lowering Your AGI and Student Loan Payments with Municipal Bonds: A Win-Win Solution (https://studentloanplanner.com/municipal-bond-reduce-agi)
- Avoid Common Pitfalls: Strategies to Prevent AGI Increase
- Checklist: 10 High-Income Tax Planning Strategies to Use Before 2025 Ends (https://harness.co/articles/year-end-tax-planning)
- Consider these strategies to potentially reduce your taxes. (https://ameriprise.com/financial-goals-priorities/taxes/ways-to-lower-taxes)
- How I’m Talking About Taxes to Clients Who Started a Family in 2025 (https://investopedia.com/fa-one-thing-2025-tax-planning-for-new-families-11834650)
- The Complete Tax Planning Guide for Parents: Maximizing Deductions, Credits, and Savings (https://blog.taxact.com/tax-planning-for-new-parents)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading