

Key Highlights:
- Understanding 403(b) inheritance rules is crucial for families to manage financial futures effectively.
- Beneficiaries must withdraw inherited 403(b) funds within 10 years, as mandated by the SECURE Act.
- Regularly updating beneficiary designations is vital to prevent unintended asset distribution.
- Inherited 403(b) distributions are taxed as ordinary income, which can impact tax brackets significantly.
- Options for beneficiaries include lump-sum distributions, inherited IRA rollovers, or maintaining the account.
- Spousal beneficiaries can treat inherited accounts as their own, offering more flexibility in management.
- State laws affect how 403(b) assets are passed on, making local regulations important for estate planning.
- Consulting with financial advisors can provide personalised strategies for managing inherited assets and tax implications.
Introduction
Navigating the complexities of 403(b) inheritance rules can feel overwhelming, especially for young parents who are dedicated to securing their family’s financial future. It’s essential to grasp these regulations, as they determine how inherited assets are managed and the tax implications that follow. Imagine the uncertainty if a parent passes away without clear guidance on these rules. This article delves into ten vital 403(b) inheritance rules that every young parent should be aware of, empowering families to make informed decisions and protect their legacy. Together, we can navigate this journey.
Bright Advisers: Personalized Guidance on 403(b) Inheritance Rules for Parents
Families may find it overwhelming to navigate the complexities of 403b inheritance rules. At Bright Advisers, we understand the challenges you face, and we’re here to help. By simplifying budgeting, we empower parents like you to grasp your options and obligations, enabling informed choices that align with your family values and financial dreams.
Imagine if you could confidently manage your family’s financial future. Understanding the 403b inheritance rules is essential, especially for young families. Efficient budgeting can significantly impact your long-term wealth and stability. With our support, you can explore and effectively utilize inherited assets, helping to reduce tax obligations while enhancing your legacy.
Together, we can navigate the intricacies of 403b inheritance rules. Our expert guidance ensures that you feel secure in your financial decisions, paving the way for a brighter future for your children. Remember, you’re not alone in this journey; we’re here for you every step of the way.

Understanding 403(b) Inheritance Rules: Key Regulations Every Parent Must Know
As a parent, it’s crucial to understand the ins and outs of 403(b) plans, especially if you’re navigating the complexities of financial planning for your family. These plans, often offered by educational institutions and non-profits, come with specific that can impact your loved ones.
Imagine if something were to happen to you. Would your family know how to access the funds you’ve set aside? It’s important to understand that recipients of 403(b) plans must follow the 403b inheritance rules, which require them to withdraw funds within a certain timeframe. This is often determined by the [SECURE Act](https://brightadvisers.com/?p=11333), which states that most non-spouse beneficiaries need to exhaust the funds within 10 years of the account holder’s passing.
By being informed about the 403b inheritance rules, you can ensure your family is better prepared for the future. Knowing the rules can help you make decisions that align with your family’s values and priorities. Remember, we’re here for you every step of the way, helping you navigate this journey together.

Beneficiary Designations: How They Impact 403(b) Inheritance for Families
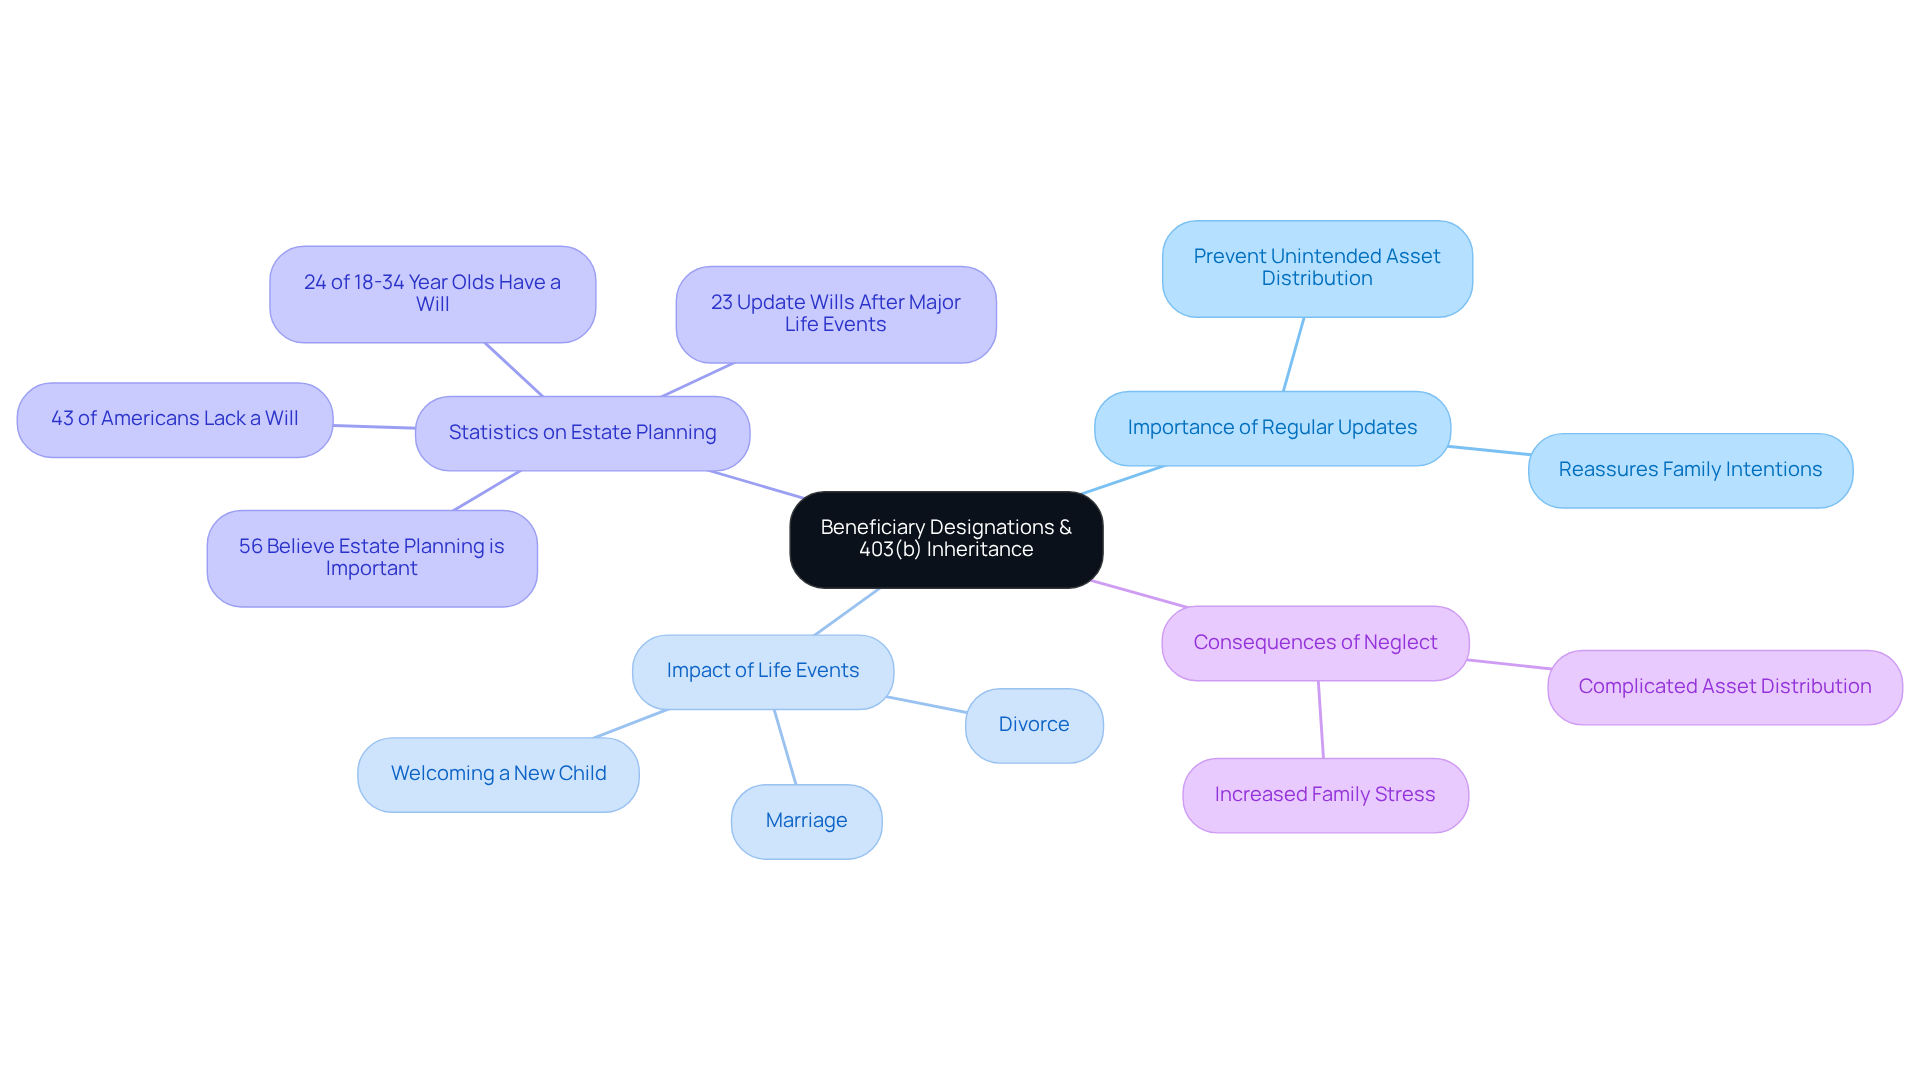
Beneficiary designations are vital for understanding the 403b inheritance rules that determine who inherits a 403(b) account. It’s essential for parents to regularly review and update these designations, especially after significant life events like marriage, divorce, or welcoming a new child. Imagine the stress a family might face if a former spouse remains the designated recipient – this could lead to unintended asset distribution and heartache.
Statistics show that nearly 43% of Americans don’t have a will or estate planning documents, often due to procrastination. This can complicate matters further, leaving families in difficult situations. Estate planning experts stress the importance of keeping designation updates current. As one expert wisely notes, “Neglecting to revise your designation of recipients can lead to your assets being allocated against your desires, particularly during periods of transition.” This highlights the need for families to take proactive steps in managing their legacies.
Life events can greatly impact the 403b inheritance rules for recipient designations. For instance, after the joy of welcoming a new child, parents should ensure their accounts reflect their current family structure. This not only secures their children’s financial future but also brings peace of mind, knowing that assets will be distributed according to the family’s wishes.
Regularly updating these designations prevents complications and reassures families that their intentions will be honored. Together, we can navigate this journey, ensuring that your and cherished.
Tax Implications of Inheriting a 403(b): What Parents Need to Consider
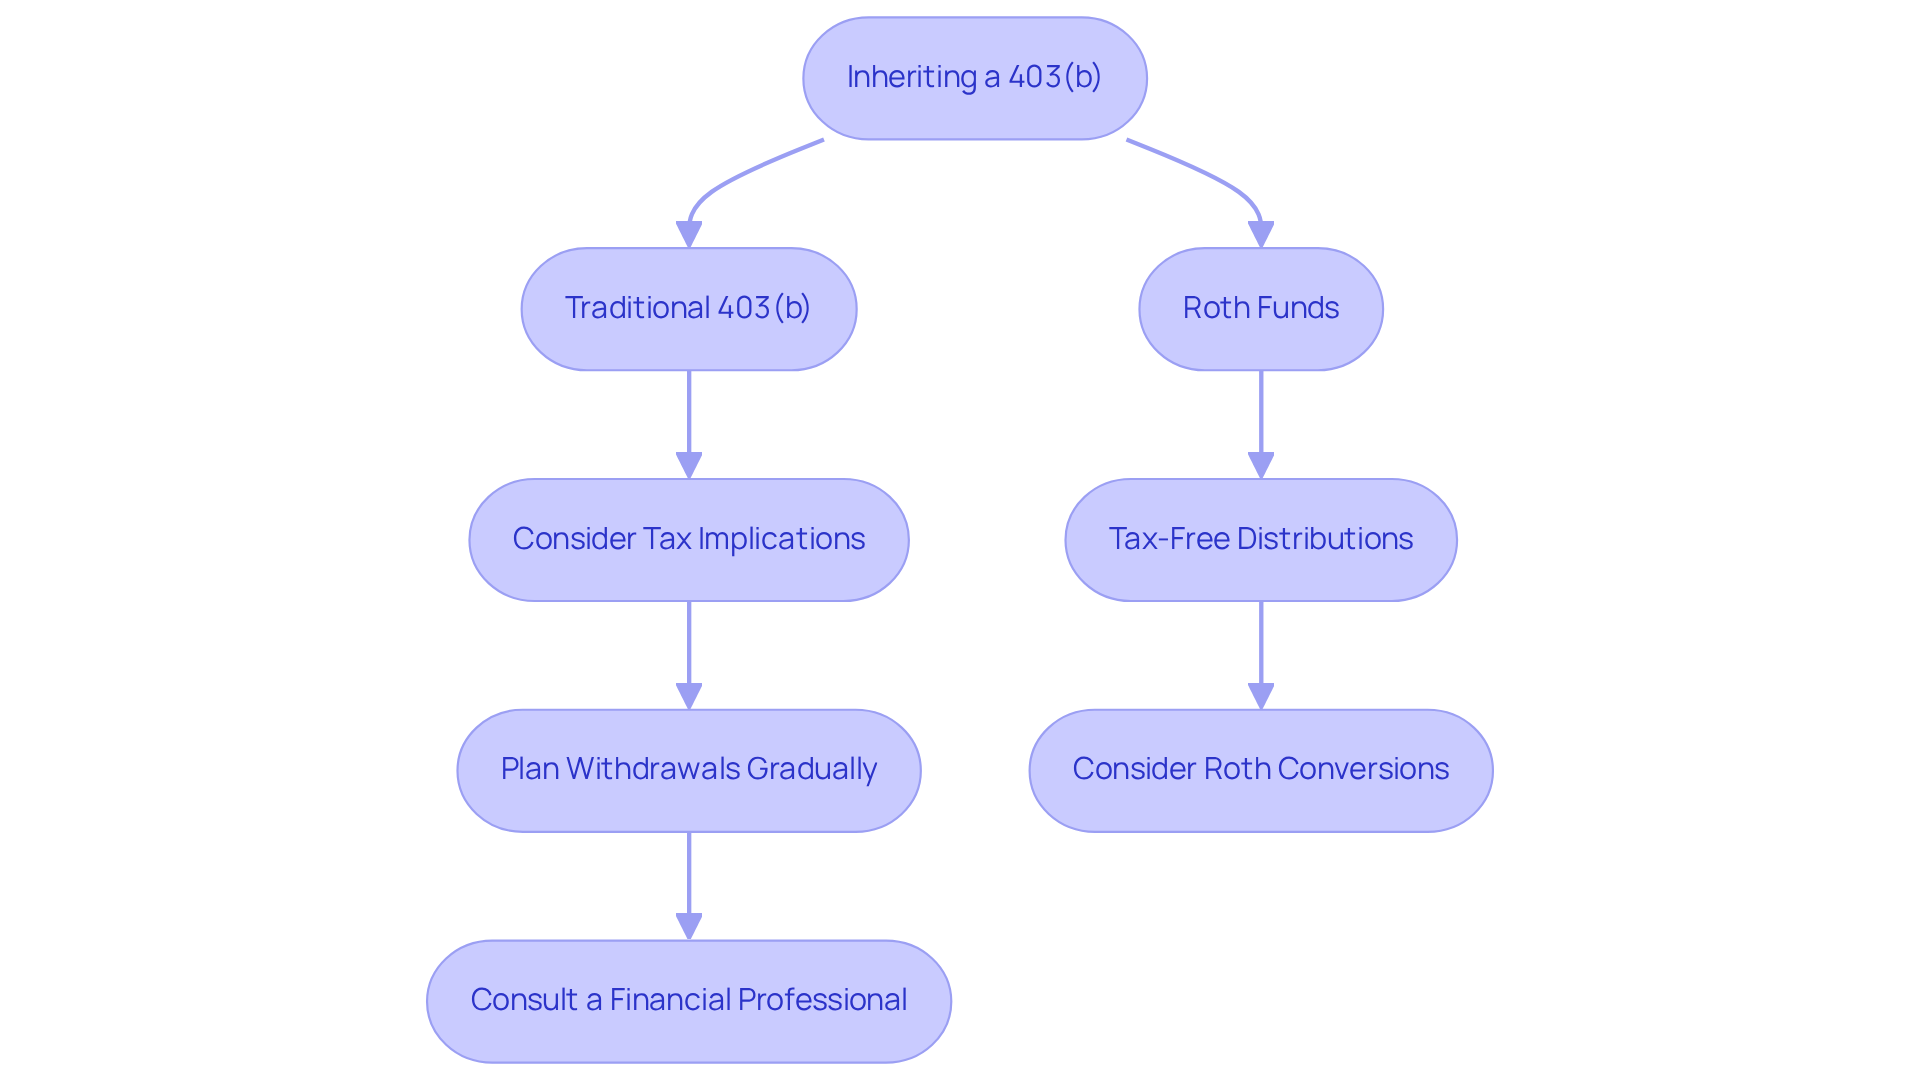
Navigating the world of 403(b) distributions can feel overwhelming, especially when considering the tax implications that come with it. It’s crucial to understand that distributions from a traditional 403(b) are taxed as ordinary income, which can significantly impact your tax bracket. Imagine if you were to withdraw a large sum all at once; you might find yourself unexpectedly pushed into a higher tax bracket, leading to a larger tax bill. Many families managing inherited 403(b) plans choose to follow the 403b inheritance rules by taking gradual withdrawals, allowing them to stay within a lower tax bracket and better manage their overall tax liability.
We understand that this can be a lot to handle, which is why tax advisors recommend , like those at Bright Advisers. They can help you devise a thoughtful strategy for managing these distributions, including essential tax planning and preparation services. This guidance is especially important for non-spouse beneficiaries, as the 403b inheritance rules require them to withdraw all funds from the inherited 403(b) within ten years. Careful planning can help you avoid unexpected tax burdens during this time.
If your portfolio includes Roth funds, there’s good news! Heirs can benefit from tax-free distributions, which highlights the importance of strategic withdrawal planning. By employing strategies like Roth conversions, you can lower future tax obligations, particularly if the original holder’s tax rate is less than that of the beneficiaries.
By grasping the subtleties of the 403b inheritance rules, families can make informed choices that align with their financial goals while minimizing tax implications. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Options for Beneficiaries: Managing Inherited 403(b) Plans Effectively
Navigating the 403b inheritance rules for managing an inheritance from a 403(b) plan can feel overwhelming, but you’re not alone. Beneficiaries have several paths to consider, each with its own set of benefits and challenges. It’s essential to choose what aligns best with your financial situation and long-term goals.
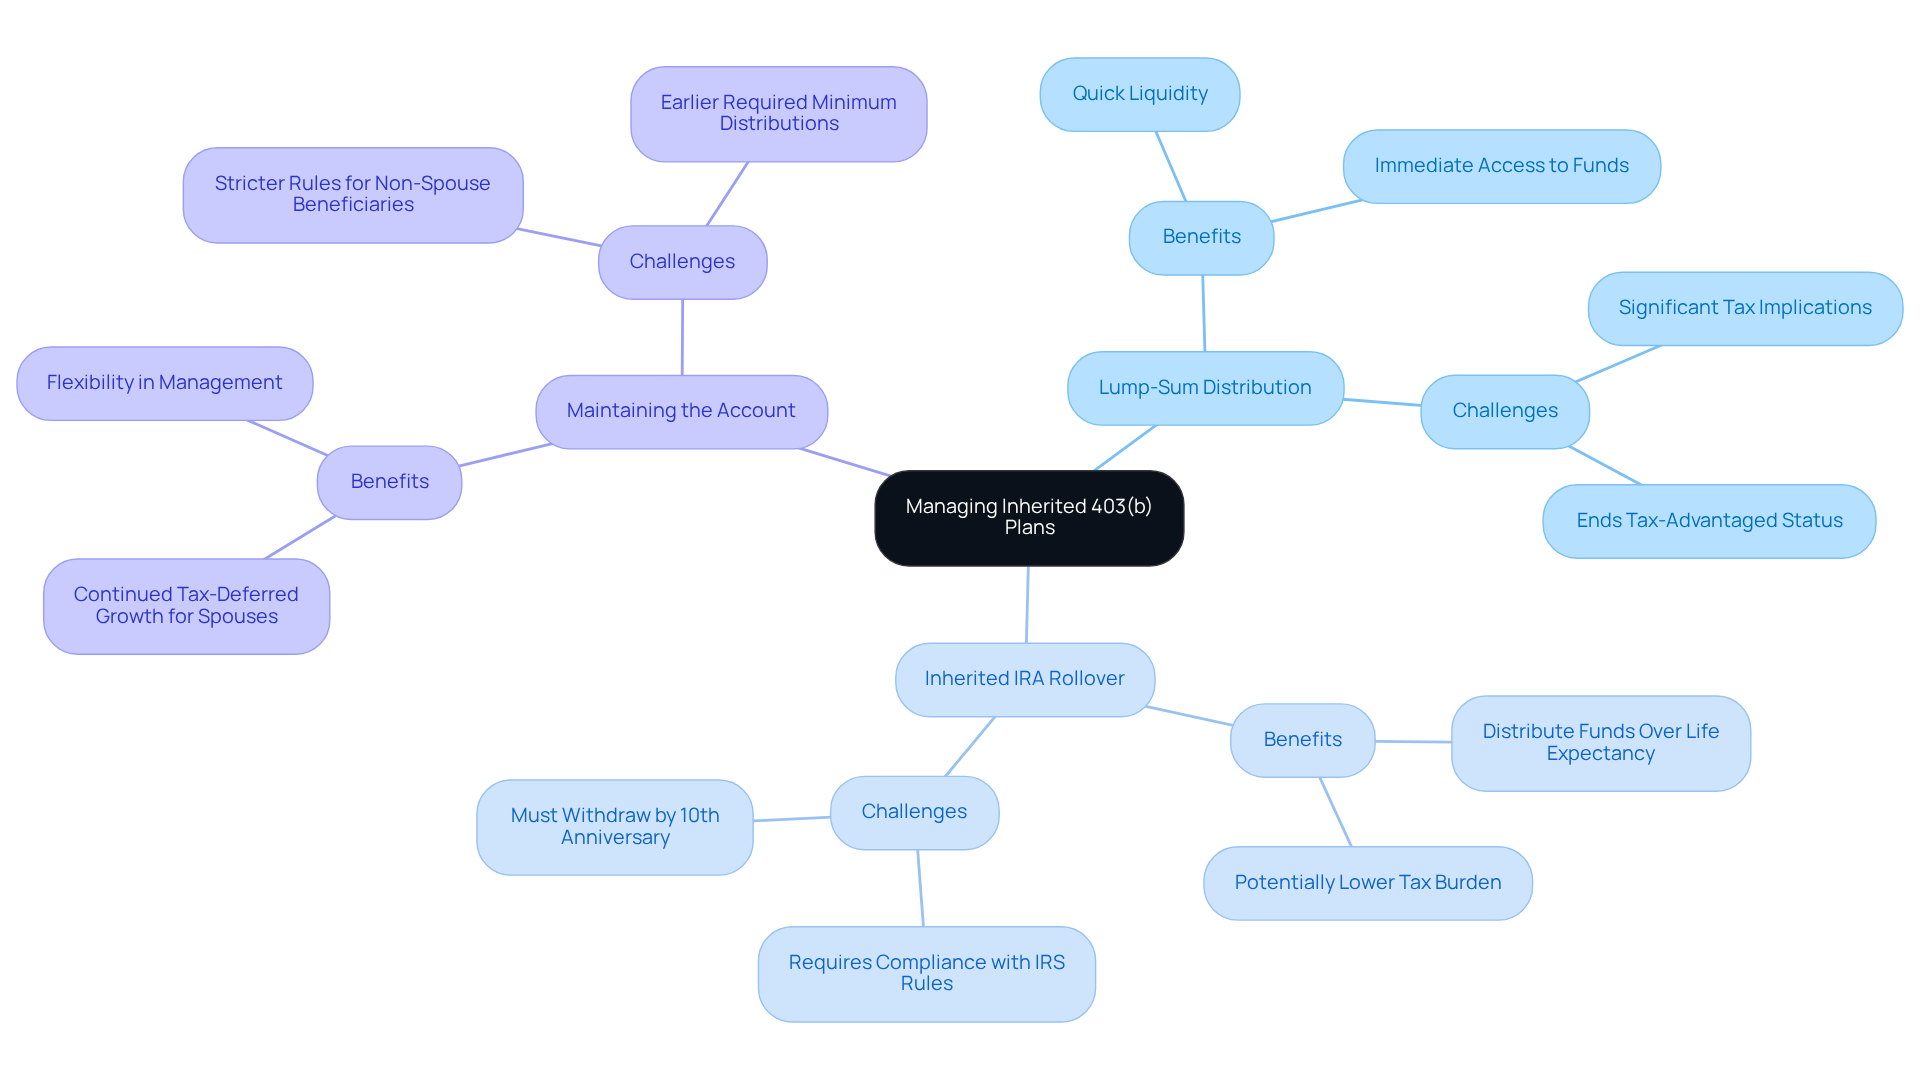
Lump-Sum Distribution: Imagine having immediate access to the entire account balance. This option offers quick liquidity, which can be tempting. However, it’s crucial to be aware that this choice can lead to significant tax implications, as the full amount is subject to income tax in the year you withdraw it. Plus, opting for this route ends the tax-advantaged status of the inherited assets, which might not be the best fit for your future financial planning.
Inherited IRA Rollover: Now, consider rolling over the funds into an inherited IRA. This can be a smart move, allowing you to distribute funds over your life expectancy, which may help reduce your tax burden. Just remember, it requires careful management to stay compliant with IRS rules, especially regarding required minimum distributions (RMDs). If you’re a beneficiary, you’ll need to withdraw the entire balance by December 31 of the year marking the 10th anniversary of the original owner’s passing, unless you qualify as an eligible designated beneficiary, which can extend your distribution period.
Maintaining the Account: Another option is to keep the 403(b) plan as it is. This can be particularly beneficial for spouses, who can treat the inherited account as their own, allowing for continued tax-deferred growth. However, if you’re a non-spouse recipient, be aware that stricter rules apply, and you’ll need to start taking distributions sooner.
As you weigh these options, it’s vital to consider your individual tax bracket and financial goals. For instance, if you find yourself in a higher tax bracket, the inherited IRA rollover might be the way to go to manage your tax exposure over time. On the other hand, if you need immediate funds, a lump-sum distribution could be appealing, despite the tax consequences.
Ultimately, managing inherited 403(b) plans effectively requires a good understanding of the 403b inheritance rules regarding distributions and the potential tax implications. We’re here for you- can help you navigate these complexities and make informed decisions that align with your family’s financial future. Together, we can navigate this journey.
Rollover Strategies: How to Handle Inherited 403(b) Accounts
Imagine if you could ensure your family’s financial future while navigating the complexities of inherited funds. According to the 403b inheritance rules, beneficiaries of an inherited 403(b) have a wonderful option: rolling over those funds into an inherited IRA. This choice not only allows for continued tax-deferred growth but also opens up more flexible withdrawal options compared to keeping the funds in the 403(b).
It’s important to understand that following the correct rollover procedures is crucial to avoid significant tax penalties. For instance, if you miss taking required minimum distributions (RMDs), you could face a hefty penalty equal to 50% of the amount that should have been withdrawn. As True Tamplin, CEO of UpDigital, wisely points out, ‘Any individual or entity identified as a recipient by the original account holder can inherit a 403(b) plan according to the 403b inheritance rules.’
Navigating these complexities can feel overwhelming, but consulting with a financial advisor can make a world of difference. They can help you understand your options and ensure compliance with IRS rules. Many advisors emphasize that transferring to an inherited IRA can be a favorable decision. It allows recipients to manage their tax responsibilities more efficiently while optimizing the growth potential of their inherited assets.
You have choices when it comes to handling these funds. Recipients can opt for:
- A lump sum distribution
- A stretch distribution
- Transferring funds to an inherited IRA
Each option comes with different tax consequences, so it’s essential to weigh them carefully.
Remember, we’re here for you. Together, we can navigate this journey and make the .

Distribution Rules: Navigating Withdrawals from Inherited 403(b) Plans
Navigating the world of inherited 403(b) plans can feel overwhelming, especially when it comes to understanding the 403b inheritance rules and specific distribution. For many families, ensuring compliance while optimizing tax efficiency is a top priority. If you’re not a spouse, it’s essential to know the 403b inheritance rules, which typically require you to withdraw the total funds within 10 years after the account holder’s passing. This timeline is crucial – missing it can lead to significant penalties. Imagine facing a 50% excise tax on the amount you should have withdrawn but didn’t. That’s a heavy burden to bear.
Families who have successfully managed their withdrawals often share how strategic planning made all the difference. By working with financial specialists, they’ve implemented tax-efficient withdrawal strategies that not only minimize their tax burden but also align with their family’s financial goals. This proactive approach helps avoid penalties and ensures that the inherited funds are used effectively.
It’s also vital to regularly review and update your beneficiary designations. Accurate designations can prevent unintended asset distribution and ensure that the inherited funds support your family’s estate planning goals. With recent changes like the , which raises federal estate, gift, and generation-skipping transfer tax exemption thresholds, careful planning has never been more important.
As the landscape of retirement fund regulations evolves, staying informed is key. Recent updates, including those from the SECURE Act, highlight the need for thoughtful planning and execution of withdrawal strategies that comply with 403b inheritance rules. Together, we can navigate this journey, ensuring that your family’s financial future is secure and aligned with your values.

Spousal Beneficiaries: Special Considerations for 403(b) Inheritance
According to the 403b inheritance rules, spousal beneficiaries truly have an edge when it comes to inherited 403(b) plans. They can treat the inherited account as their own under the 403b inheritance rules, which opens up a world of flexibility in how they manage withdrawals and contributions.
Imagine young parents like Allison and Brian, who turned to Bright Advisers for guidance. They wanted to enhance their financial situation through thoughtful tax planning. By looking at their overall financial picture, they discovered how spousal benefits could not only improve their immediate financial flexibility but also help secure their family’s future.
It’s important to understand that making informed decisions about these options can be a game-changer for families. With the right support, you can together, ensuring that your family’s needs are met today and in the years to come.
We’re here for you, ready to help you explore these options and find the best path forward for your family.

State Laws and 403(b) Inheritance: What Parents Should Be Aware Of
Understanding the is essential for parents who want to secure their family’s future. Each state has its own rules about how assets are passed on, and these can greatly affect what happens after a loved one passes away. Imagine if you could ensure that your wishes are honored, even when you’re not there to voice them. Some states may require spousal approval for changes to recipient designations, while others allow for multiple recipients without restrictions. Knowing these details can make a world of difference.
Equally important are the tax implications tied to the 403b inheritance rules associated with 403(b) accounts. Depending on where you live, inherited funds might face different tax treatments, impacting the value that ultimately reaches your beneficiaries. Estate taxes can also vary significantly, which is why it’s essential to be proactive in your estate planning. Even if your resources are limited, you can still leave a meaningful inheritance. This underscores the importance of having a well-thought-out estate plan that reflects your family’s values and priorities.
Consulting with a local financial advisor or estate planning attorney can provide you with personalized insights into these regulations. As estate planning experts often say, “If you do not have a Will or plan for your estate, then the government has one for you.” This serves as a gentle reminder that taking control of your financial legacy is crucial. Benjamin Franklin wisely noted, “By failing to plan, you are preparing to fail.” This highlights the importance of being informed about local laws and seeking professional guidance.
By understanding these aspects and reaching out for help, you can ensure that your 403(b) accounts are managed in accordance with the 403b inheritance rules. Together, we can navigate this journey, providing peace of mind for you and your family.

Consulting Financial Advisors: The Key to Navigating 403(b) Inheritance Rules
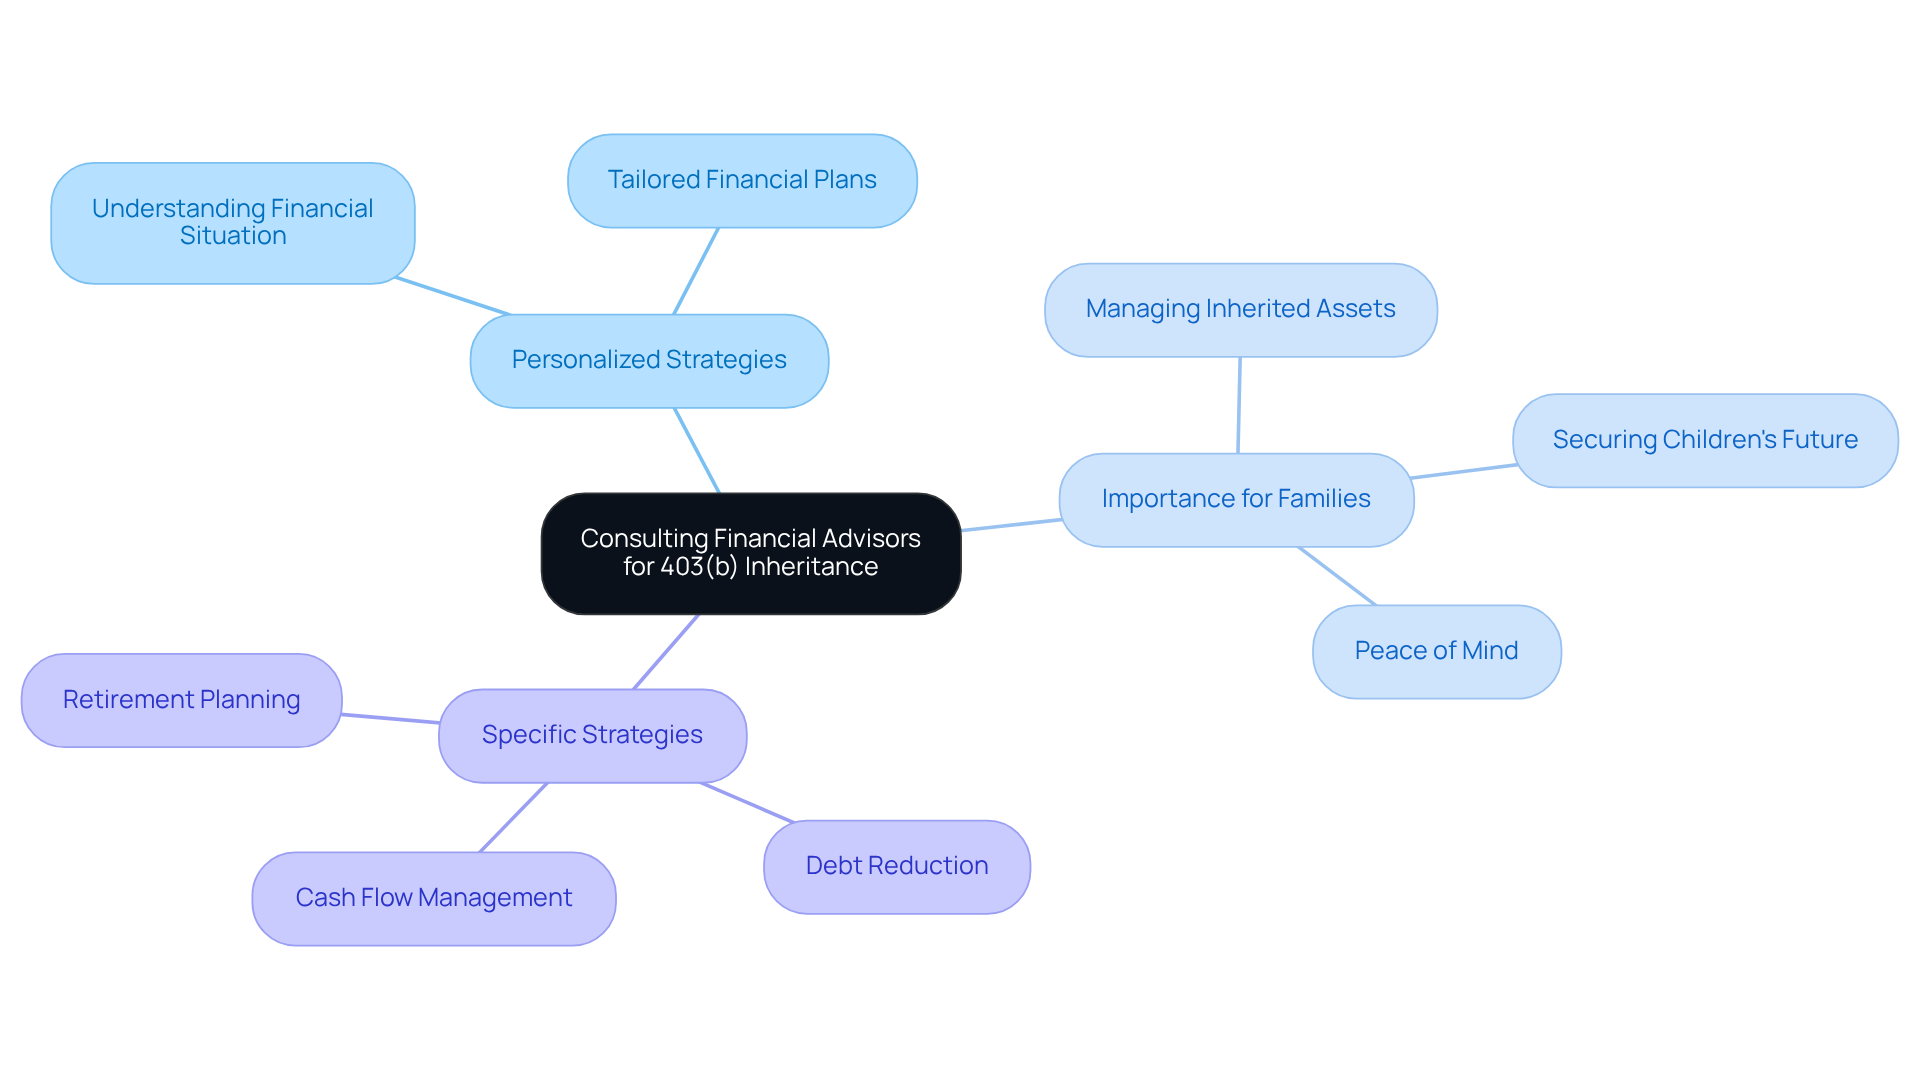
For families, navigating the complexities of 403b inheritance rules can feel overwhelming. That’s why consulting with a monetary advisor is so important. At Bright Advisers, we understand your unique situation and provide personalized strategies that cater to your family’s needs.
Imagine being able to plan for your children’s future while efficiently managing inherited assets. Our advisors help with tax planning and ensure compliance with all regulations, giving you peace of mind. This support is especially crucial for young parents who want to secure their children’s economic future.
Take Emily and Mark, for example. By working with Bright Advisers, they gained a clearer understanding of their financial situation. They crafted comprehensive plans that not only focus on enhancing their economic well-being but also allow them to make career choices that align with their desired work-life balance.
Together, we can explore strategies like:
- Debt reduction
- Cash flow management
- Retirement planning
Our goal is to help families achieve financial freedom, making work optional and ensuring a secure future for your children. Remember, we’re here for you every step of the way.
Conclusion
Understanding the nuances of 403b inheritance rules is essential for young parents who want to secure their family’s financial future. By familiarizing themselves with these important guidelines, parents can help their loved ones manage inherited assets effectively, aligning financial decisions with family values and long-term aspirations.
Throughout this article, we’ve highlighted several key points, such as the significance of beneficiary designations, the tax implications of inherited 403(b) accounts, and the various options available for managing these plans. It’s important to stay informed about state laws and seek advice from financial advisors to navigate these complexities with confidence. By doing so, families can sidestep potential pitfalls and enhance their financial strategies.
Ultimately, proactive planning and education about 403b inheritance rules can empower families to make informed decisions that safeguard their legacy. Seeking professional guidance can further enrich this process, ensuring that families not only survive but thrive in their financial journeys. Taking these steps today can pave the way for a more secure and prosperous future for generations to come.
Frequently Asked Questions
What are 403(b) plans and why are their inheritance rules important for parents?
403(b) plans are retirement savings plans often offered by educational institutions and non-profits. Understanding their inheritance rules is crucial for parents as it impacts how their loved ones can access and manage the funds set aside in case of the account holder’s passing.
What do the 403(b) inheritance rules require from beneficiaries?
The 403(b) inheritance rules require beneficiaries, especially non-spouse beneficiaries, to withdraw the funds within a certain timeframe, typically within 10 years of the account holder’s passing, as determined by the SECURE Act.
How can families prepare for the potential inheritance of a 403(b) account?
Families can prepare by understanding the 403(b) inheritance rules and ensuring that they are informed about the necessary steps to access the funds. This knowledge helps align financial decisions with family values and priorities.
What role do beneficiary designations play in 403(b) inheritance?
Beneficiary designations determine who inherits a 403(b) account. It is essential for parents to regularly review and update these designations, especially after significant life events, to ensure assets are distributed according to their wishes.
What are the consequences of not updating beneficiary designations?
Failing to update beneficiary designations can lead to unintended asset distribution, such as a former spouse inheriting the account, which can create stress and complications for families during difficult times.
Why is estate planning important for families regarding 403(b) accounts?
Estate planning is important because it helps ensure that a family’s intentions regarding asset distribution are honored. Regularly updating beneficiary designations and having a will can prevent complications and provide peace of mind.
How can Bright Advisers assist families with 403(b) inheritance rules?
Bright Advisers offers personalized guidance to help families navigate the complexities of 403(b) inheritance rules, empowering them to make informed financial decisions and explore proactive tax planning to enhance their legacy.
List of Sources
- Bright Advisers: Personalized Guidance on 403(b) Inheritance Rules for Parents
- Can Beneficiaries Elect Timing of Payments From Inherited 403(b) Assets? | PLANSPONSOR (https://plansponsor.com/can-beneficiaries-elect-timing-payments-inherited-403b-assets)
- New Rules For Non Spouse Beneficiaries Of Retirement Accounts Starting In 2020 | Greenbush Financial Group (https://greenbushfinancial.com/all-blogs/new-rules-for-non-spouse-beneficiaries-of-retirement-accounts-starting-in-2020)
- Ask an Advisor: Will the $500k in My Retirement Account Be Taxed When My Heirs Inherit it? (https://smartasset.com/financial-advisor/ask-an-advisor-500k-inheritance)
- What are the rules for inheriting a 403(b)? (https://marketwatch.com/story/what-are-the-rules-for-inheriting-a-403b-2019-04-19?gaa_at=eafs&gaa_n=AWEtsqdbWARQ10v-Q9MM9S7ua2Tt8q8TlCEgJVWyGImK-ig8FeOAOLS8kE3g&gaa_ts=69277588&gaa_sig=hlFD6QytgC2kl8z_b1tWN9QEdlewVSrSUh4xuddwHQpafSIQnHNNZadBjstx3YuhGIqL05OYMS8AVJZ3ghcsVQ%3D%3D)
- Beneficiary Designations: How They Impact 403(b) Inheritance for Families
- Estate Planning Statistics to Read Before Writing Your Will (https://legalzoom.com/articles/estate-planning-statistics)
- Tax Implications of Inheriting a 403(b): What Parents Need to Consider
- Ask an Advisor: Will the $500k in My Retirement Account Be Taxed When My Heirs Inherit it? (https://smartasset.com/financial-advisor/ask-an-advisor-500k-inheritance)
- Ask an Advisor: Will the $500k in My Retirement Account Be Taxed When My Heirs Inherit it? (https://nasdaq.com/articles/ask-advisor-will-500k-my-retirement-account-be-taxed-when-my-heirs-inherit-it)
- Options for Beneficiaries: Managing Inherited 403(b) Plans Effectively
- Inheriting a 403(b) Plan: What to Do & How It Works | MissionSquare (https://missionsq.org/products-and-services/403(b)-defined-contribution-plans/403(b)-inheritance-beneficiary.html)
- Retirement topics – Beneficiary | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary)
- Inherited 403(b) Plan | Definition, Eligibility, Distribution Options (https://financestrategists.com/retirement-planning/qualified-retirement-plans/403b-plans/inherited-403b-plan)
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)
- What Happens to Your 403(b) When You Die: A Complete Guide (https://westernsouthern.com/retirement/what-happens-to-my-403b-when-i-die)
- Rollover Strategies: How to Handle Inherited 403(b) Accounts
- Inherited 403(b) Plan | Definition, Eligibility, Distribution Options (https://financestrategists.com/retirement-planning/qualified-retirement-plans/403b-plans/inherited-403b-plan)
- Distribution Rules: Navigating Withdrawals from Inherited 403(b) Plans
- One Big Beautiful Bill Act, 2025 SECURE Act Updates and Beneficiary Designations in Estate Plans | Phillips Lytle LLP (https://phillipslytle.com/one-big-beautiful-bill-act-2025-secure-act-updates-and-beneficiary-designations-in-estate-plans)
- Spousal Beneficiaries: Special Considerations for 403(b) Inheritance
- Retirement topics – Beneficiary | Internal Revenue Service (https://irs.gov/retirement-plans/plan-participant-employee/retirement-topics-beneficiary)
- Inheriting a 403(b) Plan: What to Do & How It Works | MissionSquare (https://missionsq.org/products-and-services/403(b)-defined-contribution-plans/403(b)-inheritance-beneficiary.html)
- New RMD Rules For Spousal Beneficiaries Of Retirement Accounts (https://kitces.com/blog/rmd-spousal-election-secure-2-0-secure-act-rmd-rules-spousal-beneficiaries-retirement-account)
- What Happens to Your 403(b) When You Die: A Complete Guide (https://westernsouthern.com/retirement/what-happens-to-my-403b-when-i-die)
- Planning for Asset Transfer: A Deeper Dive into Financial Accounts (https://aafmaa.com/learning-hub/blog/post/9688/planning-for-asset-transfer-a-deeper-dive-into-financial-accounts)
- State Laws and 403(b) Inheritance: What Parents Should Be Aware Of
- 10 Inspirational Quotes About Estate Planning (https://nelsonlawgrouppc.com/10-inspirational-quotes-about-estate-planning)
- 12 Inspirational Quotes About Estate Planning – Leigh Hilton (https://dentonestateplanninglawyer.com/12-inspirational-quotes-about-estate-planning)
- Consulting Financial Advisors: The Key to Navigating 403(b) Inheritance Rules
- Few heirs keep their parents’ wealth advisors — most wealthy benefactors don’t mind (https://cnbc.com/2025/10/16/heirs-parents-wealth-advisor-cerulli-study.html)
- The Role of Financial Advisers in Managing Your Inheritance – CAA (https://coastaladvicegroup.com.au/blog/managing-your-inheritance)
- 7 Steps to Master Family Asset Management for Young Parents – Bright Advisers (https://brightadvisers.com/7-steps-to-master-family-asset-management-for-young-parents)
- Inheritors Plan to Seek Financial Advice When the Money Arrives: Survey (https://thinkadvisor.com/2022/12/06/inheritors-plan-to-seek-financial-advice-when-the-money-arrives-survey)
- Preparing for — and managing — an inheritance (https://ameriprise.com/financial-goals-priorities/family-estate/managing-an-inheritance)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading