

Overview
Custodial Roth IRAs are vital for young parents, offering a nurturing, tax-advantaged way to save for their children’s future. Imagine providing your child with a financial head start, as these accounts require that the child has earned income to contribute, with a limit of $7,000. This approach not only supports their growth but also fosters financial literacy from an early age.
The benefits are significant:
- Tax-free growth
- Flexibility in withdrawals
- The chance for parents to teach their children about investing
It’s important to understand how these advantages can resonate with your family’s values and priorities, creating a foundation for a secure future.
Together, we can navigate this journey toward financial empowerment. By engaging with custodial Roth IRAs, you are not just saving money; you are instilling essential lessons that will benefit your children throughout their lives. We’re here for you, supporting your efforts to make informed financial decisions that matter for your family.
Key Highlights:
- Bright Advisers offers personalised financial planning for families with young children, focusing on custodial Roth IRAs.
- Families can transfer up to $35,000 from a 529 plan to a Roth IRA, enhancing children’s economic futures.
- Custodial Roth IRAs require children to have earned income to qualify for contributions, limited to $7,000 or their total earned income.
- Around 40% of minors with earned income qualify for Roth IRAs, highlighting the need for early financial education.
- Withdrawals from Roth IRAs can be made tax-free after five years and if the individual is at least 59½ years old.
- Contributions can be withdrawn at any time without penalties, providing flexibility for parents.
- Custodial Roth IRAs grow tax-free, benefiting from low tax rates for minors, and instilling financial responsibility.
- Investment options include stocks, bonds, mutual funds, and ETFs, emphasising the importance of a diversified portfolio.
- Parents can contribute to their child’s account based on the child’s earnings, regardless of their own income level.
- The article outlines pros and cons of custodial Roth IRAs, emphasising long-term growth potential alongside liquidity challenges.
Introduction
The financial landscape for young families is evolving, presenting unique opportunities for parents eager to secure their children’s futures. Custodial Roth IRAs offer a powerful tool for instilling financial literacy and fostering long-term growth.
Imagine the benefits of allowing minors to enjoy tax-free savings that can significantly enhance their economic prospects. However, it’s important to understand that navigating the specific requirements and potential pitfalls can feel daunting.
How can parents effectively leverage these accounts to maximize their children’s financial well-being while adhering to IRS guidelines? Together, we can navigate this journey.
Bright Advisers: Personalized Financial Planning for Custodial Roth IRAs
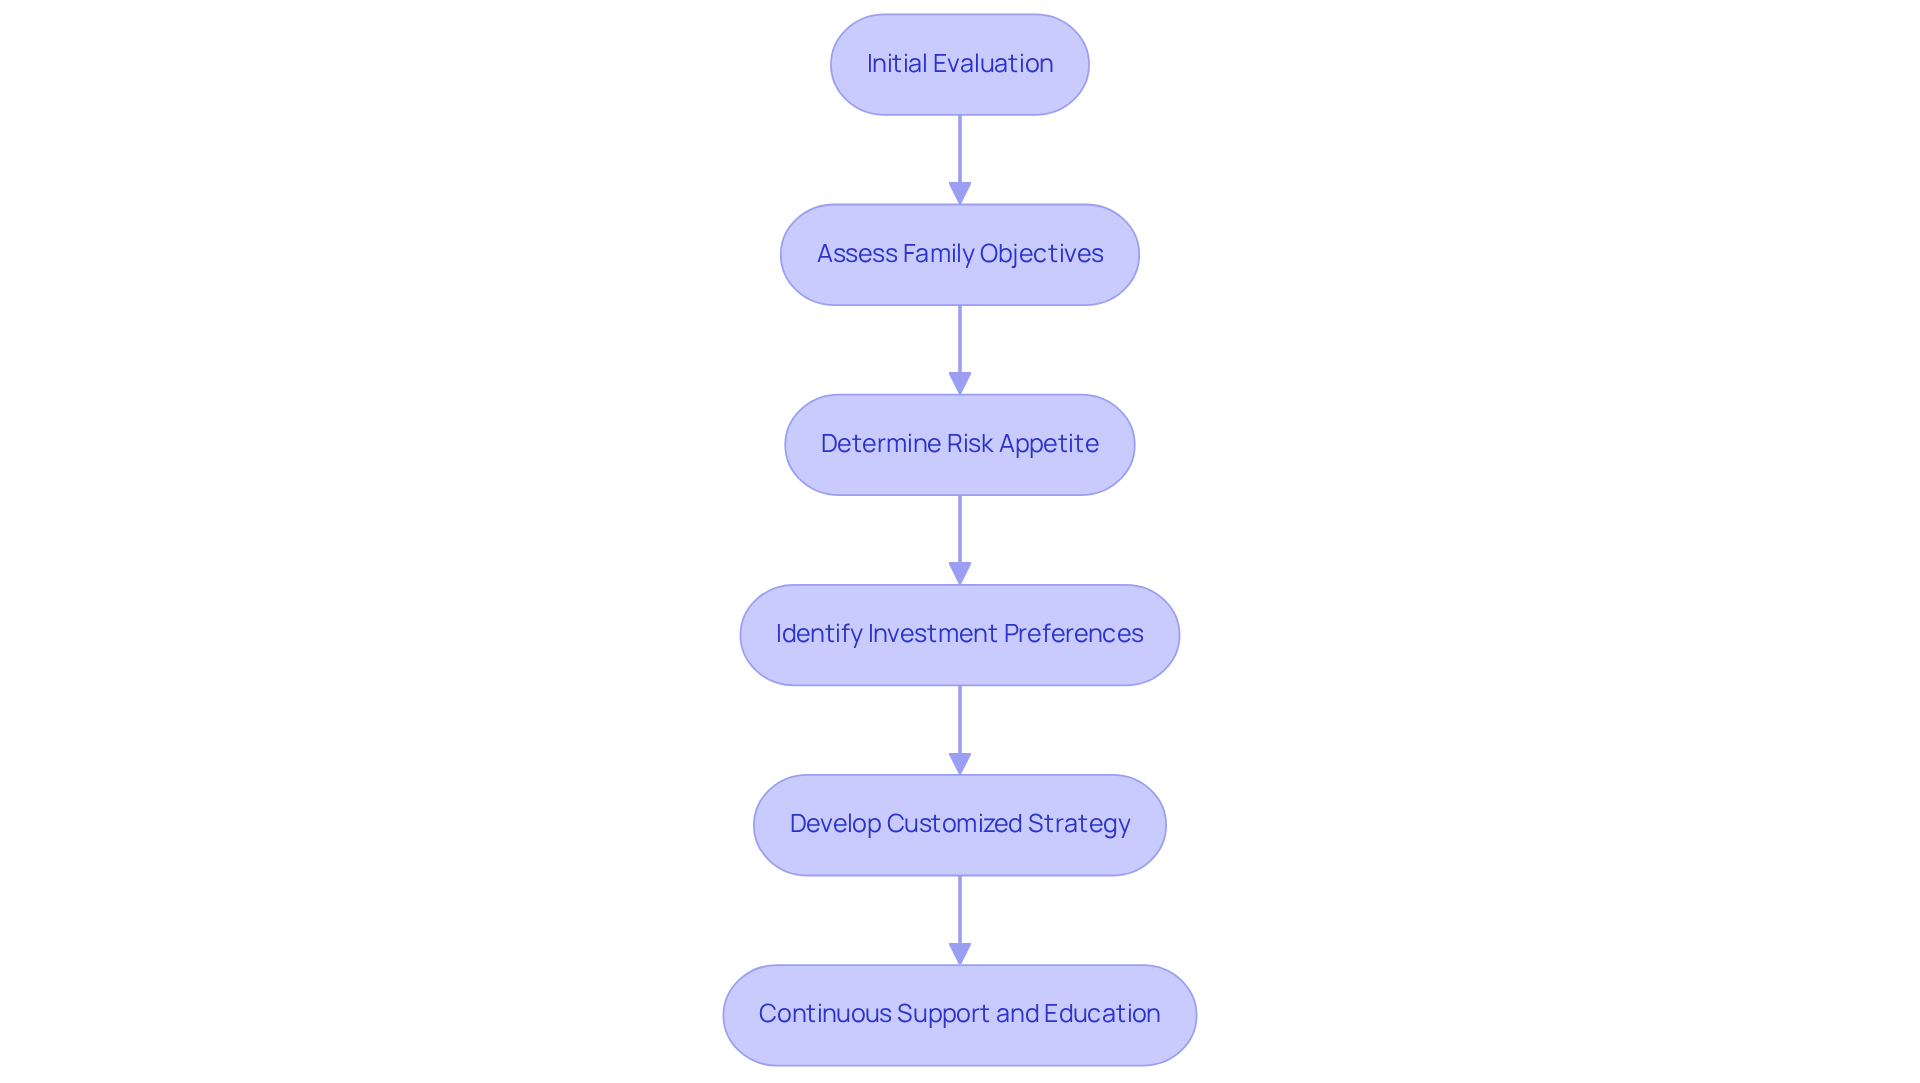
At Bright Advisers, we understand the unique challenges that families with young kids face when it comes to financial planning. We transform traditional IRAs by providing customized strategies that cater to your family’s specific needs. Imagine starting this journey with a thorough evaluation of your family’s objectives, risk appetite, and investment preferences. This thoughtful process paves the way for a tailored strategy designed to maximize the benefits of a custodial IRA while adhering to custodial Roth IRA requirements.
Consider the significant opportunity available: families can transfer up to $35,000 from a 529 plan to a Roth IRA, enhancing your children’s economic futures. With Bright Advisers’ innovative in-house technology, you can enjoy seamless planning that eliminates unnecessary fund fees while capturing valuable tax-loss harvesting opportunities.
Our investment strategies, including the Diversified Premia and Opportunity Strategy, are crafted to maximize monetary outcomes. We provide continuous support and educational resources to empower you, as parents, to make informed decisions. As finance expert Jeff White highlights, “These new rules enhance 529 plan flexibility, providing families another reason to save for college without concerning themselves about a child not going to college.” This underscores the importance of strategic planning in securing your family’s economic future.
If you’re a parent looking to start with managed retirement accounts, we invite you to consult with Bright Advisers. Together, we can create customized strategies that align with your family’s financial objectives. Remember, we’re here for you, ready to navigate this journey together.
Custodial Roth IRA Eligibility: Who Can Open One?
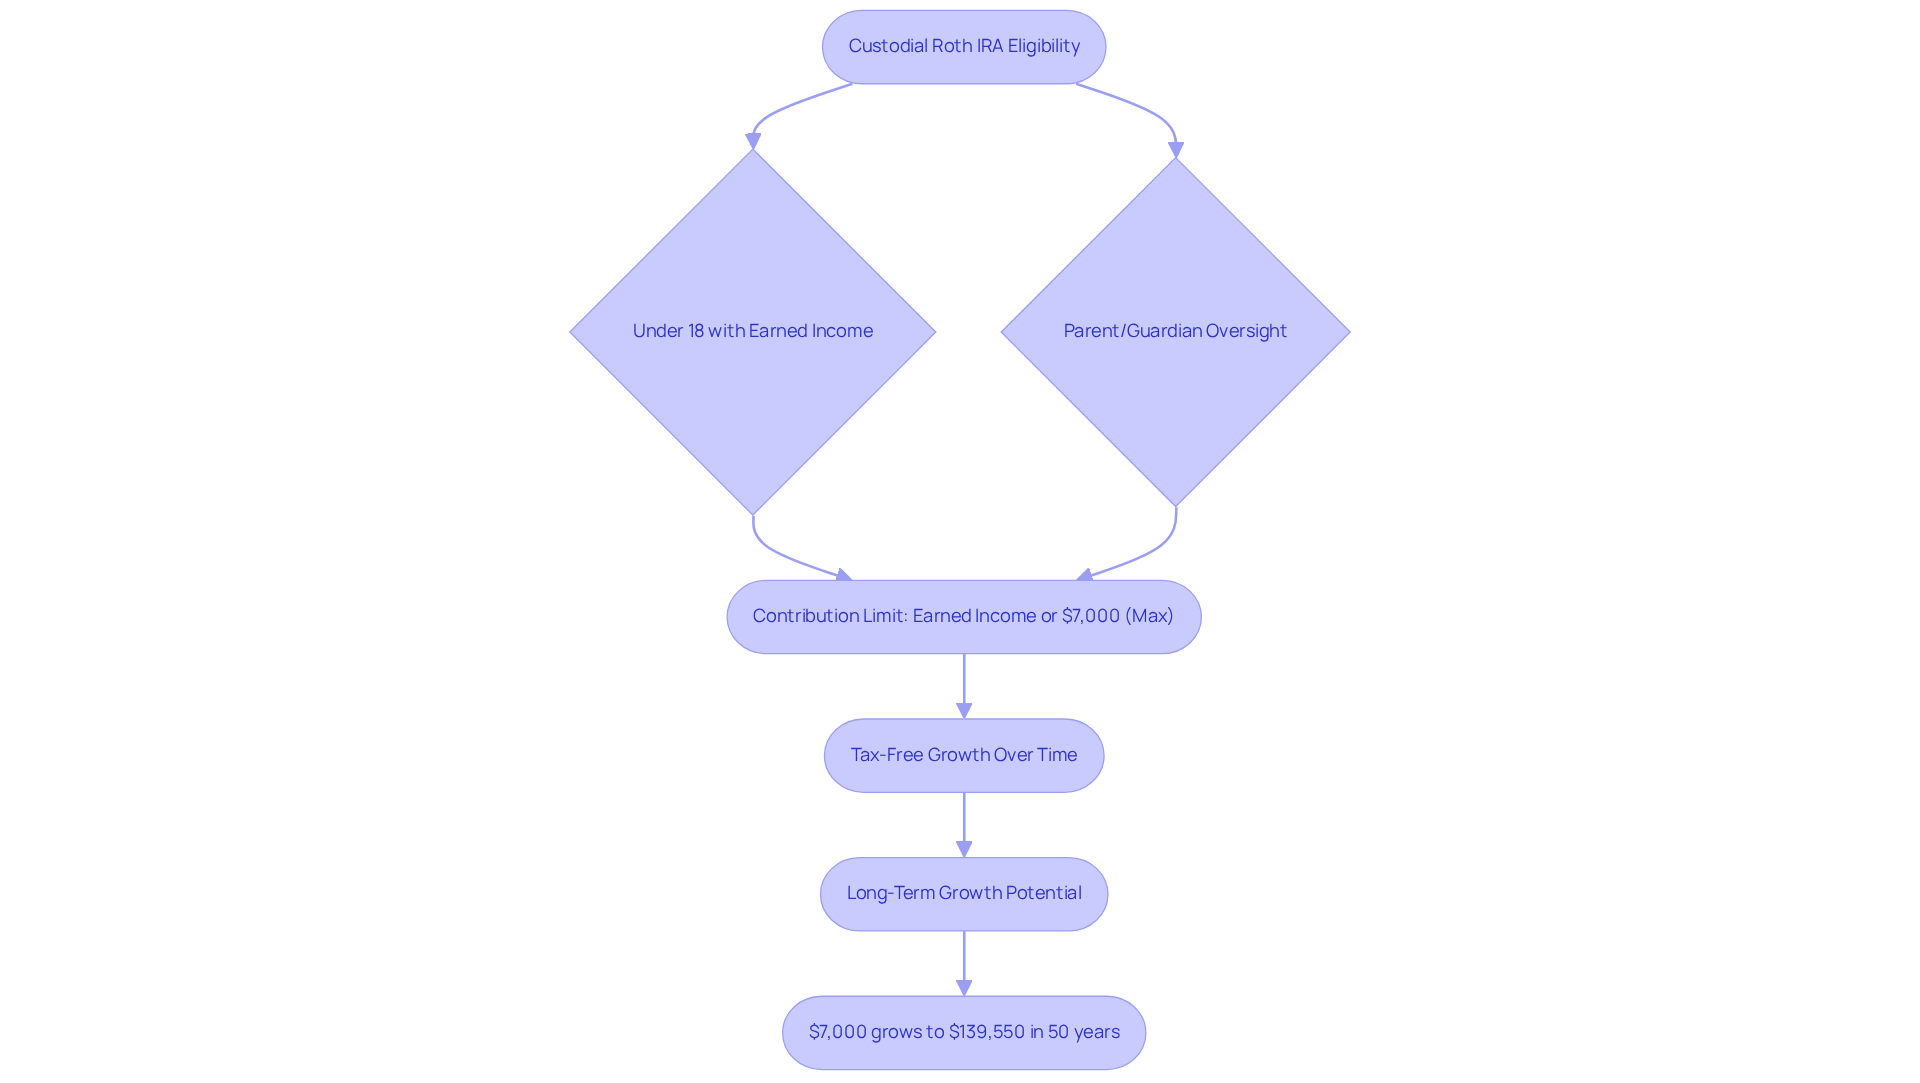
Establishing a custodial Roth IRA is a wonderful step for your child’s financial future, as it helps to meet custodial Roth IRA requirements. If your child is under 18 and has earned income from activities like babysitting or lawn mowing, they may qualify under the custodial Roth IRA requirements. A parent or guardian will oversee the account until the minor satisfies the custodial Roth IRA requirements, which is usually at the age of majority, either 18 or 21, depending on where you live. It’s important to note that contributions are limited to the total earned income for the year, with a maximum of $7,000 in 2025. So, if your child earns $3,000, that’s the amount they can contribute to their IRA.
Recent updates show that around 40% of minors with earned income qualify for Roth IRAs. This highlights the importance of early financial education. Imagine families encouraging their children to take on summer jobs or entrepreneurial activities; they can help them meet eligibility criteria for these valuable accounts.
Tax experts emphasize the significance of earned income for meeting custodial Roth IRA requirements, reminding us that contributions must come from after-tax dollars. This approach not only nurtures a sense of financial responsibility in children but also allows them to enjoy the benefits of tax-free growth over time. As Chris Kawashima wisely noted, “An account for a minor is one that a custodian (typically a parent) opens and manages for their benefit, following the custodial Roth IRA requirements.” The custodial Roth IRA requirements illustrate how the tax advantages of individual retirement accounts can be particularly beneficial for minors, given their typically low tax rates.
Getting started with a managed retirement account early can lead to significant long-term growth. For instance, a one-time contribution of $7,000 could grow to about $139,550 in 50 years with a 6% return. This illustrates the incredible growth potential that comes with starting early. One specialist shared, “It’s never too early to understand the significance of saving for retirement,” reinforcing the value of beginning this journey with an individual retirement account.
At Bright Advisers, we are dedicated to offering minimal fund fees, making wealth management more accessible for families like yours. We encourage young guardians to consider establishing a managed IRA for their children, keeping in mind the custodial Roth IRA requirements, to guide them toward a future of economic stability. Together, we can navigate this journey and ensure a brighter financial future for your family.
Custodial Roth IRA Contribution Limits: What Parents Need to Know
As you look toward 2025, it’s essential to understand the custodial Roth IRA requirements, which include a contribution limit set at $7,000 or the total earned income of your child, whichever is lower. Keeping track of these contributions is crucial, as exceeding this limit can result in penalties. Imagine the peace of mind that comes from working with a money advisor who can help you maximize contributions based on your child’s earnings and long-term financial goals.
For instance, if your young one earns $4,000, they can contribute up to that amount. However, if they earn $8,000, the maximum contribution remains at $7,000. This thoughtful approach not only ensures compliance with the custodial Roth IRA requirements but also opens the door to tax-free growth, creating a solid foundation for your child’s financial future.
Together, we can navigate this journey, ensuring that your family’s financial priorities are met with care and understanding. By planning wisely, you can empower your child to build a brighter economic future.
Investment Options for Custodial Roth IRAs: Maximizing Growth Potential
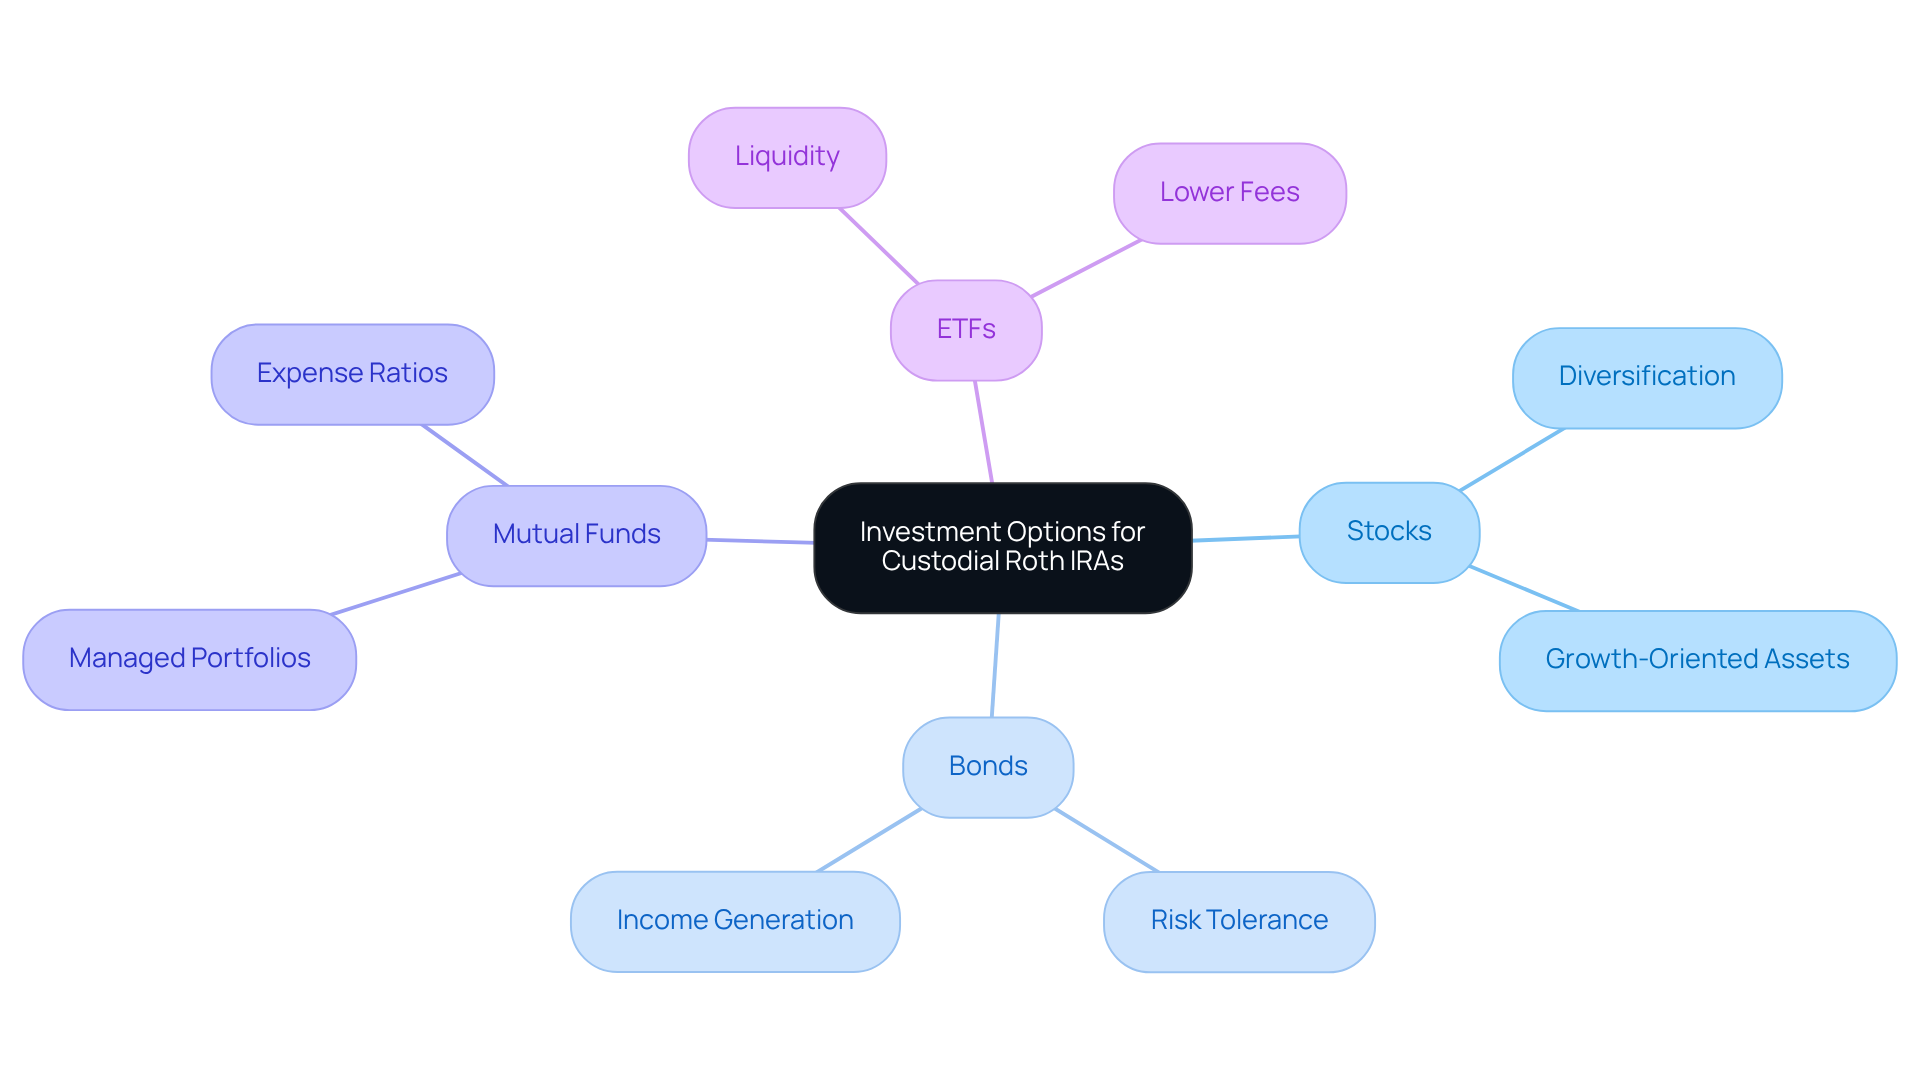
Custodial Roth IRAs present a variety of investment options, such as stocks, bonds, mutual funds, and ETFs. At Bright Advisers, we understand the importance of a diversified portfolio that aligns with your child’s long-term financial goals and risk tolerance. Imagine having a wealth management strategy that is tailored just for you—our innovative approach emphasizes hyper-personalized investment portfolios. This means you can invest in growth-oriented assets that significantly enhance the account’s value over time, ultimately benefiting your child as they step into adulthood.
It’s important to recognize that only 2.5% of households currently utilize 529 plans. This highlights the need to explore various investment alternatives, including the custodial Roth IRA requirements, for long-term savings. Additionally, high-yield savings accounts are currently offering rates close to 4.3% APY as of June 2025, providing families with alternative saving strategies.
We’re here for you. Consulting with a financial advisor at Bright Advisers can help you select the optimal investment mix. Together, we can assess how custodial accounts may impact financial aid eligibility, ensuring a comprehensive approach to your child’s financial future. Remember, navigating this journey is easier with the right support, and we are committed to assisting you every step of the way.
Distribution Guidelines for Custodial Roth IRAs: Accessing Funds Wisely
Imagine planning for your family’s future without the stress of unexpected costs. Withdrawals from a managed individual retirement account can be made tax-free and without penalties, provided the account has been established for at least five years and the individual is at least 59½ years old. This feature empowers families to manage significant expenses, such as education, with confidence.
What’s even more reassuring is that parents can withdraw contributions at any time without penalties. This flexibility allows you to respond to your family’s needs as they arise. According to Fidelity, ‘Contributions can be withdrawn without taxes or penalties, at any time,’ emphasizing the freedom these accounts offer.
However, it’s important to strategize your withdrawals carefully. By doing so, you can maintain the account’s tax advantages and ensure that funds are used for the right purposes. For instance, these resources can be directed towards educational costs, helping to secure your children’s economic future while adhering to custodial Roth IRA requirements to maximize the benefits.
Moreover, it’s essential to know that money saved in a retirement account for children does not affect their eligibility for financial aid when seeking tuition support. This makes it a wise choice for families looking to save for education without jeopardizing aid opportunities. Together, we can navigate this journey, ensuring your family’s financial future is bright and secure.
Pros and Cons of Custodial Roth IRAs: A Balanced Perspective
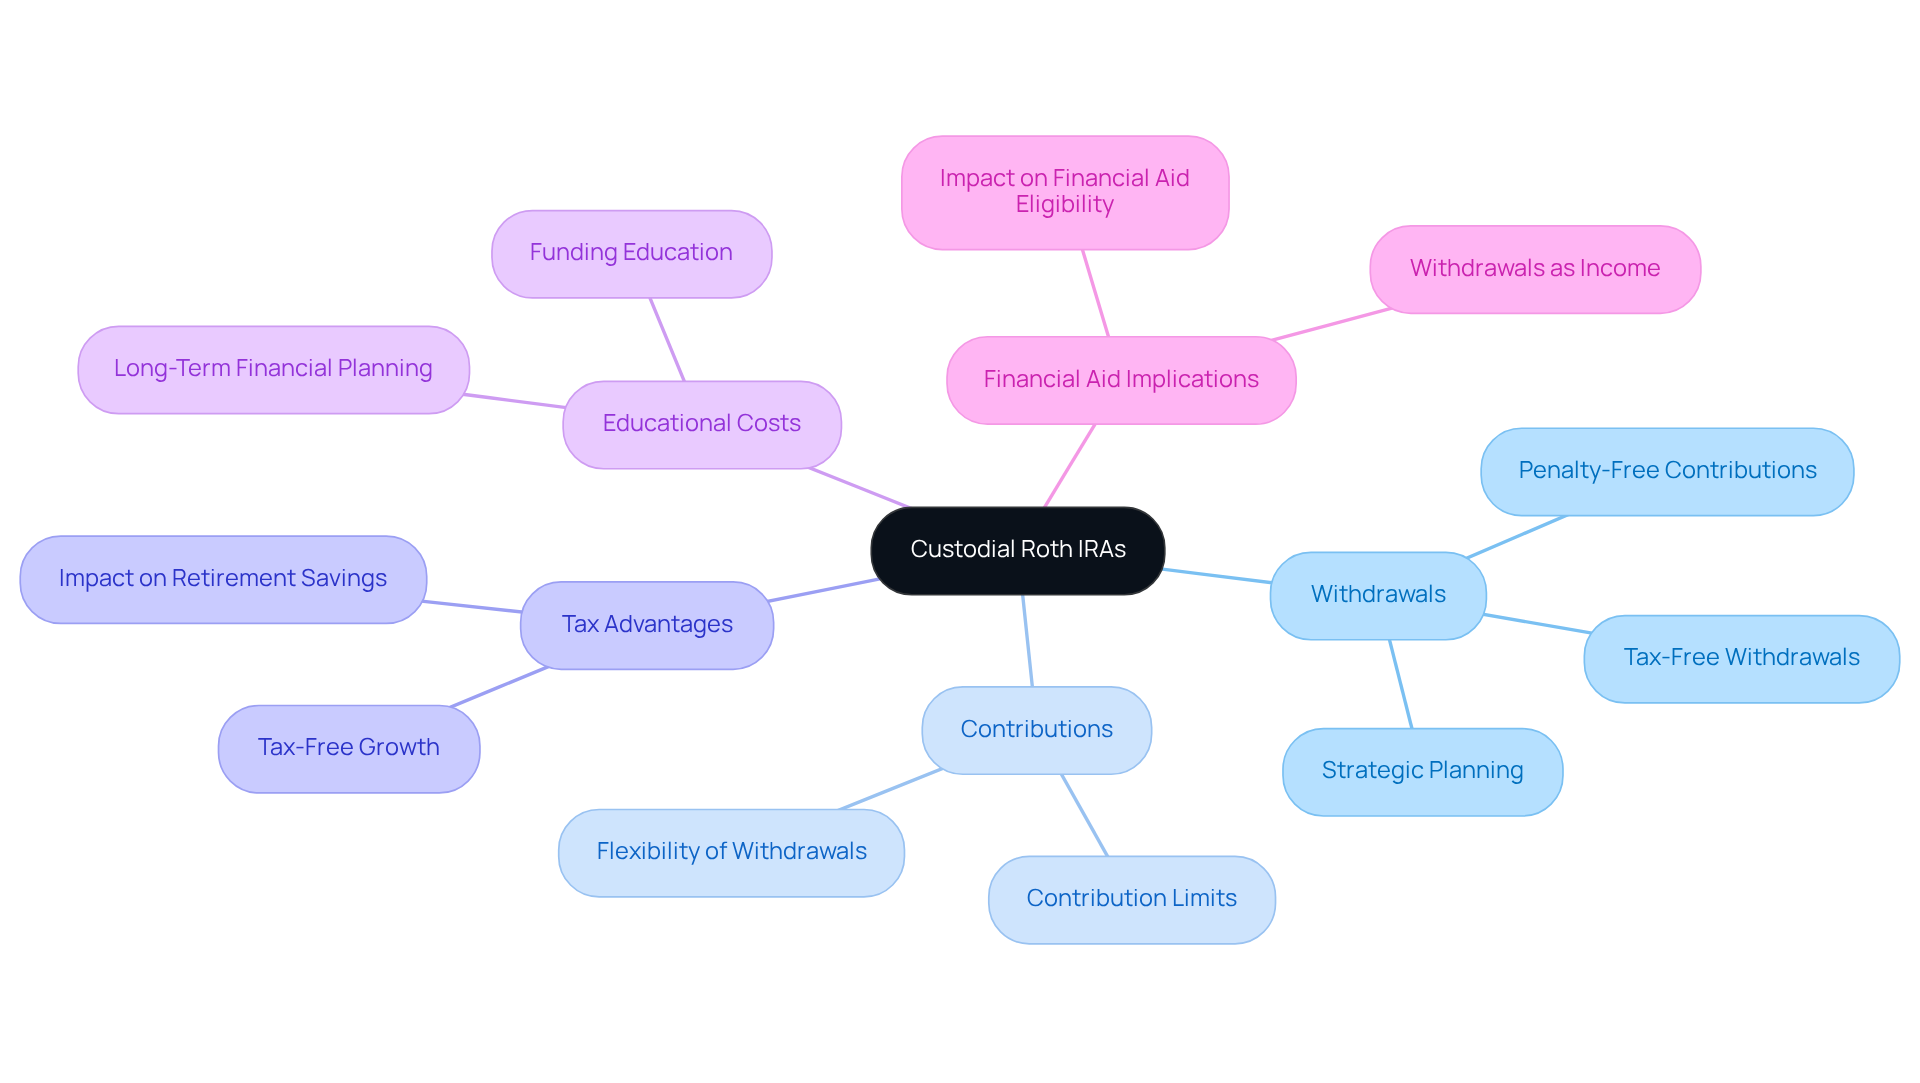
Young families can enjoy a wealth of benefits by adhering to the custodial Roth IRA requirements. Imagine a future where your investment grows tax-free, providing a variety of choices that can help instill fiscal responsibility in your children. Just think about the potential of a one-time contribution of $7,000 growing to approximately $139,550 over 50 years at a 6% return. The long-term advantages are truly significant. Moreover, these accounts provide an excellent opportunity for parents to teach their children about investing and saving from an early age, nurturing a sense of financial literacy that can last a lifetime.
However, it’s important to consider some drawbacks. Access to funds is limited until your child reaches adulthood, which might pose challenges for families needing liquidity. Additionally, contributions that exceed the annual cap could lead to penalties. It’s essential for parents to monitor their child’s earnings closely. In 2025, understanding the custodial Roth IRA requirements is crucial, as a minor can contribute up to $7,000 or their taxable income—whichever is less.
A recent survey found that more parents are contemplating retirement accounts for their children, weighing the benefits against the limitations. Financial consultants often highlight that while trust accounts can be advantageous, they require careful planning and consideration of the family’s financial goals. Ultimately, deciding to create a managed IRA should align with your family’s broader financial strategy, ensuring it becomes a valuable tool for building a secure economic future. Together, we can navigate this journey with confidence.
Custodial Roth IRA vs. Traditional IRA: Key Differences Explained
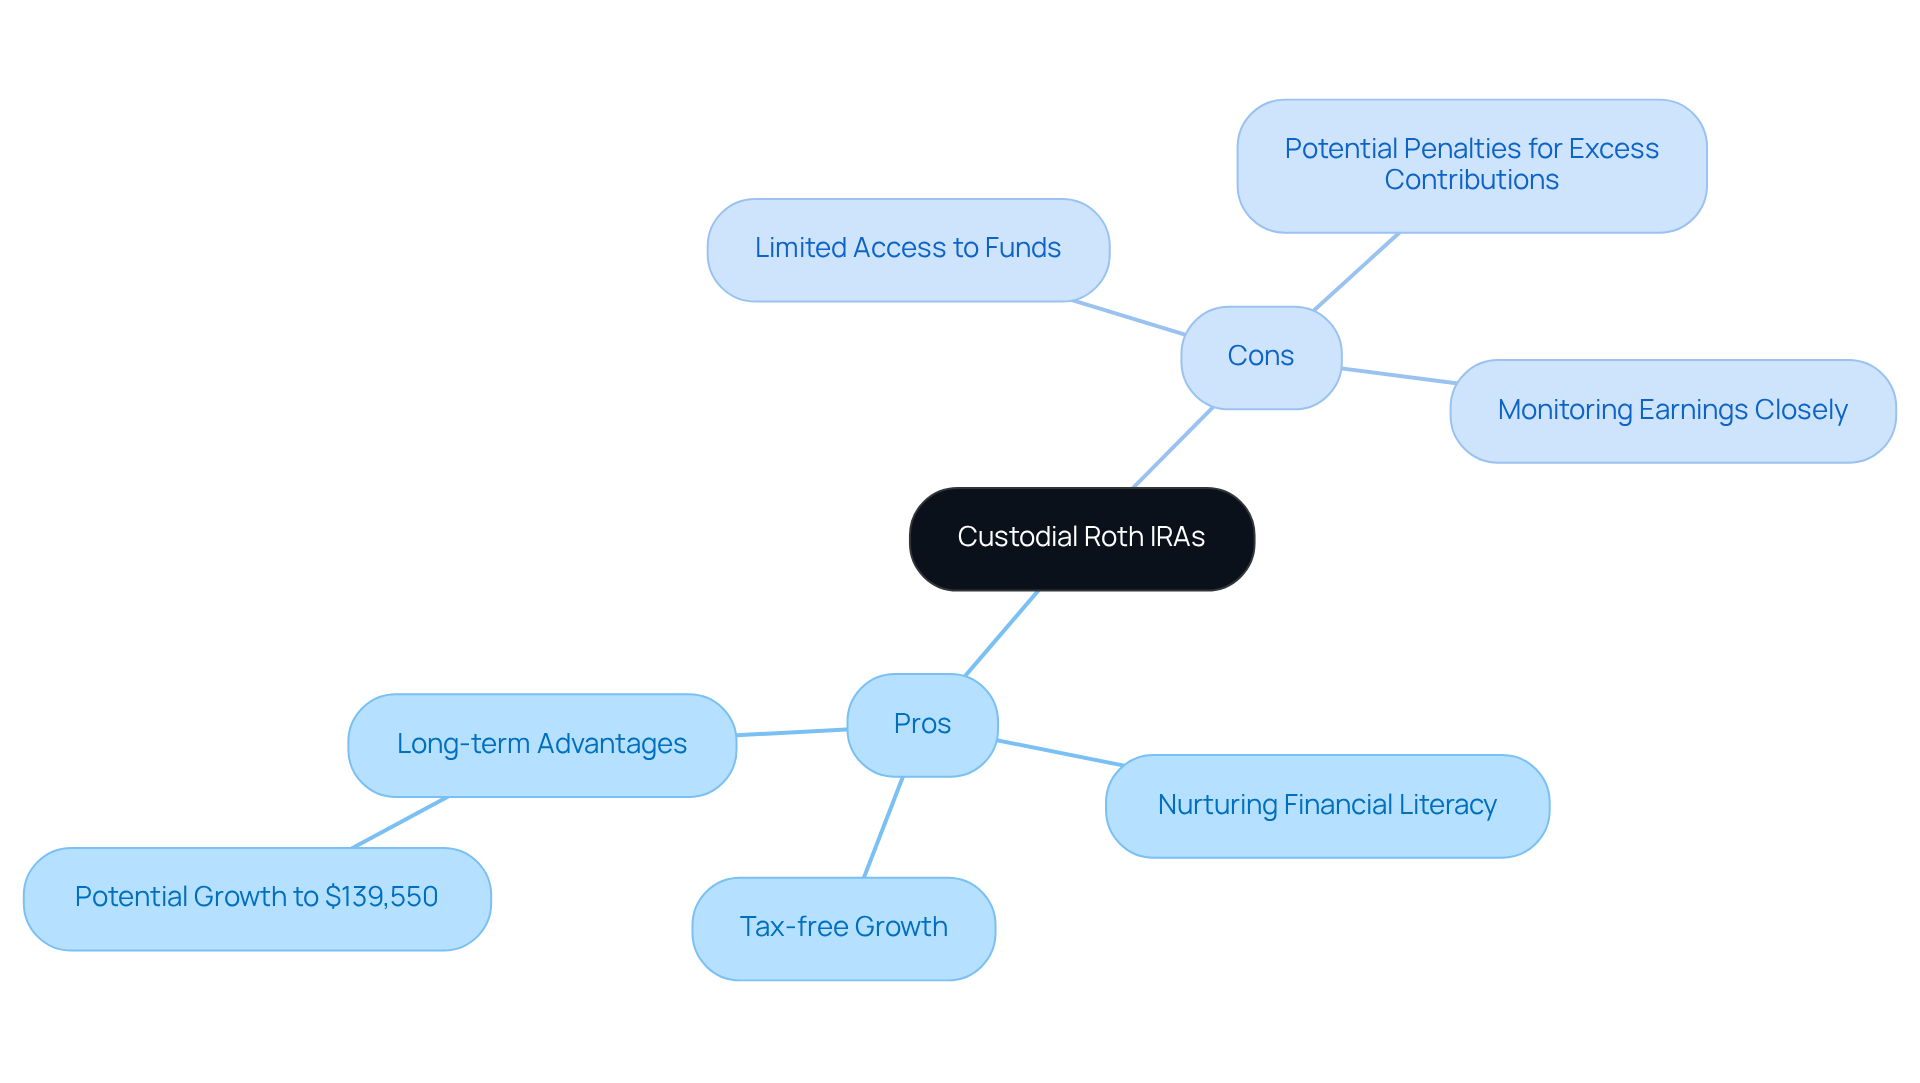
Understanding the differences between retirement accounts managed on behalf of others and traditional IRAs is essential for young families looking to secure their children’s financial future. Imagine contributing to a managed retirement account with after-tax dollars, allowing for tax-free withdrawals in retirement. This approach can significantly enhance long-term savings, providing peace of mind for parents. In contrast, traditional IRAs offer tax-deferred growth, but withdrawals are taxed as income, which might limit future financial flexibility.
It’s important to recognize that managed retirement accounts are overseen by a guardian until your child reaches adulthood. This ensures that families can tailor their investment strategies to meet specific needs and goals. Comprehending these distinctions is vital for parents, as it empowers them to make informed decisions about their children’s financial futures.
At Bright Advisers, we are dedicated to providing innovative wealth management solutions that support families through personalized planning and advanced investment strategies. Together, we can navigate this journey, ensuring that your family’s financial goals align with your values.
Custodial Roth IRA FAQs: Answers to Common Parent Questions
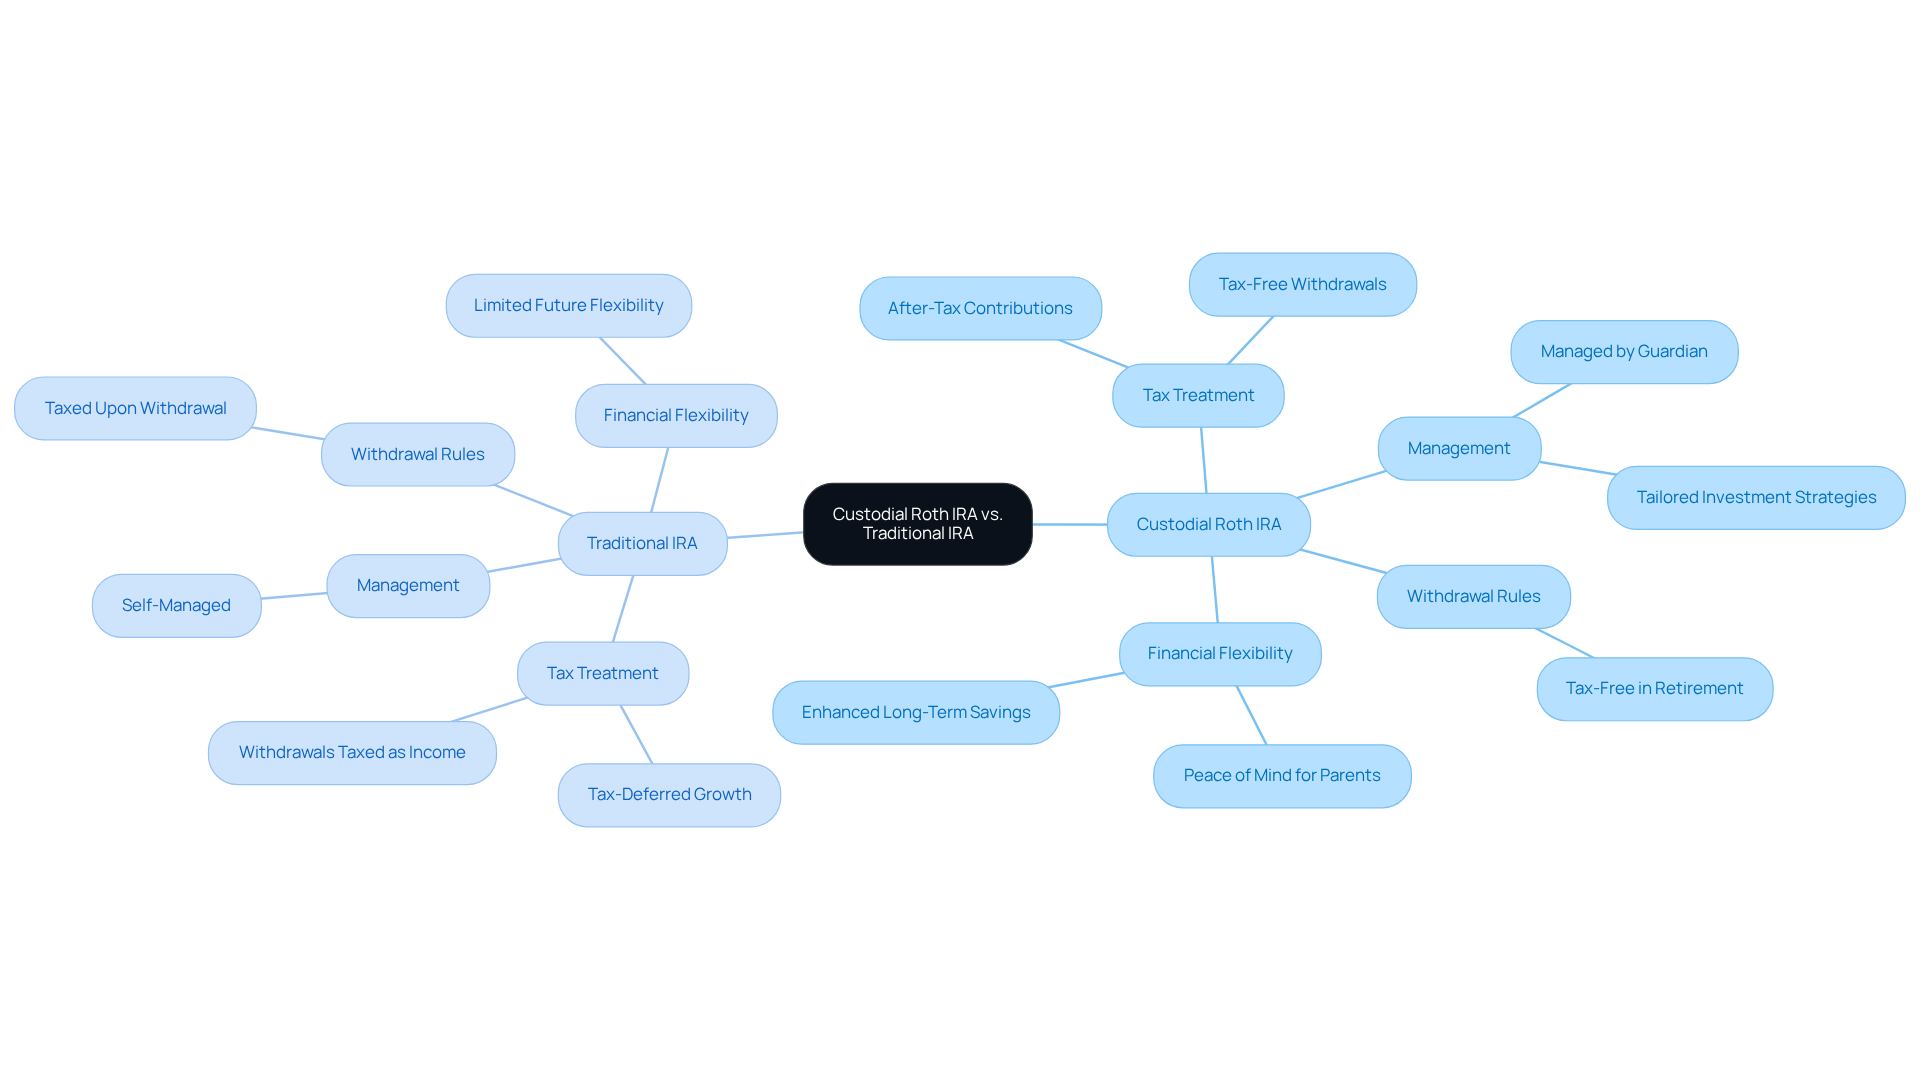
As parents, you may have common questions about custodial Roth IRAs. For example, you might wonder if you can open one for your child, even if they don’t have a job. It’s important to understand that the answer is no; your child must have earned income to qualify for contributions.
Another question often arises: what happens to the account when your child turns 18? At that point, the account becomes theirs to manage independently, marking an exciting milestone in their financial journey.
You may also be curious if you can contribute to your child’s account despite having a high income. The good news is that contributions depend solely on your child’s earnings, not your financial situation. This means that you can support their future without worrying about your own income level.
Addressing these questions helps you make informed choices about the custodial Roth IRA requirements, fostering confidence in your financial planning. Remember, we’re here for you every step of the way. At Bright Advisers, we are committed to offering customized wealth management solutions that improve accessibility and promote economic security for families. Together, we can navigate this journey towards a brighter financial future.
Impact of Custodial Roth IRAs on a Child’s Financial Future
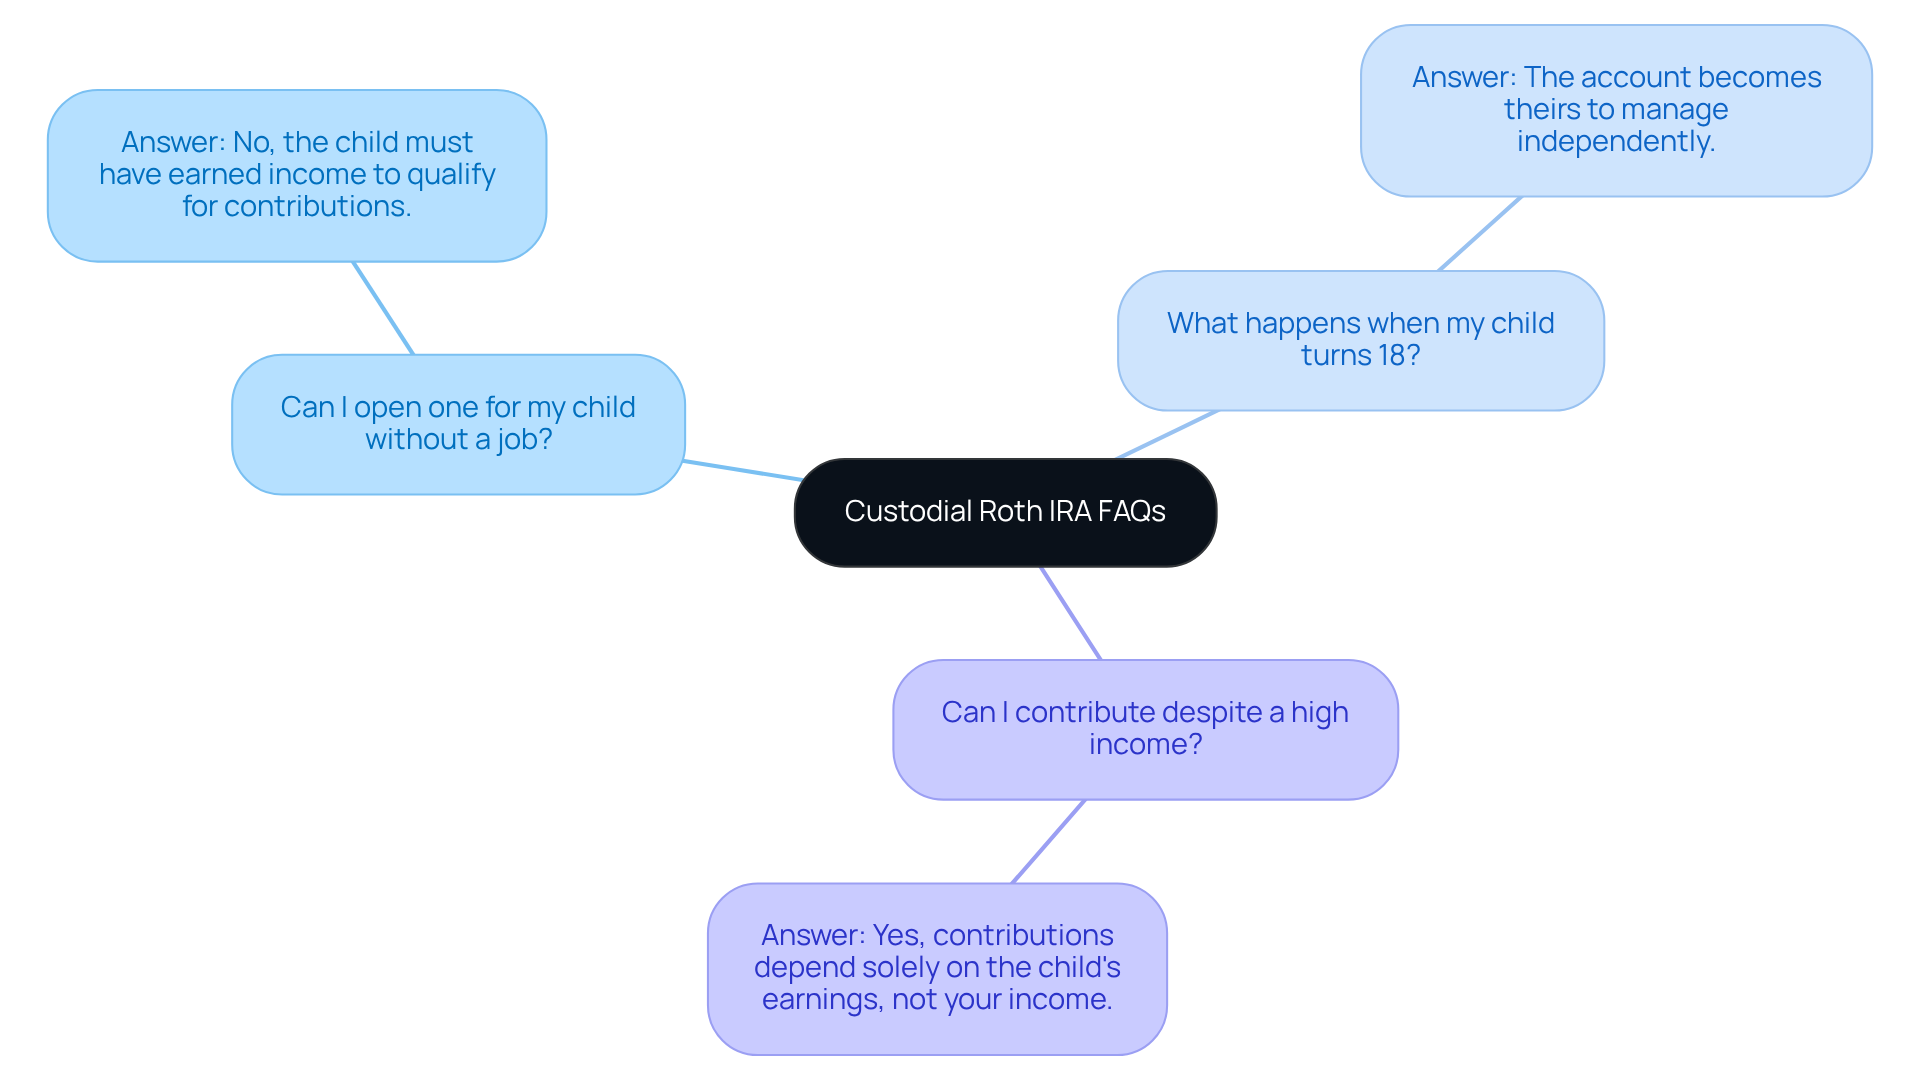
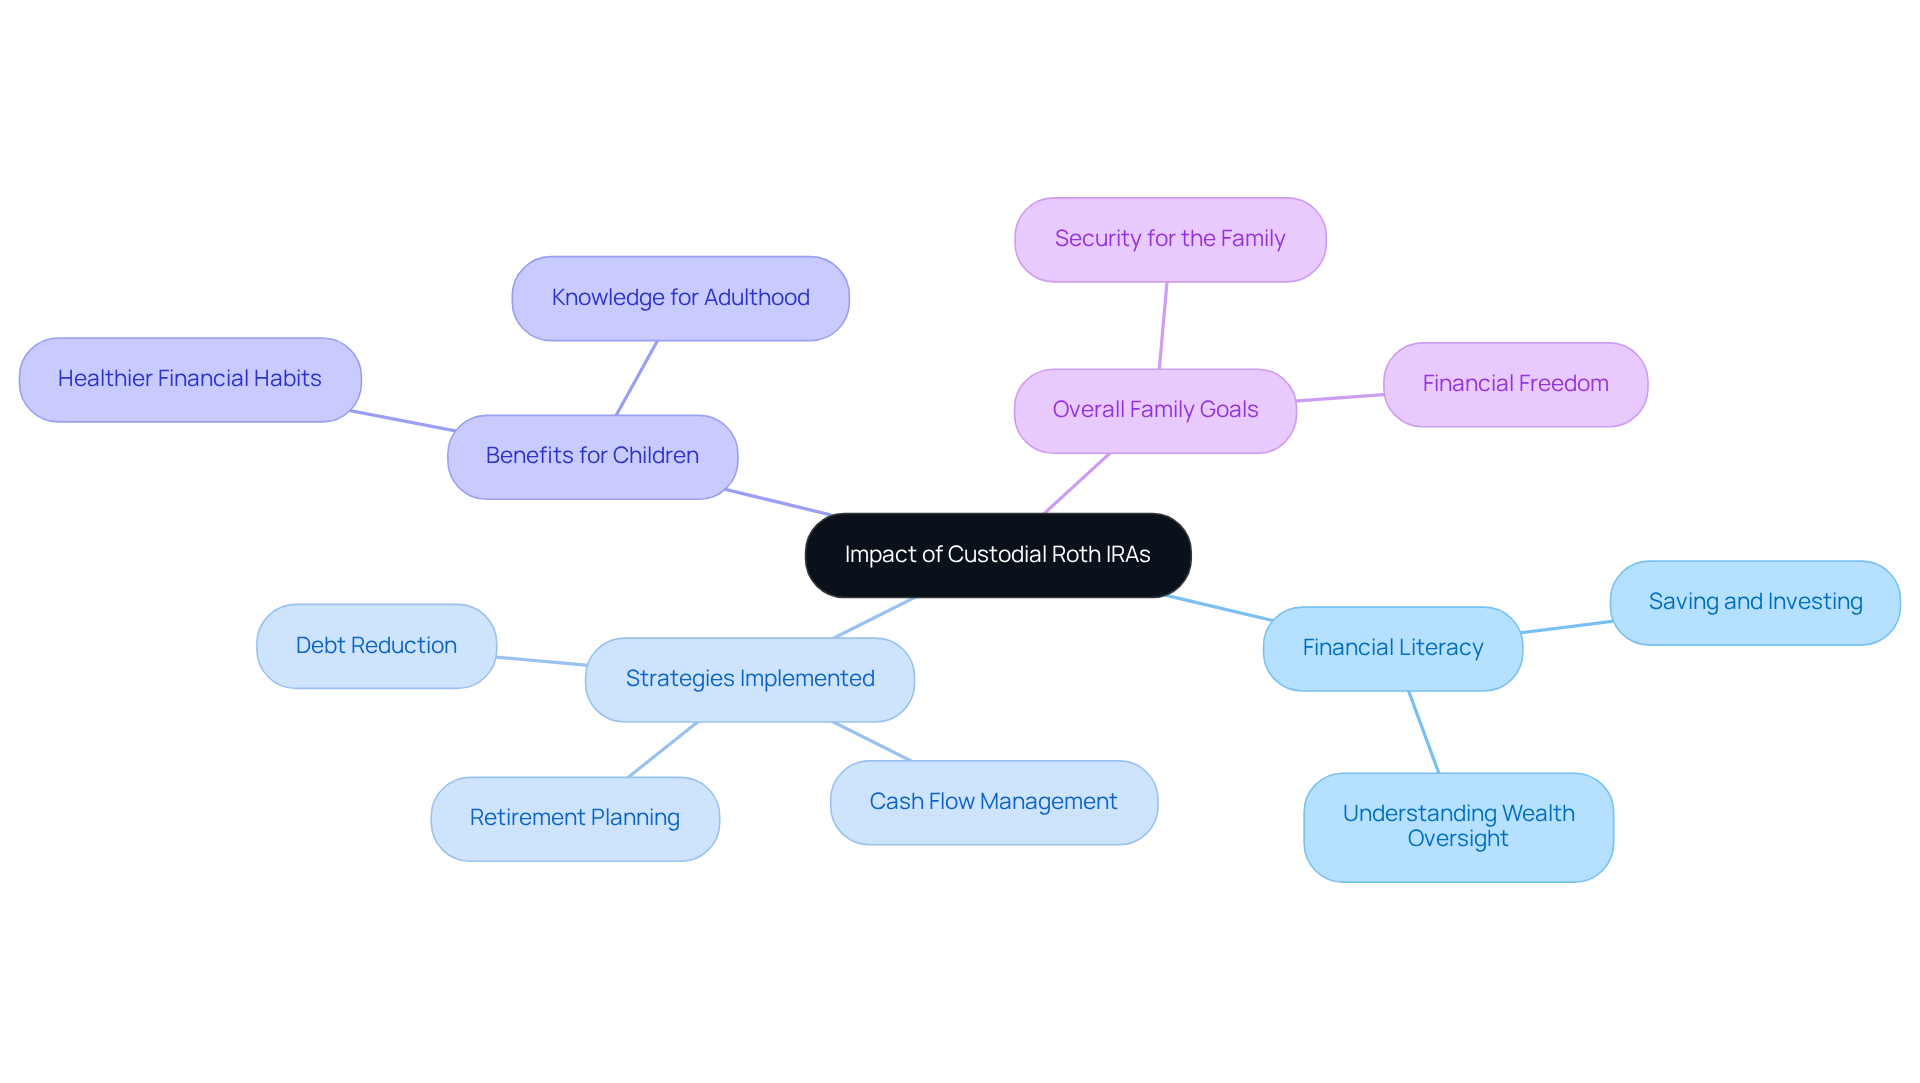
The custodial Roth IRA requirements can profoundly shape a child’s economic future by nurturing the principles of saving and investing from a young age. Imagine if your child learned about money management early on, just like Emily and Mark, young parents who partnered with Bright Advisers. Their experience shows that this early exposure can lead to healthier financial habits and a deeper understanding of wealth oversight.
Bright Advisers took the time to evaluate their financial situation comprehensively. They implemented strategies that included custodial Roth IRA requirements, debt reduction, cash flow management, and retirement planning. By empowering children to learn about managing investments, families can set them up for success in adulthood.
This proactive approach not only fosters financial literacy but also aligns with the broader goals of achieving financial freedom and security for the entire family. Together, we can navigate this journey, ensuring that our children are equipped with the knowledge they need to thrive financially. We’re here for you, supporting you every step of the way.
Alternative Ways to Start an IRA for Your Child: Exploring Options
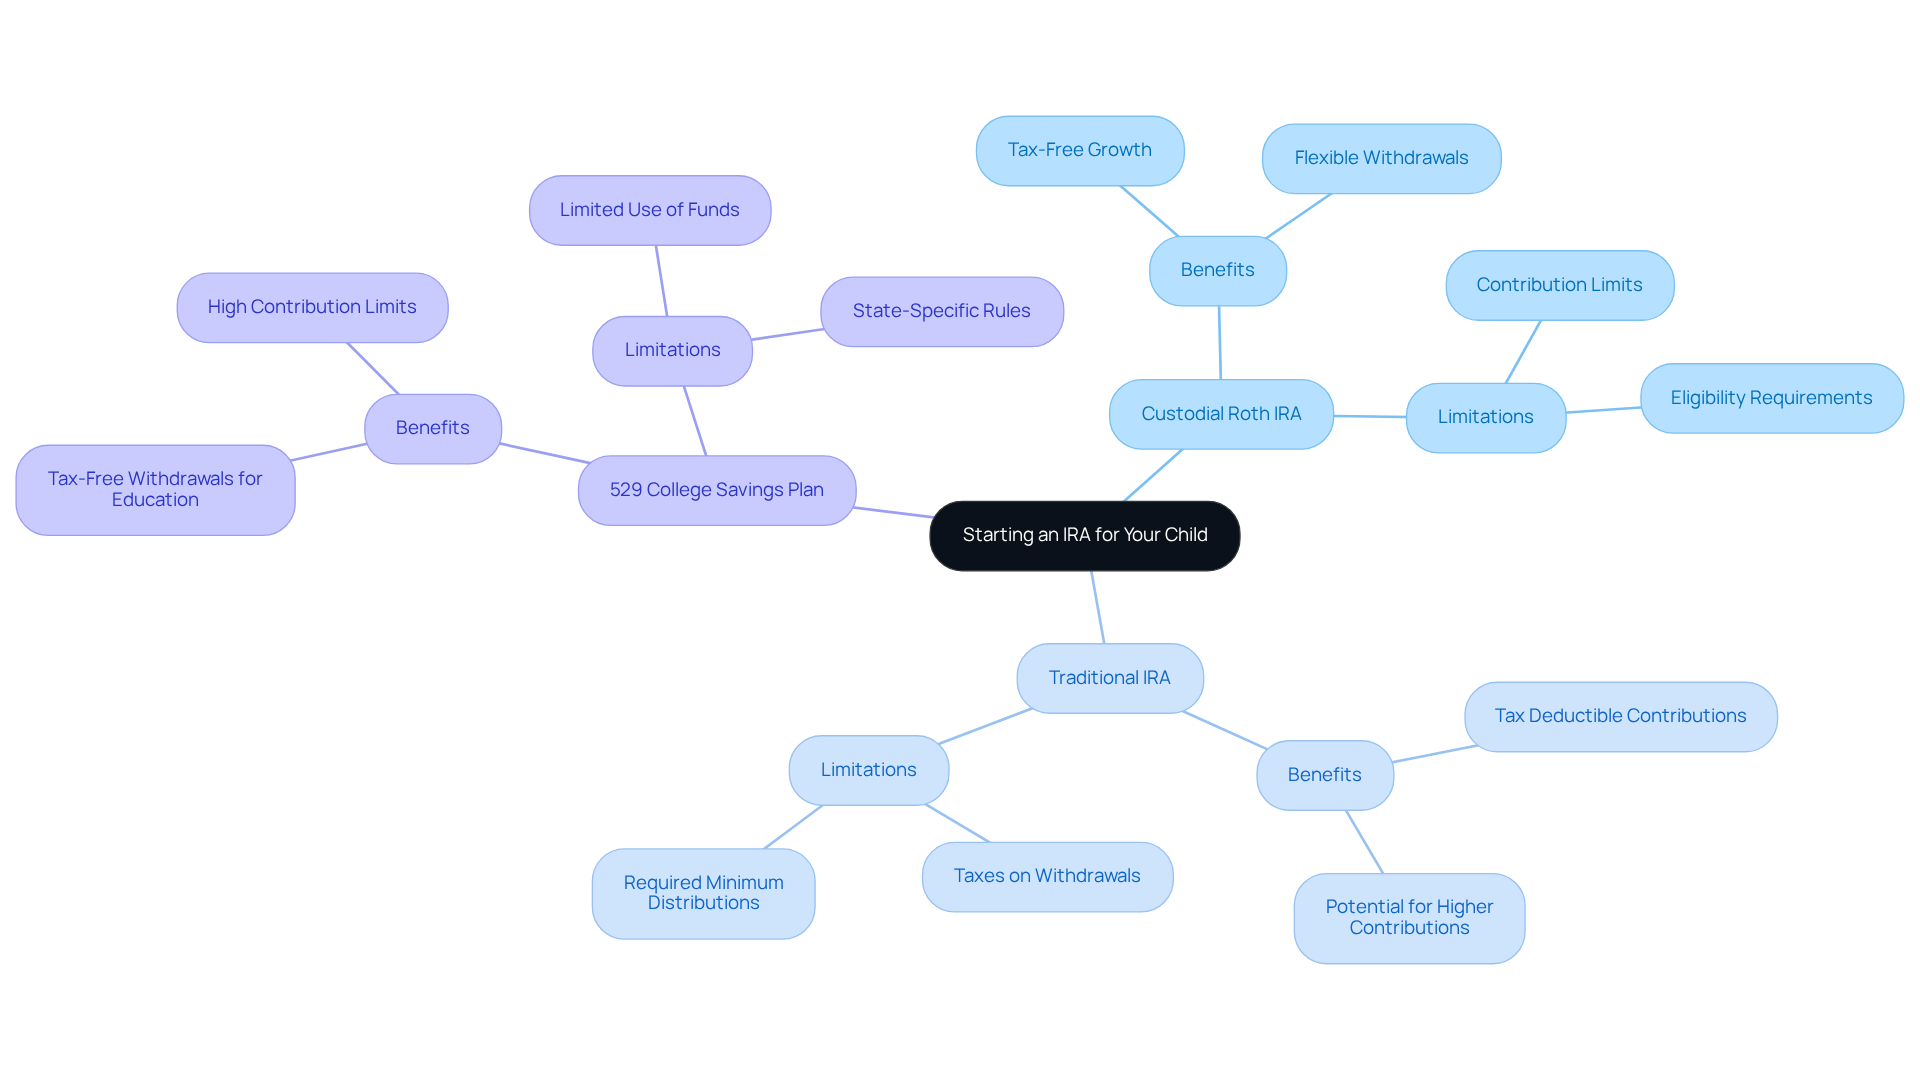
As parents, it’s natural to want the best for your child’s future. In addition to considering custodial Roth IRA requirements, there are other options to consider, such as traditional IRAs or even a 529 college savings plan. Each choice comes with its own set of benefits and limitations, and it’s essential to assess your child’s unique needs and future goals when making a decision.
Imagine if you could set your child on a path to financial success from an early age. Consulting with a financial advisor at Bright Advisers can be a wonderful step in determining the best approach to starting an IRA or savings plan for your child. Together, we can navigate this journey, ensuring a solid financial foundation that is tailored to your family’s specific circumstances.
Remember, you’re not alone in this process. We’re here for you, ready to help you make informed decisions that resonate with your family’s values and aspirations.
Conclusion
Establishing a custodial Roth IRA can be a transformative step for young parents, offering a powerful tool to secure their children’s financial future. Imagine fostering a culture of saving and investing from an early age, setting your children on a path toward economic independence. This proactive approach not only opens doors to tax-free growth opportunities but also nurtures valuable financial literacy that can last a lifetime.
As you explore this article, key insights will illuminate the eligibility criteria, contribution limits, and investment options available for custodial Roth IRAs. It’s important to understand that contributions are capped at the lesser of $7,000 or the child’s earned income, ensuring compliance while maximizing benefits. Various investment strategies, from stocks to bonds, can be leveraged to enhance growth potential. The flexibility of these accounts allows for tax-free withdrawals under certain conditions, making them an appealing option for families planning for education and other significant expenses.
Ultimately, the impact of custodial Roth IRAs goes beyond mere financial benefits; they empower families to cultivate responsible money management habits in their children. By exploring these accounts and consulting with financial advisors, you can make informed decisions that align with your long-term goals. Embracing custodial Roth IRAs not only prepares your children for future financial challenges but also strengthens your family’s overall economic stability. Remember, together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is Bright Advisers’ approach to financial planning for custodial Roth IRAs?
Bright Advisers provides personalized financial planning by evaluating a family’s objectives, risk appetite, and investment preferences to create customized strategies that maximize the benefits of custodial Roth IRAs.
How much can families transfer from a 529 plan to a Roth IRA?
Families can transfer up to $35,000 from a 529 plan to a Roth IRA, which can significantly enhance their children’s economic futures.
What investment strategies does Bright Advisers offer?
Bright Advisers offers investment strategies such as the Diversified Premia and Opportunity Strategy, designed to maximize monetary outcomes for clients.
Who is eligible to open a custodial Roth IRA?
A child under 18 who has earned income from activities like babysitting or lawn mowing can qualify for a custodial Roth IRA. A parent or guardian manages the account until the child reaches the age of majority, which is typically 18 or 21, depending on the state.
What are the contribution limits for a custodial Roth IRA?
The contribution limit for a custodial Roth IRA is $7,000 or the child’s total earned income for the year, whichever is lower.
How does earned income affect contributions to a custodial Roth IRA?
Contributions must come from after-tax dollars based on the child’s earned income. For example, if a child earns $3,000, that is the maximum they can contribute to their IRA.
What is the potential growth of a custodial Roth IRA over time?
A one-time contribution of $7,000 could grow to approximately $139,550 in 50 years with a 6% return, highlighting the importance of starting early with retirement savings.
What additional benefits do custodial Roth IRAs provide for minors?
Custodial Roth IRAs offer tax advantages that can be particularly beneficial for minors, as they typically have lower tax rates, allowing for tax-free growth over time.
List of Sources
- Bright Advisers: Personalized Financial Planning for Custodial Roth IRAs
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)
- 529 to Roth IRA: Rollover Rules, Conversion Guide, and FAQs (https://savingforcollege.com/article/roll-over-529-plan-funds-to-a-roth-ira)
- Custodial Roth IRA Eligibility: Who Can Open One?
- Custodial Roth IRA: A Roth IRA for Kids – NerdWallet (https://nerdwallet.com/article/investing/why-your-kid-needs-a-roth-ira)
- Custodial Roth IRA: Your guide to Roth IRAs for kids | Fidelity (https://fidelity.com/learning-center/personal-finance/retirement/turbocharge-childs-retirement)
- What is a Roth IRA for Kids and How Does It Work? (https://schwab.com/learn/story/roth-ira-for-kids)
- Custodial Roth IRA Contribution Limits: What Parents Need to Know
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- How Does a Custodial Roth IRA Work? (https://smartasset.com/estate-planning/custodial-roth-ira)
- Custodial Roth IRA: How to Open a Roth IRA for Kids (https://annuity.org/retirement/ira/roth-ira/custodial)
- Custodial Roth IRA: How And Why To Start A Roth IRA For Kids | Bankrate (https://bankrate.com/retirement/custodial-roth-ira-starting-ira-for-your-child)
- Investment Options for Custodial Roth IRAs: Maximizing Growth Potential
- 4 Long Term Saving Options for Families: Pros and Cons Explained – Bright Advisers (https://brightadvisers.com/4-long-term-saving-options-for-families-pros-and-cons-explained)
- Distribution Guidelines for Custodial Roth IRAs: Accessing Funds Wisely
- Roth IRA for Kids | Plan Benefits, Eligibility, and Investment Options | Fidelity (https://fidelity.com/retirement-ira/roth-ira-kids)
- Roth IRAs for Kids? Absolutely. | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/roth-iras-for-kids–absolutely-.html)
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)
- Pros and Cons of Custodial Roth IRAs: A Balanced Perspective
- Custodial Roth IRA: A Roth IRA for Kids – NerdWallet (https://nerdwallet.com/article/investing/why-your-kid-needs-a-roth-ira)
- Custodial Roth IRA: How to Open a Roth IRA for Kids (https://annuity.org/retirement/ira/roth-ira/custodial)
- Custodial Roth IRA FAQs: Answers to Common Parent Questions
- Publication 17 (2024), Your Federal Income Tax | Internal Revenue Service (https://irs.gov/publications/p17)
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading