

Key Highlights
- Irrevocable trusts help secure financial futures for families by protecting assets and reducing estate taxes.
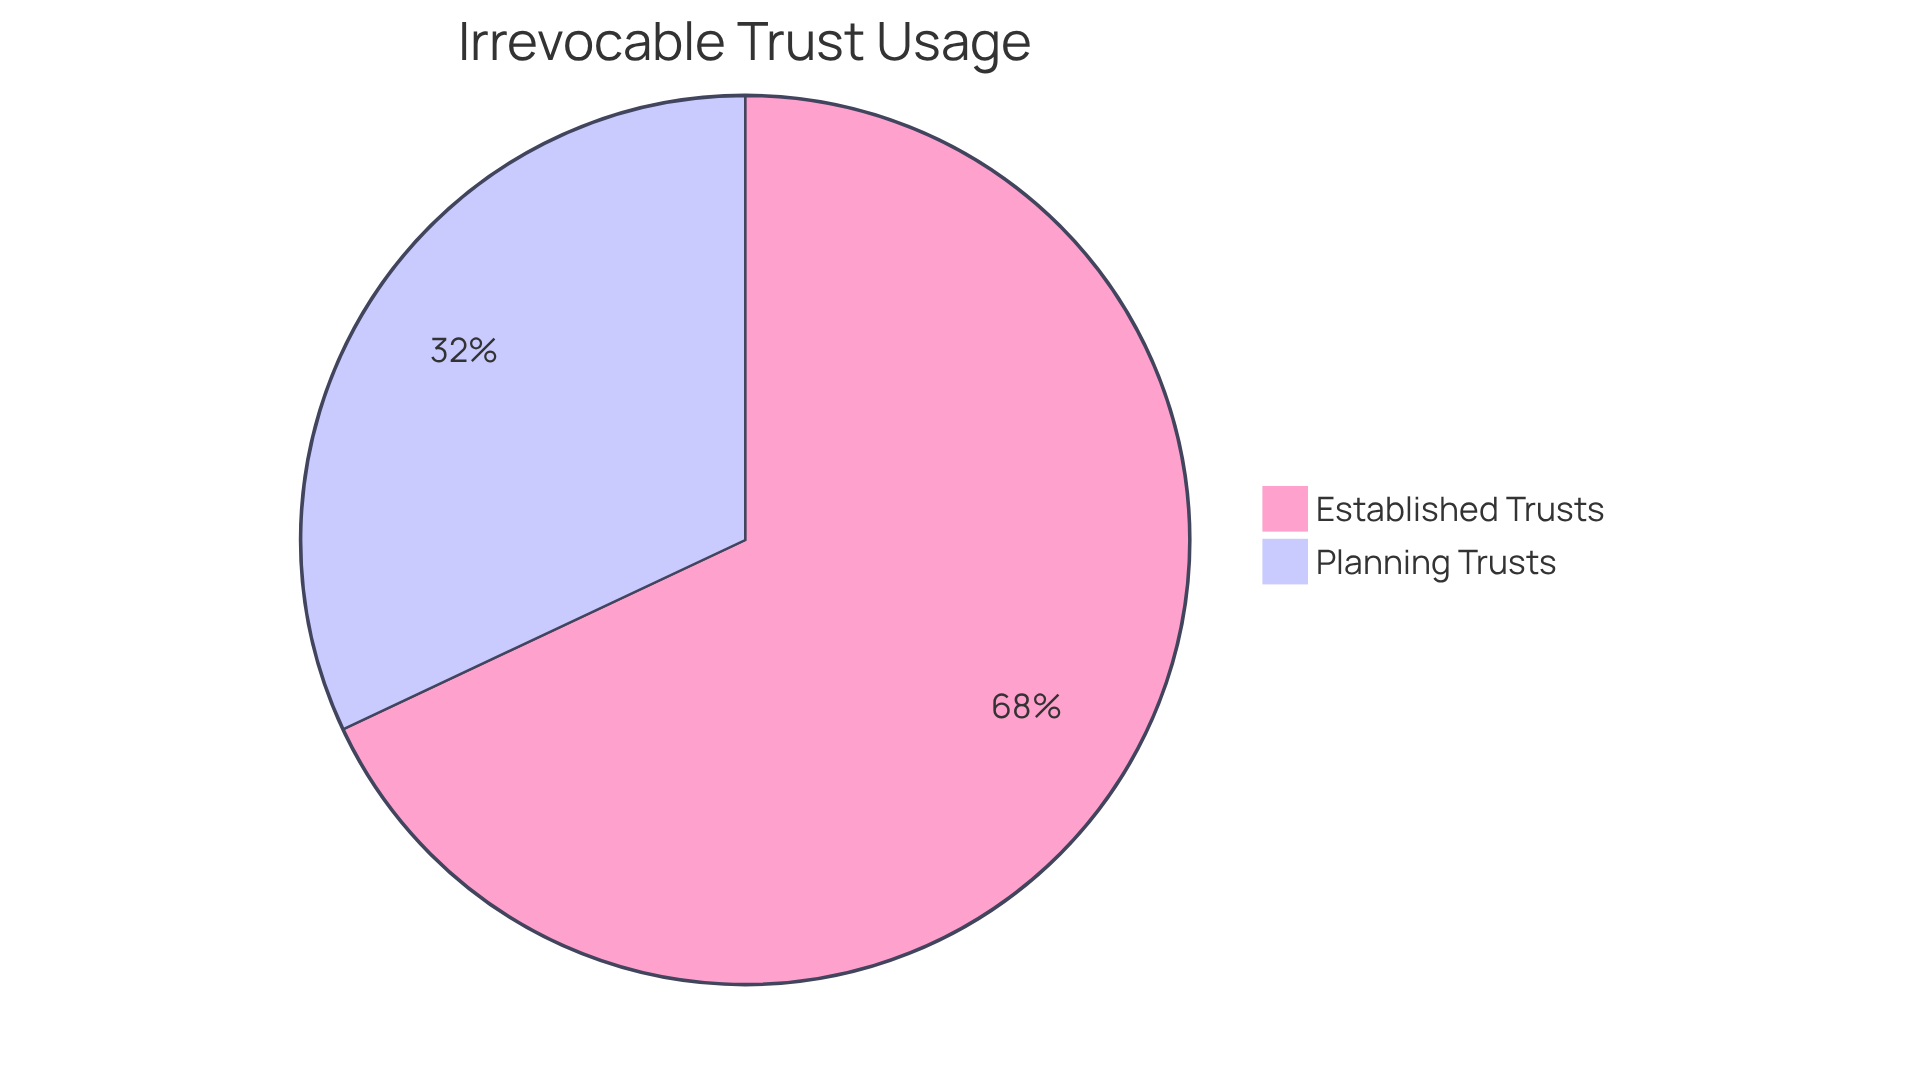
- 34% of high-income families have set up irrevocable trusts, with an additional 16% planning to do so.
- FDIC insurance covers accounts up to $250,000 per depositor, with potential increases based on the number of beneficiaries.
- New FDIC regulations effective April 1, 2024, enhance coverage for irrevocable trusts, allowing up to $1,250,000 for five beneficiaries.
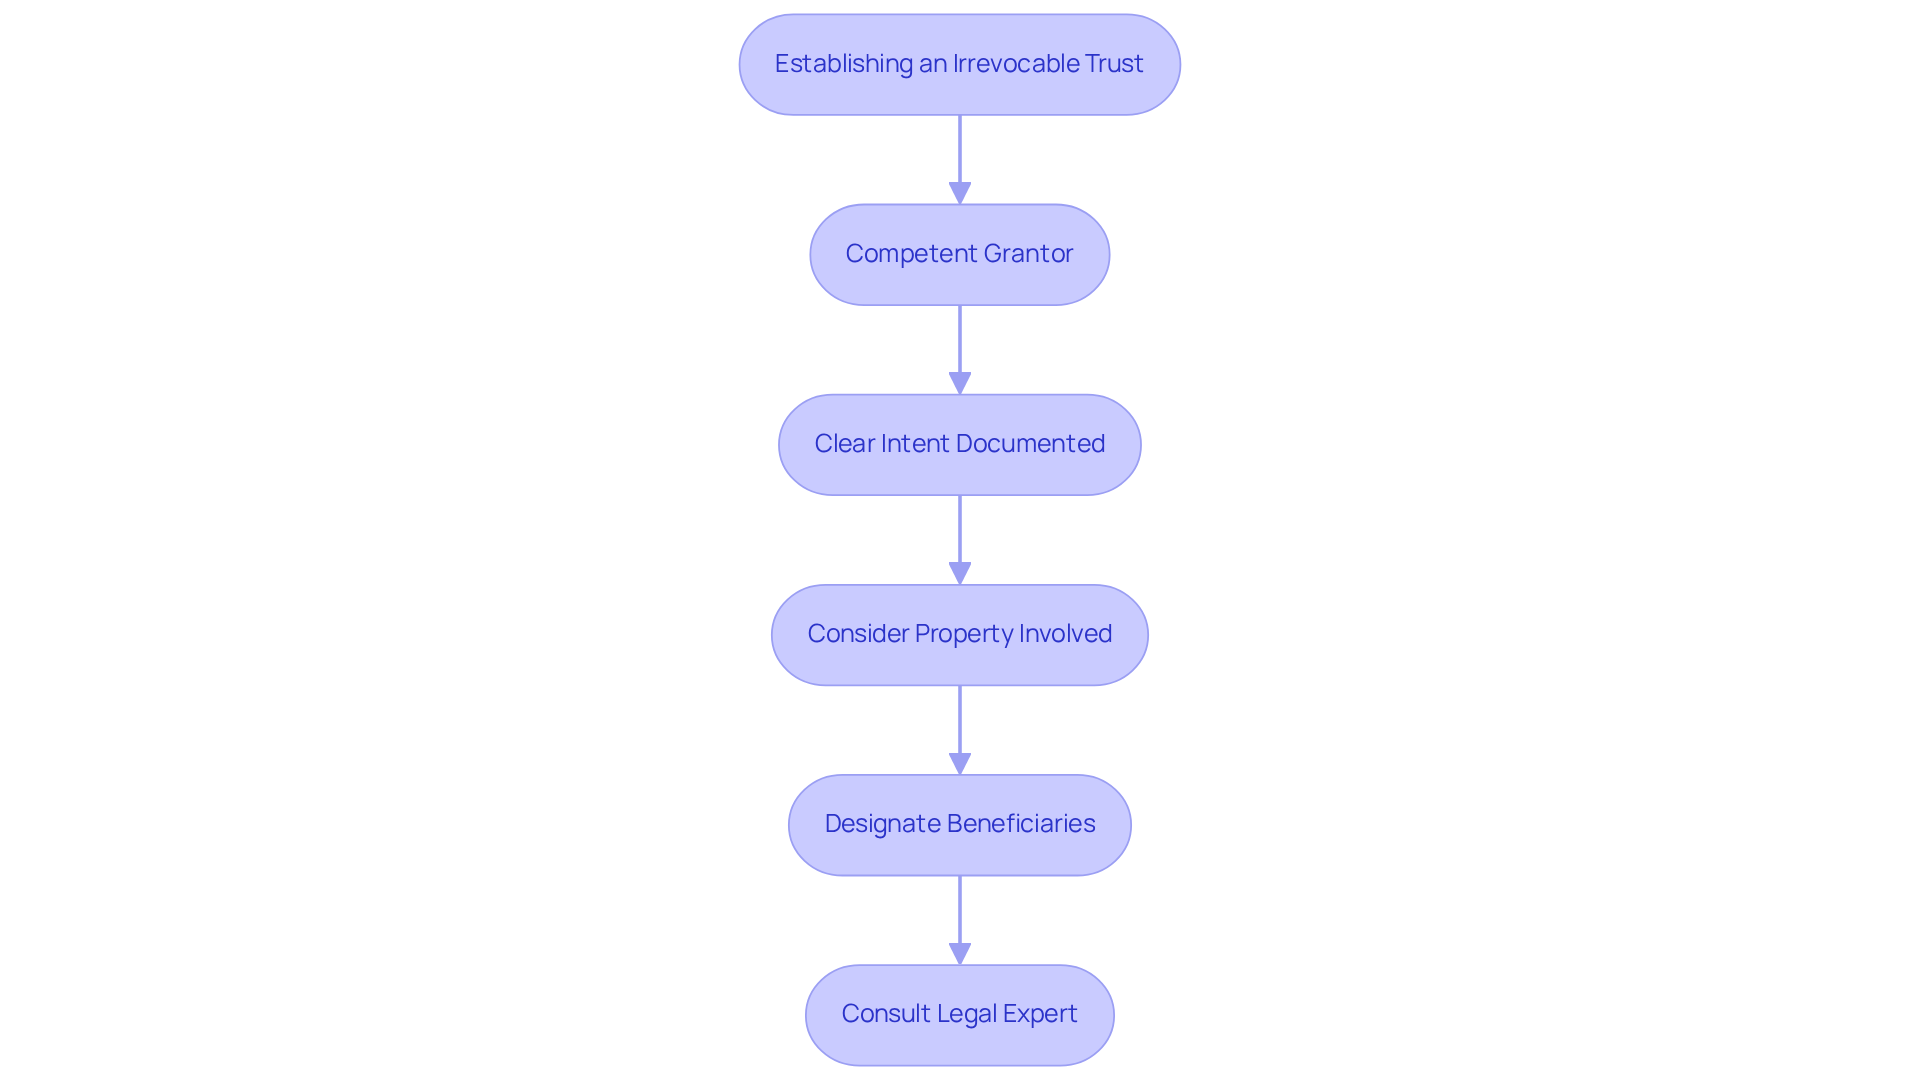
- Establishing an irrevocable trust requires a competent grantor, clear intent, designated beneficiaries, and proper documentation.
- Ineligible beneficiaries, such as charities, can reduce overall FDIC coverage for trusts.
- Primary and contingent beneficiaries must be clearly designated to avoid conflicts and ensure smooth asset distribution.
- Formal trusts provide stronger protections compared to informal arrangements, reducing potential misunderstandings.
- Upon the grantor’s death, the irrevocable trust’s rules remain unchanged, providing tax benefits and asset protection.
- Maintaining updated records for trusts is crucial for compliance and effective management of assets.
Introduction
Imagine feeling secure about your children’s financial future, even amidst the complexities of planning. Understanding the intricacies of irrevocable trusts can truly help parents like you safeguard what matters most. With the right knowledge, families can leverage irrevocable trust FDIC coverage to protect their assets and ensure a stable inheritance. Many parents feel overwhelmed by the complexities of financial planning, but with the right guidance, you can turn that confusion into confidence. It’s important to understand the essential facts every parent should know about irrevocable trusts and their FDIC insurance. This article delves into ten crucial insights that can empower families to safeguard their wealth effectively.
Define Irrevocable Trusts and Their Purpose
Imagine a future where your children are financially secure, no matter what happens to you. An irrevocable trust FDIC coverage can help make that arrangement a reality. These arrangements, which include irrevocable trust FDIC coverage, are designed to protect your family’s future, ensuring that your hard-earned assets are safe and secure for your children.
Did you know that many families just like yours are taking steps to secure their children’s future? In fact:
- 34% of high-income families have already set up these arrangements.
- 16% more are planning to do so soon.
These arrangements can help reduce estate taxes, qualify for government programs, and protect your assets from creditors.
While these arrangements can be incredibly beneficial, it’s important to plan carefully and consider your family’s unique needs to avoid any pitfalls. With the right guidance, you can ensure your family’s future is protected and thriving, giving you peace of mind.
Understand FDIC Insurance Limits for Irrevocable Trusts
Navigating the world of financial security can feel overwhelming, especially when it comes to protecting your family’s future. Did you know that FDIC insurance can cover your accounts up to $250,000 for each depositor? This means that if you have multiple recipients in an irrevocable trust FDIC coverage arrangement, your coverage can increase significantly.
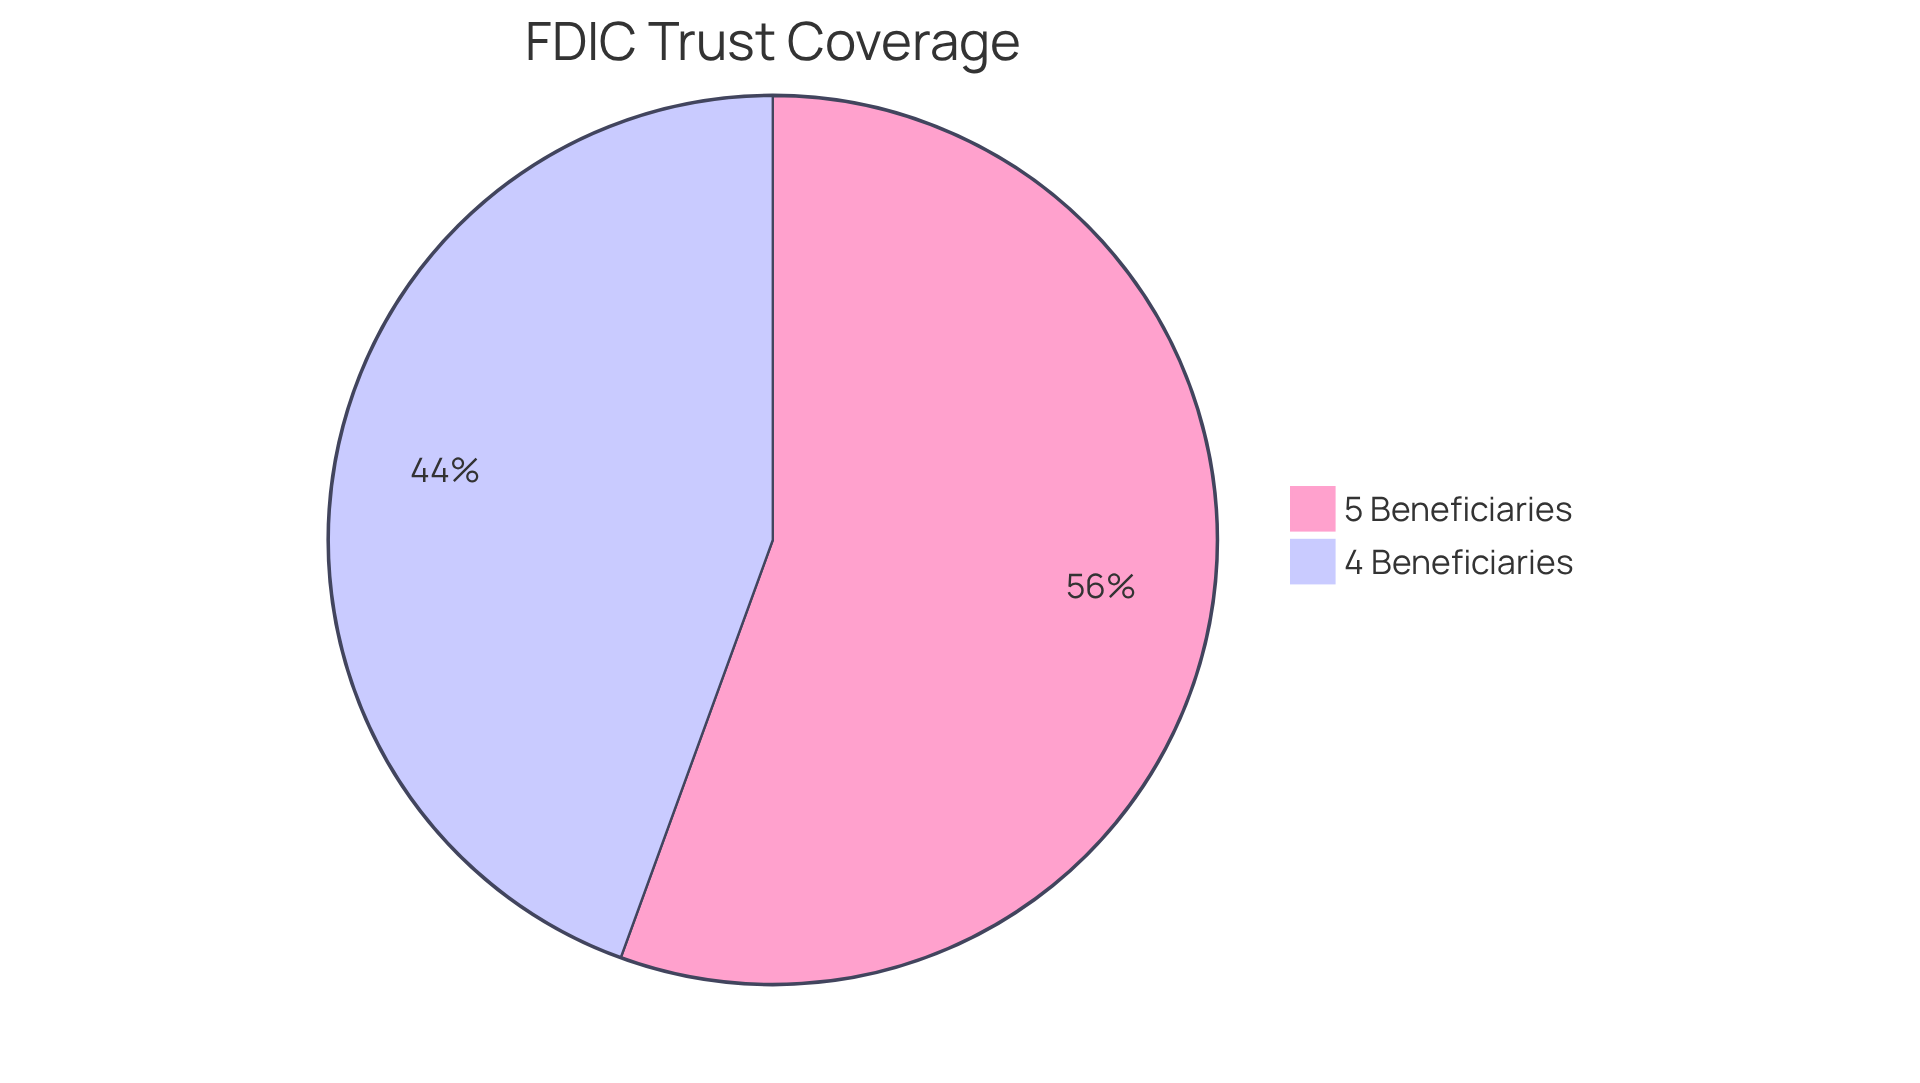
It’s important to understand how these limits work, especially when it comes to safeguarding your children’s inheritance from potential bank failures. Imagine the peace of mind knowing that new FDIC regulations, effective April 1, 2024, enhance irrevocable trust FDIC coverage, providing even greater security for your family’s future. For instance, a trust with four beneficiaries can be insured for up to $1,000,000, while one with five beneficiaries can secure up to $1,250,000. This change is especially advantageous for households planning for future generations, as it offers a more robust safety net for their assets.
Here at Bright Advisers, we understand how important these insurance limits are for your family’s financial planning. Our customized financial strategies can assist households in navigating these complexities, ensuring that your wealth is effectively managed and protected for your children’s future.
Consider how clearly defining recipients in trust accounts can make a world of difference for your family’s financial security. Trusts that specify recipients in ambiguous terms, such as ‘my relatives,’ may encounter difficulties in insurance assessments. To qualify for full FDIC coverage, individuals must be explicitly named in bank records. This clarity ensures that families can effectively manage their wealth and safeguard their children’s financial future.
Identify Requirements for Establishing an Irrevocable Trust
Imagine the peace of mind that comes from knowing your family’s future is secure with the right financial planning in place. Let’s explore what it takes to create a secure financial future for your family with irrevocable trust FDIC coverage.
To set up this kind of arrangement, there are a few important steps to consider:
- You need a competent grantor who understands what creating this arrangement means.
- It’s essential to have a clear intent, usually documented in an agreement.
- You’ll also need to think about the property involved, which can be cash, real estate, or other assets.
- Don’t forget to designate beneficiaries who will benefit from this arrangement.
Consulting with a legal expert is a wise choice to ensure everything is done correctly.
Did you know that if you transfer assets to certain irrevocable arrangements over five years before applying for Medicaid, they might not count against you? This can be a smart move for long-term care planning. For parents of children with disabilities, establishing an irrevocable trust FDIC coverage through special needs arrangements funded with life insurance or other assets can provide financial support without jeopardizing government benefits.
It’s crucial to get the legal details right, as New York law requires these agreements to be in writing to prevent any misunderstandings later on. Navigating the complexities of irrevocable arrangements, particularly regarding irrevocable trust FDIC coverage, can be challenging, especially when it comes to keeping personal and asset holdings separate to avoid unexpected tax consequences.
Understanding these criteria and seeking expert guidance can help families effectively use irrevocable trust FDIC coverage to secure their future. With the right support, you can confidently navigate these decisions and ensure a brighter future for your loved ones. Bright Advisers offers comprehensive estate planning services, including tax-loss harvesting and proactive tax planning, to help families maximize their financial outcomes while securing their legacy.
Explore Coverage Calculation for Multiple Beneficiaries
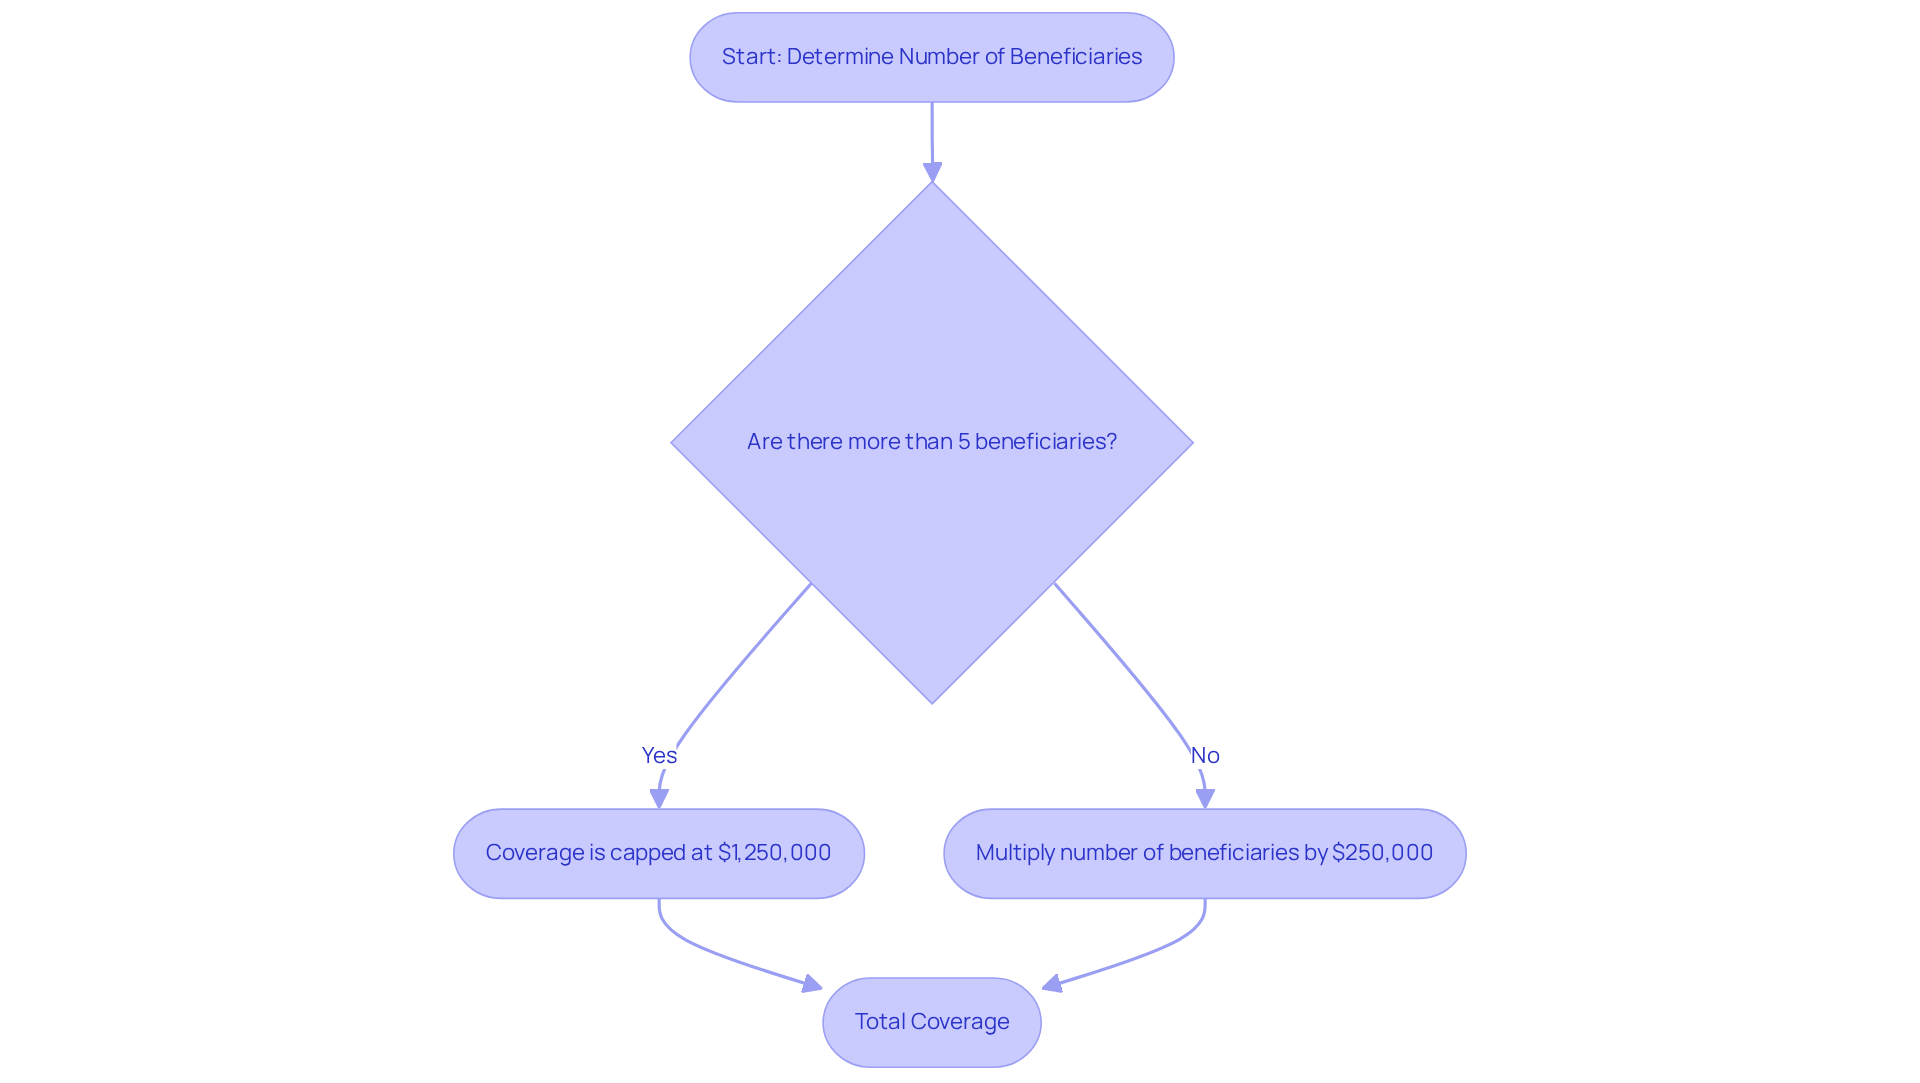
Understanding FDIC insurance coverage can feel overwhelming, but it’s crucial for securing your family’s financial future. Just multiply the number of eligible participants by $250,000 to find your coverage. For example, if you have four participants, your total coverage would be $1,000,000. However, if your arrangement includes more than five recipients, the coverage is capped at $1,250,000. This means that even with six recipients, the highest insurance coverage remains at $1,250,000, regardless of how many recipients you have.
Imagine John Jones, who has multiple accounts with six recipients. Even though he exceeds five recipients, his highest insurance coverage is limited to $1,250,000 due to FDIC regulations. It’s important for parents to grasp this limit as they plan for their children’s future, ensuring that their economic security is well protected.
Additionally, designating children as recipients of a revocable arrangement can provide extra protection. Each child qualifies for an additional $250,000 in FDIC insurance. This strategic planning can significantly enhance your family’s financial security, allowing you to focus on nurturing your children while ensuring your assets are safeguarded.
Recognize the Impact of Ineligible Beneficiaries on Coverage
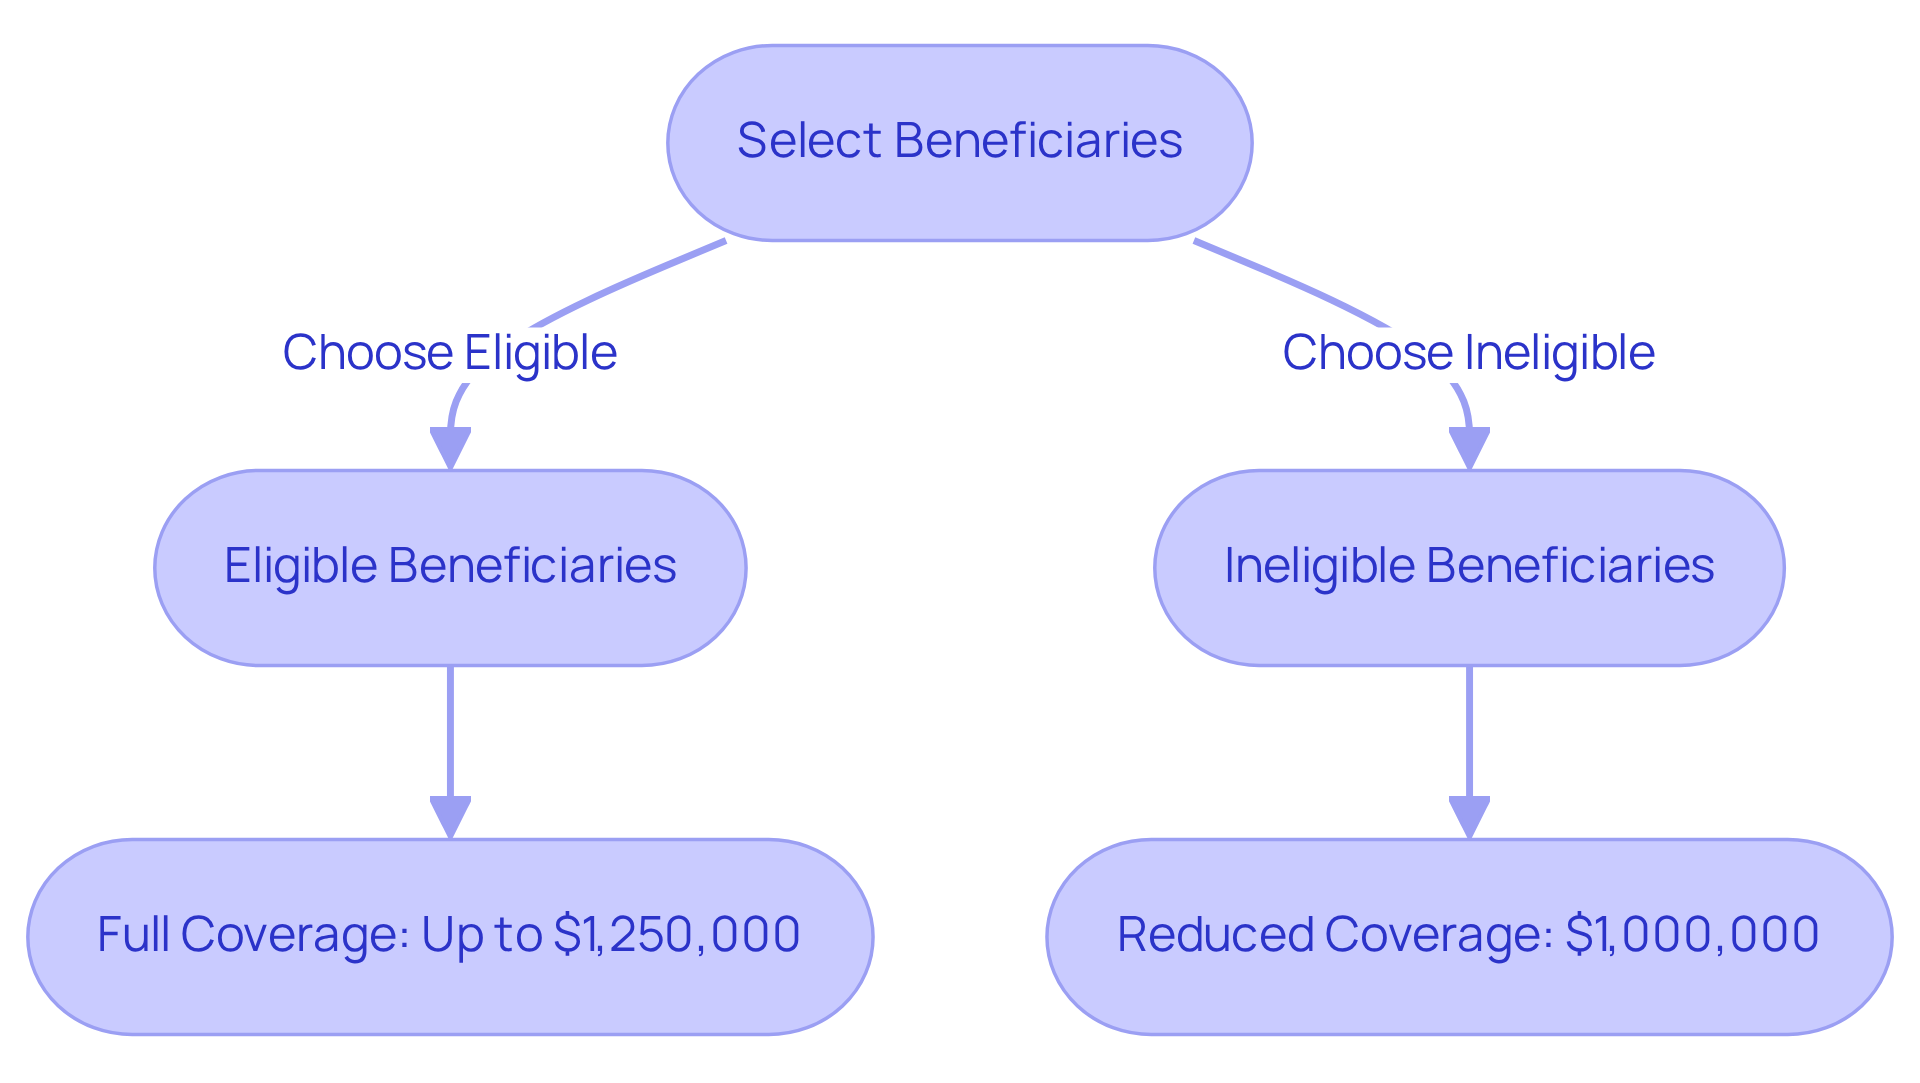
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even in the face of unexpected challenges. Certain recipients, like charities or organizations, won’t count towards the irrevocable trust FDIC coverage for irrevocable arrangements. When a fund includes ineligible recipients, the overall coverage may be reduced, meaning your family’s hard-earned wealth might not be fully protected when it matters most.
For instance, if an arrangement has five recipients, but one is not eligible, the coverage might be restricted to $1,000,000 instead of the maximum $1,250,000 available for five qualified recipients. Parents must carefully select beneficiaries to ensure that their assets are fully protected under the irrevocable trust FDIC coverage limits.
With careful planning, you can avoid unexpected losses and protect your family’s wealth for generations to come. We know how challenging it can be for families like Jay & Emma to navigate these waters. By collaborating with Bright Advisers, they created a thorough strategy that involved refining their trust’s recipient designations and utilizing innovative investment approaches such as smart beta and factor investing.
This method not only protects their assets but also aligns with their long-term financial objectives, demonstrating the significance of careful selection of recipients in achieving peace of mind. By taking these steps, you can safeguard your family’s legacy and ensure that your financial goals are met, no matter what life throws your way.
Designate Primary and Contingent Beneficiaries Effectively
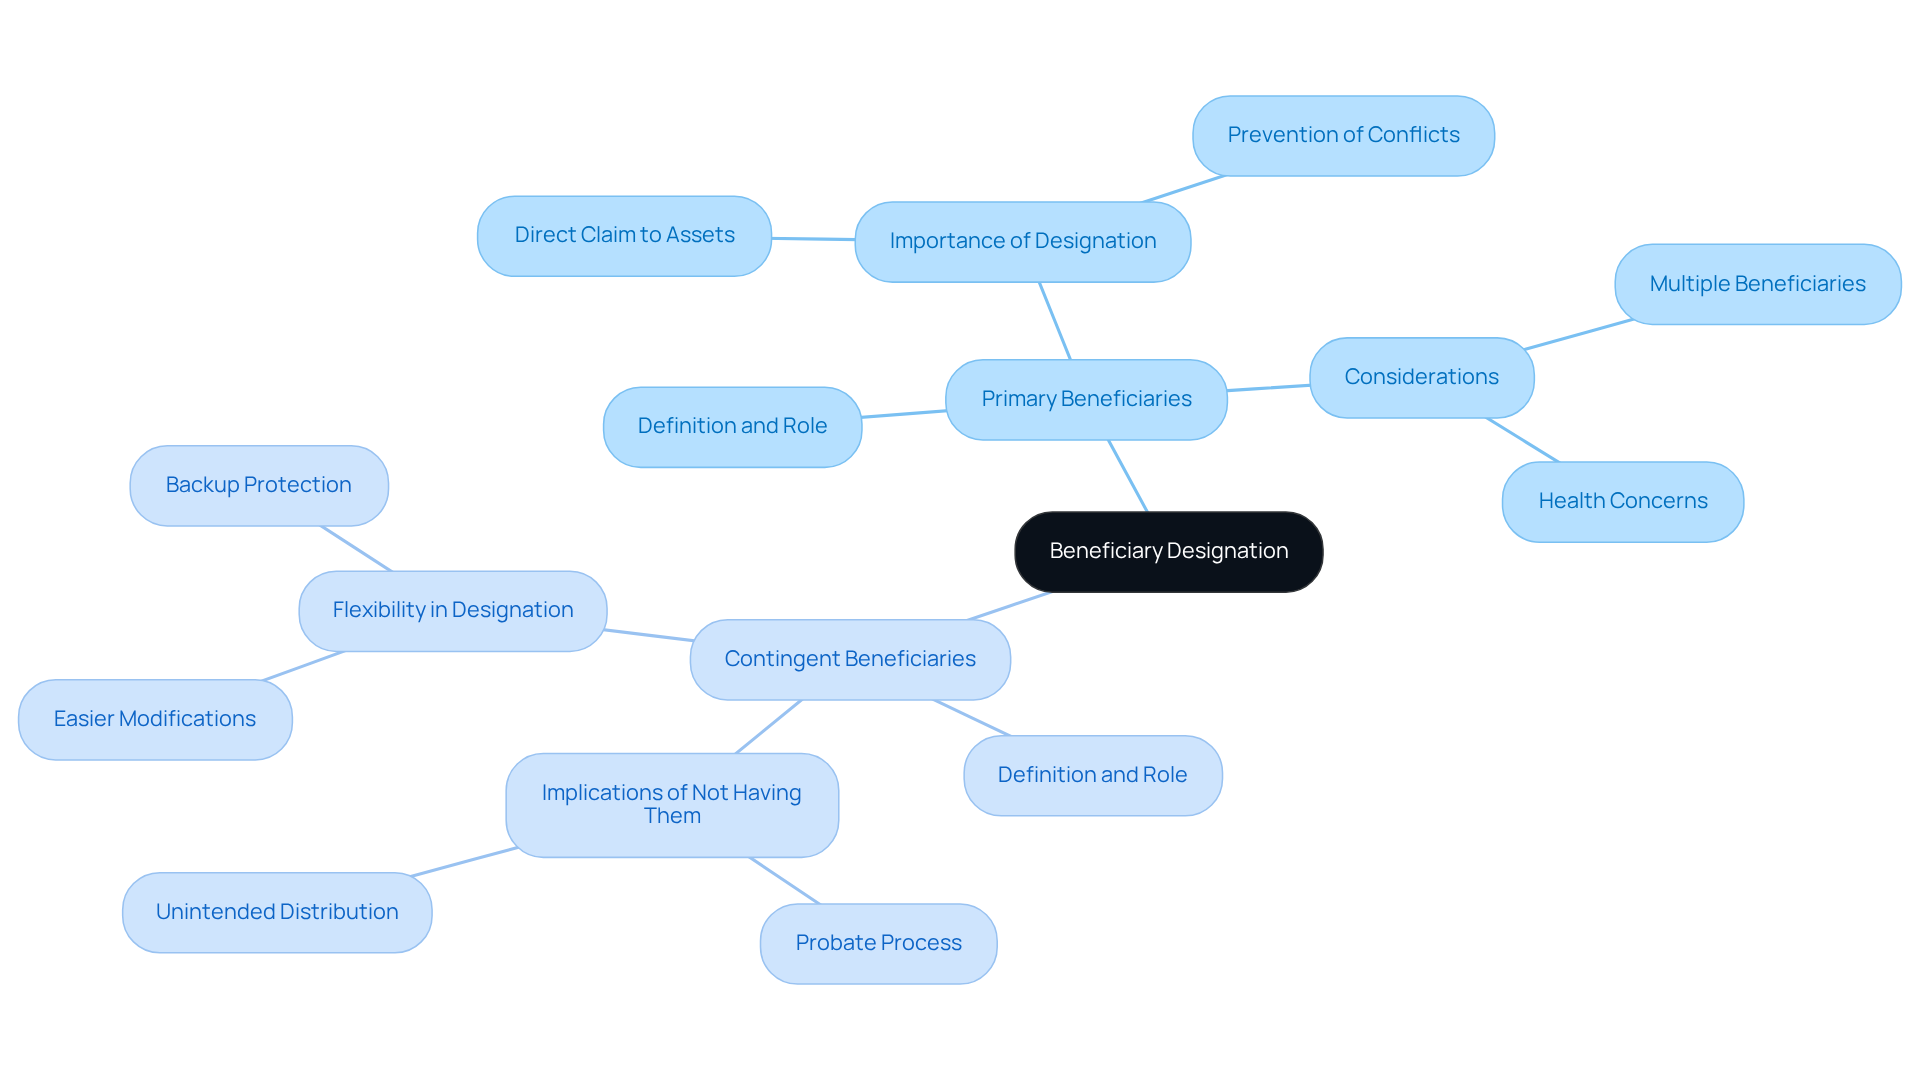
Imagine the peace of mind that comes from knowing your loved ones will be taken care of, even when you’re not there to guide them. When creating an irrevocable trust FDIC coverage arrangement, it’s essential to identify both primary and secondary recipients. Primary recipients are the first in line to receive trust assets, while alternate recipients inherit if the primary recipients are unable to do so. Understanding who will receive your assets can bring peace of mind and help avoid potential conflicts among your loved ones. For instance, if a primary recipient passes away without an appointed alternate recipient, the distribution may default to state laws, which could lead to unintended consequences and a prolonged probate process.
It’s equally important to regularly review and update these designations, especially after significant life events like marriage, divorce, or the birth of a child. Many families overlook the importance of naming a backup recipient, which can lead to unnecessary delays and stress during difficult times. By clearly identifying both primary and secondary recipients, you can maintain control over asset distribution and ensure that your financial legacy is preserved for future generations.
Creating a trust for minor recipients is a wise choice, as minors cannot directly receive substantial inheritances. This approach not only safeguards the assets but also provides a structured plan for their eventual distribution. Consulting with a knowledgeable estate planning professional can assist you in navigating these complexities and ensuring that your beneficiary designations align with your overall estate plan.
At Bright Advisers, we are dedicated to improving wealth management accessibility for families through our transparent, all-inclusive fee structure, which includes minimal fund fees. This commitment enables you to concentrate on your financial security and legacy planning without the burden of hidden costs. By reducing fees, families can direct more resources toward their estate planning requirements, ensuring that their arrangements are set up effectively and efficiently. By taking these steps, you can ensure that your family’s future is secure, allowing you to focus on what truly matters – creating lasting memories together.
Differentiate Between Formal and Informal Trusts
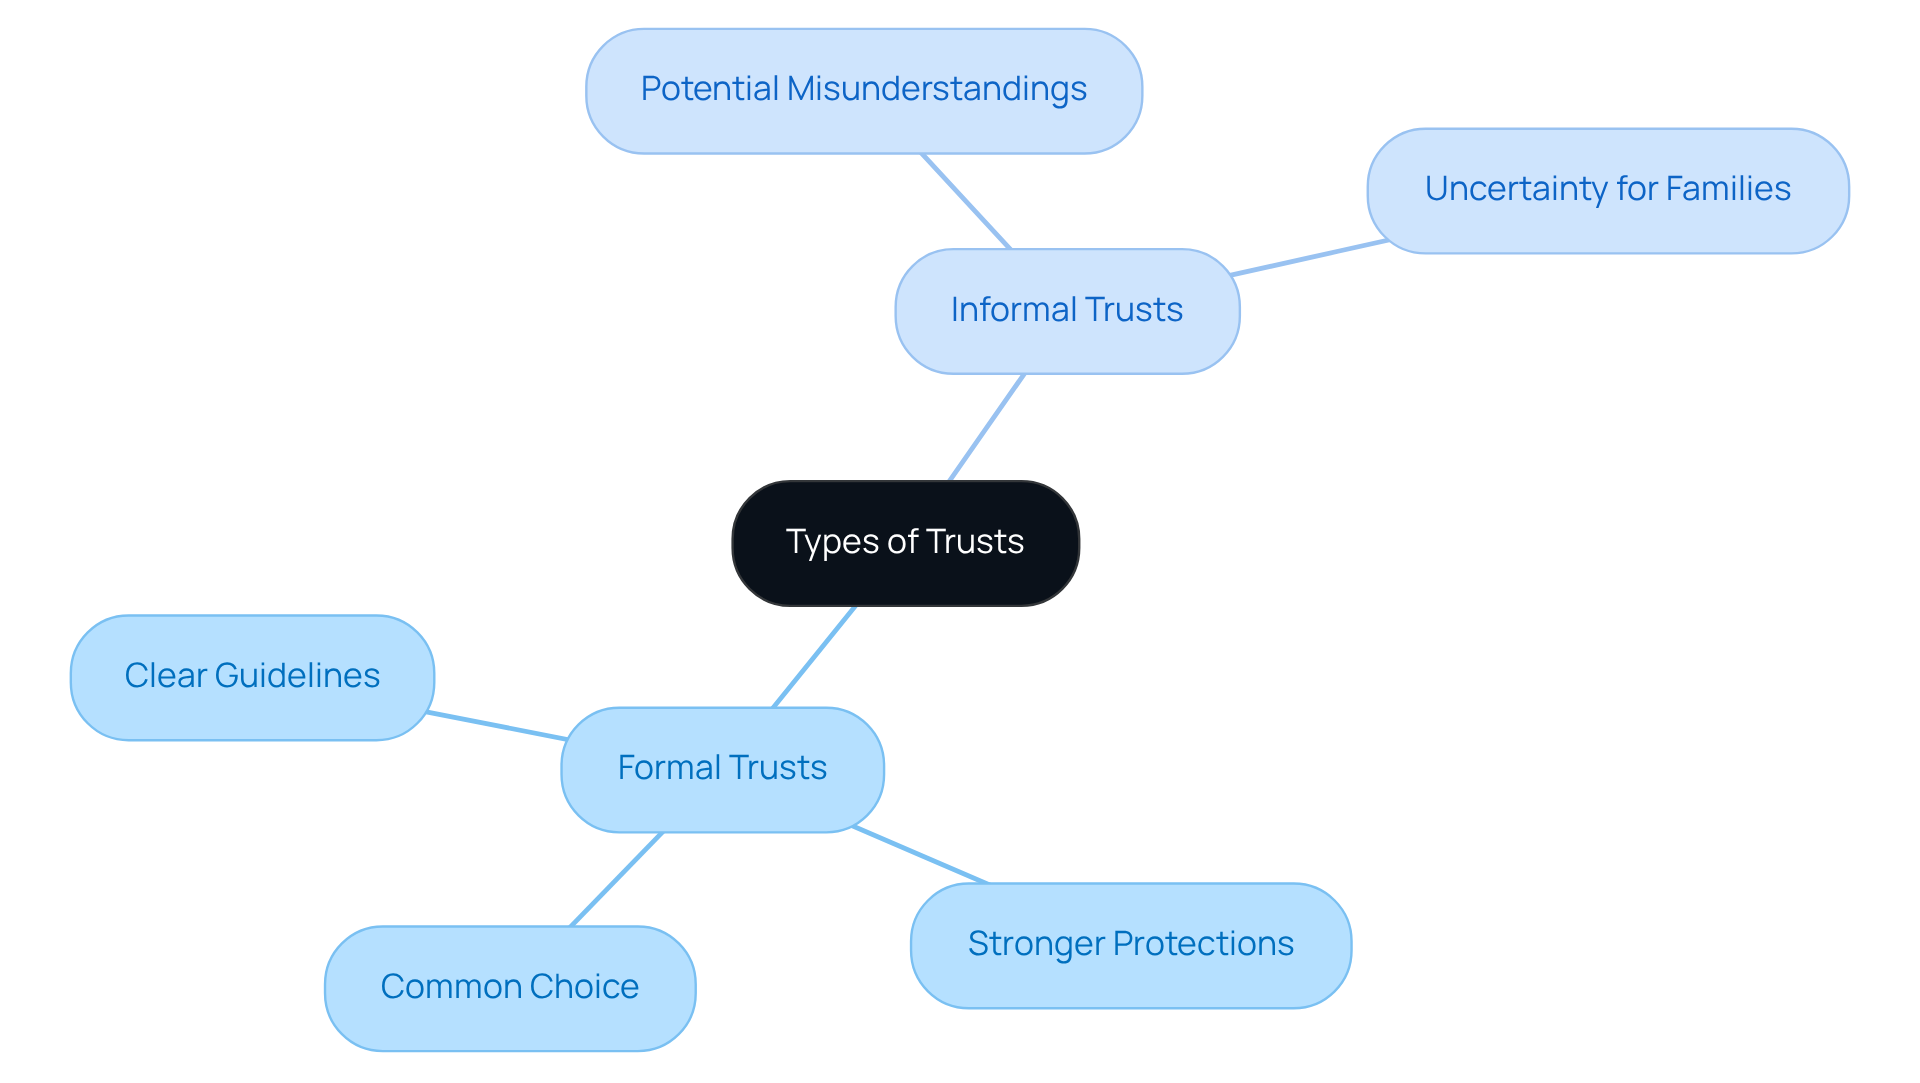
Imagine the peace of mind that comes from knowing your family’s future is secure, even when you’re not there to guide them. Formal arrangements help you set clear guidelines for managing and distributing your assets, giving you peace of mind. On the other hand, informal arrangements can be tricky. Without a written agreement, misunderstandings can arise, leaving your family’s future uncertain. As a parent, understanding these differences is crucial.
Formal arrangements offer stronger protections, ensuring your wishes are honored when it matters most. Did you know that many families choose formal arrangements? It’s a common choice that can make a big difference in securing your loved ones’ future. Families who opt for formal arrangements often find it easier to manage their assets, reducing stress during difficult times.
Consider creating formal arrangements to help protect your children’s financial future. It’s a step toward peace of mind for your family. At Bright Advisers, we’re here to support you with personalized financial planning, helping you make the best choices for your family’s future.
Assess the Effects of Death on Trust Coverage
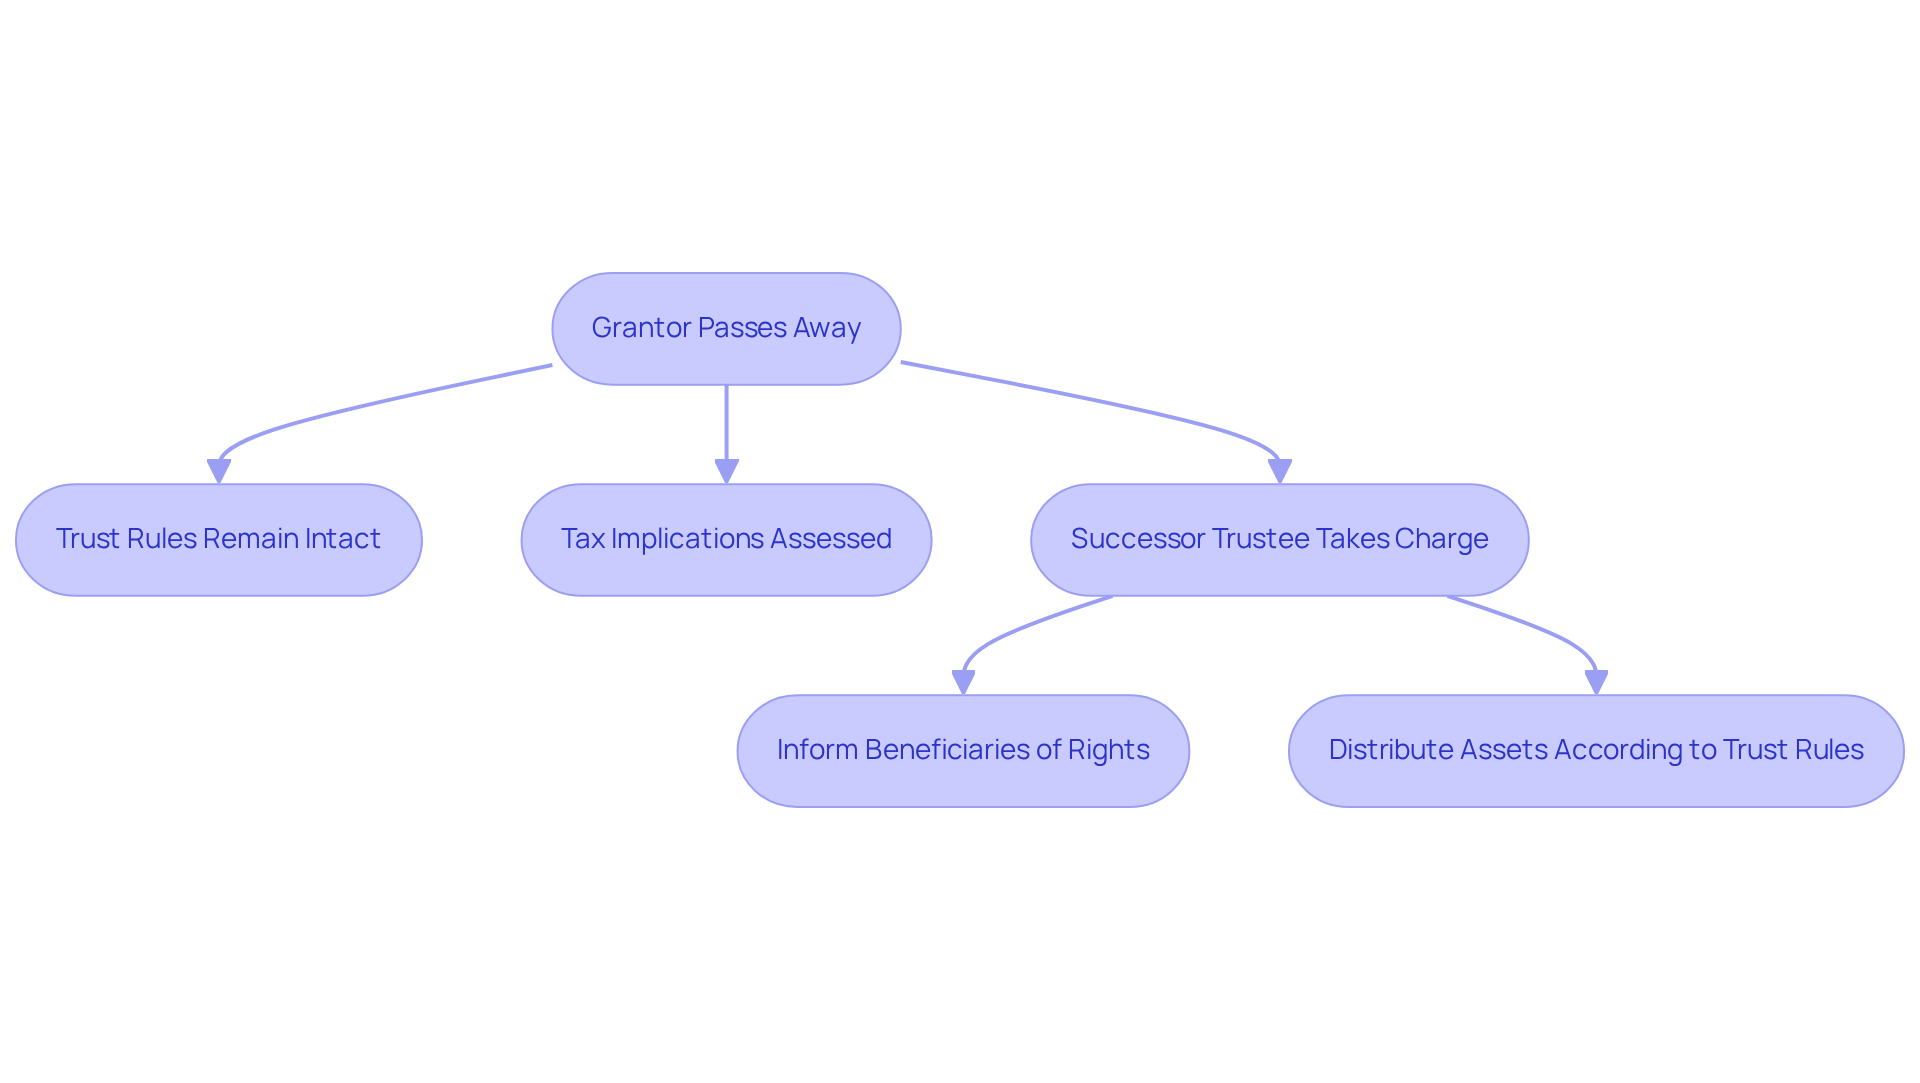
Many families feel overwhelmed by the complexities of estate planning, especially when it comes to irrevocable trusts. When the grantor passes away, the irrevocable trust can’t be changed, which means its rules stay the same. While the assets may face different tax implications, the irrevocable trust FDIC coverage for the account remains intact. Importantly, the assets of the trust are excluded from the grantor’s estate for tax purposes, which can provide significant tax benefits.
Take Jay and Emma, for instance. They wanted to ease their financial worries, and by setting up an irrevocable trust, they found a way to manage their resources better, ensuring their kids’ education and their own retirement were secure. Similarly, Emily and Mark benefited from a comprehensive strategy that included tax-loss harvesting and investment approaches tailored to their needs. Allison and Brian also recognized how vital tax planning is for enhancing their financial potential.
It’s important for families to talk to a tax expert who can help them understand how these arrangements affect their finances, ensuring they grasp how the structure can influence their overall estate strategy. Plus, the successor trustee takes charge of the trust, responsible for overseeing and distributing assets according to the trust’s rules. This change is essential, as it ensures that beneficiaries are informed of their rights and the terms of the trust within 60 days of the grantor’s passing.
By understanding these dynamics, families can feel more confident in managing their wealth for future generations.
Maintain Updated Records for Trust Compliance
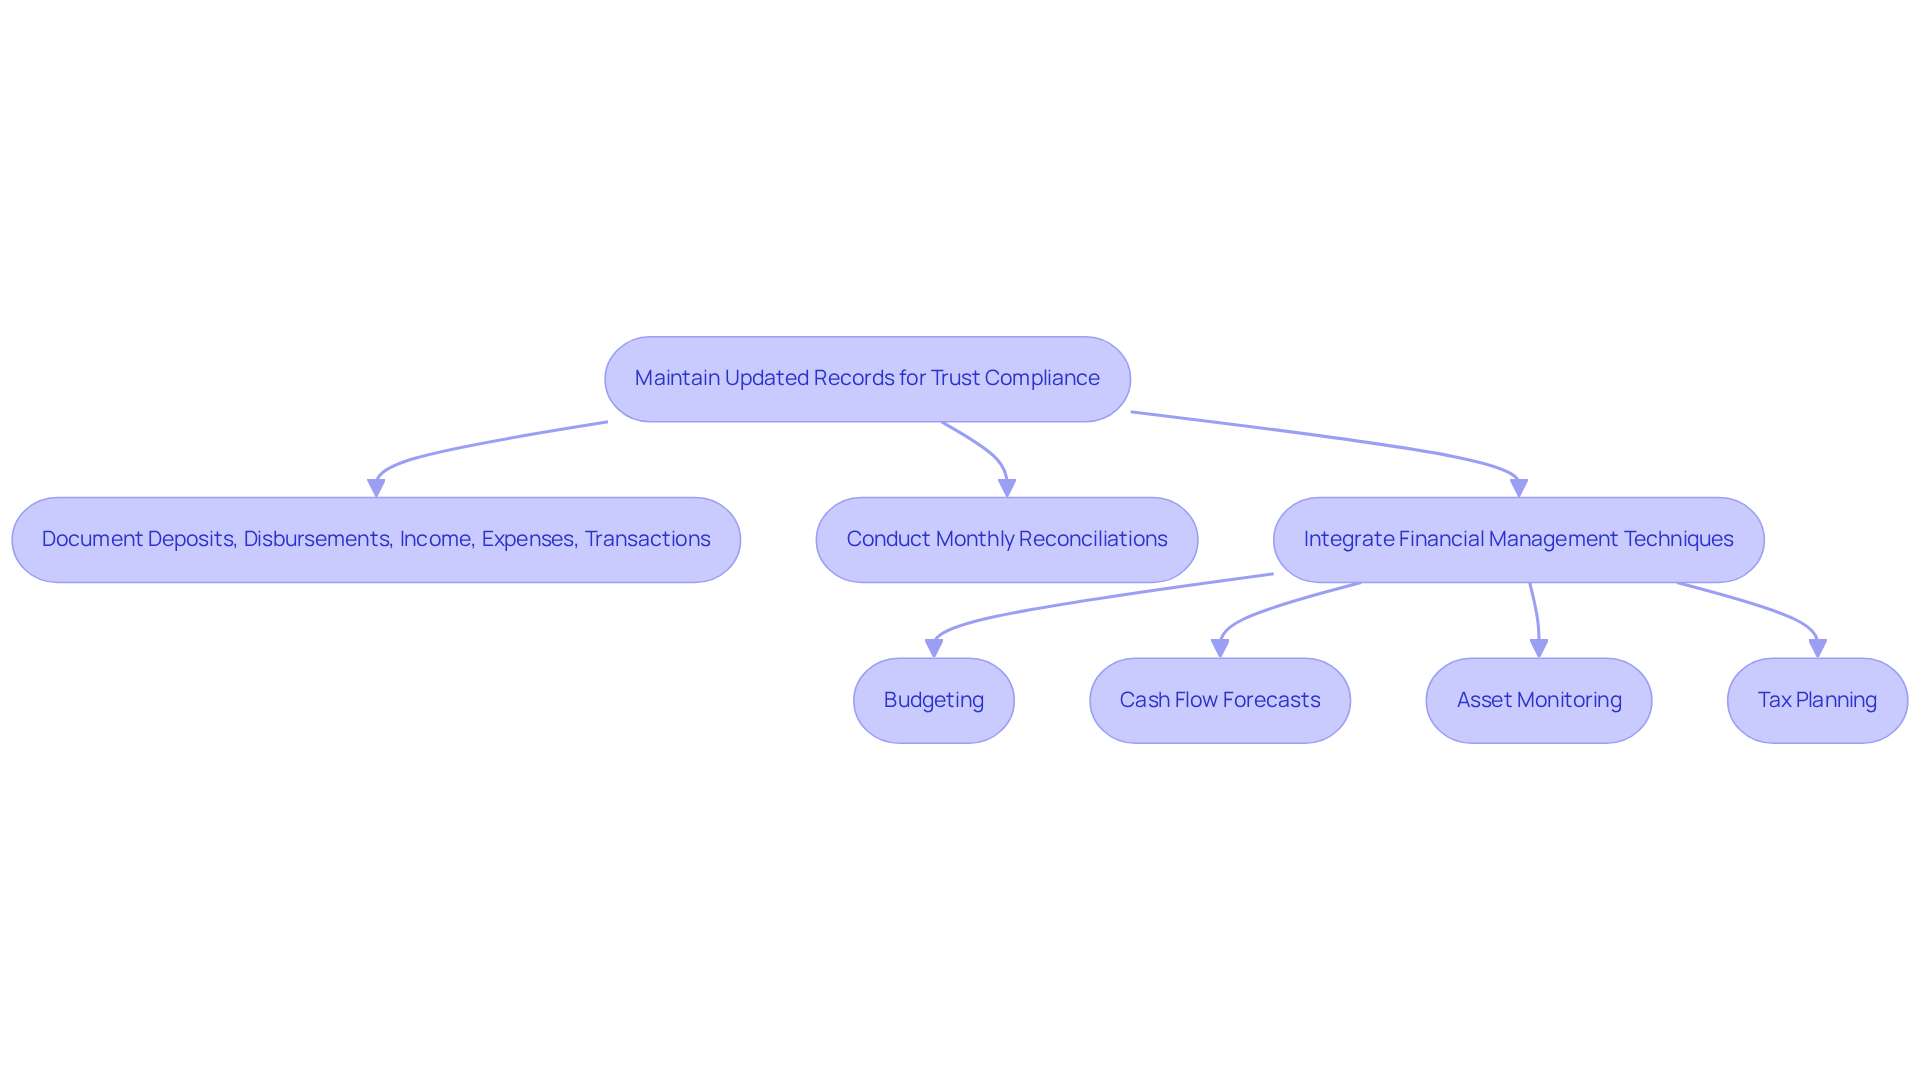
Imagine the peace of mind that comes from knowing your family’s financial future is secure and well-organized. To ensure you meet legal obligations, it’s essential to keep precise and current records for your irrevocable trust FDIC coverage arrangement. This means documenting all deposits, disbursements, income, expenses, and transactions systematically. It can feel daunting to keep track of every detail, especially when life gets busy. But consistently reviewing and updating these records can help you avoid legal complications and ensure everything runs smoothly.
When everyone is transparent, it builds trust and confidence among trustees and beneficiaries, making the process smoother for your family. It’s important to remember that mishandling funds can lead to serious consequences, which can be stressful for everyone involved. Working with a financial advisor or attorney can help ensure your records meet all legal requirements and reflect your current wishes.
Keeping account records for a minimum of five years is crucial to adhere to legal requirements. Conducting monthly reconciliations helps ensure that your accounts align with bank statements, reinforcing the importance of maintaining detailed records. Moreover, integrating thorough financial management techniques, such as:
- Budgeting
- Cash flow forecasts
- Asset monitoring
- Tax planning
can further assist you in efficiently overseeing your resources. By taking these steps, you’re not just protecting your assets; you’re safeguarding your family’s future together.
Leverage Bright Advisers for Personalized Trust Management
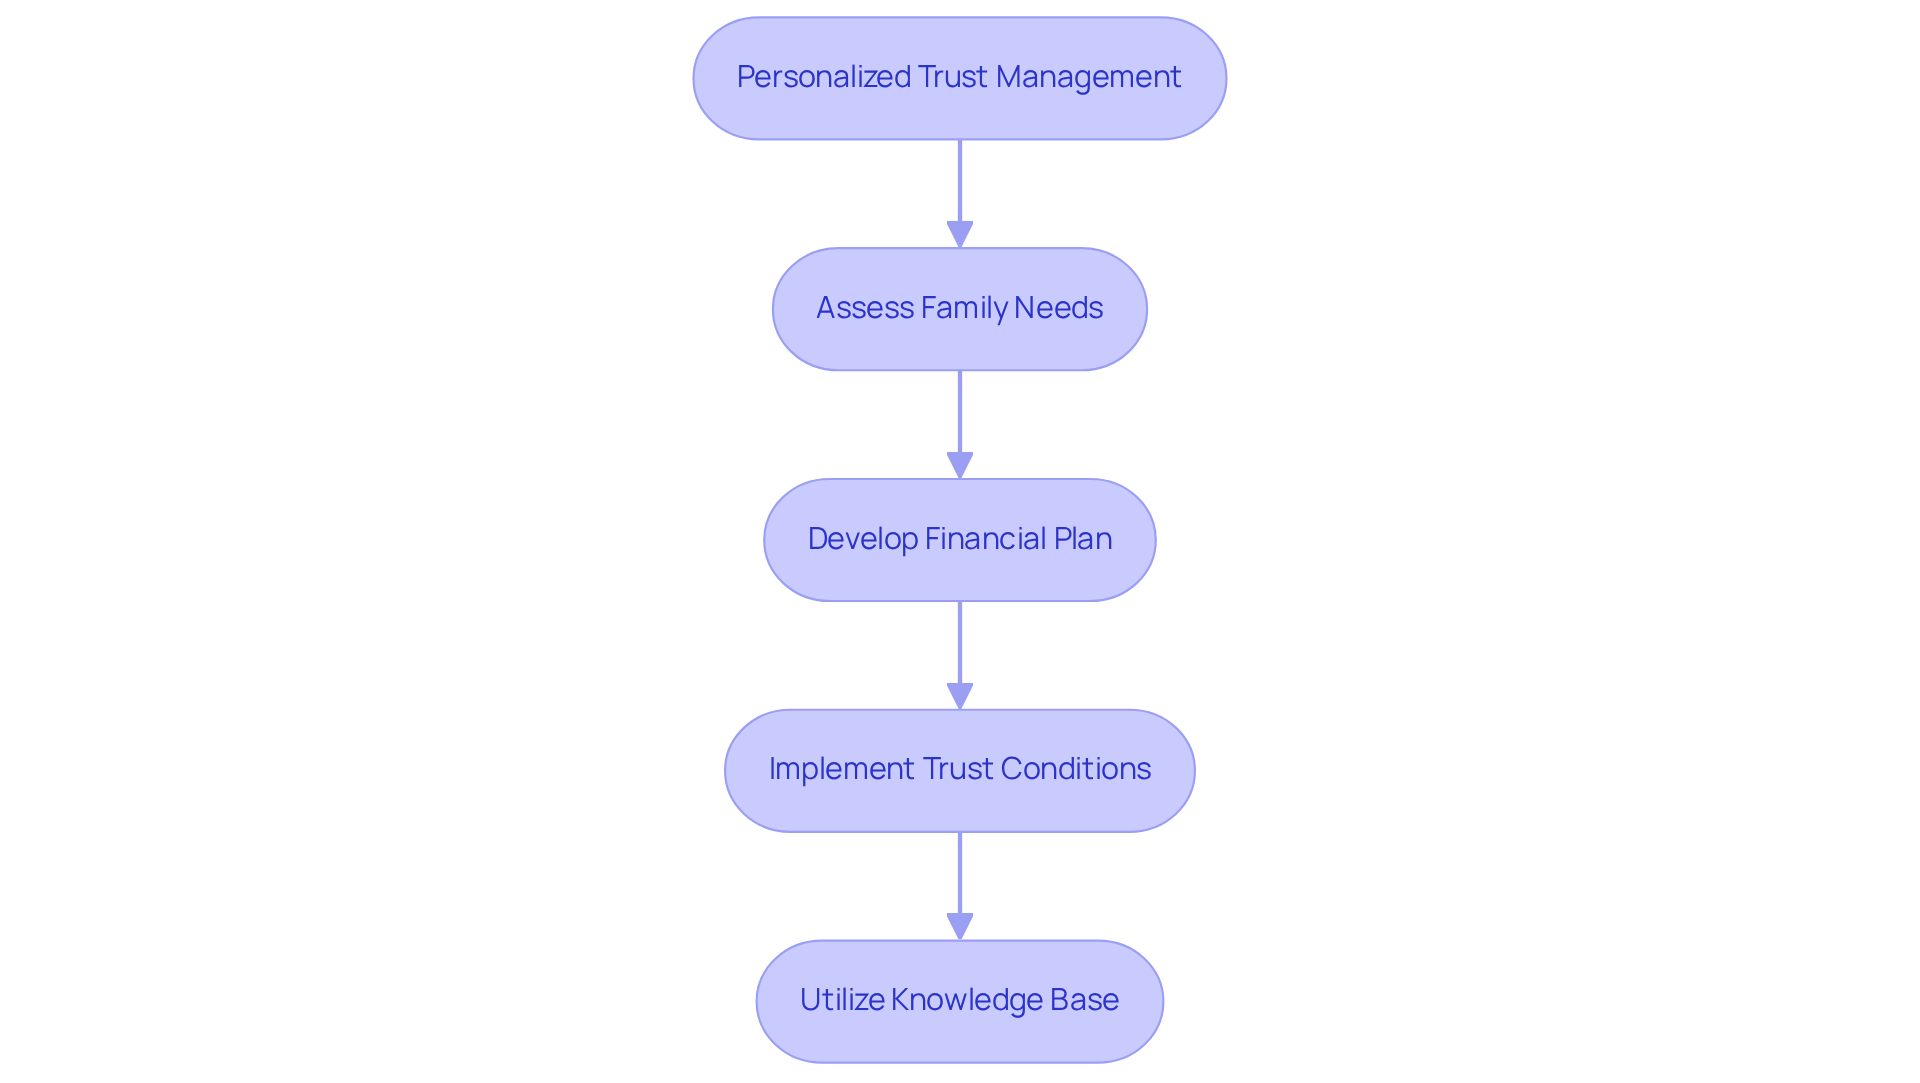
Imagine a future where your children are financially secure, and you can focus on what truly matters – your family. Bright Advisers offers customized management services designed specifically for households with young children. As a fiduciary, we prioritize transparency and your family’s unique needs, providing expert advice to help you create and manage an irrevocable trust fdic coverage. This is especially important as we look ahead to a time when $83 trillion will be passed down to future generations, highlighting the need for thoughtful wealth management.
By utilizing advanced technology and tailored strategies, Bright Advisers helps parents navigate the complexities of trust management, ensuring your children’s economic futures are secure. For instance, you can set specific conditions for when and how your children receive their inheritance, such as distributing funds at certain ages or upon achieving specific milestones. This organized approach not only protects your assets but also encourages responsible financial behavior among your beneficiaries.
The Knowledge Base is an essential tool that assists families in organizing, sharing, and safeguarding their values, stories, and traditions, further enhancing your planning efforts.
Consider the story of Emily and Mark. They faced overwhelming financial stress as rising living expenses and childcare costs weighed heavily on their shoulders. With a tailored strategy from Bright Advisers, they found relief from financial stress, allowing them to make choices that prioritized their family’s well-being and peace of mind.
With childcare expenses projected to average around $20,000 yearly in 2025, families are increasingly recognizing the need for effective budgeting. At Bright Advisers, we help families create financial plans that reflect their values and dreams, ensuring they’re ready for future expenses like education and healthcare. Plus, we offer a transparent, all-inclusive fee structure with no hidden fees, commissions, or trade fees, fostering clarity and trust for families. If you’re interested in these essential services, we invite you to join our current client waitlist for tailored support.
By taking these steps today, you’re not just planning for tomorrow; you’re building a legacy of security and love for your family.
Conclusion
Many parents feel overwhelmed by the complexities of financial planning, especially when it comes to trusts and asset protection. These trusts can protect your family’s assets while also offering benefits like tax savings and access to government programs. Setting up an irrevocable trust helps keep your family’s wealth safe, giving you peace of mind during uncertain times.
We’ve shared important insights about:
- What it takes to set up an irrevocable trust
- Why choosing the right beneficiaries matters
- How FDIC insurance limits come into play
Planning carefully can help you maximize coverage and protect your assets, so it’s crucial to be clear about who your beneficiaries are to avoid any issues. It’s also important to understand how ineligible beneficiaries can affect your trust and why keeping your records up to date is vital for managing it well.
Irrevocable trusts do more than just protect your assets; they can shape your family’s legacy in meaningful ways. Working with experts like Bright Advisers can help you navigate these complexities, ensuring you feel confident in your decisions. Taking these steps today can help ensure your family’s future is secure, allowing you to focus on what truly matters: your loved ones.
Frequently Asked Questions
What is an irrevocable trust and its purpose?
An irrevocable trust is a financial arrangement designed to protect a family’s future by ensuring that assets are secure for beneficiaries, such as children. It can help reduce estate taxes, qualify for government programs, and protect assets from creditors.
How prevalent are irrevocable trusts among high-income families?
Approximately 34% of high-income families have already established irrevocable trusts, and an additional 16% are planning to do so soon.
What are the FDIC insurance limits for irrevocable trusts?
FDIC insurance covers accounts up to $250,000 for each depositor. With multiple beneficiaries in an irrevocable trust, coverage can increase significantly. For example, a trust with four beneficiaries can be insured for up to $1,000,000, and one with five beneficiaries can secure up to $1,250,000.
When do the new FDIC regulations regarding irrevocable trust coverage take effect?
The new FDIC regulations enhancing irrevocable trust coverage will take effect on April 1, 2024.
What are the requirements for establishing an irrevocable trust?
To establish an irrevocable trust, you need a competent grantor, clear intent documented in an agreement, designated beneficiaries, and property to be included in the trust. Consulting with a legal expert is recommended to ensure proper setup.
How can irrevocable trusts assist with Medicaid planning?
Transferring assets to certain irrevocable arrangements over five years before applying for Medicaid may prevent those assets from counting against you, which can be beneficial for long-term care planning.
What legal considerations are important when creating an irrevocable trust?
It is essential to have the agreement in writing, as required by New York law, to avoid misunderstandings. Additionally, keeping personal and asset holdings separate is crucial to prevent unexpected tax consequences.
How can Bright Advisers assist families with irrevocable trusts?
Bright Advisers offers comprehensive estate planning services, including guidance on irrevocable trust FDIC coverage, tax-loss harvesting, and proactive tax planning to help families secure their financial future and legacy.
List of Sources
- Define Irrevocable Trusts and Their Purpose
- “Never do an irrevocable trust”
If your lawyer tells you that, take it as a sign that you are talking to the wrong lawyer.
I hear this one all the time. A client comes in and tells me, “My… | Michael Monteforte Jr., Esq. | 13 comments (https://linkedin.com/posts/mikemontefortelaw_never-do-an-irrevocable-trust-if-your-activity-7477696231151046656-zirK)
- Irrevocable Trusts: Advantages, Disadvantages, and Tips (https://savvywealth.com/blog-posts/pros-and-cons-of-irrevocable-trusts)
- Irrevocable Trusts: A Complete Guide (https://cantrellfirm.com/blog/irrevocable-trusts-guide)
- When Do Irrevocable Trusts Make Sense? (https://colonialsurety.com/when-do-irrevocable-trusts-make-sense-blog)
- Understand FDIC Insurance Limits for Irrevocable Trusts
- Your Insured Deposits | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/insured-deposits)
- FDIC Insurance for Trusts | Pinnacle Financial Partners (https://pnfp.com/learning-center/personal-finance/managing-your-money/fdic-insurance-for-trusts)
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- Nelson Mullins – FDIC Modifies Deposit Rules for Trusts (https://nelsonmullins.com/insights/blogs/the-estate-planning-and-probate-litigation-blog/estate-planning/fdic-modifies-deposit-rules-for-trusts)
- Identify Requirements for Establishing an Irrevocable Trust
- Irrevocable Trusts: A Complete Guide (https://cantrellfirm.com/blog/irrevocable-trusts-guide)
- Irrevocable Trust: Definition, Benefits, and Key Considerations (https://justvanilla.com/estate-planning-glossary/irrevocable-trust)
- Requirements for Establishing an Irrevocable Family Trust | Rossi & DeMarco PLLC (https://rossidemarco.com/blog/requirements-for-establishing-an-irrevocable-family-trust)
- Maximizing Estate Planning: The Benefits and Considerations of Irrevocable Trusts | Aldrich Wealth (https://wealthadvisors.com/insights/maximizing-estate-planning-benefits-considerations-irrevocable-trusts)
- Explore Coverage Calculation for Multiple Beneficiaries
- Your Insured Deposits | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/insured-deposits)
- FDIC Insurance Coverage of Trust Accounts (https://hansonbridgett.com/publication/031423-0500-fdic-coverage-trust-accounts)
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- FDIC Insurance for Trusts | Pinnacle Financial Partners (https://pnfp.com/learning-center/personal-finance/managing-your-money/fdic-insurance-for-trusts)
- Recognize the Impact of Ineligible Beneficiaries on Coverage
- FDIC Insurance & How it Works | Live Oak Bank (https://liveoak.bank/blog/how-fdic-insurance-works)
- The FDIC Has New Deposit Insurance Rules For Trust Accounts (https://conaelderlaw.com/fdic-new-deposit-insurance-rules-for-trust-accounts)
- Weinstock Manion (https://weinstocklaw.com/news/new-fdic-rules-affecting-insurance-limits-on-trust-account-deposits)
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- Your Insured Deposits | FDIC.gov (https://fdic.gov/resources/deposit-insurance/brochures/insured-deposits)
- Designate Primary and Contingent Beneficiaries Effectively
- Primary vs. Contingent Beneficiary: What You Need to Know (https://westernsouthern.com/life-insurance/primary-vs-contingent-beneficiary)
- Primary vs Contingent Beneficiary: How to Choose (https://legalshield.com/blog/primary-vs-contingent-beneficiary)
- Primary vs Contingent Beneficiary, What’s the Difference? (https://stonesalluslaw.com/primary-vs-contingent-beneficiary)
- Why Beneficiary Designations are Important (https://dalyperri.com/blog/why-beneficiary-designations-are-important)
- Differentiate Between Formal and Informal Trusts
- Trust Accounts | FDIC.gov (https://fdic.gov/financial-institution-employees-guide-deposit-insurance/trust-accounts)
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- The Ultimate Guide to Informal Trusts (For Canadians) | Eat Sleep Breathe FI (https://eatsleepbreathefi.com/informal-trusts)
- SOI Tax Stats – Estate, gift and trust statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-estate-gift-and-trust-statistics)
- What you need to know about trusts | Manulife Investments (https://manulifeim.com/retail/ca/en/viewpoints/estate-planning/understanding-trusts-and-contracts-held-in-trust)
- Assess the Effects of Death on Trust Coverage
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- What Happens To An Irrevocable Trust When The Grantor Dies? (https://aldavlaw.com/blog/what-happens-to-an-irrevocable-trust-when-the-grantor-dies)
- What Heirs Should Know About Taxes When Inheriting a Trust (https://centraltrust.net/what-heirs-should-know-about-taxes-when-inheriting-a-trust)
- Irrevocable trusts: What beneficiaries need to know to optimize their resources | J.P. Morgan Private Bank U.S. (https://privatebank.jpmorgan.com/nam/en/insights/wealth-planning/irrevocable-trusts-what-beneficiaries-need-to-know-to-optimize-their-resources)
- Life Insurance Trusts Explained | Guardian (https://guardianlife.com/life-insurance/trusts)
- Maintain Updated Records for Trust Compliance
- Trusts Accounting Essentials (https://btcpa.net/insights/trusts-accounting-essential-practices-for-managing-and-reporting-on-trusts-and-estates)
- Trust Quotes to Help Build Stronger Relationships | Adobe Express (https://adobe.com/express/discover/quotes/trust)
- How Long Must Trust Account Records Be Kept (https://irvinebookkeeping.com/post/how-long-must-trust-account-records-be-kept)
- Leverage Bright Advisers for Personalized Trust Management
- Private Wealth Management Banking for Young Families: Strategies and Services – Bright Advisers (https://brightadvisers.com/post/private-wealth-management-banking-for-young-families-strategies-and-services)
- What Do Wealth Advisors Do for Young Families? – Bright Advisers (https://brightadvisers.com/post/what-do-wealth-advisors-do-for-young-families)
- Trust Planning for Families with Young Children: What Every Parent Should Know (https://cotrustattorney.com/living-trust/trust-planning-for-families-with-young-children)
- Why Young Families Should Consider Trusts | Hermance Law (https://theheritancelawyers.com/blog/why-young-families-should-consider-trusts-a-modern-solution-for-financial-security)
- The Benefits of Creating a Trust for Your Children (https://snw.law/the-benefits-of-creating-a-trust-for-your-children)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading