

Key Highlights:
- The step-up tax basis adjusts inherited asset values to their fair market value at the time of the owner’s death, reducing capital gains tax for heirs.
- Families can benefit significantly from this provision, allowing them to pass on wealth without incurring taxes on appreciation during the original owner’s lifetime.
- Eligible assets for step-up tax basis include real estate, stocks, bonds, and certain business interests, but not all assets qualify.
- Community property states provide a full step-up in value for jointly owned assets, while common law states offer only partial adjustments, affecting estate planning strategies.
- Critics argue that the step-up tax basis disproportionately benefits wealthier families, contributing to wealth inequality and raising concerns about tax reforms.
- Staying informed about potential changes in tax laws and consulting with financial professionals is crucial for effective estate planning.
Introduction
Navigating the complexities of tax regulations can feel overwhelming, especially for young parents who are dedicated to securing their families’ financial futures. One important concept to understand is the step-up tax basis. This provision allows inherited assets to be valued at their fair market price at the time of the owner’s passing, which can save families from significant capital gains taxes.
Imagine if you could pass on your family’s wealth without the burden of hefty tax bills. This is where the step-up tax basis comes into play, offering a potential lifeline for families looking to preserve their legacy. However, it’s essential to consider the broader implications of this provision on wealth distribution and financial planning.
How can families leverage this tax benefit to ensure a lasting legacy while also addressing concerns about equity in wealth transfer? It’s a question worth exploring, as it touches on the values we hold dear as parents. By understanding these concepts, you can make informed decisions that align with your family’s goals.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and equitable. Remember, you’re not alone in this; we’re here for you every step of the way.
Bright Advisers: Personalized Financial Planning for Understanding Step-Up Tax Basis
At Bright Advisers, we understand the unique challenges that families with young children face when it comes to financial planning. Imagine if you could navigate the complexities of tax regulations with ease, ensuring a secure financial future for your little ones. By highlighting the adjusted tax value, we help you see how this essential regulation can profoundly impact your family’s financial legacy.
The step up tax basis is a key concept that can work in your favor. It adjusts the worth of inherited assets to their fair market value at the time of the owner’s passing. This means that any capital gains accrued during the original owner’s life may not be taxed. For example, if a family home purchased for $500,000 appreciates to $800,000 by the time it’s inherited, the heirs benefit from a step up tax basis of $800,000, thus avoiding taxes on the $300,000 gain. This strategic advantage is vital for families looking to preserve wealth across generations.
Through our innovative technology and client-first approach, we simplify complex financial concepts, ensuring you can make informed decisions about your wealth management strategies. Understanding the implications of increased tax valuation is crucial for parents who want to secure their children’s financial futures while juggling the intricacies of tax laws.
Consider this: families who effectively utilize the increased value method can significantly reduce their tax obligations, enhancing their overall financial well-being and legacy. This personalized guidance isn’t just helpful; it’s essential for young families striving to build a stable financial foundation for their children.
We’re here for you, ready to support you on this journey. Together, we can navigate the world of financial planning, ensuring that your family’s values and goals are at the forefront of every decision.

Step-Up in Basis Defined: What Every Parent Needs to Know
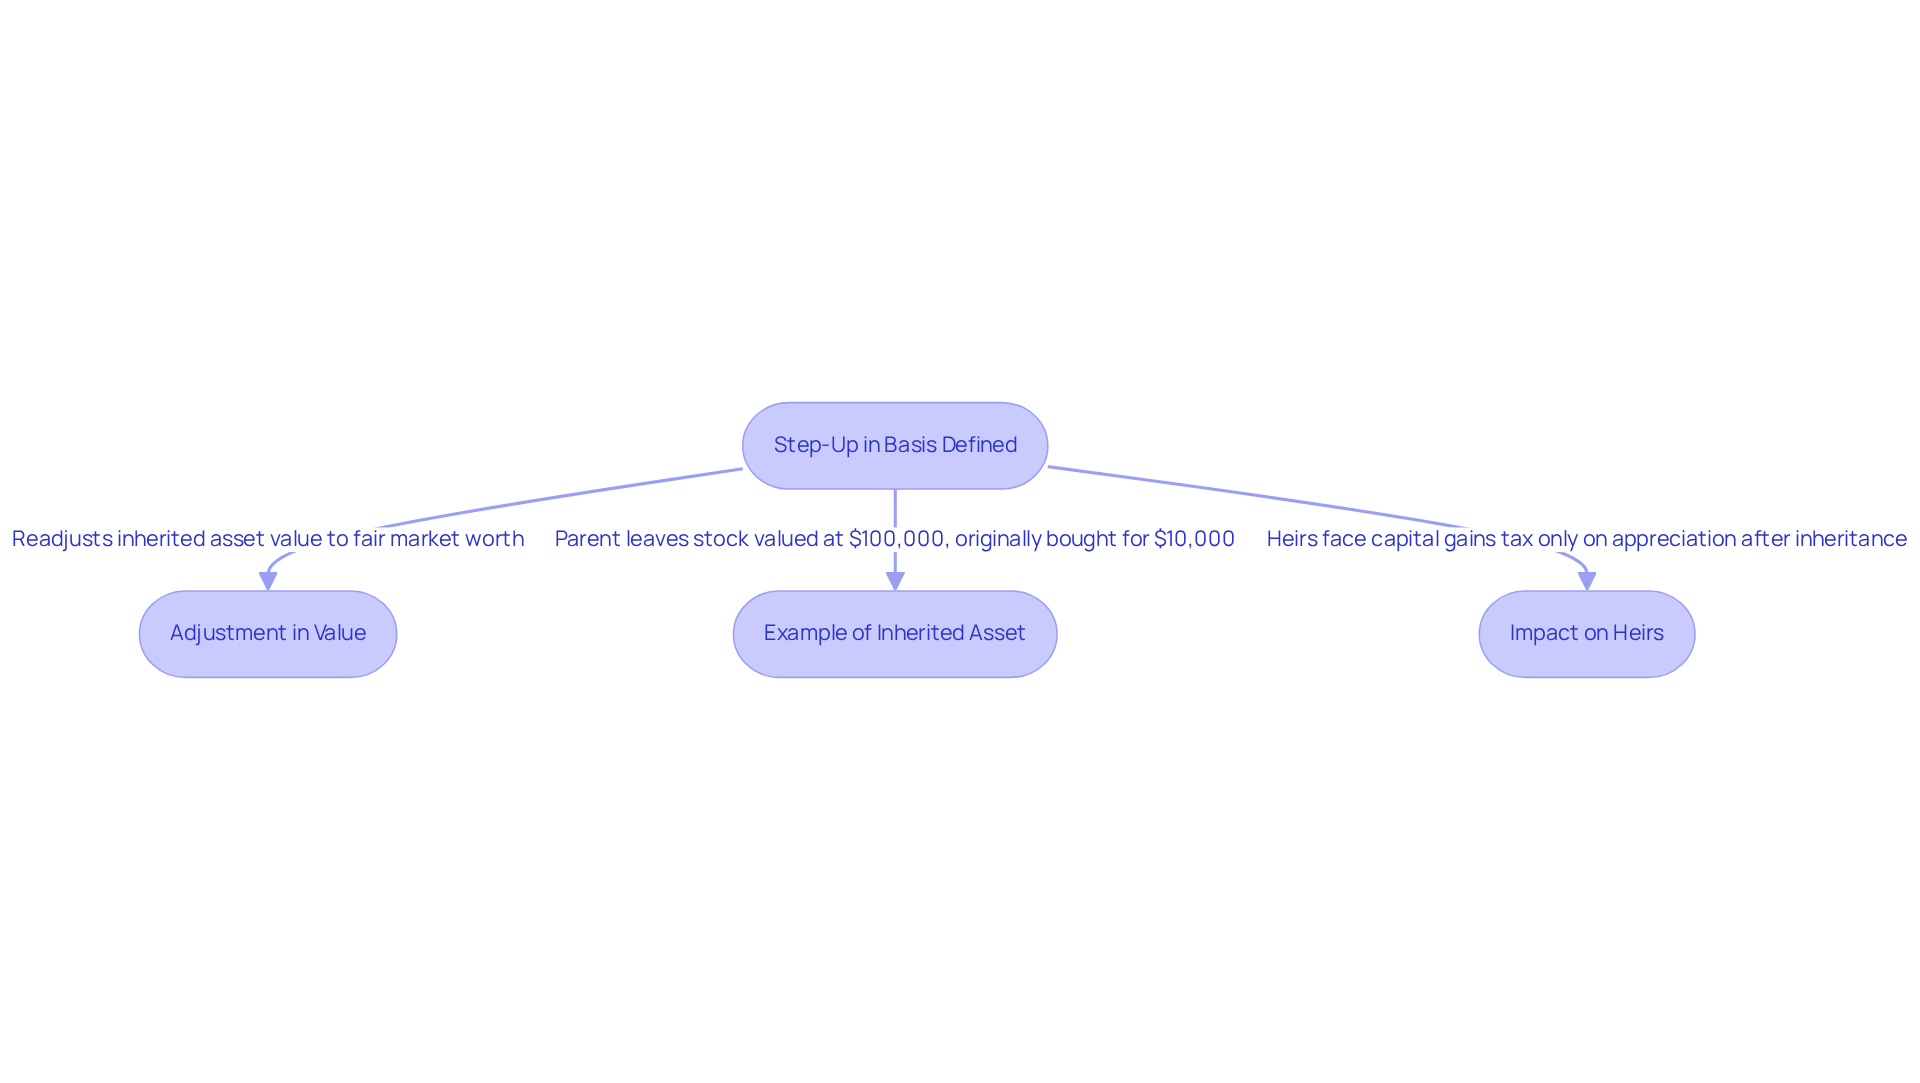
Understanding the adjustment in value is crucial for parents who want to secure their family’s financial future. This essential tax rule provides a step up tax basis by readjusting the cost valuation of inherited assets to their fair market worth at the time of the original owner’s passing. Imagine if you could pass on your hard-earned assets without the burden of hefty taxes. When an heir sells an inherited asset, they only face capital gains tax on any appreciation that occurs after the inheritance due to the step up tax basis, not on the gains made during the original owner’s lifetime.
For instance, if a parent leaves stock worth $100,000, which they initially bought for $10,000, the heir can sell it without incurring capital gains fees. This effectively allows them to step up tax basis to the current market value, resetting their financial foundation and enabling them to start fresh. Grasping this concept can profoundly influence the financial legacy you leave for your children.
Comprehending the increase in value helps in efficient estate planning and demonstrates how to step up tax basis, ensuring that you can enhance the financial advantages for your heirs. This means a better financial future for your family, filled with opportunities and security.
We understand that navigating these financial waters can feel overwhelming. That’s why consulting with a tax advisor or financial professional, like those at Bright Advisers, is a wise step. Together, we can navigate this journey, ensuring your family’s financial well-being is prioritized. We’re here for you, ready to help you create a lasting legacy.
Impact on Capital Gains: How Step-Up in Basis Influences Tax Obligations
Imagine the peace of mind that comes with understanding how inherited assets can impact your family’s financial future. When a loved one passes away, the value of their assets is adjusted to reflect the market price at that moment. This means that if you inherit a property, you might not have to worry about capital gains taxes if you sell it soon after.
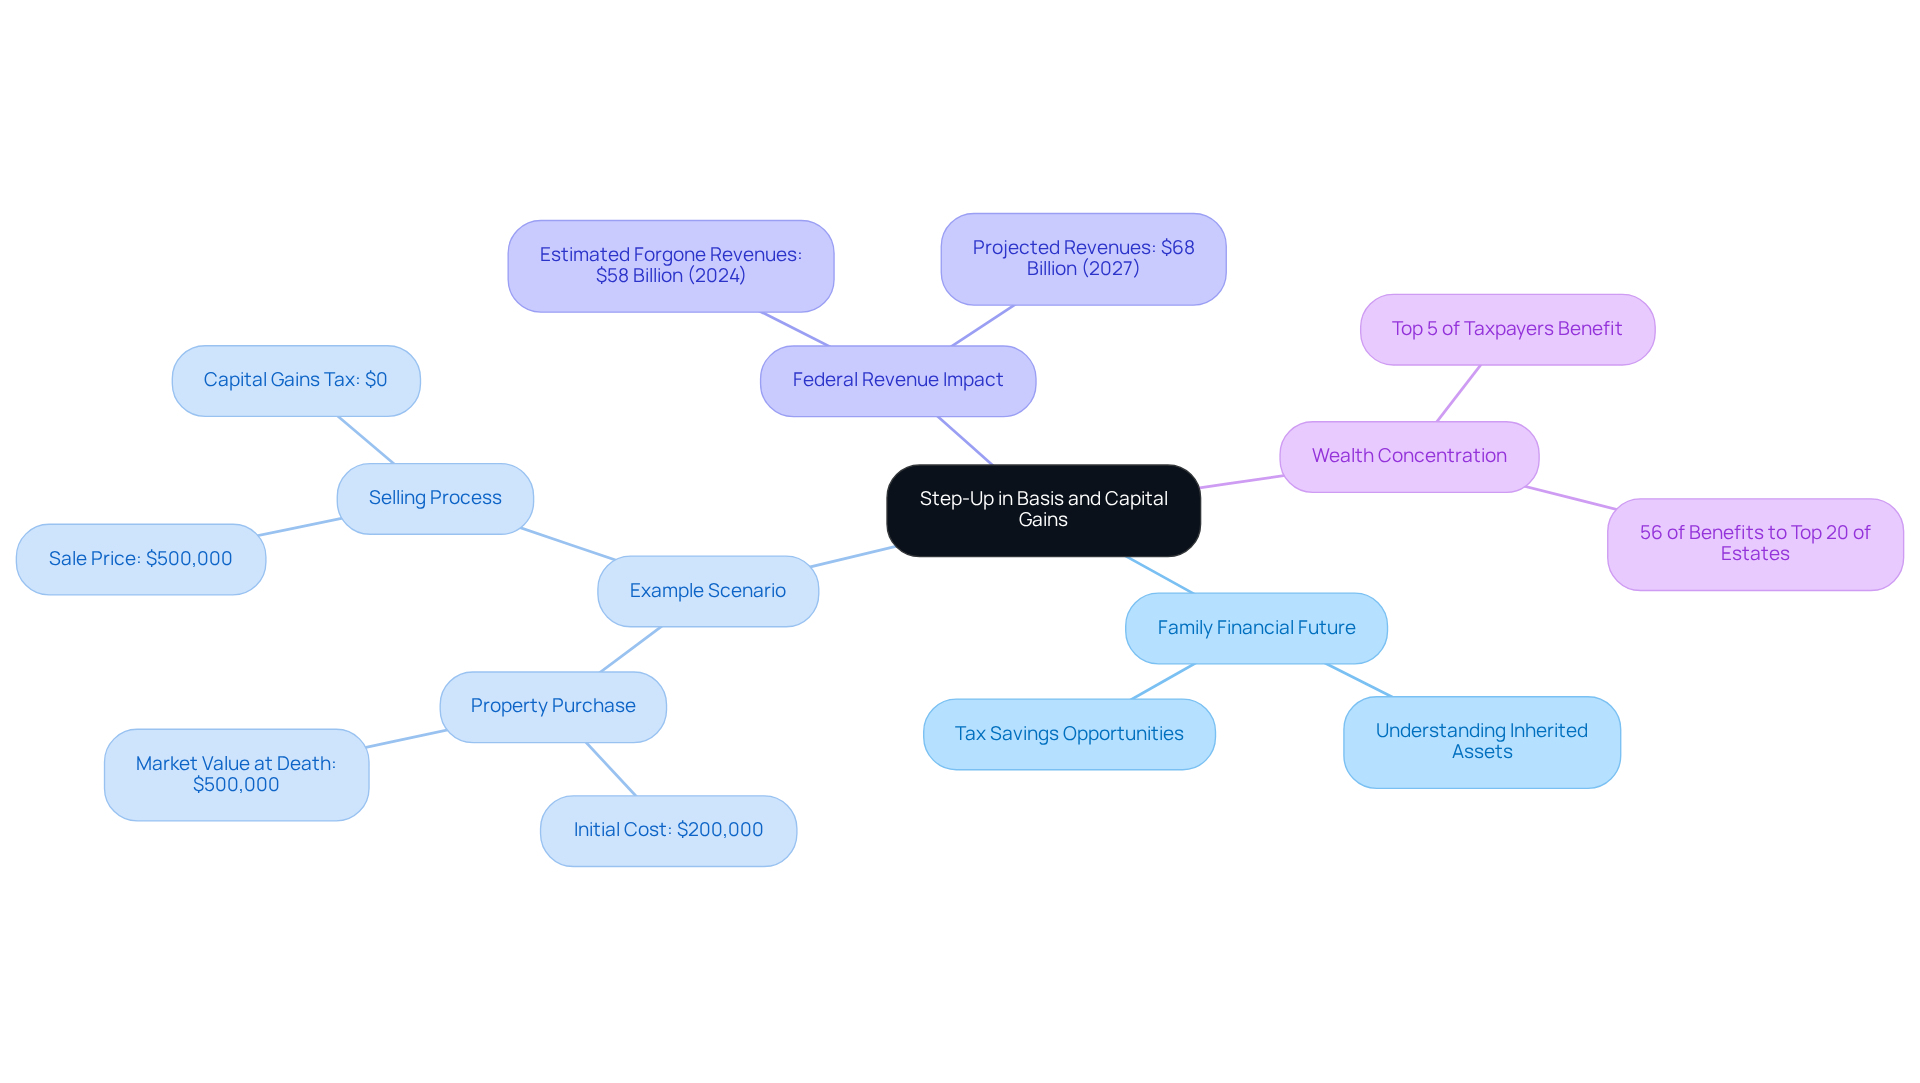
For example, picture a scenario where a parent buys a home for $200,000. At their passing, the property is valued at $500,000. As the heir, your new tax basis is now referred to as the step up tax basis of $500,000. If you sell the property for that same amount, you won’t owe any capital gains taxes. This provision can lead to significant savings, allowing families to step up tax basis and thereby retain more of their inherited wealth.
In fact, the Joint Committee on Taxation estimates that this adjustment will account for $58 billion in lost federal revenues in 2024. This highlights just how crucial it is for families to understand these dynamics as they navigate wealth transfer and tax strategies.
It’s also important to note that over half of the benefits from this provision go to the top 5% of taxpayers, which underscores its impact on wealth concentration. Understanding these nuances can empower families to make informed decisions about their financial obligations.
Together, we can navigate this journey, ensuring that your family’s legacy is preserved and that you can focus on what truly matters—your loved ones.
Qualifying Assets: What Parents Should Know About Step-Up in Basis
Understanding your family’s financial future can feel overwhelming, but it’s crucial to know which assets can truly benefit you. Not all assets qualify for a step up tax basis, so let’s explore this concept together. Generally, eligible assets include:
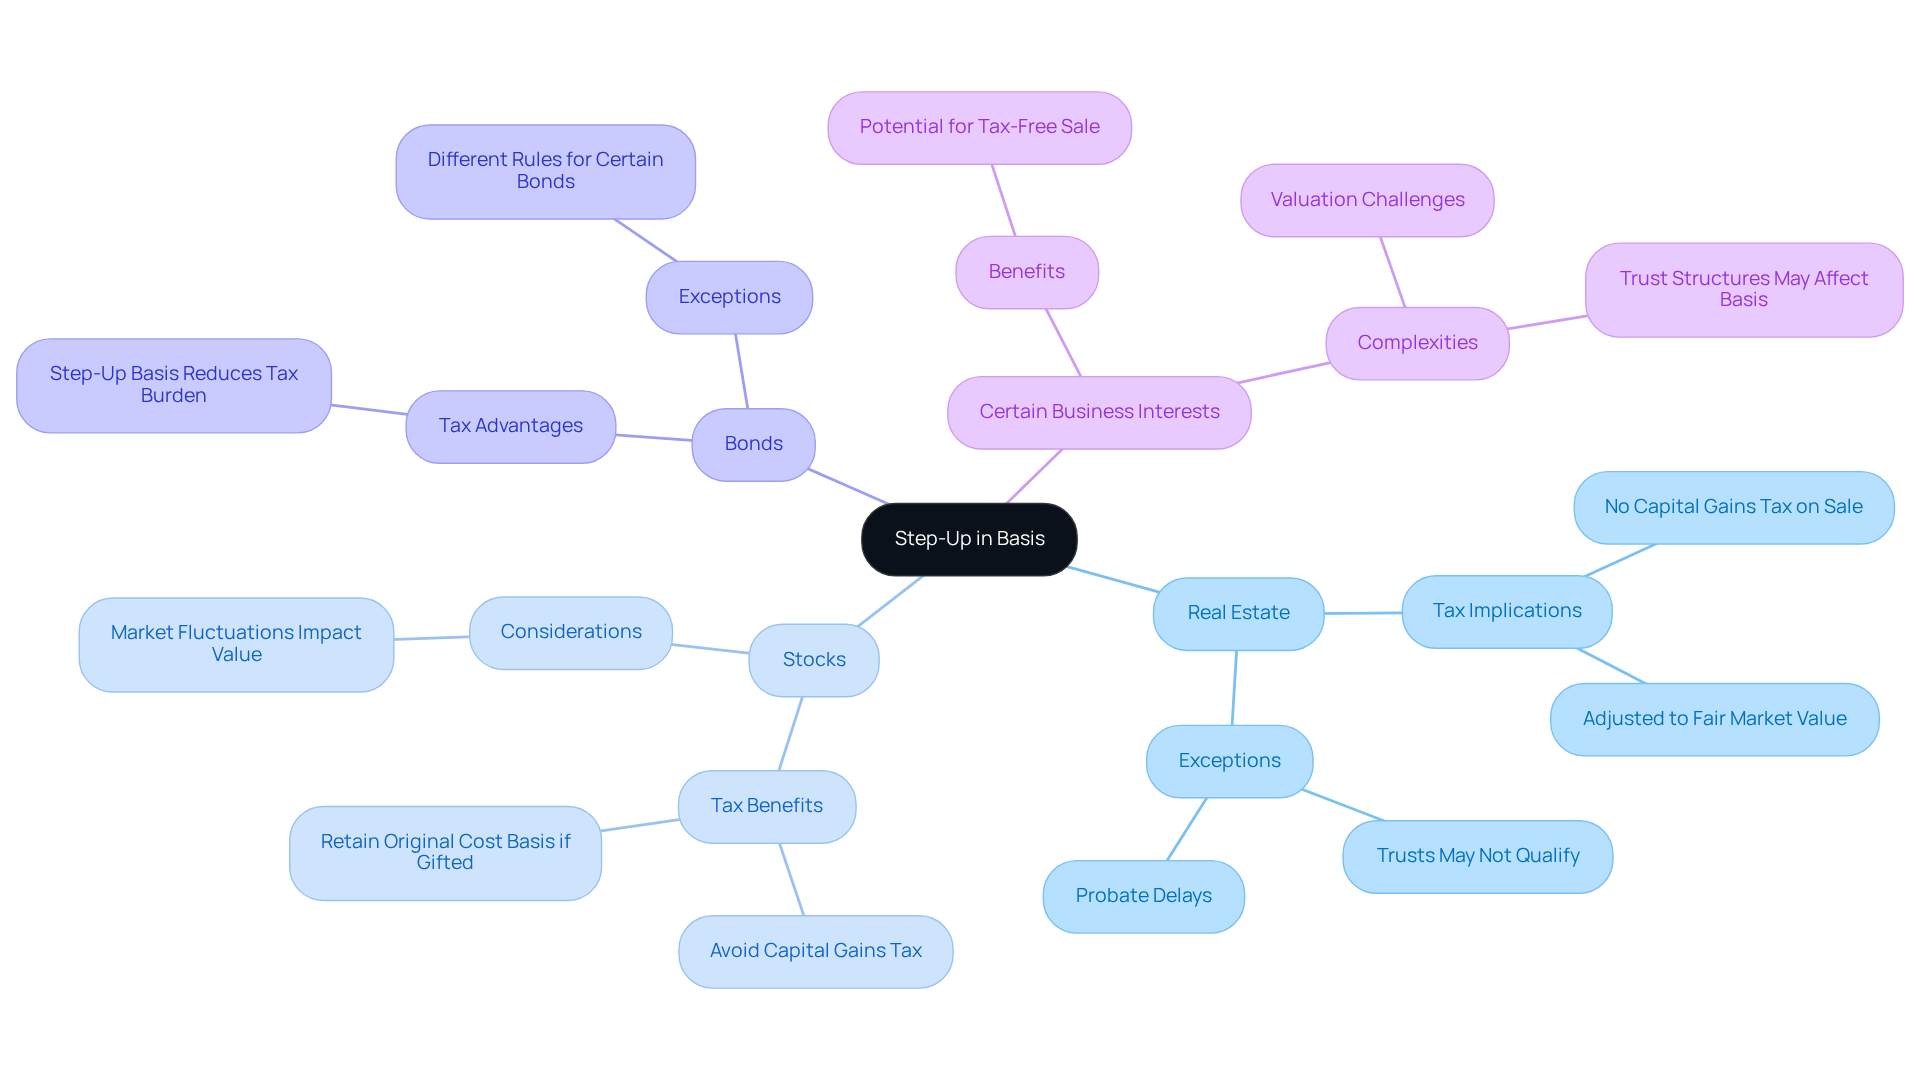
- Real estate
- Stocks
- Bonds
- Certain business interests
Imagine a property you bought for $100,000 that appreciates to $500,000. If this property is inherited, it can significantly impact your tax liabilities. Instead of facing a $400,000 taxable gain if sold while alive, inheriting it provides a step up tax basis to its fair market value at the time of death. This means no capital gains tax on a sale at that value, which is a relief for many families.
However, it’s important to understand that some assets held in specific types of trusts may not qualify for this benefit. To navigate these complexities and ensure effective financial planning for your children’s future, we encourage you to consult with a financial planner. They can clarify which assets are eligible and how to structure them for maximum benefit.
This strategic approach not only preserves wealth but also reduces tax burdens for your loved ones, allowing your family to retain more of what you’ve worked hard to build. Remember, you’re not alone in this journey; we’re here for you, ready to help you make informed decisions that align with your family values.
Estate Planning Benefits: Leveraging Step-Up in Basis for Family Wealth
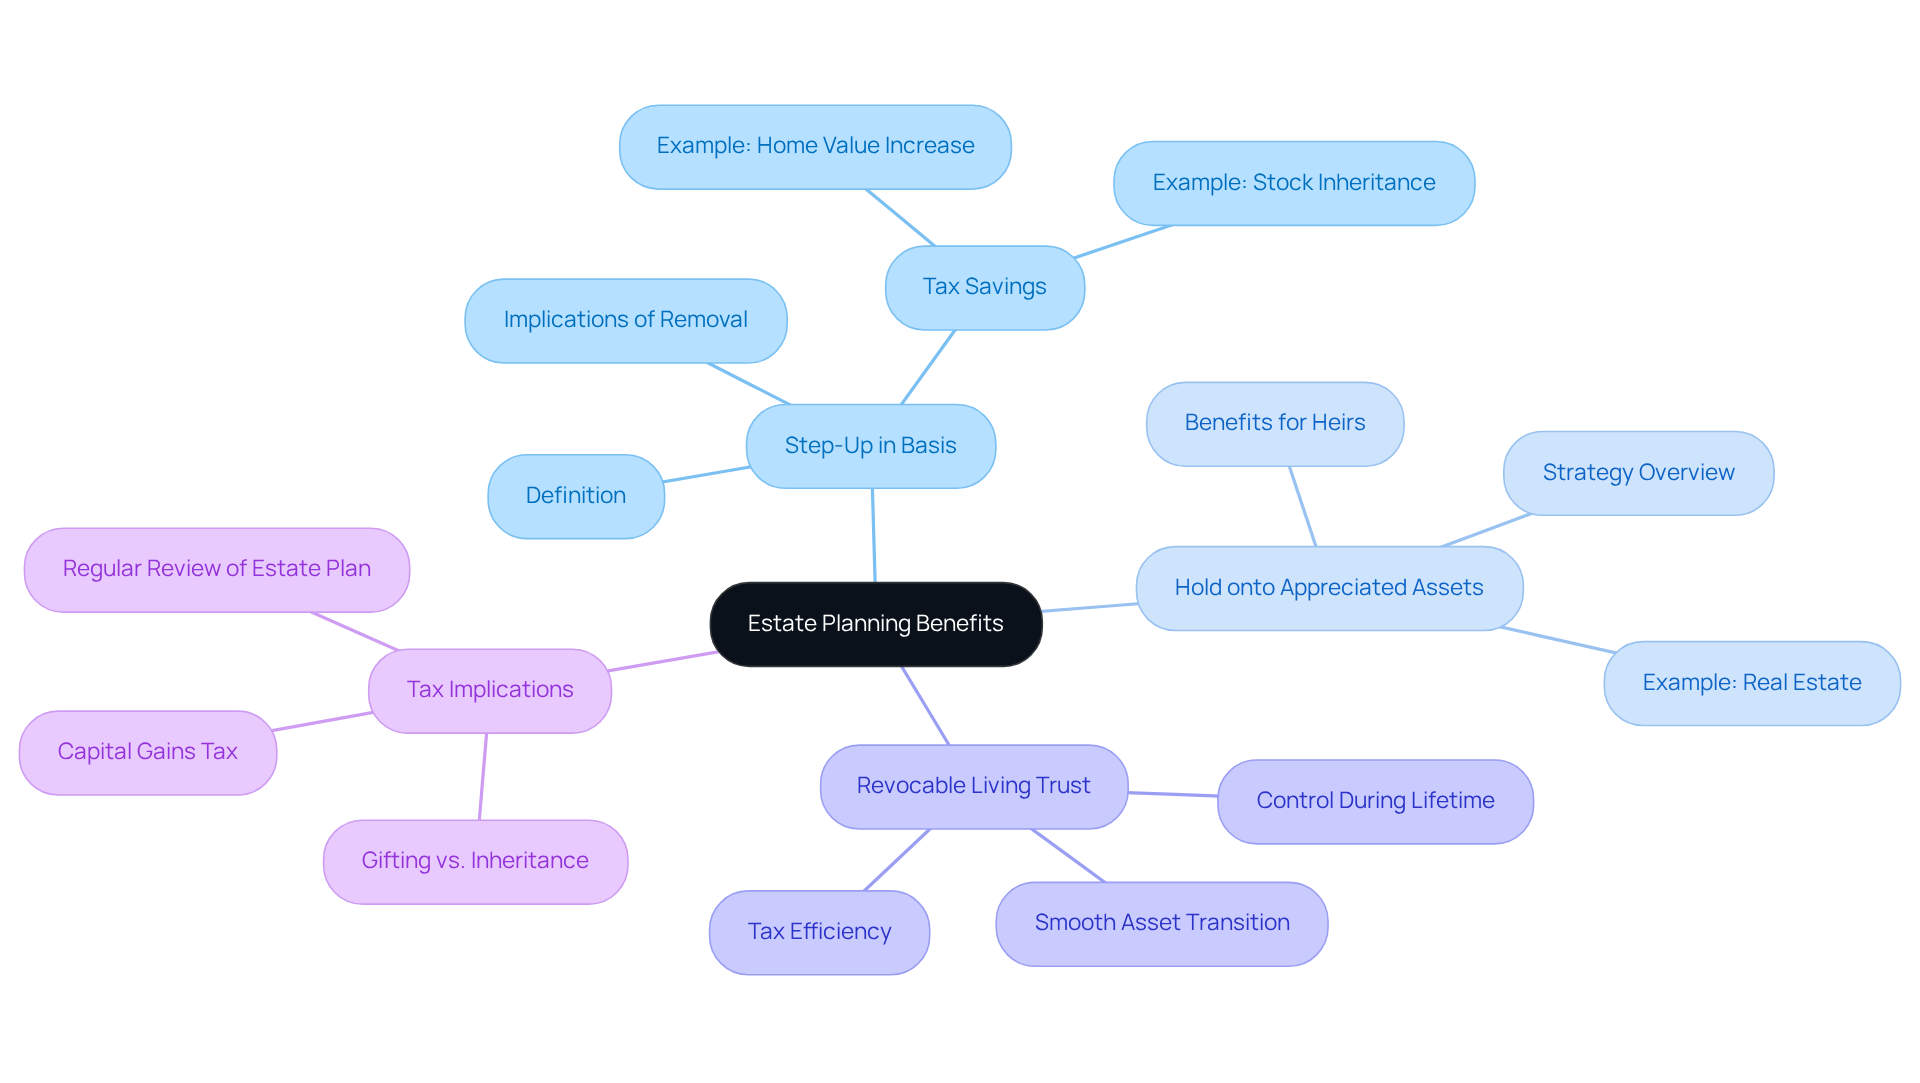
Understanding the increase in value can truly transform your estate planning journey, especially for families eager to preserve their wealth for future generations. Imagine being able to pass on your hard-earned assets without burdening your loved ones with hefty tax bills. This provision allows inherited assets to be valued at their fair market price at the time of your passing, significantly reducing capital gains tax liabilities for your heirs. By thoughtfully structuring your estate, you can ensure your children are not weighed down by excessive tax burdens.
One effective approach is to hold onto appreciated assets until you pass away. This way, your heirs can inherit them with a step up tax basis. For instance, if you bought a home for $500,000 and it appreciates to $800,000, your heirs can sell it without facing capital gains tax on that $300,000 increase. This strategy not only helps keep wealth within your family but also simplifies the transfer process, allowing your loved ones to benefit from tax advantages without the complications of gifting during your lifetime.
Additionally, consider using a revocable living trust. This can make the transition of assets smoother while you maintain control over them during your lifetime. By placing your assets in a trust, you can ensure that your heirs receive an increased valuation, which allows for a step up tax basis, enhancing tax efficiency and protecting the value of your estate.
It’s crucial to grasp the implications of the increase in value for effective estate planning. Families that proactively weave this strategy into their financial planning can significantly lower the tax liabilities tied to inherited assets, safeguarding their wealth for generations to come. Remember, we’re here for you, ready to help you navigate this important journey together.
State Variations: Understanding Step-Up in Basis in Community vs. Common Law States
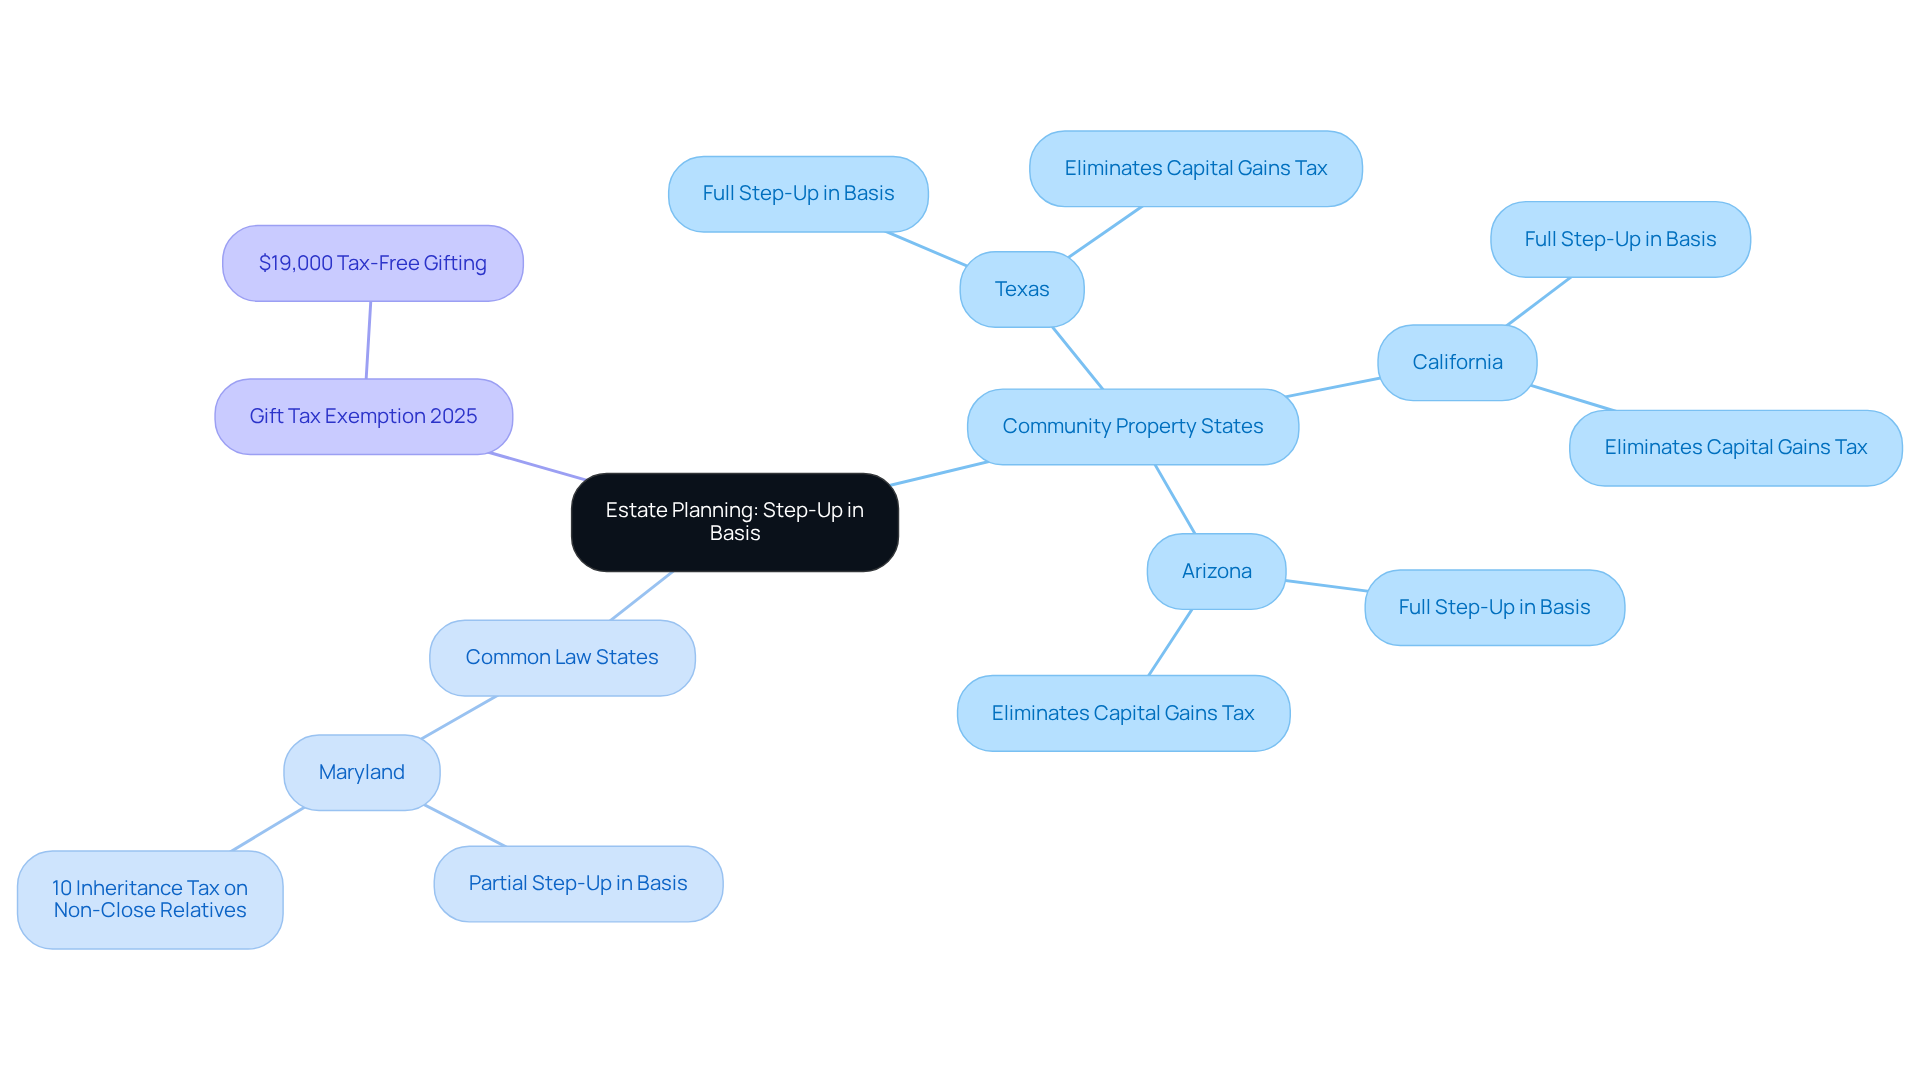
Navigating estate planning can feel overwhelming, especially for young parents. Understanding how the increase in value of assets works in different states is crucial, as it can significantly impact your family’s financial future. In community property states like Texas, California, and Arizona, when one partner passes away, the value of jointly owned assets is reset to their fair market value. This reset can be a blessing, potentially eliminating capital gains tax for the surviving spouse when they sell the asset. Imagine the relief of knowing that your loved ones won’t face hefty taxes during a difficult time.
On the other hand, in common law states, only the deceased spouse’s share of jointly held assets receives a step up tax basis. This means that heirs might face higher capital gains taxes, as they only benefit from a partial adjustment based on the deceased’s ownership percentage. For instance, in Maryland, a 10% inheritance tax applies to transfers to non-close relatives, highlighting the financial implications of estate planning in these areas. It’s important to understand how these laws can affect your family’s legacy.
As you plan for the future, consider the 2025 gift tax exemption of $19,000. This exemption allows for tax-free gifting strategies, which can be a wonderful way to support your children while managing your estate. Together, we can navigate these complexities and ensure your family’s financial well-being.
Remember, understanding these differences is not just about numbers; it’s about securing a brighter future for your children. We’re here for you, ready to help you make informed decisions that align with your family values and goals.
Tax Loopholes: The Controversial Aspects of Step-Up in Basis
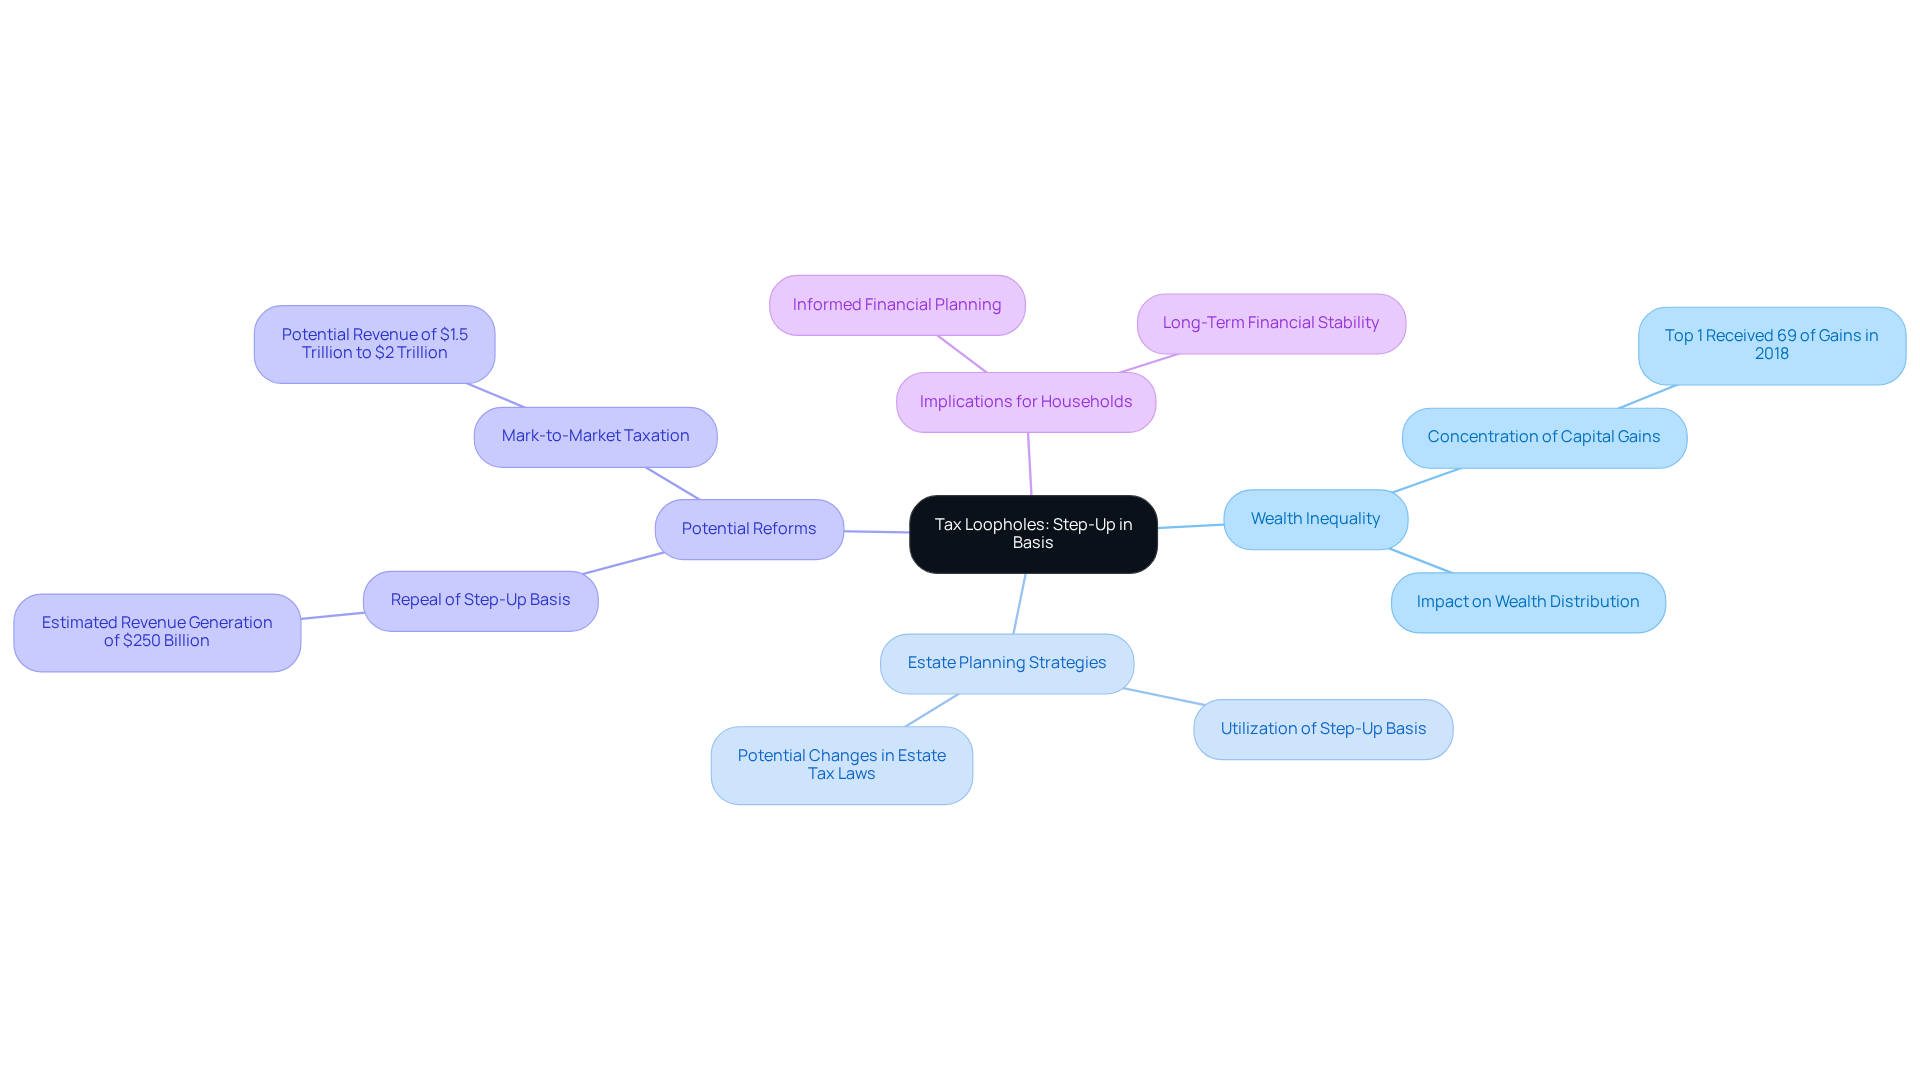
The rise in wealth can often feel like a tax loophole that unfairly benefits the affluent. This provision allows wealthy individuals to pass on significant assets to their heirs by utilizing a step up tax basis, avoiding capital gains taxes on appreciation, which can deepen wealth inequality. For example, in 2018, the top 1% of households received a staggering 69% of taxable long-term capital gains, underscoring the concentration of wealth among the richest.
As discussions around tax reform heat up, it’s essential for parents to stay alert about potential changes to this provision that might impact their estate planning strategies. Families navigating these conversations often face tough decisions about their financial futures. Imagine if suggestions to eliminate the adjustment in value were implemented; it could generate an estimated $250 billion over ten years by taxing unrealized profits at the moment of transfer. This shift wouldn’t just affect wealthy estates; it could also tackle the broader issue of wealth inequality.
Understanding the implications of such tax loopholes and how they allow for a step up tax basis empowers households to make informed decisions about their financial planning and legacy. It’s about ensuring a stable future for your children. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s financial well-being.
Debate Overview: Arguments For and Against Step-Up in Basis
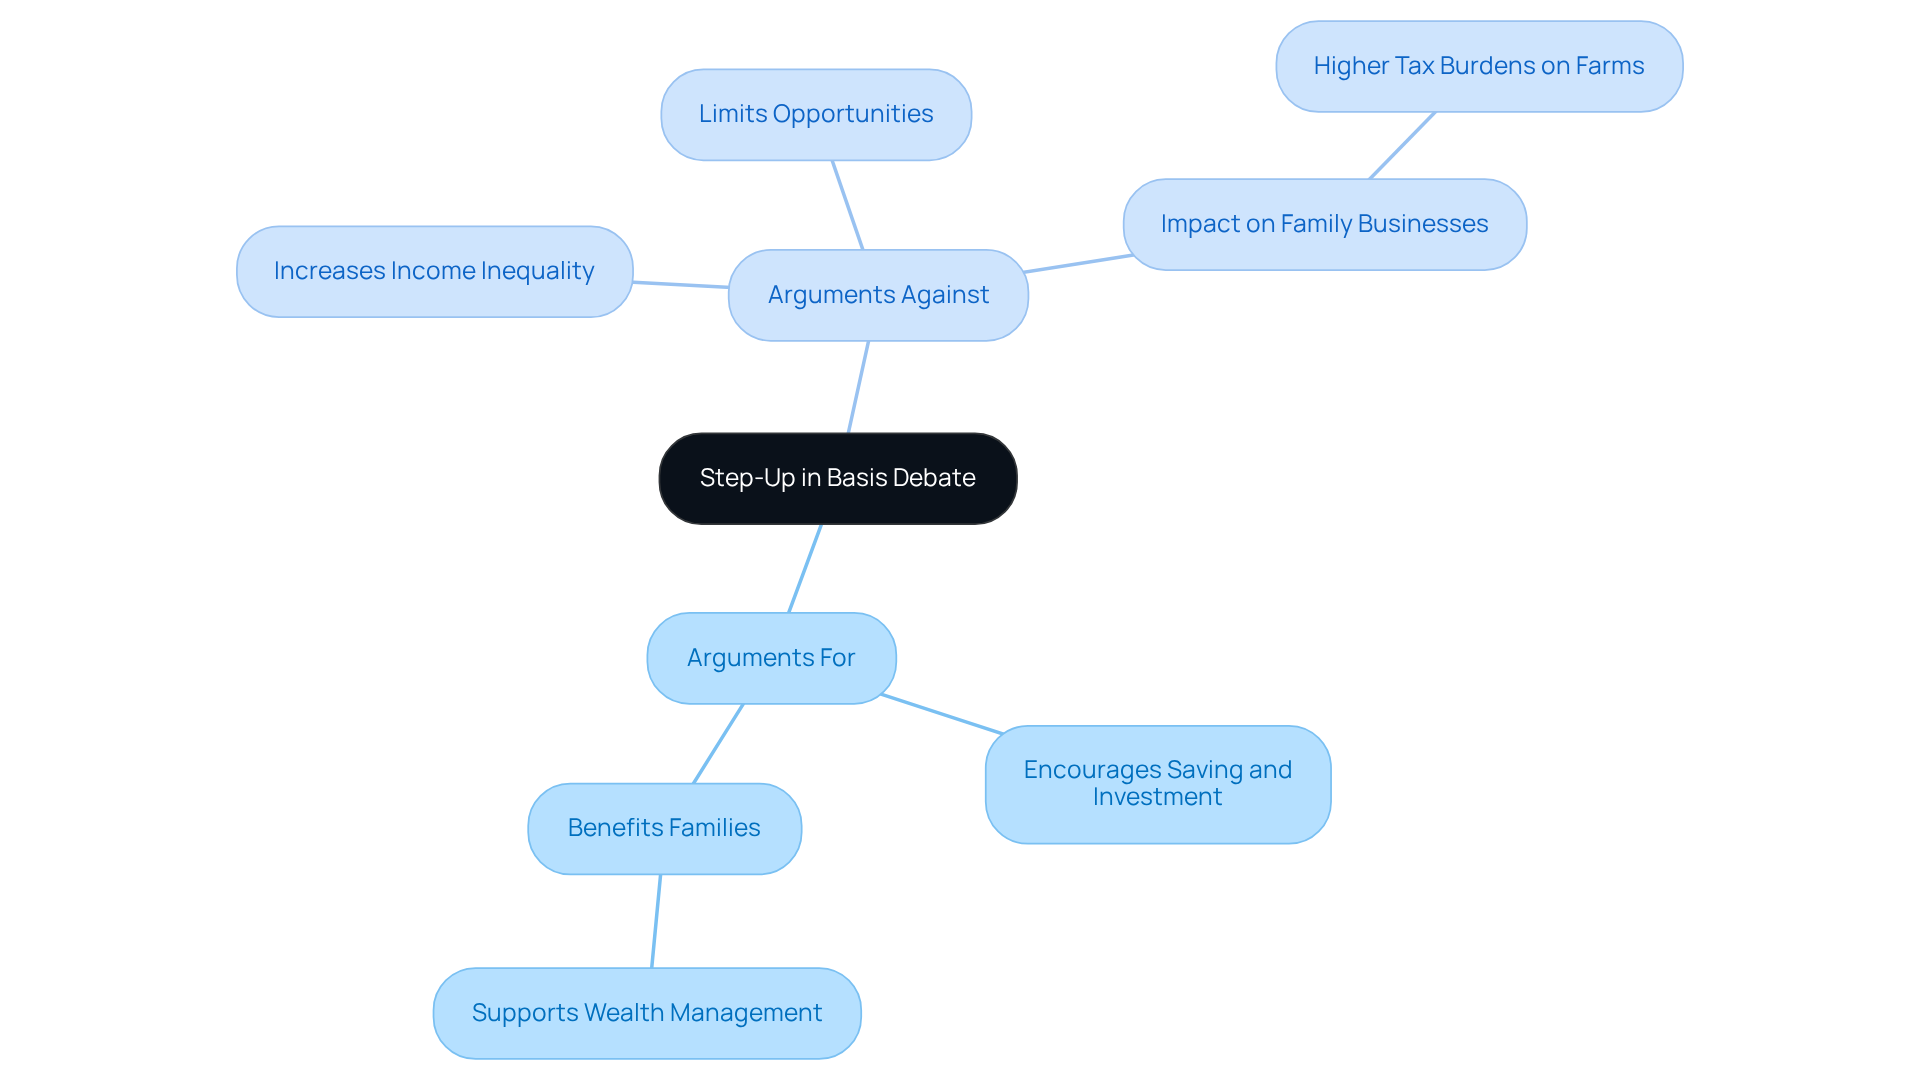
The conversation about how to step up tax basis touches on important issues of fairness and wealth distribution. Many believe this provision encourages saving and investment, allowing families to step up tax basis and pass on their wealth without facing hefty tax bills. This perspective resonates deeply with families who are working hard to secure their financial future while raising children, aligning perfectly with Bright Advisers’ commitment to innovative wealth management tailored for young families.
However, there’s another side to consider. Critics argue that this increase in valuation primarily benefits wealthier households, exacerbating income inequality and limiting opportunities for those with lower incomes. Public sentiment is shifting, with many people expressing concern over how wealth is distributed, advocating for reforms that could lead to a fairer tax system.
Imagine if two-thirds of mid-sized farms faced higher tax burdens if the valuation adjustment were removed. This scenario highlights the potential impact on family-run businesses that often play a crucial role in local economies. As families navigate these complexities, it’s vital to think about how ongoing political discussions might shape the future of these valuation increases.
Engaging with estate planning professionals, like those at Bright Advisers, can offer valuable insights into how these changes could affect your family’s financial situation and the broader implications for generational wealth. Together, we can explore proactive estate planning strategies, such as using tax-advantaged accounts or leveraging trust structures, to help ease potential tax burdens and ensure a smoother transfer of wealth.
We’re here for you, ready to support you in navigating these challenges. By taking action now, you can secure a brighter financial future for your family.
Wealth Disparities: How Step-Up in Basis Benefits Affluent Families
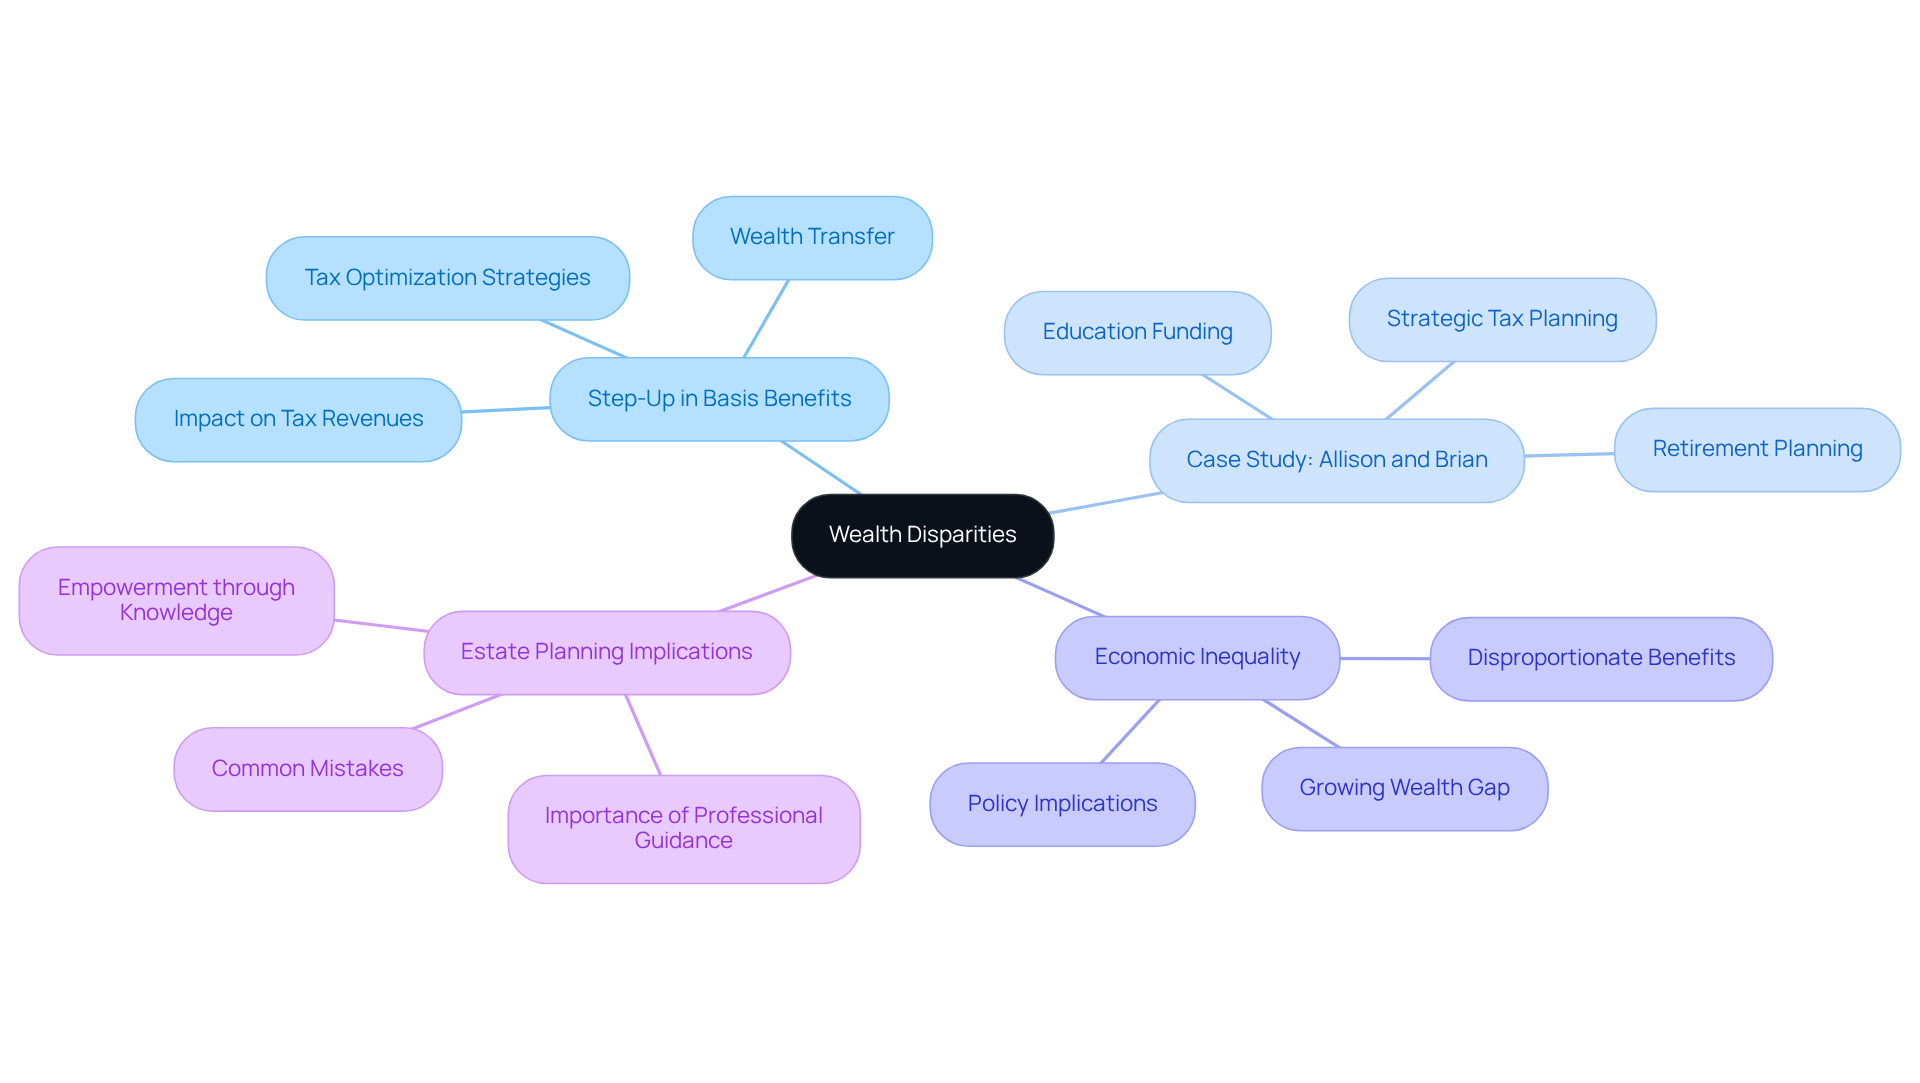
The increase in valuation provision greatly benefits wealthy households, allowing them to transfer considerable assets to their descendants while evading capital gains levies. This mechanism enables wealth transfer and sustains a cycle of wealth accumulation that can be difficult for lower-income households to escape.
Imagine inheriting a property valued at $500,000. The basis resets to this market value, which allows you to step up tax basis and sell it without incurring taxes on the appreciation that occurred during the prior owner’s lifetime. In contrast, households lacking such advantages may struggle to build and maintain wealth across generations.
A compelling case study is that of Allison and Brian. As highly compensated professionals, they initially faced challenges due to inadequate tax planning. Through their collaboration with Bright Advisers, they optimized their tax situation by implementing strategic tax strategies, secured their children’s future through education funding, and gained the ability to retire sooner. Their journey illustrates how strategic tax planning can empower families to navigate the complexities of wealth transfer effectively, providing peace of mind and allowing them to enjoy more quality time with their loved ones.
Financial analysts highlight that this tax benefit disproportionately aids wealthier families, contributing to growing economic inequality. The Congressional Budget Office estimates that the adjustment provision could lead to a loss of $58 billion in tax revenues in 2024, underscoring its effect on public finances and wealth distribution.
As young parents navigate their estate planning, it’s important to recognize these disparities. Understanding the implications of wealth transfer can empower you to make informed decisions that align with your financial goals and legacy aspirations. Together, we can navigate this journey, ensuring a brighter future for your family.
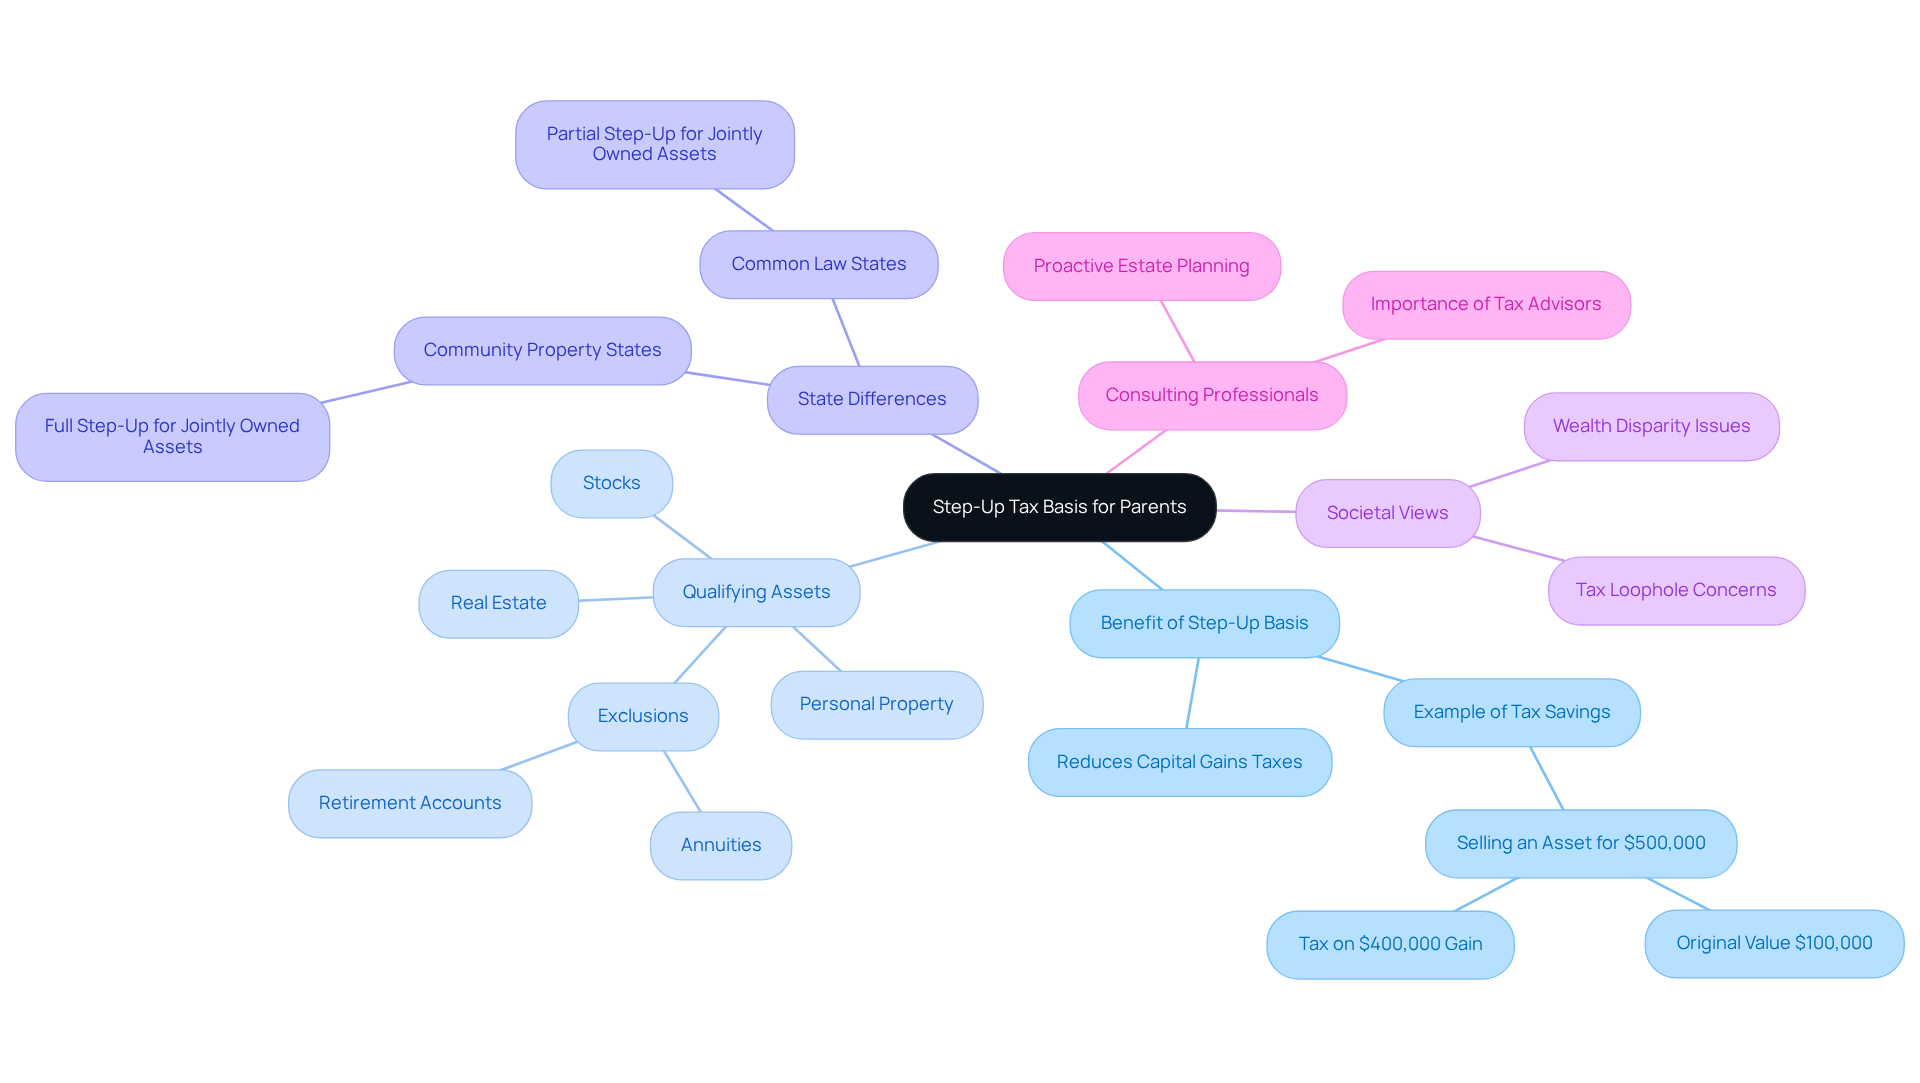
Key Takeaways: Essential Facts About Step-Up Tax Basis for Parents
-
Imagine the relief of knowing that inherited assets can benefit from a step up tax basis, adjusting their value to the fair market worth at the time of death. This adjustment can significantly step up tax basis, which can reduce capital gains taxes for beneficiaries. For example, if heirs sell an asset for $500,000 that was initially valued at $100,000, they might face taxes on $400,000 in profits.
-
However, not all assets qualify for this increase in value. It’s important for parents to identify which of their assets—like real estate, stocks, and personal property—can benefit from this adjustment.
-
Understanding the differences between states is crucial. In community property states, jointly owned assets receive a complete increase in value, while common law states only offer a partial adjustment. This distinction can greatly influence your estate planning strategies.
-
Some view the increase in valuation as a tax loophole that primarily benefits wealthy families, raising concerns about wealth disparity and potential tax reforms. As one tax expert noted, “The adjustment in cost is a valuable tax provision that allows inherited assets to be assessed at their fair market value at the time of the former owner’s passing.”
-
Staying informed about potential changes in tax laws is vital for parents. Consulting with a tax professional can help you understand how the step-up tax basis applies to your unique situation, ensuring you’re prepared for any shifts that may impact your financial legacy. Remember, we’re here for you as you navigate this journey.
Conclusion
Understanding the step-up tax basis is crucial for young parents who want to secure their family’s financial future. This provision allows inherited assets to be valued at their fair market value at the time of the original owner’s passing, which can significantly reduce potential capital gains taxes for heirs. By grasping this concept, families can navigate estate planning more strategically, ensuring they maximize the benefits of wealth transfer while minimizing tax burdens.
Imagine knowing which assets qualify for this tax adjustment. It’s essential to understand the differences in state laws that can affect these benefits and the broader implications of wealth disparities created by this provision. With the potential for tax reforms on the horizon, staying informed and proactive in financial planning becomes even more important. Engaging with financial professionals can provide clarity and tailored strategies to protect your family’s legacy.
Ultimately, understanding the intricacies of the step-up tax basis goes beyond just tax savings; it’s about empowering families to build a stable financial foundation for future generations. As young parents navigate these complexities, prioritizing informed decision-making and seeking personalized financial guidance can ensure a brighter, more secure future for their children. We’re here for you, ready to support you on this journey.
Frequently Asked Questions
What is the step-up tax basis?
The step-up tax basis is a tax provision that adjusts the value of inherited assets to their fair market value at the time of the owner’s passing, allowing heirs to avoid capital gains taxes on any appreciation that occurred during the original owner’s lifetime.
How does the step-up tax basis benefit heirs?
Heirs benefit from the step-up tax basis because it means they will only incur capital gains tax on any appreciation that occurs after they inherit the asset, not on the gains made during the original owner’s lifetime.
Can you provide an example of how the step-up tax basis works?
For instance, if a family home was purchased for $500,000 and is worth $800,000 at the time of inheritance, the heirs receive a step-up tax basis of $800,000. This allows them to avoid taxes on the $300,000 gain that occurred during the original owner’s life.
Why is understanding the step-up tax basis important for families?
Understanding the step-up tax basis is crucial for families as it can significantly reduce tax obligations, enhance financial well-being, and help preserve wealth across generations.
What role does Bright Advisers play in financial planning related to the step-up tax basis?
Bright Advisers provides personalized financial planning and guidance to help families navigate complex tax regulations, ensuring they can make informed decisions to secure their financial future.
How can the step-up tax basis influence estate planning?
The step-up tax basis can profoundly impact estate planning by enabling families to pass on assets without incurring hefty taxes, thus enhancing the financial advantages for heirs and contributing to a more secure financial legacy.
What should families do to navigate the complexities of the step-up tax basis?
Families are encouraged to consult with a tax advisor or financial professional, such as those at Bright Advisers, to effectively understand and utilize the step-up tax basis in their financial planning.
What is the estimated impact of the step-up tax basis on federal revenues?
The Joint Committee on Taxation estimates that the step-up tax basis will account for $58 billion in lost federal revenues in 2024, highlighting its significance in wealth transfer and tax strategies.
List of Sources
- Bright Advisers: Personalized Financial Planning for Understanding Step-Up Tax Basis
- Stepped-Up Basis: How It Affects Inherited Assets (https://randacpas.com/stepped-up-basis-how-it-affects-inherited-assets)
- Maximizing Tax Benefits with the Stepped-Up Basis in Estate Planning (https://llklaw.com/legal-blog/understanding-the-stepped-up-tax-basis-and-how-estate-planning-can-maximize-its-benefits)
- What the End of Step-Up in Basis Could Mean for Your Heirs | Avidian Wealth Solutions (https://avidianwealth.com/financial-insights/articles/end-of-step-up-in-basis-meaning-for-heirs)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- “Step-Up in Basis” for Inherited Assets Explained (https://sdmayer.com/resources/step-up-in-basis)
- Step-Up in Basis Defined: What Every Parent Needs to Know
- Estate Planning: Stepped-Up Tax Basis | Center for Agricultural Profitability | Nebraska (https://cap.unl.edu/news/estate-planning-stepped-tax-basis)
- Step Up in Basis — What You Need to Know | White Coat Investor (https://whitecoatinvestor.com/step-up-in-basis-what-you-need-to-know)
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Impact on Capital Gains: How Step-Up in Basis Influences Tax Obligations
- Capital Gains on Inherited Property (https://smartasset.com/taxes/capital-gains-on-inherited-property)
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- What Is Stepped-Up Basis on Capital Gains and How Does It Affect the Federal Budget? (https://pgpf.org/article/what-is-the-stepped-up-basis-and-how-does-it-affect-the-federal-budget)
- Step-Up in Basis: A Powerful Estate Planning Tool (https://brinkersimpson.com/blog/step-up-in-basis-a-powerful-estate-planning-tool)
- Qualifying Assets: What Parents Should Know About Step-Up in Basis
- Maximizing Tax Benefits with the Stepped-Up Basis in Estate Planning (https://llklaw.com/legal-blog/understanding-the-stepped-up-tax-basis-and-how-estate-planning-can-maximize-its-benefits)
- “Step-Up in Basis” for Inherited Assets Explained (https://sdmayer.com/resources/step-up-in-basis)
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Estate Planning Benefits: Leveraging Step-Up in Basis for Family Wealth
- Maximizing Tax Benefits with the Stepped-Up Basis in Estate Planning (https://llklaw.com/legal-blog/understanding-the-stepped-up-tax-basis-and-how-estate-planning-can-maximize-its-benefits)
- What the End of Step-Up in Basis Could Mean for Your Heirs | Avidian Wealth Solutions (https://avidianwealth.com/financial-insights/articles/end-of-step-up-in-basis-meaning-for-heirs)
- Estate Planning Essentials: The Impact of Step-Up in Basis on Your Legacy (https://libertygroupllc.com/blog/estate-planning-essentials-the-impact-of-step-up-in-basis-on-your-legacy)
- Estate Planning: Stepped-Up Tax Basis | Center for Agricultural Profitability | Nebraska (https://cap.unl.edu/news/estate-planning-stepped-tax-basis)
- 12 Inspirational Quotes About Estate Planning – Leigh Hilton (https://dentonestateplanninglawyer.com/12-inspirational-quotes-about-estate-planning)
- State Variations: Understanding Step-Up in Basis in Community vs. Common Law States
- The Intersection of State Lines and Estate Lines: Considerations for Married Couples Traversing Separate Property and Community Property States – Spencer Fane (https://spencerfane.com/insight/the-intersection-of-state-lines-and-estate-lines-considerations-for-married-couples-traversing-separate-property-and-community-property-states)
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Stepped-Up Basis Loophole: What It Is & Why It Matters (https://districtcapitalmanagement.com/stepped-up-basis)
- Community Property: Cost Basis Implications | RGWM Insights (https://rgwealth.com/insights/community-property-cost-basis)
- Tax Loopholes: The Controversial Aspects of Step-Up in Basis
- Case Studies | RCLCO Real Estate Consulting (https://rclco2024.lvdev.net/resources/case_studies)
- Substantial Income of Wealthy Households Escapes Annual Taxation Or Enjoys Special Tax Breaks (https://cbpp.org/research/federal-tax/substantial-income-of-wealthy-households-escapes-annual-taxation-or-enjoys)
- Debate Overview: Arguments For and Against Step-Up in Basis
- What The Potential Elimination Of Step-Up In Basis Means (https://forbes.com/councils/forbesfinancecouncil/2025/03/21/estate-planning-what-the-potential-elimination-of-step-up-in-basis-means-for-families)
- EXCLUSIVE: Costa pitches bill to protect inheritance by preserving stepped-up basis (https://costa.house.gov/media/exclusive-stories/exclusive-costa-pitches-bill-protect-inheritance-preserving-stepped-basis)
- Wealth Disparities: How Step-Up in Basis Benefits Affluent Families
- How the Government Subsidizes Wealth Inequality (https://americanprogress.org/article/how-the-government-subsidizes-wealth-inequality)
- Step Up in Basis at Death: Essential Guide for Inherited Assets (https://masseyandcompanycpa.com/step-up-in-basis-at-death-essential-guide-for-inherited-assets)
- The Big Beautiful Bill and its big opportunity for wealthy families | Retire on Track (https://heraldtribune.com/story/business/2025/08/11/the-big-beautiful-bill-and-its-big-opportunity-for-wealthy-families/85402413007)
- Understanding Step-Up Basis Tax: A Guide for Young Parents – Bright Advisers (https://brightadvisers.com/understanding-step-up-basis-tax-a-guide-for-young-parents)
- Key Takeaways: Essential Facts About Step-Up Tax Basis for Parents
- What is step-in basis and how can it affect me?| Fidelity (https://fidelity.com/learning-center/personal-finance/what-is-step-up-in-basis)
- Step-Up in Basis: Definition and How It Works for Inherited Property (https://investopedia.com/terms/s/stepupinbasis.asp)
- What the End of Step-Up in Basis Could Mean for Your Heirs | Avidian Wealth Solutions (https://avidianwealth.com/financial-insights/articles/end-of-step-up-in-basis-meaning-for-heirs)
- Step-Up in Basis and Why It Matters in Estate Planning | Shepherd Elder Law (https://shepherdelderlaw.com/step-up-in-basis-and-why-it-matters-in-estate-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading