

Key Highlights:
- Bright Advisers offers personalised financial planning for families managing inherited 401(k) accounts.
- Key regulations include the 10-year withdrawal rule for non-spouse beneficiaries, requiring full account depletion within ten years.
- Tax implications are significant; distributions are taxed as regular income, which can elevate tax burdens.
- Strategic options for beneficiaries include taking lump-sum distributions, rolling over to a beneficiary IRA, or staggered withdrawals to manage tax liabilities.
- The SECURE Act of 2019 eliminated the ‘stretch’ provision, impacting tax planning and financial strategies for families.
- Required Minimum Distributions (RMDs) will be mandated for certain non-spouse beneficiaries starting in 2025, based on life expectancy or the 10-year rule.
- Inherited IRAs generally offer more flexible withdrawal options compared to inherited 401(k) accounts.
- Understanding creditor protection for inherited 401(k) accounts is essential, as protections vary by state.
- Proactive estate planning is encouraged to safeguard inherited assets and enhance financial security.
- Consulting with financial advisors is crucial for navigating the complexities of inherited 401(k) rules effectively.
Introduction
Navigating the maze of inherited 401(k) rules can feel overwhelming, especially for young parents juggling countless financial responsibilities. It’s crucial to grasp these essential regulations – not just to secure your family’s financial future, but to empower yourself to make informed decisions that align with your long-term goals.
With recent changes from the SECURE Act, including the significant 10-year withdrawal rule, the stakes are higher than ever. Imagine if you could manage these inherited assets effectively, minimizing tax burdens while ensuring your children’s financial security.
Understanding these rules can be your first step toward peace of mind. Picture a future where you’re not just surviving but thriving, making choices that benefit your family for years to come. We’re here for you, ready to help you navigate this journey together.
Let’s explore how you can take control of your financial landscape, ensuring that your family’s values and goals are at the forefront of your planning. Together, we can turn these challenges into opportunities for growth and security.
Bright Advisers: Personalized Financial Planning for Inherited 401(k) Management
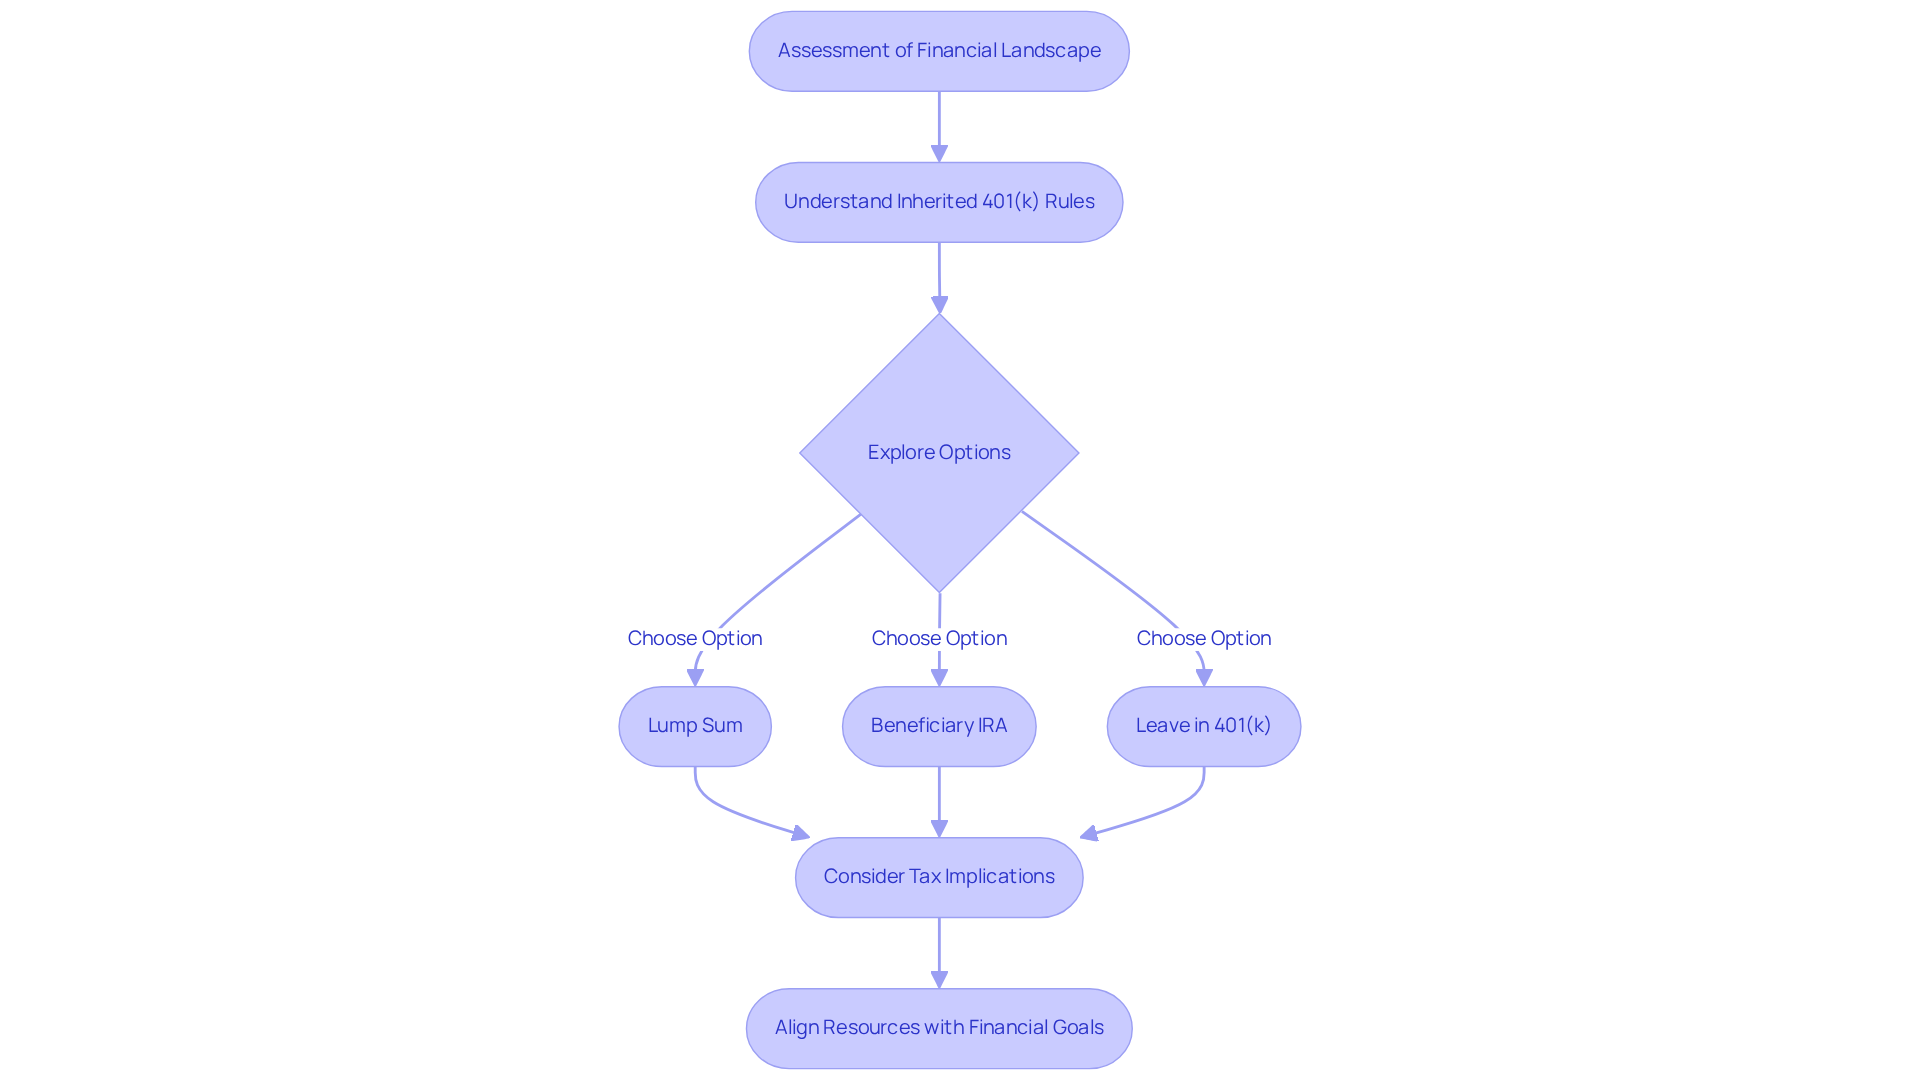
At Bright Advisers, we understand that managing 401(k) plans can feel overwhelming, especially for families with young children. That’s why we take a unique approach, focusing on customized planning that truly reflects your family’s specific needs. We start with a thorough assessment of your financial landscape, looking at both your current obligations and your future dreams. By understanding your long-term goals, we can create tailored strategies that resonate with your family’s values and priorities.
Imagine navigating the complexities of inherited 401k rules when dealing with inherited accounts. It can be daunting, especially for non-spousal beneficiaries who must follow the inherited 401k rules, such as depleting the account within ten years. With our expert guidance, you can explore your options – whether it’s taking a lump sum, transferring to a beneficiary IRA, or leaving the funds in the 401(k) – all while considering the tax implications of each choice.
Our wealth consultants emphasize the importance of aligning your resources with your broader financial objectives, such as saving for your children’s education or building a secure retirement. This personalized approach not only empowers families to make informed decisions but also fosters a sense of confidence in managing their financial future. By prioritizing education funding, tax optimization, and legacy planning, we ensure that your family can effectively weave your wealth into a sustainable financial strategy, enhancing your long-term security and peace of mind.
Together, we can navigate this journey. We’re here for you, ready to support you every step of the way.
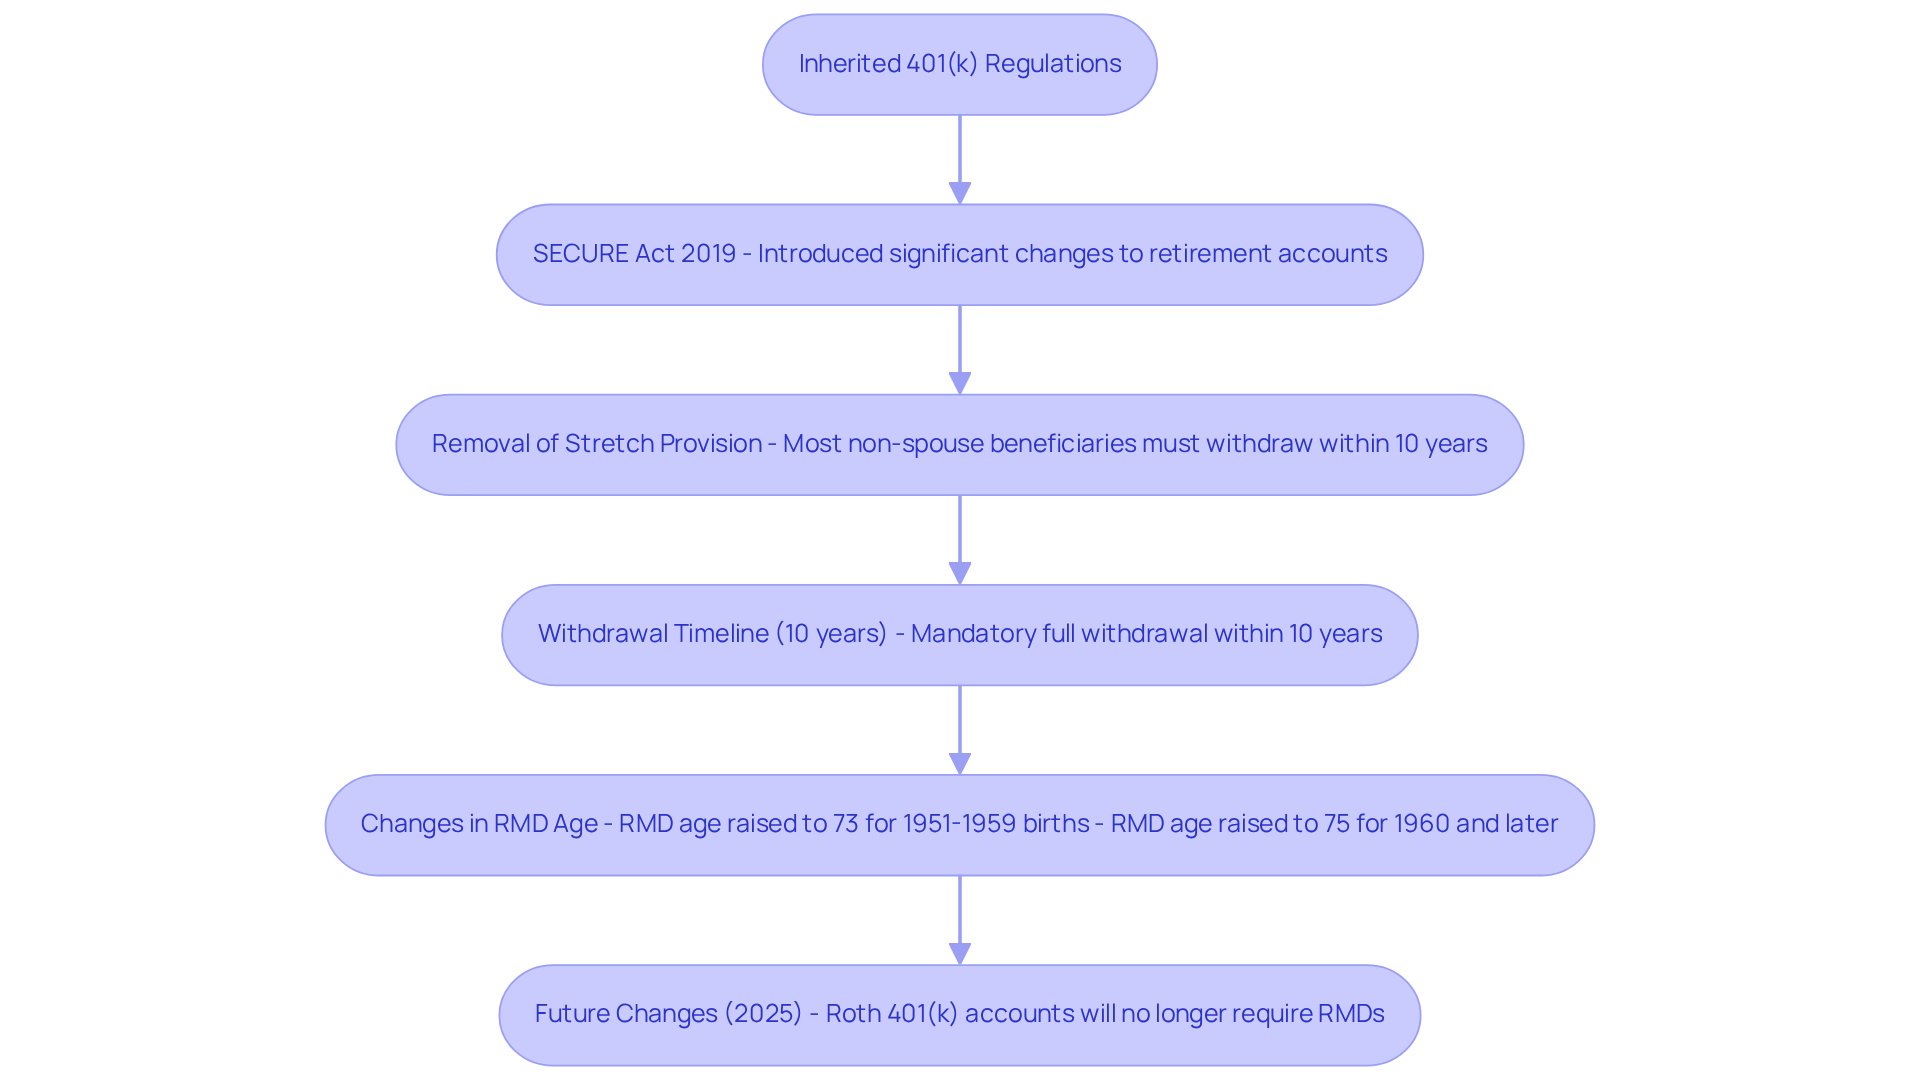
Evolution of Inherited 401(k) Regulations: Key Changes Over Time
Navigating the world of inherited 401k rules can feel overwhelming, especially for young parents. With the SECURE Act of 2019, significant changes have taken place, including the elimination of the ‘stretch’ provision for most non-spouse beneficiaries. This means that many will need to withdraw the full balance within 10 years after the owner’s passing. Such changes can have a big impact on tax planning and financial strategies, particularly for families who may receive these funds.
Looking ahead to 2025, more adjustments are on the horizon. The removal of Required Minimum Distributions (RMDs) for Roth 401(k) plans will allow for indefinite tax-free growth, which is a wonderful opportunity for families. Additionally, the SECURE Act 2.0 raises the RMD age for traditional retirement accounts to 73 for those born between 1951 and 1959, and to 75 for anyone born in 1960 or later. These changes highlight the importance of proactive estate planning, as beneficiaries will need to navigate withdrawal timelines and tax implications.
At Bright Advisers, we understand that these complexities can be daunting. Our commitment to minimizing fund fees makes wealth management more accessible, allowing families to focus on what truly matters: their economic security. For example, consider a family that inherited a 401(k) from a grandparent. They had to carefully strategize their withdrawals to minimize tax burdens, opting for staggered distributions to avoid moving into a higher tax bracket. By offering tailored wealth management options, we empower young parents to create personalized strategies that address both the immediate effects of inherited accounts and their overall financial well-being. This includes effective tax planning and educational readiness, ensuring families can secure their future while managing today’s challenges.
Experts agree that consulting with advisors is crucial to understanding the nuances of these regulations and crafting strategies that align with personal financial goals. The evolution of inherited 401k rules underscores the need for young parents to stay informed and proactive in their financial planning. Together, we can navigate this journey, ensuring that families can effectively manage inherited assets while securing their financial future.
Understanding Key Aspects of Inherited 401(k) Accounts
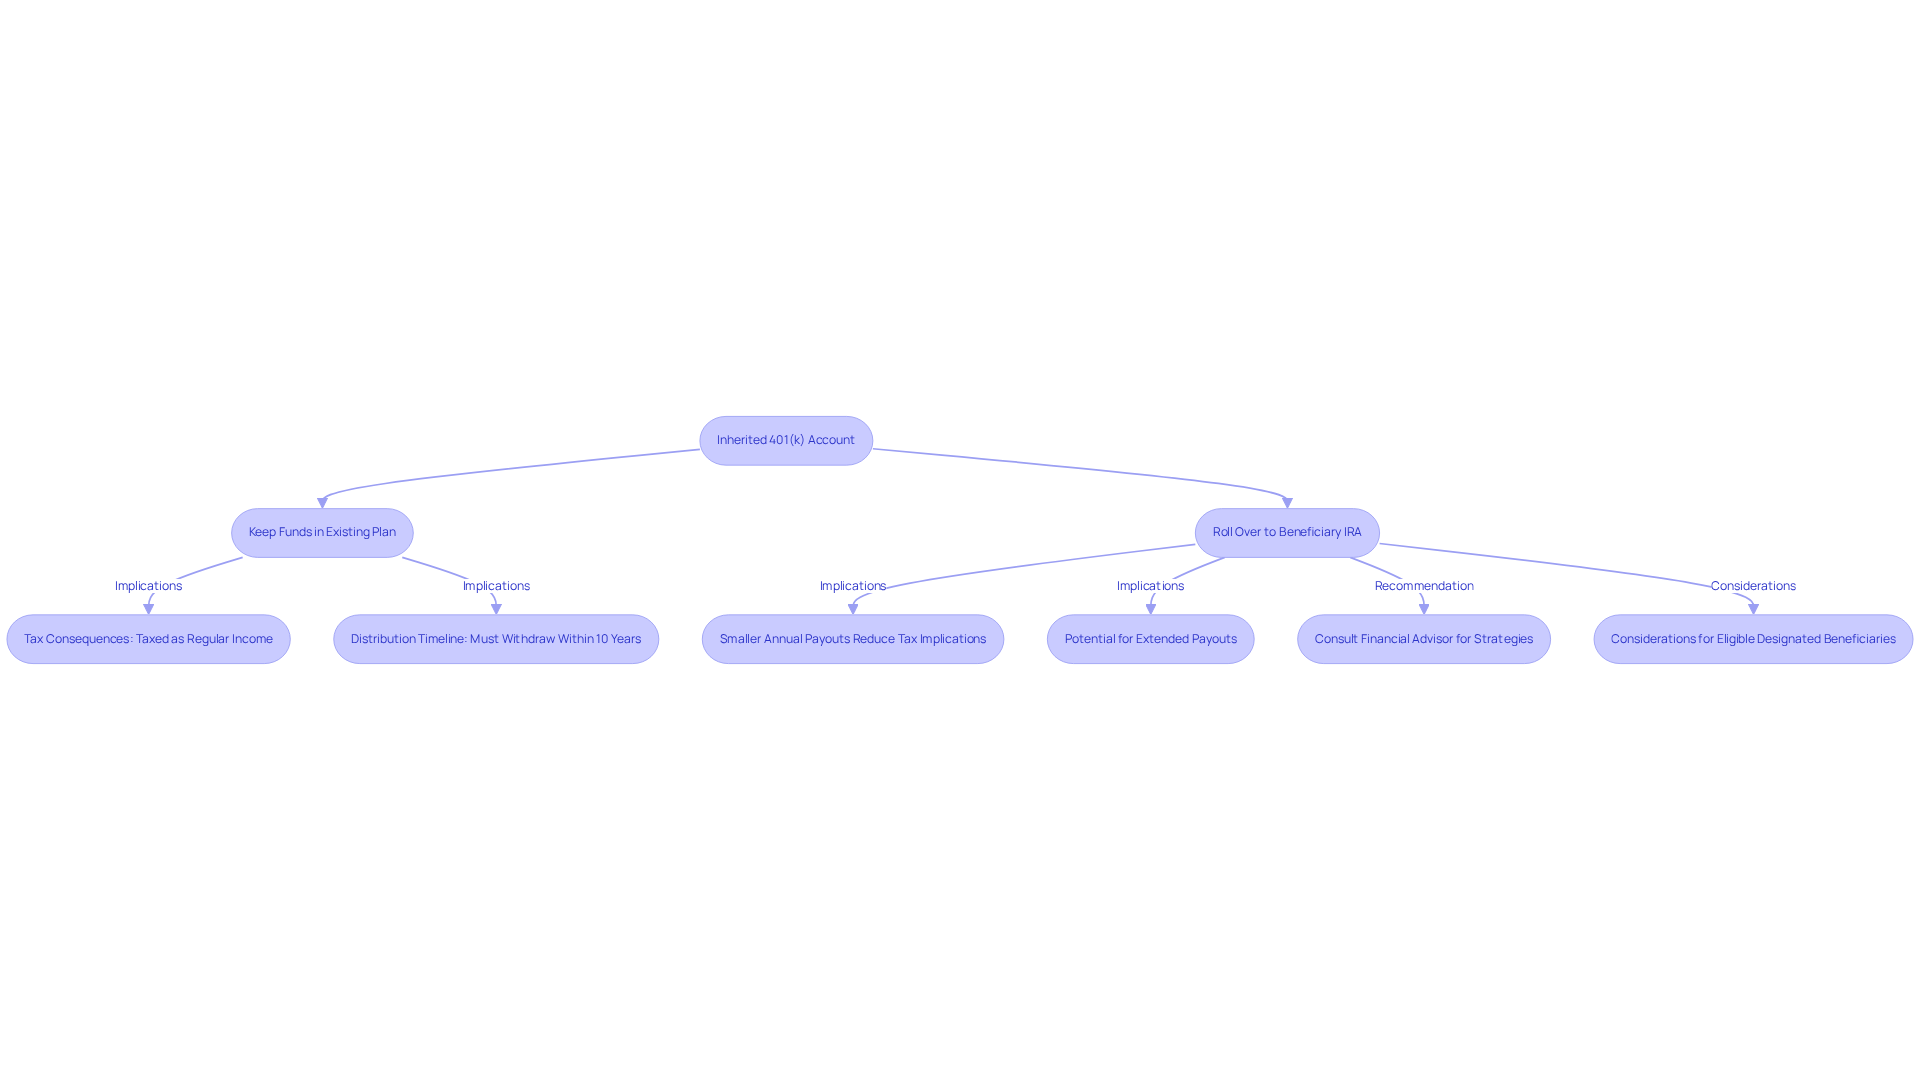
Inherited 401k rules come with unique guidelines that can feel overwhelming, especially for young parents trying to secure their family’s future. It’s essential to know that beneficiaries are required to take distributions according to the inherited 401k rules, which can lead to significant tax implications. According to the inherited 401k rules, starting in 2025, if the original account holder passed away after December 31, 2019, non-spouse beneficiaries must withdraw the entire amount within 10 years. Understanding the inherited 401k rules is crucial, as all payouts are taxed as regular income, which could push you into a higher tax bracket.
When it comes to managing these funds, you have some important choices to make. You can either:
- Keep the funds in the existing plan
- Roll them over into a beneficiary IRA
The latter option might offer different tax advantages, like stretching distributions over a longer period, which can help ease your immediate tax burden. Consulting with a financial advisor can be a game-changer in this process, providing you with personalized strategies to manage your distributions effectively.
Imagine families who have successfully navigated these guidelines; they often stress the importance of early planning and understanding the tax consequences of distributions under inherited 401k rules. Statistics show that beneficiaries who adhere to the inherited 401k rules and spread their distributions over the 10-year period can significantly lessen their overall tax impact. Engaging with a knowledgeable financial advisor can help you align your financial strategies with your family’s long-term goals, ensuring you make informed decisions that benefit your financial future.
We’re here for you as you navigate this journey. Together, we can explore the best options for your family’s financial well-being.
Managing Required Minimum Distributions for Inherited 401(k) Plans
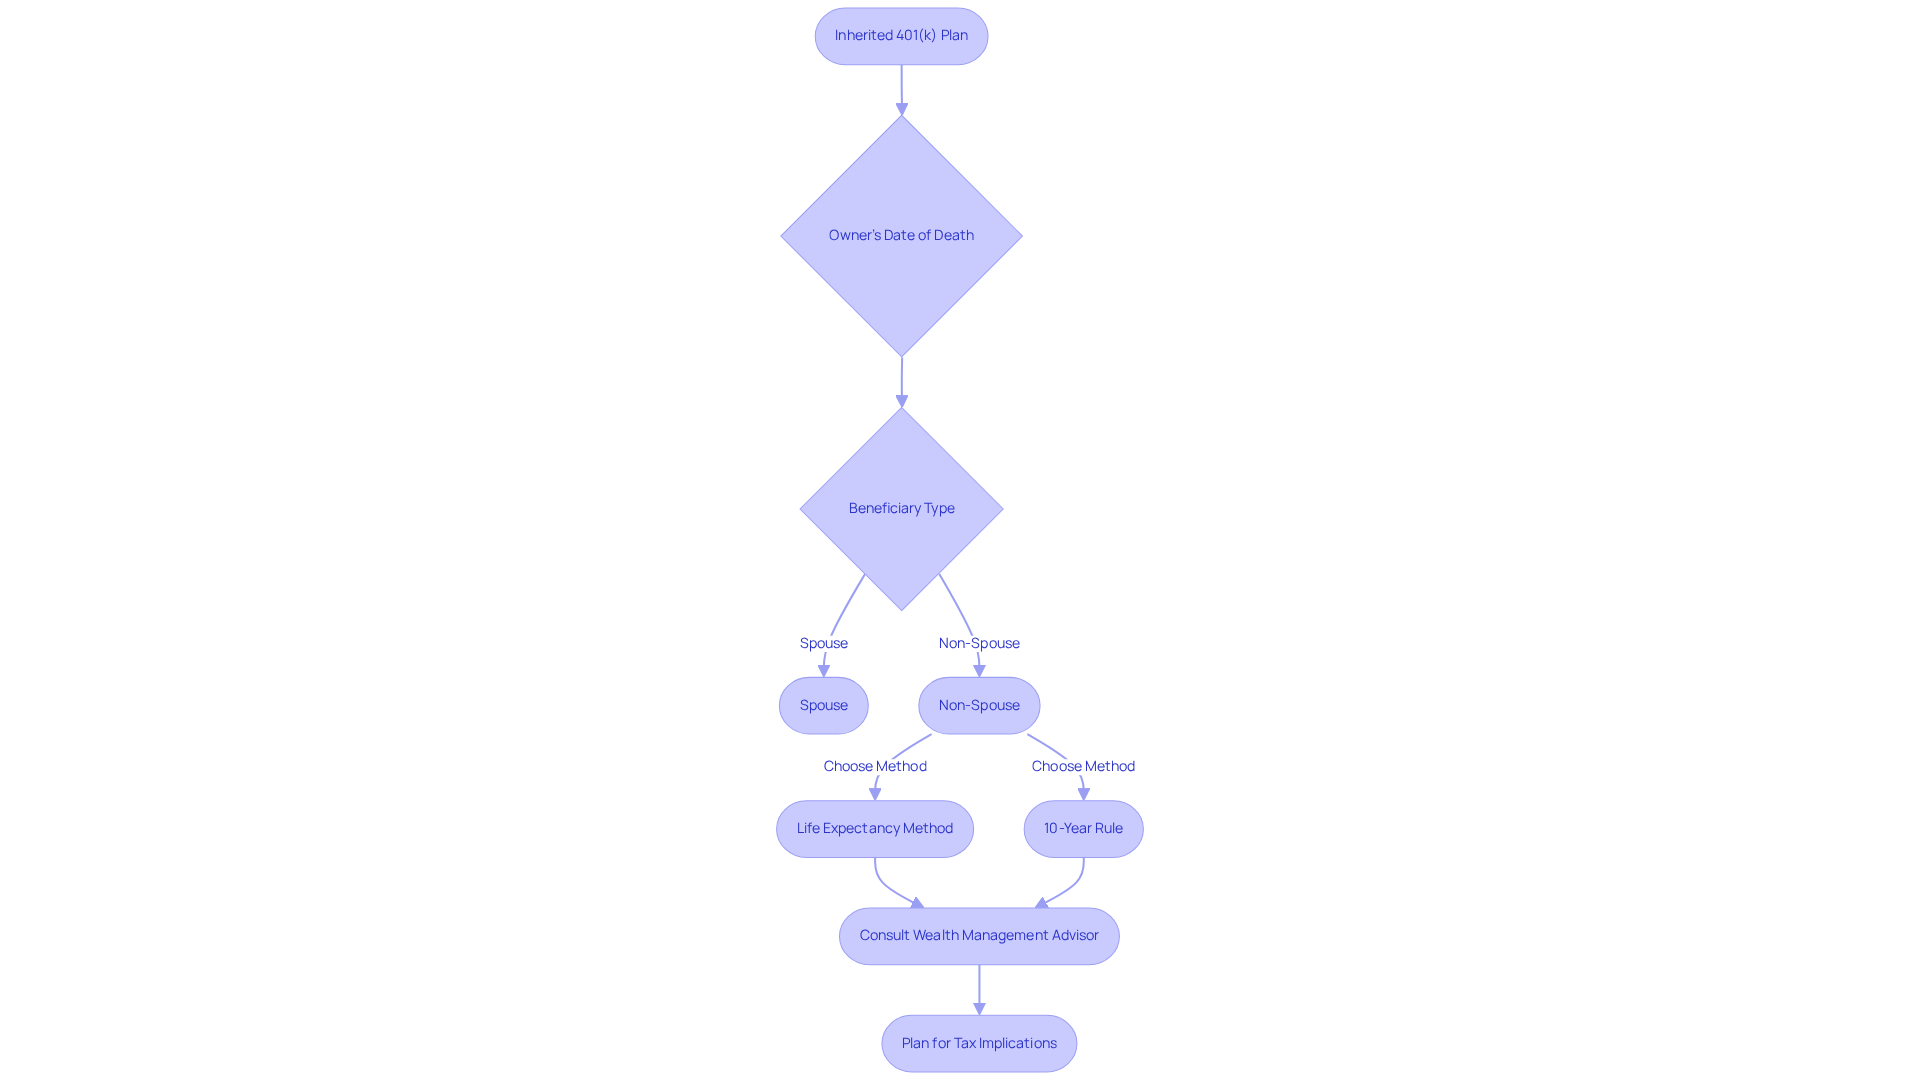
Navigating the complexities of inherited 401k rules can feel overwhelming, especially when it comes to required minimum distributions (RMDs). These distributions are determined by the owner’s date of death, and starting in 2025, certain non-spouse beneficiaries will need to take RMDs annually. This could be based on their life expectancy or under the 10-year rule, depending on the circumstances surrounding the account owner’s passing. For young parents juggling their own financial responsibilities, this change can bring significant tax implications.
Imagine if you could manage these RMDs effectively while minimizing tax liabilities. By considering proactive strategies, you can take control of your financial future. Collaborating with advisors who specialize in wealth management and estate planning can make a world of difference. For instance, an investment advisory team once helped a large business owner navigate the complexities of transitioning substantial wealth tied up in company stock. They not only guided the owner through the intricacies of wealth transition but also prepared the beneficiaries for their future responsibilities, ensuring they felt confident about the economic landscape ahead.
Understanding the impact of RMDs on inherited 401k rules empowers young parents to make informed choices that align with their long-term financial goals. Planning ahead is essential. It ensures you meet RMD requirements while safeguarding your family’s financial future. Remember, you’re not alone in this journey. Together, we can navigate these challenges and secure a brighter tomorrow for your loved ones.
The 10-Year Rule: Implications for Inherited 401(k) Withdrawals
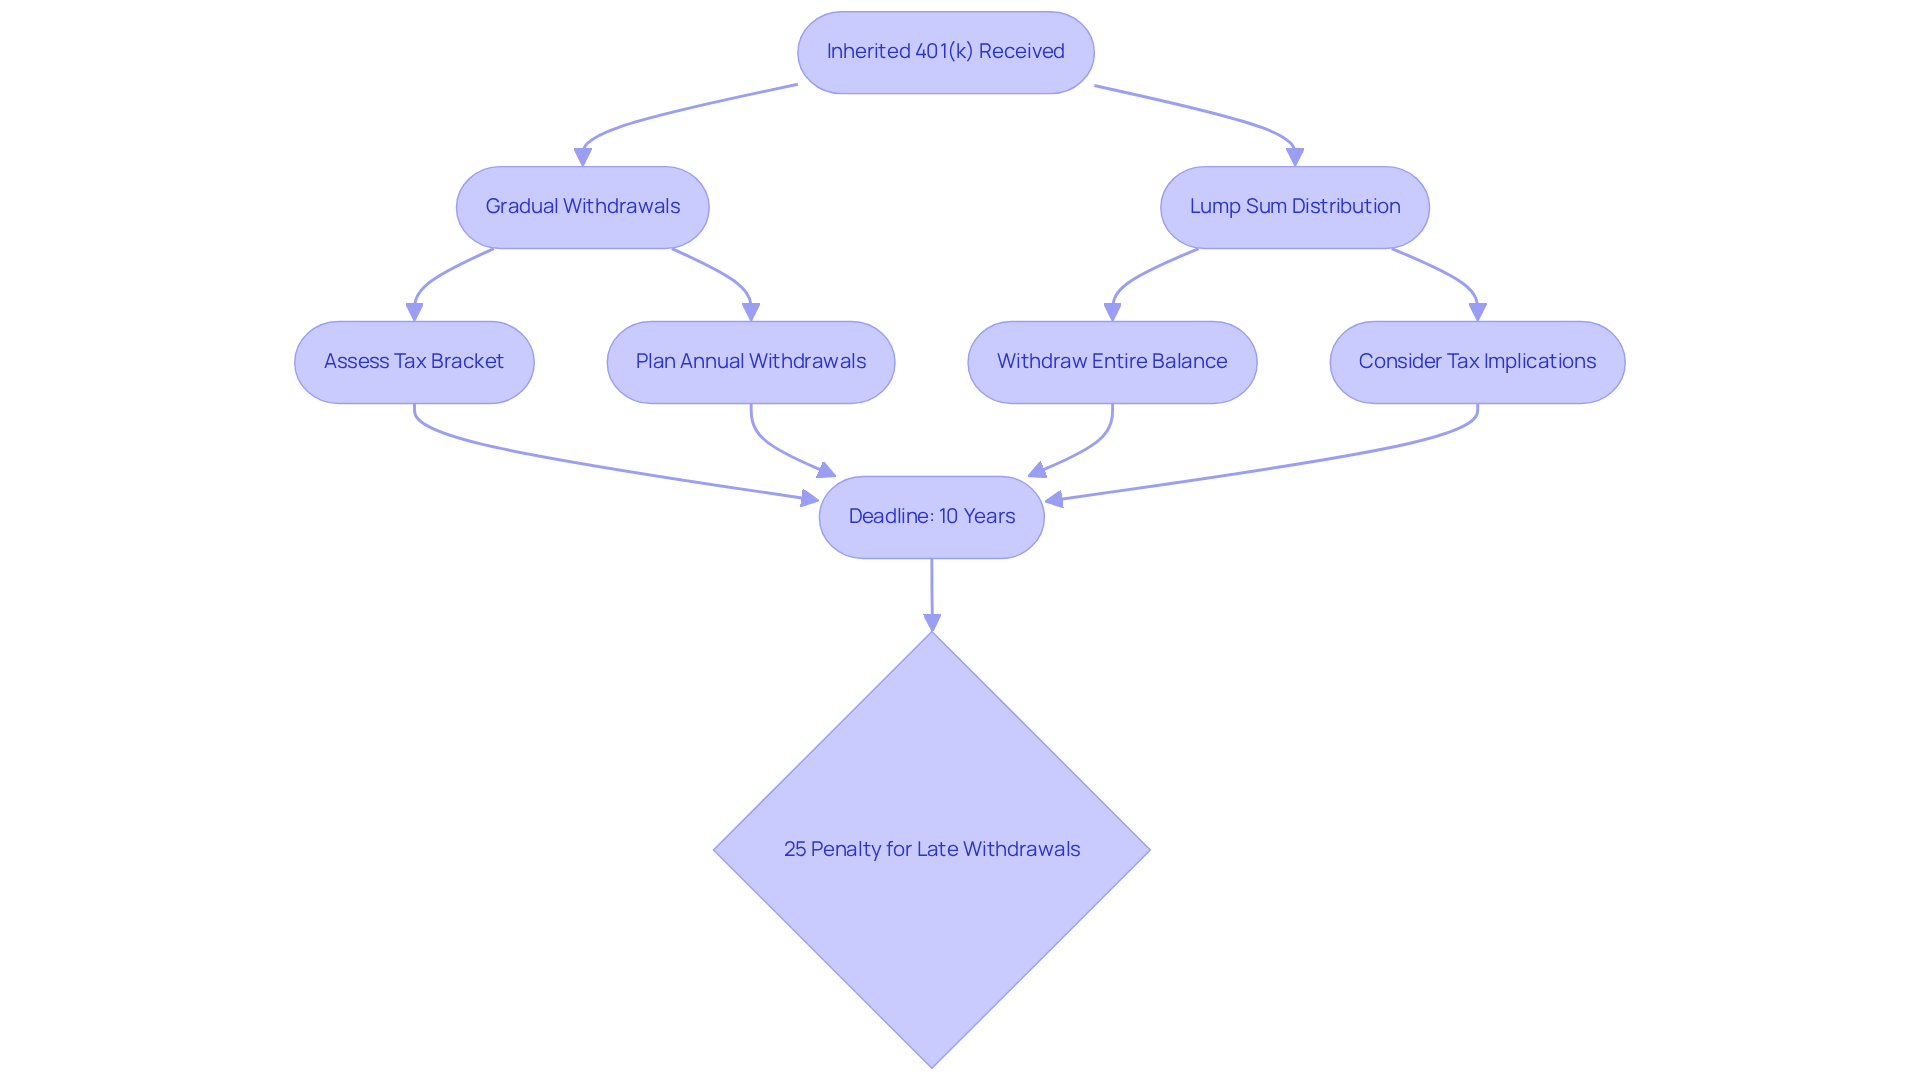
Navigating the complexities of financial planning can feel overwhelming, especially for young parents. According to the inherited 401k rules established by the SECURE Act, most non-spouse beneficiaries must withdraw the entire balance of a received 401(k) within 10 years of the account owner’s death. While this regulation offers some flexibility in managing distributions, it also comes with a critical deadline that must be met to avoid hefty tax penalties. If funds aren’t withdrawn by the end of the 10th year, a 25% penalty on any remaining balance kicks in, underscoring the importance of careful planning.
Imagine if you could take control of your financial future while ensuring your family’s needs are met. Understanding your monetary situation and tax bracket is essential when strategizing these withdrawals. For instance, families might choose to take distributions gradually over the decade to lessen tax impacts, or they could opt for a lump sum distribution to meet the 10-year requirement right away. Consulting with wealth advisors can provide tailored strategies that align with your unique circumstances, helping you maximize your inherited assets according to inherited 401k rules while minimizing tax liabilities.
Real-world examples show just how crucial proactive planning can be. Families who successfully navigate the 10-year rule often find themselves in a stronger position to manage their economic futures. As one specialist wisely notes, “The key is to act quickly,” highlighting that prompt decisions can significantly influence your overall financial outcome. By embracing the flexibility of the 10-year rule, young parents can secure their legacy while prioritizing their family’s well-being. Remember, we’re here for you, and together, we can navigate this journey.
Tax Considerations for Inherited 401(k) Accounts: What Young Parents Should Know
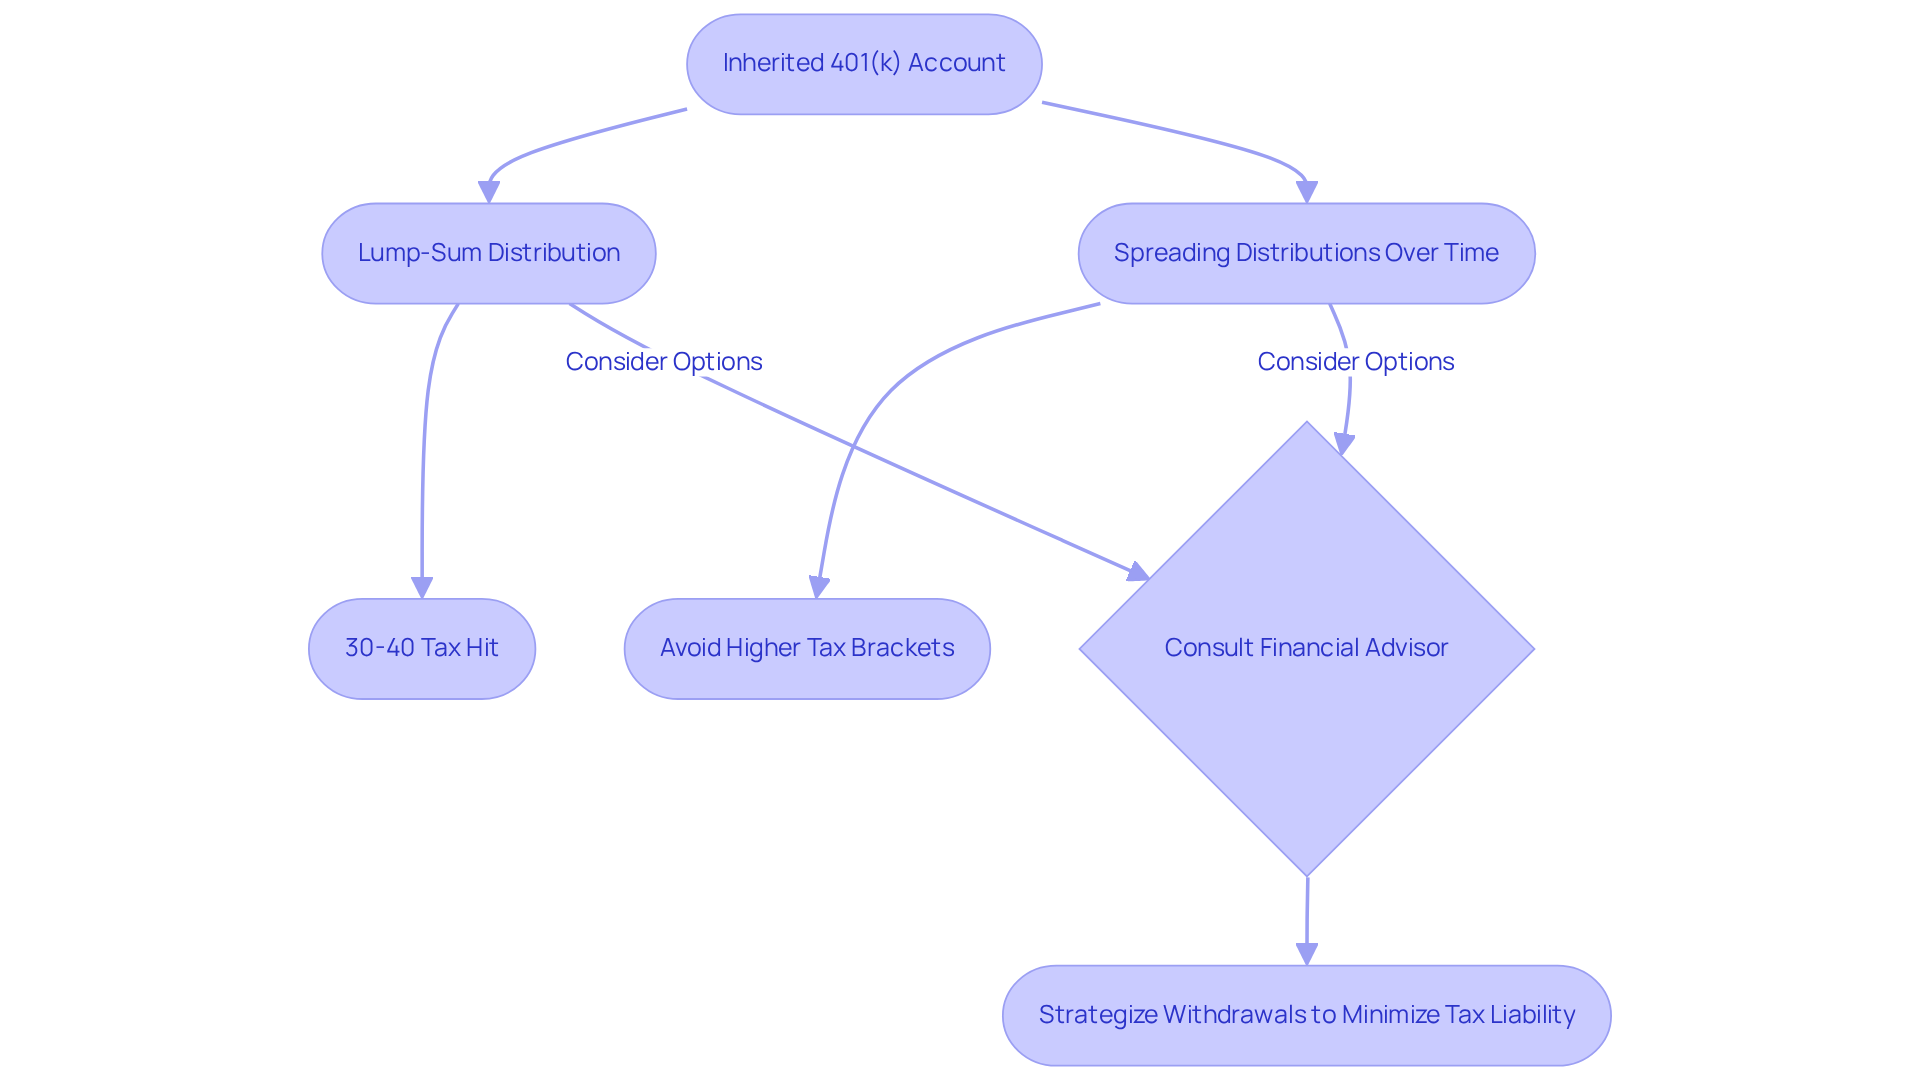
Inherited 401k rules can bring unexpected challenges, especially when it comes to taxes. For many young parents, understanding how these plans affect your family’s finances is crucial. When non-spouse beneficiaries withdraw funds, they face income tax at their ordinary rate, which can create a heavier financial burden. Imagine trying to manage family expenses while dealing with a higher tax bill – it can feel overwhelming.
To ease this strain, consider the timing of your withdrawals. Spreading distributions over several years might help you avoid jumping into a higher tax bracket. For example, if a family inherits a $200,000 traditional 401(k) and chooses a lump-sum distribution, they could face a tax hit of 30-40%. That’s a significant reduction in what they actually receive. On the other hand, taking smaller distributions over time can help manage those tax implications more effectively.
It’s important to consult with a financial advisor who can guide you through the complexities of inherited 401k rules. As one expert wisely notes, “The objective is straightforward: deplete the funds by the deadline while minimizing the tax burden.” Understanding the current average income tax rates for non-spouse beneficiaries can also aid in your planning. If the average rate is around 24%, you can strategize your withdrawals to minimize your overall tax liability.
Many families have successfully navigated these waters through careful planning. By converting a traditional 401(k) to a Roth 401(k), beneficiaries can potentially enjoy tax-free withdrawals in the future, as long as they follow the necessary rules. Together, we can navigate this journey, ensuring that proactive management of inherited 401(k) plans leads to significant financial advantages for your family.
Insights on Creditor Protection for Inherited 401(k) Accounts
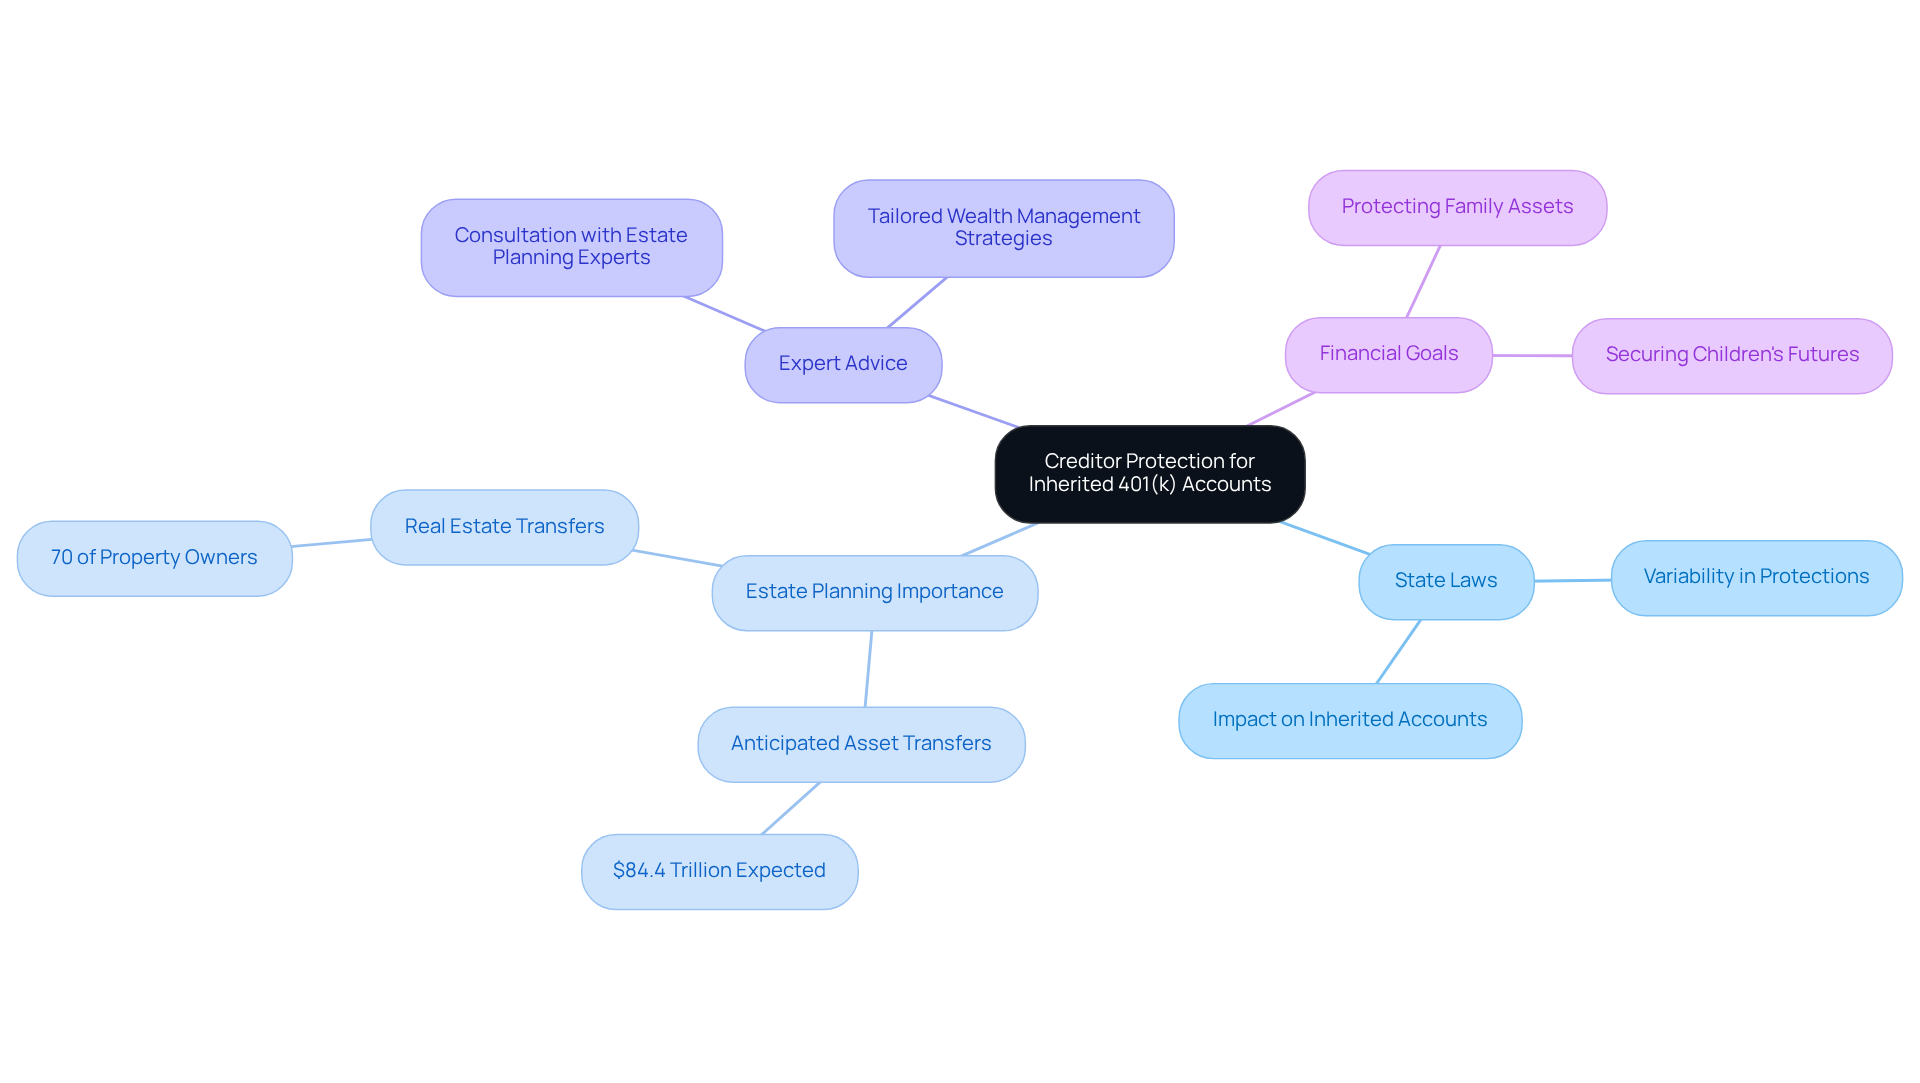
Inherited 401k rules can offer some protection from creditors, but the extent of this protection varies widely depending on state laws and individual circumstances. Unlike traditional retirement accounts, which often have strong protections in bankruptcy, inherited 401k rules may result in inherited accounts being more exposed. With an astonishing $84.4 trillion in assets expected to be passed down through estates in the coming decades, it’s vital to understand how to shield these bequeathed assets from creditor claims.
Imagine nearly 70% of property owners planning to pass on real estate to their children. This highlights the importance of thoughtful estate planning, especially for young parents. Estate planning lawyers emphasize that a well-organized strategy can effectively protect these valuable resources, helping families maintain their financial stability and secure their children’s futures.
So, how can young parents safeguard the assets they receive? Seeking advice from an estate planning expert can be a great first step. Together, you can create a personalized plan that fits your unique situation. At Bright Advisers, we focus on tailored wealth management strategies. Our liability-driven investment approach helps develop comprehensive plans that adapt to your changing needs.
By working with our diverse team at Bright Advisers, families can ensure their estate planning aligns with their financial goals. We’re here for you, providing an extra layer of security for the assets you pass down. Together, we can navigate this journey and protect what matters most.
Guidelines for Commingling Inherited 401(k) Accounts
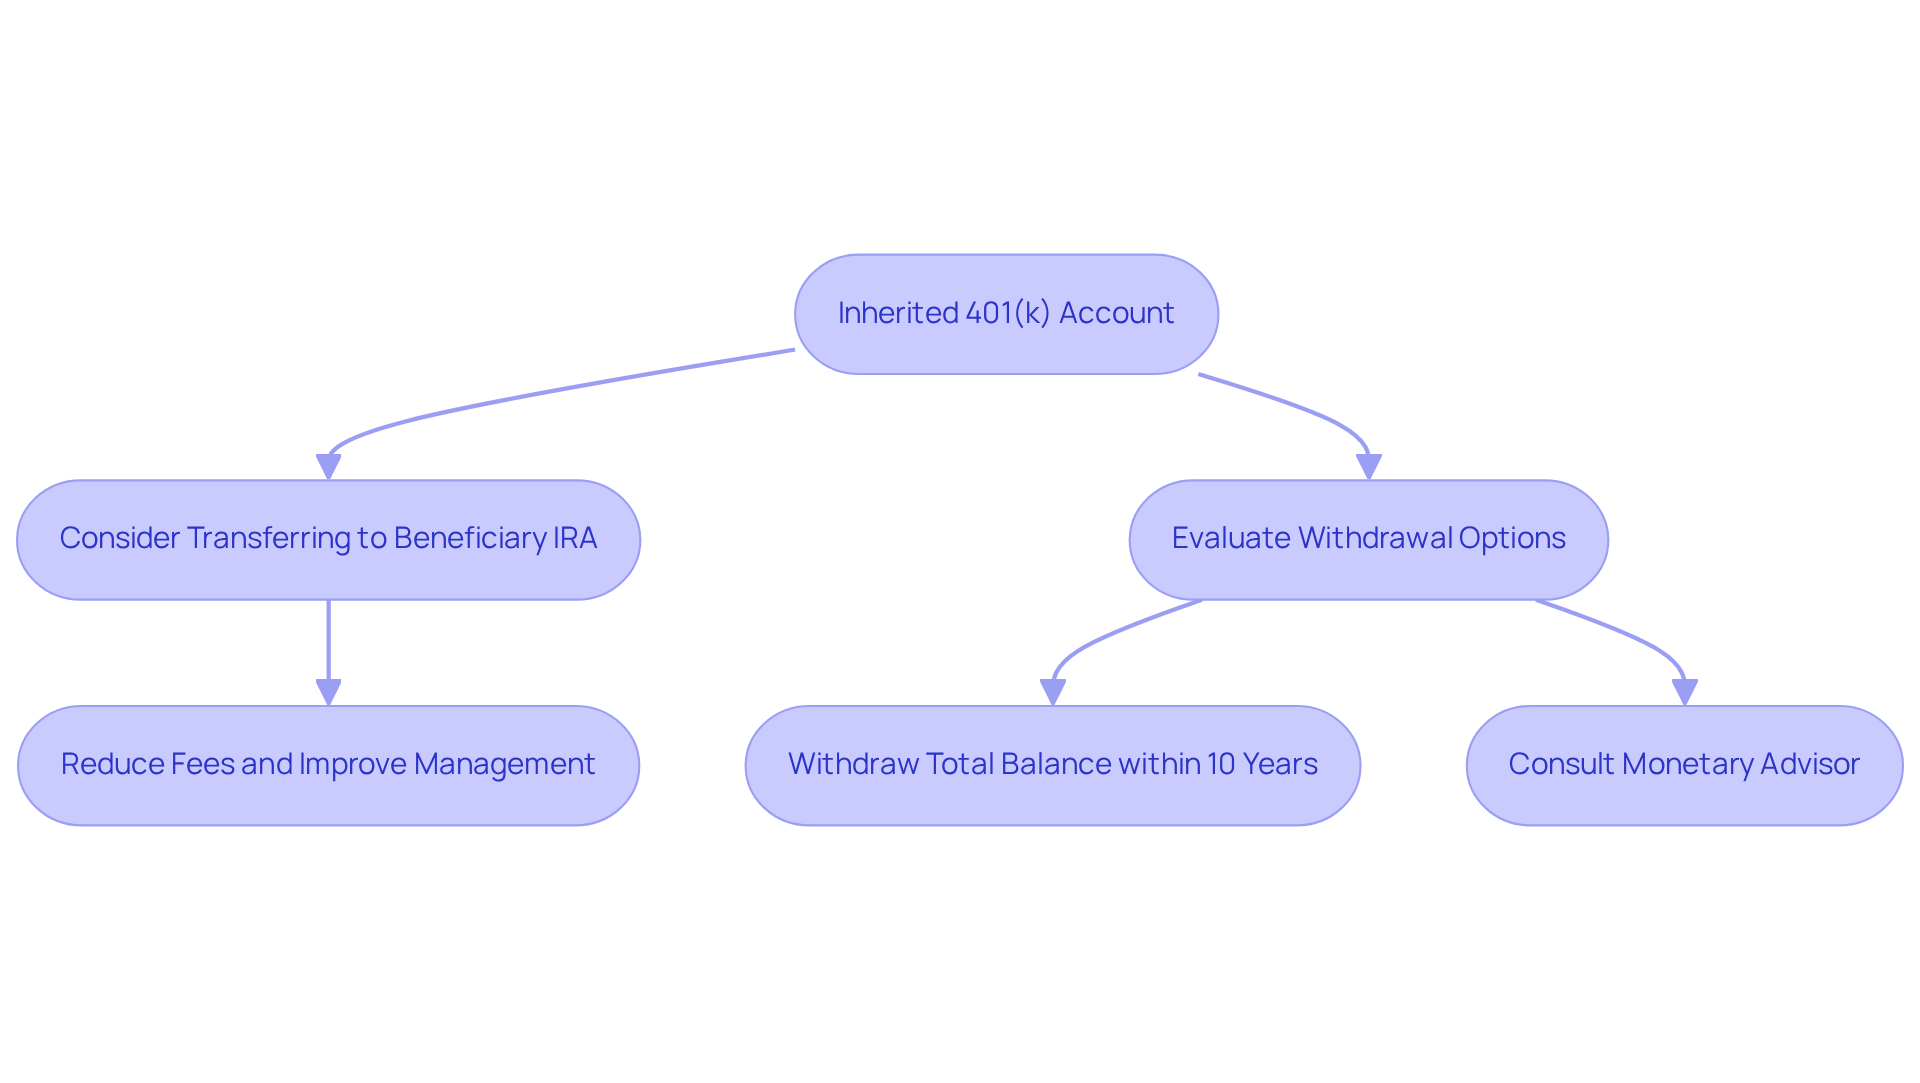
Are you a young parent feeling overwhelmed by financial decisions? You’re not alone. Many beneficiaries of 401(k) plans find themselves in a similar situation, wondering how to best manage their funds according to the inherited 401k rules. One option to consider is transferring these funds into a beneficiary IRA. This simple step can streamline your financial management, making it easier to keep track of your family’s finances.
Imagine if you could reduce fees while ensuring your family’s wealth is managed effectively. At Bright Advisers, we believe in keeping fund charges minimal, which can significantly improve accessibility to wealth management for families like yours. However, it’s important to understand that this commingling is generally allowed only for accounts inherited from the same individual.
According to the SECURE Act, non-spousal beneficiaries must follow the inherited 401k rules by withdrawing the total balance of a 401(k) within 10 years of inheritance. This makes it crucial for young parents to evaluate all available options. Consulting with a monetary advisor, such as those at Bright Advisers, can provide you with personalized guidance tailored to your family’s needs. As one advisor wisely suggests, “Consult your advisor or estate planning expert” to navigate these complexities effectively.
Additionally, keep in mind that traditional IRA accounts don’t offer the same creditor protection as standard retirement accounts. This knowledge is vital for making wise financial decisions that safeguard your family’s future. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Inherited IRA vs. Inherited 401(k): Key Differences Explained
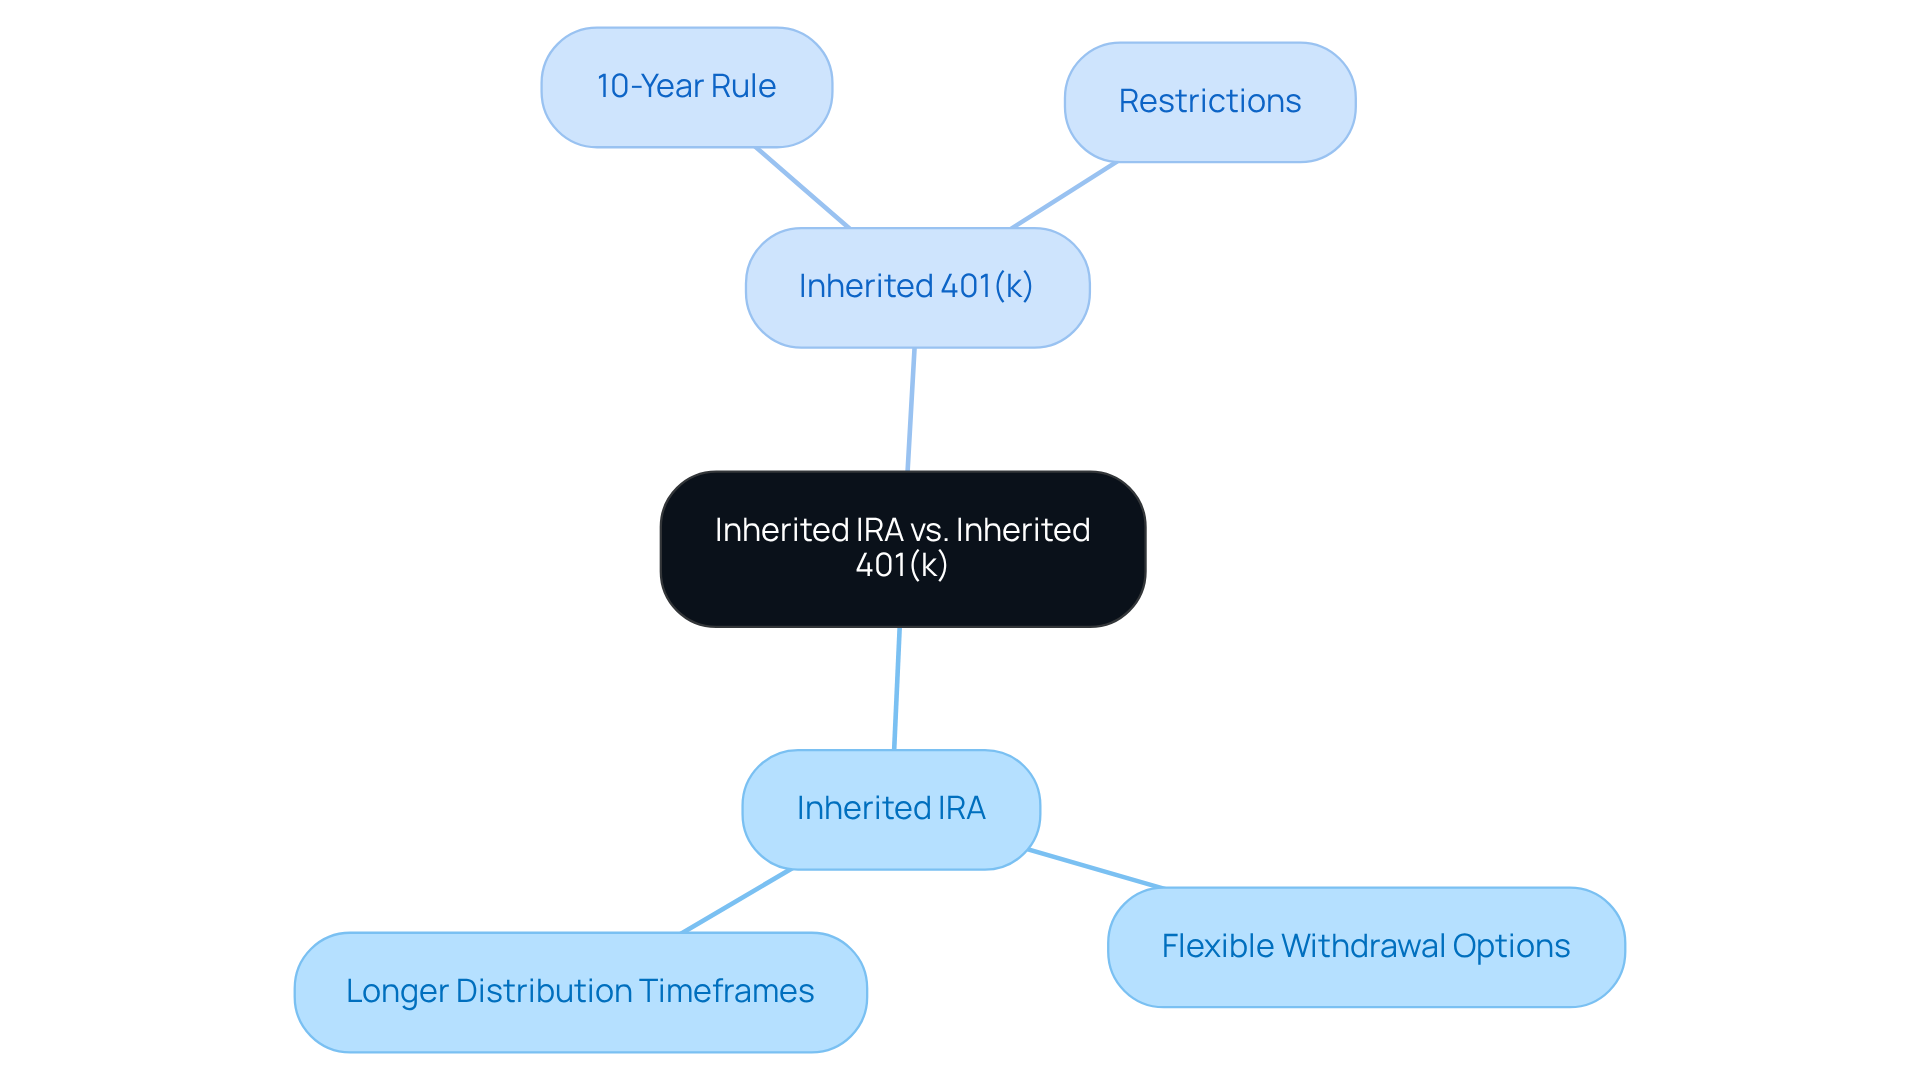
Understanding the inherited 401k rules and the regulations surrounding inherited IRAs is crucial for young parents navigating their financial futures. Imagine if you could make the most of these assets for your family’s benefit. Beneficiary IRAs often offer more flexible withdrawal options and longer timeframes for distributions, which can be a real advantage. In contrast, under the inherited 401k rules, beneficiary 401(k)s are typically subject to the 10-year rule, which can feel restrictive.
It’s important to understand these differences so you can make informed decisions about managing your acquired assets effectively. Picture this: having the freedom to choose how and when to access your funds can provide peace of mind during uncertain times.
By grasping these concepts, you can ensure that your family’s financial needs are met while also planning for the future. Remember, we’re here for you, ready to help you navigate this journey together. Your family’s well-being is our priority, and understanding these financial tools is a step toward securing that future.
The Bottom Line: Essential Inherited 401(k) Rules for Young Parents
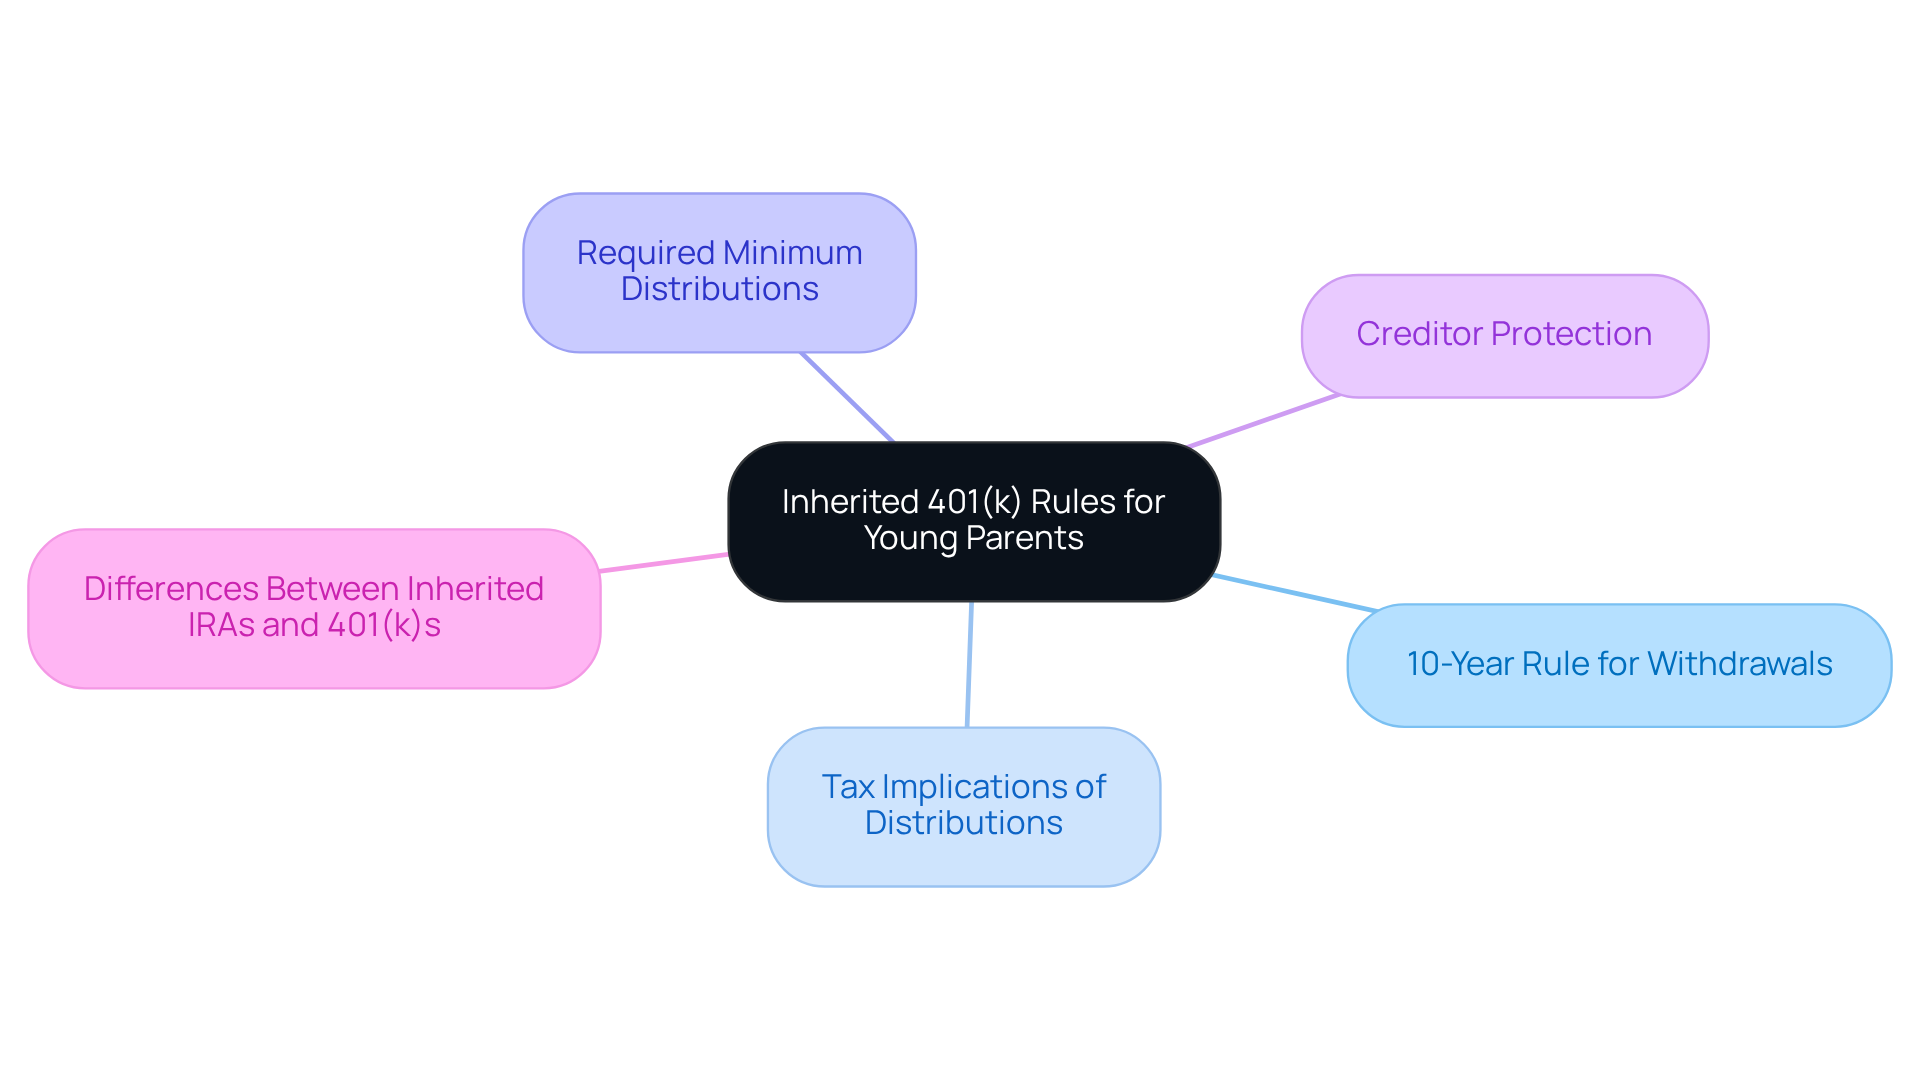
Navigating the world of inherited 401k rules can feel overwhelming for young parents, but understanding the essential regulations is crucial. Imagine if you could confidently manage your family’s financial future while ensuring your loved ones are taken care of. Key points to keep in mind regarding inherited 401k rules include:
- The 10-year rule for withdrawals
- The tax implications of distributions
- The importance of managing required minimum distributions
It’s also vital to recognize creditor protection matters and the differences between inherited IRAs and 401(k)s. At Bright Advisers, we understand the unique challenges families face, which is why we’re dedicated to offering low fund fees. This commitment enhances wealth management accessibility, allowing you to retain more of your hard-earned assets.
By staying informed and seeking professional guidance, you can effectively navigate the complexities of inherited retirement accounts. Together, we can explore tailored wealth management solutions that empower your financial security and educational readiness. Remember, you’re not alone in this journey; we’re here for you every step of the way.
Conclusion
Navigating the complexities of inherited 401(k) rules is essential for young parents who want to secure their family’s financial future. Imagine if you could understand the implications of the 10-year withdrawal rule, the tax consequences of distributions, and the importance of managing required minimum distributions (RMDs). By grasping these regulations, you can empower your family to make informed decisions that align with your long-term goals.
Throughout this article, we’ve highlighted key insights, including the impact of recent changes to regulations, the differences between inherited IRAs and 401(k)s, and the significance of proactive estate planning. It’s important to understand that consulting with financial advisors can help tailor strategies that minimize tax burdens and protect inherited assets. These considerations are crucial for young parents striving to maintain economic security while navigating the challenges of inherited wealth.
In conclusion, staying informed and proactive in managing inherited 401(k) accounts is vital for young parents. Seeking professional guidance can lead to effective wealth management solutions that enhance financial security and educational readiness for future generations. Together, we can navigate this journey, ensuring a brighter financial future while safeguarding your loved ones’ well-being. By understanding these essential rules and taking action, you can find lasting peace of mind and stability.
Frequently Asked Questions
What is Bright Advisers’ approach to managing inherited 401(k) plans?
Bright Advisers focuses on personalized financial planning that reflects each family’s specific needs. They begin with a thorough assessment of the family’s financial landscape and long-term goals to create tailored strategies.
What are the key rules for non-spousal beneficiaries of inherited 401(k) accounts?
Non-spousal beneficiaries must withdraw the entire balance of the inherited 401(k) within 10 years after the original account holder’s passing, as per the inherited 401(k) rules established by the SECURE Act of 2019.
How does the SECURE Act of 2019 affect inherited 401(k) accounts?
The SECURE Act eliminated the ‘stretch’ provision for most non-spouse beneficiaries, requiring them to withdraw the full balance within 10 years, which impacts tax planning and financial strategies.
What changes are expected in 2025 regarding inherited 401(k) accounts?
Starting in 2025, non-spouse beneficiaries must still withdraw the entire amount within 10 years, but Roth 401(k) plans will no longer require Required Minimum Distributions (RMDs), allowing for indefinite tax-free growth. The RMD age for traditional retirement accounts will also be raised to 73 and 75 for different birth years.
What options do beneficiaries have for managing inherited 401(k) funds?
Beneficiaries can either keep the funds in the existing plan or roll them over into a beneficiary IRA, which may offer different tax advantages, such as stretching distributions over a longer period.
Why is consulting with a financial advisor important for managing inherited 401(k) accounts?
A financial advisor can provide personalized strategies to manage distributions effectively, help beneficiaries understand tax implications, and align financial strategies with long-term family goals.
How can families minimize tax burdens when withdrawing from inherited 401(k) accounts?
Families can minimize tax burdens by carefully strategizing withdrawals, such as opting for staggered distributions to avoid entering a higher tax bracket.
What is the significance of early planning for inherited 401(k) accounts?
Early planning is crucial as it helps beneficiaries understand the tax consequences of distributions and allows them to spread out withdrawals over the 10-year period, which can significantly reduce their overall tax impact.
List of Sources
- Bright Advisers: Personalized Financial Planning for Inherited 401(k) Management
- What to do with an inheritance | Vanguard (https://investor.vanguard.com/investor-resources-education/article/what-to-do-with-your-inheritance)
- How to Make the Most of Inherited 401(k) Funds (https://goodlifefamhc.com/blog/how-to-make-the-most-of-inherited-401k-funds)
- Financial Advisor for Inheritance: Services and Examples (https://smartasset.com/financial-advisor/financial-advisor-for-inheritance-services-and-examples)
- You’ve Inherited Money, Now What? (https://merkleretirementplanning.com/youve-inherited-money-now-what)
- Evolution of Inherited 401(k) Regulations: Key Changes Over Time
- Inherited 401(k) Rules: What Beneficiaries Need To Know (https://bankrate.com/retirement/inherited-401k-rules)
- How the SECURE Act 2.0 Affects Your Retirement Account & Beneficiaries – Judy Mock Law (https://judymocklaw.com/how-the-secure-act-2-0-affects-your-retirement-account-beneficiaries)
- The SECURE Act of 2019 – An Analysis of Key 401(k) Changes (https://employeefiduciary.com/blog/the-secure-act-of-2019-an-analysis-of-key-401k-changes)
- SECURE Act Final Regulations and Planning Considerations – Wiss (https://wiss.com/secure-act-final-regulations)
- How a New 10-Year Rule Could Affect Your Inherited IRA (https://westernsouthern.com/retirement/10-year-rule-inherited-ira)
- Understanding Key Aspects of Inherited 401(k) Accounts
- The IRS Clarifies Rules on Inherited Retirement Accounts (https://info.northcoastam.com/resources/the-irs-clarifies-rules-on-inherited-retirement-accounts)
- Tax Implications of Inherited 401(k) Accounts – Simmons & Schiavo, LLP (https://sslawoffices.com/blog/tax-implications-of-inherited-401k-accounts)
- Inherited 401(k): Rules and Tax Information | SoFi (https://sofi.com/learn/content/inherited-401k)
- If You Inherit A 401k, Don’t Ignore This Important Rule (https://finance.yahoo.com/news/inherit-401k-dont-ignore-important-193000576.html)
- Here’s how to handle the complicated rules for an inherited 401(k) or IRA (https://cnbc.com/2021/04/11/how-to-handle-complicated-rules-for-inherited-401k-or-ira.html)
- Managing Required Minimum Distributions for Inherited 401(k) Plans
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)
- The 10-Year Rule: Implications for Inherited 401(k) Withdrawals
- 7 Best Pre-Tax Investments for Young Families’ Financial Future – Bright Advisers (https://brightadvisers.com/7-best-pre-tax-investments-for-young-families-financial-future)
- If You Inherit A 401k, Don’t Ignore This Important Rule (https://finance.yahoo.com/news/inherit-401k-dont-ignore-important-193000576.html)
- Inherited 401(k): Rules and Tax Information | SoFi (https://sofi.com/learn/content/inherited-401k)
- Inherited 401(k) Rules: What Beneficiaries Need To Know (https://bankrate.com/retirement/inherited-401k-rules)
- Tax Considerations for Inherited 401(k) Accounts: What Young Parents Should Know
- Inherited 401(k): Rules and Tax Information | SoFi (https://sofi.com/learn/content/inherited-401k)
- 401(k) Inheritance Tax Rules for Estate Planning (https://smartasset.com/taxes/401k-inheritance-tax)
- Tax on an Inherited 401k: A Complete Guide (https://commonsllc.com/insights/tax-on-inherited-401-k)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- Tax Implications of Inherited 401(k) Accounts – Simmons & Schiavo, LLP (https://sslawoffices.com/blog/tax-implications-of-inherited-401k-accounts)
- Insights on Creditor Protection for Inherited 401(k) Accounts
- Trust Wealth Management: Essential Steps for Young Families – Bright Advisers (https://brightadvisers.com/trust-wealth-management-essential-steps-for-young-families)
- 12 Inspirational Quotes About Estate Planning – Leigh Hilton (https://dentonestateplanninglawyer.com/12-inspirational-quotes-about-estate-planning)
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)
- 10 Inspirational Quotes About Estate Planning (https://nelsonlawgrouppc.com/10-inspirational-quotes-about-estate-planning)
- Guidelines for Commingling Inherited 401(k) Accounts
- Understanding Inherited IRA and 401(k) Rules: A Comprehensive Guide (https://investopedia.com/articles/personal-finance/082515/inherited-ira-and-401k-rules-explained.asp)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading