

Overview
Navigating the world of taxes can be overwhelming, especially when it comes to the K-1 tax form related to inheritance. This form is essential for beneficiaries, as it plays a crucial role in tax reporting and compliance. Understanding the K-1 form can help you manage your inherited assets effectively, ensuring you are aware of the earnings and deductions that come with them.
Imagine if you could optimize your financial outcomes while also fulfilling your family’s needs. The K-1 form details not just the numbers, but also the potential for tax savings. Strategies like the step-up in basis and the classification of income can make a significant difference in your financial planning. By grasping these concepts, you can navigate your tax obligations with confidence and ease.
It’s important to understand that you’re not alone in this journey. Many beneficiaries face similar challenges, and there are ways to approach these situations that can lead to better financial health for your family. Together, we can explore how to make the most of your inheritance, ensuring that it aligns with your family’s values and goals.
Remember, we’re here for you. With the right guidance and knowledge, you can turn the complexities of tax reporting into opportunities for your family’s future. Let’s take this journey together, ensuring that your financial decisions support your loved ones and help you achieve peace of mind.
Key Highlights:
- K-1 tax forms are essential for beneficiaries, detailing earnings, deductions, and credits from inherited assets.
- Revenue distributions from trusts are taxed as regular earnings, while principal distributions are non-taxable.
- Understanding K-1 forms is crucial for accurate tax reporting and compliance, with about 20% of estates requiring them.
- K-1 earnings are classified as pass-through revenue, affecting individual tax brackets and overall tax liability.
- The step-up in basis adjusts inherited asset values for capital gains tax calculations, potentially leading to significant tax savings.
- Beneficiaries should expect to receive K-1 forms by March 15 of the year following the tax year, unless extensions are filed.
- Common deductions available on K-1 forms include administrative costs, legal fees, and charitable contributions.
- Professional guidance can help navigate K-1 complexities, optimize tax strategies, and ensure compliance.
- K-1 earnings are categorized as unearned revenue, differing from earned income in tax implications and reporting.
- Timely and informed management of K-1 forms can enhance beneficiaries’ financial outcomes and secure their financial futures.
Introduction
Navigating the complexities of K-1 tax forms can feel overwhelming for beneficiaries, especially when it comes to understanding their implications on inherited assets. At Bright Advisers, we understand these challenges and stand ready to provide expert guidance that empowers families to manage their financial responsibilities with confidence.
Imagine the relief that comes with the potential for significant tax savings through provisions like the step-up in basis and the intricacies of income classification. It’s important to be well-informed to optimize your financial outcomes.
This article gently delves into the essential aspects of K-1 forms, from reporting requirements to strategic tax planning. Together, we can ensure that families are equipped to make informed decisions that secure their financial futures.
Bright Advisers: Expert Guidance on K-1 Tax Form Inheritance
At Bright Advisers, we understand that navigating the complexities of financial matters, especially K-1 tax forms, can feel overwhelming. Our mission is to clarify these intricate subjects, empowering families to understand the tax implications associated with the K-1 tax form inheritance of inherited assets. This understanding enables you to manage your financial responsibilities with confidence. If you are a beneficiary receiving revenue distributions from trusts in 2025, it’s important to know these are taxed as regular earnings, while principal distributions remain non-taxable. We emphasize this crucial distinction to support effective tax planning, guiding you through these complexities with ease.
Imagine this: you’re an investor in a publicly traded partnership (PTP). You may need to file Form K-1 to report any income or losses distributed by the partnership. We provide comprehensive inheritance guidance, ensuring you are well-informed about your obligations and the potential K-1 tax form inheritance liabilities. A recent case study featuring clients Allison and Brian illustrates how strategic tax planning can significantly enhance financial outcomes. By incorporating thoughtful tax strategies into their financial planning, they secured their children’s future and gained the ability to retire sooner.
Expert opinions reinforce the importance of simplifying the K-1 tax form inheritance process. Rebecca Lake, a retirement, investing, and estate planning expert, shares, “One way to make the job of filing taxes easier is with a free, easy-to-use tax return calculator.” By leveraging innovative technology and personalized service, we help you navigate these complexities, reducing the stress often associated with tax season. As the demand for virtual tax solutions grows, especially among small firms, Bright Advisers stands ready to provide effective strategies that align with your needs.
Statistics show that many recipients are unaware of the implications of K-1 forms, highlighting the necessity for clear guidance. We are committed to educating families about these tax responsibilities, ensuring you can make informed decisions that secure your financial future. For personalized guidance on K-1 tax form inheritance and to explore how our innovative investment strategies can enhance your financial planning, we invite you to consult with Bright Advisers. Together, we can navigate these complexities with confidence.
Understanding When the K-1 Tax Form Applies to Inherited Assets
Navigating the K-1 tax form inheritance can feel overwhelming, especially when it comes to receiving assets from a trust or estate. This essential document plays a crucial role in reporting your share of earnings, deductions, and credits tied to the estate or trust. Did you know that about 20% of estates require K-1 forms? Understanding this process is vital for accurate tax reporting, and it’s important to recognize that the K-1 form isn’t just a formality; it can significantly impact your personal tax returns.
Imagine if you could simplify this process with the right support. Consulting with a CPA or financial advisor can be a game-changer, particularly if you’re unfamiliar with the nuances of K-1 reporting. As the AccountingInsights Team wisely notes, “Understanding these categories is essential for accurate reporting and managing tax obligations.” Many beneficiaries who sought professional guidance reported a notable reduction in errors and enhanced compliance with tax regulations.
Looking ahead to 2025, it’s crucial to be vigilant about K-1 tax form inheritance requirements, as changes in tax laws could influence how inherited assets are reported. Comprehending the classifications of revenue on the K-1 is key to effectively managing your tax obligations. By navigating the K-1 process with the right support, you can ensure that you meet your reporting requirements while maximizing your financial outcomes. Remember, you’re not alone in this journey; together, we can navigate these complexities and secure your family’s financial future.

Types of Income Reported on Schedule K-1 for Beneficiaries
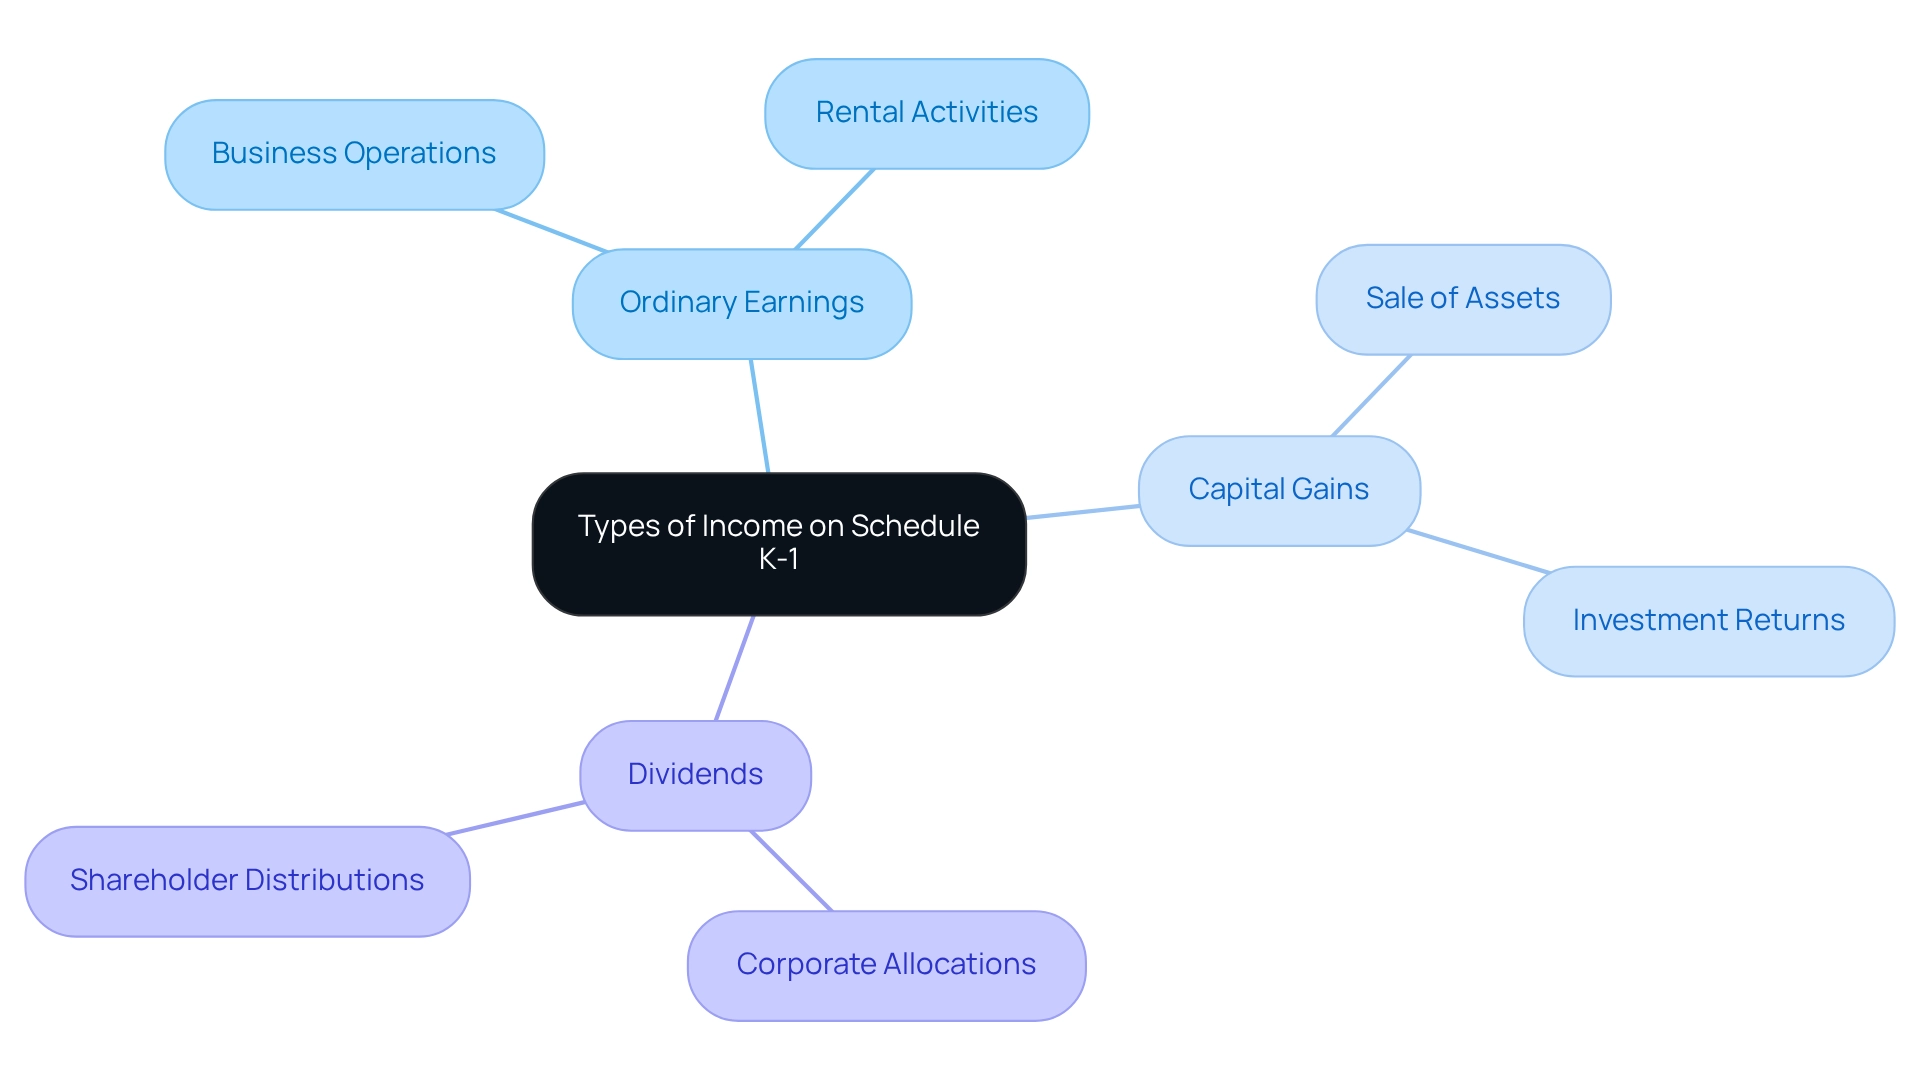
The K-1 tax form inheritance serves as an essential document for beneficiaries, detailing various types of earnings that can significantly impact their tax responsibilities. For young families, understanding these details can feel overwhelming, but it’s crucial to navigate this journey together. The main categories reported consist of ordinary earnings, capital gains, and dividends. Ordinary income typically encompasses earnings from business operations or rental activities, while capital gains arise from the sale of assets held by the partnership or trust. Dividends signify allocations from corporate earnings, which can also influence the recipient’s tax circumstances.
Imagine if you could optimize your financial situation through effective tax planning. For 2025, recipients should pay particular attention to the average capital gains reported on K-1 forms, which, according to recent statistics, can vary widely based on the underlying investments of the partnership or trust. Understanding these distinctions is essential for accurate tax reporting and compliance, especially for families like Allison and Brian, who are concerned about their financial well-being.
Expert insights emphasize that every kind of entity—be it a partnership, S corporation, or trust—employs a particular variant of Schedule K-1 to report earnings, deductions, and credits related to its members. As Angelina Graumann observes, “Each category of entity utilizes a particular version of Schedule K-1 to report the earnings, deductions, and credits assigned to its members or shareholders.” This detail highlights the significance of recipients being informed about the revenue classifications that pertain to them, especially in managing the intricacies of tax strategy.
It’s important to understand that trusts may have state-level tax obligations based on their location and the residency of recipients, adding another layer to tax reporting. By being aware of these earnings classifications and their implications, recipients can better handle their tax obligations and evade possible penalties. Moreover, the K-1 tax form inheritance is submitted to the IRS alongside the partnership’s tax return, which directly influences how recipients report their income and fulfill their tax responsibilities. This understanding is vital for high-income families like Allison and Brian, who are seeking professional guidance to navigate these complexities and optimize their wealth accumulation potential.
Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Step-Up in Basis: Implications for Inherited Assets on K-1
Understanding the step-up in basis is vital for your family’s financial future. This important tax provision adjusts the value of inherited assets to their fair market value at the time of the decedent’s death. This means that when you sell an inherited asset, you only pay capital gains tax on the appreciation that occurs after you inherit it. This can lead to significant tax savings, allowing you to keep more of your family’s wealth intact.
Imagine inheriting a property valued at $500,000 when your loved one passes away, while they originally purchased it for $300,000. If you later sell that property for $600,000, you would only owe capital gains tax on the $100,000 increase after you inherited it. Without the step-up in basis, you would have faced taxes on a $300,000 gain, which could be a heavy burden.
However, it’s important to be aware that certain inherited assets, like traditional IRAs, 401(k) plans, and some trusts, do not qualify for this adjustment. These exceptions highlight the necessity of consulting with tax professionals who can guide you through the complexities of K-1 tax form inheritance reporting, ensuring compliance while maximizing your potential tax benefits. As Gary Massey, CPA, wisely states, “We know the tax issues. We know our way around the IRS. We know QuickBooks. And we know how to help you save taxes and keep more of your hard-earned profits.”
Grasping these implications can significantly influence your family’s financial well-being, enabling you to retain more of your inherited wealth. High-income families should be mindful of these opportunities and seek professional guidance to ensure they are not missing out on valuable tax savings.
Tip: Regularly review your inherited assets with a tax professional to fully understand the implications of the step-up in basis and explore other tax strategies that can enhance your family’s financial situation. Remember, together, we can navigate this journey towards a more secure future.

Allocating Deductions and Expenses on Schedule K-1
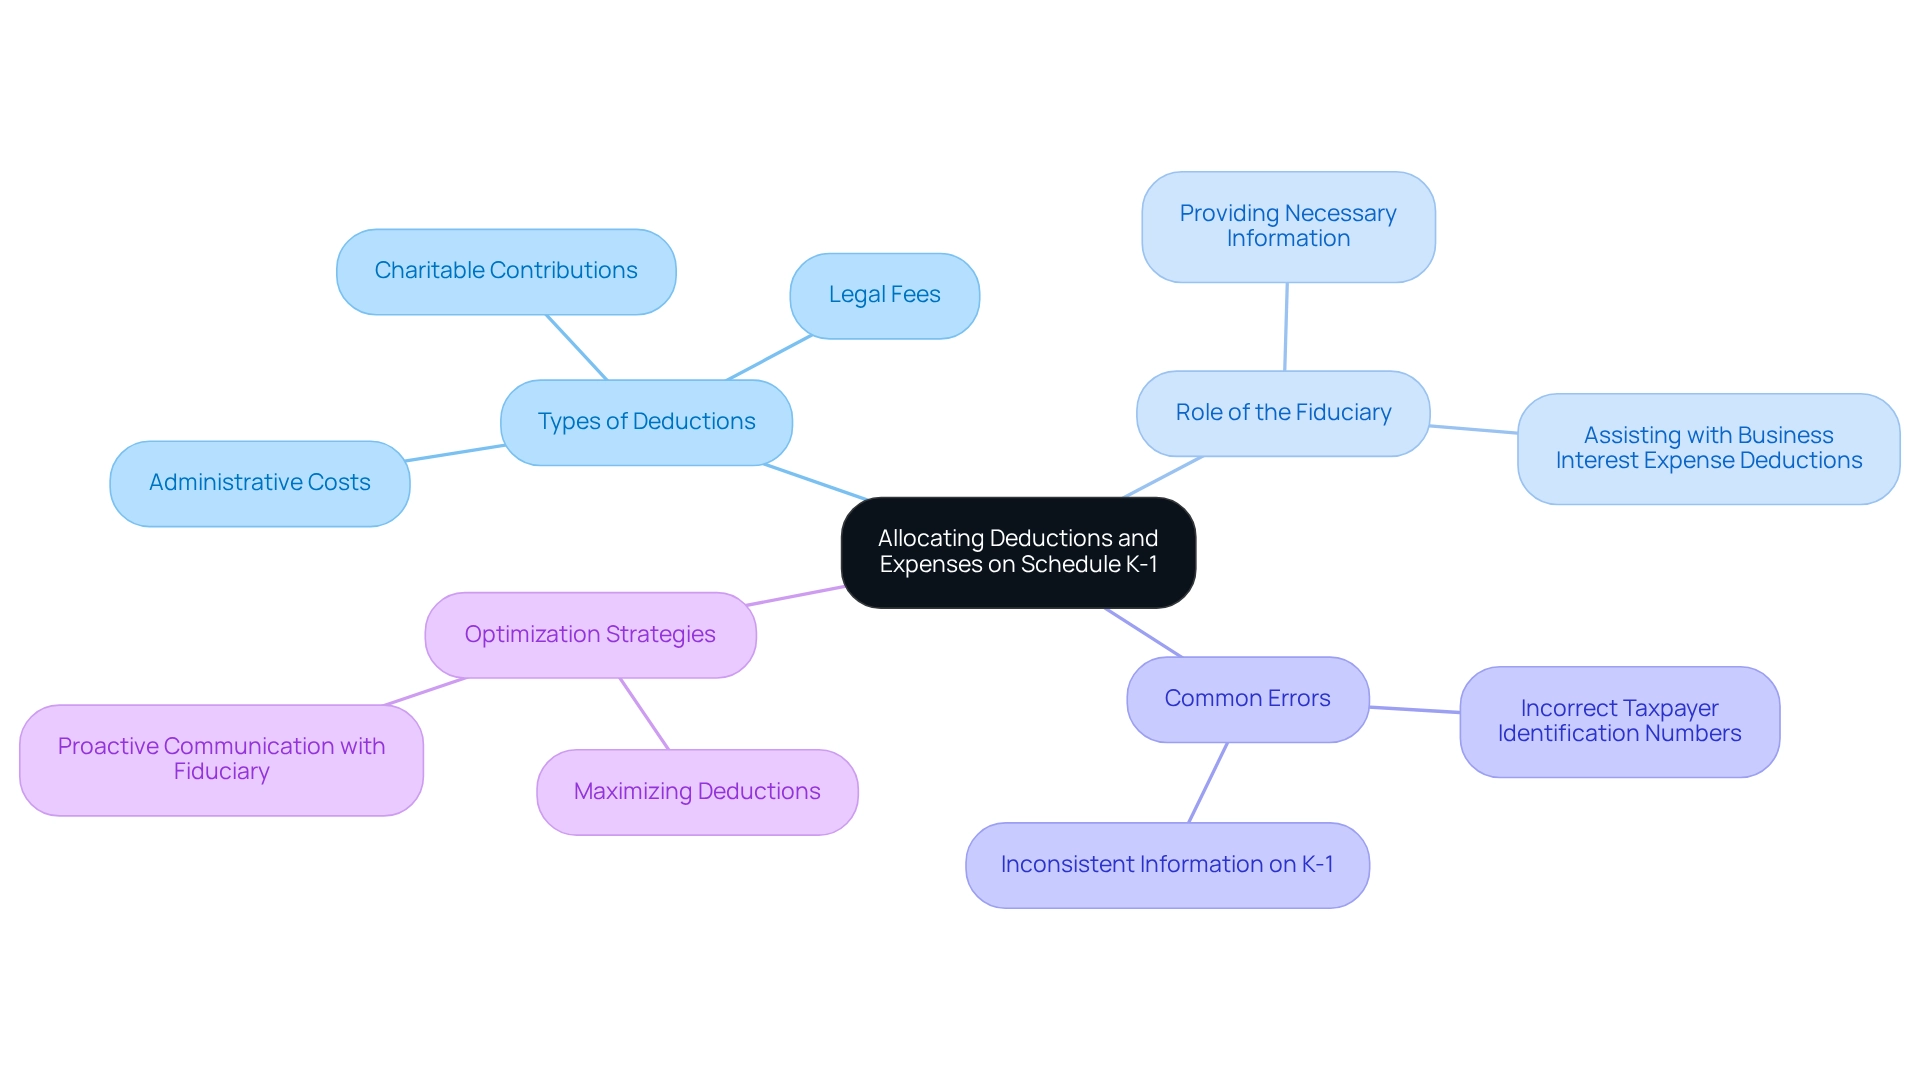
Beneficiaries have the opportunity to take advantage of various deductions that can significantly reduce their taxable income and overall tax liability. Common deductions include expenses related to the estate or trust, such as administrative costs, legal fees, and charitable contributions. Imagine receiving a K-1 that highlights a deduction for administrative expenses—this can be a helpful way to offset taxable income.
Proper allocation of these deductions is essential for maximizing benefits. The fiduciary plays a vital role in providing the necessary information to recipients, allowing them to accurately calculate any business interest expense deductions. It’s important to understand that Code ZZ in box 14 contains other crucial information needed for filing, which can be key for accurate reporting. Awareness of common errors, like incorrect taxpayer identification numbers or inconsistent details on the K-1, is crucial for ensuring compliance and avoiding penalties. Recipients should take the time to verify all details to prevent major issues when submitting Schedule K-1.
Optimizing deductions is a key strategy for minimizing taxable earnings effectively. By thoughtfully utilizing K-1 deductions, recipients can reduce their tax burden. For example, many have successfully lowered their taxable income by leveraging deductions associated with charitable contributions made by the estate. This proactive approach not only aids in tax reduction but also aligns with the values of families looking to leave a meaningful legacy, and understanding the K-1 tax form inheritance is a vital strategy for recipients aiming to enhance their financial outcomes. As a practical tip, beneficiaries should reach out to their fiduciary to ensure they are fully benefiting from available deductions and to clarify any uncertainties regarding their K-1 forms. Together, we can navigate this journey towards financial well-being.
Filing Your K-1 Form with Personal Tax Returns: A Step-by-Step Guide
Filing your K-1 form with your personal tax return can feel daunting, but we’re here to help you navigate this important process with care. Here’s a gentle guide to ensure your experience is smooth and stress-free:
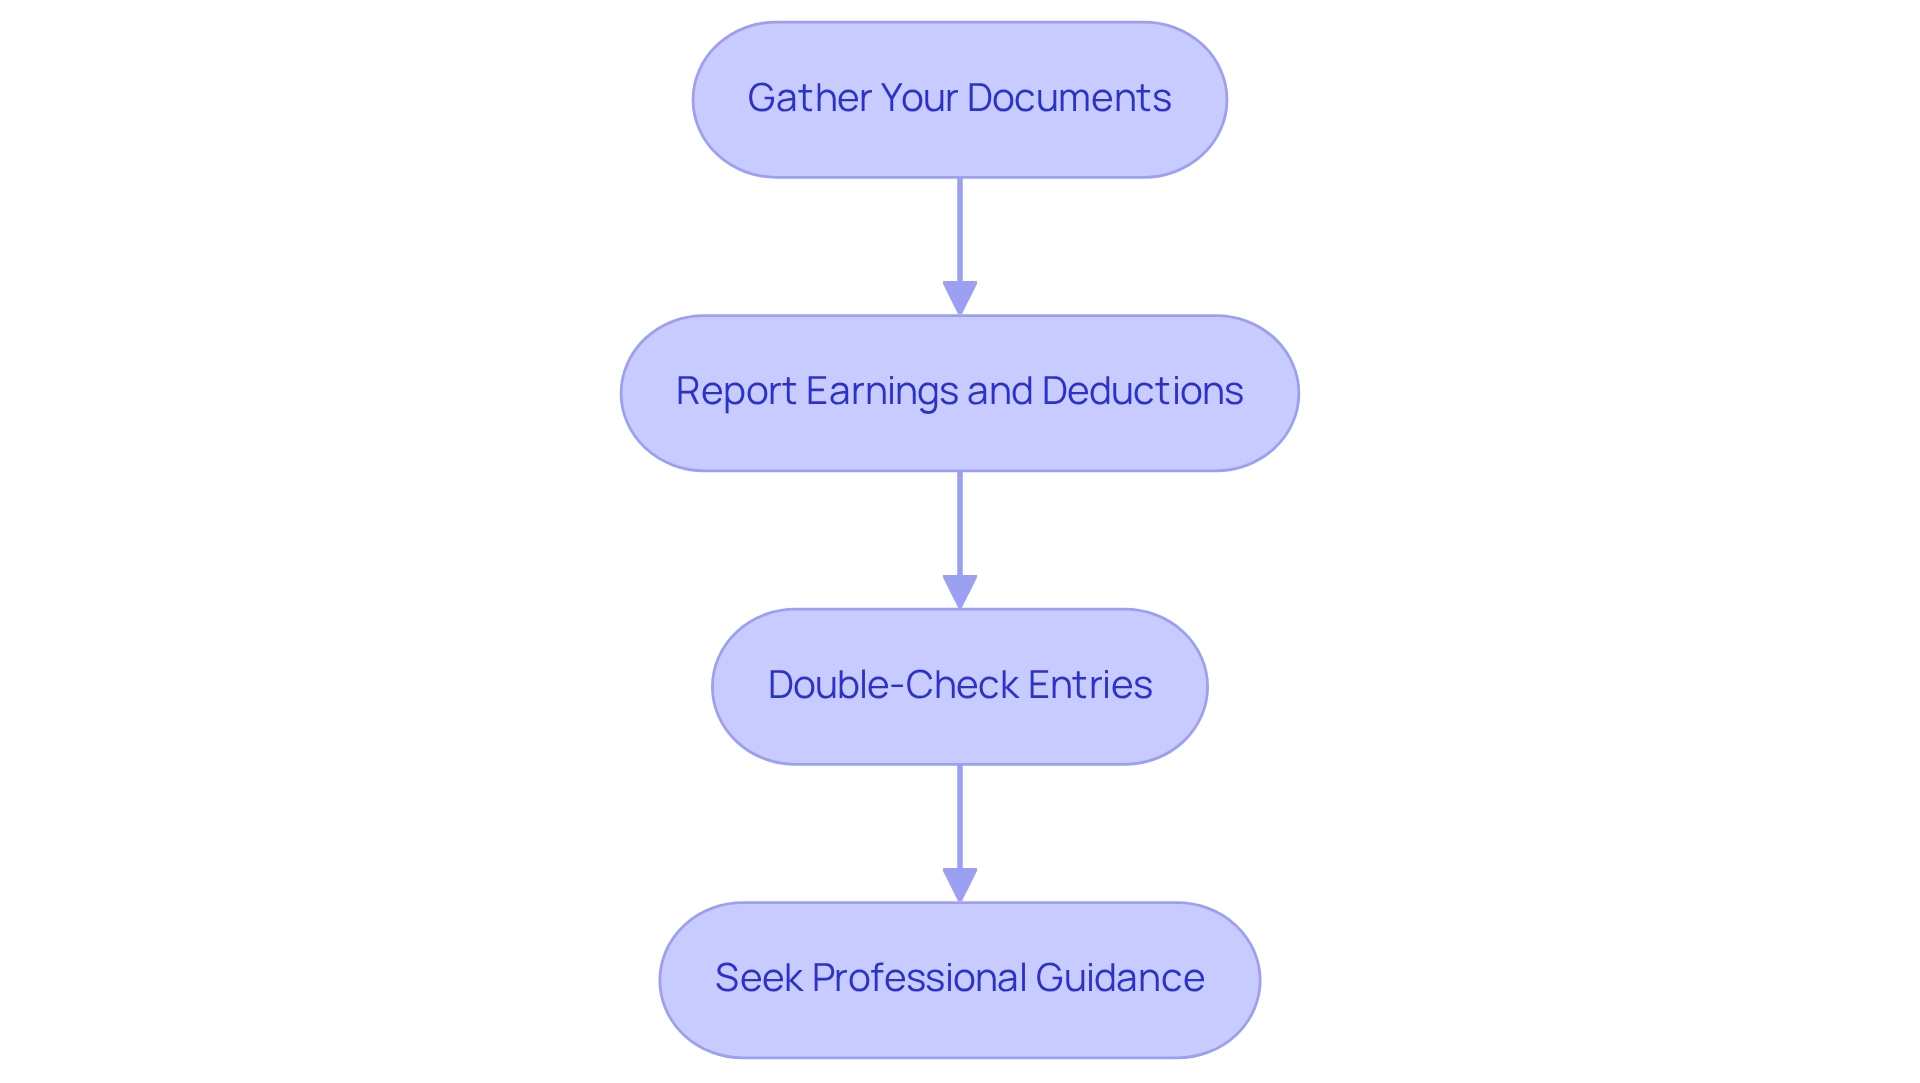
- Gather Your Documents: Begin by collecting your K-1 form along with any other relevant tax documents, like your W-2s and 1099s. Imagine having everything at your fingertips, making the process easier for you.
- Report Earnings and Deductions: It’s essential to transfer the earnings, deductions, and credits from your K-1 to your Form 1040. This step can significantly impact your overall tax liability. Remember, trusts and estates submit Form 1041 to report their earnings to the IRS, illustrating how the K-1 tax form inheritance fits into the larger tax picture.
- Double-Check Entries: Take a moment to verify that all amounts from the K-1 are accurately entered on your Form 1040. This simple act can prevent discrepancies that might lead to audits or penalties. Common mistakes include misreporting earnings or overlooking vital deductions, so a careful review is key.
- Seek Professional Guidance: If you find yourself uncertain about specific entries or the implications of K-1 earnings, consider reaching out to a tax expert. As many specialists note, K-1 earnings can even trigger alternative minimum tax, which primarily affects higher earners.
By following these steps, you can simplify your K-1 filing process, ensuring your tax return is accurate and complete. Additionally, opting for digital delivery of K-1 forms can expedite access, allowing for timely tax preparation and reducing the risk of errors. This approach can help you access your K-1 forms sooner, facilitating timely tax preparation. Together, we can navigate this journey with confidence and ease.
When Should You Expect to Receive Your K-1 Form?
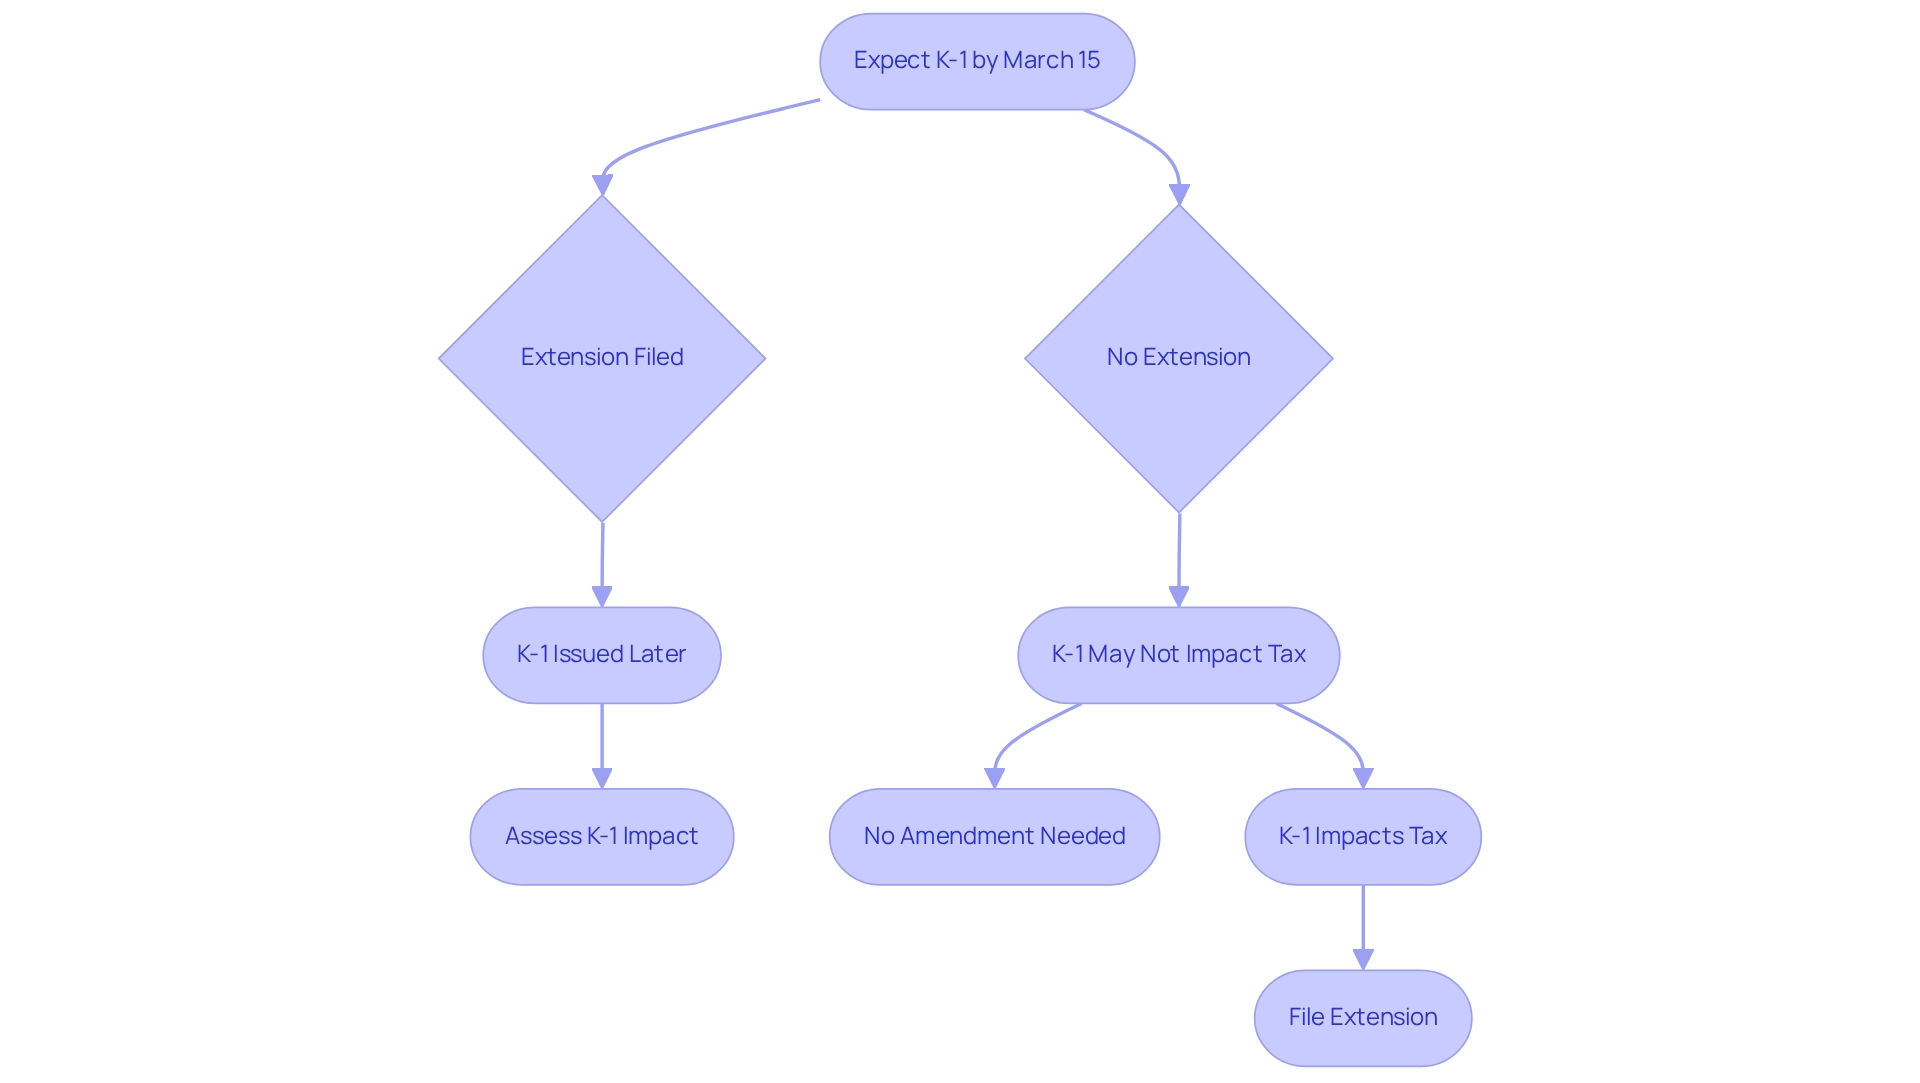
Beneficiaries can typically expect to receive their k-1 tax form inheritance by March 15 of the year following the tax year in which the estate or trust was active. However, if the estate or trust files for an extension, the k-1 tax form inheritance may not be issued until later in the year. This timeline is crucial for ensuring timely tax filing and avoiding potential penalties.
It’s important to understand that entities with fiscal years concluding on a date other than December 31 may issue K-1s three months after their tax year ends, which can further influence when recipients obtain their k-1 tax form inheritance. Imagine this: a client recently inquired about receiving a k-1 tax form inheritance for 2023 after already filing their tax return. In such cases, if the K-1 does not alter the tax situation, no amendment is necessary.
As Chase Charaba observes, ‘You and your partners will then utilize your separate K-1s to report your share of the organization’s earnings on your individual tax returns.’ If a refund was received based on the original return and the K-1 does not impact tax liability, no further action is required. However, if no refund has been issued, beneficiaries may need to file an extension while assessing the K-1’s implications.
For young parents, understanding these timelines is essential not only for navigating tax obligations but also for integrating this knowledge into their broader financial planning. By partnering with Bright Advisers, families can receive tailored wealth management solutions that empower them to optimize their tax situations and secure their financial futures. Together, we can ensure you are well-prepared for educational expenses and other long-term goals. We’re here for you on this journey.
How K-1 Income Affects Your Personal Tax Obligations
K-1 earnings are categorized as pass-through revenue, which means they are taxed at the individual level rather than at the entity level. This classification can have a significant impact on your overall tax bracket and liability, particularly for high-income families like Allison and Brian, who have faced the financial challenges of inadequate tax planning. It’s essential for beneficiaries to recognize that K-1 earnings can increase their taxable amount, potentially pushing them into a higher tax bracket. As tax regulations evolve, understanding these consequences becomes increasingly vital.
Imagine this: in 2022, the top 1 percent of taxpayers earned 22.4 percent of total adjusted gross revenue (AGI) and contributed 40.4 percent of all federal income taxes. This concentration underscores the importance of K-1 earnings for high-earning individuals, as it can significantly affect their tax responsibilities. K-1 earnings often lead to an average rise in tax liability, especially for those already in higher tax brackets. For instance, a beneficiary receiving substantial K-1 distributions may find themselves facing a tax rate that aligns with their new earnings level, which could reach as high as 33 percent for long-term capital gains, according to recent tax reforms.
Real-world examples illustrate how families like Allison and Brian manage increased tax obligations stemming from K-1 earnings. They turned to Bright Advisers for guidance to enhance their financial outcomes, employing strategies such as deferring earnings or maximizing deductions to alleviate the tax burden. By integrating professional tax planning into their financial strategy, they not only secured their children’s future but also positioned themselves for an earlier retirement.
To navigate the complexities of K-1 earnings, families should consider actionable strategies:
- Consulting with tax professionals can help identify potential deductions.
- Exploring earnings deferral options is worthwhile.
- Regularly reviewing financial plans can ensure adaptability to changing tax laws.
Understanding the nuances of pass-through earnings from K-1 tax form inheritance is crucial for beneficiaries aiming to effectively manage their tax responsibilities. As tax regulations continue to shift, staying informed about the K-1 tax form inheritance will empower families to make educated financial decisions and secure their financial futures. Together, we can navigate this journey and ensure a brighter tomorrow for our loved ones.
K-1 Income vs. Earned Income: Key Differences for Beneficiaries
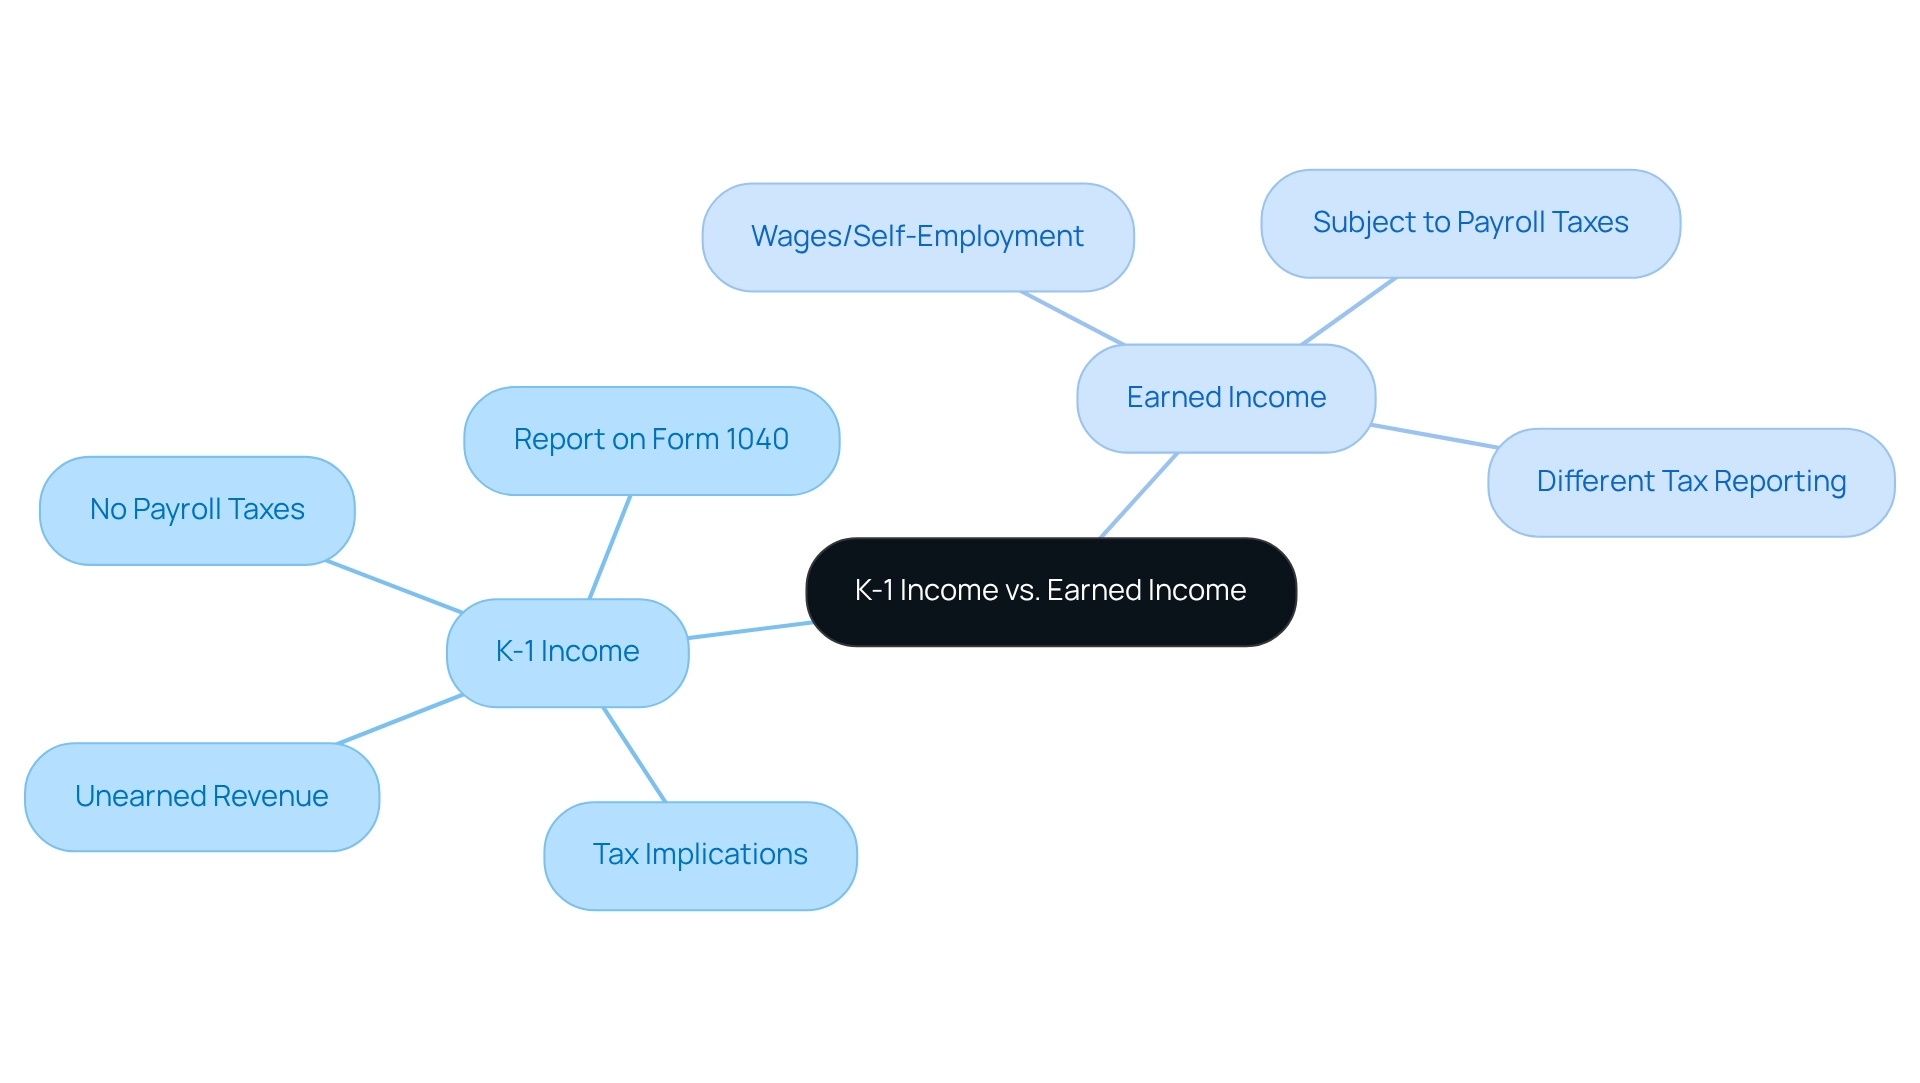
K-1 earnings are classified as unearned revenue, which contrasts sharply with earned revenue derived from wages or self-employment. This distinction is essential for you, as it affects how each type of revenue is reported and taxed. Unlike earned earnings, which are subject to payroll taxes, K-1 earnings avoid this burden, leading to different tax implications. If you are receiving K-1 earnings, it’s important to report it alongside your other earnings on Form 1040. This can significantly affect your overall tax obligation.
Imagine this: approximately 30% of families receive K-1 earnings, highlighting its importance in financial planning. Many families, like Jay and Emma, who sought advice from Bright Advisers, may not fully grasp the subtleties of K-1 earnings compared to earned wages. This lack of understanding can lead to unexpected tax implications. For instance, comprehending how K-1 earnings interact with other revenue sources or potential deductions is crucial for effective financial management. By partnering with Bright Advisers, they optimized their tax planning and crafted a customized retirement plan that addressed their unique financial needs.
It’s important to understand these differences. As one specialist noted, “Navigating the complexities of K-1 earnings requires a solid grasp of its implications on personal tax situations.” This emphasizes the value of seeking guidance from a tax expert, especially if you’re unfamiliar with the intricacies of K-1 earnings and how it impacts your overall financial well-being. By understanding the differences between K-1 and earned revenue, you can make more informed choices about your financial future, ultimately leading to greater financial stability and independence. Together, we can navigate this journey and ensure your family’s financial health is prioritized.
Key Takeaways: Essential Facts About K-1 Tax Forms for Beneficiaries
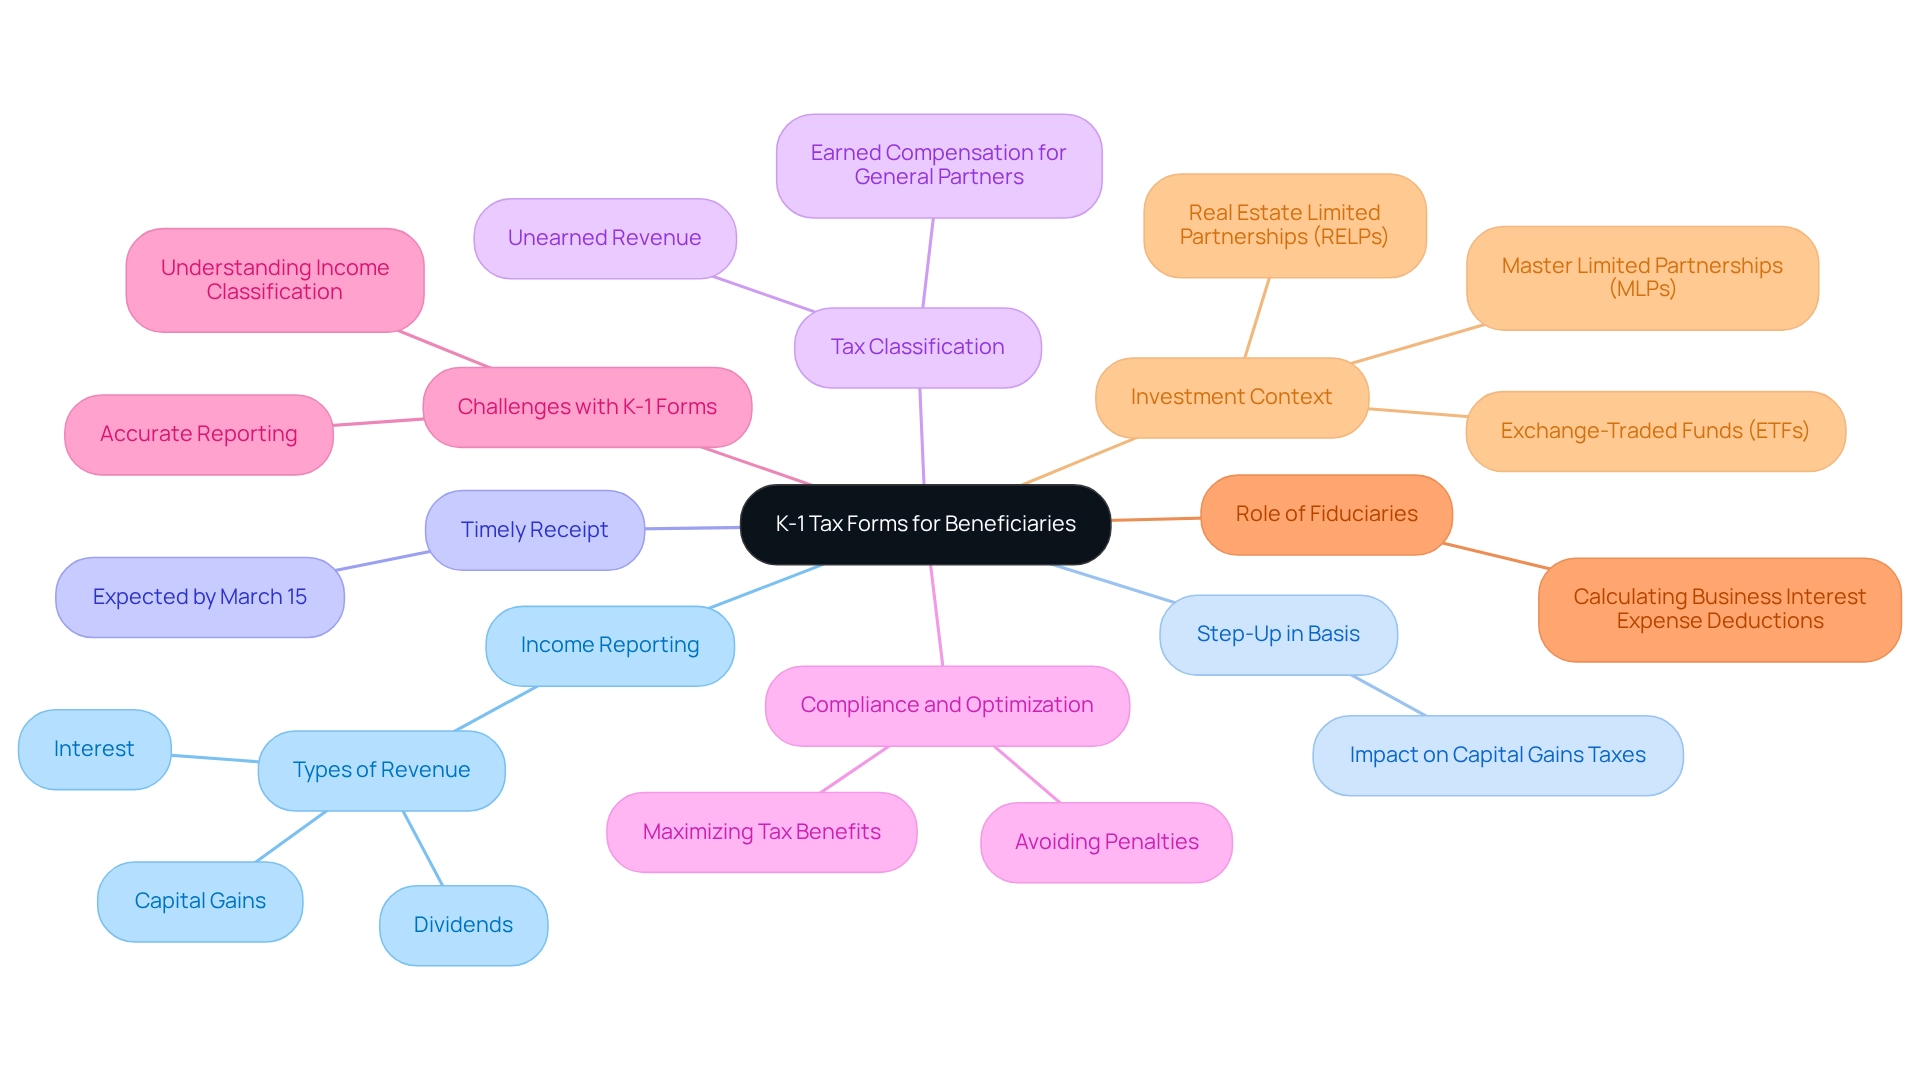
The K-1 tax form inheritance is essential for recipients, as it details a person’s share of earnings, deductions, and credits from an estate or trust. Understanding these forms is vital for effective tax planning and compliance. Let’s explore some important details together:
- Income Reporting: K-1 forms outline a recipient’s portion of earnings, which can include various types of revenue, such as dividends, interest, and capital gains. This information is crucial for accurately reporting earnings on personal tax returns, ensuring you’re on the right track.
- Step-Up in Basis: The step-up in basis can significantly impact capital gains taxes when beneficiaries sell inherited assets. This adjustment can reduce taxable gains, making it a critical factor in estate planning. Imagine the peace of mind knowing you’re making informed decisions for your family’s future.
- Timely Receipt: Beneficiaries should expect to receive their K-1 forms by March 15 each year. This timeline is important for prompt tax submission and planning, helping you stay organized and ahead of deadlines.
- Tax Classification: K-1 earnings are categorized as unearned revenue, taxed differently than earned revenue. For general partners and active owners in a business or pass-through entity, K-1 earnings may be viewed as earned compensation, potentially exposing them to self-employment tax. Grasping these distinctions is essential for navigating your tax obligations effectively.
- Compliance and Optimization: Properly understanding and filing K-1 forms is key for compliance and optimizing tax liabilities. Recipients who are well-informed can avoid potential penalties and maximize their tax benefits, ensuring your family’s financial well-being.
In addition to these key points, recipients often face challenges with K-1 forms, such as understanding the complexities of income classification and ensuring accurate reporting. For instance, fiduciaries play a crucial role in providing necessary information for calculating business interest expense deductions under section 163(j), which can further complicate the tax landscape.
Real-world examples illustrate how recipients can optimize their tax liabilities with K-1 forms. By familiarizing themselves with the intricacies of these forms, recipients can make informed decisions that enhance their financial outcomes. As noted by experts, investments like master limited partnerships (MLPs), real estate limited partnerships (RELPs), and certain exchange-traded funds (ETFs) routinely issue K-1s. Zoe Hansen emphasizes that understanding the K-1 tax form inheritance is essential for beneficiaries involved in such investments, highlighting its importance in various investment contexts. Overall, the K-1 tax form inheritance is a vital component of estate planning and tax compliance for beneficiaries. A thorough understanding can lead to significant financial advantages, and remember, we’re here for you as you navigate this journey.
Conclusion
Navigating the complexities of K-1 tax forms is essential for beneficiaries managing inherited assets. It’s important to understand the implications of these forms, from income classification to the step-up in basis, as this knowledge is crucial for optimizing your financial outcomes. By recognizing the significance of timely receipt and accurate reporting, you can avoid potential penalties and maximize your tax benefits.
The distinction between K-1 income and earned income plays a vital role in your tax planning. Remember, K-1 income, classified as unearned income, carries different tax implications than earned income, which can impact your overall tax liability. Engaging with tax professionals can enhance your understanding and compliance, ensuring your family is well-prepared to navigate these complexities together.
Ultimately, informed decision-making regarding K-1 forms can lead to substantial financial advantages. By leveraging expert guidance and proactive strategies, you can secure your financial future and effectively manage your inherited wealth. Embracing this knowledge equips you with the confidence needed to tackle your tax responsibilities and enhance your overall financial well-being. We’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is the purpose of the K-1 tax form in inheritance?
The K-1 tax form is essential for beneficiaries as it reports their share of earnings, deductions, and credits associated with an estate or trust, significantly impacting their tax responsibilities.
How are revenue distributions from trusts taxed in 2025?
Revenue distributions from trusts are taxed as regular earnings, while principal distributions remain non-taxable.
Why is it important to understand K-1 tax forms for financial planning?
Understanding K-1 tax forms is vital for accurate tax reporting and can significantly influence personal tax returns, helping individuals manage their financial responsibilities effectively.
What types of earnings can be reported on a K-1 form?
The main categories reported on a K-1 form include ordinary earnings, capital gains, and dividends. Ordinary income comes from business operations or rental activities, capital gains arise from asset sales, and dividends are allocations from corporate earnings.
What should beneficiaries do if they are unfamiliar with K-1 reporting?
Beneficiaries are encouraged to consult with a CPA or financial advisor to navigate the nuances of K-1 reporting and ensure compliance with tax regulations.
How can strategic tax planning affect financial outcomes for families?
Strategic tax planning can enhance financial outcomes by optimizing tax liabilities and securing financial futures, as illustrated by case studies like that of clients Allison and Brian.
What role does technology play in simplifying the K-1 tax form process?
Innovative technology, such as free tax return calculators, can simplify the tax filing process, making it easier for individuals to manage their tax obligations.
What is the significance of understanding the classifications of revenue on the K-1?
Understanding the classifications of revenue on the K-1 is key to effectively managing tax obligations and ensuring compliance, as different types of income can have varying tax implications.
How does the location of trusts affect tax obligations?
Trusts may have state-level tax obligations based on their location and the residency of recipients, adding complexity to tax reporting.
What resources are available for personalized guidance on K-1 tax form inheritance?
Bright Advisers offers personalized guidance and innovative investment strategies to help individuals navigate the complexities of K-1 tax form inheritance and enhance their financial planning.
List of Sources
- Bright Advisers: Expert Guidance on K-1 Tax Form Inheritance
- 1041 Distributions: Form K-1’s Role for Beneficiaries (https://ultimatetax.com/blog/understanding-1041-distributions-to-beneficiaries)
- Everything you need to know about Form K-1s in 2025 (https://taxandaccounting.com/post/everything-you-need-to-know-about-form-k-1s-in-2025)
- A Guide to Schedule K-1 (Form 1041) (https://smartasset.com/estate-planning/k-1-tax-form-inheritance)
- Understanding When the K-1 Tax Form Applies to Inherited Assets
- What is a Schedule K-1 Form 1041: Estates and Trusts? (https://turbotax.intuit.com/tax-tips/estates/what-is-a-schedule-k-1-form-1041-estates-and-trusts/L6XWJCf3c)
- A Guide to Schedule K-1 (Form 1041) (https://smartasset.com/estate-planning/k-1-tax-form-inheritance)
- What is a Schedule K-1 for Estates and Trusts | Trust & Will (https://trustandwill.com/learn/what-is-a-schedule-k-1-form?srsltid=AfmBOopgbfdQej8QvezGA2LyUccIMvC0uZQnMnaM9Izv5TKUVx7rWH5m)
- When Does the K-1 Tax Form Apply to an Inheritance? (https://accountinginsights.org/when-does-the-k-1-tax-form-apply-to-an-inheritance)
- Types of Income Reported on Schedule K-1 for Beneficiaries
- What is a Schedule K-1: A Comprehensive Guide (https://visible.vc/blog/what-is-a-schedule-k1)
- How Schedule K-1 Works for Estates and Trusts (https://k1x.io/how-schedule-k-1-works-for-estates-and-trusts)
- Schedule K-1 Federal Tax Form: What Is It and Who Is It For? (https://investopedia.com/terms/s/schedule-k-1.asp)
- Step-Up in Basis: Implications for Inherited Assets on K-1
- Understanding Step-Up in Basis for Assets Upon Inheritance (https://geigerlawoffice.com/blog/understanding-step-up-in-basis-for-assets-upon-inheritance.cfm)
- Step Up in Basis at Death: Essential Guide for Inherited Assets (https://masseyandcompanycpa.com/step-up-in-basis-at-death-essential-guide-for-inherited-assets)
- Understanding the ‘Step-Up in Basis’ When Selling Inherited Assets: Insights from Greensboro Estate Planning Attorneys – Medicaid, Asset Protection Trusts and Estate Planning Law Firm – Greensboro, NC (https://elderlawfirm.com/understanding-the-step-up-in-basis-when-selling-inherited-assets-insights-from-greensboro-estate-planning-attorneys)
- Allocating Deductions and Expenses on Schedule K-1
- irs.gov (https://irs.gov/instructions/i1041sk1)
- How to Allocate Income on Schedule K-1 for Estates and Trusts | dummies (https://dummies.com/article/business-careers-money/personal-finance/estate-planning/how-to-allocate-income-on-schedule-k-1-for-estates-and-trusts-190720)
- Form 1041 Schedule K-1: Beneficiary’s Share Snapshot (https://fincent.com/irs-tax-forms/schedule-k-1-form-1041)
- A Guide to Schedule K-1 (Form 1041) (https://smartasset.com/estate-planning/k-1-tax-form-inheritance)
- Filing Your K-1 Form with Personal Tax Returns: A Step-by-Step Guide
- Navigating Tax Time: Tips for Filing Your K-1 Form – Zajac Group (https://zajacgrp.com/insights/navigating-tax-time-tips-for-filing-your-k-1-form)
- Schedule K-1 Income Reported on 1040-SE (https://ttlc.intuit.com/community/business-taxes/discussion/schedule-k-1-income-reported-on-1040-se/01/1988583)
- Schedule K-1 Tax Form: What Business Owners Need to Know (https://lendingtree.com/business/schedule-k-1-tax-form)
- All About Schedule K-1 : Filling of Form 1065 (https://deskera.com/blog/schedule-k-1-form-1065)
- When Should You Expect to Receive Your K-1 Form?
- peoplekeep.com (https://peoplekeep.com/blog/what-is-a-schedule-k-1)
- K-1 form received late? (https://sierrapfa.com/blog/k-1-form-received-late)
- Everything you need to know about Form K-1s in 2025 (https://taxandaccounting.com/post/everything-you-need-to-know-about-form-k-1s-in-2025)
- How K-1 Income Affects Your Personal Tax Obligations
- Federal Individual Income Tax Brackets, Standard Deduction, and Personal Exemption: 1988 to 2025 (https://crsreports.congress.gov/product/pdf/RL/RL34498)
- Summary of the Latest Federal Income Tax Data, 2025 Update (https://taxfoundation.org/data/all/federal/latest-federal-income-tax-data-2025)
- K-1 Income vs. Earned Income: Key Differences for Beneficiaries
- Schedule K-1 Federal Tax Form: What Is It and Who Is It For? (https://investopedia.com/terms/s/schedule-k-1.asp)
- Guides: How to Read a K-1: For Partners, Shareholders, and Beneficiaries (https://found.com/resources/how-to-read-a-K-1)
- Schedule K-1 & Earned Income (https://ttlc.intuit.com/community/business-taxes/discussion/schedule-k-1-earned-income/00/3400055)
- Key Takeaways: Essential Facts About K-1 Tax Forms for Beneficiaries
- Schedule K-1 Federal Tax Form: What Is It and Who Is It For? (https://investopedia.com/terms/s/schedule-k-1.asp)
- irs.gov (https://irs.gov/instructions/i1041sk1)
- justvanilla.com (https://justvanilla.com/blog/schedule-k-1-forms)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading