

Key Highlights:
- MAGI is crucial for tax planning and determining eligibility for credits like the Child Tax Credit.
- Start with total income, including wages, salaries, and taxable income, to calculate MAGI.
- Adjusted Gross Income (AGI) is derived by subtracting eligible deductions from gross income.
- Common deductions include student loan interest, retirement contributions, and certain medical expenses.
- Student loan interest must be added back to AGI when calculating MAGI, potentially raising it.
- Tax-exempt interest from municipal bonds must also be included in MAGI calculations.
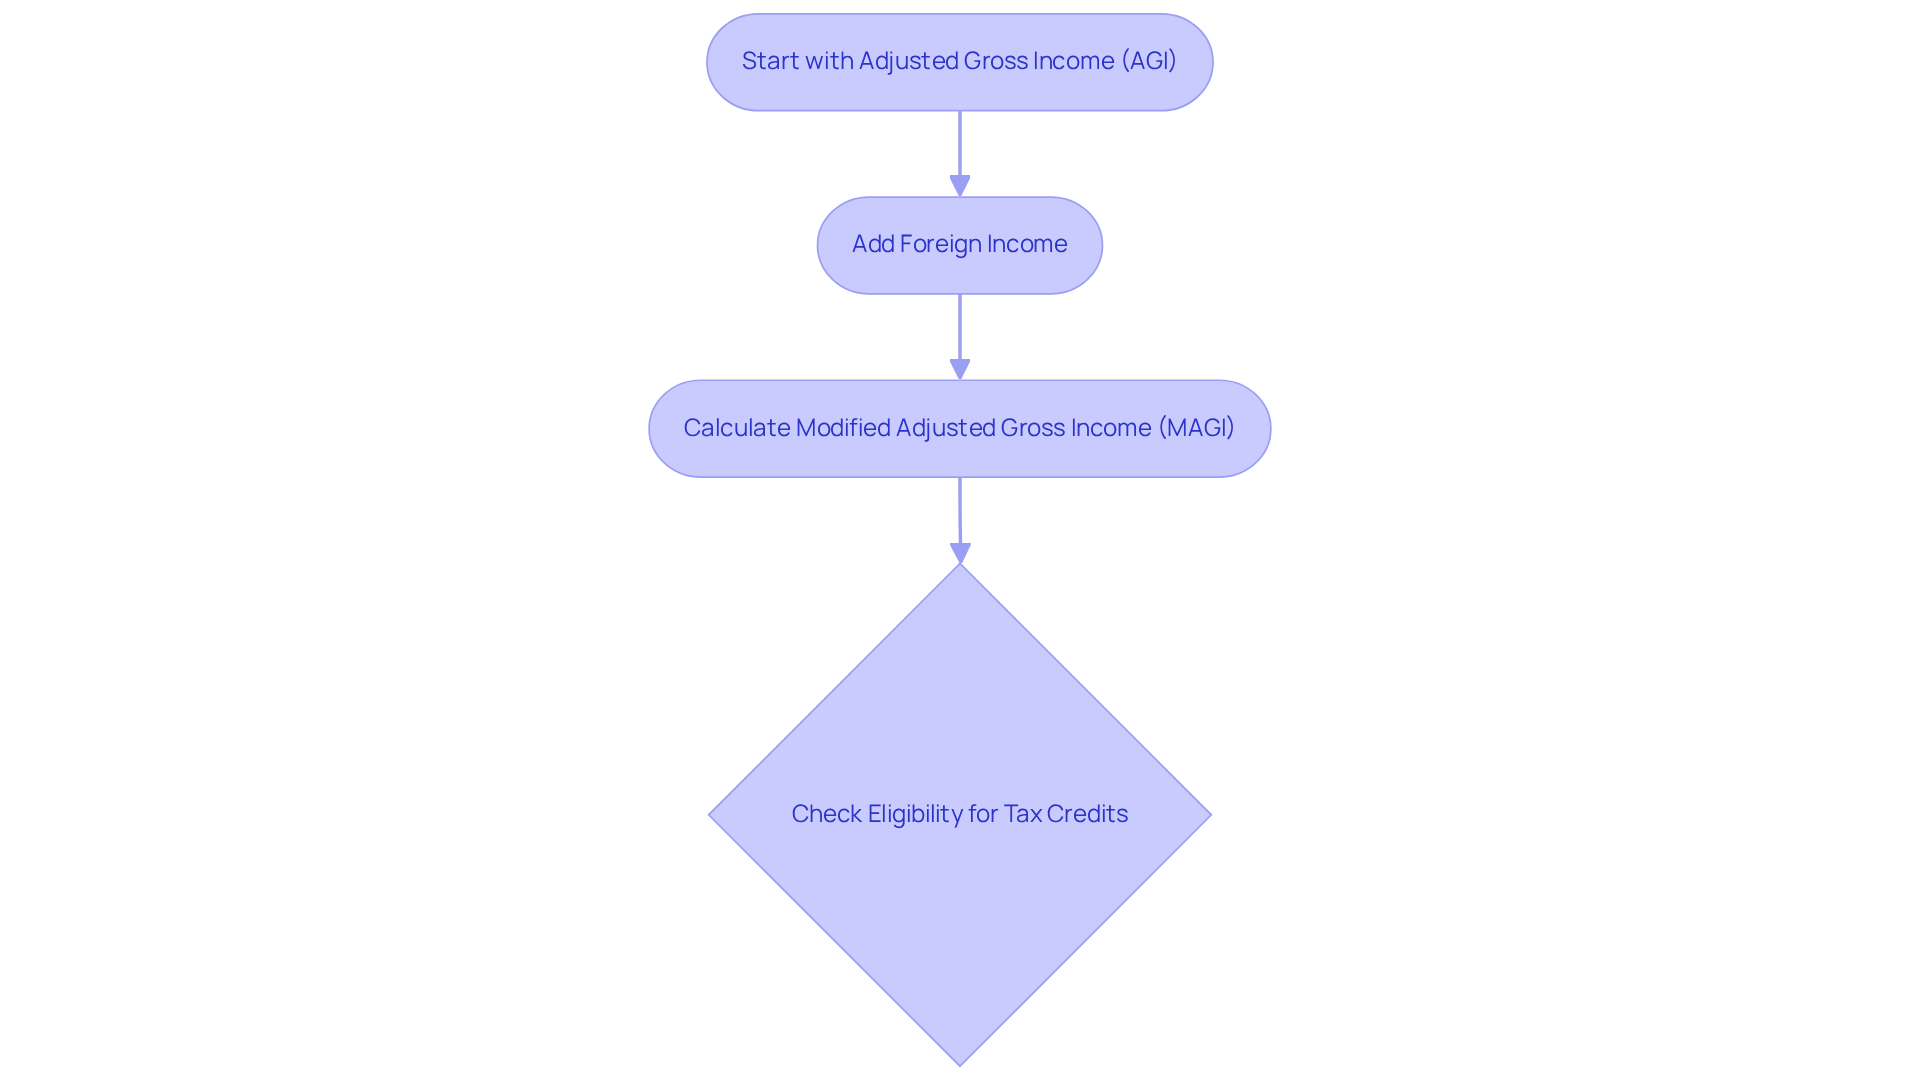
- Foreign income excluded from AGI must be added back to accurately determine MAGI.
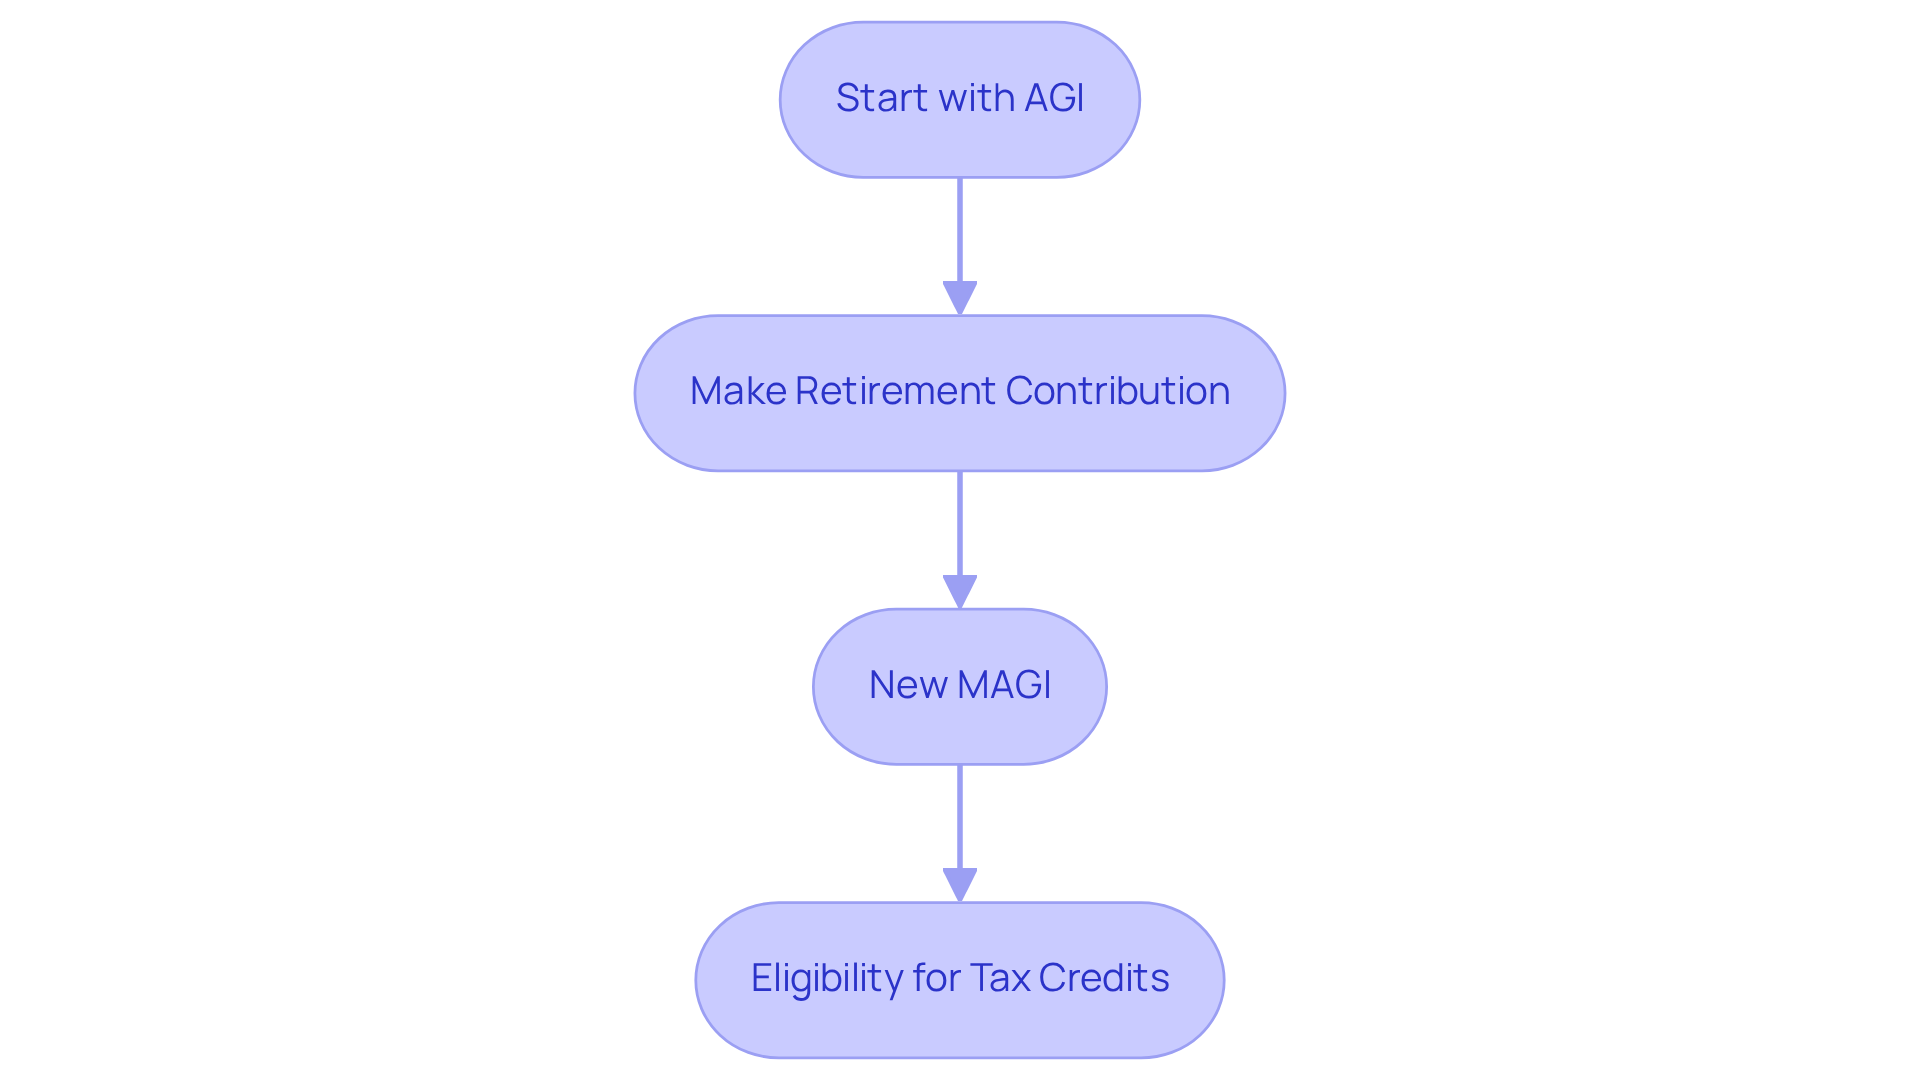
- Retirement contributions can lower AGI and MAGI, enhancing eligibility for tax credits.
- Understanding MAGI is essential for maximising tax credits and benefits, especially for families.
- Maintaining accurate financial records simplifies MAGI calculations and helps avoid common mistakes.
Introduction
Understanding the nuances of Modified Adjusted Gross Income (MAGI) is crucial for young parents looking to enhance their financial strategies. This important figure not only plays a key role in tax planning but also affects eligibility for valuable credits like the Child Tax Credit. It truly is a cornerstone of effective budgeting.
However, calculating MAGI accurately can be challenging. Families often face hurdles, from missing deductions to miscalculating income sources. Imagine if you could navigate these complexities with confidence and clarity. How can you ensure that you’re maximizing your financial benefits?
In this article, we’ll explore ten essential MAGI calculation examples that illuminate the path forward for young parents. Together, we can navigate this journey, helping you feel more secure and informed about your financial future.
Calculate MAGI Using Your Total Income
Understanding your (MAGI) is a vital step in your financial journey. Start with your total earnings – this includes wages, salaries, tips, and any other taxable income. This figure serves as the foundation for calculating your MAGI, which plays a crucial role in tax planning and determining eligibility for credits like the Child Tax Credit.
Imagine if your total income is $80,000. This is just the beginning of your [MAGI calculation example](https://brightadvisers.com/calculate-your-magi-estimator-a-step-by-step-guide-for-families). For young families, grasping your MAGI can significantly influence your financial strategies. By accurately determining your MAGI, you can improve your tax situation, ensuring you’re making the most of available credits and deductions.
This proactive approach not only helps you manage your current financial responsibilities but also sets a strong foundation for your family’s future educational needs and long-term financial security. Think about families like Jay and Emma or Emily and Mark, who have benefited from tailored strategies developed through Bright Advisers.
We’re here for you, ready to help you navigate this journey together. Understanding your MAGI calculation example is an important step towards a brighter financial future for you and your loved ones.

Adjust Your Gross Income for MAGI Calculation
Understanding your can feel overwhelming, but it’s a crucial step in managing your family’s finances. Start with your Adjusted Gross Income (AGI) from your tax return. This number comes from subtracting eligible deductions from your gross income. As young parents, you might find common deductions like:
- student loan interest
- retirement contributions
- certain medical expenses
particularly helpful.
Imagine this: your AGI is $70,000, and you have $2,000 in student loan interest. By factoring in that deduction, your modified adjusted gross income drops to $68,000. It’s important to understand how these changes can impact your budgeting. They can significantly affect your eligibility for various tax credits and benefits, including the Child Tax Credit, which phases out entirely at a modified adjusted gross income of $240,000 for single filers.
By maximizing your deductions, you can lower your adjusted gross income and potentially increase your tax savings. At Bright Advisers, we’re here for you. Our team of consultants is dedicated to helping you create a financial plan that aligns with your values and vision. Together, we can ensure that your income calculations and overall financial strategies, including investment management and tax-loss harvesting, support your family’s objectives. Let’s navigate this journey together.

Include Student Loan Interest in Your MAGI
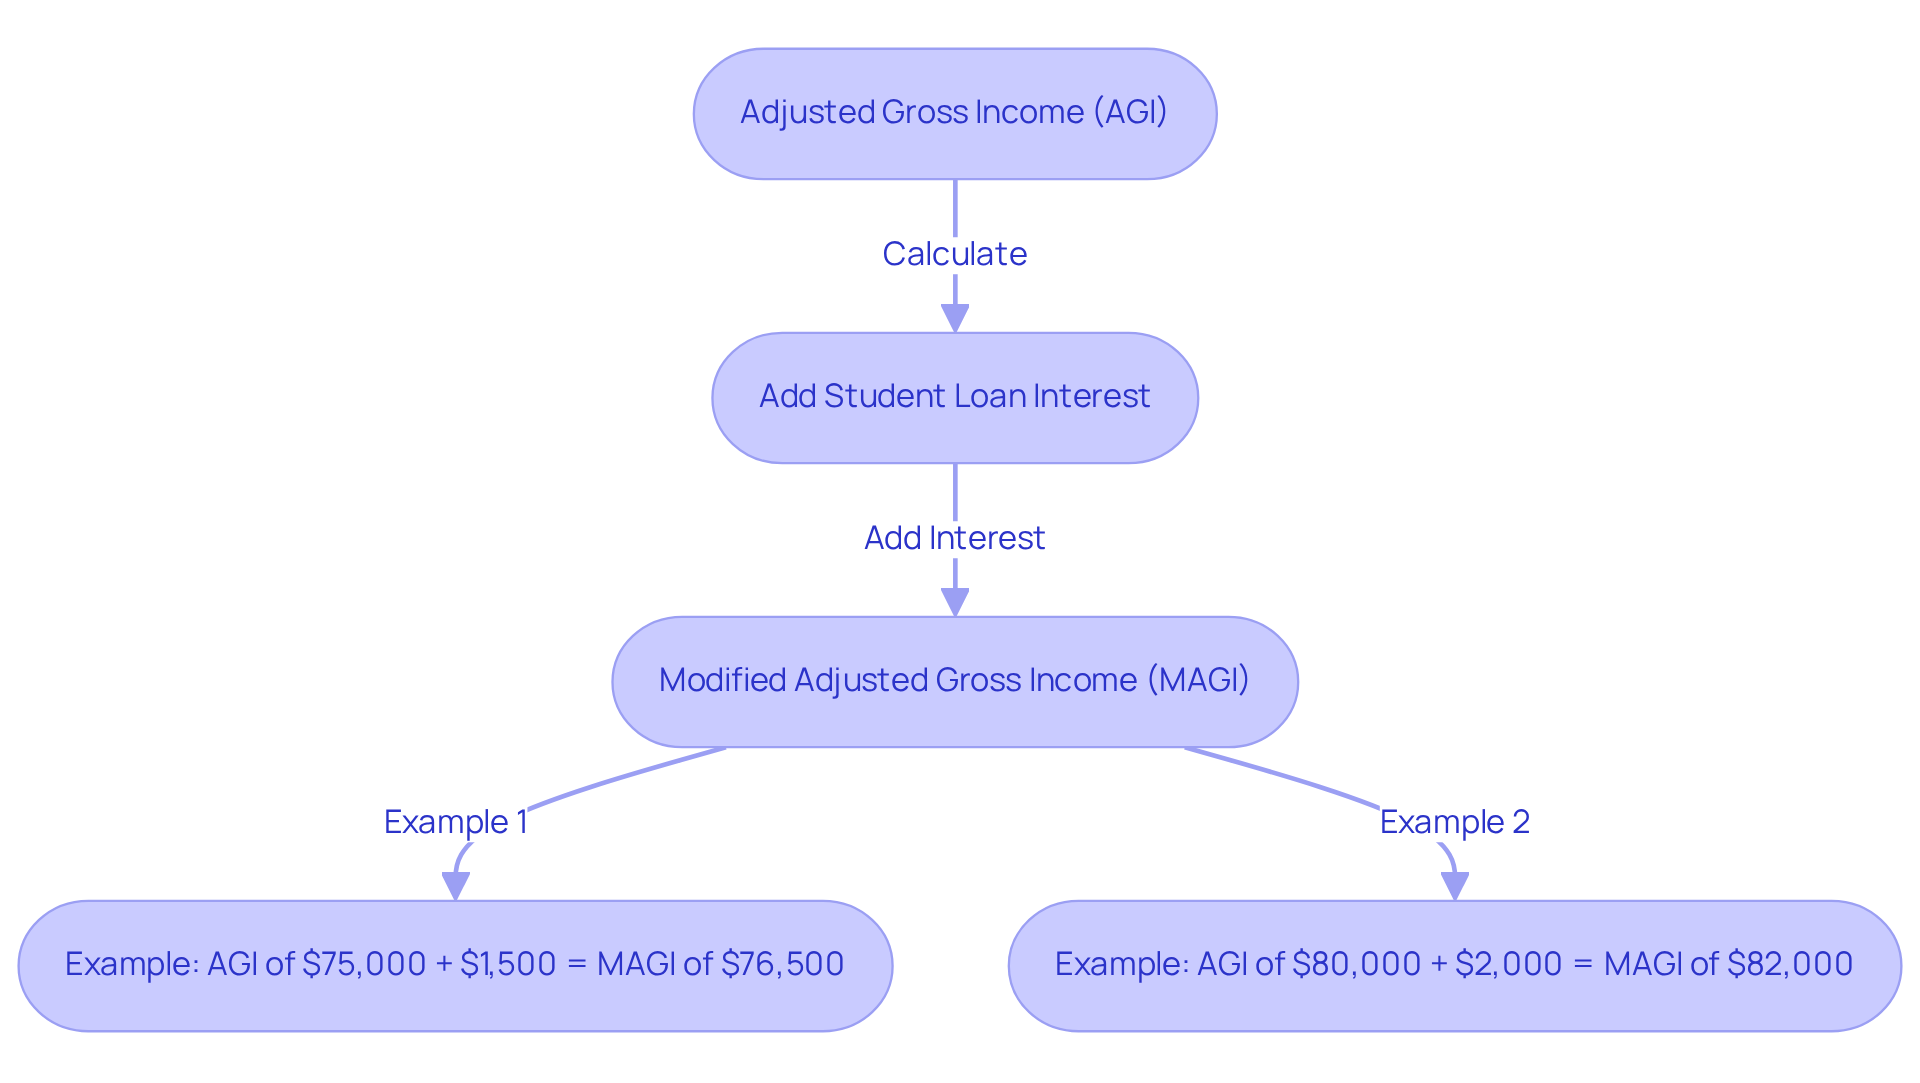
When figuring out your Modified Adjusted Gross Income, it’s important to remember to include any you paid during the year. This interest gets added back to your Adjusted Gross Income (AGI), which could raise your total Modified Adjusted Gross Income. For example, if your AGI is $75,000 and you paid $1,500 in student loan interest, your modified adjusted gross income would go up to $76,500 after this addition.
Families with children, like Emily and Mark, who work with Bright Advisers, often find themselves paying significant amounts in student loan interest. This can really impact their financial planning and tax obligations. As we look ahead to 2026, understanding how student loan interest affects modified adjusted gross income calculations, such as in a MAGI calculation example, remains vital, especially since income thresholds for various tax benefits are closely tied to these figures. Financial specialists emphasize that knowing how to factor in student loan interest is key to maximizing tax savings and ensuring eligibility for credits and deductions.
Imagine a young parent with an AGI of $80,000 who pays $2,000 in student loan interest. Their modified adjusted gross income would rise to $82,000. This increase could influence their eligibility for certain tax credits, like the American Opportunity Tax Credit, which starts to phase out at a MAGI of $80,000 for single filers. Keeping organized records of loan payments and interest statements is essential for accurately claiming these deductions and improving financial outcomes.
Moreover, families with children typically face an average of $2,500 in student loan interest, which emphasizes the importance of understanding these calculations, including a MAGI calculation example, in relation to their overall financial health and journey toward economic independence. Bright Advisers helped Emily and Mark with personalized strategies to manage their student loan interest effectively, ensuring they can maximize their financial potential. Together, we can navigate this journey and make informed decisions that benefit your family.
Consider Tax-Exempt Interest in Your MAGI
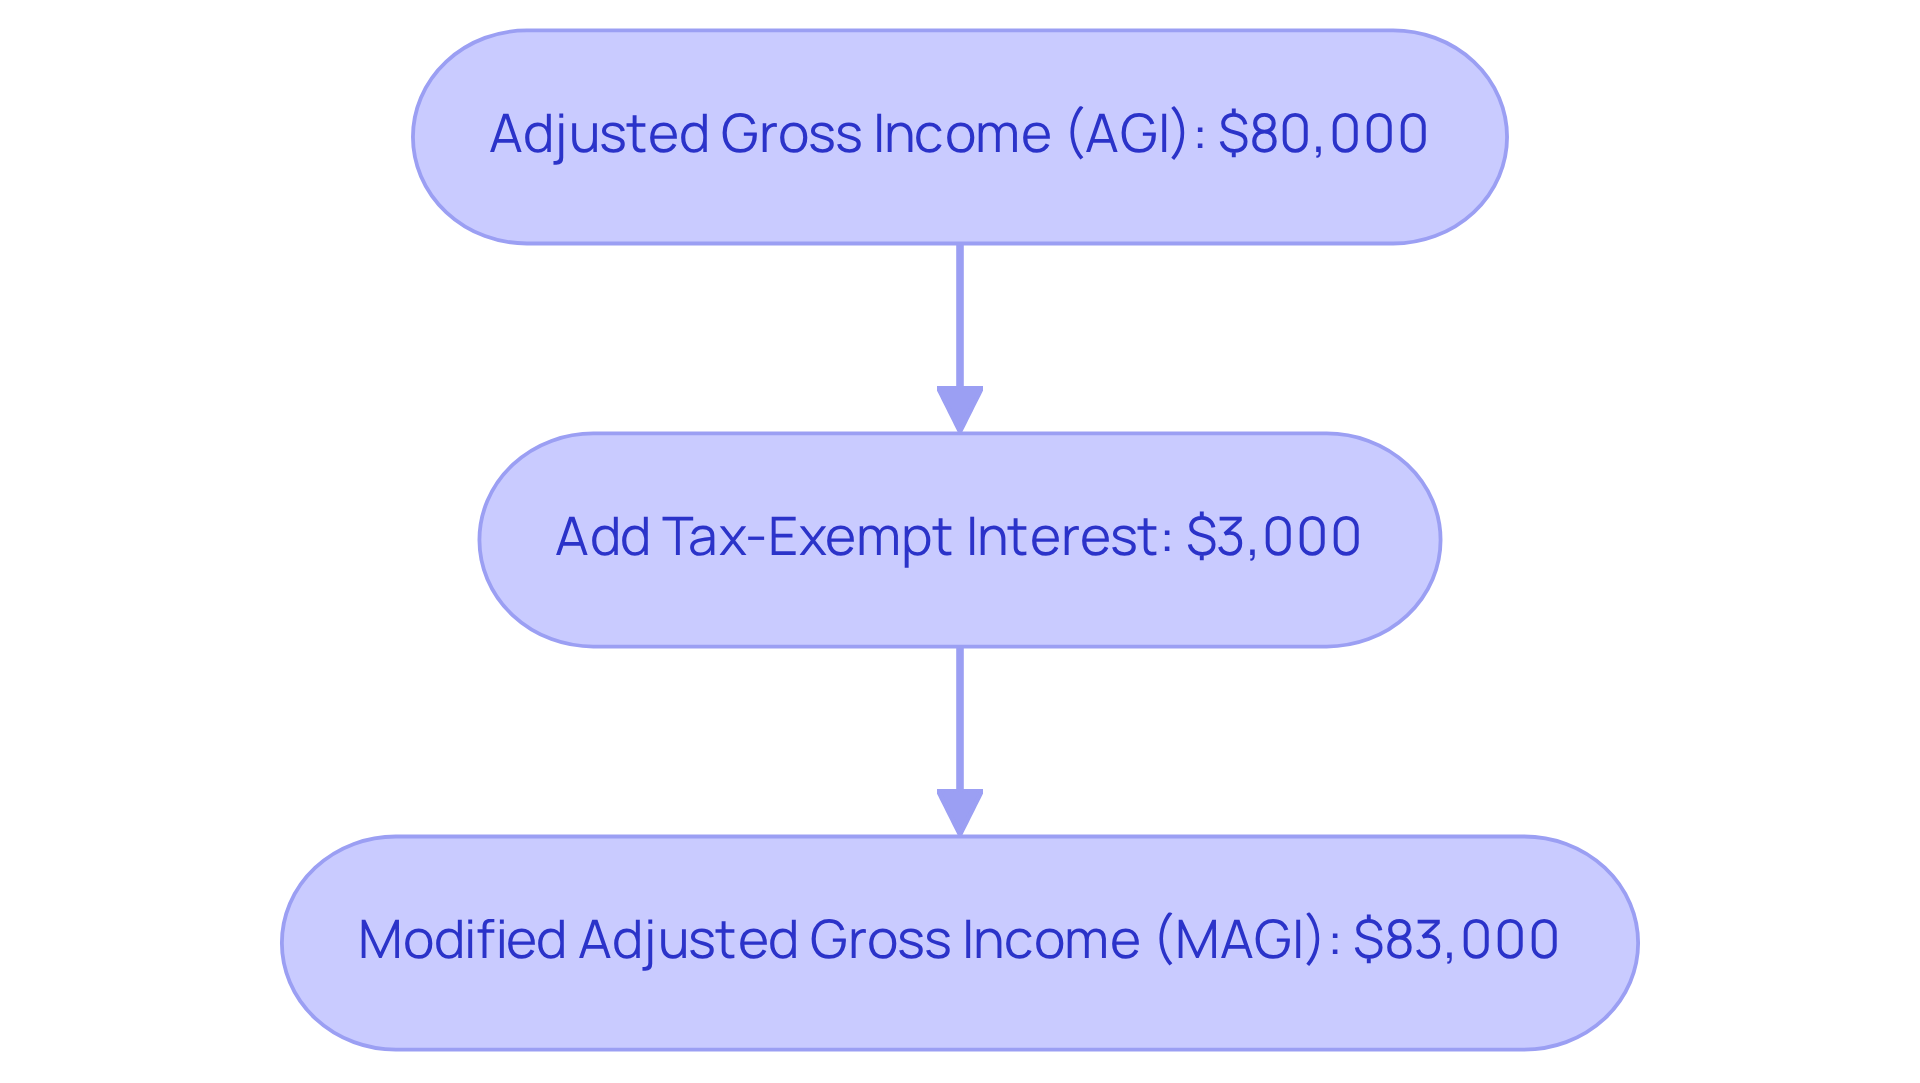
Understanding your finances can feel overwhelming, especially when it comes to tax-exempt interest from municipal bonds. Imagine if you earned $3,000 in tax-exempt interest. It’s important to know that this amount must be included again in your adjusted gross income (AGI) when determining your modified adjusted gross income (MAGI).
So, let’s say your AGI was $80,000. By adding that $3,000 in tax-exempt interest, you can see in the [MAGI calculation example](https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/magi-modified-adjusted-gross-income) that your MAGI would then be $83,000. This might seem like just numbers, but it’s crucial for your financial planning, especially as you navigate the responsibilities of family life.
We’re here for you, helping you understand these details so you can make that benefit your family. Together, we can navigate this journey and ensure your financial future is secure.
Factor in Foreign Income for Accurate MAGI
When it comes to figuring out your , it’s crucial to include any foreign earnings. This can really affect your financial situation. If you have foreign income that’s excluded from your Adjusted Gross Income (AGI), you’ll need to add it back in to get an accurate picture of your Modified Adjusted Gross Income. For instance, if your AGI is $90,000 and you earn $10,000 from abroad, this scenario serves as a MAGI calculation example, showing how your modified adjusted gross income would jump to $100,000 once you factor in that amount.
In 2026, understanding how foreign income impacts your modified adjusted gross income is especially important for young parents. This knowledge can affect your eligibility for various tax credits and deductions. Financial advisors often recommend that families take these adjustments into account when planning their taxes. Imagine a household reporting an average foreign income of $15,000; this could elevate their modified adjusted gross income from $85,000 to $100,000. Such a change might influence their eligibility for benefits like the Child Tax Credit, which begins to phase out at a modified adjusted gross income of $200,000 for joint filers.
By accurately including foreign income, families can navigate their tax responsibilities more effectively and maximize the benefits available to them. This way, you can make informed financial decisions that align with your long-term goals. Remember, we’re here for you, and together, we can navigate this journey.
Account for Retirement Contributions in Your MAGI
Retirement contributions, like those made to a 401(k) or IRA, are essential for lowering your Adjusted Gross Income (AGI) and Modified Adjusted Gross Income. Imagine if your AGI is $85,000, and you decide to use a magi calculation example to add $5,000 to your 401(k). Just like that, your modified adjusted gross income drops to $80,000! This reduction can be a game-changer, enhancing your eligibility for valuable tax credits, such as the Child Tax Credit, which starts to phase out at an AGI of $200,000 for individual filers.
Understanding how retirement savings is crucial for families looking to strengthen their financial plans and ease worries about future expenses. Take young families like Jay and Emma, for instance. They’re eager to allocate resources wisely for both retirement and their children’s education. If a young parent has an AGI of $73,000 and contributes $7,000 to an IRA, this scenario serves as a magi calculation example, as their modified adjusted gross income adjusts accordingly, potentially opening the door to additional tax benefits.
It’s important to understand that the effect of retirement contributions on modified adjusted gross income can vary based on your filing status and income levels. For married couples filing jointly, the ability to deduct contributions to traditional IRAs begins to diminish at a modified adjusted gross income of $240,000. Therefore, maximizing contributions to retirement accounts is a smart strategy for families aiming to secure their financial future while navigating the complexities of tax regulations.
Together, we can navigate this journey toward financial stability. We’re here for you, ready to support you in making the most of your retirement contributions and ensuring a brighter future for your family.
Understand MAGI’s Role in Tax Credit Eligibility
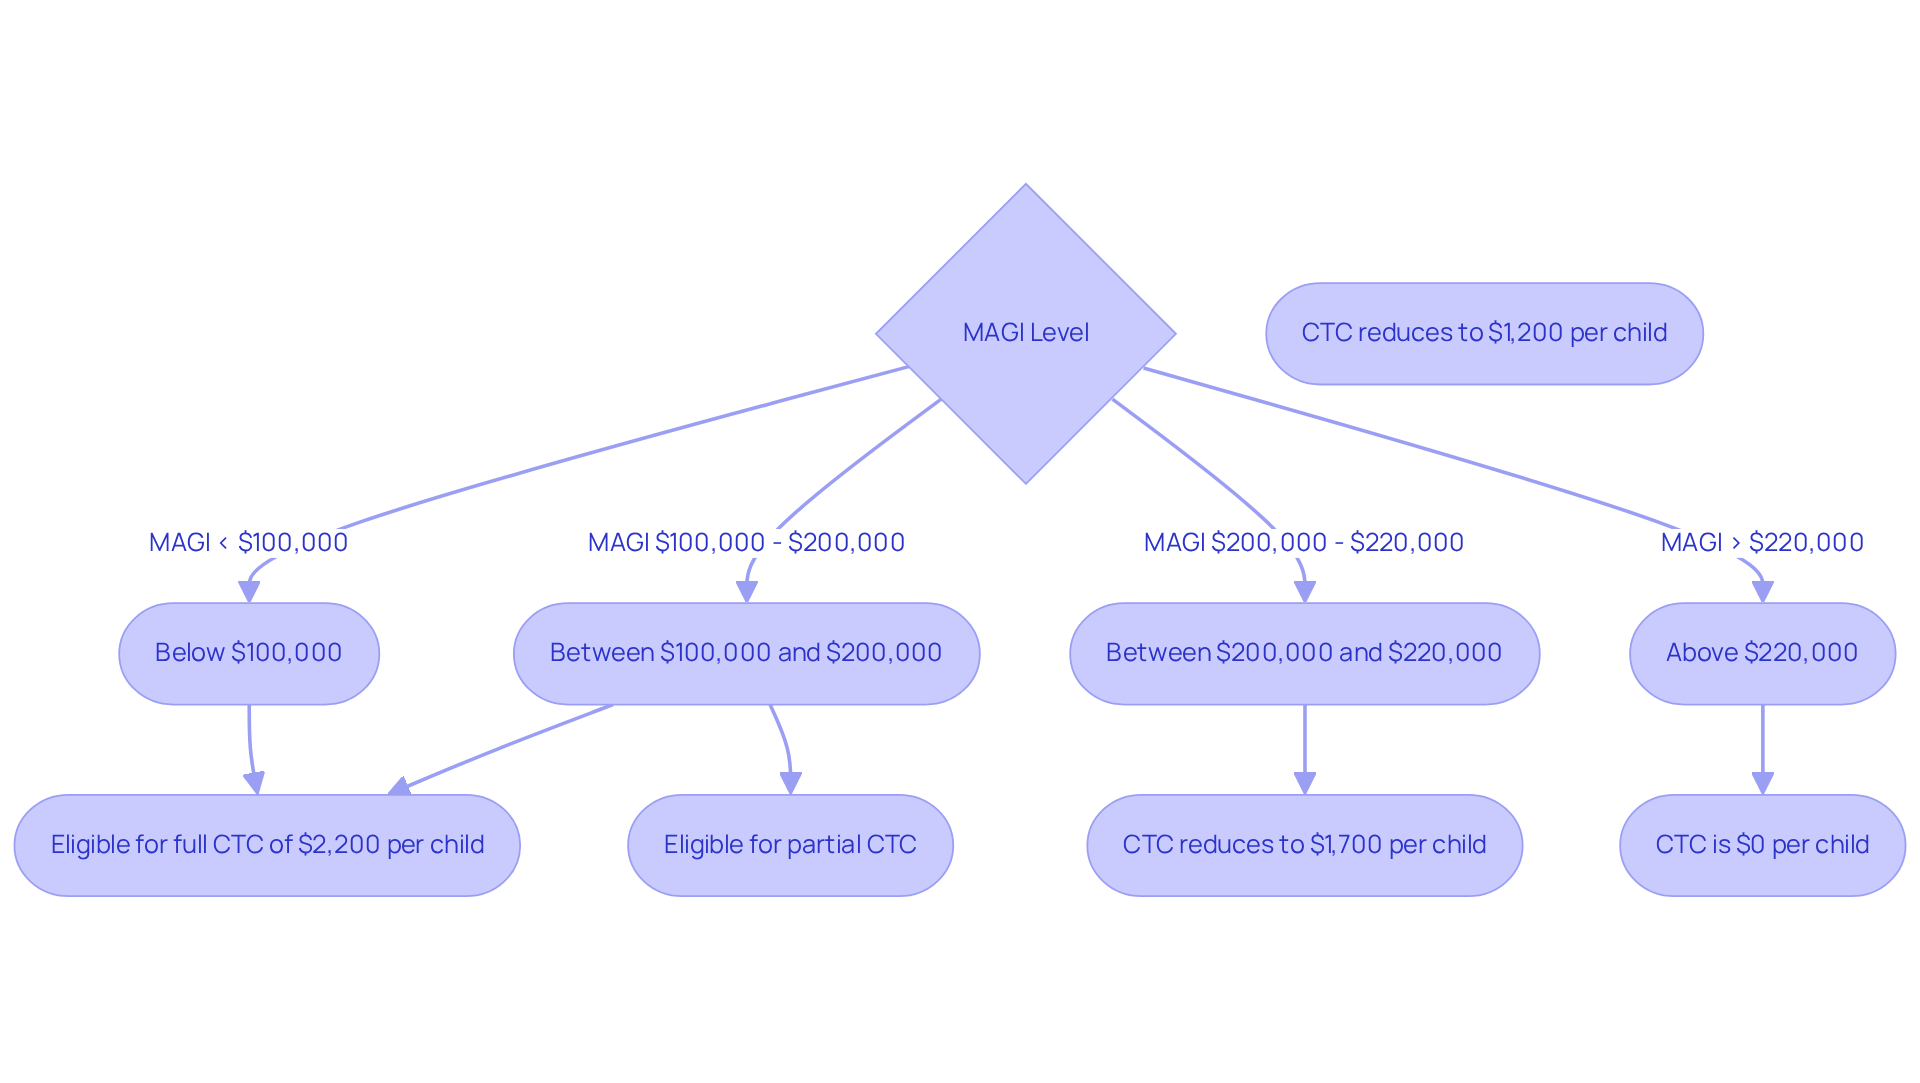
Understanding the is essential for young parents navigating the complexities of tax credits, especially the Child Tax Credit and education-related benefits. Imagine if your MAGI exceeds $200,000; your eligibility for the full Child Tax Credit starts to decrease. For every $1,000 above this limit, your credit reduces by $50. This means that a household with an adjusted gross income of $210,000 might qualify for a CTC of $1,700 per child, while those at $220,000 could see their credit drop to $1,200 per child.
It’s important to grasp how MAGI affects your financial planning. For instance, a family with an AGI of $90,000, including $3,000 in tax-exempt interest, would have an adjusted gross income of $93,000. This could make them eligible for significant healthcare subsidies under the Affordable Care Act, provided their earnings remain below certain thresholds.
Financial advisors emphasize the importance of using a magi calculation example to keep track of your modified adjusted gross income and maximize tax credits. For the 2026 tax year, individual filers need to keep their MAGI below $150,000 to qualify for full Roth IRA contributions. This highlights the need for strategic resource management. Did you know that households earning under $100,000 may qualify for substantial tax credits, including the CTC, which can provide up to $2,200 per eligible child?
By understanding how MAGI influences tax credit eligibility, families can make informed decisions that enhance their economic security. Together, we can navigate this journey, just like the hypothetical clients of Bright Advisers, who have successfully optimized their financial planning with a focus on tax benefits and education funding. Remember, we’re here for you, ready to support you every step of the way.
Example: Calculate MAGI with Multiple Income Sources
Imagine a family navigating their finances with various income sources:
- $60,000 from wages
- $5,000 from freelance work
- $2,000 in tax-exempt interest
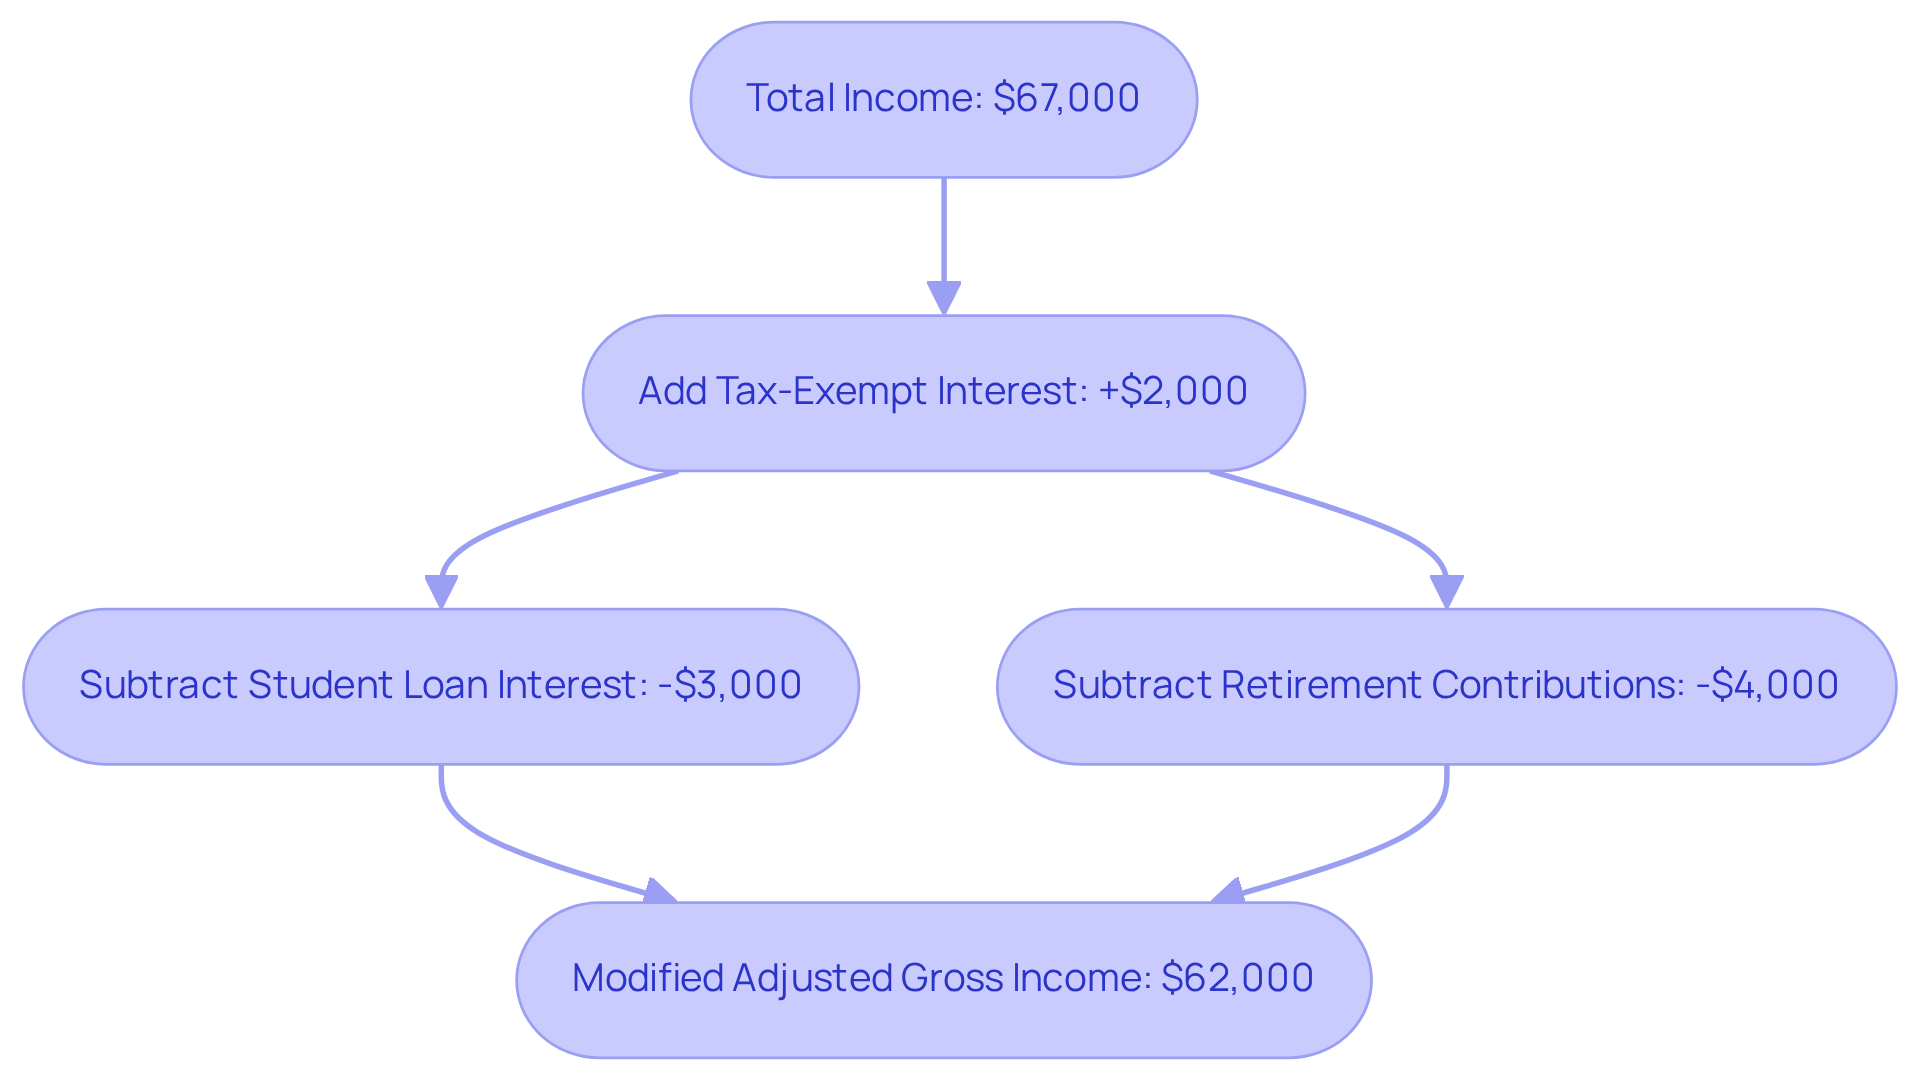
Their total income adds up to $67,000. To determine their Modified Adjusted Gross Income, we start with this total and adjust for specific deductions, as illustrated in a MAGI calculation example. If they have $3,000 in student loan interest and contribute $4,000 to a retirement account, the calculation looks like this:
$67,000 (total income) + $2,000 (tax-exempt interest) – $3,000 (student loan interest) – $4,000 (retirement contributions) = $62,000.
It’s important to understand that single taxpayers with an adjusted gross income over $100,000 can’t claim a student loan interest deduction, which might impact their overall tax situation. Additionally, increasing contributions to retirement accounts is a smart way to lower modified adjusted gross income, aligning with effective financial planning for families.
This MAGI calculation example highlights how families with diverse income sources can effectively manage their income calculations, ensuring they understand how different deductions affect their budgeting. Just like Jay and Emma, Emily and Mark, and Allison and Brian have worked with Bright Advisers to improve their financial situations, young parents can also benefit from personalized wealth management strategies that empower them to achieve economic security and freedom.
Bright Advisers offers tailored planning services focused on tax optimization and strategic investment, helping families like yours navigate the complexities of income calculations and enhance their overall financial health. We’re here for you, ready to .
Maintain Accurate Records for MAGI Calculations
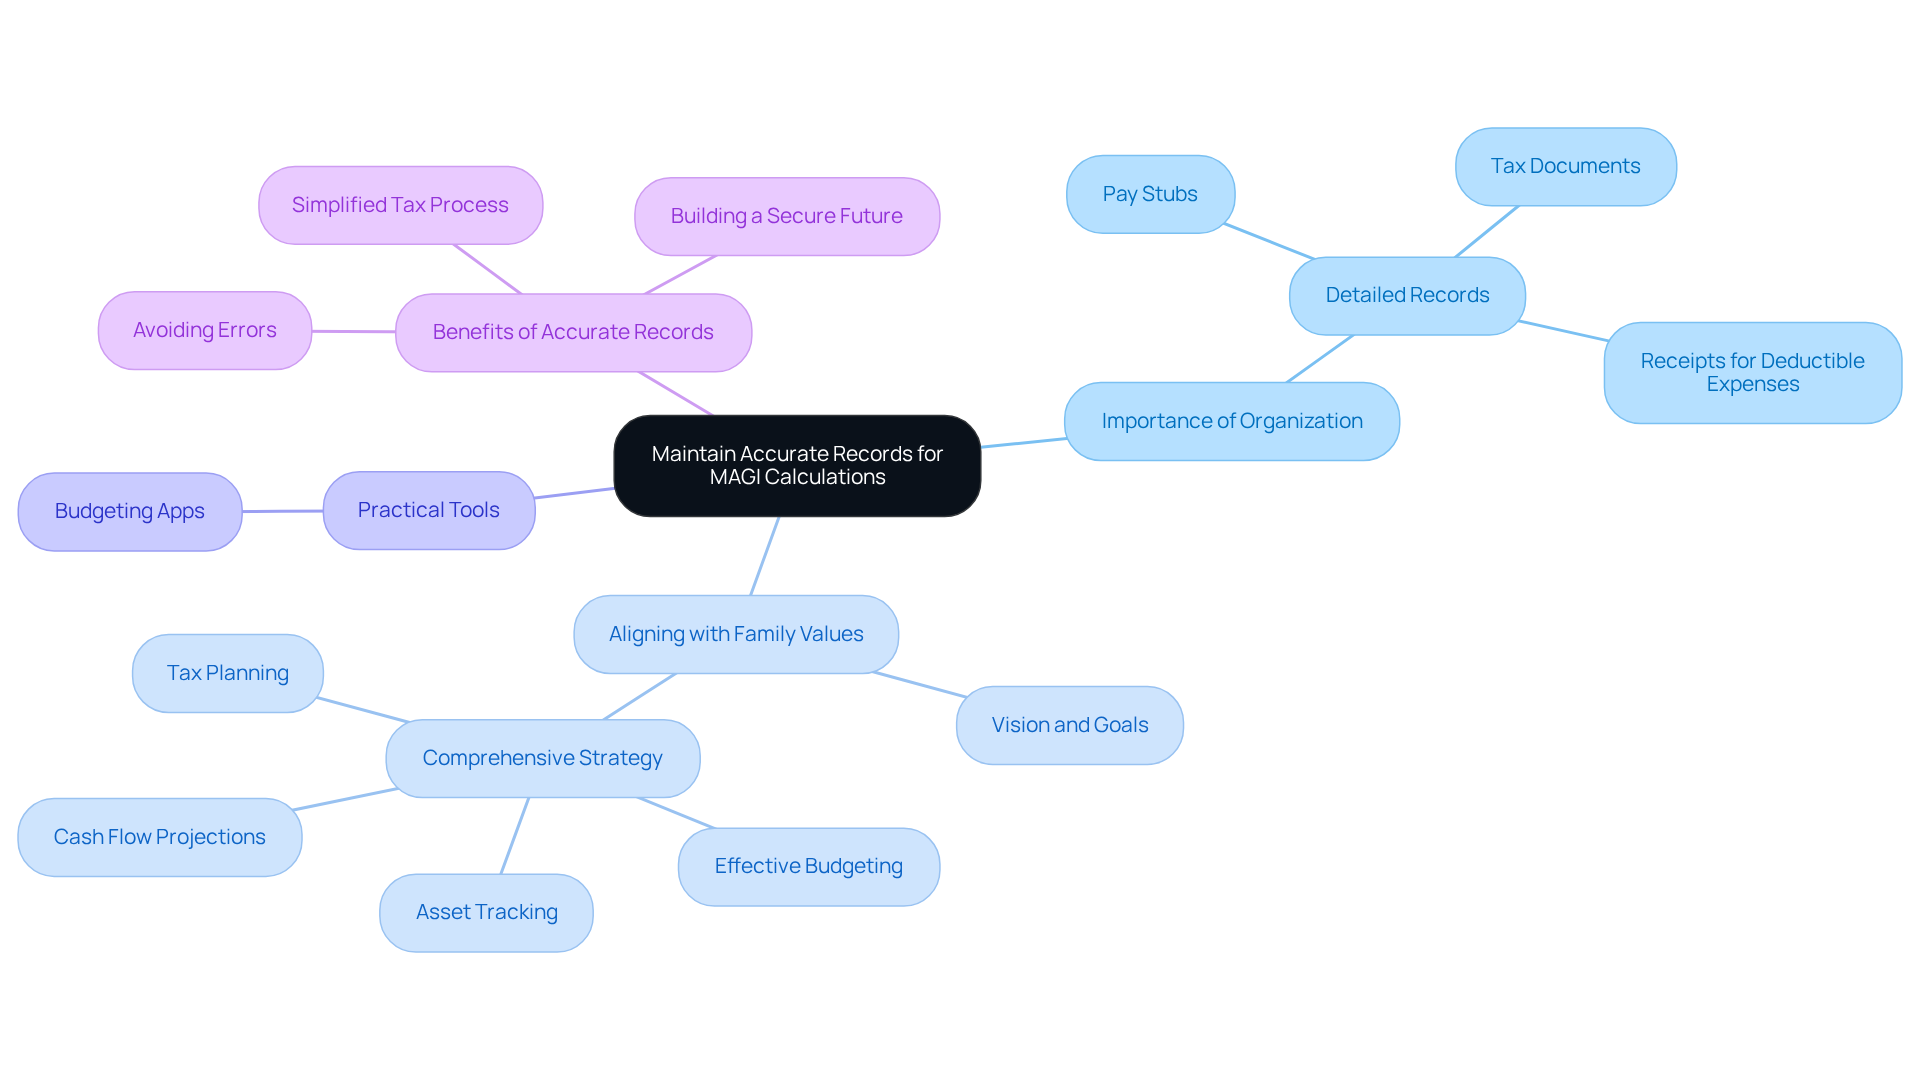
Keeping track of your family’s finances can feel overwhelming, but it doesn’t have to be. To ensure precise calculations of your modified adjusted gross income, referring to a MAGI calculation example highlights the importance of maintaining detailed records of all income sources, deductions, and adjustments. Think about your pay stubs, tax documents, and receipts for deductible expenses. By keeping everything organized, you’ll simplify the process during tax season and help avoid any errors that could impact your MAGI.
Imagine if you could align your financial record-keeping with your family’s values, vision, and goals. This approach can help you create a comprehensive strategy that supports effective budgeting, asset tracking, cash flow projections, and tax planning. It’s not just about numbers; it’s about building a secure future for your loved ones.
For practical implementation, consider using a dedicated budgeting app. These tools can make tracking your expenses and income much easier, allowing you to manage your household’s monetary future with confidence. Remember, we’re here for you every step of the way. Together, we can .
Avoid Common Mistakes in MAGI Calculation
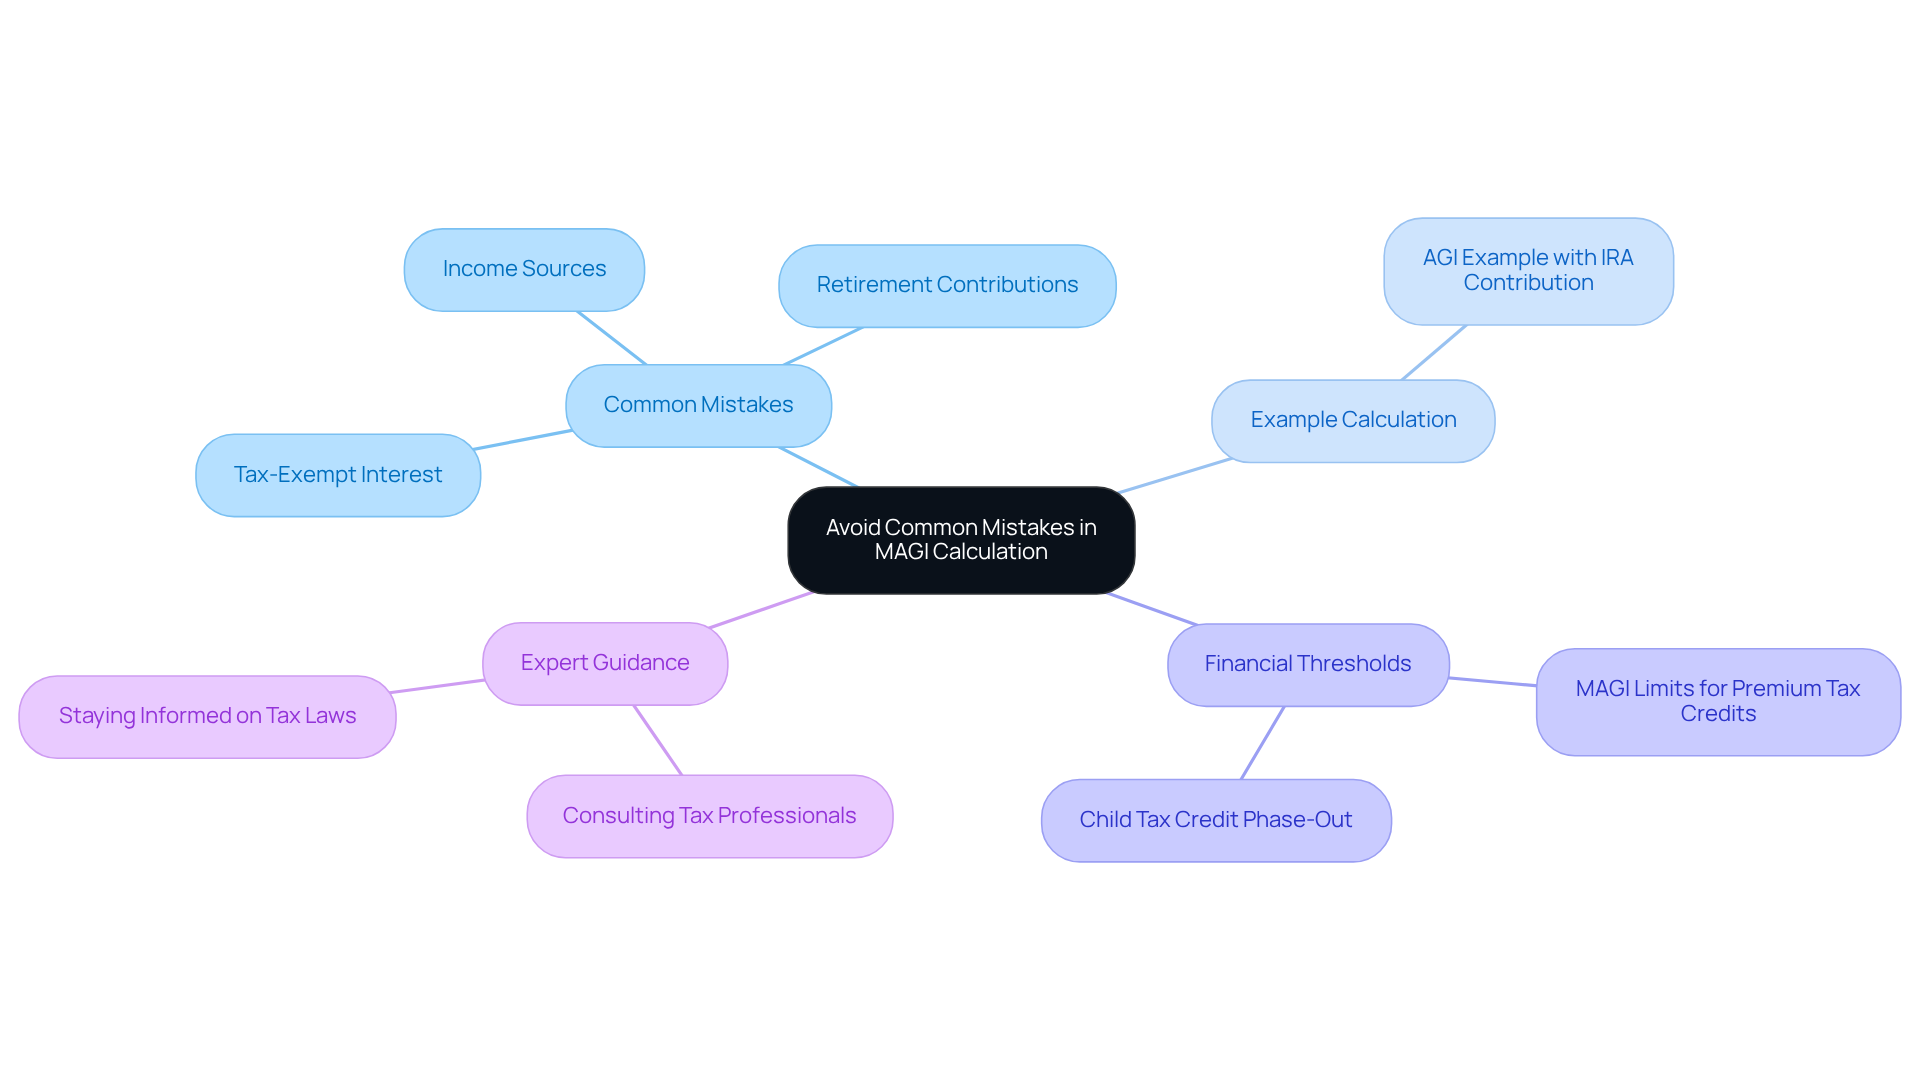
Avoiding common pitfalls in a MAGI calculation example is crucial for young families aiming for financial success. Picture this: you’re working hard to provide for your loved ones, but a simple mistake could cost you. Many families overlook adding back tax-exempt interest, miscalculate retirement contributions, or forget to include all income sources, like freelance work or rental income.
For example, imagine a household with an Adjusted Gross Income (AGI) of $70,000 that misses a $6,000 Traditional IRA contribution. They might mistakenly think their MAGI is $70,000, when in reality, it should be $81,000. To avoid such errors, it’s vital to [double-check your calculations](https://brightadvisers.com/?p=12694) and refer to a MAGI calculation example to ensure every income source is accounted for.
Seeking guidance from a tax expert, like those at Bright Advisers, can provide valuable insights. They can help you navigate the complexities of MAGI, ensuring you qualify for all available tax credits and benefits. Many families have reported saving an average of $2,500 in student loan interest reductions, which can significantly lower their MAGI.
By staying informed and diligent, you can unlock substantial financial advantages that enhance your family’s stability. Remember, monitoring your MAGI throughout the year is key to maintaining eligibility for tax benefits. In 2025, the MAGI limit for married couples filing jointly to qualify for premium tax credits was set at $400,000, while the threshold for the Child Tax Credit begins to phase out at $200,000.
Understanding these thresholds and effectively managing your finances with a can position your family for financial success. Just like the clients of Bright Advisers, who have optimized their financial strategies, you too can take control of your financial journey. Together, we can navigate this path and ensure a brighter future for your family.
Conclusion
Understanding how to accurately calculate Modified Adjusted Gross Income (MAGI) is essential for young parents looking to optimize their financial health. Imagine if you could navigate tax planning with confidence, maximizing available credits and aligning your financial strategies with your family’s long-term goals. This knowledge becomes a powerful tool, ensuring that you not only meet your current financial obligations but also secure a brighter future for your children.
Throughout this article, we explored key aspects of MAGI calculation, including the importance of:
- Total income
- Adjustments for student loan interest
- Tax-exempt interest
- Retirement contributions
Each example illustrated how these factors contribute to determining eligibility for significant tax credits, such as the Child Tax Credit and education-related benefits. We also provided practical tips on maintaining accurate records and avoiding common mistakes that could lead to financial disadvantages.
Ultimately, staying informed about MAGI and its implications can empower you to make strategic financial decisions. As you navigate the complexities of income calculations and tax regulations, remember that seeking guidance from financial experts can enhance your understanding and ability to optimize your financial outcomes. Together, we can navigate this journey. By taking proactive steps today, you can build a secure foundation for your future, ensuring you are well-prepared to meet both current needs and long-term aspirations.
Frequently Asked Questions
What is Modified Adjusted Gross Income (MAGI)?
Modified Adjusted Gross Income (MAGI) is a financial figure that plays a crucial role in tax planning and determining eligibility for various tax credits, including the Child Tax Credit.
How do I calculate my MAGI?
To calculate your MAGI, start with your total income, which includes wages, salaries, tips, and other taxable income. This figure serves as the foundation for your MAGI calculation.
Why is understanding MAGI important for families?
Understanding MAGI is important for families as it can significantly influence financial strategies, tax situations, and eligibility for credits and deductions, thereby impacting long-term financial security and educational needs.
What is Adjusted Gross Income (AGI) and how does it relate to MAGI?
Adjusted Gross Income (AGI) is the income figure obtained after subtracting eligible deductions from your gross income. AGI is the starting point for calculating MAGI, as certain adjustments, such as adding back student loan interest, are made to arrive at the MAGI.
What common deductions can affect my AGI?
Common deductions that can affect your AGI include student loan interest, retirement contributions, and certain medical expenses.
How does student loan interest affect MAGI?
Student loan interest paid during the year must be added back to your AGI when calculating MAGI, which can increase your total MAGI and potentially affect your eligibility for tax credits.
Can you provide an example of how to calculate MAGI with student loan interest?
For instance, if your AGI is $75,000 and you paid $1,500 in student loan interest, your MAGI would increase to $76,500 after including the interest.
What is the significance of MAGI thresholds for tax credits?
MAGI thresholds are important because they determine eligibility for various tax credits. For example, the Child Tax Credit phases out entirely at a MAGI of $240,000 for single filers.
How can families maximize their tax savings related to MAGI?
Families can maximize their tax savings by accurately calculating their AGI, taking advantage of eligible deductions, and understanding how these deductions influence their MAGI, which can affect their eligibility for tax credits.
How can Bright Advisers assist families in managing their financial strategies?
Bright Advisers offers personalized strategies to help families manage their financial situations, including understanding MAGI calculations, maximizing deductions, and creating a financial plan that aligns with their values and goals.
List of Sources
- Calculate MAGI Using Your Total Income
- Modified Adjusted Gross Income (MAGI): How To Calculate It | Bankrate (https://bankrate.com/taxes/modified-adjusted-gross-income-magi-what-it-is-why-it-matters-and-how-to-calculate-it)
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/taxes/learn/modified-adjusted-gross-income-magi)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Adjust Your Gross Income for MAGI Calculation
- 7 Big Tax Changes for 2026 (https://aarp.org/money/taxes/2026-tax-changes)
- Modified adjusted gross income (AGI): What it is & how to calculate | Fidelity (https://fidelity.com/learning-center/personal-finance/magi-modified-adjusted-gross-income)
- Case Study: Financial Plan For New Parents And FIRE | PlanEasy (https://planeasy.ca/case-study-financial-planning-for-new-parents-and-financial-independence-retire-early-fire)
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill | Internal Revenue Service (https://irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Include Student Loan Interest in Your MAGI
- The Student Loan Interest Deduction: A Tax Benefit for Borrowers (https://eztaxreturn.com/blog/student-loan-interest-deduction)
- Student Loan Debt Statistics [2025]: Average + Total Debt (https://educationdata.org/student-loan-debt-statistics)
- Student Loan Interest Deduction Should Factor Into Debates on Student Debt, Tax Code (https://pew.org/en/research-and-analysis/articles/2017/09/21/student-loan-interest-deduction-should-factor-into-debates-on-student-debt-tax-code)
- How Student Loans Impact Your Taxes | Bankrate (https://bankrate.com/loans/student-loans/student-loan-interest-deduction)
- This May Be the Last Year to Claim Student Loan Tax Deduction (https://studentloanplanner.com/student-loan-tax-deduction-ending)
- Consider Tax-Exempt Interest in Your MAGI
- Understanding IRMAA and Your 2026 Medicare Costs – Cardinal Guide (https://cardinalguide.com/posts/understanding-irmaa-and-your-2026-medicare-costs)
- Modified adjusted gross income (MAGI): How to calculate MAGI (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/magi-modified-adjusted-gross-income)
- MAGI & US expats eligibility: Senior bonus, SALT, FEIE | TfE (https://taxesforexpats.com/articles/tax-reform-2025/senior-bonus-deduction-magi-ssdi-ssi-foreign-income.html)
- Modified adjusted gross income (MAGI) (https://public.com/learn/modified-adjusted-gross-income)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Factor in Foreign Income for Accurate MAGI
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- Modified Adjusted Gross Income (MAGI): What US Expats Should Know | Bright!Tax Expat Tax Services (https://brighttax.com/blog/modified-adjusted-gross-income-magi)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- Frequently Requested Statistics on Immigrants and Immigration in the United States (https://migrationpolicy.org/article/frequently-requested-statistics-immigrants-and-immigration-united-states-2024)
- Account for Retirement Contributions in Your MAGI
- 4 Steps on How to Reduce Modified Adjusted Gross Income – Bright Advisers (https://brightadvisers.com/4-steps-on-how-to-reduce-modified-adjusted-gross-income)
- Modified adjusted gross income (AGI): What it is & how to calculate | Fidelity (https://fidelity.com/learning-center/personal-finance/magi-modified-adjusted-gross-income)
- Modified adjusted gross income (MAGI) (https://public.com/learn/modified-adjusted-gross-income)
- What is MAGI retirement income & how does it affect you? (https://thrivent.com/insights/retirement-planning/what-is-magi-retirement-income-how-does-it-affect-you)
- Understand MAGI’s Role in Tax Credit Eligibility
- Child Tax Credit | Internal Revenue Service (https://irs.gov/credits-deductions/individuals/child-tax-credit)
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- Child tax credit 2025: Child tax credit updates and payments (https://jacksonhewitt.com/tax-help/tax-tips-topics/family/child-tax-credit-2025)
- 10 MAGI Examples Every Young Parent Should Know – Bright Advisers (https://brightadvisers.com/10-magi-examples-every-young-parent-should-know)
- The Child Tax Credit: How It Works and Who Receives It (https://congress.gov/crs-product/R41873)
- Example: Calculate MAGI with Multiple Income Sources
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)
- What Is MAGI? How to Calculate Your Modified Adjusted Gross Income (https://eztaxreturn.com/blog/what-is-magi-how-to-calculate-your-modified-adjusted-gross-income)
- What Is Modified Adjusted Gross Income (MAGI)? (https://smartasset.com/taxes/what-is-modified-adjusted-gross-income)
- What Is Modified Adjusted Gross Income (MAGI) and How Is It Calculated? – Intuit TurboTax Blog (https://blog.turbotax.intuit.com/tax-tips/what-is-modified-adjusted-gross-income-magi-48384)
- What Is Modified Adjusted Gross Income (MAGI)? – NerdWallet (https://nerdwallet.com/taxes/learn/modified-adjusted-gross-income-magi)
- Avoid Common Mistakes in MAGI Calculation
- How to Get MAGI: A Step-by-Step Guide for Young Families – Bright Advisers (https://brightadvisers.com/how-to-get-magi-a-step-by-step-guide-for-young-families)
- Master the MAGI Line on 1040: A Step-by-Step Guide for Parents – Bright Advisers (https://brightadvisers.com/master-the-magi-line-on-1040-a-step-by-step-guide-for-parents)
- Three Tax Resolutions to Protect Your Income in 2026 (https://wsj.com/personal-finance/taxes/three-tax-resolutions-to-protect-your-income-in-2026-d0e8708c?gaa_at=eafs&gaa_n=AWEtsqc1MCiDkeQJtEOQ4ROgMjnhq6K4wbDmFpSsBOopFoFgFyDHxX2WUuCl&gaa_ts=695ed08b&gaa_sig=B_2SL3ujr4Kod1EJ_qj-9l18yOnt9sv9sSHGr6nS0MmH5-mKXwBNPLUnhE35DFOSOYgQybZSNA6JmqQdE1VJ4w%3D%3D)
- Your Guide to Understanding Modified Adjusted Gross Income (MAGI) (https://irmaacertifiedplanner.com/your-guide-to-understanding-modified-adjusted-gross-income)
- Modified Adjusted Gross Income (MAGI): Calculating and Using It (https://investopedia.com/terms/m/magi.asp)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading