

Overview
This article outlines ten essential rules for parents regarding Mega Backdoor Roth withdrawals, emphasizing the importance of understanding tax implications, withdrawal timing, and record-keeping. Imagine if you could make tax-free withdrawals after age 59½ while holding the account for five years. This flexibility allows you to access contributions without penalties to meet immediate financial needs, providing peace of mind during challenging times.
We’re here for you, guiding you through these important decisions as you prioritize your family’s financial future.
Key Highlights:
- Bright Advisers specialises in personalised financial planning, particularly for families utilising Mega Backdoor Roth IRAs to maximise retirement savings.
- Mega Backdoor Roth IRAs allow high-income earners to contribute significantly more than traditional IRAs, with potential contributions up to $70,000 in 2025.
- Withdrawals from a Mega Backdoor Roth IRA can be tax-free if the account holder is over 59½ and has held the account for at least five years.
- Early withdrawals of earnings before age 59½ or the five-year period may incur income tax and a 10% penalty, while contributions can be withdrawn anytime without penalty.
- Maintaining detailed records of contributions, conversions, and withdrawals is crucial for compliance and efficient tax management.
- Engaging with financial advisors can help families tailor their investment strategies and withdrawal plans to align with their unique financial goals.
- The advisory services market is growing, reflecting the increasing demand for personalised financial guidance, particularly regarding retirement planning.
Introduction
Navigating the complexities of retirement savings can feel overwhelming for parents. The intricacies of the Mega Backdoor Roth IRA may add to this challenge. Yet, this innovative financial strategy opens doors for high-income families, allowing them to significantly boost their retirement contributions beyond conventional limits. Imagine the possibilities for reshaping your financial future! However, with great opportunity comes the need for careful understanding of the withdrawal rules and associated tax implications.
It’s important to understand how parents can effectively leverage this powerful tool while avoiding common pitfalls. This article explores ten essential rules surrounding Mega Backdoor Roth withdrawals, providing valuable insights for families eager to secure their financial well-being. Together, we can navigate this journey toward a more secure financial future.
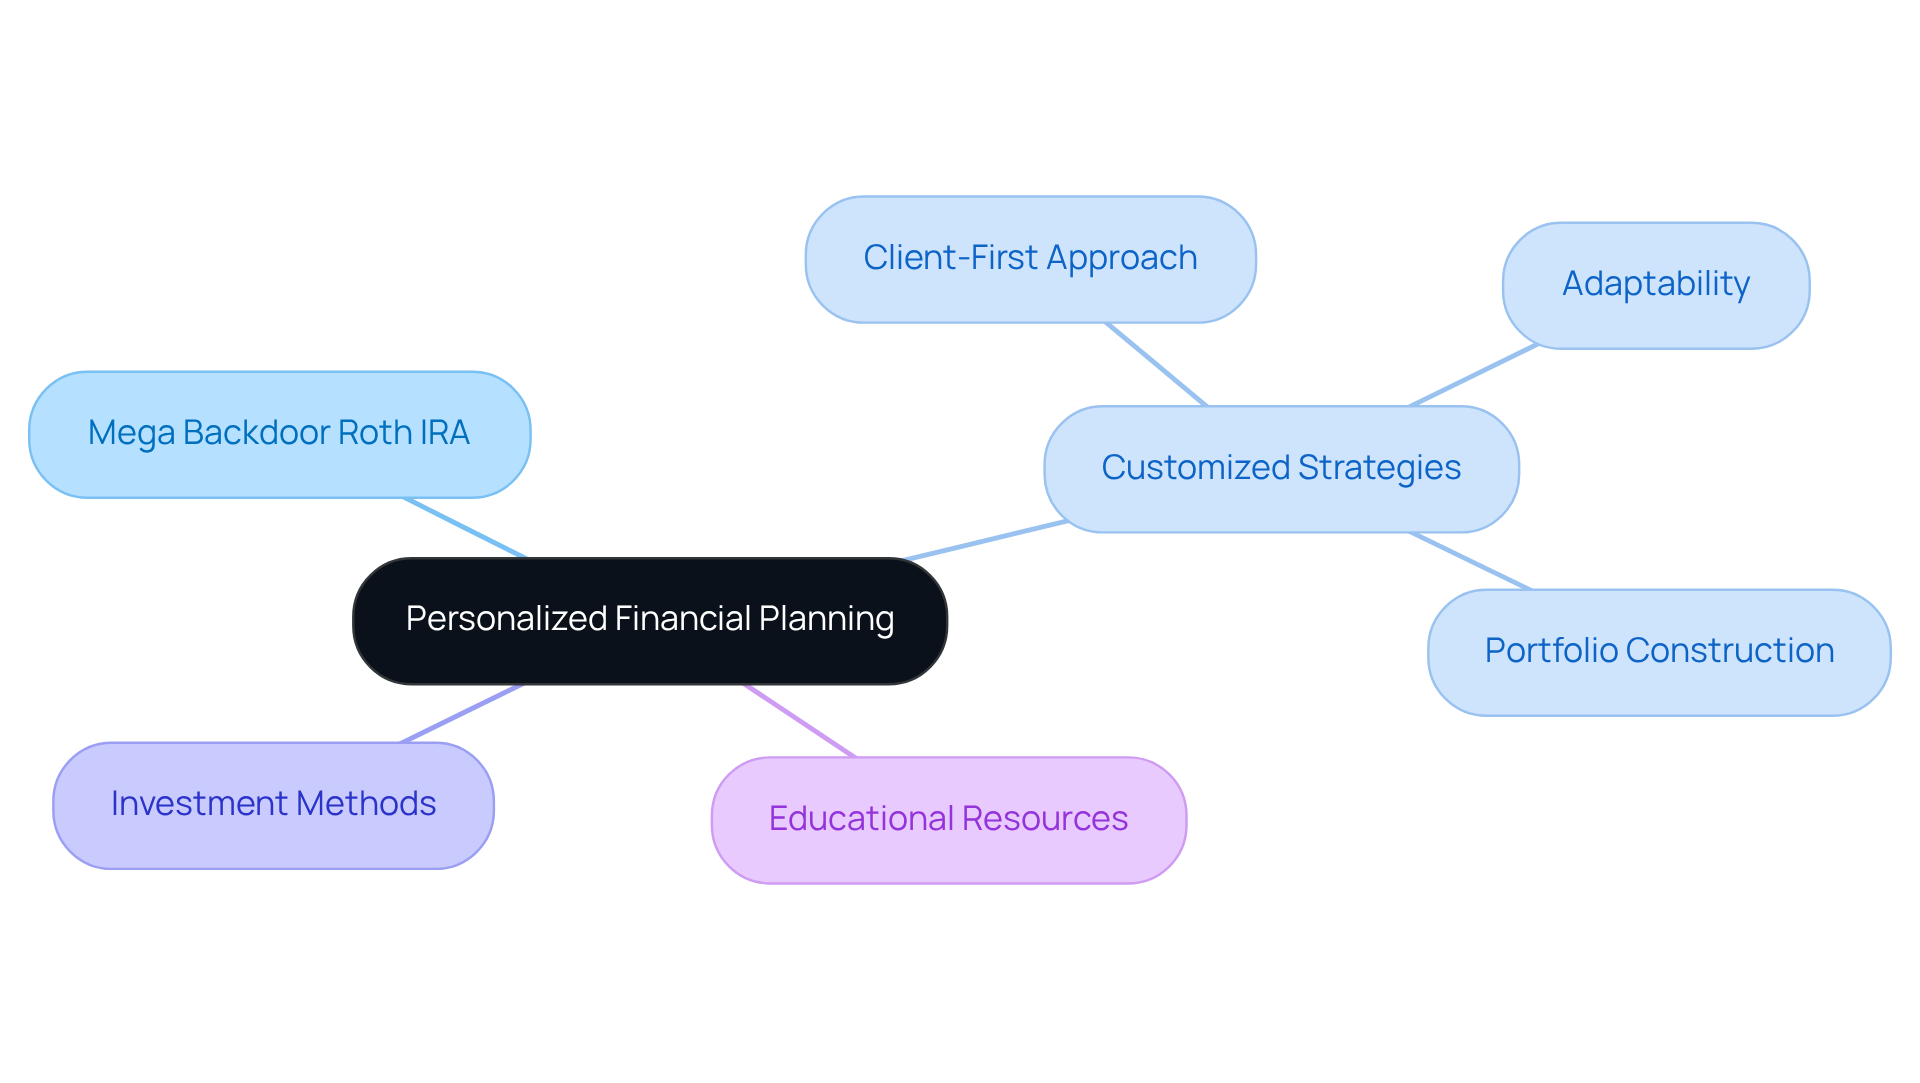
Bright Advisers: Personalized Financial Planning for Mega Backdoor Roth IRAs
At Bright Advisers, we understand that planning for your family’s future can feel overwhelming. That’s why we excel in customized strategies, particularly for households aiming to maximize retirement savings by understanding the mega backdoor roth withdrawal rules through innovative options like the Mega Backdoor Roth IRA. Imagine being able to contribute significantly more to your retirement accounts than traditional methods allow—this creative approach can truly enhance your long-term financial security.
We prioritize a client-first approach, using advanced technology to simplify the complexities of financial planning. Our goal is to ensure your investment strategies are tailored to meet the unique needs of your family. Each portfolio is constructed from the ground up, reflecting your household’s specific investment goals and incorporating proven methods like smart beta and factor investing.
As wealth consultants often emphasize, a personalized investment strategy not only aligns with your family’s objectives but also adapts to life’s changes. This adaptability is essential for effective asset management, particularly for young families navigating various financial responsibilities. We’re here for you every step of the way.
In addition to our advisory services, we offer educational resources, including interactive lessons designed for children, to help prepare the next generation for financial responsibility. Together, we can navigate this journey toward a secure future.
The advisory services market is projected to grow significantly, from $114.39 billion in 2023 to $123.89 billion in 2024. This growth reflects the increasing demand for personalized financial guidance. As one financial advisor wisely noted, ‘A tailored investment strategy is crucial for families to navigate their unique financial landscapes and secure their children’s futures.’ Let us help you create a plan that not only meets your needs today but also builds a legacy for tomorrow.
Eligibility Criteria: Who Can Withdraw from a Mega Backdoor Roth IRA?
Withdrawing from a Mega Backdoor IRA can be a valuable step for families, especially considering the mega backdoor roth withdrawal rules when involved in a 401(k) plan that allows after-tax contributions and in-service withdrawals. This strategy is particularly beneficial for high-income earners who find themselves exceeding the income limits for direct IRA contributions. Imagine this: in 2025, individuals earning over $165,000 as singles or $246,000 as married couples filing jointly will discover they are ineligible for conventional contributions. This is where the mega backdoor roth withdrawal rules shine as an attractive alternative.
It’s essential for parents to check their specific plan’s provisions, as not all 401(k) plans accommodate this option. Many high-income earners are already utilizing this strategy to enhance their retirement savings, successfully sidestepping the restrictions set by conventional IRAs. For instance, consider households like Jay and Emma, who aimed to reduce financial stress while maximizing their resources. They found that methods like the mega backdoor roth withdrawal rules helped them balance short-term needs with long-term goals.
Furthermore, with the contribution limit for 401(k) plans set at $23,500 for individuals under 50 in 2025, families should think about maximizing their contributions to fully benefit from this strategy. Consulting with tax experts can provide clarity on how this approach aligns with your personal objectives, ensuring that your family can secure a bright economic future. Remember, we’re here for you as you navigate this journey together.

Tax Implications: Understanding the Tax Rules for Mega Backdoor Roth Withdrawals
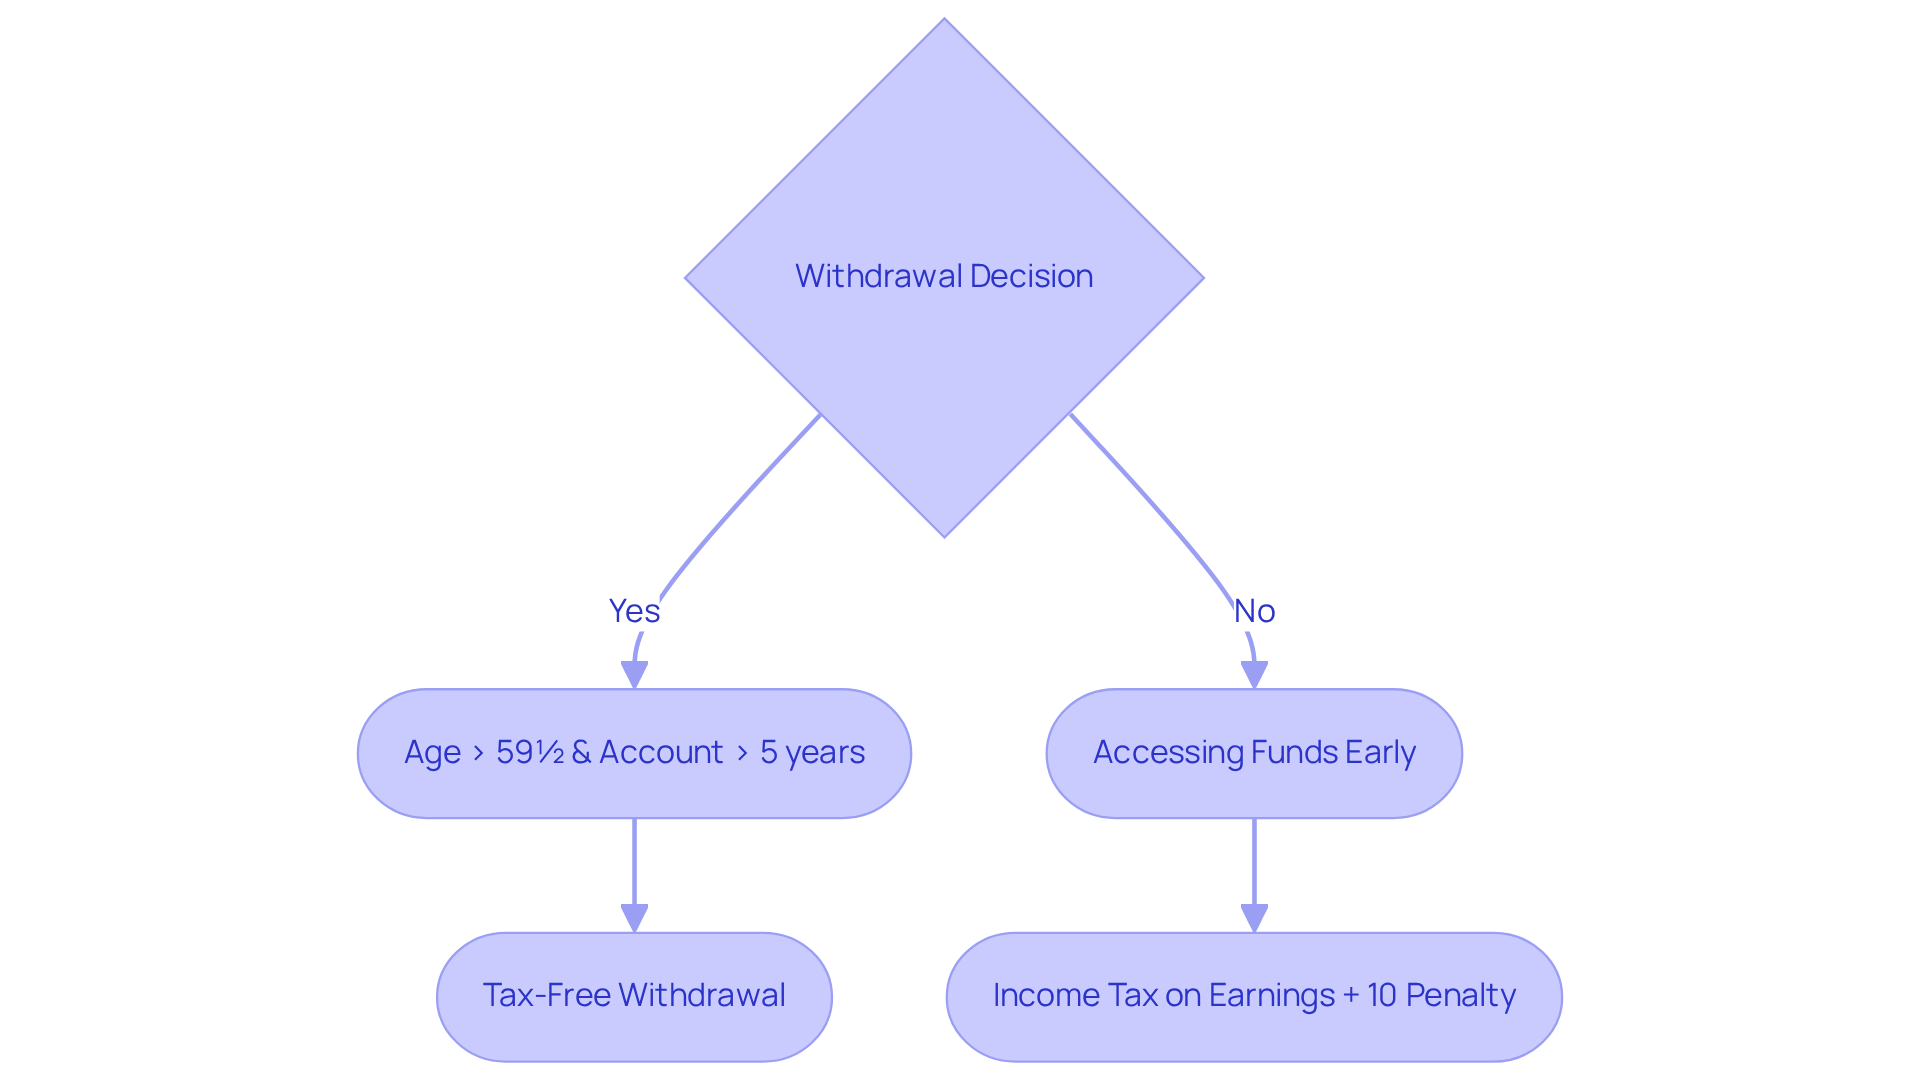
Imagine securing a brighter financial future for your family. According to the mega backdoor Roth withdrawal rules, withdrawals from a Mega Backdoor Individual Retirement Account can be tax-free, especially if you’re over 59½ and have held the account for at least five years. However, it’s important to understand that according to the mega backdoor Roth withdrawal rules, accessing funds before reaching this age or before completing the five-year holding period may lead to income tax on earnings and a 10% early withdrawal penalty.
Many families, like yours, can benefit from understanding the mega backdoor Roth withdrawal rules to avoid unnecessary economic burdens. In fact, in 2018, about 15% of working-age taxpayers made early withdrawals from retirement accounts, highlighting the importance of being aware of tax implications.
By familiarizing yourself with these regulations, you can maximize your retirement savings while minimizing tax liabilities. We’re here for you, guiding you through this journey to ensure your family’s financial well-being. Together, we can navigate these important aspects of financial planning, helping you make informed decisions that resonate with your family’s values.
Withdrawal Timing: When is the Right Time to Access Your Mega Backdoor Roth Funds?
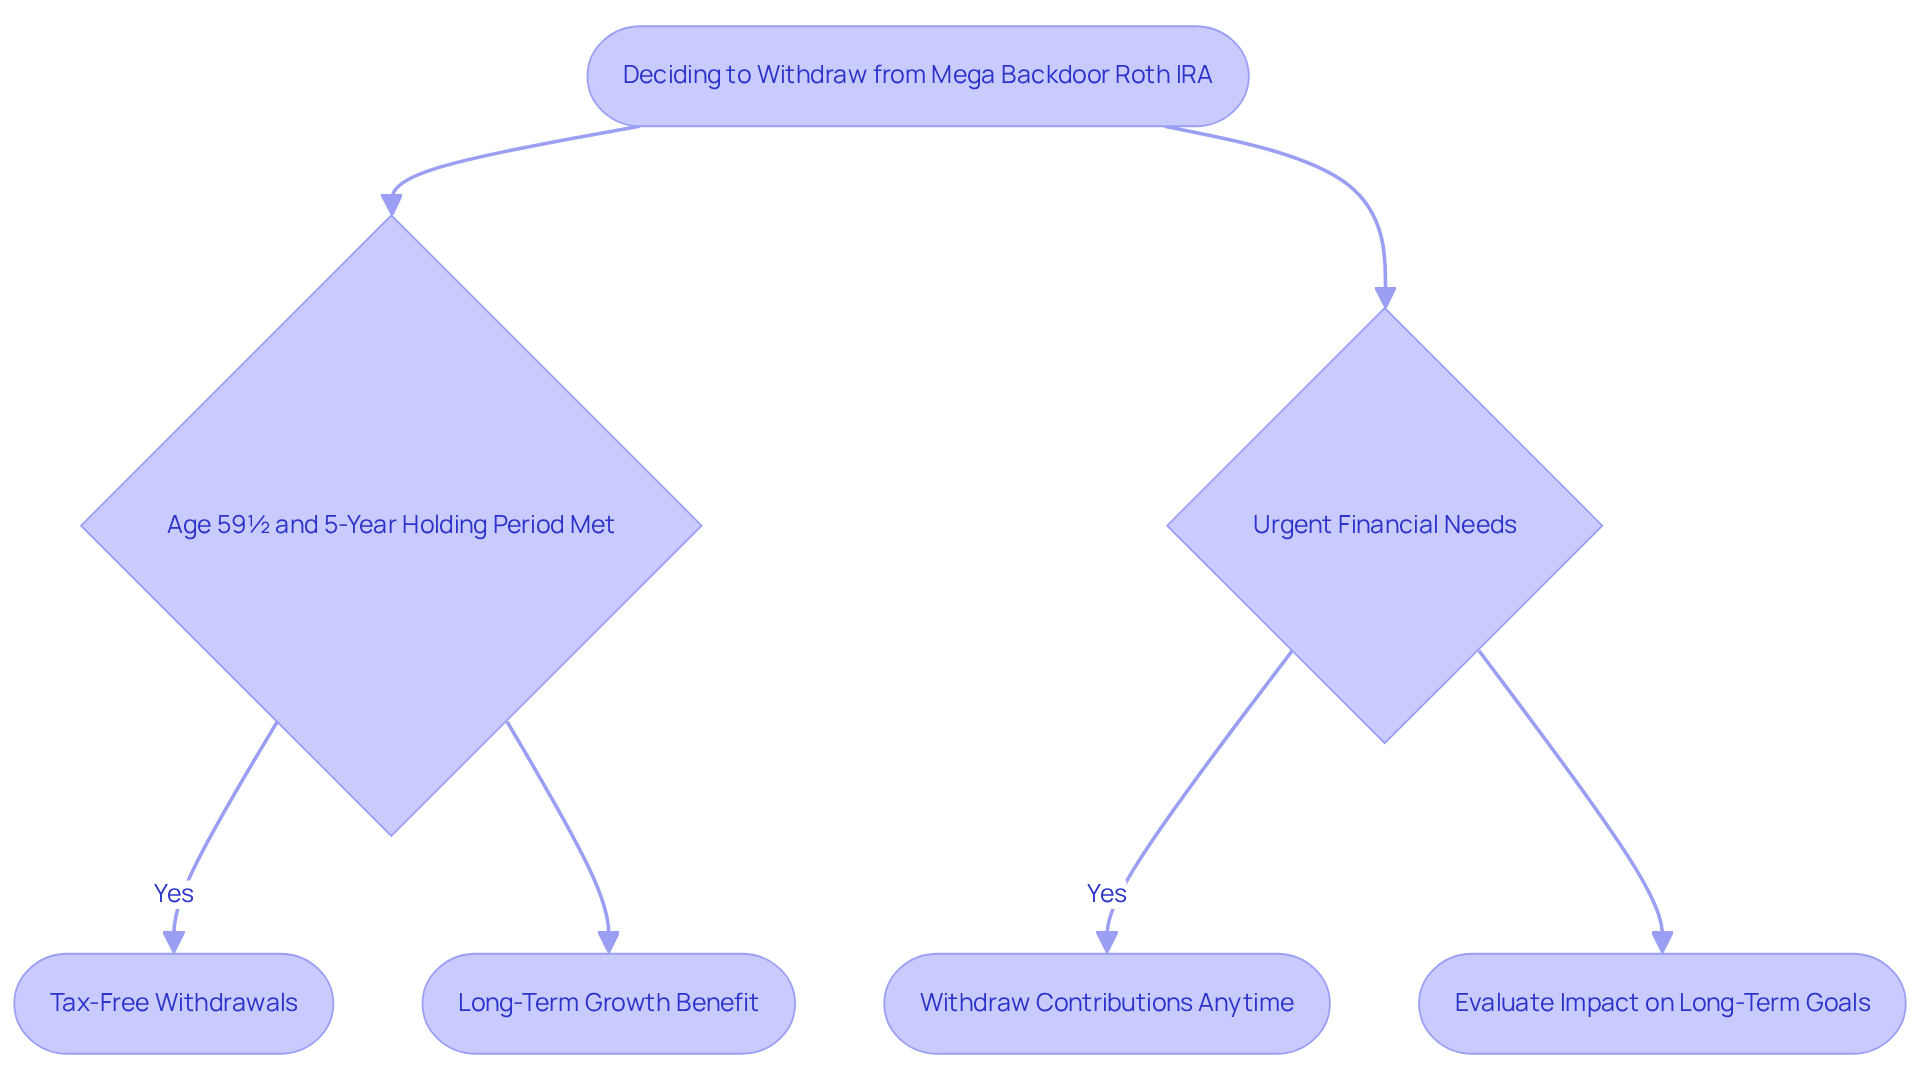
According to the mega backdoor roth withdrawal rules, accessing funds from a Mega Backdoor Roth IRA can be a thoughtful decision, ideally made after reaching age 59½ and completing the five-year holding period, which allows for tax-free withdrawals. However, we understand that parents may face urgent monetary needs, enabling them to withdraw their contributions at any time without incurring penalties. This flexibility is crucial for families striving to balance immediate expenses with long-term financial goals. Imagine a household needing to cover unexpected medical bills while also planning for their children’s education. In such instances, withdrawing contributions can provide essential liquidity without compromising future retirement savings.
At Bright Advisers, we are committed to minimizing fund fees, making wealth management more accessible for families. This dedication allows parents to focus on their economic security and freedom through personalized planning and tax optimization. Retirement planners highlight the importance of evaluating the trade-offs involved in accessing these funds.
“While it’s appealing to utilize these savings for urgent necessities, parents should reflect on how this choice affects their long-term economic objectives,” recommends a financial advisor. This perspective underscores the necessity for careful planning and consideration of the mega backdoor roth withdrawal rules when choosing to withdraw from a Mega Backdoor IRA. Ultimately, parents must weigh their current financial needs against the benefits of allowing their investments to grow tax-free over time. Together, we can navigate this journey with support and understanding.
Early Withdrawal Penalties: What Parents Need to Know About Mega Backdoor Roth IRAs
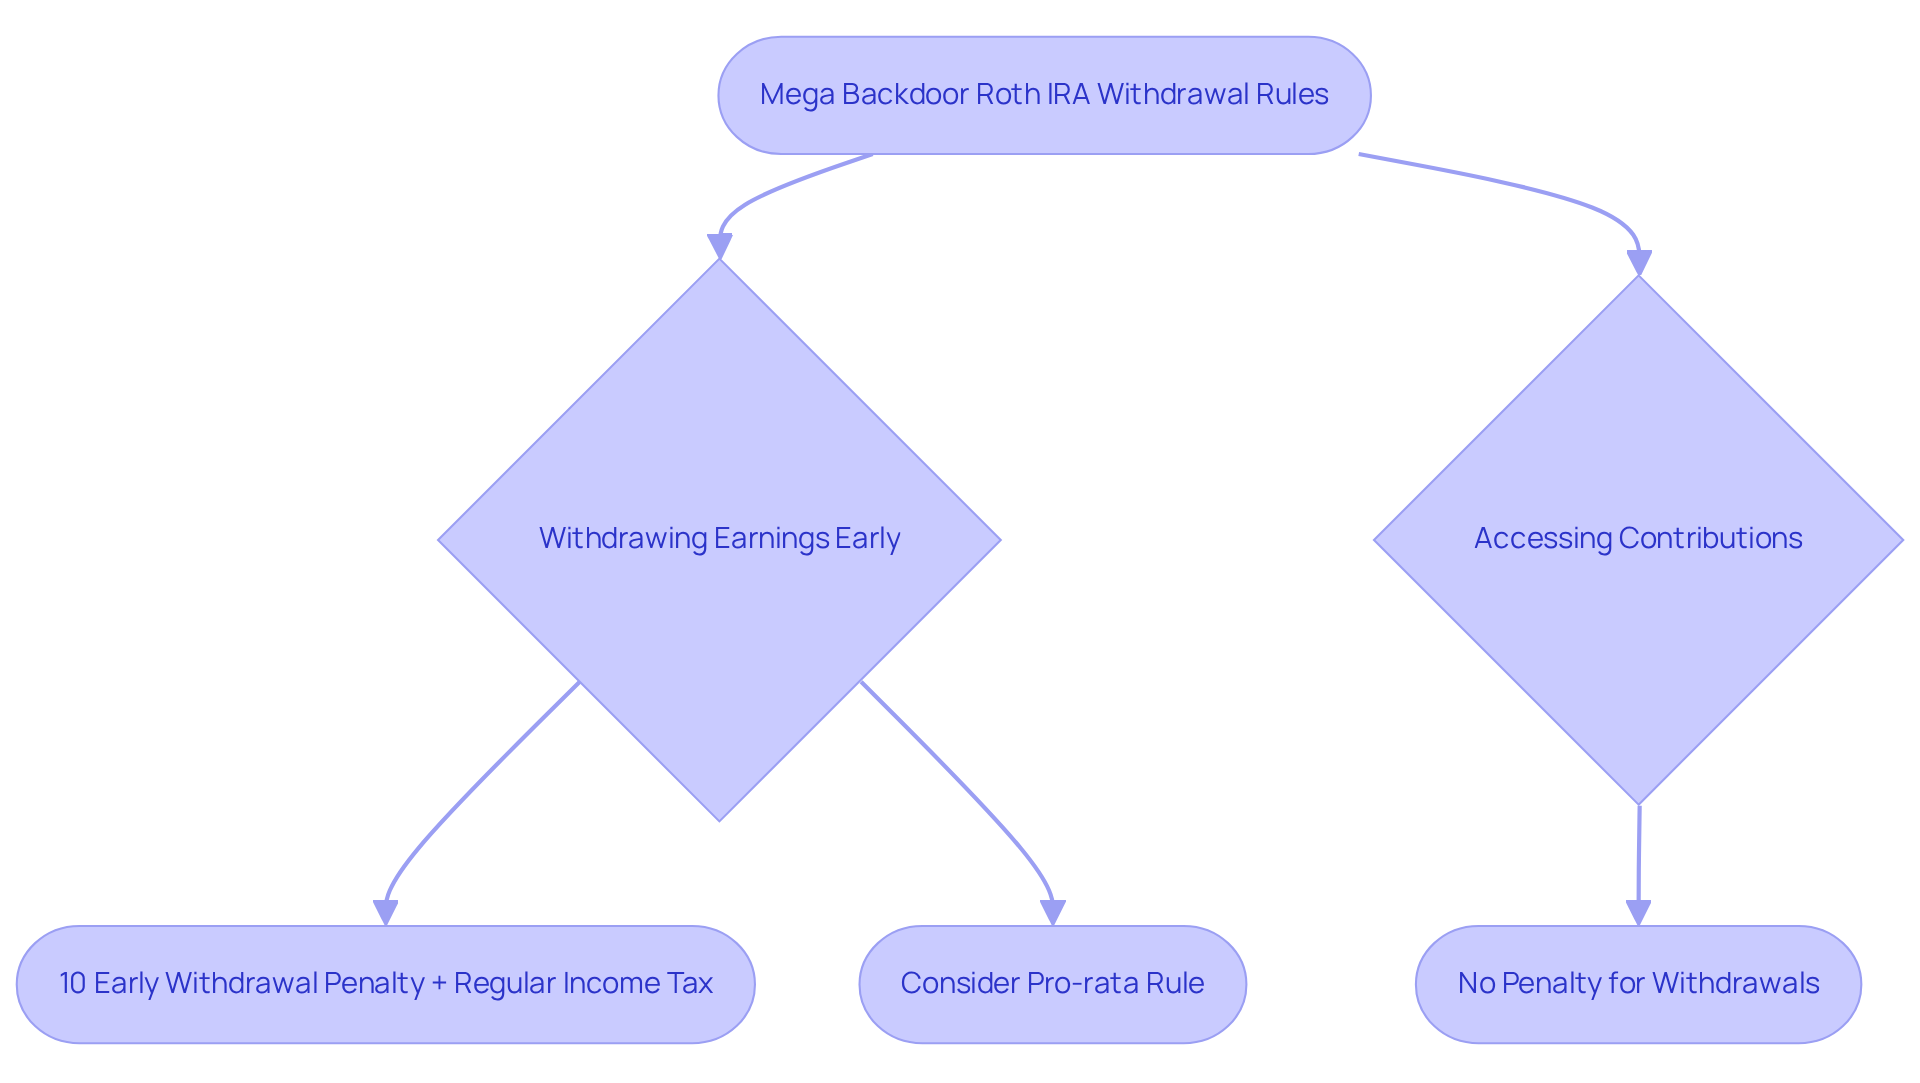
It’s essential for parents to understand the mega backdoor Roth withdrawal rules, which indicate that withdrawing earnings from a Mega Backdoor IRA before reaching age 59½ or before completing the five-year holding period can result in a 10% early withdrawal penalty, in addition to regular income tax on those earnings. Imagine if you had to pay a penalty on your hard-earned savings! In contrast, contributions can be accessed at any time without penalty, offering a more flexible option for families.
For instance, consider a household that converted $20,000 to an IRA. If they were to withdraw earnings early, they could face a $1,000 penalty. This scenario underscores the importance of strategic planning when it comes to your family’s financial future. Additionally, the pro-rata rule can complicate matters; if pre-tax IRA dollars are involved, a portion of the withdrawal may be taxable. This further highlights the need for careful management of retirement accounts.
Understanding the mega backdoor Roth withdrawal rules and their associated penalties and tax implications is crucial for effective financial planning. We’re here for you, ensuring that families can navigate their options without incurring unnecessary costs. Together, we can navigate this journey and secure a brighter future for your loved ones.
Conversion Process: How to Move Funds into Your Mega Backdoor Roth IRA
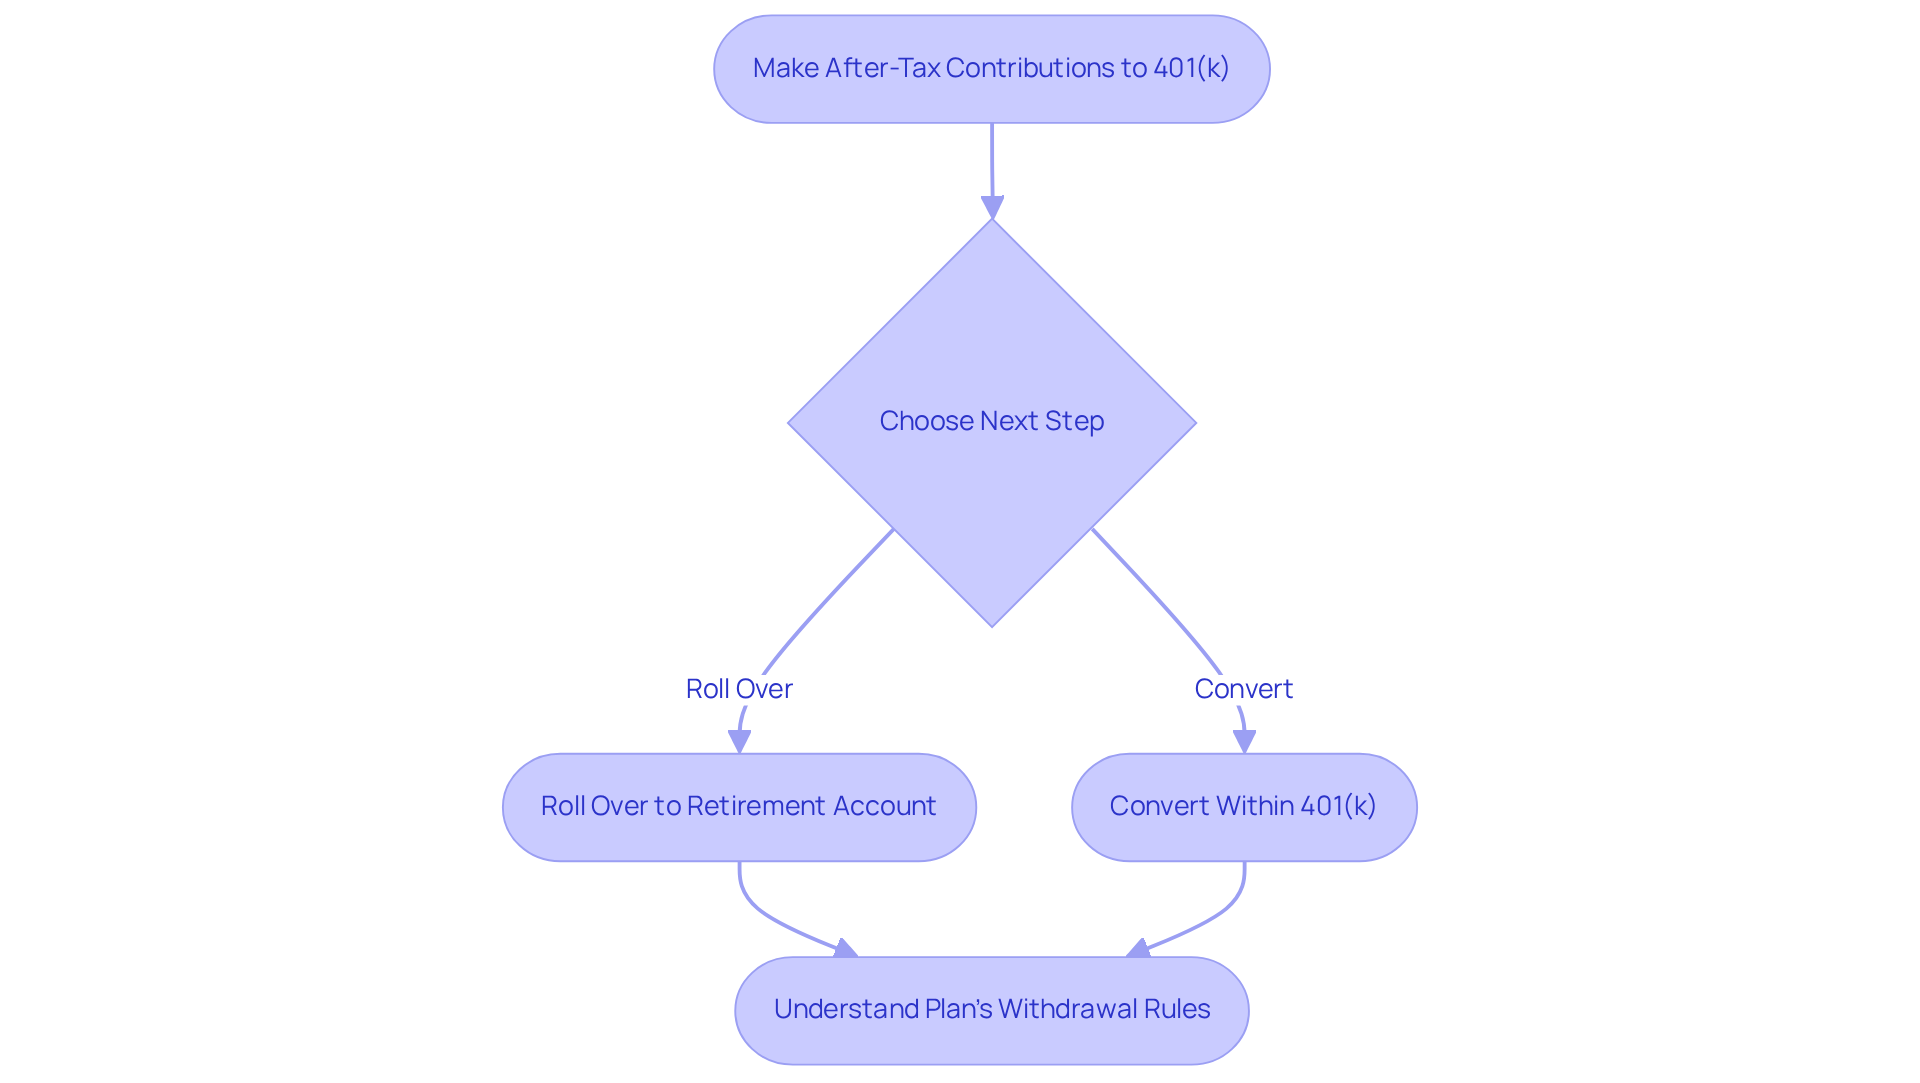
To successfully convert funds into a Mega Backdoor IRA, it’s essential to start by making after-tax contributions to your 401(k) plan. Imagine if you could take advantage of a strategy that many families are using to secure their financial future. Recent data shows that approximately 94.4% of 401(k) plans offer a contribution choice, which is a crucial first step in this process.
Once you’ve made those after-tax contributions, you have options. You can either:
- Roll these funds over to a retirement account
- Convert them directly within your 401(k) plan
It’s important to understand the mega backdoor Roth withdrawal rules established by your plan administrator, as they can guide you through the necessary steps and requirements for the conversion process.
For households looking to optimize their retirement savings, understanding these steps can lead to significant tax-free growth and enhanced financial security. Remember, we’re here for you, and together, we can navigate this journey toward a brighter financial future for your family.
Record-Keeping: Essential Documentation for Mega Backdoor Roth Withdrawals
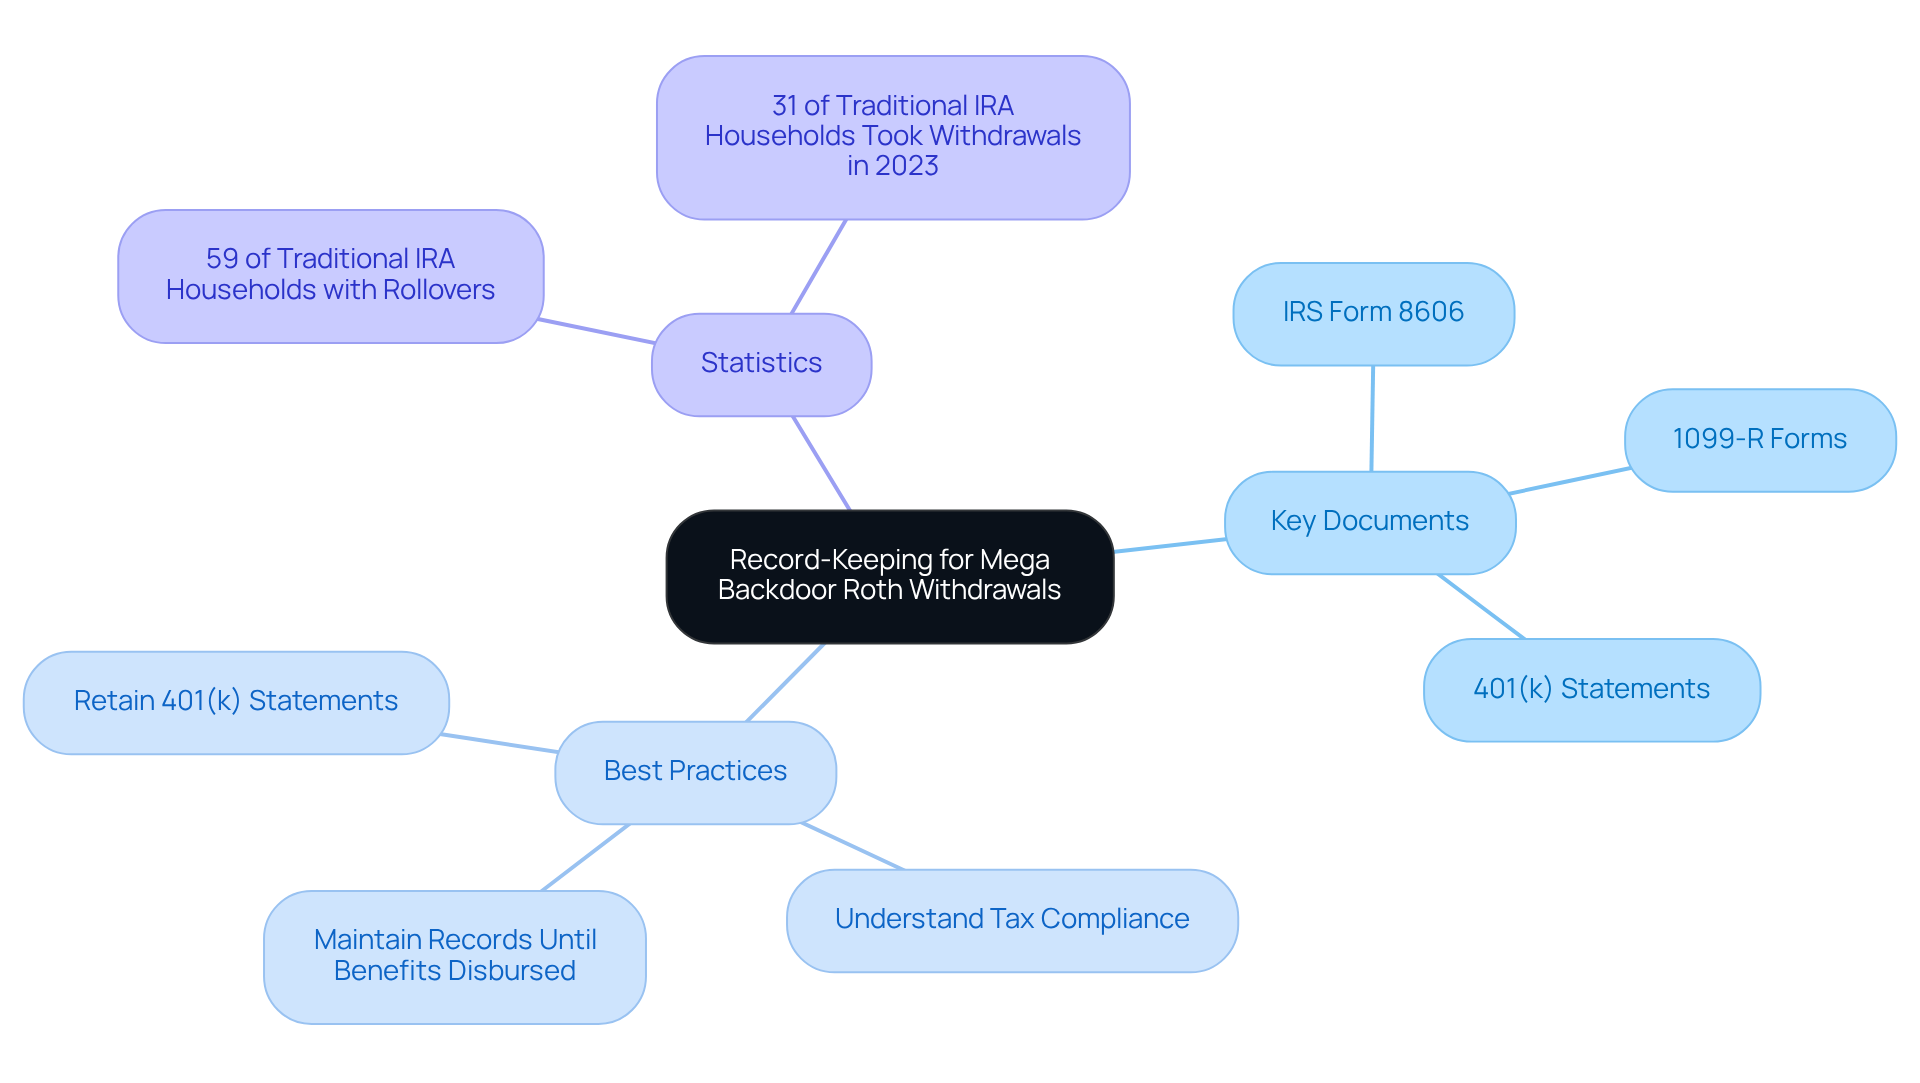
As parents, it’s essential to keep detailed records of all contributions, conversions, and withdrawals to comply with the mega backdoor Roth withdrawal rules related to your Mega Backdoor Roth IRA. Key documents to have on hand include:
- IRS Form 8606, which is vital for reporting nondeductible contributions
- 1099-R forms for any distributions taken
Imagine having everything organized when tax season arrives! Retaining statements from your 401(k) plan is also crucial for tracking contributions and ensuring compliance with tax regulations.
In mid-2024, a significant 59 percent of traditional IRA-owning households shared that they had rollovers from employer-sponsored retirement plans. This statistic underscores the importance of maintaining records for contributions and rollovers. By managing your records efficiently, you not only streamline the tax submission process but also help your family avoid potential audits. It’s important to understand that the Internal Revenue Code and ERISA require that retirement plan records be kept until all benefits have been disbursed, allowing ample time to reduce audit risks.
By following these best practices, you can navigate the complexities of retirement account management with confidence. Remember, we’re here for you, and together, we can ensure that your family’s financial future is secure and well-organized.
Traditional vs. Mega Backdoor Roth IRA: Key Differences for Parents
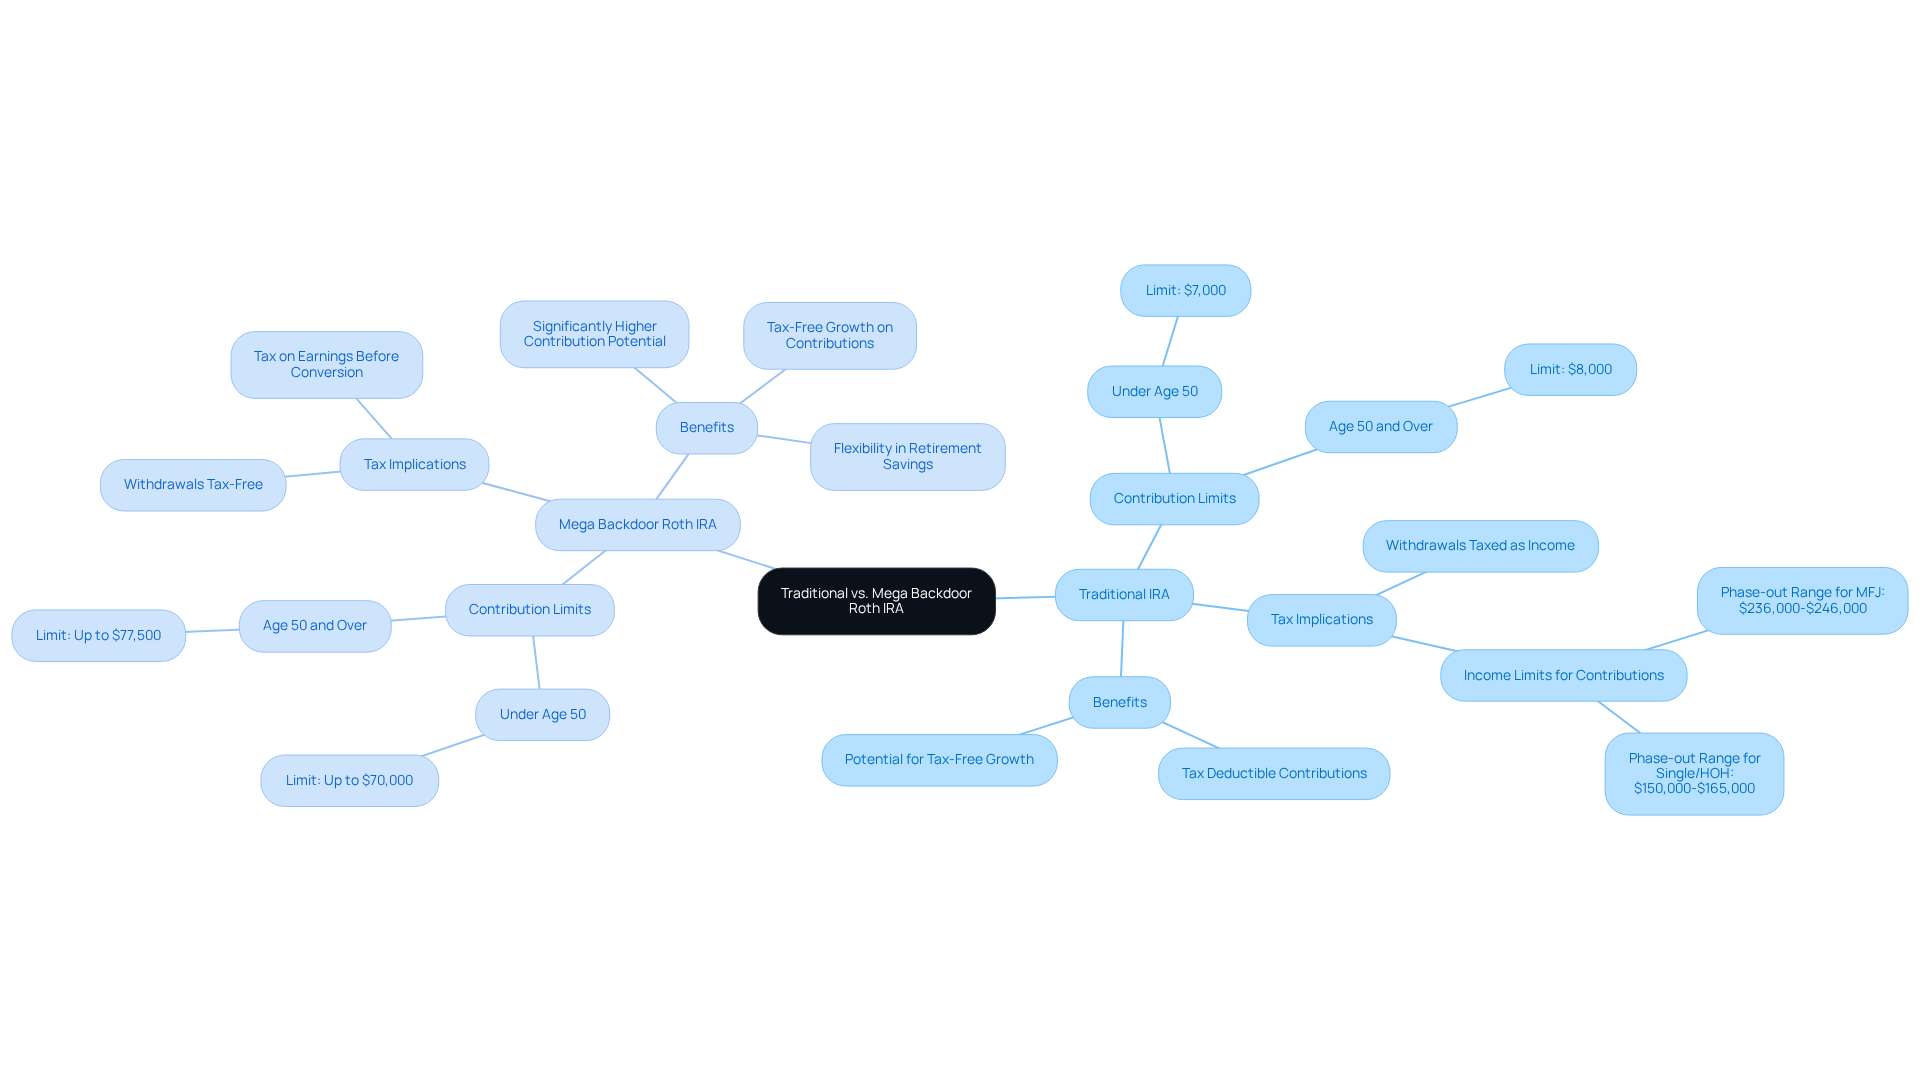
Understanding the difference between a Traditional IRA and the mega backdoor Roth withdrawal rules can feel overwhelming, but we’re here to help you navigate this important aspect of your financial planning. The key distinction lies in their contribution limits and tax implications. Traditional IRAs set income limits that can restrict contributions for high earners, while the Mega Backdoor version opens the door for these individuals to contribute significantly more by utilizing after-tax contributions within their 401(k) plans.
Imagine being able to contribute up to $70,000 in 2025 if you’re under 50. This amount includes both employee deferrals and after-tax contributions, providing you with the flexibility to enhance your retirement savings substantially. For families looking to secure their financial future, this option can be a game-changer.
What’s more, according to the mega backdoor Roth withdrawal rules, withdrawals from a Mega Backdoor IRA are tax-free during retirement. This is a significant benefit compared to Traditional IRAs, where withdrawals are taxed as regular income. This tax-free growth potential is particularly beneficial for high-income earners who may face higher tax brackets in retirement. As investment advisors often share, understanding the mega backdoor Roth withdrawal rules is essential for utilizing the Mega Backdoor IRA as an effective tool for optimizing tax-free retirement savings, especially for those who have reached the limit on their standard 401(k) and IRA contributions.
By considering this approach, you can ensure a more solid economic future for your family while reducing tax obligations. Together, we can navigate this journey towards financial security, empowering you to make informed decisions that resonate with your family values and shared goals.
Income Limits: How They Affect Your Mega Backdoor Roth IRA Withdrawals
The Mega Backdoor Roth IRA presents a wonderful opportunity for high-income earners, as it opens doors without imposing income limits on contributions. Imagine being able to contribute up to $70,000 in 2025, or $77,500 if you’re 50 or older. This strategy can be a game changer for families like Jay and Emma, enhancing their economic security while thoughtfully managing resources for both retirement and their children’s education.
By embracing tax optimization tactics and exploring education savings options with Bright Advisers, they can alleviate financial stress and pave the way for a brighter future. However, it’s important for parents to reflect on their overall economic picture, as income levels can influence the timing and strategy for adhering to mega backdoor roth withdrawal rules. Understanding these dynamics is vital for effective retirement planning, ensuring that families can leverage this powerful tool to protect their financial future.
Together, we can navigate this journey, helping you make informed decisions that resonate with your family values and shared goals. Remember, we’re here for you every step of the way.

Best Practices: Managing Your Mega Backdoor Roth IRA Withdrawals Effectively
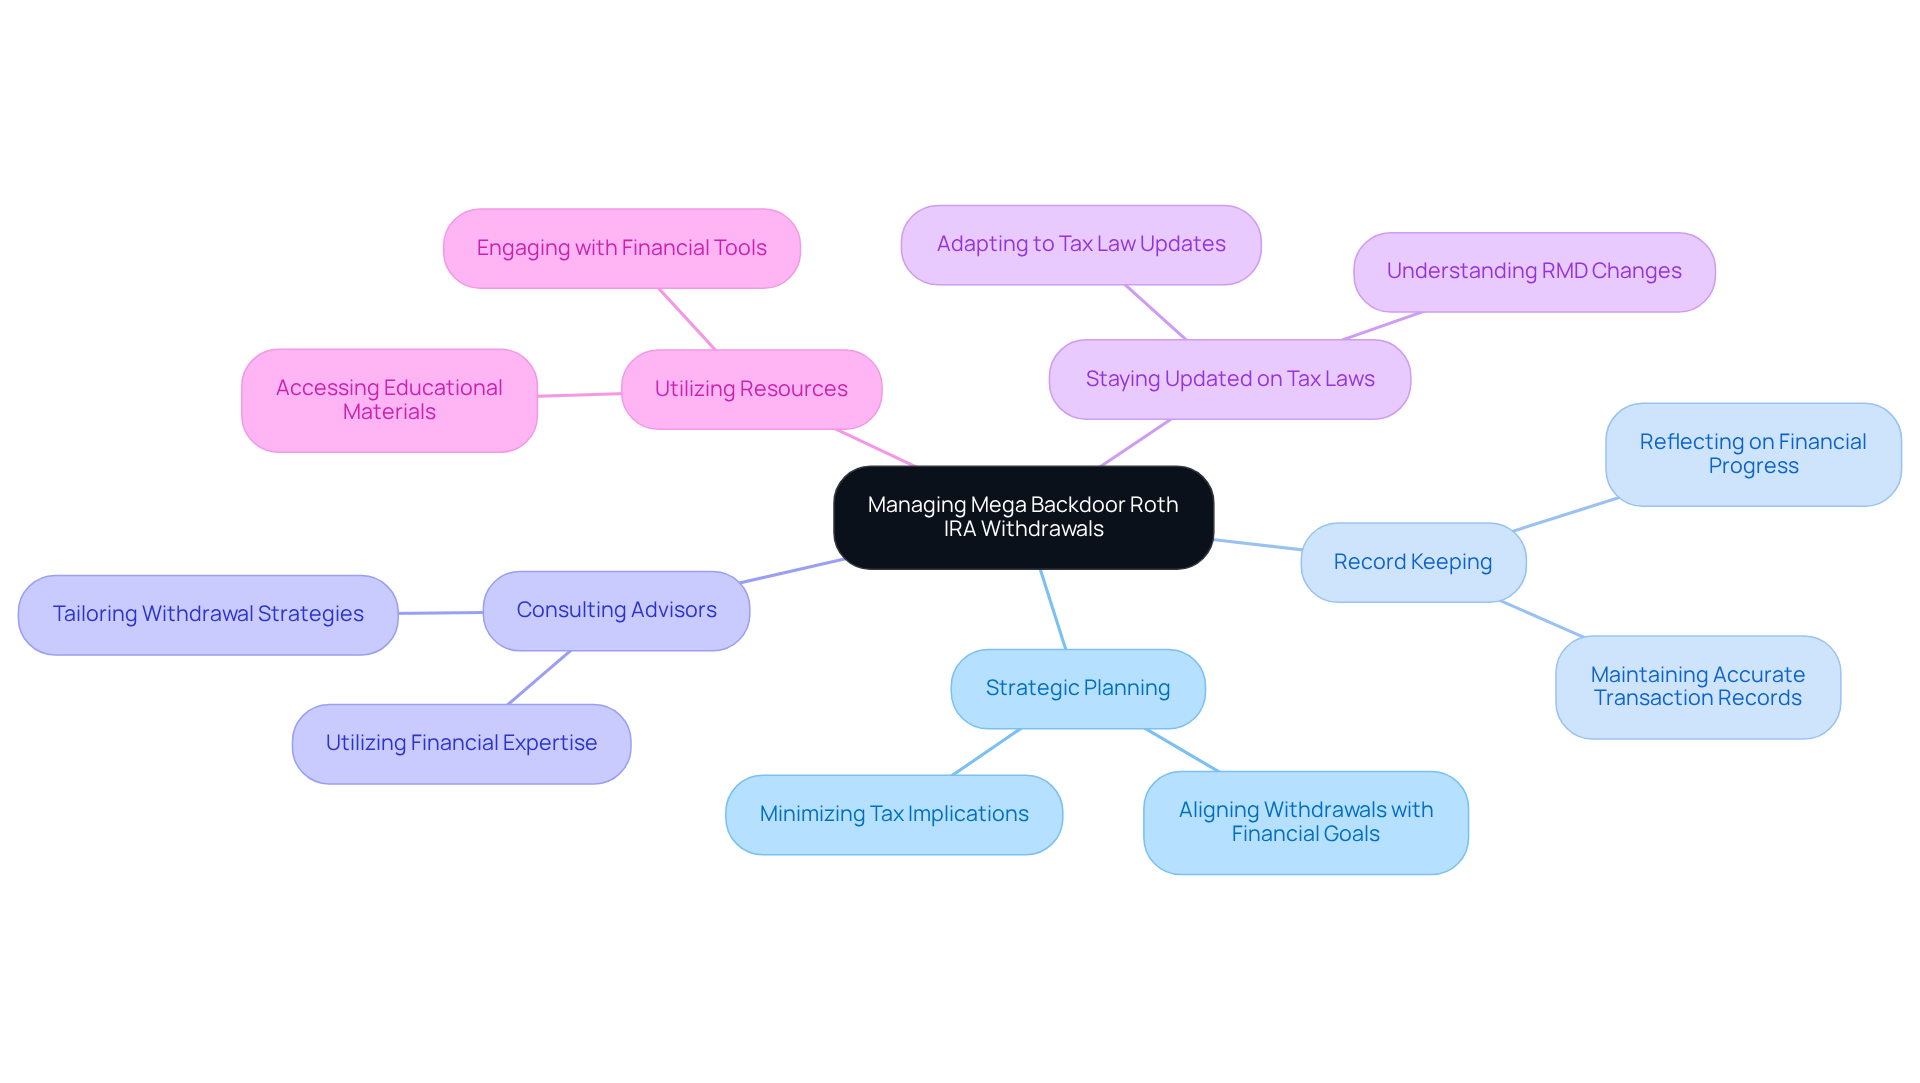
To effectively manage the mega backdoor roth withdrawal rules, it’s essential for parents to embrace some best practices that can truly make a difference in their financial journey. Imagine strategically planning your withdrawals to minimize tax implications; this means ensuring that the timing and amount align with your family’s monetary goals. By doing so, you can feel more secure about your financial future.
Keeping meticulous records of all transactions is another crucial step. This not only facilitates accurate reporting but also aids in future planning, allowing you to reflect on your progress with confidence. Remember, every detail matters, and having a clear picture of your finances can provide peace of mind.
Engaging with a financial advisor, like those at Bright Advisers, is a wonderful way to tailor withdrawal strategies that meet the unique needs of your household. These experts can help you complement your overall monetary objectives, ensuring that your family’s financial goals are within reach.
Staying updated on tax law changes is equally important, as these can significantly influence your retirement planning and withdrawal strategies. By being informed, you empower yourself to make decisions that align with your family’s best interests.
By adopting these practices, families can fully utilize the benefits of their Mega Backdoor Roth IRA while following the mega backdoor roth withdrawal rules, enhancing their economic results. And remember, you don’t have to navigate this journey alone. Consulting with a financial advisor or utilizing specific resources can provide you with tailored wealth management solutions that empower your financial security and freedom. We’re here for you, and together, we can navigate this journey towards a brighter financial future.
Conclusion
Navigating the complexities of Mega Backdoor Roth IRAs can significantly enhance your family’s financial future. This innovative strategy allows high-income earners to contribute more towards retirement while bypassing the limitations of traditional IRAs. By understanding and adhering to the specific withdrawal rules, you can make informed decisions that align with your long-term financial goals.
Key insights covered in this article include:
- Eligibility criteria for withdrawals
- Tax implications
- Best practices for managing contributions and distributions
It’s important to be aware of the significance of:
- Timing your withdrawals
- Maintaining meticulous records
- Consulting with financial advisors to optimize your strategies
These steps can help your family maximize retirement savings while minimizing potential penalties and tax burdens.
Ultimately, the Mega Backdoor Roth IRA serves as a powerful tool for families aiming to secure their financial legacy. By embracing personalized financial planning and staying informed about the latest regulations, you can pave the way for a more stable and prosperous future. Engaging with a knowledgeable financial advisor can provide the necessary guidance to navigate this journey, ensuring that your family can effectively leverage retirement accounts for long-term success. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What is the Mega Backdoor Roth IRA?
The Mega Backdoor Roth IRA is a strategy that allows individuals to contribute significantly more to their retirement accounts than traditional methods permit, particularly beneficial for high-income earners exceeding the income limits for direct IRA contributions.
Who can withdraw from a Mega Backdoor Roth IRA?
Individuals involved in a 401(k) plan that allows after-tax contributions and in-service withdrawals can withdraw from a Mega Backdoor Roth IRA. This option is especially advantageous for high-income earners who cannot make conventional IRA contributions due to income limits.
What are the income limits for conventional IRA contributions in 2025?
In 2025, individuals earning over $165,000 as singles or $246,000 as married couples filing jointly will be ineligible for conventional IRA contributions.
What are the tax implications of withdrawing from a Mega Backdoor Roth IRA?
Withdrawals from a Mega Backdoor Roth IRA can be tax-free if the account holder is over 59½ and has held the account for at least five years. If funds are accessed before reaching this age or before completing the five-year holding period, there may be income tax on earnings and a 10% early withdrawal penalty.
What should families consider when planning to utilize the Mega Backdoor Roth strategy?
Families should check their specific 401(k) plan provisions to ensure it accommodates the Mega Backdoor Roth option. Additionally, they should consider maximizing their contributions, as the 401(k) contribution limit is set at $23,500 for individuals under 50 in 2025.
How does Bright Advisers support families in financial planning?
Bright Advisers provides personalized financial planning strategies, including educational resources for children, and utilizes advanced technology to simplify financial complexities, ensuring investment strategies meet the unique needs of each family.
Why is a personalized investment strategy important?
A personalized investment strategy is crucial as it aligns with a family’s specific objectives and adapts to life changes, which is essential for effective asset management, especially for young families with various financial responsibilities.
List of Sources
- Bright Advisers: Personalized Financial Planning for Mega Backdoor Roth IRAs
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- 30+ Financial Advisor Statistics (https://bizplanr.ai/blog/financial-advisor-statistics)
- Personal Finance Statistics You Should Be Aware of in 2025 (https://moneyzine.com/personal-finance/personal-finance-statistics)
- Eligibility Criteria: Who Can Withdraw from a Mega Backdoor Roth IRA?
- Your Guide to the Mega Backdoor Roth: Case Study + Free Flow Chart (https://cordantwealth.com/mega-backdoor-roth-guide)
- Mega Backdoor Roth Conversions: Everything You Need to Know (https://rgwealth.com/insights/mega-backdoor-roth-strategies)
- Mega Backdoor Roth Explained: Eligibility, Contribution Limits, and Tax Benefits (https://withum.com/resources/mega-backdoor-roth-explained-eligibility-contribution-limits-and-tax-benefits)
- What is a mega backdoor Roth? | IRA conversion | Fidelity (https://fidelity.com/learning-center/personal-finance/mega-backdoor-roth)
- Simple, Affordable 401k Plans Built for Small and Medium-Sized Businesses | ShareBuilder 401k (https://sharebuilder401k.com/blog/what-is-the-mega-backdoor-roth)
- Tax Implications: Understanding the Tax Rules for Mega Backdoor Roth Withdrawals
- American Retirement and Tax-Preferred Savings Accounts, Tax Year 2018 (https://taxfoundation.org/data/all/federal/401k-ira-retirement-savings-accounts)
- Mega Backdoor Roth Conversions: Everything You Need to Know (https://rgwealth.com/insights/mega-backdoor-roth-strategies)
- Mega Backdoor Roth IRA: A Neat Idea that Rarely Works (https://asppa-net.org/news/2021/5/mega-backdoor-roth-ira-neat-idea-rarely-works)
- Individual Retirement Account (IRA) Ownership: Data and Policy Issues (https://congress.gov/crs-product/R46635)
- Early Withdrawals from Retirement Plans; 10% Penalty Information (https://efile.com/tax-penalty-early-retirement-withdrawals-distributions)
- Withdrawal Timing: When is the Right Time to Access Your Mega Backdoor Roth Funds?
- Mega Backdoor Roths: A How-to Guide (https://harness.co/articles/mega-backdoor-roth-how-to-guide)
- Mega Backdoor Roth IRA | Everything You Need to Know (https://firstfinancial.is/mega-backdoor-roth-ira)
- The Mega Backdoor Roth Strategy: Is It Right for You & How to Do It (https://plancorp.com/blog/mega-backdoor-roth)
- 2025 Mega-Backdoor Roth Guide: Limits, Benefits & Setup (https://safelandingfinancial.com/mega-backdoor-roth)
- Early Withdrawals for Roth IRAs, Backdoor Roth IRAs, & Mega Backdoor Roth 401ks | Astra Wealth Partners (https://astrawp.com/early-withdrawals-for-roth-accounts)
- Early Withdrawal Penalties: What Parents Need to Know About Mega Backdoor Roth IRAs
- Early Withdrawals for Roth IRAs, Backdoor Roth IRAs, & Mega Backdoor Roth 401ks | Astra Wealth Partners (https://astrawp.com/early-withdrawals-for-roth-accounts)
- Backdoor Roth IRA for High Earners | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/backdoor-roth-ira-strategy.html)
- Roth IRA Withdrawal Rules – NerdWallet (https://nerdwallet.com/article/investing/roth-ira-withdrawal-rules)
- Conversion Process: How to Move Funds into Your Mega Backdoor Roth IRA
- Mega Backdoor Roth Before Retirement (https://modwm.com/mega-backdoor-roth-before-retirement)
- Mega Backdoor Roth Conversions: Everything You Need to Know (https://rgwealth.com/insights/mega-backdoor-roth-strategies)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Mega Backdoor Roth Explained: What Is a Mega Backdoor Roth IRA? (https://dechtmanwealth.com/insights/blog/what-is-a-mega-backdoor-roth-ira)
- Record-Keeping: Essential Documentation for Mega Backdoor Roth Withdrawals
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Maintaining your retirement plan records | Internal Revenue Service (https://irs.gov/retirement-plans/maintaining-your-retirement-plan-records)
- IRA Ownership Reaches Record Highs (https://ici.org/25-view-ira-ownership-reaches-record-highs)
- 50+ Essential Retirement Statistics for 2025: Demographics (https://annuity.org/retirement/retirement-statistics)
- Making a Backdoor or Mega Backdoor Roth Contribution in 2025 (https://merceradvisors.com/insights/retirement/making-a-backdoor-or-mega-backdoor-roth-contribution-in-2025)
- Traditional vs. Mega Backdoor Roth IRA: Key Differences for Parents
- Simple, Affordable 401k Plans Built for Small and Medium-Sized Businesses | ShareBuilder 401k (https://sharebuilder401k.com/blog/what-is-the-mega-backdoor-roth)
- Mega Backdoor Roth (2025): Limits, Steps & Big Benefits (https://districtcapitalmanagement.com/mega-backdoor-roth)
- What is a Mega Backdoor Roth IRA? (https://visionretirement.com/articles/investing/what-is-a-mega-backdoor-roth-ira)
- Backdoor Roth: Standard and Mega | White Coat Investor (https://whitecoatinvestor.com/backdoor-roth-standard-and-mega-430)
- The Mega Backdoor Roth vs. the Backdoor Roth: Understanding the Differences (https://popovichfinancialgroup.com/blog/the-mega-backdoor-roth-vs-the-backdoor-roth-understanding-the-differences)
- Income Limits: How They Affect Your Mega Backdoor Roth IRA Withdrawals
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- Backdoor Roth: Standard and Mega | White Coat Investor (https://whitecoatinvestor.com/backdoor-roth-standard-and-mega-430)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- Best Practices: Managing Your Mega Backdoor Roth IRA Withdrawals Effectively
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- The Best Retirement Account Withdrawal Strategies (https://money.usnews.com/money/retirement/401ks/articles/retirement-account-withdrawal-strategies)
- IRA Withdrawal Strategies: How to Maximize Your Savings (https://covenantwealthadvisors.com/post/ira-withdrawal-strategies-how-to-maximize-your-savings)
- Retirement Plans – 7 withdrawal strategies to consider for retirement (https://nysdcp.com/rsc-preauth/learn-about-retirement/close-to-or-living-in-retirement/articles/withdrawal-strategies-to-consider-for-retirement)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading