

Key Highlights
- The W-2 form reports RSU income as ordinary income, impacting tax brackets and overall tax bills for families.
- When RSUs vest, their fair market value is included in taxable income, necessitating careful review of W-2 forms.
- The 1099-B form details proceeds from RSU sales, crucial for calculating capital gains or losses.
- Accurate cost basis documentation is essential to avoid double taxation and unexpected tax liabilities.
- The 83(b) election allows employees to pay taxes on RSUs at grant, potentially securing lower tax rates.
- Understanding vesting schedules helps families anticipate tax responsibilities and manage cash flow effectively.
- California has specific RSU tax regulations, including mandatory withholding rates that families must prepare for.
- Consulting with financial advisors can provide tailored strategies for managing RSU tax obligations and optimising financial outcomes.
- Families should gather all relevant RSU tax documents, including W-2 and 1099-B forms, for accurate tax reporting.
Introduction
It’s easy to feel overwhelmed when trying to understand Restricted Stock Units (RSUs), especially as a young parent focused on your family’s future. Knowing the key tax documents tied to RSUs can make a big difference for your family’s financial journey. In this article, we’ll explore ten important RSU tax documents that can help you feel more secure and informed as you plan for your family’s future. Let’s discover how you can feel prepared for the complexities of RSU taxation while keeping your family’s needs in focus.
W-2 Form: Reporting RSU Income
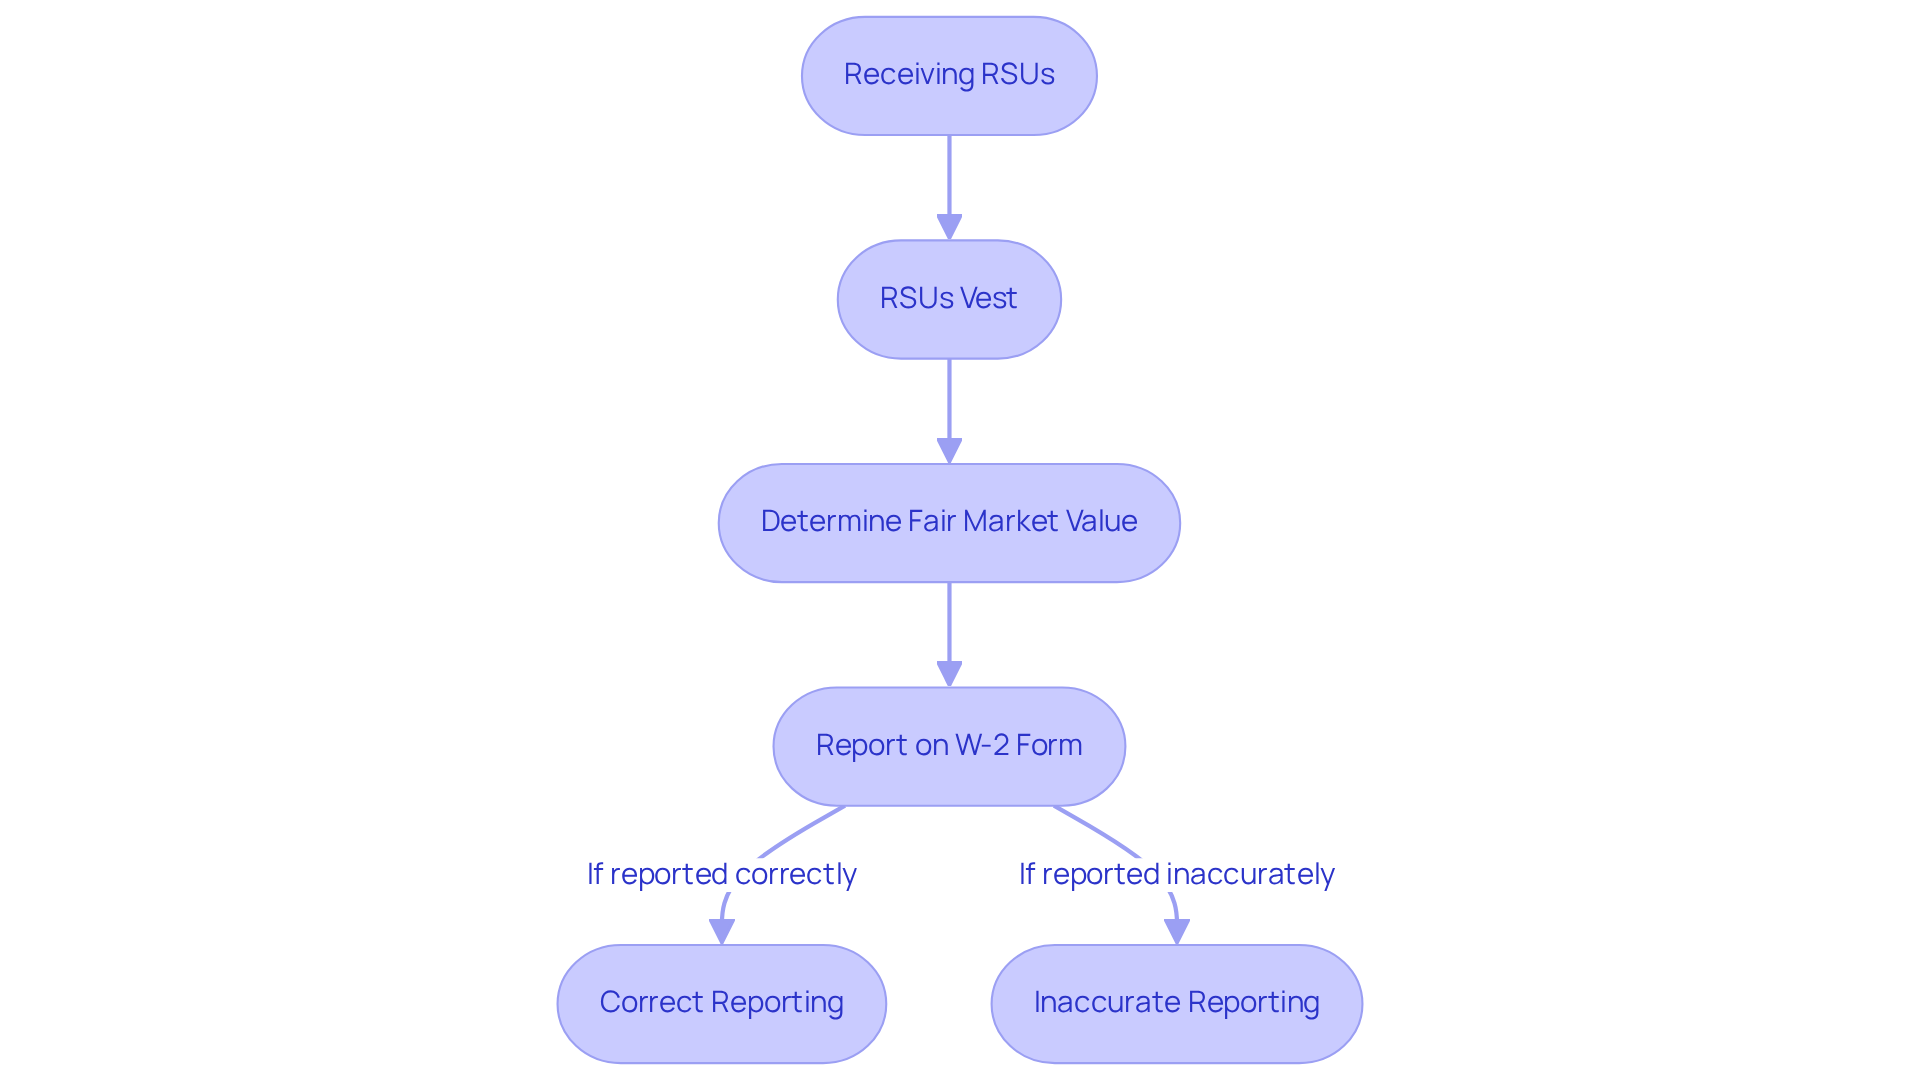
Imagine receiving a bonus that could significantly impact your family’s finances, yet feeling uncertain about how it affects your taxes. The W-2 form is a critical document issued by employers to report an employee’s annual wages and the taxes withheld from their paycheck.
For parents receiving Restricted Stock Units, the value of vested units is included in Box 1 of the W-2 as part of their taxable income. When your restricted stock units vest, their fair market value counts as ordinary income. This can really impact your family’s tax bracket and overall tax bill.
For example, if 2,500 restricted stock units vest at a stock price of $20 per share, the total fair market value of $50,000 is reported as ordinary income on the W-2. This amount is subject to federal and state income taxes, as well as payroll taxes.
So, it’s really important for parents to take a close look at their W-2 forms to make sure all RSU tax documents report RSU income correctly. Inconsistencies in reporting can lead to tax issues, making it essential to seek advice from tax experts or human resources for clarification on eligibility and conditions related to RSU tax documents.
Failing to accurately report RSU income can result in unexpected tax liabilities, impacting your family’s financial stability. Getting a handle on how RSU income affects your finances is crucial for planning effectively, especially when you’re juggling family needs and wealth management.
Remember, we’re here for you as you navigate this journey.
1099-B Form: Reporting RSU Sales and Gains
Imagine receiving a tax form that could impact your family’s financial future – it’s crucial to understand how to navigate it effectively. When you sell Restricted Stock Units, the brokerage firm issues the rsu tax documents in the form of a 1099-B. This form plays a vital role in helping you understand your family’s financial picture come tax time. It details the proceeds from the sale and any related costs, which is essential for calculating capital gains or losses.
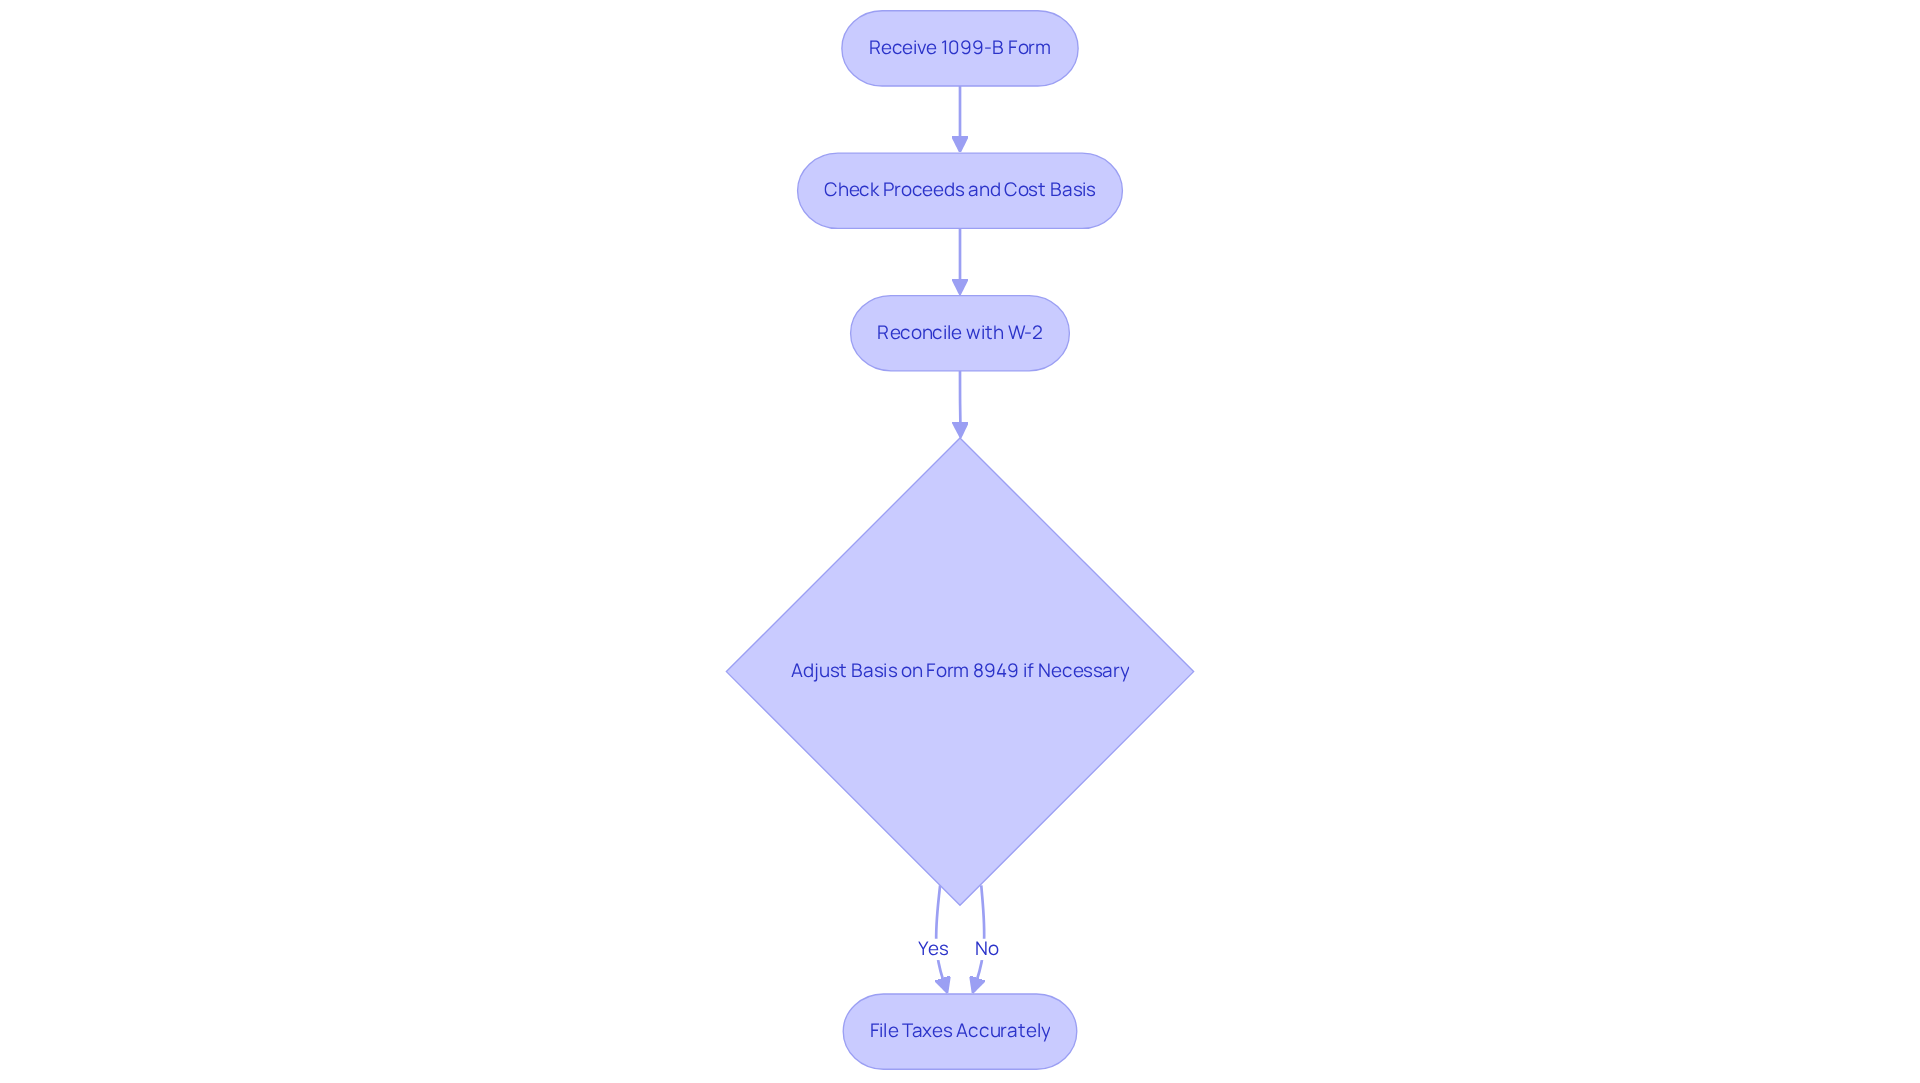
As a parent, it’s important to keep an eye on the cost basis reported on your 1099-B, because even small inaccuracies can lead to unexpected tax burdens. For instance, think of reconciling your 1099-B with your W-2 as a way to safeguard your family’s financial future – it’s a step that can prevent unnecessary stress later on.
Consider a parent who sold 1,000 shares and received a 1099-B showing $105,000 in proceeds but mistakenly reported a cost basis of $0 – this could lead to a hefty tax bill that they weren’t prepared for. By adjusting the basis on Form 8949, they ensured compliance with IRS regulations and avoided unnecessary tax liabilities.
Understanding these details, including rsu tax documents, is key for families looking to improve their financial situation, especially when dealing with the complexities of equity compensation and taxes. By taking the time to understand these details, you can protect your family’s financial well-being and avoid unnecessary stress come tax season.
83(b) Election: A Strategic Tax Option for RSUs
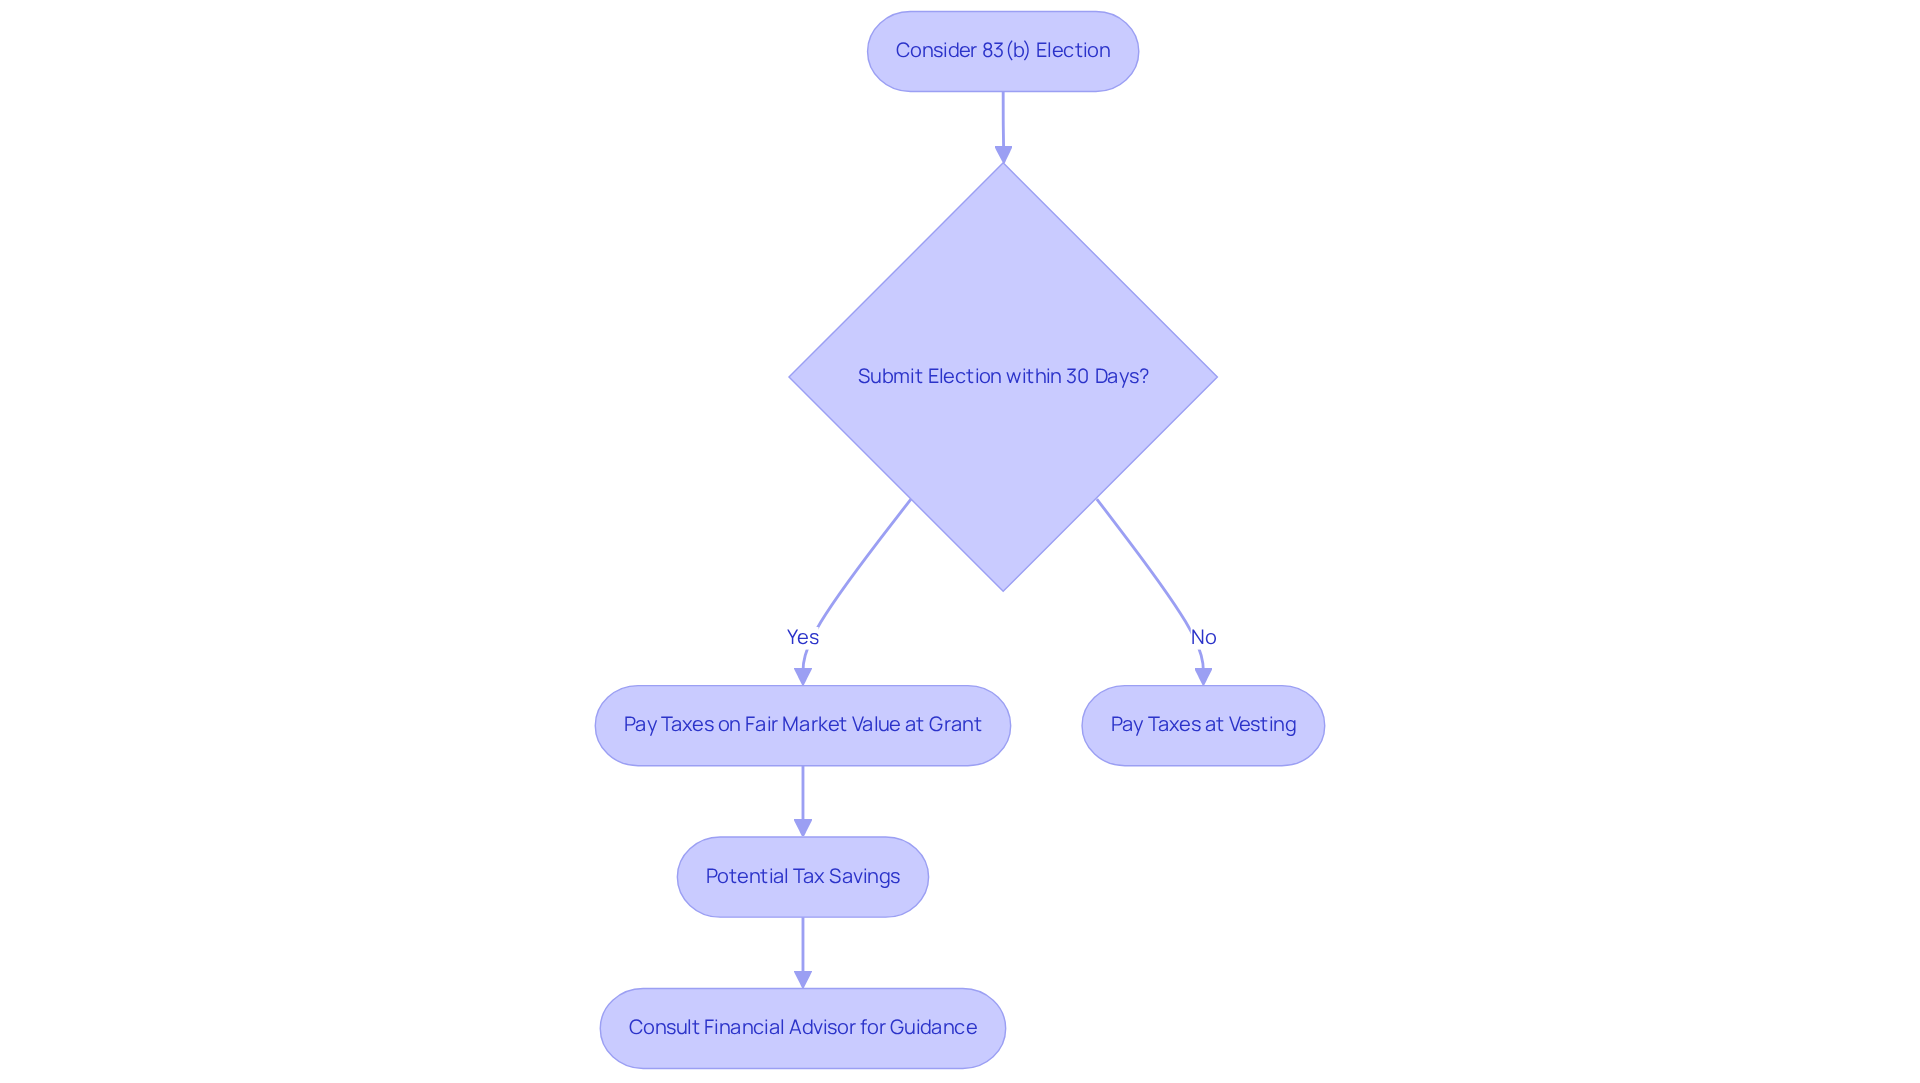
Imagine being able to ease your financial worries while planning for your family’s future. The 83(b) election allows employees to pay taxes on the fair market value of Restricted Stock Units at the time of grant, instead of at vesting. This option can really help young parents by securing a lower tax rate right from the start, especially if they expect their stock to grow.
By submitting the election within 30 days of obtaining the restricted stock units, families can potentially achieve significant tax savings, which is essential for handling future monetary obligations. Navigating tax strategies can feel overwhelming, especially when balancing family needs.
It’s important to know that grasping this option can truly make a difference for your family’s finances. Consulting with a financial advisor can help you navigate the complexities of this tax strategy effectively. With the right guidance, you can turn this tax strategy into a stepping stone for your family’s financial well-being.
Vesting Schedule: Timing and Tax Implications
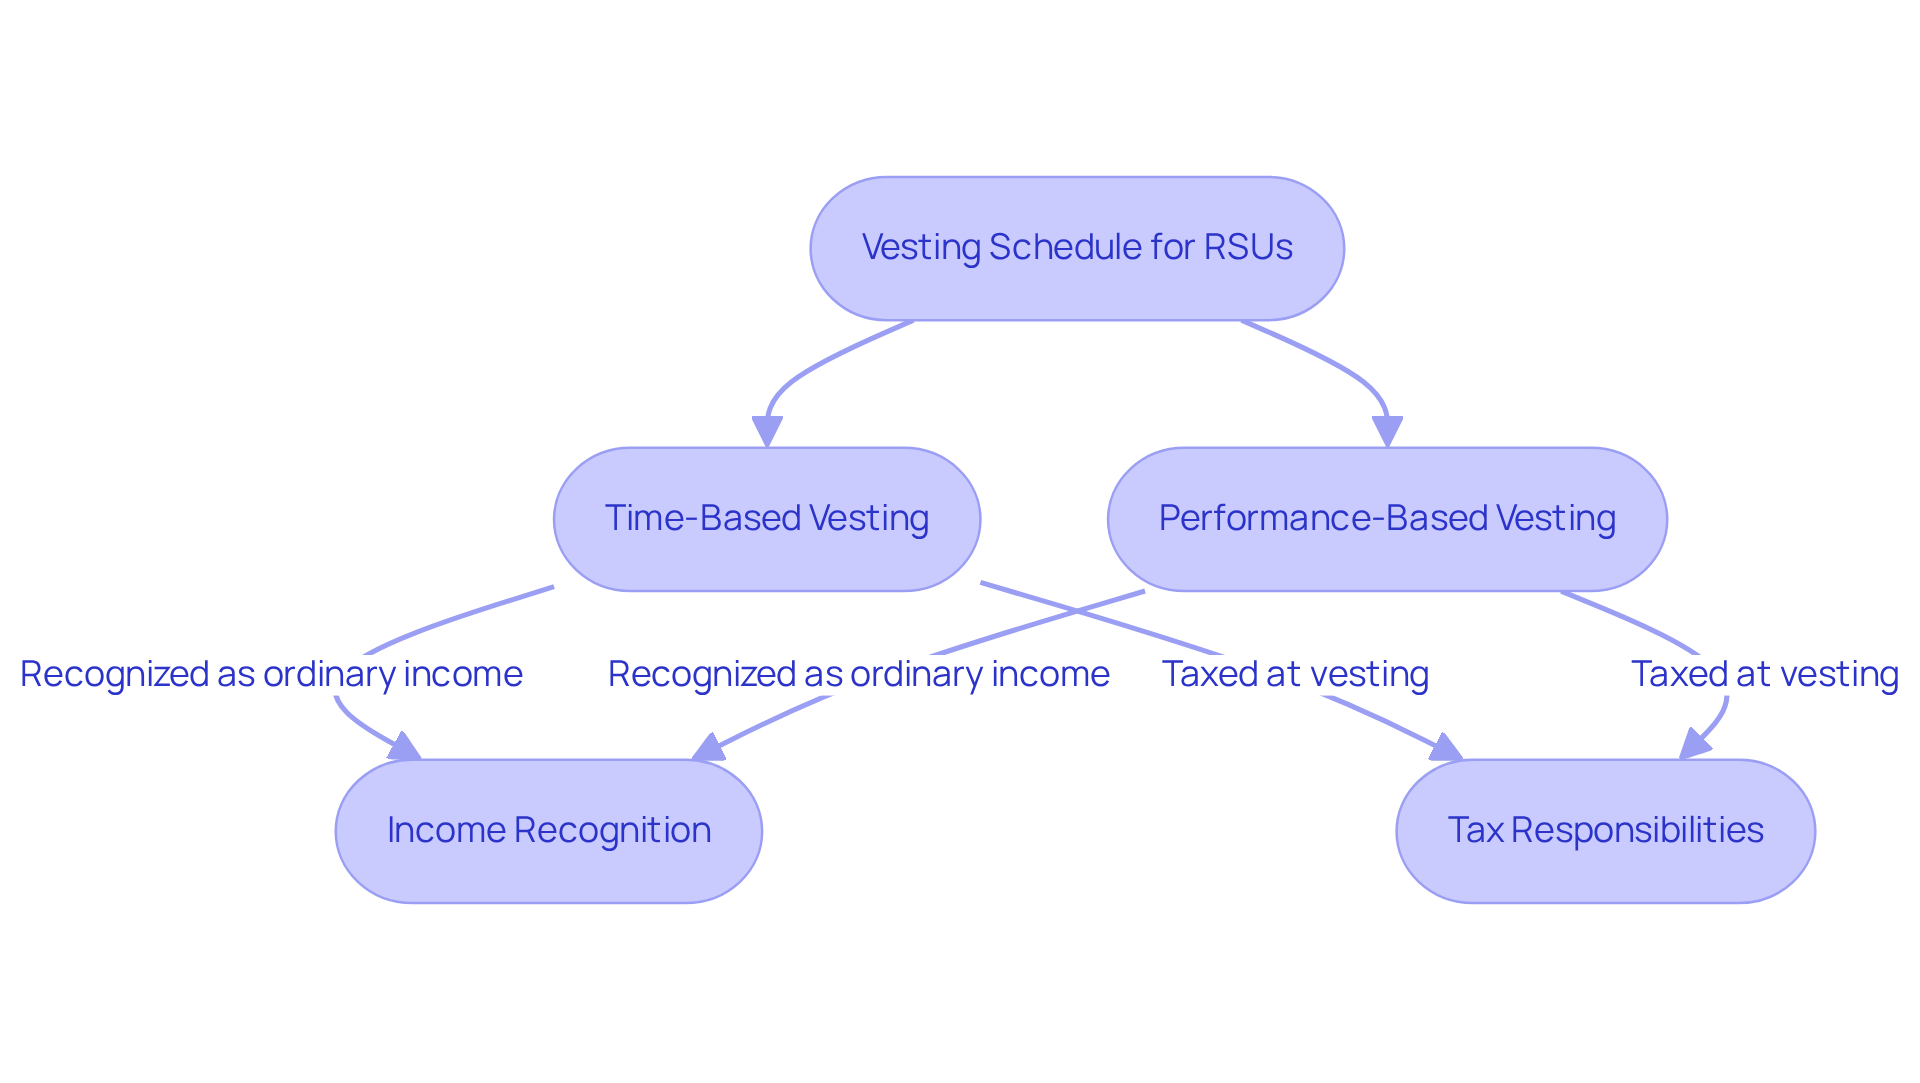
Imagine the relief of knowing exactly when your financial rewards will come, especially when you’re balancing family needs. The vesting schedule for Restricted Stock Units (RSUs) determines when you fully own your shares, often based on time or performance milestones. Each time RSUs vest, their fair market value is considered ordinary income, which can significantly impact your rsu tax documents.
For families, especially young parents, understanding this schedule is essential for effective budgeting. It enables you to foresee tax responsibilities related to rsu tax documents and adjust your cash flow and savings plans accordingly, helping to alleviate unexpected financial burdens.
For example, if an employee like Regina receives $50,000 in restricted stock units that vest, this amount is added to her income, potentially increasing her total taxable income to $150,000. Imagine the stress of unexpected tax bills when you’re already juggling family expenses.
By grasping the timing of these vesting events, families can avoid financial surprises and plan more effectively. With the right knowledge, you can turn potential financial stress into a well-planned future for your family.
Cost Basis Documentation: Essential for Accurate Reporting
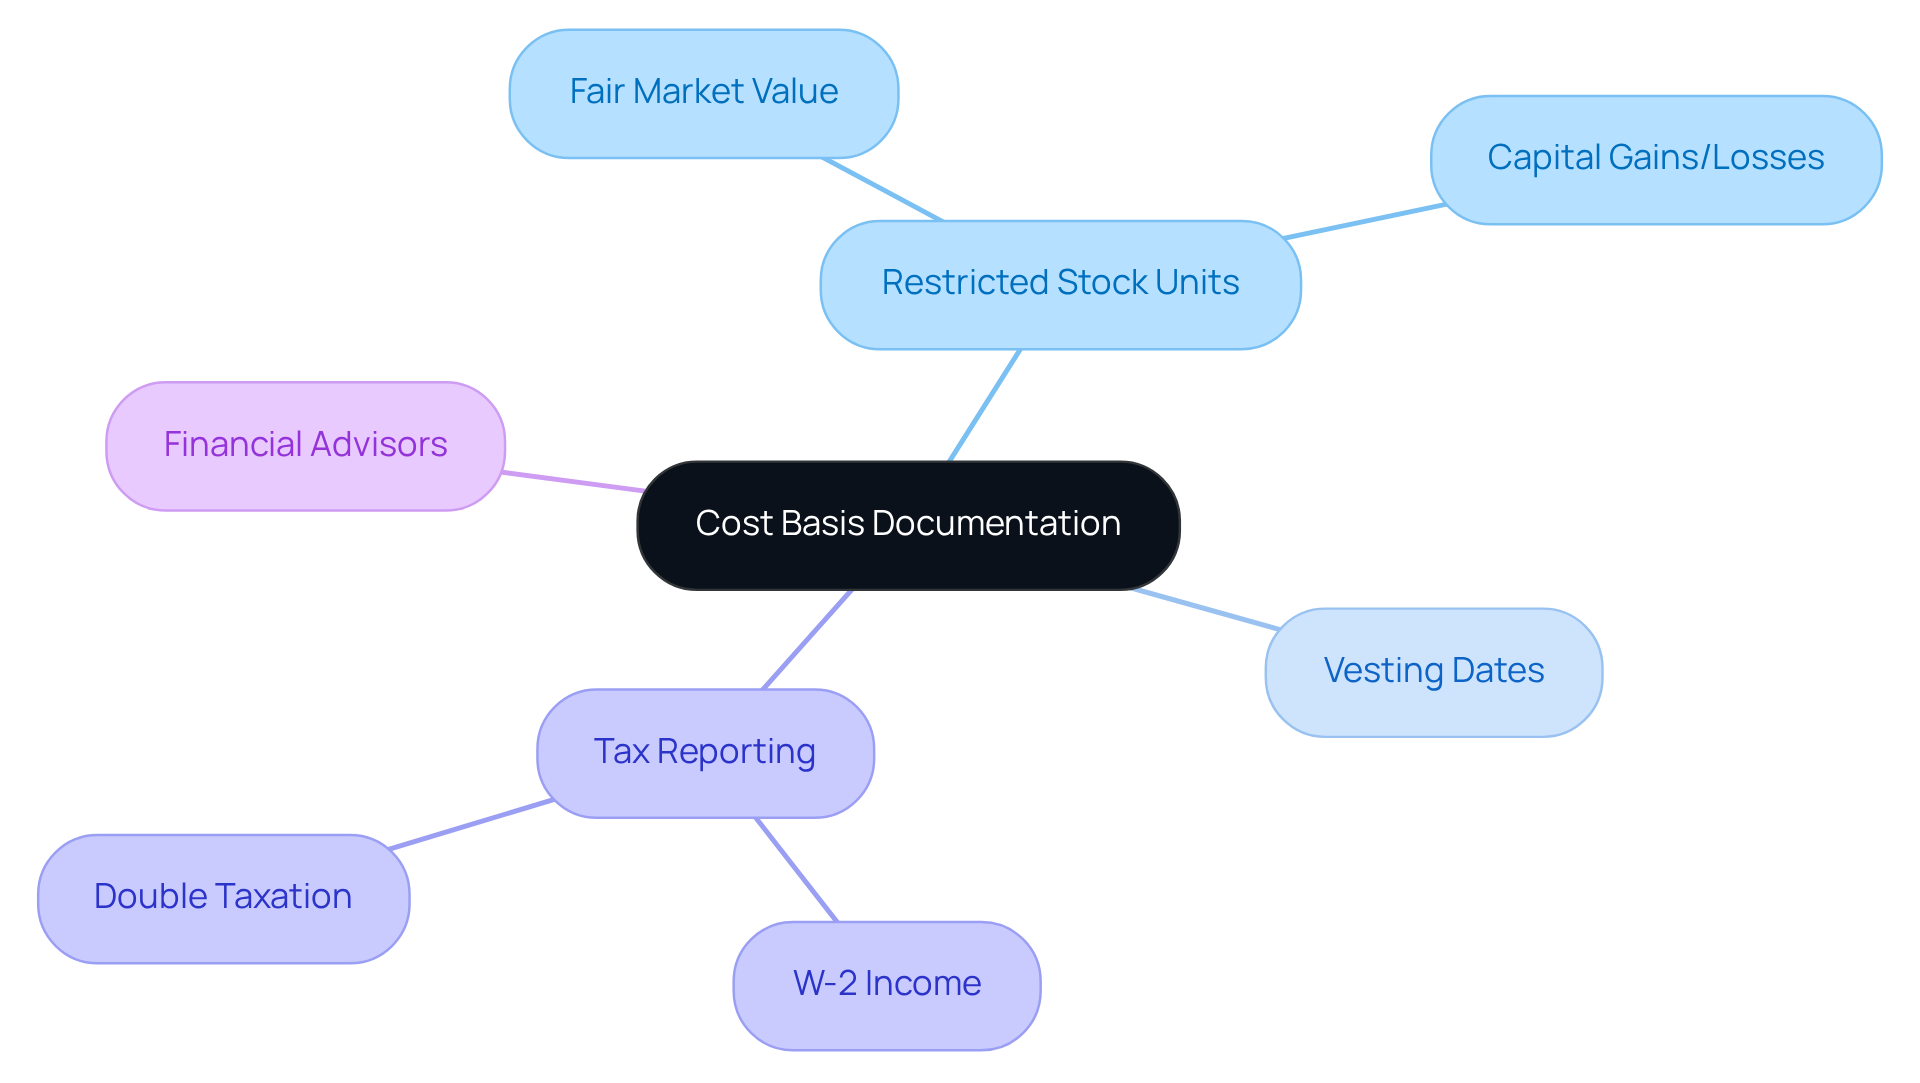
Imagine the stress of managing your family’s finances while trying to understand the complexities of Restricted Stock Units. Cost basis represents the original value of an asset, and it’s crucial for determining capital gains or losses when you sell. For Restricted Stock Units, the cost basis is usually the fair market value at the time they vest.
Keeping track of your RSU vesting dates and the stock prices is essential for accurately calculating your cost basis. These RSU tax documents are essential for your tax reporting. It helps prevent double taxation, which can lead to financial stress for your family. For instance, if 1,000 restricted stock units vest at $100 each, that’s $100,000 of W-2 income that needs to be reported correctly to avoid overpayment.
Talking to a financial advisor can help you feel more confident about how to include your RSUs in your family’s investment plans. Many clients have reported overpaying in taxes due to incorrect RSU tax documents, which highlights the importance of accurate cost basis documentation. By prioritizing this aspect of your financial planning, you can navigate the complexities of RSU taxation with greater confidence and protect your family’s financial future from unexpected tax burdens.
Capital Gains Tax Rates: Understanding RSU Implications
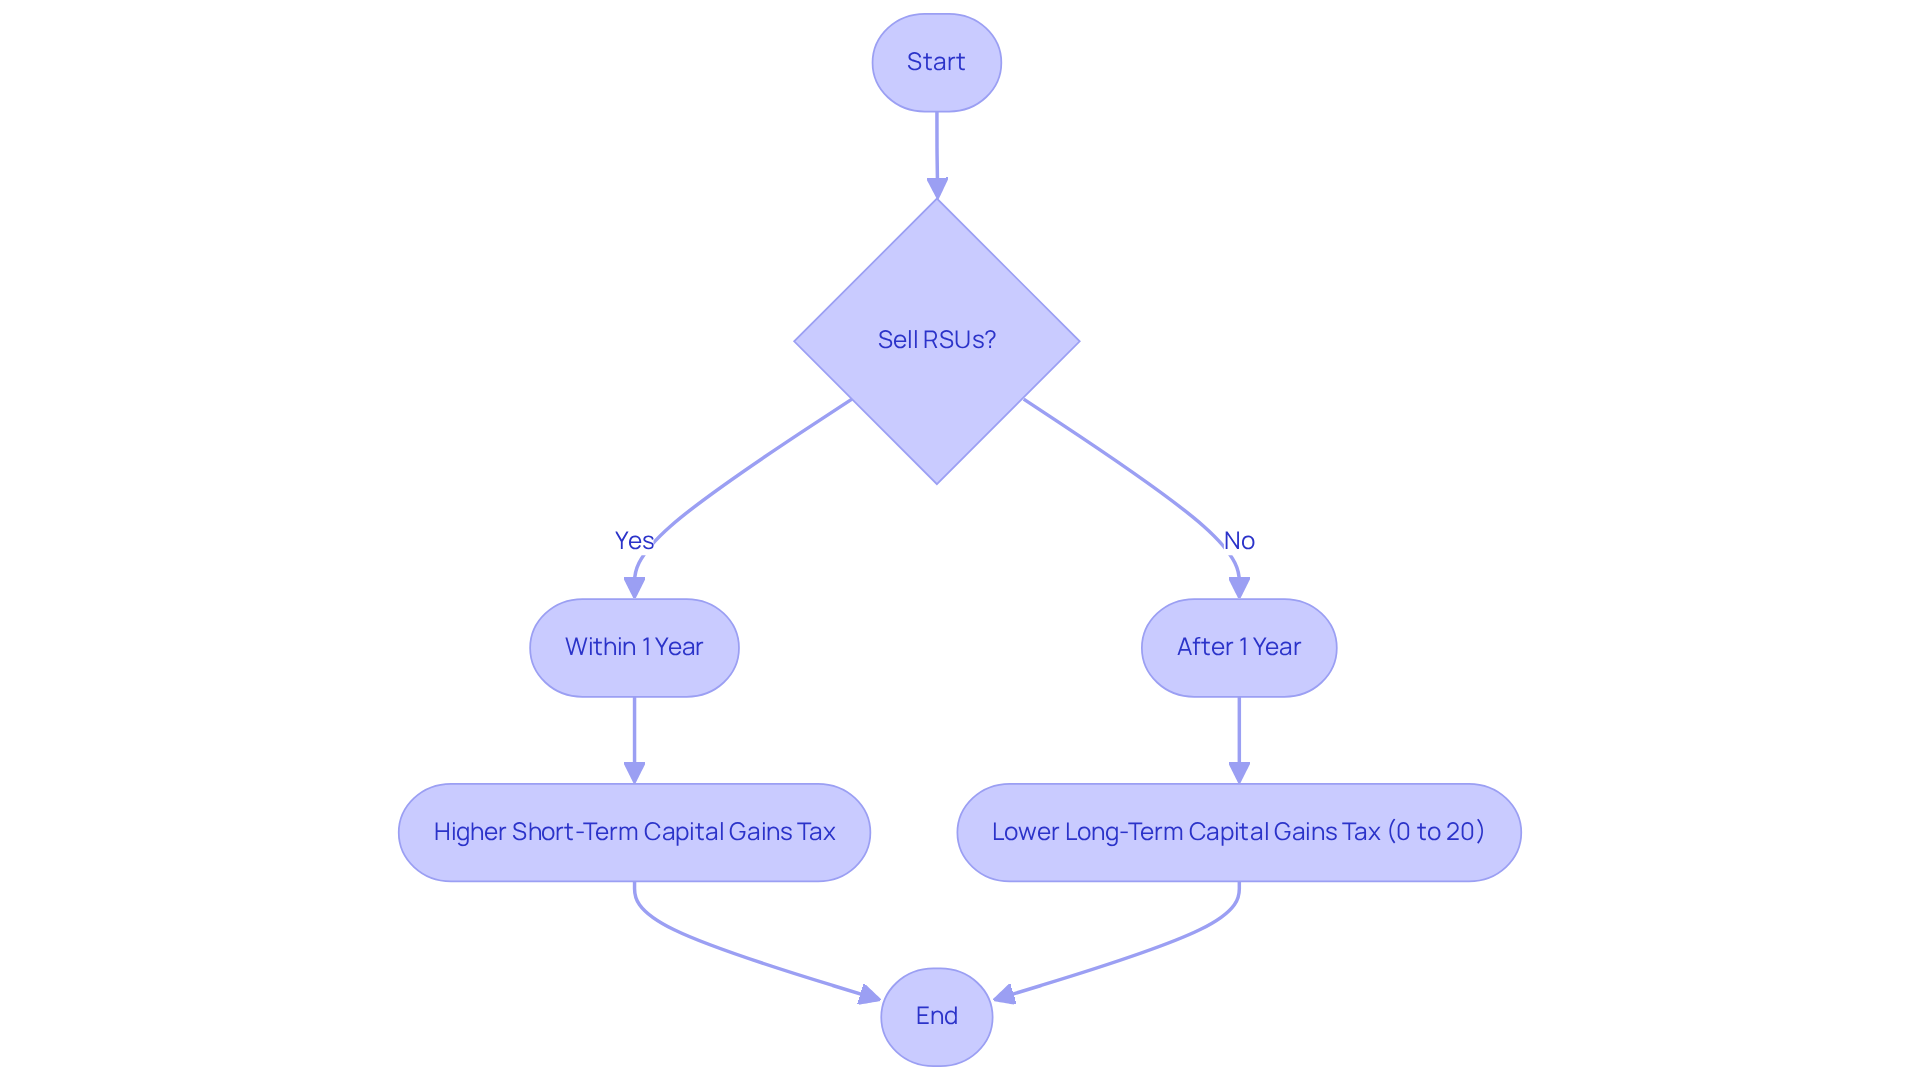
Imagine the relief of knowing you can make the most of your restricted stock units while securing your family’s future. When you sell your shares within a year, you might face higher short-term capital gains taxes, which can feel overwhelming when you’re trying to plan for your family’s future. On the flip side, if you hold onto those restricted stock units for more than a year, you can benefit from lower long-term capital gains tax rates. These rates can range from 0% to 20%, depending on your income level.
This is especially important for young parents like you, as the timing of selling your restricted stock units can significantly affect your family’s financial well-being. By holding onto your shares longer, you could potentially reduce your tax burden, freeing up more resources for important family needs like education or a new home.
Understanding these tax implications can empower you to make informed decisions that truly benefit your family’s financial journey. Together, we can navigate this path with confidence and care.
Tax Withholding Documents: Managing RSU Tax Liabilities
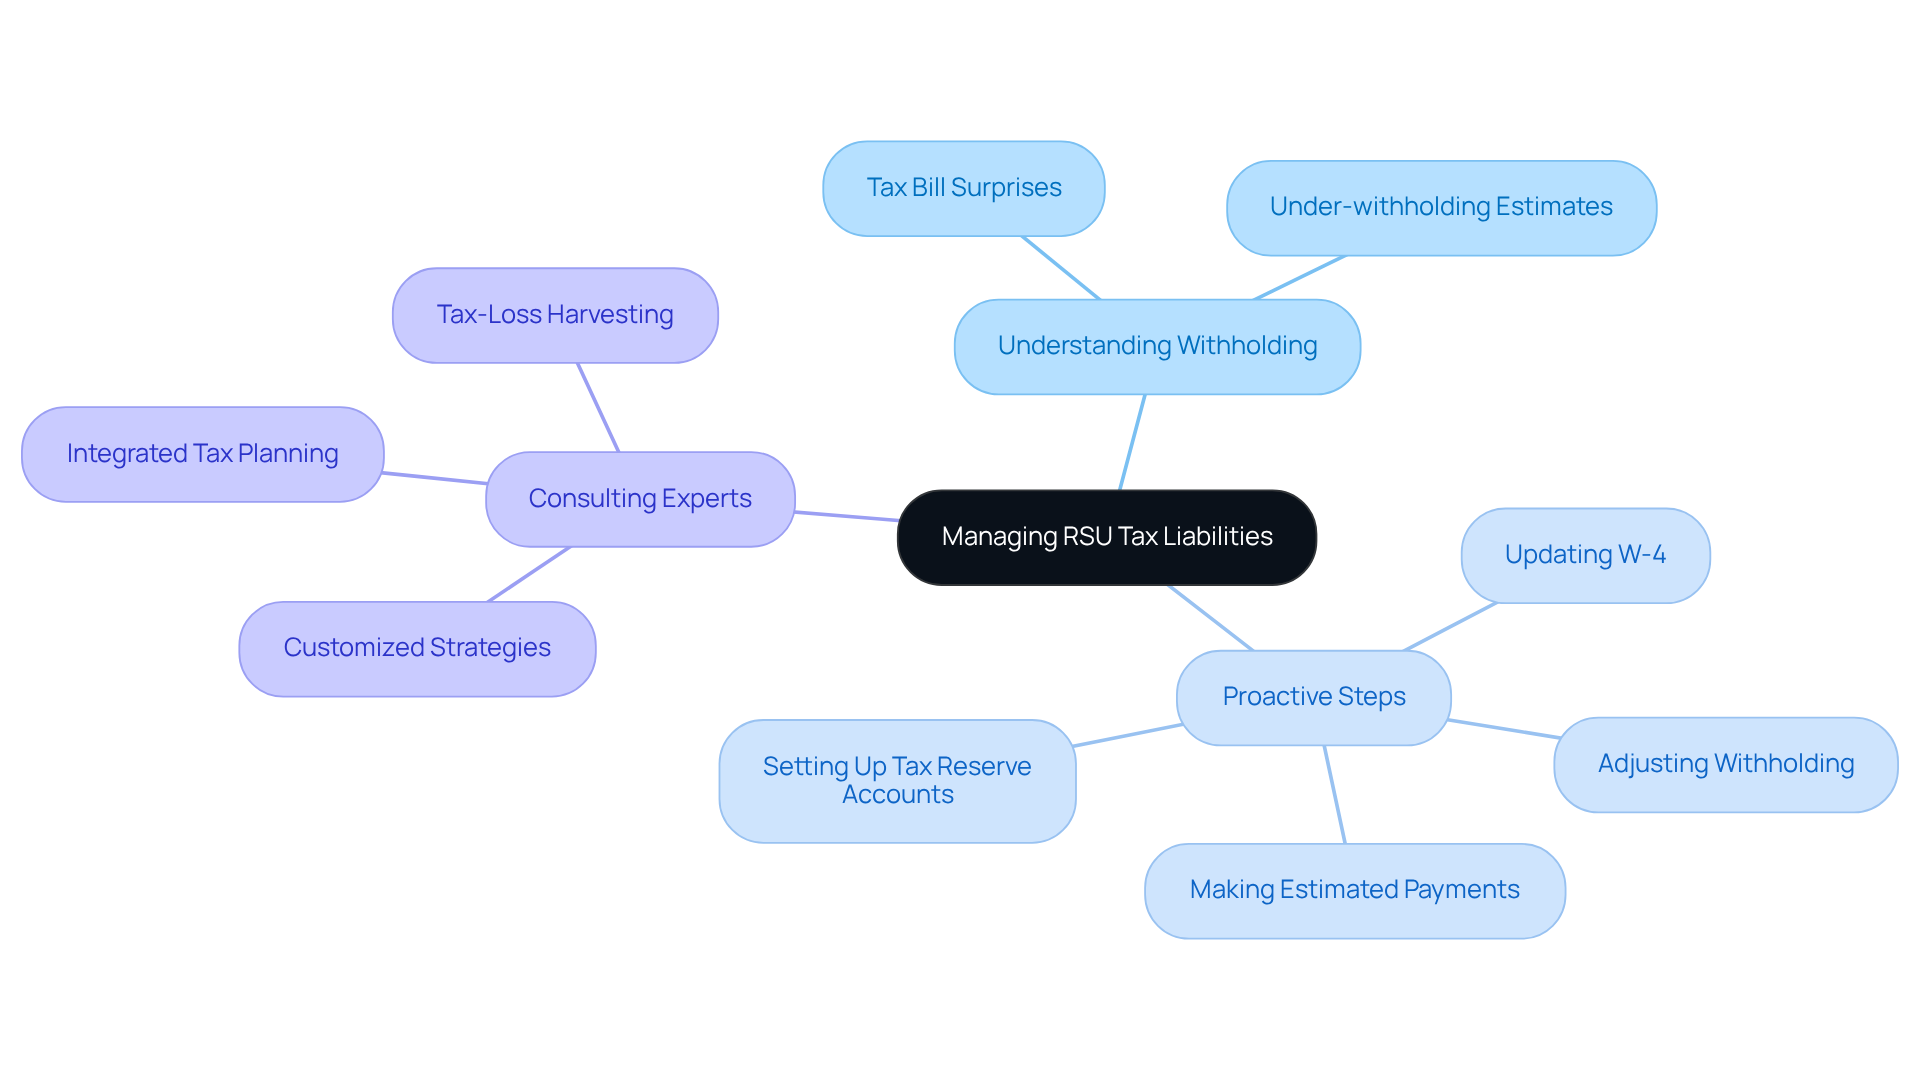
Imagine receiving an unexpected tax bill just when you thought you were on top of your finances. When restricted stock units vest, employers usually retain a portion of the shares to address tax obligations, as detailed in the rsu tax documents. It’s important to know how much is withheld when your restricted stock units vest, as this can help you understand your rsu tax documents and plan for taxes to avoid surprises later on.
Many families face unexpected tax bills due to under-withholding, which can create financial stress. Estimates suggest that many tech workers in California are under-withheld by 15-28% according to their rsu tax documents related to restricted stock units.
But there are proactive steps you can take to manage your tax obligations effectively, such as:
- Adjusting your withholding allowances
- Making estimated payments if you expect a significant tax bill due to rsu tax documents
- Updating your W-4 forms
- Setting up tax reserve accounts to better manage your tax obligations
Consulting with a qualified tax expert can offer customized strategies, such as integrated tax planning and tax-loss harvesting, to navigate these complexities.
Bright Advisers is here to help families like Jay & Emma, who want to ease financial stress and make the most of their resources. Through tailored planning and tax enhancement, Bright Advisers enables young households to attain economic stability and educational preparedness, allowing them to focus on what truly matters-your family’s future.
Tax Return Documentation: Locating RSU Information
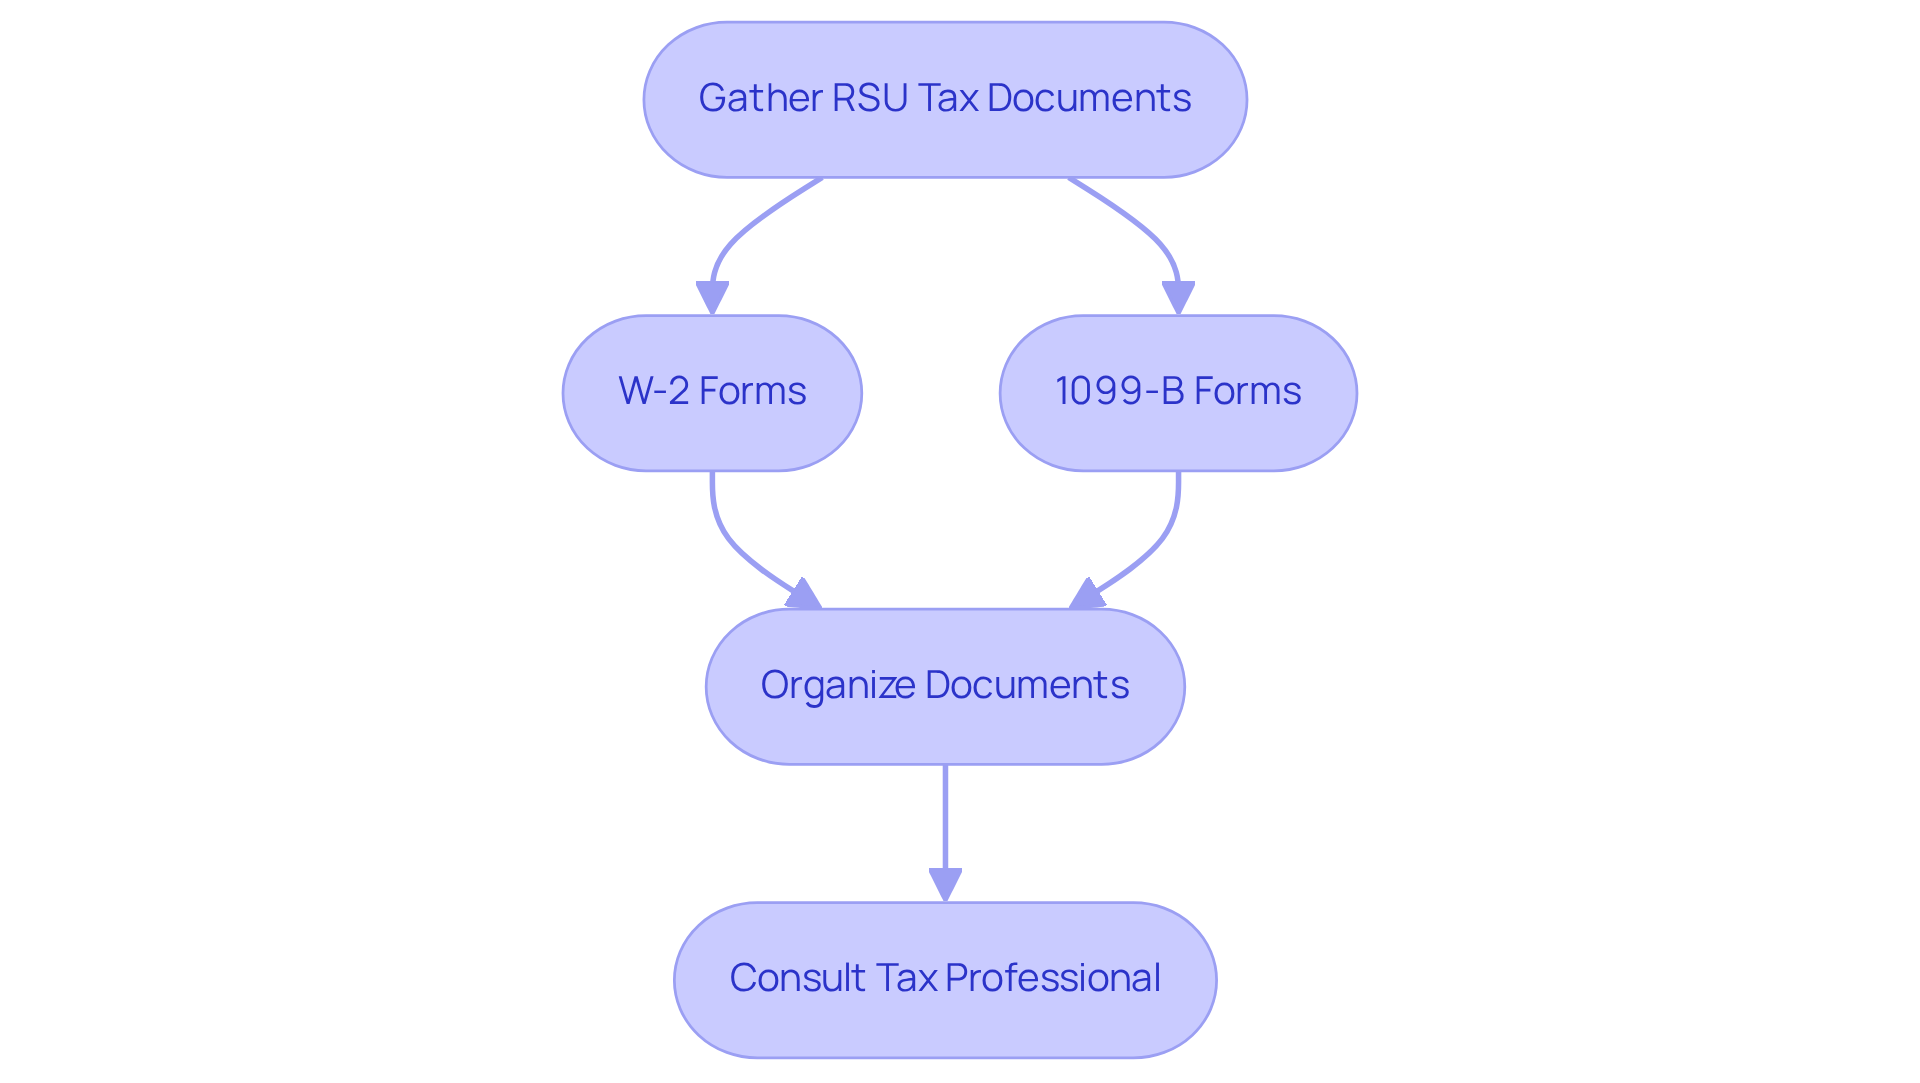
Imagine the stress of sorting through piles of paperwork while trying to manage your family’s needs. When preparing tax returns, young parents must gather all pertinent RSU tax documents related to their Restricted Stock Units. This includes W-2 forms, which report the taxable income recognized at vesting, and 1099-B forms, detailing proceeds from stock sales. Keeping your documents organized can make reporting your income and capital gains much easier.
Reaching out to a tax professional can help ease your worries about RSU tax documents and ensure you’re on the right track. Consulting with experts can guide you through the complexities, ensuring compliance and maximizing potential deductions. At Bright Advisers, we’re here to offer tailored wealth management solutions that fit your family’s unique needs, including integrated tax planning and tax-loss harvesting strategies.
Together, we can help families like Jay & Emma, Emily & Mark, and Allison & Brian achieve financial security and educational preparedness through personalized planning. With the right support, you can ensure your family’s financial future is secure and bright.
State-Specific Tax Documents: Navigating RSU Regulations
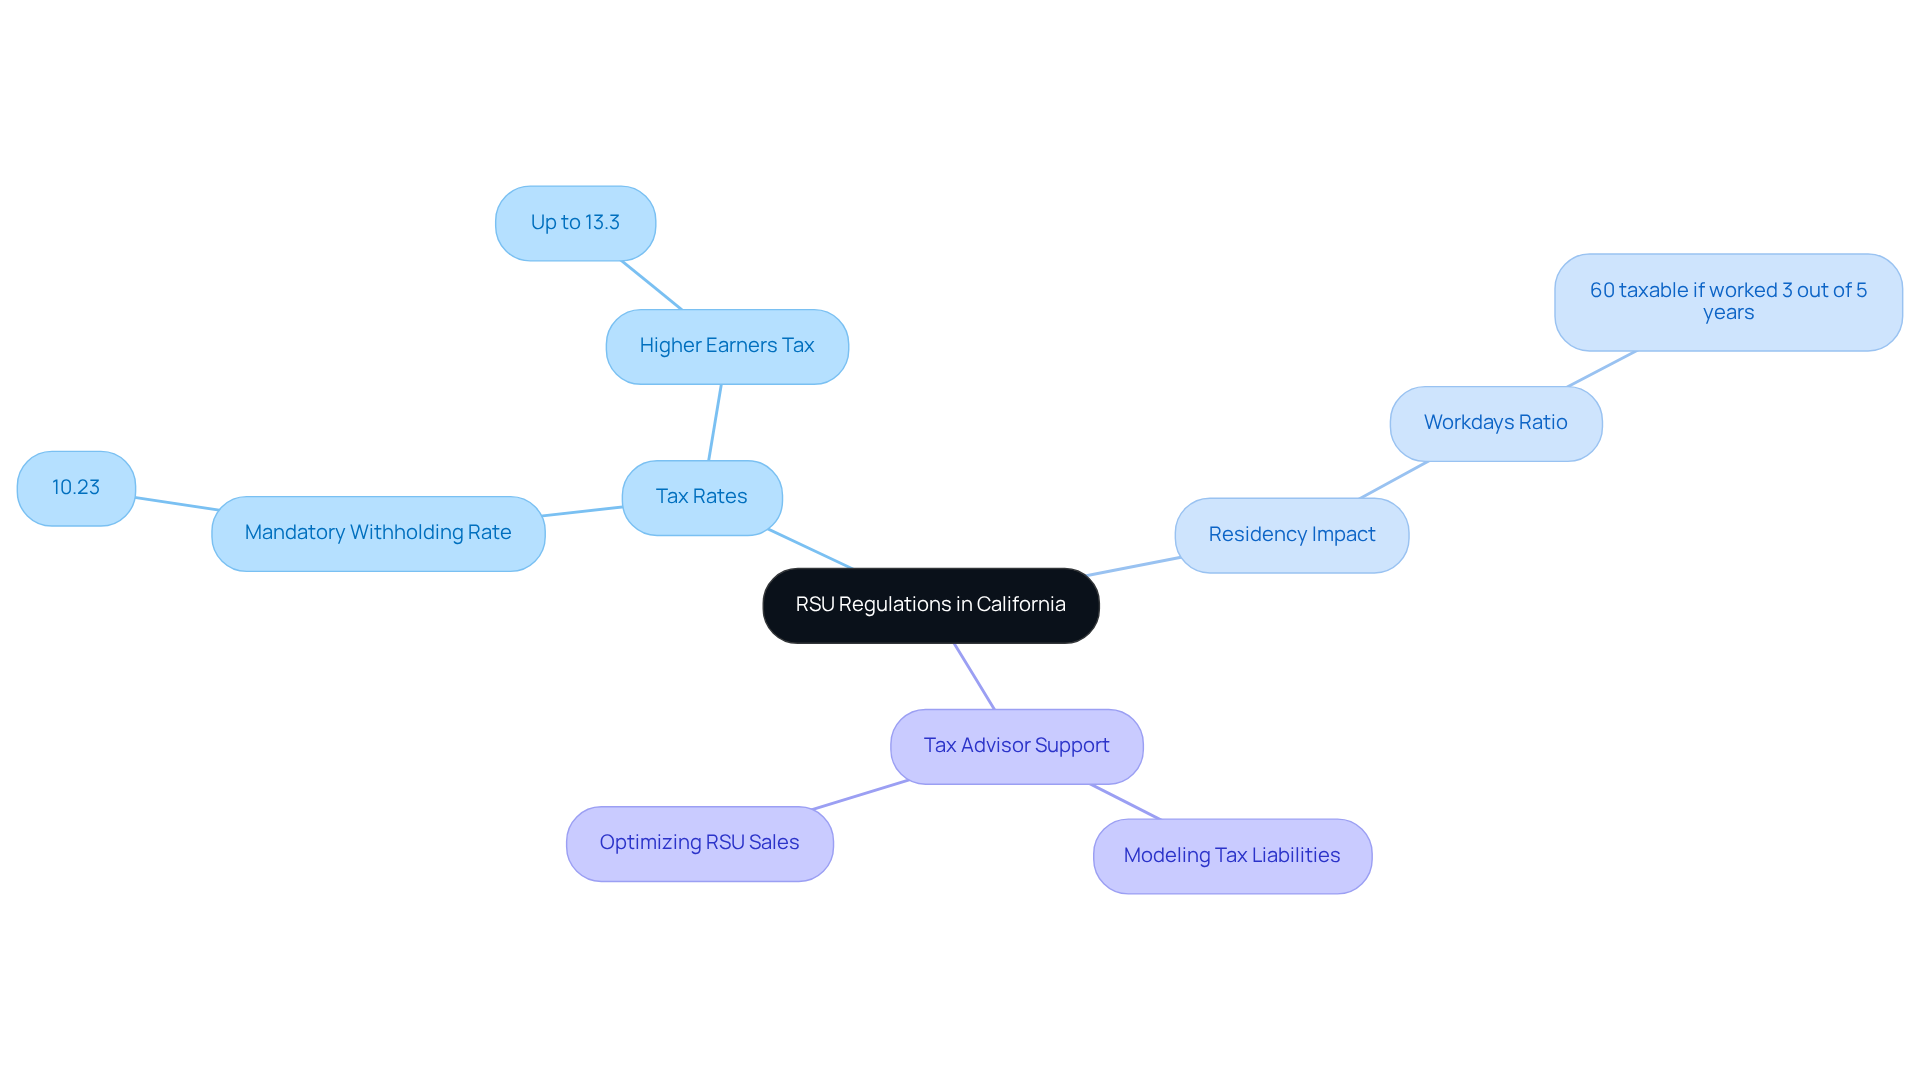
Imagine facing a tax landscape that feels overwhelming, especially when it comes to your family’s financial future. For young households in California, understanding the specific regulations around Restricted Stock Units (RSUs) is essential. California has a mandatory withholding rate of 10.23% on RSUs at vesting, which can increase to 13.3% for higher earners due to additional taxes like the Mental Health Services Tax. This means that if you’re expecting substantial RSU payouts, it’s important to prepare for a heavier tax burden, particularly if your income pushes you into a higher tax bracket.
It’s important for young parents to understand the RSU tax documents needed to report RSU income in California. The taxable portion of RSUs is determined by the ratio of workdays spent in California during the vesting period. For example, if you worked in California for three out of five years, 60% of your RSU income could be subject to California taxes, even if you relocate to a no-tax state before vesting.
Reaching out to a tax advisor who understands California’s tax landscape can make a world of difference for your family. A knowledgeable advisor can help you model your tax liabilities accurately, identify potential withholding shortfalls, and optimize RSU sales to lessen tax impacts. This proactive approach is vital for ensuring compliance with state regulations while maximizing your family’s financial outcomes.
By staying informed about the RSU tax documents in California, you can better prepare your family for the future. With the right support, you can turn these challenges into opportunities for your family’s financial growth.
Financial Advisors: Navigating RSU Tax Documents with Expert Help
Imagine the stress of managing your family’s finances while navigating the complexities of Restricted Stock Units. Hiring a financial advisor can be a game-changer for young parents like you. Financial advisors can help you understand your tax obligations and ensure you follow the law, which is crucial since vested restricted stock units are taxed as regular income.
For instance, if you have restricted stock units valued at $100,000 and face a 22% withholding rate, you might be looking at an additional $10,000 tax liability when filing, especially if your marginal tax rate is higher. Many parents feel overwhelmed by the complexities of tax obligations related to their RSUs.
With expert guidance, you can feel more confident navigating the complexities of RSU taxation. Investment consultants can assist you in understanding how RSUs influence your overall financial strategies, including retirement savings and educational funding for your children.
Without expert guidance, families risk facing unexpected tax liabilities that could strain their finances. Many families have found that collaborating with a financial advisor results in better management of their RSU tax documents. With the right support, you can turn these challenges into opportunities for your family’s financial growth.
Conclusion
Many young parents find themselves overwhelmed by the complexities of RSU tax documents, unsure of how to navigate this crucial aspect of their financial journey. By familiarizing themselves with forms like the W-2, 1099-B, and understanding the implications of the 83(b) election, families can make informed decisions that significantly impact their financial well-being. This knowledge empowers parents to manage their tax liabilities effectively, ensuring they are prepared for the financial responsibilities that come with restricted stock units.
Throughout this article, we’ve shared key insights about:
- The importance of accurate reporting
- The timing of vesting schedules
- The necessity of maintaining proper documentation
Each of these elements plays a vital role in safeguarding your family’s financial future, helping to avoid unexpected tax burdens and ensuring compliance with state-specific regulations. Engaging with a financial advisor can further enhance your understanding and provide tailored strategies that align with your family’s needs.
This journey isn’t just about ticking boxes; it’s about building a secure financial future for your family. By taking proactive steps and seeking expert guidance, families can turn potential financial hurdles into stepping stones toward a brighter future together. Embracing this knowledge allows young parents to focus on what truly matters – nurturing their families and building a prosperous future together.
Frequently Asked Questions
What is a W-2 form and how does it relate to RSU income?
A W-2 form is a document issued by employers to report an employee’s annual wages and the taxes withheld from their paycheck. For parents receiving Restricted Stock Units (RSUs), the value of vested units is included in Box 1 of the W-2 as part of their taxable income, impacting their tax bracket and overall tax bill.
How is the value of vested RSUs reported on the W-2 form?
When RSUs vest, their fair market value is counted as ordinary income and reported on the W-2 form. For example, if 2,500 RSUs vest at a stock price of $20 per share, the total fair market value of $50,000 is reported as ordinary income, subject to federal and state income taxes, as well as payroll taxes.
Why is it important to check the W-2 form for RSU income?
It is crucial to review the W-2 form to ensure that all RSU tax documents report RSU income correctly. Inaccuracies can lead to tax issues, making it essential to seek advice from tax experts or human resources for clarification on eligibility and conditions related to RSU tax documents.
What is a 1099-B form and how does it relate to RSU sales?
A 1099-B form is issued by brokerage firms when you sell RSUs. It details the proceeds from the sale and any related costs, which is essential for calculating capital gains or losses, impacting your family’s financial picture during tax time.
What should parents be cautious about when reviewing their 1099-B form?
Parents should pay close attention to the cost basis reported on their 1099-B, as inaccuracies can lead to unexpected tax burdens. Reconciling the 1099-B with the W-2 can help prevent unnecessary stress and financial issues later on.
What is the 83(b) election and how can it benefit families?
The 83(b) election allows employees to pay taxes on the fair market value of RSUs at the time of grant instead of at vesting. This option can help families secure a lower tax rate early on, especially if they expect their stock to grow, potentially leading to significant tax savings.
How can families effectively navigate the complexities of RSU taxation?
Consulting with a financial advisor can help families understand and navigate the complexities of RSU taxation and strategies like the 83(b) election, ensuring they make informed decisions that benefit their financial well-being.
List of Sources
- W-2 Form: Reporting RSU Income
- Stock-based compensation: Tax forms and implications (https://thetaxadviser.com/newsletters/2024/jan/stock-based-compensation-tax-forms-and-implications)
- RSU and stock grant tax guide (https://instead.com/resources/blog/rsu-and-stock-grant-tax-guide)
- How to Report RSUs or Stock Grants on Your Tax Return (https://turbotax.intuit.com/tax-tips/investments-and-taxes/how-to-report-rsus-or-stock-grants-on-your-tax-return/L55yZieu0)
- Year-End Tax Reporting Questions Answered – Equity Compensation (https://naspp.com/blog/year-end-tax-reporting-questions-answered-equity-compensation)
- SOI Tax Stats Individual Information Return Form W2 Statistics | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-individual-information-return-form-w2-statistics)
- 1099-B Form: Reporting RSU Sales and Gains
- #1 Tax Trap for RSUs – John McCarthy, CPA (https://johnmccarthycpa.com/1-tax-trap-for-restricted-stock-units-rsus)
- RSU Sales and 1099-B Errors: How to Avoid Double Taxation with Form 8949 (https://vipwealthadvisors.com/insights/rsu-tax-reporting-1099b-form-8949)
- Don’t Pay Tax Twice on RSU Sales (https://savantwealth.com/savant-views-news/article/dont-pay-tax-twice-on-rsu-sales)
- 5 Bad Tax-Return Mistakes To Avoid With RSUs, Stock Options, And ESPPs (https://forbes.com/sites/brucebrumberg/2026/02/05/5-bad-tax-return-mistakes-to-avoid-with-rsus-stock-options-and-espps)
- RSU Sales and 1099-B Errors: How to Avoid Double Taxation with Form 8949 (https://vipwealthadvisors.com/insights/rsu-tax-reporting-1099b-form-8949?hs_amp=true)
- 83(b) Election: A Strategic Tax Option for RSUs
- Essential Startup IPO Tax Planning for High-Income Earners – Bright Advisers (https://brightadvisers.com/essential-startup-ipo-tax-planning-for-high-income-earners)
- When to Pay Taxes on Restricted Stock Awards (https://schwab.com/learn/story/when-to-pay-taxes-on-restricted-stock-awards)
- Restricted Shares Defined (2025): How Does It Work? (https://thetradinganalyst.com/restricted-shares)
- Understanding The 83(b) Election and Restricted Stock | RGWM (https://rgwealth.com/insights/restricted-stock-and-the-83b-election-2)
- Vesting Schedule: Timing and Tax Implications
- An RSU Vesting Guide: Understanding Your Restricted Stock Unit Vesting Schedule (https://summitry.com/blog/rsu-vesting-schedules)
- Restricted Stock Unit (RSU) Tax Guide: Vesting, Selling & Reporting (https://summitry.com/blog/how-are-rsus-taxed)
- Tax Treatment of Your Restricted Stock Units (RSUs) – Vesting Can Be Taxing (https://blog.bakerave.com/blog/vesting-rsu-tax?hs_amp=true)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Cost Basis Documentation: Essential for Accurate Reporting
- RSU Cost Basis: How to Calculate It and Avoid the Double-Tax Mistake (https://kbfinancialadvisors.com/rsu-cost-basis-tech-employees-guide)
- RSU Sales and 1099-B Errors: How to Avoid Double Taxation with Form 8949 (https://vipwealthadvisors.com/insights/rsu-tax-reporting-1099b-form-8949)
- RSU Cost Basis Is Wrong on Your 1099 — How to Fix It and Avoid Double Taxation – Powwow, LLC (https://powwowllc.com/investing/rsu-cost-basis-is-wrong-on-your-1099)
- Capital Gains Tax Rates: Understanding RSU Implications
- How RSU Or Stock Gains Are Taxed: A Detailed Guide (https://blog.thayerpartnersllc.com/how-rsu-or-stock-gains-are-taxed-a-detailed-guide-with-a-real-world-example)
- RSU Taxes Explained and 4 Tax Strategies for 2023 (https://ceritypartners.com/insights/rsu-taxes-explained-and-4-tax-strategies-for-2023)
- How RSUs Are Taxed — And 3 Tax-Savvy Steps to Take – NerdWallet (https://nerdwallet.com/investing/learn/how-are-rsus-taxed)
- A Guide to the Capital Gains Tax Rates: Short-term vs. Long-term Capital Gains Taxes (https://turbotax.intuit.com/tax-tips/investments-and-taxes/guide-to-short-term-vs-long-term-capital-gains-taxes-brokerage-accounts-etc/L7KCu9etn)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Tax Withholding Documents: Managing RSU Tax Liabilities
- RSUs and California Tax (https://savantwealth.com/savant-views-news/article/rsus-and-california-tax)
- California RSU Tax Calculator 2026: Equity Tax Savings (https://sdocpa.com/rsu-tax-calculator-california)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- RSU tax in California: What you need to know (https://wise.com/gb/blog/rsu-california-tax)
- Tax Return Documentation: Locating RSU Information
- How to Report RSUs or Stock Grants on Your Tax Return (https://turbotax.intuit.com/tax-tips/investments-and-taxes/how-to-report-rsus-or-stock-grants-on-your-tax-return/L55yZieu0)
- RSU and stock grant tax guide (https://instead.com/resources/blog/rsu-and-stock-grant-tax-guide)
- Restricted Stock and Performance Stock Taxes: A Guide (https://schwab.com/learn/story/rsu-taxes-and-psu-taxes)
- Stock Market News & Investing Research | The Motley Fool (https://fool.com/taxes/2015/03/01/the-average-american-spends-this-much-time-on-thei.aspx)
- Average American Spends 13 Hours and $290 to File Taxes (https://ntu.org/foundation/detail/taxpayers-will-spend-71-billion-hours-464-billion-on-tax-compliance-in-2025)
- State-Specific Tax Documents: Navigating RSU Regulations
- California RSU Tax Rate: Strategies for Young Families – Bright Advisers (https://brightadvisers.com/california-rsu-tax-rate-strategies-for-young-families)
- How Restricted Stock Units (RSUs) are Taxed in California – Summitry (https://summitry.com/blog/rsu-taxes-in-california)
- California RSU Tax Guide 2026: Withholding Rate, SDI, and the $1M Trap (https://countrytaxcalc.com/tax-guides/california-rsu-tax-guide-2026)
- RSU tax in California: What you need to know (https://wise.com/gb/blog/rsu-california-tax)
- RSUs and California Tax (https://savantwealth.com/savant-views-news/article/rsus-and-california-tax)
- Financial Advisors: Navigating RSU Tax Documents with Expert Help
- Financial Planning With Restricted Stock Units: 3 Key Questions | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/restricted-stock-units-and-financial-planning)
- RSUs 101: A Tech Professional’s Guide to Equity, Tax Strategy, and Financial Planning (https://merceradvisors.com/investing/rsus-101-a-tech-professionals-guide-to-equity-tax-strategy-and-financial-planning)
- Tax And Financial Planning Strategies For Employees Receiving RSUs (https://forbes.com/sites/cicelyjones/2024/07/01/tax-and-financial-planning-strategies-for-employees-receiving-rsus)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading