

Key Highlights:
- Bright Advisers offers guidance on navigating the complexities of 529 plan ownership transfers to secure children’s educational futures.
- 529 plans provide tax-advantaged savings for educational expenses, allowing contributions to grow tax-free and withdrawals for eligible costs to be tax-free.
- Ownership transfer of a 529 plan allows flexibility in beneficiary designation, enabling families to adapt to changing educational needs.
- Many states offer tax deductions for contributions to 529 accounts, enhancing their appeal for families saving for education.
- The process of transferring ownership typically requires filling out a transfer form and submitting documentation, with many states permitting changes once a year without penalties.
- Tax implications of ownership transfers can arise if the transfer is considered a gift, necessitating awareness of gift tax exclusions and exemptions.
- Common mistakes in the transfer process include ignoring state-specific rules, neglecting tax consultation, and failing to document the transfer accurately.
- Benefits of transferring ownership include increased flexibility, potential tax advantages, alignment with educational goals, and enhanced control over funds.
Introduction
Navigating the complexities of 529 plan ownership transfers can feel overwhelming for many families. Yet, understanding these essential processes is vital for securing your child’s educational future. In this article, we’ll explore ten vital tips designed to empower you as parents and guardians, helping you make informed decisions about transferring ownership of your 529 accounts.
Imagine if you could simplify this process and ensure that your child’s education is well-funded. What happens when the stakes are high, and the rules seem daunting? By uncovering common pitfalls and expert advice, you’ll discover strategies to streamline the transfer process. This way, you can maximize tax benefits while aligning your educational goals with your financial planning.
We’re here for you, ready to guide you through this journey. Together, we can navigate the intricacies of 529 plans, ensuring that your family’s future is bright and secure.
Bright Advisers: Expert Guidance on 529 Plan Ownership Transfers
Navigating the world of 529 transfer ownership can feel overwhelming, but Bright Advisers is here to assist you every step of the way. We understand that as a parent, your focus is on securing your child’s educational future, and we’re dedicated to guiding you through the complexities of financial planning with care and compassion.
Imagine if you could fully grasp your options and the potential outcomes of your decisions regarding 529 accounts. By prioritizing personalized financial planning, we empower you to make informed choices that align with your long-term educational savings goals. It’s essential to understand the intricacies of these accounts, as they can significantly impact your family’s financial approach.
Successful strategies for 529 transfer ownership often involve open communication among family members and seeking advice from financial professionals. With our support, you can navigate this process effectively, ensuring that everyone is on the same page. We utilize scientific investment techniques and tailor portfolios to enhance the management of your 529 accounts, seamlessly integrating them with your broader parenting strategies.
Families committed to securing their children’s educational futures can confidently tackle financial complexities with Bright Advisers by their side. Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial decisions.
As a practical step, consider arranging a consultation with one of our caring financial advisors. We’re here for you to explore your specific 529 account choices and develop effective strategies for 529 transfer ownership. Let’s work together to create a brighter future for your children.

Understanding 529 Plans: Basics and Benefits
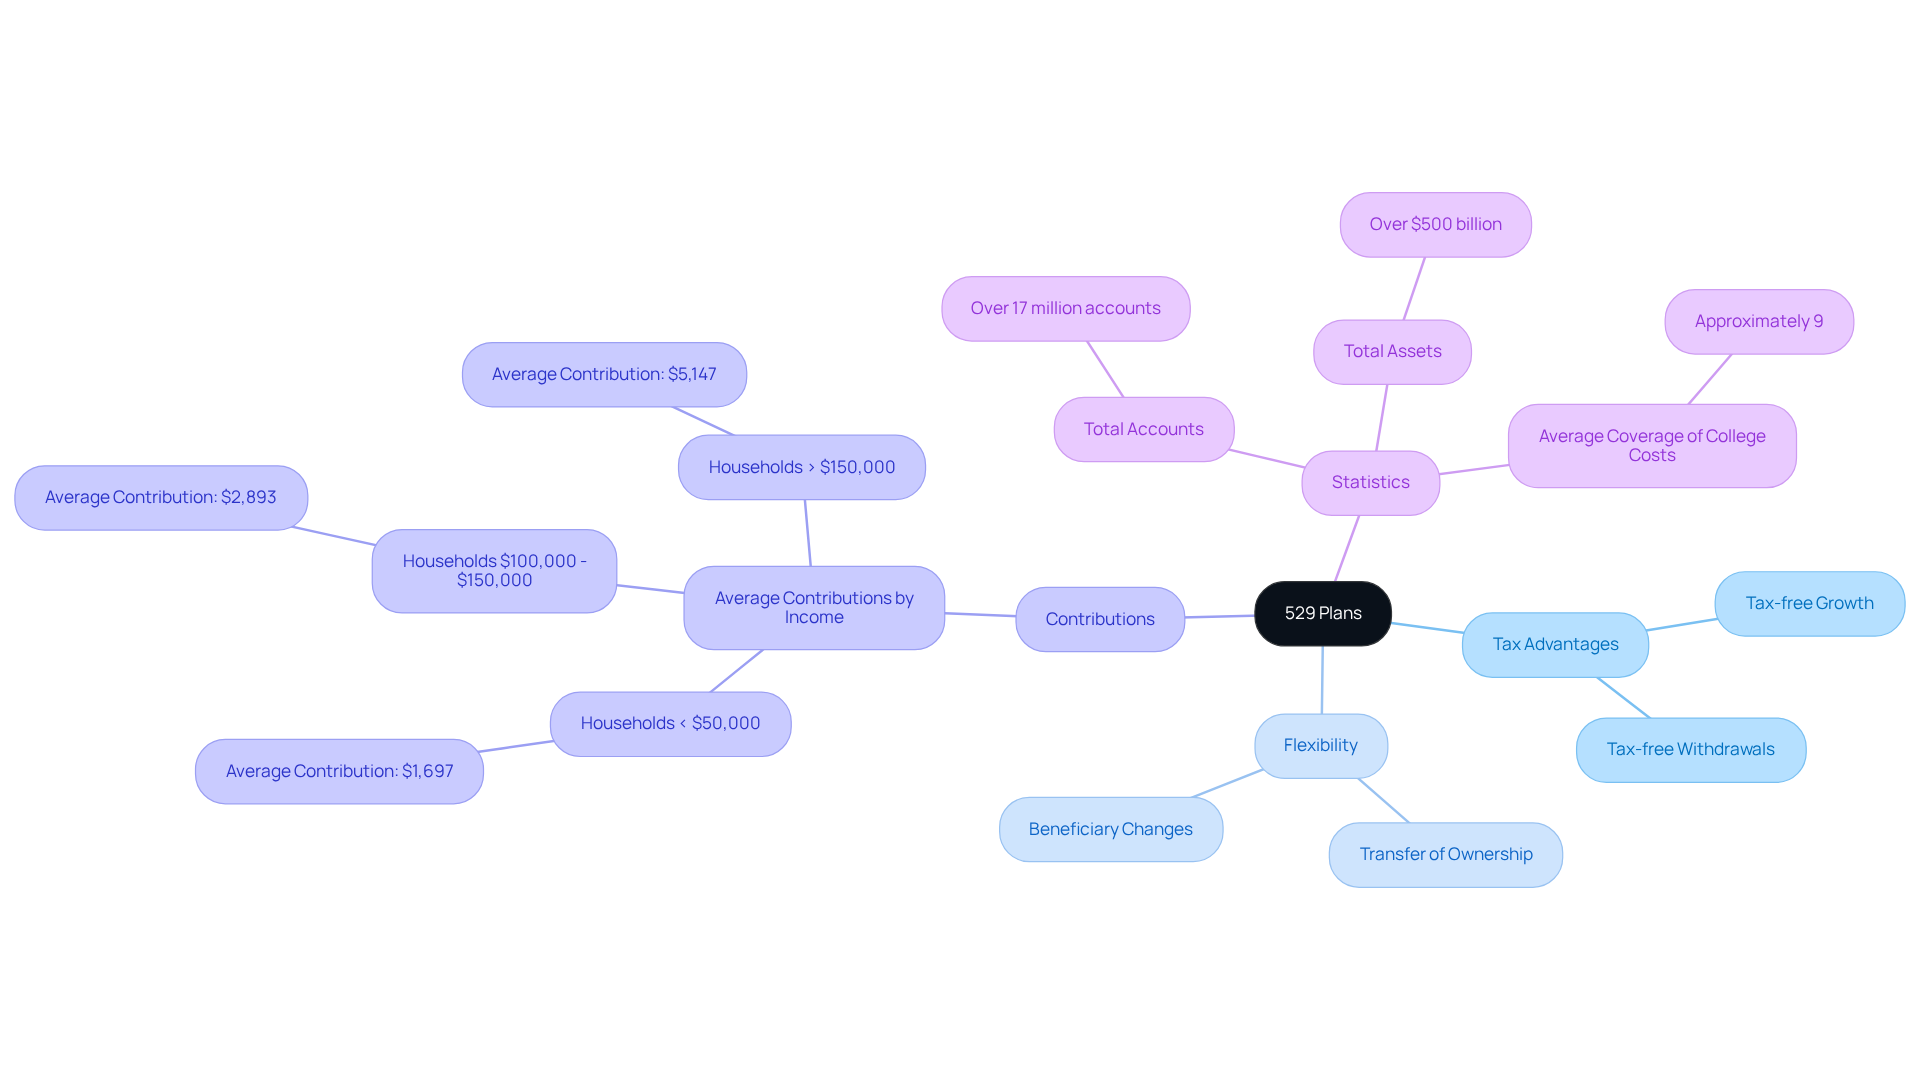
A 529 scheme serves as a tax-advantaged savings account designed to help families like Jay and Emma gather resources for upcoming educational expenses. Contributions to these programs grow without taxes, and withdrawals for eligible costs, such as tuition and books, are also tax-free. This dual tax advantage is especially beneficial for families in higher tax brackets, allowing them to maximize their savings potential and ease financial stress.
One of the standout features of 529 plans is the ability for 529 transfer ownership, which offers flexibility regarding beneficiaries. Imagine being able to use a 529 transfer ownership to change the designated beneficiary to another eligible family member, ensuring that the funds can still be used effectively, even if the original beneficiary decides not to pursue higher education. This flexibility is crucial for families navigating the complexities of educational funding, as it allows them to adapt to changing needs through a 529 transfer ownership. Additionally, many states offer tax deductions for contributions made to 529 accounts, making them even more appealing. For instance, in Colorado, joint tax filers can deduct up to $34,000 per beneficiary in 2024, providing a strong incentive for families to invest in education savings.
Statistics show a growing reliance on 529 programs among families. As of 2024, over 17 million accounts hold more than $500 billion in assets, reflecting a significant increase in contributions driven by rising education costs. On average, families save around $18,135 for their child’s college education, yet the typical 529 account only covers about 9% of overall college expenses. This highlights the importance of strategic planning and professional tax optimization to address financial challenges for high-income families like Jay and Emma.
Real-world examples illustrate the effectiveness of 529 savings accounts. Families earning between $100,000 and $150,000 contribute an average of $2,893 to their 529 accounts, while those making over $150,000 contribute an average of $5,147. This shows how affluent families are leveraging these strategies to secure their children’s educational futures. Moreover, the ability to redistribute resources among relatives fosters a broader support network, making it easier to gather essential funds for education.
In summary, the combination of tax-free growth, flexible beneficiary options, and potential state tax deductions makes 529 accounts an attractive choice for families committed to financing their children’s education. By embracing these strategies, families can effectively reduce financial stress and work towards a stable educational future. Remember, together, we can navigate this journey and empower young households through personalized wealth management solutions.
Ownership Transfer Rules: What You Need to Know
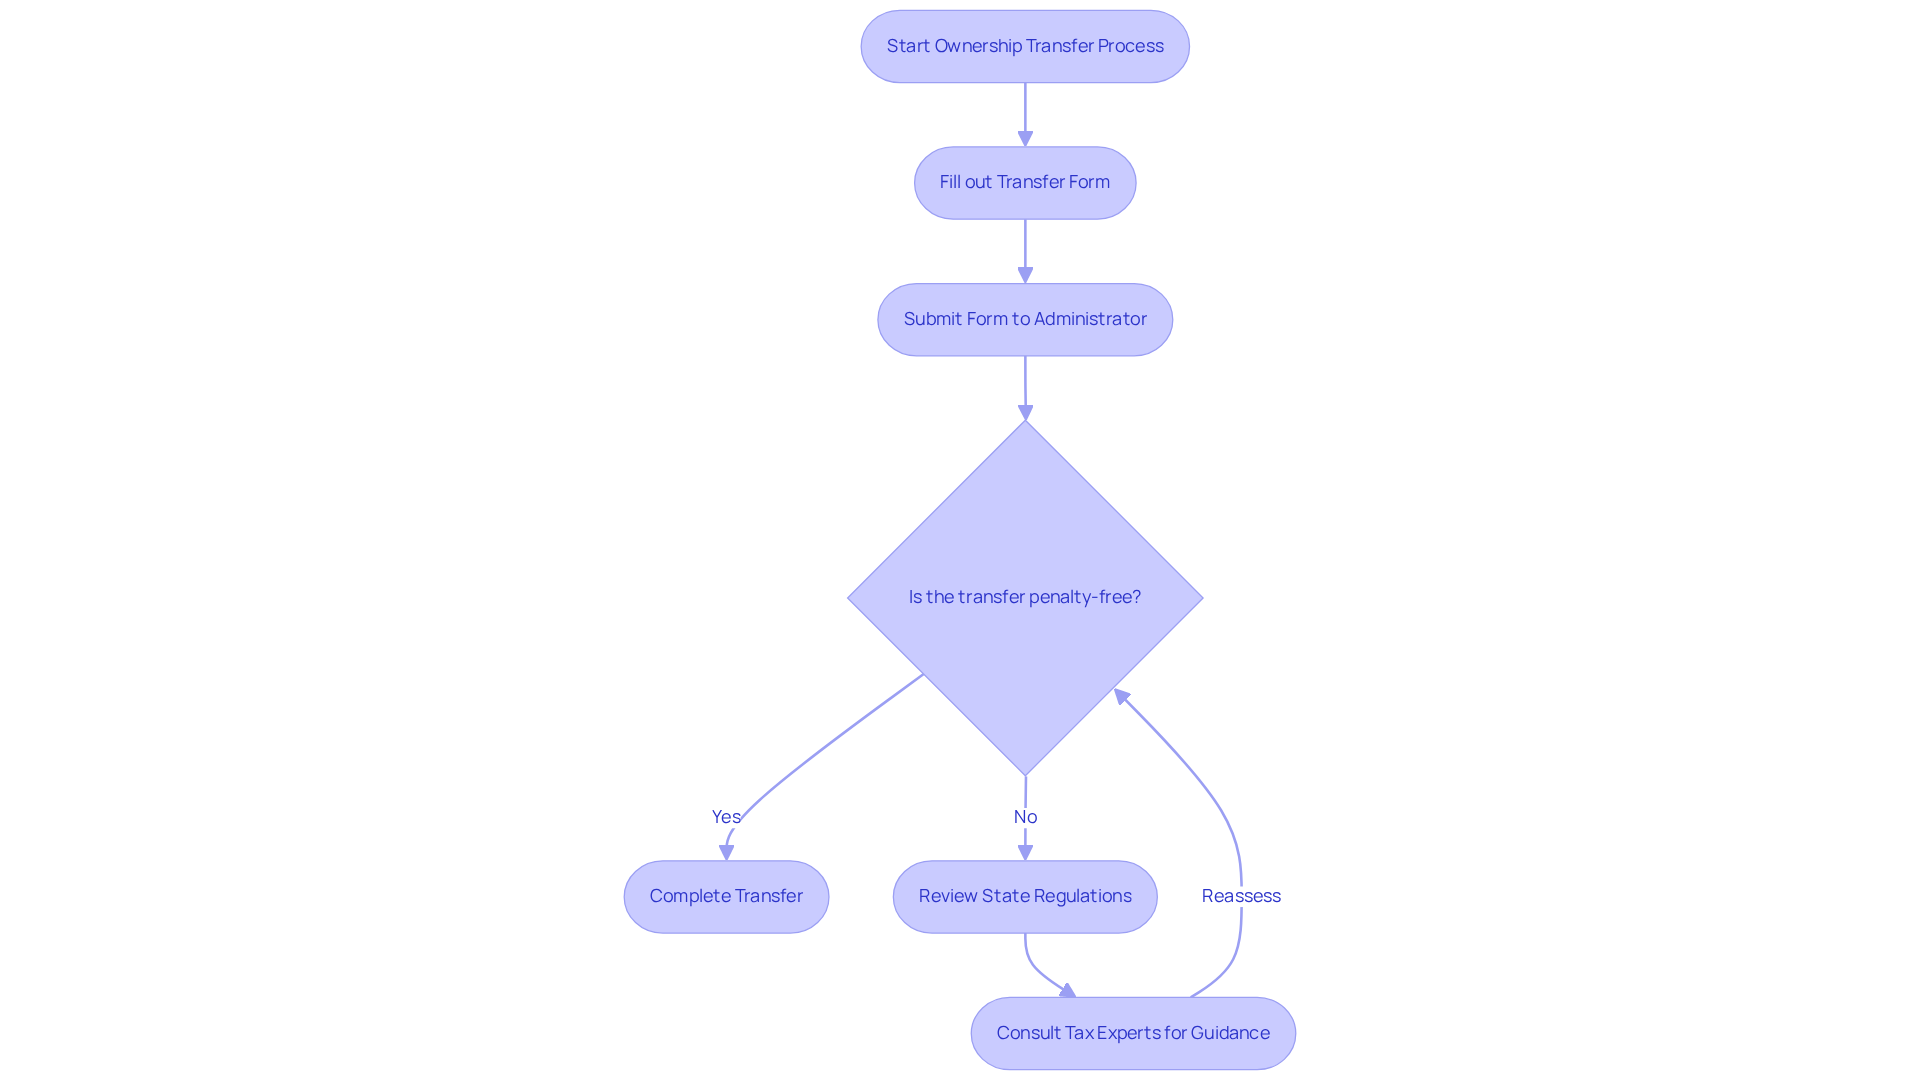
A 529 transfer ownership of an account can be a smooth process, with many states allowing these changes without restrictions on the relationship between the former and new owner. However, it’s crucial for families, especially young parents like Jay and Emma or Emily and Mark, to understand their state’s specific regulations to avoid any complications.
Imagine if you could easily pass on the benefits of your 529 account to someone who needs it. The usual procedure involves filling out a transfer form and sending it to the administrator. Plus, over 30 states offer tax deductions or credits for contributions to 529 accounts, which can motivate families to manage ownership transfers effectively.
In states where 529 transfer ownership is permitted, you can typically make these changes penalty-free once every 12 months. But it’s important to be aware that changing the beneficiary or account owner might reset the 15-year eligibility clock for rollovers, potentially impacting your future financial planning.
Seeking advice from tax experts can provide you with a clearer understanding of these regulations. They can help you make informed choices about your 529 accounts. By leveraging tailored wealth management solutions, you can empower your family’s financial security and ensure your children are ready for their educational journey.
Remember, we’re here for you. Together, we can navigate this journey and make the most of your 529 account.
Tax Implications of 529 Ownership Transfers
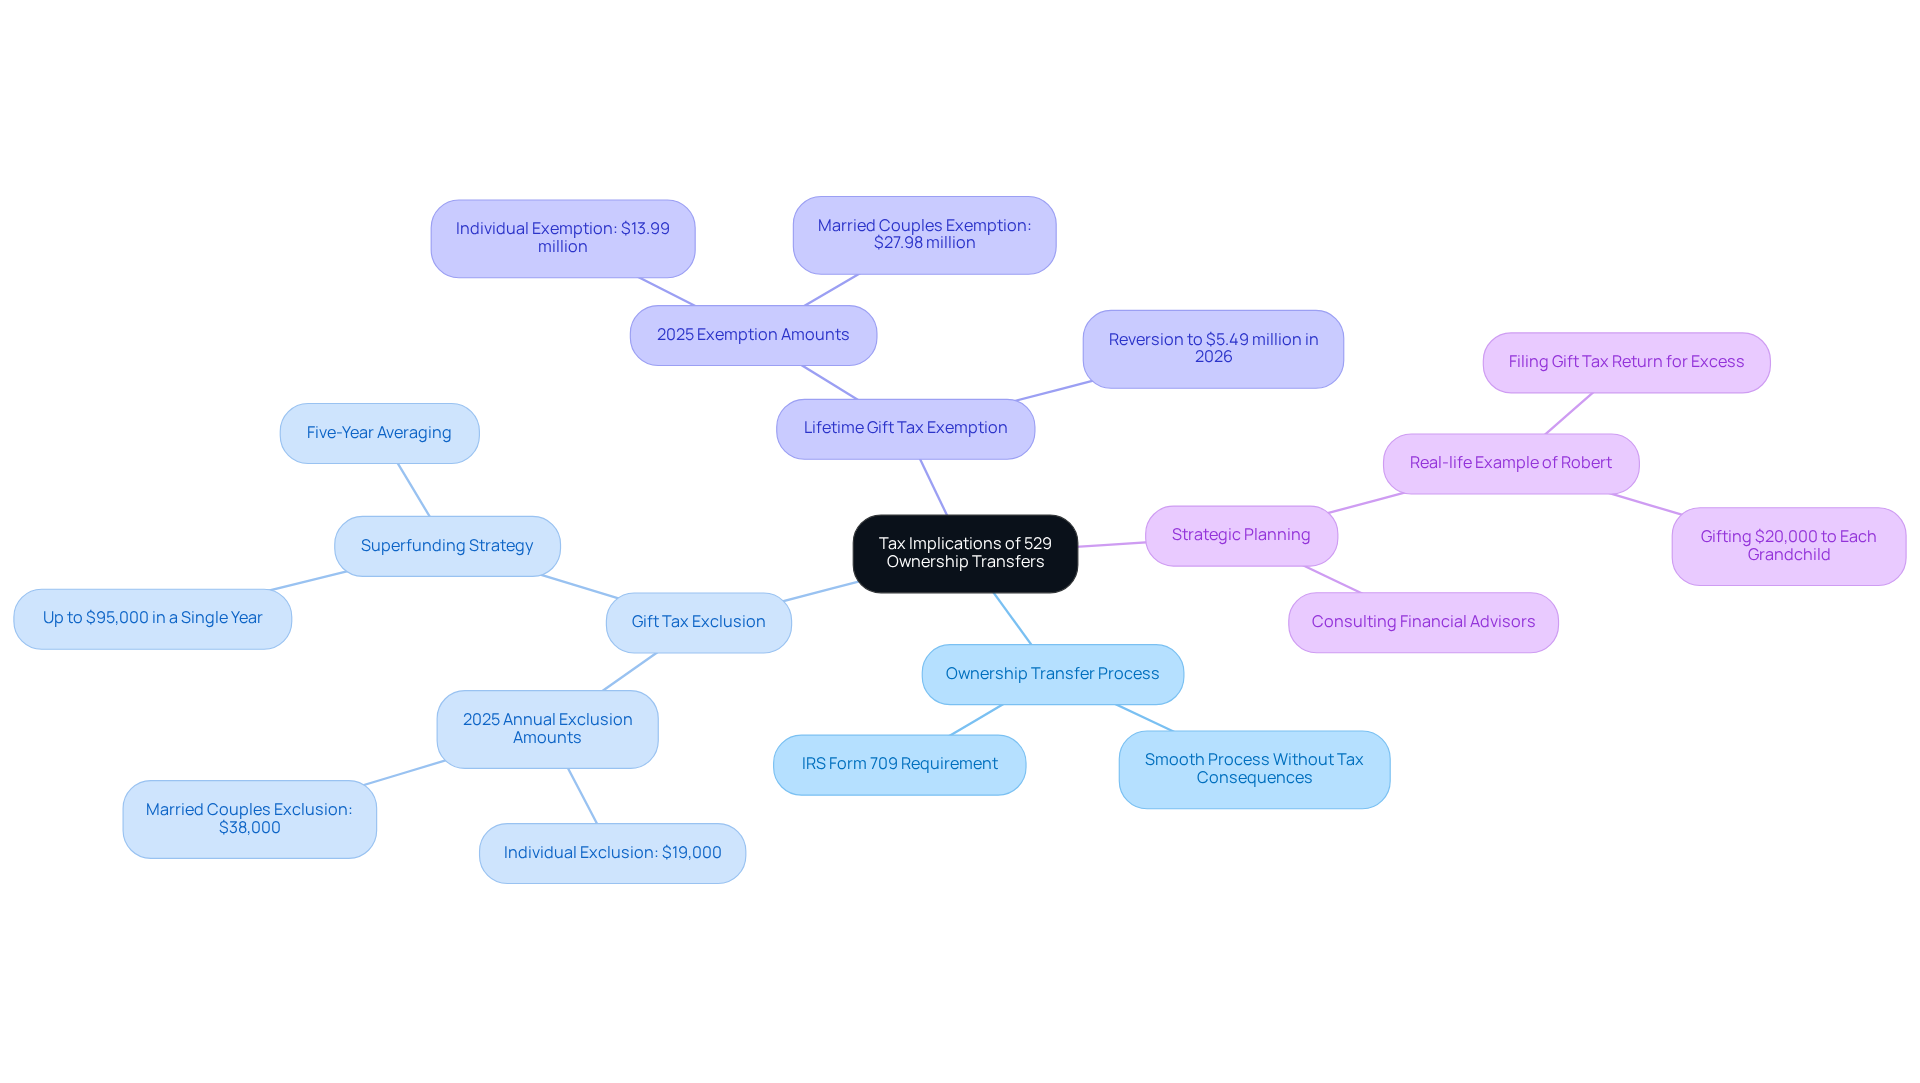
A 529 transfer ownership can be a smooth process, often without tax consequences, as long as no payment is exchanged. However, if the transfer is seen as a gift, it might bring about gift tax implications. In 2025, the annual gift tax exclusion is set at $19,000 per recipient. This means you can gift multiple beneficiaries without needing to file a gift tax return. For married couples, this exclusion doubles to $38,000 when giving jointly.
It’s important for families to know that contributions to a 529 account are considered completed gifts for tax purposes. If your total contributions exceed the annual exclusion, you’ll need to file a gift tax return (IRS Form 709). For example, if a grandparent contributes $20,000 to a grandchild’s 529 plan, they would need to file a gift tax return for the amount over the annual exclusion.
Additionally, the lifetime gift tax exemption is $13.99 million for individuals and $27.98 million for married couples in 2025. This means that most households won’t face gift taxes unless their total contributions go beyond these limits. Consulting with a financial advisor can provide valuable insights into how ownership transfers might affect your overall tax situation and help ensure compliance with IRS regulations.
Consider this real-life scenario: Robert gifts $20,000 annually to each of his three grandchildren. He must file a gift tax return for the excess amount, but only a portion counts against his lifetime exemption. This kind of strategic planning allows families to maximize their contributions while minimizing tax obligations. By understanding these nuances, families can navigate the complexities of 529 transfer ownership and optimize their educational savings strategies.
Together, we can navigate this journey, ensuring that your family’s financial future is secure and bright.
Steps to Transfer Ownership of a 529 Plan
A 529 transfer ownership can feel daunting, but it doesn’t have to be. Here’s a gentle guide to help you through the process:
-
Review State Regulations: It’s important to start by understanding your state’s specific rules regarding ownership transfers. These can vary quite a bit. For example, you can typically change ownership of a 529 account without penalty only once during a 12-month period.
-
Obtain the Transfer Form: Reach out to your 529 investment administrator to request the necessary transfer form. This form is essential for initiating the ownership change, so don’t hesitate to ask for help if you need it.
-
Complete the Form Accurately: Take your time filling out the transfer form. Ensuring that all required information is correct will help avoid any delays in the process.
-
Submit Required Documentation: Along with the completed form, you’ll need to provide any necessary documentation as indicated by your administrator. This might include identification or proof of the relationship between the current and new owner.
-
Confirm the Transfer: After you submit everything, it’s a good idea to follow up. Confirm that the transfer has been processed successfully and that the new owner has access to the account. Keeping a record of all communications and confirmations is wise for your peace of mind.
In 2025, parents reported an average savings of $18,135 for college education, underscoring the importance of effectively managing your 529 account. As Lyss Welding notes, “529 College Savings Plans: Tax-advantaged, state-sponsored investment accounts that gain or lose money with the stock market.” By following these steps, you can ensure a smooth 529 transfer ownership process for your account, allowing the new owner to manage it effectively. Remember, we’re here for you every step of the way.

Choosing the Right Beneficiary for Your 529 Plan
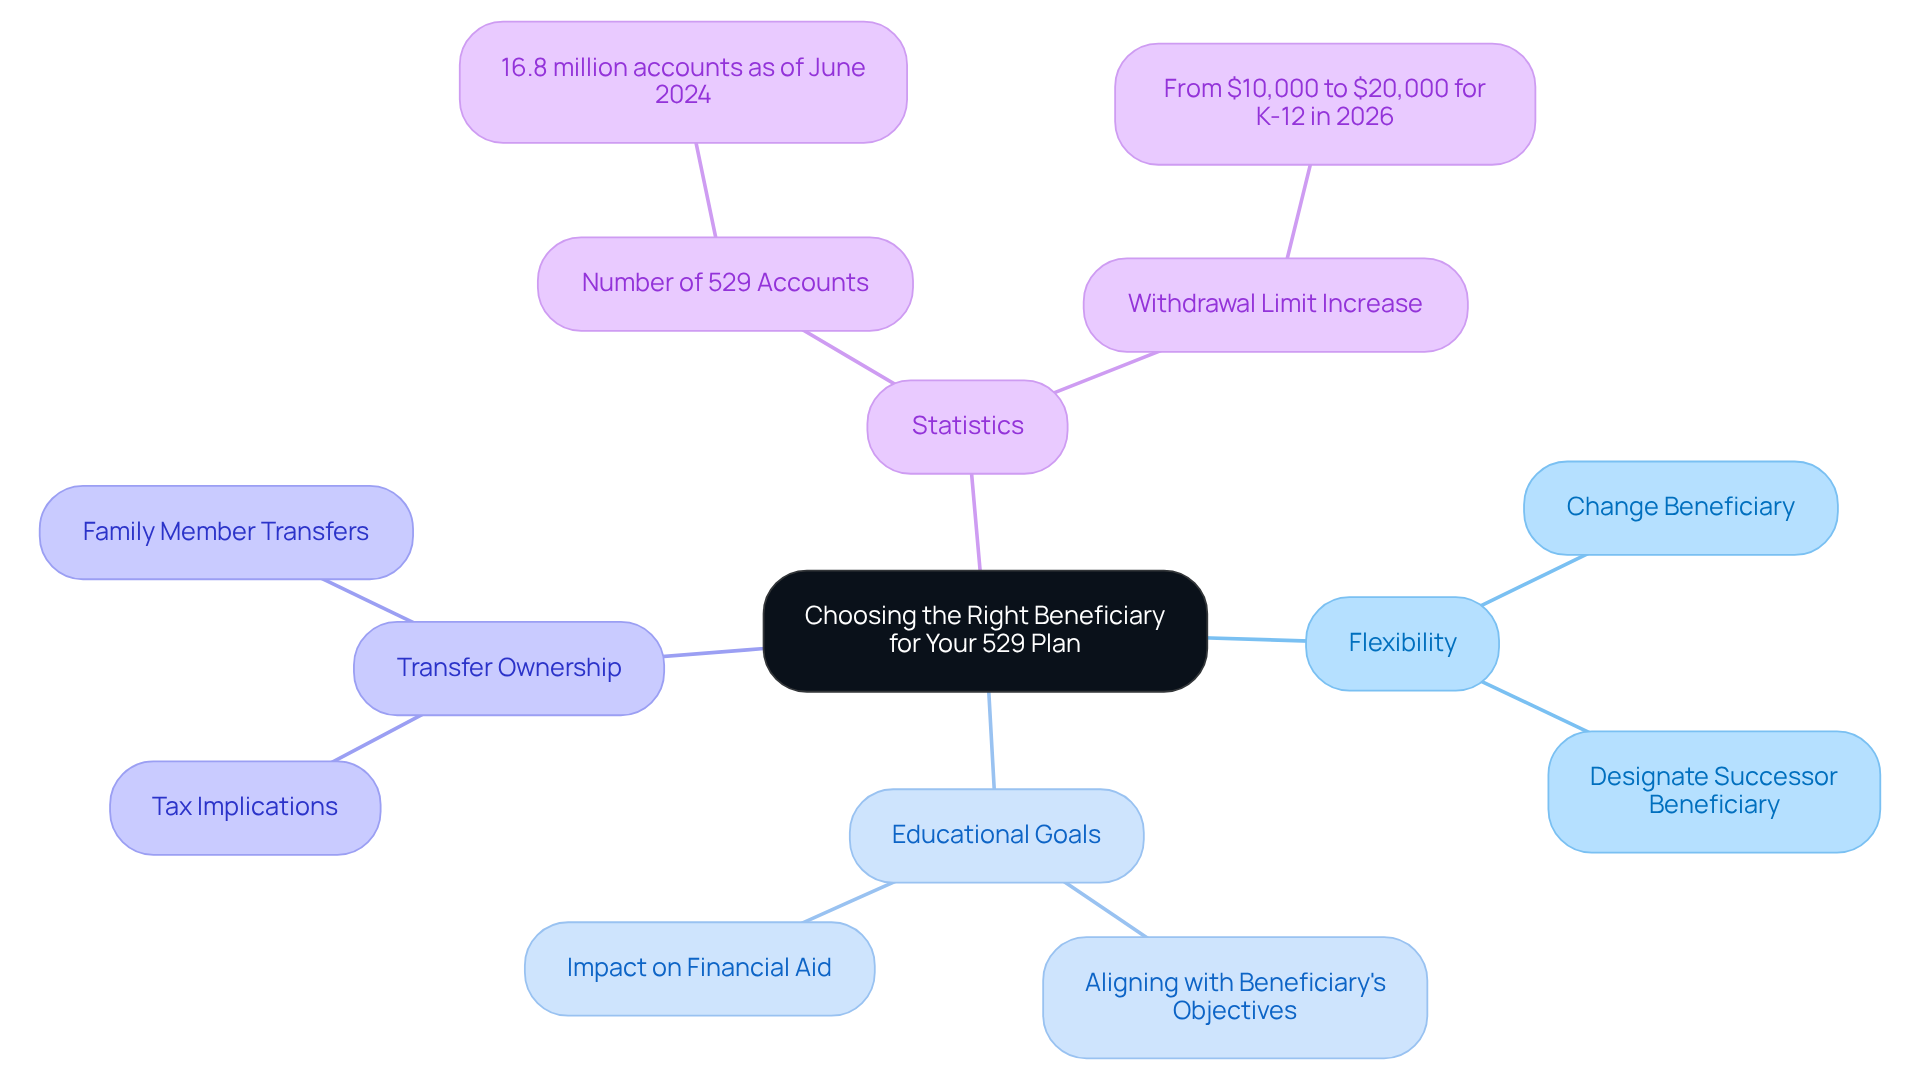
Choosing a beneficiary for a 529 plan is an important step in supporting your children’s educational dreams. It’s essential to think about their unique goals and needs. The beauty of a 529 plan is its flexibility; you can 529 transfer ownership by changing the beneficiary to another relative without worrying about tax implications. This means you can ensure that the funds are used effectively, helping to ease financial stress and secure your family’s future.
Imagine if you could designate a successor beneficiary. This simple act can preserve the advantages of your investment if the original beneficiary decides not to pursue higher education through a 529 transfer ownership. It’s a thoughtful way to keep your options open and support your loved ones.
As of June 2024, there were 16.8 million 529 accounts, showing just how appealing these plans are for families looking to allocate resources wisely. Financial planners often stress the importance of understanding each beneficiary’s educational journey. One expert noted, “Aligning the beneficiary with their educational objectives can greatly improve the efficiency of a 529 plan, ensuring that the investment produces the most favorable results for the household.”
With the yearly withdrawal limit for K-12 expenses set to increase from $10,000 to $20,000 in 2026, there’s even more reason to carefully assess educational goals. By utilizing the flexibility of beneficiary modifications, you can enhance your family’s financial stability and independence through a 529 transfer ownership.
Together, we can navigate this journey, ensuring that your financial decisions align with your family values and aspirations.
Common Mistakes in 529 Ownership Transfers
Common errors in 529 transfer ownership can significantly impact your family’s financial planning. Let’s explore some key pitfalls to avoid, ensuring your educational savings remain secure and accessible.
-
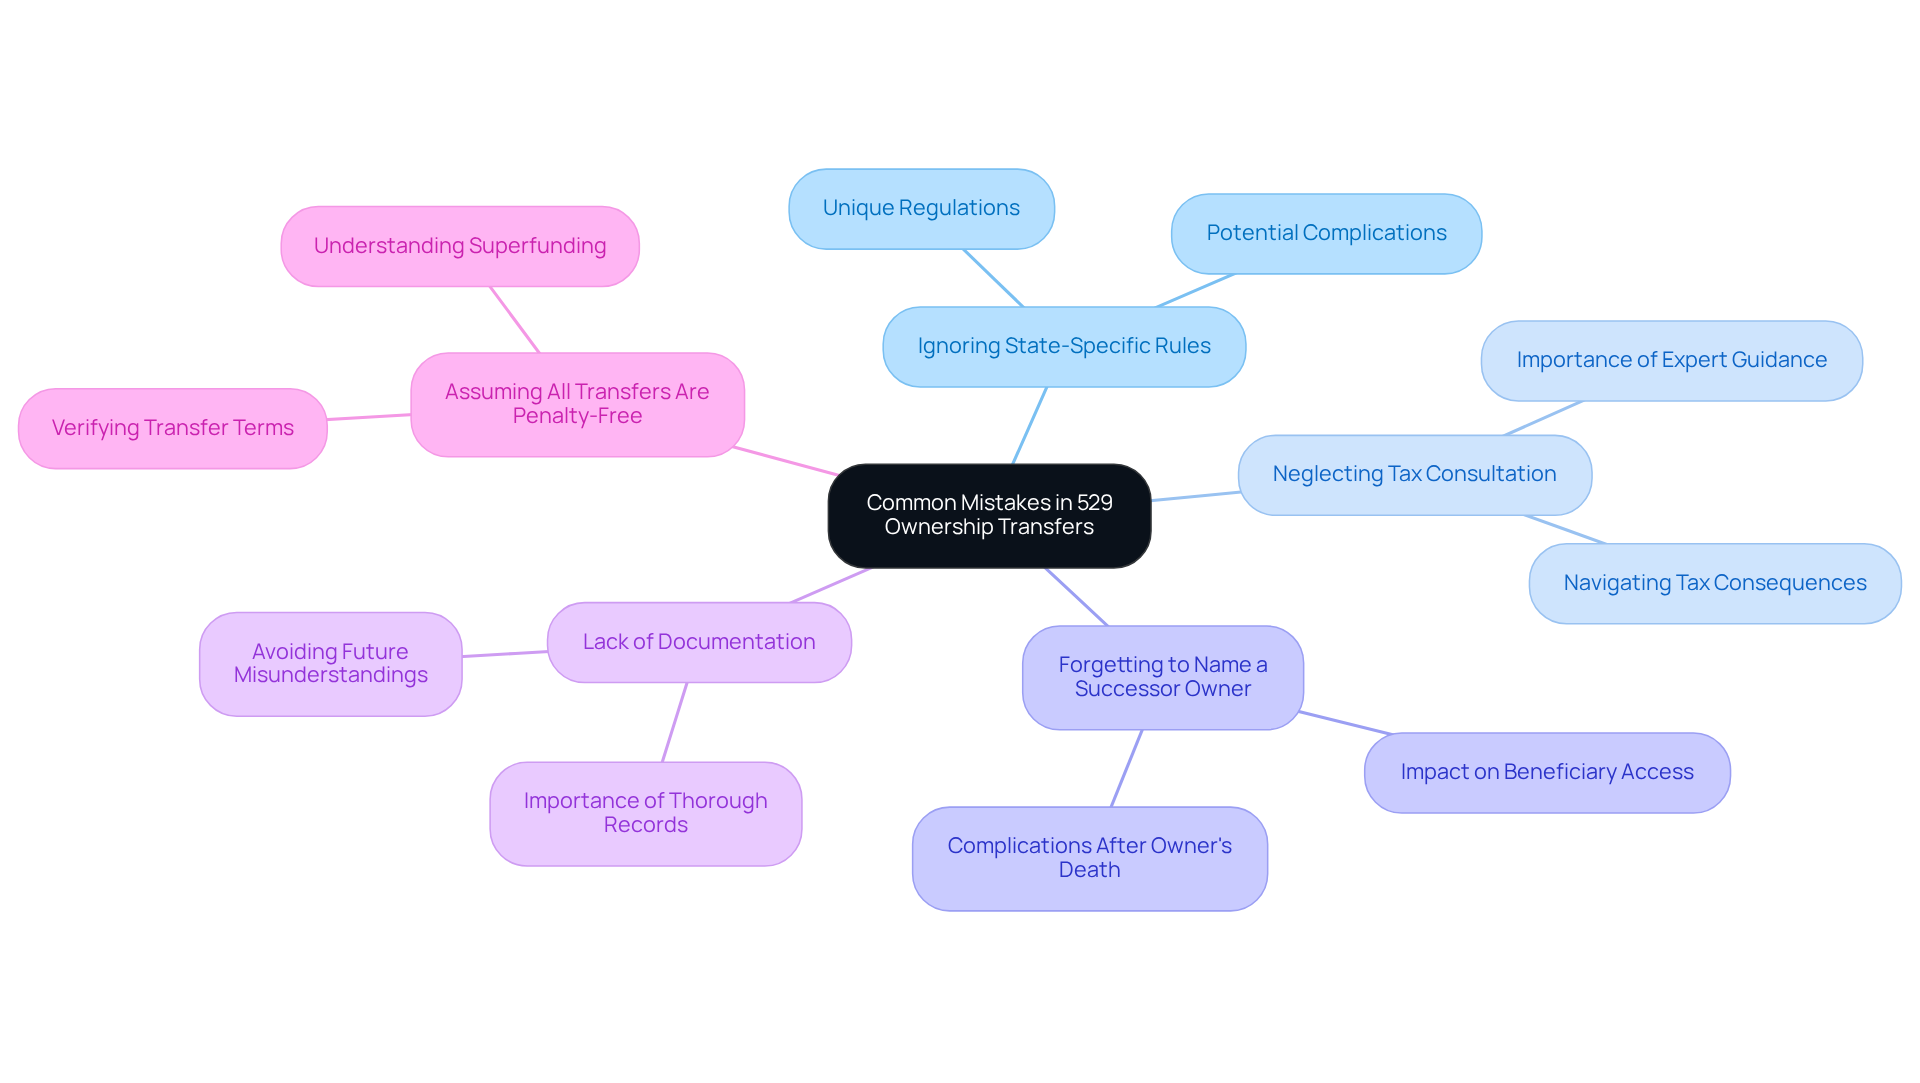
Ignoring State-Specific Rules: Each state has its own unique regulations regarding 529 programs. If you overlook these, you might face unexpected complications and penalties. As student finance expert Alex Hillsberg wisely points out, “Each state offers different tax benefits, so understanding your state’s rules and limits is crucial.”
-
Neglecting Tax Consultation: It’s easy to overlook the importance of consulting a tax advisor. Many families with 529 accounts find that expert guidance helps them navigate potential tax consequences effectively. By partnering with Bright Advisers, you can make informed choices that align with your financial goals.
-
Forgetting to Name a Successor Owner: Not designating a successor owner can lead to complications if the original owner passes away, leaving the account in limbo. This oversight can hinder the transfer process and affect your beneficiary’s access to funds.
-
Lack of Documentation: Keeping thorough records of the transfer process is essential. Neglecting this can complicate future transactions and lead to misunderstandings. Families should maintain clear documentation to ensure smooth transitions.
-
Assuming All Transfers Are Penalty-Free: Many families mistakenly believe that all transfers are penalty-free. It’s vital to verify the specific terms of your arrangement to avoid unexpected costs. For instance, understanding superfunding—a strategy that allows larger contributions—can help you maximize savings while avoiding penalties.
By recognizing these common errors, you can navigate the complexities of 529 transfer ownership more effectively. Regular meetings with a financial advisor, like those at Bright Advisers, can provide valuable insights into optimizing your 529 strategies and enhancing your overall financial security.
Together, we can navigate this journey, ensuring your family’s educational savings are well-managed and protected.
Benefits of Transferring Ownership of a 529 Plan
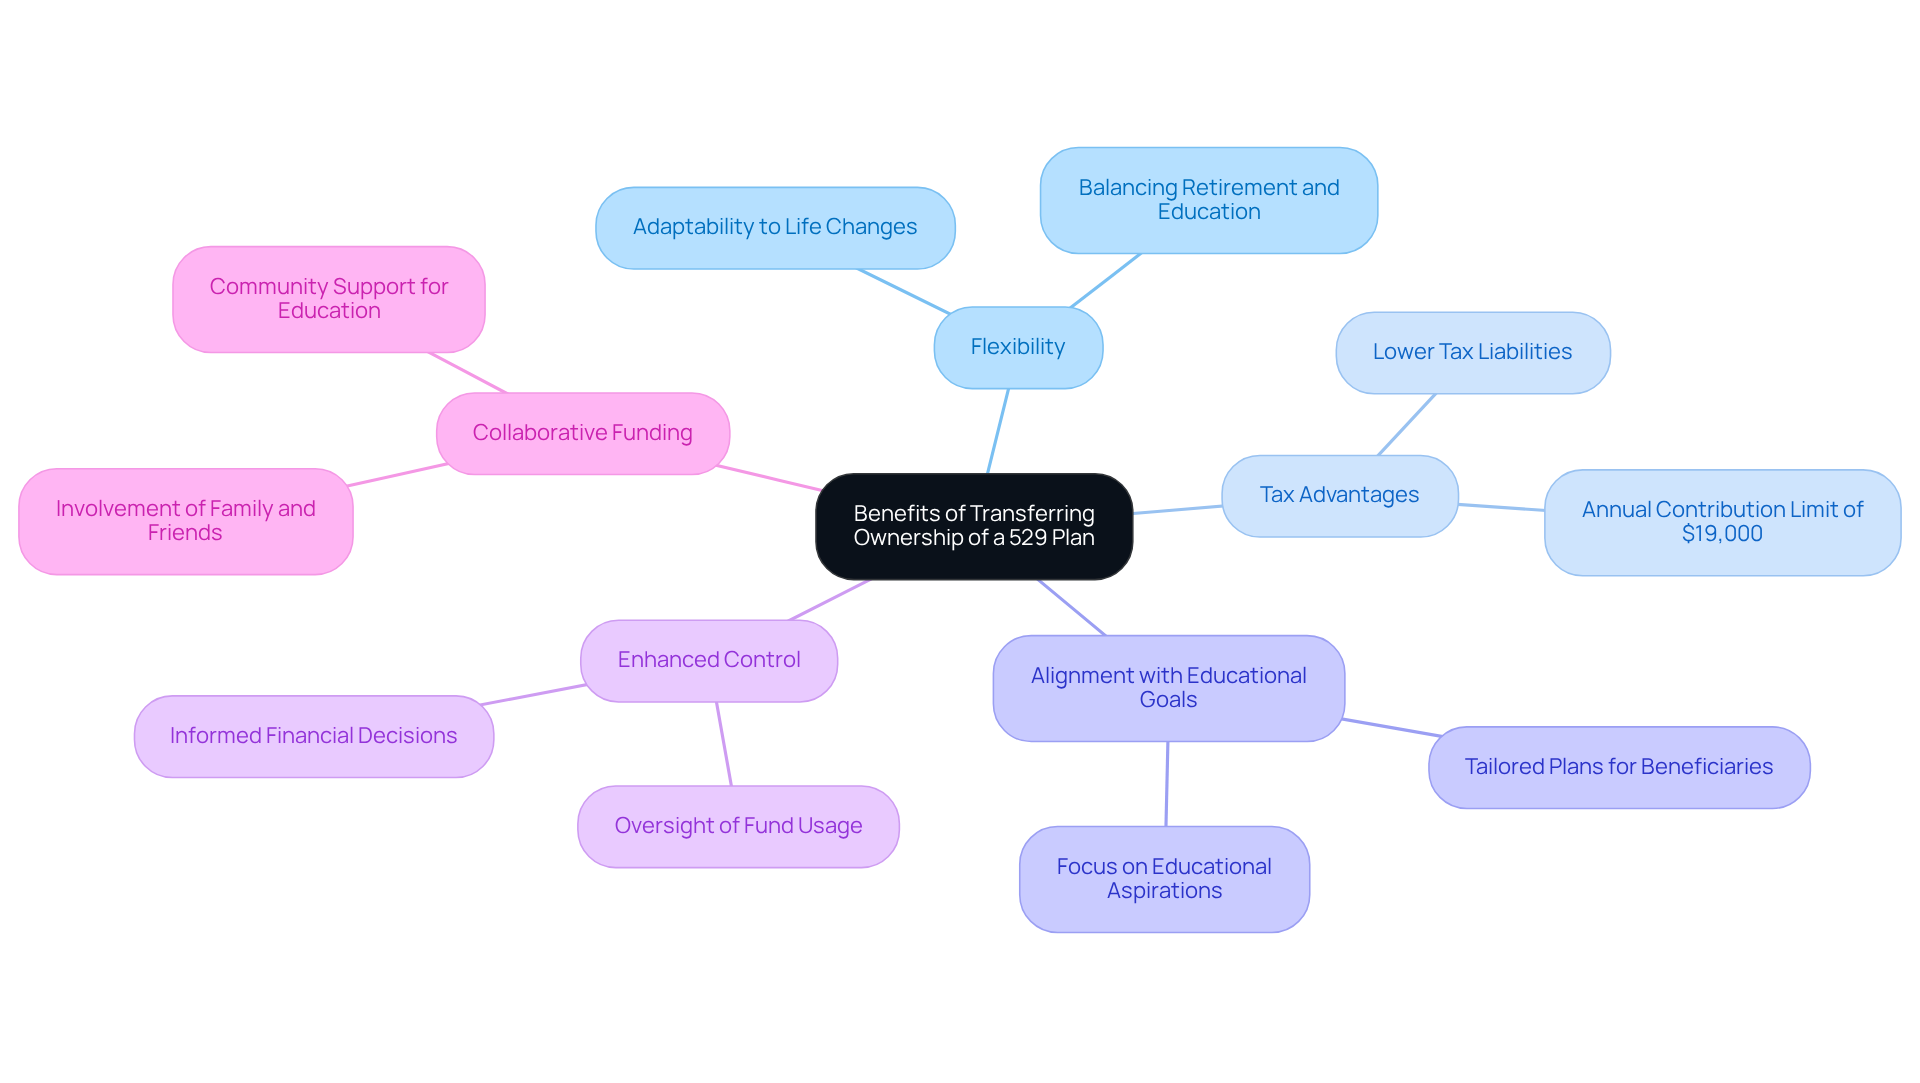
A 529 transfer ownership can bring a world of benefits for families navigating the journey of educational savings. For young parents like Jay and Emma, it’s a way to ease financial worries and secure a brighter future for their children. Let’s explore some key advantages:
-
Flexibility: Life is full of changes, and a 529 transfer ownership allows families to manage their educational savings more effectively. This adaptability is crucial for balancing retirement planning with the educational needs of children.
-
Tax Advantages: If the new owner falls into a lower tax bracket, they could see reduced tax liabilities on earnings, which helps maximize the growth potential of their savings. Plus, individuals can contribute up to $19,000 per year to a beneficiary’s 529 account without needing to file a gift tax return. This is especially important for families like Allison and Brian, who discovered how vital tax planning is for making the most of their financial resources.
-
Alignment with Educational Goals: Transferring ownership means the plan can be tailored to fit the new beneficiary’s educational aspirations. This ensures that funds are directed toward what matters most, helping families secure their children’s educational futures while keeping their own financial goals in sight.
-
Enhanced Control: The new owner gains greater oversight of the funds, ensuring they’re used for their intended educational purposes, whether that’s K-12 expenses or college tuition. This level of control is essential for families wanting to make informed decisions about their financial planning.
-
Collaborative Funding: Involving relatives in the educational savings process creates a supportive environment. Contributions from grandparents, aunts, uncles, and friends can enhance the overall funding strategy, easing some of the financial burden and fostering a sense of community.
These advantages demonstrate how a 529 transfer ownership can transform 529 accounts into a strategic resource for families eager to secure their children’s educational prospects. Plus, with the SECURE 2.0 Act, beneficiaries can roll over up to $35,000 from a 529 account into a Roth IRA, offering even more flexibility in managing both educational and retirement savings.
Together, we can navigate this journey, ensuring that your family’s future is bright and secure.
FAQs About 529 Plan Ownership Transfers
-
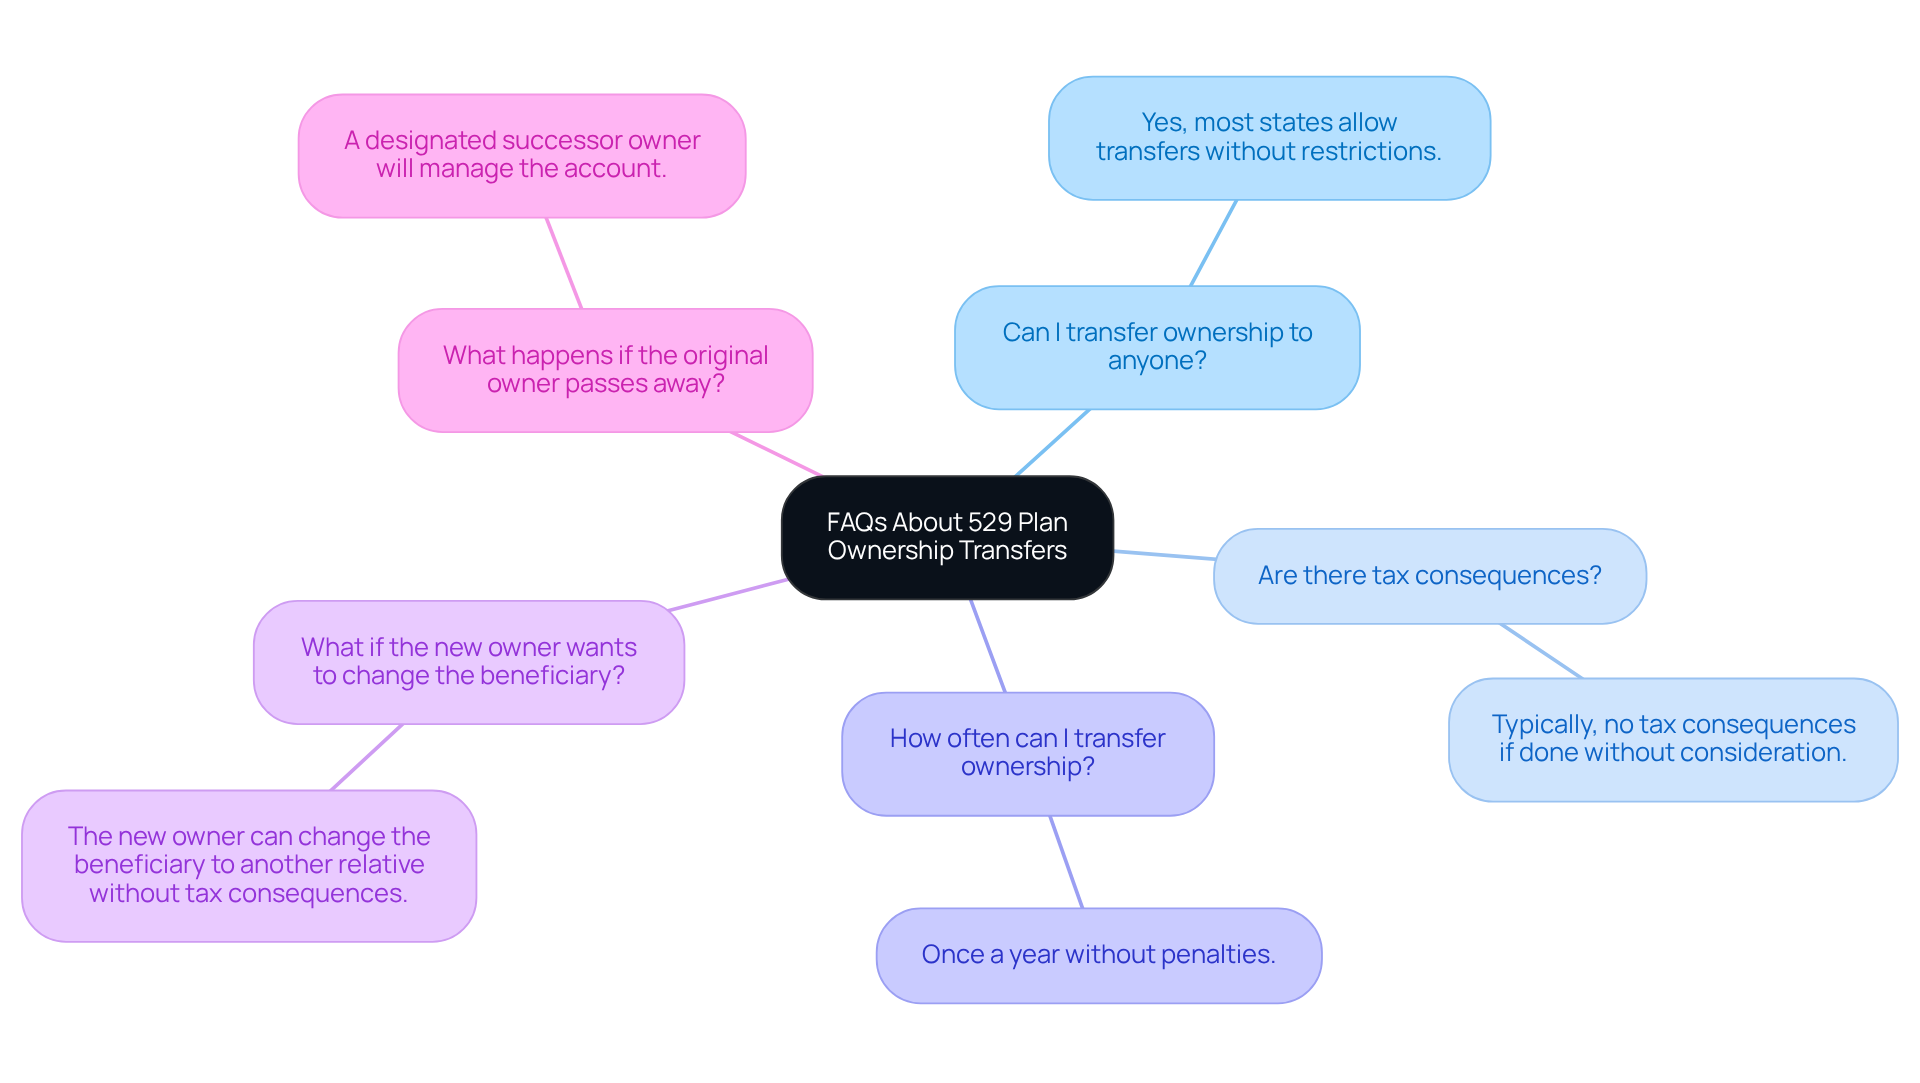
Can I transfer ownership to anyone? Absolutely! Most states permit a 529 transfer ownership without any restrictions on the relationship between the former and new owner. This flexibility makes it easier for you to manage your account in a way that suits your family’s needs.
-
Are there tax consequences? Typically, there are no tax consequences as long as the transfer is done without consideration. This means it’s a straightforward process for households, allowing you to focus on what truly matters.
-
How often can I transfer ownership? Generally, you can perform a 529 transfer ownership once a year without incurring penalties. This gives you the freedom to adjust your arrangements as your family’s needs evolve.
-
What if the new owner wants to change the beneficiary? The new owner can easily change the beneficiary to another relative without facing any tax consequences. This is a wonderful opportunity for families looking to optimize their educational savings.
-
What happens if the original owner passes away? If a successor owner is designated, they will seamlessly manage the 529 transfer ownership of the account. This ensures that your educational savings remain intact for the intended beneficiary, providing peace of mind as you navigate the complexities of 529 plans. Remember, we’re here for you, helping you secure your family’s financial future.
Consulting Professionals: The Role of Bright Advisers in 529 Planning
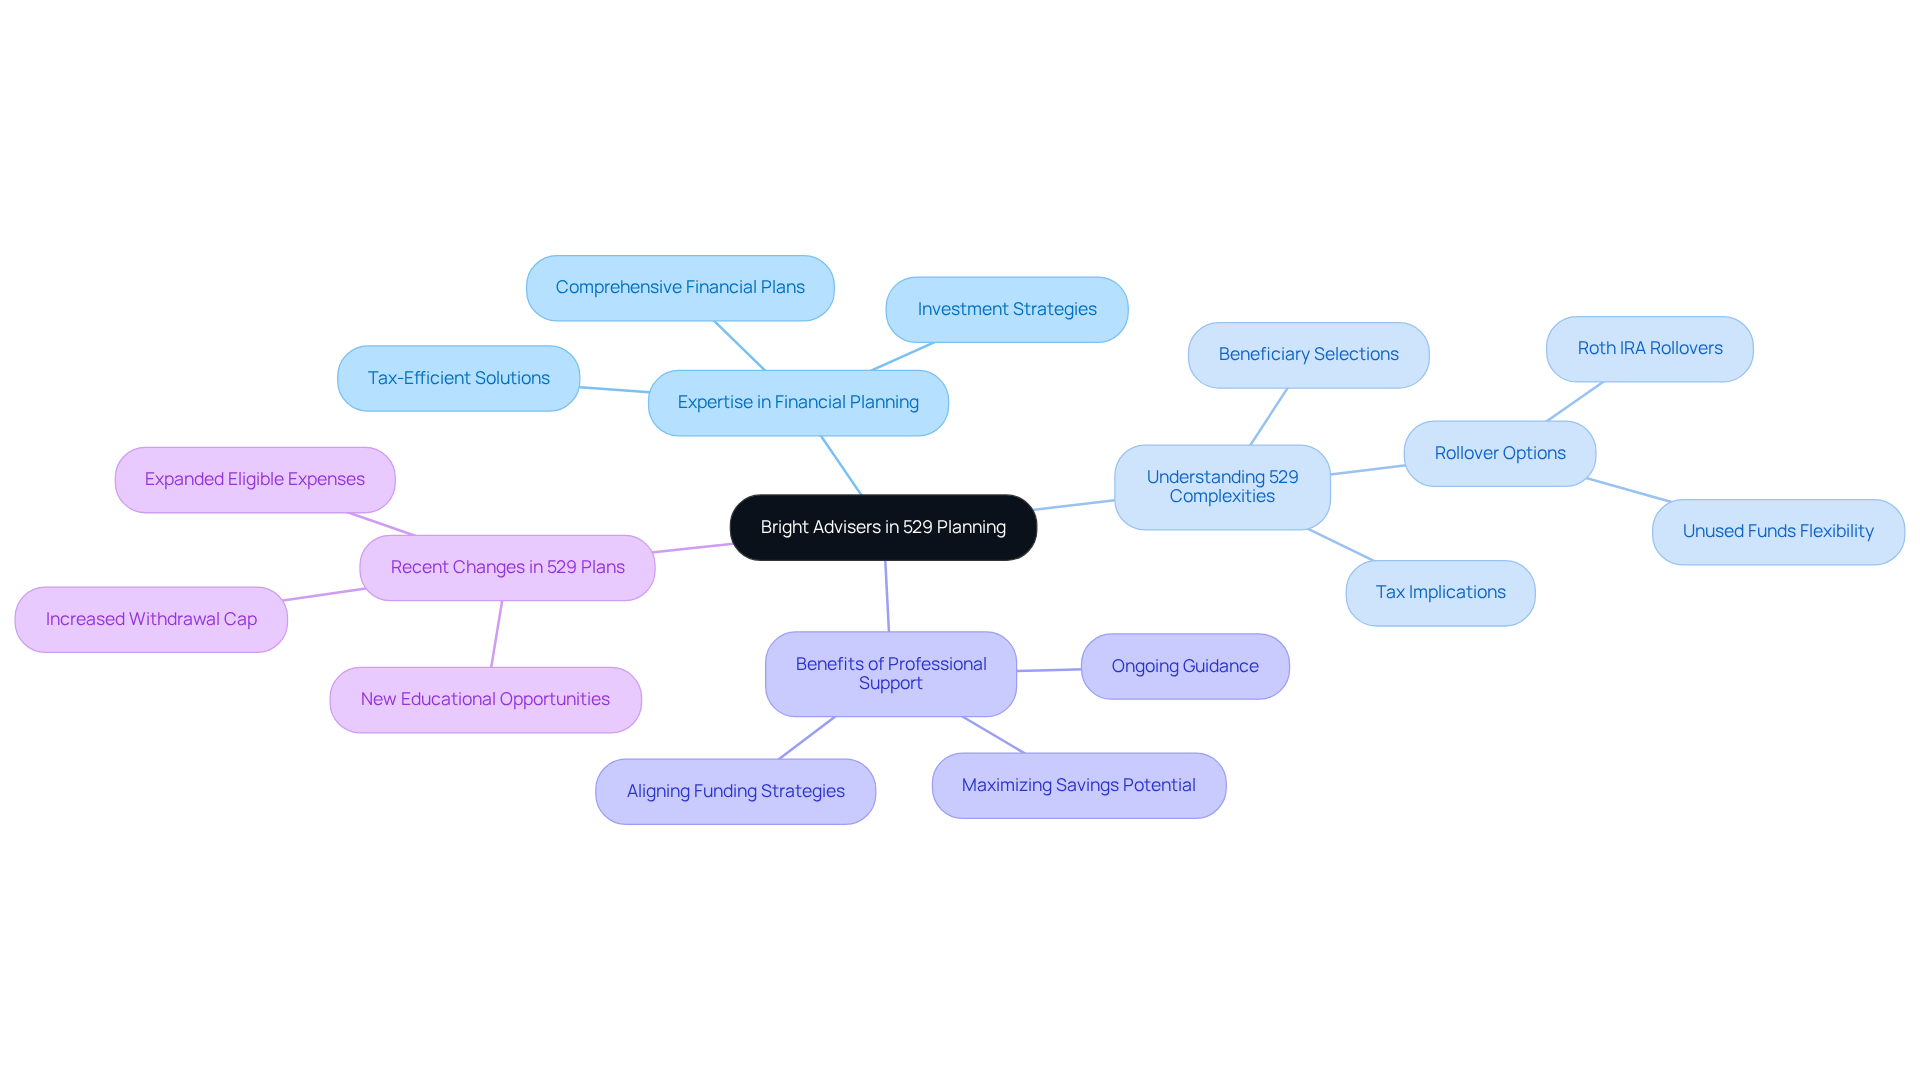
Imagine if you could transform your 529 planning experience into a journey of confidence and clarity. Engaging with professionals like Bright Advisers can truly make a difference for families navigating this important financial path. Their expertise in financial planning and investment strategies empowers you to make informed choices tailored to your unique situation.
Bright Advisers understand the complexities of 529 transfer ownership, including tax implications and beneficiary selections. They provide reassurance and a clear pathway toward achieving your educational savings goals. With their guidance, you can enhance your 529 strategies, paving the way for a brighter financial future for your children.
Wealth management experts emphasize that a well-structured 529 plan, combined with professional support, can significantly improve your outcomes. This means maximizing your savings potential and aligning your educational funding strategies with your long-term financial aspirations.
Together, we can navigate this journey, ensuring that your family’s values and goals are at the forefront of your financial planning. Remember, you’re not alone in this process; we’re here for you every step of the way.
Conclusion
Navigating the complexities of 529 plan ownership transfers is essential for families who want to secure their children’s educational futures. Imagine having the flexibility and tax advantages that these plans offer, allowing you to adapt your financial strategies as your educational goals evolve. Understanding the rules and benefits of ownership transfers can significantly enhance your ability to manage educational savings effectively.
It’s important to recognize the value of consulting with financial professionals, like Bright Advisers, to avoid common pitfalls associated with 529 transfers. They can help you navigate state-specific regulations and understand tax implications, providing invaluable guidance that empowers you to make informed decisions. Plus, the ability to change beneficiaries without tax consequences adds a layer of adaptability that is crucial for maintaining financial stability.
Ultimately, you don’t have to navigate the journey toward effective educational savings alone. By leveraging expert advice and understanding the intricacies of 529 ownership transfers, you can cultivate a supportive financial environment that prioritizes your children’s educational aspirations. Together, we can take proactive steps to ensure that the financial future of the next generation remains bright and secure.
Frequently Asked Questions
What is a 529 plan?
A 529 plan is a tax-advantaged savings account designed to help families save for educational expenses. Contributions grow without taxes, and withdrawals for eligible costs, such as tuition and books, are tax-free.
What are the benefits of a 529 plan?
The main benefits of a 529 plan include tax-free growth on contributions, tax-free withdrawals for qualified educational expenses, and potential state tax deductions for contributions.
How does 529 transfer ownership work?
529 transfer ownership allows the account owner to transfer the account to another eligible family member. This process typically involves filling out a transfer form and submitting it to the account administrator.
Are there any restrictions on transferring ownership of a 529 plan?
Many states allow 529 transfer ownership without restrictions on the relationship between the former and new owner. However, it’s essential to understand your specific state’s regulations.
How often can I transfer ownership of a 529 plan?
In states where 529 transfer ownership is permitted, you can typically make these changes penalty-free once every 12 months.
What impact does changing the beneficiary or account owner have on my 529 plan?
Changing the beneficiary or account owner may reset the 15-year eligibility clock for rollovers, which could affect your future financial planning.
What strategies can families use to manage their 529 accounts effectively?
Families can benefit from open communication among members, seeking advice from financial professionals, and utilizing tailored portfolios to enhance the management of their 529 accounts.
How can Bright Advisers assist with 529 plans?
Bright Advisers provides expert guidance on 529 plan ownership transfers, personalized financial planning, and strategies to empower families in securing their children’s educational futures.
What are the statistics regarding 529 plan usage?
As of 2024, there are over 17 million 529 accounts holding more than $500 billion in assets, with families saving an average of $18,135 for their child’s college education, which typically covers about 9% of overall college expenses.
Why is it important to seek professional advice for 529 plans?
Seeking professional advice can help families navigate the complexities of 529 plans, understand specific regulations, and make informed financial decisions that align with their educational savings goals.
List of Sources
- Bright Advisers: Expert Guidance on 529 Plan Ownership Transfers
- It Can Be Tricky to Navigate 529 Plan Rules, But Advisors Can Help (https://advisorperspectives.com/articles/2025/06/10/can-tricky-navigate-529-plan-rules-advisors-help)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 5 Things About 529 Plans From a Financial Advisor – Blog (https://olderaleighfinancial.com/orfg-resources/5-things-about-529-plans-from-a-financial-advisor)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Understanding 529 Plans: Basics and Benefits
- Three Reasons You Need to Use a 529 Plan (and Two Reasons You Don’t) (https://kiplinger.com/personal-finance/reasons-to-use-a-529-plan-and-reasons-not-to)
- Top 9 Benefits Of 529 Education Savings Plans | Bankrate (https://bankrate.com/investing/529-plan-benefits)
- 529 Plan Statistics | The Motley Fool (https://fool.com/research/529-plan-statistics)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- Ownership Transfer Rules: What You Need to Know
- Financial – Planning – Case – Studies 2023 | PDF | Investment Fund | Exchange Traded Fund (https://scribd.com/document/695749725/Financial-Planning-Case-Studies-2023)
- Big Changes to Section 529 Plans | Carr, Riggs & Ingram (https://criadv.com/insight/big-changes-to-section-529-plans)
- Changing Your 529 Plan Ownership, Beneficiaries and More | Farm Bureau Financial Services (https://fbfs.com/learning-center/making-changes-to-your-529-account)
- Tax Implications of 529 Ownership Transfers
- Do You Have to Pay Gift Taxes on 529 Plan Contributions? (https://savingforcollege.com/article/dont-worry-too-much-about-the-annual-gift-tax-limit)
- 529 Plan | College Savings Account | Vanguard (https://investor.vanguard.com/accounts-plans/529-plans)
- The big changes to 529s in the 2025 spending bill (https://empower.com/the-currency/money/big-changes-529s-2025-spending-bill-news)
- The unique benefits of 529 college savings plans (https://thetaxadviser.com/issues/2023/may/the-unique-benefits-of-529-college-savings-plans)
- Tax strategies for college savings and gifting (https://ameriprise.com/financial-goals-priorities/education-planning/529-plan-tax-benefits)
- Steps to Transfer Ownership of a 529 Plan
- Changing Your 529 Plan Ownership, Beneficiaries and More | Farm Bureau Financial Services (https://fbfs.com/learning-center/making-changes-to-your-529-account)
- Release: 529 Plan Program Statistics, June 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q2)
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Choosing the Right Beneficiary for Your 529 Plan
- The Biggest Pros and Cons of 529 Plans for College (https://studentloanplanner.com/pros-cons-529-plans)
- 529 Plans: Questions and answers | Internal Revenue Service (https://irs.gov/newsroom/529-plans-questions-and-answers)
- The big changes to 529s in the 2025 spending bill (https://empower.com/the-currency/money/big-changes-529s-2025-spending-bill-news)
- Release: 529 Plan Program Statistics, June 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q2)
- 529 Plan FAQ – About 529 Plan Accounts – Fidelity (https://fidelity.com/529-plans/faqs-about-accounts)
- Common Mistakes in 529 Ownership Transfers
- 10 Rules for Superfunding a 529 Plan for 2025 | Research.com (https://research.com/student-loans/rules-for-superfunding-a-529-plan)
- How new 529 plan rules can help with retirement planning (https://ameriprise.com/financial-goals-priorities/education-planning/new-529-plan-rules)
- Release: 529 Plan Program Statistics, December 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q4)
- 529 Plan FAQ – About 529 Plan Accounts – Fidelity (https://fidelity.com/529-plans/faqs-about-accounts)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Benefits of Transferring Ownership of a 529 Plan
- The Latest 529 Plan Rule Changes: What’s New for 2025 (https://savingforcollege.com/article/529-plan-new-rules-changes)
- The unique benefits of 529 college savings plans (https://thetaxadviser.com/issues/2023/may/the-unique-benefits-of-529-college-savings-plans)
- Big Changes to Section 529 Plans | Carr, Riggs & Ingram (https://criadv.com/insight/big-changes-to-section-529-plans)
- Top 9 Benefits Of 529 Education Savings Plans | Bankrate (https://bankrate.com/investing/529-plan-benefits)
- FAQs About 529 Plan Ownership Transfers
- 529 Plans: Questions and answers | Internal Revenue Service (https://irs.gov/newsroom/529-plans-questions-and-answers)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- 529 Plan FAQ – About 529 Plan Accounts – Fidelity (https://fidelity.com/529-plans/faqs-about-accounts)
- Release: 529 Plan Program Statistics, June 2024 | Investment Company Institute (https://ici.org/research/stats/529s/529s_24_q2)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Consulting Professionals: The Role of Bright Advisers in 529 Planning
- The big changes to 529s in the 2025 spending bill (https://empower.com/the-currency/money/big-changes-529s-2025-spending-bill-news)
- A Financial Planner’s Guide to Unlocking the Power of a 529 Plan (https://kiplinger.com/personal-finance/college/how-to-unlock-the-power-of-a-529-plan)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading