

Key Highlights
- High-income families in the Bay Area should prioritise maximising contributions to retirement accounts like 401(k)s and IRAs to lower taxable income.
- For 2026, contribution limits are $24,500 for 401(k)s and $7,500 for IRAs, with additional catch-up contributions for those aged 50 and older.
- Tax-loss harvesting allows families to offset gains with losses, reducing taxable income and is particularly effective in volatile markets.
- Strategic charitable giving methods, such as donor-advised funds, can enhance tax benefits by allowing families to combine contributions in one year.
- Health Savings Accounts (HSAs) provide a triple tax advantage for families, with contributions being tax-deductible and withdrawals for medical expenses being tax-free.
- Homeowners can deduct mortgage interest and property taxes, significantly reducing taxable income and easing financial burdens.
- Estate planning tools like irrevocable trusts and gifting strategies can help lower estate taxes and secure wealth for future generations.
- Tax-efficient investment options, such as municipal bonds, can provide tax-free income, benefiting families in higher tax brackets.
- Roth conversions allow families to pay taxes now for tax-free withdrawals later, which can be advantageous for those expecting higher tax rates in retirement.
- Engaging a fiduciary financial advisor ensures families receive personalised, transparent guidance tailored to their financial goals.
Introduction
Imagine feeling overwhelmed by financial decisions while trying to provide the best for your family in the Bay Area. Navigating the financial landscape as a high-income family can be challenging, especially with California’s steep tax rates looming over every choice. But what if you could find ways to ease that burden and focus on what truly matters – your family’s well-being? Understanding and implementing effective tax strategies can significantly help. Together, let’s explore ten essential tax strategies that can help your family thrive, offering insights into:
- Maximizing retirement contributions
- Leveraging tax-loss harvesting
- Engaging with fiduciary advisors
With so many options, it’s natural to wonder which strategies will truly support your family’s dreams and align with your long-term goals.
Maximize Retirement Account Contributions
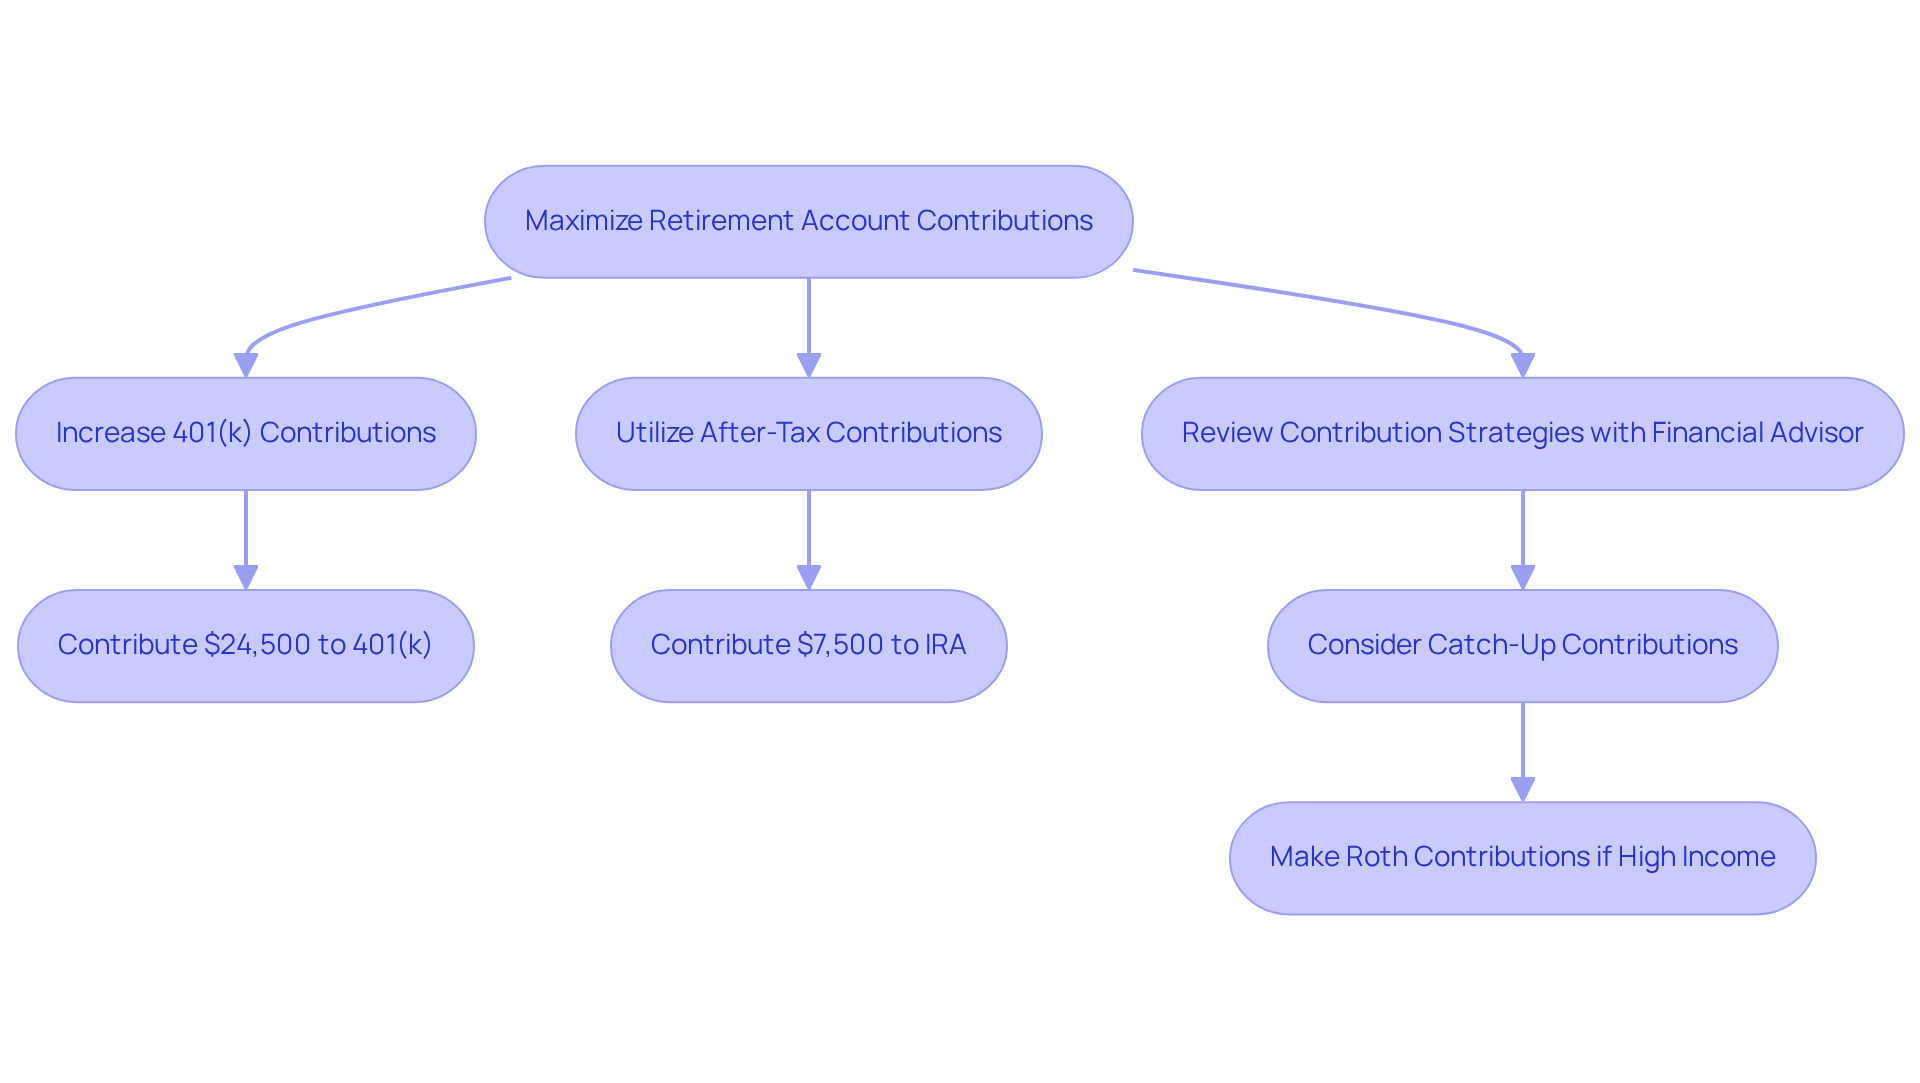
Imagine feeling secure about your family’s financial future while navigating the challenges of high taxes and retirement planning. High-income households in the Bay Area should adopt a high income tax strategy in the Bay Area by prioritizing increased contributions to retirement accounts like 401(k)s and IRAs. For 2026, the contribution limits are set at $24,500 for 401(k)s and $7,500 for IRAs. Contributing the maximum to your retirement accounts can help lower your taxable income, which is vital in high-tax states like California, where rates can reach 13.3%.
Additionally, families can use after-tax contributions to a 401(k) to fund a Roth IRA, allowing for tax-free growth and withdrawals in retirement. This approach not only helps with tax reduction but also builds a strong retirement fund for the future.
Consider the case of Jay and Emma, a couple in their late 40s with two children. They felt overwhelmed by financial worries and sought guidance from Bright Advisers. With help from their investment consultant, they worked together to create a budget and pick investment strategies that balanced growth and safety while preparing for their children’s education and their retirement.
Similarly, Emily and Mark, both in their mid-30s, faced the challenge of managing their finances while juggling demanding careers. They collaborated with Bright Advisers to create a thorough plan that focused on enhancing their economic well-being while giving them the freedom to choose their work-life balance. By adopting methods to decrease debt, manage cash flow, and invest wisely, they gained the flexibility to make career choices that suited their family.
In 2026, individuals aged 50 and older can contribute an additional $8,000 to their 401(k), while those aged 60 to 63 can qualify for a higher ‘super catch-up’ contribution of $11,250. High earners must make all catch-up contributions on a Roth basis, which can significantly enhance their retirement savings as they approach retirement age.
Understanding these contribution limits and the high income tax strategy in the Bay Area is essential for families wanting to secure their future while managing the complexities of high-income tax planning. A practical suggestion for households is to regularly review their contribution strategies with a financial advisor to ensure they are making the most of their retirement savings opportunities.
It’s important to note that past performance does not guarantee future results, and securities investments are subject to risk. All advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Utilize Tax-Loss Harvesting Techniques
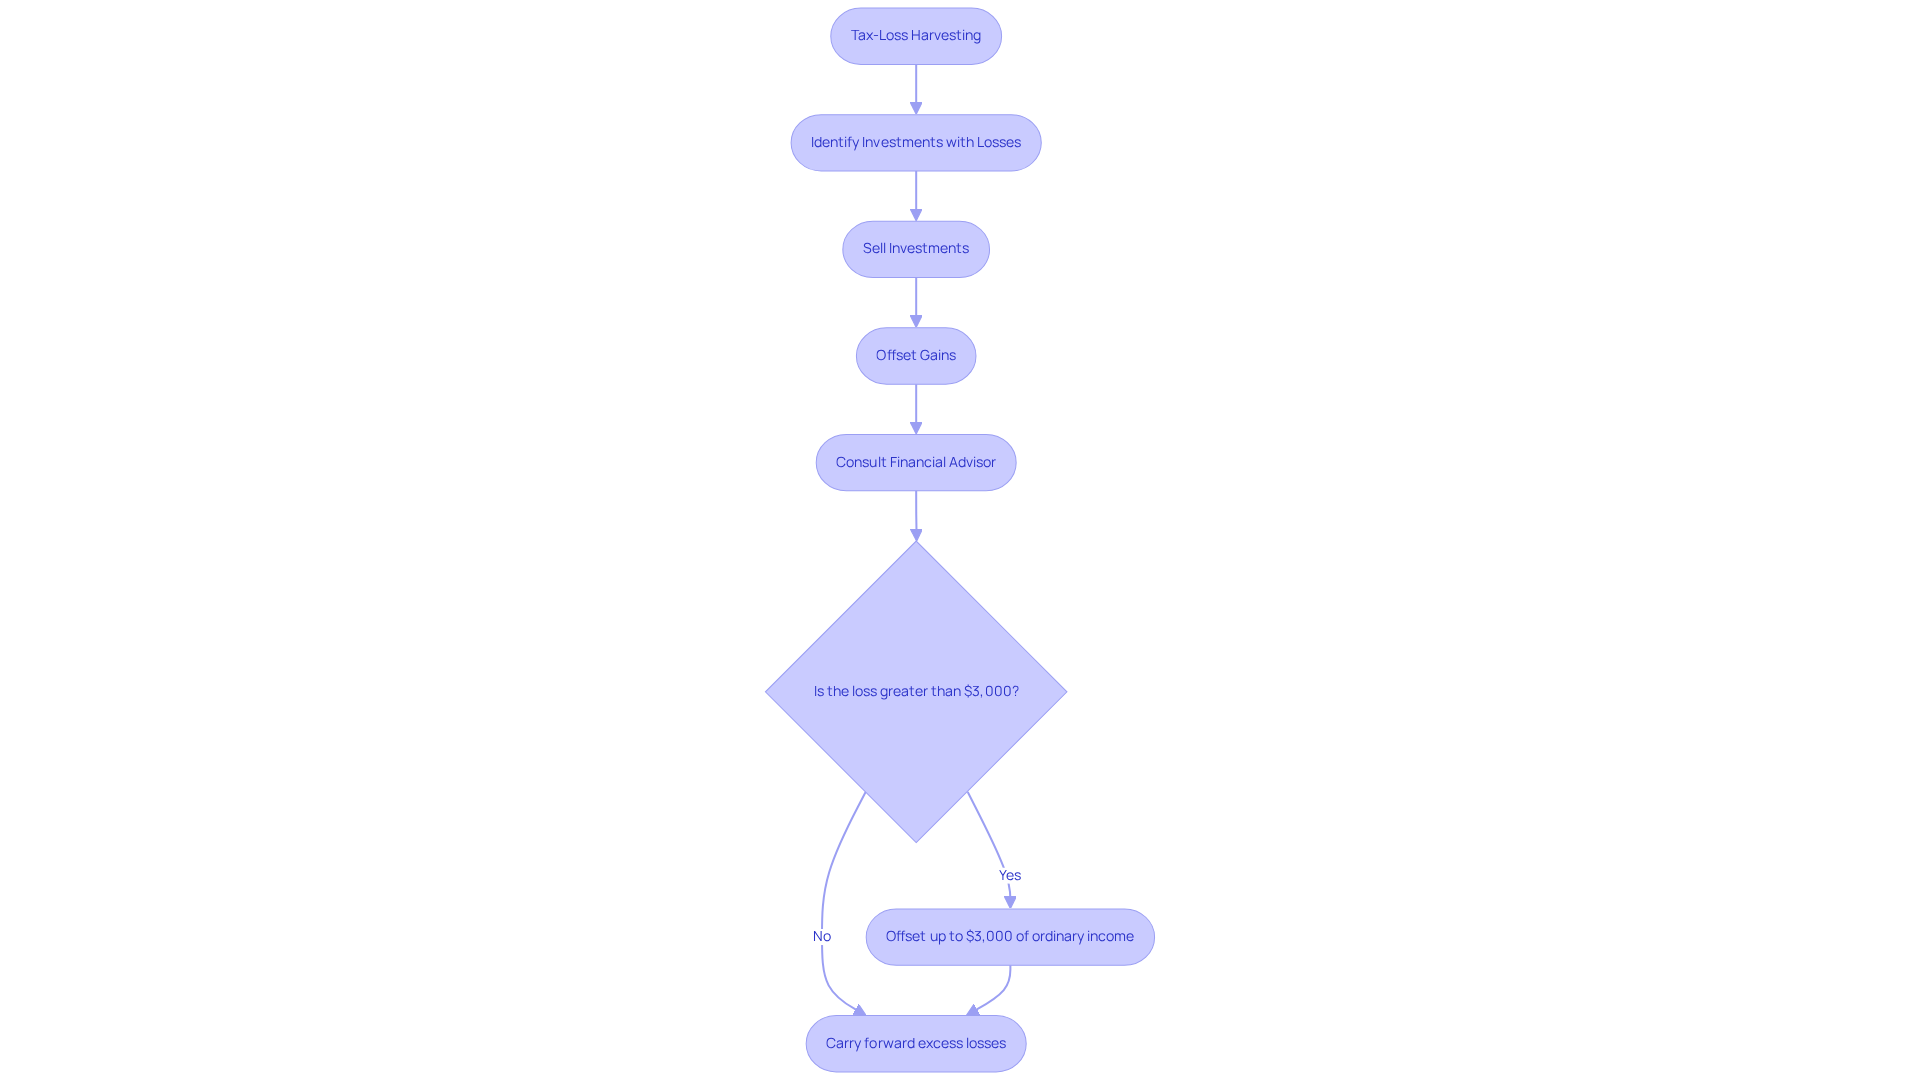
Imagine finding a way to ease your family’s financial burden while navigating the complexities of taxes. Tax-loss harvesting helps you sell investments that have lost value, balancing out gains from others. This can lower your taxable income, which is especially important for families trying to make every dollar count. By recognizing losses, you can offset up to $3,000 of ordinary income each tax year, with any additional losses carried forward to future years.
It’s important to understand that this strategy shines during unstable market conditions. It allows you to maintain your investment approach while reducing tax effects. For instance, if your family sells an investment at a loss of $30,000 and has realized gains of $25,000 from another investment, you can offset the entire gain, resulting in no capital gains taxes owed.
Navigating tax rules can feel overwhelming, especially when trying to maximize your family’s financial health. Working with a caring financial advisor can make tax-loss harvesting feel less daunting and more manageable for your family. They can help ensure that this strategy is executed effectively, particularly in adhering to the IRS wash-sale rule, which prohibits claiming a loss if the same or substantially identical investment is repurchased within 30 days before or after the sale.
This careful planning can lead to significant tax savings over time, making tax-loss harvesting a valuable tool for families looking to manage their wealth efficiently. With the right support, you can turn tax challenges into opportunities for your family’s future.
Implement Strategic Charitable Giving
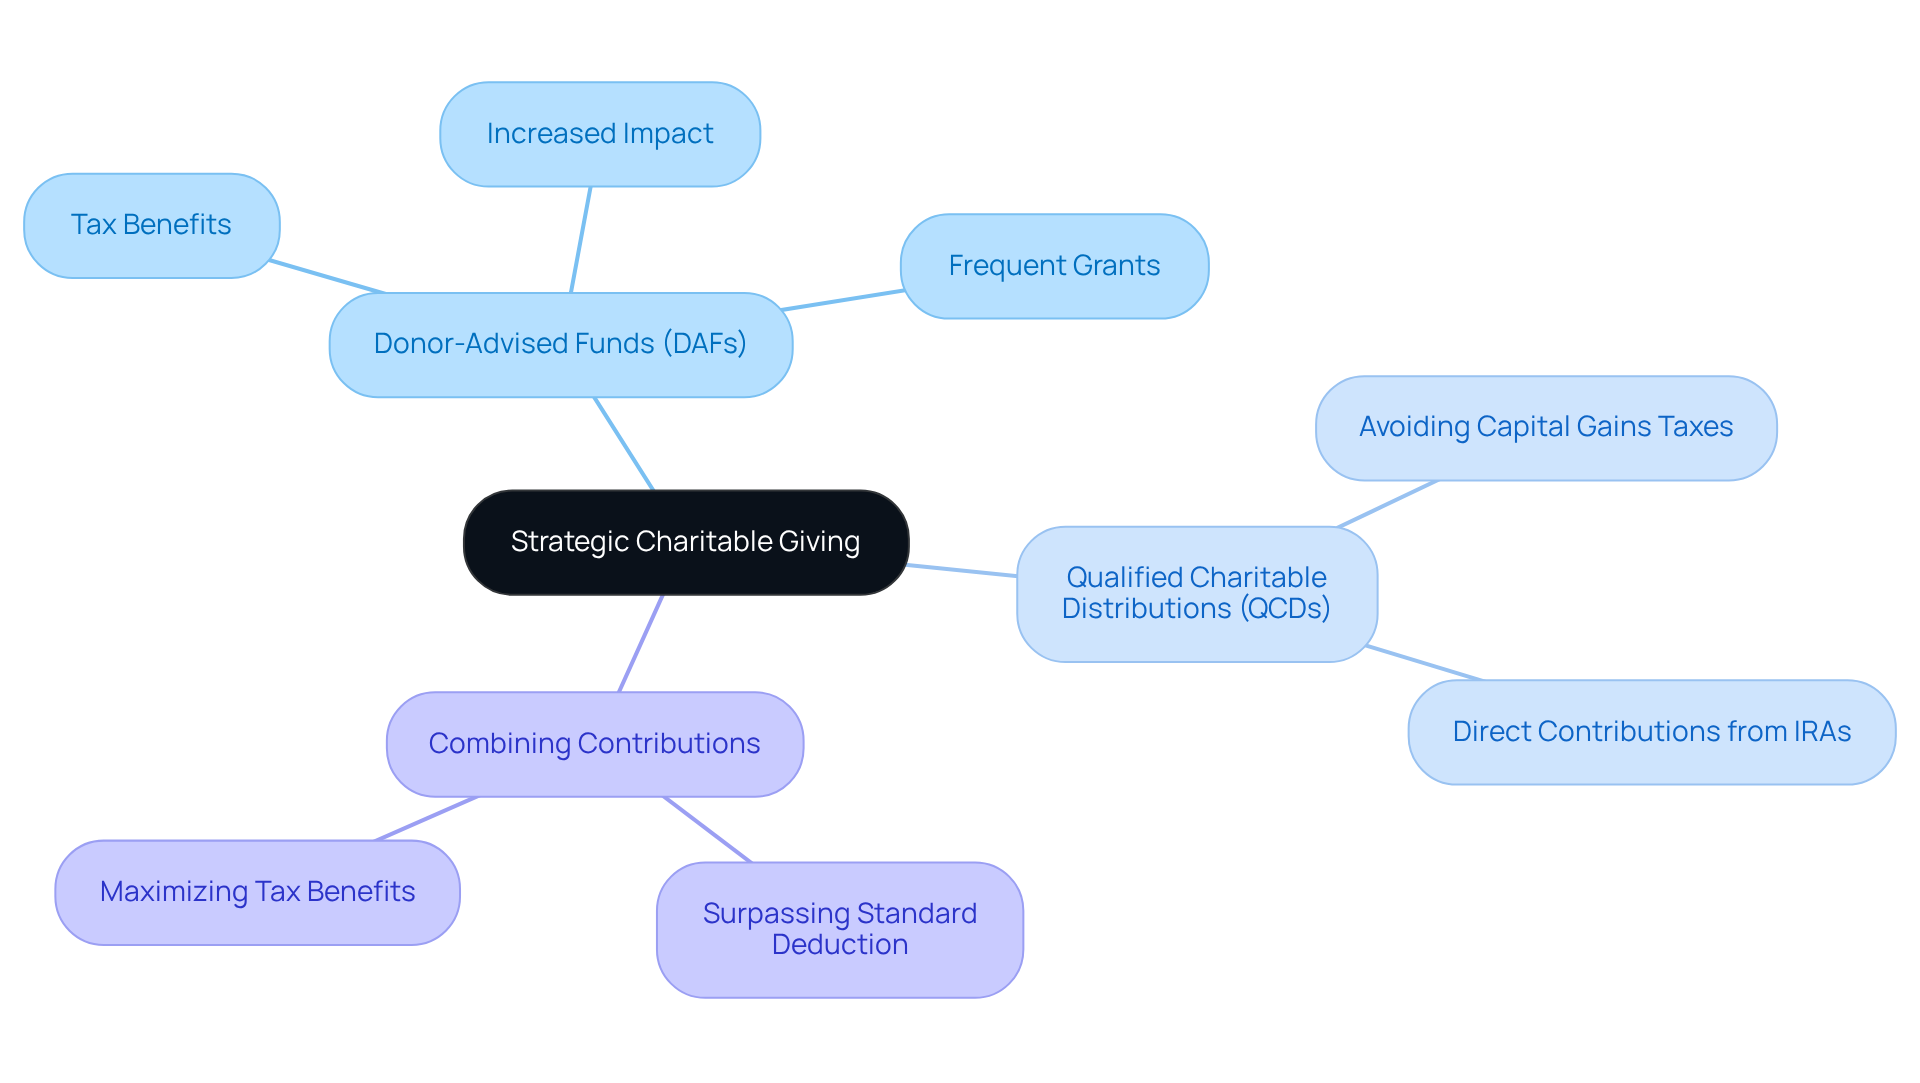
Imagine wanting to make a difference in your community but feeling overwhelmed by the options available for charitable giving. High-income households can significantly enhance their charitable impact through a high income tax strategy in the Bay Area by utilizing strategic giving methods like donor-advised funds (DAFs) and qualified charitable distributions (QCDs) from IRAs. When families combine their charitable contributions into one year, they can surpass the standard deduction limit, which can lead to greater tax benefits. For example, a household that contributes $40,000 in a single year can subtract this amount from their taxable income, resulting in a significant decrease in their tax obligation.
It’s common for families to want to give back but feel uncertain about the best ways to make their contributions count. Donating appreciated assets allows households to avoid capital gains taxes while still providing substantial support to charitable organizations. This method not only enhances the economic effect of their contributions but also aligns with the charitable objectives of many affluent families.
Consider how philanthropic experts often utilize DAFs to manage their charitable contributions efficiently. Many families make an average of 11.8 grants per account, which is significantly higher than typical donors. This shows how thoughtful families are about their giving, ensuring their support goes to causes they truly care about.
Did you know that nearly a quarter of families like yours are now using structured giving methods to make their charitable contributions more impactful? With 48% of households worth $5-20 million planning to establish a high income tax strategy in the Bay Area within three years, this increasing trend highlights the significance of strategic charitable giving in the financial planning of high-income households. By embracing these strategies, you can ensure your family’s generosity leaves a lasting legacy while also benefiting from tax advantages.
Leverage Health Savings Accounts for Tax Benefits
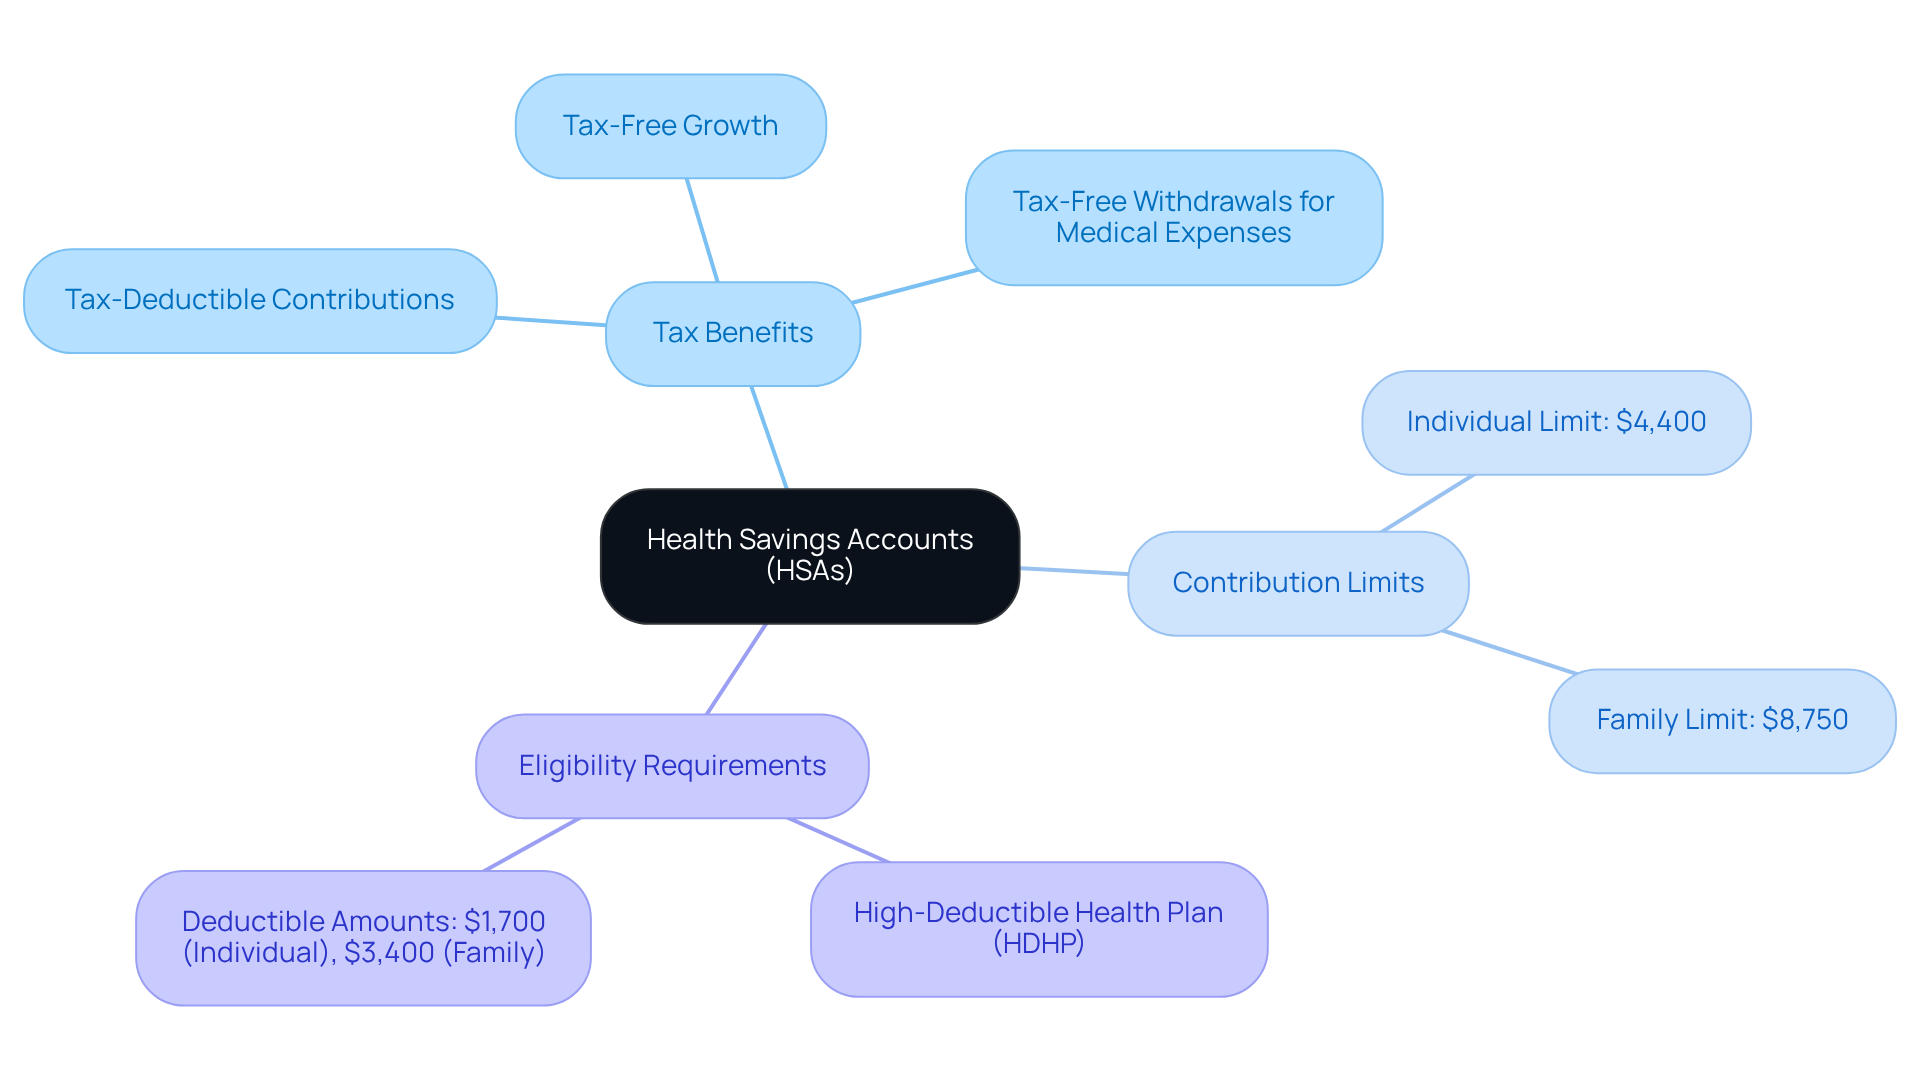
Imagine facing unexpected medical expenses while trying to provide the best for your family – this is where Health Savings Accounts (HSAs) can make a real difference. HSAs offer a financial tool that not only helps you save for your family’s healthcare needs but also provides a triple tax advantage: contributions you make are tax-deductible, your savings grow tax-free, and when you need to use them for medical expenses, it’s all tax-free too!
In 2026, you can contribute up to $4,400 as an individual or $8,750 as a family, giving you more flexibility to manage your healthcare costs. To take advantage of HSAs, you’ll need a high-deductible health plan (HDHP), which means having a deductible of at least $1,700 for yourself or $3,400 for your family. This can feel daunting, but it’s a step towards better financial health for your loved ones.
As a family, think about maximizing your HSA contributions – this can be a smart move, especially if you’re navigating a high-deductible health plan. It’s about securing your family’s future together. Not only does this help lower your taxable income, but it also prepares your family for future healthcare costs while implementing a high income tax strategy in the Bay Area to avoid extra tax burdens. It’s a win-win for your peace of mind!
Starting January 1, 2026, more families will have the chance to open HSAs, thanks to the expansion of eligibility to Bronze and Catastrophic ACA marketplace plans. This means that around 7.3 million more Americans can access these valuable accounts, making healthcare savings more attainable for everyone.
In 2026, the highest out-of-pocket costs for HDHPs will be capped at $8,500 for individuals and $17,000 for families. Knowing these limits can help you plan better for your family’s healthcare needs. By embracing HSAs, you’re not just managing healthcare costs; you’re taking a proactive step towards securing your family’s financial future while enjoying significant tax savings. Together, we can navigate this journey!
Optimize Home Ownership Deductions
Imagine feeling the weight of financial stress lift as you discover the tax benefits of home ownership in the Bay Area. Homeowners can deduct mortgage interest on loans up to $750,000, which can significantly reduce taxable income. Plus, property levies are deductible, limited to $10,000 for state and local deductions. By itemizing these deductions, families can ease their overall tax burden. Keeping track of home improvements is important, as they can help lower your taxes when it’s time to sell your home. For instance, if you invest in energy-efficient upgrades before the expiration of related tax credits in 2025, you can enhance your deductions while increasing your home’s value.
Consider Jay and Emma, a couple in their late 40s with two children. They felt overwhelmed by their financial situation and sought guidance from Bright Advisers. With a thorough monetary plan, they refined their tax arrangements and explored education savings options, allowing them to balance their current obligations with future goals. Similarly, Emily and Mark, both in their mid-30s, collaborated with Bright Advisers to develop a monetary plan that granted them the freedom to decide whether to continue working, while also managing their home ownership deductions effectively. These success stories show how families can use tax strategies, like tax-loss harvesting and strategic investment planning, to improve their financial well-being and secure their futures.
We’re here to help you connect with experts like Bright Advisers, who can create a personalized plan that fits your family’s unique financial journey.
Incorporate Estate Planning into Tax Strategy
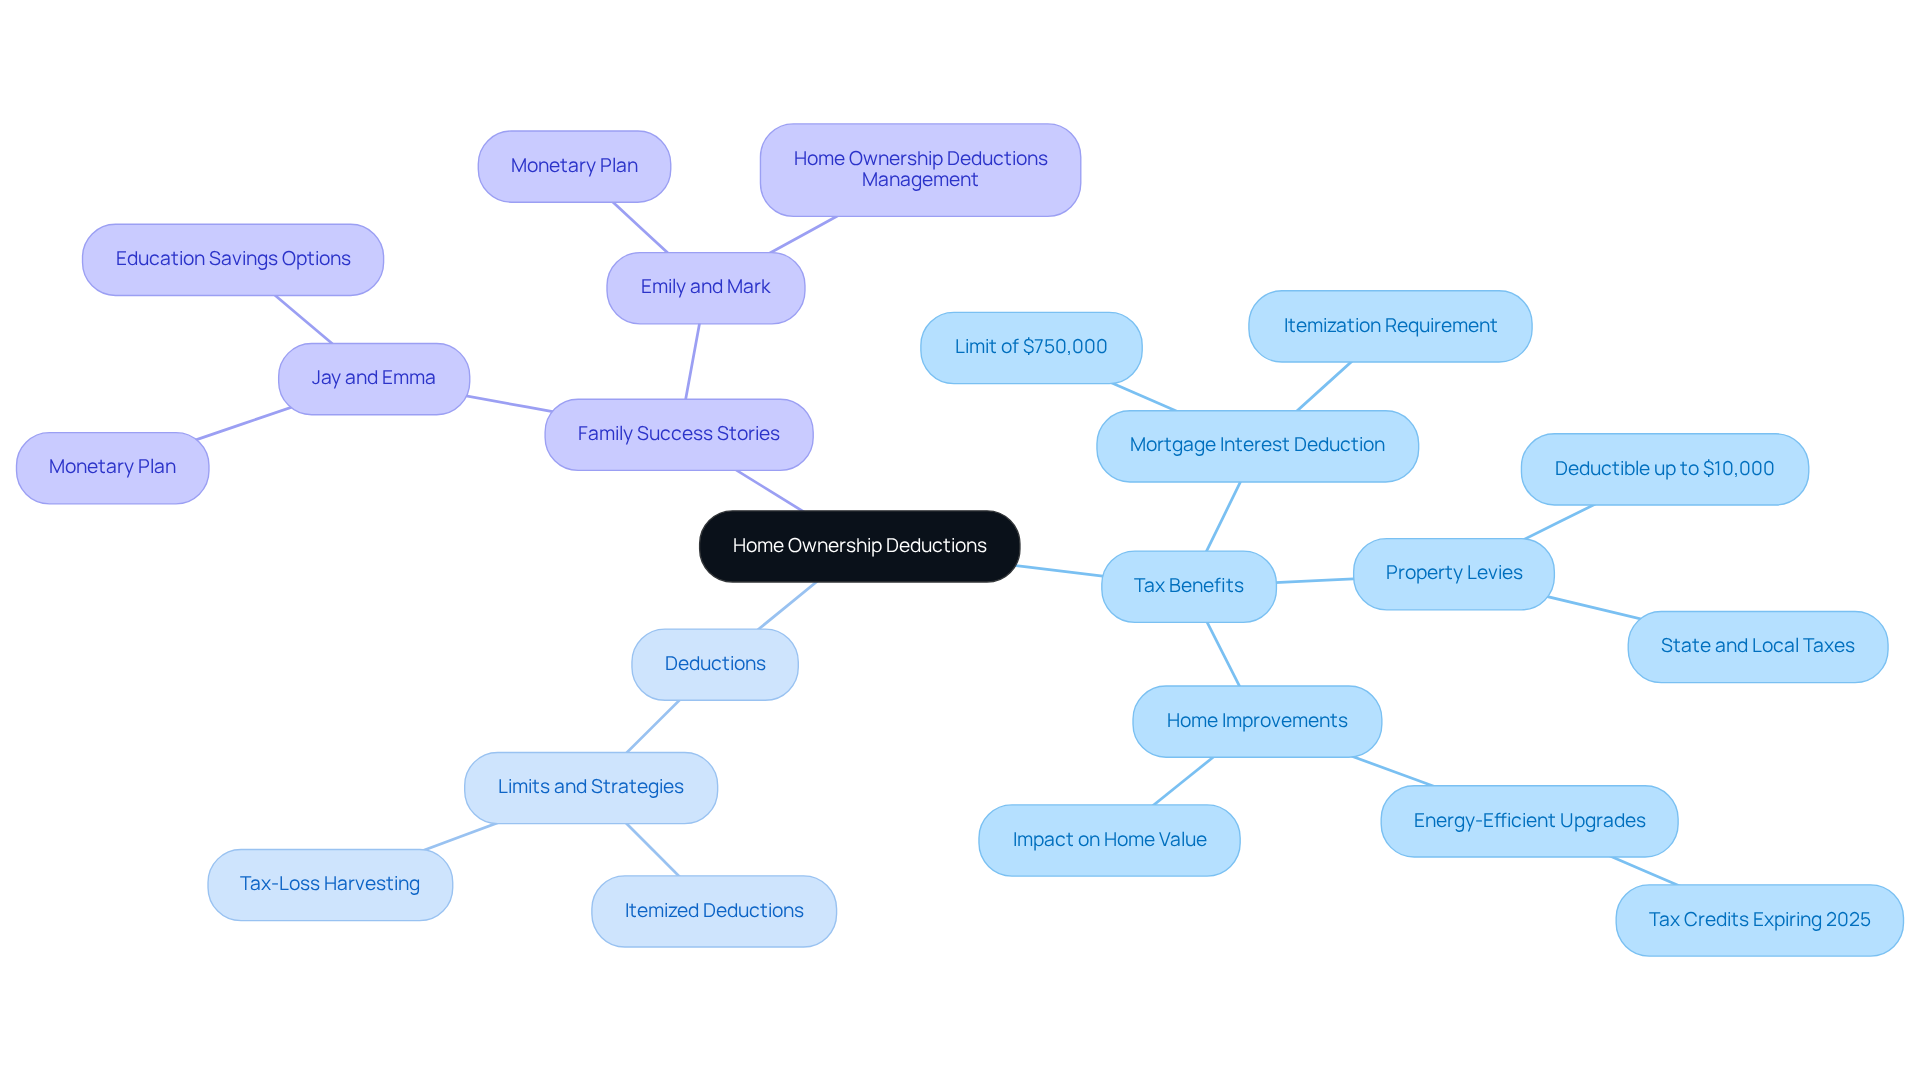
Imagine the peace of mind that comes from knowing your family’s future is secure, even in the face of rising estate taxes. Estate planning is essential for high-income households looking to implement a high income tax strategy in the Bay Area. You can use tools like irrevocable trusts and gifting strategies to lower estate taxes and make transferring your wealth easier. For example, in 2026, families can give gifts of up to $19,000 to each recipient each year without incurring gift taxes. This helps reduce the size of the taxable estate.
Establishing irrevocable trusts can further protect your assets from estate taxes while ensuring that future generations are taken care of. Proactive gifting strategies can help you avoid future tax obligations, allowing you to maximize your estate planning benefits before any potential changes in legislation.
Many families worry about how much of their hard-earned wealth will be lost to taxes. Without proper planning, families risk leaving their loved ones with financial burdens instead of a legacy. With the help of Bright Advisers, Allison and Brian found a way to not only save on taxes but also ensure their kids have the education they deserve.
With the right planning, you can ensure your family’s legacy thrives, not just survives.
Choose Tax-Efficient Investment Options
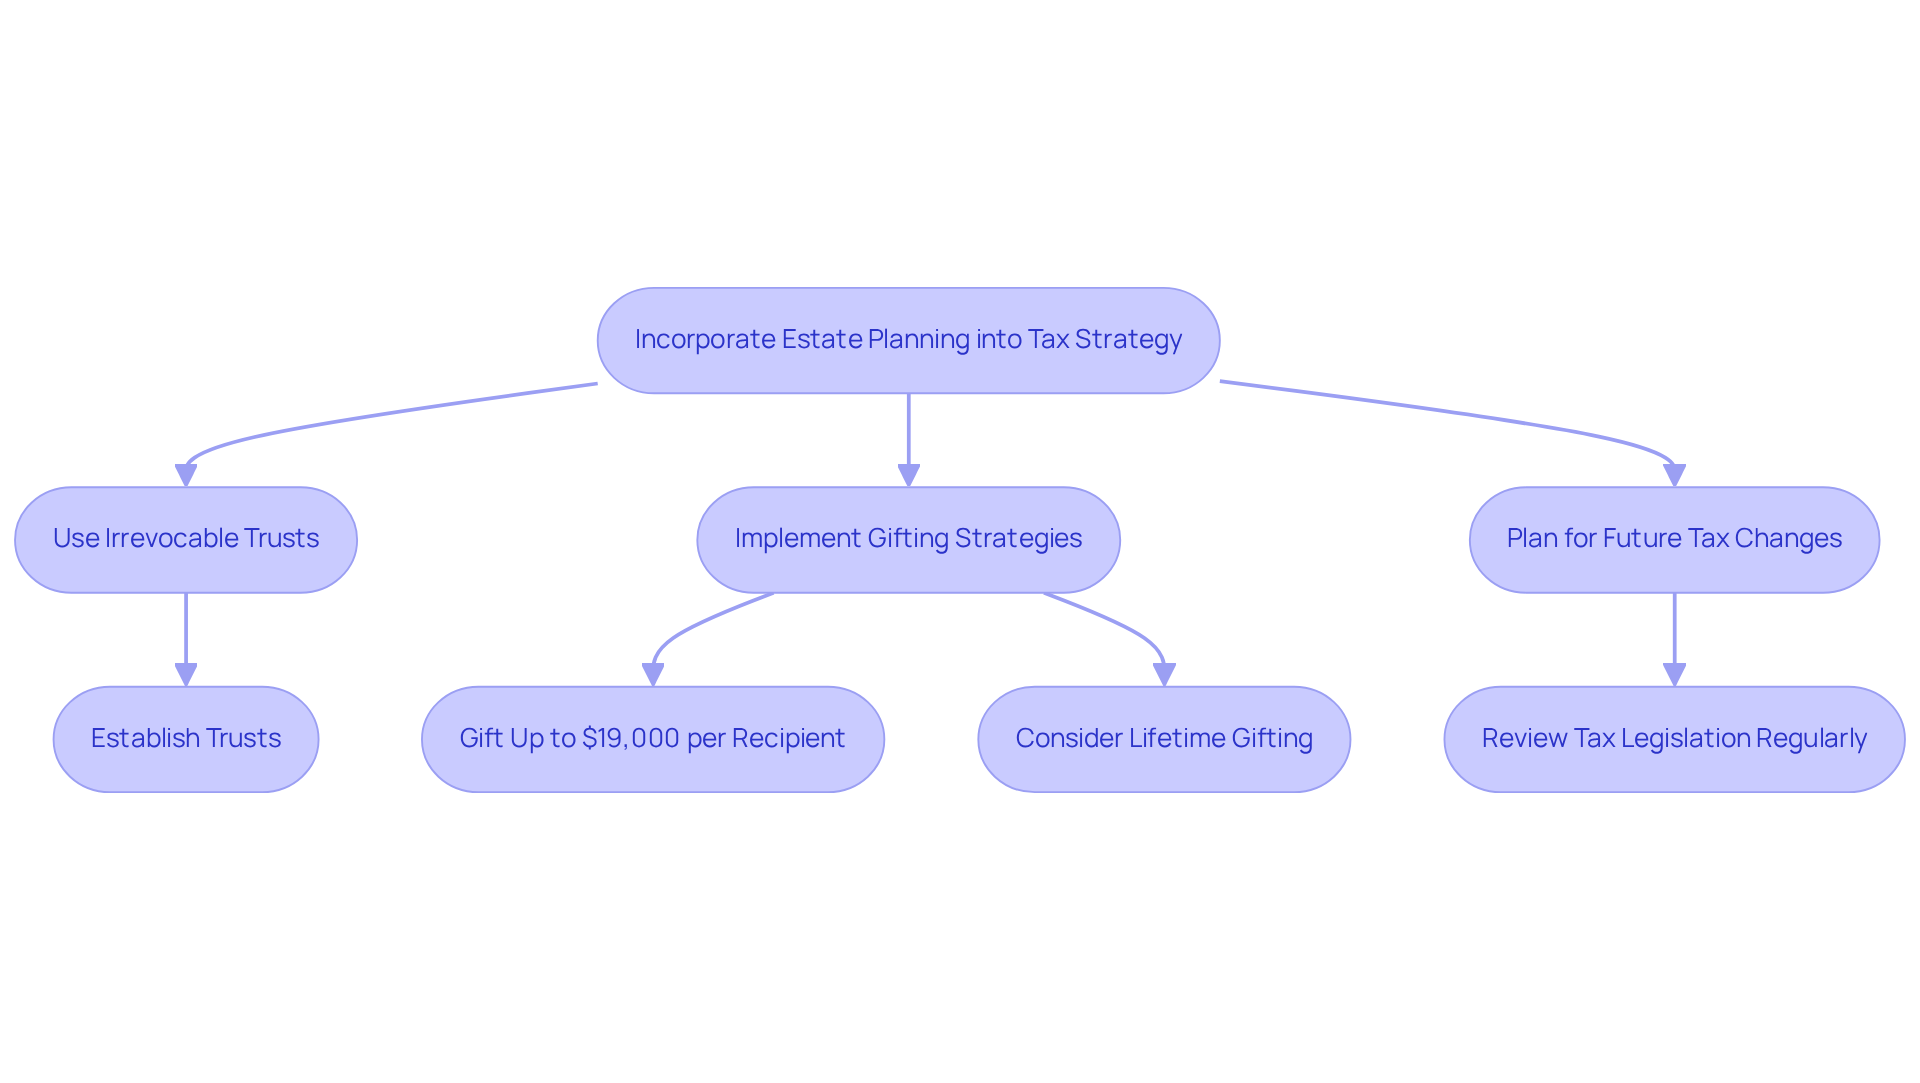
Imagine feeling confident about your family’s financial future, knowing you’re making the best choices for your loved ones. Many families find themselves wondering how to make the most of their hard-earned money. Tax-efficient investment options, like index funds and municipal bonds, can be a great place to start. Take municipal bonds, for instance. They provide tax-free interest income, which can be a real blessing for families in higher tax brackets. Consider this: if you’re in the top tax bracket, you’d need to earn almost 7.6% from a taxable bond just to match the 4.5% yield from a municipal bond. That’s a significant difference!
It’s also wise for families to think about holding investments that generate capital gains in tax-advantaged accounts like IRAs or 401(k)s. This way, you can defer taxes until retirement, giving you more time to grow your savings. By doing this, you can put off paying taxes until retirement, which can really help your investments grow over time. When you place your investments in the right accounts, you can lighten your tax burden and pave the way for a brighter financial future.
Take Jay and Emma, for example. As busy parents of two, they teamed up with Bright Advisers to create a solid plan that focused on tax planning and education savings. Then there’s Emily and Mark, who, despite their busy careers, found the freedom to choose whether to keep working by effectively managing their finances. Allison and Brian, even with their high incomes, discovered they were missing out on opportunities due to their high income tax strategy in the Bay Area. With Bright Advisers’ help, they secured their children’s future through education funding and gained the chance to retire sooner.
Talking with financial and tax experts can really boost your efforts. One specialist even said, ‘It’s wise to consult a professional tax advisor before making decisions that affect your tax obligations.’ By taking these steps, families can breathe a little easier, knowing they’re setting themselves up for a more secure future. With the right guidance, you can transform your financial landscape and create a legacy of security for your children.
Consider Roth Conversions for Future Tax Savings
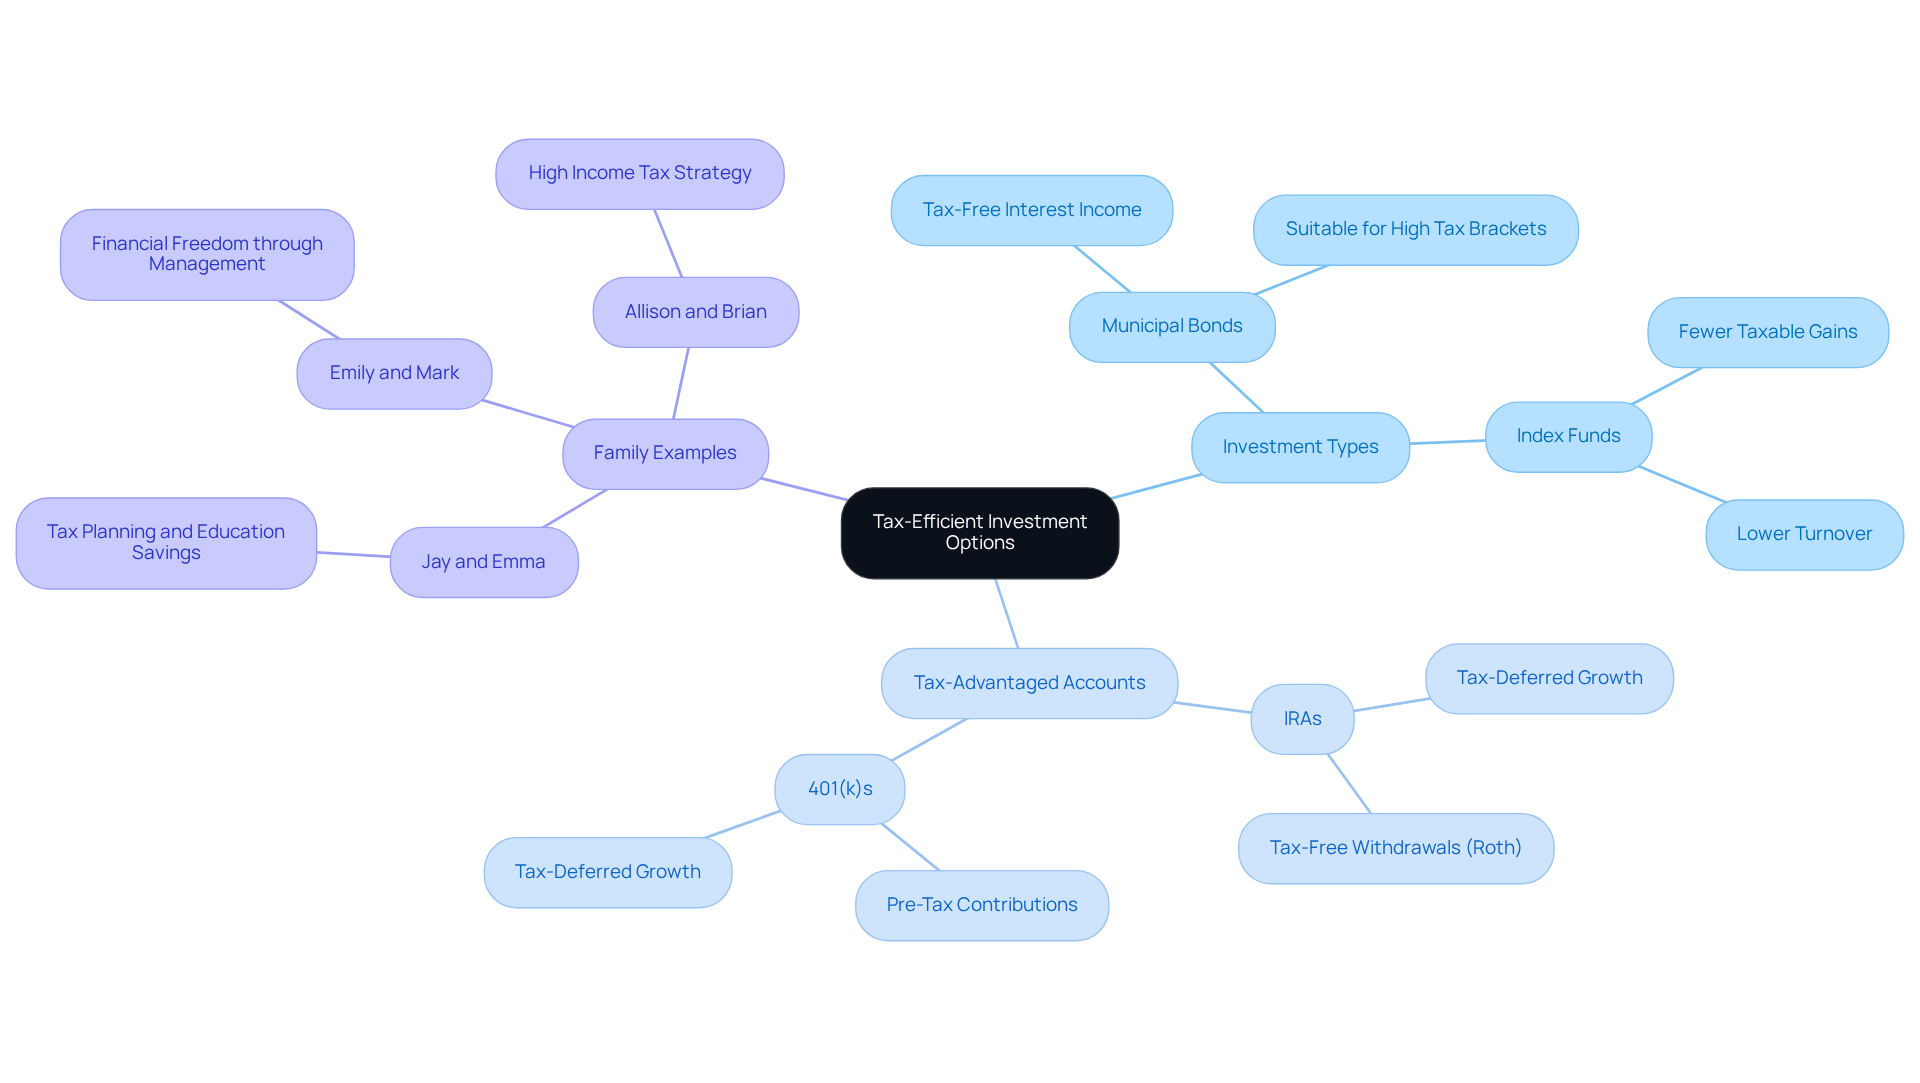
Imagine the weight of financial uncertainty as you think about your family’s future. How can you ensure their dreams are secure? Have you ever wondered how Roth conversions can help your family? By moving funds from a traditional IRA or 401(k) to a Roth IRA, you can enjoy tax-free withdrawals in the future. This strategy can be a game-changer for families who anticipate being in a higher tax bracket when they retire. By making the conversion now, you can pay taxes at your current rate, which might save you a lot in the long run.
Take Jay and Emma, for instance. They were able to ease their financial worries and support their children’s education by working with Bright Advisers on a Roth conversion strategy that fit their family goals. Timing is everything! If you can execute conversions during years when your income is lower, you can lessen the tax impact. For example, if your family withdraws $11,000 after a year, you might face a tax of $2,750. This really shows how important it is to plan strategically.
Working with a financial advisor can help your family navigate these choices. Just like Emily and Mark, who found the guidance they needed to build a strong financial foundation, giving them the freedom to choose their path. Using Roth conversions and other smart tax strategies can help your family feel more secure and achieve your dreams. Remember, past performance doesn’t guarantee future results, and investing always comes with risks. All our advisory services are offered through Lifeworks Advisors, a trusted partner in your financial journey.
Understand Capital Gains Tax Implications
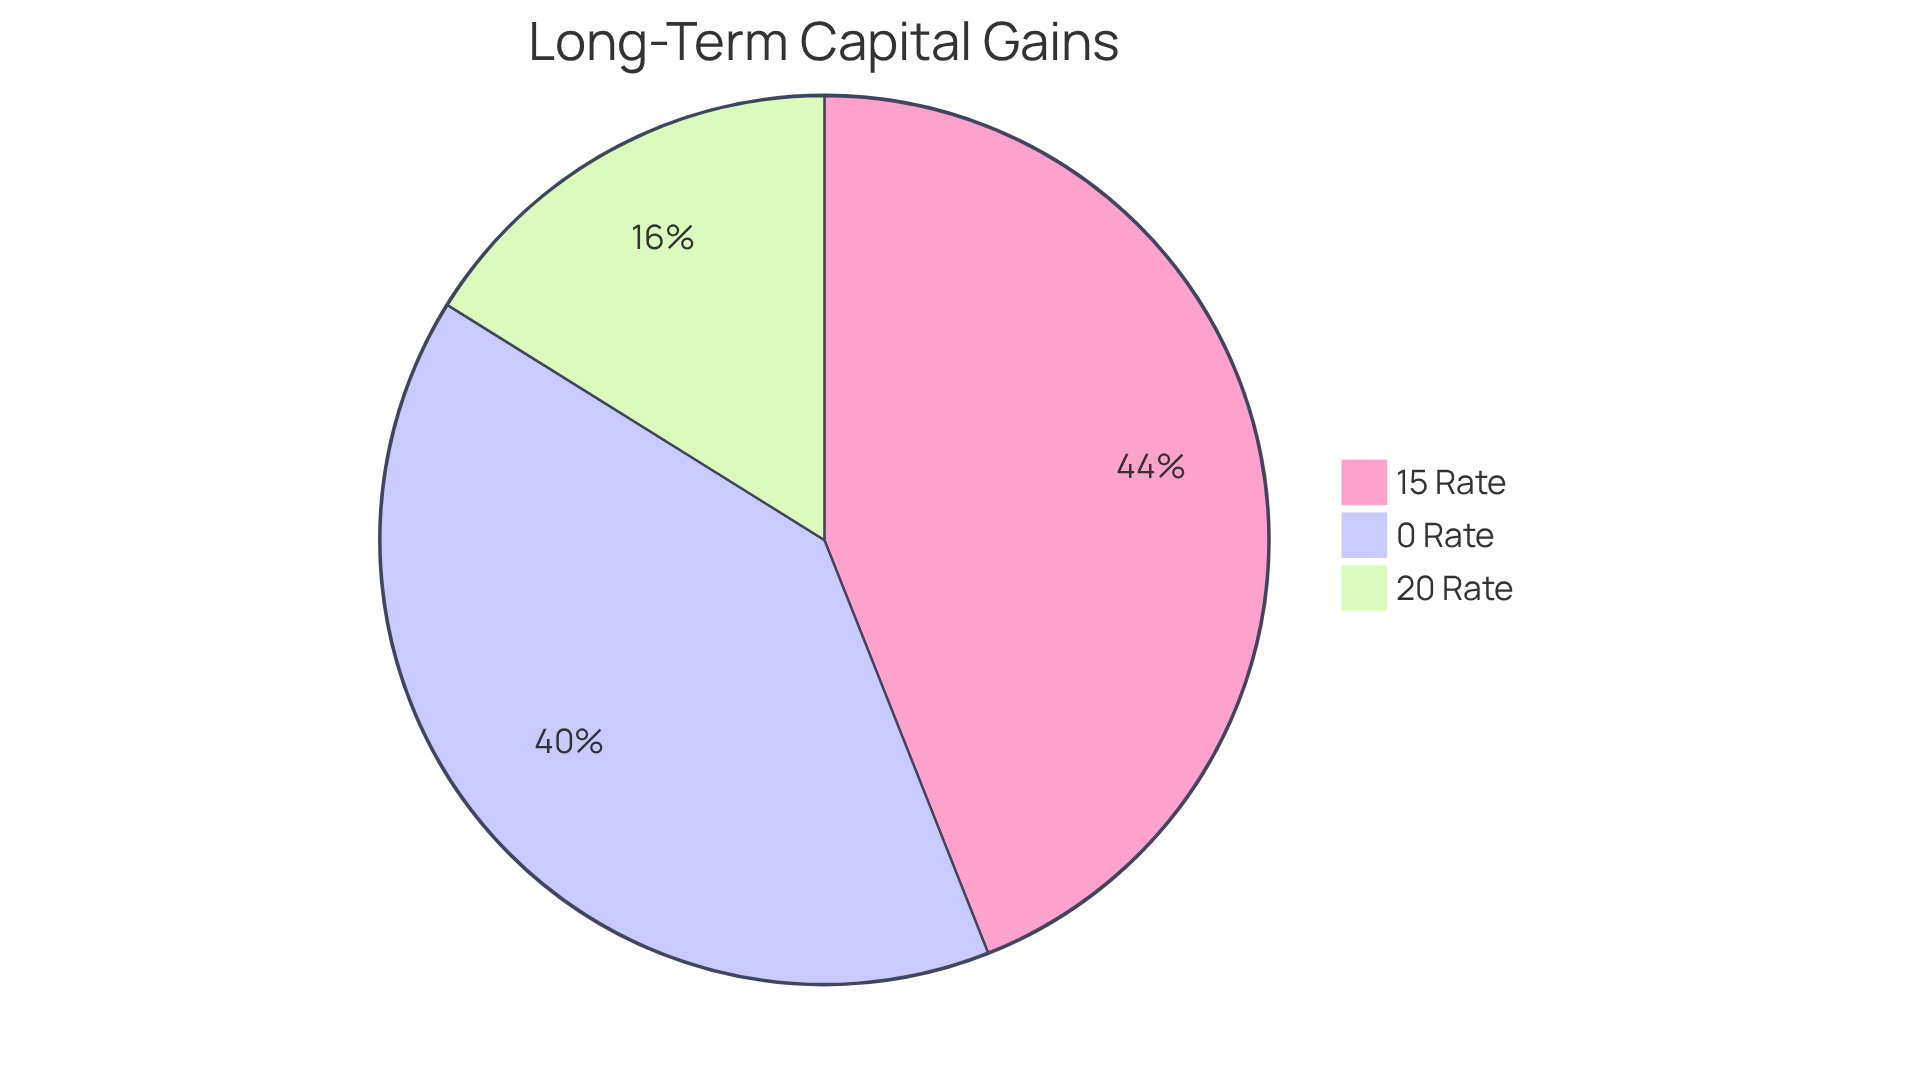
Imagine facing a hefty tax bill just when you thought you were making progress with your investments. Capital gains taxes can significantly impact high-income households, especially when they consider a high income tax strategy in the Bay Area while selling appreciated assets. For 2026, here’s how long-term capital gains tax rates break down:
- 0% for income up to $49,450
- 15% for income up to $545,500
- 20% for income beyond that
It’s important to understand that long-term capital gains are taxed at lower rates than ordinary income, making it essential to plan accordingly. You might consider strategies like tax-loss harvesting, which can help reduce your gains and manage your tax responsibilities. Moreover, holding investments for over a year qualifies them for these lower long-term capital gains rates, enabling households to retain more of their investment profits. Navigating capital gains taxes can feel overwhelming, especially for families trying to make the most of their investments. Understanding these tax implications can empower your family to make informed financial decisions that support your future, particularly in relation to a high income tax strategy in the Bay Area.
Engage a Fiduciary Financial Advisor for Tax Planning
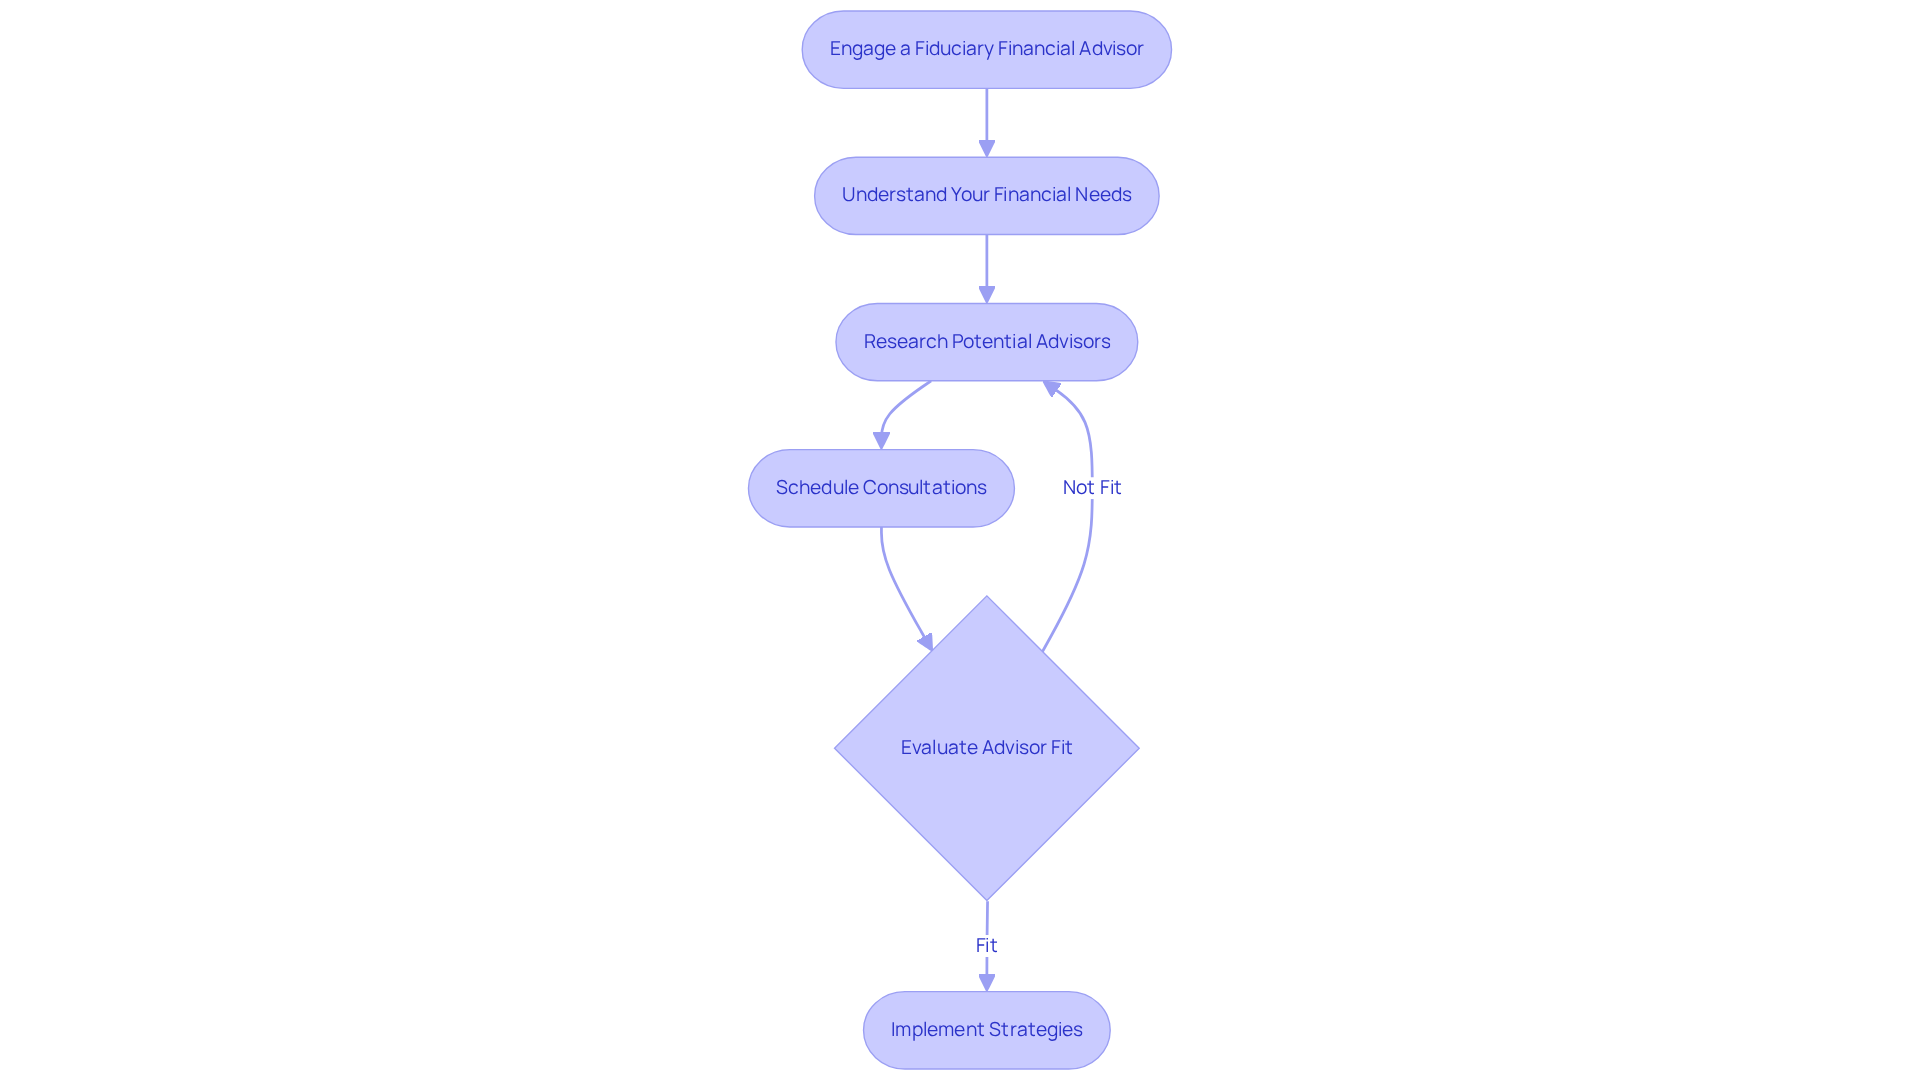
Imagine navigating the complexities of tax planning with a trusted partner by your side, ensuring your family’s financial future is secure. Affluent households ought to think about hiring a fiduciary advisor for efficient tax planning. A fiduciary advisor is someone who puts your family’s needs first, offering guidance tailored just for you. This includes strategies for enhancing deductions, improving investment portfolios for tax efficiency, and preparing for future tax consequences. Imagine having a fiduciary advisor who helps you understand tax regulations, making it easier to reduce your tax burden while reaching your financial goals.
Let’s look at how families like yours have thrived with the help of fiduciary advisors. For instance, fiduciary advisors do not earn commissions from financial products, allowing them to suggest strategies based solely on your economic goals. This approach ensures that you receive the most tax-efficient and beneficial solutions for your estate planning needs. Additionally, fiduciary advisors are committed to full transparency, disclosing all fees and potential conflicts of interest, which fosters trust and confidence in the wealth management process.
The demand for fiduciary advisors is increasing, with around 42,000 job openings anticipated each year for personal advisors from 2022 to 2032. This trend reflects the increasing need for comprehensive planning services, particularly in the context of high income tax strategy in the bay area. With the right support, you can confidently take steps toward a brighter financial future for your family. Engaging a fiduciary financial advisor can lead to better financial outcomes, as families benefit from personalized strategies that align with their long-term financial objectives.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the complexities of California’s tax landscape. You can take steps like:
- Contributing to retirement accounts
- Using tax-loss harvesting
- Giving to charity
to ease your tax burden and protect your family’s future. These strategies not only help you manage your taxes today but also set you up for a secure financial future.
Throughout this journey, remember the importance of:
- Leveraging Health Savings Accounts for tax benefits
- Optimizing home ownership deductions
- Incorporating estate planning into your tax strategies
Understanding capital gains tax implications and considering Roth conversions can further enhance your family’s financial position. Working with a trusted financial advisor can give you personalized support, helping you navigate tax planning with confidence.
Ultimately, strategic tax planning is essential. High-income families face a maze of tax laws and regulations, making it vital to stay informed and seek expert advice. By taking these steps, you can alleviate financial stress and create a legacy of security and prosperity for your loved ones. By embracing these strategies, you’re not just planning for today; you’re building a secure future for your loved ones, ensuring your hard work pays off for generations to come.
Frequently Asked Questions
What are the contribution limits for retirement accounts in 2026?
In 2026, the contribution limits are set at $24,500 for 401(k)s and $7,500 for IRAs.
How can contributing to retirement accounts benefit high-income households?
Contributing the maximum to retirement accounts can help lower taxable income, which is particularly important in high-tax states like California, where tax rates can reach 13.3%.
What is the advantage of using after-tax contributions to a 401(k)?
After-tax contributions to a 401(k) can be used to fund a Roth IRA, allowing for tax-free growth and withdrawals in retirement.
What additional contributions can individuals aged 50 and older make to their 401(k) in 2026?
Individuals aged 50 and older can contribute an additional $8,000 to their 401(k), while those aged 60 to 63 can qualify for a higher ‘super catch-up’ contribution of $11,250.
What is tax-loss harvesting and how does it work?
Tax-loss harvesting involves selling investments that have lost value to offset gains from other investments, which can lower taxable income. Families can offset up to $3,000 of ordinary income each tax year, with any additional losses carried forward.
When is tax-loss harvesting most effective?
Tax-loss harvesting is particularly effective during unstable market conditions, allowing families to maintain their investment approach while reducing tax effects.
What are some strategic charitable giving methods for high-income households?
High-income households can utilize donor-advised funds (DAFs) and qualified charitable distributions (QCDs) from IRAs to enhance their charitable impact and achieve greater tax benefits.
How can combining charitable contributions in one year benefit families?
By combining charitable contributions into one year, families can surpass the standard deduction limit, leading to a significant decrease in their tax obligation.
What is the benefit of donating appreciated assets?
Donating appreciated assets allows households to avoid capital gains taxes while still providing substantial support to charitable organizations.
What trend is observed among high-income households regarding charitable giving?
Nearly a quarter of families are using structured giving methods to make their charitable contributions more impactful, with many planning to establish a high income tax strategy in the Bay Area within three years.
List of Sources
- Maximize Retirement Account Contributions
- What are 2026 401(k) and individual retirement account max contribution limits? (https://principal.com/individuals/learn/what-are-2026-401k-and-ira-max-contribution-limits)
- What the Higher 401(k) and IRA Contribution Limits for 2026 Mean for Your Retirement Strategy (https://wealthenhancement.com/blog/401k-ira-contribution-limits)
- 2026 401(k) Contribution Limits Issued by the IRS (https://asppa-net.org/news/2025/11/2026-401k-contribution-limits-issued-by-the-irs)
- 401(k) Contribution Limits |2026, 2025 and Earlier | ADP (https://adp.com/resources/articles-and-insights/articles/4/401k-contribution-limits.aspx)
- Utilize Tax-Loss Harvesting Techniques
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Tax-loss harvesting | Capital gains and lower taxes | Fidelity (https://fidelity.com/viewpoints/personal-finance/tax-loss-harvesting)
- Tax Loss Harvesting Tips: Smart Strategies to Cut Taxes & Boost Returns (https://wealthenhancement.com/blog/essential-tax-loss-harvesting-tips)
- The Power of Tax-Loss Harvesting: A Key Tax Optimization Tool (https://assetmark.com/resources/blog/tax-loss-harvesting-for-tax-optimization)
- Implement Strategic Charitable Giving
- Activating DAF Donors with Wealth Data for Maximum Impact (https://windfall.com/blog/activating-daf-donors-with-wealth-data-for-maximum-impact)
- The 2024 DAF Report (https://nptrust.org/reports/the-2024-daf-report)
- Affluent Charitable Giving Trends and Statistics in 2024 (https://privatebank.bankofamerica.com/articles/bank-of-america-study-of-philanthropy.html)
- Who uses a DAF? (https://givechariot.com/resources/insights/who-uses-a-daf)
- 50 Giving Quotes to Re-Energize Your Nonprofit Community (https://pro.gofundme.com/c/blog/giving-quotes-inspire-nonprofit-community)
- Leverage Health Savings Accounts for Tax Benefits
- IRS Announces 2026 HSA and HDHP Limits (https://keenan.com/knowledge-center/news-and-insights/blogs/irs-announces-2026-hsa-and-hdhp-limits)
- HSA Changes 2026: New Rules, Contribution Limits, and What They Mean for You (https://healthcareinsider.com/hsa-changes-2026-rules-contribution-limits)
- HSA contribution limits 2026 and 2027 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- HSA contribution limits (https://optumbank.com/health-savings-accounts/resources/contribution-limits.html)
- Health Savings Accounts (HSAs) (https://congress.gov/crs-product/R45277)
- Optimize Home Ownership Deductions
- One Big Beautiful Bill: SALT deduction and other changes for homeowners (https://hrblock.com/tax-center/irs/tax-law-and-policy/one-big-beautiful-bill-salt-deduction?srsltid=AfmBOooL-0CwrBy9y0gwFIA6g3b5ZLDIGNMQ3igdJgyB2IU34vOo_4Wy)
- Homeowners should review any tax benefits for homeownership | Internal Revenue Service (https://irs.gov/newsroom/homeowners-should-review-any-tax-benefits-for-homeownership)
- 7 tax deductions every homeowner should claim in 2026 (https://cnbc.com/select/tax-deductions-for-homeowners)
- Is property tax deductible? (https://hrblock.com/tax-center/filing/adjustments-and-deductions/deducting-property-taxes?srsltid=AfmBOoq2SoWI1KPThuHC5J2AHkJpIfhTOBDc7NJoQ8tC9ZCvQJGH1ib7)
- Reforms to the Mortgage Interest Deduction with Revenue Estimates (https://congress.gov/crs-product/IF13190)
- Incorporate Estate Planning into Tax Strategy
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- Gifting Strategies to Minimize Estate Tax Beyond Exemptions (https://privatebank.bankofamerica.com/articles/estate-tax-savings-beyond-exemptions.html)
- The Estate Tax and Lifetime Gifting (https://schwab.com/learn/story/estate-tax-and-lifetime-gifting)
- Reduce Your Estate’s Tax Burden with Gifting (https://epwealth.com/blog/tax-efficient-gifting-reduce-estate-tax-burden)
- Estate Tax Planning Strategies for High-Net-Worth Clients (https://icfs.com/specialists-desk/estate-tax-strategies-high-net-worth)
- Choose Tax-Efficient Investment Options
- Tax-efficient investments | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/tax-saving-investments)
- Tax-Efficient Investing for High-Income Earners (https://lpl.com/investors/investment-essentials/investing/tax-efficient-investing-for-high-earners.html)
- Tax-Efficient Investing: How to Minimize Investment Taxes (https://merrilledge.com/article/tax-smart-investment-strategies-you-should-consider)
- Tax-efficient investing for high-income earners (https://edwardjones.com/us-en/market-news-insights/guidance-perspective/tax-efficient-investing)
- How to Invest in Municipal Bonds for Tax-Free Income | VanEck (https://vaneck.com/us/en/blogs/income-investing/how-to-invest-in-municipal-bonds-for-tax-free-income)
- Consider Roth Conversions for Future Tax Savings
- Is a Roth IRA conversion right for you? | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/ira-roth-conversion)
- Net Present Value Analysis of Roth Conversions (https://financialplanningassociation.org/learning/publications/journal/SEP24-net-present-value-analysis-roth-conversions-OPEN)
- The Case for Roth Conversions through 2025 | Serving Those Who Serve (https://stwserve.com/case-for-roth-conversions-through-2025-tax-rates-chart)
- Size Matters in the Roth IRA Conversion Decision | Elm Wealth (https://elmwealth.com/roth-conversion)
- Roth conversions could offer more value than your clients expect (https://advisors.vanguard.com/insights/article/roth-conversions-could-offer-more-value-than-your-clients-expect)
- Understand Capital Gains Tax Implications
- What is capital gains tax? | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/realized-capital-gains)
- Capital gains tax: Definition, rates, and ways to save | Fidelity (https://fidelity.com/learning-center/smart-money/capital-gains-tax-rates)
- 2026 Federal Income Tax Brackets and Interactive Calculator (https://bipartisanpolicy.org/explainer/2026-federal-income-tax-brackets-and-interactive-calculator)
- How are capital gains taxed? (https://taxpolicycenter.org/briefing-book/how-are-capital-gains-taxed)
- Engage a Fiduciary Financial Advisor for Tax Planning
- Study: Americans Working With CFP® Professionals Enjoy Greater Financial Well-Being (https://cfp.net/news/2025/02/news-releases/americans-working-with-cfp-professionals-enjoy-greater-financial-well-being)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- Cerulli Associates | Research and Consulting for U.S. Financial… (https://cerulli.com/reports/us-advisor-metrics-2024)
- Why Fiduciary Responsibility is Crucial in Financial Planning (https://team.monetagroup.com/why-fiduciary-responsibility-is-crucial-in-financial-planning)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Philanthropy for high-income W-2 families at Bright Advisers.
Keep reading