

Key Highlights
- Emily exercises 1,000 ISOs at a $10 price while the market price is $50, illustrating potential tax implications.
- Families can exercise up to $30,123 of bargain element without incurring AMT, emphasising the need for careful planning.
- In 2026, the AMT exemption for joint filers will be $137,000, and selling ISO stock in the same year results in ordinary income tax.
- The bargain element is the difference between the fair market value and the exercise price, which can significantly impact tax liabilities.
- Case studies show families like Allison and Brian improved their tax situations by collaborating with Bright Advisers.
- Timing strategies, such as exercising ISOs early or staggering exercises, can help manage AMT exposure effectively.
- Families can leverage AMT credits in future tax years to offset regular tax liabilities, improving financial outcomes.
- Understanding AMT implications is crucial for families during high-income years to avoid unexpected tax burdens.
- Immediate sales post-exercise can avoid AMT but may lead to higher ordinary income taxes, necessitating careful evaluation.
- Strategic planning around ISO exercises can help families manage tax liabilities and secure their financial future.
Introduction
Imagine navigating tax planning, a task that can feel overwhelming for young parents. Families like Emily and Mark often face unexpected tax bills that leave them feeling anxious and uncertain. Together, we’ll explore ten common pitfalls with ISOs and AMT that families often encounter, ensuring you can make informed decisions that align with your financial goals. But how can you, as a young parent, navigate these challenges and find peace of mind when tax season arrives?
Case Study: Exercising ISOs and Triggering AMT
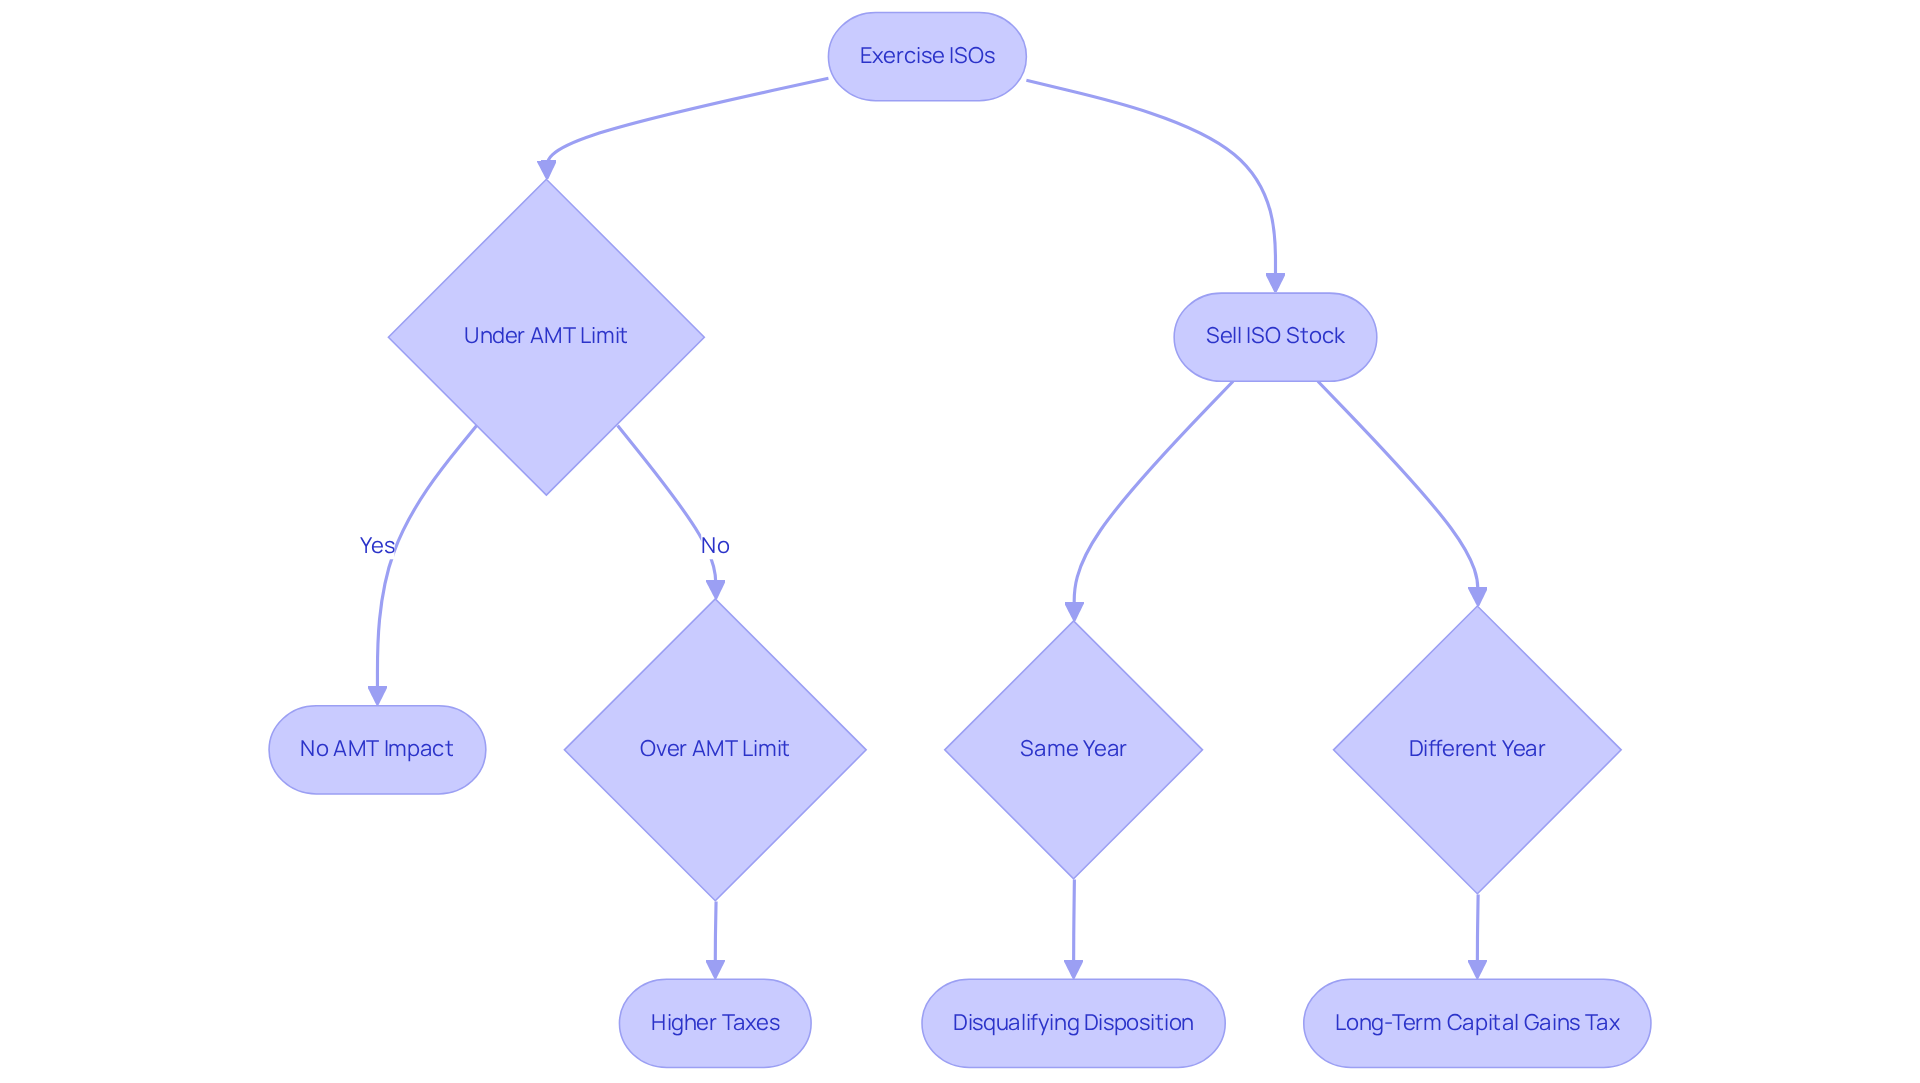
Imagine the surprise of receiving a hefty tax bill after exercising stock options, leaving you wondering how to manage unexpected expenses. Let’s consider Emily, a parent just like you, who exercises 1,000 ISOs at an exercise price of $10 while the market price is $50, providing an iso amt example. This situation highlights how important it is to plan carefully when exercising stock options, so you don’t end up with unexpected tax bills that can cause stress.
If Emily’s household has a combined income of $300,000, they can exercise up to $30,123 of bargain element, which serves as an iso amt example, without incurring AMT. But if they go over that limit, it could mean facing higher taxes, which can feel overwhelming for families trying to manage their finances. The AMT is activated by the difference between the exercise price and the market price at the time of exercise, which can complicate tax calculations for households, especially if they are not prepared for the potential tax impact.
Looking ahead to 2026, families should know that the AMT exemption for joint filers will be $137,000, and the top long-term capital gains tax rate will be 20%. Families must be aware that if they sell ISO stock in the same year it is exercised, it results in a disqualifying disposition, eliminating the need for an AMT adjustment but subjecting the spread to ordinary income tax. This highlights the importance of understanding the timing of sales and exercises to manage tax liabilities effectively.
By planning ahead, families can feel more confident in their decisions about exercising ISOs, knowing they’re managing their tax exposure effectively. Together, we can navigate this journey, ensuring that your family’s financial future is secure.
Understanding the Bargain Element in AMT Calculations
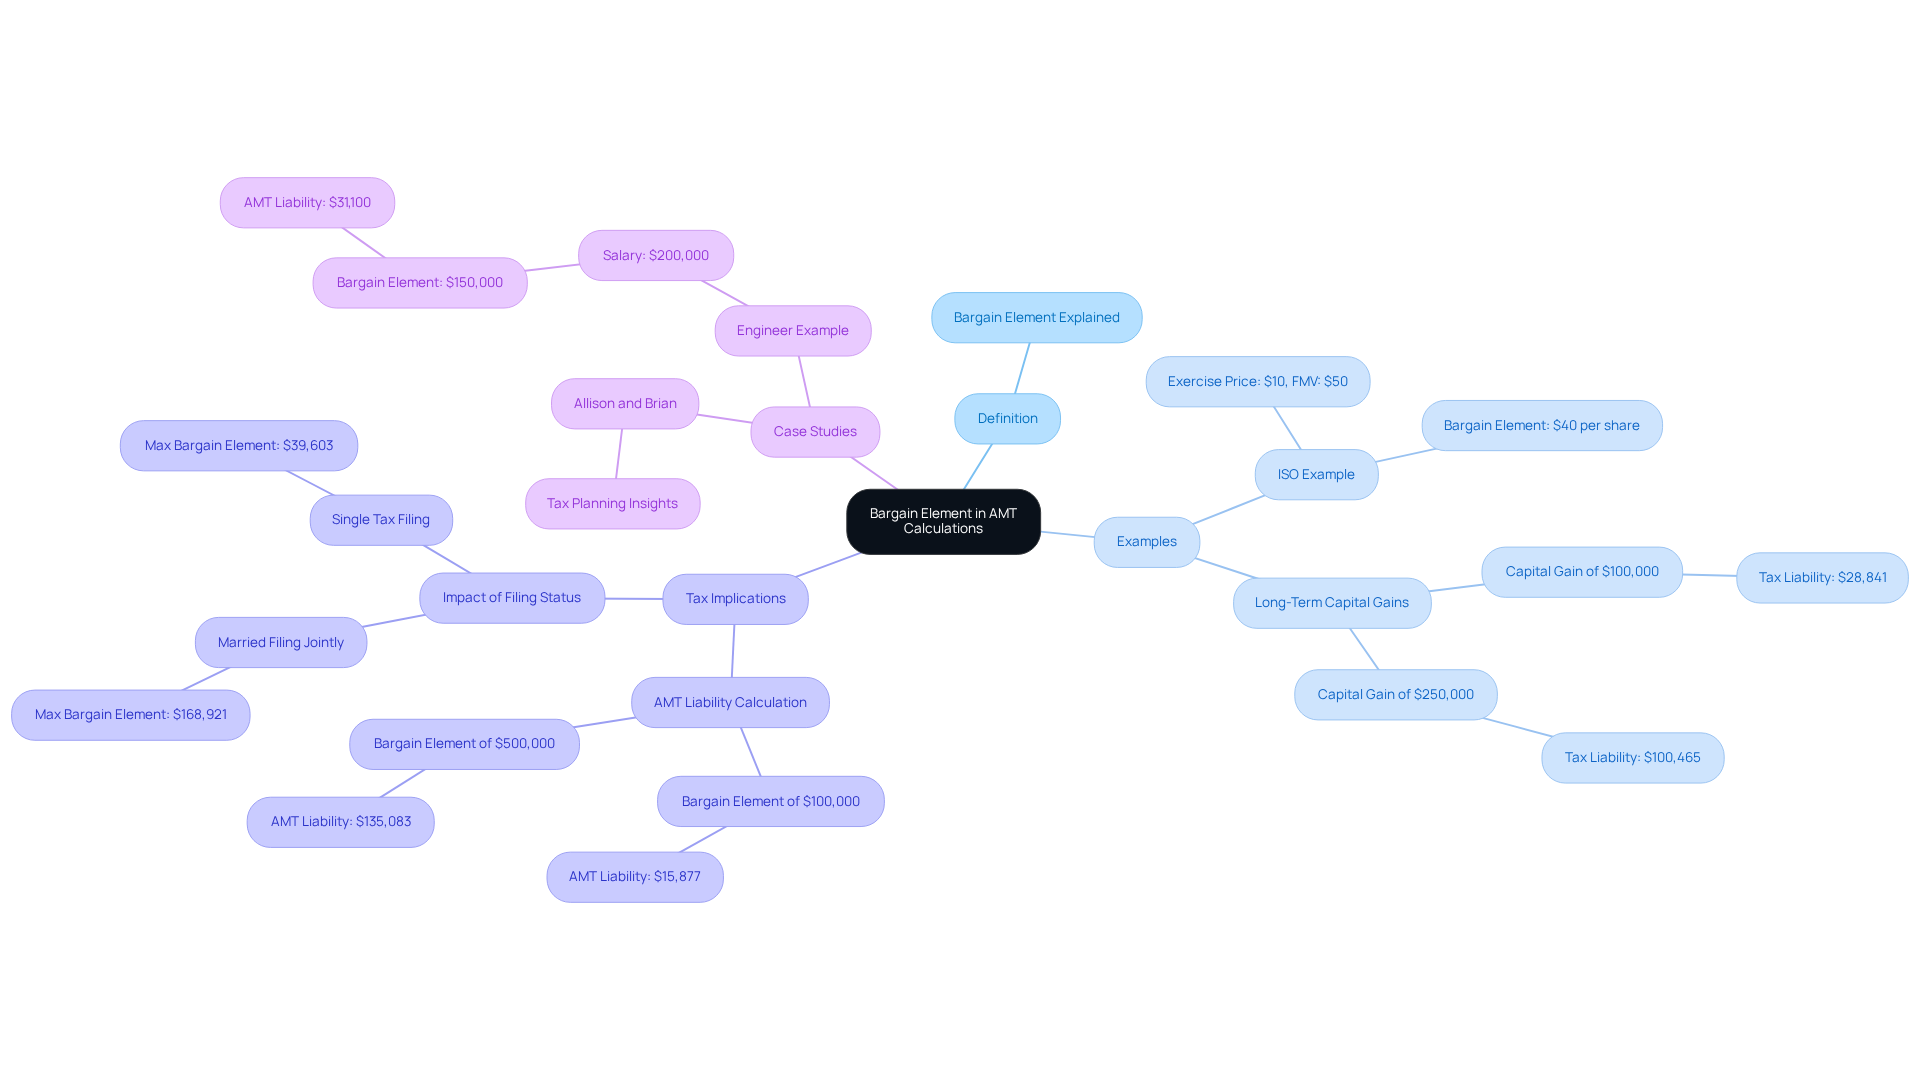
Imagine the surprise when tax season arrives, and you find out your tax bill is much higher than expected. The bargain element represents the difference between the fair market value (FMV) of stock at the time of exercise and the exercise price. For instance, if you exercise incentive stock options (ISOs) at an exercise price of $10 while the FMV is $50, that means you have a bargain element of $40 per share. Understanding this figure can help you avoid unexpected tax surprises, especially when considering the iso amt example, which can significantly increase tax liabilities. It’s important for families to monitor this closely to avoid surprises during tax season.
In 2026, the AMT exemption for single taxpayers is set at $90,100, while for married couples filing jointly, it is $140,200. The AMT applies statutory rates of 26% and 28% to alternative minimum taxable income. For instance, if you have a long-term capital gain of $100,000, you might be surprised to see a tax bill of nearly $28,841. If your long-term capital gain rises to $250,000, that liability could jump to $100,465. An iso amt example illustrates that the bargain element of $100,000 results in an AMT liability of $15,877, leading to a total federal tax liability of $29,718.
Case studies illustrate the importance of understanding the bargain element. Take Allison and Brian, for example. This couple, with significant incomes, was initially unaware of the monetary opportunities they were missing due to insufficient tax planning. After collaborating with Bright Advisers, they learned how to effectively manage their tax situation. An engineer with a $200,000 salary who exercises 10,000 ISOs at a $5 strike price incurs a bargain element of $150,000, which serves as an iso amt example resulting in an AMT liability of approximately $31,100. This highlights the potential tax implications of exercising ISOs without selling shares.
Together, we can explore effective planning strategies that help your family manage AMT exposure and keep your AMT income below the exemption threshold. By utilizing professional guidance, households like Allison and Brian can navigate these complexities and improve their financial security.
Timing Strategies: Managing AMT Through ISO Exercises
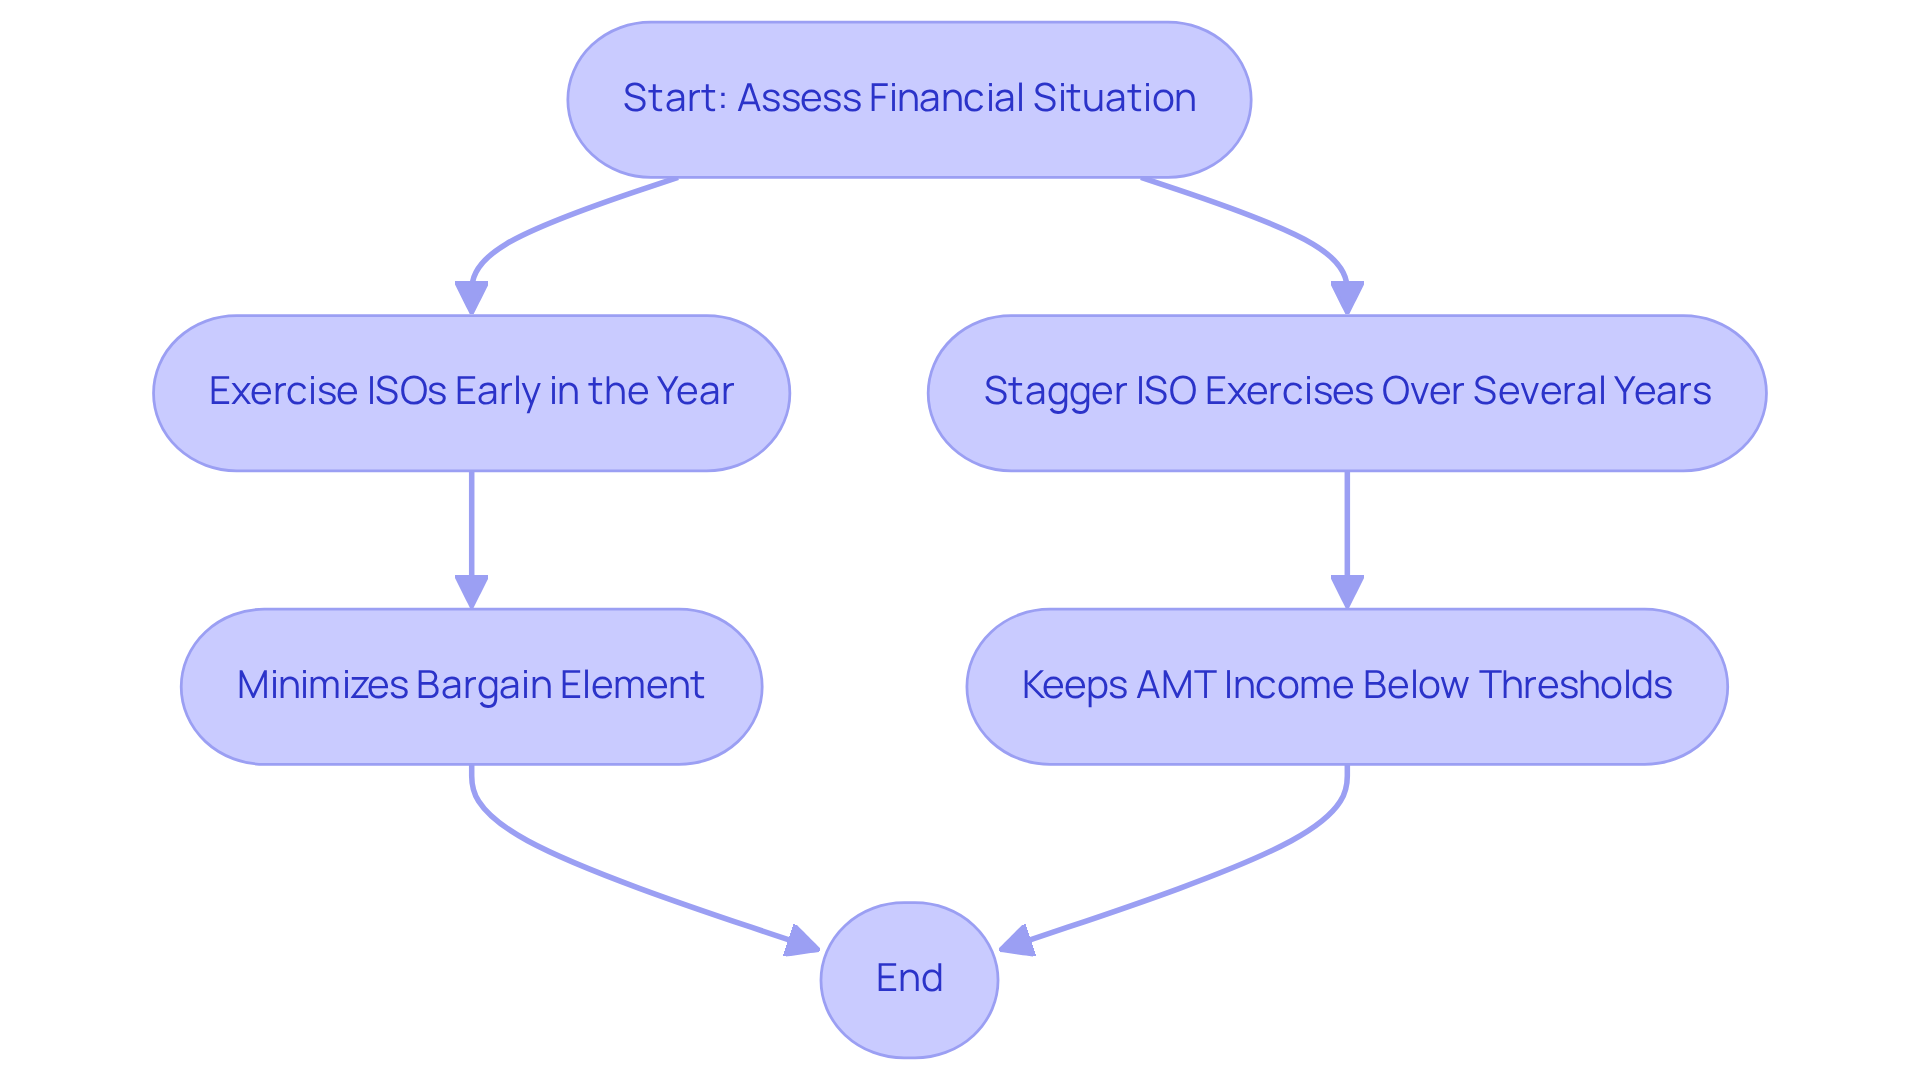
Imagine the relief of knowing your family’s finances are secure, even when faced with complex tax challenges like AMT liabilities. You might find it helpful to exercise ISOs early in the year when your income is lower. This approach minimizes the bargain element, which is the difference between the strike price and the fair market value, making the iso amt example less likely to become a burden.
Consider this: if the fair market value is significantly higher than the strike price, the bargain element can lead to a surprising increase in iso amt example income. You might also find it beneficial to stagger your ISO exercises over several years, which can serve as an iso amt example to help keep your AMT income below those thresholds and avoid unexpected tax bills.
By taking control of your AMT strategies, you can create a more secure financial future for your family. Exercising options when the difference between the strike price and fair market value is small can further ease your AMT worries. For instance, exercising options with just a $1 spread adds only $10,000 to your Alternative Minimum Taxable Income (AMTI), compared to a much larger amount if the spread is wider.
With these timing strategies in place, you can navigate the complexities of AMT more effectively, turning potential tax burdens into opportunities for financial growth and peace of mind for your family.
Bright Advisers: Optimizing AMT Outcomes for Families
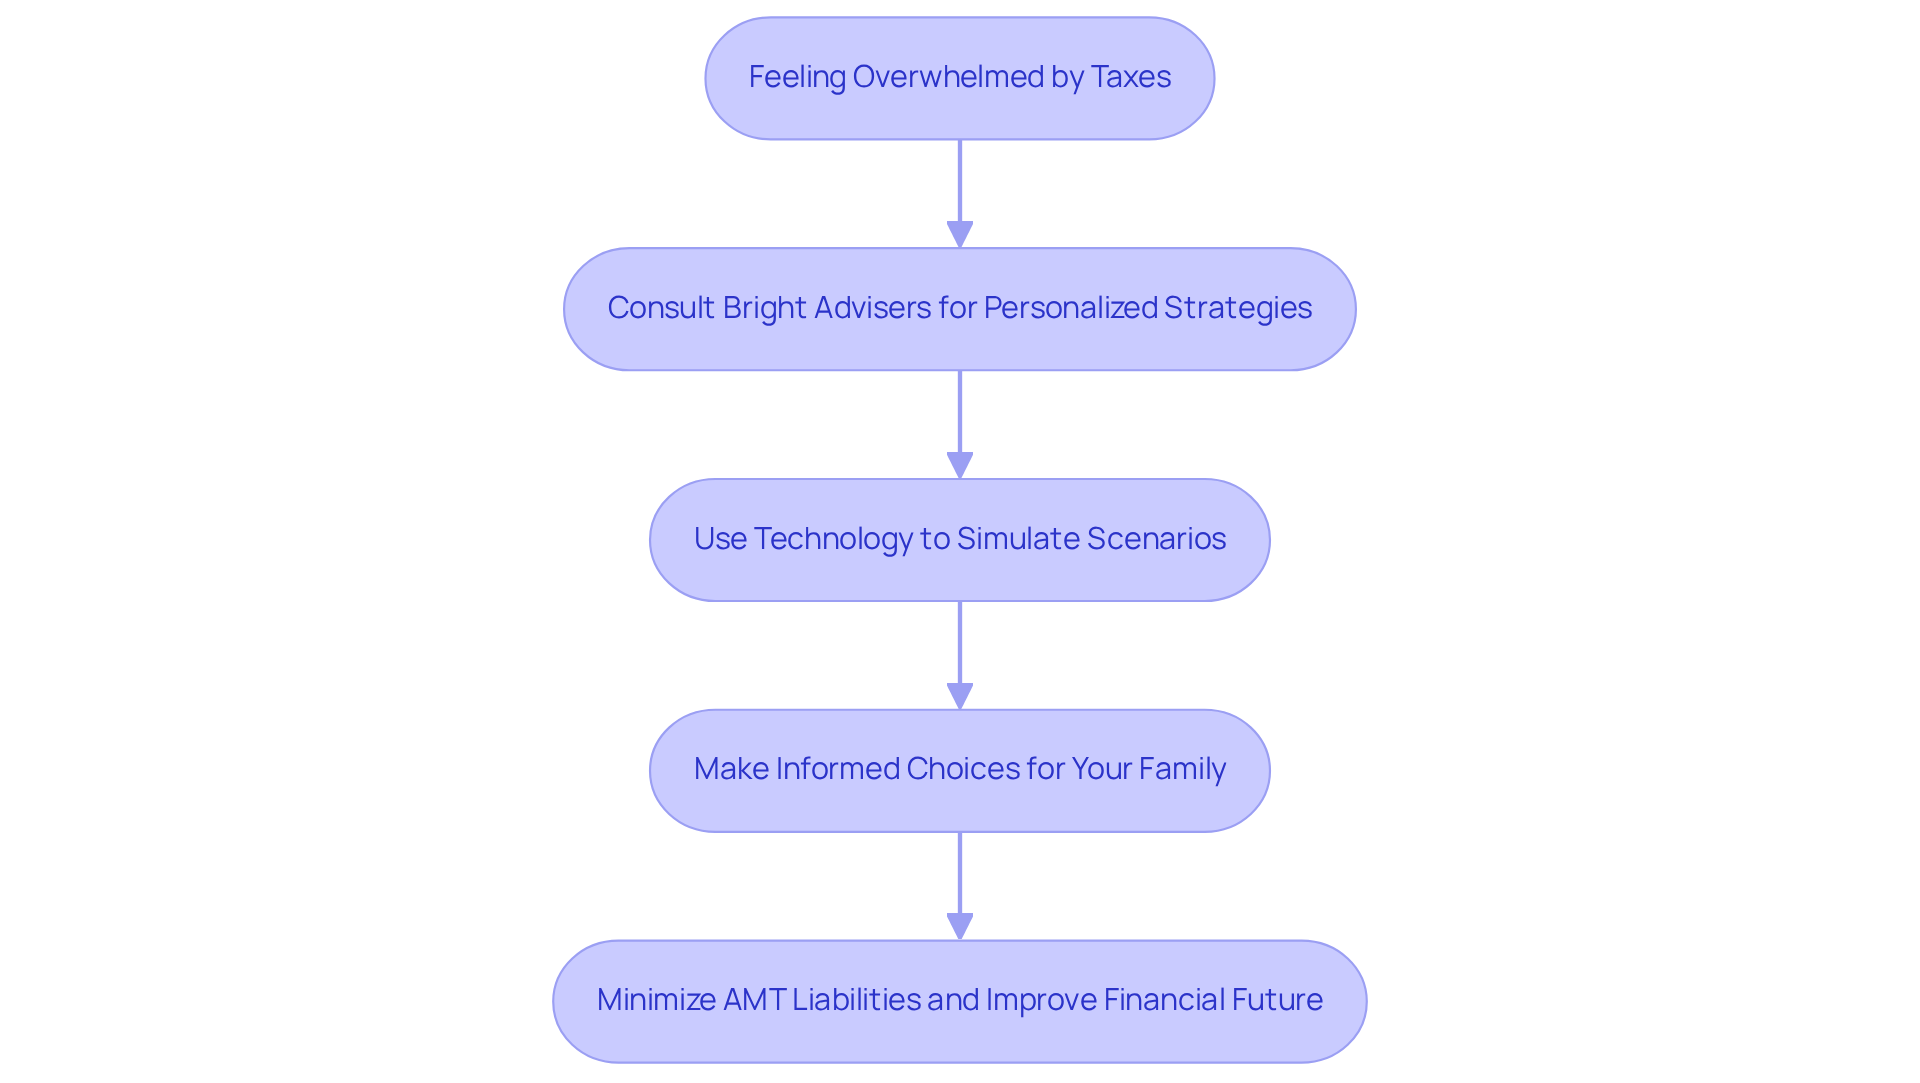
Imagine feeling overwhelmed by the complexities of taxes, especially when it comes to your family’s financial future. Bright Advisers is here to help. We provide personalized tax planning strategies, which serve as an iso amt example, to help families understand their AMT liabilities. This way, you can take effective steps to minimize them.
We use advanced technology to simulate different scenarios. This helps families make informed choices that focus on what matters most – their children. With careful planning, families can tackle AMT challenges and improve their financial future together by using an iso amt example.
Unexpected AMT Liabilities: A Cautionary Tale
Imagine Mark and Allison, who thought they were making a smart financial move by exercising their incentive stock options (ISOs). But they didn’t realize the implications of the ISO AMT example, which led to a shocking $30,000 tax bill from their exercised options. This unexpected burden put a strain on their finances, forcing them to rethink their entire financial strategy. Their story highlights how crucial it is for families to understand AMT and seek guidance from a wealth advisor to navigate these tricky waters together.
Leveraging AMT Credits: A Successful Tax Strategy
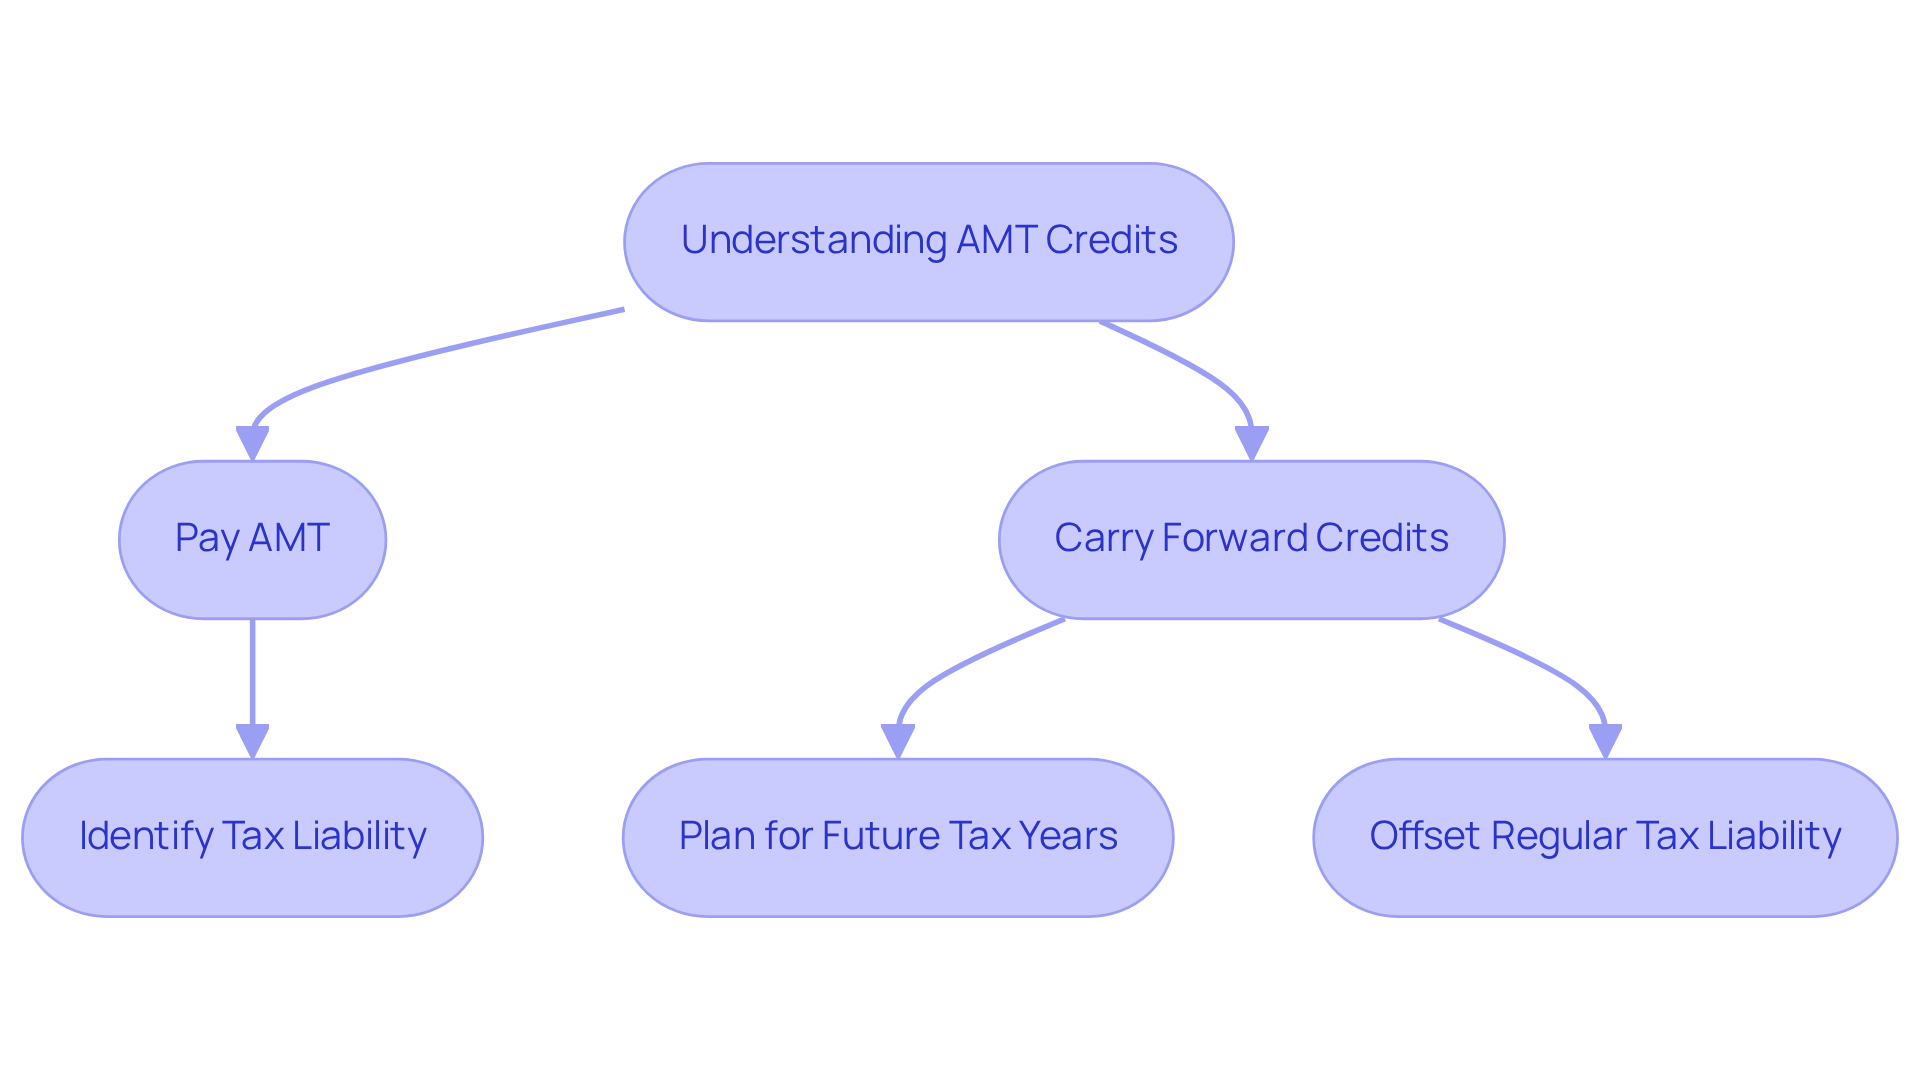
Imagine feeling uncertain about your family’s financial future due to taxes you didn’t expect. Families who pay Alternative Minimum Tax (AMT) because of exercising Incentive Stock Options (ISOs) can find hope in strategically leveraging iso amt example credits in future tax years. For instance, if Allison and Brian paid AMT last year, the iso amt example allows them to carry forward that credit to offset their regular tax liability in the years to come.
Keeping an eye on AMT credits can really help your family save on taxes in the long run. This strategy not only assists households in recovering some of the taxes paid but also improves their overall financial situation. It’s common for families to feel lost when it comes to tax credits and their impact on financial well-being.
In 2026, households can anticipate that the AMT exemption amount for Married Filing Jointly will be $137,000, and for Single or Head of Household, it will be $88,100. When you know how to use these credits, it can make a big difference for your family’s finances.
As noted by Secfi, ‘The key is not just understanding whether you might owe AMT, but planning for it ahead of time.’ By collaborating with Bright Advisers, households like Allison and Brian can create a thorough strategy that encompasses tax efficiency, securing their children’s future through education funding, and achieving the ability to retire earlier.
With the right guidance, you can turn tax challenges into opportunities for your family’s growth and security.
Young Parents and AMT: Navigating Stock Option Challenges
Imagine the worry of young parents trying to balance their dreams with the complexities of stock options and taxes. Managing stock options and navigating the Alternative Minimum Tax (AMT) can feel overwhelming, especially when using an ISO AMT example while prioritizing household expenses. Understanding how AMT impacts their financial situation is crucial. For instance, an ISO AMT example would be if a parent exercises Incentive Stock Options (ISOs) during a high-income year, which may inadvertently trigger AMT, leading to unexpected tax liabilities. In 2026, the AMT exemption amounts are set at $90,100 for single taxpayers and $140,200 for married couples filing jointly, with phase-outs beginning at $500,000 for singles and $1,000,000 for joint filers. This means many families could quickly lose their AMT exemption as their income rises.
It’s important for families to partner with advisors who can help them align their stock option decisions with their financial dreams. Take Katie and Christopher, for example. This married couple earned $300,000 in 2025 and faced an AMT liability due to their stock options. Their Tentative Minimum Tax (TMT) was calculated at $42,302, while their regular tax bill was $50,134. They owed no AMT but still had to manage their overall tax burden effectively. This scenario highlights the importance of understanding the interplay between regular tax and AMT calculations.
Moreover, employing strategies such as exercising ISOs in smaller amounts or using an ISO AMT example to time exercises can help mitigate tax liabilities by staying below the AMT threshold. By understanding their AMT crossover point, families can make informed decisions about when and how to exercise their options. This way, they can avoid unnecessary tax burdens while still working towards their financial goals. By taking proactive steps, families can navigate these challenges together, ensuring a brighter financial future for their loved ones.
High-Income Years: AMT Implications of ISO Exercises
Imagine feeling overwhelmed by unexpected tax bills just when you thought your financial situation was improving. During high-income years, families like Emily and Mark might find themselves facing the Alternative Minimum Tax (AMT), which serves as an iso amt example due to the bargain element from exercised Incentive Stock Options (ISOs). As families grow, understanding tax implications can feel daunting, especially with changes on the horizon.
It’s important to understand that as your income rises, the financial relief you once counted on may start to slip away. This can create stress and uncertainty for families trying to plan for their future. Together, we can explore ways to manage your options, ensuring you feel confident in your financial decisions.
We’re here for you, ready to help you understand your options and make informed choices. At Bright Advisers, we focus on your family’s unique needs, helping you navigate financial challenges with care. Together, we can navigate these complexities and find a path that supports your family’s financial well-being.
Immediate Sales Post-Exercise: AMT Consequences Explained
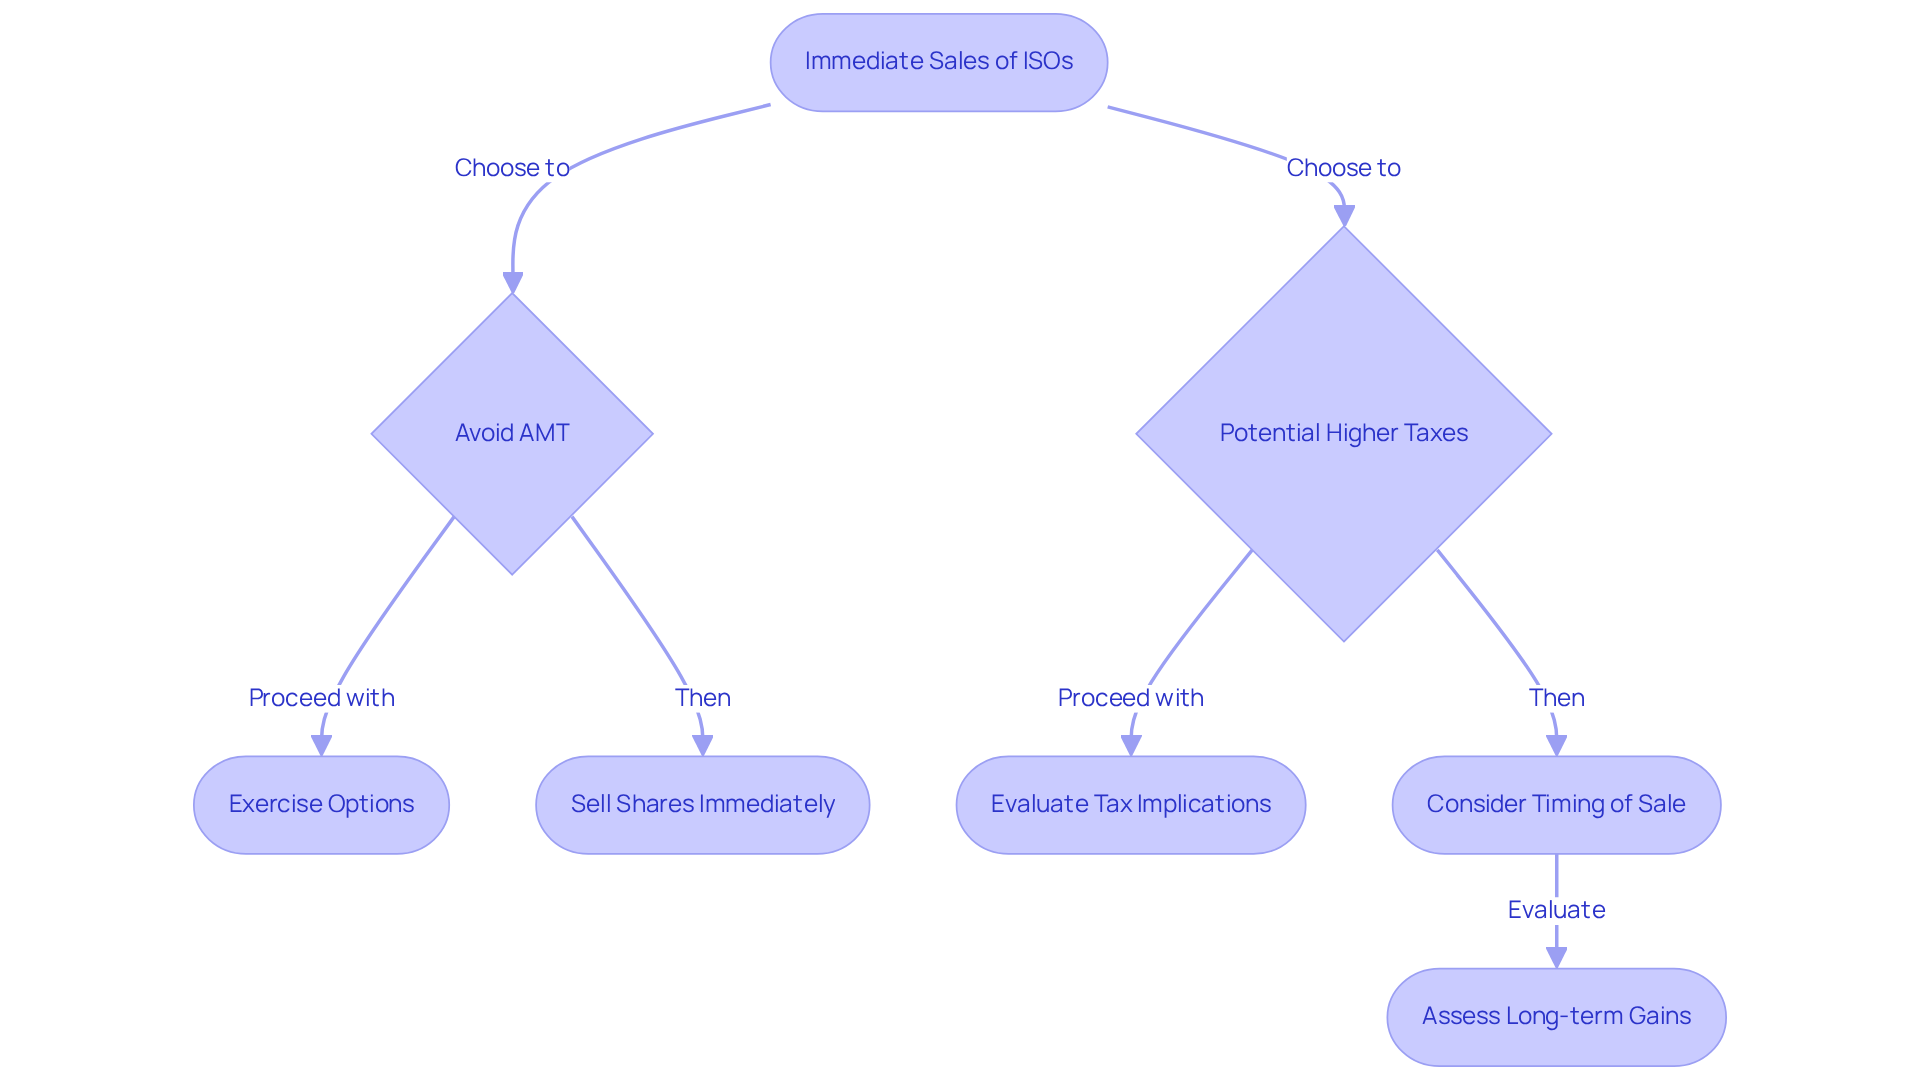
Imagine feeling the weight of financial decisions as you navigate the complexities of stock options and taxes for your family. Families considering immediate sales of shares after exercising Incentive Stock Options (ISOs) can avoid the Alternative Minimum Tax (AMT) by following an iso amt example to create a disqualifying disposition. For instance, if Emily exercises her options and sells her shares right away, the bargain element won’t factor into her AMT calculation. But keep in mind, this could lead to higher taxes on your gains. Families must carefully evaluate the trade-offs between sidestepping AMT and facing potentially elevated taxes from immediate sales. Navigating these tax implications can feel overwhelming for families trying to make the best financial choices.
In 2026, the AMT will become a significant concern for high-income households due to changes in exemption thresholds. Married couples will see their AMT exemption fully phased out at approximately $1.28 million of AMT income, compared to about $1.8 million in 2025. This change highlights why it’s so important to plan carefully when it comes to your stock options and sales.
Case studies illustrate the implications of immediate sales. For an iso amt example, if an employee exercises 1,000 shares of an ISO at a strike price of $10, with a fair market value (FMV) of $30 at exercise, and sells them immediately, they may avoid AMT complications. However, if the shares appreciate significantly, delaying the sale could lead to larger tax liabilities. It’s worth thinking about when to sell your shares, as timing can make a big difference for your family.
Expert insights suggest that households should consider the timing of their sales carefully. Immediate sales can simplify tax calculations but may not always be the most tax-efficient strategy. Balancing the desire to avoid AMT with the possibility of higher ordinary income tax rates necessitates careful consideration of each household’s distinct economic circumstances. Taking the time to understand these options can help ensure your family’s financial future remains secure and bright.
Strategic Planning: Avoiding AMT Pitfalls with ISOs
Imagine the worry of unexpected tax bills looming over your family’s financial plans. Engaging in thoughtful planning around your ISO AMT example exercises can help alleviate that burden.
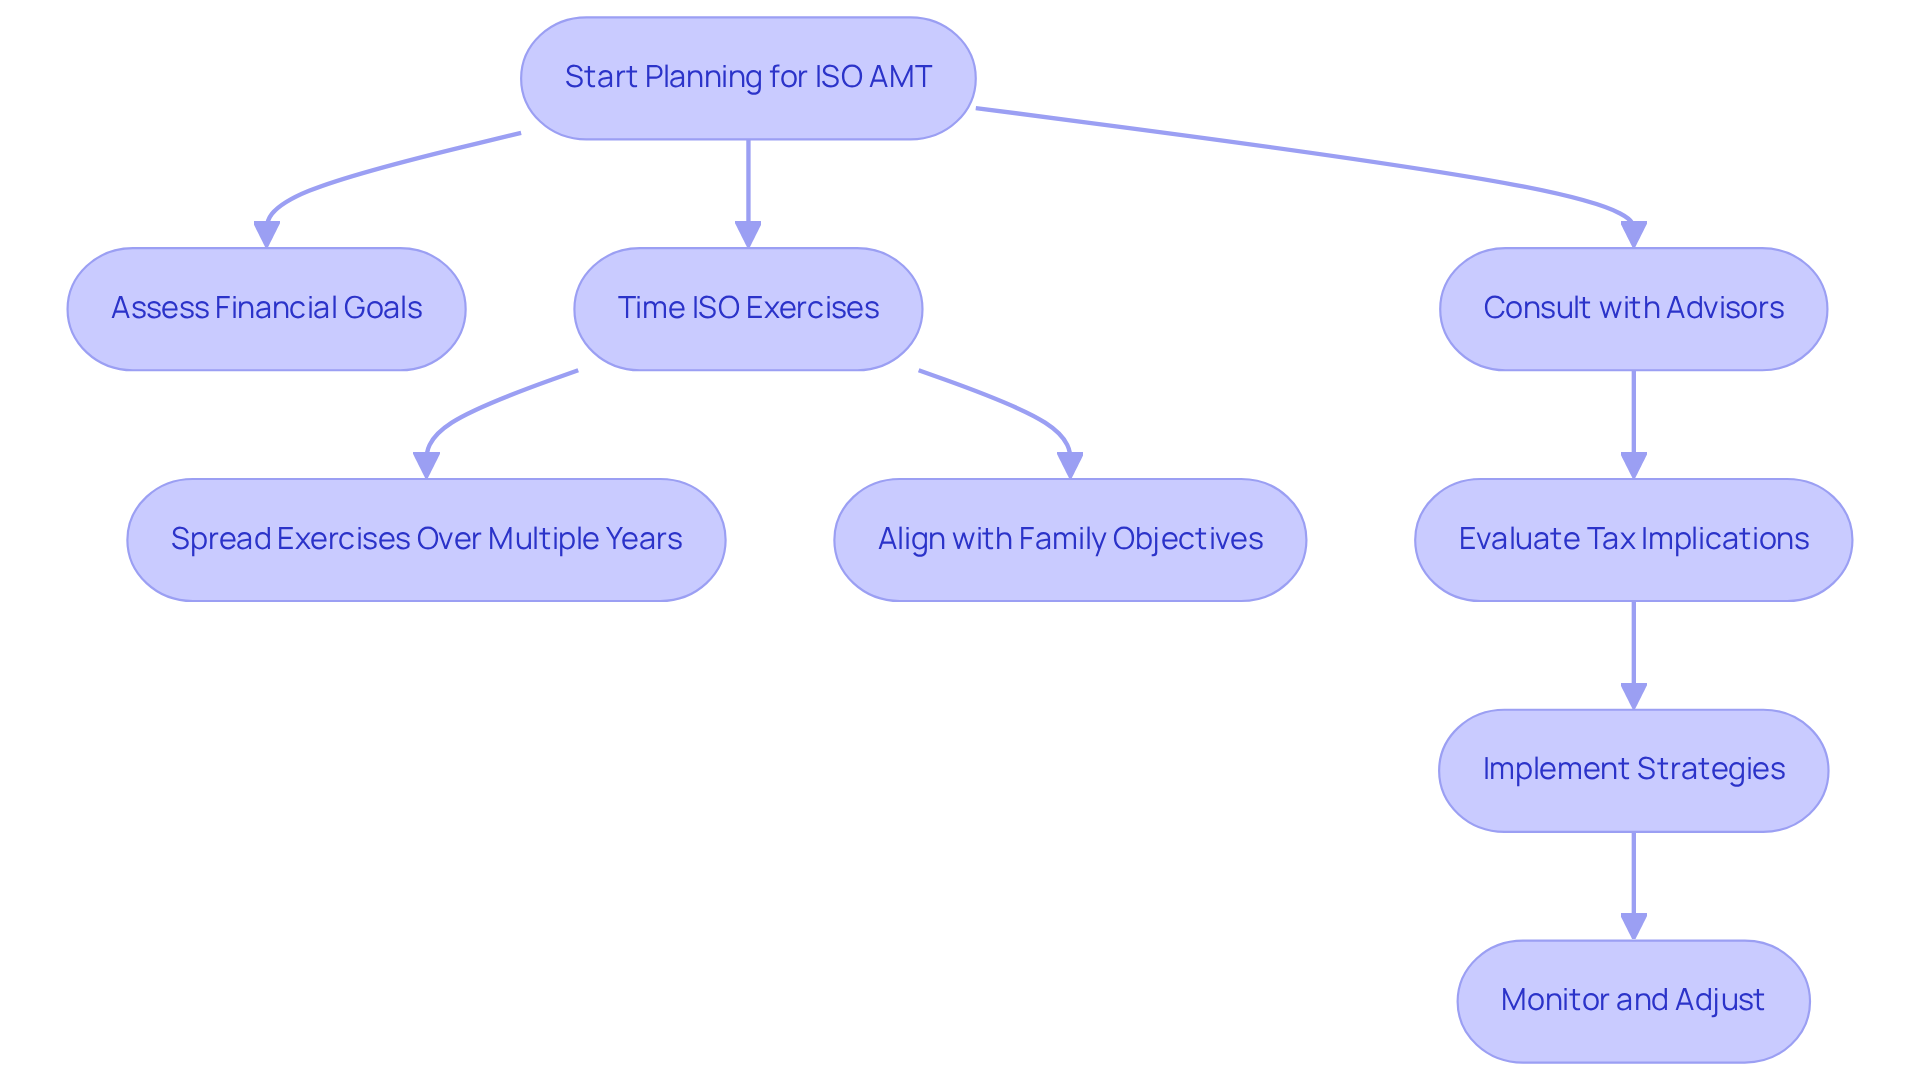
An ISO AMT example is timing your ISO exercises wisely to help keep your family’s taxable income below important thresholds, thereby reducing the stress of AMT. For instance, take Jay and Emma. By timing their ISO exercises to fit their family’s financial goals, they found peace of mind and a more stable future.
Spreading ISO AMT example exercises over multiple years can also effectively help manage tax liabilities. This strategy is especially beneficial for families with young children, as it aligns with their long-term objectives. Emily and Mark, both in tech, used this approach to balance their finances while ensuring their kids’ education was secure.
Consulting with advisors is crucial. They can model different scenarios and provide an ISO AMT example to help families understand the impact of their decisions on AMT exposure. Allison and Brian learned this firsthand when they discovered that working with Bright Advisers improved their tax situation and secured their children’s future.
By taking charge of their stock options and using these thoughtful planning techniques, families can feel more secure in their financial journey. Bright Advisers is here to help you make wise wealth decisions and preserve your family’s legacy. Together, we can navigate these challenges and secure a brighter future for your family.
Conclusion
Imagine facing unexpected tax burdens while trying to secure your family’s future. Understanding the intricacies of exercising Incentive Stock Options (ISOs) and their implications on the Alternative Minimum Tax (AMT) is essential for young families. Families like Emily and Mark have found that by planning ahead, they can avoid surprises and feel secure in their financial choices. Careful planning can prevent unexpected tax burdens, ensuring that families can navigate their financial futures with confidence.
It’s important to understand the potential pitfalls and leverage strategies such as timing exercises and understanding the bargain element. By doing so, families can make informed decisions that align with their financial goals. Key insights emphasize the importance of awareness regarding AMT thresholds, the impact of high-income years, and the benefits of consulting with experts like Bright Advisers.
Real-life examples illustrate how families have successfully managed their tax liabilities through strategic planning. This proactive approach can lead to peace of mind and financial stability. Ultimately, together, we can navigate the complexities of tax planning to ensure your family’s financial future is bright. By taking these steps, you can turn potential tax challenges into stepping stones for your family’s financial success.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options (ISOs) are a type of stock option that allows employees to purchase company stock at a predetermined price, known as the exercise price, which can lead to tax advantages if certain conditions are met.
What is the bargain element in relation to ISOs?
The bargain element is the difference between the fair market value (FMV) of the stock at the time of exercise and the exercise price. For example, if the exercise price is $10 and the FMV is $50, the bargain element is $40 per share.
How does exercising ISOs affect Alternative Minimum Tax (AMT)?
Exercising ISOs can trigger AMT if the bargain element exceeds certain thresholds. The AMT is calculated based on the difference between the exercise price and the market price at the time of exercise, which can complicate tax calculations.
What are the AMT exemption limits for 2026?
In 2026, the AMT exemption for single taxpayers is set at $90,100, while for married couples filing jointly, it will be $140,200.
What happens if I sell ISO stock in the same year it is exercised?
If you sell ISO stock in the same year it is exercised, it results in a disqualifying disposition, which eliminates the need for an AMT adjustment but subjects the spread to ordinary income tax.
How can families manage their AMT exposure when exercising ISOs?
Families can manage AMT exposure by planning the timing of their ISO exercises, such as exercising early in the year when income is lower, staggering exercises over several years, and exercising options when the difference between the strike price and FMV is small.
What are the potential tax implications of not planning for AMT when exercising ISOs?
Without proper planning, families may face unexpected tax bills due to high AMT liabilities, which can complicate their financial situation and lead to stress.
How can professional guidance help families with ISOs and AMT?
Professional guidance can help families understand the complexities of ISOs and AMT, allowing them to develop effective strategies to manage their tax exposure and improve their financial security.
List of Sources
- Case Study: Exercising ISOs and Triggering AMT
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Summary of the Tax Consequences of Incentive Stock Options (ISOs) (https://heltzelkallozfinancial.com/tax-consequences-of-isos.htm)
- How to help avoid AMT when exercising options — Secfi (https://secfi.com/learn/avoiding-amt-taxes-iso-stock-options)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Understanding the Bargain Element in AMT Calculations
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- How Much ISO Bargain Element Triggers AMT? A Tax Planning Guide by Income and Filing Status | TAN Wealth Management | Certified Financial Planner (CFP®) San Francisco | Advisor (https://tanphan.com/blog/iso-amt-bargain-element-tax-guide)
- What You Should Know About the Alternative MInimum Tax (https://zajacgrp.com/insights/what-you-should-know-about-the-alternative-minimum-tax)
- ISO AMT: The 2026 Alternative Minimum Tax Math | Taxstra (https://taxstra.com/iso-amt)
- Timing Strategies: Managing AMT Through ISO Exercises
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- How to help avoid AMT when exercising options — Secfi (https://secfi.com/learn/avoiding-amt-taxes-iso-stock-options)
- Strategies to Reduce AMT on Stock Options – Phoenix Strategy Group (https://phoenixstrategy.group/blog/strategies-reduce-amt-stock-options)
- Bright Advisers: Optimizing AMT Outcomes for Families
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- Planning for the AMT (https://thetaxadviser.com/issues/2025/mar/planning-for-the-amt)
- Understanding the Alternative Minimum Tax | Morgan Stanley at Work (https://morganstanley.com/atwork/employees/learning-center/articles/alternative-minimum-tax)
- How the New 2026 Cost-of-Living Adjustments Could Impact You | Clark Schaefer Hackett (https://cshco.com/insights/how-the-new-2026-cost-of-living-adjustments-could-impact-you)
- Alternative minimum tax optimization methods (https://instead.com/resources/blog/alternative-minimum-tax-optimization-methods)
- Unexpected AMT Liabilities: A Cautionary Tale
- How to help avoid AMT when exercising options — Secfi (https://secfi.com/learn/avoiding-amt-taxes-iso-stock-options)
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- AMT Changes Made in the Tax Cuts and Jobs Act – Eye On Housing (https://eyeonhousing.org/2018/07/amt-changes-made-in-the-tax-cuts-and-jobs-act)
- Leveraging AMT Credits: A Successful Tax Strategy
- Alternative minimum tax optimization methods (https://instead.com/resources/blog/alternative-minimum-tax-optimization-methods)
- AMT Credit Carryforward: How To Use It for Tax Savings (https://brightonjones.com/blog/amt-credit-carryforward)
- What is the AMT credit? — Secfi (https://secfi.com/learn/amt-credit)
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- Young Parents and AMT: Navigating Stock Option Challenges
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- What is the alternative minimum tax (AMT)? — Secfi (https://secfi.com/learn/alternative-minimum-tax)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- High-Income Years: AMT Implications of ISO Exercises
- ISO AMT: The 2026 Alternative Minimum Tax Math | Taxstra (https://taxstra.com/iso-amt)
- Year-end tax moves for high earners (https://firstcitizens.com/wealth/insights/tax-planning/top-year-end-tax-strategies)
- Alternative Minimum Tax (AMT): How It Works for Stock Options in 2026 (https://esofund.com/blog/alternative-minimum-tax-amt)
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- Immediate Sales Post-Exercise: AMT Consequences Explained
- How ISOs Trigger Alternative Minimum Tax in 2026 (https://wealthgenadvisor.com/how-isos-trigger-alternative-minimum-tax-in-2026)
- Disqualifying vs Qualifying: ISOs (https://naspp.com/blog/disqualifying-vs-qualifying-isos)
- The Return of AMT: What High Earners Need to Know in 2026 (https://wealthspire.com/blog/the-return-of-alternative-minimum-tax-amt-what-high-earners-need-to-understand-about-2026)
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Strategic Planning: Avoiding AMT Pitfalls with ISOs
- ISO AMT: The 2026 Alternative Minimum Tax Math | Taxstra (https://taxstra.com/iso-amt)
- 7 ISO Strategies That Can Help Minimize Alternative Minimum Tax (https://mystockoptions.com/articles/incentive-stock-option-strategies-to-help-minimize-the-alternative-minimum-tax)
- ISO Taxes: How AMT and AMT Credits Work + Avoiding AMT on ISO Exercises | Darrow Wealth Management (https://darrowwealthmanagement.com/blog/tax-isos-amt-credits)
- Tax Planning Strategies for Incentive Stock Options (ISOs) (https://cbh.com/insights/articles/tax-planning-strategies-for-incentive-stock-options-isos)
- Strategies to Reduce AMT on Stock Options – Phoenix Strategy Group (https://phoenixstrategy.group/blog/strategies-reduce-amt-stock-options)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading