

Key Highlights:
- Bright Advisers offers personalised financial planning tailored to the needs of young parents, focusing on SEP IRA vs Roth IRA comparisons.
- In 2025, SEP IRA allows contributions up to 25% of compensation, with a limit of $70,000, while Roth IRA limits contributions to $7,000 (or $8,000 for those 50+).
- SEP IRAs provide tax advantages by lowering taxable income, while Roth IRAs offer tax-free withdrawals in retirement for after-tax contributions.
- Withdrawals from a SEP IRA before age 59½ incur a 10% penalty, whereas Roth IRA contributions can be accessed anytime without penalty.
- SEP IRAs have no income limits, making them advantageous for high-income earners, while Roth IRAs have income thresholds for full contributions.
- SEP accounts require minimum distributions (RMDs) starting at age 73, while Roth IRAs have no RMDs during the account holder’s lifetime.
- Both accounts offer various investment options, with SEP IRAs often providing a broader range for self-employed individuals.
- Catch-up contributions for Roth IRAs allow those 50+ to contribute an extra $1,000, while SEP IRAs do not permit such contributions.
- Understanding early withdrawal penalties is crucial; Roth IRAs allow penalty-free access to contributions, unlike SEP IRAs.
- Choosing between SEP IRA and Roth IRA depends on individual financial circumstances and goals, with each offering distinct advantages.
Introduction
Navigating the financial landscape can feel overwhelming for young parents. Balancing family life with the intricacies of retirement planning is no small feat. It’s crucial to understand the key differences between SEP IRAs and Roth IRAs. This knowledge can empower you to make informed decisions that significantly impact your family’s financial future.
Imagine if you could secure your family’s future while also addressing your immediate financial needs. This article explores the unique advantages and considerations of each account type, offering insights that can help you optimize your savings strategies. By understanding these options, you can choose a retirement plan that aligns with your family values and goals.
We’re here for you, guiding you through this journey. Together, we can navigate the complexities of financial planning, ensuring that your family’s needs are met today and in the years to come. How can you choose the right retirement plan that not only secures your future but also supports your family’s current financial situation? Let’s explore this together.
Bright Advisers: Personalized Financial Planning for SEP and Roth IRA Decisions
Are you a young parent feeling overwhelmed by financial planning? Bright Advisers understands the unique challenges you face, especially when it comes to the comparison of SEP IRA vs Roth IRAs. We’re here for you, providing that speaks directly to your family’s needs.
Imagine having a trusted partner who recognizes the complexities of your economic situation. At Bright Advisers, we tailor our guidance to align with your long-term goals, ensuring that you can make informed choices about your savings options. We know that every family is different, and our personalized approach helps you consider both your current financial landscape and your aspirations for the future.
By focusing on the distinct requirements of young parents, we empower you with the knowledge and resources essential for securing your financial future. Our services include:
All designed to enhance your family’s economic well-being.
Together, we can navigate this journey towards financial stability. To take the first step, consider scheduling a meeting with Bright Advisers. Let’s explore customized strategies that address your specific needs and help you achieve peace of mind for your family.
Contribution Limits: SEP IRA vs Roth IRA Explained
In 2025, the comparison of contribution limits in SEP IRA vs Roth IRA reveals a significant difference that can truly benefit [self-employed individuals](https://brightadvisers.com/?p=11513), especially young parents eager to secure their family’s financial future. Imagine being able to contribute up to 25% of your compensation to a SEP IRA, with a limit of $70,000. This presents a wonderful opportunity for savings that can make a real difference.
When examining SEP IRA vs Roth, it is evident that the – just $7,000 for individuals under 50, and $8,000 for those aged 50 and older, which includes a $1,000 catch-up contribution for those eligible. This disparity is particularly advantageous for self-employed parents and small business owners, allowing them to set aside more of their hard-earned money for the future while also preparing for their children’s educational needs.
Financial experts often highlight that utilizing a SEP IRA can be a smart move for self-employed individuals. Not only does it maximize your savings potential, but it also offers tax advantages that can significantly enhance your long-term financial security. Many families have successfully used SEP IRAs to build substantial savings for their later years, often comparing their contributions in SEP IRA vs Roth IRAs.
Additionally, when considering your retirement savings strategy, it’s important to evaluate the differences between SEP IRA vs Roth, as you can combine a SEP IRA with a traditional or Roth IRA for more flexibility. This makes the SEP IRA an appealing option for young parents who want to secure their financial future while navigating the challenges of family life. Remember, together, we can navigate this journey and ensure a brighter tomorrow for your loved ones.

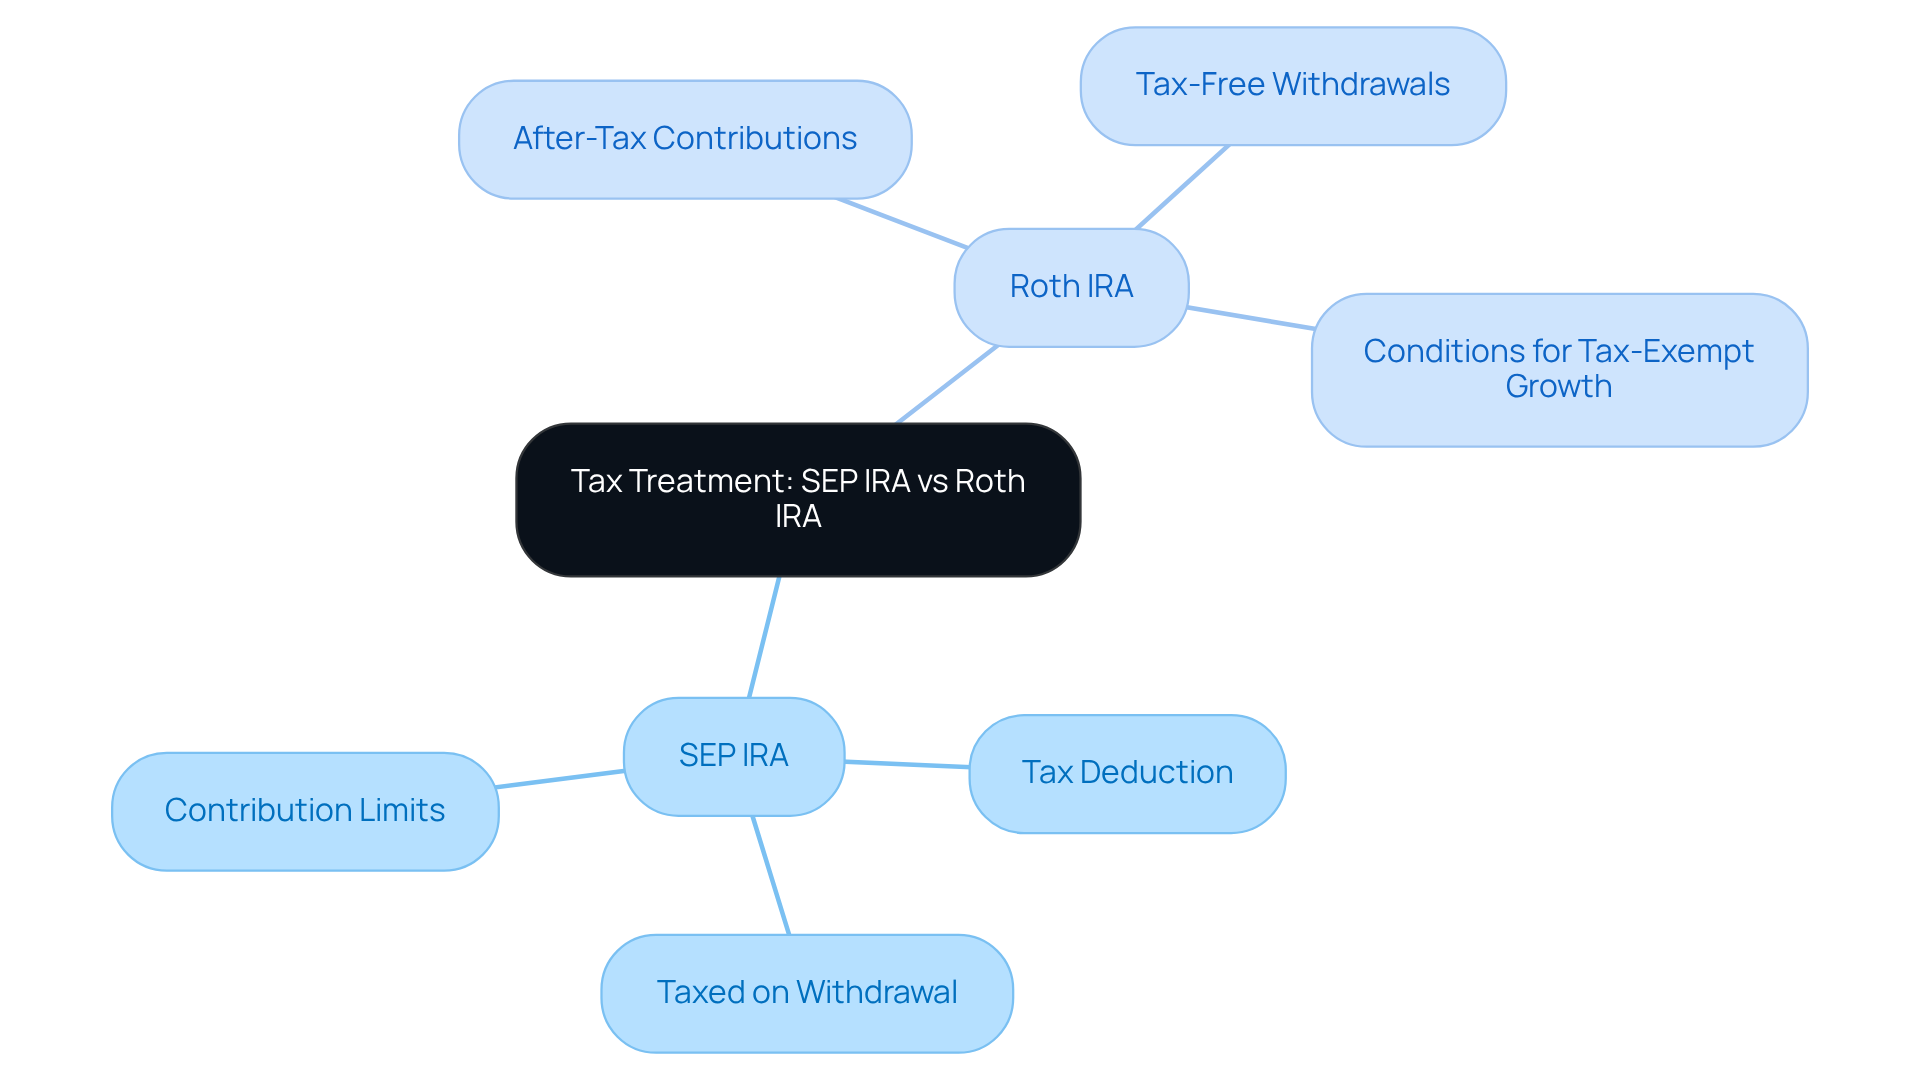
Tax Treatment: Understanding SEP IRA and Roth IRA Tax Benefits
Navigating the world of retirement savings can feel overwhelming, especially for young families like yours. Understanding the tax treatment of SEP IRA vs Roth can open doors to financial opportunities that support your family’s future.
Imagine being able to lower your taxable income this year with contributions to a SEP IRA. It’s a straightforward way to save, but remember, withdrawals in your later years will be taxed as ordinary income. On the other hand, consider the benefits of a Roth IRA. With contributions made from after-tax dollars, you can enjoy , including any earnings, as long as you meet certain conditions. This tax-exempt growth can be a game-changer for families striving for long-term economic stability.
It’s crucial to grasp these differences, particularly regarding SEP IRA vs Roth, especially if you’re like Allison and Brian, who might not fully recognize the financial opportunities that come with thoughtful tax planning. By seeking professional guidance, you can make informed decisions that align with your family’s goals, optimize your financial situation, and minimize tax liabilities.
At Bright Advisers, we’re dedicated to providing tailored wealth management solutions with minimal fund fees. Together, we can navigate this journey toward financial security and freedom through personalized planning and tax optimization. Remember, we’re here for you every step of the way.
Withdrawal Rules: Key Differences Between SEP IRA and Roth IRA
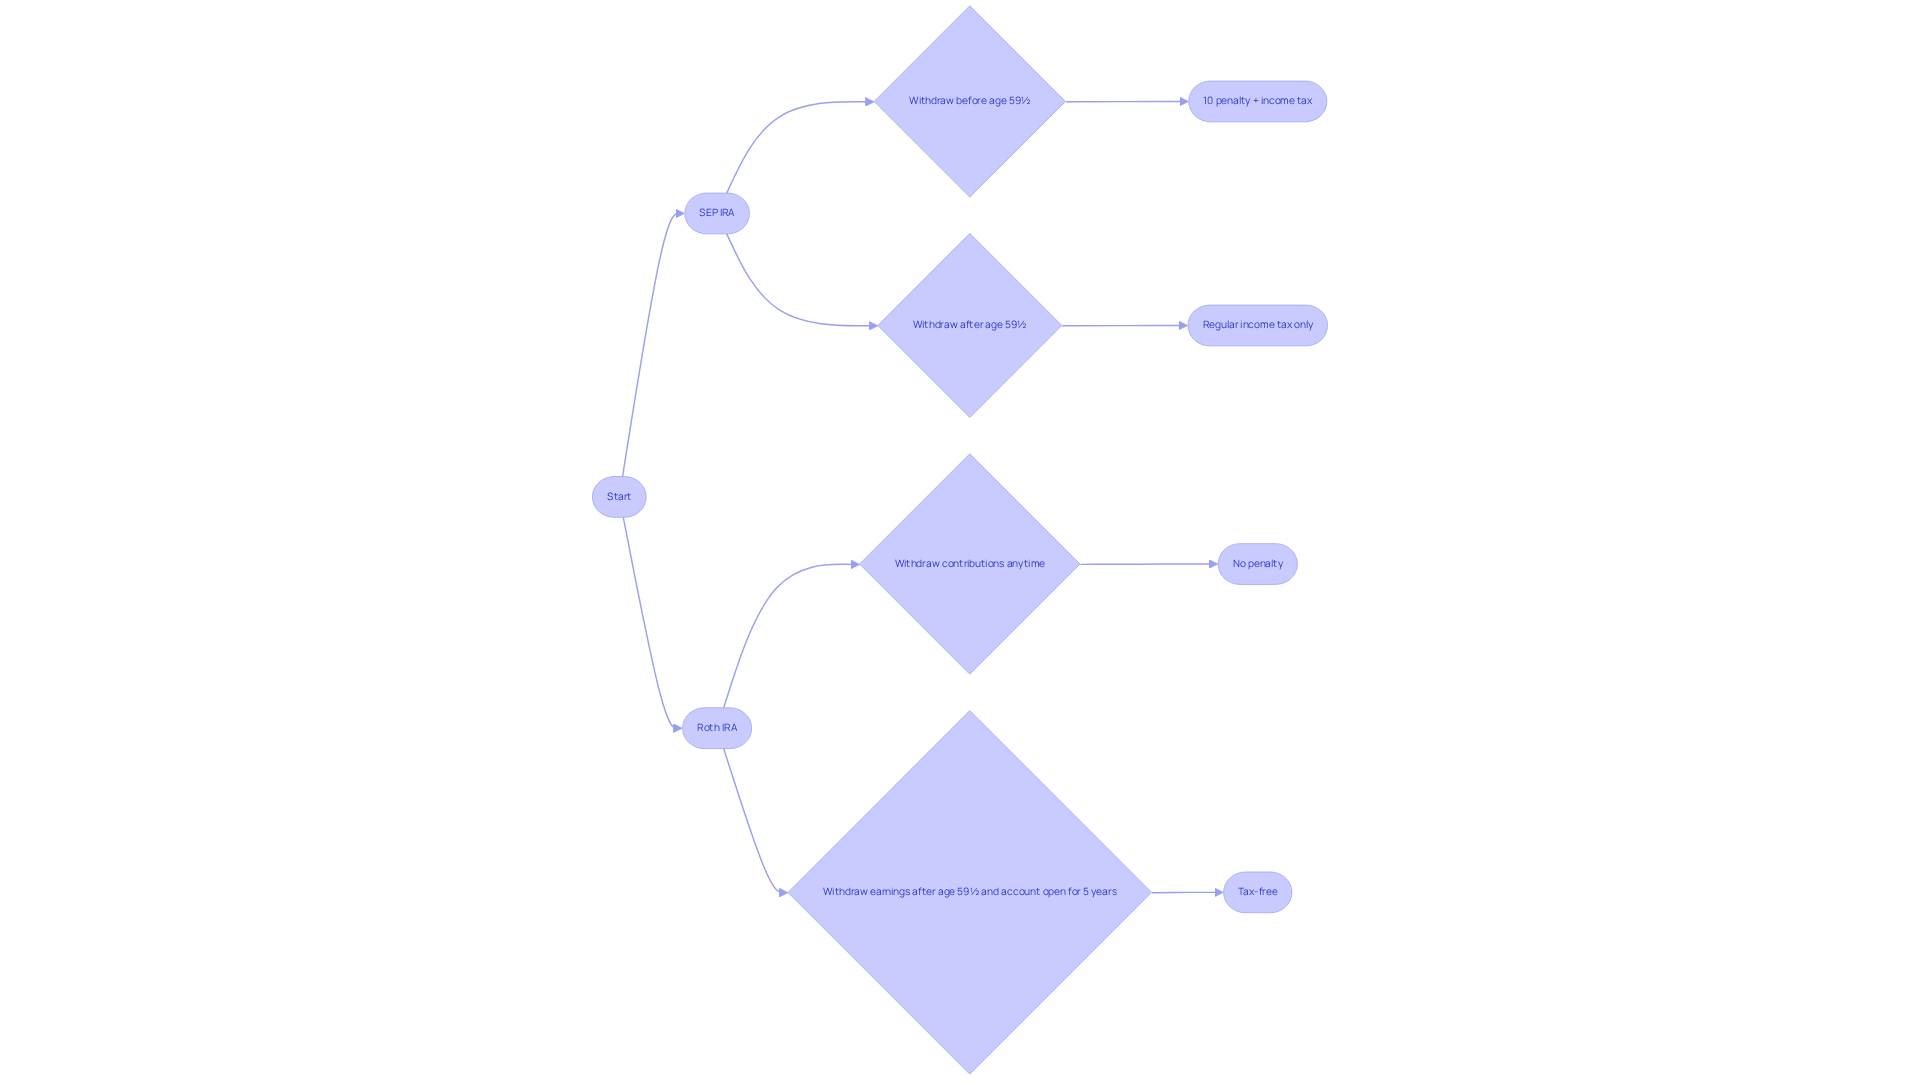
Navigating withdrawal regulations can feel overwhelming for young parents when comparing SEP IRA vs Roth accounts. When comparing SEP IRA vs Roth, it’s important to note that if you withdraw funds from a SEP IRA before age 59½, you typically face a 10% penalty alongside regular income tax. But here’s where it gets interesting: when considering SEP IRA vs Roth, it’s important to note that Roth IRA contributions can be accessed anytime without penalty. Plus, if you’re over 59½ and your account has been open for at least five years, you can withdraw earnings tax-free.
This flexibility is a game-changer for families like yours, especially when unexpected expenses arise or when planning for your children’s education. Imagine having the peace of mind that comes with knowing you can access your savings when you need them most. At Bright Advisers, we truly understand the unique financial challenges faced by young households, like Emily and Mark, who are balancing their careers while dreaming of a secure future for their family.
By offering tailored wealth management options and keeping fund fees low, we empower families to make informed decisions about their savings. Together, we can navigate this journey, ensuring you have the to choose your path. Remember, we’re here for you every step of the way.
Income Limits: How They Affect SEP IRA and Roth IRA Contributions
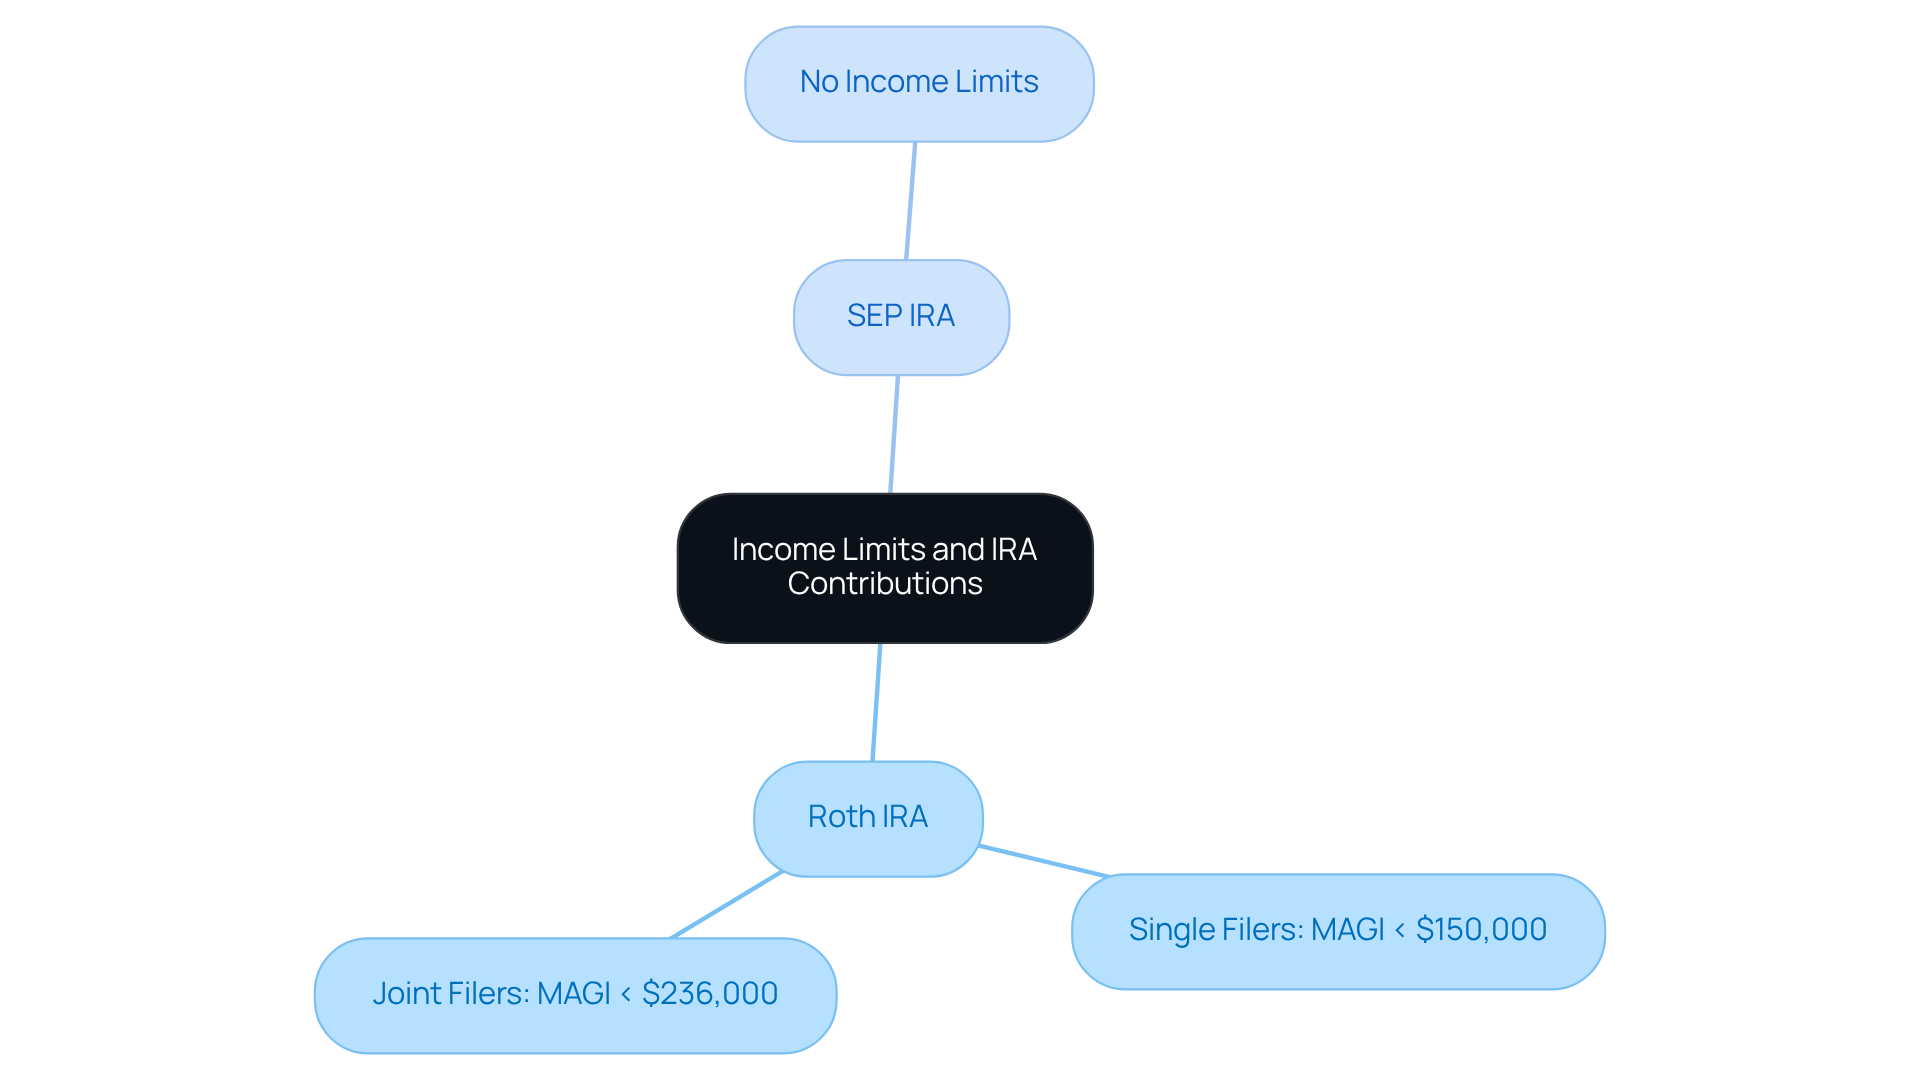
Understanding is crucial for young families looking to secure their financial future. For 2025, single filers need to keep their modified adjusted gross income (MAGI) below $150,000 to make full contributions to a Roth IRA. Joint filers have a slightly higher threshold of $236,000.
But what if you’re a high-income household? That’s where SEP accounts come into play. They offer a more flexible option, with no income limits on contributions. This means families like Allison and Brian can fully tap into their savings potential through SEP IRAs, particularly when comparing the advantages of SEP IRA vs Roth.
Many families may feel the weight of these income limits, which is why it’s so important to understand the differences between SEP IRA vs Roth accounts. By doing so, you can make informed decisions that align with your family’s financial goals.
Take a look at Allison and Brian’s journey. They optimized their tax situation and maximized their savings for the future through a thoughtful financial plan with Bright Advisers. Their story is a testament to how understanding these options can lead to a brighter financial outlook.
Remember, we’re here for you. Together, we can navigate this journey and ensure your family’s financial well-being.
Required Minimum Distributions: SEP IRA vs Roth IRA
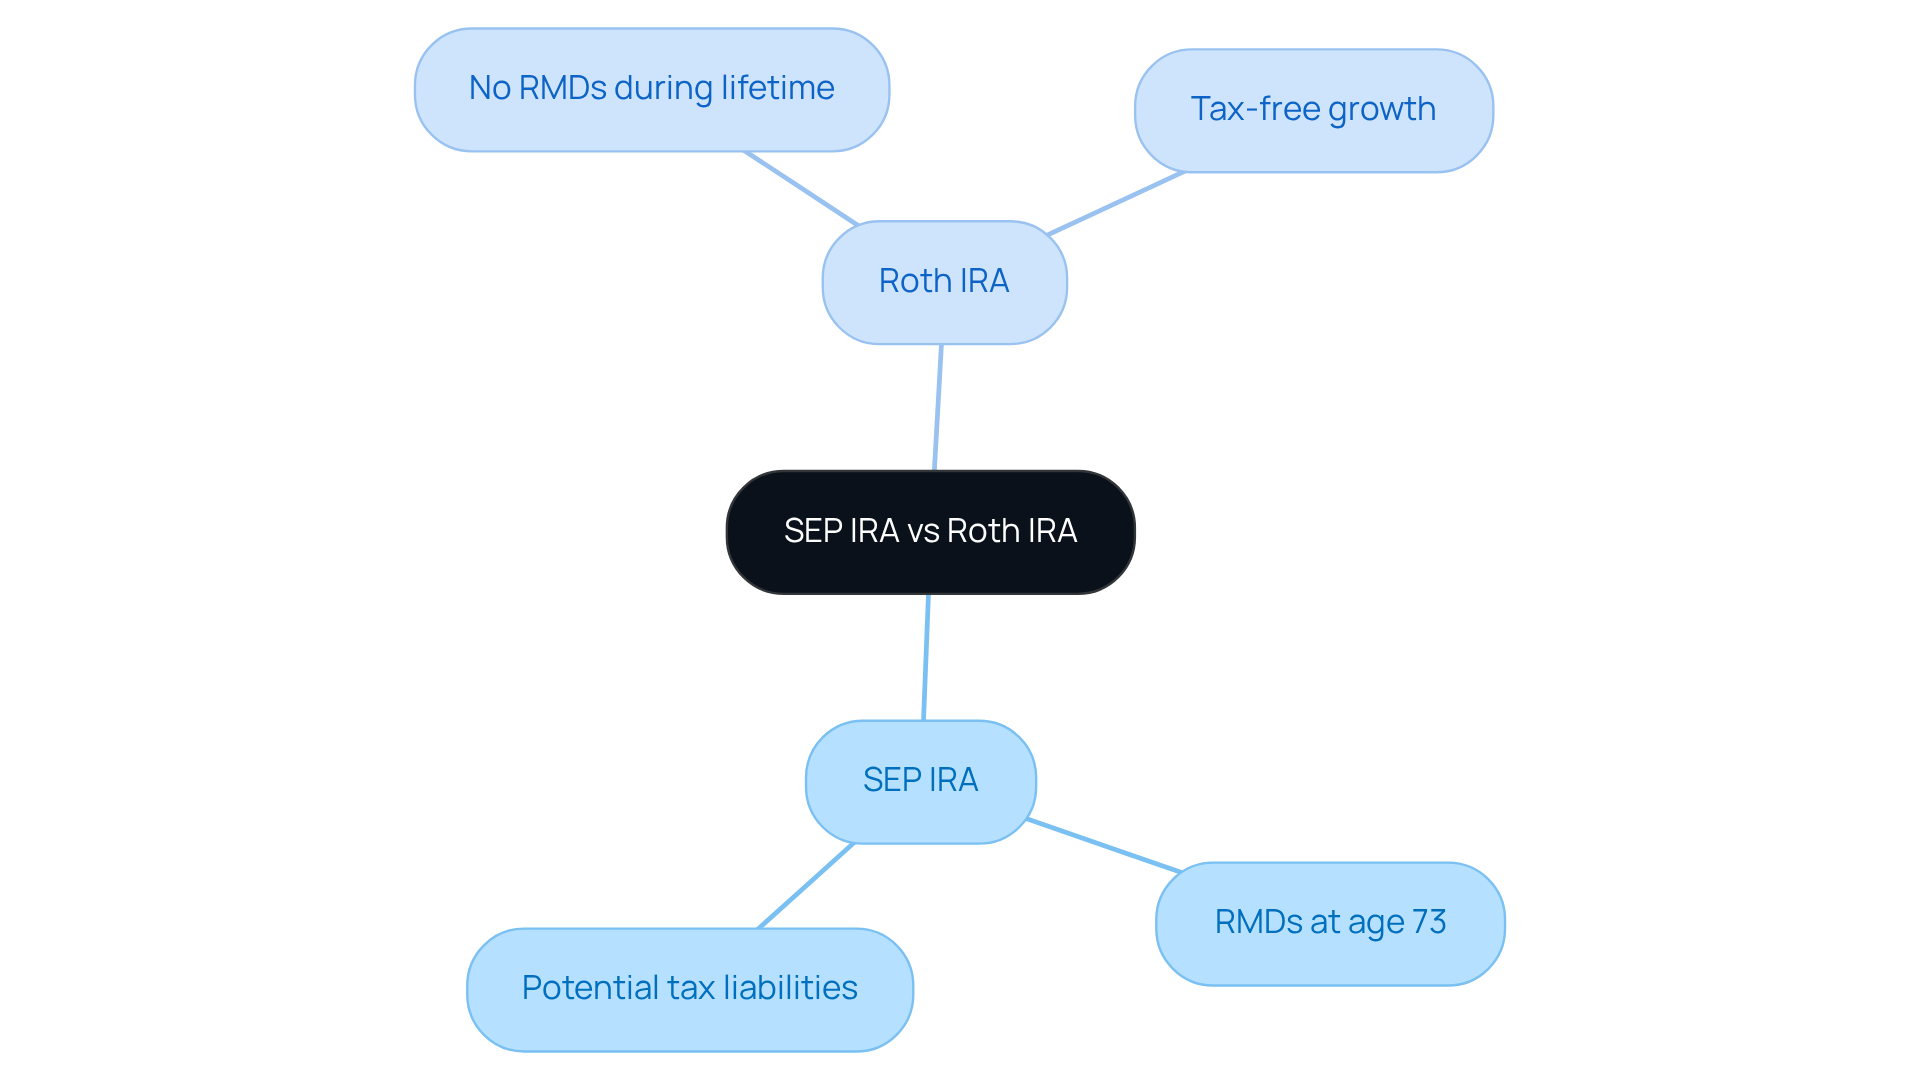
When it comes to planning for your family’s future, understanding the differences between SEP IRA vs Roth accounts is crucial. One significant distinction is the requirement for minimum distributions (RMDs). For SEP accounts, you’ll need to start taking RMDs at age 73. This can complicate your income planning and might lead to unexpected tax liabilities, reducing the funds available for your retirement spending.
Now, imagine if you could avoid that stress. With Roth individual retirement accounts, there are . This means your funds can grow tax-free for as long as you need, giving you the flexibility to manage your investments without the pressure of required withdrawals.
This flexibility is especially beneficial for young parents like you, who are striving to create a lasting legacy for your children. You can maintain control over your investments, allowing you to focus on what truly matters – your family’s future. Experts agree that when considering SEP IRA vs Roth, the absence of RMDs in Roth accounts can significantly enhance your planning strategies for later life.
By choosing a Roth IRA, you can align your retirement savings with your aspirations for future generations. Together, we can navigate this journey, ensuring that your financial goals support your family’s values and dreams. Remember, we’re here for you every step of the way.
Investment Options: Comparing SEP IRA and Roth IRA Choices
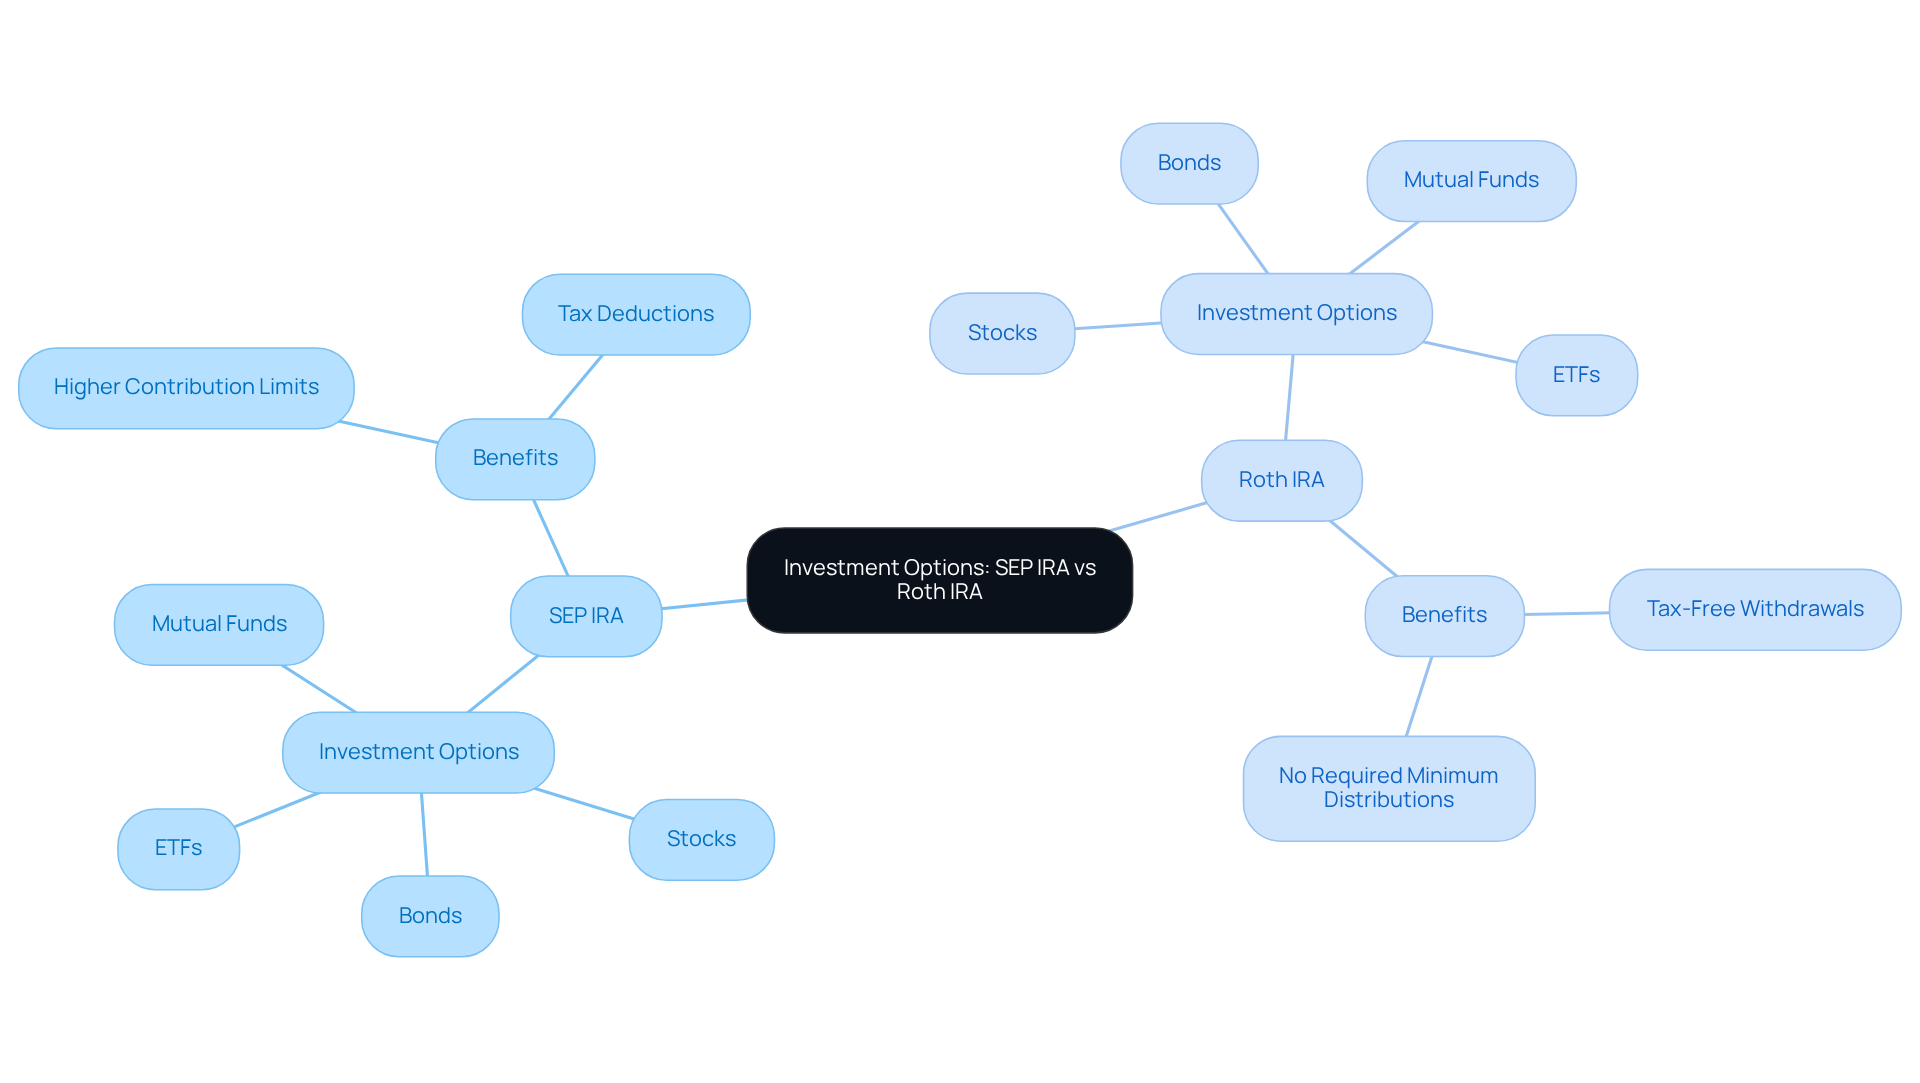
When discussing in the context of planning for your family’s future, both account types offer a variety of investment options that can help you feel secure. Imagine having access to stocks, bonds, mutual funds, and ETFs – all tailored to fit your family’s unique needs. SEP IRAs, in particular, often provide a broader range of investment vehicles, which can be especially helpful for self-employed individuals or small business owners like you. This flexibility allows you to customize your investment strategy based on your family’s risk tolerance and financial goals, nurturing a strong portfolio for years to come.
Think about it: with a Roth IRA, you can focus on tax-efficient investments that allow for tax-free withdrawals later on. This can be a fantastic choice if you anticipate being in a higher tax bracket down the road. On the flip side, in the debate of SEP IRA vs Roth, SEP IRAs are great for those who want to take advantage of higher contribution limits and immediate tax deductions, giving your savings a significant boost.
Current trends show that many young families are choosing to combine both accounts, especially when considering SEP IRA vs Roth, leveraging the unique benefits of each to create a balanced financial strategy. By thoughtfully selecting your investment options, you can ensure that your family’s portfolio not only grows but also aligns with your long-term financial dreams.
Remember, we’re here for you. Together, we can navigate this journey and help you build a future that reflects your family’s values and aspirations.
Catch-Up Contributions: SEP IRA vs Roth IRA Opportunities
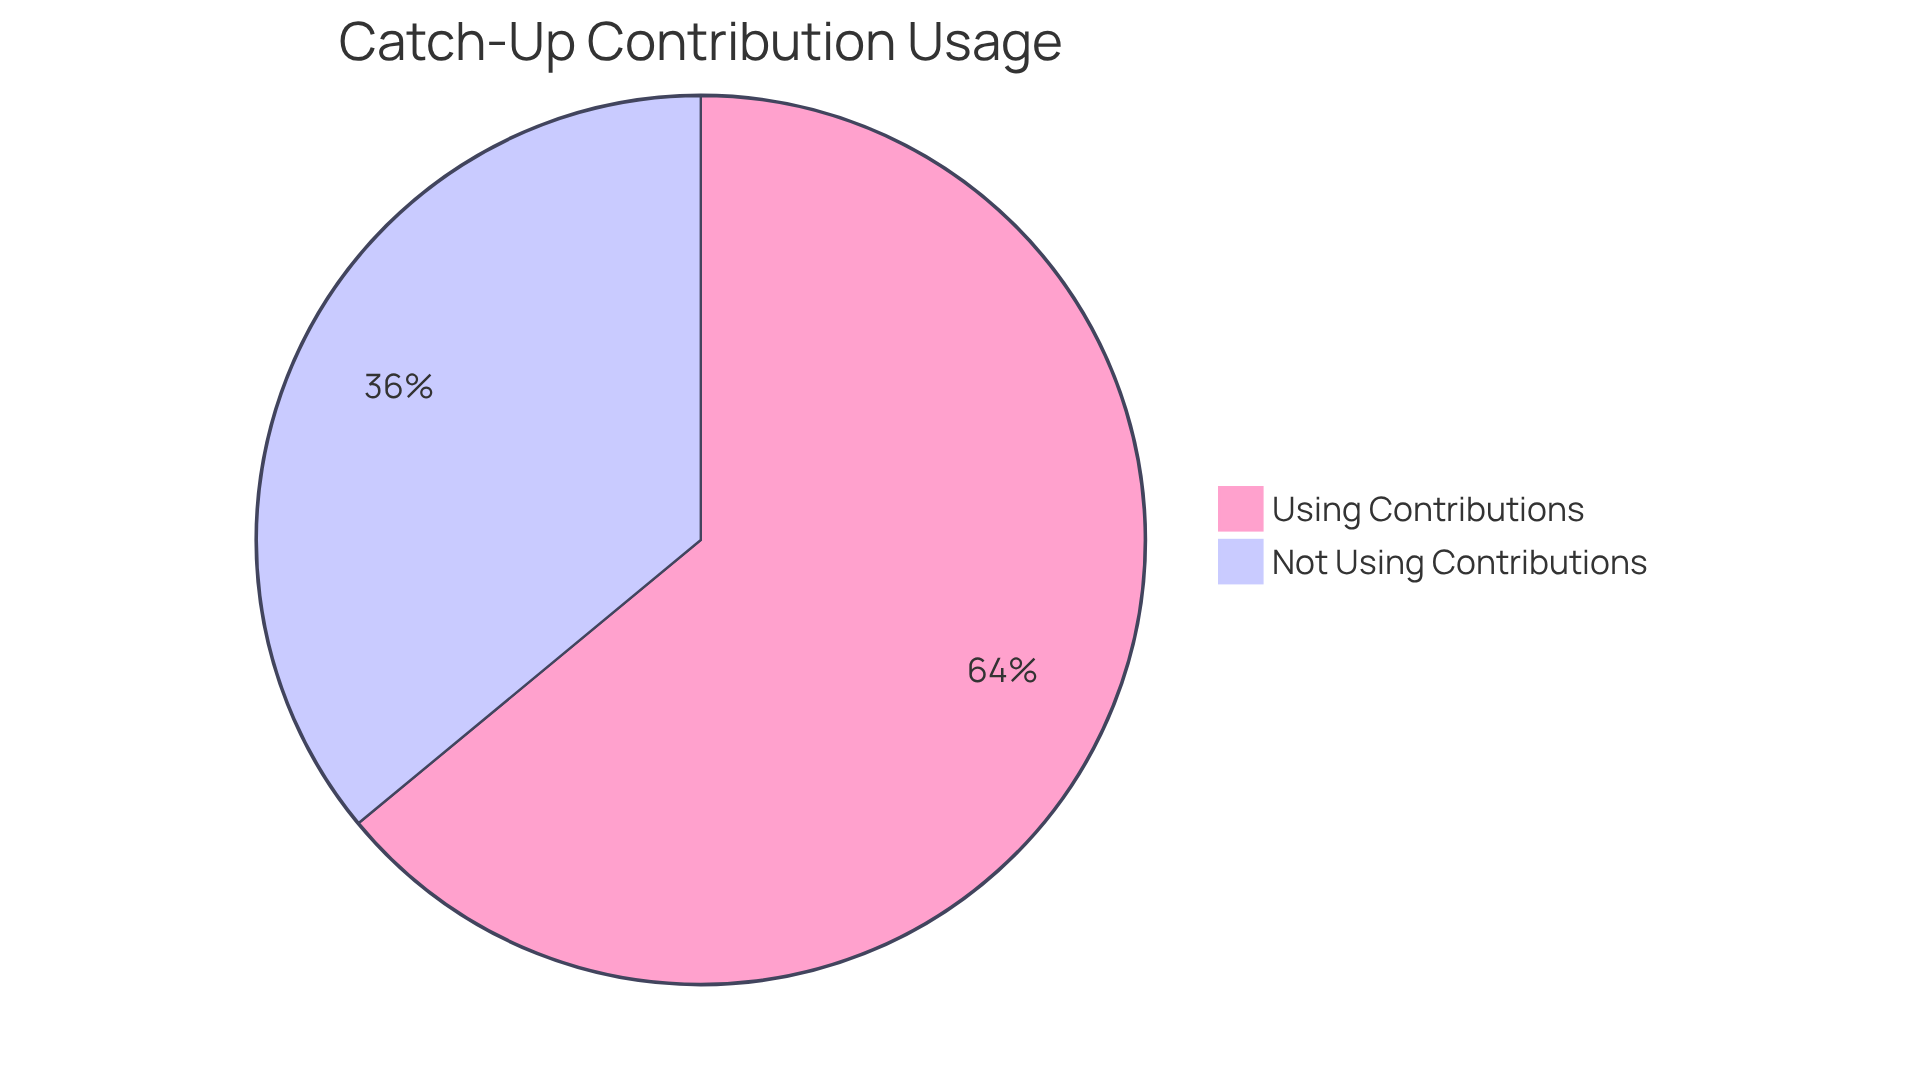
Catch-up contributions present a vital opportunity for individuals aged 50 and older to bolster their savings for the future. In 2025, those contributing to a Roth IRA can add an extra $1,000, raising their total contribution limit to $8,000. This flexibility is particularly beneficial for older parents who may need to accelerate their savings as they approach retirement. When discussing , it’s important to note that SEP IRAs do not permit catch-up contributions, which can significantly hinder older parents’ ability to maximize their savings. This limitation is crucial for families aiming to secure their financial futures, as it may impede their capacity to save adequately for what lies ahead.
Imagine this: around 64% of older parents are taking advantage of catch-up contributions to enhance their savings. Financial advisors emphasize the importance of these contributions, noting that they can make a substantial difference in achieving financial goals. One advisor shared, “Catch-up contributions are crucial for older parents who need to compensate for lost time in their savings for the future.” These contributions provide a meaningful chance to strengthen economic stability as one’s career comes to a close. Families who actively engage in catch-up contributions often find themselves in a more secure financial position, allowing them to focus on their loved ones without the burden of financial uncertainty.
This distinction between the [SEP IRA vs Roth](https://brightadvisers.com/?p=10093) is essential for households as they plan their financial futures. It highlights the advantages of choosing a retirement account that aligns with their long-term savings strategies. Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized.
Early Withdrawal Penalties: Understanding SEP IRA and Roth IRA Rules
Navigating the world of retirement savings can feel overwhelming, especially for young parents. Understanding the rules about early withdrawals in the context of SEP IRA vs Roth is crucial for your family’s financial health.
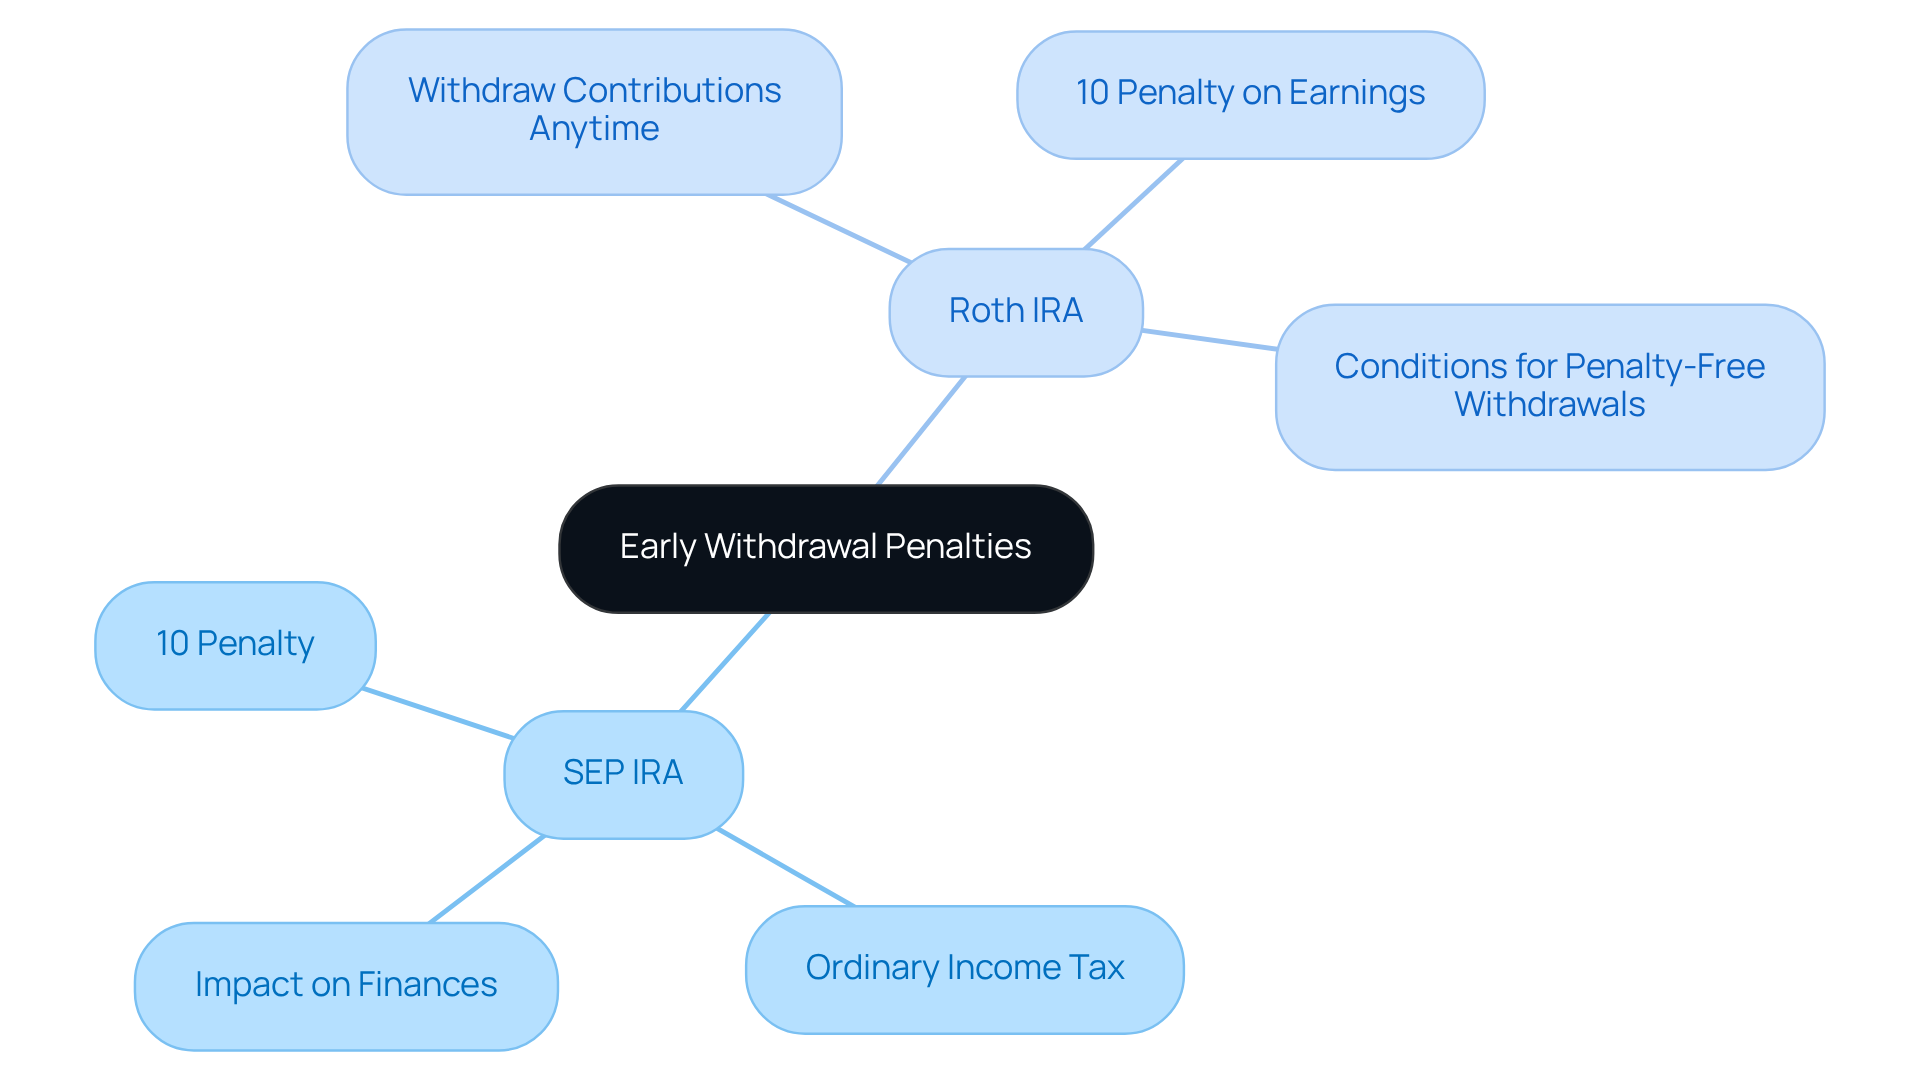
Imagine this: if a young household needs to withdraw $20,000 from a SEP IRA before age 59½, they face a 10% penalty on top of ordinary income tax. That means a $2,000 penalty plus taxes could significantly impact their finances. It’s a tough situation that many families might find themselves in.
On the other hand, in the discussion of SEP IRA vs Roth, Roth IRAs offer a bit more flexibility. You can without penalties, which can be a lifesaver when unexpected expenses arise. However, if you need to access your earnings before age 59½, a 10% penalty may apply unless you meet certain conditions, like using the funds for a first-time home purchase or qualified education expenses. This flexibility can be especially beneficial for young families facing economic challenges, allowing them to access their contributions without the fear of penalties.
Financial advisors emphasize the importance of understanding these regulations. By knowing the ins and outs, families can make informed decisions about their retirement savings and avoid costly mistakes. Together, we can navigate this journey and ensure your family’s financial stability during emergencies.
By planning withdrawals strategically, you can mitigate penalties and safeguard your family’s future. Remember, we’re here for you, ready to support you in making the best choices for your family.
Overall Comparison: Pros and Cons of SEP IRA vs Roth IRA for Young Parents
As young parents, navigating the world of retirement accounts can feel overwhelming. When considering SEP IRA vs Roth, it’s essential to weigh several important factors that can impact your family’s future.
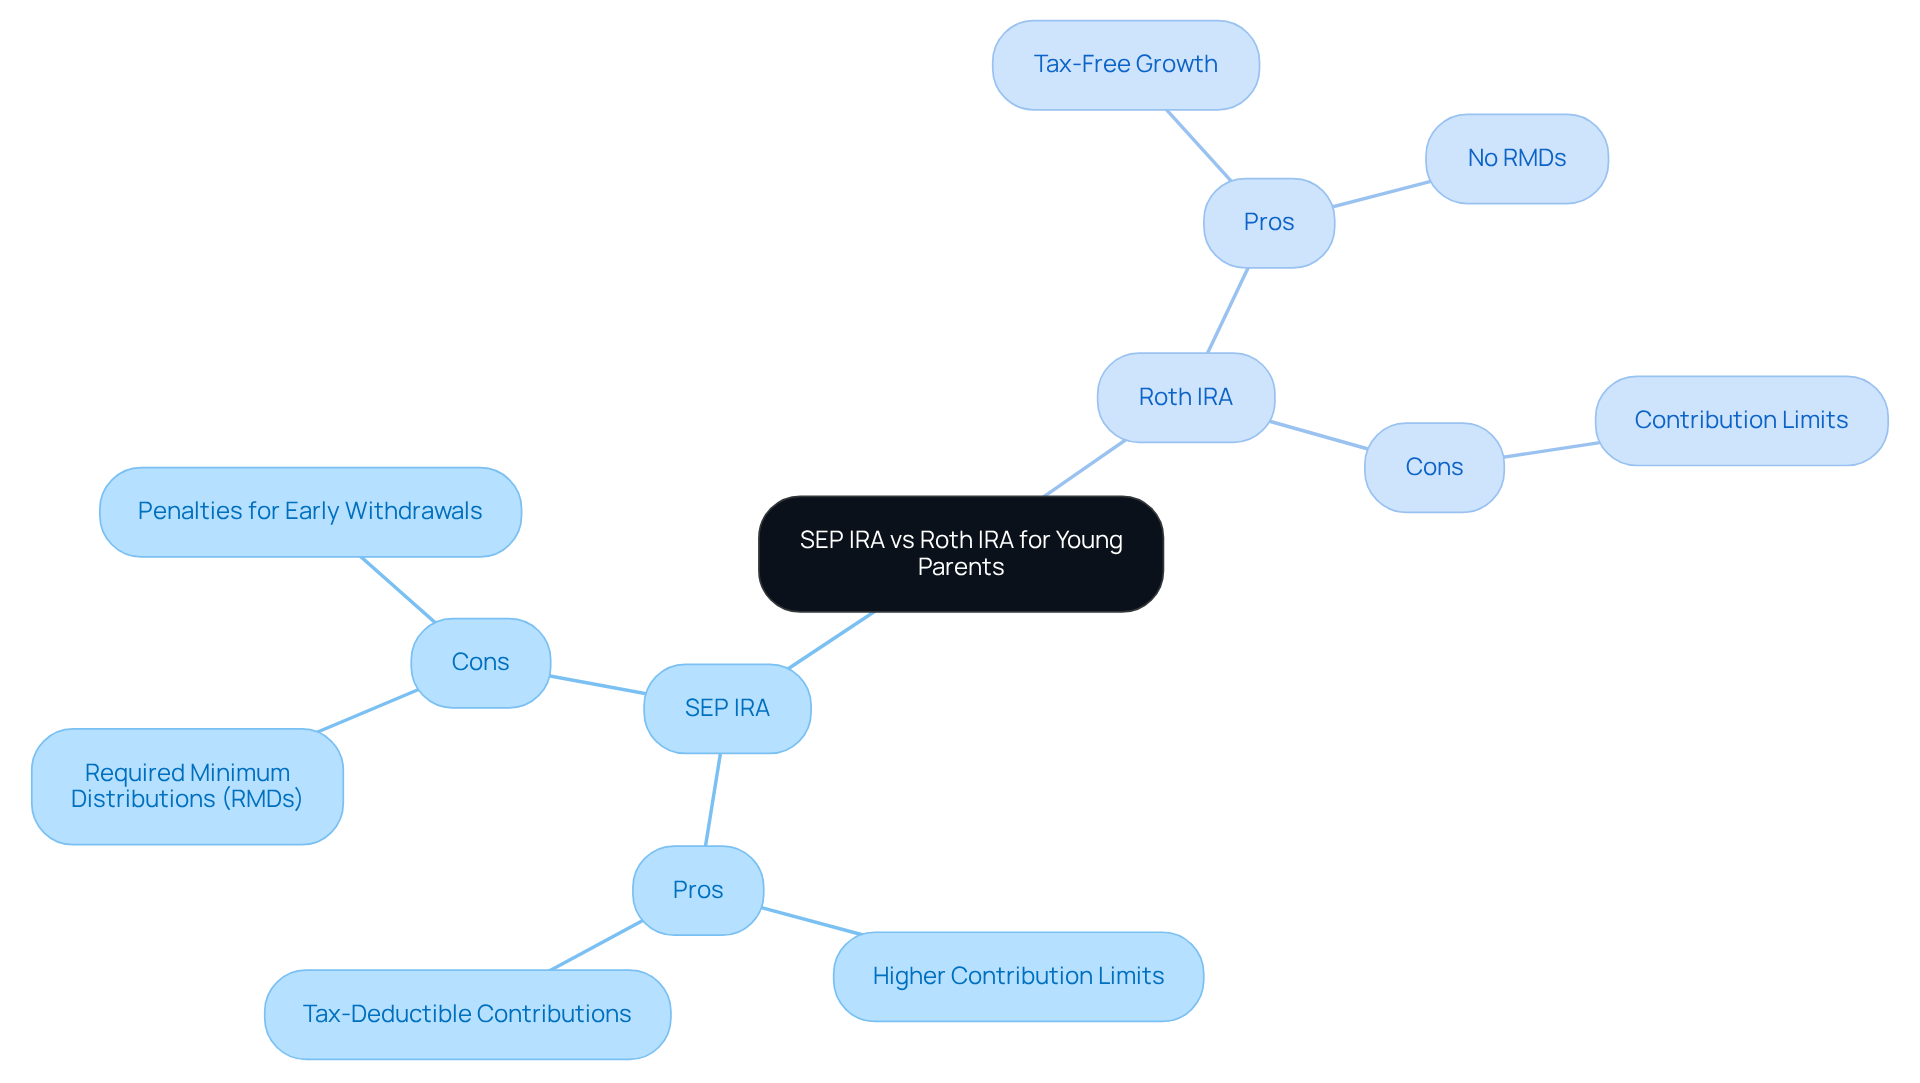
- SEP accounts are particularly advantageous for self-employed individuals or small business owners. They offer higher contribution limits and tax-deductible contributions, which can be a significant boost for your finances. However, it’s important to note that these accounts come with required minimum distributions (RMDs) and penalties for early withdrawals. This can limit your flexibility when you need access to funds.
- On the other hand, Roth IRAs provide a different set of benefits. With , and no RMDs during your lifetime, they offer a more adaptable choice for families. Imagine having the freedom to access your funds without worrying about penalties or mandatory withdrawals. This flexibility can be a game-changer for your family’s financial planning.
Ultimately, the decision regarding SEP IRA vs Roth depends on your personal circumstances, future goals, and the need for accessible funds. Financial experts emphasize the importance of aligning your retirement account choices with your family’s aspirations. After all, these decisions can significantly impact your long-term financial health.
Remember, you’re not alone in this journey. Together, we can navigate these choices and ensure that your family’s financial future is secure.
Conclusion
Navigating the financial landscape as a young parent can feel overwhelming, especially when deciding between a SEP IRA and a Roth IRA. It’s crucial to understand the nuances of these retirement accounts to make informed choices that will positively impact your family’s future. Each option has its own unique advantages and considerations, allowing families to customize their retirement savings strategies to fit their specific needs and goals.
Let’s explore the critical differences between SEP IRAs and Roth IRAs. These include:
- Contribution limits
- Tax treatment
- Withdrawal rules
- Implications of required minimum distributions
SEP IRAs allow for higher contributions and tax deductions, making them a great fit for self-employed individuals. On the other hand, Roth IRAs provide tax-free growth and flexibility when accessing funds. Plus, understanding income limits and catch-up contributions can significantly shape your family’s financial planning.
Ultimately, the choice between a SEP IRA and a Roth IRA should reflect your family’s financial situation, aspirations, and the level of accessibility you need for your savings. Imagine having the peace of mind that comes from knowing you’ve made the right choice for your family’s future. Engaging with financial advisers who specialize in personalized planning can offer valuable insights and help you navigate these options effectively.
By taking the time to explore these retirement accounts, young parents can secure a brighter financial future for themselves and their children. Remember, you’re not alone in this journey; we’re here for you, ready to support you every step of the way.
Frequently Asked Questions
What services does Bright Advisers offer for financial planning?
Bright Advisers offers personalized financial planning services that include cash flow management, debt reduction strategies, and retirement planning, specifically tailored for young parents.
What are the contribution limits for a SEP IRA and a Roth IRA in 2025?
In 2025, individuals can contribute up to 25% of their compensation to a SEP IRA, with a limit of $70,000. In contrast, the contribution limit for a Roth IRA is $7,000 for individuals under 50 and $8,000 for those aged 50 and older, which includes a $1,000 catch-up contribution.
Why might a SEP IRA be advantageous for self-employed individuals?
A SEP IRA allows self-employed individuals to maximize their savings potential by contributing a larger percentage of their income compared to a Roth IRA. It also offers tax advantages that can enhance long-term financial security.
How does the tax treatment differ between a SEP IRA and a Roth IRA?
Contributions to a SEP IRA can lower your taxable income in the year they are made, but withdrawals in retirement are taxed as ordinary income. In contrast, Roth IRA contributions are made with after-tax dollars, allowing for tax-free withdrawals in retirement, including earnings, provided certain conditions are met.
Can you combine a SEP IRA with other retirement accounts?
Yes, individuals can combine a SEP IRA with a traditional or Roth IRA for more flexibility in their retirement savings strategy.
How can Bright Advisers help with tax planning related to SEP and Roth IRAs?
Bright Advisers provides professional guidance to help families understand the tax implications of SEP and Roth IRAs, enabling them to make informed decisions that align with their financial goals and optimize their tax situation.
List of Sources
- Bright Advisers: Personalized Financial Planning for SEP and Roth IRA Decisions
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- The State of Personal Finance in America Q3 2025 (https://ramseysolutions.com/budgeting/state-of-personal-finance?srsltid=AfmBOopVsWz8ABNrWkNfqOT10Md3aRgTtnUEJdU932ejc9ouMVgstOKm)
- 13 Important Personal Finance Stats You Need to Know – Savology (https://savology.com/13-financial-statistics-you-need-to-know)
- 2024 Schwab Modern Wealth Survey Shows Increasing Financial Confidence From Generation to Generation and Younger Americans Investing at an Earlier Age (https://pressroom.aboutschwab.com/press-releases/press-release/2024/2024-Schwab-Modern-Wealth-Survey-Shows-Increasing-Financial-Confidence-From-Generation-to-Generation-and-Younger-Americans-Investing-at-an-Earlier-Age/default.aspx)
- Americans with a financial advisor expect to retire two years earlier according to Northwestern Mutual’s Planning & Progress Study (https://news.northwesternmutual.com/2024-07-09-Americans-with-a-financial-advisor-expect-to-retire-two-years-earlier-according-to-Northwestern-Mutuals-Planning-Progress-Study)
- Contribution Limits: SEP IRA vs Roth IRA Explained
- 2025 IRA Contribution Limits: What You Need To Know (https://cornerstonelicensing.com/resources/2025-ira-contribution-limits)
- What Is a Simplified Employee Pension Plan? SEP Basics – NerdWallet (https://nerdwallet.com/retirement/learn/what-is-a-sep-ira)
- SEP IRA contribution limits for 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Estimated 2025 IRA Contribution Limits – uDirect IRA Services, LLC (https://udirectira.com/estimated-2025-ira-contribution-limits)
- Tax Treatment: Understanding SEP IRA and Roth IRA Tax Benefits
- For Your Reading Entertainment: As Certain As Death, Quotations About Taxes. (https://taxfoundation.org/blog/your-reading-entertainment-certain-death-quotations-about-taxes)
- Who uses individual retirement accounts? (https://taxpolicycenter.org/briefing-book/who-uses-individual-retirement-accounts)
- Taxation Quotes on Money and Responsibility (https://techhelp.ca/taxation-quotes)
- Ownership of Retirement Accounts in 2022: Amounts in Defined Contribution Plans and Individual Retirement Accounts (https://congress.gov/crs-product/R48143)
- These 20 Quotes about Taxes Will Make You Think (https://cabotwealth.com/daily/stock-market/quotes-taxes-make-you-think)
- Income Limits: How They Affect SEP IRA and Roth IRA Contributions
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 10 Powerful Quotes from Financial Gurus on the Importance of Saving for Retirement (https://linkedin.com/pulse/10-powerful-quotes-from-financial-gurus-importance-saving-majmudar)
- 2023 – 2024 Roth IRA Contribution Limits (https://schwab.com/ira/roth-ira/contribution-limits)
- Roth IRA income limits for 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/roth-ira-income-limits)
- Roth IRA income and contribution limits for 2025 | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-ira-income-limits)
- Required Minimum Distributions: SEP IRA vs Roth IRA
- SEP IRA vs. Roth IRA: What You Should Know (https://smartasset.com/retirement/sep-ira-vs-roth-ira-whats-the-difference)
- Demystifying Required Minimum Distributions for Traditional SDIRAs (https://madisontrust.com/required-minimum-distributions)
- 7 Crucial Differences Between a SEP IRA and a Roth IRA Every Self-Employed Person Must Know (https://annuityexpertadvice.com/sep-ira-vs-roth-ira)
- Roth IRA vs. Traditional IRA: Rules & Tax Benefits | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira)
- A Simple Guide to RMDs for Retirees (https://bankerslife.com/insights/personal-finance/a-simple-guide-to-rmds-for-retirees)
- Investment Options: Comparing SEP IRA and Roth IRA Choices
- SEP IRA vs. Roth IRA: What You Should Know (https://smartasset.com/retirement/sep-ira-vs-roth-ira-whats-the-difference)
- 150 Quotes on Saving, Investing, and Financial Wellness (https://deliberatedirections.com/quotes-financial-wellness)
- 57 Important Retirement Plan Statistics For 2025 – Carry (https://carry.com/learn/retirement-plan-statistics)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Catch-Up Contributions: SEP IRA vs Roth IRA Opportunities
- Professor Samantha Prince quoted in the Independent about new 401(k) catch-up contribution law – Penn State Dickinson Law (https://dickinsonlaw.psu.edu/news/professor-samantha-prince-quoted-in-the-independent-about-new-401k-catch-up-contribution-law)
- 2025 401(k) and IRA Contribution Limits (https://modwm.com/2025-401k-and-ira-contribution-limits)
- Roth IRA Savings Account Statistics | Unbiased (https://unbiased.com/discover/retirement/roth-ira-statistics)
- Roth IRA contribution and income limits for 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/roth-ira-contribution-limits)
- 14 Must-Know Retirement Stats For 2025 – Carry (https://carry.com/learn/retirement-stats)
- Early Withdrawal Penalties: Understanding SEP IRA and Roth IRA Rules
- Early Withdrawal Penalties for Traditional and Roth IRAs (https://investopedia.com/ask/answers/082515/how-do-you-calculate-penalties-ira-or-roth-ira-early-withdrawal.asp)
- What Is The Tax Penalty For A SEP IRA? (https://annuityexpertadvice.com/what-is-the-tax-penalty-for-a-sep-ira)
- Here’s How You Can Withdraw From a SEP IRA Without Penalties (https://zacks.com/personal-finance/article/2590680/heres-how-you-can-withdraw-from-a-sep-ira-without-penalties)
- How Do I Know When to Withdraw From a Roth IRA? (https://westernsouthern.com/retirement/when-to-withdraw-from-a-roth-ira)
- Advisors Urge Caution On Penalty-Free IRA, 401(k) Early Withdrawals (https://fa-mag.com/news/how-to-take-early-withdrawals-from-iras-and-401-k-s-without-penalty-76939.html)
- Overall Comparison: Pros and Cons of SEP IRA vs Roth IRA for Young Parents
- The Best Quotes About Retirement (https://retirable.com/advice/lifestyle/best-retirement-quotes)
- SEP IRA vs. Roth IRA: What You Should Know (https://smartasset.com/retirement/sep-ira-vs-roth-ira-whats-the-difference)
- 124 Retirement Quotes: Funny Retirement Quotes, Inspirational Retirement Quotes and More! (https://boldin.com/retirement/retirement-quotes)
- Roth IRAs Holdings Have Shot Up among Young Households – Center for Retirement Research (https://crr.bc.edu/roth-iras-holdings-have-shot-up-among-young-households)
- 5 Mark Cuban Quotes Every Retiree Should Live By (https://kiplinger.com/retirement/happy-retirement/mark-cuban-quotes-every-retiree-should-live-by)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin