

Overview
Did you know that a baby can have a Roth IRA? Yes, it’s true! If they have earned income from part-time jobs or self-employment activities, they can start building their financial future early. Just remember, contributions are limited to their earned income or $7,000 for 2025, whichever is less.
Imagine the possibilities! A child’s Roth IRA requires careful monitoring of their income, but the rewards can be significant. Early contributions can lead to tax-free growth, allowing your little one to benefit from compounding interest over time. This could mean substantial savings as they grow.
It’s important to understand that by taking these steps now, you’re investing in your child’s future. We’re here for you on this journey, helping you navigate the world of financial planning with care and compassion. Together, we can ensure that your family’s financial goals are met, creating a secure foundation for your child’s tomorrow.
Key Highlights:
- Bright Advisers offers tailored wealth planning for setting up Roth IRAs for minors, addressing common questions like whether a baby can have a Roth IRA.
- A child’s Roth IRA requires earned income, which can come from part-time jobs or self-employment activities.
- For 2025, the contribution limit for a Roth IRA is $7,000 or the child’s total earned income, whichever is less.
- Roth IRAs provide tax-free growth on contributions, allowing earnings to be withdrawn tax-free in retirement.
- Compounding interest benefits significantly from early contributions, with modest investments potentially growing substantially over time.
- Contributions to a Roth IRA can be withdrawn at any time without penalties, providing financial flexibility for emergencies.
- Custodial accounts are necessary for managing a child’s Roth IRA until they reach the age of majority, with adults overseeing investment decisions.
- Roth IRAs do not count as assets for financial aid but withdrawals may be considered income, impacting eligibility for college assistance.
- Choosing the right financial institution is crucial; factors to consider include fees, investment options, and customer support.
Introduction
Understanding the potential of a Roth IRA for children opens up a world of financial possibilities for families. Imagine setting your little ones on a path to financial independence, where they can benefit from tax-free growth and the power of compounding interest.
However, it’s important to address a common question: can a baby have a Roth IRA? This article gently delves into the nuances of establishing a Roth IRA for minors, exploring the requirements, benefits, and strategic considerations that can empower families to make informed financial decisions for their children’s futures.
Together, we can navigate this journey toward a brighter financial future.
Bright Advisers: Personalized Financial Planning for Your Child’s Roth IRA
At Bright Advisers, we understand the unique challenges young parents face when it comes to planning for their children’s financial futures. That’s why we excel in tailored wealth planning, making the process of setting up an individual retirement account for minors a nurturing experience, especially when considering the question, can a baby have a Roth IRA?
Imagine if you could provide your child with a head start on their financial journey. By employing advanced technology and a client-focused strategy, our firm offers personalized advice that aligns with your family’s monetary goals. This customized service is essential for navigating the specific details of a minor’s Roth IRA, particularly addressing the question of can a baby have a Roth IRA, including contribution limits and tax implications.
It’s important to understand that by concentrating on these subtleties, Bright Advisers empowers families to secure their children’s financial futures efficiently. Effective strategies, such as establishing automatic contributions, can be life-changing. Moreover, teaching young individuals about the importance of saving and investing early cultivates a solid financial base that can support them throughout their lives.
Together, we can navigate this journey, ensuring that your family’s values and aspirations are at the forefront of your financial planning. We’re here for you, ready to .
Earned Income: The Key Requirement for a Child’s Roth IRA
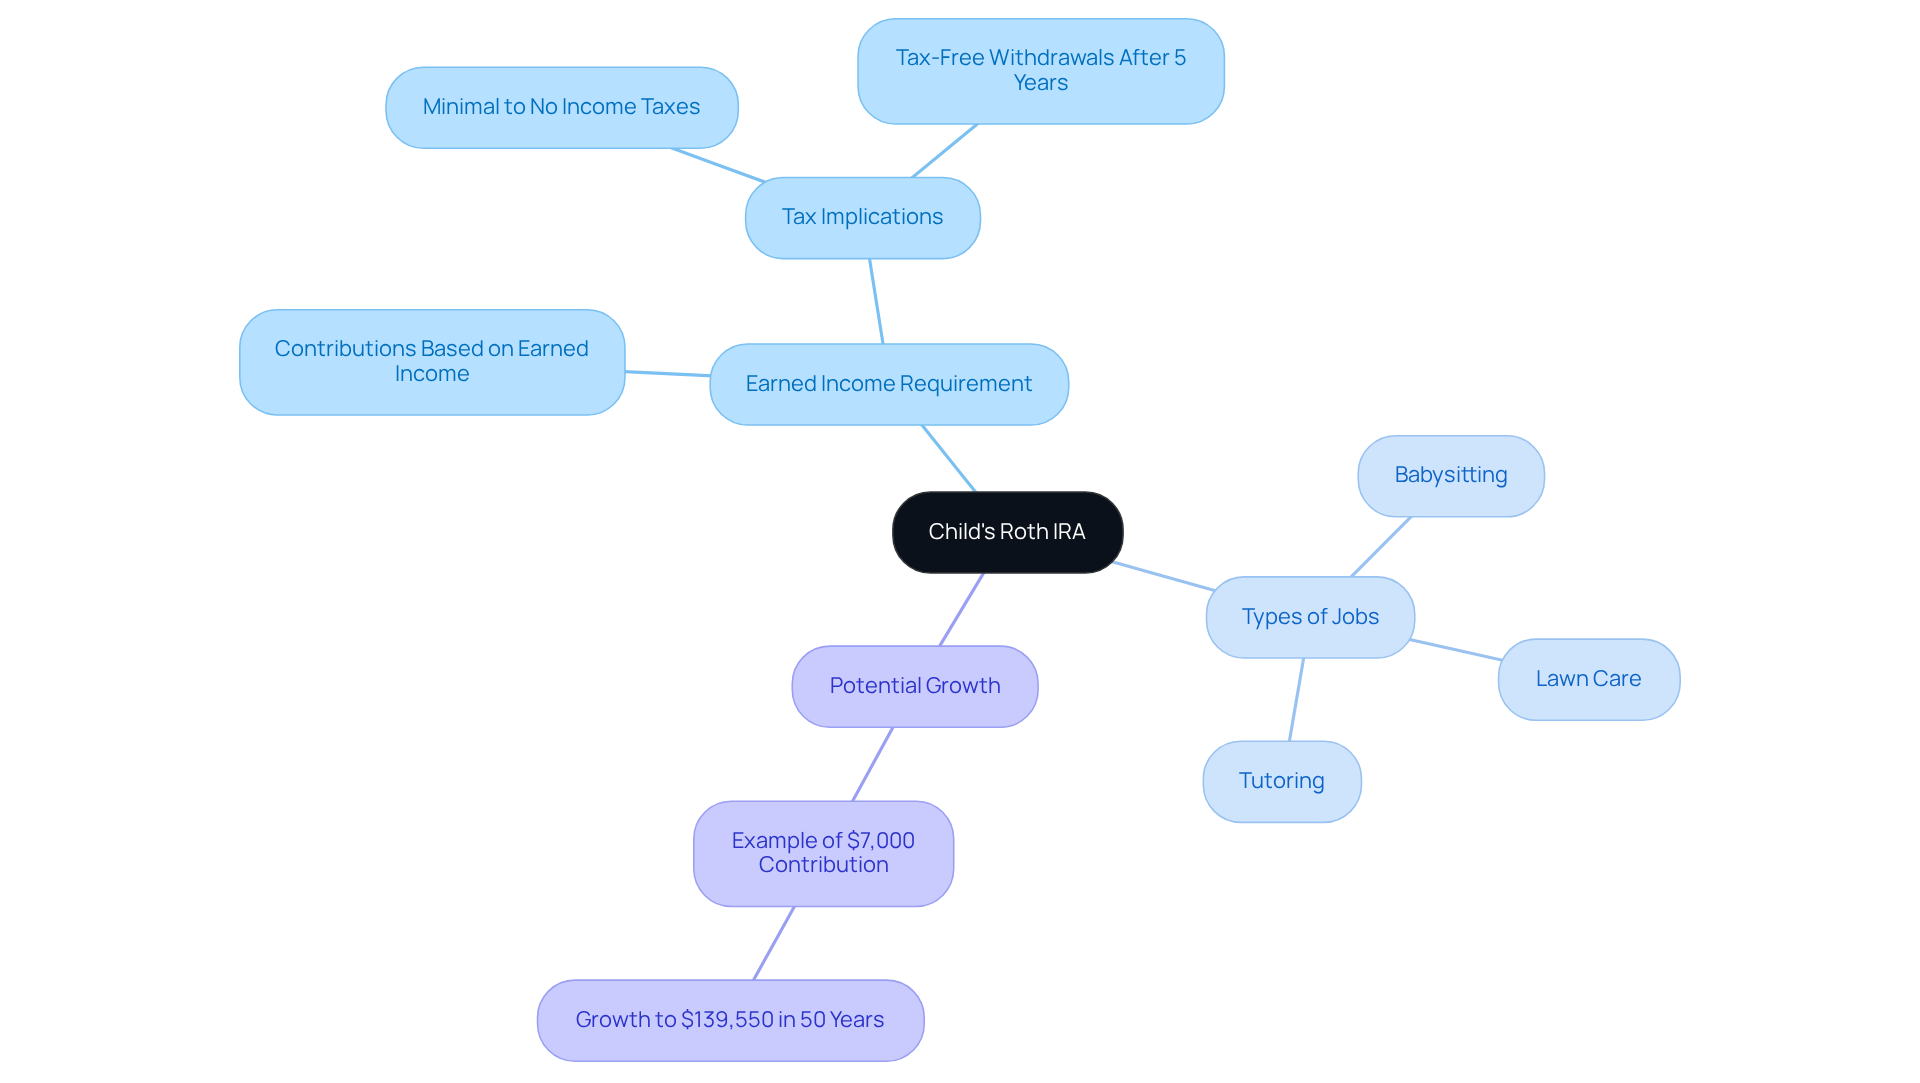
A meaningful step toward your child’s financial future is setting up a Roth IRA, so you might wonder, can a baby have a Roth IRA? To begin, it’s essential that your child has earned income, which raises the question of can a baby have a Roth IRA, as this income can come from various sources like part-time jobs or self-employment activities. This requirement ensures that contributions to the individual retirement account, such as can a baby have a Roth IRA, are based on actual earnings, providing a solid foundation for their savings journey.
Interestingly, most children pay minimal to no income taxes on their earnings, allowing them to make contributions to a traditional IRA without the burden of taxes. As a caring parent, it’s important to monitor your dependent’s income closely to maximize the benefits of this tax-advantaged account. For 2025, the contribution limit for a traditional IRA is $7,000 for individuals under age 50, a key figure for families planning their contributions.
Moreover, you can contribute to your child’s IRA, as long as total contributions do not exceed their earned income, but can a baby have a Roth IRA? Typical part-time positions that can generate earned income include:
- Babysitting
- Lawn care
- Tutoring
These roles not only provide monetary benefits but also teach young individuals valuable lessons about work and saving.
Imagine if a one-time contribution of $7,000 in an individual retirement account could grow to approximately $139,550 in 50 years with a 6% investment return and monthly compounding. By understanding and leveraging these income opportunities, families can effectively prepare for their child’s long-term economic security through an IRA. Together, we can navigate this journey and ensure a brighter financial future for your family.
Tax-Free Growth: Maximizing Your Child’s Roth IRA Benefits
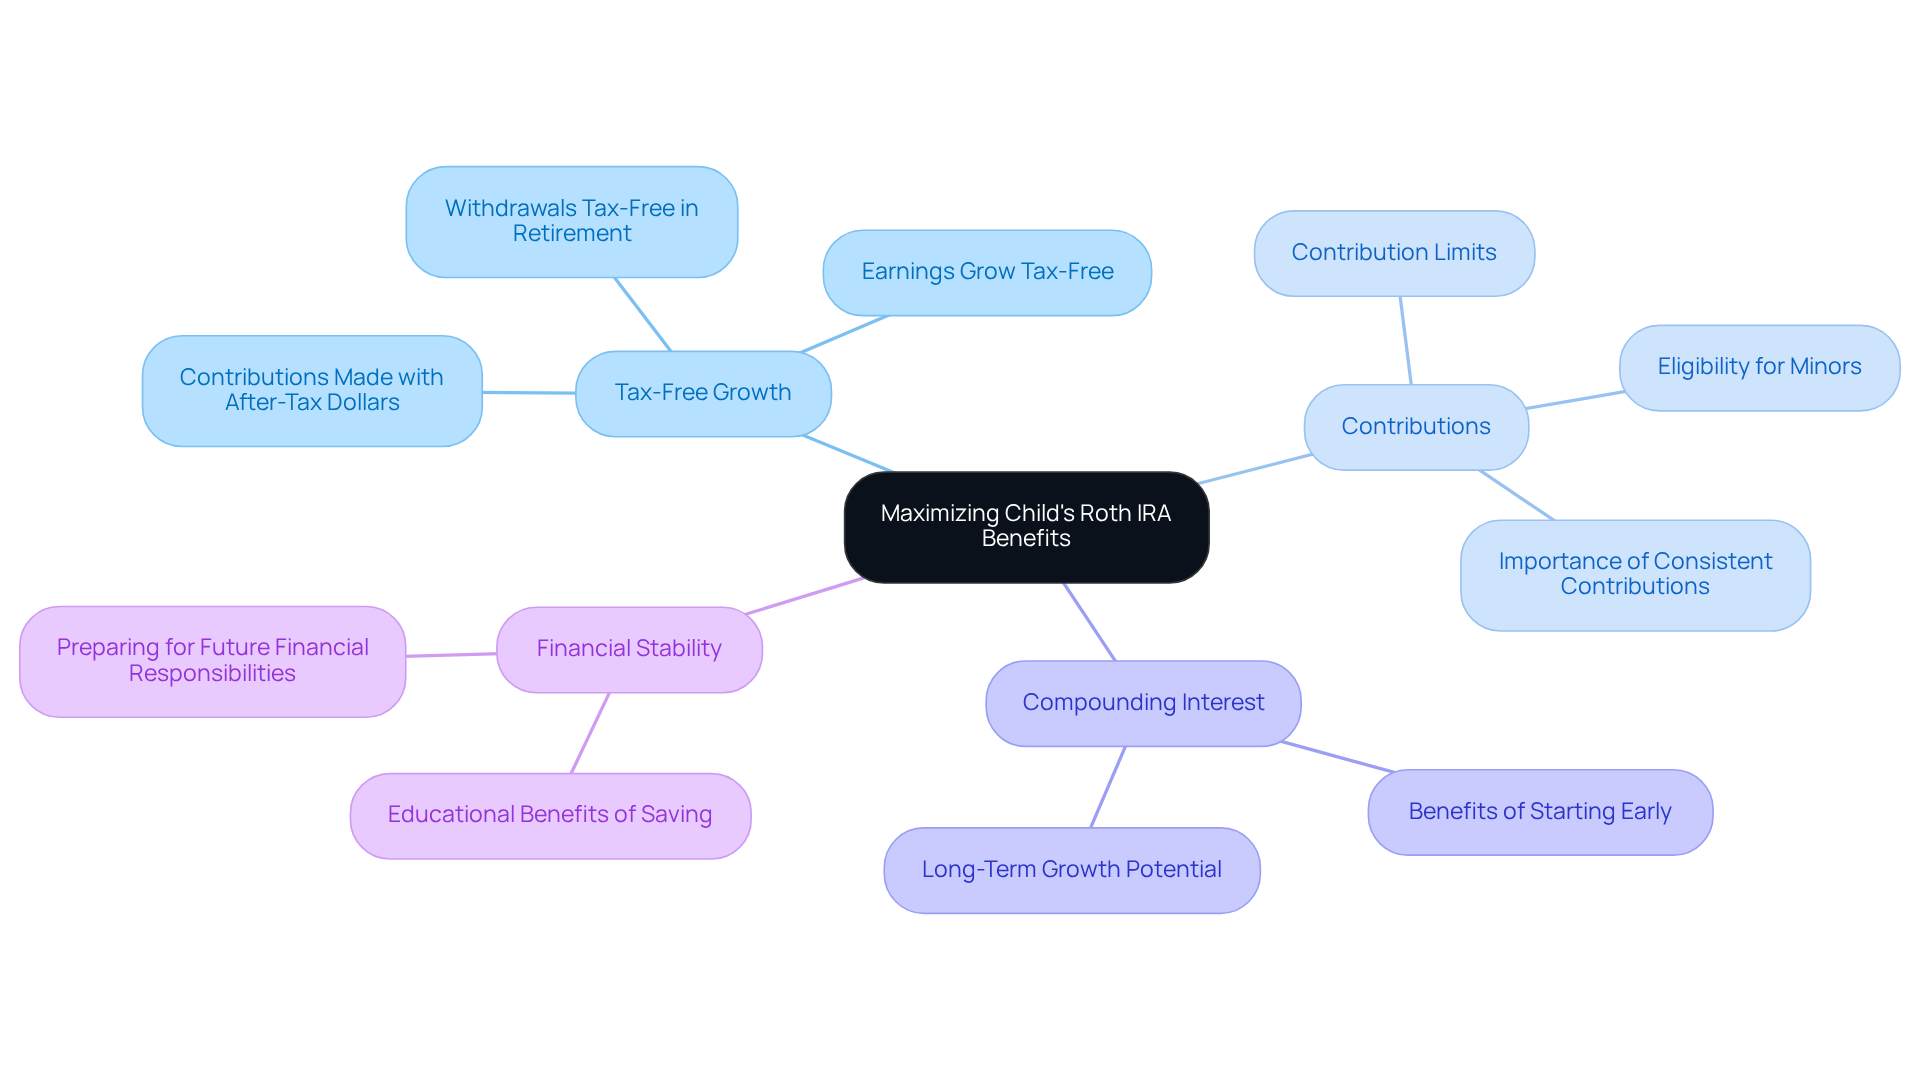
One of the most compelling benefits of a Roth IRA is its potential for tax-free growth. Imagine being able to watch your contributions blossom without the worry of taxes eating away at your hard-earned savings. Contributions are made with after-tax dollars, allowing any earnings generated within the account to be withdrawn tax-free in retirement. For young individuals, this can lead to considerable monetary expansion over time. By beginning early, families can utilize the benefits of compounding interest, resulting in significant savings by the time their children reach adulthood.
It’s important to understand that investment advisors often stress the value of increasing contributions to a minor’s IRA, particularly when discussing whether can a baby have a Roth IRA. This proactive approach can lay the groundwork for a stable economic future. Families who consistently contribute the maximum allowed amount can see their investments grow significantly, benefiting from the tax-free nature of the account. This not only promotes economic understanding but also teaches the significance of saving from an early age, ensuring that youngsters are well-prepared for their monetary responsibilities.
Together, by utilizing the distinct benefits of a retirement account, families can consider whether a baby can have a Roth IRA to establish a strong financial base that supports their children’s long-term objectives. We’re here for you on this journey, helping you navigate the path toward a for your family.
Compounding Interest: The Advantage of Starting Early with a Roth IRA
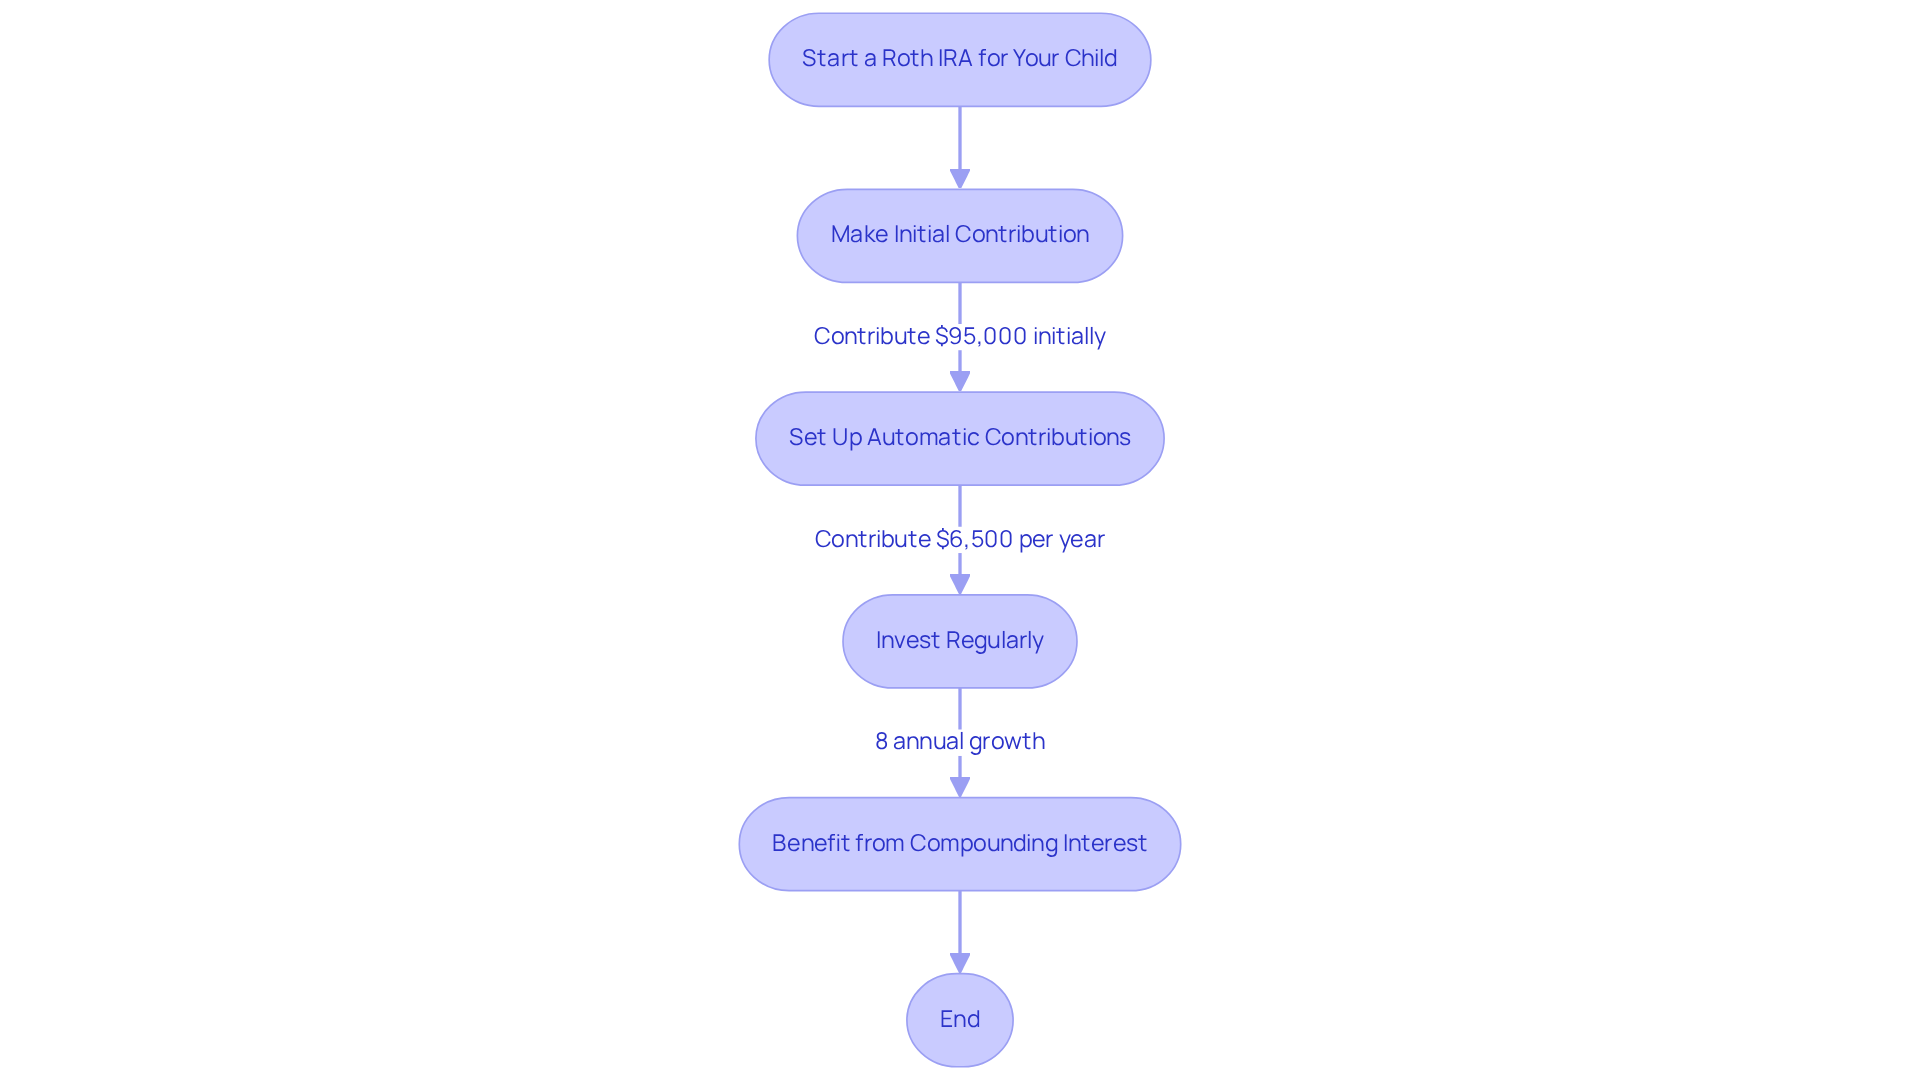
Creating a Roth IRA for your child at a young age raises the question: can a baby have a Roth IRA, and it can truly enhance the benefits of compounding interest. The earlier you start making contributions, the more time your investment has to grow. Compounding allows the interest earned on the account to generate additional earnings, creating a snowball effect that can be quite powerful over time. Even modest contributions can accumulate into significant savings by the time your child reaches retirement age.
Imagine if a single lump-sum contribution of $95,000 could potentially grow to approximately $379,621 over 18 years at an 8% annual growth rate. This illustrates just how impactful early investment can be. Investment experts consistently encourage starting early, emphasizing that the sooner you begin, the greater the potential for wealth accumulation. This approach not only lays a financial foundation for your child but also instills the importance of saving and investing from an early age.
To further enhance your financial planning, consider setting up to the individual retirement account. This ensures a steady investment over time, making it easier for you to manage. It’s also important to note that the contribution limit for individual retirement accounts is $6,500 per year for those under 50. On average, IRA account holders wonder if a baby can have a Roth IRA, as they retire around 59 years old, making those early contributions even more beneficial.
To get started, you can open an IRA through a banking organization or investment platform. Taking this first step can help secure your child’s economic future. Remember, together, we can navigate this journey, and we’re here for you every step of the way.
Emergency Access: Flexibility of Contributions in a Roth IRA
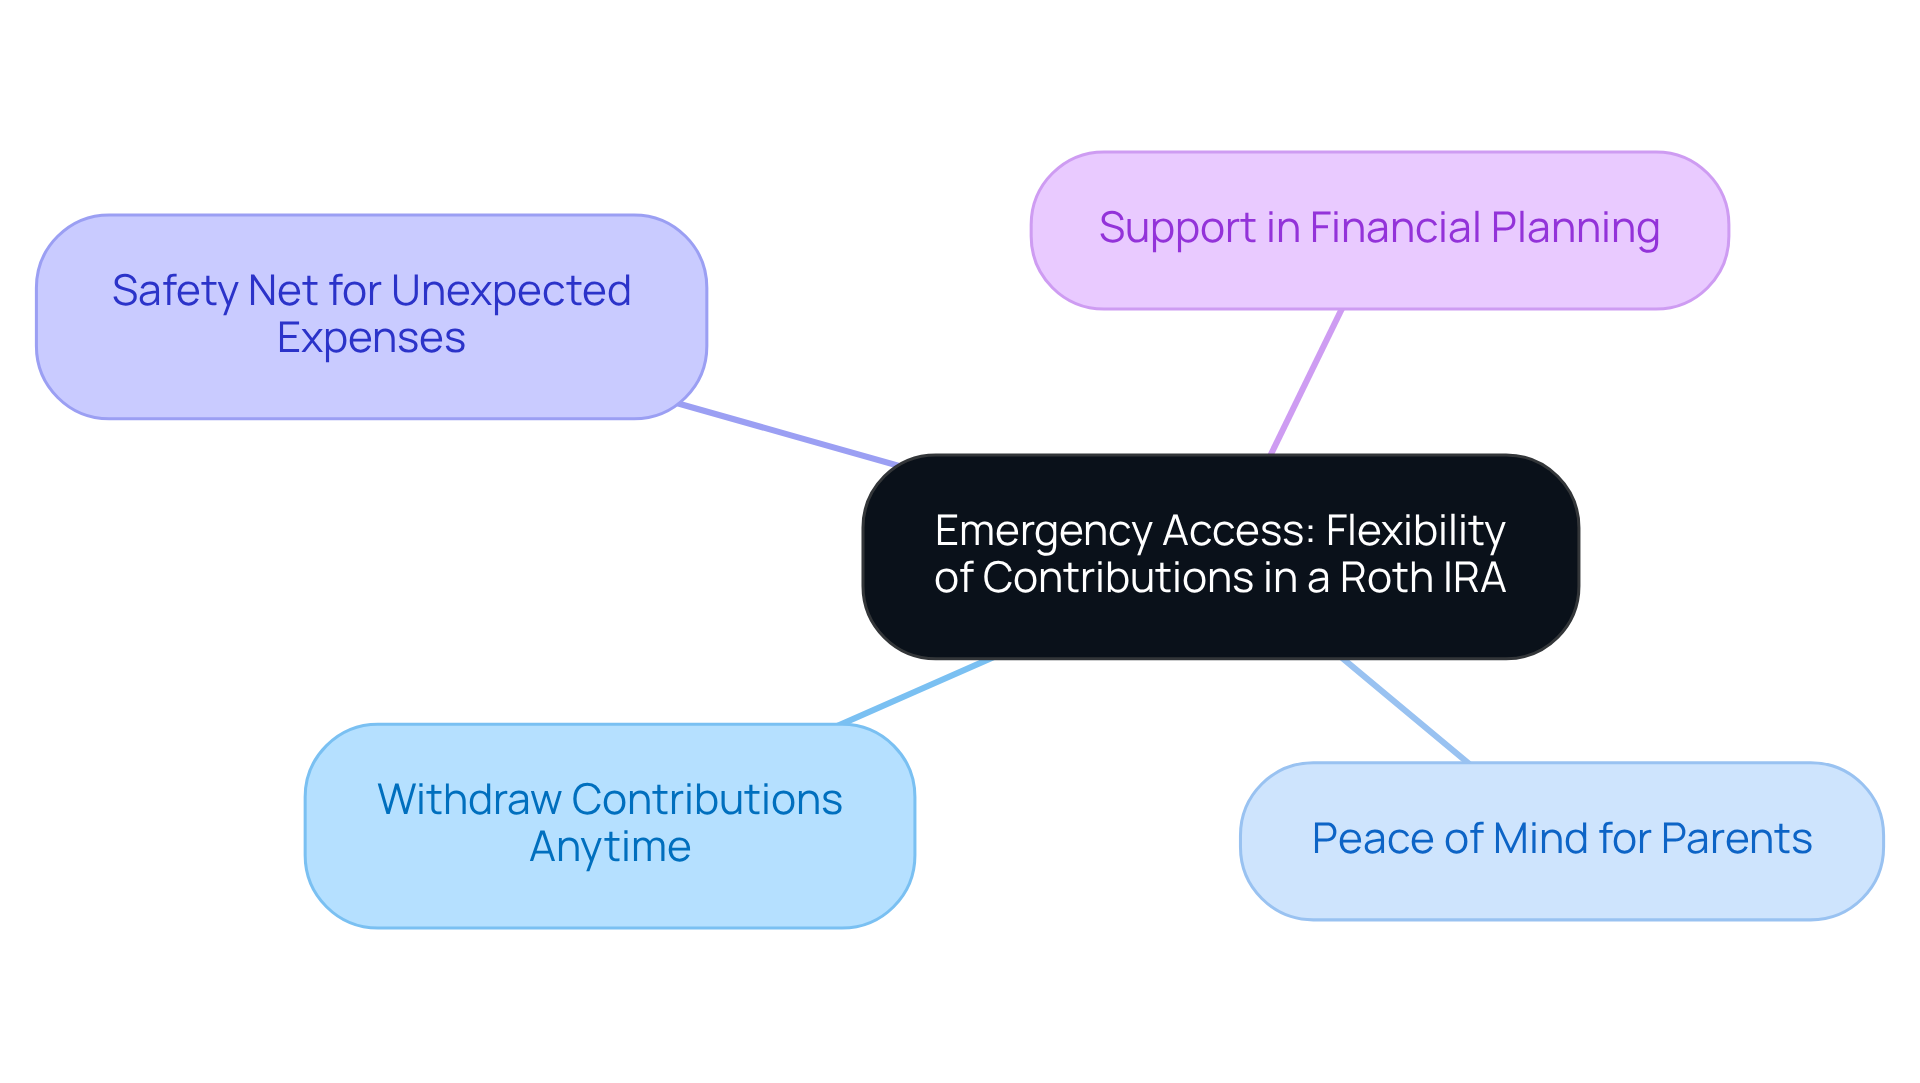
One of the most appealing features of an IRA is the ability to withdraw contributions at any time without facing penalties. This flexibility offers peace of mind for parents, knowing they can access funds in case of an emergency. It aligns beautifully with Bright Advisers’ commitment to keeping fund fees minimal, making wealth management more accessible for families.
While it’s generally wise to let the funds grow untouched for maximum benefit, having the option to withdraw contributions acts as a safety net for families encountering unexpected expenses. Imagine the relief of knowing you have financial security and freedom to handle life’s surprises. This empowerment is essential for nurturing a stable family environment.
We’re here for you, ensuring that your financial planning journey is supported every step of the way. Together, we can navigate this journey, making choices that .
Custodial Rules: Understanding Roth IRA Management for Kids
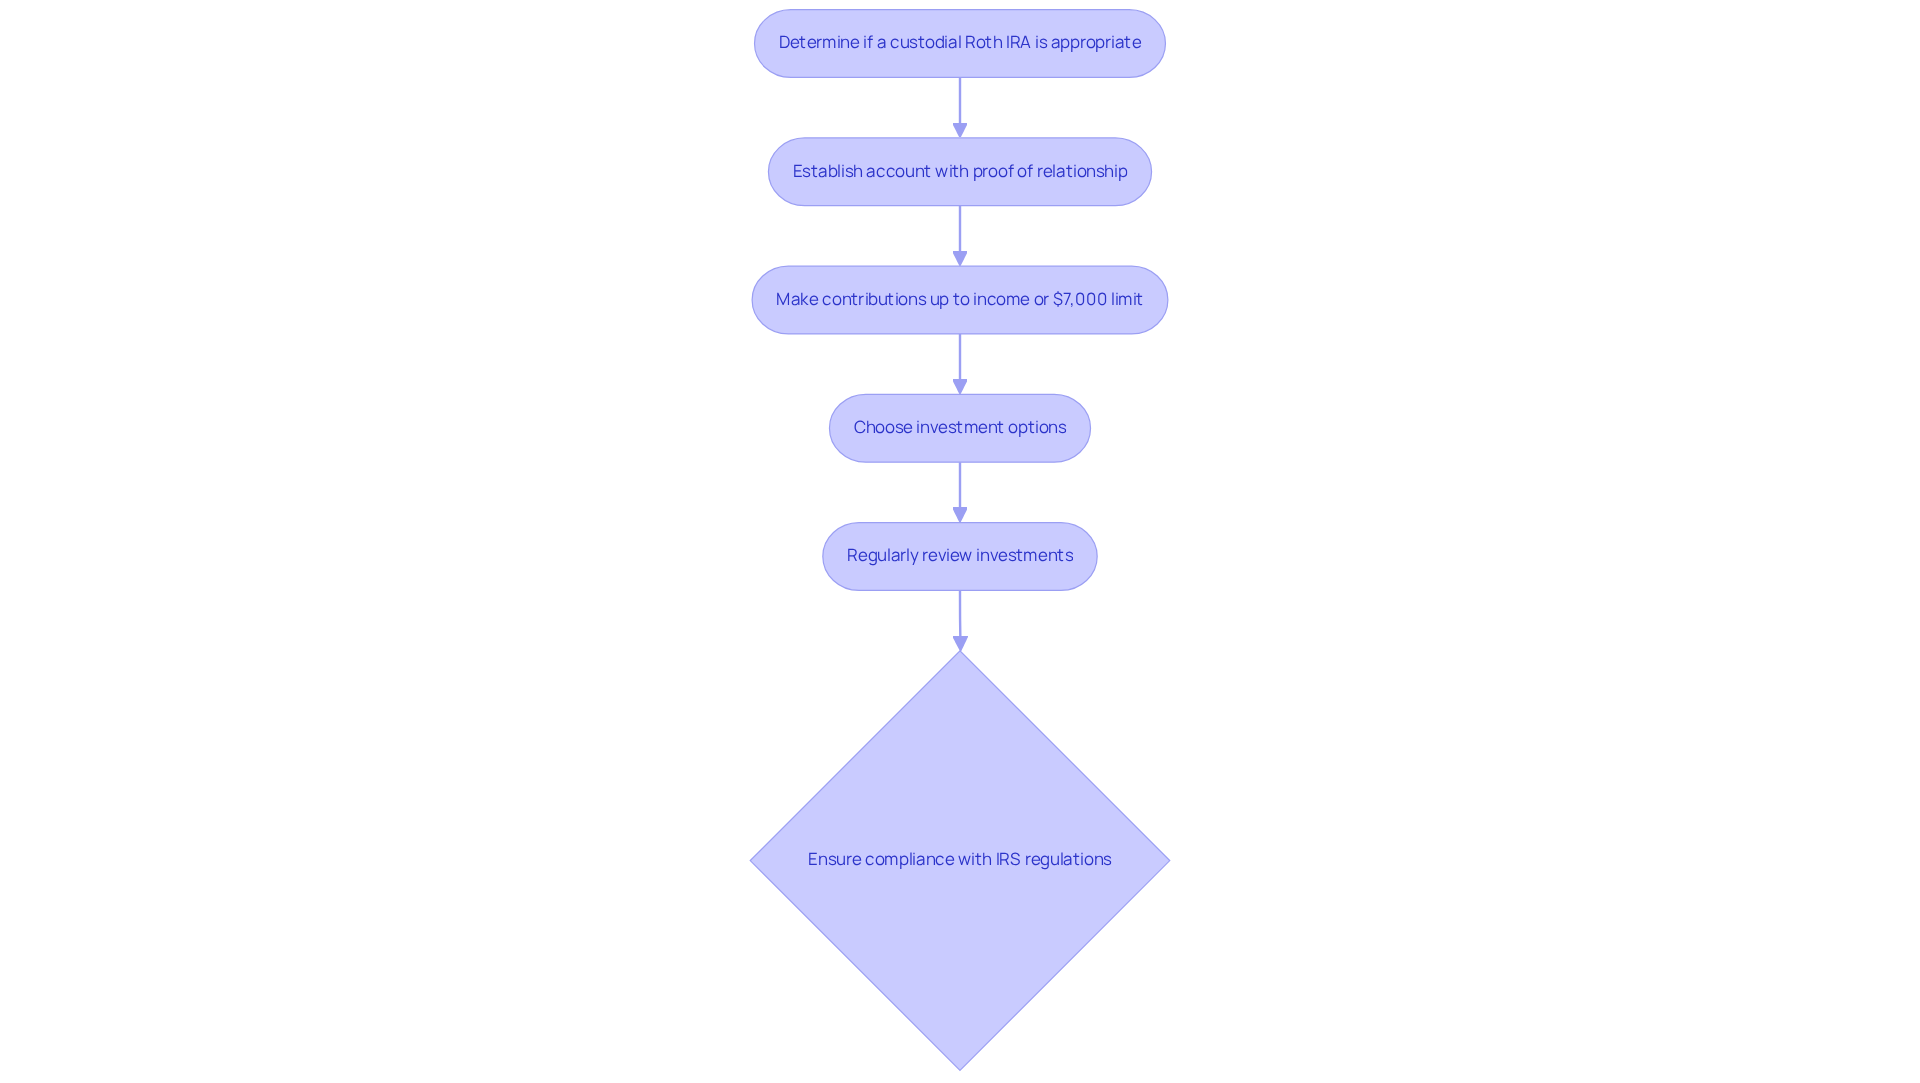
A nurturing step towards your child’s financial future is to consider whether can a baby have a Roth IRA. Typically, this involves managing it as a until they reach the age of majority, which varies from 18 to 21 years depending on your state. During this time, an adult custodian, like yourself, will oversee the account, making investment decisions and ensuring everything aligns with IRS regulations.
It’s essential to remember that contributions can only be made up to your child’s earned income or the annual limit of $7,000 for 2024 and 2025, whichever is lower, which leads to the question: can a baby have a Roth IRA? This careful oversight is crucial for aligning the account with your family’s long-term financial goals. At Bright Advisers, we are dedicated to providing minimal fund fees, making wealth management more accessible for families like yours, ensuring that more of your investment is directed towards building your child’s future.
Imagine the possibilities! Effective management of a custodial retirement account includes regularly reviewing investment options. These can range from stocks and bonds to mutual funds and ETFs, allowing for a diversified portfolio that can grow tax-free. For instance, consider Ava, a 15-year-old who earned $2,000 from selling baked goods, and this raises the question: can a baby have a Roth IRA? She can contribute that amount to her custodial individual retirement account, potentially increasing her savings significantly over time. Assuming an average annual return of 7%, her contributions could accumulate to over $505,790.80 by the time she retires.
It’s important to understand IRS regulations regarding custodial accounts. As one expert wisely noted, “Investment choices should always be made based on an investor’s particular monetary needs, objectives, goals, time horizon, and risk tolerance.” This guidance is invaluable for custodians navigating the complexities of managing an individual retirement account for minors. By involving young individuals in the management process, custodians can instill valuable lessons about saving and investing, fostering a mindset geared towards long-term economic responsibility.
Lastly, don’t forget that proof of your relationship with the minor, such as a birth certificate, is required during the application process for a custodial individual retirement account. Together, we can navigate this journey and ensure a bright financial future for your child.
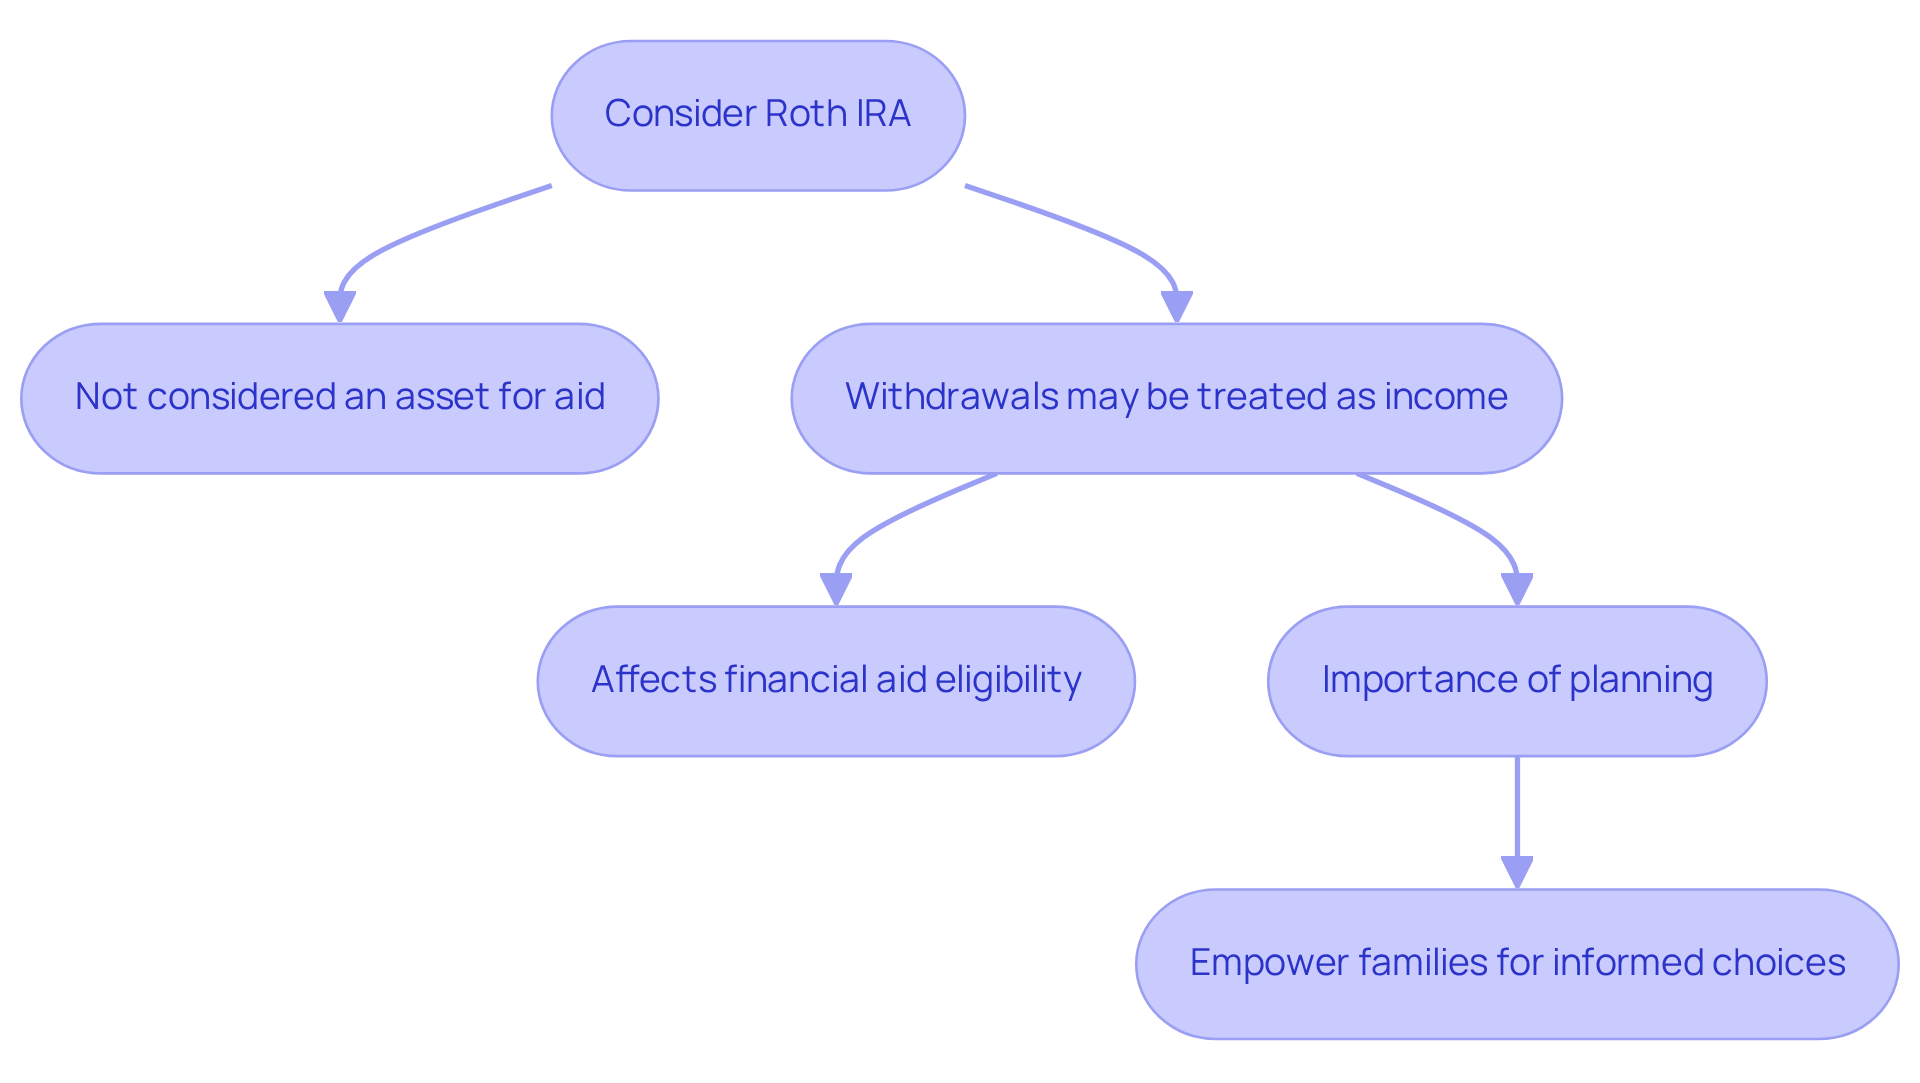
Financial Aid Impact: How a Roth IRA Affects Your Child’s Eligibility
As parents, it’s essential to recognize how an individual retirement account can impact your child’s eligibility for college assistance and to consider if a baby can have a Roth IRA. While the account itself isn’t considered an asset for aid purposes, the question of can a baby have a Roth IRA is relevant, as withdrawals from a Roth IRA may be treated as income, potentially affecting financial aid calculations. This understanding is crucial for families like Jay and Emma, who are committed to supporting their children’s education while also planning for their own financial future.
Imagine if you could navigate these complexities with confidence. By partnering with Bright Advisers, families can develop a comprehensive financial strategy that not only focuses on retirement savings but also thoughtfully considers the implications for educational funding. This approach empowers families to make informed choices that ensure their children are prepared for their educational journey, all while safeguarding their long-term financial goals.
Together, we can navigate this journey, ensuring that your family’s values and aspirations are at the forefront of your planning. We’re here for you, ready to help you create a without compromising your financial well-being.
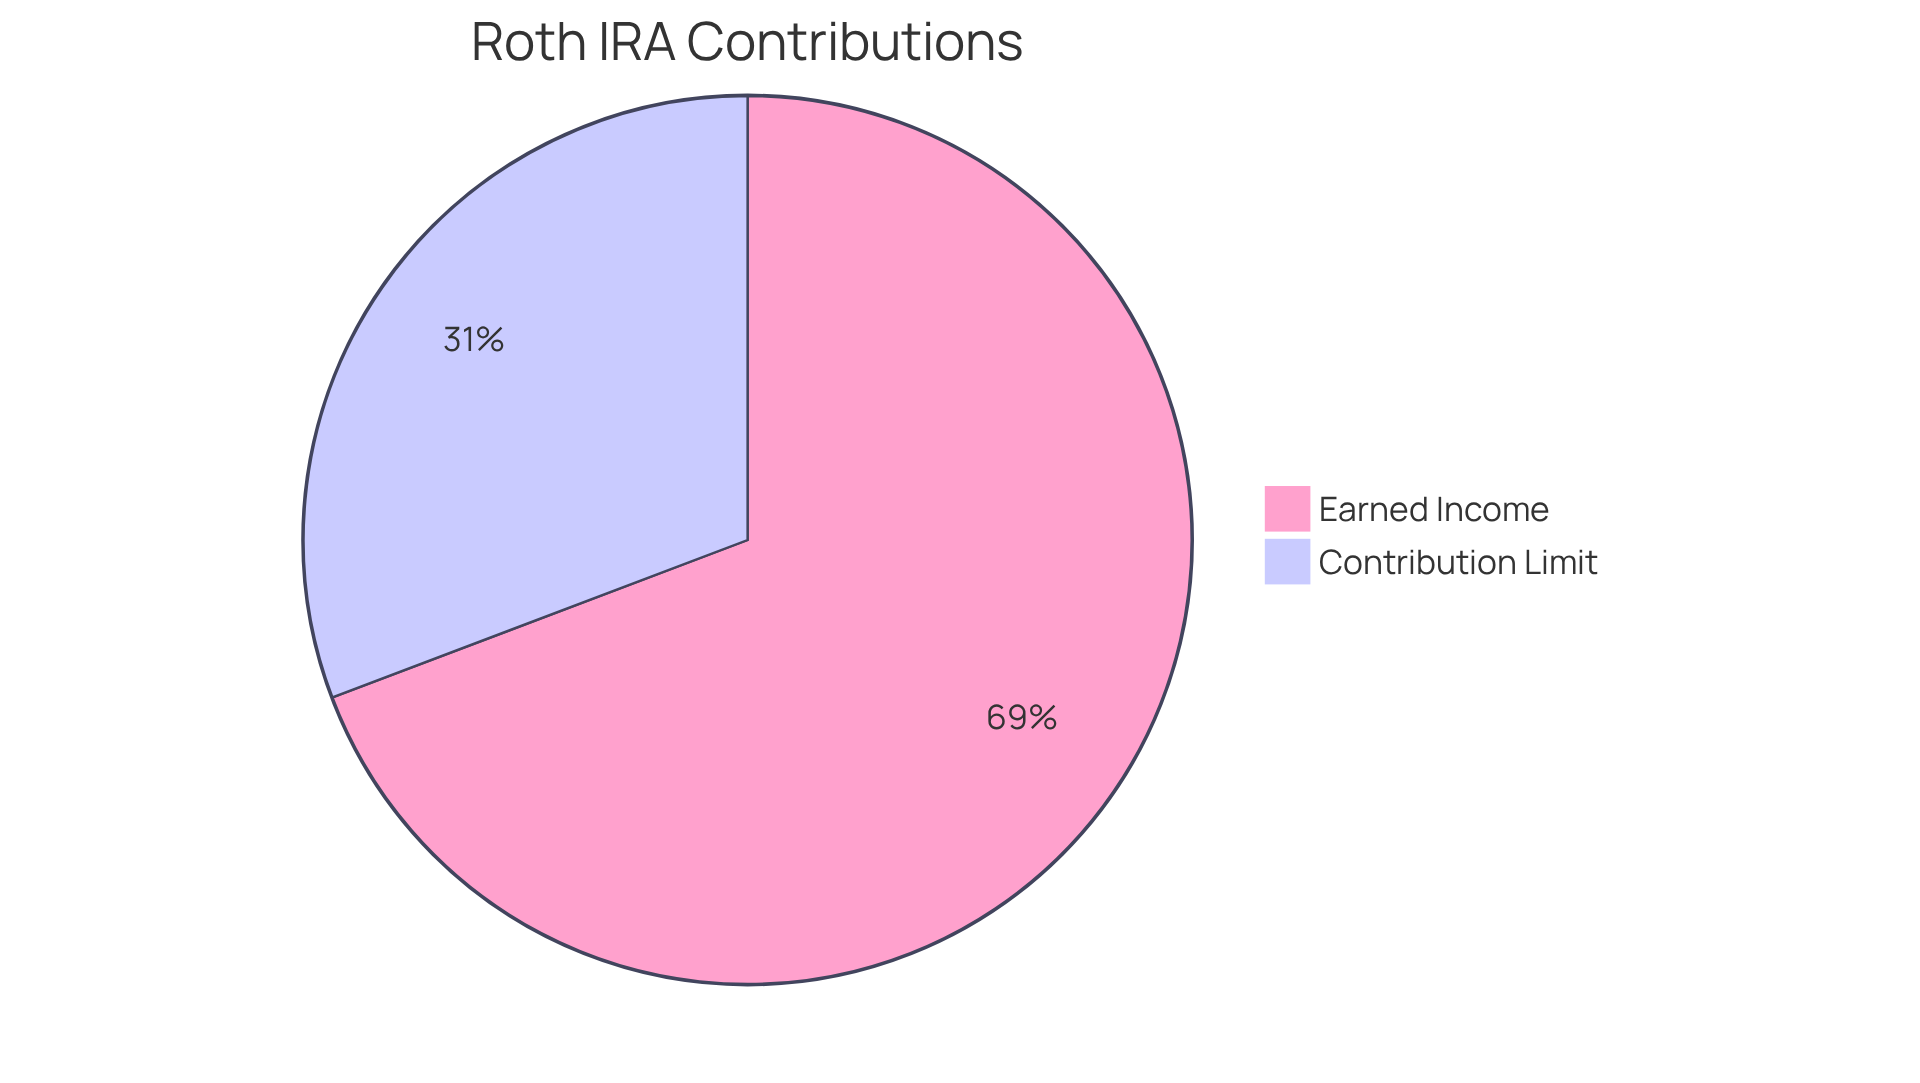
Contribution Limits: What Parents Need to Know for a Child’s Roth IRA
For the tax year 2025, the contribution limit for an individual retirement account is set at $7,000 or the total amount of earned income, whichever is less. This limit applies only if your child has earned income, making it essential for parents to monitor their contributions closely. Exceeding this limit could lead to penalties, and understanding these boundaries is vital for effective financial strategy.
Imagine if your young one earns $15,750 in 2025. In that case, you can contribute the full $7,000 to their Roth IRA, which raises the question: can a baby have a Roth IRA to harness the power of compounding growth over time? If your child begins contributing $7,000 annually at age 10, their account could grow to approximately $384,000 by age 25 with an 8% return.
Furthermore, contributions can be withdrawn without taxes or penalties at any time, offering flexibility and promoting responsible money management. We’re here for you, and can help your family understand these regulations and avoid potential pitfalls. Together, we can navigate this journey, ensuring that your child’s IRA raises the question of can a baby have a Roth IRA as a valuable resource for future economic security.
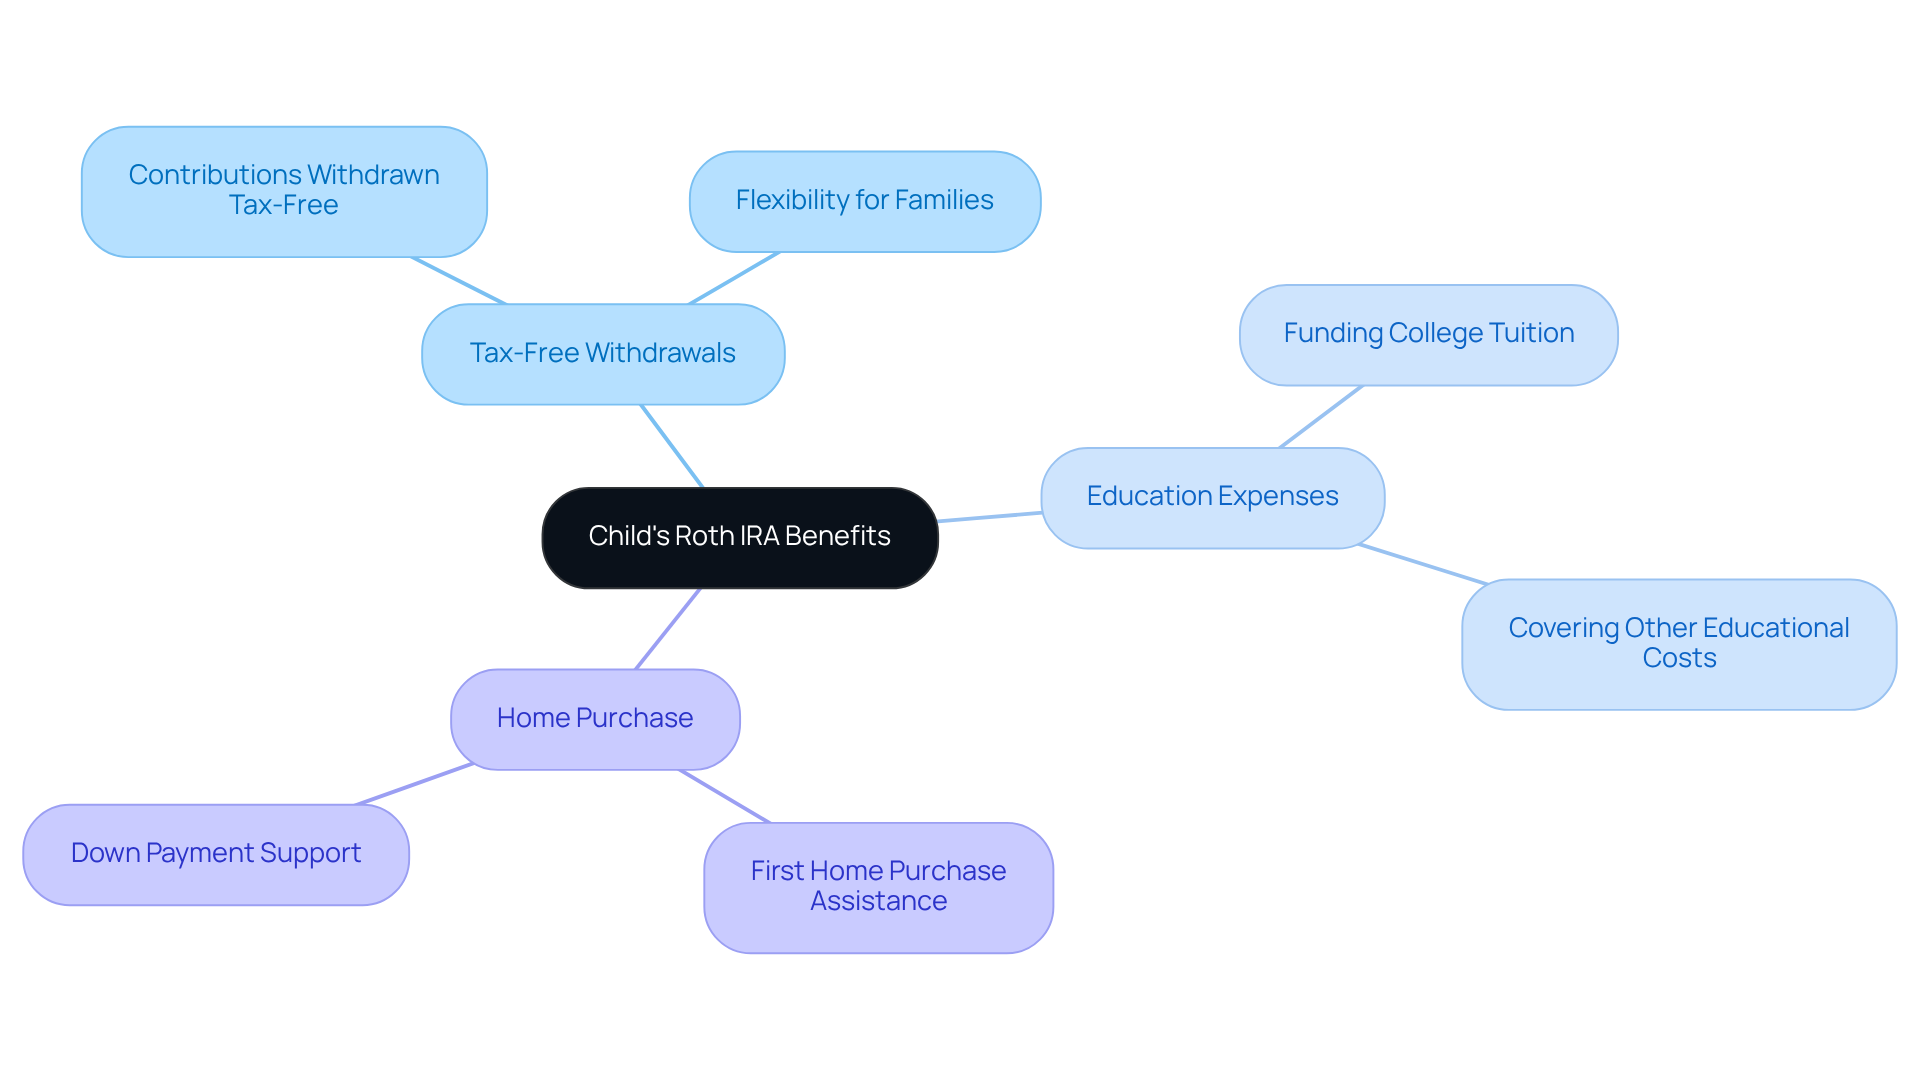
Beyond Retirement: Additional Benefits of a Child’s Roth IRA
This type of IRA offers more than just retirement savings; it plays a crucial role in a personalized financial strategy that truly understands the needs of families. Imagine being able to withdraw contributions tax-free for important expenses like education or a first home purchase. This flexibility allows parents to view the IRA as a versatile resource, perfectly aligned with Bright Advisers’ innovative approach to wealth management.
By recognizing these additional advantages, families can effectively allocate resources to ease financial stress and ensure their children have a bright future. Together, we can and other significant life events, making sure they are well-equipped every step of the way.
Choosing the Right Financial Institution for Your Child’s Roth IRA
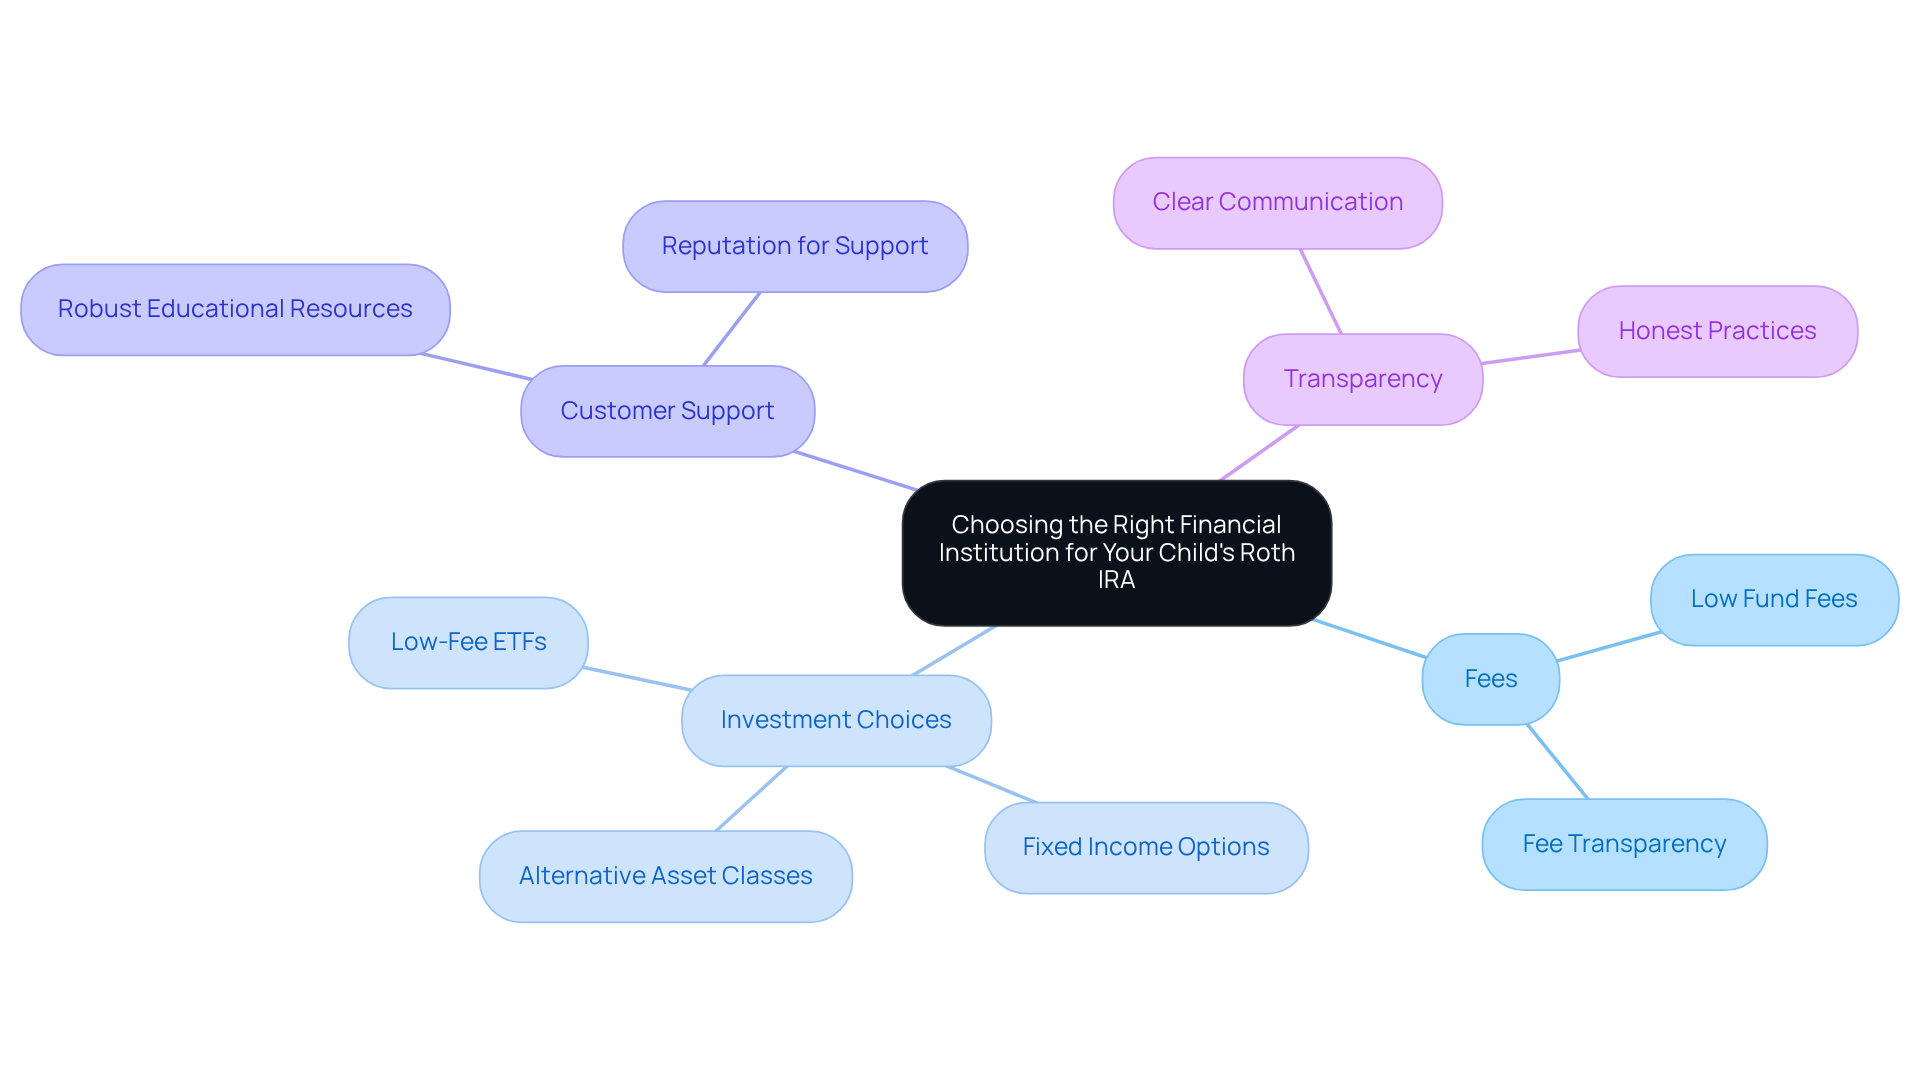
Choosing the right banking establishment for your child’s IRA can feel overwhelming, but you’re not alone in this journey. As a guardian, it’s essential to consider factors like fees, investment choices, and customer support. Imagine if you could find an institution that prioritizes low fund fees, making wealth management more accessible for your family. Bright Advisers, for instance, offers a range of investment options, including low-fee ETFs that provide exposure to fixed income or alternative asset classes, all while ensuring robust educational resources are available for you.
It’s important to seek out institutions that are transparent and have a strong reputation for customer support. By making an informed decision, you can ensure that your child’s Roth IRA is managed effectively, addressing the question of how can a baby have a Roth IRA while aligning with your family’s financial goals. Remember, together, we can , ensuring a brighter future for your loved ones.
Conclusion
Establishing a Roth IRA for a child can be a transformative step towards securing their financial future. This investment vehicle not only allows for tax-free growth but also instills the importance of saving and financial responsibility from an early age. Imagine the possibilities as families understand the eligibility requirements, contribution limits, and the potential for compounding interest—effectively leveraging this opportunity to build a solid foundation for their children’s economic well-being.
It’s important to understand that several key aspects come into play, including:
- The necessity for earned income
- The advantages of tax-free growth
- The flexibility of withdrawals
Additionally, the role of custodians in managing these accounts until the child reaches adulthood cannot be overlooked, ensuring that investments align with long-term financial goals. Moreover, families should consider the implications of a Roth IRA on financial aid eligibility for college, a crucial aspect when planning their children’s educational futures.
In conclusion, taking action to open a Roth IRA for a child is more than just a financial decision; it’s an investment in their future. By utilizing the benefits of this account, families can not only prepare for retirement but also create pathways for educational expenses and other significant life events. Together, we can navigate this journey by engaging with financial advisers who specialize in children’s IRAs, further enhancing this planning and ensuring that every decision reflects the family’s values and aspirations. Embrace this opportunity to nurture your child’s financial literacy and security, paving the way for a brighter tomorrow.
Frequently Asked Questions
Can a baby have a Roth IRA?
Yes, a baby can have a Roth IRA, but the child must have earned income from sources such as part-time jobs or self-employment activities to qualify for contributions.
What is the key requirement for setting up a Roth IRA for a child?
The key requirement is that the child must have earned income, which can come from various activities like babysitting, lawn care, or tutoring.
What are the contribution limits for a child’s Roth IRA?
For 2025, the contribution limit for a traditional IRA is $7,000 for individuals under age 50. Contributions to the child’s IRA cannot exceed their earned income.
How does a Roth IRA benefit a child’s financial future?
A Roth IRA allows for tax-free growth of contributions, meaning any earnings within the account can be withdrawn tax-free in retirement, leading to significant savings over time.
What are the advantages of starting a Roth IRA early for children?
Starting a Roth IRA early allows families to benefit from compounding interest, which can result in considerable monetary growth by the time the child reaches adulthood.
Can parents contribute to their child’s Roth IRA?
Yes, parents can contribute to their child’s Roth IRA, as long as the total contributions do not exceed the child’s earned income.
Why is it important to monitor a child’s income for a Roth IRA?
Monitoring a child’s income is important to maximize the benefits of the tax-advantaged account and ensure contributions are based on actual earnings.
What are some common part-time jobs that can provide earned income for a child’s Roth IRA?
Common part-time jobs include babysitting, lawn care, and tutoring, which not only provide income but also teach valuable lessons about work and saving.
List of Sources
- Bright Advisers: Personalized Financial Planning for Your Child’s Roth IRA
- The Dynamics of Family Financial Socialization: Impact on Financial Self-efficacy and Financial Behavior – Rajwinder Kaur, Manjit Singh, 2024 (https://journals.sagepub.com/doi/10.1177/09711023241282195)
- Frontiers | Youth, money, and behavior: the impact of financial literacy programs (https://frontiersin.org/journals/education/articles/10.3389/feduc.2024.1397060/full)
- Earned Income: The Key Requirement for a Child’s Roth IRA
- Custodial Roth IRA: A Roth IRA for Kids – NerdWallet (https://nerdwallet.com/article/investing/why-your-kid-needs-a-roth-ira)
- Roth IRAs Holdings Have Shot Up among Young Households – Center for Retirement Research (https://crr.bc.edu/roth-iras-holdings-have-shot-up-among-young-households)
- Roth IRAs: Put Your Child’s Summer Earnings to Work (https://robertprussocpa.com/roth-iras-put-your-childs-summer-earnings-to-work)
- Roth IRAs for Kids? Absolutely. | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/roth-iras-for-kids–absolutely-.html)
- Surprise! Your Child’s Summer Job Can Turn Into a Million-Dollar Roth IRA (https://nasdaq.com/articles/surprise-your-childs-summer-job-can-turn-million-dollar-roth-ira)
- Tax-Free Growth: Maximizing Your Child’s Roth IRA Benefits
- 8 Key Benefits of a Roth IRA | Vanguard (https://investor.vanguard.com/investor-resources-education/article/benefits-of-a-roth-ira)
- Roth IRA vs. Traditional IRA: Rules & Tax Benefits | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira)
- Roth IRA | Powerful Way to Save for Retirement | Fidelity Investments (https://fidelity.com/retirement-ira/roth-ira)
- 5 Essential Benefits of Roth IRAs (https://merceradvisors.com/insights/retirement/5-essential-benefits-of-roth-iras)
- Unlocking the power of Roth IRAs (https://ml.com/articles/unlocking-the-power-of-roth-iras.html)
- Compounding Interest: The Advantage of Starting Early with a Roth IRA
- 10 Key Benefits of 529 Superfund for Young Families – Bright Advisers (https://brightadvisers.com/10-key-benefits-of-529-superfund-for-young-families)
- Custodial Rules: Understanding Roth IRA Management for Kids
- Roth IRA for Kids Explained (https://merceradvisors.com/insights/family-finance/roth-ira-for-kids-explained)
- Roth IRA for Kids | Plan Benefits, Eligibility, and Investment Options | Fidelity (https://fidelity.com/retirement-ira/roth-ira-kids)
- Roth IRAs for Kids? Absolutely. | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/roth-iras-for-kids–absolutely-.html)
- How Custodial Roth IRAs Work: Everything to Know (https://horizontrust.com/how-custodial-roth-iras-work-everything-to-know)
- Custodial Roth IRA: What It Is and How to Set It Up (https://composer.trade/learn/custodial-roth-ira)
- Contribution Limits: What Parents Need to Know for a Child’s Roth IRA
- Roth IRA for Kids Explained (https://merceradvisors.com/insights/family-finance/roth-ira-for-kids-explained)
- Roth IRA for Kids | Plan Benefits, Eligibility, and Investment Options | Fidelity (https://fidelity.com/retirement-ira/roth-ira-kids)
- Roth IRAs for Kids: Smart Tax & Wealth Strategy for Dentists (https://practicecfo.com/roth-iras-for-kids-smart-tax-wealth-strategy-for-dentists)
- 2025 Contribution Limits: 401(k), Traditional, & Roth IRA | Britannica Money (https://britannica.com/money/2025-contribution-limits-401k-ira)
- How a Roth IRA can give your adult children and grandchildren a running start | TIAA (https://tiaa.org/public/invest/services/wealth-management/perspectives/roth-ira-for-adult-children)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading