

Key Highlights
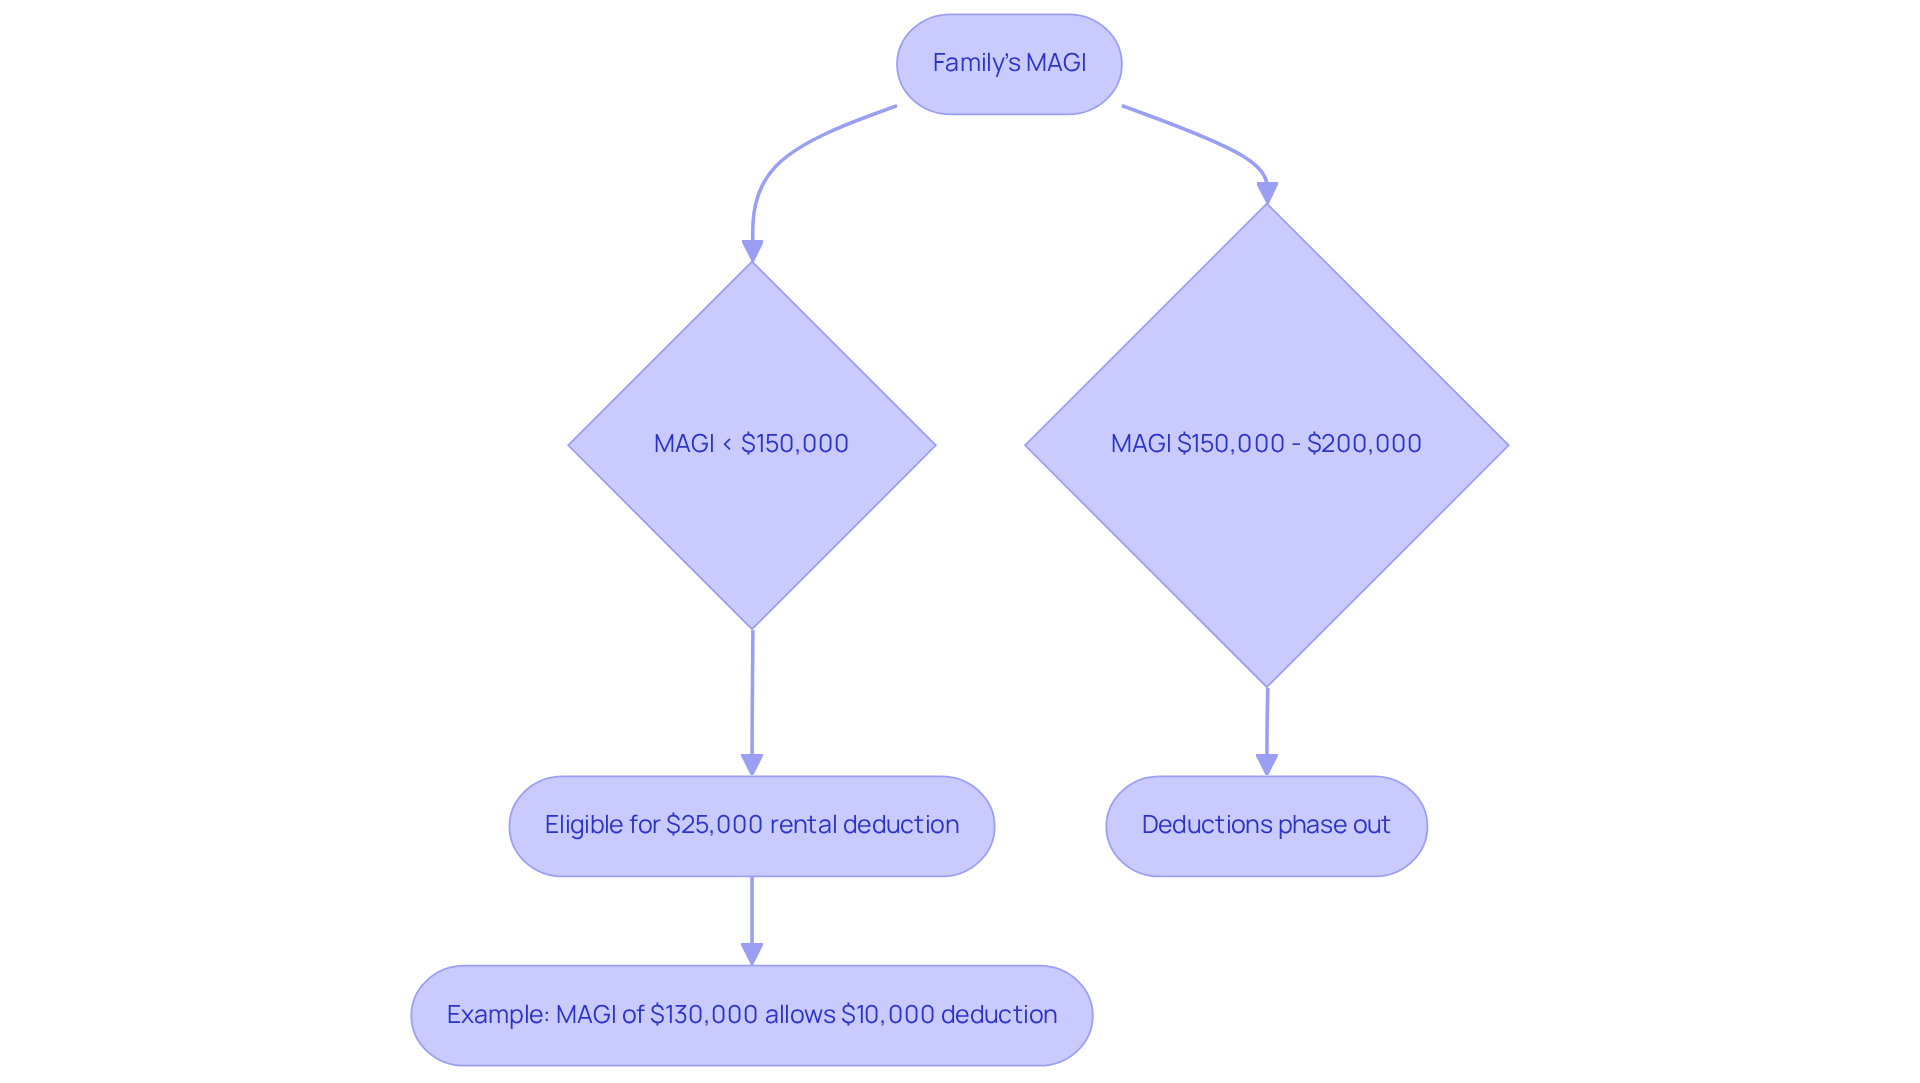
- Families with a Modified Adjusted Gross Income (MAGI) below $150,000 can deduct up to $25,000 in rental losses against non-passive earnings, but this benefit phases out entirely at $200,000 MAGI.
- Active management of rental properties allows families to utilise deductions effectively, with potential for significant tax savings if income levels are monitored.
- The grouping election can treat multiple rental activities as a single activity for tax purposes, but it is generally irrevocable and should be approached with professional advice.
- Real estate professionals can bypass passive loss limitations, allowing for more strategic tax planning by offsetting rental losses against other income.
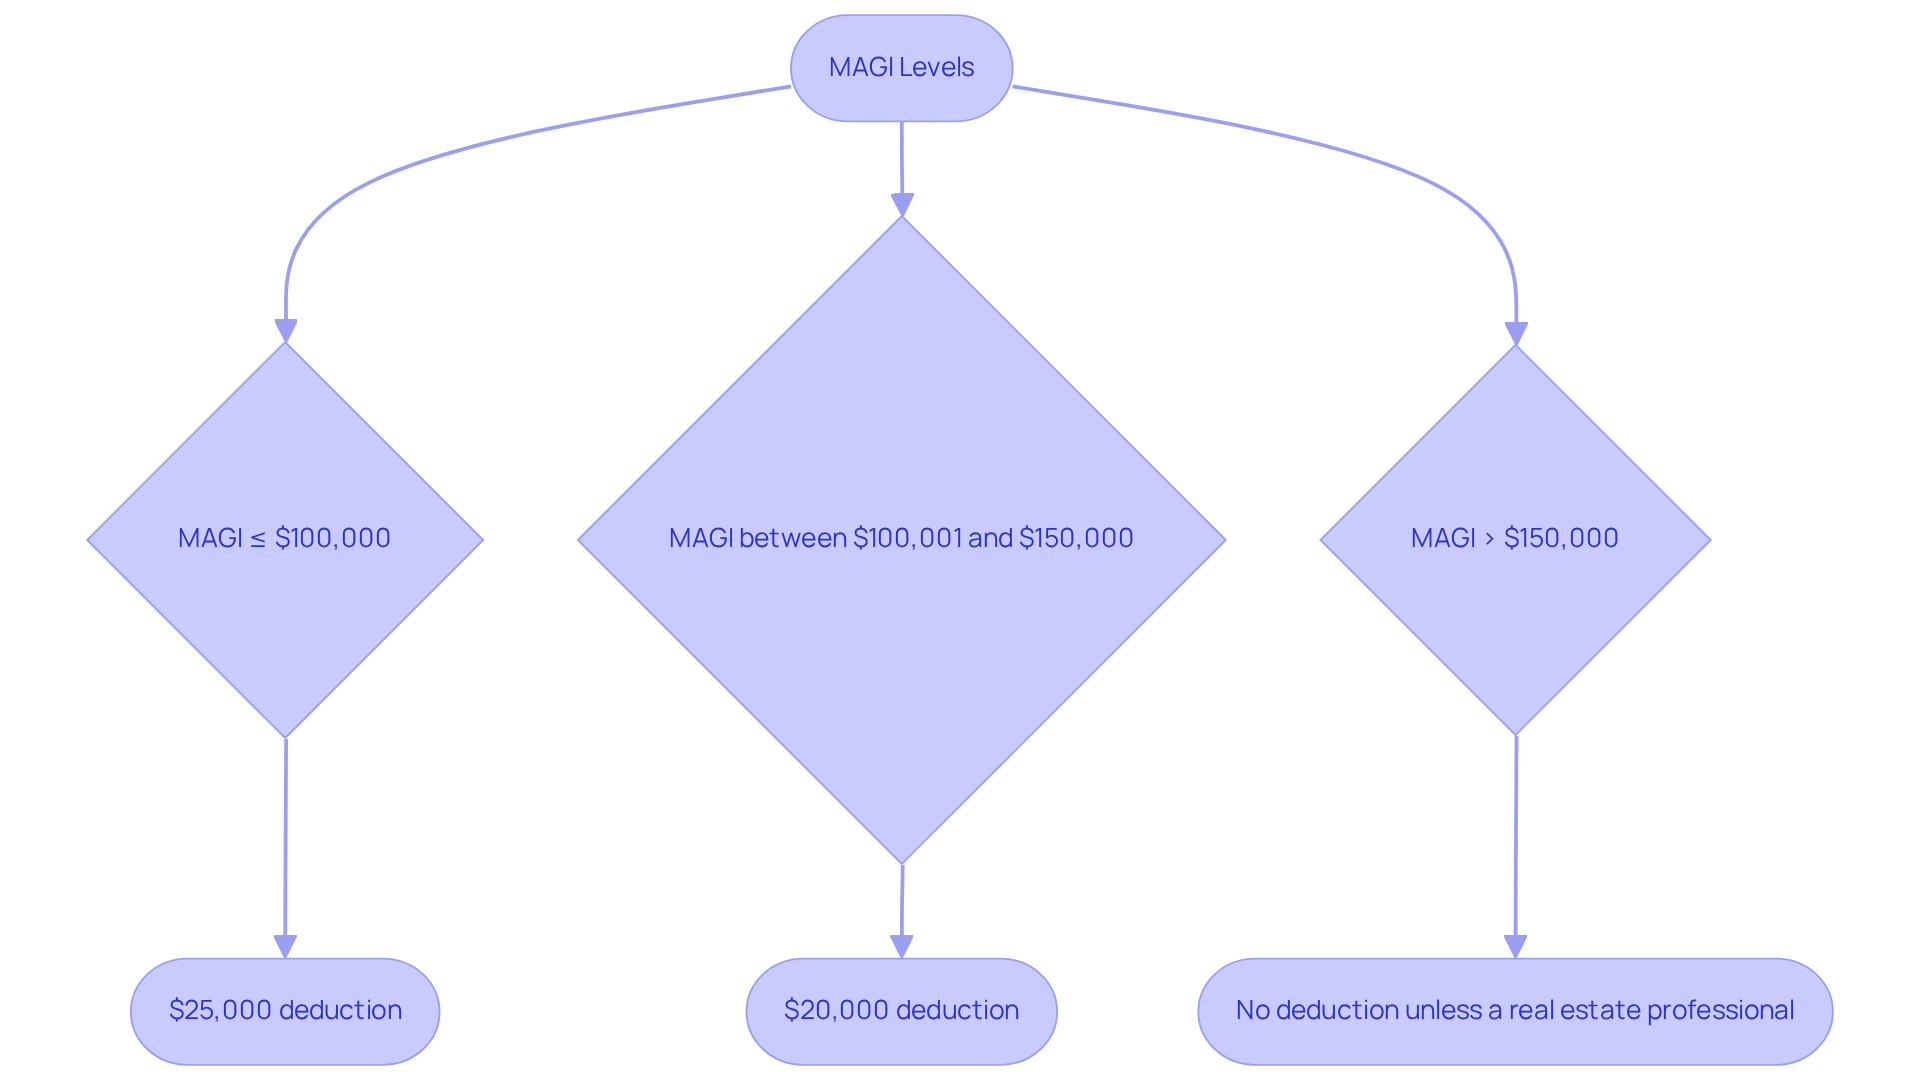
- The $25,000 passive loss allowance is fully available for households with MAGI under $100,000, but begins to phase out at $100,000 and is eliminated at $150,000 unless qualifying as a real estate professional.
- Families should track participation hours in real estate activities to meet IRS criteria for claiming deductions, as accurate records are essential for compliance.
- Selling rental properties can release suspended passive losses, providing tax benefits that can significantly impact a household’s financial situation.
- Common mistakes to avoid include failing to maintain accurate records, misunderstanding earnings thresholds, and not consulting tax professionals for guidance.
Introduction
Imagine feeling confident about your family’s financial future, even amidst the complexities of tax regulations. With the IRS updating its rules for 2026, it’s important to grasp these changes to make the most of your tax benefits and steer clear of costly errors. In this article, we’ll share ten insights that can help your family:
- Manage passive losses
- Discover new opportunities
- Stay on the right side of changing tax laws
Together, we can explore how these insights can help your family protect your wealth and grow financially, even in the face of complex tax rules.
Bright Advisers: Tailored Strategies for Navigating Passive Loss Income Limitations
Imagine feeling lost in the maze of tax deductions while trying to secure your family’s financial future. At Bright Advisers, we understand that navigating the complexities of passive loss income limitations 2026 can feel daunting for families. Our strategies focus on enhancing tax advantages while helping you manage your investments effectively. For instance, if your household has a modified adjusted gross income (MAGI) below $150,000, you can deduct up to $25,000 in rental deductions against non-passive earnings. However, this allowance phases out entirely at $200,000 MAGI. It’s important for families to consider their earnings levels to keep those valuable deductions in reach.
Let’s take a moment to think about a married couple with a MAGI of $130,000 who actively manages their rental property. They can subtract $10,000 from their $28,000 deficit in the first year. But if their income increases, they might face a complete halt of deductions in later years. By the time they sell the property in Year 5, they could access $60,000 in deferred expenses, showing just how crucial it is to keep track of these numbers as they grow.
Bright Advisers uses advanced technology and personalized financial planning to help families structure their portfolios effectively. For example, you can create income from additional rental properties or other qualifying activities to counterbalance any setbacks. This approach allows you to manage inactive activity setbacks across your real estate portfolio more efficiently.
Additionally, families can benefit from the grouping election, which lets multiple rental activities be treated as a single activity for tax purposes. This can help meet participation thresholds, but it’s essential to seek professional advice before making such decisions, as the grouping election is generally irrevocable.
With the right guidance, you can turn these challenges into opportunities for your family’s financial growth. Bright Advisers equips families with the resources and strategies essential to navigate the complex landscape of passive loss income limitations 2026, ensuring you can make informed choices that align with your long-term financial objectives.
Understanding Passive Activity Loss Rules: Key Regulations for 2026
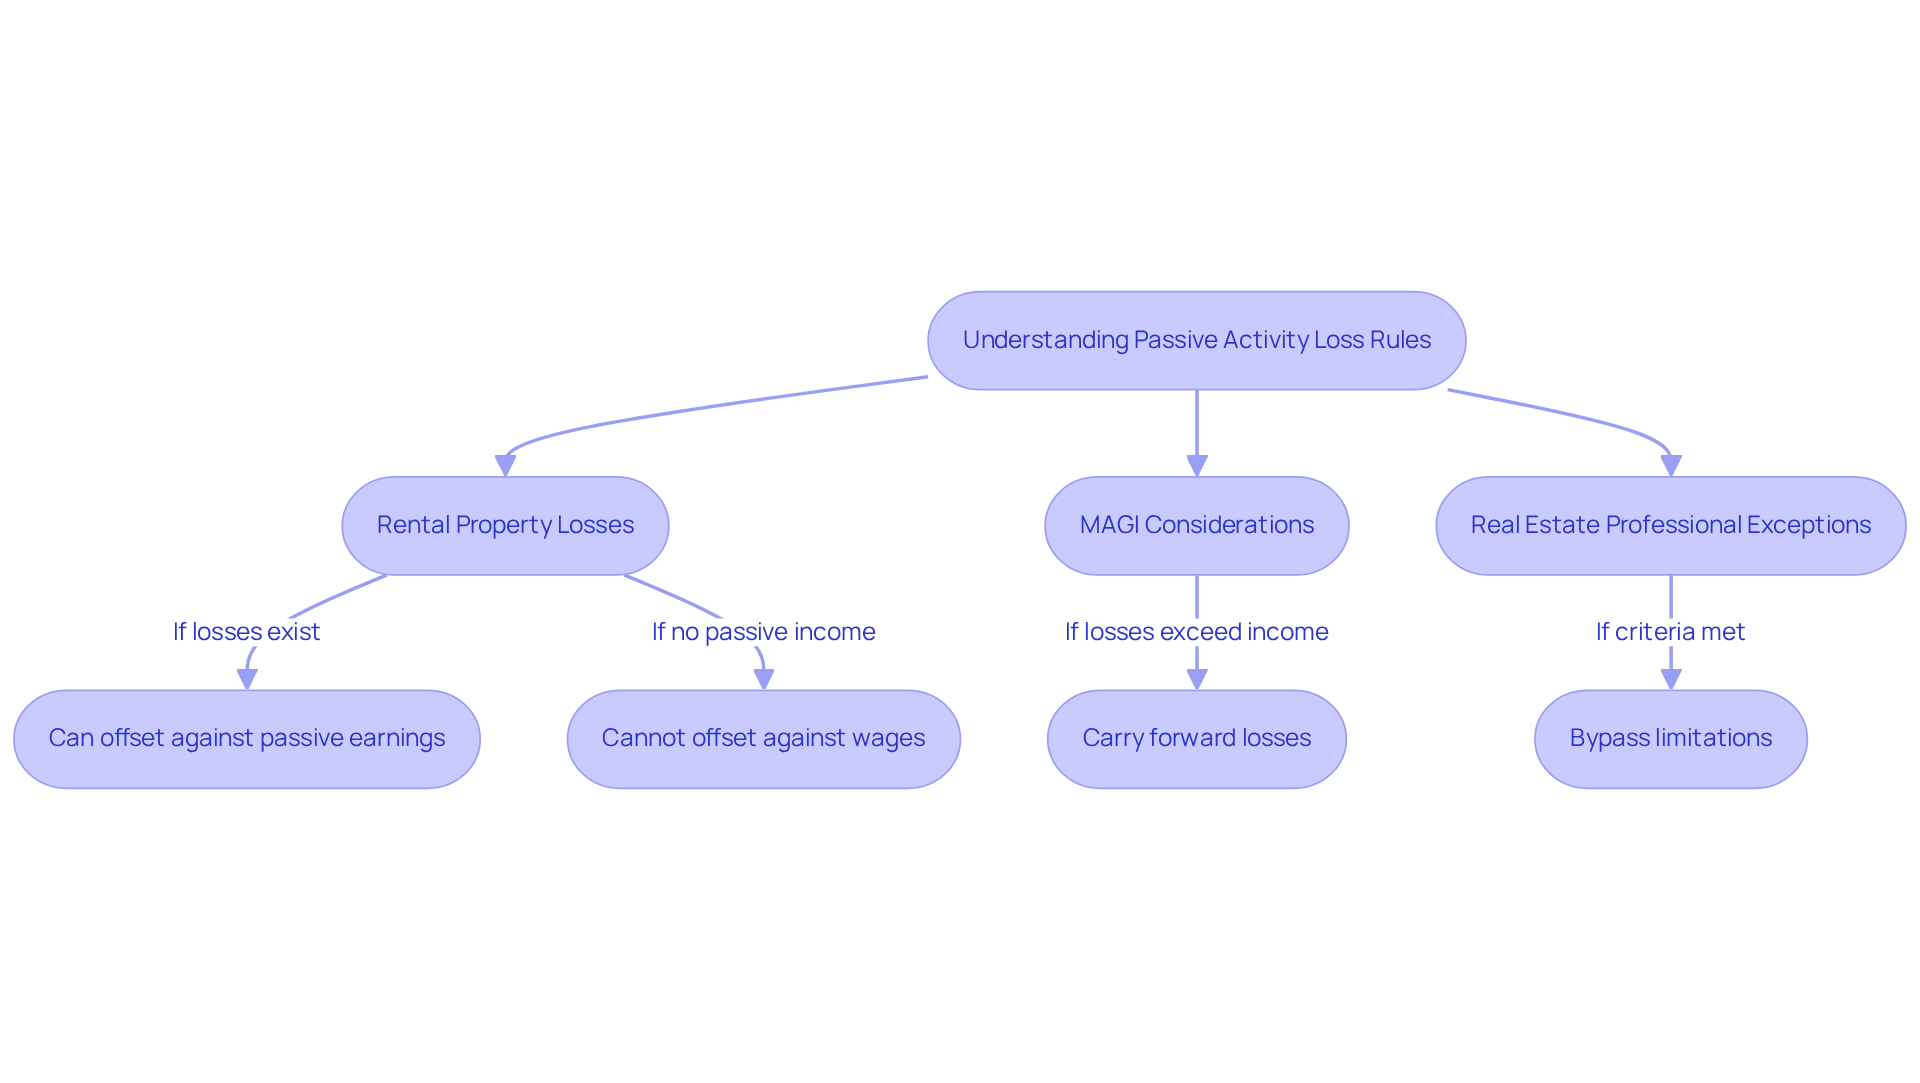
Imagine the relief of knowing your family’s finances are secure, even when navigating complex tax rules. Did you know that the IRS has specific rules about passive loss income limitations 2026 concerning losses from businesses or investments you’re not actively involved in? These are known as passive loss income limitations 2026. For 2026, the passive loss income limitations 2026 indicate that the rules regarding activity deductions remain mostly the same, allowing you to offset these deductions against earnings only. This means that if you have rental properties that are losing money, those losses can only balance out earnings from other non-active activities, not your regular wages or portfolio returns, in accordance with the passive loss income limitations 2026.
By understanding these rules, you can protect your family from unexpected tax surprises. If your deductions exceed earnings from passive activities, the passive loss income limitations 2026 permit you to carry those losses over to future years, which could lead to tax advantages when your activities start generating income again. For instance, if your Modified Adjusted Gross Income (MAGI) is $125,000 and you have $30,000 in non-operating expenses, your deduction might be limited to $12,500 due to phase-out rules, with the remaining expenses carried forward.
Additionally, if you’re a real estate professional meeting specific criteria, you can bypass these limitations entirely, allowing for more strategic tax planning. Keeping track of your family’s earnings and expenses can feel overwhelming, but it’s essential for maximizing your potential deductions. With the right knowledge and support, you can transform your family’s financial future, ensuring peace of mind for years to come.
Identifying Exceptions to Passive Loss Limitations: Opportunities for Investors
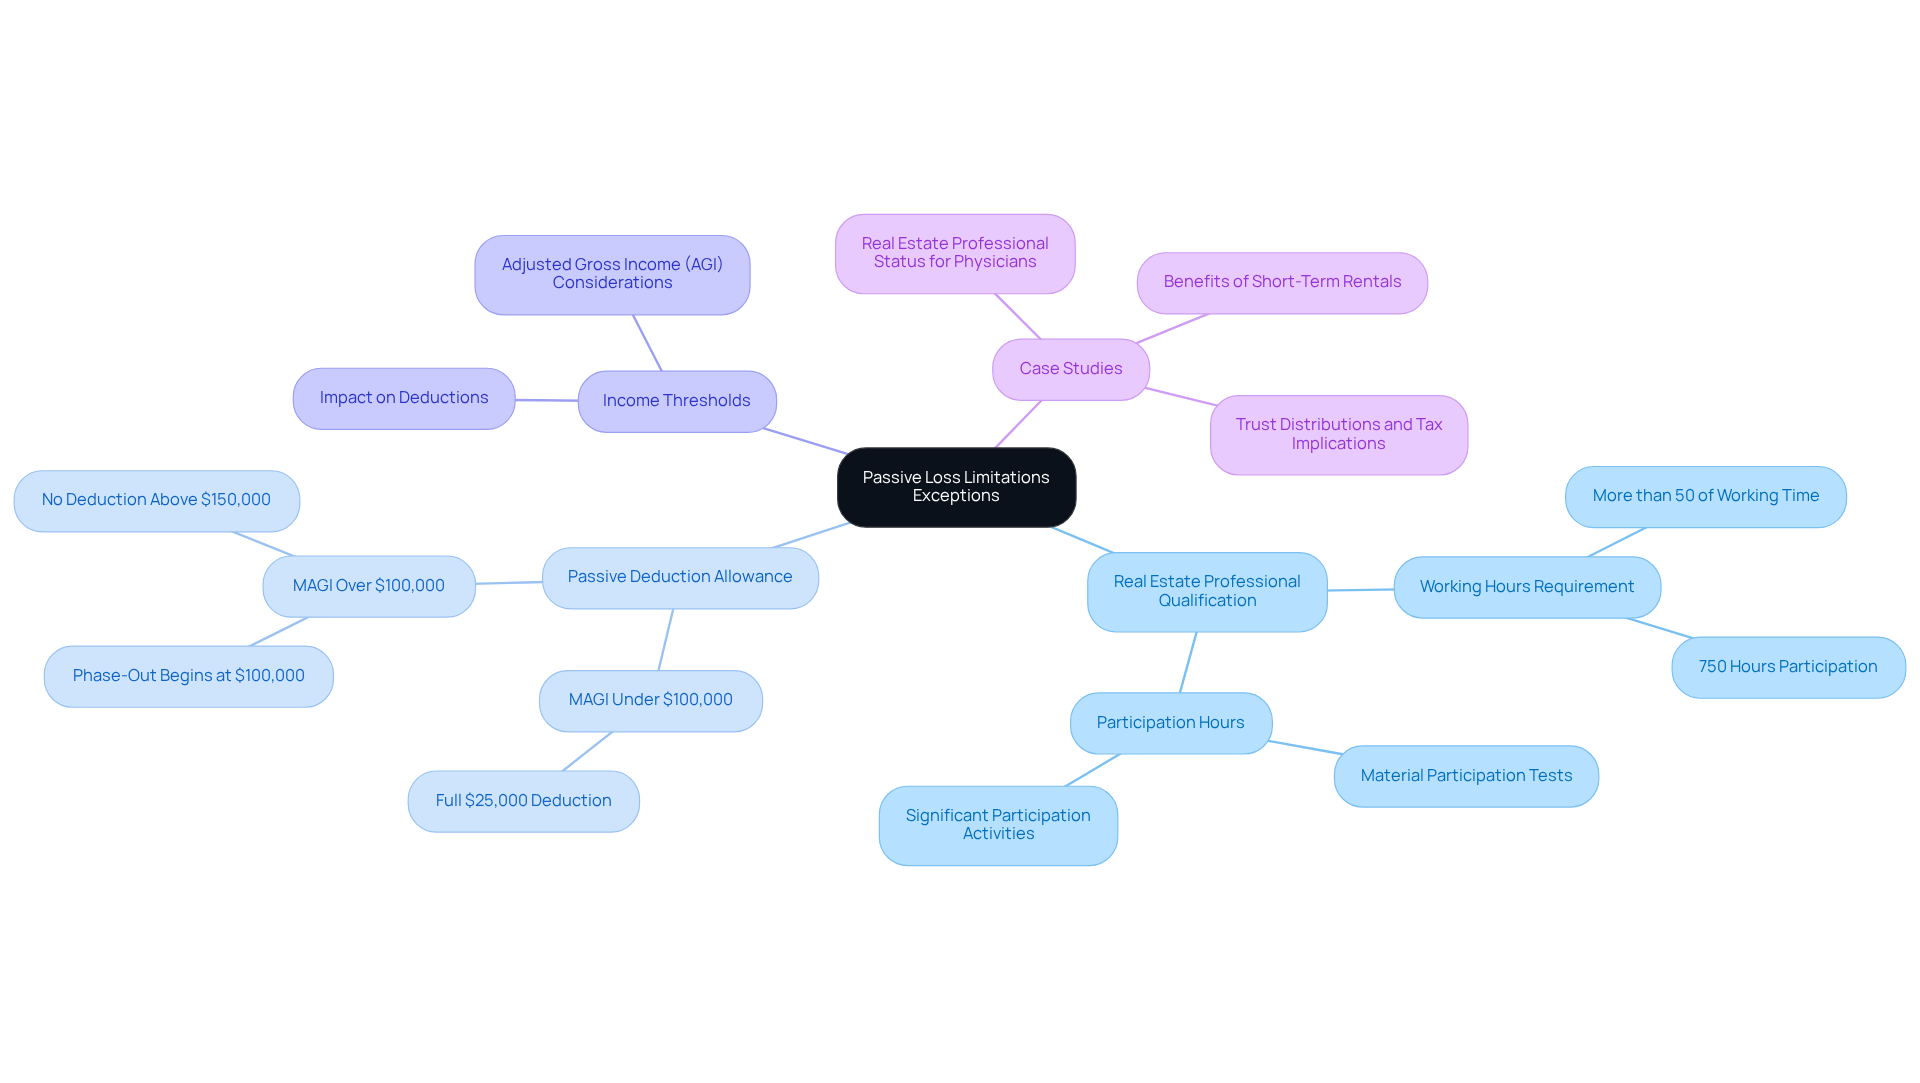
Imagine navigating the maze of tax regulations while trying to secure your family’s future – it’s a challenge many parents face. Families can gain significantly from certain exceptions to the passive loss income limitations 2026 regarding deductions. For instance, qualifying as a real estate professional allows you to subtract losses from rental properties against your other income. To qualify, you’ll need to dedicate more than half of your working hours to real estate activities and participate in these activities for at least 750 hours each year.
Additionally, the $25,000 passive deduction allowance can help families with a modified adjusted gross income (MAGI) under $100,000 offset their non-passive earnings with rental losses. But keep in mind, this benefit starts to fade for families with an adjusted gross income over $100,000, and it’s completely gone for those above $150,000 because of the passive loss income limitations 2026.
Consider the case of doctors who own rental properties; qualifying as real estate professionals can be a game-changer, allowing them to offset taxable income with rental losses, especially if their properties are running at a loss. Plus, short-term rentals, like those from Airbnb, aren’t classified as passive activities by the IRS, meaning you can deduct losses without needing to qualify as a real estate professional, as long as you’re actively involved.
Take Allison and Brian, for example. Through their collaboration with Bright Advisers, they optimized their tax situation and secured their children’s future through education funding. They even found a way to retire sooner by incorporating tax optimization into their comprehensive financial plan. This experience highlights how strategic tax planning can lead to financial security and freedom for families.
To effectively navigate these complexities, it’s essential for households to track their participation hours in real estate activities and consult with a tax professional. Bright Advisers offers customized wealth management solutions that empower families to make informed financial choices and protect their wealth for generations to come.
$25,000 Passive Loss Allowance: Maximizing Your Tax Benefits
Imagine the relief of knowing you can save on taxes while providing for your family. For households with modified adjusted gross earnings (MAGI) of $100,000 or less, the $25,000 passive deduction allowance offers a significant tax advantage. This allowance allows you to deduct up to $25,000 of rental real estate losses against your non-passive income, effectively lowering your taxable income. But it’s important to know that if your MAGI goes over $100,000, you might start losing some of this benefit. For example, if your household’s MAGI is $110,000, you would only be able to deduct $20,000 of the allowance. Once your earnings reach $150,000, the passive loss allowance is completely eliminated unless you qualify as a real estate professional, which allows for unlimited deductions regardless of earnings level.
Planning your finances wisely can make a big difference for your family, helping you keep more of what you earn. By keeping your MAGI below the $100,000 threshold, you can fully benefit from the $25,000 deduction, which can significantly reduce your overall tax liability. Imagine the worry of missing out on tax benefits that could ease your financial burden. Families actively overseeing their rental properties and managing their income within this advantageous range can effectively leverage the allowance for unutilized deductions, improving their financial situation.
As we look ahead to 2026, these tax benefits can be a lifeline for families investing in real estate, particularly in light of the passive loss income limitations 2026. This allowance not only encourages investment in rental properties but also provides a way for families to manage their tax obligations more efficiently. By understanding the implications of your MAGI and actively participating in property management, you can leverage this tax strategy to your advantage. By taking control of your financial planning, you can ensure your family enjoys the benefits of these tax strategies.
Material Participation: Essential Criteria for Claiming Passive Loss Deductions
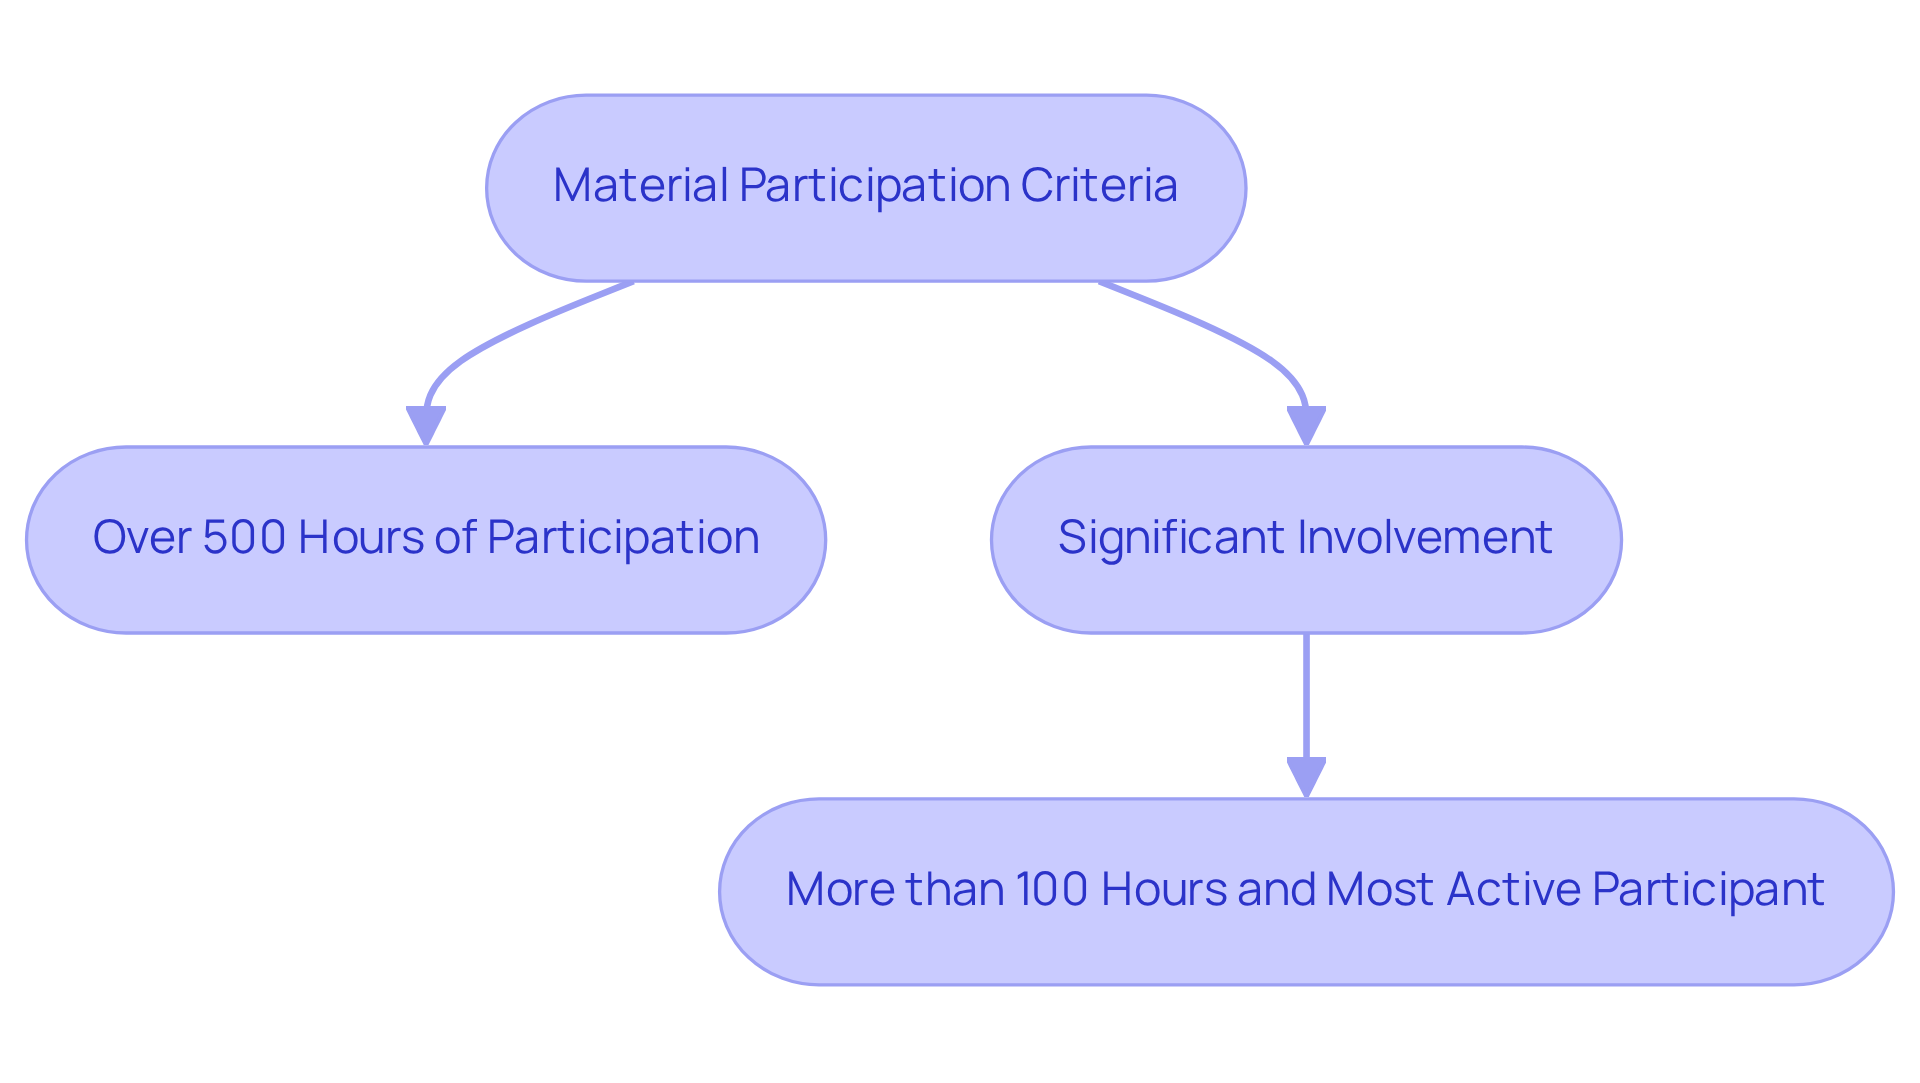
Imagine feeling overwhelmed by tax rules while trying to provide for your family. It’s essential for families to understand the material participation criteria set by the IRS. To qualify for deductions related to non-active income, families must meet specific criteria. Key tests include:
- Participating in the activity for over 500 hours during the year.
- Showing significant involvement, which means participating for more than 100 hours and being the most active participant.
It’s important for families to keep track of their participation, as failing to maintain accurate records can lead to disallowed deductions. For instance, if one partner dedicates over 500 hours to a rental activity, both can be seen as actively participating. This could enable them to offset rental deficits against other income, easing financial stress.
Understanding these details can help families navigate the complexities of tax deductions more easily. Remember, you’re not alone in this journey; together, we can tackle these challenges and ensure your family benefits from every opportunity.
Income Levels and Passive Loss Phase-Out: What Investors Need to Know
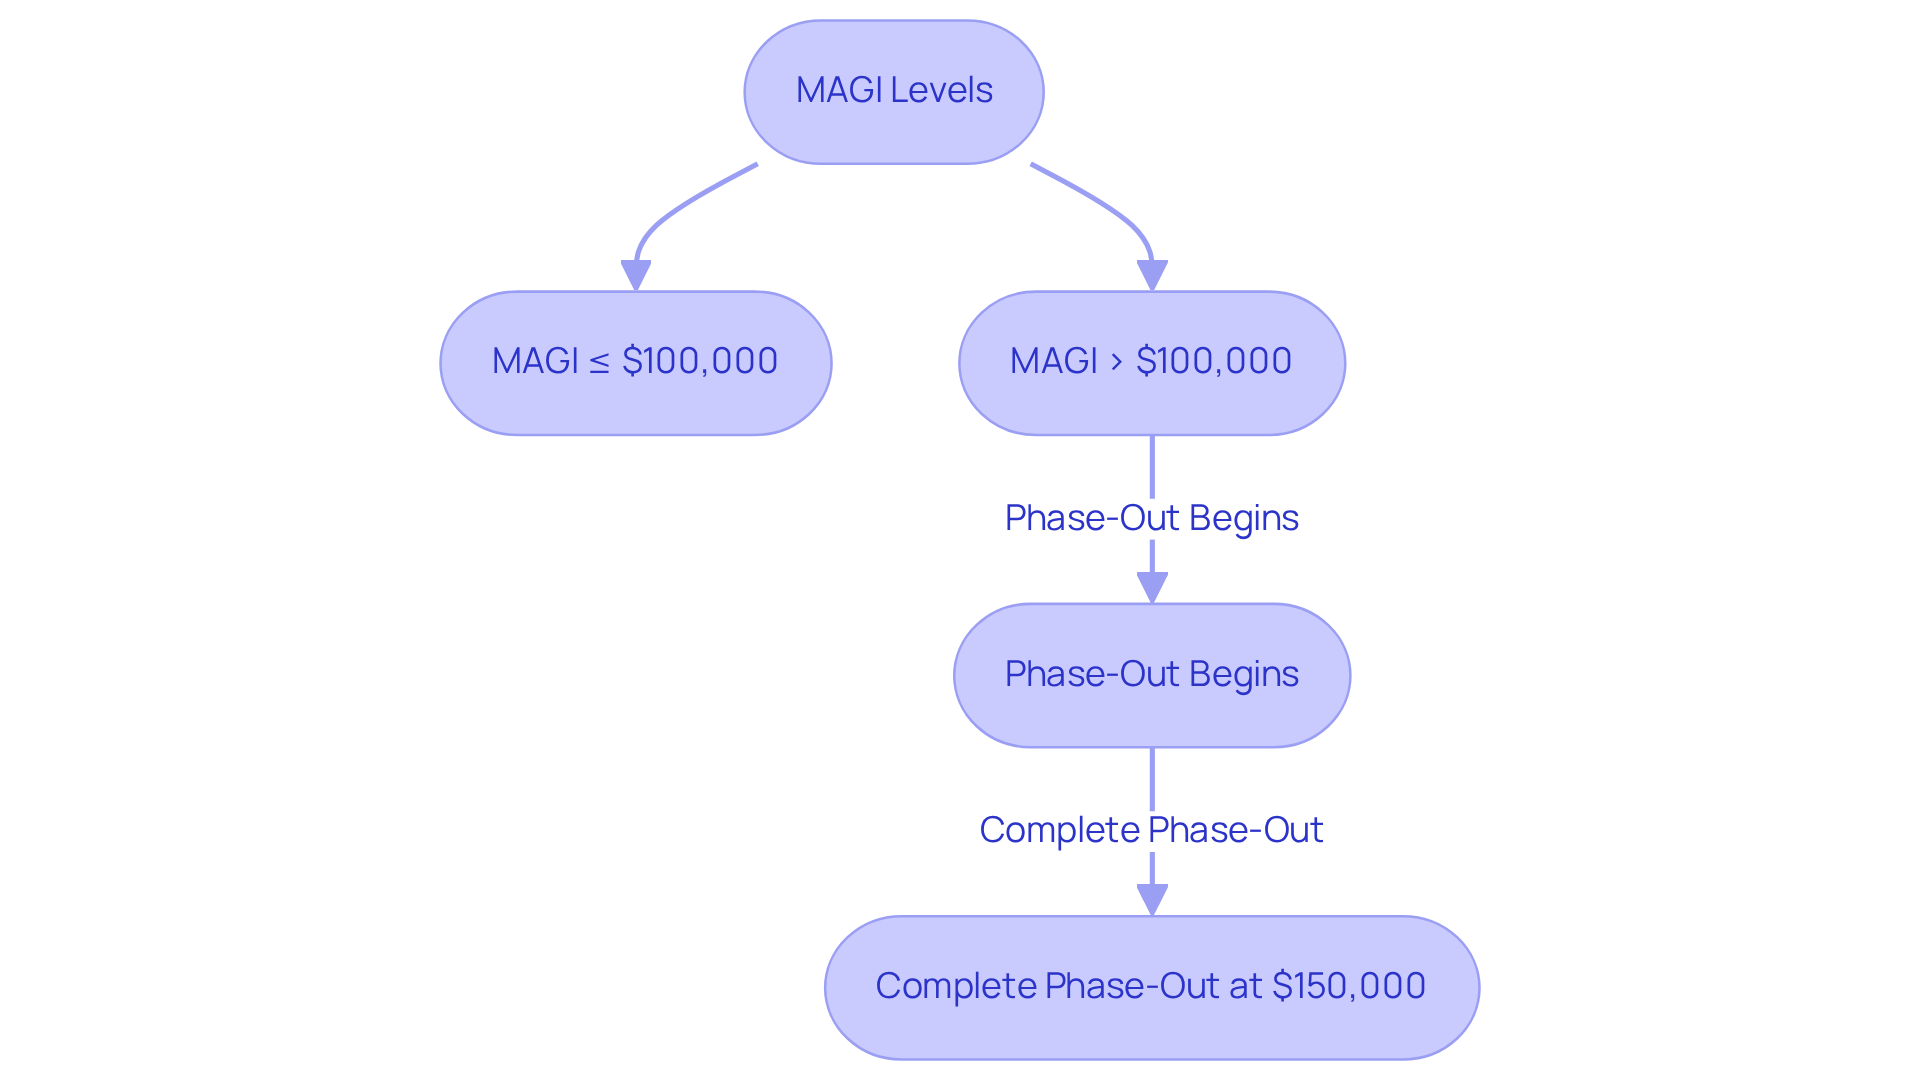
Imagine feeling overwhelmed by the complexities of tax deductions and how they impact your family’s finances. For 2026, the passive loss income limitations will phase out for taxpayers with a Modified Adjusted Gross Income (MAGI) between $100,000 and $150,000. It’s important for families to keep an eye on their earnings levels, as this can help them make informed decisions. Specifically, for every $2 of MAGI exceeding $100,000, the allowance is reduced by $1, leading to a complete phase-out at $150,000.
Consider strategies like tax-loss harvesting, where you sell investments at a loss to balance out gains, or adjusting your investment returns to stay eligible for the full non-active loss allowance. For example, a single taxpayer with a MAGI of $130,000 and a rental deficit of $31,000 can deduct $10,000 against non-passive earnings this year, while $21,000 remains suspended and carried forward.
Many families find it challenging to navigate the complexities of income deductions and tax strategies. By understanding the passive loss income limitations for 2026 and planning ahead, families can navigate their financial journey with greater confidence. Failing to monitor these limits could mean losing out on valuable deductions that could ease financial burdens.
Carrying Over Passive Losses: Strategies for Long-Term Tax Management
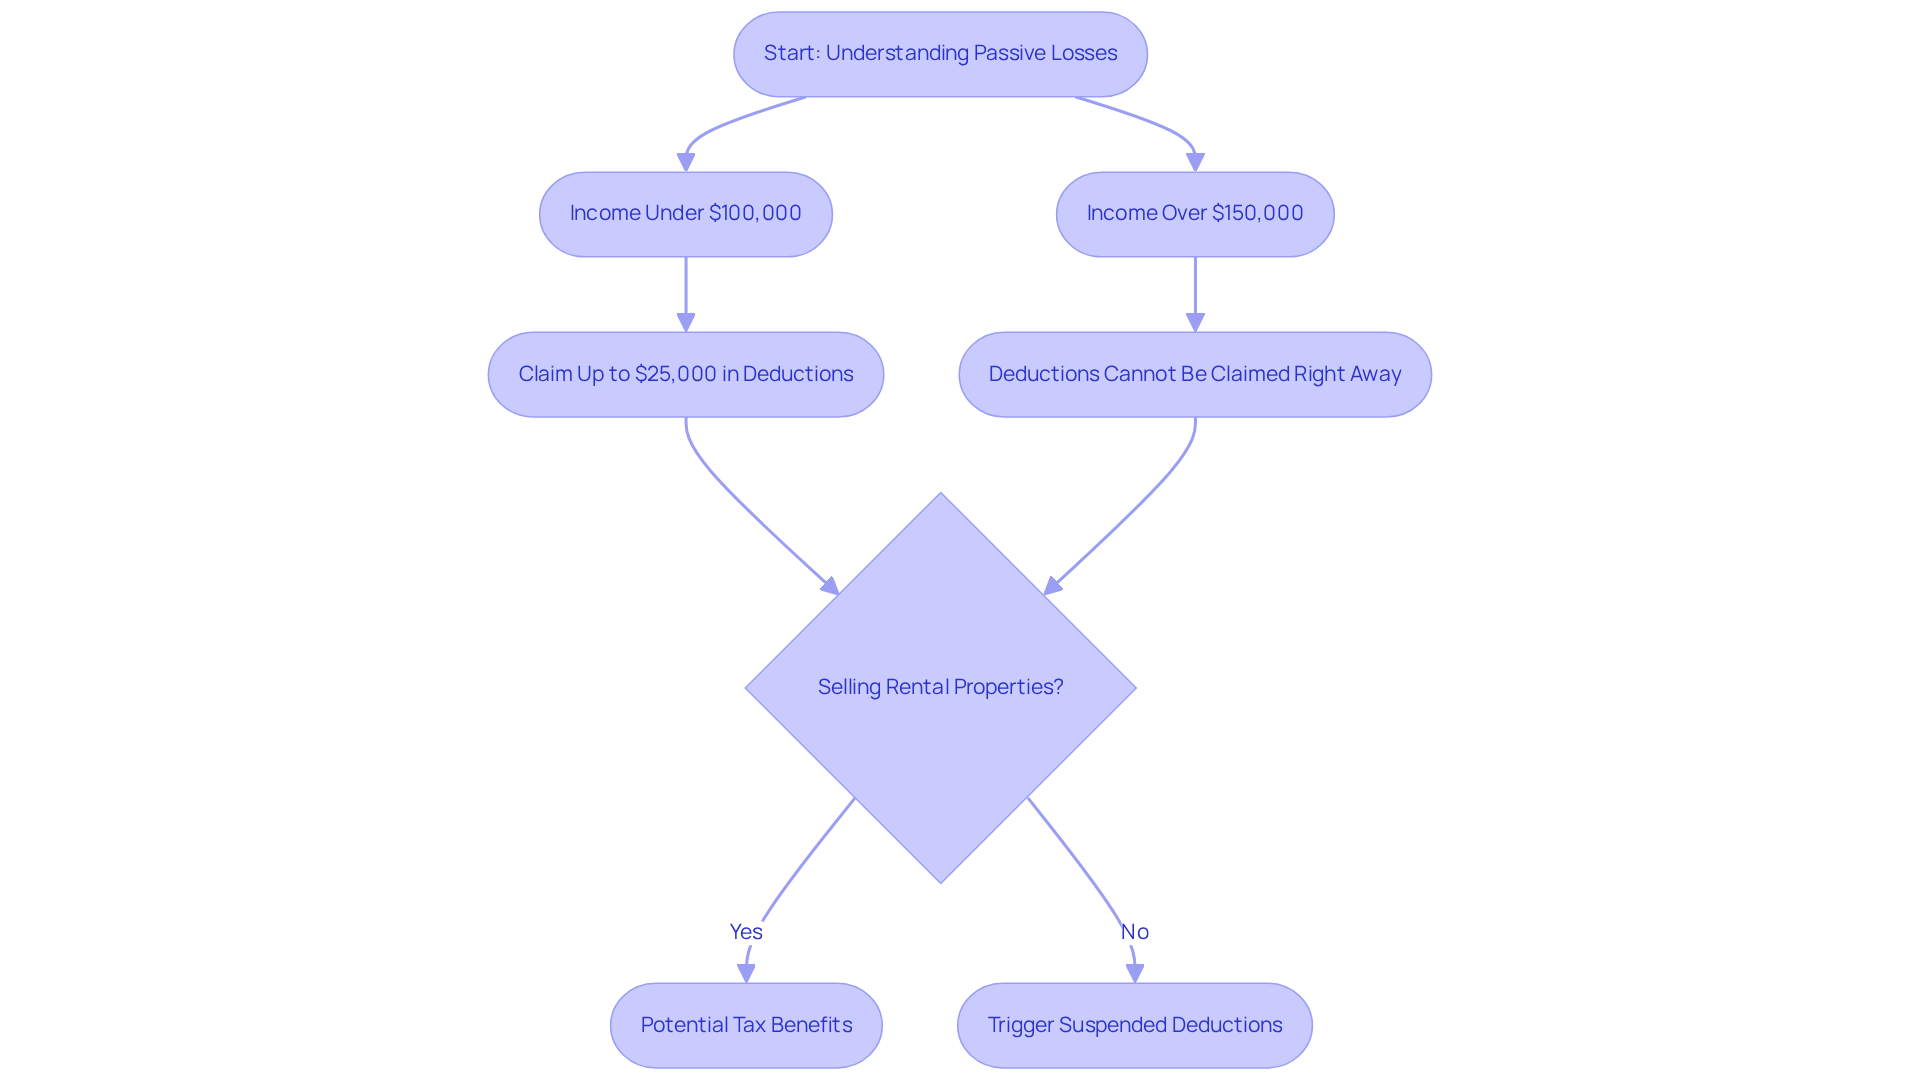
Imagine feeling overwhelmed by tax laws while trying to secure your family’s future – you’re not alone in this journey. If your family can’t fully use your tax losses this year, don’t worry – you can carry them over to future years. These carried-over losses can help balance out future earnings, giving your family a helpful advantage in planning for the long run. For instance, when earnings are under $100,000, households can claim up to $25,000 of non-operating deductions against active earnings, which can greatly lower taxable earnings. But if your income goes over $150,000, those deductions can’t be claimed right away, which means you’ll need to wait until your income allows it.
It’s important to understand how to effectively handle these setbacks. Families should diligently monitor their suspended setbacks and plan accordingly. This means being aware of the consequences of selling rental properties, as doing so can trigger suspended deductions from other properties, allowing for potential tax benefits. If you don’t plan carefully, you could miss out on tax benefits that might lighten your financial load. For example, if a household has $100,000 in deferred non-operating expenses and earns $300,000, they can lower their taxable income to $200,000, leading to nearly $30,000 in tax benefits.
Moreover, qualifying as a real estate professional can stop non-operating deductions from being entirely suspended, allowing households to fully claim these deductions each year. This requires meeting specific criteria, including working at least 750 hours in real estate activities. By implementing these strategies, households can enhance their tax advantages and ensure they are well-prepared for future financial planning.
Consider the case of Allison and Brian, who, as high-income professionals, sought guidance from Bright Advisers to optimize their tax situation. They learned how strategic tax planning could significantly enhance their financial potential, allowing them to secure their children’s future through education funding and gain the ability to retire sooner. Their experience underscores the importance of proactive tax management in achieving financial security and freedom. By understanding these strategies, you can take control of your financial future and ensure your family’s needs are met, today and tomorrow.
Selling Rental Properties: Releasing Suspended Passive Losses
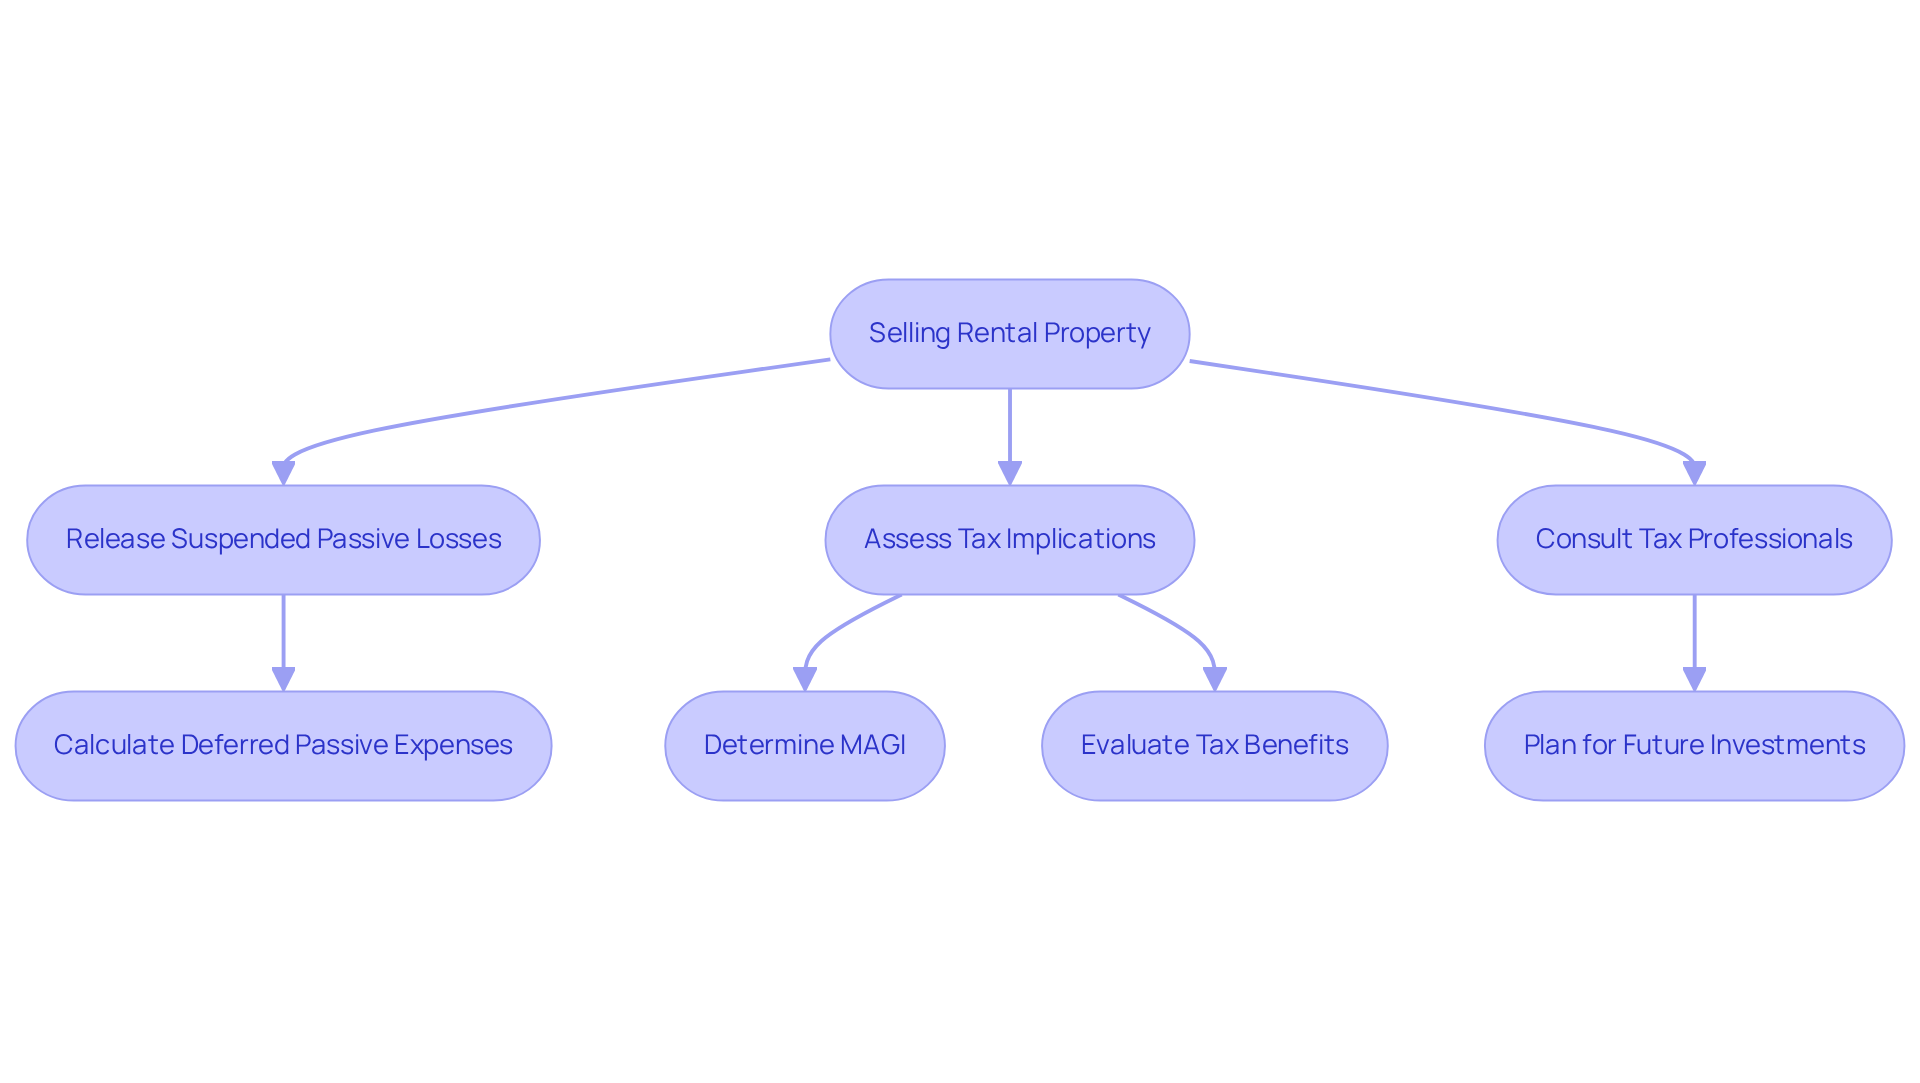
Imagine the relief of finally understanding how to make your rental property work for your family’s future. When households sell rental properties, they can release any suspended non-active deductions linked to those properties, meaning you could lighten your tax load when you sell, giving your family more breathing room. For example, if a household has accumulated $100,000 in deferred passive expenses over several years, selling the property can allow them to subtract this amount from their taxable earnings, potentially leading to significant tax benefits.
In 2026, households with modified adjusted gross income (MAGI) below $100,000 can deduct up to $25,000 in rental deductions against their active income, but passive loss income limitations 2026 will apply as this allowance phases out for incomes exceeding $150,000. It’s important to think about when to sell your rental property to make the most of those potential savings.
Case studies illustrate the importance of strategic planning: one household, Allison and Brian, after years of accumulating $108,000 in suspended losses due to a high MAGI, sold their rental property and successfully deducted all accumulated losses, significantly impacting their tax liability for that year. Through their collaboration with Bright Advisers, they not only optimized their tax situation but also secured their children’s future through education funding and gained the ability to retire sooner. This journey shows how smart tax planning can bring peace of mind, letting families focus on what truly matters – each other.
Additionally, maintaining organized records is essential, as it protects deductions and simplifies compliance with IRS regulations. Families should consult with tax professionals, like those at Bright Advisers, to navigate these complexities and ensure they are taking full advantage of available deductions when selling rental properties. Please note that past performance does not guarantee future results, and all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Interested families may join our current client waitlist for future opportunities.
Passive Losses vs. Capital Gains: Navigating Tax Implications
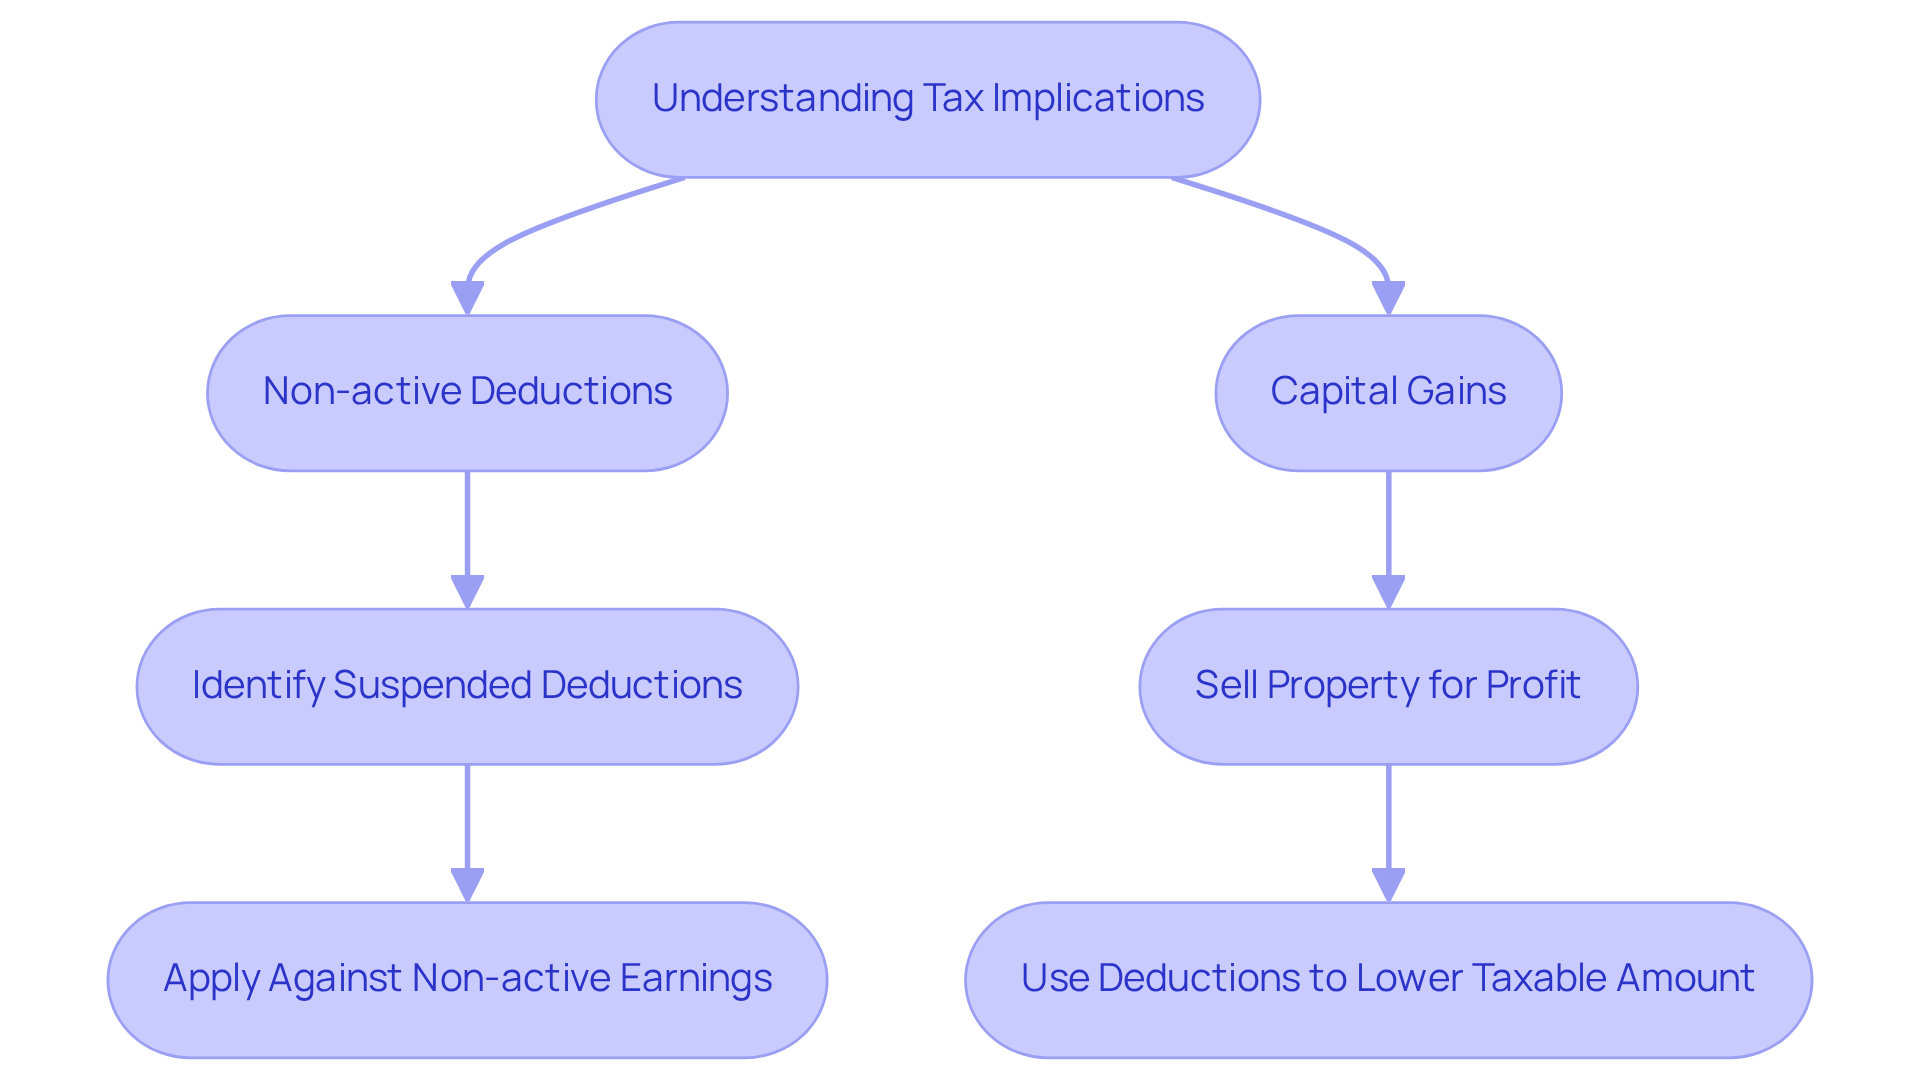
Imagine navigating the complexities of tax regulations while trying to secure your family’s financial future. Non-active deductions can only counterbalance non-active earnings, and capital gains are treated differently under tax laws. It’s important to understand that non-operating deductions can’t directly offset capital gains.
If your family sells a property for a profit, you can use any suspended non-active deductions to help lower the taxable amount. This can be a great way to save on taxes. For instance, if your household has $35,000 in combined deferred deductions from two rental properties and sells one for a profit, you can apply those deductions against that profit, effectively reducing your taxable income.
This interaction between non-active deductions and capital gains highlights the importance of strategic tax planning. Without proper planning, families may miss out on significant tax savings. Additionally, it’s essential to recognize that suspended non-deductible expenses carry forward indefinitely until they can be applied against non-taxable earnings or released through the sale of the property causing the expense.
By grasping these important details, you can feel more confident in your tax planning, even as laws change. Remember, we’re here for you as you navigate this journey.
Avoiding Common Mistakes with Passive Loss Limitations: Best Practices for Investors
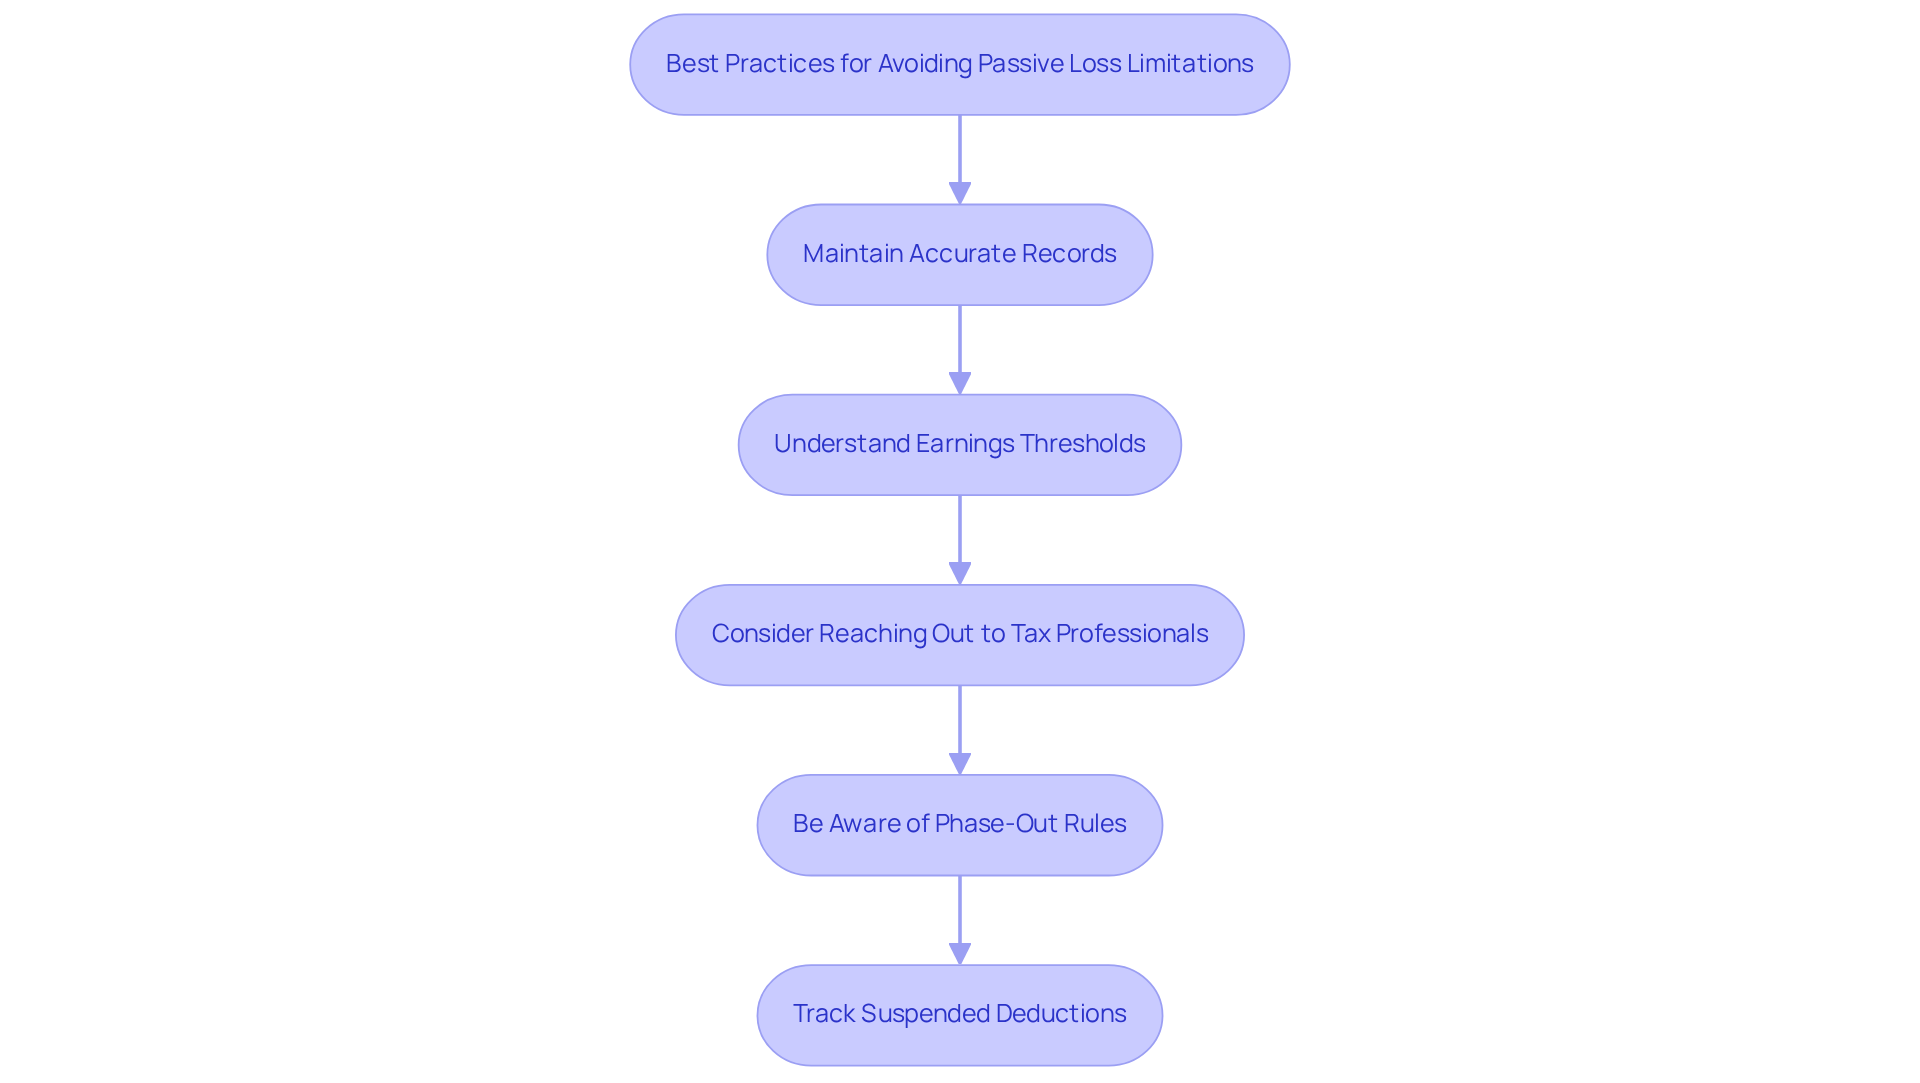
Imagine trying to manage your family’s finances while juggling the complexities of tax regulations – it’s a challenge many parents face. It’s important for families to take proactive steps to avoid common pitfalls that can arise from passive loss income limitations 2026. Here are some best practices to help you navigate these challenges with confidence:
- Maintain Accurate Records: Keeping detailed records of your rental activities is crucial. Documenting the time you spend and the decisions you make can substantiate your claims of active participation. Remember, the IRS requires contemporaneous time records to support these claims.
- Understand Earnings Thresholds: Familiarize yourself with the earnings thresholds for the $25,000 allowance. If you actively participate, you can deduct up to $25,000 of rental expenses against ordinary income. However, this allowance phases out at modified adjusted gross income (MAGI) levels of $100,000 and disappears entirely at $150,000.
- Consider Reaching Out to Tax Professionals: Engaging with tax professionals can help your family navigate IRS regulations and optimize your tax strategies. They can offer valuable insights on the consequences of non-active deductions and ensure you stay compliant.
- Be Aware of Phase-Out Rules: Understanding how phase-out rules affect your ability to claim deductions is essential. For married couples filing separately, the allowance is halved to $12,500, with a stricter phase-out range.
- Track Suspended Deductions: Suspended deductions can carry forward indefinitely, so it’s essential to monitor these on Form 8582. This way, you can take advantage of these deductions in upcoming tax years when you might have non-active income.
By following these best practices, you can feel more confident in navigating the complexities of passive loss income limitations 2026, which will help ensure your family’s financial well-being.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the complexities of tax regulations. When families understand these limitations, they can make choices that truly benefit their financial well-being. Using strategies like the $25,000 passive loss allowance can help families manage their investments more effectively and ease their tax burdens.
We’ve shared important insights, like:
- Tracking your modified adjusted gross income
- Understanding how selling rental properties can affect your finances
Reaching out to professionals at Bright Advisers can provide families with the personalized support they need to navigate these tax challenges.
Understanding these limitations is key to feeling secure in your financial decisions. Taking charge of your financial journey today can open doors to a brighter tomorrow for your family.
Frequently Asked Questions
What are passive loss income limitations?
Passive loss income limitations refer to IRS rules that restrict the ability to deduct losses from businesses or investments in which you are not actively involved. For 2026, these limitations allow you to offset passive losses only against earnings from other passive activities, not against regular wages or portfolio returns.
How can families benefit from understanding passive loss income limitations?
By understanding these limitations, families can avoid unexpected tax surprises and potentially carry over excess losses to future years, which may provide tax advantages when their activities start generating income again.
What is the modified adjusted gross income (MAGI) threshold for rental deductions?
Families with a MAGI below $150,000 can deduct up to $25,000 in rental deductions against non-passive earnings. This allowance phases out entirely at a MAGI of $200,000.
What is the grouping election in relation to passive loss income limitations?
The grouping election allows multiple rental activities to be treated as a single activity for tax purposes, which can help meet participation thresholds. However, it is generally irrevocable, so professional advice is recommended before making such decisions.
Who qualifies as a real estate professional under IRS rules?
To qualify as a real estate professional, an individual must dedicate more than half of their working hours to real estate activities and participate in these activities for at least 750 hours each year. This status allows them to offset rental losses against other income.
What happens to the $25,000 passive deduction allowance for families with a MAGI over $100,000?
The $25,000 passive deduction allowance begins to phase out for families with a MAGI over $100,000 and is completely eliminated for those with a MAGI above $150,000.
Can short-term rental losses be deducted without qualifying as a real estate professional?
Yes, short-term rentals, such as those from Airbnb, are not classified as passive activities by the IRS, allowing individuals to deduct losses without needing to qualify as a real estate professional, provided they are actively involved.
How does Bright Advisers assist families with passive loss income limitations?
Bright Advisers provides personalized financial planning and advanced technology to help families structure their portfolios effectively, manage investments, and navigate the complexities of passive loss income limitations to achieve their long-term financial objectives.
List of Sources
- Bright Advisers: Tailored Strategies for Navigating Passive Loss Income Limitations
- Passive Activity Loss Rules for Real Estate 2026 (https://senecacostseg.com/feeds/blog/passive-activity-loss-rules-real-estate-2026)
- Passive Activity Loss Rules 2026 | TS CPA (https://tscpatax.com/articles/passive-activity-loss-rules-2026)
- 2026 Passive Loss Limitation Changes: A Complete Guide for Real Estate Investors & Business Owners – Uncle Kam (https://unclekam.com/tax-strategy-blog/2026-passive-loss-limitation-changes-a-complete-guide-for-real-estate-investors-business-owners)
- Passive Activity Loss Rules and Form 8582 | Taxstra (https://taxstra.com/strategies/passive-activity-loss-rules)
- Passive Activity Loss Limitations | Cary Millar, PC (https://carymillar.com/passive-activity-loss-limitations)
- Understanding Passive Activity Loss Rules: Key Regulations for 2026
- Untangling passive activity rules for business and rentals (https://natptax.com/news-insights/blog/untangling-passive-activity-rules-for-business-and-rentals?srsltid=AfmBOoqZjOGPLO9eCoJnfHF9Gpxpuxa3OAVrT9K8AAT8EULeLxyZwn0H)
- IRS Form 8582: Calculating Passive Activity Losses for Real Estate (https://turbotax.intuit.com/tax-tips/rental-property/irs-form-8582-calculating-passive-activity-losses-for-real-estate/c71Jm0iM7)
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Identifying Exceptions to Passive Loss Limitations: Opportunities for Investors
- Real Estate Professional Status: A Tax Shelter for Physicians (https://cerebraltaxadvisors.com/blog/real-estate-professional-status)
- Passive loss limitations on rental real estate – Journal of Accountancy (https://journalofaccountancy.com/issues/2023/sep/passive-loss-limitations-on-rental-real-estate)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- $25,000 Passive Loss Allowance: Maximizing Your Tax Benefits
- What Is the $25,000 Passive Loss Allowance? – Hall CPA (https://therealestatecpa.com/blog/what-is-the-25000-passive-loss-allowance)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Passive Activity Loss Limitations | Cary Millar, PC (https://carymillar.com/passive-activity-loss-limitations)
- Material Participation: Essential Criteria for Claiming Passive Loss Deductions
- Understanding Material Participation Rules | SKP Accountants & Advisors, LLC (https://skpadvisors.com/2026/04/21/understanding-material-participation-rules)
- Real Estate Tax Rules Explained: Material Participation, Qualified… (https://doeren.com/viewpoint/real-estate-tax-rules-explained-material-participation-qualified-business-income-and-net-investment-income-tax)
- Meeting the 100-Hour Significant Participation Activity Test (https://thetaxadviser.com/issues/2015/oct/meeting-100-hour-significant-participation-activity-test)
- Material Participation Short Term Rental: 7 IRS Tests (2026) (https://gowithsurge.com/blog/material-participation-short-term-rental)
- Topic no. 425, Passive activities – Losses and credits | Internal Revenue Service (https://irs.gov/taxtopics/tc425)
- Income Levels and Passive Loss Phase-Out: What Investors Need to Know
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Passive Activity Loss Rules for Real Estate 2026 (https://senecacostseg.com/feeds/blog/passive-activity-loss-rules-real-estate-2026)
- Passive Activity Loss Limitations | Cary Millar, PC (https://carymillar.com/passive-activity-loss-limitations)
- Passive loss limitations on rental real estate – Journal of Accountancy (https://journalofaccountancy.com/issues/2023/sep/passive-loss-limitations-on-rental-real-estate)
- Carrying Over Passive Losses: Strategies for Long-Term Tax Management
- Strategies to Use Suspended Passive Losses from Rental Real Estate (https://therealestatecpa.com/blog/strategies-suspended-passive-losses-rental-real-estate)
- Passive activity loss: Overview and FAQs (https://tax.thomsonreuters.com/en/glossary/passive-activity-loss)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Selling Rental Properties: Releasing Suspended Passive Losses
- What Happens to Suspended Passive Losses When You Sell (Or Lose) Your Rental Property? (https://nolo.com/landlord-tenant/what-happens-suspended-passive-losses-sell-rental-property-foreclosure.html)
- Passive Activity Loss Rules for Rental Property: What Real Estate Investors Need to Know (2025) (https://madrasaccountancy.com/blog-posts/passive-activity-loss-rules-for-rental-property-what-real-estate-investors-need-to-know-2025)
- Suspended Passive Losses on Rental Property (https://pimtax.com/suspended-passive-losses-on-rental-property)
- Selling Your Rental Property- Passive Losses And NIIT (https://wcginc.com/kb-rental-property/selling-your-rental-property-passive-losses-and-niit)
- Disposing of passive activities (https://thetaxadviser.com/issues/2017/apr/disposing-passive-activities)
- Passive Losses vs. Capital Gains: Navigating Tax Implications
- Topic no. 425, Passive activities – Losses and credits | Internal Revenue Service (https://irs.gov/taxtopics/tc425)
- Understanding Passive Activity Losses: A Comprehensive Guide|Greg O’Brien, CPA (https://anomalycpa.com/post/passive-activity-loss-guide)
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Disposing of passive activities (https://thetaxadviser.com/issues/2017/apr/disposing-passive-activities)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Avoiding Common Mistakes with Passive Loss Limitations: Best Practices for Investors
- Passive Activity Loss Rules and Form 8582 | Taxstra (https://taxstra.com/strategies/passive-activity-loss-rules)
- Real Estate Professional Passive Loss Rules 2026 – Uncle Kam (https://unclekam.com/tax-strategy-blog/real-estate-professional-passive-loss-rules-2026)
- Passive loss limitations on rental real estate – Journal of Accountancy (https://journalofaccountancy.com/issues/2023/sep/passive-loss-limitations-on-rental-real-estate)
- Passive Activity and Passive Activity Loss Limitations in Real Estate (https://landlordstudio.com/blog/passive-activity-and-passive-activity-loss-limitations-in-real-estate)
- Topic no. 425, Passive activities – Losses and credits | Internal Revenue Service (https://irs.gov/taxtopics/tc425)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading