

Key Highlights
- Bright Advisers helps families navigate tax deduction complexities related to rental properties.
- Families can deduct up to $25,000 of passive losses against non-passive income, subject to limitations based on modified adjusted gross income (MAGI).
- In 2026, the deduction phases out for MAGI exceeding $100,000 and is eliminated at $150,000.
- Proper tax planning can help families retain valuable deductions and reduce tax liabilities.
- Material participation criteria include participating in rental activities for over 500 hours or being the sole participant for more than 100 hours.
- Families can aggregate multiple rental properties for tax purposes to enhance deduction potential.
- Documentation of rental activities is crucial for substantiating claims for deductions and avoiding audit issues.
- Past performance does not guarantee future results; all advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Introduction
Imagine feeling overwhelmed by tax deductions while trying to provide for your family. Navigating the intricate world of tax deductions can be daunting for young families, especially with the impending changes to passive loss limitations in 2026. Many families feel overwhelmed by the complexities of tax deductions, especially with upcoming changes. But with the right knowledge, families can turn these challenges into opportunities for financial relief. Understanding these rules is crucial, as they can significantly impact how families manage their rental properties and maximize tax benefits. Together, we can explore ten key insights on passive loss limitations that can help your family thrive amidst the evolving tax landscape.
Bright Advisers: Tailored Strategies for Navigating Passive Loss Limitations
Imagine navigating the complexities of tax deductions while trying to secure your family’s future – it’s a challenge many young parents face. Bright Advisers utilizes personalized strategies to help households comprehend and navigate the intricacies of deduction restrictions. By concentrating on the distinct financial circumstances of families with young children, the firm assists clients in effectively managing their rental properties while enhancing tax advantages. For instance, families actively engaging in rental real estate can deduct up to $25,000 of passive losses against non-passive income, but this benefit is subject to passive loss limitations 2026 if their modified adjusted gross income (MAGI) exceeds $150,000. This means that if your income exceeds $150,000, you could lose out on valuable deductions, so planning is crucial.
In one case study, Allison and Brian, a couple with substantial incomes from their careers, sought guidance from Bright Advisers to maximize their financial potential through proper tax planning. They were unaware of the financial opportunities they were missing due to inadequate tax strategies. Working together, they discovered ways to save on taxes, ensuring their kids would have the education they deserve and even paving the way for an earlier retirement. This case highlights the importance of tax planning in minimizing tax liabilities and increasing wealth accumulation potential.
Families utilizing short-term rentals, such as those listed on platforms like Airbnb, must determine their level of material participation to classify these activities correctly for tax purposes. This classification can significantly impact their tax liabilities, underscoring the importance of tailored financial strategies.
Moreover, households that qualify as real estate professionals and actively engage in rental activities can classify those activities as non-passive, which helps them navigate the passive loss limitations 2026 and provides greater flexibility in managing their tax situations. Bright Advisers utilizes advanced technology to deliver personalized insights and strategies that align with each household’s financial objectives, ensuring they can navigate these complexities effectively. Our extensive financial planning services encompass tax strategies, risk management, and legacy planning, all designed to assist households in achieving their financial goals. With the right guidance, you can turn potential tax liabilities into opportunities for your family’s growth and security.
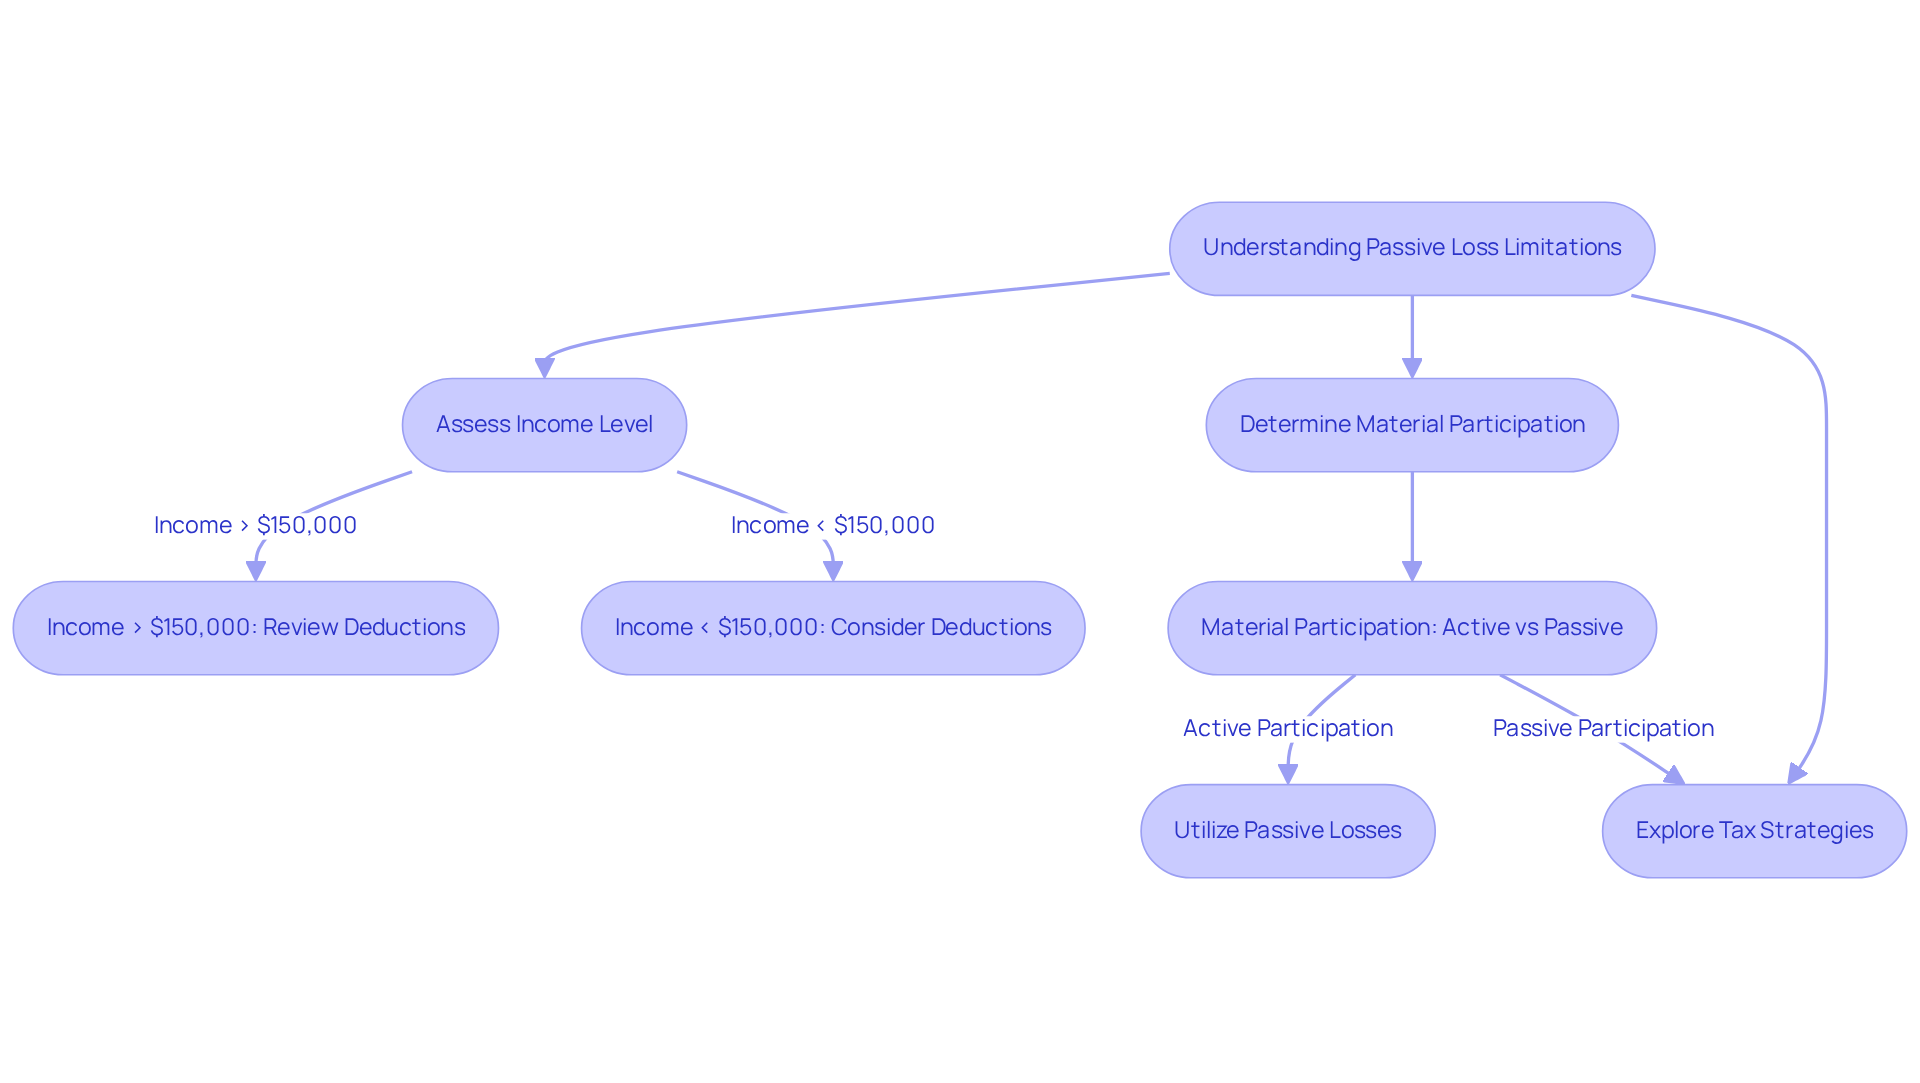
Understanding the 2026 Passive Activity Loss Rules: Key Changes and Implications
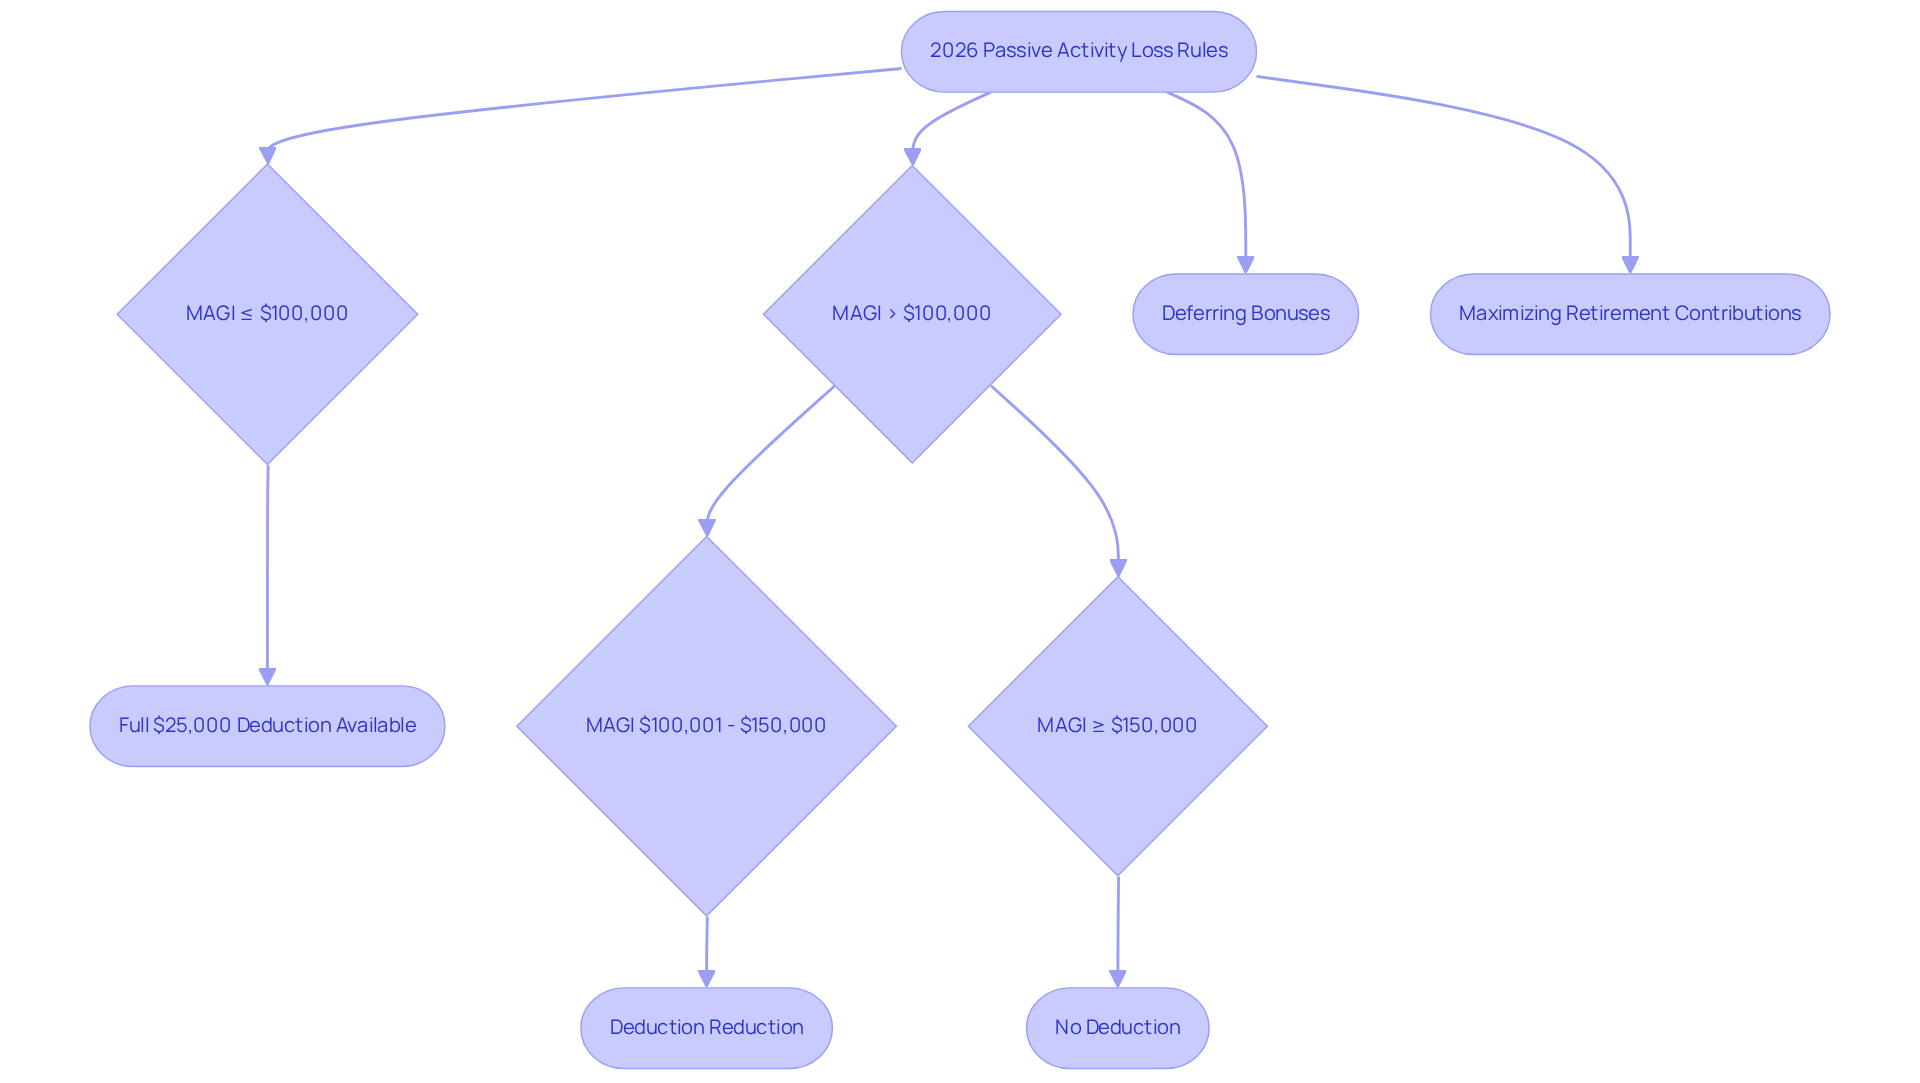
Imagine the worry of unexpected tax bills when you’re already juggling family expenses. In 2026, the passive loss limitations will change how you can claim expenses from rental properties. The $25,000 deduction for rental real estate setbacks will start to phase out for modified adjusted gross incomes (MAGI) exceeding $100,000, completely vanishing at $150,000. For instance, if your household has a MAGI of $130,000, you can only deduct $10,000 of your rental losses, leaving $21,000 suspended for future years. Understanding the passive loss limitations 2026 is important so you can plan ahead and avoid surprises come tax time.
But don’t worry, there are ways to keep your deductions intact and ease your financial stress. For example, deferring bonuses or maximizing retirement contributions can help keep your MAGI below those critical thresholds. One family recorded their property management efforts to qualify for material participation, allowing them to deduct significant rental losses against their W-2 income, leading to real tax savings.
Grasping the implications of these rules, including passive loss limitations 2026, is essential for families aiming to navigate the complexities of rental property investments and tax deductions effectively. By staying informed and planning strategically, you can feel more secure and prepared for your financial future, especially with the changes coming in 2026.
Material Participation: Criteria for Maximizing Passive Loss Deductions
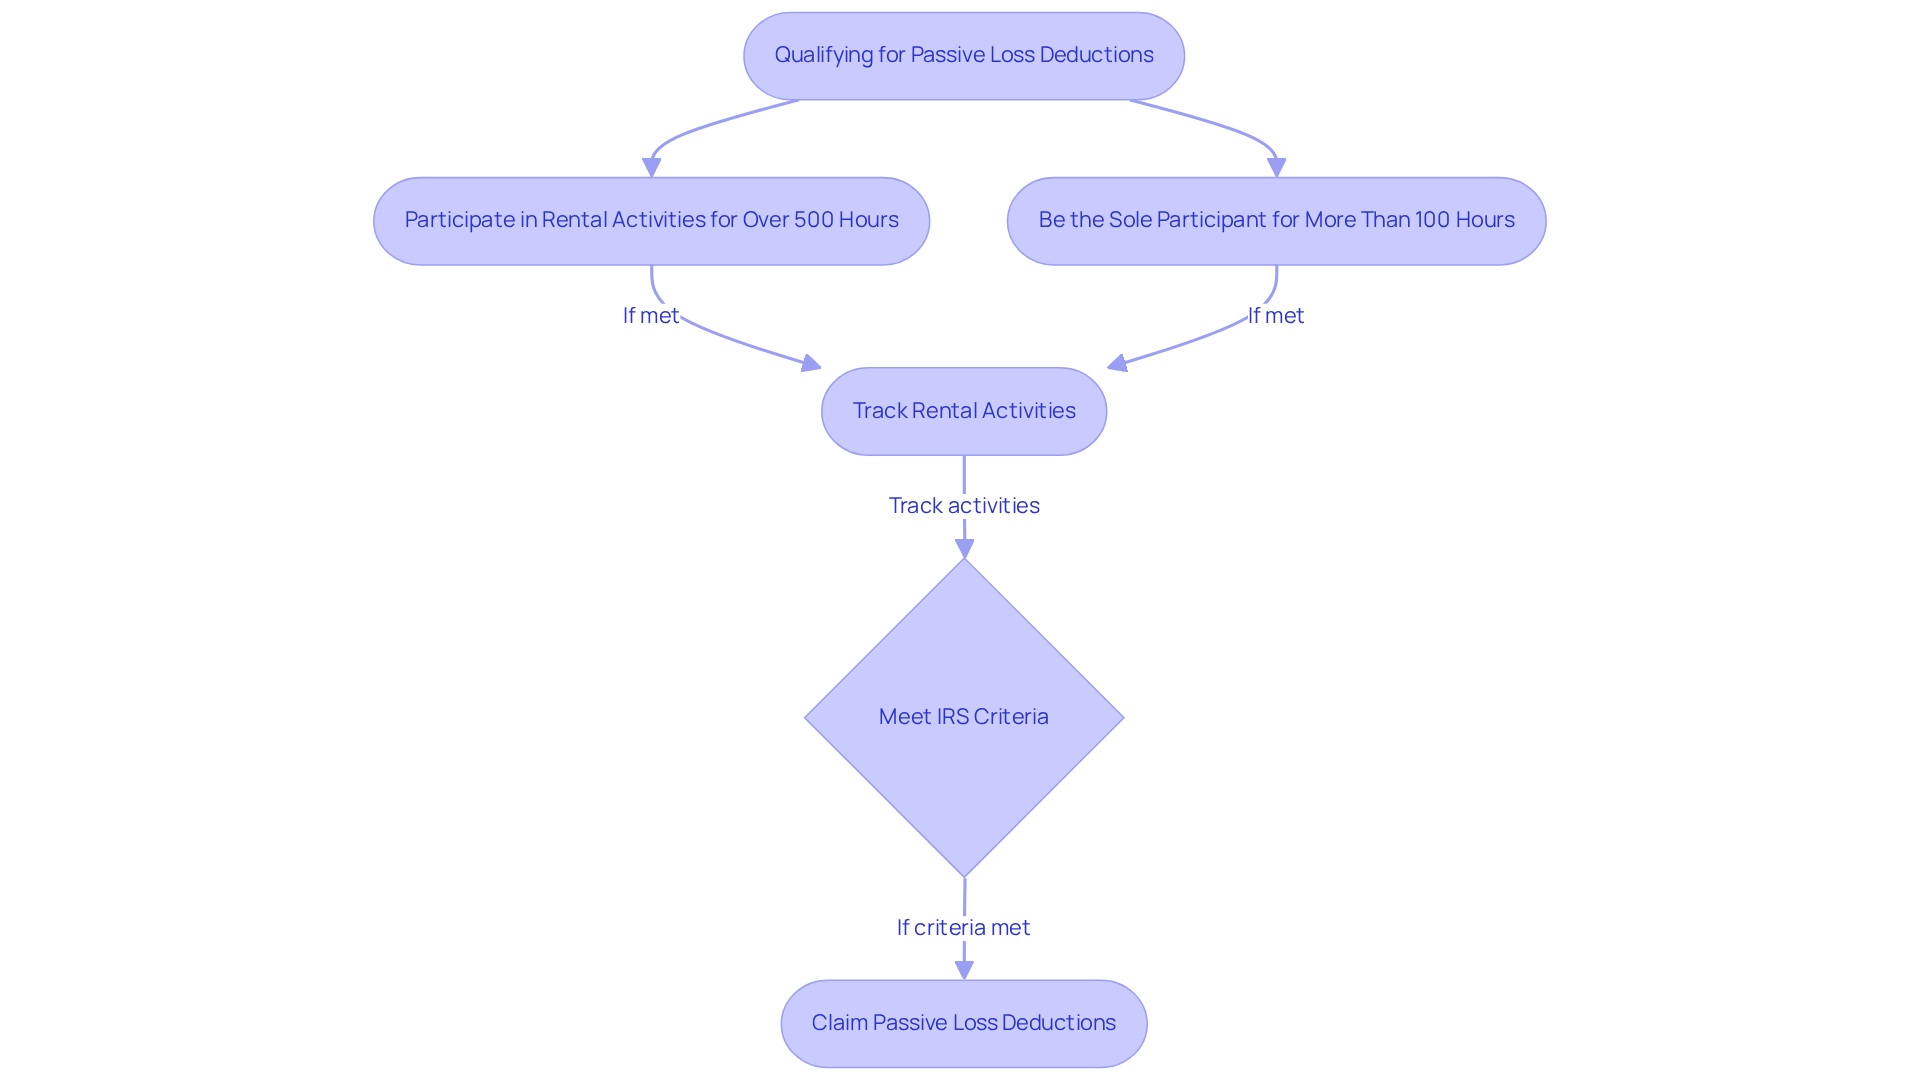
Imagine feeling confident about your financial decisions while juggling the demands of family life. It’s important to know that to qualify for passive loss limitations 2026, you’ll need to meet certain IRS criteria. This includes:
- Participating in rental activities for over 500 hours in a year
- Being the sole participant for more than 100 hours
For example, Jay and Emma, with Bright Advisers by their side, carefully tracked their rental activities, helping them back up their claims and get the most out of their deductions. This thoughtful approach helped them manage their finances better and eased their worries about money.
Similarly, Emily and Mark recognized the importance of tracking their involvement in rental activities. By doing so, they felt empowered to make informed career choices that aligned with their personal aspirations. By partnering with Bright Advisers, families can ensure they’re well-prepared to meet IRS requirements, particularly regarding passive loss limitations 2026, while enhancing their overall financial strategy. Navigating IRS requirements can feel daunting, especially when you’re trying to balance family life and finances. But remember, maintaining detailed records as you go is more credible than trying to piece everything together at year-end.
Additionally, it’s essential to keep in mind that past performance doesn’t guarantee future results. All advisory services are provided through Lifeworks Advisors, a registered investment adviser. With the right support, you can turn financial stress into a manageable part of your family’s journey.
Income Limits for Passive Loss Deductions: What Investors Need to Know
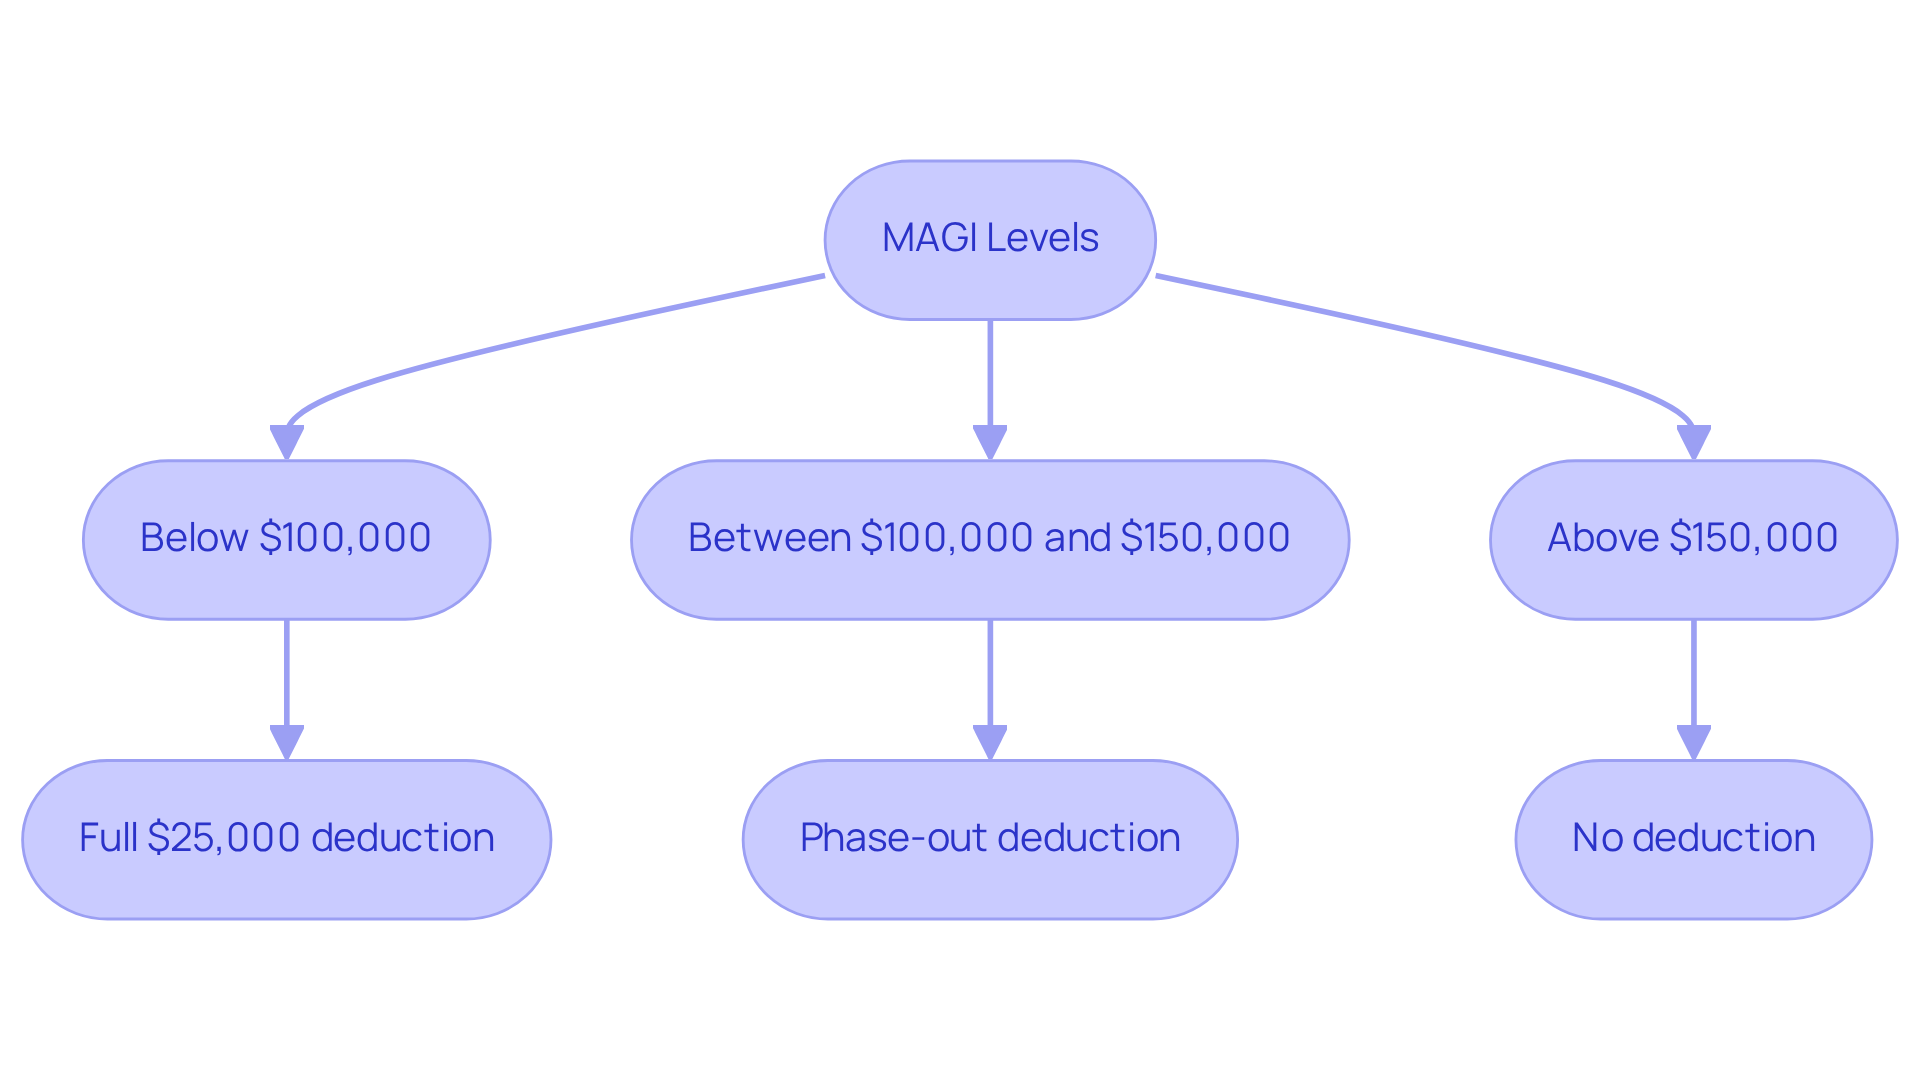
Imagine feeling confident about your family’s financial future, even when faced with complex tax rules. Many families feel overwhelmed by the complexities of tax deductions and how they relate to their income. The passive loss limitations 2026 indicate that the highest deduction for rental real estate activities is $25,000. However, it’s important to understand how your income can impact your ability to take advantage of tax deductions when investing in rental properties. The deduction begins to phase out for modified adjusted gross income (MAGI) exceeding $100,000, reducing by $1 for every $2 over this threshold, and is completely eliminated at a MAGI of $150,000.
For instance, a household with a MAGI of $130,000 can only deduct $10,000 of their non-active deductions against their non-active income due to the phase-out regulations. Additionally, families can combine passive losses from multiple rental properties when calculating their total loss for the year, which can be beneficial for those managing several investments, especially considering the passive loss limitations 2026.
To fully benefit from the $25,000 deduction, families need to be hands-on with their rental properties, making choices like selecting tenants and overseeing repairs. This requirement promotes active participation in property management, enabling families to benefit from tax deductions while still utilizing property management services. By understanding these income limits and regulations, your family can unlock valuable tax advantages from your rental investments.
Exceptions to Passive Activity Loss Rules: Unlocking Additional Deductions
Imagine facing tax season, feeling overwhelmed by the complexities of deductions and write-offs that could ease your financial burden. Certain exceptions to the passive loss limitations 2026 can actually help you find relief!
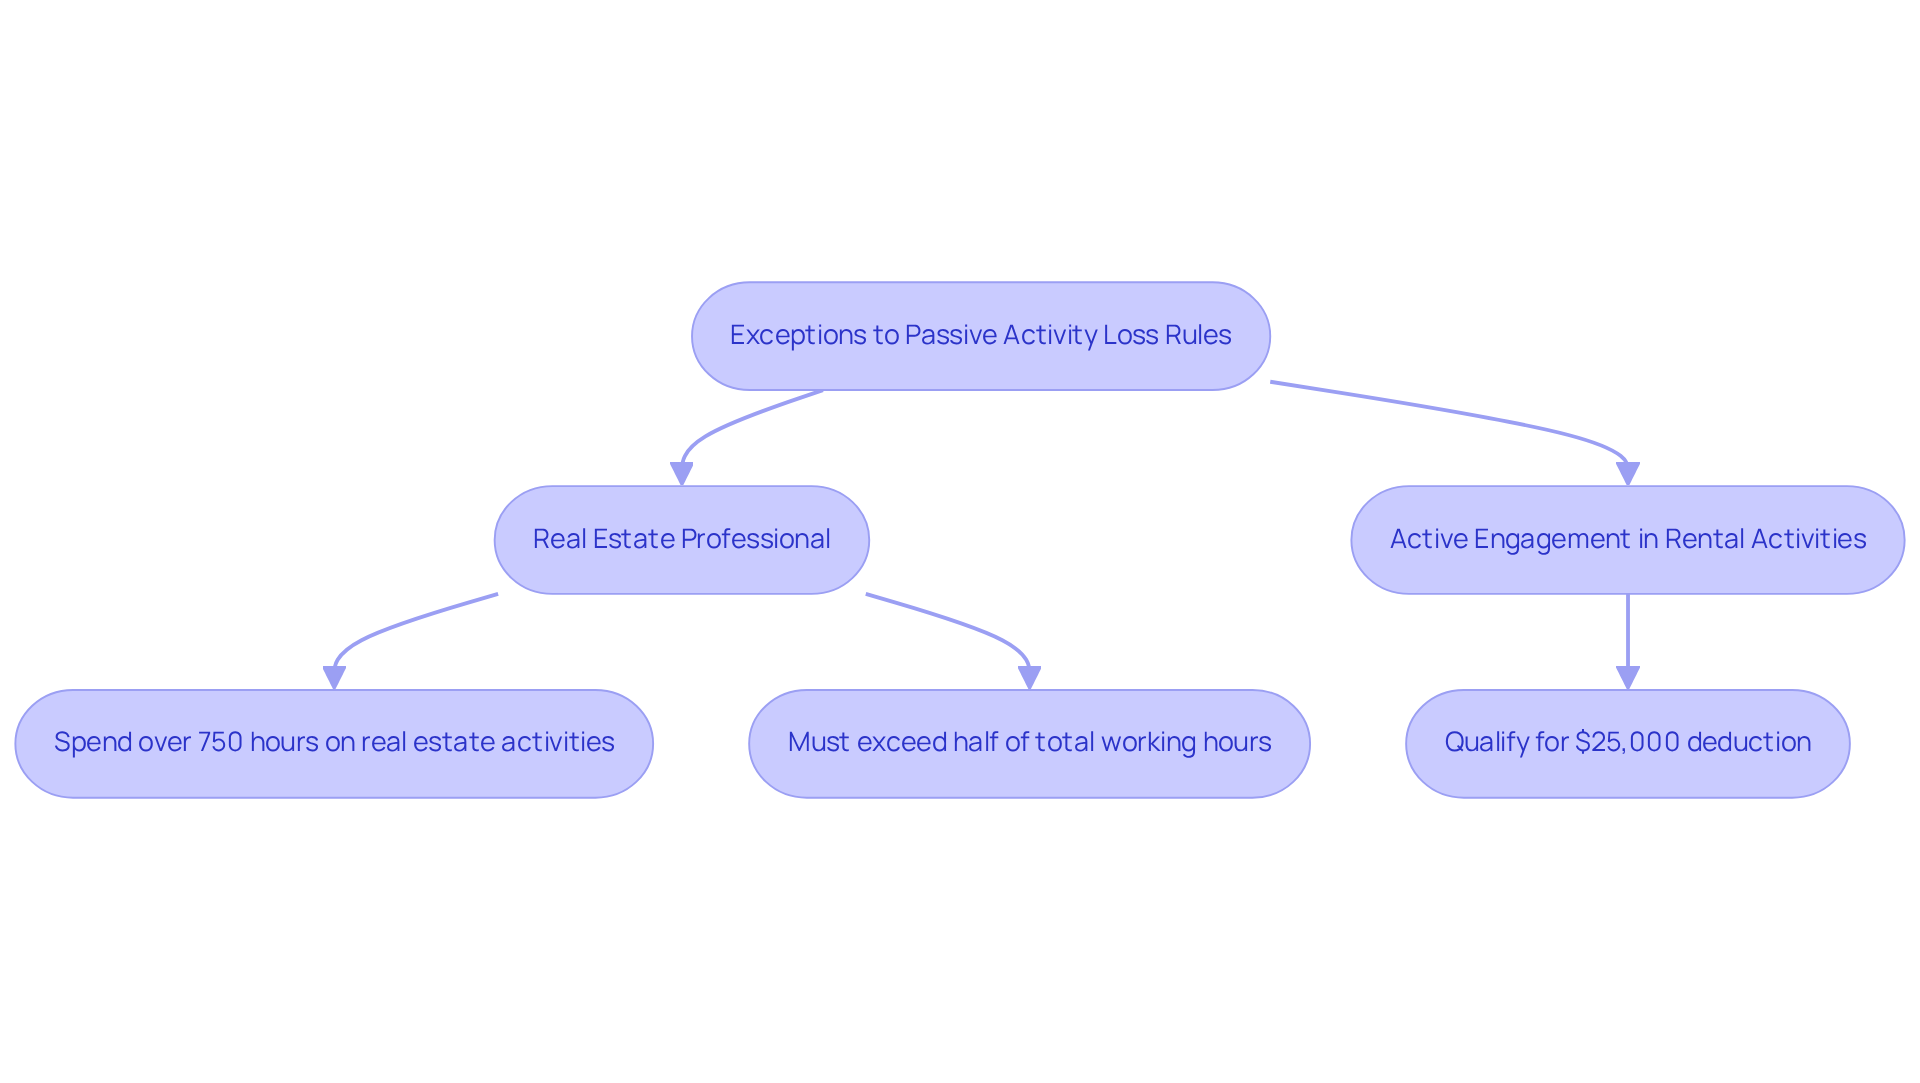
For instance, if you qualify as a real estate professional, you can subtract all your rental expenses from your non-passive income, which is a huge relief! This status requires you to spend over 750 hours on real estate activities, and it must exceed half of your total working hours for the year.
Additionally, if you actively engage in rental activities, you might qualify for a $25,000 deduction, even if your income surpasses the standard thresholds. Take Rachel and her spouse, for example. They incurred over $315,000 in rental deficits, allowing them to significantly lower their tax obligation by utilizing these exceptions.
Understanding the passive loss limitations 2026 can empower your family to make informed decisions, ensuring you keep more of what you earn for the things that truly matter.
Selling Rental Properties: Managing Suspended Passive Losses Effectively
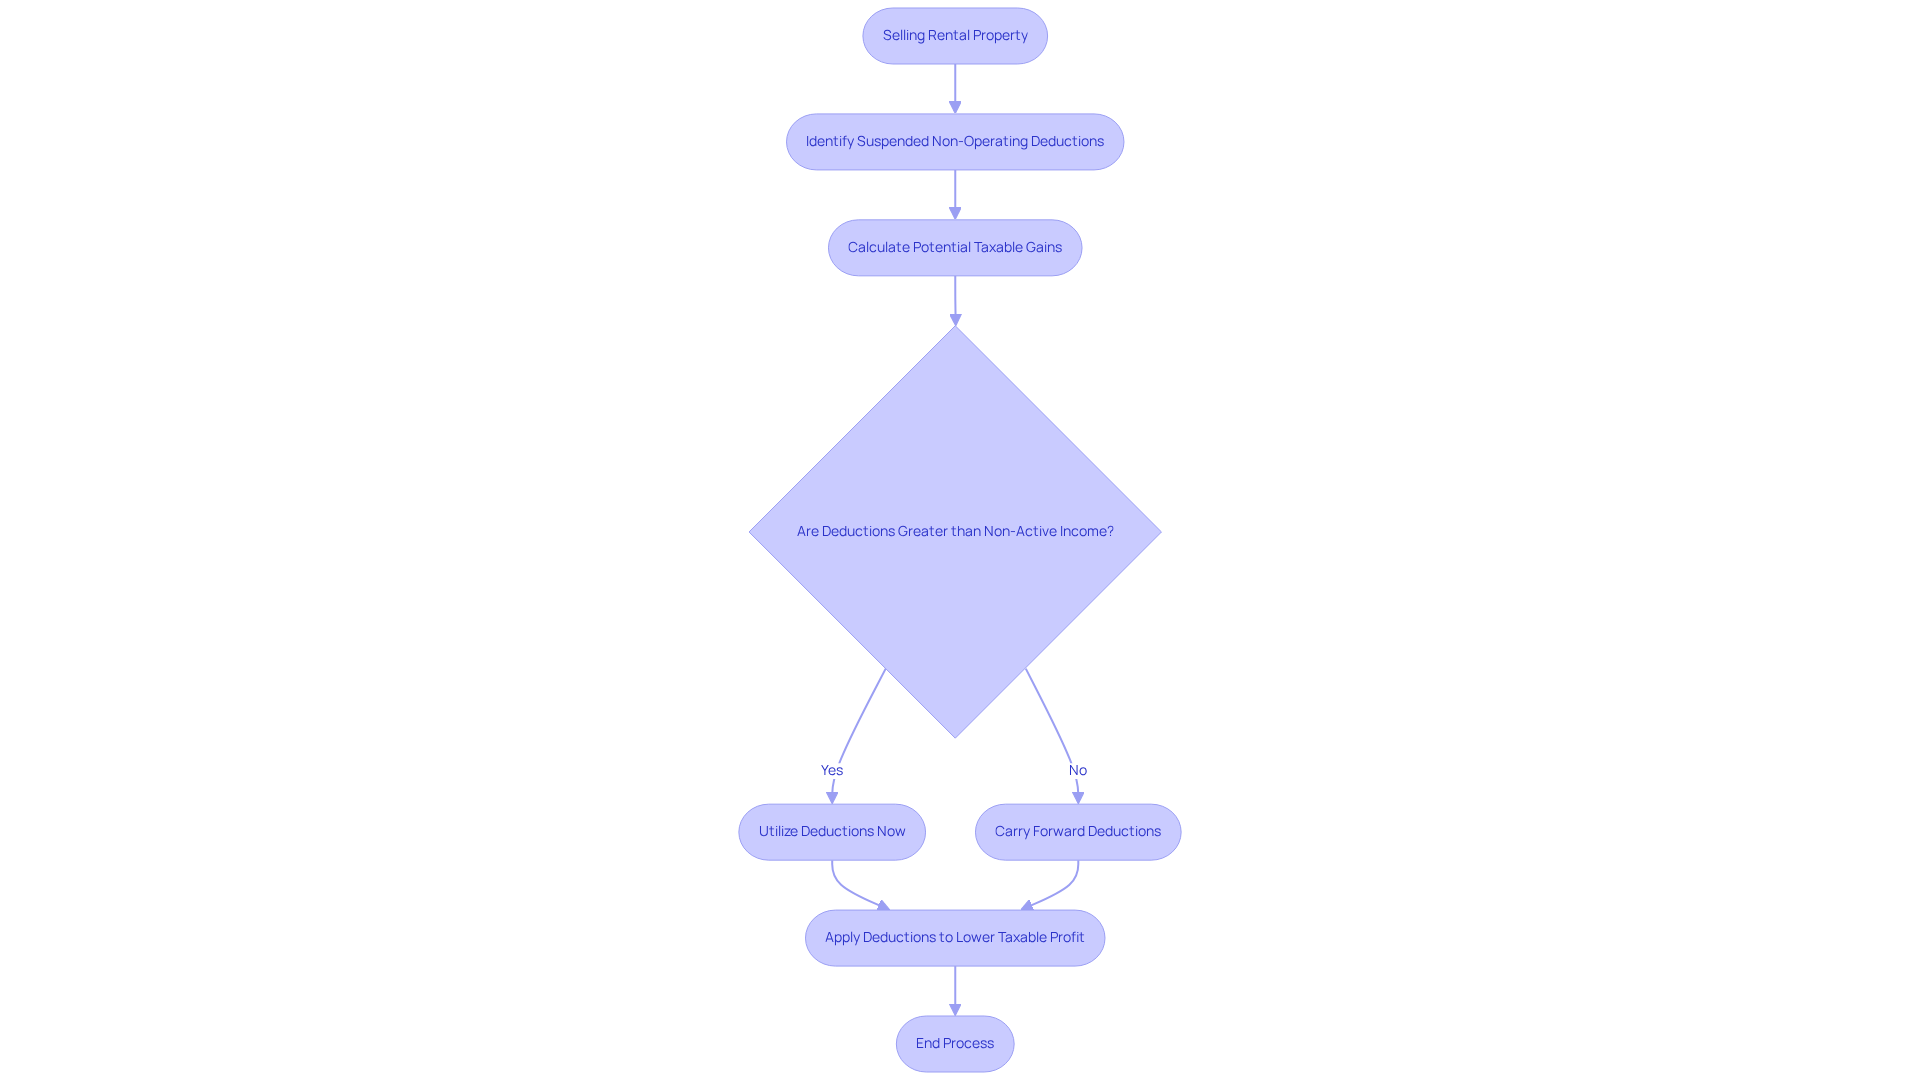
Imagine the relief of knowing you can lower your tax bill when selling a rental property. When households sell rental properties, they can use any suspended non-operating deductions to offset gains from the sale. If your family has non-operational deductions from previous years, you can use them to reduce any taxable gains when selling your property. For example, if a family has $30,000 in deferred non-operating expenses and sells a property for a $40,000 profit, they can lower their taxable profit to $10,000 by utilizing those expenses. Thorough planning and careful documentation are crucial to ensure these setbacks are effectively utilized.
It’s common for families to feel overwhelmed by the complexities of tax deductions. Taxpayers need to understand that non-active deductions can only counterbalance non-active income. If non-active deductions surpass non-active income, they may be carried forward indefinitely. This enables households to strategically prepare for upcoming tax years, especially if they expect to generate income from other rental properties. For instance, if a family sells a rental property at a profit, any suspended non-active deductions from that property can be utilized to counterbalance the taxable profit, potentially lowering their overall tax obligation.
It’s important to know that if you’re filing as a single person, the special allowance caps at $100,000, and for married couples filing separately, it’s $50,000. Keeping detailed records of all reported income and expenses associated with non-active activities is essential. This documentation streamlines the submission process for Form 8582, which is crucial for reporting non-active activity deductions. Families should also seek guidance from tax experts to navigate the specific IRS regulations regarding non-active deductions. With the right guidance, you can navigate these complexities and secure a brighter financial future for your family.
Carrying Forward Passive Losses: Strategies for Future Tax Planning
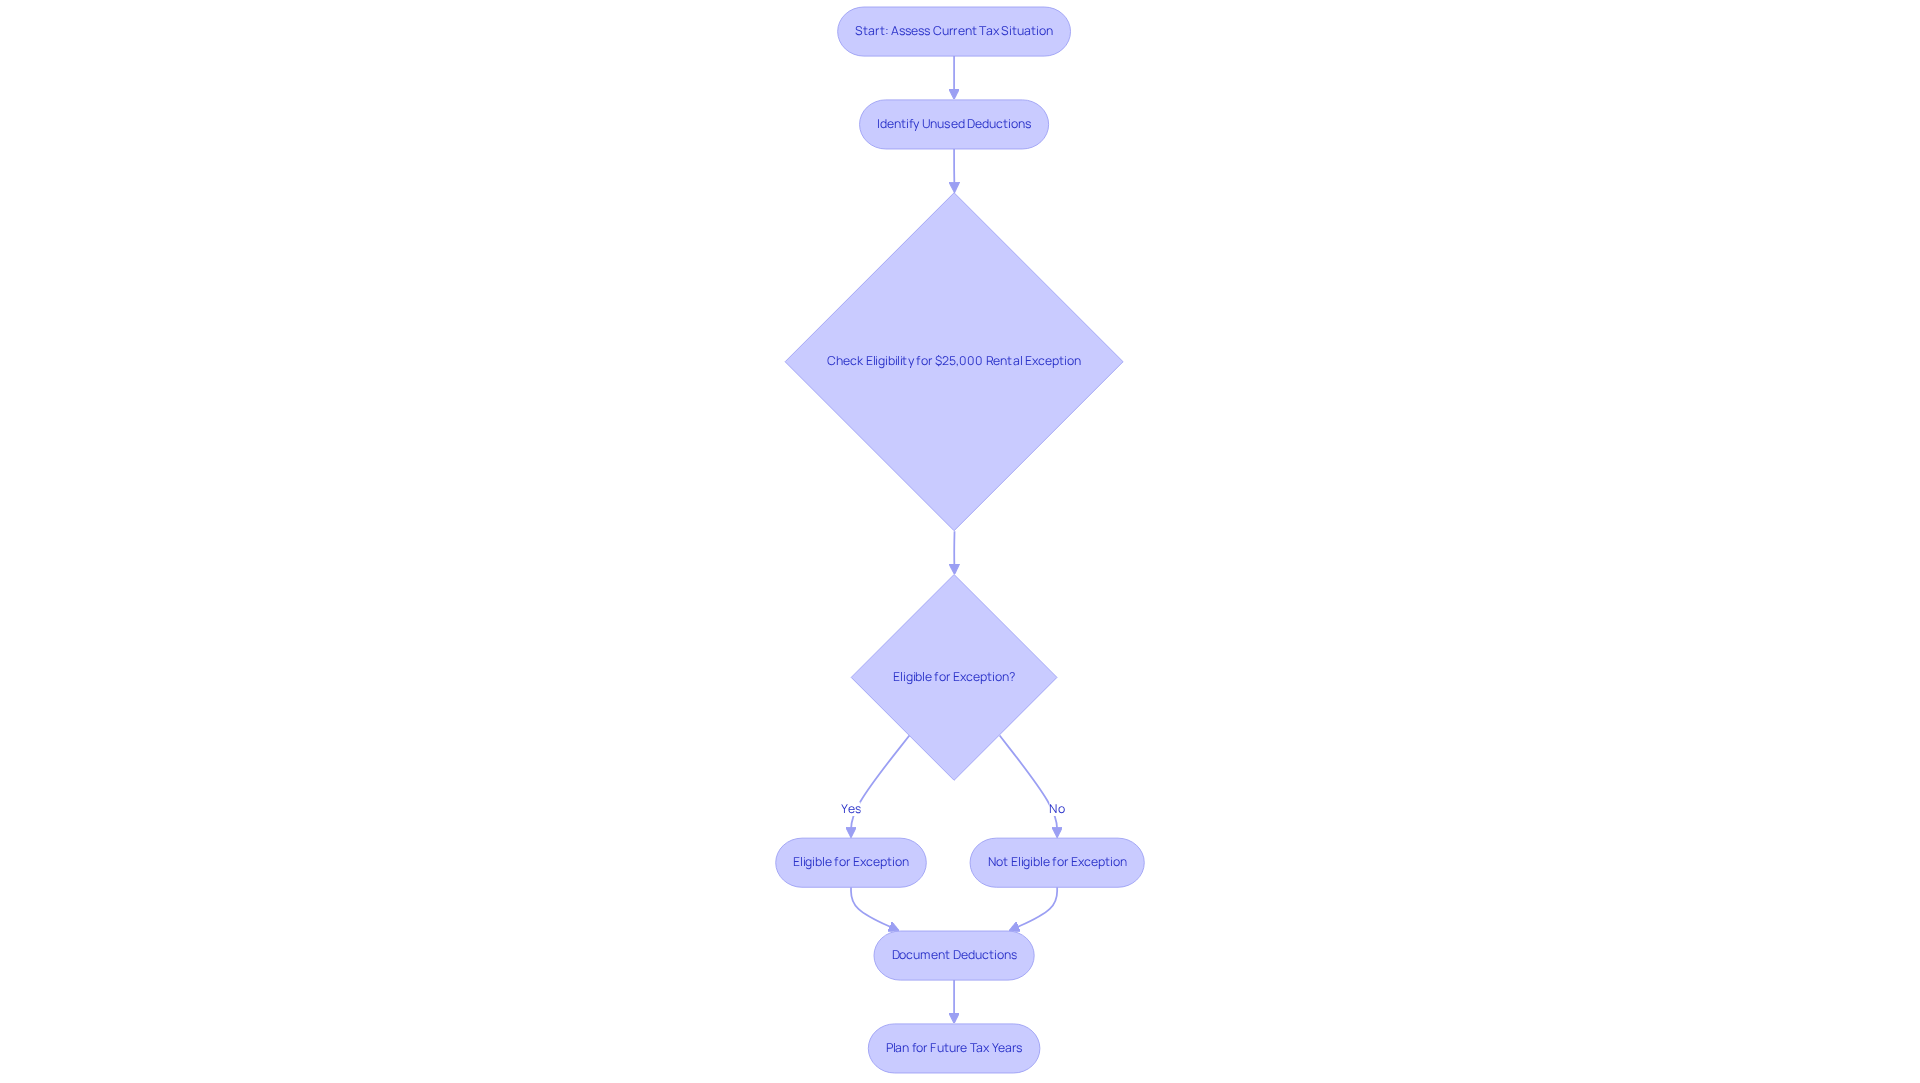
Imagine feeling overwhelmed by tax deductions that seem to slip through your fingers, leaving you uncertain about your family’s financial future. Families like yours can carry forward unused non-operating deductions to future tax years, helping to ease financial burdens down the road. This can be a real lifesaver for families who might not have enough income this year to fully benefit from their deductions. Keeping good records and knowing the carryforward rules can help your family plan for a brighter financial future.
If your family is involved in rental activities and meets certain criteria, you could qualify for a $25,000 rental exception, which can really help your financial situation. It’s also important to know that non-active deductions can’t offset capital gains, so planning ahead is key for your family’s financial health. With the right strategies and careful documentation, your family can navigate the complexities of tax planning and set yourselves up for future benefits.
Couples like Jay & Emma and Emily & Mark have effectively employed similar strategies with the support of Bright Advisers, enabling them to attain financial stability and independence through customized planning and tax strategies. Bright Advisers is committed to helping families make wise wealth decisions and preserve wealth across generations, ensuring that they can enjoy quality time with their loved ones while planning for a secure future.
Rental Real Estate Activities: Impacts on Passive Loss Limitations
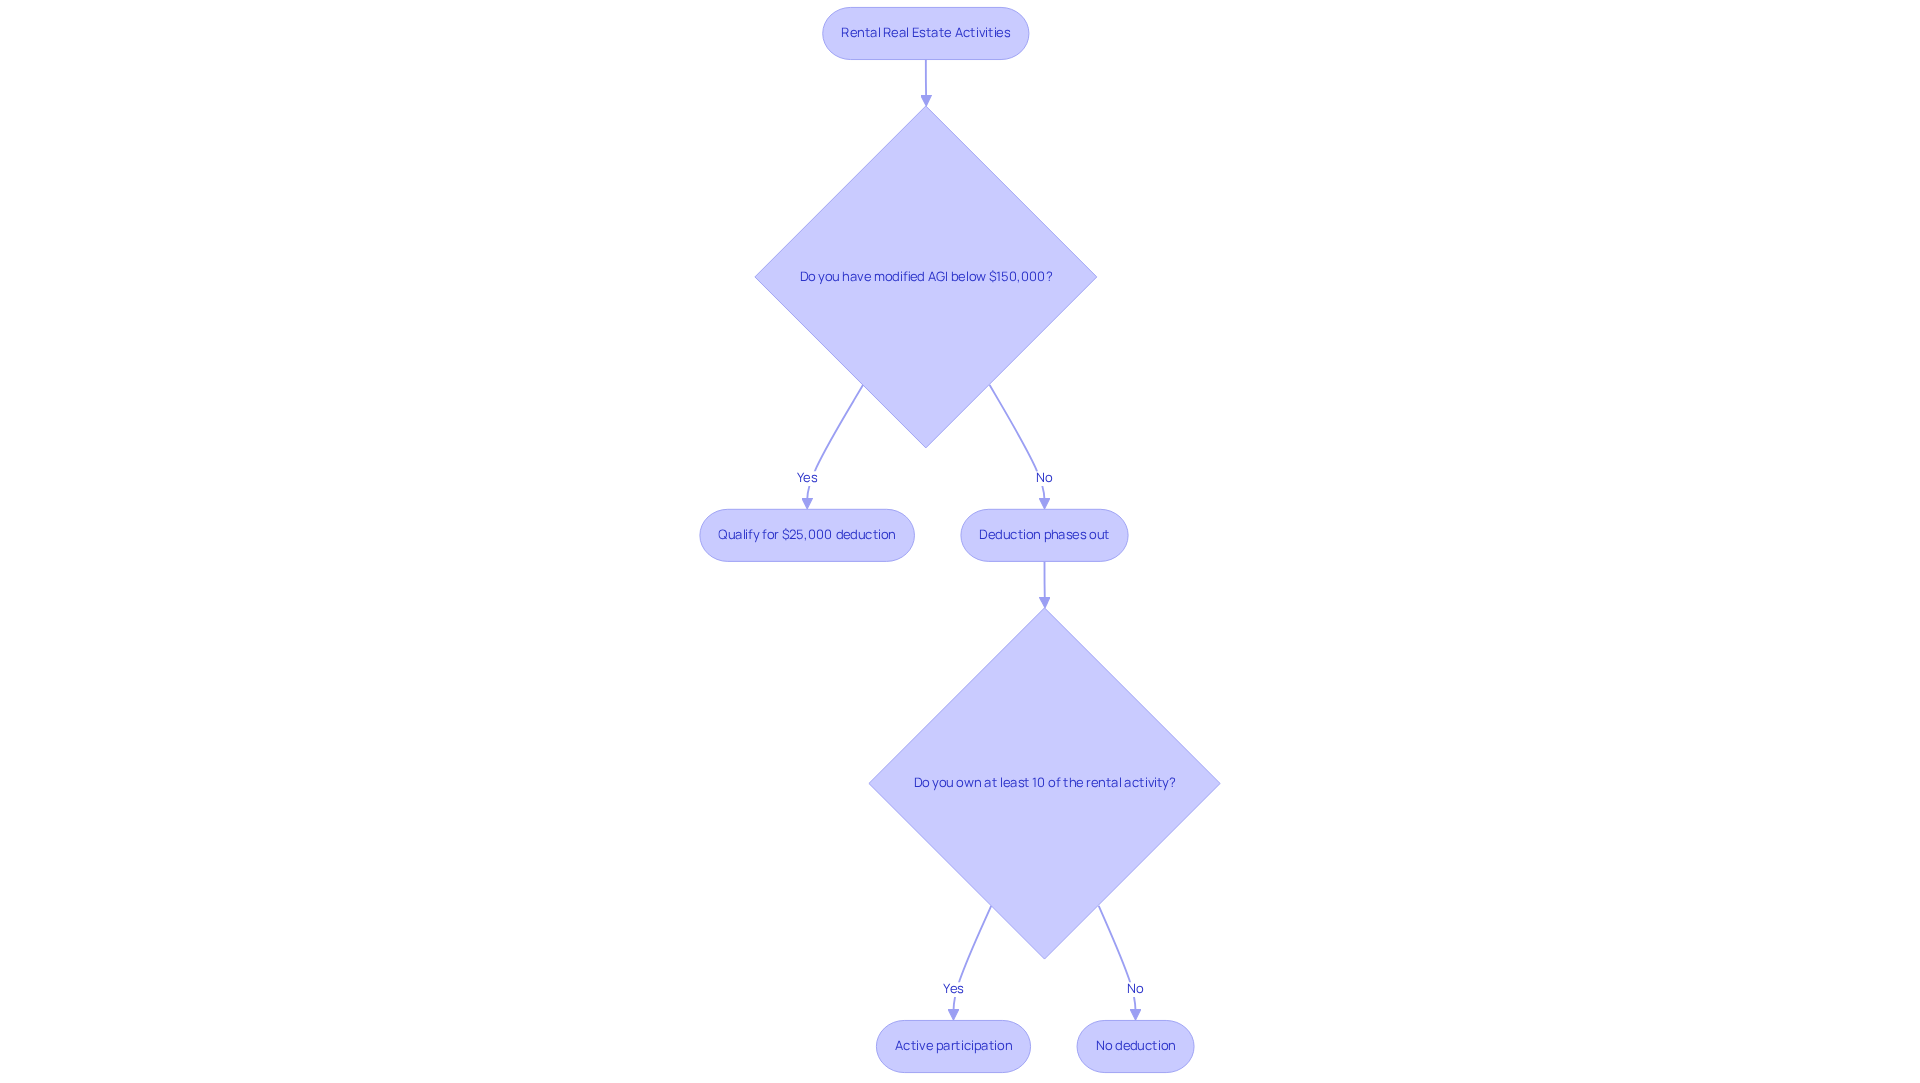
Imagine feeling overwhelmed by rental real estate rules and wondering how they affect your family’s finances. Rental real estate activities are often seen as non-active, which means that if you face deficits, they can only offset non-active income. Specifically, the $25,000 allowance for rental real estate deductions can help offset up to $25,000 of nonpassive income for qualifying individuals. This can be particularly beneficial for those with modified adjusted gross income (AGI) close to the phaseout thresholds. But here’s the catch: this deduction starts to disappear once your modified AGI hits $150,000. For every dollar over $100,000, the deduction drops by 50%. If you’re married and filing separately, there are special rules that can complicate your tax planning even further.
If you want to qualify for this deduction, you’ll need to own at least 10% of the rental activity and be involved in its operations throughout the year. Active participation doesn’t mean you have to be physically present at the rental property; making significant management decisions is enough. However, if you own rental real estate through a limited partnership, you won’t qualify for the $25,000 offset. Additionally, the passive loss limitations 2026 restrict the deduction of non-active expenses to the amount of your at-risk investment in the activity, which is essential for families to understand.
It’s important to grasp these limitations so you can plan your taxes effectively and feel more in control of your finances. For example, suspended deductions from passive activities can be carried forward indefinitely until they can offset future passive income, in accordance with passive loss limitations 2026, or are released upon the full disposition of the activity. This means that by managing your rental investments wisely and keeping an eye on your tax situation, you can find ways to save and support your family better. There’s no time limit for carrying forward these deductions, which could be substantial for families considering their tax planning strategies.
Case studies show how these regulations can impact taxpayers: those who incur non-active deductions may find their current tax advantages restricted unless they meet certain exceptions. Moreover, the interaction between passive activity deductions and AGI can greatly influence tax obligations, making it crucial for families to stay updated on passive loss limitations 2026 that may impact their rental real estate endeavors. By staying informed and proactive, you can turn these challenges into opportunities for your family’s financial future.
Aggregation Election: A Strategic Approach to Managing Passive Losses
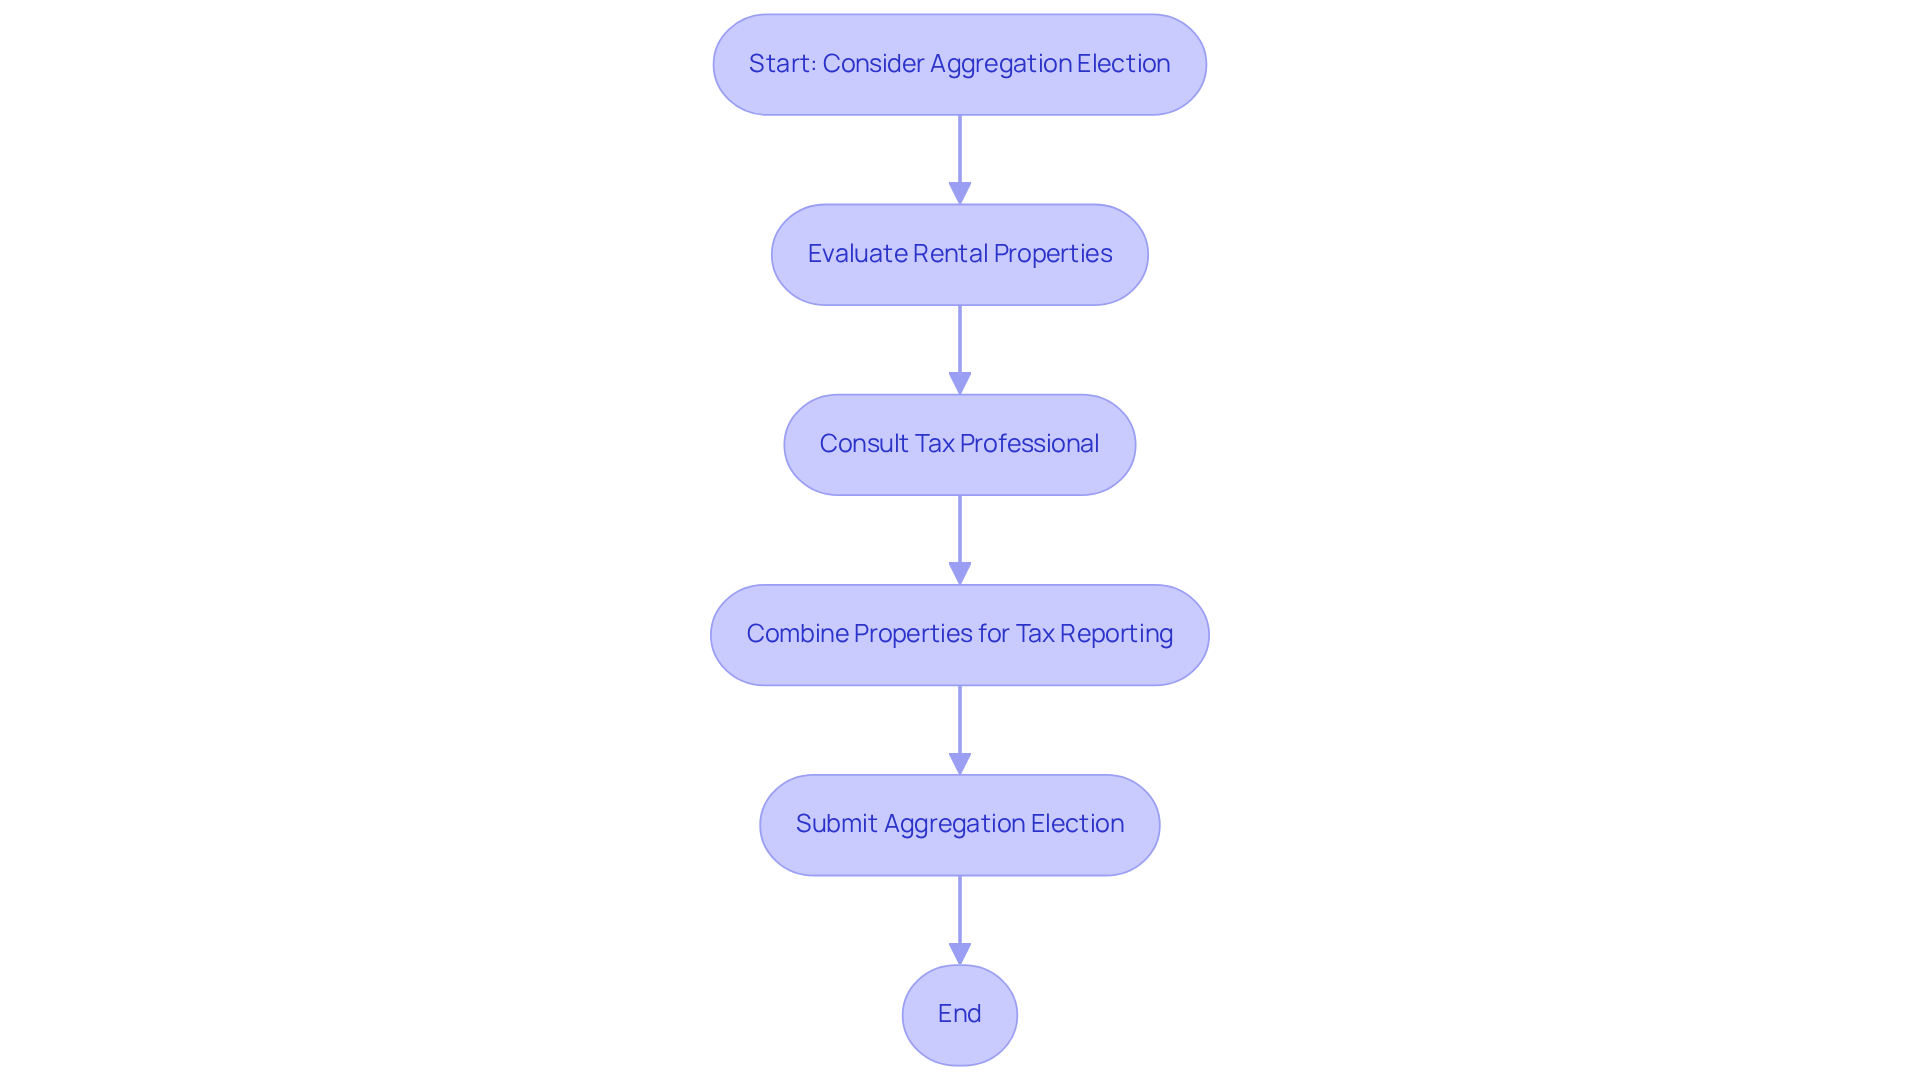
Imagine feeling overwhelmed by the complexities of managing multiple rental properties while trying to secure your family’s financial future. The aggregation election allows households to consolidate these properties for tax purposes, enhancing their potential to deduct losses. By choosing to aggregate, families can treat their combined rental activities as a single entity. This approach helps families managing multiple rental properties by simplifying tax reporting. It can lead to significant tax advantages.
For example, deductions that would usually be deferred under inactive activity regulations can become allowable when properties are combined. This means families can enhance their cash flow and overall financial standing. At Bright Advisers, we understand families like Jay and Emma, who are looking for ways to ease their financial worries. They sought guidance to allocate resources effectively and reduce financial anxiety. By establishing a comprehensive budget, conducting cash flow projections, and selecting investment strategies focused on diversification, they successfully navigated funding their children’s education while planning for retirement.
But remember, if you have prior year suspended passive losses, they cannot be used against other income after making this election under the passive loss limitations 2026. Families should consider consulting with a tax professional to understand how to initiate the aggregation election process effectively and ensure they meet all necessary qualifications. Through Bright Advisers, households can access customized financial planning and tax strategies that enable them to reach their financial objectives. With the right guidance, families can transform their financial landscape and focus on what truly matters – their loved ones.
Documentation for Material Participation: Proving Your Case for Deductions
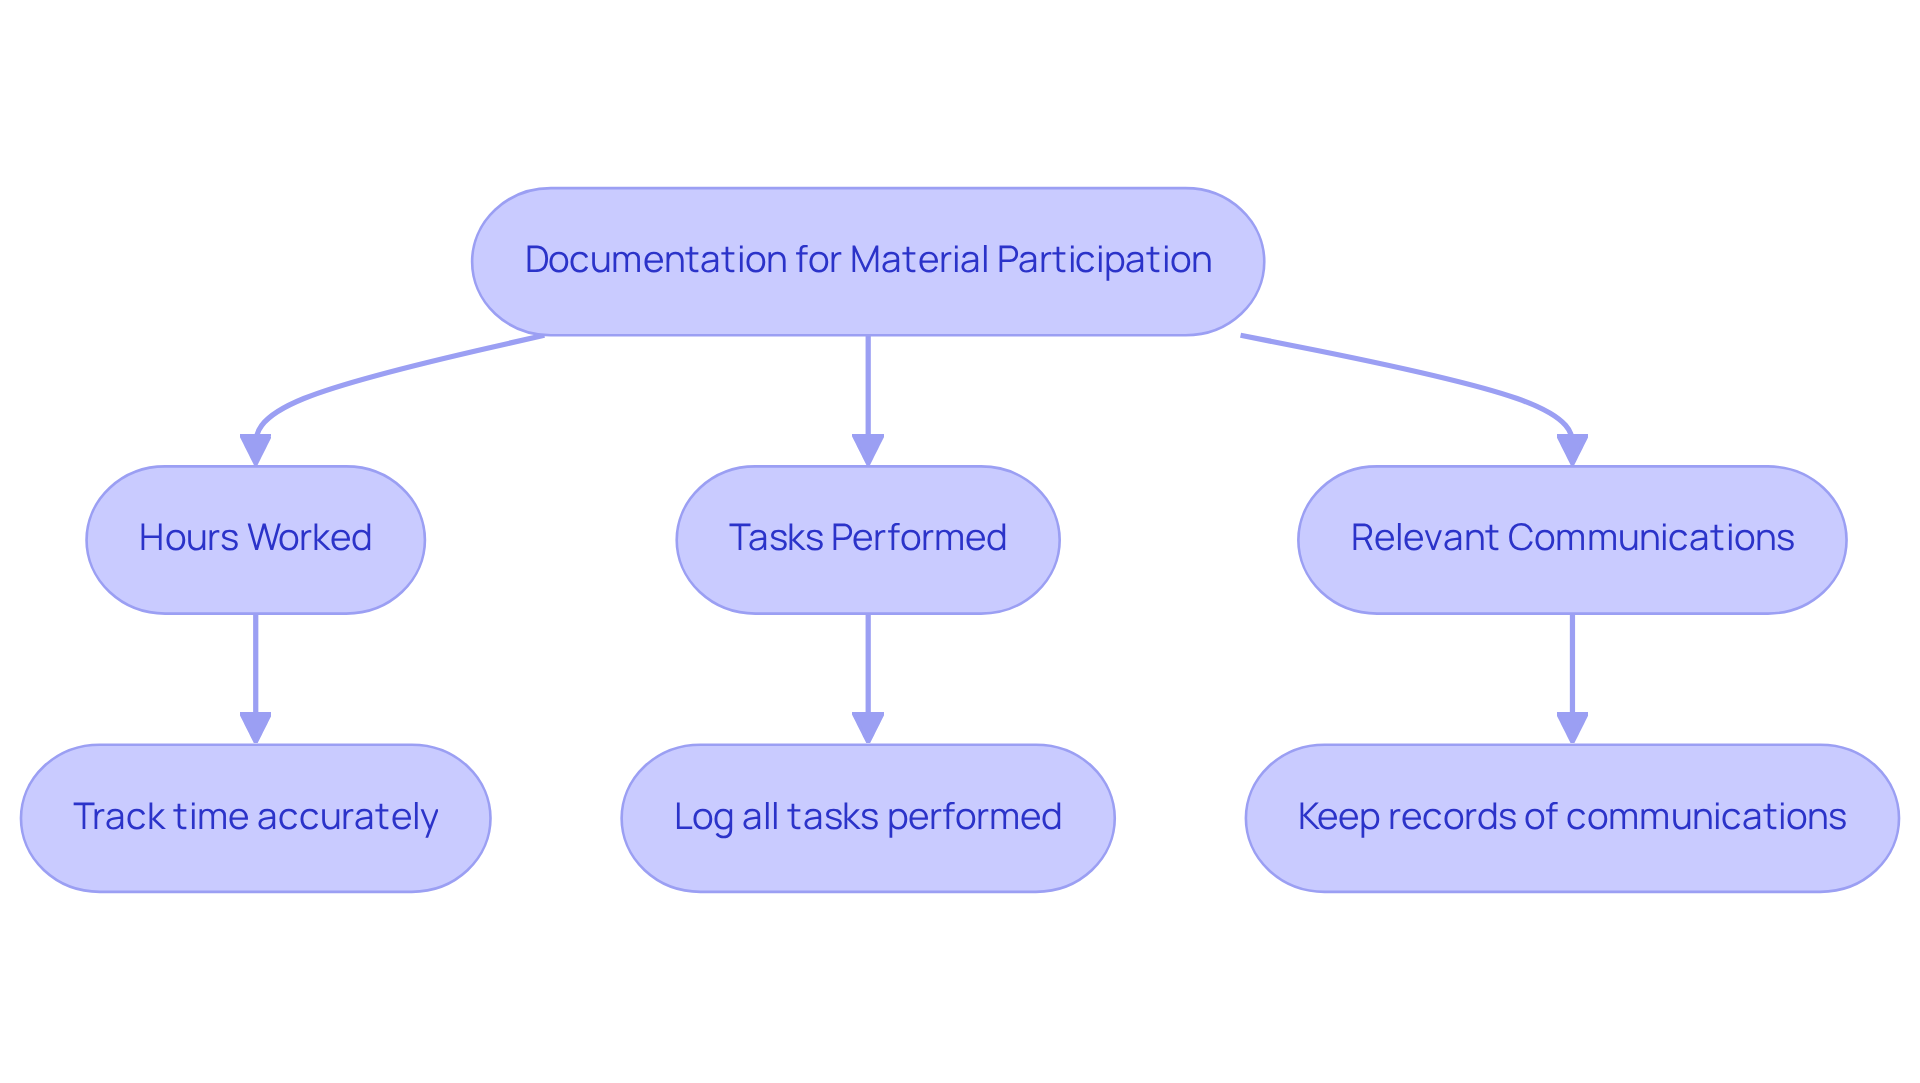
Imagine the peace of mind that comes from knowing your family’s financial records are in order. Keeping track of your rental activities can help you feel secure and prepared. To substantiate claims for material participation, it’s essential to maintain thorough documentation of your involvement. This means keeping detailed records of:
- Hours worked
- Tasks performed
- Any relevant communications
When you keep detailed records, you’re not just preparing for deductions; you’re also safeguarding your family against potential audit surprises. Many families find it challenging to keep track of all the details involved in rental activities. That’s why we recommend exploring user-friendly digital tools that can make record-keeping easier and help you stay on top of IRS requirements. Together, we can navigate this journey!
Conclusion
It can feel overwhelming to navigate tax laws, especially when you’re trying to provide for your family. Understanding these limitations can turn challenges into opportunities for your family’s future. We’re here to help you navigate these changes, providing the support you need to feel confident in your financial decisions.
We’ve shared important insights about how passive loss limitations can affect your family, including key factors to consider. By keeping track of your rental activities and knowing what deductions you qualify for, you can save money on taxes and support your family’s needs. Understanding these limitations is key to making the most of your family’s financial situation.
Together, we can turn potential tax challenges into opportunities for your family’s growth and security. These strategies can ease financial stress, allowing you to focus on what truly matters – creating lasting memories with your loved ones. For tailored guidance and support, we encourage you to explore the resources available through Bright Advisers and take proactive steps toward achieving your financial goals.
Frequently Asked Questions
What are passive loss limitations and how do they affect families with rental properties?
Passive loss limitations restrict the ability to deduct passive losses from rental properties against non-passive income. For families with modified adjusted gross income (MAGI) exceeding $150,000, the ability to deduct up to $25,000 of passive losses is phased out, which can lead to lost tax benefits.
What changes to passive loss limitations will occur in 2026?
In 2026, the $25,000 deduction for rental real estate losses will begin to phase out for MAGI exceeding $100,000 and will completely disappear at $150,000. This means families with a MAGI of $130,000 can only deduct $10,000 of their rental losses.
How can families manage their MAGI to retain tax deductions?
Families can manage their MAGI by deferring bonuses or maximizing retirement contributions to keep their income below critical thresholds, thus retaining their ability to deduct rental losses.
What is material participation and why is it important for tax deductions?
Material participation refers to the level of involvement in rental activities required to classify those activities as non-passive for tax purposes. To qualify, individuals must participate in rental activities for over 500 hours in a year or be the sole participant for more than 100 hours. Meeting these criteria allows families to deduct rental losses against their W-2 income.
How can Bright Advisers assist families in navigating tax strategies related to rental properties?
Bright Advisers provides personalized strategies to help families understand and navigate tax deduction restrictions, ensuring they can effectively manage their rental properties and enhance tax advantages. They utilize advanced technology to deliver insights aligned with each household’s financial objectives.
What should families do to prepare for the changes in passive loss limitations?
Families should stay informed about the implications of the upcoming changes and plan strategically to avoid unexpected tax bills. This includes tracking rental activities and understanding IRS criteria for material participation.
What services does Bright Advisers offer to support families in their financial planning?
Bright Advisers offers extensive financial planning services that encompass tax strategies, risk management, and legacy planning, all designed to assist families in achieving their financial goals while navigating complexities related to rental properties and tax deductions.
What is the importance of maintaining detailed records for rental activities?
Keeping detailed records of rental activities is crucial for substantiating claims for material participation and maximizing deductions. It is more effective to maintain records throughout the year rather than trying to compile them at year-end.
List of Sources
- Bright Advisers: Tailored Strategies for Navigating Passive Loss Limitations
- Passive loss limitations on rental real estate – Journal of Accountancy (https://journalofaccountancy.com/issues/2023/sep/passive-loss-limitations-on-rental-real-estate)
- Navigating Passive Loss Limitations: Understanding the IRS Rules and Strategies (https://lifepointfd.com/navigating-passive-loss-limitations-understanding-the-irs-rules-and-strategies)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Four Tactics to Turn Suspended Passive Losses into Tax Deductions (https://agfintax.com/suspended-passive-losses)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Understanding the 2026 Passive Activity Loss Rules: Key Changes and Implications
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Passive Activity Loss Rules for Real Estate 2026 (https://senecacostseg.com/feeds/blog/passive-activity-loss-rules-real-estate-2026)
- IRS Form 8582: Calculating Passive Activity Losses for Real Estate (https://turbotax.intuit.com/tax-tips/rental-property/irs-form-8582-calculating-passive-activity-losses-for-real-estate/c71Jm0iM7)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Material Participation: Criteria for Maximizing Passive Loss Deductions
- Material Participation: Your Complete Guide to Unlocking Business Loss Deductions (https://cssiservices.com/material-participation-guide)
- Passive Activity and At-Risk Rules: How They Impact Your Taxes | Stephano Slack LLC (https://stephanoslack.com/2025/03/25/passive-activity-and-at-risk-rules-how-they-impact-your-taxes)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Short-Term Rental Material Participation Playbook for 2025 (https://airdna.co/blog/short-term-rental-material-participation)
- Income Limits for Passive Loss Deductions: What Investors Need to Know
- What Is the $25,000 Passive Loss Allowance? – Hall CPA (https://therealestatecpa.com/blog/what-is-the-25000-passive-loss-allowance)
- Passive Activity Loss Limits (https://wcginc.com/kb-rental-property/passive-activity-loss-limits)
- Unlock Bigger Deductions on Rental Real Estate – Sasserath & Co. (https://sasscpas.com/blog/index.php/2026/02/02/unlock-bigger-deductions-on-rental-real-estate)
- Passive Activity Loss Rules 2026: How Real Estate Investors Can Maximize Deductions – Uncle Kam (https://unclekam.com/tax-strategy-blog/passive-activity-loss-rules)
- Passive Activity Loss Rules for Real Estate 2026 (https://senecacostseg.com/feeds/blog/passive-activity-loss-rules-real-estate-2026)
- Exceptions to Passive Activity Loss Rules: Unlocking Additional Deductions
- Passive activity loss: Overview and FAQs (https://tax.thomsonreuters.com/en/glossary/passive-activity-loss)
- Qualifying as a Real Estate Professional and Deducting Passive Losses (https://therealestatecpa.com/blog/qualifying-as-a-real-estate-professional-and-deducting-passive-losses)
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Rental Real Estate Losses – Olsen Thielen CPAs & Advisors (https://otcpas.com/rental-real-estate-losses)
- Maximizing Tax Benefits through Real Estate Professional Status and Passive Activity Rules (https://thecjgroup.com/maximizing-tax-benefits-through-real-estate-professional-status-and-passive-activity-rules)
- Selling Rental Properties: Managing Suspended Passive Losses Effectively
- IRS Form 8582: Calculating Passive Activity Losses for Real Estate (https://turbotax.intuit.com/tax-tips/rental-property/irs-form-8582-calculating-passive-activity-losses-for-real-estate/c71Jm0iM7)
- Strategies to Use Suspended Passive Losses from Rental Real Estate (https://therealestatecpa.com/blog/strategies-suspended-passive-losses-rental-real-estate)
- Selling Your Rental Property- Passive Losses And NIIT (https://wcginc.com/kb-rental-property/selling-your-rental-property-passive-losses-and-niit)
- Carrying Forward Passive Losses: Strategies for Future Tax Planning
- Understanding Passive Activity Losses: A Comprehensive Guide|Greg O’Brien, CPA (https://anomalycpa.com/post/passive-activity-loss-guide)
- Understanding Passive Activity Loss Rules (https://leyton.com/us/insights/articles/understanding-passive-activity-loss-rules)
- Topic no. 425, Passive activities – Losses and credits | Internal Revenue Service (https://irs.gov/taxtopics/tc425)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- Rental Real Estate Activities: Impacts on Passive Loss Limitations
- Avoiding passive loss limitations on rental real estate losses (https://thetaxadviser.com/issues/2024/jul/avoiding-passive-loss-limitations-on-rental-real-estate-losses)
- Understanding Passive Activity Loss Limitations (https://taxslayerpro.com/blog/post/understanding-passive-loss-limitations)
- KBKG Tax Insight: Overcoming Passive Losses from Self-Rental Property Using the Grouping Election (https://kbkg.com/cost-segregation/kbkg-tax-insight-overcoming-passive-losses-from-self-rental-property-using-grouping-elections)
- Topic no. 425, Passive activities – Losses and credits | Internal Revenue Service (https://irs.gov/taxtopics/tc425)
- Can Rental Real Estate Losses Offset Other Income? | Forvis Mazars US (https://forvismazars.us/forsights/2026/08/can-rental-real-estate-losses-offset-other-income)
- Aggregation Election: A Strategic Approach to Managing Passive Losses
- New Guidance on the Grouping Election for Passive Activities (https://calt.iastate.edu/new-guidance-grouping-election-passive-activities)
- Section 469 Grouping Election for Real Estate Professionals (https://kahnlitwin.com/blogs/tax-blog/the-pros-cons-of-making-the-grouping-election-for-your-rental-real-estate-a)
- Election to group activities for purposes of passive activity loss rules (https://thetaxadviser.com/issues/2017/may/election-group-activities-passive-activity-loss-rules)
- What are the Different Grouping Elections? (https://therealestatecpa.com/blog/what-are-the-different-grouping-elections-when-can-i-use-them)
- Should You Make the Grouping Election for Your Rental Real Estate Activities? – Dahl Law Group (https://tqdlaw.com/should-you-make-the-grouping-election-for-your-rental-real-estate-activities)
- Documentation for Material Participation: Proving Your Case for Deductions
- Real Estate Tax Rules Explained: Material Participation, Qualified… (https://doeren.com/viewpoint/real-estate-tax-rules-explained-material-participation-qualified-business-income-and-net-investment-income-tax)
- What Does It Mean To Materially Participate In Real Estate? (https://landlordstudio.com/blog/materially-participate-meaning)
- Short-Term Rental Material Participation Playbook for 2025 (https://airdna.co/blog/short-term-rental-material-participation)
- How LLP and LLC Owners Can Qualify for Material Participation and Maximize Tax Deductions – Thomas Howell Ferguson (https://thf.cpa/2026/06/09/how-llp-and-llc-owners-can-qualify-for-material-participation-and-maximize-tax-deductions)
- What Are the Material Participation Rules for Real Estate Investors? (https://linkedin.com/pulse/what-material-participation-rules-real-estate-investors-7cw0c)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading