

Key Highlights
- Bright Advisers prioritises transparent fee structures, allowing families to understand their financial obligations without hidden costs.
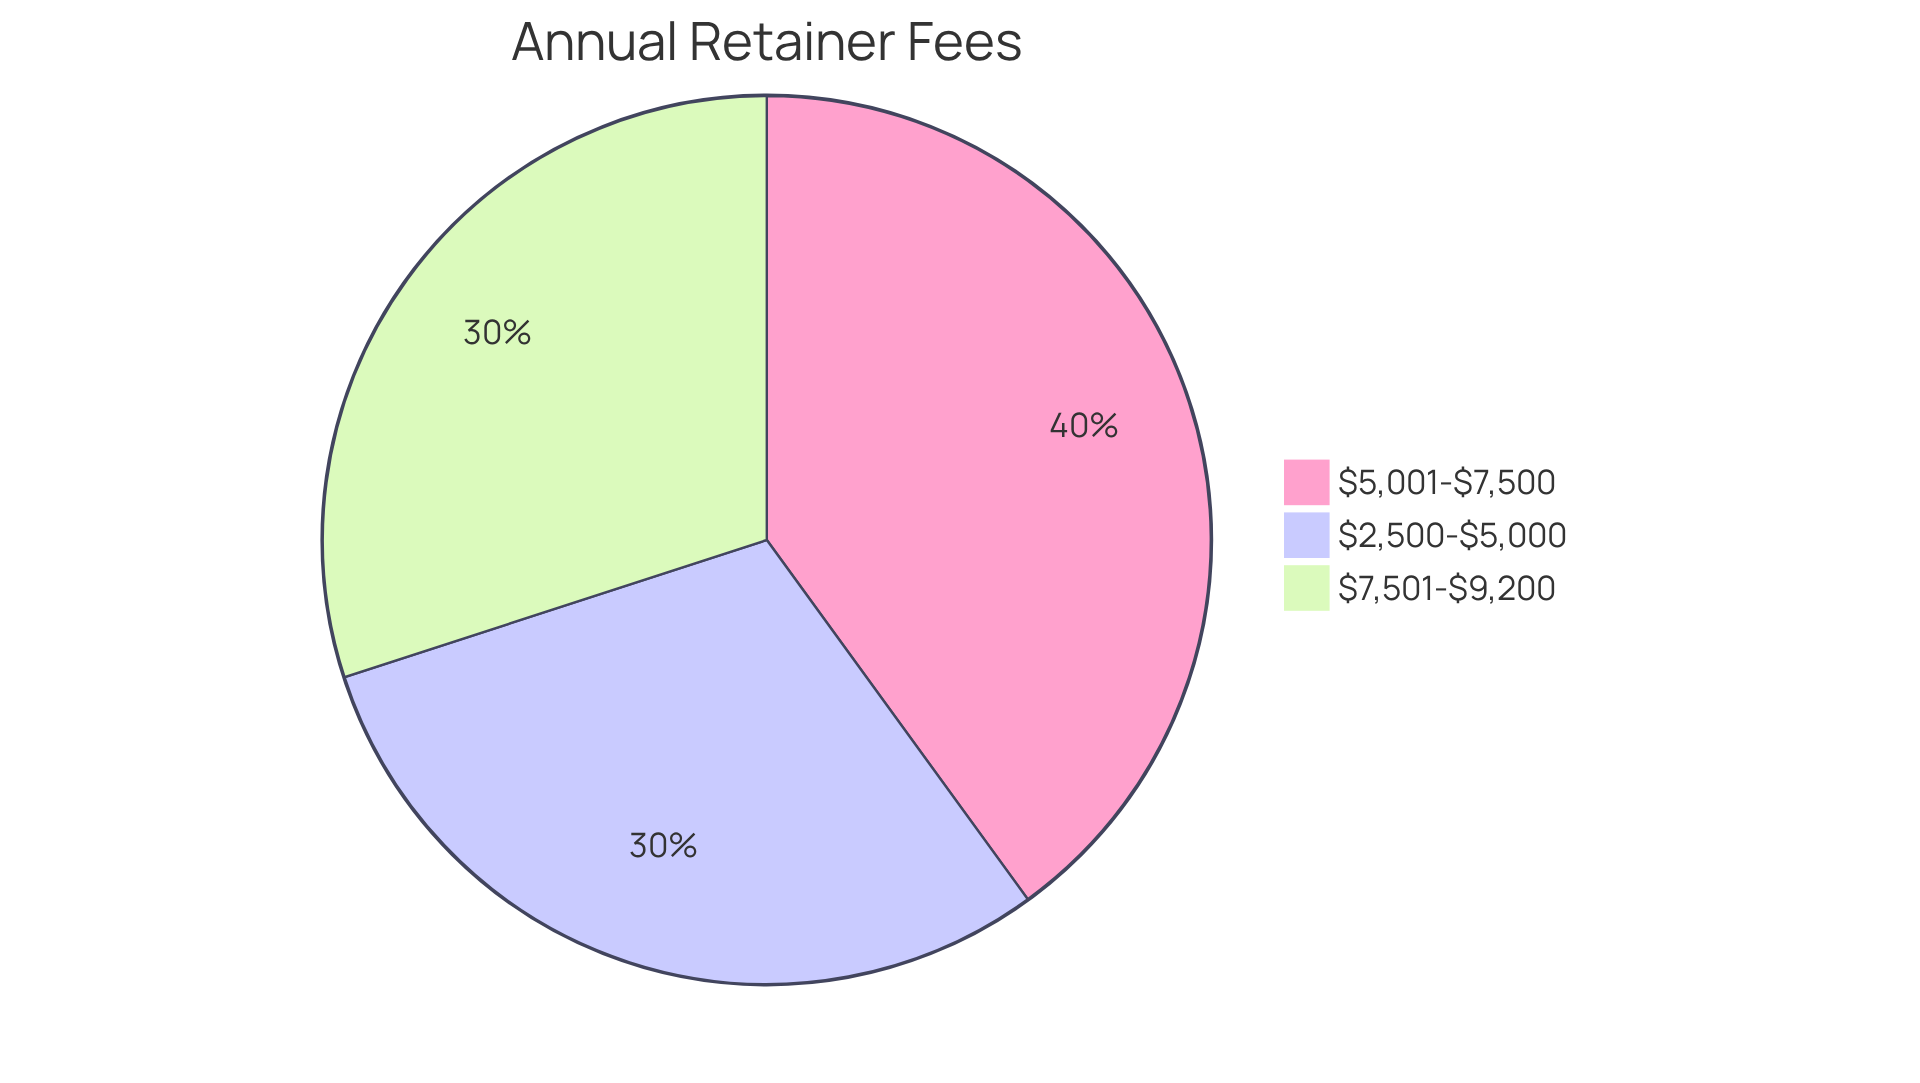
- Annual retainer fees at Bright Advisers range from $2,500 to $9,200, tailored to individual planning needs.
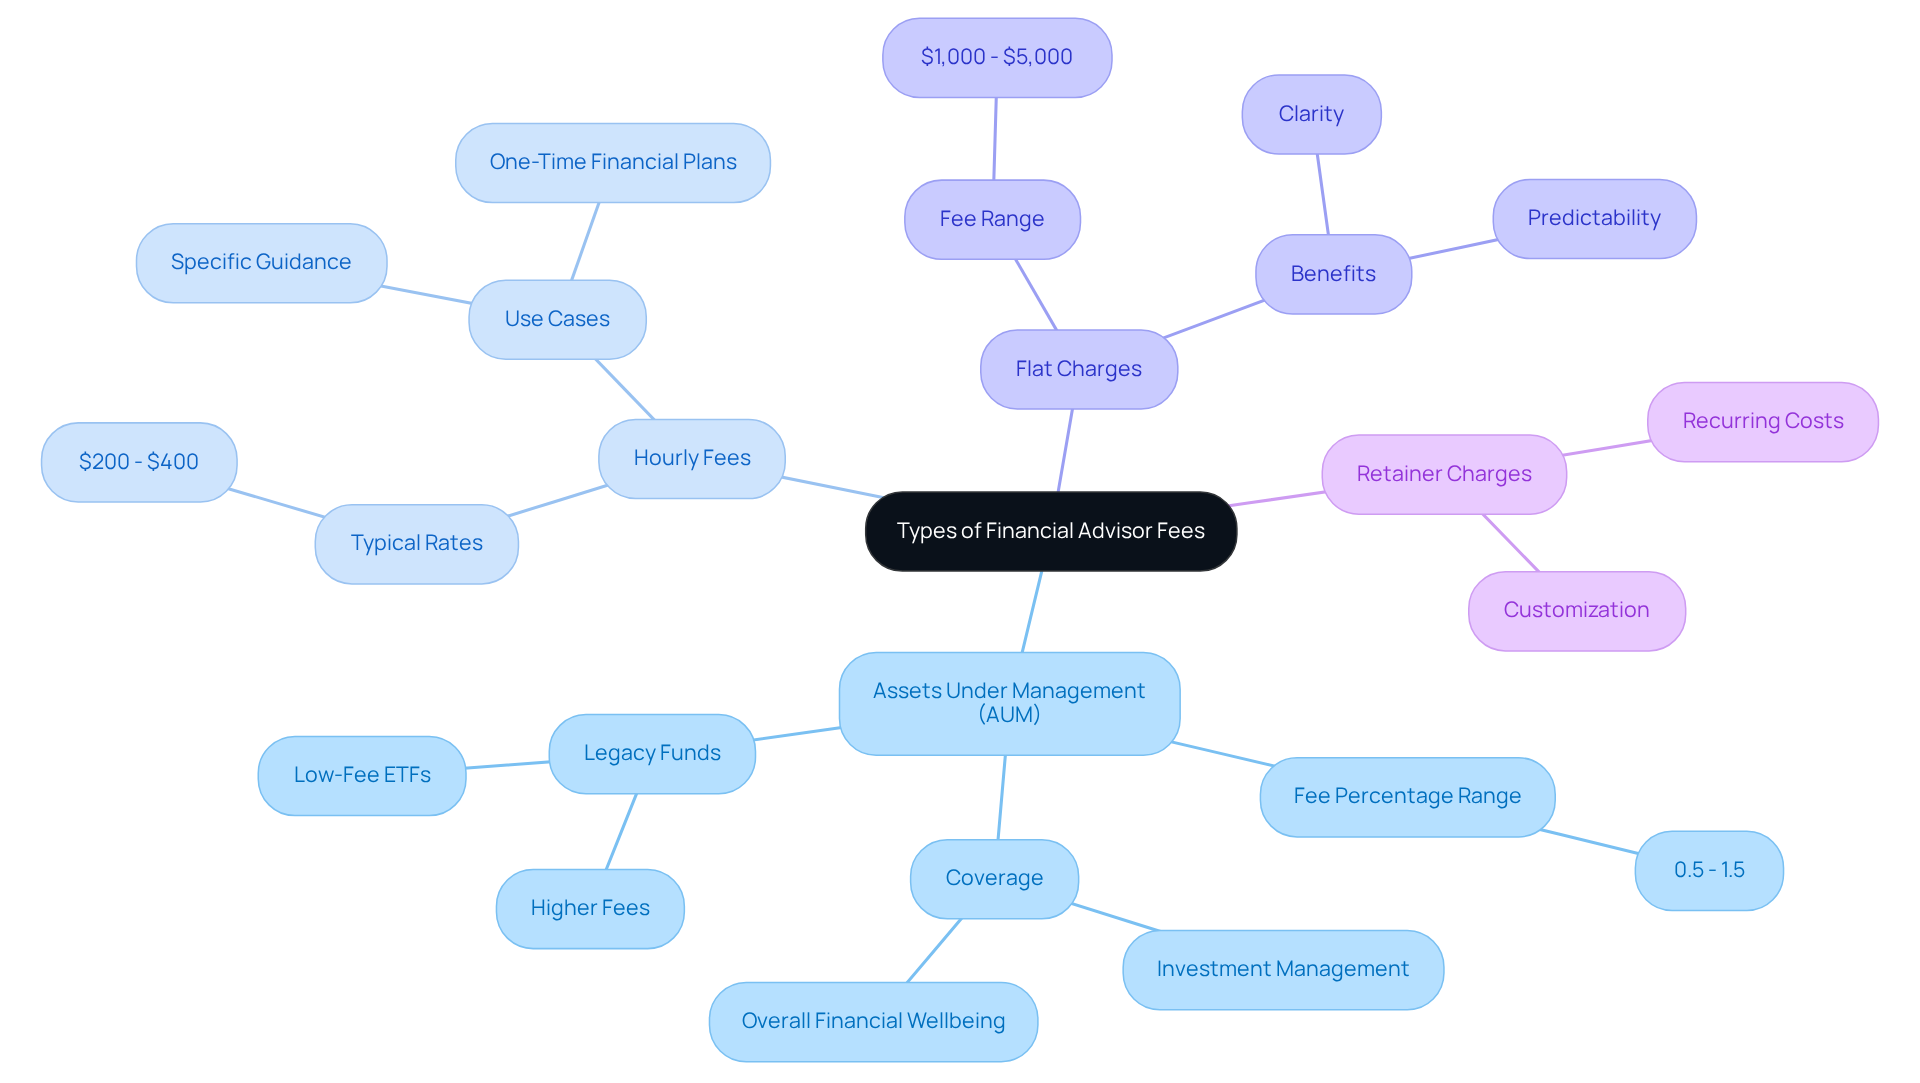
- Different fee models include Assets Under Management (AUM), hourly fees, flat charges, and retainer charges, each with unique implications for families.
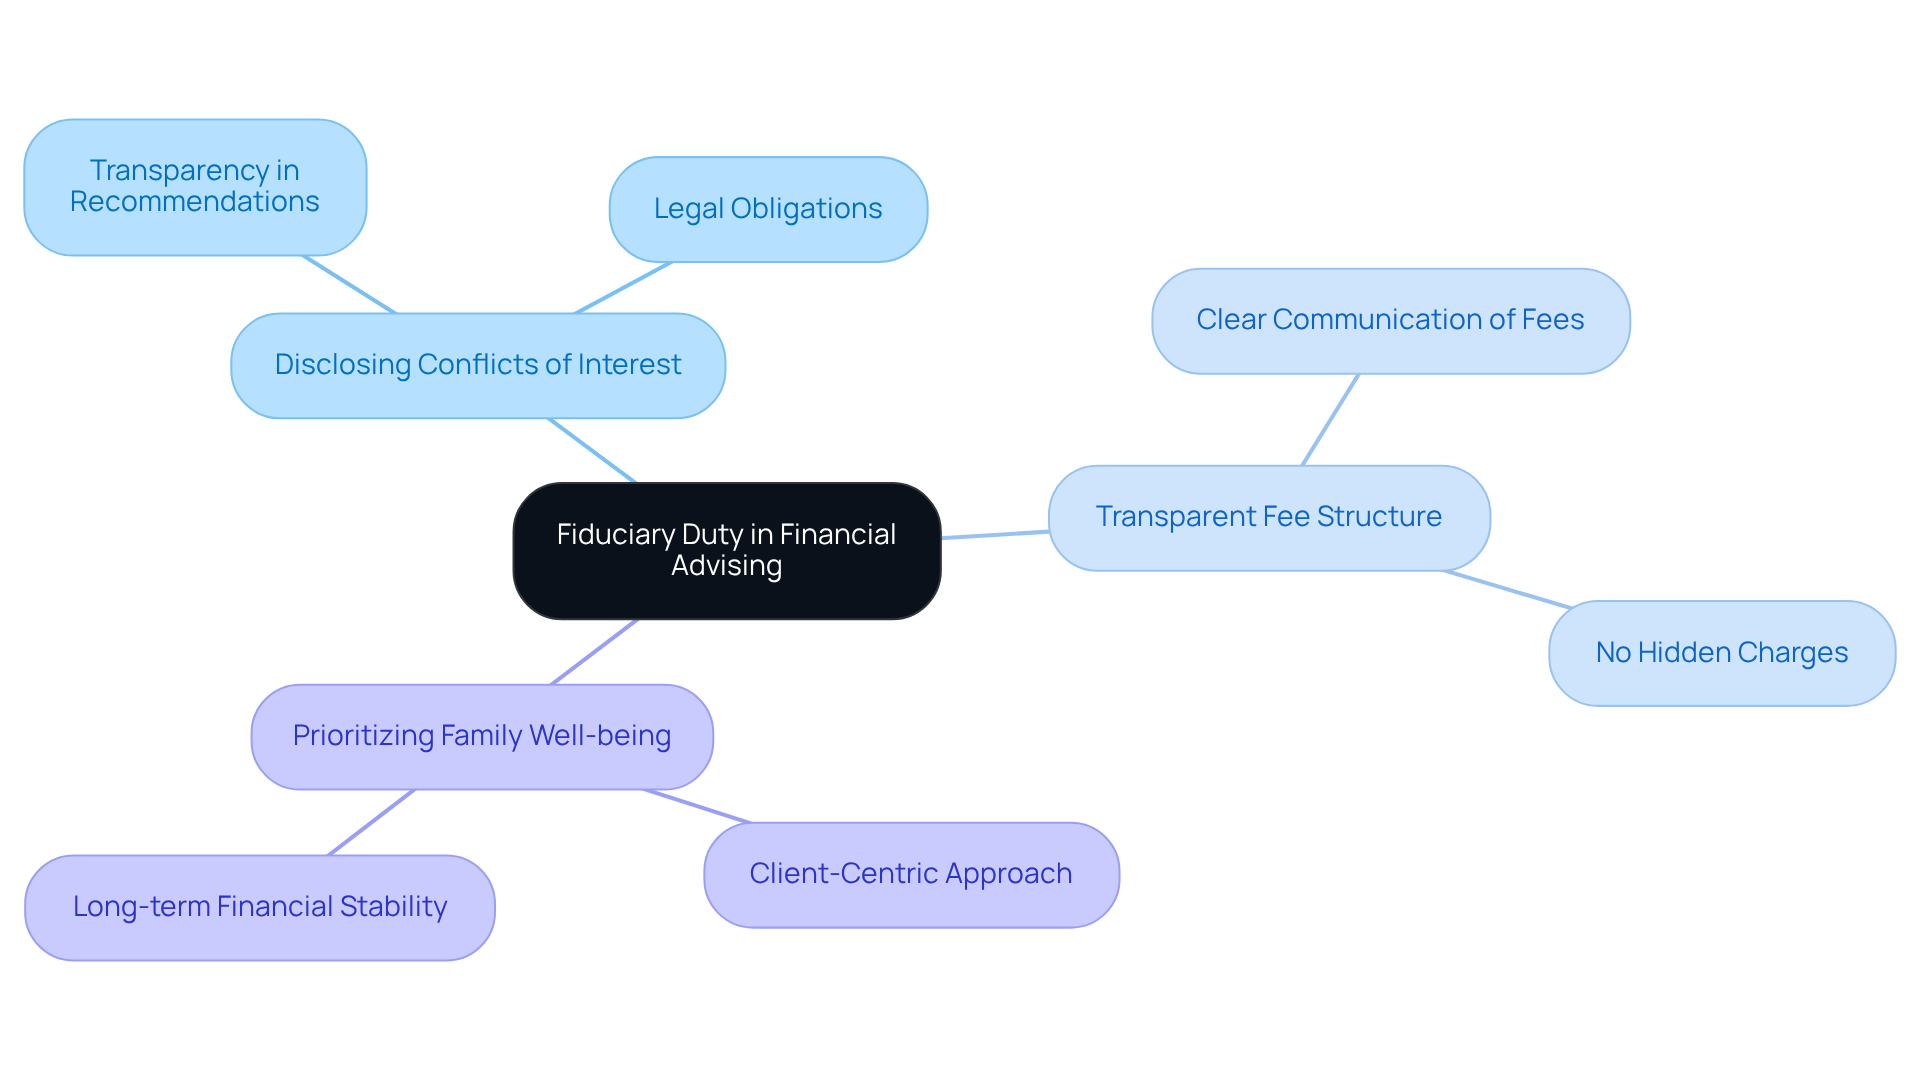
- Fiduciary duty ensures that advisors act in the best interests of families, disclosing conflicts of interest and prioritising client welfare.
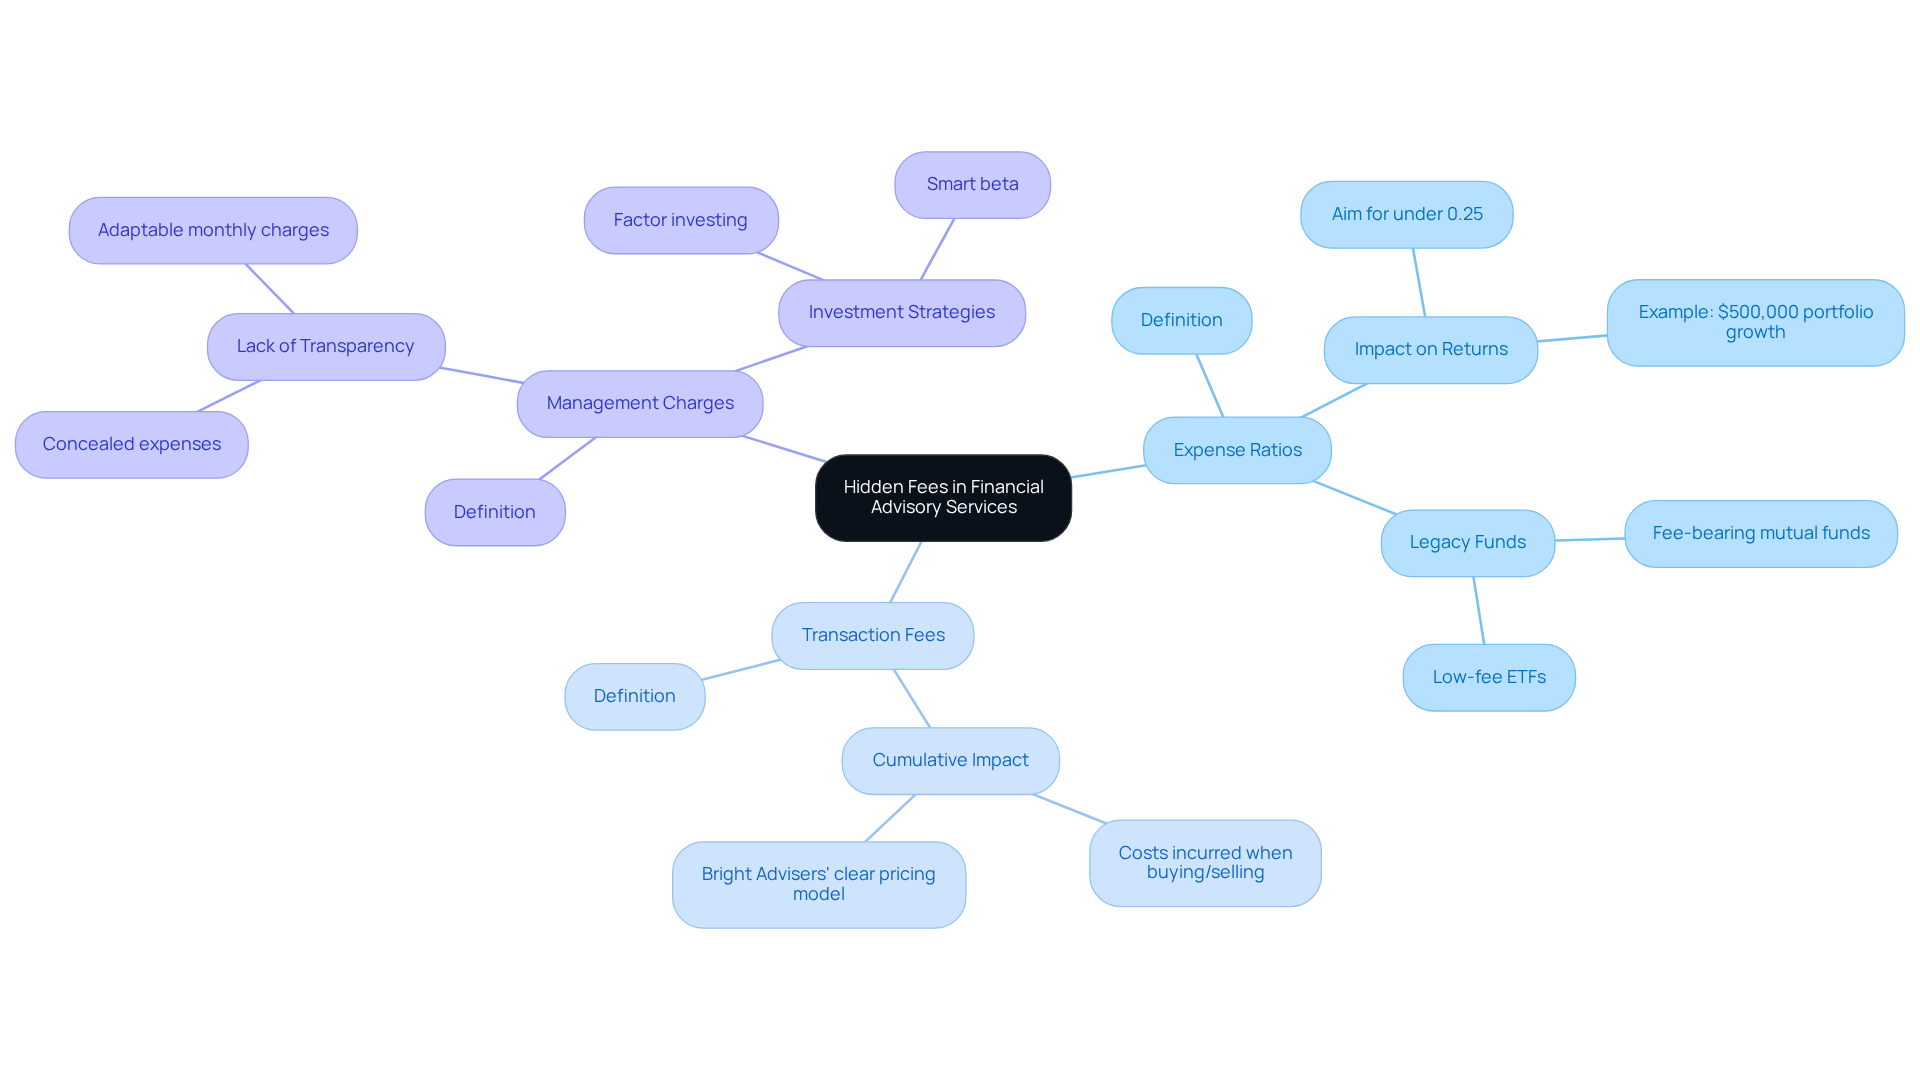
- Understanding hidden fees, such as expense ratios and transaction fees, is crucial for families to maximise investment returns.
- Fee-only financial advisors offer advantages like transparency, fiduciary responsibility, and unbiased advice, but may come with higher upfront costs.
- Discussing fees openly with financial advisors builds trust and prevents unexpected expenses, enhancing the advisory relationship.
- Regular assessments of financial advisor fees help families ensure they receive optimal value for their financial planning services.
- Negotiating fees can empower families to secure better financial outcomes, with strategies like researching market rates and requesting flexibility.
Introduction
Many parents feel lost when faced with the complexities of financial advisor fees. Together, we’ll explore ten essential insights that can help you understand the various fee structures, the importance of transparency, and the benefits of choosing a fiduciary advisor like Bright Advisers. As families navigate the challenges of financial planning, it’s important to understand how to ensure you’re receiving the best value for your investment while avoiding hidden costs. With the right knowledge, you can confidently secure your family’s financial future.
Bright Advisers: Transparent Fee Structures for Financial Planning
Imagine navigating your family’s financial future without the worry of hidden fees or unexpected costs. Bright Advisers is dedicated to transparent personal financial advisor fees, ensuring you have a clear understanding of your financial obligations. When you know exactly what you’re paying for, it helps you focus on your family’s financial goals without the stress of surprise fees. Clients can expect a simple pricing structure tailored to their planning needs, with annual retainer charges typically ranging from $2,500 to $9,200.
While many firms have raised their fees, Bright Advisers is here to provide affordable options that fit your family’s needs, especially for accessing fixed income and alternative asset categories with minimal fund costs. This approach ensures that households can concentrate on their economic well-being while receiving expert advice tailored to their unique circumstances.
Understanding personal financial advisor fees is crucial for families to assess the value they receive from their consultants and to make informed decisions about their financial planning. With no platform charges, trading costs, or commissions, Bright Advisers is committed to offering clear investment management solutions that enhance wealth management accessibility for families.
With Bright Advisers, you can focus on what truly matters-your family’s financial well-being-knowing you’re supported every step of the way.
Understanding Different Types of Financial Advisor Fees
Imagine navigating the complex world of financial fees while trying to secure your family’s future – it’s not easy, is it? Let’s explore how financial advisors charge and what it means for your family’s financial journey:
- Assets Under Management (AUM): This model charges a percentage fee based on the assets managed, usually between 0.5% and 1.5% each year. AUM charges now often cover more than just managing your investments; they focus on your family’s overall financial wellbeing and long-term goals. Some families might still have legacy mutual funds and ETFs with higher fees, while others choose low-fee ETFs to diversify into fixed income or even precious metals and cryptocurrencies. At Bright Advisers, we prioritize minimal fund charges, ensuring families can access wealth management services without excessive expenses.
- Hourly Fees: Advisors may charge for consultations on an hourly basis, with rates typically between $200 and $400. This structure is especially helpful for families seeking specific guidance or one-time financial plans.
- Flat Charges: A fixed amount for particular services, often ranging from $1,000 to $5,000, flat charges are becoming more popular as they provide clarity and predictability in expenses. This model is particularly suitable for households with straightforward financial needs, aligning with Bright Advisers’ mission to improve accessibility to wealth management.
- Retainer Charges: These recurring costs for ongoing service can vary significantly, allowing for a customized approach to money management.
Understanding personal financial advisor fees can be overwhelming for families trying to make the best financial choices. Recent trends show a shift towards greater fee transparency, with many firms updating their pricing structures to foster trust and clarity in client relationships. As younger clients increasingly ask about charges and compare options, clear communication regarding expenses is more crucial than ever. As Andrew Blake observed, open conversations about service costs build trust and strengthen connections between families and advisors, which is vital during this significant transfer of approximately $84 trillion from Baby Boomers to younger generations. By choosing a transparent advisor, you’re not just making a financial decision; you’re investing in your family’s peace of mind for generations to come.
The Role of Fiduciary Duty in Financial Advisor Fees
Imagine feeling overwhelmed by the choices in financial planning while wanting the best for your children. Fiduciary duty means that your advisor is dedicated to acting in your family’s best interests at all times. This commitment includes several key responsibilities:
- Disclosing any potential conflicts of interest.
- Providing transparent information about personal financial advisor fees and services, including a clear structure for personal financial advisor fees with no hidden charges.
- Prioritizing your family’s financial well-being over their own compensation.
When you choose a fiduciary consultant, you’re not just getting advice; you’re gaining a partner who understands your unique family needs. This is especially vital for parents who are planning for their children’s futures. Did you know that only around 4.92% of wealth consultants are fiduciaries? This highlights the importance of discerning when selecting a financial partner.
Consider the case of Emily and Mark, who collaborated with Bright Advisers. Their experience illustrates how fiduciary advisors can help families navigate complex financial landscapes, ensuring long-term economic stability and success. Similarly, Jay and Emma achieved a balanced financial strategy that included optimized tax planning and a customized retirement plan. Their story showcases the transformative impact of personalized wealth management strategies.
By choosing the right financial partner, you can gain the flexibility to make career choices based on your desired work-life balance. Ultimately, this empowers you to create a life that truly reflects your family’s dreams and values.
Identifying Hidden Fees in Financial Advisory Services
Imagine discovering that hidden fees are quietly eating away at your family’s hard-earned savings. These fees in financial advisory services can significantly erode investment returns and come in several common forms:
- Expense Ratios: These are fees charged by mutual funds or ETFs, which can diminish overall returns. Aim for expense ratios under 0.25% to maximize your investment growth. At Bright Advisers, we emphasize low fund charges, ensuring that families can access wealth management services without the burden of excessive costs. Some clients may hold legacy fee-bearing mutual funds and low-fee-bearing ETFs, particularly to gain exposure to fixed income or alternative asset classes like precious metals and cryptocurrencies.
- Transaction Fees: Costs incurred when buying or selling investments can add up, impacting your net returns. Bright Advisers’ clear pricing model removes concealed charges, enabling families to retain more of their funds working for them.
- Management Charges: Frequently not explicitly revealed in initial proposals, these costs can differ significantly and may encompass concealed expenses that impact your portfolio’s performance. At Bright Advisers, we highlight openness and impose straightforward, adaptable monthly charges, ensuring families comprehend precisely what they are paying for. Our investment strategies, including factor investing and smart beta, are designed to enhance returns while minimizing costs.
It’s important to understand how to navigate these hidden expenses, so consider asking your advisor for a clear outline of all personal financial advisor fees and regularly reviewing your account statements together. According to a Harris Poll, concealed charges can cost investors up to 2.5% each year, which could result in substantial losses over time. For example, a $500,000 portfolio generating 6% each year might increase to merely $1.3 million in 25 years with only 1% in extra charges, in contrast to $1.6 million without those charges. This highlights the critical need for transparency in financial advisory services.
Furthermore, a survey revealed that 48% of U.S. adults have faced unanticipated charges, underscoring the importance of being aware of all possible expenses. As Jim Cunningham, a Certified Specialist in Estate, Trust, and Probate Law, states, “Every dollar lost to charges is a dollar that doesn’t grow for you.” By comprehending and recognizing these concealed charges, families can make more educated choices and retain more of their funds working for them. Bright Advisers, established by Kevin Luu and Kathleen Chou in 2010, is committed to assisting families in making prudent financial choices and safeguarding wealth across generations.
Benefits of Choosing Fee-Only Financial Advisors
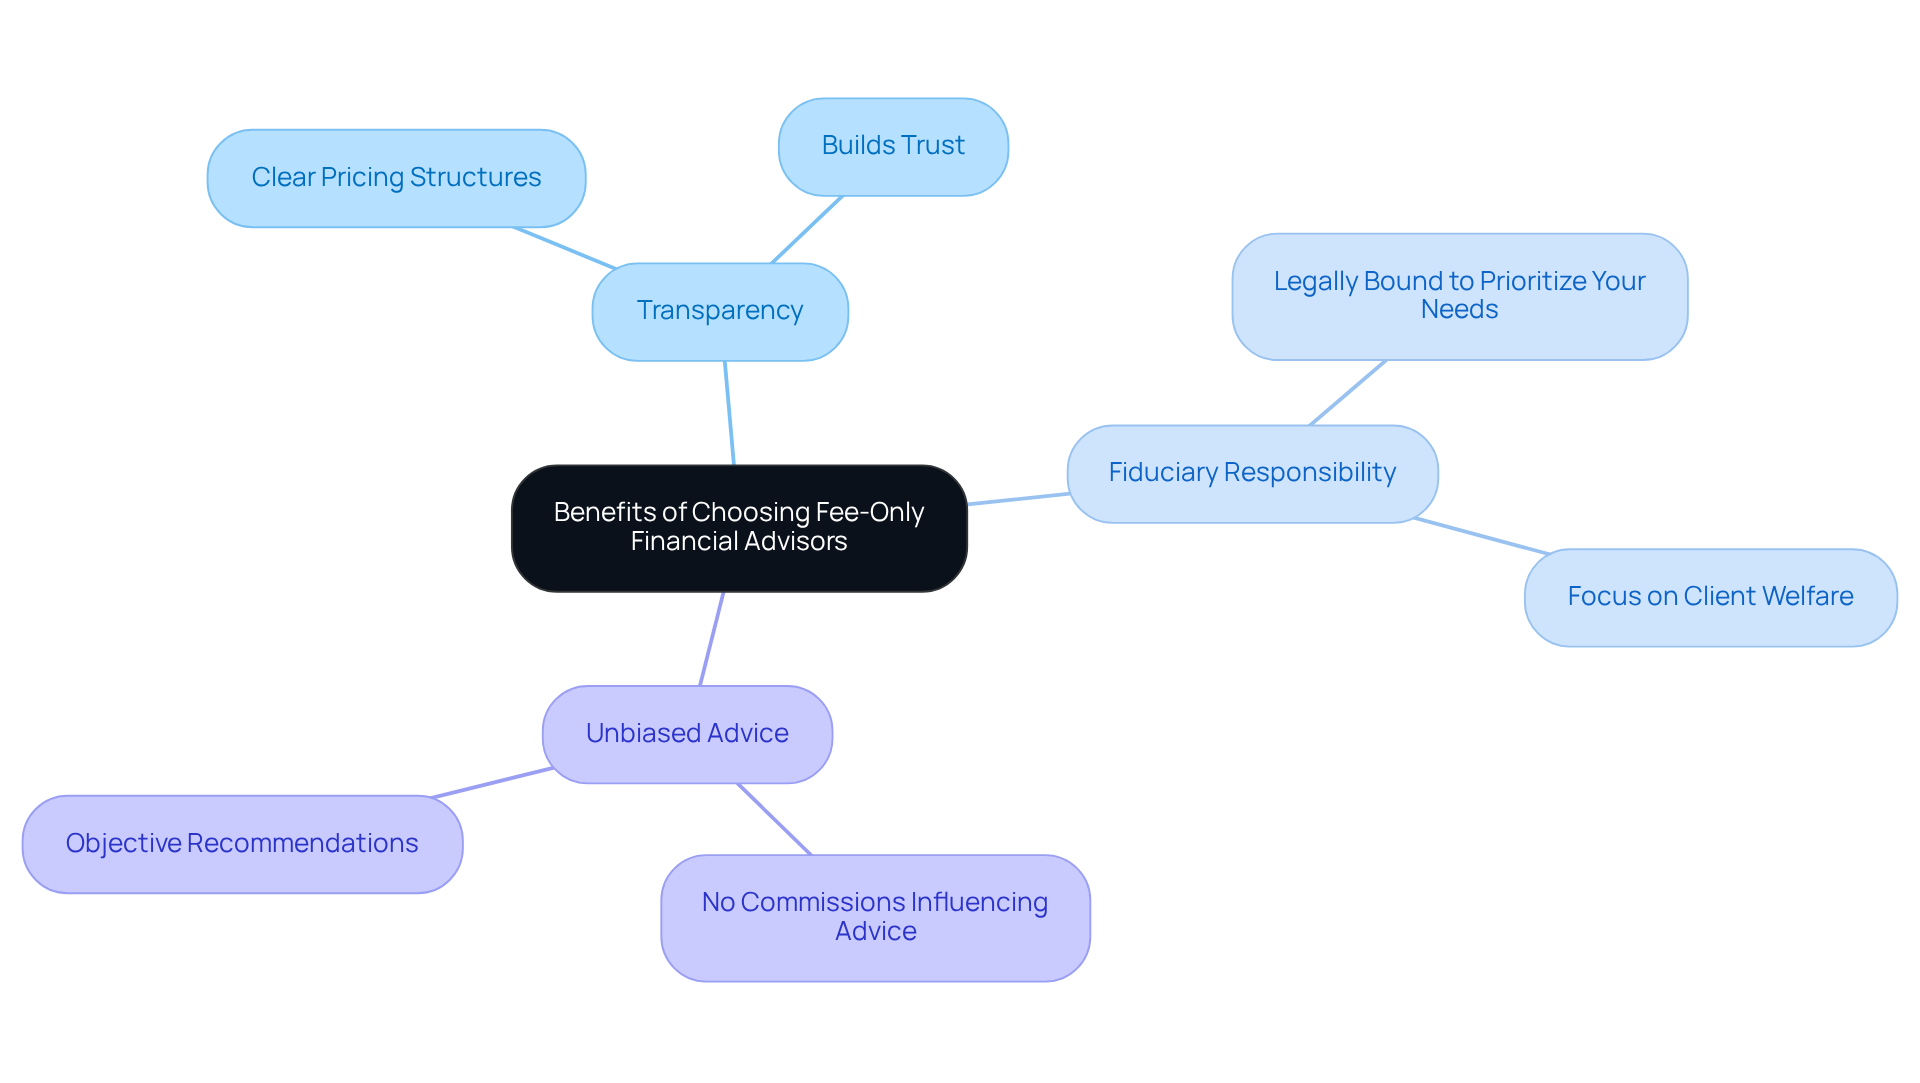
Imagine navigating the complex world of finances with a trusted partner by your side, guiding you every step of the way. Choosing fee-only financial advisors presents numerous advantages for families seeking financial guidance:
- Transparency: You deserve to know exactly what you’re paying for, and that’s why fee-only advisors offer clear pricing structures that build trust. Bright Advisers exemplifies this with their transparent, all-inclusive personal financial advisor fees, which foster confidence in your advisory relationship.
- Fiduciary Responsibility: With fee-only consultants, you can rest easy knowing they’re legally bound to put your family’s needs first. This assurance means that every monetary decision is made with your welfare as the priority.
- Unbiased Advice: Because these advisors don’t earn commissions, their advice is truly focused on what’s best for your family, free from any conflicts of interest. This model is especially beneficial for households that need clear monetary guidance.
At Bright Advisers, we use innovative technology to craft personalized portfolios that fit your family’s unique needs, helping you achieve your dreams while managing today’s responsibilities. This approach helps ensure that you can access customized planning and investment management tailored to your situation, assisting you in reaching your long-term goals while handling current obligations.
With the right support, you can confidently build a secure financial future for your family, knowing you’re not alone on this journey.
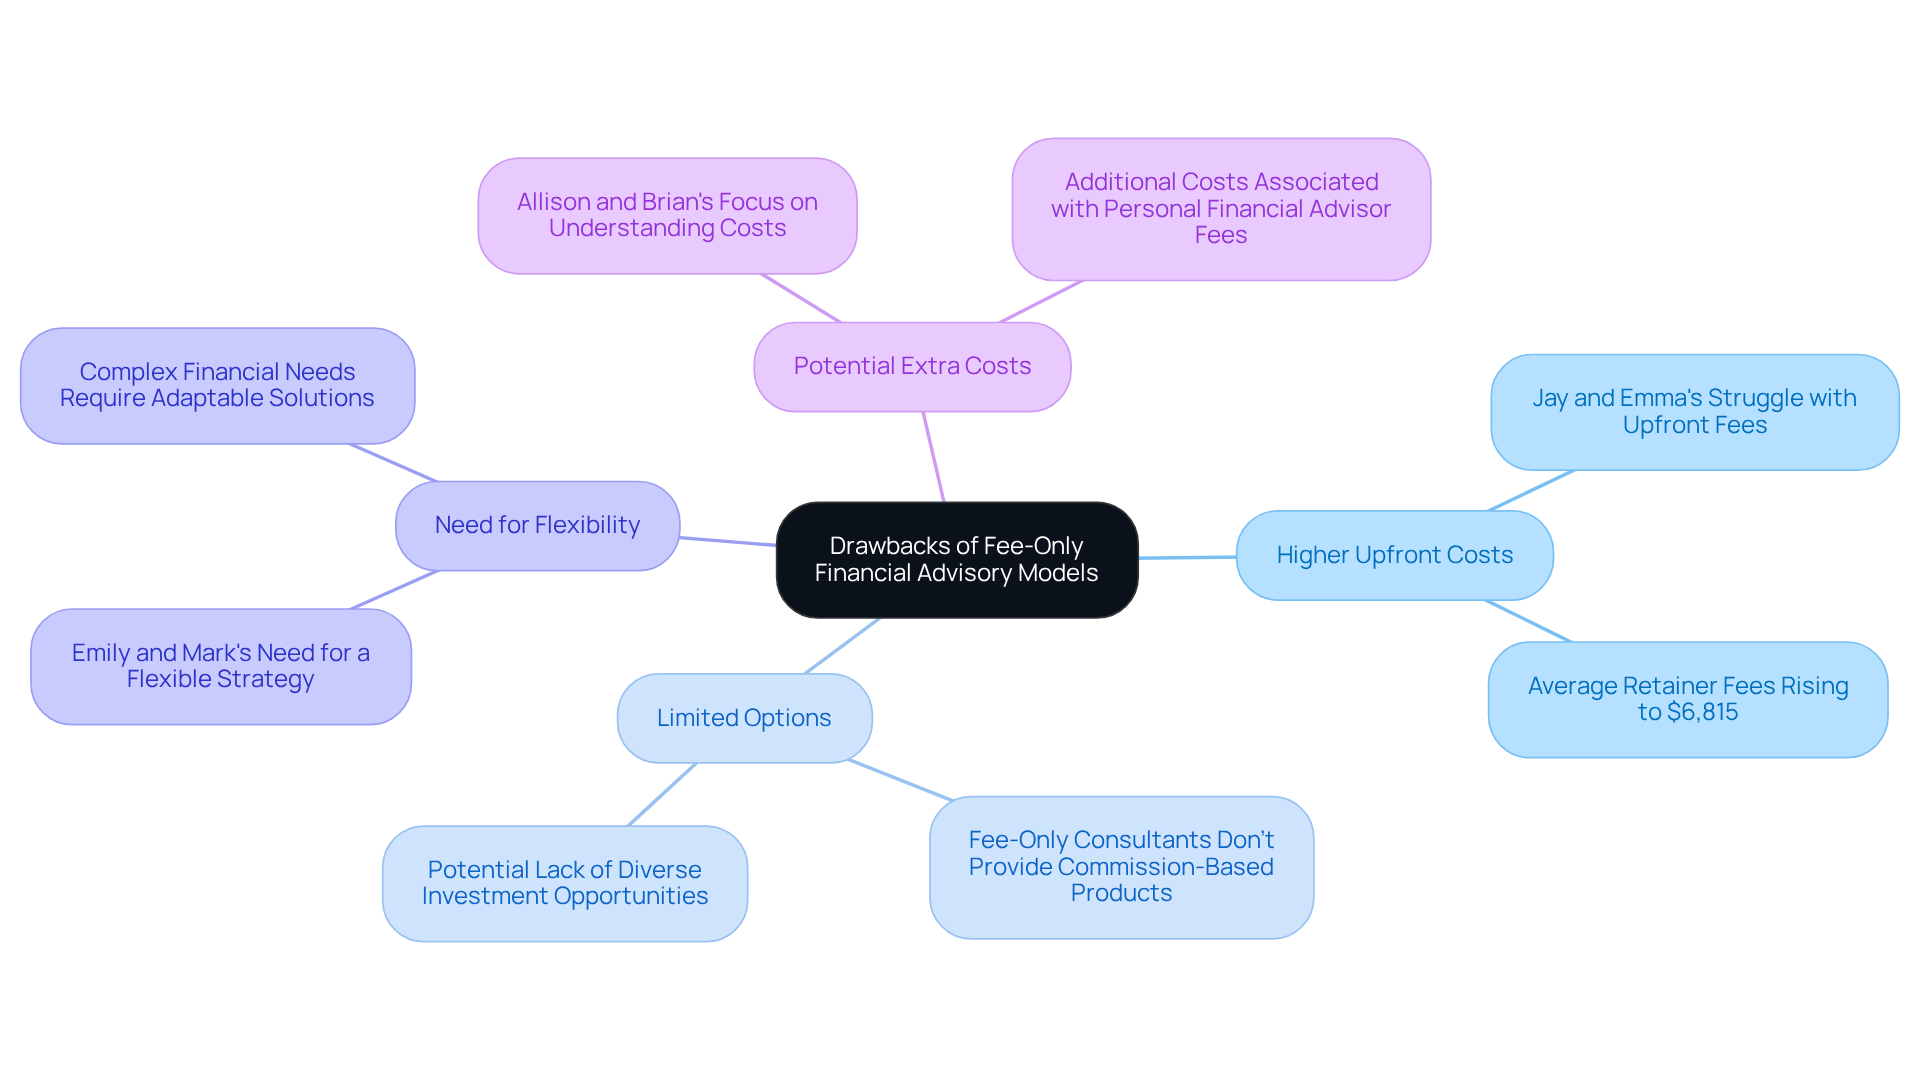
Drawbacks of Fee-Only Financial Advisory Models
Imagine facing the challenge of higher upfront costs when all you want is to secure your family’s future. While fee-only financial advisors, including their personal financial advisor fees, can offer valuable guidance, it’s important to consider both the benefits and challenges they may bring to your family.
You might find that the upfront costs can feel daunting, especially when you’re trying to manage a tight budget. In 2026, the average personal financial advisor fees for financial consultants are expected to rise to around $6,815, reflecting a significant increase. This can be tough for families like yours who are looking for diverse investment opportunities.
Additionally, fee-only consultants typically don’t provide commission-based products, which may limit your options. It’s understandable to hesitate when the value of upfront fees isn’t immediately clear, especially when you’re focused on your family’s needs. For example, Jay and Emma, a couple aiming to lessen monetary stress, initially struggled to see the worth of their investment in planning until they recognized the advantages of a customized approach that catered to their educational and retirement objectives.
If your family has complex financial needs, the fee-only model might not always be the best fit for you. Case studies suggest that families with intricate monetary situations often benefit from a more flexible fee arrangement that can adapt to their changing circumstances. Emily and Mark, for instance, required a thorough strategy that provided them the freedom to decide whether to keep working, necessitating a sophisticated approach to budgeting.
While fee-only consultants strive to keep your best interests at heart, it’s crucial to be aware of potential extra costs associated with personal financial advisor fees that could add up over time. Allison and Brian, who aimed to maximize their monetary potential through proper tax planning, learned that understanding all associated costs was vital to their economic security.
Understanding these factors can empower families to make informed choices that truly align with their financial dreams. Bright Advisers is dedicated to assisting families navigate these complexities with customized wealth management solutions that promote economic security and freedom through personalized planning and tax optimization.
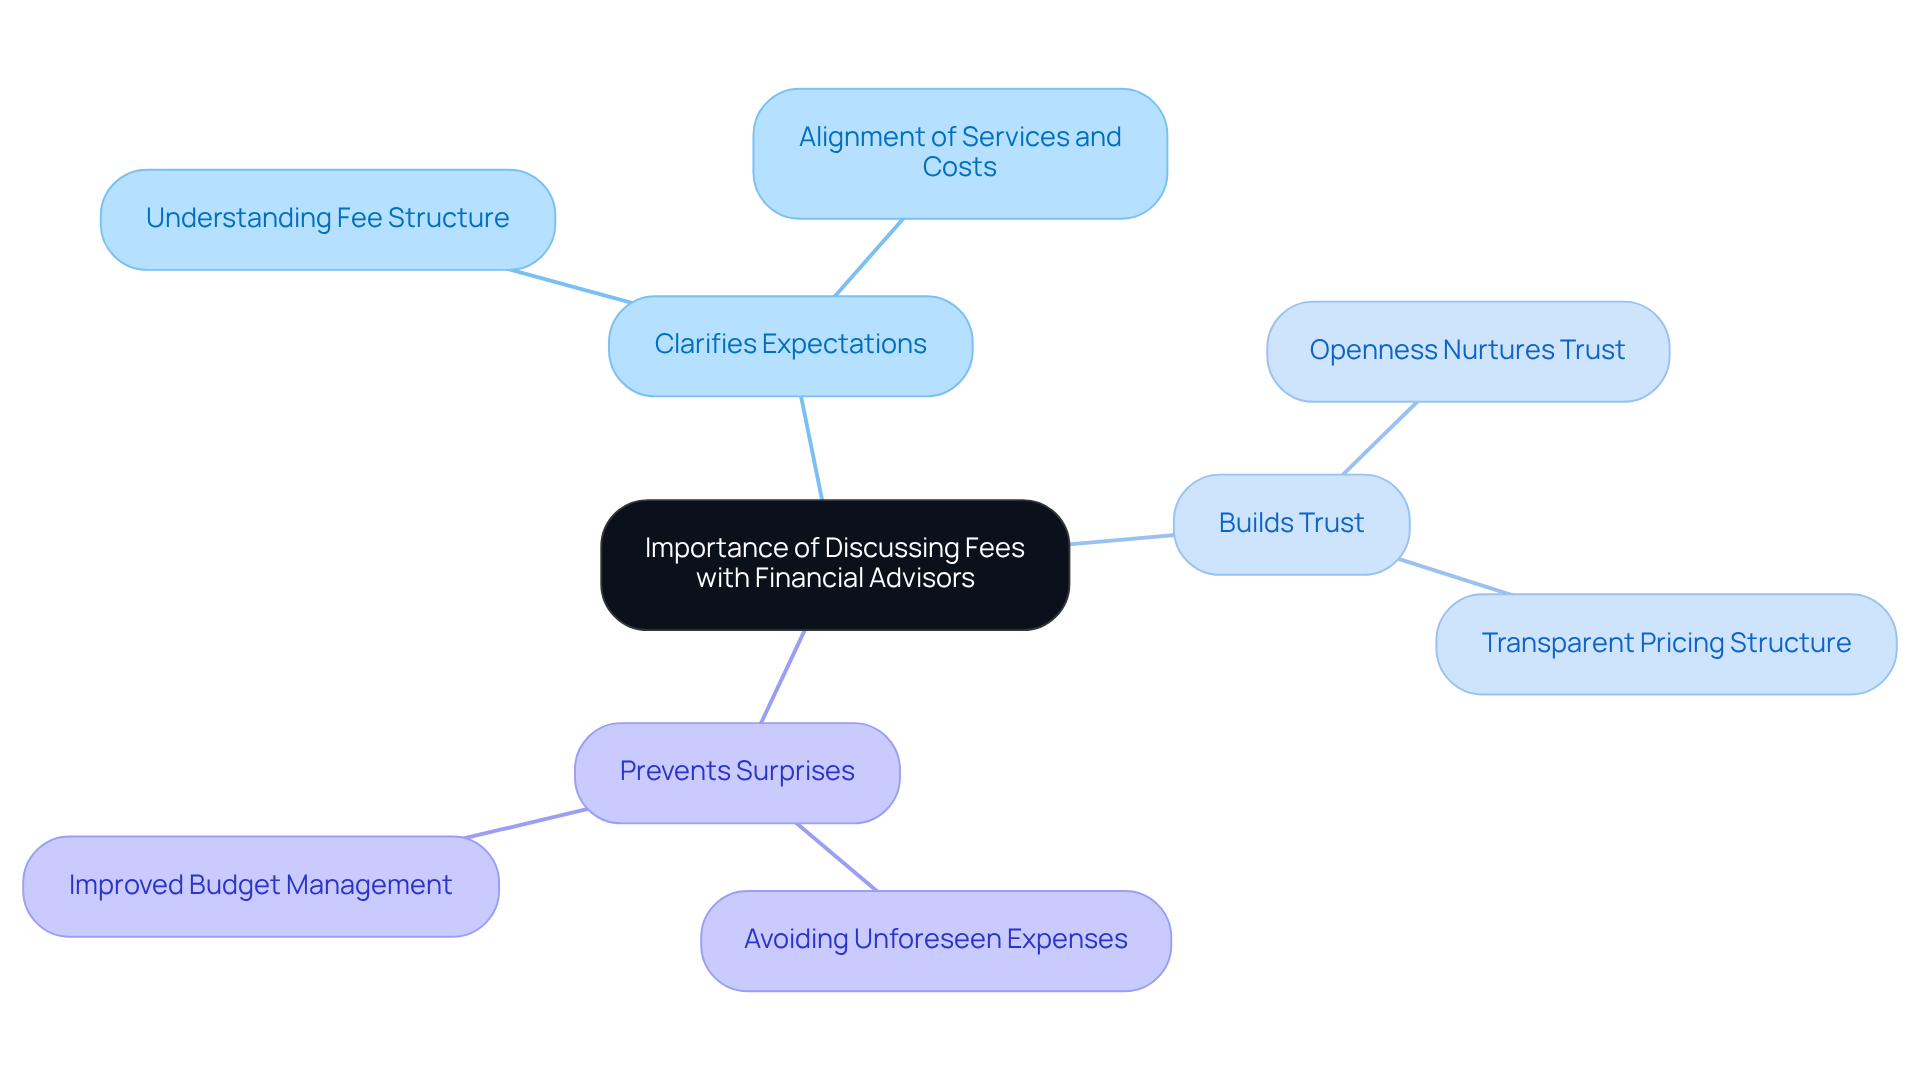
Importance of Discussing Fees with Financial Advisors
Many families feel anxious about discussing personal financial advisor fees, but it’s a conversation that can lead to greater peace of mind.
- Clarifies Expectations: Understanding the fee structure, including Bright Advisers‘ commitment to minimal fund fees, allows families to know precisely what services they are paying for, ensuring alignment between expectations and actual services rendered.
- Builds Trust: Openness in fee conversations nurtures a trusting bond between clients and advisors, which is essential for effective planning. Bright Advisers exemplifies this commitment by providing a transparent, all-inclusive pricing structure with no hidden charges, commissions, or conflicts of interest.
- Prevents Surprises: Discussing charges in advance assists families in evading unforeseen expenses later, enabling improved budget management and planning.
Families should feel confident to ask about costs and ensure they are at ease with the payment arrangements. It’s important to know that many advisors charge personal financial advisor fees for their services, with nearly half using a flat fee model. Understanding these costs can help you feel more in control of your financial journey. Furthermore, the success narrative of clients Jay and Emma demonstrates how Bright Advisers assisted them in formulating a solid monetary strategy that optimized tax planning, assessed education savings options, and crafted a tailored retirement plan. Their joint efforts with a monetary consultant not only instilled confidence but also enabled them to manage funding their children’s education while preparing for retirement, achieving a balance between current obligations and future goals. Founded by Kevin Luu and Kathleen Chou in 2010, Bright Advisers continues to prioritize fiduciary duty and transparency in all client interactions. As the financial planning sector progresses in 2026, engaging in these discussions will be more crucial for households managing their monetary futures.
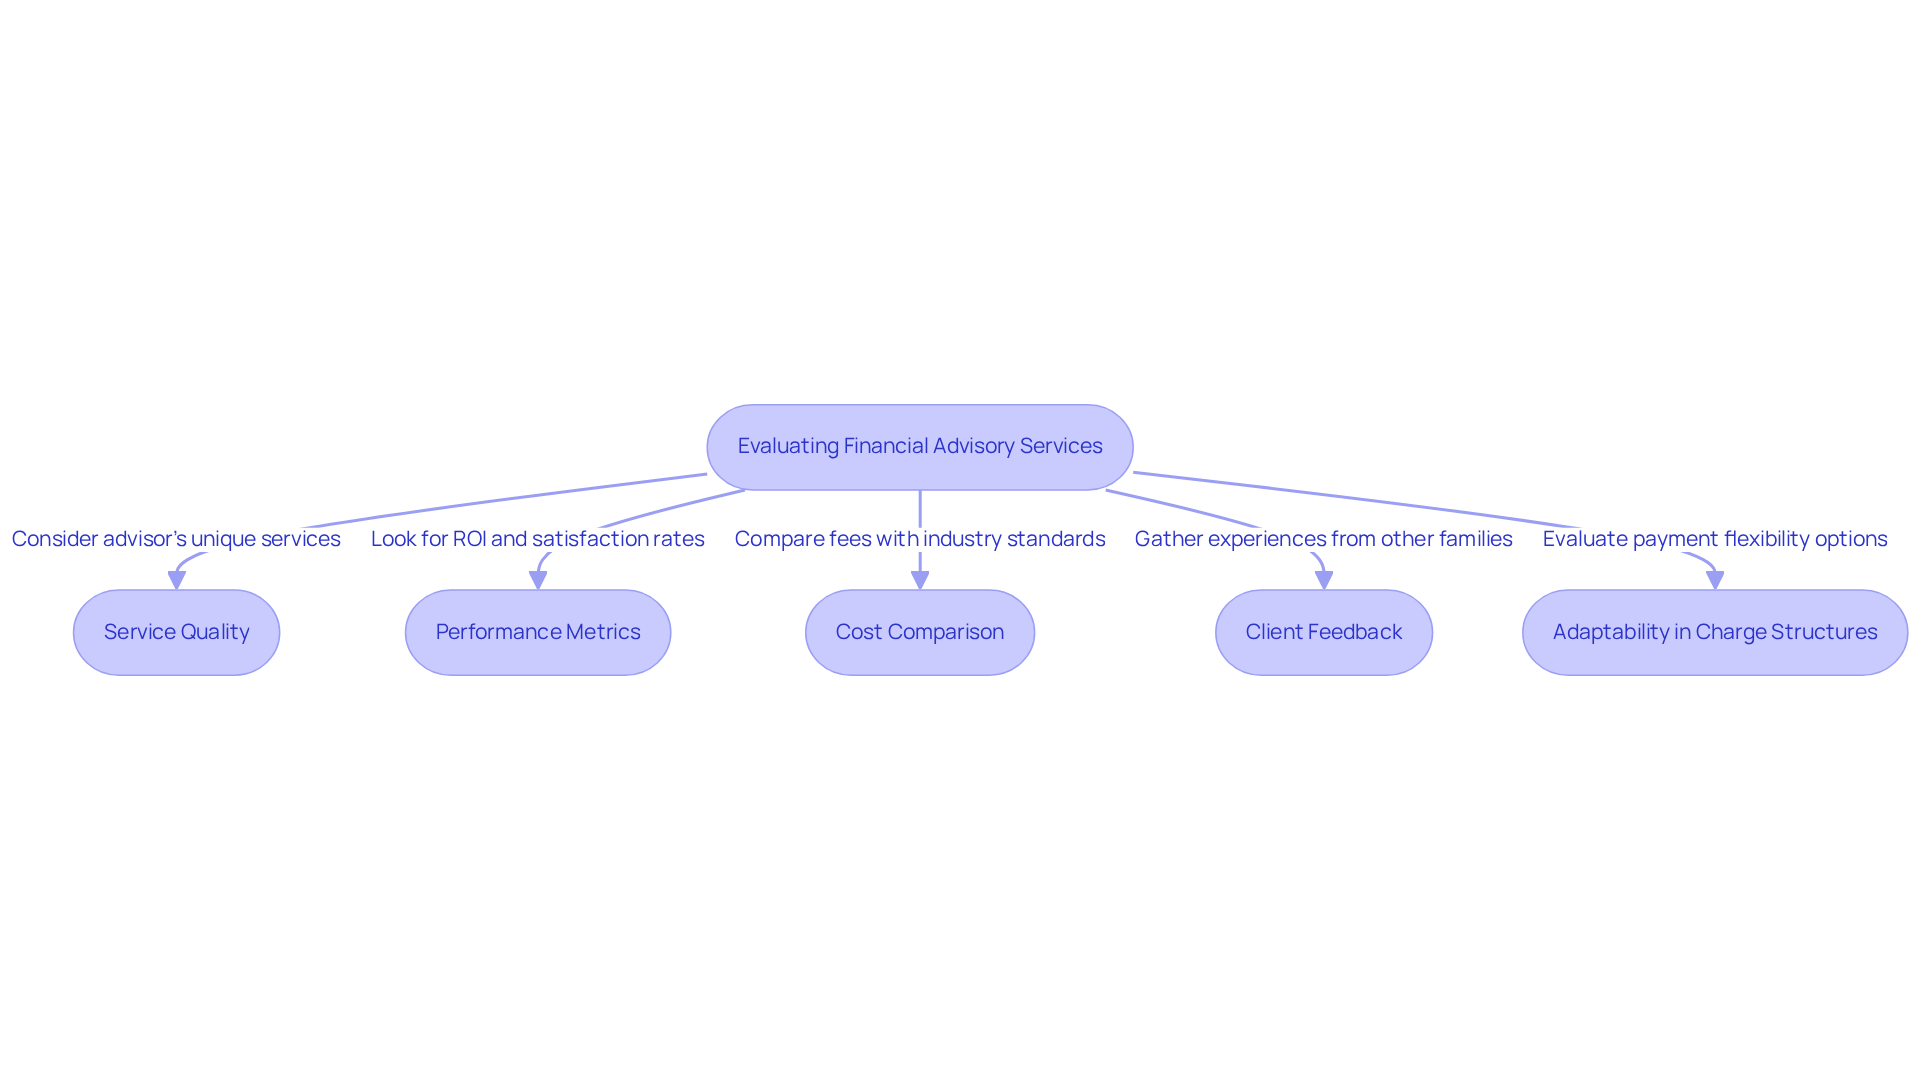
Evaluating Cost-Effectiveness of Financial Advisory Services
Many families feel overwhelmed when trying to navigate the personal financial advisor fees associated with financial advice. To help you make the best decision for your family, consider these key factors:
- Service Quality: Think about whether the advisor provides services that truly cater to your family’s unique needs, like financial planning, tax strategies, and estate planning. A holistic approach can significantly enhance the value you receive. Just look at clients like Allison and Brian, who optimized their tax situation and secured their children’s future through education funding.
- Performance Metrics: It’s important to look at how the consultant has helped families like yours reach their financial goals. Look for metrics like return on investment and client satisfaction rates, which can show how effective the professional is in helping clients retire earlier and build wealth.
- Cost Comparison: Take a moment to see how the personal financial advisor fees compare to what others are charging. As of 2026, the average charges for portfolios under $1 million range from 100 to 120 basis points, while charges for portfolios over $2 million generally decrease to 80 to 100 basis points. Understanding these benchmarks helps ensure that fees are reasonable and aligned with the services provided.
- Client Feedback: Don’t hesitate to ask other families about their experiences with the consultant. High retention rates and positive client experiences often indicate the quality of service and satisfaction, which are essential for households seeking to optimize their planning investment.
- Adaptability in Charge Structures: Consider whether the consultant offers flexible payment options, like unbundled services or retainer charges. This can give you better control over expenses, especially if your household has varying asset levels.
By grasping these key elements, families can feel empowered to make informed choices that secure their financial future. Together, we can navigate this journey toward effective wealth management across generations.
Negotiating Financial Advisor Fees: Tips and Strategies
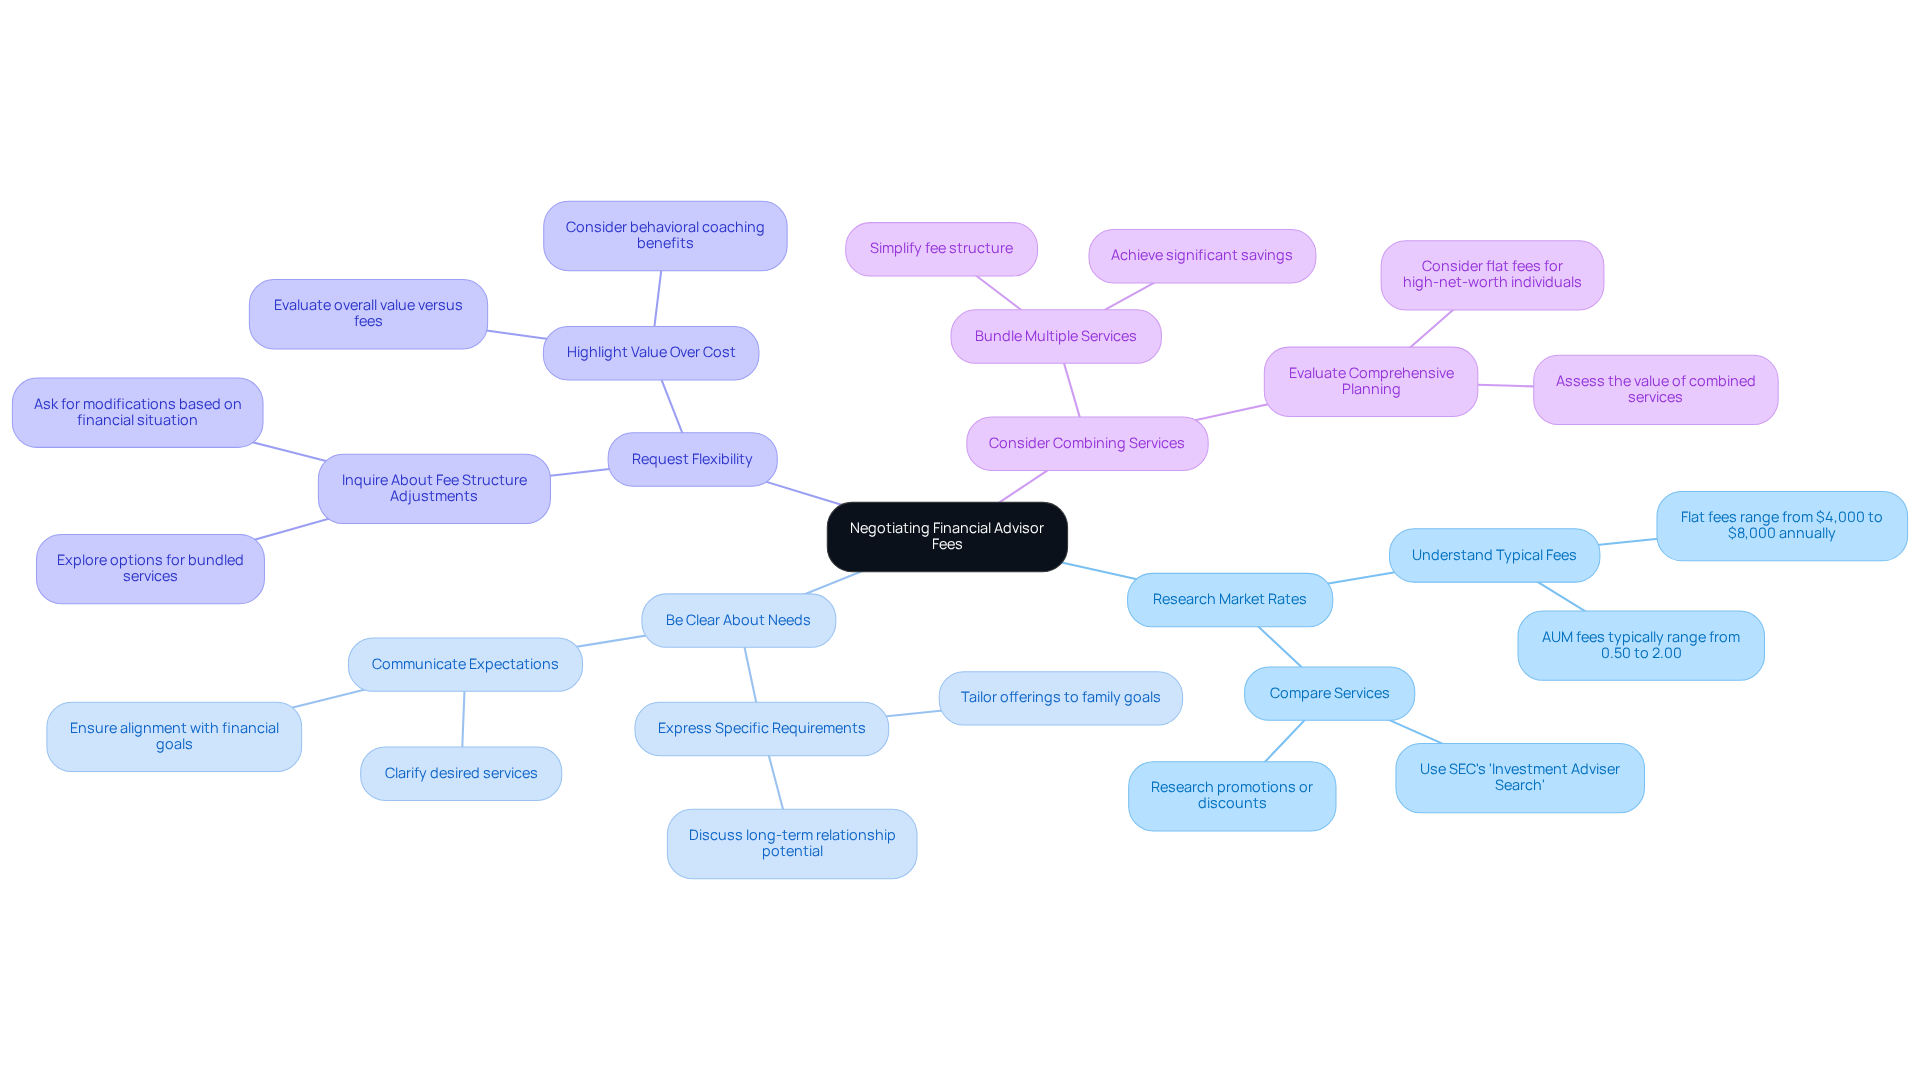
Imagine feeling confident and empowered as you navigate the world of financial planning for your family. When it comes to negotiating personal financial advisor fees, there are several effective strategies that can help you feel more at ease.
- Research Market Rates: Knowing what others typically pay can help you feel more confident in your negotiations. For instance, flat charges for thorough monetary planning can range from $4,000 to $8,000 each year. This understanding gives you a solid foundation for discussions.
- Be Clear About Needs: It’s important to clearly express your specific monetary requirements and expectations to your consultant. This openness allows them to tailor their offerings and possibly adjust their fees to align with your family’s financial goals.
- Request Flexibility: Don’t hesitate to ask if the consultant can modify their fee structure based on your family’s financial situation. Many advisors, including Bright Advisers, are open to negotiation, especially if they see the potential for a long-term relationship. As financial expert Adrianna Adams reminds us, it’s not just about the cost; it’s about the value you receive in return.
- Consider Combining Services: Families can often save money by bundling multiple services together. This not only simplifies the fee structure but can also lead to significant savings.
By using these strategies, families can feel more empowered to negotiate fees with their financial consultants, ensuring they get the best value for their hard-earned money. At Bright Advisers, we believe in being transparent and fair, with no hidden fees and flexible monthly options that work for your family. Plus, behavioral coaching can enhance decision-making, potentially contributing an additional 2-3% each year. Case studies show that families who successfully negotiate costs often achieve better financial outcomes, reinforcing the importance of these strategies. When you take these steps, you’re not just negotiating fees; you’re investing in your family’s future and well-being.
Regularly Assessing Financial Advisor Fees for Optimal Value
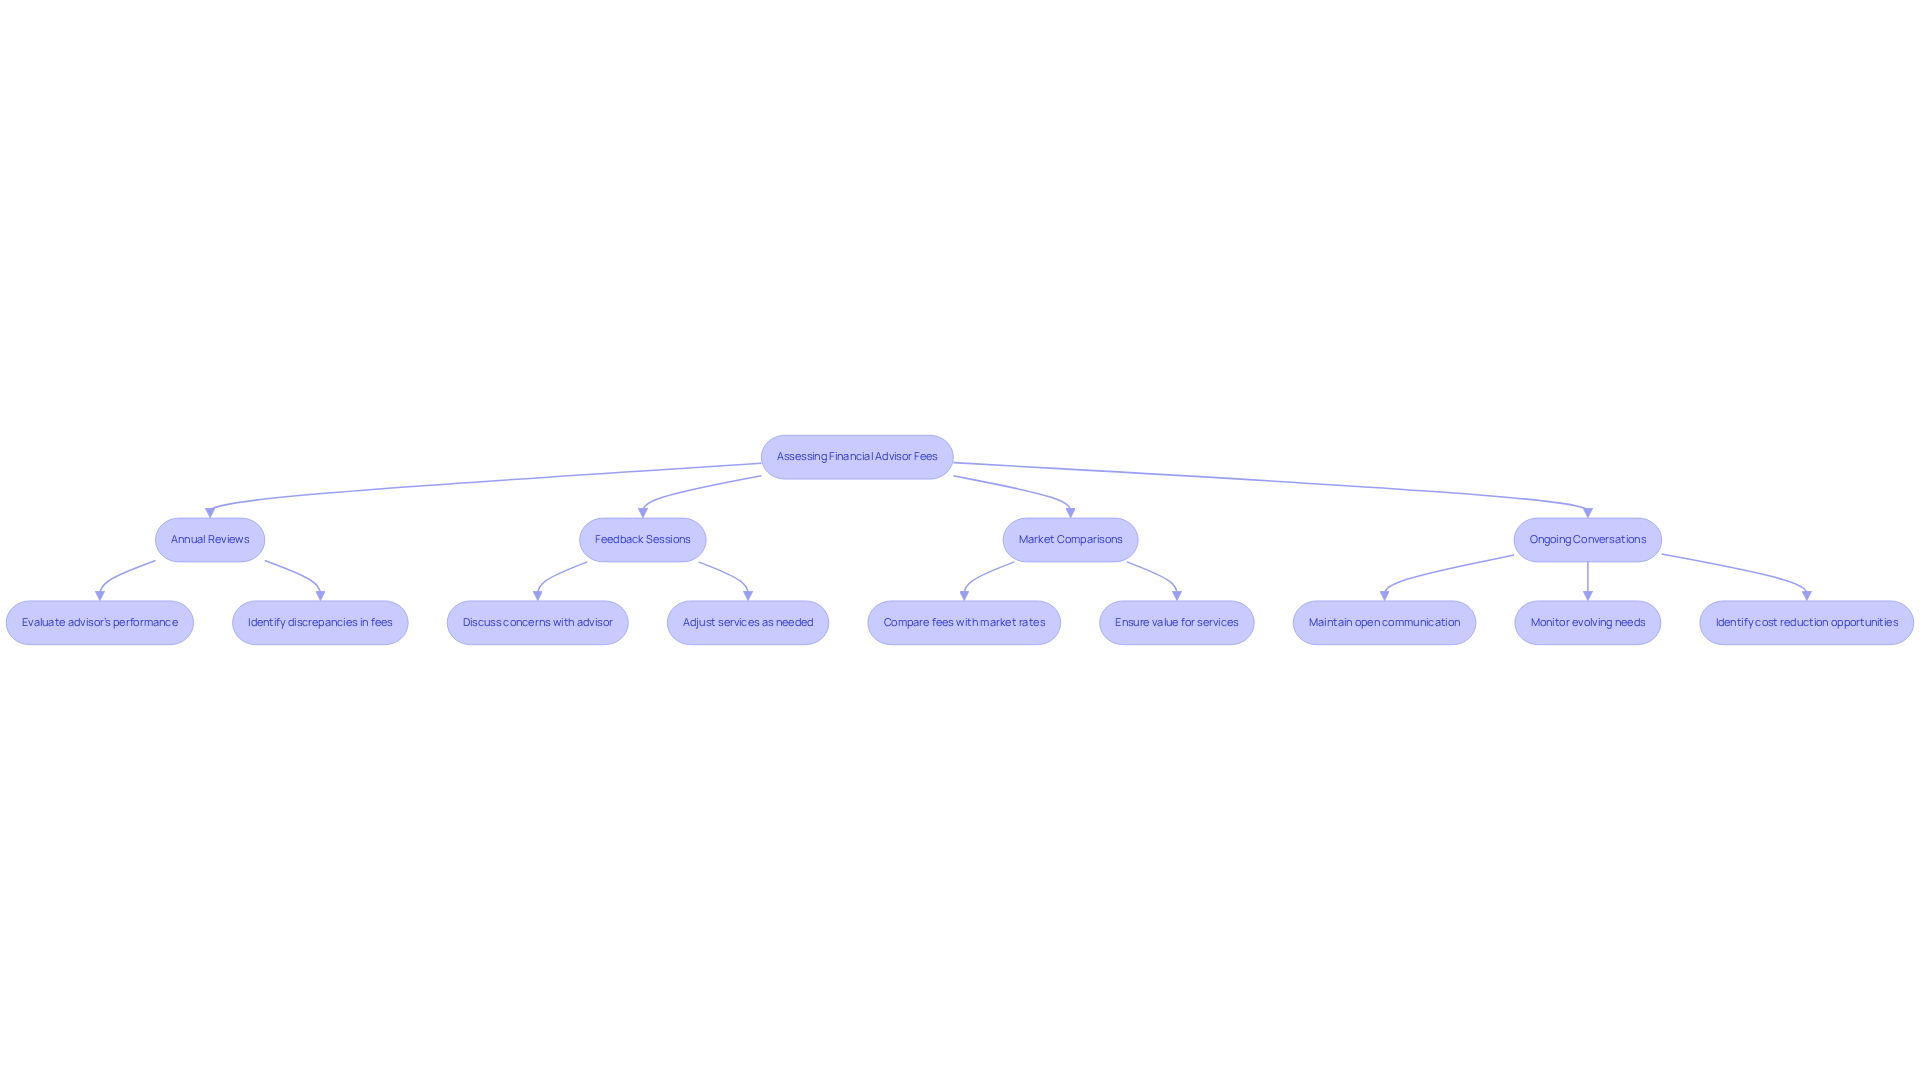
Imagine feeling confident that your family’s financial future is secure and that you’re getting the best value from your financial consultant. Let’s explore some gentle ways to ensure you’re getting the most from your financial consultant.
- Annual Reviews: Consider that many families face an average yearly retainer of about $6,815 for personal financial advisor fees, a figure that can feel daunting. Conducting yearly evaluations of your advisor’s performance and personal financial advisor fees can help you identify any discrepancies between the services provided and the costs incurred. At Bright Advisers, we believe in being open and clear about our pricing, so you never have to worry about hidden fees. Our personalized portfolios are designed with your family’s needs in mind, avoiding costly mutual funds and ETFs.
- Feedback Sessions: Schedule regular check-ins with your advisor to discuss any concerns regarding personal financial advisor fees or the services provided. Open communication can lead to adjustments that better align with the needs of your loved ones. As Sydney Squires notes, “72% of advisory firms use more than one charging method, allowing for greater flexibility in serving a broader range of clients.” Bright Advisers’ approach allows families to customize their financial planning to suit their unique situations, including integrated tax planning and tax-loss harvesting strategies.
- Market Comparisons: Market comparisons are important to understand how your consultant’s personal financial advisor fees compare to those of others. Comparing personal financial advisor fees can help determine whether the charges are warranted based on the services provided. For instance, a $1.5 million portfolio would incur a total annual charge of $15,000 at an effective rate of 1.0%. By keeping an eye on these details, you can ensure that your family is getting the best value from your investments. Bright Advisers’ emphasis on low fund costs can greatly improve the value households obtain from their investments.
- Ongoing Conversations: Keeping an ongoing conversation about costs is so important for families, helping you stay aligned with your evolving needs. Regular evaluations can uncover chances for cost reductions and better service, ultimately improving your household’s economic well-being. Moreover, be wary of excessive personal financial advisor fees, as they can diminish investment returns and should be observed closely. By choosing a firm like Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, you can rest assured that your family’s financial security is in caring hands, guiding you every step of the way.
Conclusion
Imagine navigating the world of financial planning without the stress of hidden fees weighing you down. For young families, understanding personal financial advisor fees can feel overwhelming, but it doesn’t have to be. At Bright Advisers, we believe in keeping things simple and transparent, so you can focus on what truly matters – your family’s future.
When you choose a fiduciary advisor, you’re putting your family’s needs first, creating a bond built on trust and understanding. This relationship is crucial for effective financial planning, allowing you to feel secure in your decisions.
Throughout this article, we’ve shared insights about various fee structures, including:
- Assets under management
- Hourly fees
- Retainer charges
It’s important to discuss these fees openly with your financial advisor, as this builds trust and helps prevent unexpected expenses.
By actively engaging in your financial planning and regularly assessing advisor fees, you can ensure you’re receiving the best value from your financial consultants. Together, we can ensure your family’s financial journey is clear and supportive, paving the way for a brighter future. Bright Advisers is here to assist you in navigating these complexities, helping you make informed decisions that will preserve wealth across generations and align with your unique financial aspirations.
Frequently Asked Questions
What is Bright Advisers’ approach to financial advisor fees?
Bright Advisers is dedicated to transparent personal financial advisor fees, ensuring clients have a clear understanding of their financial obligations without hidden fees or unexpected costs. Their pricing structure is simple and tailored to individual planning needs, with annual retainer charges typically ranging from $2,500 to $9,200.
How do financial advisors typically charge for their services?
Financial advisors may charge in several ways, including: – Assets Under Management (AUM): A percentage fee based on managed assets, usually between 0.5% and 1.5% annually. – Hourly Fees: Charges for consultations on an hourly basis, typically between $200 and $400. – Flat Charges: A fixed amount for specific services, often ranging from $1,000 to $5,000. – Retainer Charges: Recurring costs for ongoing service that can vary significantly.
What is fiduciary duty in the context of financial advising?
Fiduciary duty means that a financial advisor is committed to acting in the best interests of their clients at all times. This includes disclosing potential conflicts of interest, providing transparent information about fees and services, and prioritizing the client’s financial well-being over their own compensation.
Why is it important to understand personal financial advisor fees?
Understanding personal financial advisor fees is crucial for families to assess the value they receive from their consultants and to make informed decisions about their financial planning. Clear communication regarding expenses fosters trust and strengthens the relationship between families and advisors.
What are the benefits of choosing a fiduciary financial advisor?
Choosing a fiduciary financial advisor provides families with a partner who prioritizes their unique needs and financial well-being. Fiduciary advisors are dedicated to transparency and act in the best interests of their clients, which is especially important for families planning for their children’s futures.
How does Bright Advisers ensure affordability in their services?
Bright Advisers offers affordable options that fit families’ needs, particularly for accessing fixed income and alternative asset categories with minimal fund costs. They focus on providing clear investment management solutions without platform charges, trading costs, or commissions.
What is the significance of transparency in financial advising?
Transparency in financial advising is essential for building trust between clients and advisors. It allows families to make informed decisions about their financial planning and ensures they understand the costs associated with the services they receive.
List of Sources
- Bright Advisers: Transparent Fee Structures for Financial Planning
- 2026 State Of Financial Planning Fees (https://lifehealth.com/2026-state-of-financial-planning-fees)
- Average Financial Planning Retainer Fee Surges 52% Since 2023, as Industry Accelerates Toward Planning-Led Advice (https://newsroom.envestnet.com/2026-05-04-Average-Financial-Planning-Retainer-Fee-Surges-52-Since-2023,-as-Industry-Accelerates-Toward-Planning-Led-Advice)
- Understanding Financial Advisor Fees Percentage: Key Insights for Families – Bright Advisers (https://brightadvisers.com/understanding-financial-advisor-fees-percentage-key-insights-for-families)
- 2026 State of Financial Planning Fees Study: 52% Fee Surge | Wally Okby posted on the topic | LinkedIn (https://linkedin.com/posts/wally-okby-b9308b2_financialplanning-wealthmanagement-financialadvisors-activity-7457321063652274176-pYM6)
- 2026 State of Financial Planning Fees (https://resources.envestnet.com/whitepapers/2026-state-of-financial-planning-fees)
- Understanding Different Types of Financial Advisor Fees
- The most influential financial planning trends for advisors in 2026 | Human Interest (https://humaninterest.com/learn/articles/financial-planning-trends-for-advisors)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- The Role of Fiduciary Duty in Financial Advisor Fees
- Fiduciary vs. Financial Advisor (https://smartasset.com/financial-advisor/fiduciary-vs-financial-advisor)
- 27+ Financial Advisor Statistics to Know in 2025 – CircleBlack (https://circleblack.com/financial-advisor-statistics)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- What Percentage of Financial Advisors Are Fiduciaries? – Bright Advisers (https://brightadvisers.com/what-percentage-of-financial-advisors-are-fiduciaries)
- How Many Financial Advisors Are in the U.S.? | Finance Strategists (https://financestrategists.com/financial-advisor/advisor-types/how-many-financial-advisors-are-in-the-us)
- Identifying Hidden Fees in Financial Advisory Services
- The Hidden Costs When Working with Financial Advisors – Spinnaker Investment Group (https://spinninvest.com/finance/the-hidden-costs-when-working-with-financial-advisors)
- The Hidden Fees in Your Investments: What to Look for and How to Protect Yourself (https://langanfinancialgroup.com/the-hidden-fees-in-your-investments)
- Financial Advisors And Their Hidden Fees (https://cunninghamlegal.com/avoiding-hidden-tricky-charges-from-financial-advisors)
- Hidden brokerage fees erode more than investors’ bottom line (https://northcoastam.com/blog/hidden-brokerage-fees-erode-more-than-investors-bottom-line?hs_amp=true)
- Benefits of Choosing Fee-Only Financial Advisors
- 14 Quotes About Financial Planning to Share With Clients | Blueleaf (https://blueleaf.com/blog/14-quotes-about-financial-planning-to-share-with-clients)
- 4 Fee-Only Financial Planning Benefits (https://stagereadyfp.com/blog/fee-only-financial-planning-benefits)
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- Drawbacks of Fee-Only Financial Advisory Models
- Fee-Only vs. Fee-Based Financial Advisors (https://smartasset.com/financial-advisor/fee-based-vs-fee-only-financial-advisor)
- Personal Financial Advisor Cost Guide 2026: Fees & Value (https://blog.guardiawealth.com/personal-financial-advisor-cost-2026)
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- What You Need To Know About Fee-Only Financial Advisors (https://investopedia.com/articles/investing/102014/feeonly-financial-advisers-what-you-need-know.asp)
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- Importance of Discussing Fees with Financial Advisors
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- The Real Cost of a Financial Advisor (https://investopedia.com/articles/personal-finance/021216/can-you-afford-financial-advisor.asp)
- I Have $2.2 Million Invested and Pay a 1% Advisor Fee. Is That Too High? (https://finance.yahoo.com/news/2-2-million-invested-advisor-134203276.html)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Evaluating Cost-Effectiveness of Financial Advisory Services
- Cerulli Associates | More Than 72% of Financial Advisors Are… (https://cerulli.com/press-releases/more-than-72-of-financial-advisors-are-compensated-by-fee-based-models)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Financial advisor industry statistics: key data and trends (https://unbiased.com/pro/discover/trends-insight/financial-advisor-industry-statistics)
- The Most Important KPIs for Financial Advisors to Track – Independent Financial Partners (https://ifpartners.com/kpis-financial-advisors-should-track)
- Key Performance Indicator (KPI) Metrics For Financial Advisors (https://kitces.com/blog/what-are-the-key-performance-indicators-kpis-for-your-financial-planning-firm)
- Negotiating Financial Advisor Fees: Tips and Strategies
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- How to Compare Financial Advisor Fees | Medical Economics (https://medicaleconomics.com/view/how-to-compare-financial-advisor-fees)
- Financial Advisor Cost | Fee Structures & Average Cost Backed by Data (https://financestrategists.com/financial-advisor/advisor-cost)
- Are Financial Advisor Fees Negotiable? (https://smartasset.com/financial-advisor/are-financial-advisor-fees-negotiable)
- Regularly Assessing Financial Advisor Fees for Optimal Value
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- Financial Advisor Statistics in 2026: Growth and Trends in the Financial Advisory Industry in the USA (https://randallwealthgroup.com/financial-advisor-statistics)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading