

Key Highlights:
- Bright Advisers offers personalised financial planning tailored to young families, utilising provisions of the SECURE Act 2.0.
- The SECURE Act 2.0 allows employers to provide matching contributions to Roth accounts, enabling tax-free growth.
- Starting in 2025, individuals aged 60-63 can contribute an additional $10,000 to their retirement savings, enhancing financial security.
- Families can roll over 529 plans into Roth IRAs after 15 years, promoting savings for both education and retirement.
- The SECURE Act 2.0 introduces automatic enrolment in savings plans, increasing participation rates among employees.
- Tax planning strategies, including tax-loss harvesting and optimising contributions to tax-advantaged accounts, can significantly reduce tax liabilities.
- Bright Advisers provides educational resources to help families understand financial concepts and navigate the SECURE Act 2.0.
- Leveraging technology can simplify retirement account management, enhancing efficiency in financial planning.
- Families should consult financial advisors to develop personalised strategies that align with the changes introduced by the SECURE Act 2.0.
Introduction
The SECURE Act 2.0 is transforming the way families think about retirement savings, especially for those eager to secure their financial futures. Imagine having the chance to enhance your savings strategies without the immediate tax burden—thanks to innovative provisions like employer match Roth contributions, this is now a reality.
However, navigating these changes can feel overwhelming. How can families effectively leverage these new benefits to maximize their financial potential? It’s important to understand that you’re not alone in this journey. This article explores ten key insights designed to empower families, helping you take full advantage of the SECURE Act 2.0. Together, we can ensure a brighter financial outlook for generations to come.
Bright Advisers: Personalized Financial Planning Aligned with SECURE Act 2.0
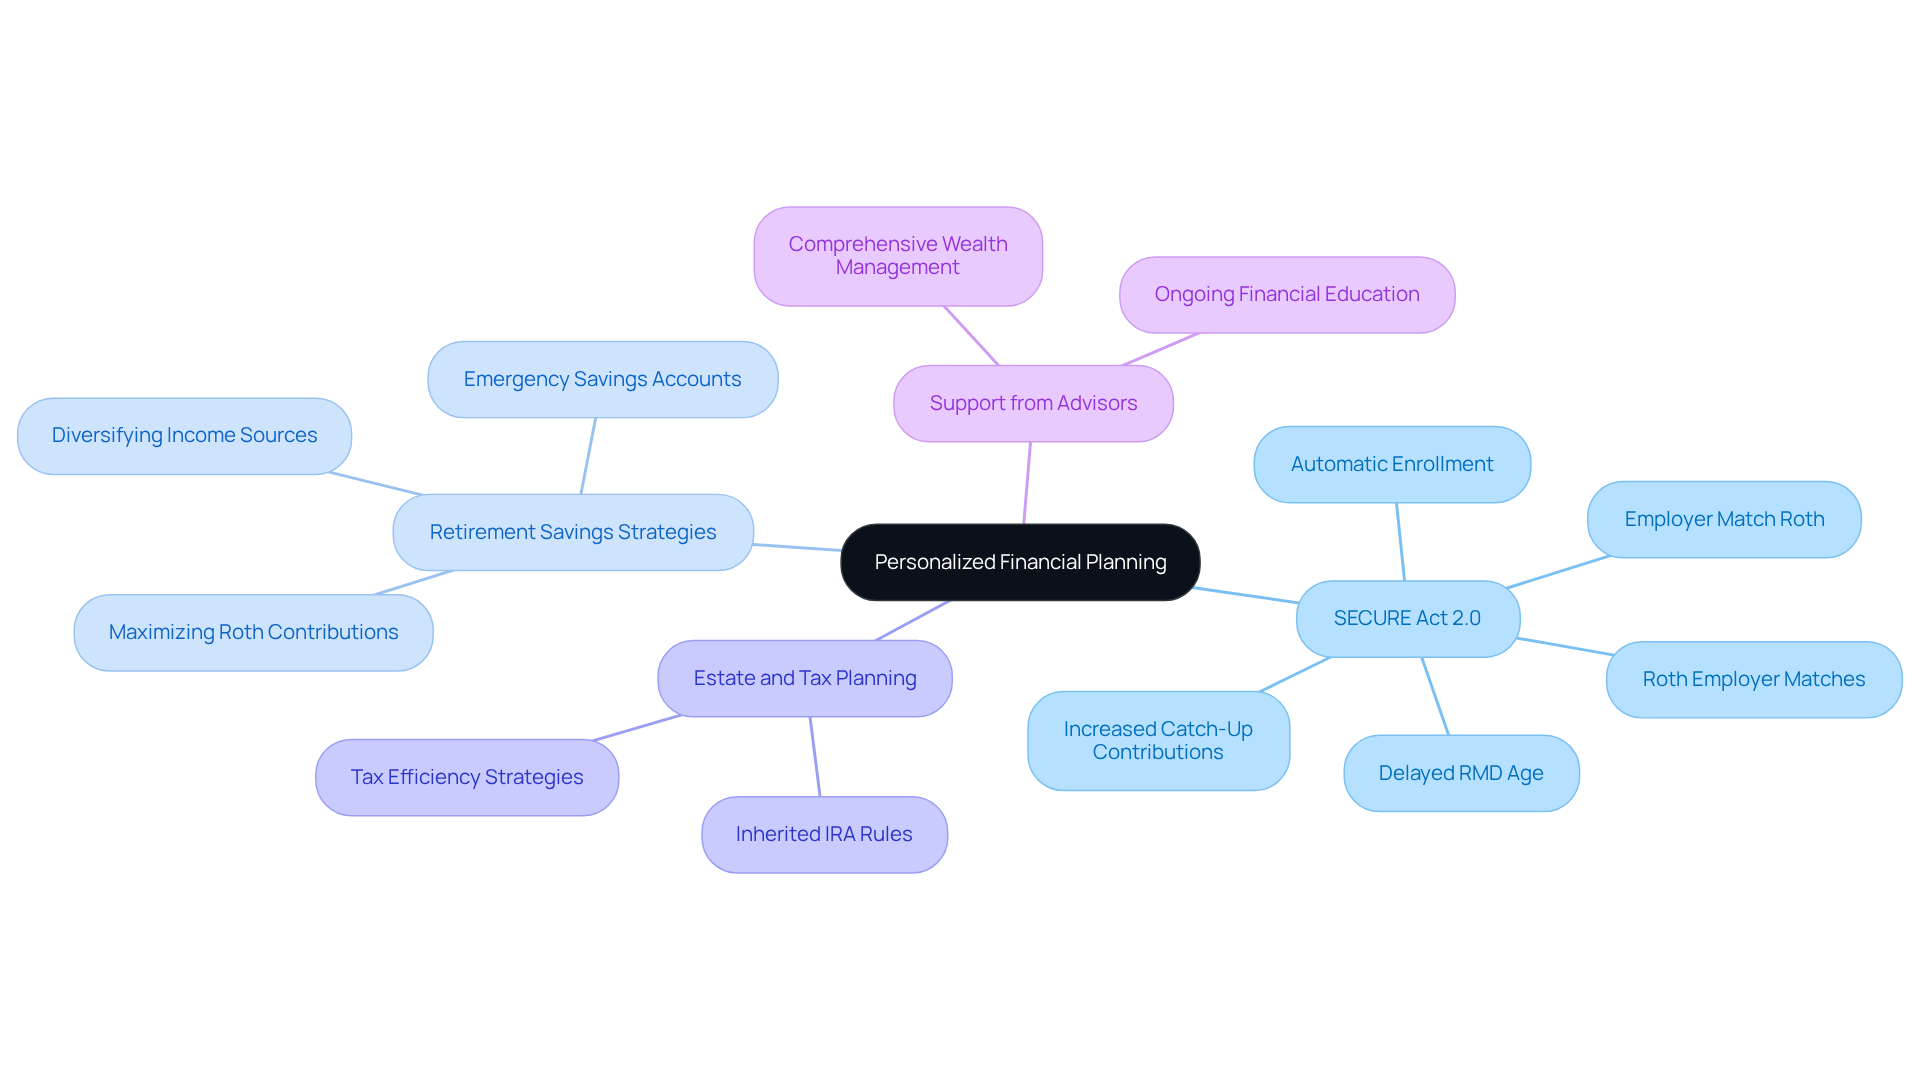
Bright Advisers understands the challenges young parents face when it comes to financial planning. By effectively utilizing the provisions of the SECURE Act 2.0, we enhance our personalized planning services to better serve your family’s needs. Imagine being able to maximize your savings for the future with strategies that highlight the SECURE Act 2.0 employer match Roth, including increased catch-up contributions and the introduction of Roth employer matches. This proactive approach not only clarifies the complexities of retirement planning but also empowers you to make informed choices that secure your economic future while prioritizing your children’s well-being.
We know that estate and tax planning can feel overwhelming, but you don’t have to navigate this journey alone. Our dedicated teams of advisors are here to assist you every step of the way, ensuring a comprehensive strategy for wealth management. With our FamilyKnowledge™ Base, families can organize and protect their values, enhancing their legacy for generations to come.
As financial advisors often stress, adapting to these legislative changes is crucial for optimizing benefits and ensuring long-term wealth growth. Together, we can navigate this journey, making sure your family’s future is bright and secure. We’re here for you, ready to support you in achieving your financial goals.
Understanding Employer Match Roth Contributions Under SECURE Act 2.0
Imagine if you could boost your family’s savings without the immediate tax burden. With the secure act 2.0 employer match roth, employers now have the opportunity to provide matching payments to Roth accounts. This means your deposits can grow tax-free, giving you a wonderful chance to secure your family’s future.
At Bright Advisers, we understand the unique challenges young households face. We emphasize the importance of hyper-personalized investment portfolios and thoughtful planning strategies tailored just for you. By optimizing the secure act 2.0 employer match roth contributions within your overall savings plan, you can effectively manage your resources, reduce financial stress, and protect what matters most.
Our innovative approach ensures that you not only take full advantage of the benefits your employer offers but also enhance your wealth through expert tax planning and customized financial solutions. Together, we can navigate this journey, making sure your family’s financial future is bright and secure.
Adapting Retirement Savings Strategies to SECURE Act 2.0 Changes
Families, it’s time to take a fresh look at your savings strategies with the SECURE Act 2.0. This new legislation brings important changes that can truly enhance your financial planning. For instance, starting in 2025, individuals aged 60-63 can contribute significantly more to their savings—up to $10,000 or 50% above the standard catch-up amount. This is especially beneficial for those nearing retirement who may need to boost their savings quickly.
Imagine being able to designate employer matches as Roth contributions through the SECURE Act 2.0 employer match Roth. This means that the money your employer adds can grow without being taxed, giving you a wonderful opportunity to enhance your retirement savings while easing future tax burdens.
Working with a financial planner can make a world of difference in tailoring your investment strategies to fit these new provisions. Take Allison and Brian, for example. They reached out to Bright Advisers and found ways to optimize their tax situation while also securing their children’s educational future. Their partnership not only helped them navigate the complexities of tax optimization but also positioned them to retire sooner, allowing them to enjoy precious moments with their loved ones.
Statistics reveal that many households aged 60-63 are taking advantage of catch-up contributions, reflecting a proactive approach to financial planning. A recent survey found that 45% of households in this age group have utilized the increased limits to enhance their savings for the future. As families reassess their strategies, these changes can pave the way for a more secure financial future, enabling you to focus on what truly matters—your loved ones.
Additionally, retirement plans established after December 29, 2022, must increase contribution percentages by at least 1% each year. This underscores the importance of staying informed and proactive in your retirement planning.
Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.

Exploring Retroactive Provisions of the SECURE Act 2.0
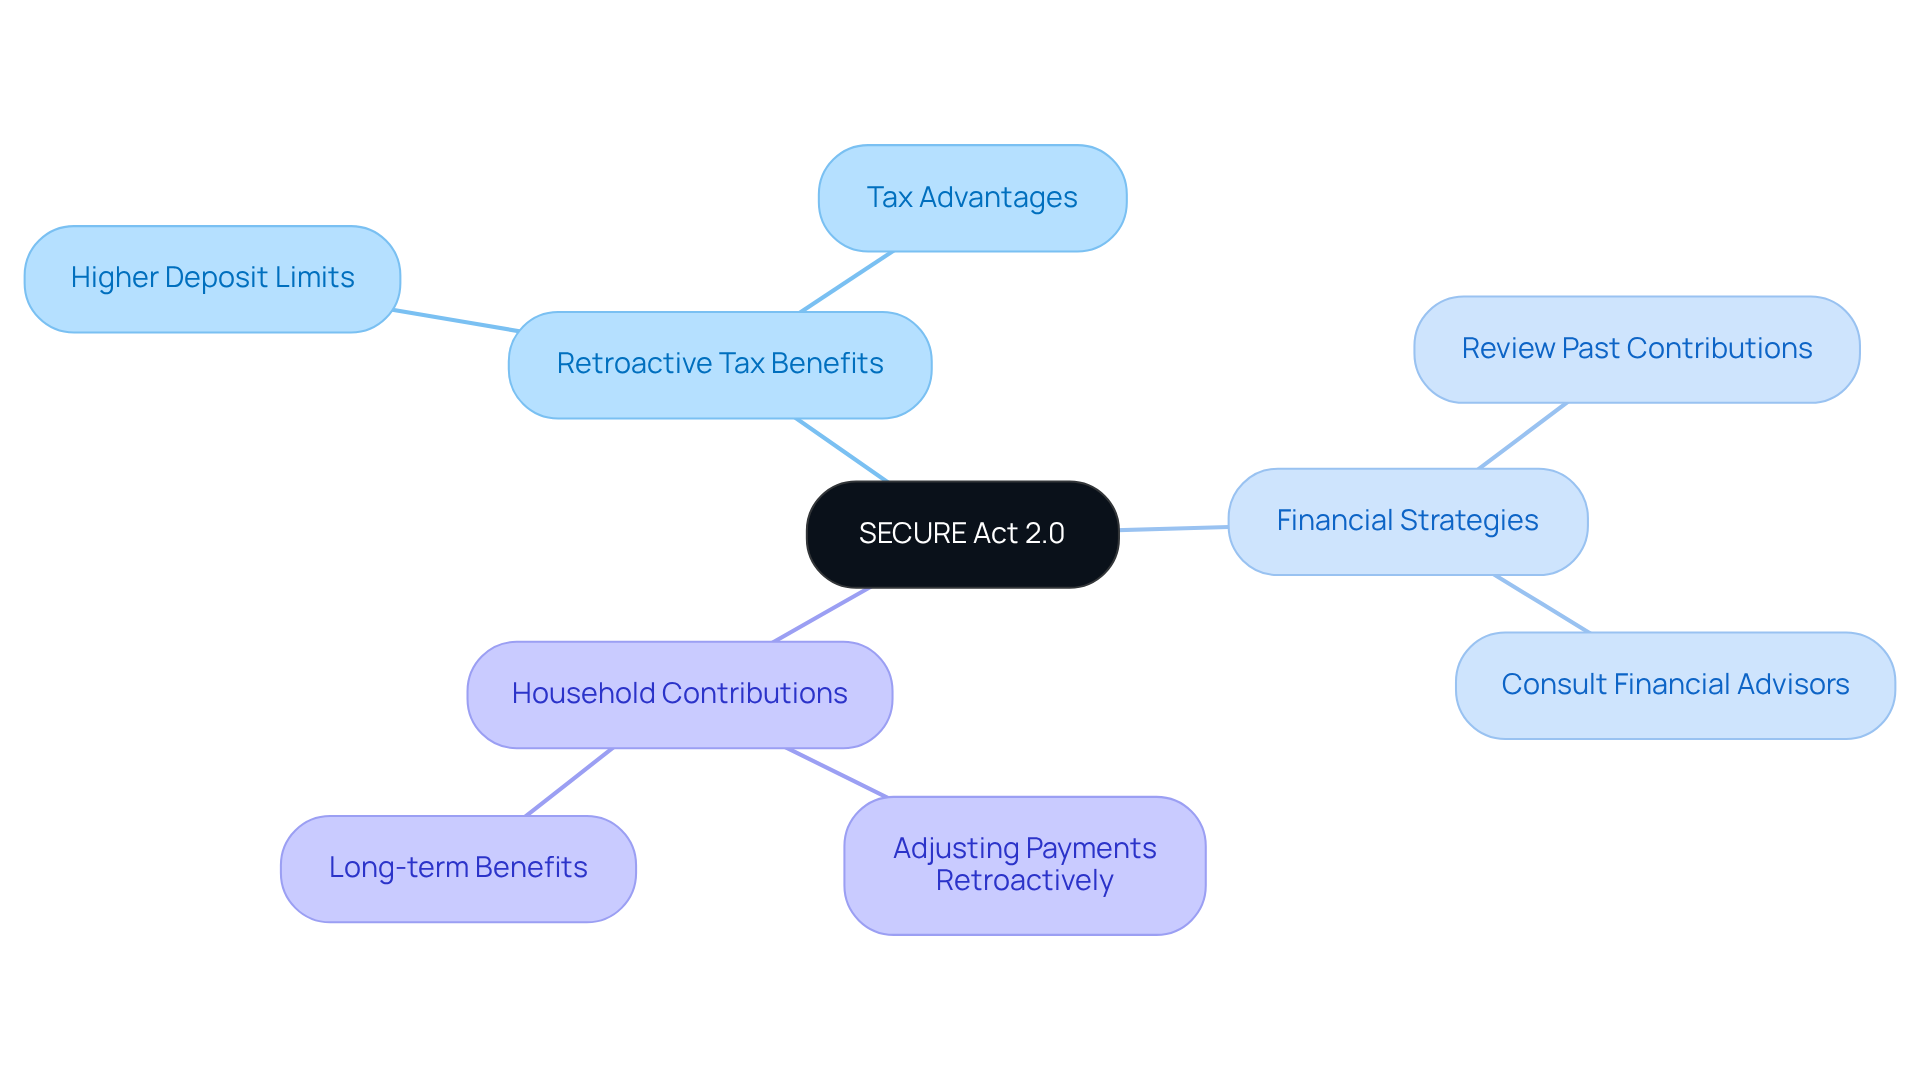
The SECURE Act 2.0 brings some exciting changes that could really help families rethink their financial strategies. Imagine if payments you made in previous years could now qualify for better tax advantages or higher deposit limits. Recent data shows that many households might be able to tap into these retroactive tax benefits, potentially saving thousands of dollars.
It’s important for families to take a moment to review their past contributions and consider reaching out to financial advisors. Together, you can explore how to make the most of these provisions to boost your savings for the future. For example, if your household has previously contributed to savings accounts, you might find that adjusting those payments retroactively could lead to significant long-term benefits.
As one tax expert wisely noted, ‘Enhancing previous contributions is not solely about making up for lost time; it’s about strategically arranging your household’s economic future.’ This proactive approach not only helps improve savings for the years ahead but also aligns with broader financial goals, ensuring your family is well-prepared for what lies ahead.
Remember, you’re not alone in this journey. We’re here for you, ready to help you navigate these changes and make the best decisions for your family’s financial future.
Ameritas: Existing Provisions Supported by SECURE Act 2.0
Bright Advisers understands the challenges families face when it comes to financial planning, and they’ve positioned their options to align with the secure act 2.0 employer match roth, making it easier for households to access valuable benefits. Imagine being able to watch your savings grow tax-free with contributions from the secure act 2.0 employer match roth—this is a game changer for long-term financial security.
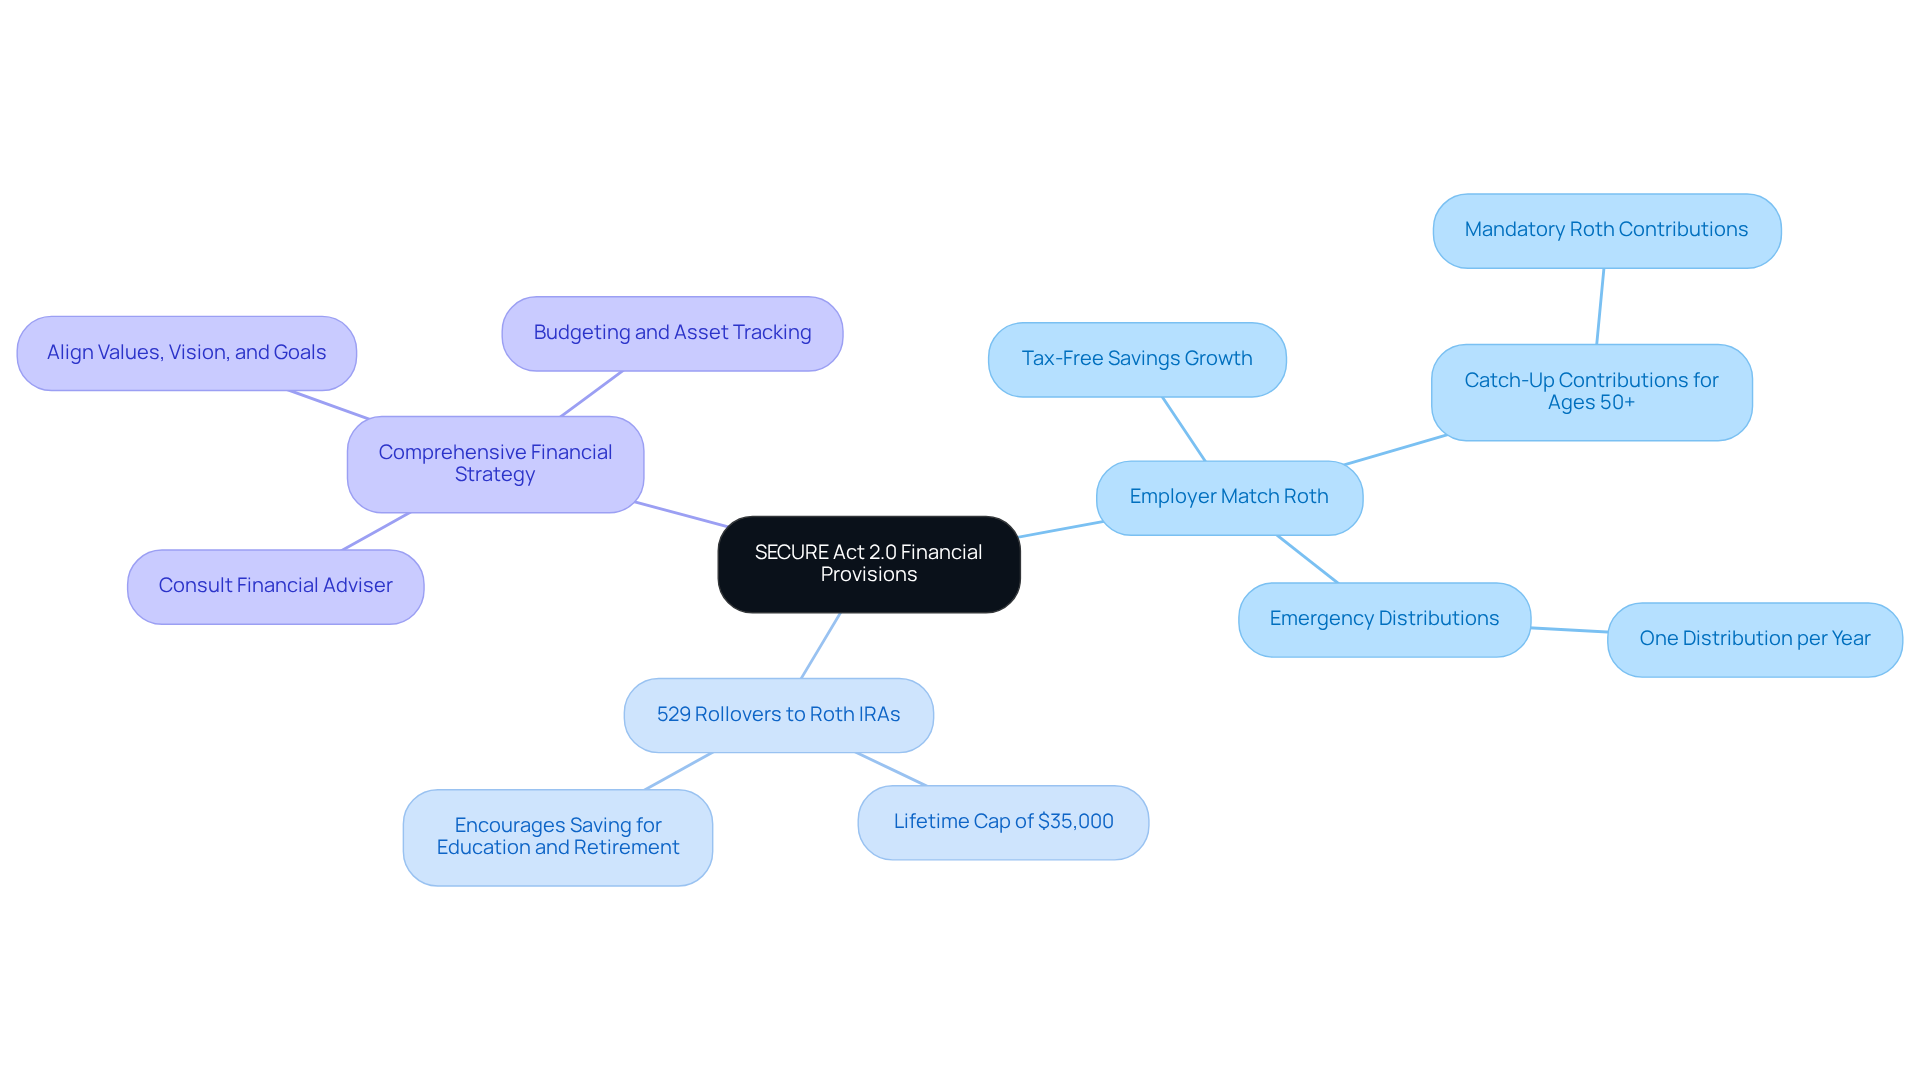
Now, families can roll over 529 plans into Roth IRAs after keeping the plan for at least 15 years, with a lifetime cap of $35,000. This flexibility encourages parents to save not just for their child’s education, but also for their own financial future. Financial expert Seth J. Edgil notes, ‘The new provisions introduced by the SECURE Act 2.0 employer match Roth should offer some assistance to those Americans who feel they are lagging in their financial planning.’
It’s important to explore how these provisions can fit into your family’s financial strategy. By doing so, you can maximize your savings potential and secure a brighter future for your loved ones. Bright Advisers emphasizes the importance of a comprehensive household monetary strategy that aligns your values, vision, and goals with budgeting, asset tracking, and tax planning.
To effectively integrate the secure act 2.0 employer match roth with Roth matching contributions and utilize strategies like the Tactical Portfolio or Opportunity Strategy, we encourage you to consult with a financial adviser. Together, we can customize your retirement plans to meet your unique needs, helping to ease financial worries and ensure a secure future for your family. Remember, we’re here for you every step of the way.
Educational Resources for Families on SECURE Act 2.0 Implications
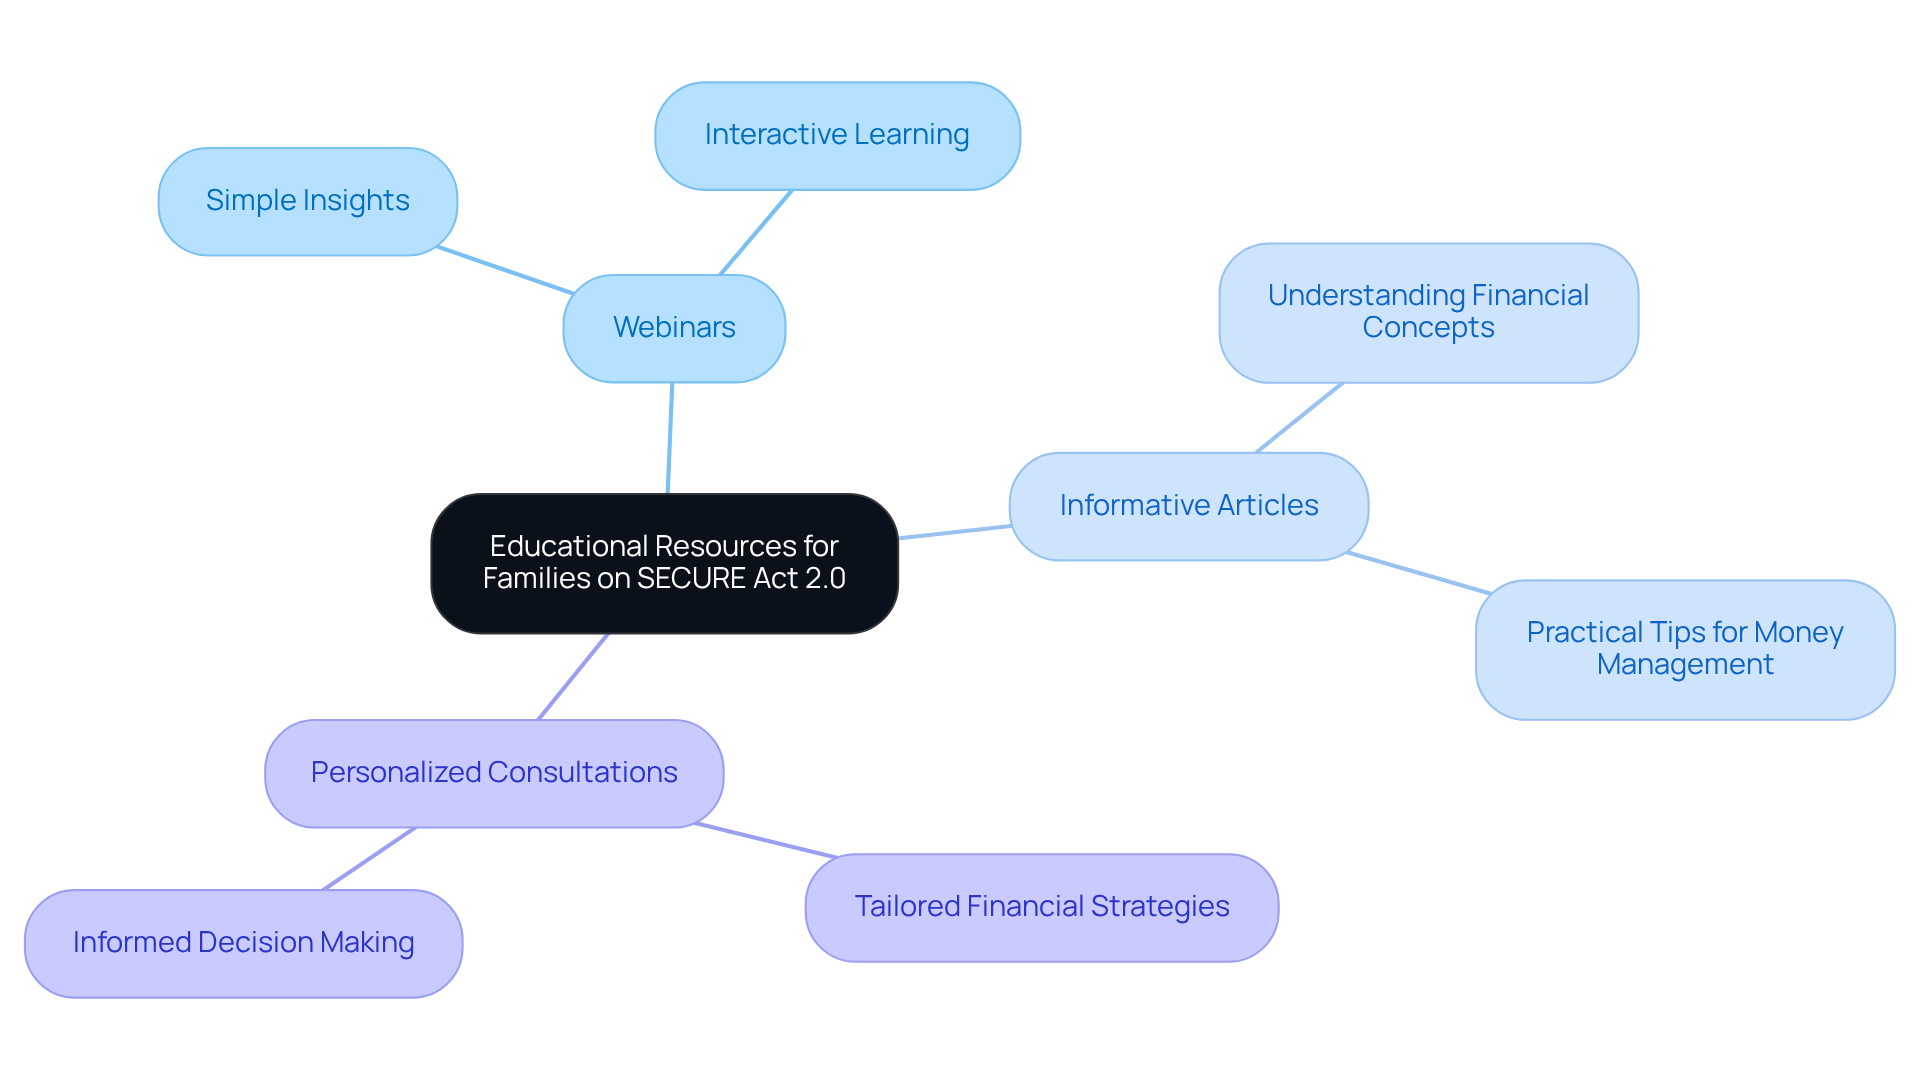
At Bright Advisers, we understand that navigating financial planning can feel overwhelming, especially for young families. That’s why we offer a comprehensive set of educational tools designed to help you grasp the impacts of the secure act 2.0 employer match roth. Imagine having access to webinars, informative articles, and personalized consultations that break down complex economic concepts into simple, actionable insights.
By engaging with these resources, you can significantly enhance your money management skills. This preparation empowers you to make informed decisions about your savings for the future and broader economic strategies. It’s important to understand that a solid grasp of fiscal regulations is crucial for effective planning as you look ahead to later life.
Moreover, the influence of financial literacy initiatives on household planning is profound. They encourage a proactive approach to managing finances, leading to better outcomes for you and your loved ones. Together, we can navigate this journey, ensuring that you’re equipped to secure a brighter financial future for your family.
We’re here for you, ready to support you every step of the way. Let’s take this important step together, ensuring that your family’s financial well-being is prioritized.
Tax Planning Strategies Post-SECURE Act 2.0
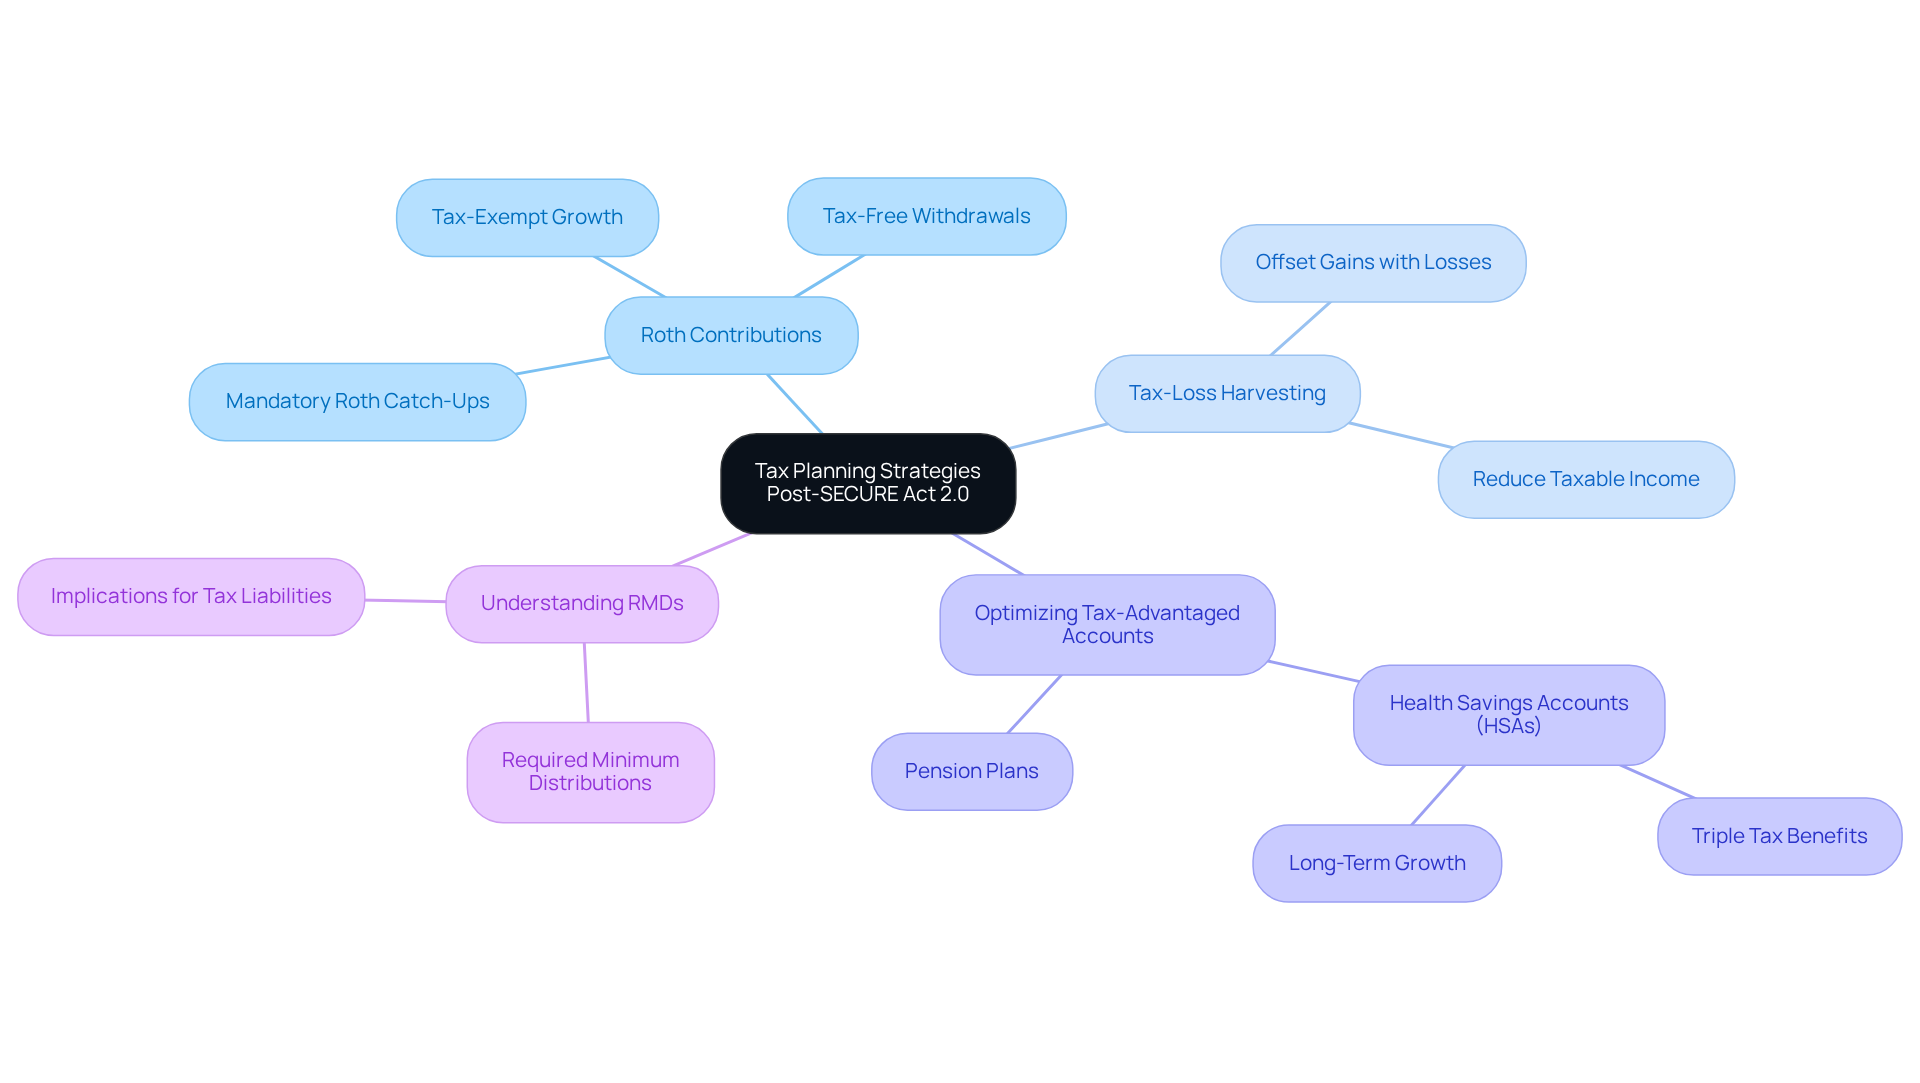
In the wake of the SECURE Act 2.0 employer match Roth, it’s a great time for families to reassess their tax planning strategies. This new law brings exciting opportunities, particularly with the secure act 2.0 employer match roth payments. Imagine being able to influence your tax liabilities during retirement! By opting for Roth payments as part of the secure act 2.0 employer match roth, you can enjoy tax-exempt growth and withdrawals, which is especially beneficial if you expect tax rates to rise in the future.
To make the most of your tax situation, consider working with a tax professional. They can help you implement strategies like tax-loss harvesting, which allows you to offset gains with losses, ultimately reducing your taxable income. Plus, optimizing your deposits into tax-advantaged accounts, such as Health Savings Accounts (HSAs) and pension plans, can further enhance your tax efficiency. It’s also important to understand the implications of required minimum distributions (RMDs) under the new law, as these can significantly affect your overall tax liabilities and retirement planning.
Statistics show that families using the secure act 2.0 employer match roth payments can experience a remarkable decrease in their tax obligations, potentially saving thousands over time. For example, a $3,750 Roth contribution made through the secure act 2.0 employer match roth could grow to over $14,000 tax-free in 20 years at a 7% return. This illustrates the long-term benefits of thoughtful tax planning. By proactively adjusting your financial strategies in light of the SECURE Act 2.0 employer match Roth, you can create a more favorable tax situation and enhance your family’s overall economic well-being.
Remember, you’re not alone in this journey. Together, we can navigate these changes and find the best path for your family’s future.
Long-Term Wealth Implications of SECURE Act 2.0 for Families
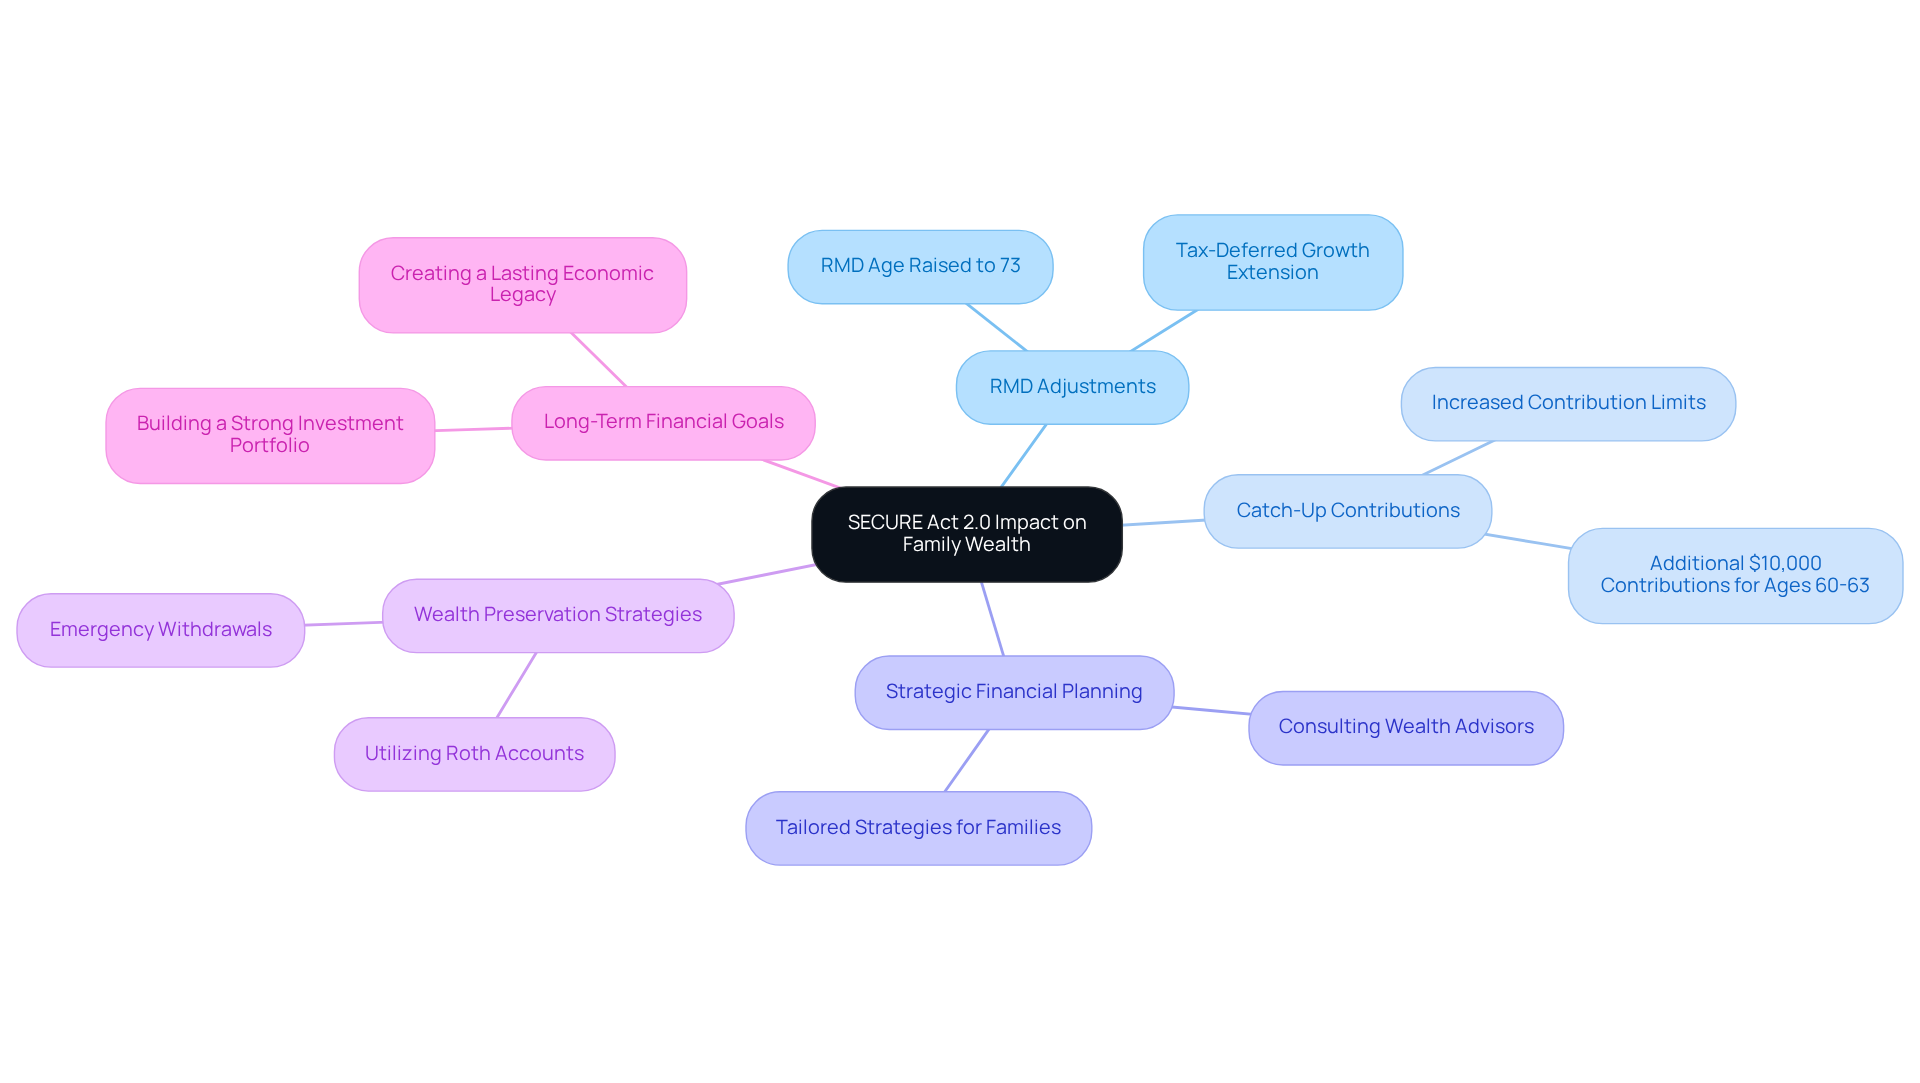
Imagine a future where your family’s financial stability is secure. The changes introduced by the SECURE Act 2.0 employer match Roth can truly impact long-term wealth for households like yours. By encouraging greater contributions and utilizing the SECURE Act 2.0 employer match Roth, you can build a stronger investment portfolio that aligns with your family’s financial goals for generations to come.
It’s important to understand how adjustments to Required Minimum Distributions (RMDs) and the tax treatment of retirement accounts can enhance your wealth preservation strategies. For instance, the RMD age has been raised to 73, allowing your investments to grow tax-deferred for a longer time. This is crucial for families looking to ensure a stable future.
Families can also take advantage of catch-up contributions for those aged 60-63, who will be able to contribute an additional $10,000 starting in 2025. With over half of households having retirement accounts, it’s vital for those without to leverage the SECURE Act 2.0 employer match Roth provisions to create a lasting economic legacy for their children.
Consider the success story of Allison and Brian. Through thoughtful tax planning with Bright Advisers, they improved their financial situation and secured their children’s future. Their journey shows how strategic planning can make a difference.
To maximize these benefits, we encourage you to consult with wealth advisors who can help tailor strategies to fit your unique situation. Together, we can navigate this journey and ensure your family’s financial well-being.
Leveraging Technology for Retirement Account Management Under SECURE Act 2.0
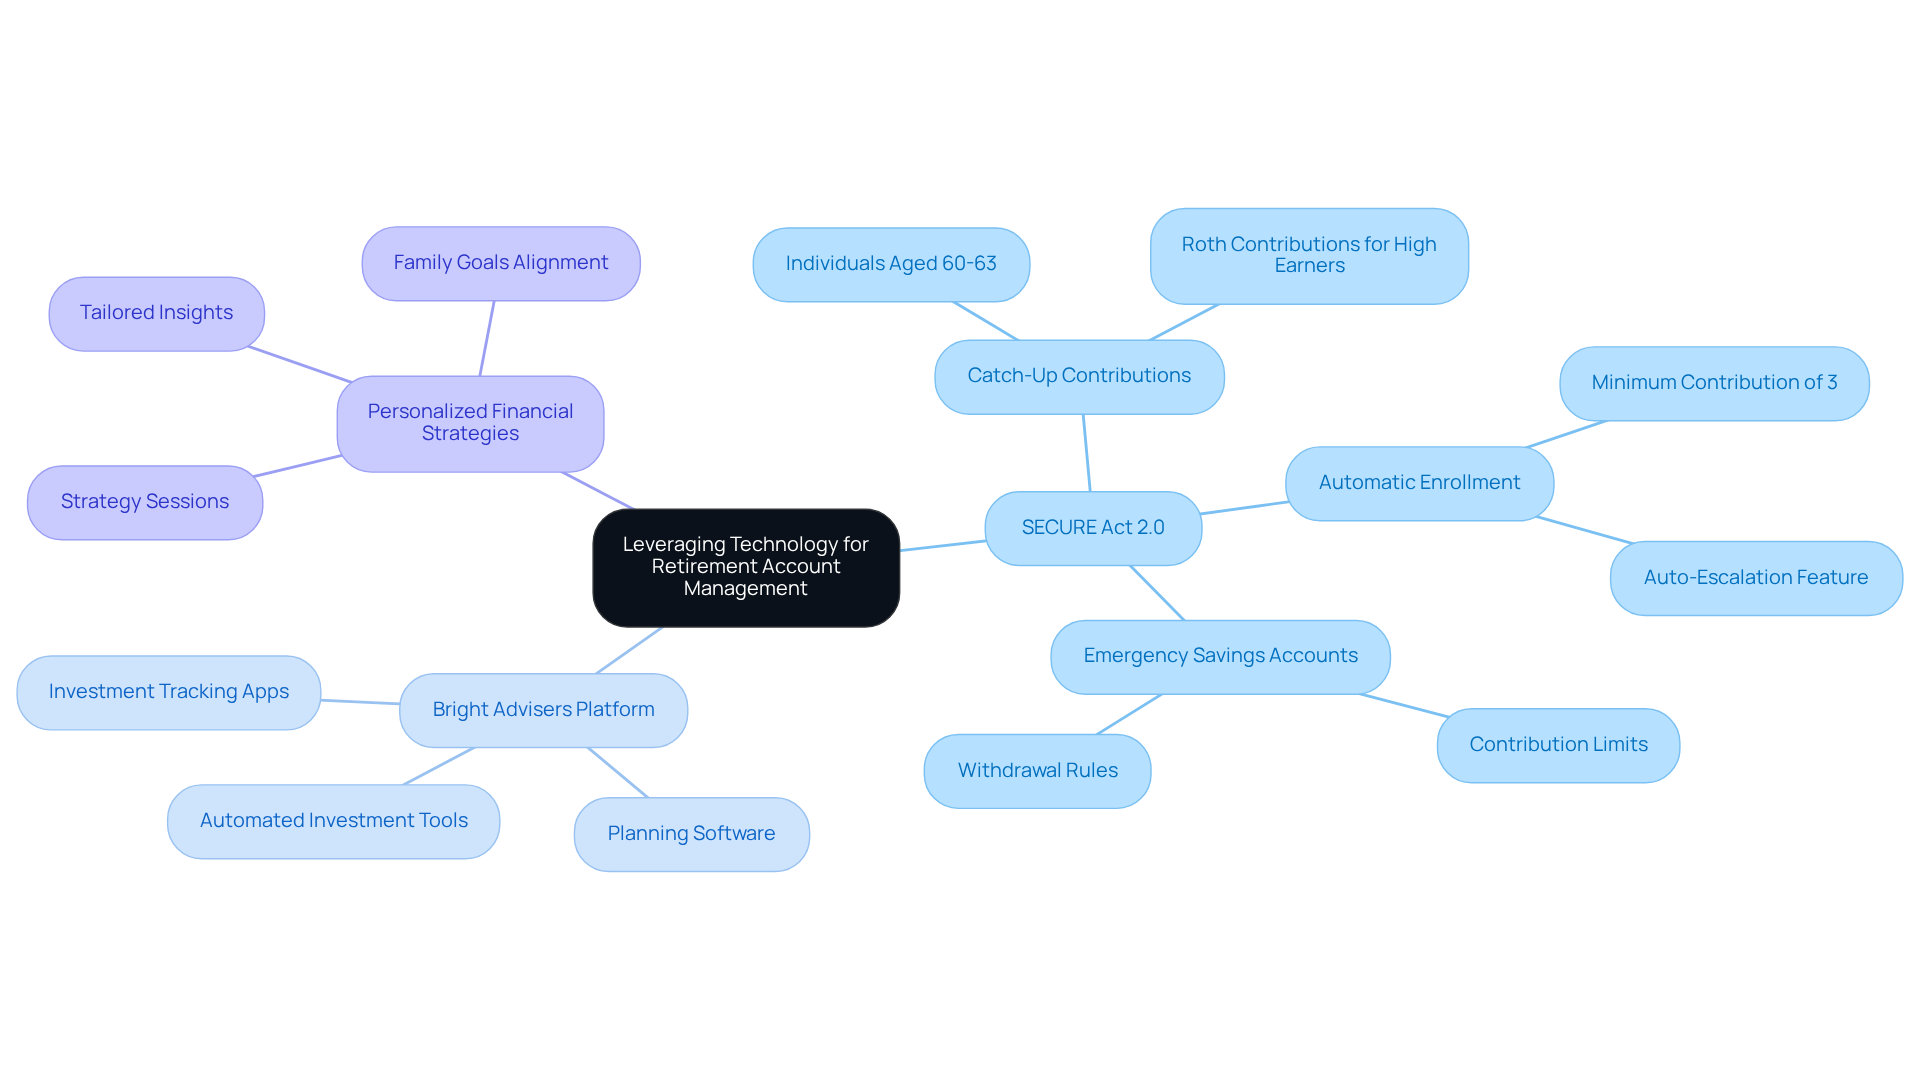
Imagine if you could simplify your family’s financial planning with the help of technology. With the SECURE Act 2.0 employer match Roth, families have a unique opportunity to enhance their account management. Bright Advisers offers an innovative wealth management platform that connects your financial plan with your investment strategy. This platform provides valuable resources like planning software, mobile apps for tracking deposits, and automated investment tools that make saving for the future easier than ever.
Starting in 2025, individuals aged 60 to 63 can contribute up to $10,000 as a catch-up contribution. This change highlights the importance of leveraging technology to maximize your retirement savings. At Bright Advisers, we understand that every family’s needs are different. That’s why our team is here to support you through a series of strategy sessions, helping you create a personalized financial plan that aligns with your unique family goals.
We use cutting-edge technology to provide tailored insights and recommendations, ensuring you can make informed decisions that resonate with your family’s values. As savings expert James Royal, Ph.D., wisely points out, “Understanding the types of accounts and how to choose investments is crucial for effective planning for the future.”
By adopting these technological solutions, you can achieve more efficient planning and better financial outcomes for your family. We’re here for you, ready to navigate this journey together. Let’s take the first step towards securing your family’s financial future.
Key Takeaways from the SECURE Act 2.0 for Employers and Employees
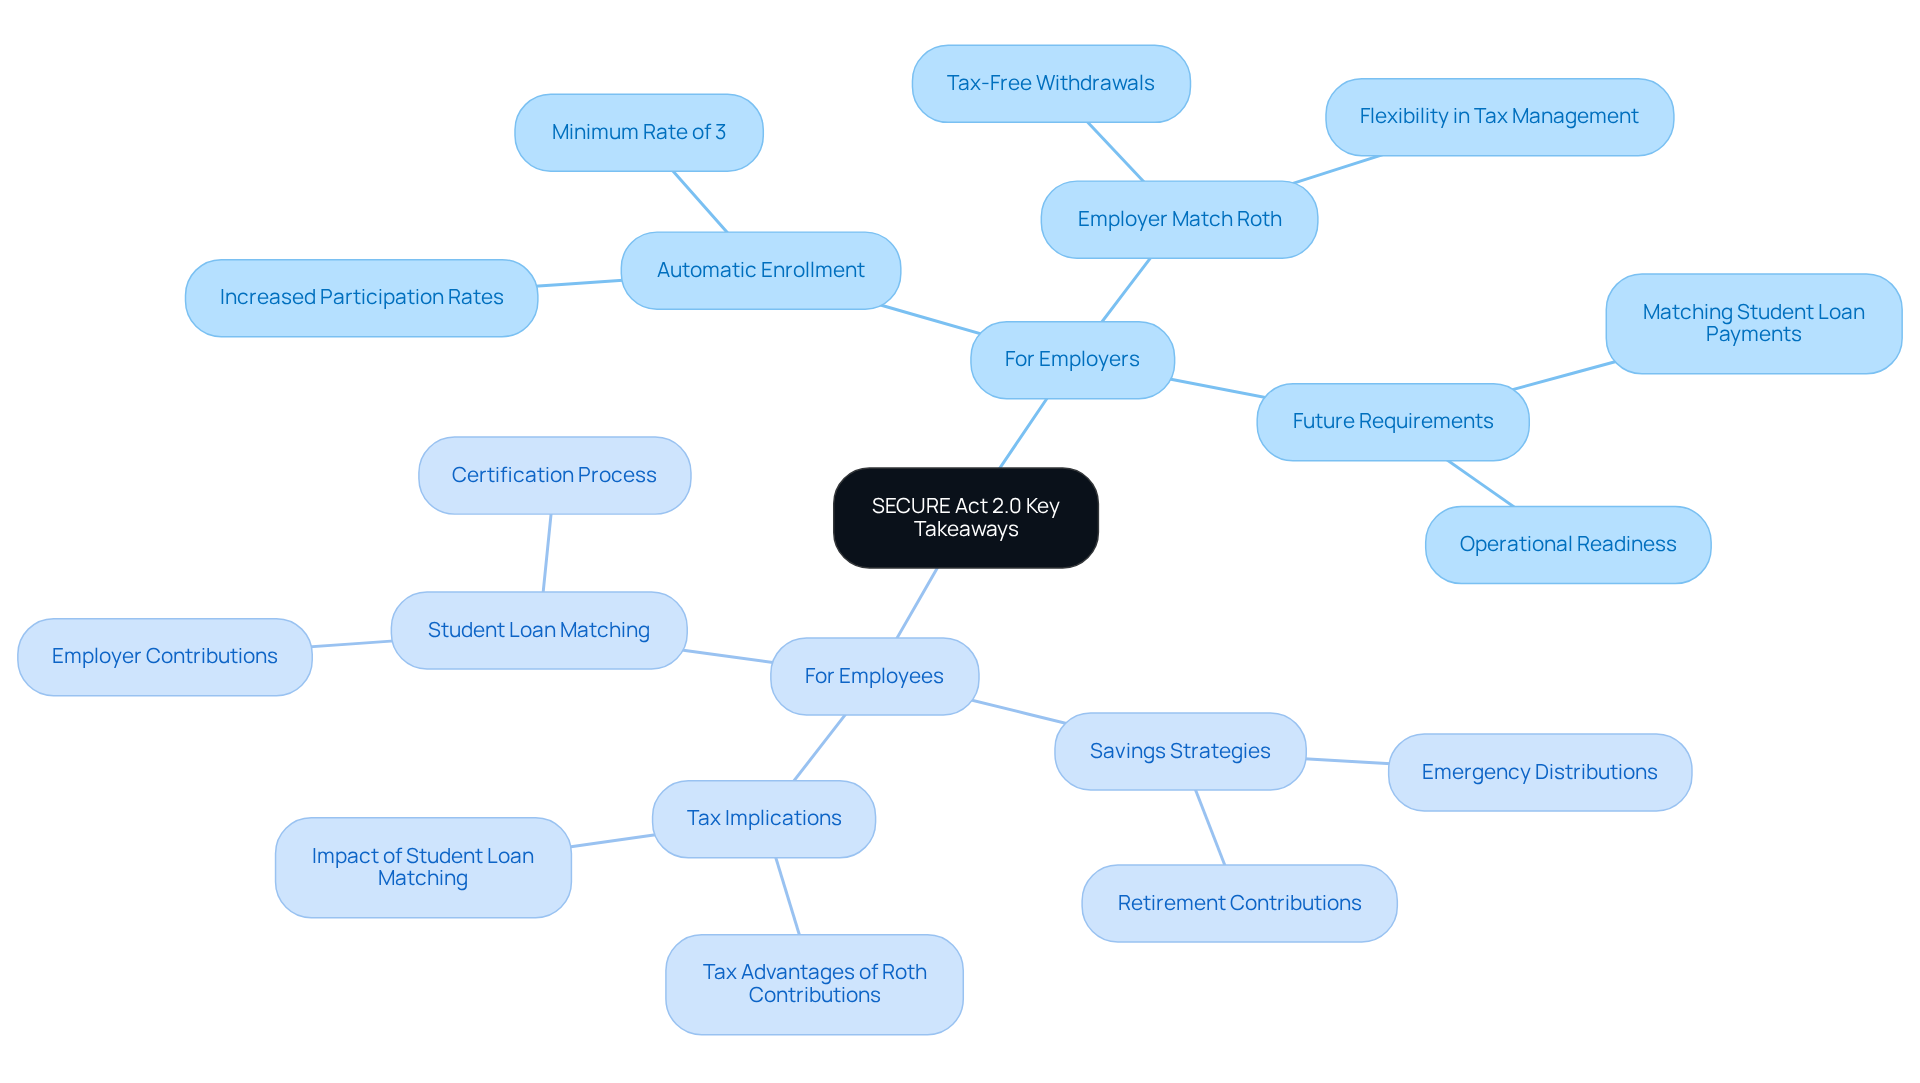
The SECURE Act 2.0 brings significant changes that can impact both employers and employees, especially for young families striving for financial stability. Imagine if your workplace could help you save more effectively for your future. With the introduction of the SECURE Act 2.0 employer match Roth and automatic enrollment in savings plans, employers can foster an environment that promotes participation and satisfaction among employees. Research shows that automatic enrollment can boost participation rates by as much as 20%. Starting in 2025, employers will need to automatically enroll employees at a minimum rate of three percent, which could further enhance participation and improve savings outcomes for families.
For households, understanding the new funding thresholds and tax implications is vital for effective future planning. Families can take advantage of these changes to optimize their savings strategies. For instance, beginning in 2024, employers will be able to match eligible student loan payments as if they were savings deposits. This means that even while managing student debt, families can benefit from employer support. This innovative approach not only helps with future savings but also addresses the financial challenges many families face today. Just like Jay and Emma, who worked with Bright Advisers to ease their financial stress while preparing for their children’s education and future.
HR experts emphasize the importance of these changes, noting that the SECURE Act 2.0 employer match Roth allows employees greater flexibility in managing their tax responsibilities. As one specialist shared, “Roth contributions allow workers to enjoy tax-free withdrawals in their later years, which can truly transform long-term financial planning.” To maximize retirement savings, families should consider reaching out to financial advisors to develop personalized strategies that incorporate these new provisions. Emily and Mark did just that by partnering with Bright Advisers to create a comprehensive financial plan that aligns with their family goals.
We’re here for you as you navigate these changes. Together, we can explore how to make the most of these opportunities for your family’s future.
Conclusion
The SECURE Act 2.0 brings exciting changes that can truly empower families to enhance their retirement savings and financial planning. Imagine being able to optimize your contributions through employer match Roth options, reducing tax burdens while securing a brighter future for your loved ones. With a focus on personalized financial strategies, every household can navigate these changes effectively, aligning their financial goals with the new opportunities available.
Throughout this journey, it’s crucial to adapt to these legislative updates. Think about the increased catch-up contributions for those nearing retirement or the ability to roll over 529 plans into Roth IRAs. These innovative options present families with fresh ways to grow their wealth. Plus, the introduction of automatic enrollment and matching contributions for student loan payments shows how employers can support their employees’ financial well-being, fostering a culture of savings that benefits everyone involved.
Ultimately, the SECURE Act 2.0 isn’t just about compliance with new regulations; it’s a significant opportunity for families to reassess their financial strategies and take proactive steps toward long-term security. Engaging with financial advisors and utilizing available resources can make a substantial difference in optimizing these benefits. By embracing these changes, families can build a legacy of financial stability and prepare for a future where their loved ones thrive.
Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.
Frequently Asked Questions
What is Bright Advisers’ approach to financial planning for young parents?
Bright Advisers provides personalized financial planning that utilizes the provisions of the SECURE Act 2.0, helping young parents maximize their savings and secure their economic future while prioritizing their children’s well-being.
What are the key features of the SECURE Act 2.0 that Bright Advisers highlights?
Key features include employer match Roth contributions, increased catch-up contributions for individuals aged 60-63, and the ability for employers to provide matching payments to Roth accounts, which allows deposits to grow tax-free.
How can the SECURE Act 2.0 benefit retirement savings?
The SECURE Act 2.0 allows individuals aged 60-63 to contribute significantly more to their savings, up to $10,000 or 50% above the standard catch-up amount, helping those nearing retirement boost their savings quickly.
What is the FamilyKnowledge™ Base offered by Bright Advisers?
The FamilyKnowledge™ Base is a tool that helps families organize and protect their values, enhancing their legacy for future generations.
How does Bright Advisers assist families in navigating estate and tax planning?
Bright Advisers has dedicated teams of advisors who support families in developing comprehensive strategies for wealth management, making the process of estate and tax planning less overwhelming.
What is the significance of employer match Roth contributions under the SECURE Act 2.0?
Employer match Roth contributions allow employers to match employee contributions to Roth accounts, enabling those contributions to grow tax-free, which can significantly enhance a family’s savings.
What proactive steps can families take under the SECURE Act 2.0?
Families can reassess their savings strategies, utilize increased catch-up contributions, and work with financial planners to optimize their tax situations and retirement savings.
What recent statistics reflect the impact of the SECURE Act 2.0 on households aged 60-63?
A recent survey found that 45% of households aged 60-63 have utilized increased catch-up contributions, demonstrating a proactive approach to enhancing their savings.
What requirement is set for retirement plans established after December 29, 2022?
Retirement plans established after this date must increase contribution percentages by at least 1% each year, emphasizing the importance of staying informed in retirement planning.
List of Sources
- Bright Advisers: Personalized Financial Planning Aligned with SECURE Act 2.0
- What You Need to Know About the SECURE 2.0 Act | Key Private Bank (https://key.com/kpb/our-insights/articles/need-to-know-secure-act.html)
- How SECURE Act 2.0 Changed Retirement: 16 Key Facts (https://tencap.com/blog/how-secure-act-2-0-changed-retirement)
- Why the SECURE 2.0 Act can be good news for retirement planning (https://rbcwealthmanagement.com/en-us/insights/why-the-secure-2-0-act-can-be-good-news-for-retirement-planning)
- SECURE Act 2.0 Makes Sweeping Changes to Retirement Savings Plans (https://adp.com/spark/articles/2023/01/secure-20-act-of-2022-makes-sweeping-changes-to-retirement-savings-plans.aspx)
- Understanding Employer Match Roth Contributions Under SECURE Act 2.0
- Biggest Changes To Retirement Accounts Due To New 401(k) And IRA Rules | Bankrate (https://bankrate.com/retirement/secure-act-2-retirement-account-changes)
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- SECURE Act 2.0 – A Summary of the Major 401(k) Provisions (https://employeefiduciary.com/blog/secure-act-2.0-summary)
- IRS guidance illuminates SECURE 2.0’s Roth employer contributions (https://mercer.com/en-us/insights/law-and-policy/irs-guidance-illuminates-secure-2-0-s-roth-employer-contribution)
- SECURE Act 2.0 – What Employers Need to Know (https://oswaldfinancial.com/news-events/secure-act-2-0-what-employers-need-to-know)
- Adapting Retirement Savings Strategies to SECURE Act 2.0 Changes
- What You Need to Know About the SECURE 2.0 Act | Key Private Bank (https://key.com/kpb/our-insights/articles/need-to-know-secure-act.html)
- SECURE Act 2.0 – A Summary of the Major 401(k) Provisions (https://employeefiduciary.com/blog/secure-act-2.0-summary)
- SECURE 2.0 Act Summary: New Retirement Savings Changes to Know (https://kiplinger.com/retirement/bipartisan-retirement-savings-package-in-massive-budget-bill)
- Secure 2.0 Act and Your Retirement Savings | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/saving-for-retirement-secure-act.html)
- Exploring Retroactive Provisions of the SECURE Act 2.0
- 50 funny and inspirational quotes for accountants, tax pros, and financial advisors – Blog (https://blog.taxdome.com/quotes-for-accountants)
- 151 Motivational Quotes for Accountants and CPAs [2026] (https://acecloudhosting.com/blog/motivational-quotes-accountants)
- 20 Quotes that will Motivate Finance and Accounting Professionals (https://medium.com/@thewallstreetschool/20-quotes-that-will-motivate-finance-and-accounting-professionals-a688888709f5)
- Tax Season Motivation – MSATP (https://msatp.org/tax-season-motivation)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- Ameritas: Existing Provisions Supported by SECURE Act 2.0
- SECURE Act 2.0: Roth & RMD Rules for 2026 (https://ameritas.com/insights/secure-act-2-0-roth-rmd-rules-for-2026)
- Cumberland Foreside, ME financial advice topics | Bob Daggett (https://ameripriseadvisors.com/robert.l.daggett/insights/secure-act-2-opportunities)
- Understanding the Transformative Landscape of Retirement Planning Changes with SECURE Act 2.0 – Keystone Financial (https://keystonefingrp.com/articles/understanding-the-transformative-landscape-of-retirement-planning-changes-with-secure-act-2-0)
- SECURE 2.0 Wins Positive Reviews (https://asppa-net.org/news/2024/5/secure-20-wins-positive-reviews)
- Educational Resources for Families on SECURE Act 2.0 Implications
- Financial Education Quotes (https://financialeducatorscouncil.org/financial-education-quotes)
- 75+ BEST FINANCIAL LITERACY QUOTES TO INSPIRE YOUR FINANCIAL SUCCESS (https://thestrive.co/financial-literacy-quotes)
- Financial Education Quotes (58 quotes) (https://goodreads.com/quotes/tag/financial-education)
- 40 quotes to help your child learn the value of money | GoHenry (https://gohenry.com/us/blog/financial-education/40-quotes-to-help-your-child-learn-the-value-of-money)
- The Proposed SECURE Act 2.0: Key Takeaways for Family Businesses | Davis Wright Tremaine (https://dwt.com/blogs/family-business-resource-center/2022/07/secure-act-employer-sponsored-retirement-plans)
- Tax Planning Strategies Post-SECURE Act 2.0
- Ten Retirement Tax Plan Moves to Make Before December 31 (https://kiplinger.com/taxes/retirement-tax-plan-moves-to-make-before-december-31)
- Why Experts Say a Roth 401(k) Could Supercharge Your Retirement (https://nasdaq.com/articles/why-experts-say-roth-401k-could-supercharge-your-retirement)
- Year-End Tax Planning Strategies for 2024 (https://eisneramper.com/insights/tax/year-end-tax-1124)
- SECURE Act 2.0: Summary of Key Tax Provisions (https://cbh.com/insights/articles/secure-act-2-0-summary-of-key-tax-provisions)
- Smart Retirement Strategies for High Earners Secure Act 2.0 (https://shpfinancial.com/smart-retirement-strategies-for-high-earners)
- Long-Term Wealth Implications of SECURE Act 2.0 for Families
- Retirement Account Statistics 2025 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- How SECURE Act 2.0 Changed Retirement: 16 Key Facts (https://tencap.com/blog/how-secure-act-2-0-changed-retirement)
- SECURE Act 2.0 Makes Sweeping Changes to Retirement Savings Plans (https://adp.com/spark/articles/2023/01/secure-20-act-of-2022-makes-sweeping-changes-to-retirement-savings-plans.aspx)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 24 Wealth Building Quotes You Can Use to Motivate Yourself (https://edelweisslife.in/blogs/wealth-accumulation/twenty-four-wealth-building-quotes-you-can-use-now)
- Leveraging Technology for Retirement Account Management Under SECURE Act 2.0
- Biggest Changes To Retirement Accounts Due To New 401(k) And IRA Rules | Bankrate (https://bankrate.com/retirement/secure-act-2-retirement-account-changes)
- SECURE Act 2.0 Makes Sweeping Changes to Retirement Savings Plans (https://adp.com/spark/articles/2023/01/secure-20-act-of-2022-makes-sweeping-changes-to-retirement-savings-plans.aspx)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- SECURE 2.0 Roth Mandate: Preparing for 2026 with Confidence | UKG (https://ukg.com/blog/hr-leaders/7-benefit-program-changes-secure-20-act-2022)
- SECURE Act 2.0: A Blueprint for Enhanced Employee Benefits Packages (https://sunnydayfund.com/blog/secure-act-2-0-a-blueprint-for-enhanced-employee-benefits-packages)
- Key Takeaways from the SECURE Act 2.0 for Employers and Employees
- SECURE Act 2.0 Key Take Aways | Syracuse CPA (https://dbbllc.com/newsletters/focus-our-tax-e-newsletter/secure-act-20-key-take-aways-employers)
- SECURE Act 2.0 Key Provisions and Implementation Challenges for Defined Contribution Plans (https://withum.com/resources/secure-act-2-0-key-provisions-and-implementation-challenges-for-defined-contribution-plans)
- SECURE Act 2.0: Key Takeaways & Changes to 401k Plans (2023) – 401k Advisors of Retirement Partners of Santa Clarita, California (https://retirementpartnersofcalifornia.com/secure-act-2-changes-retirement-planning-2023)
- SECURE 2.0 Act Summary: New Retirement Savings Changes to Know (https://kiplinger.com/retirement/bipartisan-retirement-savings-package-in-massive-budget-bill)
- SECURE Act 2.0 Makes Sweeping Changes to Retirement Savings Plans (https://adp.com/spark/articles/2023/01/secure-20-act-of-2022-makes-sweeping-changes-to-retirement-savings-plans.aspx)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading