

Key Highlights
- Reflecting on spending habits can help families identify areas to cut back and make intentional choices.
- Impulse buying is common among young parents; understanding triggers can lead to better financial decisions.
- Creating a comprehensive budget helps families balance financial responsibilities and long-term goals.
- Involving children in budgeting teaches them the value of money and shared responsibility.
- Regularly tracking spending can reveal overspending areas and reduce financial stress.
- Reducing unnecessary spending through simple changes can enhance family bonding and financial security.
- Establishing an emergency fund of three to six months’ expenses provides a financial cushion for unexpected costs.
- Setting clear financial goals, both short-term and long-term, fosters accountability and family collaboration.
- Using debt repayment strategies like the avalanche or snowball method can help families manage and reduce debt effectively.
- Staying aware of lifestyle creep helps families maintain financial stability as income increases.
- Negotiating bills and rates can lead to lower monthly expenses, easing financial burdens.
- Exploring side hustle opportunities can boost family income while teaching children about responsibility and money management.
Introduction
Many young parents feel overwhelmed by financial pressures, unsure of how to balance their budgets while providing for their families. Imagine a family sitting around the dinner table, discussing their dreams and goals, but feeling the weight of financial stress. Here are ten practical strategies to help families cultivate healthier financial habits, ensuring that every dollar is spent wisely while still enjoying the joys of parenthood. It’s important to understand: how can families cut costs while still cherishing those precious moments together? With these actionable tips, you can pave the way for financial stability, easing stress and nurturing a positive environment for your children.
Examine Your Financial Habits
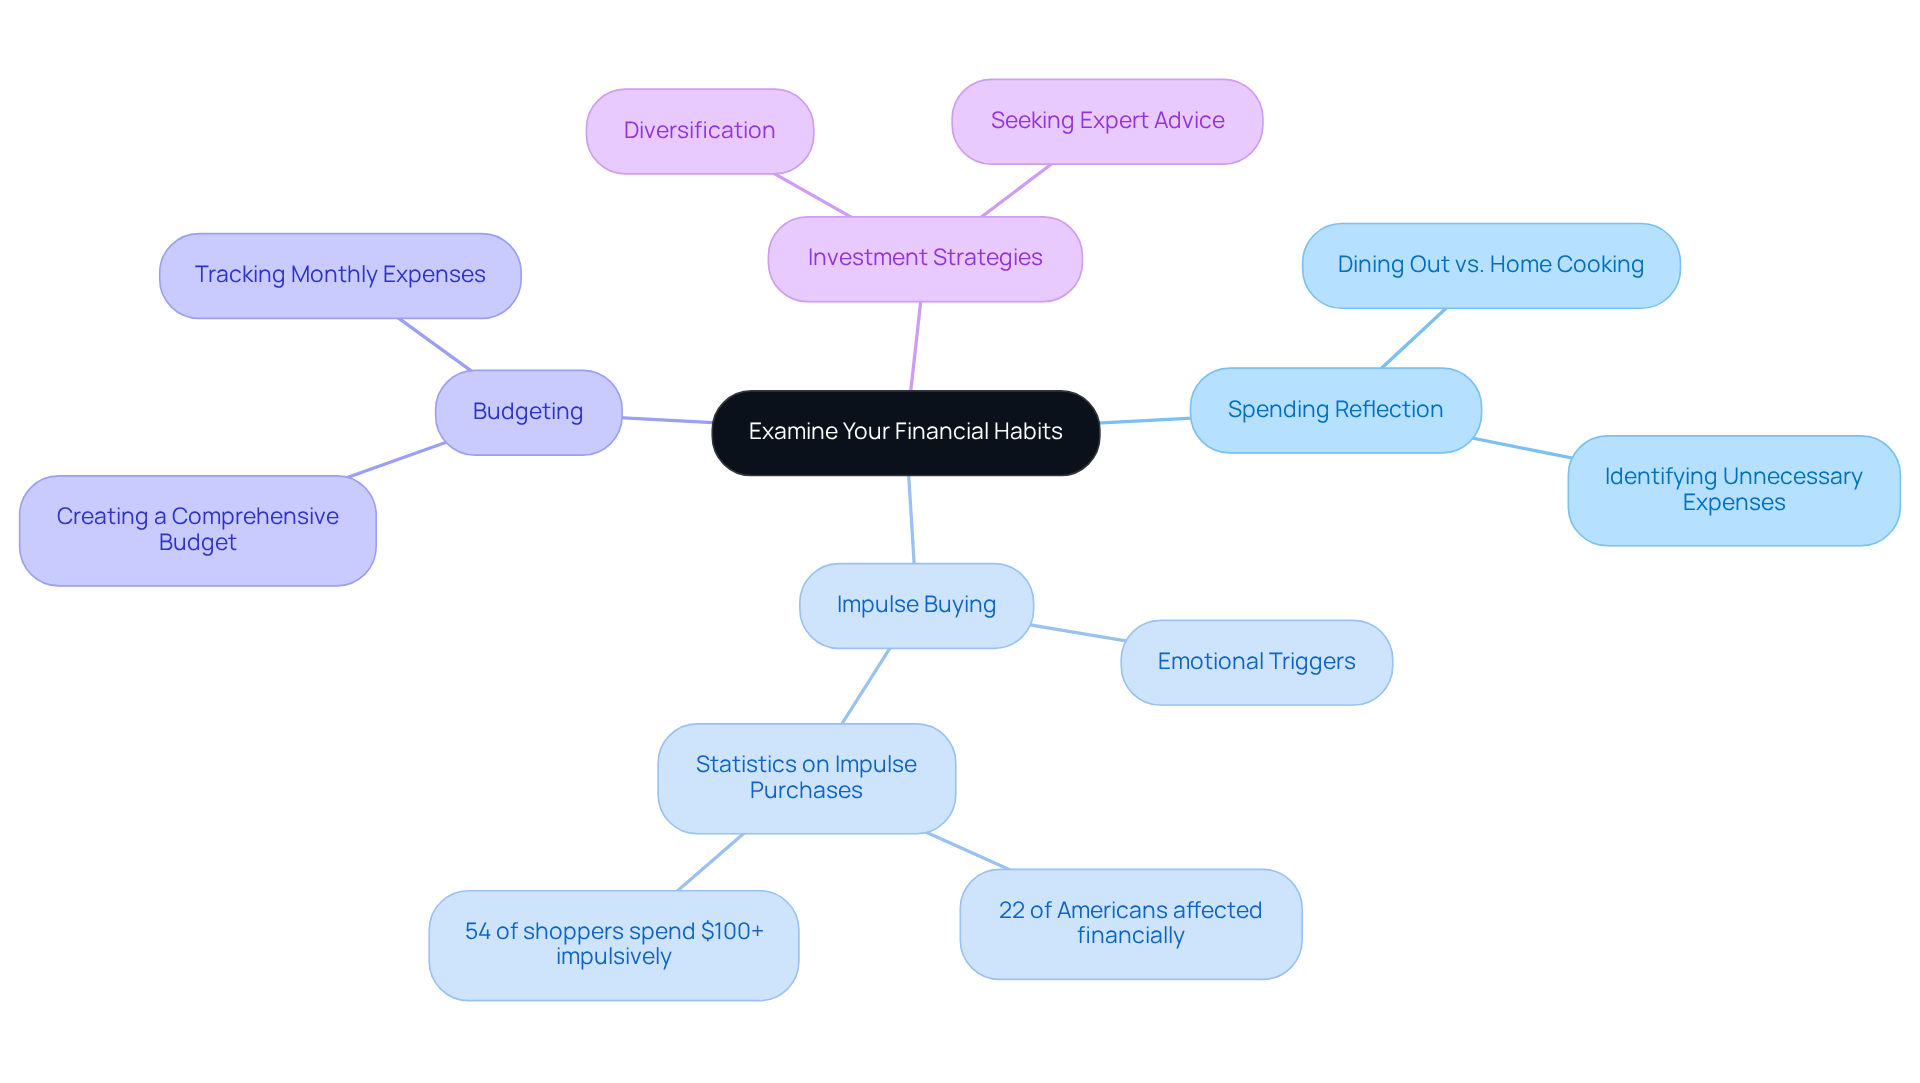
Have you ever felt overwhelmed by your spending habits, wondering if you’re truly making the best choices for your family? Reflecting on your current financial habits can be a great first step. Why not take a moment to look back at your spending over the past month? This simple exercise can help you uncover areas where you might cut back and make more intentional choices. For instance, if dining out is a frequent expense, consider preparing meals at home more often. Not only will this save money, but it also offers a wonderful opportunity to teach your kids about healthy eating habits.
It’s surprising to think that many families struggle with impulse buying, which can take a big chunk out of their budgets. Recent studies show that many young parents, like you, often find themselves making impulsive purchases due to emotional triggers and societal pressures. By taking a closer look at your spending habits, you can make thoughtful choices that not only help your family today but also set a great example for your kids.
At Bright Advisers, we understand the unique challenges young families face, like Jay & Emma, who are balancing financial responsibilities while planning for their children’s education. By creating a comprehensive budget and exploring investment strategies that focus on diversification, including integrated tax planning, families can find a balance between growth potential and risk management. This approach not only eases financial stress but also empowers parents to make informed decisions that align with their long-term goals.
As you assess your money habits, remember that seeking advice from experts can provide you with the tools and strategies needed to improve your financial situation. Just like Emily & Mark found the freedom to choose whether to continue working by implementing effective financial planning, you too can build a solid foundation for your family’s future.
By partnering with Bright Advisers, founded by Kevin Luu and Kathleen Chou in 2010, you can develop a personalized financial strategy that meets your unique needs. This way, you’ll be well-prepared for both your current responsibilities and future aspirations. Please remember that advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and all investments are subject to risk. There are no guarantees of results, and all advisory services are subject to registration and compliance regulations. With the right support, you can transform your financial habits and create a brighter future for your family, one step at a time.
Create and Stick to a Budget
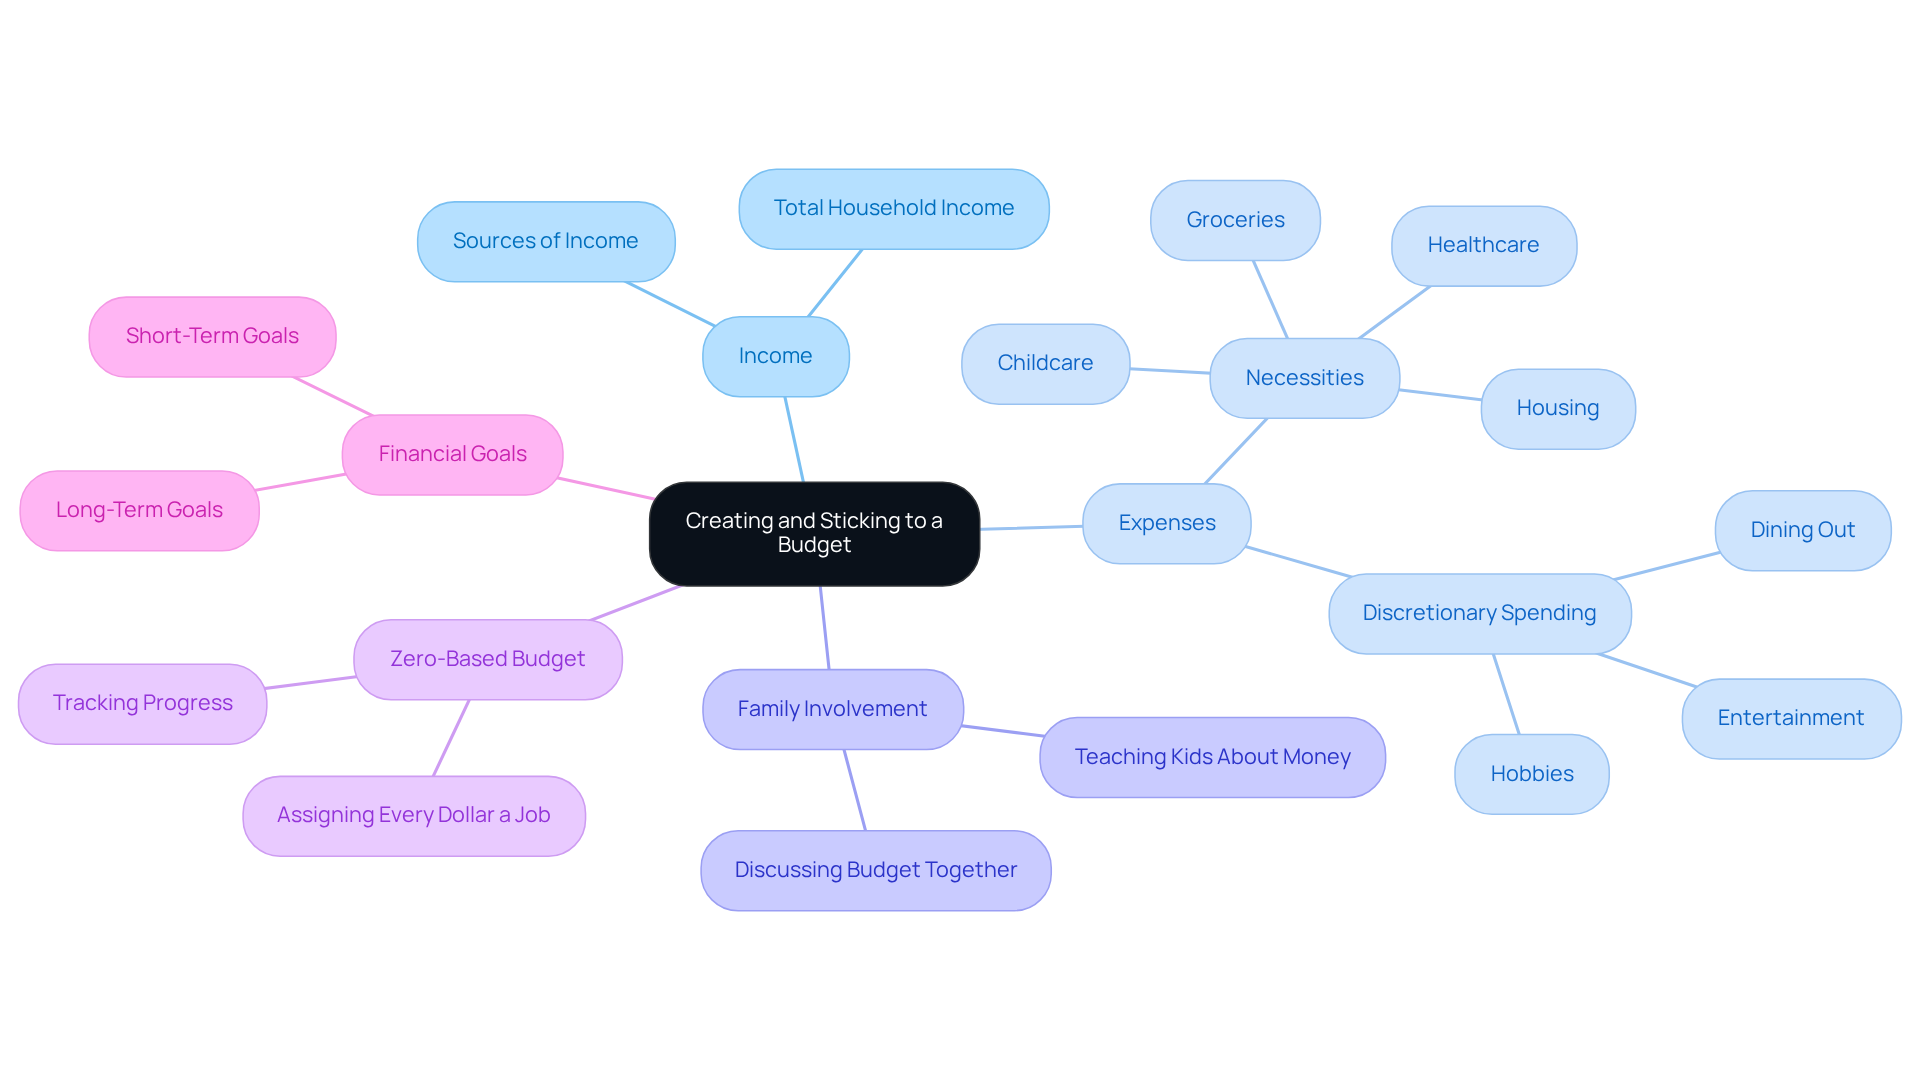
Imagine feeling in control of your family’s finances, even amidst the chaos of daily life. Creating a household budget can help you achieve that sense of security. Start by outlining your income and categorizing your expenses into necessities like housing, groceries, and childcare, along with discretionary spending. Using budgeting tools or apps can make tracking your progress easier and more engaging.
Make budgeting a family affair. Discuss it together, and help your children understand the value of money and the importance of saving. For instance, if your budget allows for a family outing, involve your kids in choosing an affordable option that aligns with your financial goals. This not only teaches them about budgeting but also fosters a sense of shared responsibility in managing money.
Imagine if every dollar you earned had a purpose, helping you feel more secure and less stressed about money. Creating a zero-based budget, where every dollar is assigned a specific purpose, can significantly enhance your resource management. This approach encourages thoughtful spending and helps families avoid unnecessary debt.
Did you know that households with children typically spend between $8,809 and $9,780 each month, depending on their kids’ ages? This highlights the importance of careful budgeting. With the yearly inflation rate for all items at 4.2% as of May 2026, budgeting becomes even more crucial for maintaining economic stability.
Together, we can navigate this journey. This company offers customized planning strategies, including retirement income approaches and education funding, to help families like Jay and Emma’s alleviate financial stress while effectively managing resources for significant purchases. By collaborating with Bright Advisers, families can develop tailored portfolios aimed at achieving their financial aspirations, ensuring a stable future for their children while pursuing their own long-term goals.
Please remember that all advisory services are provided through Lifeworks Advisors, a registered investment adviser. Investing involves risk, and past performance does not guarantee future results. There are no guarantees of results, and all investments are subject to risk.
Track Your Spending Regularly
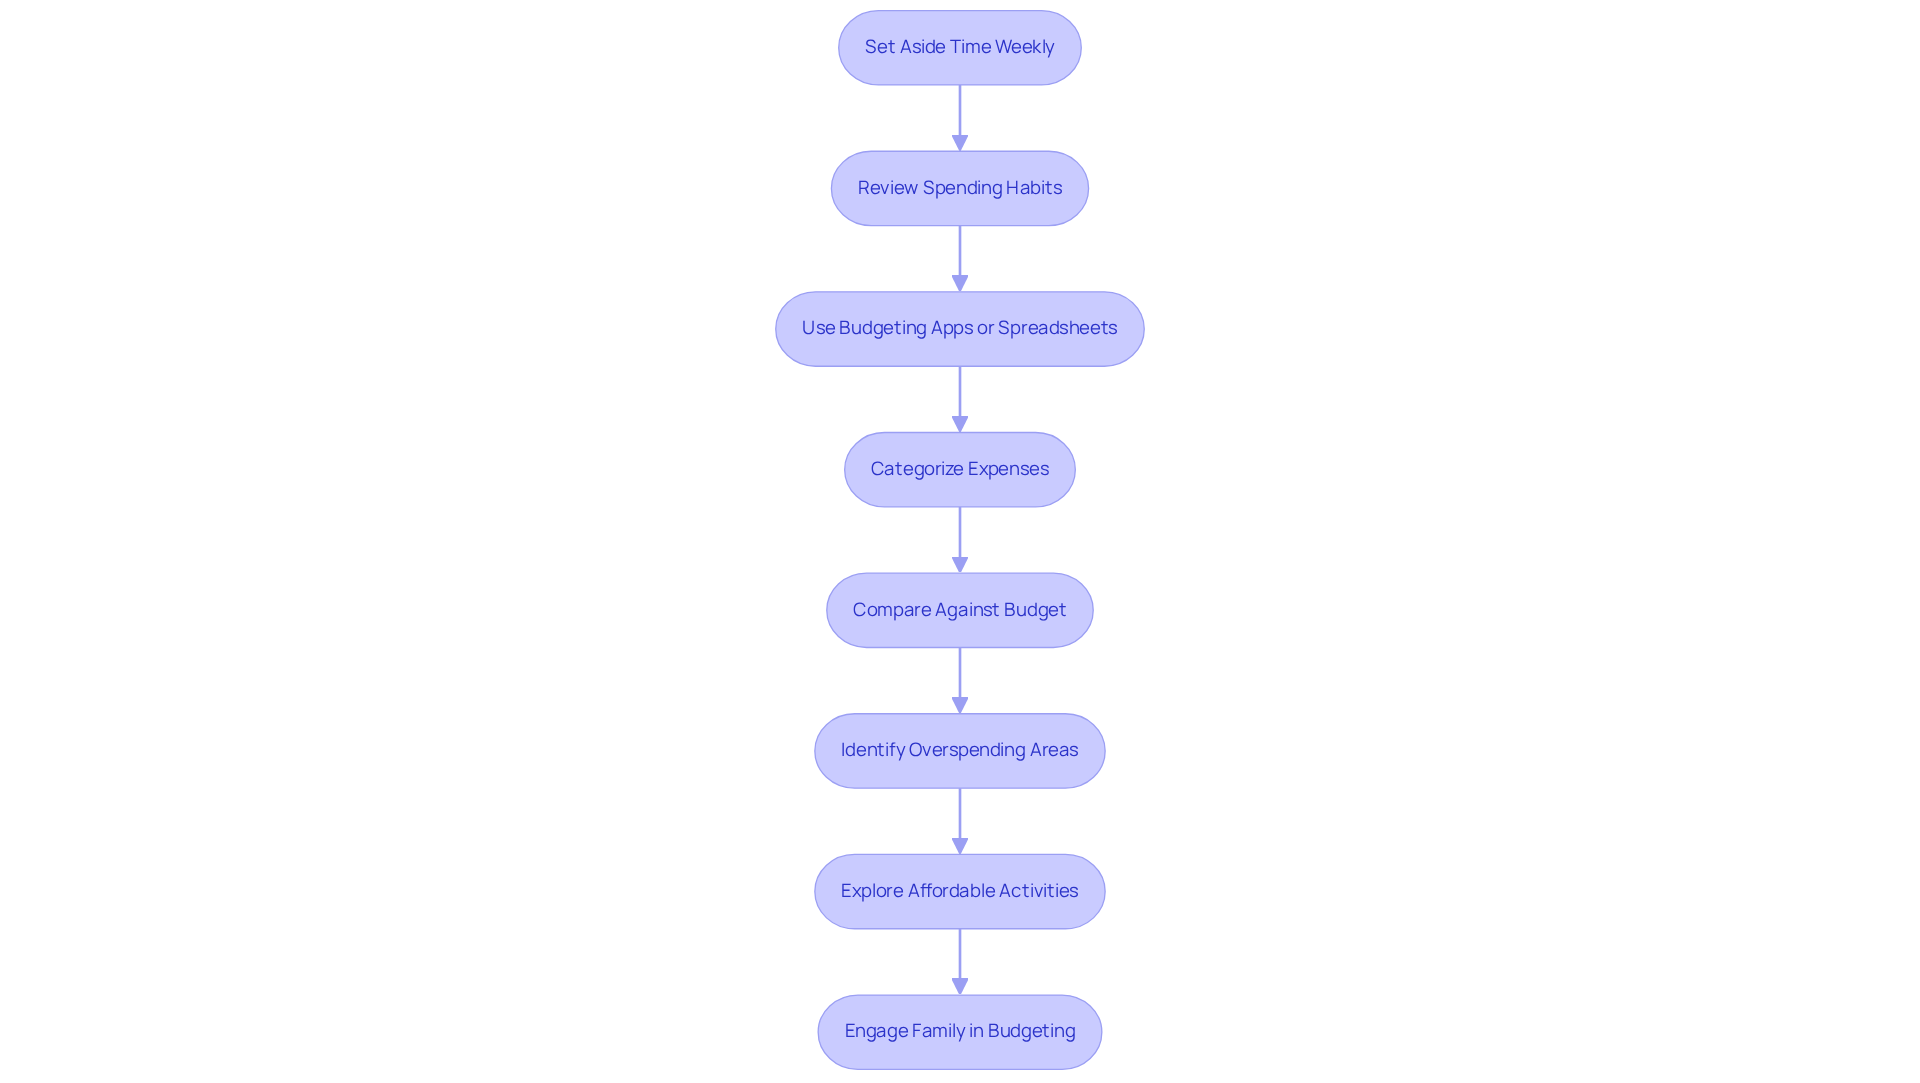
Imagine feeling overwhelmed by your family’s finances, unsure of where your money goes each month. Consider setting aside a little time each week to gently review your spending habits together as a family. You can use budgeting apps or spreadsheets to categorize your expenses and compare them against your budget. This practice can reveal areas where you might be overspending, like those entertainment costs that seem to add up quickly.
If you notice that entertainment is taking a big chunk of your budget, think about exploring free or affordable activities for your loved ones. Engaging your children in this process not only promotes transparency but also teaches them important lessons about budgeting and responsibility with money. Many families find that keeping an eye on their expenses can actually help reduce financial stress, even if it feels daunting at first.
By making tracking a family activity, you can cultivate a culture of monetary awareness and responsibility that benefits everyone. Reflect on the tale of Jay and Emma, who sought advice from Advisers to alleviate their monetary concerns. By establishing a comprehensive budget and selecting investment strategies focused on diversification, including tax optimization, they balanced growth potential and risk management.
Likewise, Emily and Mark collaborated with Bright Advisers to enhance their monetary situation, granting them the liberty to decide whether or not to keep working. These live below your means examples demonstrate how regular spending evaluations can result in efficient resource distribution and long-term economic stability for households. Ultimately, tracking your expenses can transform your family’s financial journey, leading to a brighter, more secure future together.
Reduce Unnecessary Spending
Imagine feeling overwhelmed by monthly expenses, wondering how to balance family fun with financial stability. Let’s explore some gentle ways to ease your spending worries together.
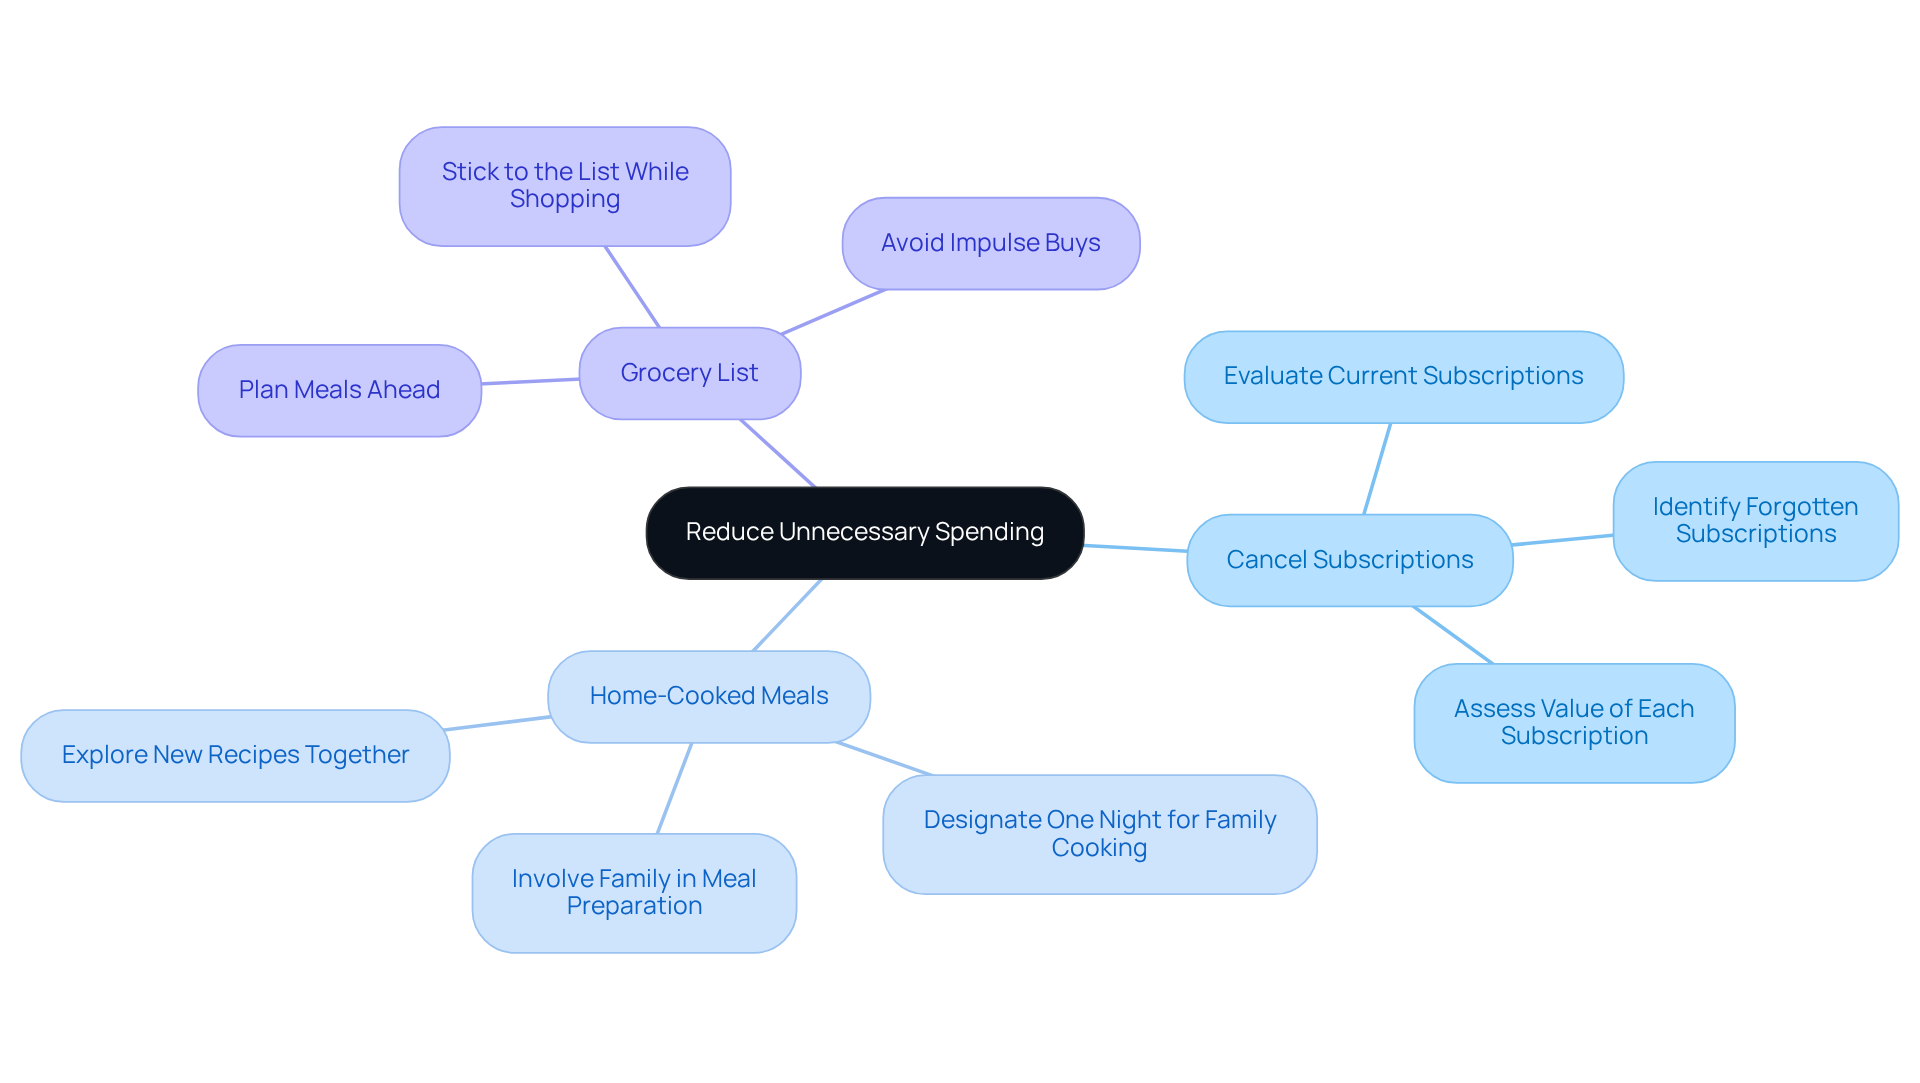
Consider this: what if you could find joy in simple changes, like:
- canceling subscriptions that no longer serve you
- enjoying home-cooked meals
- making a grocery list to keep those impulse buys at bay?
For instance, imagine designating one night a week for a homemade dinner, where everyone pitches in. Not only does this save money, but it also creates precious bonding moments and teaches your little ones about cooking and nutrition. Together, we can navigate this journey toward a more secure and joyful family life.
Save for Emergencies
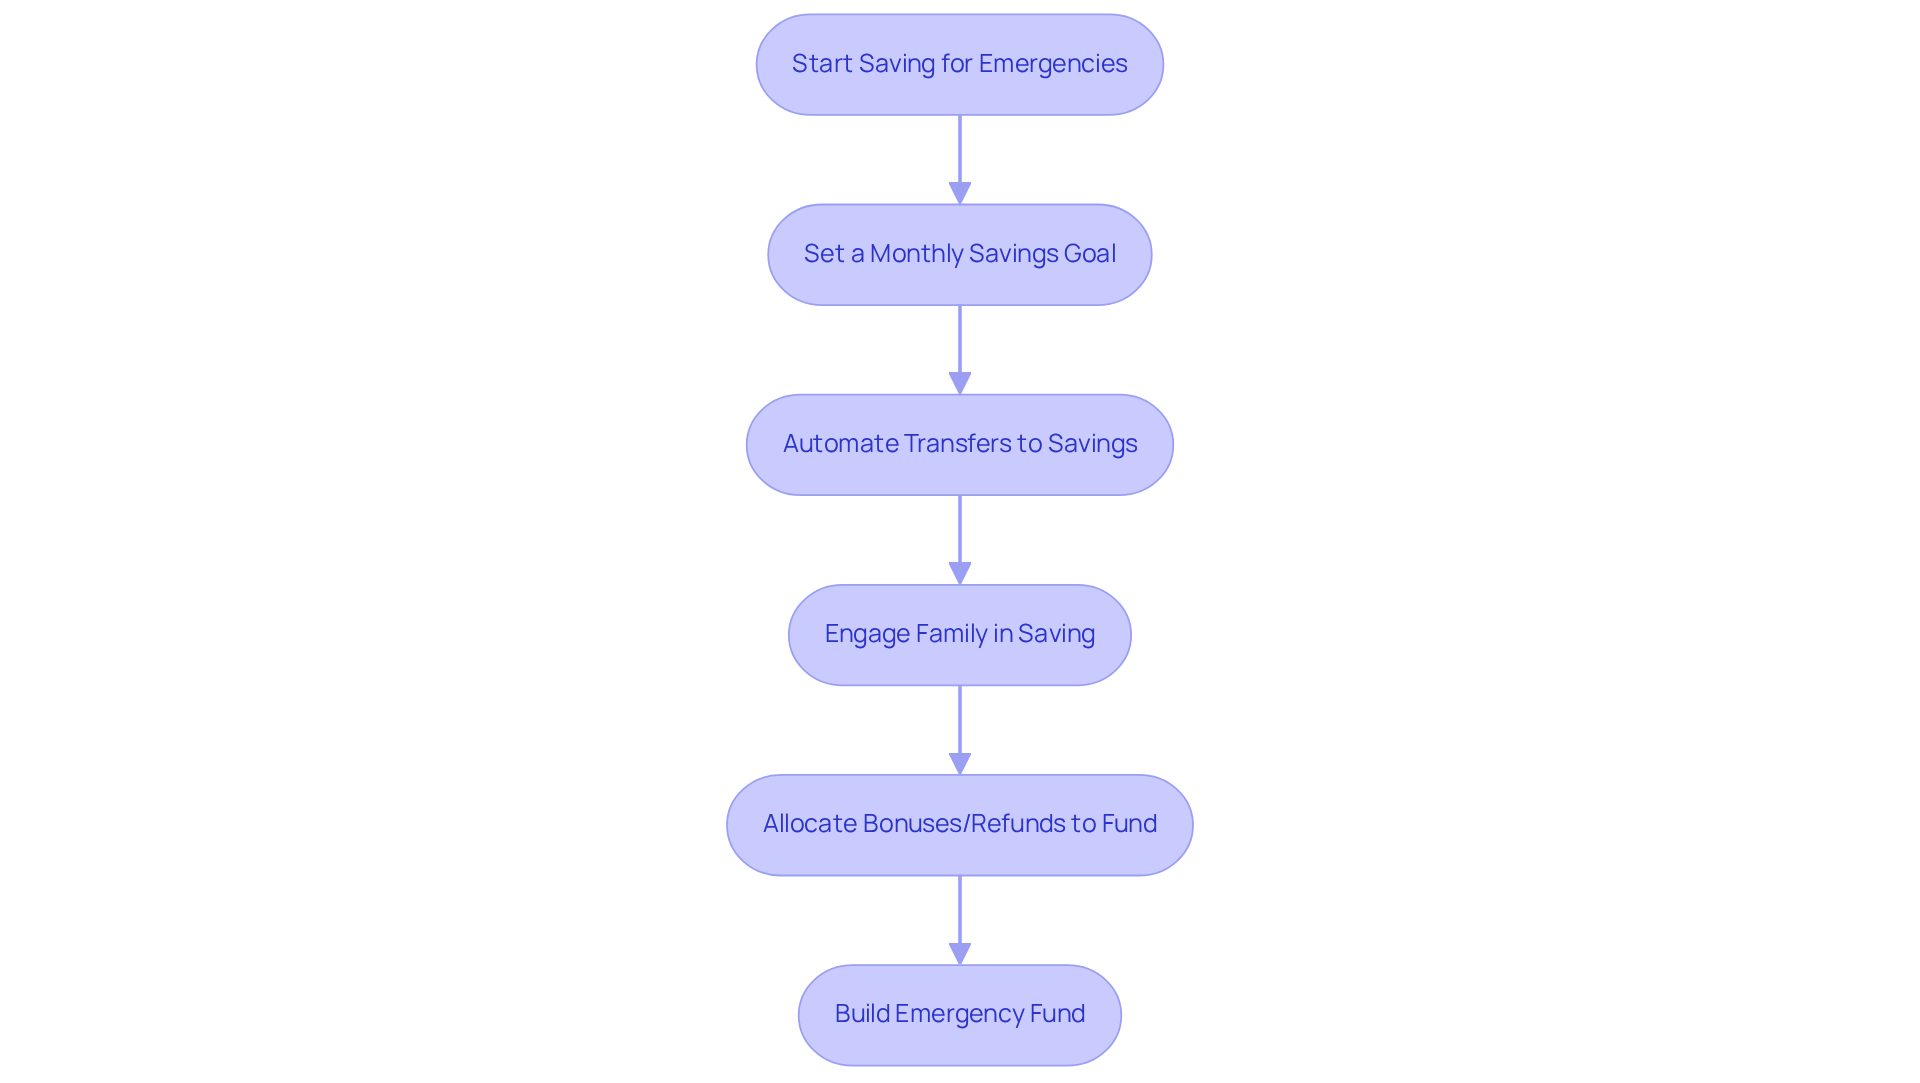
Imagine the relief of knowing you have a financial cushion ready for those unexpected moments that life throws your way. Aim to save at least three to six months’ worth of living expenses in an easily accessible account. This is especially vital for young households, as unforeseen costs can occur at any moment.
Start small by setting aside a portion of your income each month; even a modest amount can accumulate over time. Automating transfers to your savings account simplifies this process, ensuring that saving becomes a regular habit rather than an afterthought. For instance, if you receive a bonus or tax refund, consider allocating a portion of that to your emergency fund.
Engaging your children in this objective not only imparts the importance of saving but also nurtures a household culture of responsibility regarding money. Families who prioritize building an emergency fund often find themselves feeling more secure and less anxious when unexpected expenses arise.
For instance, Jay and Emma, a pair assisted by their advisers, successfully managed their planning by creating a thorough budget that included a contingency fund. By taking control of their finances, Jay and Emma found peace of mind, knowing they were prepared for whatever life threw their way.
Bright Advisers provides customized wealth management solutions, including integrated tax planning strategies, to assist households like Jay and Emma in optimizing their resources effectively. With the right support, you can create a secure future for your family, filled with possibilities rather than worries.
Set Clear Financial Goals
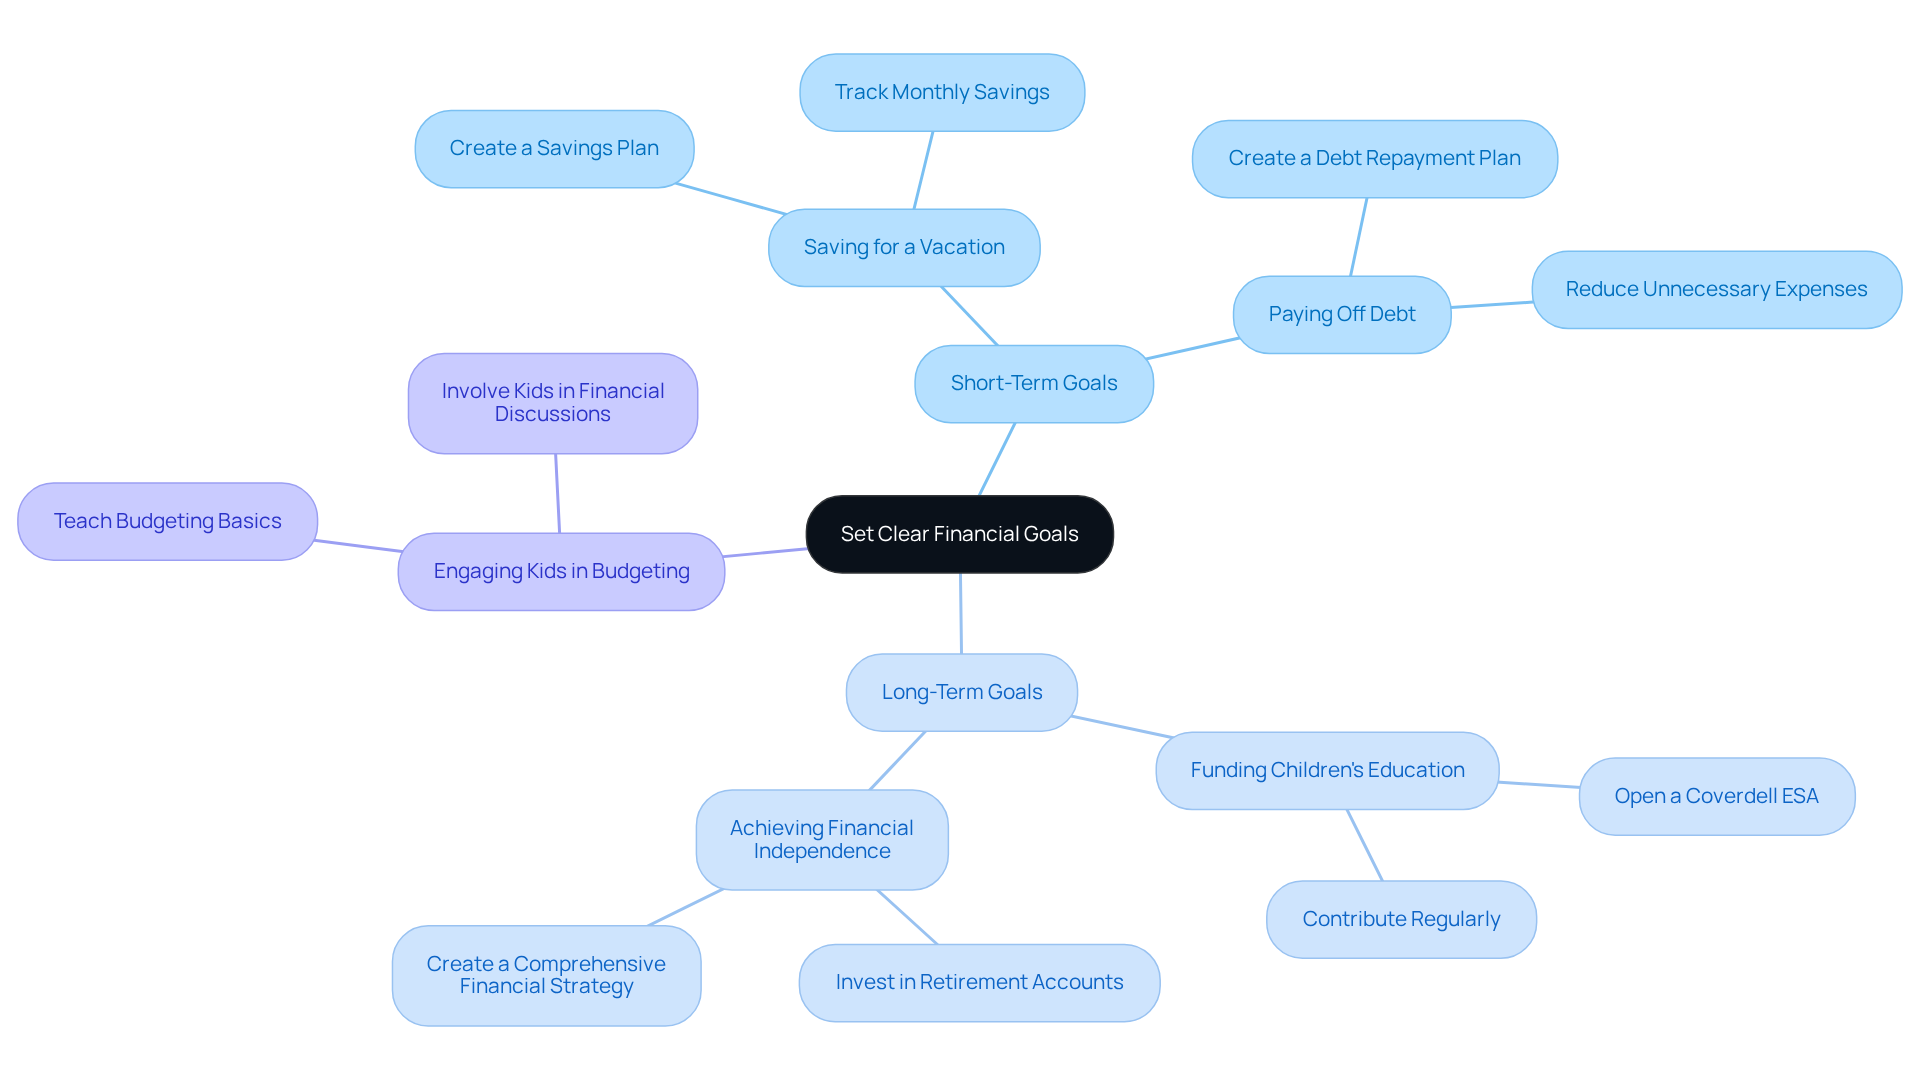
Imagine feeling confident about your family’s financial future, knowing you have a plan in place to achieve your dreams. Setting both short-term and long-term financial objectives can help you get there. Short-term goals might include saving for a vacation, while long-term objectives could focus on funding your children’s education. Writing these goals down and reviewing them regularly enhances accountability and clarity. For instance, if your goal is to save for a vacation, create a detailed savings plan that specifies how much you need to set aside each month to achieve that objective.
Engaging your kids in this process not only teaches them about budgeting but also shows them the importance of working towards shared financial goals. Families who set financial goals together often feel more secure and confident in their choices, with many reporting a positive change in just a year. This collaborative approach strengthens family bonds and prepares children for their financial futures, easing the stress that often comes with money matters.
Consider how Bright Advisers has helped families like Emily and Mark, who wanted the freedom to make work optional. By creating a comprehensive financial strategy that includes personalized wealth management solutions, they managed their finances effectively while balancing demanding careers. Similarly, Allison and Brian maximized their financial potential through coordinated tax strategies, ensuring they could secure their children’s future while enjoying peace of mind. With the right support, you can turn your financial goals into reality, creating a brighter future for your family.
Pay Down Existing Debt
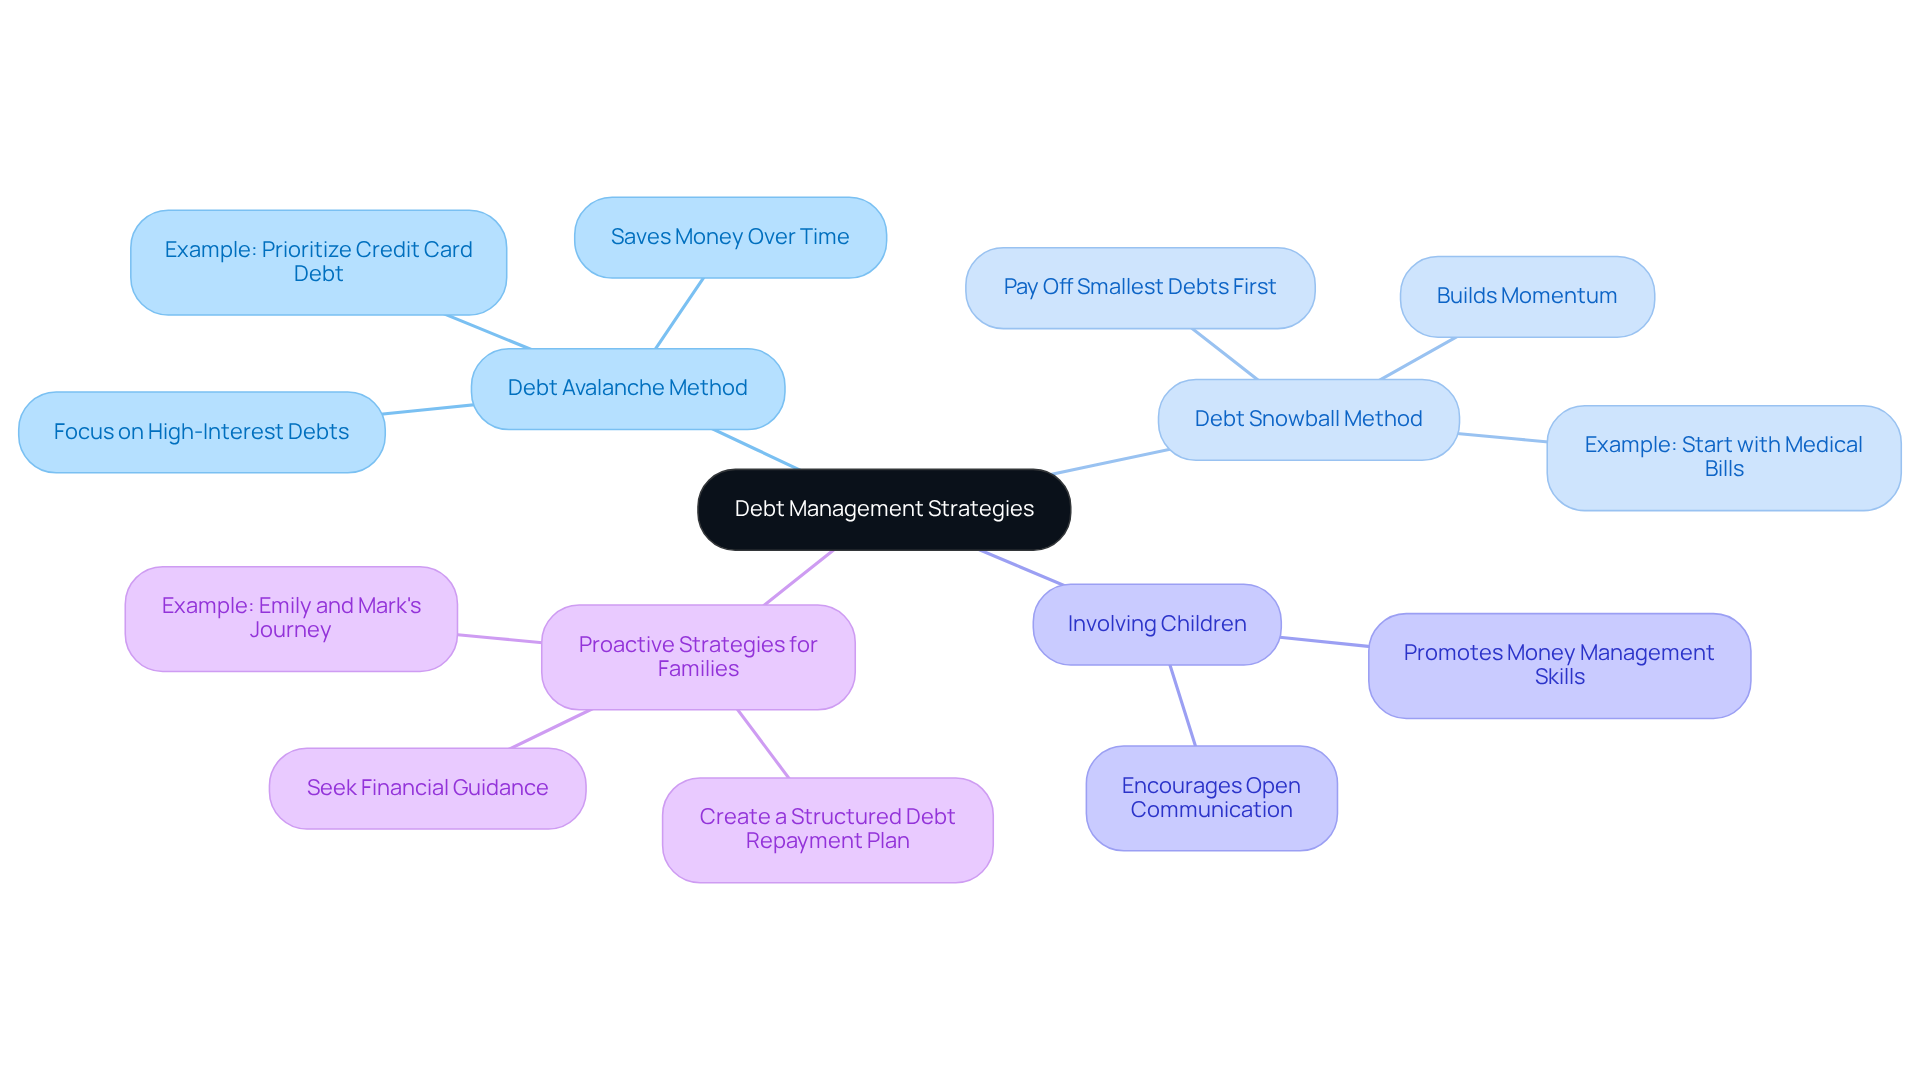
Tackling debt can feel like an uphill battle, but you don’t have to face it alone. Using the debt avalanche method can really help you save money over time by tackling those high-interest debts first. If that feels daunting, you might also consider the snowball method, which focuses on paying off the smallest debts first. This can help you build momentum and motivation. For example, if you have credit card debt, try to pay more than the minimum payment each month. This approach not only speeds up your debt reduction but also cuts down on interest costs over time.
Involving your children in discussions about debt can promote money management skills from a young age. Teach them about the implications of borrowing and the importance of responsible money habits. This not only prepares them for future financial responsibilities but also fosters open communication within your household about money matters.
Many parents in Southern California are feeling the weight of financial stress, struggling to keep up with their expenses. A significant number have taken on debt for essential costs, like medical bills and education. By adopting proactive debt management strategies, families can work towards economic stability and ease the emotional burden that debt can bring. Take Emily and Mark, for instance. They faced similar challenges and sought guidance to navigate their financial complexities. With the help of Bright Advisers, they developed a comprehensive plan that included strategies to reduce debt, manage cash flow effectively, and leverage integrated tax planning. Together, they built a life that aligned with their personal and financial goals, balancing their current responsibilities with long-term aspirations.
Ultimately, creating a structured plan for debt repayment, whether through the avalanche or snowball method, can lead to a more secure economic future for your family. With a clear plan in place, you can pave the way for a brighter financial future for your family.
Stay Aware of Lifestyle Creep
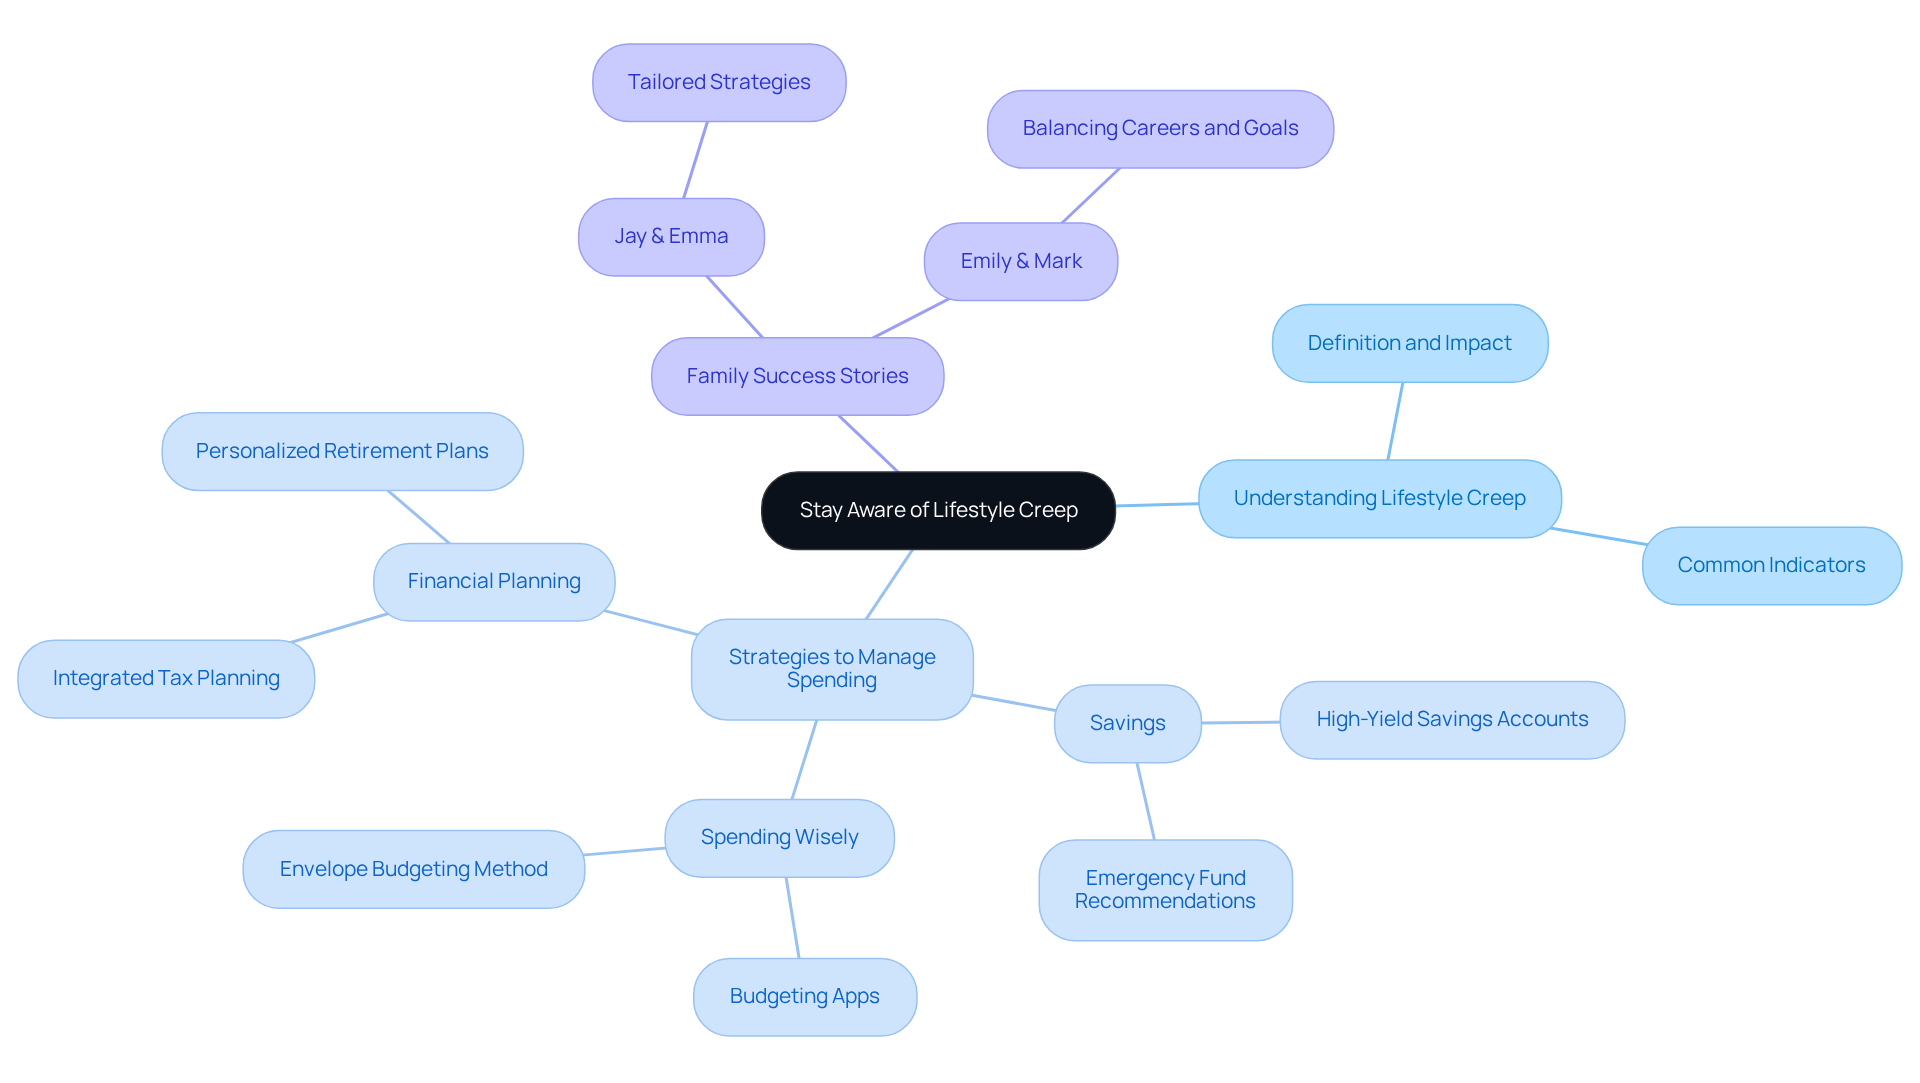
Imagine feeling the weight of rising expenses as your income grows, leaving you questioning if you’re truly making progress. When your income goes up, it’s easy to start spending more without realizing it. Let’s take a moment to think about how we can keep our spending in check. If you get a raise, a good live below your means example would be to put some of that extra money into savings instead of allowing your lifestyle expenses to increase. Talk to your kids about how we can choose to spend wisely, showing them that happiness comes from experiences, not just things.
We’ve helped families like Jay & Emma find relief from financial stress by creating tailored strategies that fit their unique needs. They learned how to manage their resources effectively, allowing them to focus on what truly matters. Similarly, Emily & Mark discovered how to balance their demanding careers with their financial goals, gaining the freedom to choose whether to continue working. By implementing strategies like integrated tax planning and personalized retirement plans, you can find harmony between your current responsibilities and your long-term dreams.
When you take charge of your financial journey, you empower your family to thrive, creating a legacy of security and happiness.
Negotiate Bills and Rates
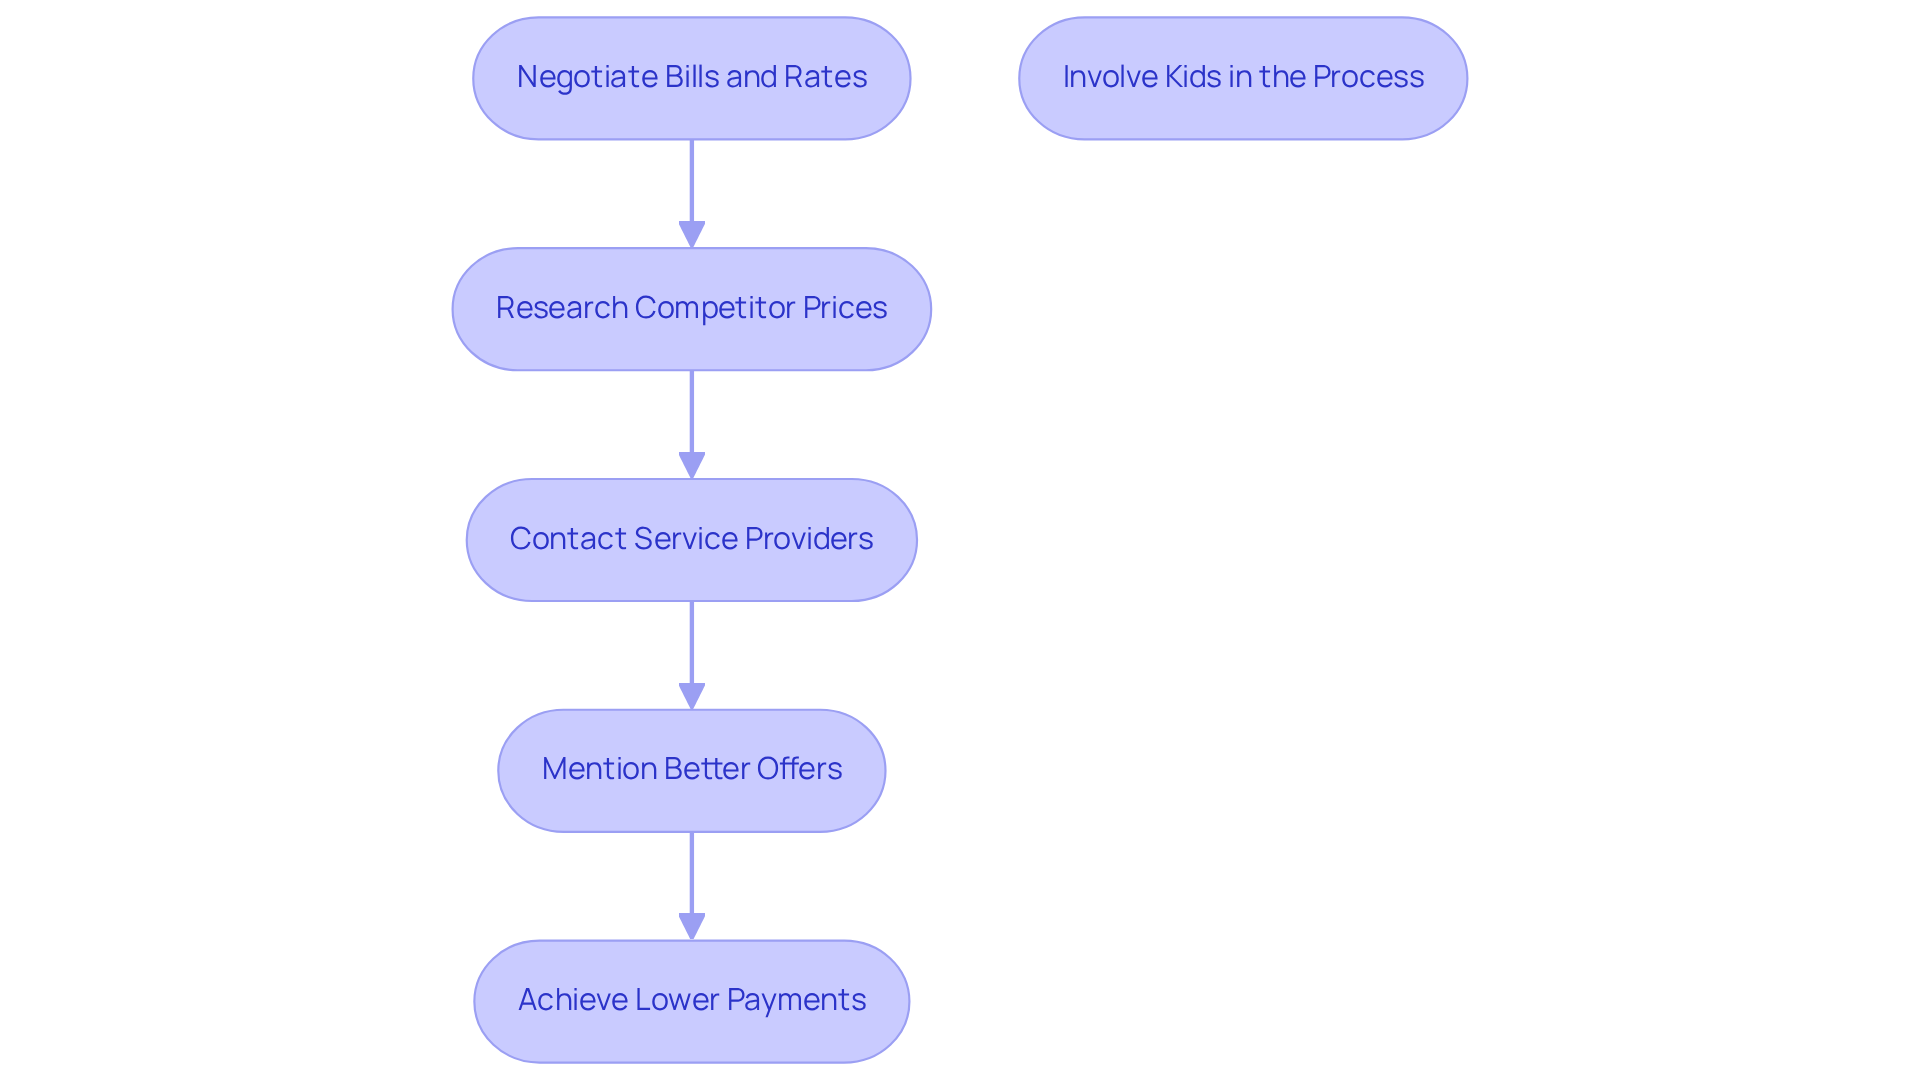
Imagine feeling the weight of rising bills pressing down on your family budget. Why not reach out to your service providers and see if you can negotiate better rates on those essential bills like internet, cable, and insurance? Start by researching competitor prices to strengthen your negotiating position. If you find a more attractive offer from another provider, mention it during your conversation. This simple tactic can lead to lower monthly payments, easing the financial burden for families like Jay and Emma, who are just trying to manage their resources with less stress.
Engaging your kids in this process not only teaches them the importance of self-advocacy but also helps them understand the value of money. Did you know that studies show 93% of Americans who negotiate their medical bills successfully achieve reductions or eliminations of their debt? By fostering these discussions at home, talking about money not only prepares your kids for future financial challenges but also helps them learn valuable money management skills they’ll carry into adulthood.
Bright Advisers can assist you in developing strategies to negotiate effectively and manage your finances better.
Explore Additional Income Opportunities
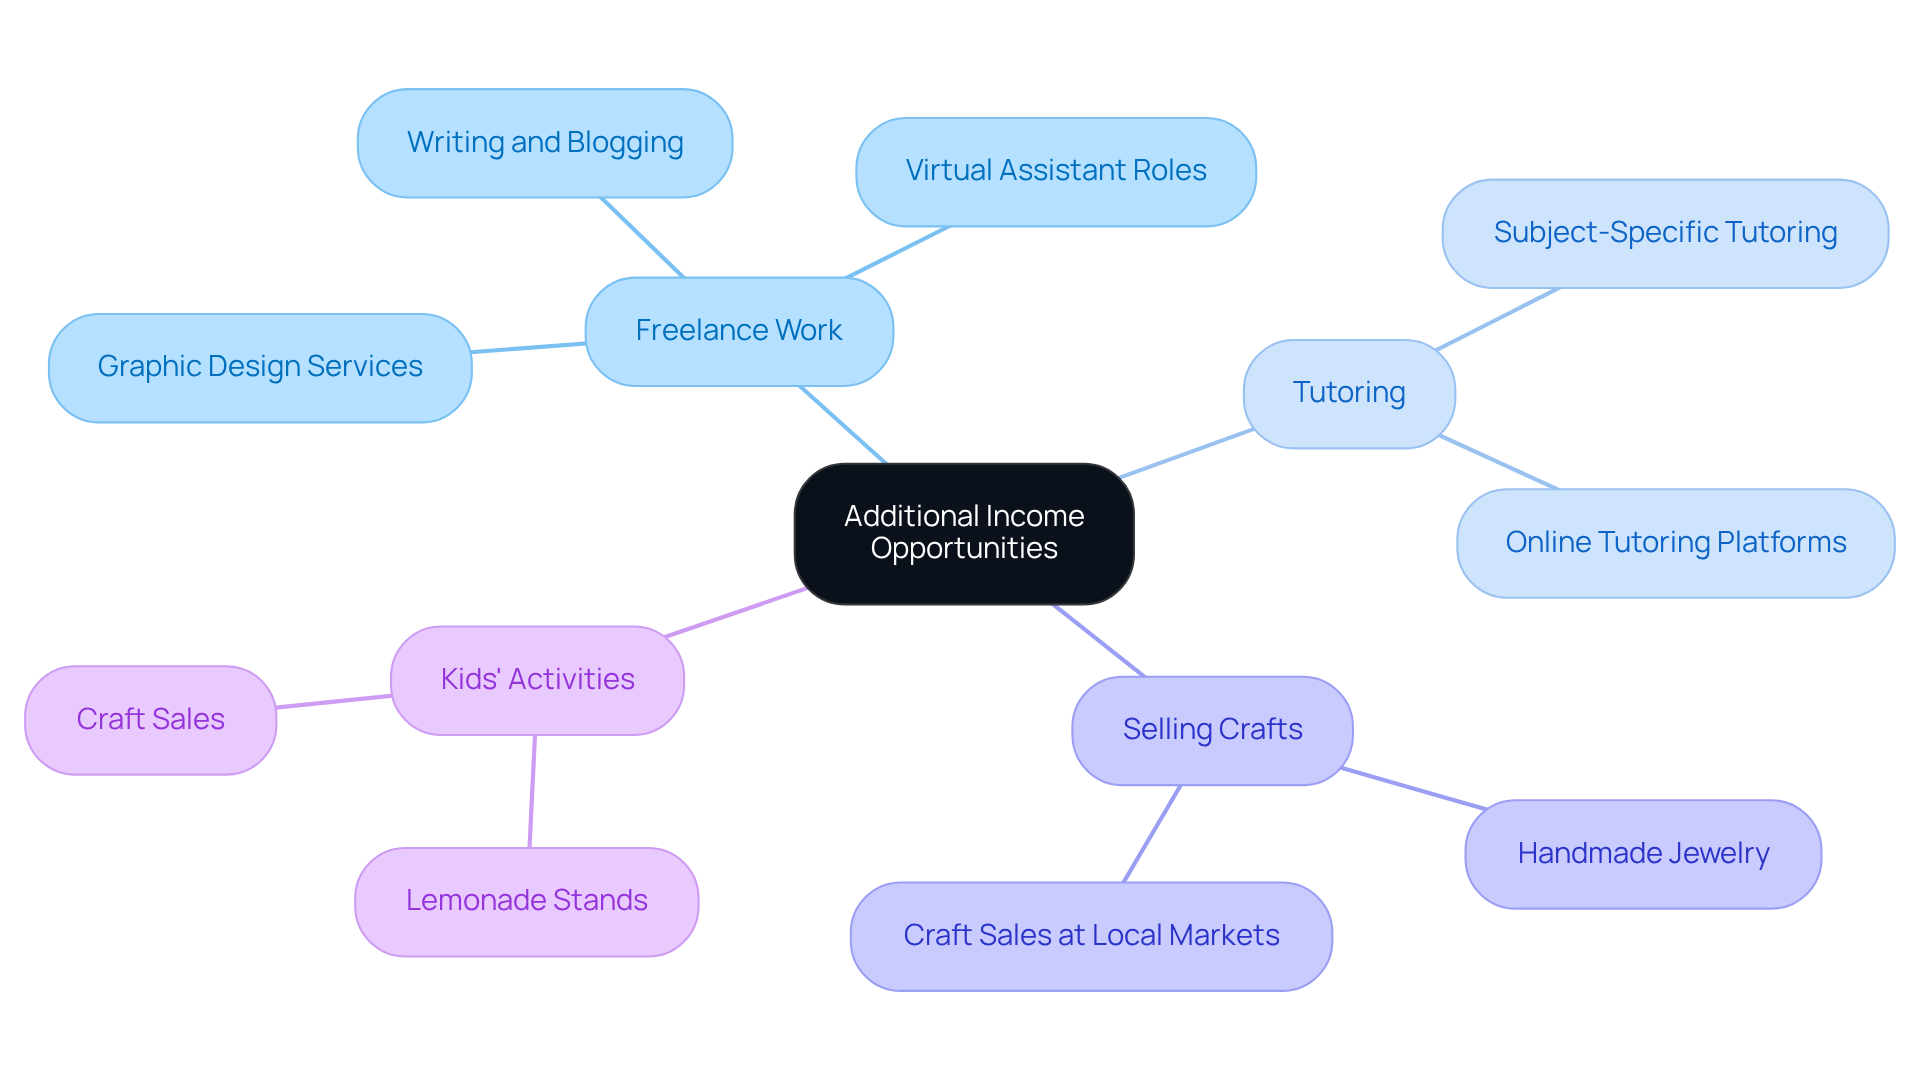
Imagine finding ways to boost your family’s income without sacrificing precious time together. Explore side hustle opportunities that seamlessly fit into your household’s lifestyle, like:
- Freelance work
- Tutoring
- Selling handmade crafts
If you have graphic design skills, consider offering your services online through platforms that cater to creative professionals. You might even declutter your home by selling items you no longer need, turning unused possessions into extra income. Many families are feeling the pinch of rising costs, making it harder to make ends meet, and many are turning to side hustles for relief.
Encouraging your kids to join in these activities can help them learn about responsibility and the value of money in a fun way. Simple tasks like chores can be monetized, or they can brainstorm small entrepreneurial ideas, such as:
- Lemonade stands
- Craft sales
This not only teaches them the value of money but also promotes a cooperative household atmosphere centered on economic growth.
In 2026, nearly 45% of parents with children under 18 have a side hustle, showing how families are creatively adapting to challenges and finding new ways to thrive. Popular side hustles among young parents include:
- App-based driving
- Tutoring
- Virtual assistant roles
These options offer flexibility and the potential for substantial earnings. With the average side hustler earning around $891 per month in 2024, these additional income streams can significantly enhance your family’s financial stability, providing a live below your means example while preparing for future expenses. Embracing these opportunities can not only ease financial burdens but also strengthen family bonds through shared experiences.
Conclusion
Imagine a family life where financial worries don’t overshadow your precious moments together. Living below your means as young parents isn’t just about saving money; it’s about creating a more intentional and fulfilling family life. By examining your financial habits, establishing a budget, and tracking your spending, you can cultivate a sense of control and security over your finances. When you take this proactive approach, it not only eases your stress but also shows your kids how to handle money wisely from an early age.
Throughout this article, we’ve shared practical examples to illustrate how families can effectively reduce unnecessary spending, save for emergencies, and set clear financial goals. Strategies like negotiating bills, exploring additional income opportunities, and being mindful of lifestyle creep empower you to make informed decisions that align with your long-term aspirations. Engaging your children in these discussions fosters a culture of financial awareness and responsibility, ensuring that the lessons learned today will benefit future generations.
Remember, this journey to financial stability is something you can tackle together as a family. By embracing these strategies and seeking guidance from experts like Bright Advisers, you can navigate your financial landscape with confidence. The importance of intentional wealth management cannot be overstated; it lays the foundation for a secure and prosperous future. By taking these steps, you’re not just securing your finances; you’re nurturing a legacy of financial wisdom for your children.
Frequently Asked Questions
Why is it important to examine my financial habits?
Examining your financial habits helps you identify areas where you can cut back on spending and make more intentional choices, ultimately leading to better financial management for your family.
How can I start reflecting on my spending habits?
You can start by reviewing your spending over the past month to uncover areas where you might reduce expenses, such as dining out less and preparing meals at home.
What common issues do families face regarding spending?
Many families struggle with impulse buying, often driven by emotional triggers and societal pressures, which can significantly impact their budgets.
How can creating a budget benefit my family?
Creating a budget helps you gain control over your finances by outlining income and categorizing expenses, which can reduce financial stress and promote responsible spending.
What is a zero-based budget, and how can it help?
A zero-based budget assigns every dollar a specific purpose, encouraging thoughtful spending and helping families avoid unnecessary debt.
How can I involve my children in the budgeting process?
You can make budgeting a family affair by discussing it together and involving your children in choosing affordable options for family outings, teaching them the value of money and saving.
What should I do to track my spending regularly?
Set aside time each week to review your spending habits using budgeting apps or spreadsheets, which can help you identify areas of overspending and promote financial awareness.
How can tracking spending reduce financial stress?
Regularly tracking expenses can help families understand their financial situation better, leading to more informed decisions and reduced anxiety about money management.
What services does Bright Advisers offer to help families with financial planning?
Bright Advisers provides personalized financial strategies, including budgeting, investment planning, and education funding, to help families manage their resources effectively and achieve their financial goals.
What important disclaimers should I be aware of regarding financial advice?
Advisory services are provided through Lifeworks Advisors, a registered investment adviser. Past performance does not guarantee future results, and all investments are subject to risk. There are no guarantees of results, and all advisory services are subject to registration and compliance regulations.
List of Sources
- Examine Your Financial Habits
- Impulse Buying Statistics (2026): Consumer Spending Habits (https://capitaloneshopping.com/research/impulse-buying-statistics)
- Impulse Buying Statistics 2025: Powerful Trends Reshaping Spontaneous Shopping (https://awisee.com/blog/impulse-buying-statistics)
- Survey: Impulse Buys May Be Ruining Some Americans’ Finances – NerdWallet (https://nerdwallet.com/finance/learn/survey-impulse-buys-may-be-ruining-some-americans-finances)
- The State of Impulse Buying (Statistics & Trends 2025) – Invesp (https://invespcro.com/blog/impulse-buying)
- (PDF) Financial Behavior and Its Association with Impulsive Buying Behavior: An Empirical Analysis on Gen Z and Millenials (https://researchgate.net/publication/397674940_Financial_Behavior_and_Its_Association_with_Impulsive_Buying_Behavior_An_Empirical_Analysis_on_Gen_Z_and_Millenials)
- Create and Stick to a Budget
- Average American’s Monthly Expenses by Category (https://ramseysolutions.com/budgeting/american-average-monthly-expenses?srsltid=AfmBOorTi87_Gb0knYY9CW2Xo_MdnVcUw0Lo94oHLn15WVzkqzwM2NuP)
- Average Monthly Expenses For American Households (https://incharge.org/financial-literacy/budgeting-saving/average-monthly-expenses)
- Making Ends Meet: How Much Does It Cost to Support a Family in California? (https://calbudgetcenter.org/resources/making-ends-meet-much-cost-support-family-california)
- Cost of Living in California (https://sofi.com/cost-of-living-in-california)
- U.S. Bureau of Labor Statistics (https://bls.gov/regions/west/news-release/consumerexpenditures_losangeles.htm)
- Track Your Spending Regularly
- New Data Shows Who Controls Household Spending and Budget | Salsify (https://salsify.com/blog/data-shows-controls-household-spending-and-budget?hs_amp=true)
- Household Budget Statistics | Self. Credit Builder. (https://self.inc/info/household-budget-statistics)
- Money Talk: 10 Great Quotes About Personal Finance (https://3riversfcu.org/resources/financial-education/detail/money-talk-10-great-quotes-about-personal-finance)
- Study reveals household spending trends over 30 years (https://port.ac.uk/news-events-and-blogs/news/study-reveals-household-spending-trends-over-30-years)
- Understanding family spending through data analysis | data.europa.eu (https://data.europa.eu/en/publications/datastories/understanding-family-spending-through-data-analysis)
- Reduce Unnecessary Spending
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Savings and Investments (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm)
- How Much Money Americans Save Each Year (by Age, Income, and State) – Carry (https://carry.com/learn/how-much-money-americans-save-each-year)
- New 2025 wealth stats reveal how Americans are saving, spending, and stacking cash – where do you stand? (https://m.economictimes.com/news/international/us/2025-u-s-wealth-statistics-new-2025-wealth-stats-reveal-how-americans-are-saving-spending-and-stacking-cash-where-do-you-stand/articleshow/124275655.cms)
- Subscription Spending Statistics (2026): What the Data Shows (https://resubs.app/resources/subscription-spending-statistics)
- New Survey Finds Americans’ Spending Habits Are Ruining Their Retirement (https://finance.yahoo.com/news/survey-finds-americans-spending-habits-100000015.html)
- Save for Emergencies
- US Emergency Savings Fund Statistics (https://remitly.com/blog/finance/us-emergency-savings-statistics)
- Median Emergency Savings By Age In 2026: Are You Financially Prepared? (https://forbes.com/sites/investor-hub/article/median-emergency-savings-by-age)
- Bankrate’s 2026 Emergency Savings Report | Bankrate (https://bankrate.com/banking/savings/emergency-savings-report)
- The Average American Has This Much in Emergency Savings. Do You? (https://oldnational.com/resources/insights/the-average-american-has-this-much-in-emergency-savings-do-you)
- 49% of Americans Can’t Afford a $1,000 Emergency (https://lendingtree.com/debt-consolidation/emergency-savings-survey)
- Set Clear Financial Goals
- Strategies for Funding a Child’s Education in 2026 (https://creativeplanning.com/insights/financial-planning/strategies-education-funding-2026)
- Setting New Financial Goals Feels Powerful; Sticking to Them Can Be Tough (https://newsroom.wf.com/news-releases/news-details/2026/Setting-New-Financial-Goals-Feels-Powerful-Sticking-to-Them-Can-Be-Tough/default.aspx)
- Understanding the Financial Goal Setting Worksheet for Young Families – Bright Advisers (https://brightadvisers.com/understanding-the-financial-goal-setting-worksheet-for-young-families)
- Key Financial Literacy Statistics in 2023 (https://annuity.org/financial-literacy/financial-literacy-statistics)
- Pay Down Existing Debt
- How Much Debt Does Your Generation Carry? (https://sofi.com/learn/content/average-debt-age)
- How much debt does the average American have? (https://cnbc.com/select/average-american-debt-by-age)
- Soaring living costs push majority of parents into debt – Talker Research (https://talkerresearch.com/soaring-living-costs-push-majority-of-parents-into-debt)
- American Household Debt: Statistics and Demographics (https://debt.org/faqs/americans-in-debt/demographics)
- Average American Debt by Age, US State, Credit Score and Type in 2025 (https://experian.com/blogs/ask-experian/research/consumer-debt-study)
- Stay Aware of Lifestyle Creep
- What is lifestyle creep? (https://cnbc.com/select/what-is-lifestyle-inflation)
- Report on the Economic Well-Being of U.S. Households in 2024 – May 2025 – Income and Expenses (https://federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-income-and-expenses.htm)
- 25 Quotes that will change how you look at money (https://seedtime.com/quotes-about-money)
- Household Expenditures and Income (https://pew.org/en/research-and-analysis/issue-briefs/2016/03/household-expenditures-and-income)
- Negotiate Bills and Rates
- 93% of Americans Who Negotiate A Medical Bill Get It Eliminated or Reduced (https://press.lendingtree.com/news/press-releases/93-of-americans-who-negotiate-a-medical-bill-get-it-eliminated-or-reduced)
- The best bill negotiation services of 2026 (https://cnbc.com/amp/select/best-bill-negotiation-services)
- Consumers find success in medical bill disputes (https://healthcarefinancenews.com/news/consumers-find-success-medical-bill-disputes)
- Negotiation (https://emryhealth.com/negotiation)
- Struggling to pay monthly bills? These companies say they can help lower them. (https://usatoday.com/story/money/personalfinance/2024/10/12/professional-negotiators-slash-bills-save-money/75568869007)
- Explore Additional Income Opportunities
- The rise of the Gen Z side hustle (https://bbc.com/worklife/article/20230302-the-rise-of-the-gen-z-side-hustle)
- Side Hustles Shift From Optional to Essential as California Ranks 2nd in National Search Data (https://smdp.com/side-hustles-shift-from-optional-to-essential-as-california-ranks-2nd-in-national-search-data)
- Side hustle statistics for [year]: Key data, trends, and what they mean (https://hostinger.com/in/tutorials/side-hustle-statistics)
- ‘My Schedule Is Mayhem:’ Nearly 50% of Parents Now Have Side Hustles, According to a New Survey (https://entrepreneur.com/business-news/nearly-50-of-parents-have-started-side-hustles-survey/476978)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading