

Key Highlights:
- Bright Advisers offers personalised tax planning for high-income families, integrating advanced technology with a personal touch.
- Tailored tax strategies aim to reduce obligations while aligning with long-term financial goals and family values.
- Depreciation recapture can lead to significant tax liabilities; strategies like 1031 exchanges can help defer these taxes.
- Tax-loss harvesting allows high-income earners to offset gains and reduce taxable income by selling underperforming investments.
- Maximising contributions to retirement accounts, such as 401(k)s and IRAs, can significantly lower taxable income and enhance tax benefits.
- Health Savings Accounts (HSAs) provide tax-deductible contributions and tax-free withdrawals for medical expenses, offering a triple tax advantage.
- Charitable contributions can reduce taxable income, with strategies like donating appreciated assets and using donor-advised funds (DAFs) to maximise tax benefits.
- Investing in Opportunity Zones allows postponement of taxes on gains and can result in tax-free earnings after ten years.
- 1031 exchanges enable real estate investors to defer capital gains taxes by reinvesting in similar properties.
- Flexible Spending Accounts (FSAs) help families manage healthcare costs with pre-tax dollars, reducing taxable income.
- Estate planning strategies, including trusts and gifting, can minimise taxes and preserve wealth for future generations.
Introduction
Navigating the complex world of taxes can feel overwhelming, especially for high-income earners. You might be facing unique financial challenges and opportunities that can leave you feeling uncertain. This article explores ten strategic tax loopholes designed to help you maximize your savings while staying compliant with regulations.
Imagine if you could identify and leverage these strategies to minimize your tax liabilities. Understanding the nuances of these loopholes could be the key to unlocking significant financial advantages for you and your family, paving the way for a prosperous future.
We’re here for you, ready to guide you through this journey. Together, we can explore how these strategies can align with your family values and financial goals. Let’s take a closer look at how you can navigate this landscape with confidence and clarity.
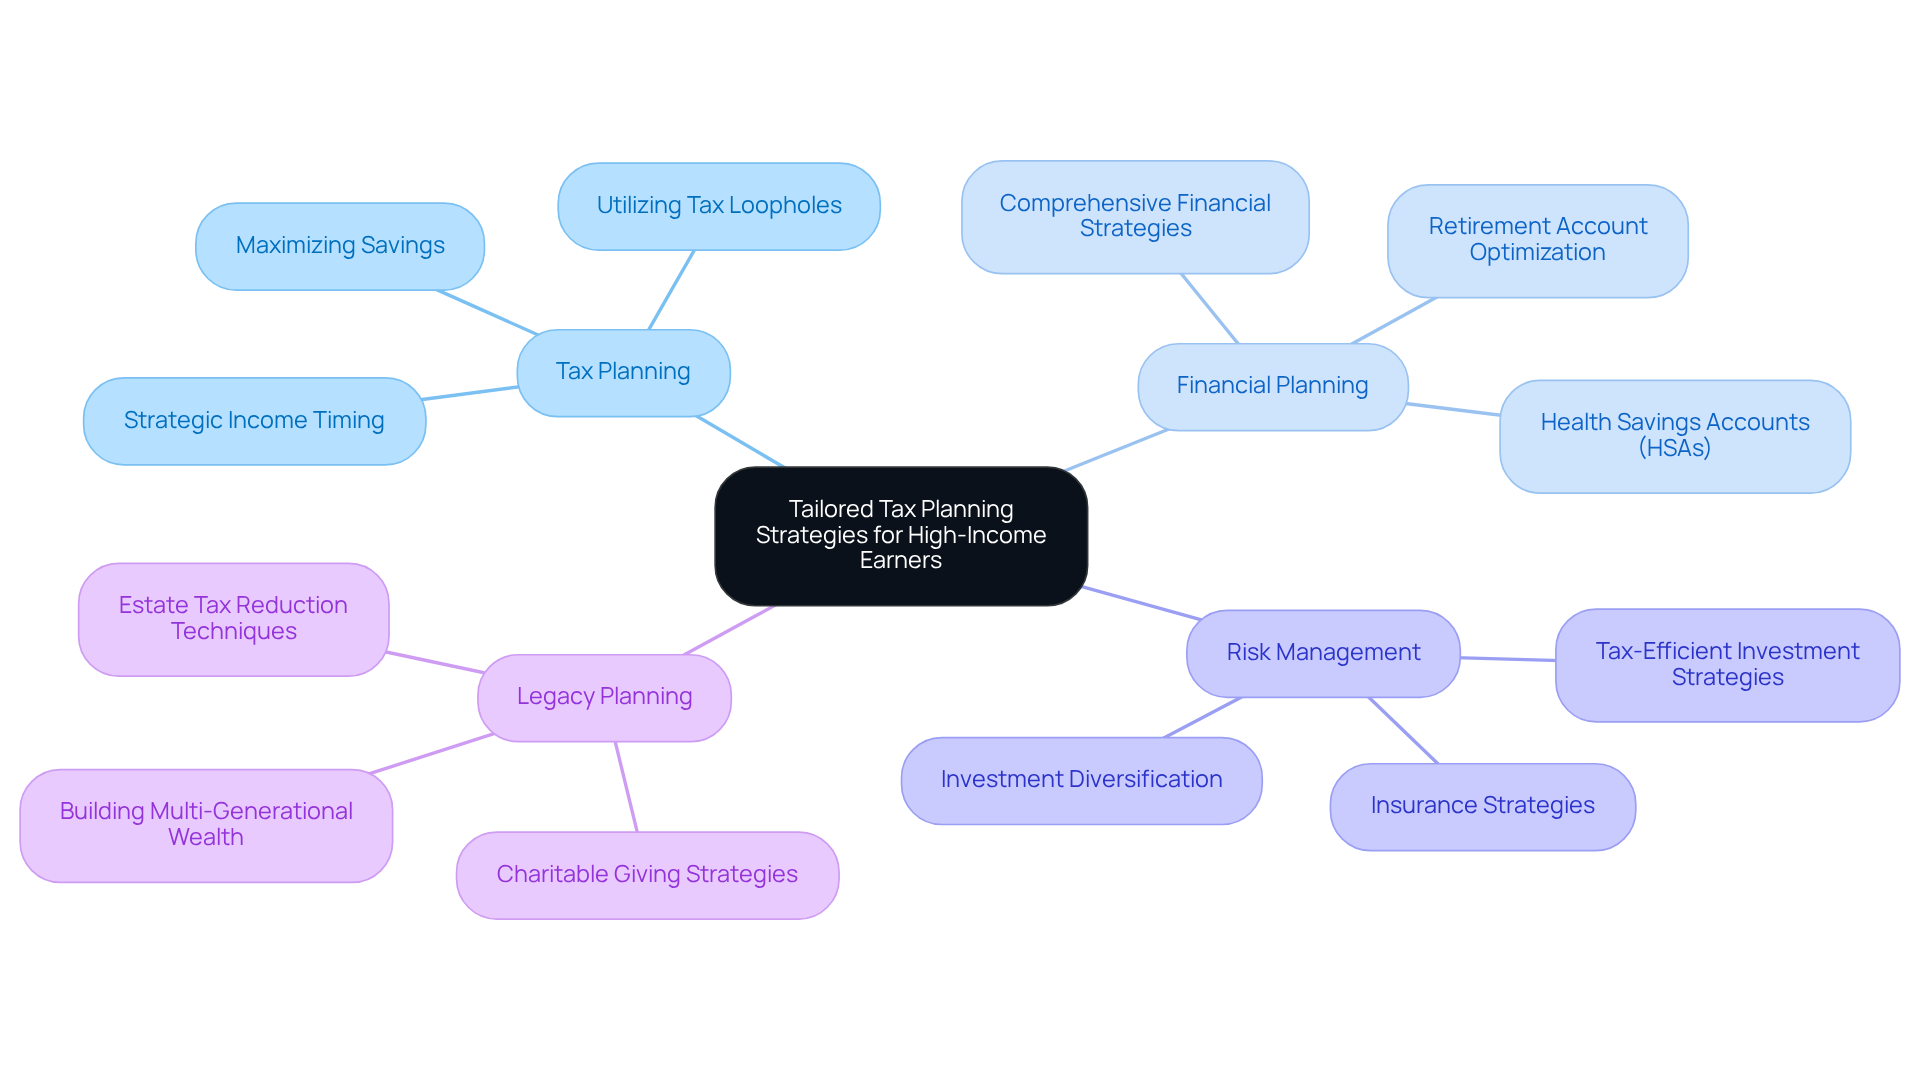
Bright Advisers: Tailored Tax Planning Strategies for High-Income Earners
At Bright Advisers, we understand the unique challenges that high-income families face when navigating tax loopholes for high-income earners in their tax planning. Imagine if you could maximize your savings while ensuring that you’re fully compliant with tax regulations. Our tailored approaches are designed just for you, blending advanced technology with a personal touch to help you navigate the often complex world of taxes.
We take the time to truly comprehend your family’s distinct financial situation. By doing so, we create plans that not only aim to reduce your tax obligations but also take advantage of tax loopholes for high-income earners while aligning with your long-term financial goals. We believe in incorporating your family values and knowledge to help build multi-generational wealth that you can be proud of.
Our holistic wealth management service goes beyond just tax strategies. We offer comprehensive financial planning, risk management, and legacy planning, empowering you to plan purposefully for the future while enjoying life today. Together, we can navigate this journey, ensuring that your family’s financial future is secure and prosperous.
Let us help you create a legacy that reflects your values and aspirations. We’re here for you, ready to .
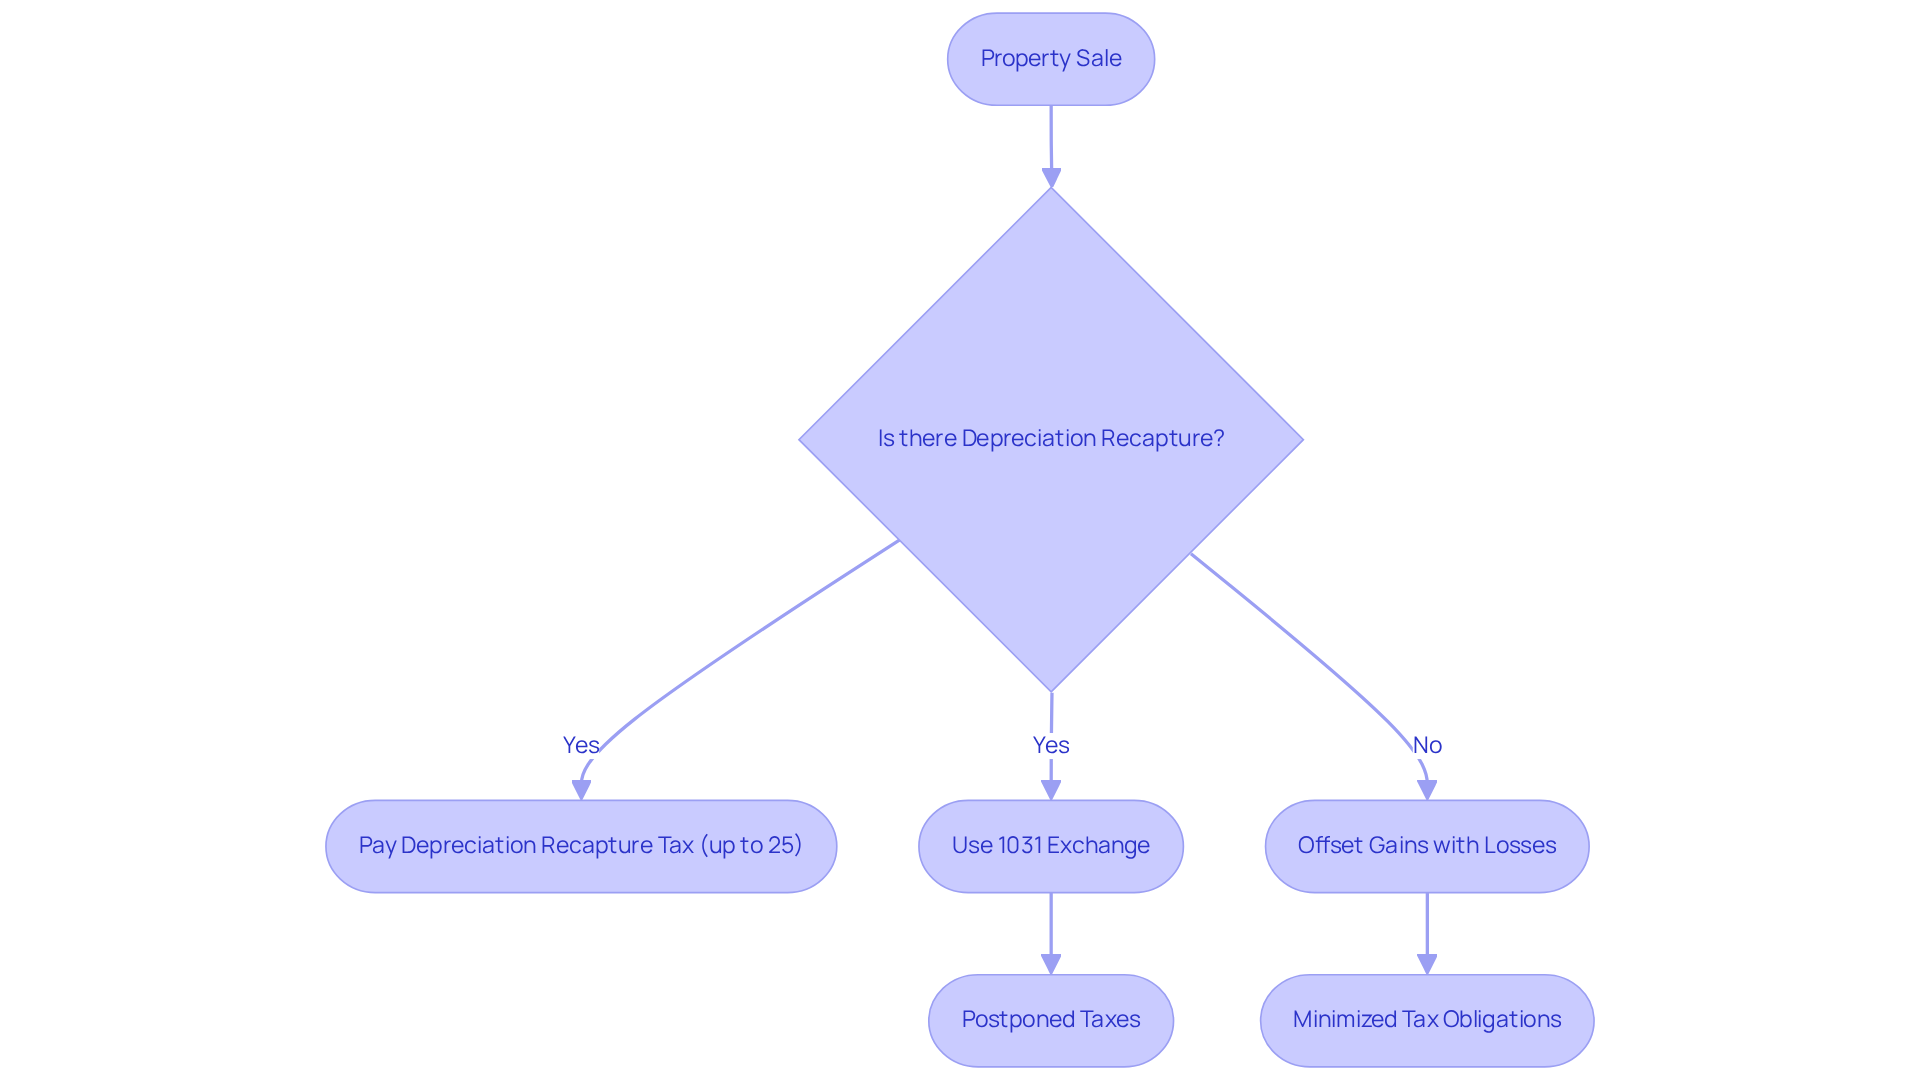
Depreciation Recapture: A Key Tax Loophole for High-Income Earners
When you sell a property that has depreciated, you might face something called depreciation recapture, especially if you sell it for more than what you originally paid. This can lead to tax liabilities that can be quite hefty, particularly due to tax loopholes for high-income earners. Did you know that the tax rate on recaptured depreciation can soar up to 25%? That’s a significant hit to your overall tax obligations. But don’t worry—there are ways to navigate this challenge.
One effective strategy is the use of 1031 exchanges. These allow you to postpone both gains and depreciation recapture taxes by reinvesting the proceeds from your property sale into a similar asset. This not only helps you preserve your capital but also supports ongoing tax-deferred growth, which is crucial for your family’s financial future.
Many high-income earners consider tax loopholes for high-income earners a cornerstone of their tax planning through 1031 exchanges. Take the story of Allison and Brian, for example. This couple, despite their impressive incomes, found themselves struggling financially due to a lack of effective tax planning. After teaming up with Bright Advisers, they learned how to improve their tax situation, including the benefits of 1031 exchanges. This proactive approach allowed them to , freeing up more funds for future investments, securing their children’s education, and even paving the way for an earlier retirement.
Tax professionals stress the importance of understanding depreciation recapture and the advantages of 1031 exchanges. As Randall Weaver, a Partner at Trout CPA, wisely noted, “Avoiding or postponing taxes like gains from investments and depreciation recapture should be an aspect of every serious investor’s approach.” This insight is especially vital for high-income individuals, including young parents, who need to engage in proactive tax planning to navigate tax loopholes for high-income earners. It’s all about being prepared for potential liabilities while maximizing investment opportunities.
Additionally, if you’re in a high-income bracket, consider the possibility of using losses to offset gains from depreciation recapture to take advantage of tax loopholes for high-income earners. This can further refine your tax strategy. Plus, holding onto property until death can provide heirs with a step-up in basis, effectively eliminating depreciation recapture and gains tax—an essential consideration for estate planning.
In summary, by grasping the complexities of depreciation recapture and leveraging strategies like 1031 exchanges, high-income individuals can skillfully navigate their tax landscape, taking advantage of tax loopholes for high-income earners. This not only minimizes liabilities but also enhances financial outcomes for their families. Remember, we’re here for you, and together, we can navigate this journey toward a more secure financial future.
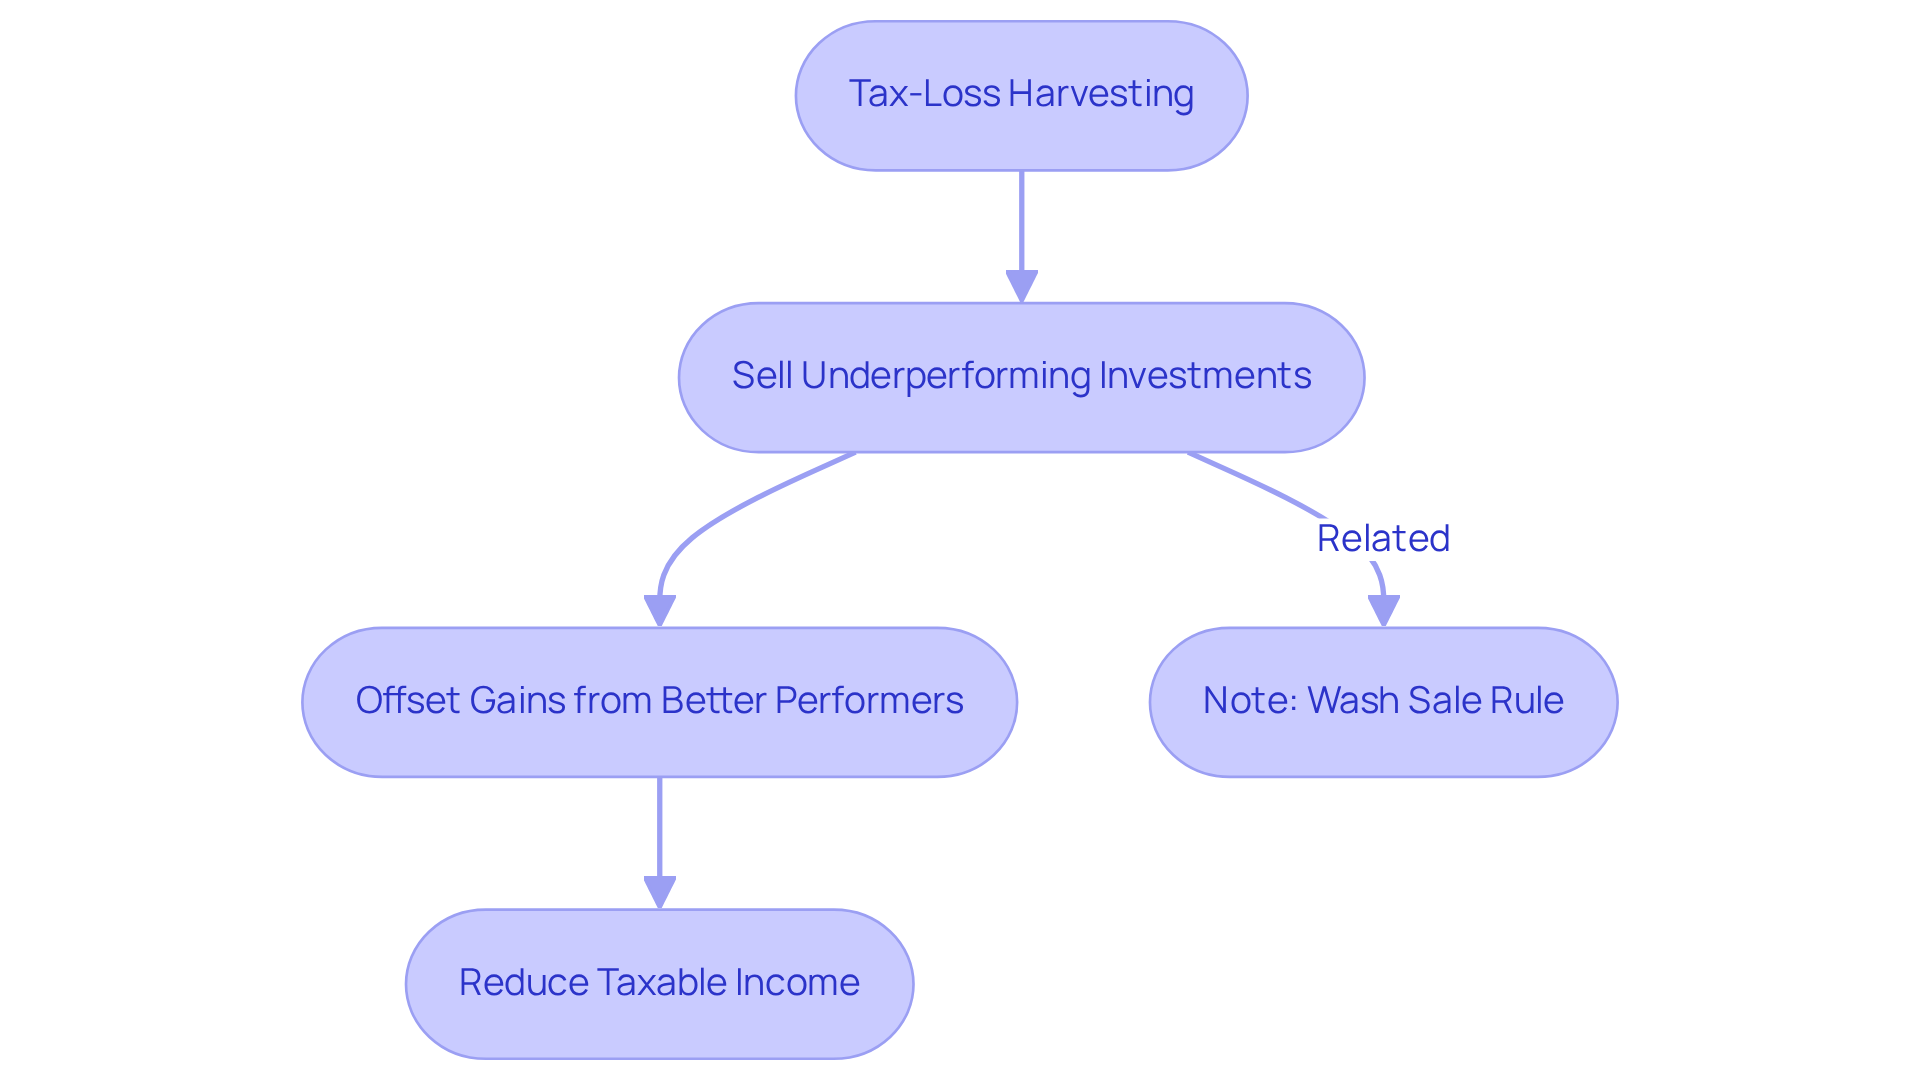
Tax-Loss Harvesting: Offset Gains and Reduce Taxable Income
Tax-loss harvesting can be a smart way to help you keep more of your hard-earned money. By selling investments that aren’t performing well, you can offset the gains from those that are doing better, which can lower your taxable income. This strategy is especially beneficial for high-income earners, as it utilizes tax loopholes for high-income earners, allowing you to hold onto more of your earnings for your family’s needs. For instance, if you make a $10,000 profit from one stock but lose $4,000 on another, you can reduce your taxable income by that loss, leaving you with a net taxable gain of just $6,000.
In times of market ups and downs, tax-loss harvesting becomes even more effective. The fluctuations in asset values can create more chances to realize losses. Studies show that investors who actively engage in this strategy during volatile periods can significantly boost their after-tax returns. Take Jane, for example. She faced a $15,000 drop in her mutual fund investments but managed to cut her tax bill by $3,450 through smart loss harvesting. This clearly shows how beneficial this approach can be.
Financial advisors often stress the importance of including tax-loss harvesting in your overall investment strategy, particularly to take advantage of tax loopholes for high-income earners. By balancing your investment gains with realized losses, you can lower your tax bill for the current year and potentially improve your tax situation in the future. However, it’s essential to approach this thoughtfully, ensuring that your long-term growth goals aren’t overshadowed by short-term tax benefits.
Also, keep in mind the ‘wash sale’ rule, which prevents you from claiming a loss if you buy the same or a similar security within 30 days. You can with capital losses up to $3,000 each year, and remember that all tax-loss harvesting must be wrapped up by December 31 of the tax year. If you’re feeling uncertain about how to implement this strategy, reaching out to a financial advisor can provide you with the guidance you need.
Together, we can navigate this journey toward better financial health for you and your family.
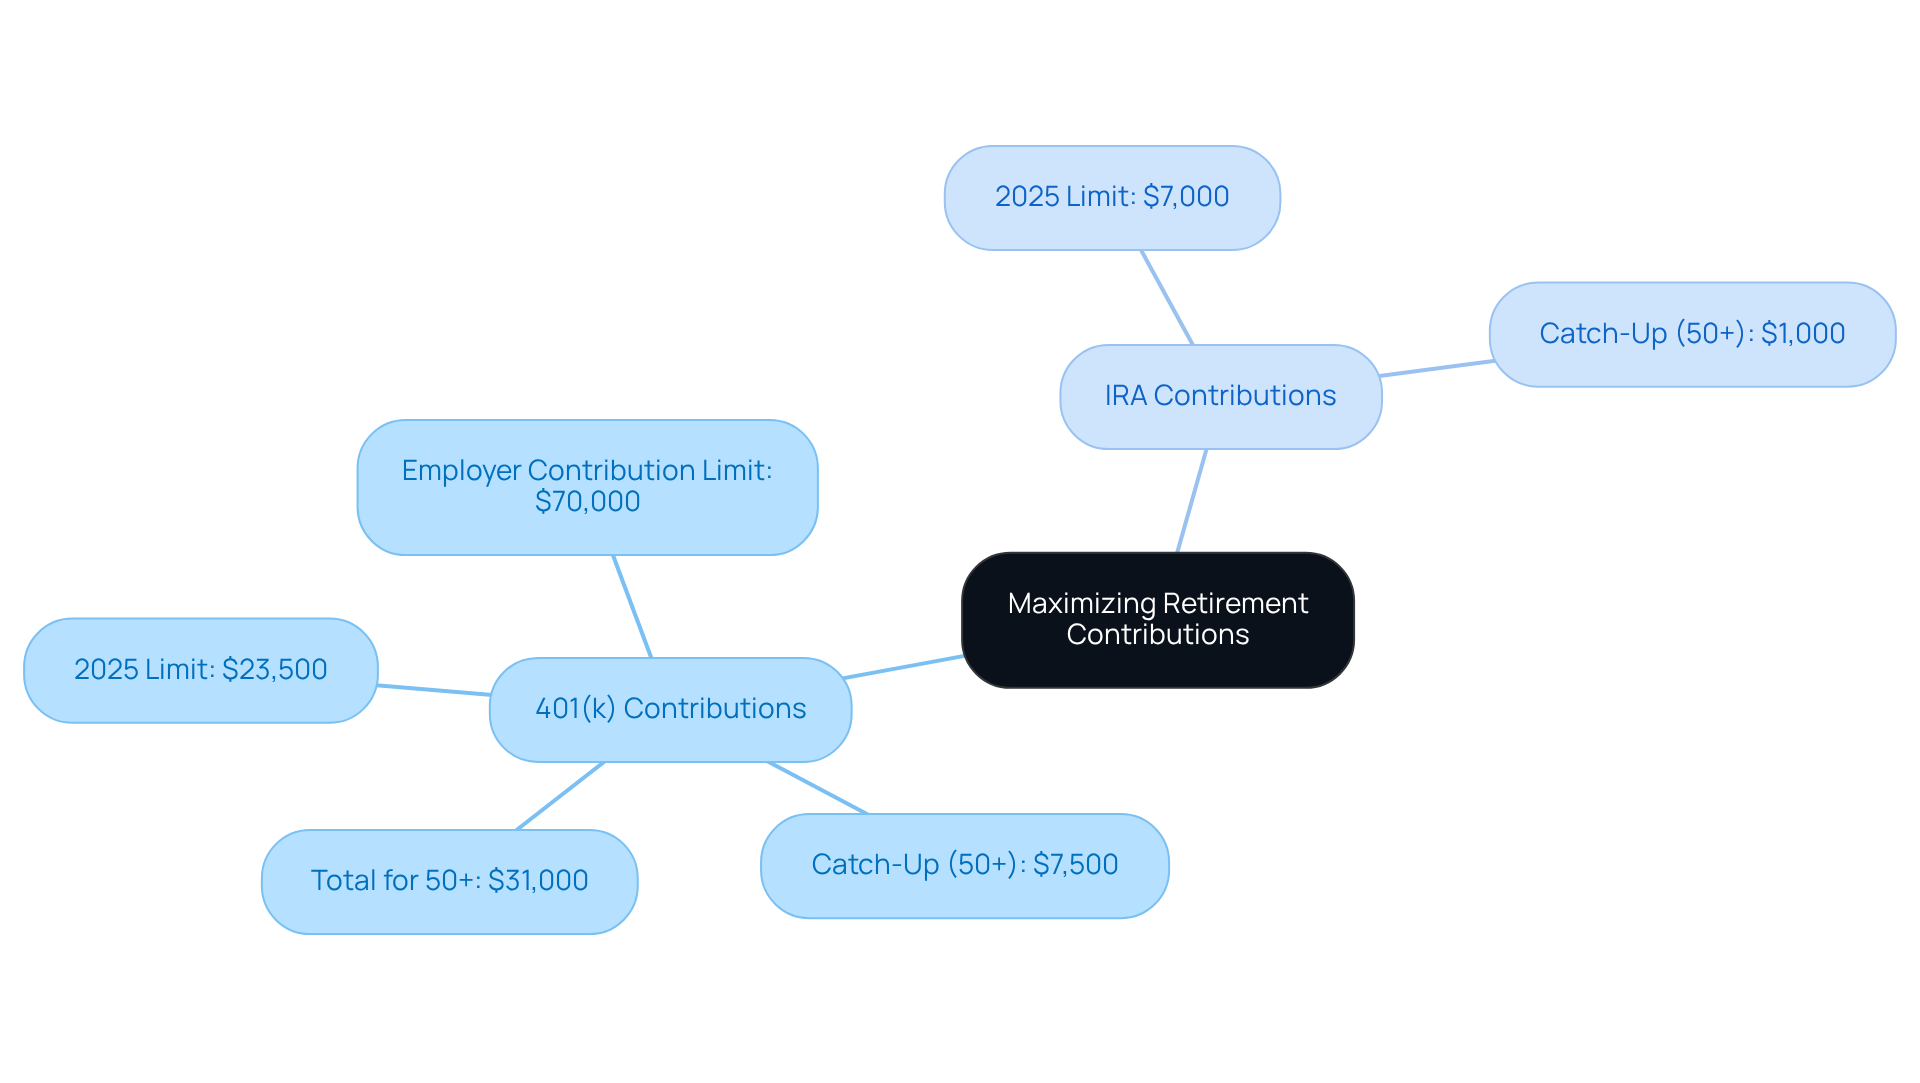
Retirement Accounts: Maximize Contributions for Tax Benefits
Are you a parent looking to secure your family’s financial future? You’re not alone. Many individuals with high incomes can effectively reduce their taxable income by maximizing contributions to retirement accounts, like 401(k)s and IRAs. In 2025, the contribution limit for 401(k)s is set at $23,500, plus an additional catch-up contribution of $7,500 for those aged 50 and older. This means that if you’re in this age group, you can contribute up to $31,000, significantly .
Imagine the peace of mind that comes from fully funding these accounts. Not only do you reduce your current tax liabilities, but you also benefit from tax-deferred growth, which can lead to substantial savings over time. And for those under 50, the combined contribution limit for employee and employer contributions to a 401(k) plan will reach $70,000, allowing for even greater tax efficiency.
Financial planners often highlight that maximizing these contributions helps to exploit tax loopholes for high-income earners. It’s not just about retirement planning; it’s also a way to lessen the impact of higher tax brackets. Plus, if you’re aged 60-63, you can take advantage of an extended catch-up contribution limit of $11,250 in 2025, further enhancing your retirement savings.
It’s also important to understand the IRS definition of a highly compensated employee (HCE). This includes anyone who owns more than 5% of the business or is in the top 20% of employees by compensation. HCEs face unique challenges in maximizing their contributions due to additional limits and restrictions set by the IRS.
In addition to 401(k)s, you can also contribute up to $7,000 to IRAs in 2025, with a catch-up contribution of $1,000 for those aged 50 and above. By utilizing both 401(k) and IRA contributions, you can further enhance your tax benefits and retirement readiness.
Overall, strategically maximizing your retirement account contributions is a powerful tool for individuals with high incomes who can take advantage of tax loopholes for high-income earners. It’s a way to optimize your tax situation while securing your family’s financial future. Remember, we’re here for you, and together, we can navigate this journey.
Health Savings Accounts: Tax-Advantaged Savings for Medical Expenses
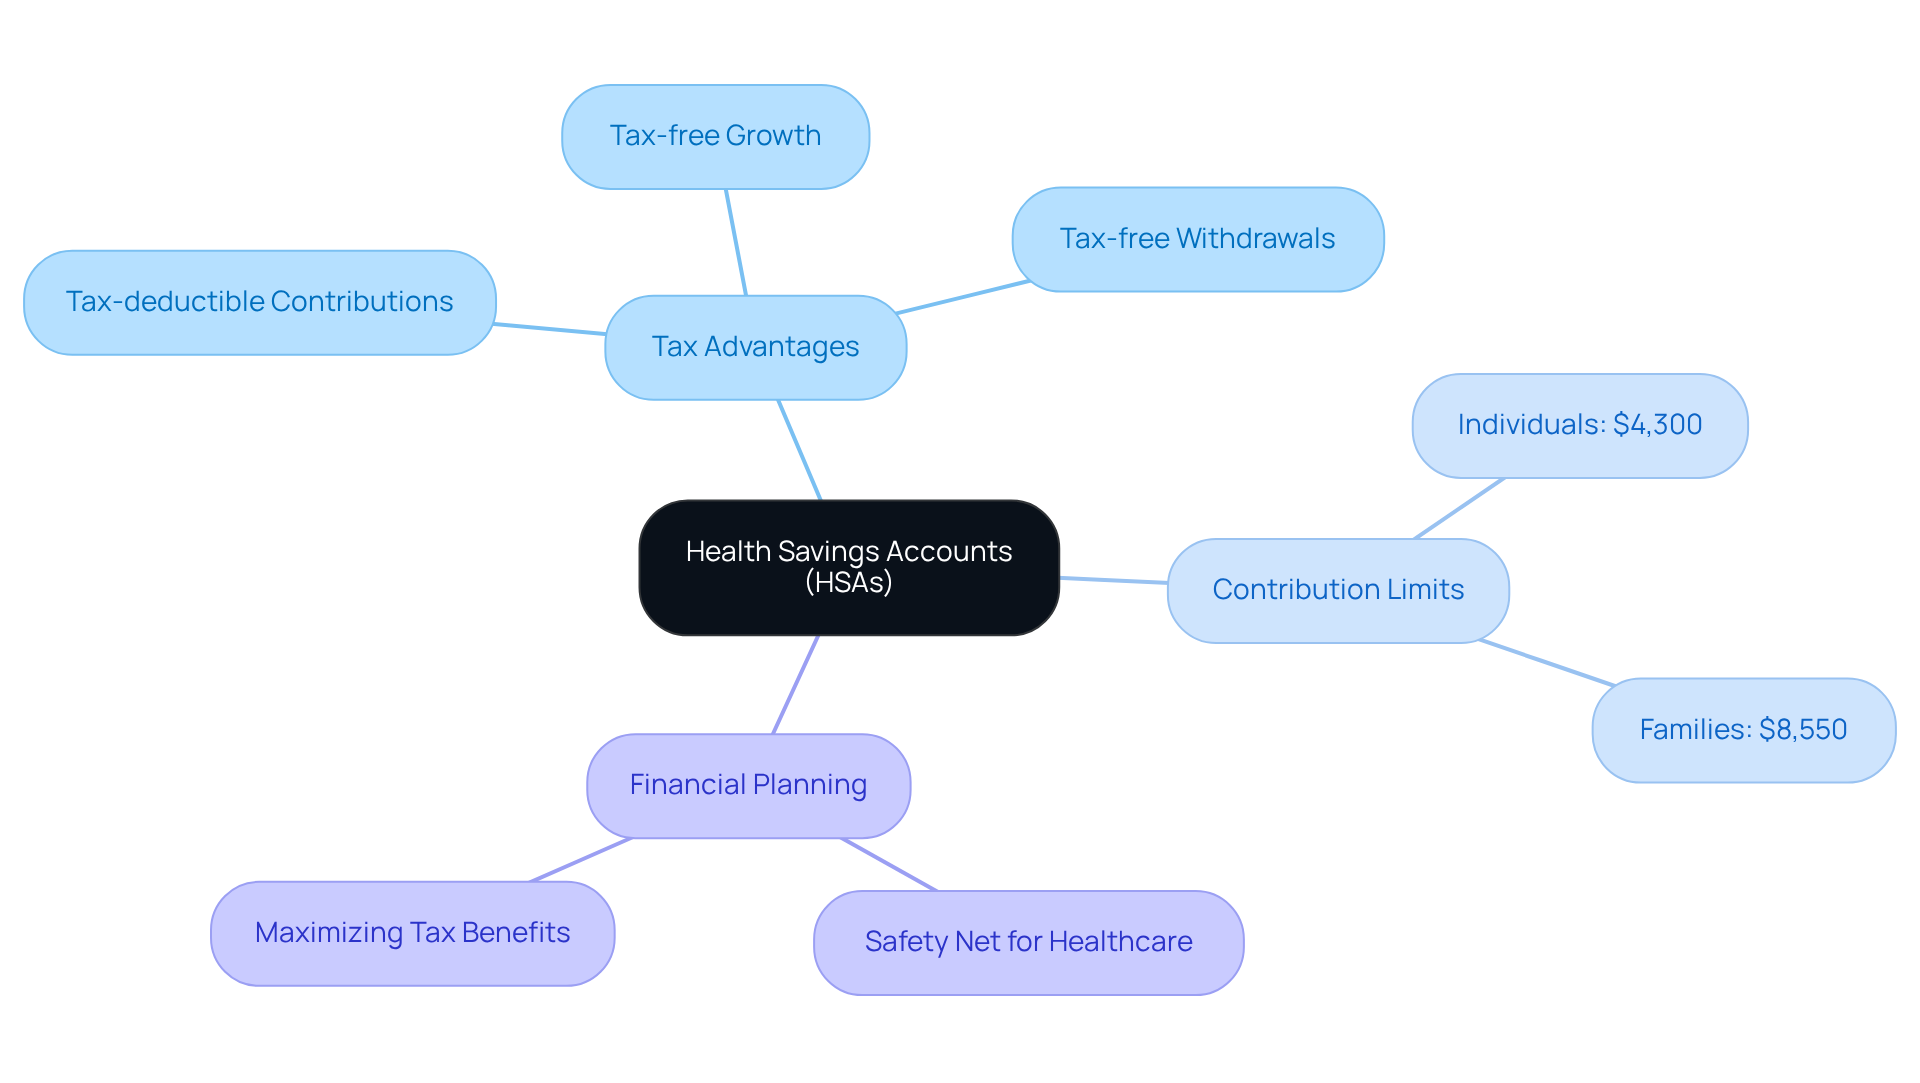
Imagine a way to ease the financial burden of healthcare while also saving on taxes. Health Savings Accounts (HSAs) offer a wonderful opportunity for families to do just that. With a , contributions to your HSA are tax-deductible, the account grows tax-free, and withdrawals for qualified medical expenses are also tax-free.
For 2025, individuals can contribute up to $4,300 to their HSA, while families can contribute up to $8,550. This means that by utilizing HSAs, you can effectively manage healthcare costs while enjoying significant tax benefits.
Think about how this could impact your family’s financial planning. By setting aside money in an HSA, you’re not just saving for medical expenses; you’re also creating a safety net for your family’s health needs. It’s important to understand that these accounts can be a vital part of your overall financial strategy, especially for high-income individuals looking to maximize their savings and navigate tax loopholes for high-income earners.
Together, we can navigate this journey toward better financial health. By considering HSAs, you’re taking a proactive step in securing your family’s future. Remember, we’re here for you, ready to help you explore the best options for your family’s needs.
Charitable Contributions: Reduce Taxable Income While Giving Back
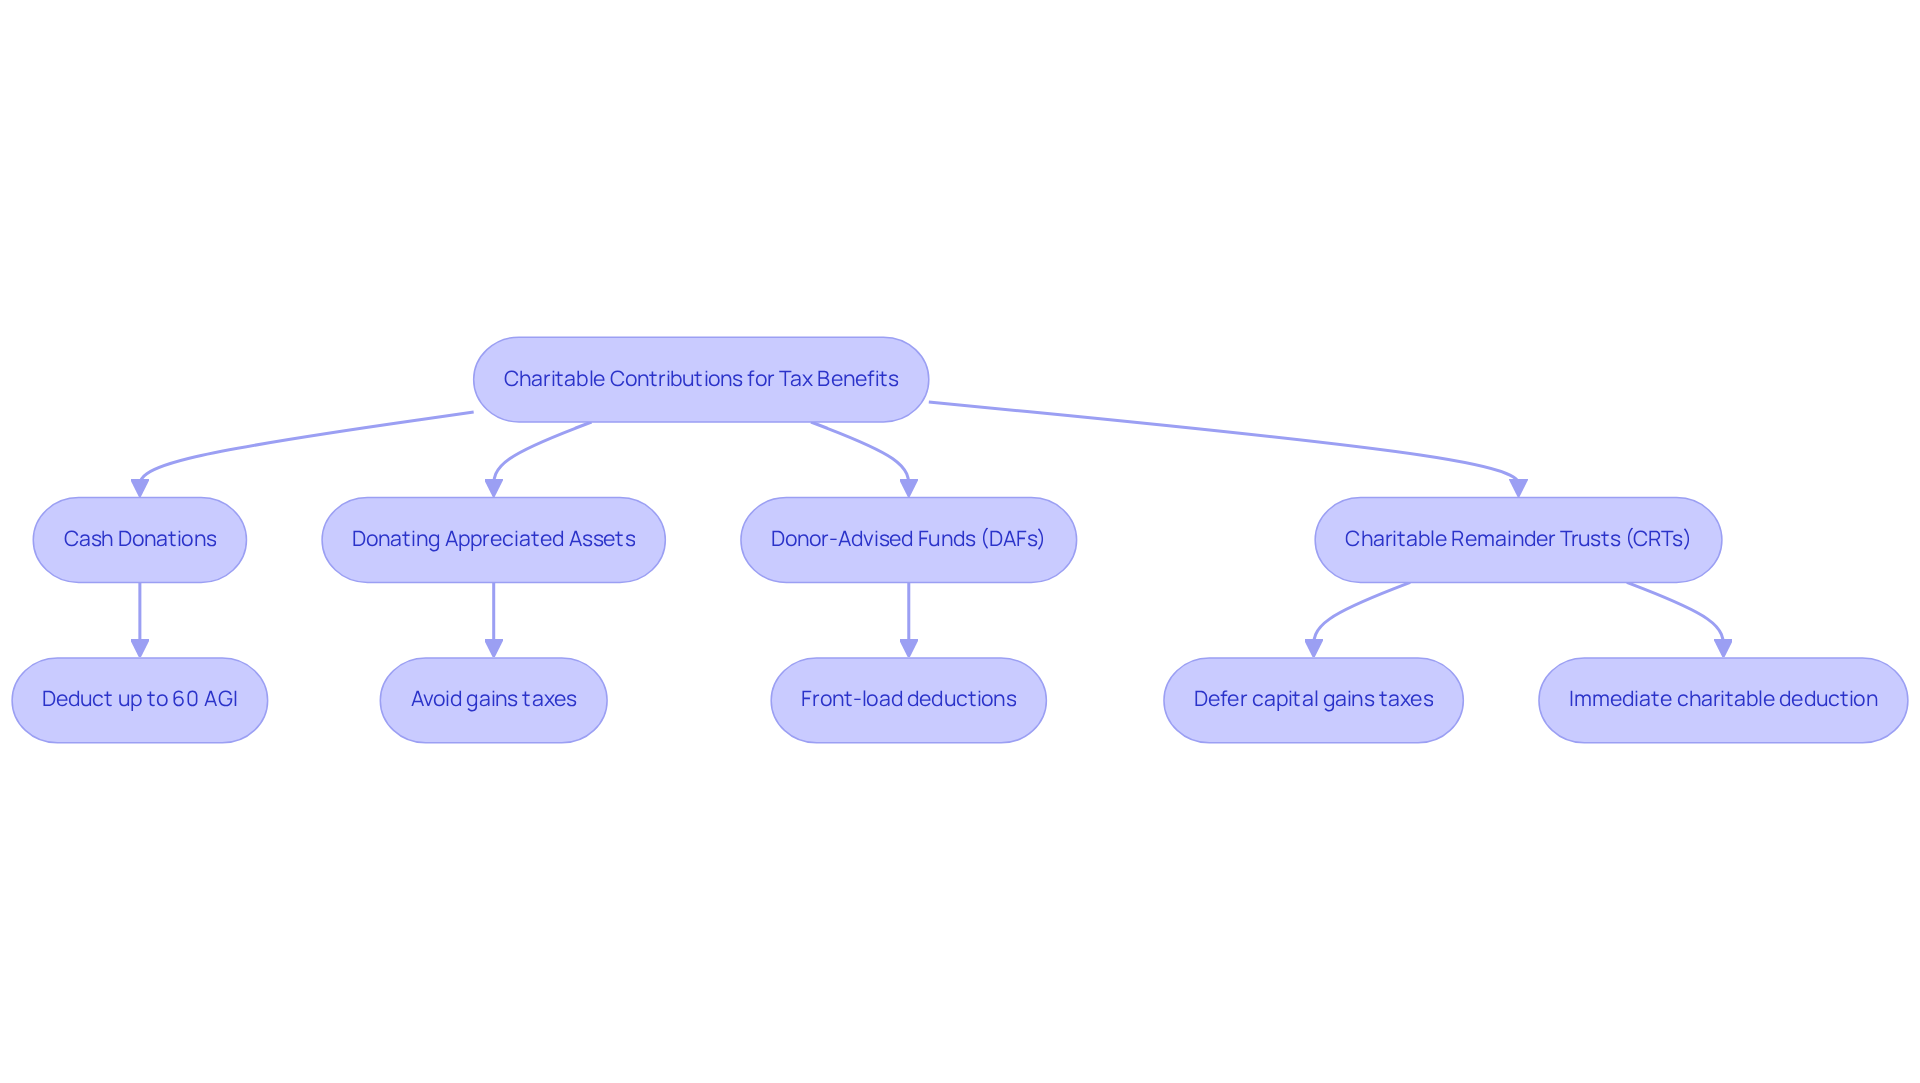
Charitable contributions can be a wonderful way for high-income individuals to not only support meaningful causes but also utilize tax loopholes for high-income earners to lower their taxable income. Imagine being able to make a difference while easing your tax burden! By donating to qualified charities, you can significantly reduce your tax liabilities. In 2025, taxpayers can deduct up to 60% of their adjusted gross income (AGI) for cash donations to public charities. This creates a fantastic incentive for giving back. However, starting in 2026, the deduction for top earners will be capped at 35%. It’s crucial to consider maximizing your contributions before this change takes effect.
Moreover, donating appreciated assets, like stocks or real estate, offers dual tax advantages. Not only do you receive a deduction based on the fair market value of the asset, but you also avoid gains taxes on the appreciation. For instance, if a couple has an AGI of $1 million, they could donate $50,000 in appreciated stock. This allows them to itemize their deduction while sidestepping a potential capital gains tax of 15% on the appreciation. This strategy not only amplifies their charitable impact but also .
High-income earners are increasingly turning to donor-advised funds (DAFs) to front-load their charitable deductions during high-income years, utilizing tax loopholes for high-income earners. This approach separates the tax event from the actual charitable disbursement, offering greater flexibility in how and when grants are distributed. Financial advisors often highlight this method as particularly beneficial for clients who anticipate fluctuating incomes or have strategic giving goals.
Additionally, charitable remainder trusts (CRTs) are becoming popular among wealthy individuals for their unique tax benefits. By donating appreciated assets into a CRT, clients can defer capital gains taxes, receive an income stream, and claim an immediate charitable deduction based on the remainder interest. This approach not only supports philanthropic efforts but also fits seamlessly into estate and retirement planning.
With the upcoming changes from the One Big Beautiful Bill Act (OBBBA) in 2026, it’s a good time for high-income individuals to reassess their charitable giving strategies, especially considering the potential tax loopholes for high-income earners. New limitations on deductions are on the horizon, so maximizing contributions before the end of 2025 can lead to significant tax benefits. By adopting a structured giving plan, families can effectively manage their taxable income while making a lasting impact on their communities. Remember, we’re here for you as you navigate this journey!
Opportunity Zones: Invest for Growth and Tax Benefits
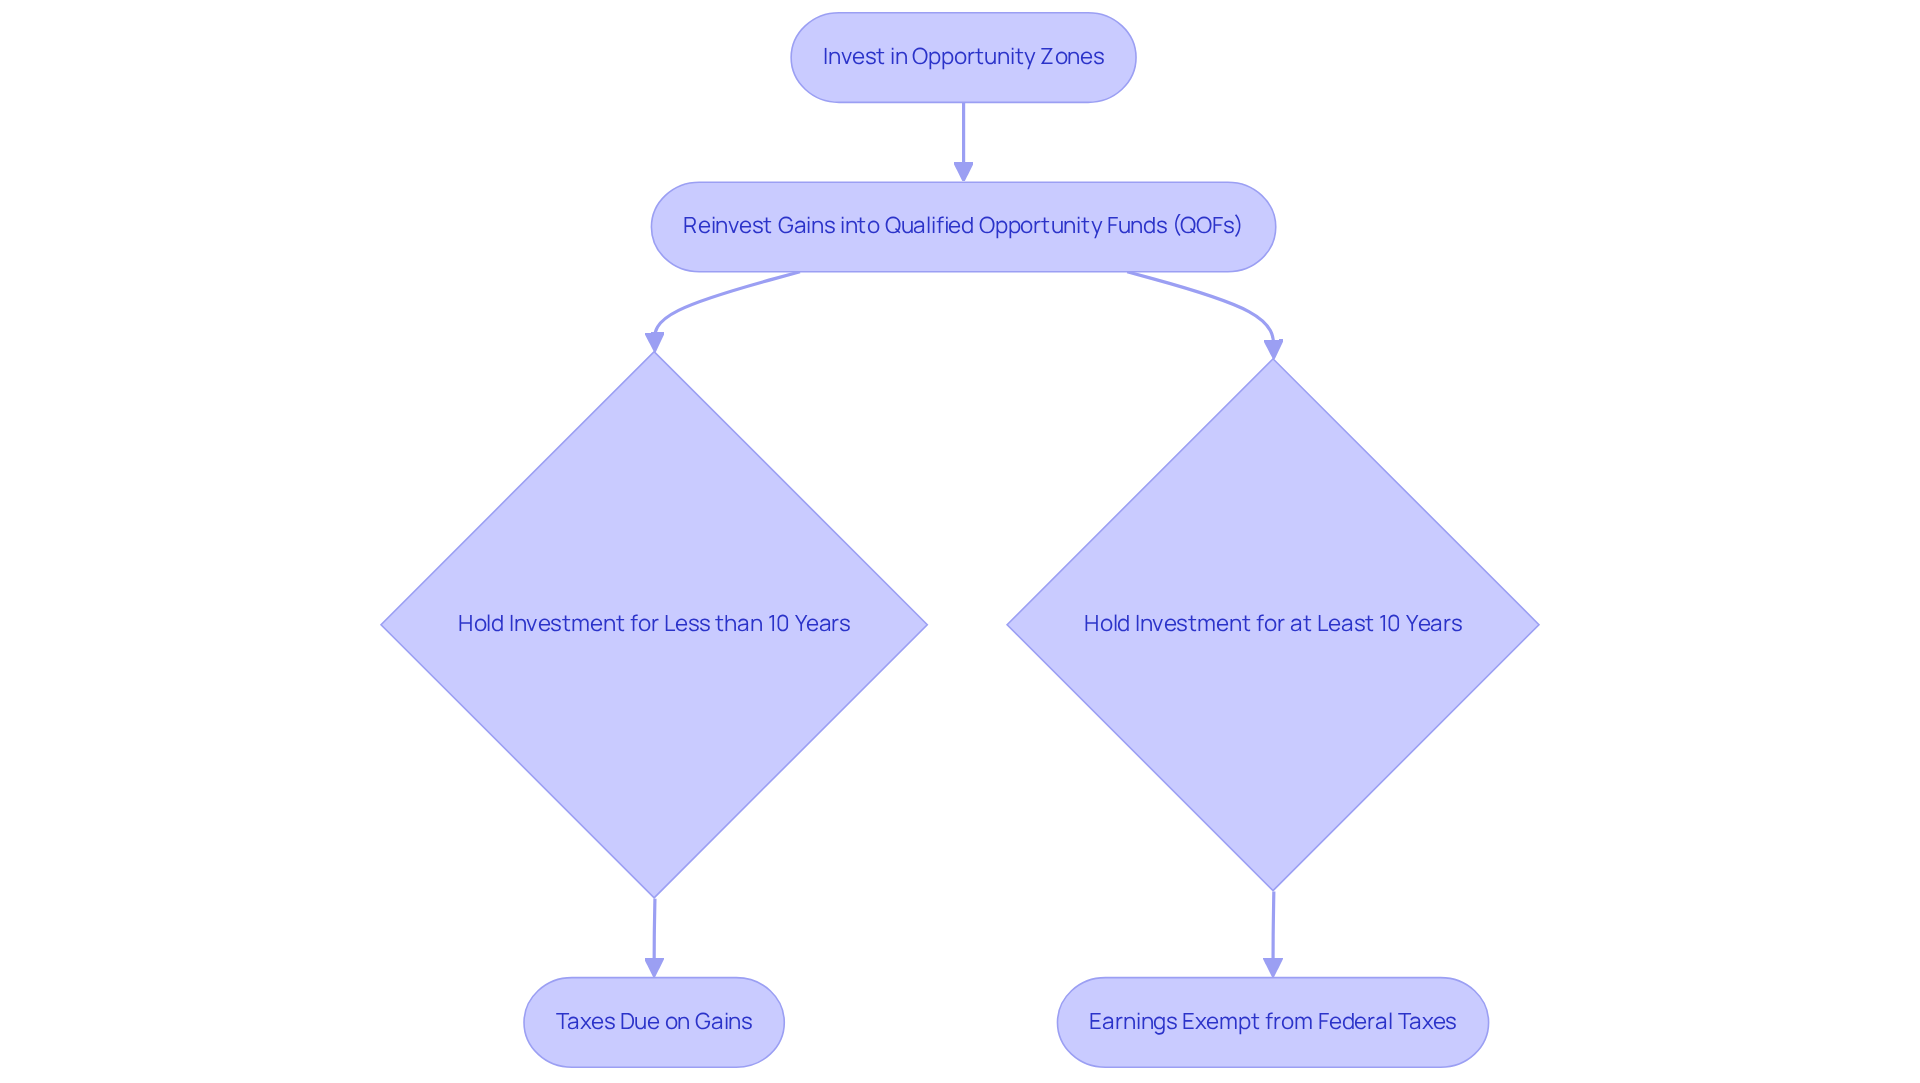
Investing in Opportunity Zones presents a unique chance for high-income individuals, like Allison and Brian, to postpone taxes on gains from investments in designated low-income areas. By reinvesting these gains into Qualified Opportunity Funds (QOFs), they can delay tax payments until they exit the investment or until December 31, 2026. And here’s the exciting part: if they hold onto their investment for at least ten years, any earnings generated are exempt from federal taxes. This offers a compelling reason to think long-term.
This approach not only supports community development but also enriches the investor’s portfolio with appealing tax benefits. Imagine cities like Erie, PA, successfully attracting over $100 million in private funding through Opportunity Zone investments, leading to new housing units and businesses. These examples beautifully illustrate how investing can help local economies thrive while also enhancing tax strategies.
Financial experts emphasize that utilizing QOFs can truly transform the financial landscape for investors eager to [maximize their tax savings](https://brightadvisers.com/?p=8880) while positively impacting economically distressed areas. By embracing professional tax planning, families like Allison and Brian can navigate these opportunities with confidence, securing their children’s future through education funding and paving the way for an earlier retirement—all while making the most of their financial resources.
Together, we can and find the best path forward for your family. Remember, we’re here for you, ready to support you in this journey toward financial well-being.
1031 Exchanges: Defer Capital Gains Taxes on Real Estate
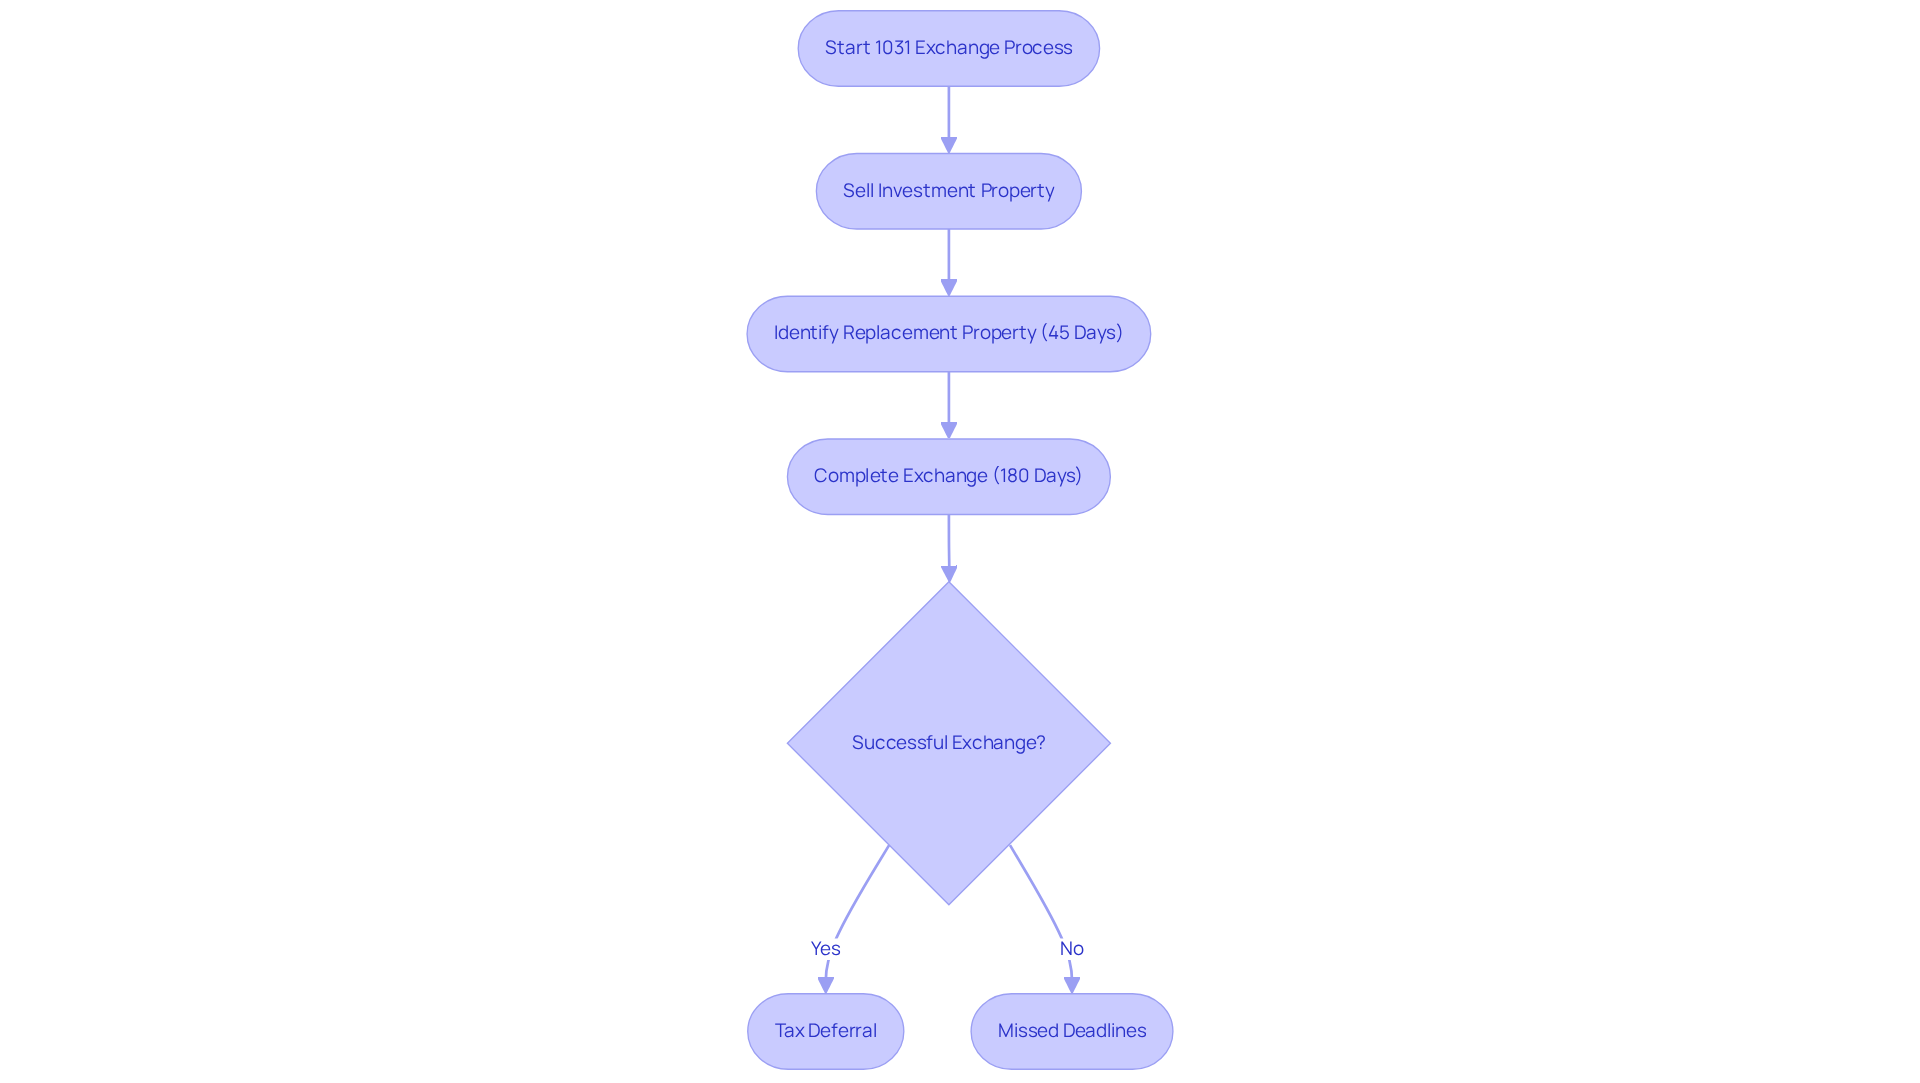
Imagine if you could sell your investment property without the immediate worry of taxes. A 1031 exchange allows real estate investors to postpone gains taxes when selling, as long as the proceeds are reinvested in a similar property. This strategy can be a game-changer for high-income individuals looking to grow their real estate assets while benefiting from tax loopholes for high-income earners. With the now at 20% for single filers earning over $492,300, the benefits of 1031 exchanges become even more crucial due to the existence of tax loopholes for high-income earners.
It’s important to understand the rules and timelines that come with 1031 exchanges. Investors need to identify a replacement property within 45 days and complete the exchange within 180 days to qualify for tax deferral. By following these guidelines, high-income earners can effectively manage their tax exposure and utilize tax loopholes for high-income earners while building wealth through real estate.
Consider the possibilities of postponing gains taxes through 1031 exchanges. Upgrading to larger properties, consolidating several assets into one, or diversifying investments across different markets can be effective strategies. For instance, trading an 8-unit apartment building for a 50-unit property can significantly boost cash flow and appreciation potential. These approaches not only protect against regional economic downturns but also help investors keep capital that might otherwise go to taxes.
As industry experts suggest, mastering the 1031 exchange can fast-track your journey to financial freedom. However, it’s essential to be mindful of potential pitfalls, like missing deadlines or mishandling funds, which could jeopardize the benefits of the exchange.
Together, we can navigate this journey and ensure you make the most of your investments. We’re here for you, ready to support you every step of the way.
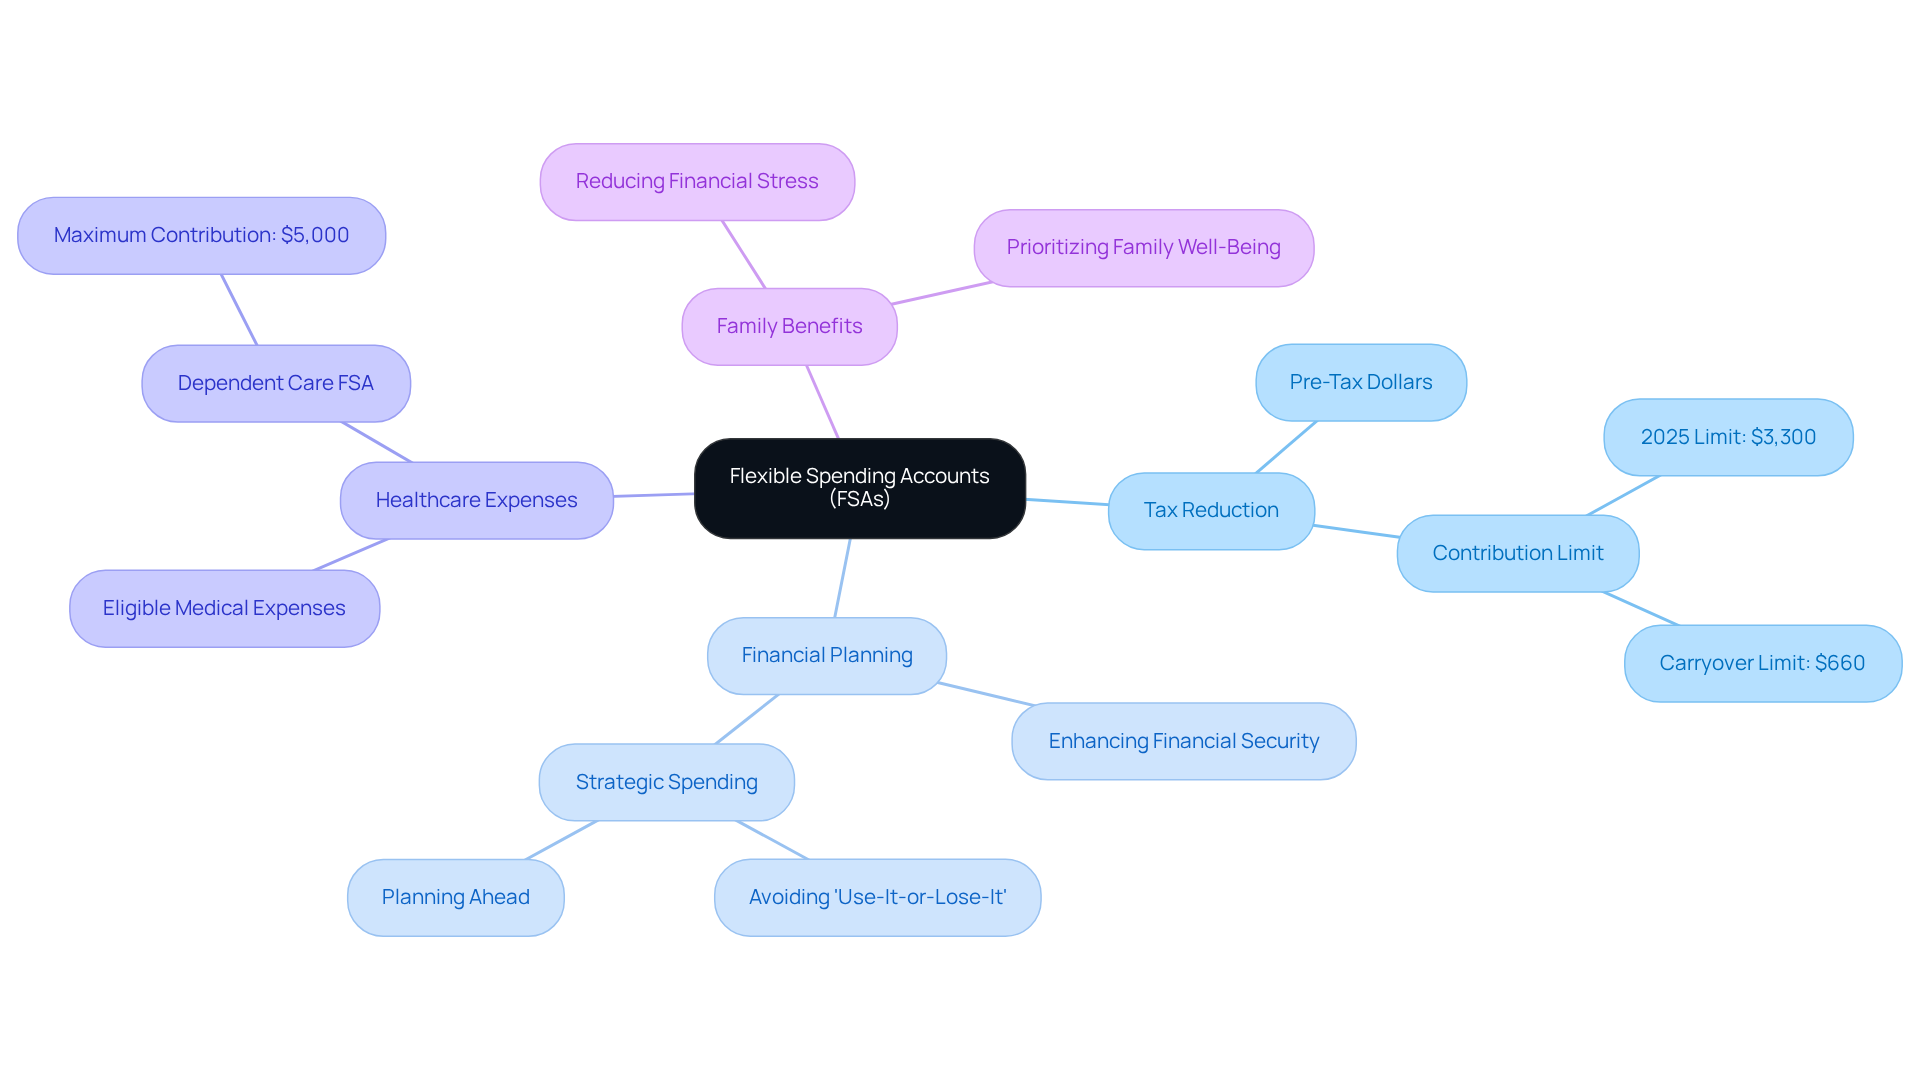
Flexible Spending Accounts: Reduce Taxable Income with Health Expenses
Flexible Spending Accounts (FSAs) can be a game-changer for families looking to ease financial burdens. By allowing employees to set aside pre-tax dollars for eligible healthcare expenses, FSAs can be seen as a means to exploit tax loopholes for high-income earners, thereby helping to reduce their taxable income. For 2025, the contribution limit for healthcare FSAs is $3,300.
Imagine if you could manage out-of-pocket medical costs more effectively. For families like Jay and Emma, this means less financial stress and more resources to focus on what truly matters. By utilizing an FSA, they can not only reduce expenses but also enhance their overall financial plan.
Incorporating FSAs into your financial strategy can lead to greater tax efficiency by utilizing tax loopholes for high-income earners while ensuring that your family’s healthcare needs are met. This approach contributes to long-term financial security and freedom, allowing you to prioritize your family’s well-being.
We’re here for you, ready to help you navigate this journey. Together, we can explore how FSAs can , making a positive impact on your family’s future.
Estate Planning Strategies: Minimize Taxes and Preserve Wealth
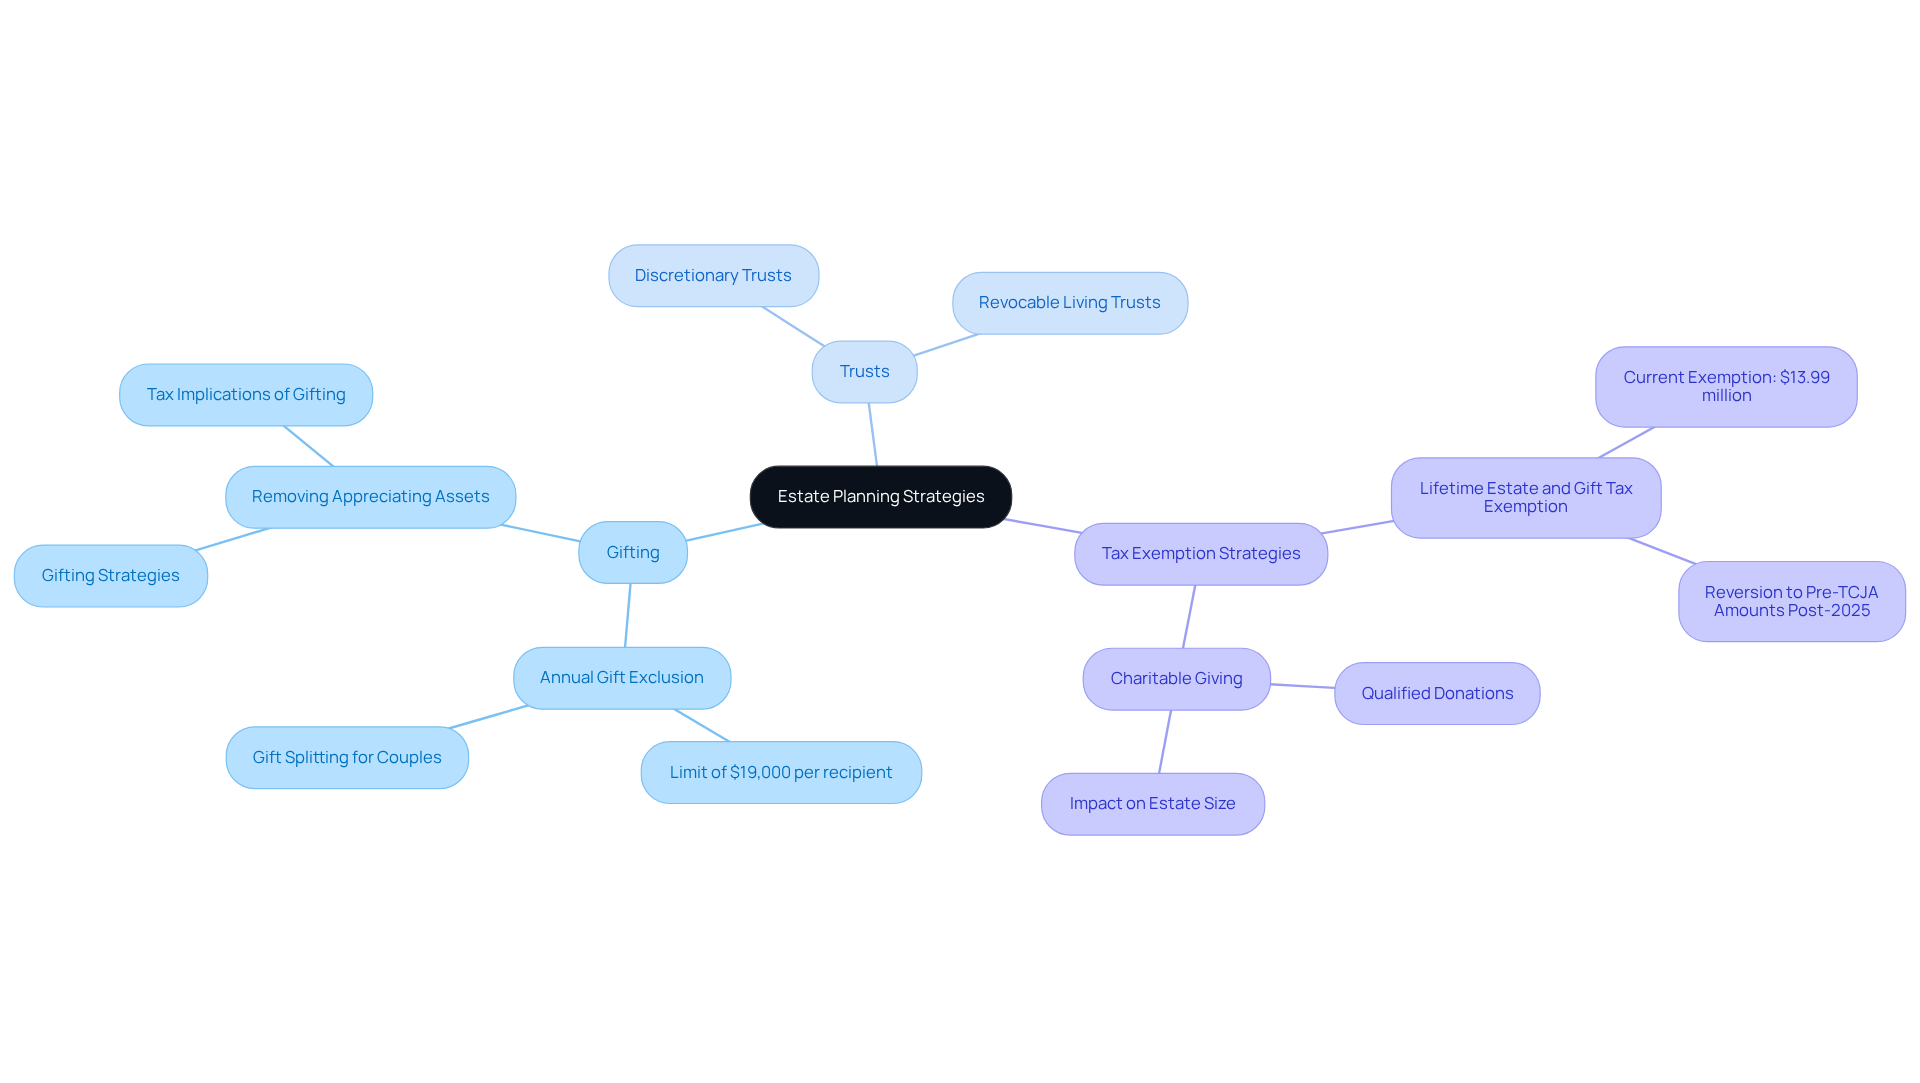
Estate arrangement approaches are essential for high-income individuals who want to protect their assets and ensure a secure future for their loved ones. Imagine if you could reduce levies while safeguarding your family’s financial legacy. Techniques like gifting, setting up discretionary and revocable living trusts, and utilizing the lifetime estate and gift tax exemption can significantly lower the taxable value of your estate. As of 2025, this exemption is $13.99 million, but it’s important to understand that it will revert to pre-TCJA amounts after 2025. This makes proactive planning all the more urgent.
Families can also take advantage of gifting strategies, such as the annual gift exclusion of $19,000 per recipient. This allows you to remove appreciating assets from your taxable estate, potentially saving millions in levies. Trusts provide flexibility and security, enabling you to manage your assets in a way that .
As estate planning expert Susan B. Geffen wisely notes, ‘Successful wealth transfer requires family coordination and understanding.’ This highlights the importance of coming together as a family to discuss these matters. Thomas Fridrich adds, ‘Giving is an important part of our society for many. It can provide us the opportunity to support causes we believe in and make a positive impact.’
By engaging in thoughtful planning, high-income earners can navigate the complexities of estate taxes and utilize tax loopholes for high-income earners to secure their financial legacies. Remember, we’re here for you, ready to help you consider the implications of state estate taxes and more. Together, we can navigate this journey and ensure your family’s future is bright.
Conclusion
Maximizing tax savings is essential for high-income earners, especially for families striving to secure their financial futures. Understanding the various tax loopholes available can truly make a difference in your financial journey. This article has explored a range of strategies, from utilizing 1031 exchanges and tax-loss harvesting to leveraging retirement accounts and health savings accounts. Each of these methods not only helps minimize tax liabilities but also aligns with your long-term goals of building and preserving wealth for your loved ones.
Imagine if you could navigate the complexities of tax regulations with ease. Key insights discussed include:
- The importance of proactive tax planning
- The benefits of charitable contributions that not only reduce your tax burden but also support your community
- The strategic use of estate planning to safeguard your assets for future generations
By implementing these tailored approaches, you can feel confident in your ability to maximize your savings potential while ensuring compliance.
Ultimately, the journey toward financial well-being requires a comprehensive understanding of available tax strategies and a commitment to informed decision-making. We encourage high-income earners like you to consult with financial advisors who can help tailor your tax planning strategies effectively. By taking action now, you can secure your family’s financial future, uphold your values, and create lasting legacies. Remember, together, we can navigate this journey.
Frequently Asked Questions
What services does Bright Advisers offer for high-income earners?
Bright Advisers provides tailored tax planning strategies, comprehensive financial planning, risk management, and legacy planning to help high-income families maximize savings while ensuring compliance with tax regulations.
How does Bright Advisers approach tax planning for families?
They take the time to understand each family’s unique financial situation and create plans that aim to reduce tax obligations while aligning with long-term financial goals and incorporating family values.
What is depreciation recapture and why is it important for high-income earners?
Depreciation recapture occurs when you sell a depreciated property for more than its original purchase price, leading to potential tax liabilities that can be as high as 25%. Understanding this concept is crucial for high-income earners to manage their tax obligations effectively.
What is a 1031 exchange and how can it benefit high-income earners?
A 1031 exchange allows property owners to defer both gains and depreciation recapture taxes by reinvesting the sale proceeds into a similar asset, preserving capital and supporting tax-deferred growth.
Can you provide an example of how tax planning helped a high-income family?
Allison and Brian, a high-income couple, improved their financial situation by utilizing effective tax planning strategies, including 1031 exchanges, which allowed them to defer significant tax obligations and secure funds for future investments and their children’s education.
What is tax-loss harvesting and how does it work?
Tax-loss harvesting involves selling underperforming investments to offset gains from better-performing ones, thereby lowering taxable income. This strategy can be particularly beneficial for high-income earners.
What are the potential benefits of tax-loss harvesting during market fluctuations?
During volatile market periods, tax-loss harvesting can create more opportunities to realize losses, potentially boosting after-tax returns for investors.
What should investors be aware of when implementing tax-loss harvesting?
Investors should consider the ‘wash sale’ rule, which disallows claiming a loss if a similar security is purchased within 30 days, and ensure that tax-loss harvesting is completed by December 31 of the tax year.
How can high-income earners further refine their tax strategies?
High-income earners can use losses to offset gains from depreciation recapture, hold onto property until death for a step-up in basis, and engage in proactive tax planning to navigate tax loopholes effectively.
List of Sources
- Bright Advisers: Tailored Tax Planning Strategies for High-Income Earners
- High Income Tax Planning: Strategies for the Wealthy (https://bettehochberger.com/quickies/high-income-tax-planning-strategies-for-the-wealthy-8393)
- High-income tax planning: 11 Clever Strategies (https://brillantlaw.com/high-income-tax-planning)
- 11 Ways for High Earners to Reduce Taxable Income [2025] (https://blog.cmp.cpa/reduce-taxable-income-high-earners)
- Tax Planning Strategies for High-Income Earners (https://farther.com/resources/foundations/tax-planning-strategies-for-high-income-earners)
- Beyond the Basics: Tax strategies for High Income Earners (https://modernfamilyfinance.com/beyond-the-basics-tax-strategies-for-high-income-earners)
- Depreciation Recapture: A Key Tax Loophole for High-Income Earners
- Depreciation recapture tax: Overview and FAQs (https://tax.thomsonreuters.com/en/glossary/depreciation-recapture-tax)
- Tax Strategies for High Income Earners | White Coat Investor (https://whitecoatinvestor.com/pay-less-taxes)
- Understanding Depreciation Recapture on Real Estate Sales (https://troutcpa.com/blog/understanding-depreciation-recapture-on-real-estate-sales)
- A Guide to Depreciation Recapture for Real Estate (https://eisneramper.com/insights/real-estate/depreciation-recapture-real-estate-0124)
- How Does Depreciation Recapture Work for Investors? (https://origininvestments.com/how-does-depreciation-recapture-work-for-investors)
- Tax-Loss Harvesting: Offset Gains and Reduce Taxable Income
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Tax-loss harvesting | Capital gains and lower taxes | Fidelity (https://fidelity.com/viewpoints/personal-finance/tax-loss-harvesting)
- Tax-Loss Harvesting: What It Is, How It Works – NerdWallet (https://nerdwallet.com/taxes/learn/tax-loss-harvesting)
- T. Rowe Price Personal Investor – How tax loss harvesting can help improve your investment returns (https://troweprice.com/personal-investing/resources/insights/how-improve-your-investment-returns-through-tax-loss-harvesting.html)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Retirement Accounts: Maximize Contributions for Tax Benefits
- 401(k) Contribution Limits in 2025 | Guideline (https://guideline.com/education/articles/how-much-can-you-contribute-to-a-401-k-in-2025)
- 401(k) Catch-Up Contributions: Final SECURE 2.0 Rules for Employers (https://employeefiduciary.com/blog/401k-catch-up-contributions)
- 401(k) Contribution Limits for Highly Compensated Employees in 2025 (https://epwealth.com/blog/401k-contribution-limits-for-highly-compensated-employees)
- 401(k) Contribution Limits in 2025 – NerdWallet (https://nerdwallet.com/article/investing/401k-contribution-limits)
- There’s still time for ‘super catch-up’ 401(k) contributions for 2025 — here’s who benefits (https://cnbc.com/2025/09/10/super-catch-up-401k-contributions-2025.html)
- Health Savings Accounts: Tax-Advantaged Savings for Medical Expenses
- Top 8 Reasons To Use Health Savings Accounts (HSAs) (https://pebnd.com/top-8-reasons-to-use-health-savings-accounts)
- IRS announces 2025 contribution and benefit limits | CWRU Newsroom | Case Western Reserve University (https://case.edu/news/irs-announces-2025-contribution-and-benefit-limits)
- HSA contribution limits 2025 and 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- Health Savings Accounts: A Triple Tax Advantage | Prosperity Planning, Inc. (https://prosperityplanninginc.com/blogs/health-savings-accounts-a-triple-tax-advantage)
- Health savings accounts and their triple tax benefits (https://natptax.com/news-insights/blog/health-savings-accounts-and-their-triple-tax-benefits?srsltid=AfmBOoo5xC4nF1OSJ1FtPGBt4rgrjHfziqt0pZNshrL7cQgqrQXkwzHM)
- Charitable Contributions: Reduce Taxable Income While Giving Back
- How High-Income Earners Build Giving Into Their Tax Strategy — and How You Can, Too (https://finance.yahoo.com/news/high-income-earners-build-giving-131608071.html)
- Beyond Cash: The Benefits of Donating Appreciated Assets (https://soundmindinvesting.com/articles/beyond-cash-the-benefits-of-donating-appreciated-assets)
- Last Chance to Maximize Your Charitable Tax Deduction Benefits Before New 2026 Limitations (https://merceradvisors.com/insights/taxes/last-chance-to-maximize-your-charitable-tax-deduction-benefits-before-new-2026-limitations)
- OBBBA Insight: Charitable Giving for High-Income Individuals – Why Give to Charity in 2025, Not 2026 (https://deandorton.com/obbba-insight-charitable-giving-for-high-income-individuals)
- Why top earners should make donations before 2026 (https://cnbc.com/2025/10/23/why-top-earners-should-make-donations-before-2026.html)
- Opportunity Zones: Invest for Growth and Tax Benefits
- Tax Benefits of Investing in Qualified Opportunity Zones (https://taxplaniq.com/blog/tax-benefits-of-investing-in-qualified-opportunity-zones)
- USA Opportunity Zones (https://statsamerica.org/opportunity)
- Exploring Opportunity Zones: New Data on the Positive Impact of OZs (https://forbes.com/sites/sorensonimpact/2023/05/22/exploring-opportunity-zones-exciting-new-data-on-the-positive-impact-of-ozs-across-the-nation)
- Opportunity Zone Regime Permanently Extended With New Benefits, Limitations, and Requirements, With a New Rural Focus (https://saul.com/insights/alert/opportunity-zone-regime-permanently-extended-new-benefits-limitations-and)
- Guide to the New Opportunity Zones: A Primer for Cities – Local Infrastructure Hub (https://localinfrastructure.org/resources/guide-to-the-new-opportunity-zones-a-primer-for-cities)
- 1031 Exchanges: Defer Capital Gains Taxes on Real Estate
- Defer Capital Gains Taxes with a 1031 Exchange – Asset Preservation, Inc. (https://apiexchange.com/defer-capital-gains-taxes-with-1031-exchange)
- Market Dynamics: Unveiling the Annual Statistics of 1031 Exchanges (https://1031specialists.com/blog-posts/market-dynamics-unveiling-the-annual-statistics-of-1031-exchanges)
- How Smart Investors Use 1031 Exchange To Build Multi-Million Dollar Portfolios | Primior Group (https://primior.com/how-smart-investors-use-1031-exchange-to-build-multi-million-dollar-portfolios)
- 20 Famous Real Estate Investing Quotes (https://realtymogul.com/knowledge-center/article/20-famous-real-estate-investing-quotes)
- Why Section 1031 Like-Kind Exchanges Matter More Than Ever in 2025 (https://1031corp.com/exchanging-thoughts-blog/why-section-1031-like-kind-exchanges-matter-more-than-ever-in-2025)
- Flexible Spending Accounts: Reduce Taxable Income with Health Expenses
- 7 Smart Ways to Maximize Your Flexible Spending Account (FSA) Before It’s Too Late (https://annuityexpertadvice.com/flexible-spending-account-fsa)
- Flexible Spending Account Dollar Limits for 2025 (https://lcwlegal.com/news/flexible-spending-account-dollar-limits-for-2025)
- IRS: Healthcare FSA reminder: Employees can contribute up to $3,300 in 2025; must elect every year | Internal Revenue Service (https://irs.gov/newsroom/irs-healthcare-fsa-reminder-employees-can-contribute-up-to-3300-in-2025-must-elect-every-year)
- Estate Planning Strategies: Minimize Taxes and Preserve Wealth
- How Estate and Gift Taxes Can Impact Your Financial Plan (https://oakesonsteiner.com/insights/blog/how-estate-and-gift-taxes-can-impact-your-financial-plan)
- Time is Running Out: How the 2025 Estate Tax Exemption Sunset Could Cost Your Family Millions | Susan B. Geffen (https://susanbgeffenlaw.com/blog/time-is-running-out-how-the-2025-estate-tax-exemption-sunset-could-cost-your-family-millions)
- Estate Planning Advice for Advisors – eMoney Heart of Advice Podcast (https://emoneyadvisor.com/blog/podcast-episode-7-spotlight-on-estate-planning-with-christina-lynn)
- Wealth Protection: Financial Experts Share Their Tips (https://kubera.com/blog/wealth-protection)
- Monthly Technical Newsletter – NAEPC (https://naepc.org/events/newsletter/7/2010)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading