

Key Highlights
- High-income W-2 employees should maximise 401(k) contributions, with a limit of $24,500 in 2026, to reduce tax burdens.
- Employer matching contributions can enhance retirement savings without additional costs.
- A Backdoor Roth IRA allows high earners to secure tax-free growth by making non-deductible contributions to a traditional IRA and converting it to a Roth IRA.
- Health Savings Accounts (HSAs) enable families to set aside pre-tax dollars for medical expenses, with increased contribution limits in 2026.
- Charitable donations can be strategically timed to maximise tax deductions, using Donor-Advised Funds (DAFs) to group multiple years of donations.
- Investing in tax-efficient vehicles like index funds, ETFs, and municipal bonds can lower capital gains distributions and enhance after-tax returns.
- Nonqualified Deferred Compensation (NQDC) plans allow high earners to postpone earnings, potentially lowering current tax liabilities.
- Families can utilise the Child and Dependent Care Tax Credit (CDCTC) to claim a percentage of qualifying childcare expenses, with limits of $3,000 for one child or $6,000 for two or more in 2026.
- Tax-loss harvesting can offset gains from investments, reducing overall tax liability, while adhering to IRS regulations.
- Engaging with a tax professional can help families navigate complex financial situations and avoid common tax planning mistakes.
Introduction
Imagine feeling overwhelmed by tax planning, where even a small mistake could impact your family’s financial future. Let’s explore ten common tax planning mistakes many families face and how you can avoid them to build a more secure financial future together. As families work hard to grow their wealth and reduce tax burdens, it’s crucial to ask: what strategies can help you keep more of what you earn? Together, we’ll uncover practical tax planning techniques that can boost your financial well-being and protect your family’s future.
Maximize Pre-Tax Retirement Contributions
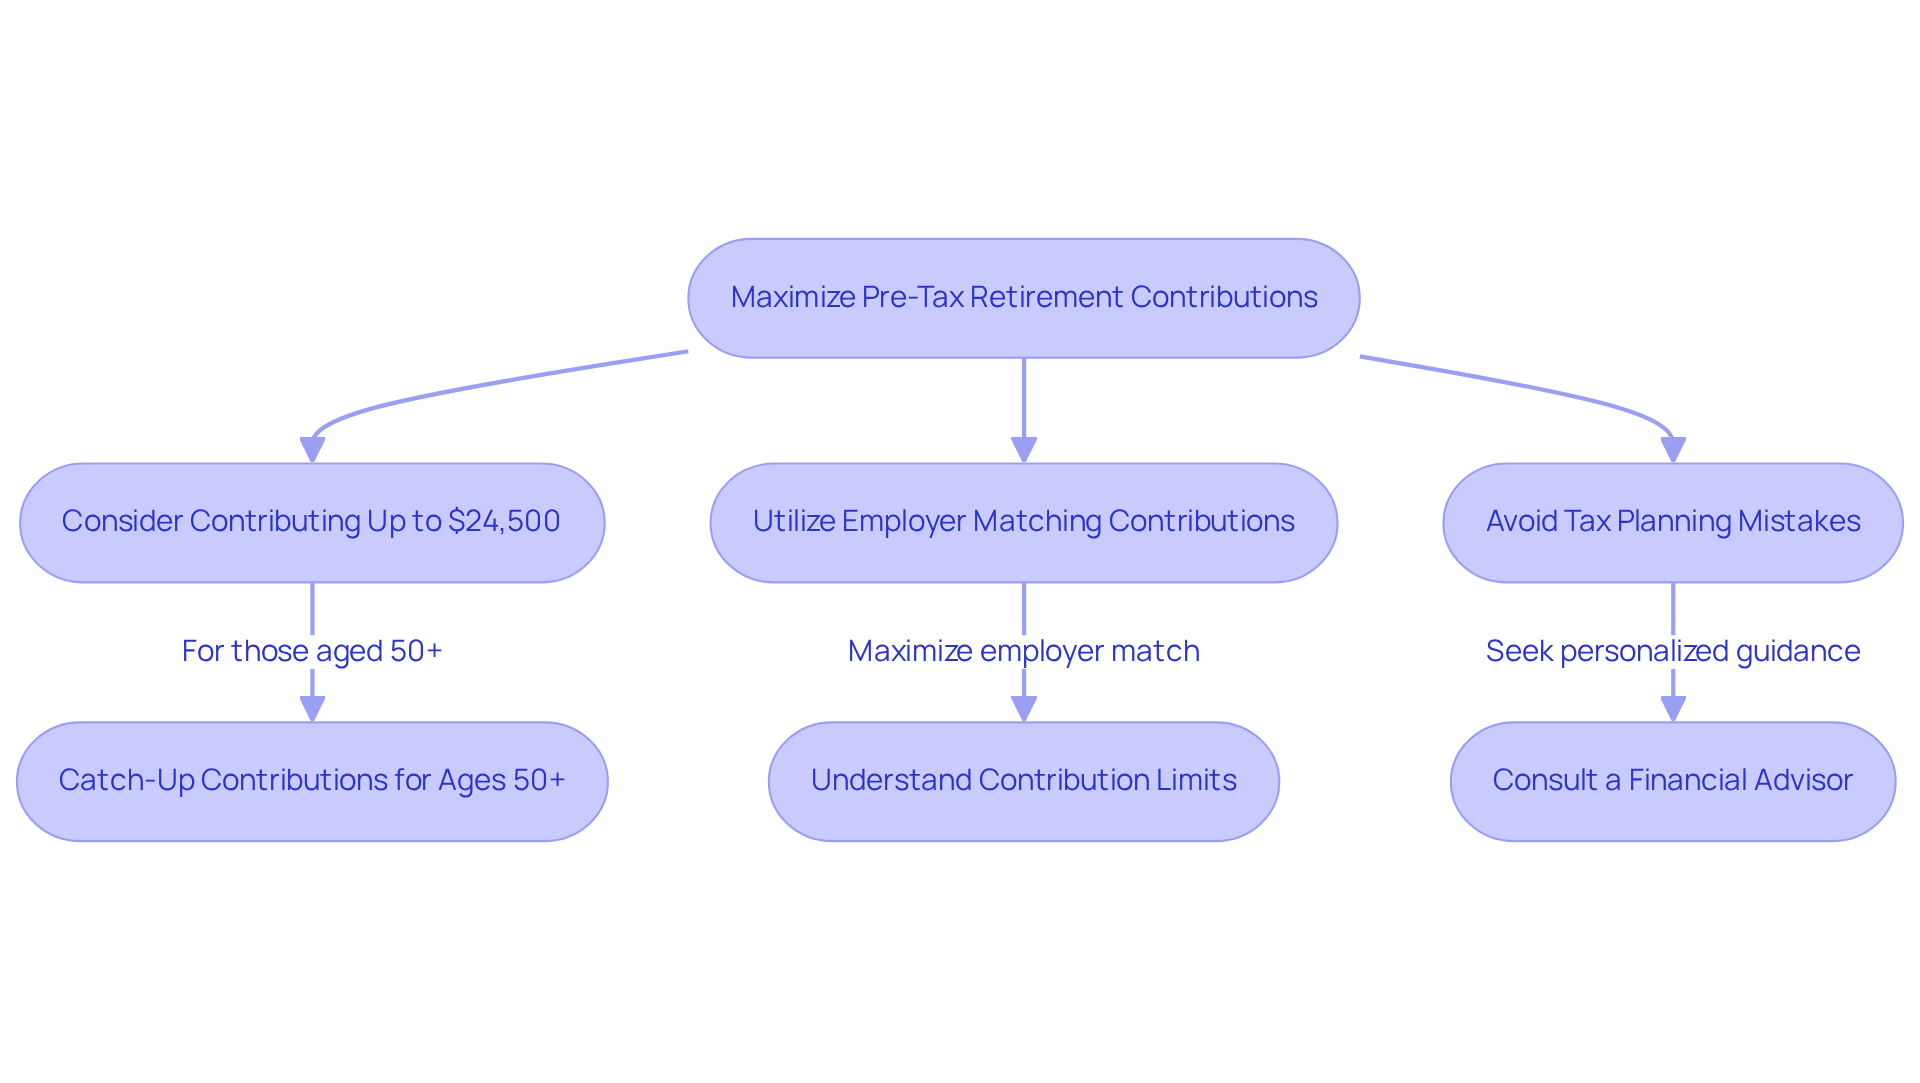
Imagine feeling secure about your family’s future while navigating the challenges of daily life. If you’re a high-income W-2 employee, it’s important to avoid tax planning mistakes for high income W-2 employees by considering contributing the maximum to your 401(k) to help secure your family’s future.
In 2026, you can contribute up to $24,500 to your 401(k), helping to ease the burden of taxes and secure your family’s future. Don’t forget about employer matching contributions; they can enhance your retirement savings without any extra cost.
By taking advantage of this strategy, you can not only reduce your tax burden but also avoid tax planning mistakes for high income W-2 employees, paving the way for a more secure retirement for your family. Together, we can navigate this journey toward financial stability.
Utilize a Backdoor Roth IRA Conversion
Imagine a way to secure your family’s financial future, even if you earn too much for a traditional Roth IRA. If you’re a high earner, you might feel stuck when it comes to retirement savings. But there’s a way to work around those limits with a Backdoor Roth IRA.
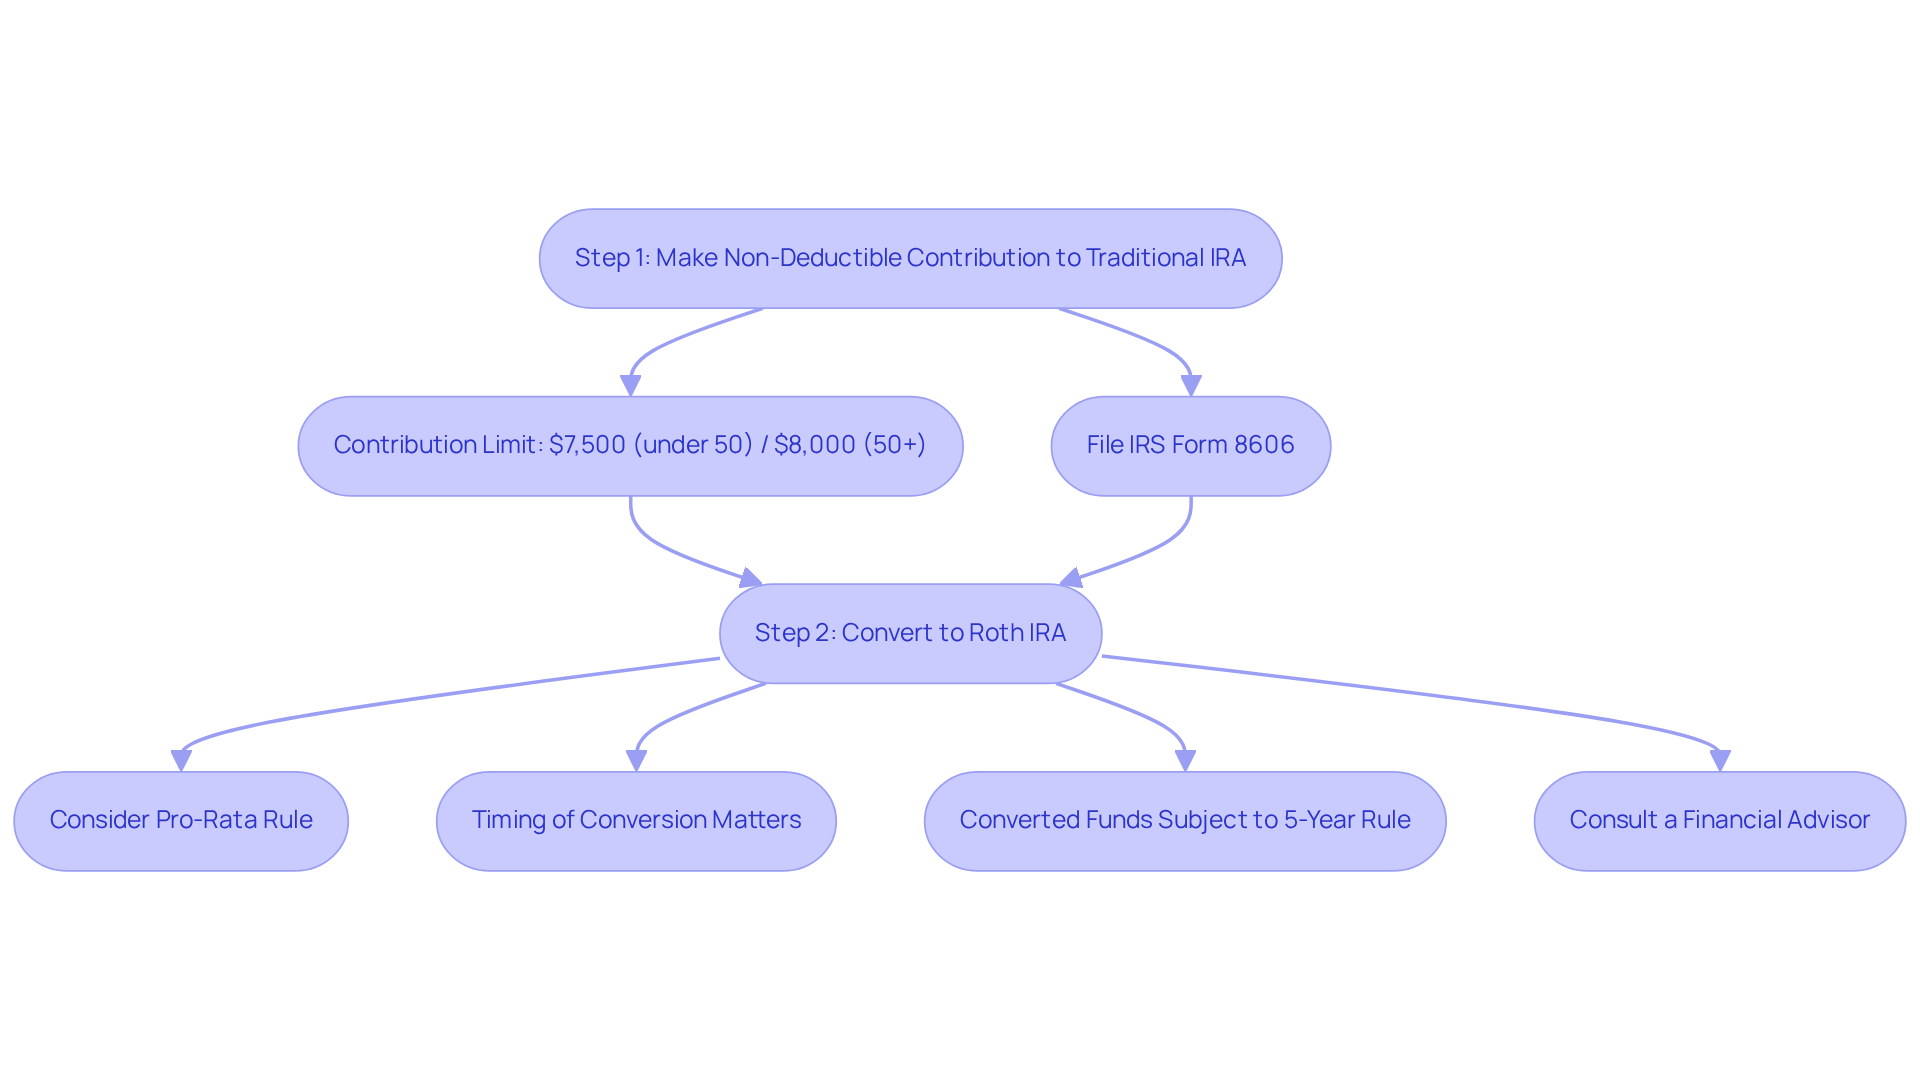
This simple two-step process can help your family enjoy tax-free growth and withdrawals when you retire, giving you peace of mind about your savings. Start by making a non-deductible contribution to a traditional IRA, which for 2025 is capped at $7,500 for individuals under 50 and $8,000 for those aged 50 or older. After that, you can convert your traditional IRA to a Roth IRA. Don’t forget to file IRS Form 8606 to keep track of your contributions and ensure everything is in order.
The Backdoor Roth IRA is especially helpful for families whose income exceeds the limits for direct Roth IRA contributions, which are set at $153,000 for single filers and $242,000 for married couples in 2026. By using this strategy, your family can secure tax-free growth on your investments, as Roth IRAs don’t require minimum distributions during your lifetime.
However, navigating the tax implications and avoiding tax planning mistakes for high income W-2 employees can feel overwhelming, especially when trying to secure your family’s financial future. It’s crucial to be aware of the pro-rata rule, which requires that conversions include a proportional mix of pre-tax and after-tax funds across all IRAs. If you have existing pre-tax balances in traditional IRAs, this can complicate the conversion process. For example, if you have a $50,000 pre-tax IRA and make a $7,500 non-deductible contribution, approximately 86.9% of the conversion would be taxable. Understanding these complexities can help you avoid tax planning mistakes for high income W-2 employees and make informed decisions that protect your family’s wealth.
Families should also consider the timing of the conversion; executing it quickly after the contribution can help avoid any taxable gains. If the value of investments in the traditional IRA increases before conversion, taxes will be owed on those gains. Consulting a money advisor can offer customized insights into whether a Backdoor Roth IRA fits with your household’s long-term monetary objectives. Bright Advisers provides extensive planning services through Lifeworks Advisors, a registered investment adviser, ensuring compliance and transparency. Moreover, households interested in customized monetary strategies are encouraged to join our current client waitlist for upcoming opportunities. With the right guidance, you can confidently navigate these strategies and ensure a brighter future for your loved ones.
Fund a Health Savings Account (HSA)
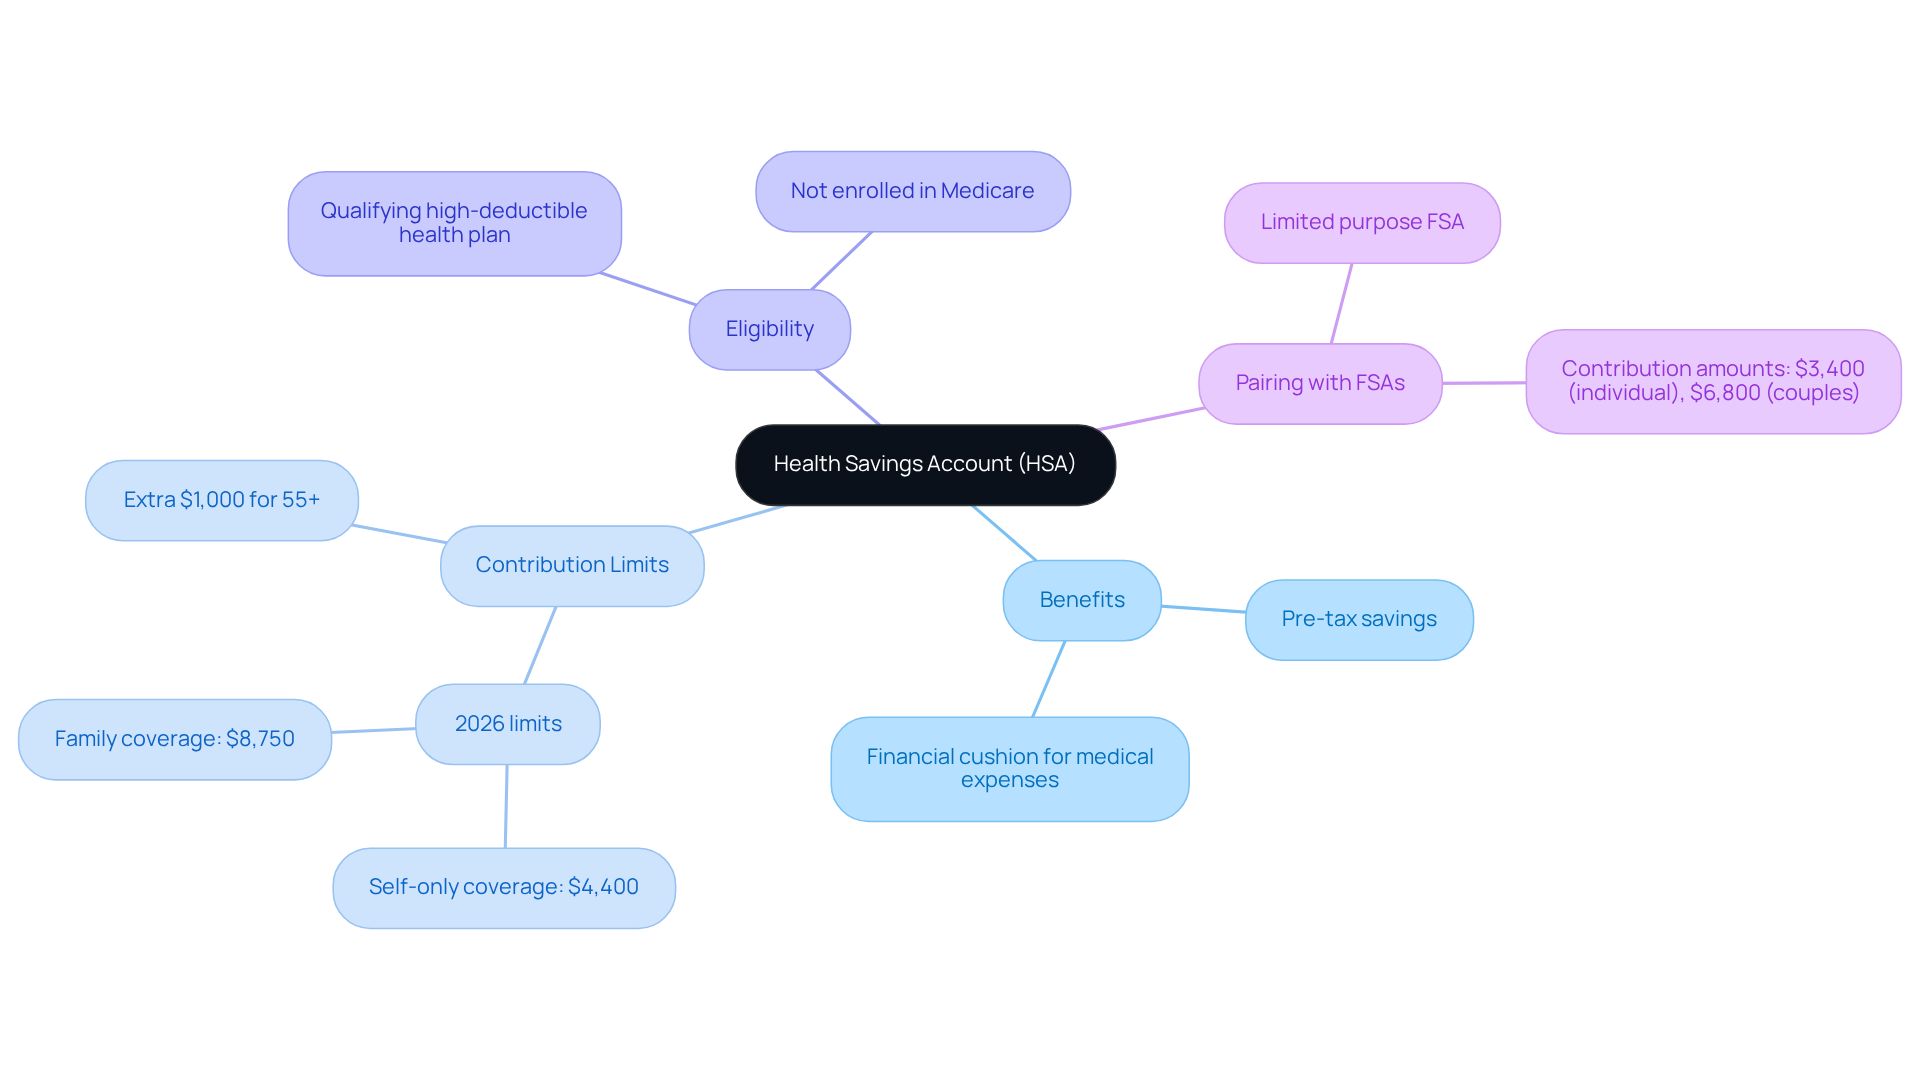
Imagine having a financial cushion for those unexpected medical expenses that can catch any family off guard. Contributing to a Health Savings Account (HSA) can help you set aside pre-tax dollars for qualified medical expenses, making it a valuable tool for your family’s financial health.
In 2026, you can take advantage of increased contribution limits, allowing you to allocate more resources for potential medical expenses. This means you can feel more prepared for those unexpected healthcare costs that life throws your way. Plus, if you’re 55 or older, you can contribute an extra $1,000 to your HSA, giving you even more flexibility. Just remember, to contribute to an HSA, you need to be enrolled in a qualifying high-deductible health plan and not in Medicare.
Families can also pair HSAs with limited purpose health care Flexible Spending Accounts (FSAs), which can cover specific expenses like vision or dental care. In 2026, you can contribute up to $3,400 to a limited purpose FSA, or $6,800 for couples, alongside your HSA contributions. This combination can enhance your overall strategy for managing healthcare costs.
Keeping an eye on your HSA contributions throughout the year can help you avoid any surprises, ensuring you stay within the limits and make the most of your savings. Bright Advisers is here to support you in this process, offering a transparent, all-inclusive fee structure with no hidden fees or commissions. Together, we can navigate this journey toward effective wealth management solutions.
Strategically Utilize Charitable Donations
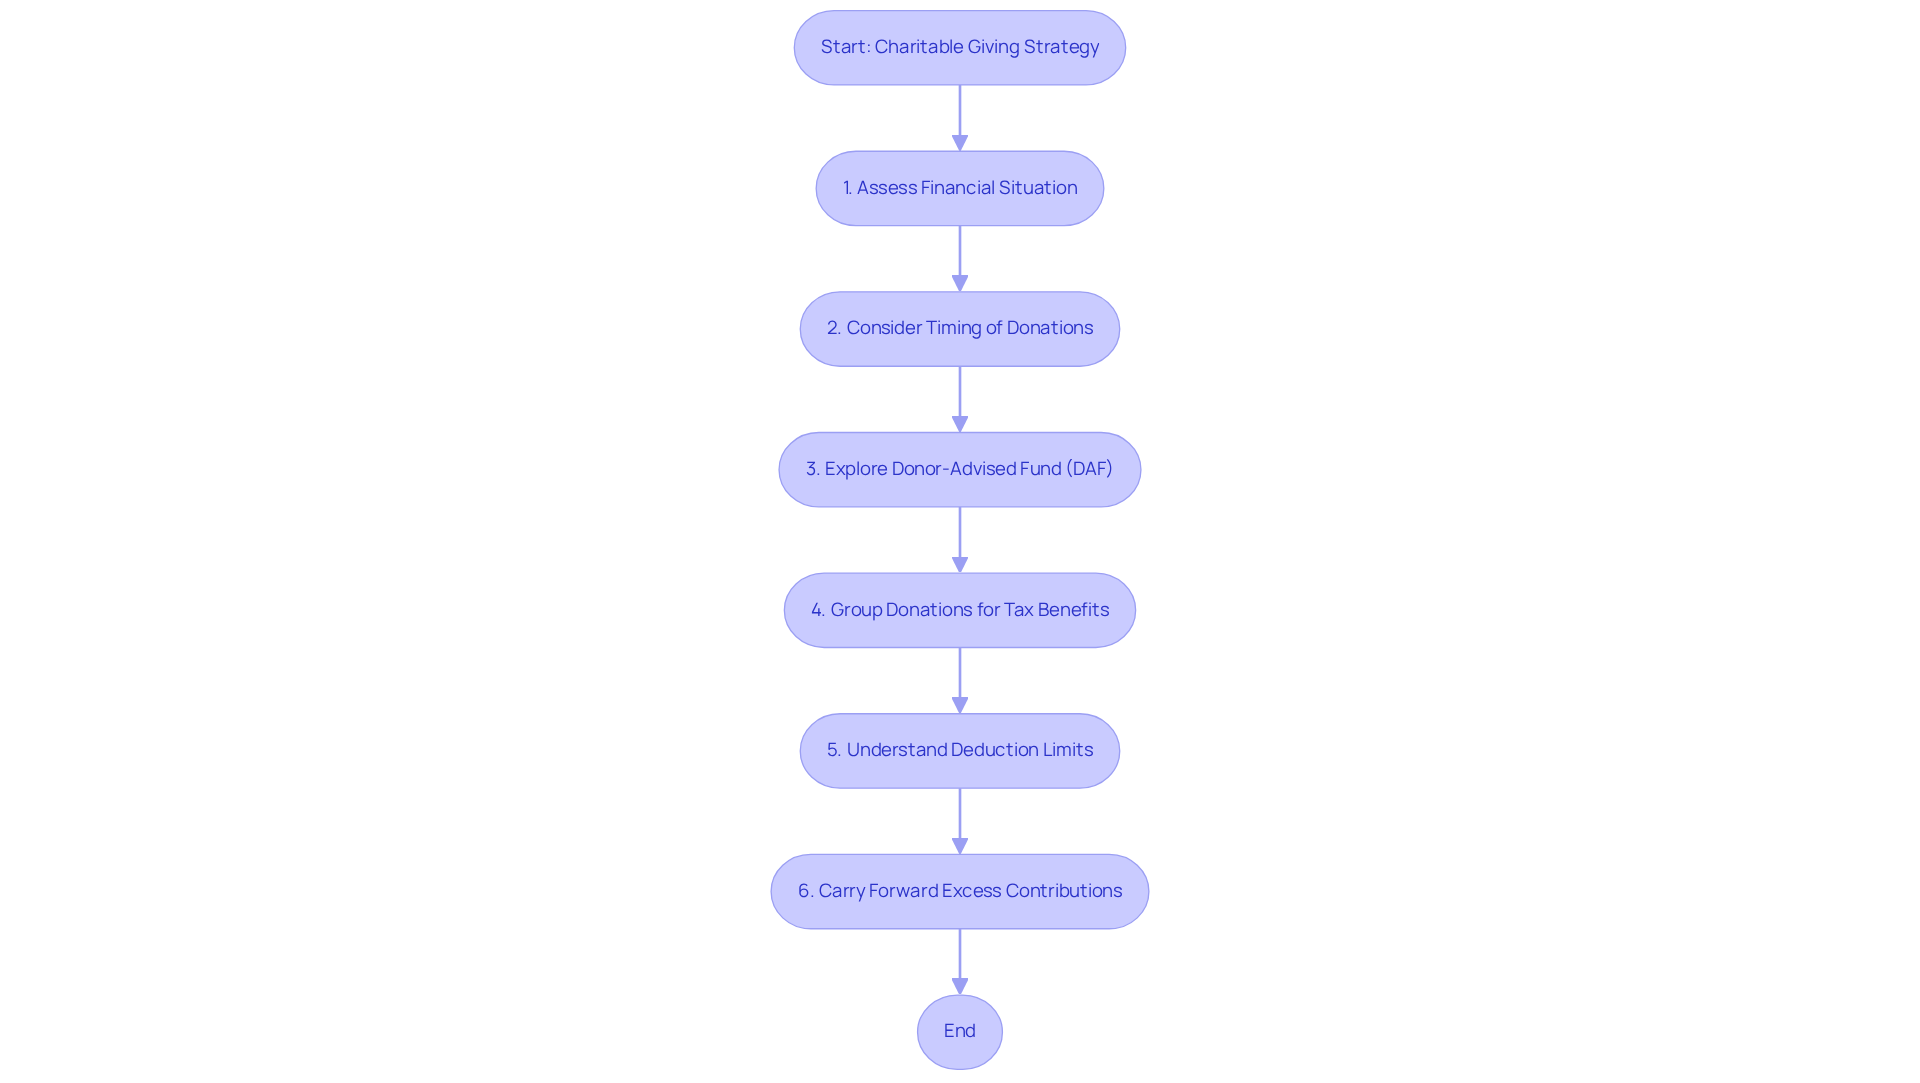
Imagine feeling empowered to make a difference while also securing your family’s financial future through smart charitable giving. High-income earners can avoid tax planning mistakes for high income W2 employees by strategically timing their charitable donations to enhance tax deductions. A Donor-Advised Fund (DAF) lets families group multiple years of donations into one tax year, helping them surpass the standard deduction limit. This approach not only amplifies charitable impact but also provides a larger tax deduction in the year of contribution. Did you know that cash donations can be deducted up to 60% of your adjusted gross income (AGI)? Plus, contributing appreciated assets directly to a DAF can help you avoid capital gains taxes while allowing you to deduct the asset’s fair market value. For example, if a family donates stock worth $50,000 that was purchased for $10,000, they can claim a $50,000 charitable deduction without incurring capital gains taxes. This strategy effectively increases their philanthropic capacity and tax savings. Furthermore, contributions exceeding annual limits can be carried forward for up to five additional tax years, helping to avoid tax planning mistakes for high income W2 employees and providing even more flexibility.
Allison and Brian, a couple in their late 40s, illustrate how effective tax planning can change economic futures. Their journey shows how smart tax strategies, like charitable giving, can truly enhance family well-being. By collaborating with Bright Advisers, they not only optimized their tax situation but also secured their children’s future through education funding and gained the ability to retire sooner. Through comprehensive planning, they achieved peace of mind, allowing them to enjoy more quality time with their loved ones.
With the right strategies in place, you can transform your family’s financial landscape and create lasting memories together.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Invest in Tax-Efficient Vehicles
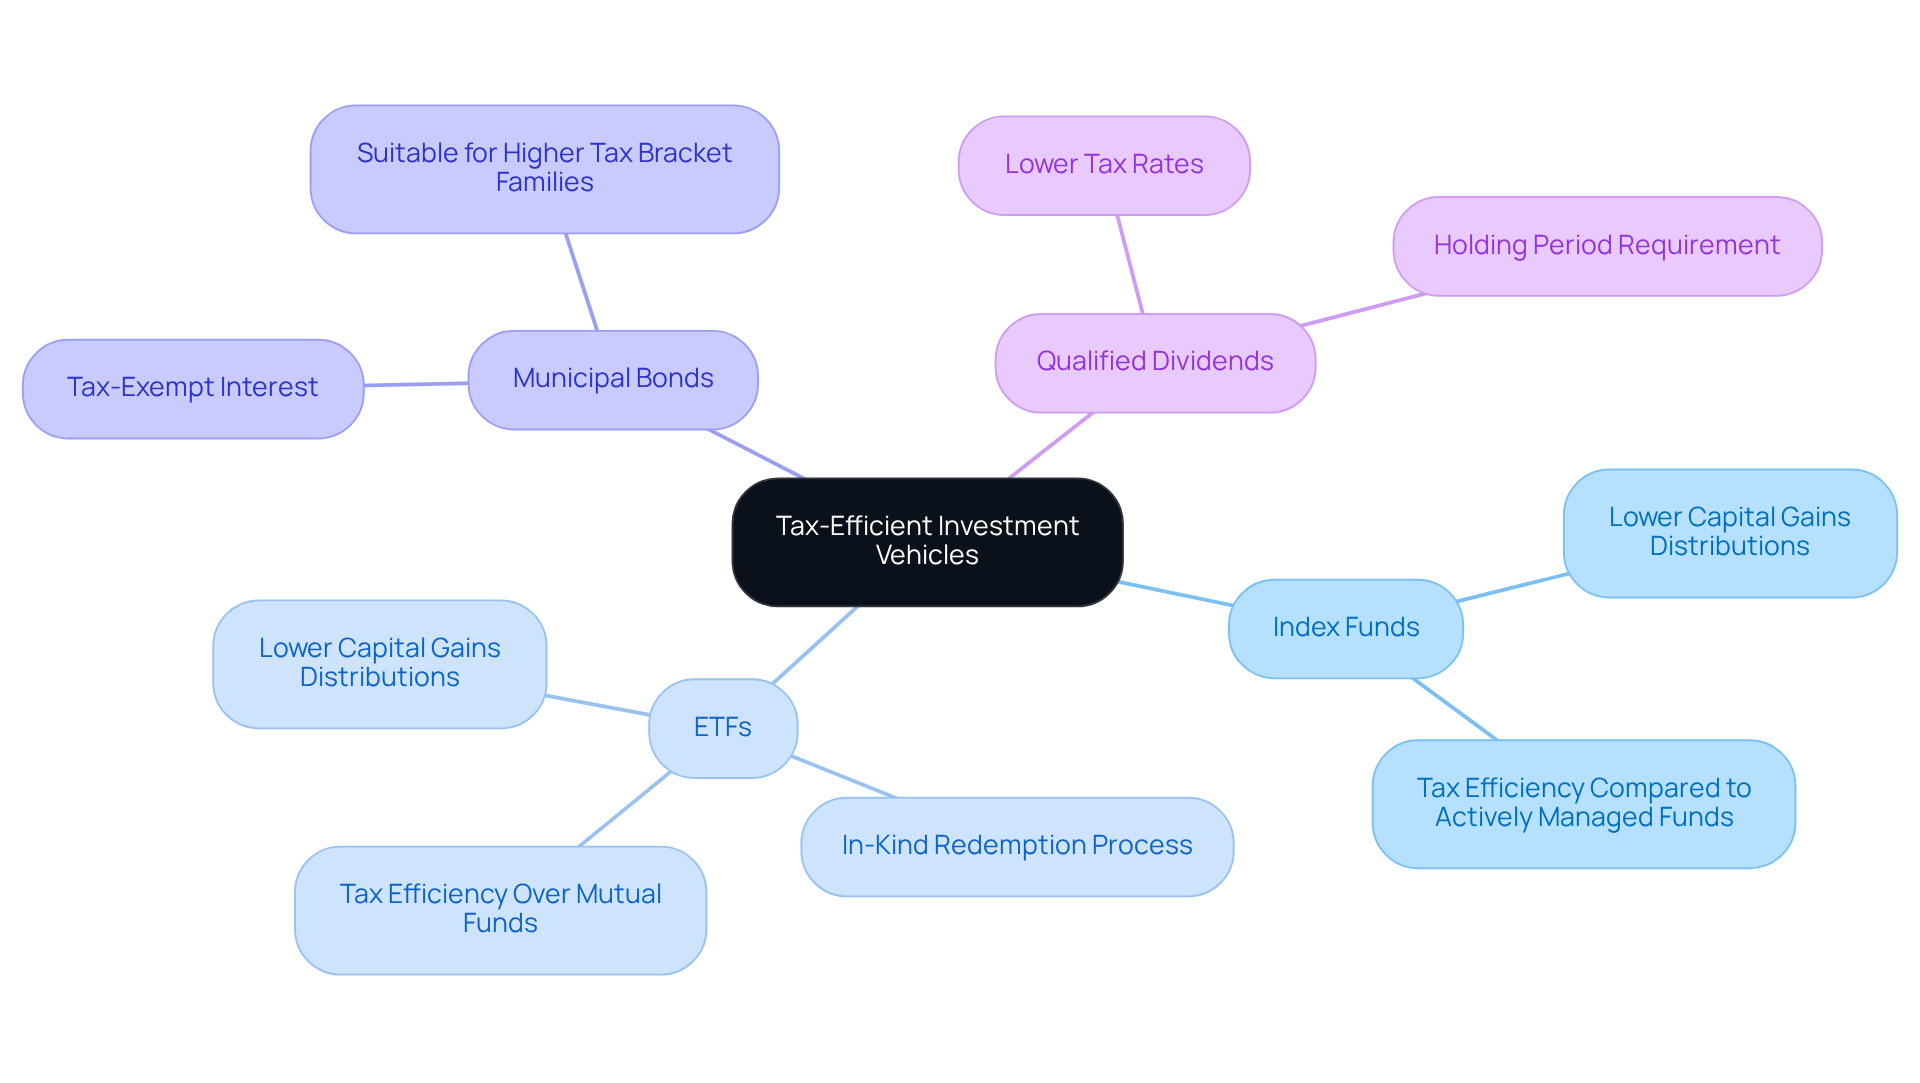
Navigating the world of investments can feel overwhelming, especially when you’re trying to secure a bright future for your family. As you think about your family’s future, consider focusing on tax-efficient investment options like:
- Index funds
- ETFs
- Municipal bonds
These choices often lead to lower capital gains distributions, which means less tax stress for your family. For example, ETFs have been known to distribute fewer capital gains compared to mutual funds, which can be a real win for your family’s finances.
Also, consider investments that provide qualified dividends, as they’re taxed at a lower rate, helping your family keep more of what you earn. This strategy can enhance your after-tax returns, bringing you closer to achieving your family’s financial dreams.
Many families in higher tax brackets find that municipal bonds can be a great choice, often providing tax-exempt interest that helps your money grow. Plus, tools like the Tax Impact Tool can help you spot opportunities to save on taxes, making sure your investment strategy is always working for you.
By embracing these tax-efficient options, you can confidently navigate your family’s financial journey and move closer to your long-term dreams.
Manage Equity Compensation Effectively
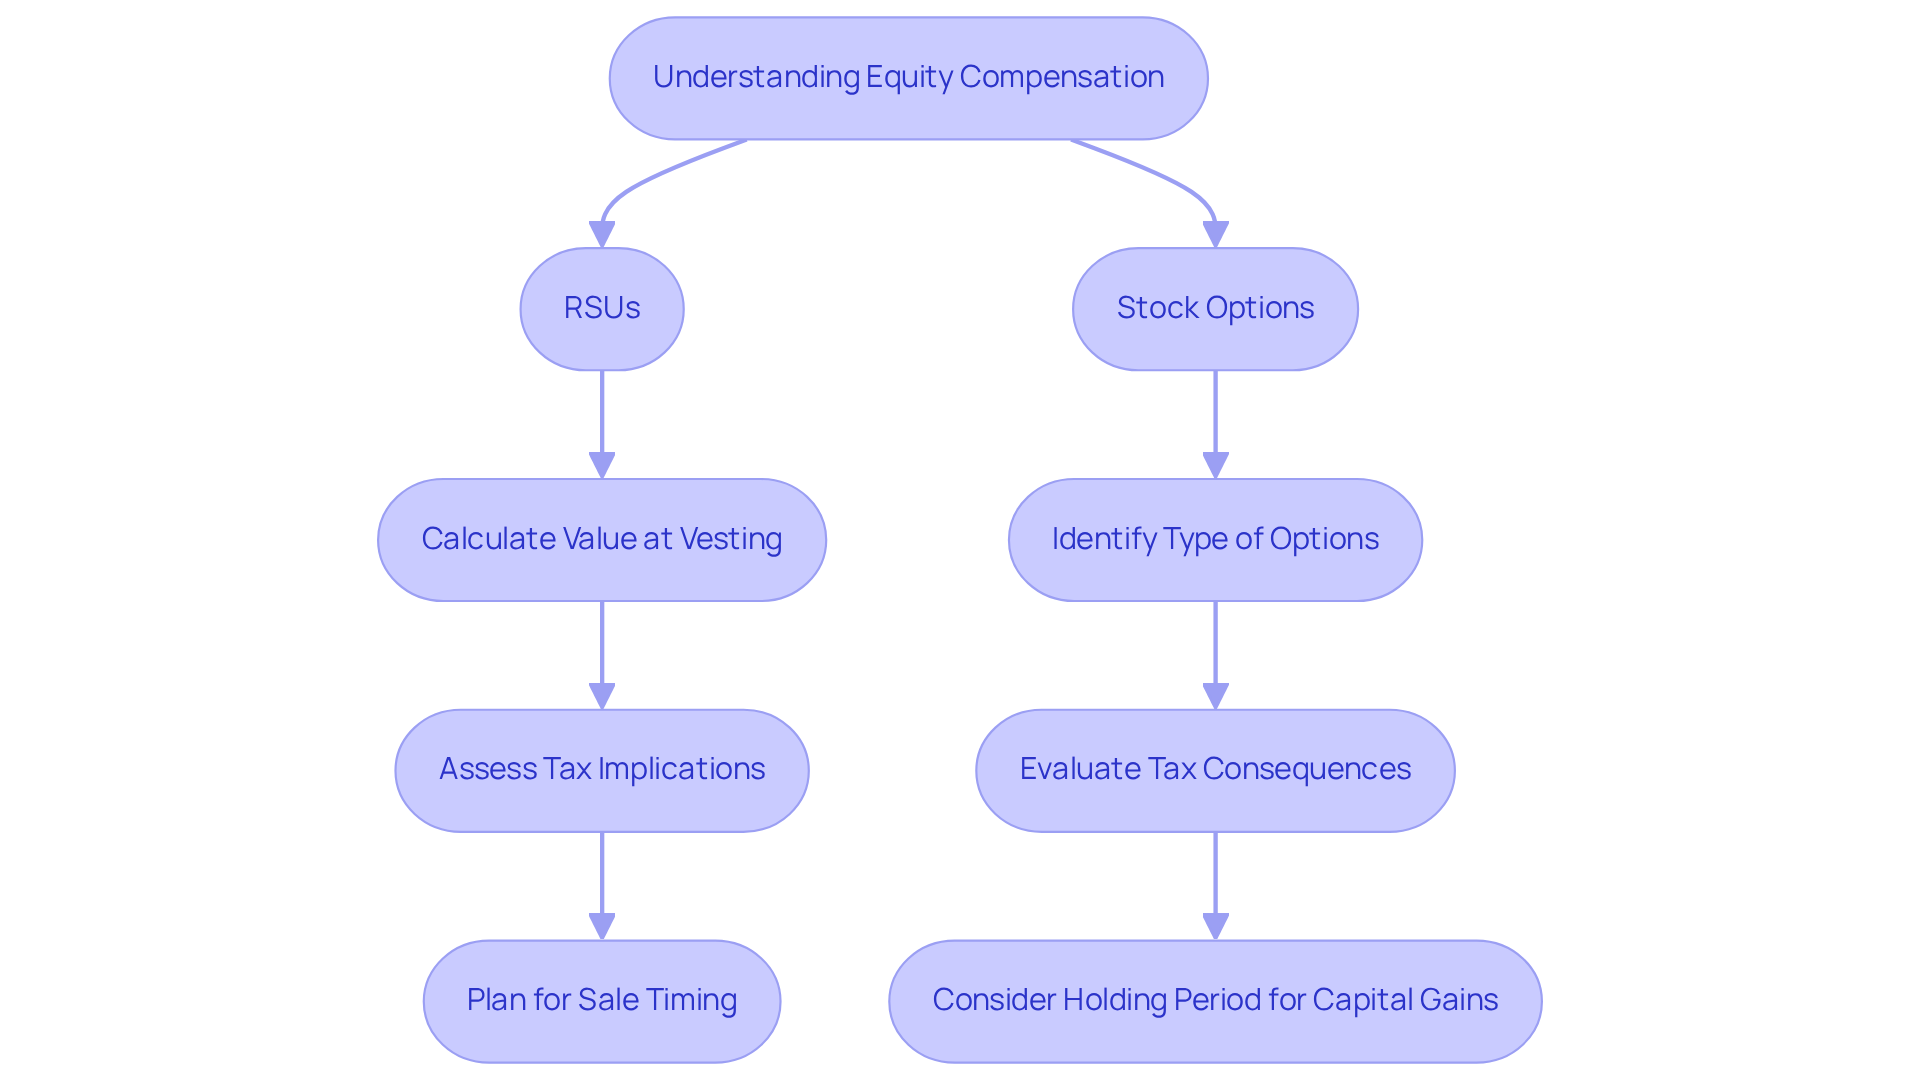
Imagine the stress of managing your family’s finances while navigating the complexities of equity compensation. High-income employees often receive equity compensation, like stock options and restricted stock units (RSUs). It’s important to grasp how these awards can impact your family’s finances.
Let’s break it down: if you have 2,000 RSUs that vest at $150 each, that’s a significant amount that could affect your tax situation. When these RSUs vest, they’re taxed as regular earnings, which can lead to a hefty tax bill. Plus, there’s an additional 7.65% tax for Social Security and Medicare that can add to your worries.
On the other hand, stock options can complicate things even more when it comes to taxes. For example, non-statutory stock options (NSOs) are taxed as regular earnings when exercised, while incentive stock options (ISOs) can lead to long-term capital gains if held for the right period.
Together, we can create a strategy that helps you manage these assets wisely. Timing the sale of shares can be key to minimizing tax liabilities. Imagine the relief of distributing earnings recognition over several tax years to avoid peak marginal rates, which can be quite high when considering state taxes and the net investment income tax.
Consulting with a tax professional can be a great step in navigating these complexities. With the right support, you can turn these challenges into opportunities for your family’s financial growth and security.
Defer Income with Nonqualified Deferred Compensation Plans
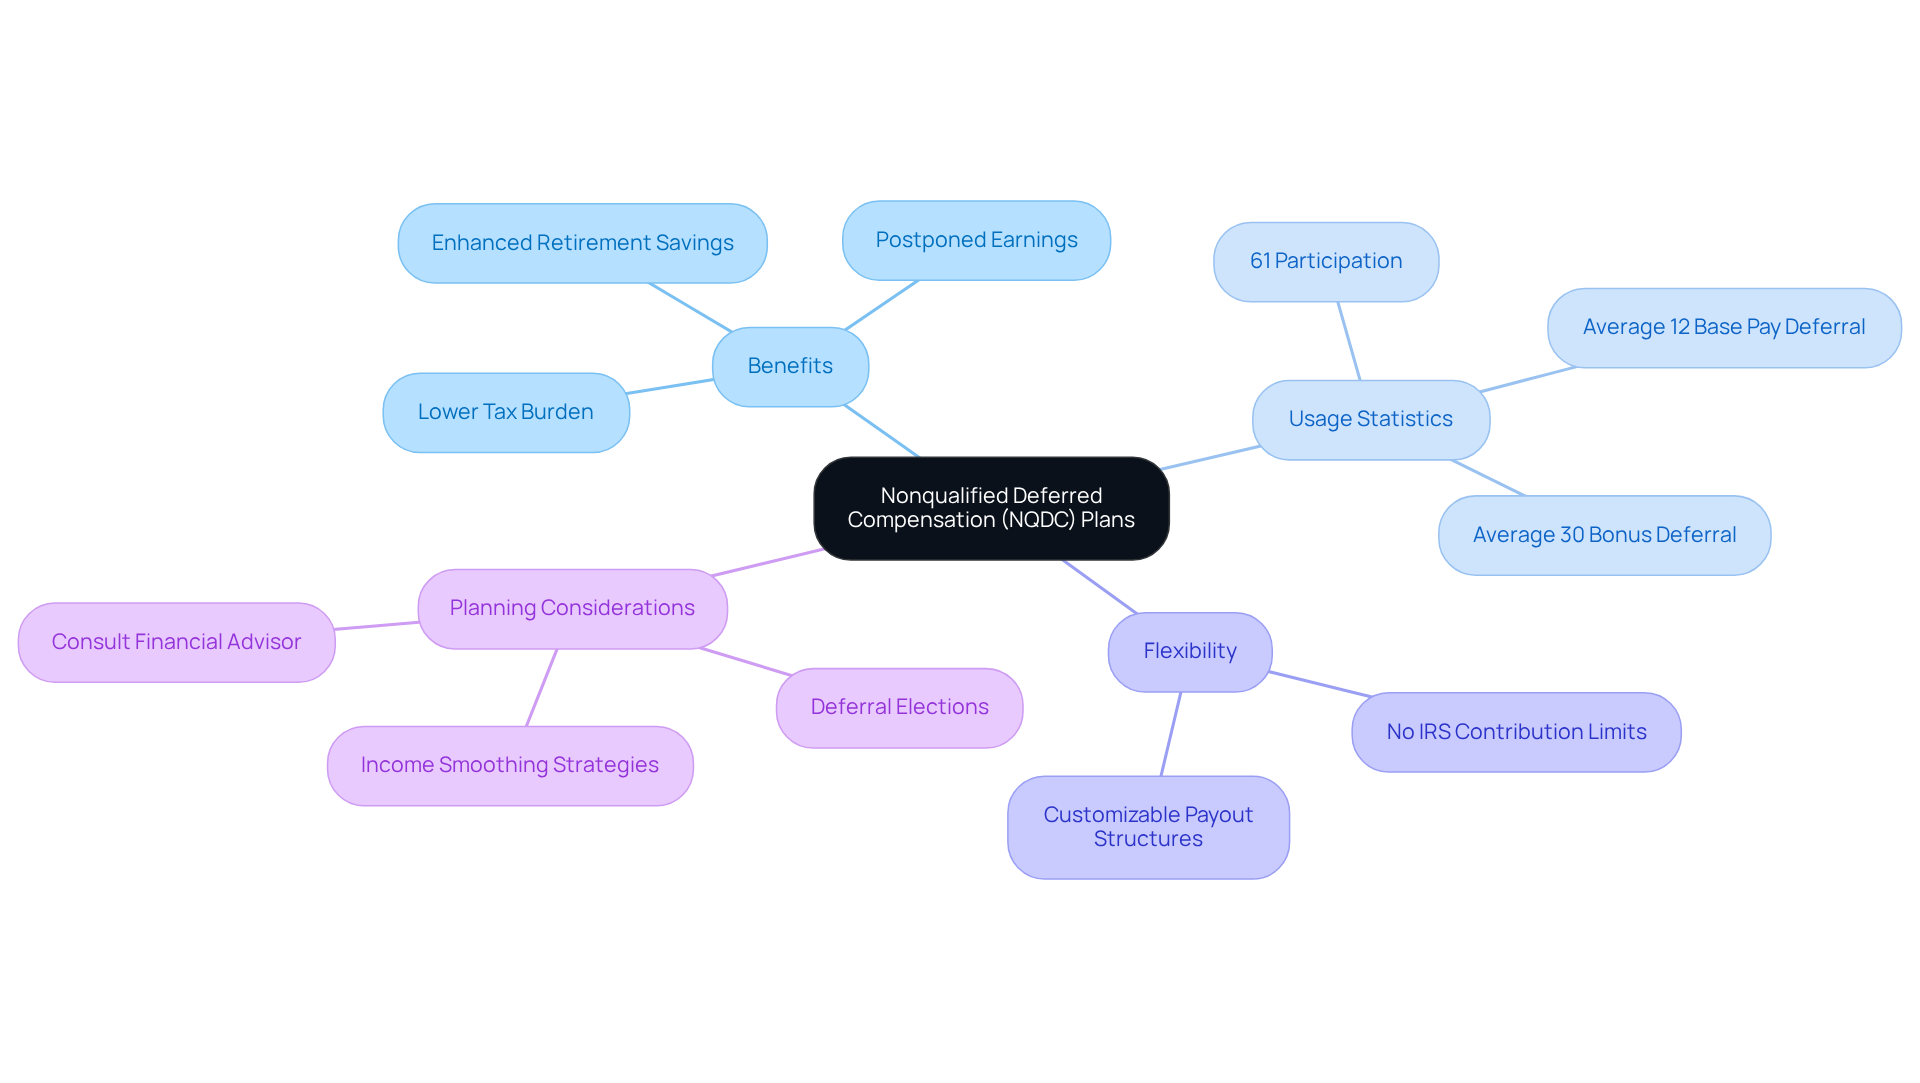
Imagine having a way to save more for your family’s future while potentially lowering your tax burden today. Nonqualified Deferred Compensation (NQDC) plans offer high-earning employees a strategic method to postpone a portion of their earnings, effectively lowering their current taxable amount. This can be a great option if you expect to be in a lower tax bracket when you retire. By postponing earnings, you can potentially decrease your overall tax liability while enhancing your retirement savings.
Many people, about 61% of those eligible, are taking advantage of NQDC plans, setting aside an average of 12% of their base pay and almost 30% of their bonuses to secure their futures. This shows a strong commitment among high-income earners to utilize these plans for their retirement savings.
NQDC plans also provide greater flexibility compared to traditional retirement accounts, as they don’t impose IRS contribution limits. This feature is especially beneficial for executives and professionals who have maxed out their 401(k) contributions. But it’s important to remember that NQDC funds aren’t guaranteed, which means they could be at risk if your employer faces financial trouble.
To really make the most of an NQDC plan, a little planning goes a long way. Deferral elections must be made in the calendar year prior to earnings, so it’s essential to think ahead when budgeting. Consulting with a financial advisor can help ensure that your deferral strategies align with your long-term financial goals, ultimately providing a more secure financial future for your family.
Optimize Dependent Care Deductions
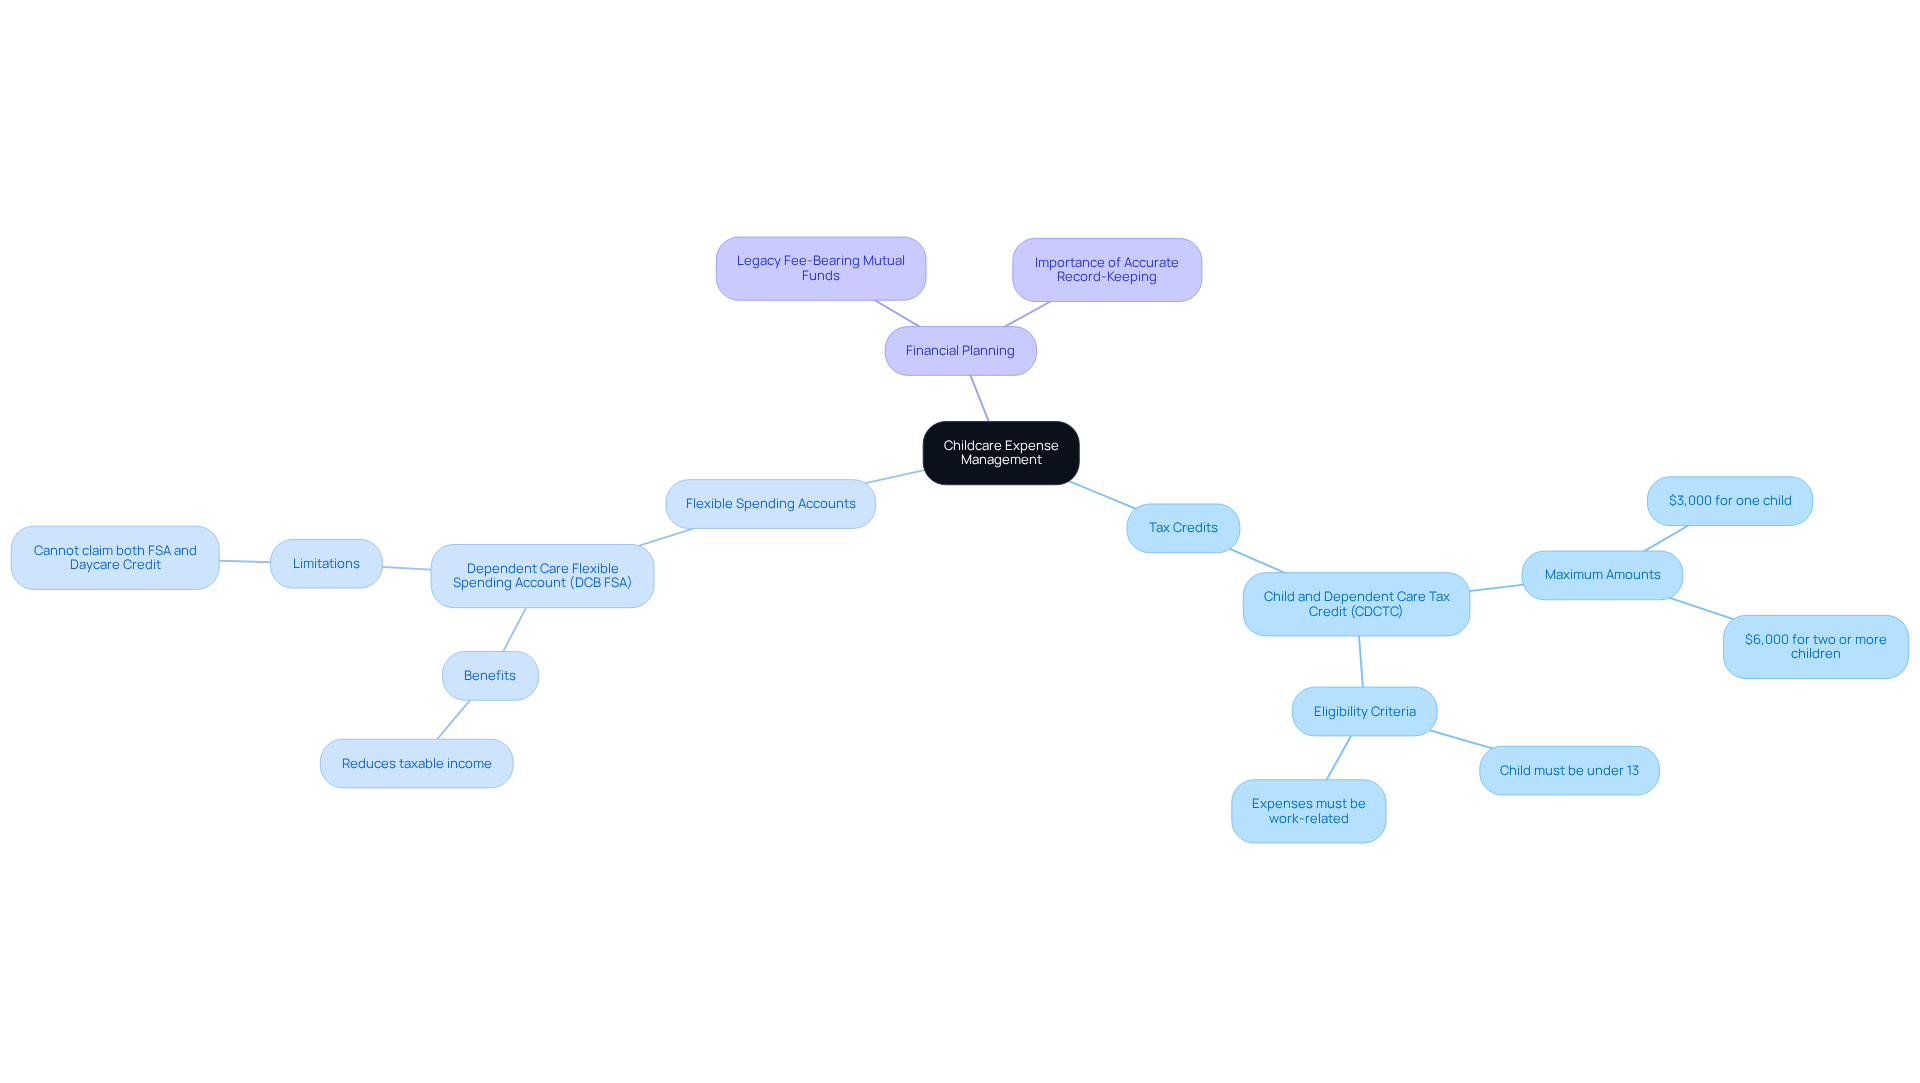
Imagine the relief of easing your childcare expenses while juggling work and family life. Families with young children can benefit from the Child and Dependent Care Tax Credit (CDCTC), which allows them to claim a percentage of qualifying childcare expenses based on their earnings. For the 2026 tax year, families can claim up to $3,000 for one child or $6,000 for two or more children. To qualify, the child must be under 13 years old, and the expenses must be work-related. Keeping accurate records of childcare expenses is essential for claiming this credit.
Imagine the stress of managing childcare costs that can exceed $10,000 a year. Using a Dependent Care Flexible Spending Account (FSA) can further decrease taxable earnings; however, expenses covered by a DCB FSA cannot also be claimed for the Daycare Credit. For instance, a single parent in Louisiana with an adjusted gross income (AGI) of $19,900 can claim $1,241 in tax credits for $2,640 in childcare expenses. This credit lightens the load of childcare costs, helping parents stay employed and pursue their educational goals.
We’re here to help you manage your childcare expenses with a clear and straightforward fee structure, so you can focus on what truly matters-your family. It’s essential to recognize that some families may possess legacy fee-bearing mutual funds and ETFs, which can influence overall planning. Please remember that past performance does not guarantee future results, and all investments are subject to risk. With the right support, you can navigate these financial challenges and secure a brighter future for your family.
Employ Tax-Loss Harvesting Strategies
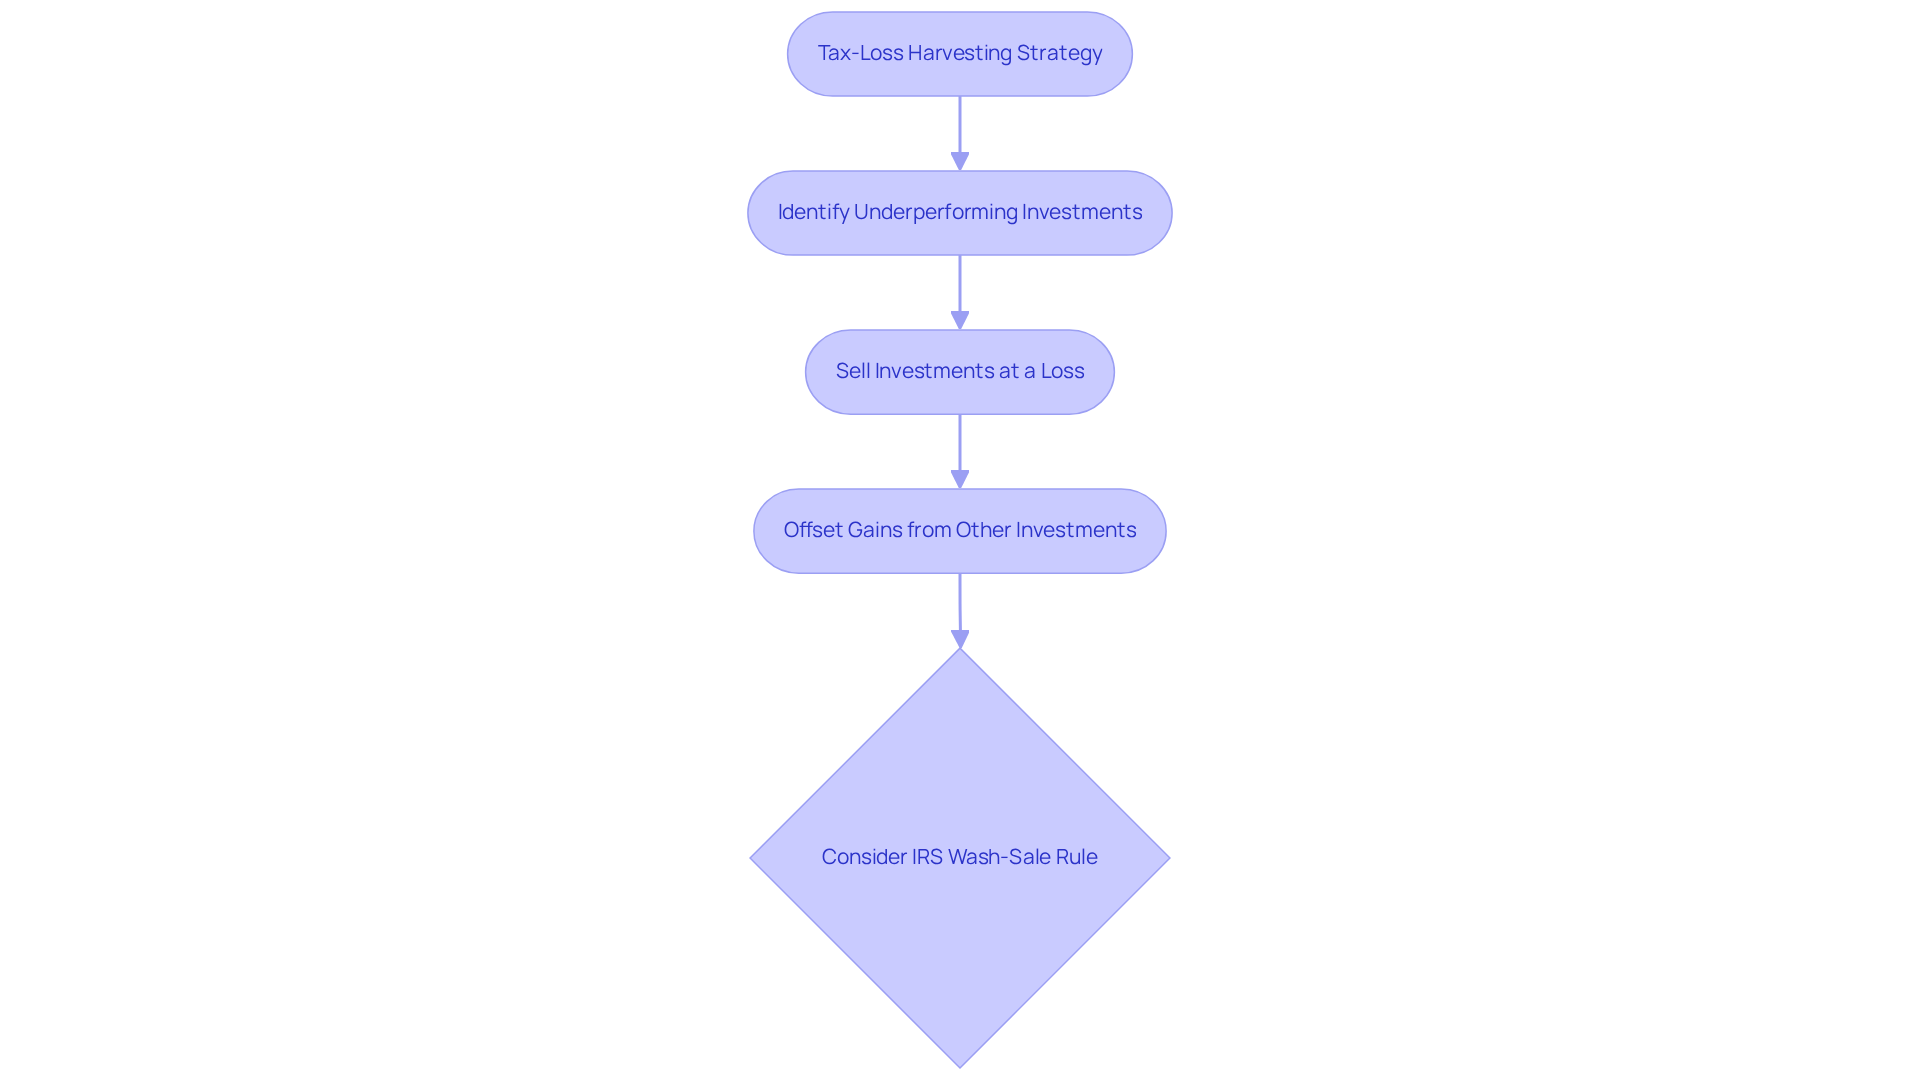
Imagine feeling empowered to make your investments work harder for your family’s future, even when the market isn’t in your favor. Tax-loss harvesting can help you sell investments that aren’t performing well, allowing you to balance out gains from other investments and lower your tax bill. This approach can significantly reduce your overall tax liability, giving you more resources to support your family’s needs.
Just keep in mind the IRS wash-sale rule: if you buy back the same investment within 30 days after selling it at a loss, you can’t claim that loss on your taxes. Navigating tax rules can feel overwhelming, especially when you’re trying to secure your family’s future. But by proactively managing your investments, you can enhance your after-tax returns and better support your family’s monetary goals.
Think about Emily and Mark, a couple just like you, striving to balance their careers and family life. They sought advice from Bright Advisers to navigate the complexities of planning their finances. By implementing tax-loss harvesting strategies, they were able to offset gains from their investments, allowing them to maintain financial stability while pursuing their personal aspirations. For example, if they sold an investment at a loss of $30,000 while realizing a gain of $25,000 from another, they effectively avoided capital gains taxes, resulting in significant tax savings of approximately $4,800.
Did you know that families can offset up to $3,000 of their regular income with losses from investments? This can lead to real savings on your taxes! Engaging with a tax advisor can provide tailored strategies to maximize the effectiveness of tax-loss harvesting, ensuring compliance with IRS regulations while enhancing overall investment performance. At Bright Advisers, we are dedicated to assisting households like Emily and Mark in reaching their monetary objectives through customized planning and tax strategies, including extensive planning services that incorporate tax-loss harvesting into a wider approach. Imagine the peace of mind you’ll feel knowing your family’s financial future is secure, thanks to smart strategies like tax-loss harvesting.
Seek Professional Tax Guidance
Navigating the tax code can feel overwhelming, especially when juggling family responsibilities. A caring advisor can help you find the right deductions and credits tailored to your family’s needs, making the process feel less daunting. This support is invaluable for families like yours, who may have different income streams or complex financial situations. With the right guidance, you can feel secure in your financial choices while maximizing your family’s well-being.
For example, Jay and Emma, a couple with two children, sought Bright Advisers’ expertise to alleviate their monetary stress and allocate resources effectively. They developed a comprehensive monetary strategy that included optimized tax planning and a customized retirement plan.
Likewise, Emily and Mark, both high-earning professionals, collaborated with Bright Advisers to develop a plan that granted them the liberty to decide whether or not to keep working. Their collaboration resulted in a clearer understanding of their monetary situation and strategies to manage cash flow and invest wisely.
Engaging with a tax professional can empower families like yours to avoid tax planning mistakes for high income W-2 employees while navigating financial complexities and achieving peace of mind.
Please note that past performance does not guarantee future results, and all investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine navigating the complexities of tax planning without the right guidance – it’s a challenge many high-income families face. Avoiding tax planning mistakes is crucial for securing your family’s financial future. This article highlights ten common pitfalls that can lead to unnecessary tax burdens and missed opportunities for savings. By understanding these mistakes and implementing effective strategies, you can navigate the complexities of tax planning with confidence.
Key insights discussed include:
- Maximizing pre-tax retirement contributions
- Utilizing Backdoor Roth IRAs
- Strategically funding Health Savings Accounts
- Considering tax-efficient investments
- Managing equity compensation
- Optimizing dependent care deductions
Each of these strategies not only helps in reducing tax liabilities but also contributes to long-term financial stability for families.
Getting the right tax guidance can truly change the game for families like yours. Engaging with experts like Bright Advisers ensures that you receive tailored advice that aligns with your unique financial situation. Together, by taking proactive steps and using the resources available, you can sidestep common tax pitfalls and build a secure future for your family.
Frequently Asked Questions
What is the maximum contribution limit for a 401(k) in 2026?
In 2026, you can contribute up to $24,500 to your 401(k).
How can employer matching contributions benefit my retirement savings?
Employer matching contributions can enhance your retirement savings without any extra cost to you, helping to secure your family’s future.
What is a Backdoor Roth IRA and how does it work?
A Backdoor Roth IRA is a two-step process that allows high earners to contribute to a Roth IRA despite income limits. First, you make a non-deductible contribution to a traditional IRA, then convert it to a Roth IRA.
What are the contribution limits for a traditional IRA in 2025?
For 2025, the contribution limit for a traditional IRA is capped at $7,500 for individuals under 50 and $8,000 for those aged 50 or older.
What are the income limits for direct Roth IRA contributions in 2026?
The income limits for direct Roth IRA contributions in 2026 are set at $153,000 for single filers and $242,000 for married couples.
What is the pro-rata rule in relation to Backdoor Roth IRA conversions?
The pro-rata rule requires that conversions include a proportional mix of pre-tax and after-tax funds across all IRAs, which can complicate the conversion process if you have existing pre-tax balances.
How can I avoid taxable gains when converting to a Roth IRA?
To avoid taxable gains, execute the conversion quickly after making the non-deductible contribution to the traditional IRA, as any increase in value before conversion may incur taxes.
What is a Health Savings Account (HSA) and its benefits?
A Health Savings Account (HSA) allows you to set aside pre-tax dollars for qualified medical expenses, providing a financial cushion for unexpected healthcare costs.
What are the contribution limits for HSAs in 2026?
In 2026, you can contribute up to $3,400 to an HSA, or $6,800 for couples. If you are 55 or older, you can contribute an additional $1,000.
What is required to contribute to an HSA?
To contribute to an HSA, you must be enrolled in a qualifying high-deductible health plan and not be enrolled in Medicare.
How can HSAs be paired with Flexible Spending Accounts (FSAs)?
HSAs can be paired with limited purpose health care FSAs, which can cover specific expenses like vision or dental care, enhancing your overall strategy for managing healthcare costs.
List of Sources
- Maximize Pre-Tax Retirement Contributions
- 401(k) Contribution Limits for Highly Compensated Employees in 2026 (https://epwealth.com/blog/401k-contribution-limits-for-highly-compensated-employees)
- 401(k) Catch-Up Contributions: Final SECURE 2.0 Rules for Employers (https://employeefiduciary.com/blog/401k-catch-up-contributions)
- 401(k) Contribution Limits for 2026 (https://northwesternmutual.com/life-and-money/401k-contribution-limits)
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- Utilize a Backdoor Roth IRA Conversion
- Roth IRAs Are for High-Income Earners, Too (https://matsorensen.com/roth-iras-are-for-high-income-earners-too)
- The Backdoor Roth IRA Strategy – Mahoney | CPAs and Advisors (https://mahoneycpa.com/the-backdoor-roth-ira-strategy)
- Backdoor Roth IRAs for High-Income Earners: Are They Still Allowed? (https://kahnlitwin.com/blogs/tax-blog/backdoor-roth-iras-for-high-income-earners-are-they-still-allowed)
- The Backdoor Roth IRA: The Ultimate Guide for High Earners Who Exceed Roth Income Limits | WealthRabbit Blog (https://wealthrabbit.com/blog/the-backdoor-roth-ira-the-ultimate-guide-for-high-earners-who-exceed-roth-income-limits)
- Backdoor Roth IRA: A tax-saving strategy for some high earners (https://wolterskluwer.com/en/expert-insights/backdoor-roth-ira-a-tax-saving-strategy-for-some-high-earners)
- Fund a Health Savings Account (HSA)
- 2026 Health Savings Account (https://dartmouth.edu/hr/benefits_compensation/benefits/2026_benefits/hsa.php)
- HSA contribution limits (https://optumbank.com/health-savings-accounts/resources/contribution-limits.html)
- HSA contribution limits 2026 and 2027 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- IRS Announces 2026 HSA and HDHP Limits (https://keenan.com/knowledge-center/news-and-insights/blogs/irs-announces-2026-hsa-and-hdhp-limits)
- HSA Contribution Limits to Increase in 2026 (https://bpbcpa.com/hsa-contribution-limits-to-increase-in-2026)
- Strategically Utilize Charitable Donations
- Donor Advised Funds Tax Benefits (https://ghcf.org/articles/donor-advised-funds-tax-benefits)
- Tax Advantages for Donor-Advised Funds | NPTrust (https://nptrust.org/what-is-a-donor-advised-fund/daf-tax-consideration)
- An Analysis of Charitable Giving and Donor Advised Funds (https://congress.gov/crs-product/R42595)
- The Future is #DAF: Donor-Advised Fund Growth and How Nonprofits Can Benefit – CCS Fundraising (https://ccsfundraising.com/insights/the-future-is-daf-donor-advised-fund-growth)
- Charitable Giving Statistics for 2023 (https://definefinancial.com/uncategorized/charitable-giving-statistics)
- Invest in Tax-Efficient Vehicles
- Capital Gains Distributions: Mutual Funds v. ETFs | Russell Investments (https://russellinvestments.com/us/blog/capital-gains-distributions-season)
- ETF versus Mutual Fund Taxes – Fidelity (https://fidelity.com/learning-center/investment-products/etf/etfs-tax-efficiency)
- 25 Top Picks for Tax-Efficient ETFs and Mutual Funds (https://morningstar.com/funds/25-top-picks-tax-efficient-etfs-mutual-funds)
- ETFs and tax efficiency: What you need to know (https://ssga.com/us/en/individual/resources/education/etfs-and-tax-efficiency-what-you-need-to-know)
- What drives fund tax efficiency? | BlackRock (https://blackrock.com/us/financial-professionals/insights/what-drives-fund-tax-efficiency)
- Manage Equity Compensation Effectively
- RSU vs. stock options: What’s the difference? (https://empower.com/the-currency/money/stock-options-vs-rsu)
- Managing RSUs and Stock Options: A Tax-Efficient Strategy for Executives and High-Income Professionals – True Wealth Design (https://truewealthdesign.com/managing-rsus-and-stock-options)
- Equity Compensation Tax Strategies for High Wealth Individuals (https://bradyware.com/equity-compensation-tax-strategies-high-wealth-individuals)
- RSU Tax Strategy Guide for High Earners | VIP Wealth Advisors (https://vipwealthadvisors.com/insights/rsu-tax-strategy-guide)
- How Are My RSUs Taxed, and What Can I Do to Pay Less in Taxes? (https://blog.sweeneyconrad.com/how-are-my-rsus-taxed-and-what-can-i-do-to-pay-less-in-taxes)
- Defer Income with Nonqualified Deferred Compensation Plans
- Deferred Compensation: How High Earners Can Reduce Taxes (https://aspiriant.com/fathom/deferred-compensation)
- Here’s Why Companies Offer Nonqualified Deferred Compensation Plans (https://napa-net.org/news/2025/2/heres-why-companies-offer-nonqualified-deferred-compensation-plans)
- Nonqualified Deferred Compensation Plans (NQDCs) | Fidelity Investments (https://fidelity.com/viewpoints/retirement/nqdc)
- Non-Qualified Deferred Compensation (NQDC) | Wealthspire (https://wealthspire.com/financial-dictionary/non-qualified-deferred-compensation-nqdc)
- Optimize Dependent Care Deductions
- Child and Dependent Care Tax Credit (CDCTC) (https://economicprogressri.org/resources/child-and-dependent-care-tax-credit-cdctc)
- Deducting Summer Camps and Daycare with the Child and Dependent Care Credit (https://turbotax.intuit.com/tax-tips/family/deducting-summer-camps-and-daycare-with-the-child-and-dependent-care-credit/L8aAzvmjB)
- The Child and Dependent Care Tax Credit: How It Works – First Five Years Fund (https://ffyf.org/2026/06/25/cdctc-how-it-works)
- Credit for child and dependent care expenses explained (https://jacksonhewitt.com/tax-help/tax-tips-topics/family/child-and-dependent-care-credit)
- Federal Child Care Tax Policy Changes and What They Mean for New Hampshire Families – New Hampshire Fiscal Policy Institute (https://nhfpi.org/resource/federal-child-care-tax-policy-changes-and-what-they-mean-for-new-hampshire-families)
- Employ Tax-Loss Harvesting Strategies
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Wealthfront Tax-Loss Harvesting | Wealthfront Whitepapers (https://research.wealthfront.com/whitepapers/tax-loss-harvesting)
- How to Cut Your Tax Bill with Tax-Loss Harvesting (https://schwab.com/learn/story/how-to-cut-your-tax-bill-with-tax-loss-harvesting)
- WSJ: Just How Valuable Is Tax-Loss Harvesting? (https://linkedin.com/pulse/wsj-just-how-valuable-tax-loss-harvesting-derek-horstmeyer)
- Seek Professional Tax Guidance
- Tax Planning Strategies for High-Income Earners (https://farther.com/foundations/tax-planning-strategies-for-high-income-earners)
- Tax Day: Five Charts on Who Pays, How Much (https://adamnmichel.substack.com/p/tax-day-five-charts-on-who-pays-how)
- Summary of the Latest Federal Income Tax Data, Tax Year 2022 (https://taxfoundation.org/data/all/federal/latest-federal-income-tax-data-2025)
- Tax Planning for High-Income Earners: Strategies That Work (2026) | Taxstra (https://taxstra.com/tax-strategy/high-income-tax-planning)
- Who Is Paying Their Fair Share of Taxes? A New Analysis and Interactive Tool (https://budgetlab.yale.edu/research/who-paying-their-fair-share-taxes-new-analysis-and-interactive-tool)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading