

Key Highlights
- Upcoming tax law changes in 2026 include an increased standard deduction of $16,100 for single filers and $32,200 for married couples, providing opportunities to lower taxable income.
- The SALT deduction cap will rise to $40,000, making itemising deductions more appealing for families in high-tax states like California and New York.
- High-income earners should consider tax-loss harvesting to manage investments effectively during market downturns, especially for those with stock options or RSUs.
- Investing in tax-advantaged accounts (e.g., 401(k)s, IRAs) and municipal bonds can enhance long-term wealth while providing tax benefits.
- Charitable giving strategies, such as donating appreciated assets and establishing Donor-Advised Funds (DAFs), can provide significant tax savings.
- Advanced estate planning techniques, including irrevocable trusts and family limited partnerships, can help preserve wealth and minimise tax burdens.
- Families are encouraged to collaborate with Bright Advisers for personalised guidance in navigating tax complexities and optimising financial strategies.
Introduction
Imagine facing a maze of tax regulations while trying to secure your family’s future. As the landscape of tax laws shifts, high-income executives encounter unique challenges and opportunities in their financial planning. With changes on the horizon for 2026, it’s crucial for families to grasp the nuances of tax law to preserve their wealth and secure their financial futures.
Many families feel lost when it comes to navigating tax laws. Let’s explore four best practices that can guide your family through these complexities, from tax-efficient investment strategies to leveraging charitable giving for maximum benefits. Without a clear strategy, families risk losing their hard-earned wealth.
How can families ensure they are not only compliant but also strategically positioned to thrive amidst these changes? With the right strategies, families can not only comply but also thrive in this changing landscape.
Understand Tax Law Changes for 2026
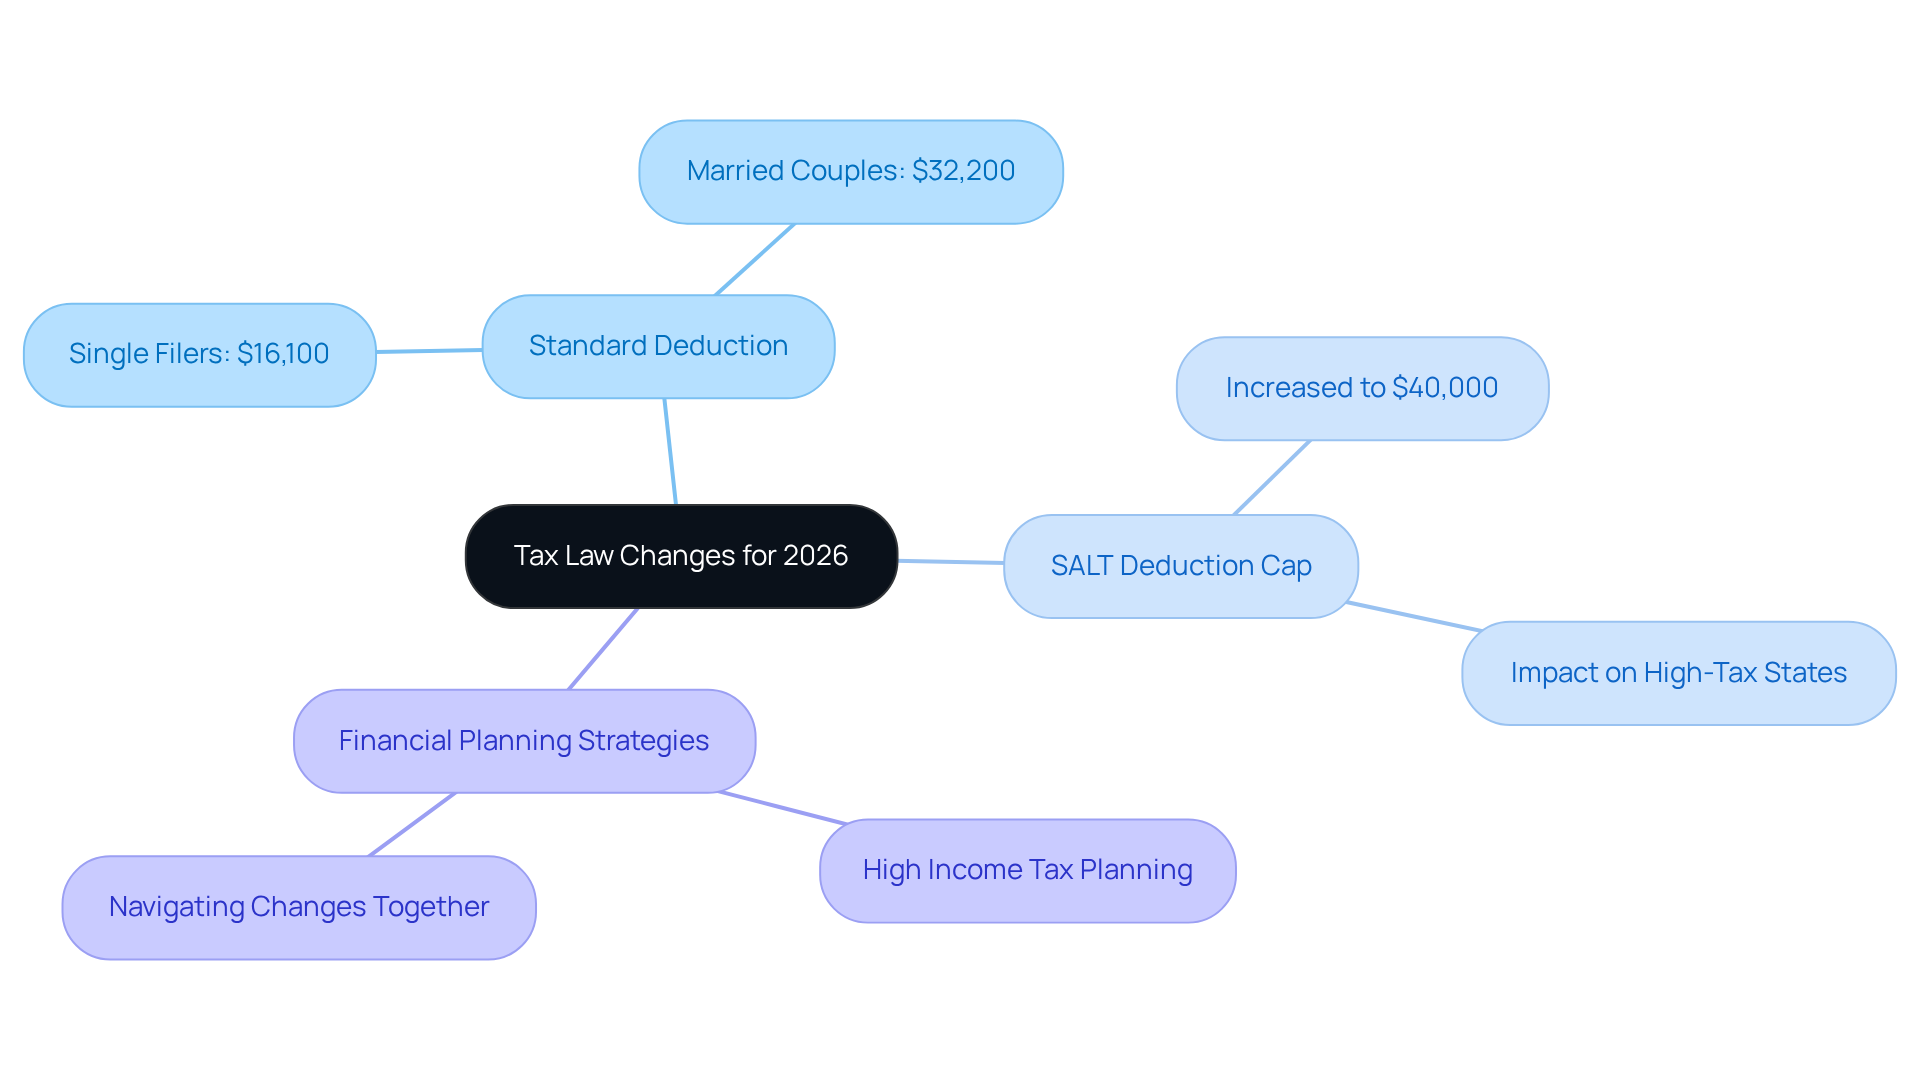
As we look ahead to 2026, many families may feel anxious about the upcoming tax law changes that could affect their financial well-being. High-income earners, particularly those in executive roles, should consider high income tax planning for executives due to the significant changes introduced by the One Big Beautiful Bill Act (OBBBA). The standard deduction will increase to $16,100 for single filers and $32,200 for married couples filing jointly. This adjustment offers a wonderful opportunity for households to lower their taxable income.
Additionally, the state and local tax (SALT) deduction cap will rise to $40,000, which is great news for families living in high-tax states like California and New York. This change makes itemizing deductions more appealing for those facing high state and local taxes.
However, navigating these changes can feel overwhelming, especially when trying to balance family needs and financial responsibilities. It’s important for families to explore ways to navigate these changes together, ensuring that their financial decisions align with the new tax landscape.
For instance, the increased standard deduction and SALT cap can significantly influence tax liabilities, allowing families to retain more of their income. Without a solid plan, families might find themselves paying more than necessary, impacting their ability to save for future goals. Understanding these adjustments is crucial for effective high income tax planning for executives, allowing families to make informed decisions as they prepare for the upcoming tax year.
With the right guidance, families can navigate these changes confidently, ensuring they keep more of what they earn for their loved ones.
Implement Tax-Efficient Investment Strategies
Imagine the weight of financial stress as you try to provide for your family’s future. Every dollar counts, and navigating taxes can feel overwhelming. If you’re a high-income earner, high income tax planning for executives can help you manage the pressure of taxes weighing you down. But there are ways to ease that burden through smart investment choices.
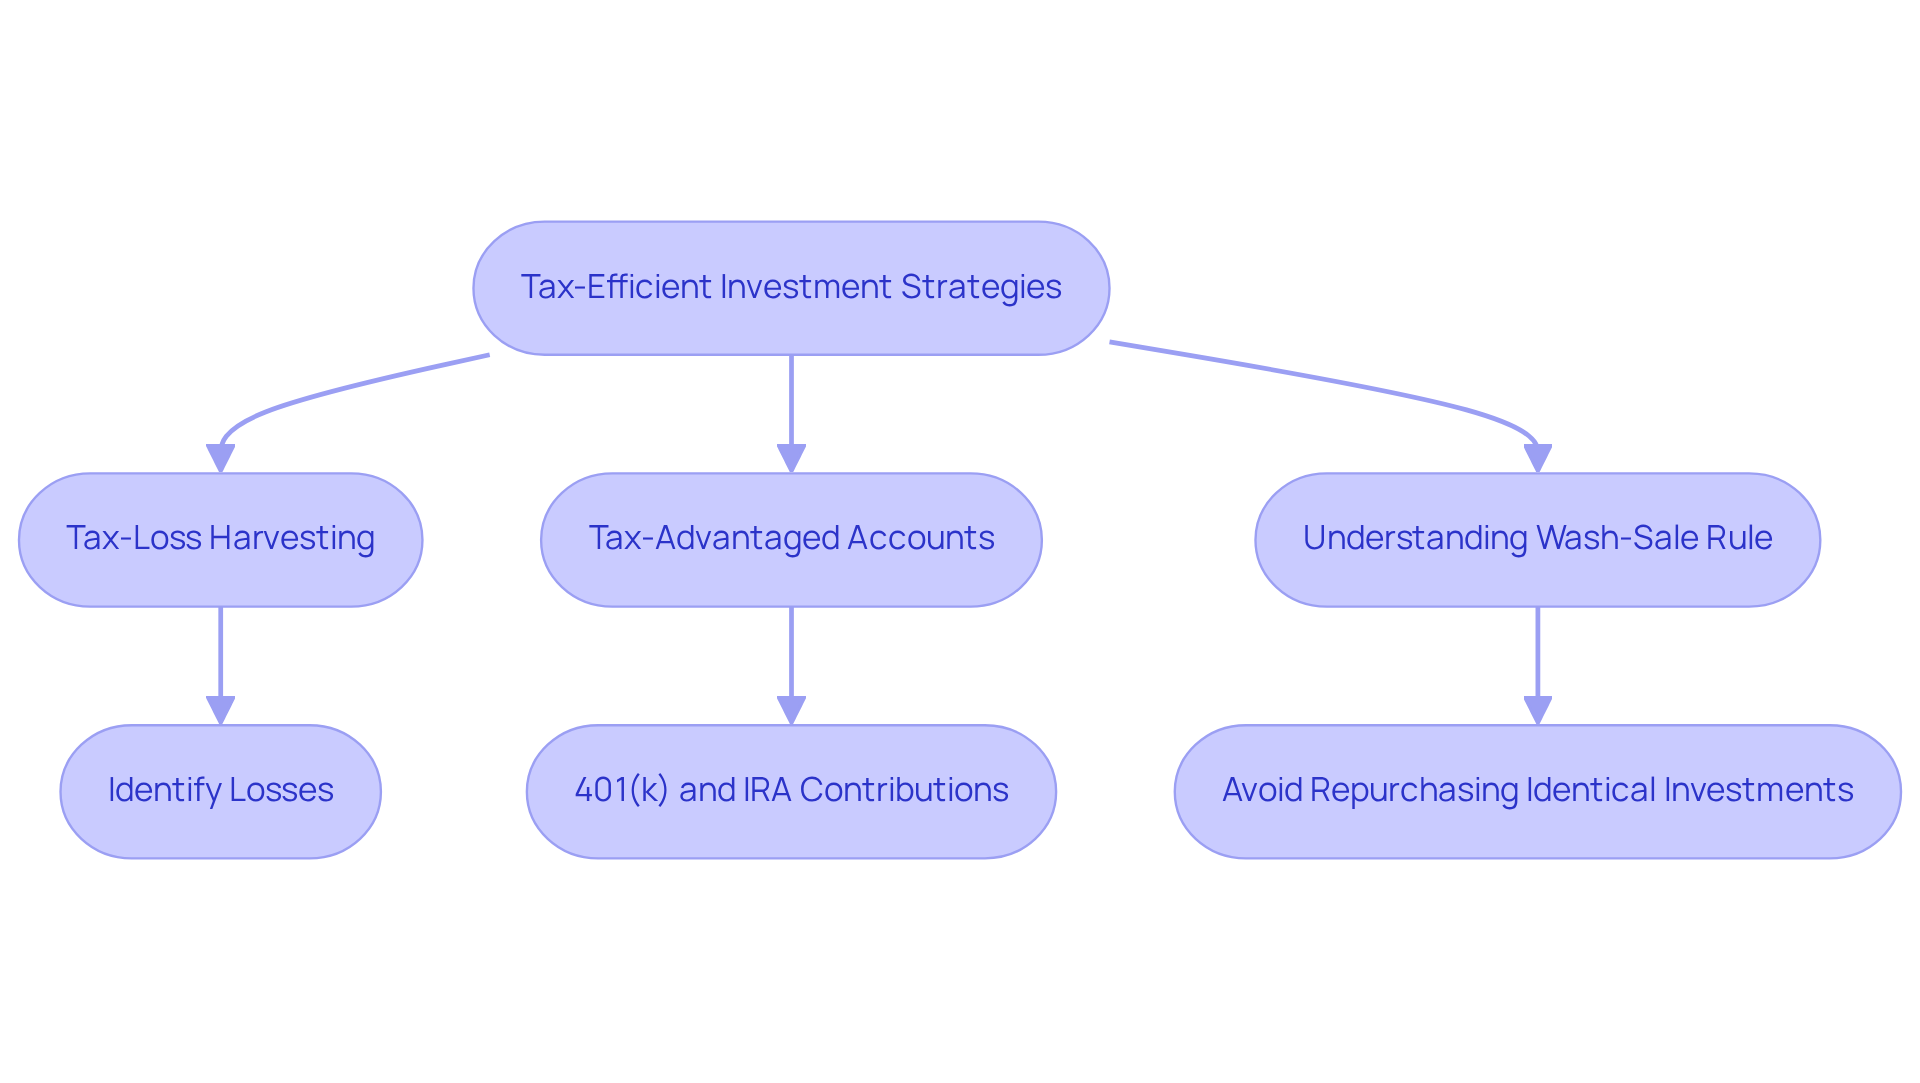
Imagine if you could turn market downturns into opportunities for your family’s financial growth. That’s where tax-loss harvesting comes in, helping you make the most of your investments even when the market dips. This approach is especially beneficial for those with substantial stock options or restricted stock units (RSUs). In fact, in 2024, many stocks faced challenges, presenting numerous opportunities for tax-loss harvesting.
Investing in tax-advantaged accounts, like 401(k)s or IRAs, allows for tax-deferred growth, which can significantly enhance your family’s long-term wealth. You might also consider municipal bonds, which provide tax-free income, as part of high income tax planning for executives, making them an attractive option for high-income earners. By managing your investments wisely and regularly reviewing your portfolio, you can optimize your tax efficiency and support your family’s growth.
Consider the story of Allison and Brian, a couple who faced challenges due to inadequate tax planning. Through their collaboration with Bright Advisers, they learned to implement tax-loss harvesting and other strategies. This not only helped them secure their children’s future through education funding but also allowed them to retire sooner. By integrating these tax strategies into their financial plan, they found peace of mind, enabling them to enjoy more quality time with their loved ones.
It’s important to be aware of the wash-sale rule, which prohibits claiming a capital loss if you repurchase the same or substantially identical investment within 30 days. But don’t worry; you can avoid this by purchasing similar securities, allowing you to maintain market exposure while still realizing tax benefits. By implementing these tax-efficient approaches, you can improve your financial planning and secure a more stable future for your family.
If you’re interested in learning more about how Bright Advisers can assist your household in navigating these complexities, consider joining our current client waitlist. Remember, past performance does not guarantee future results, and all investments carry risks. Advisory services are provided through Lifeworks Advisors, a registered investment adviser. Together, we can navigate these complexities and build a secure future for your family, ensuring you have more time to cherish those precious moments together.
Leverage Charitable Giving for Tax Benefits
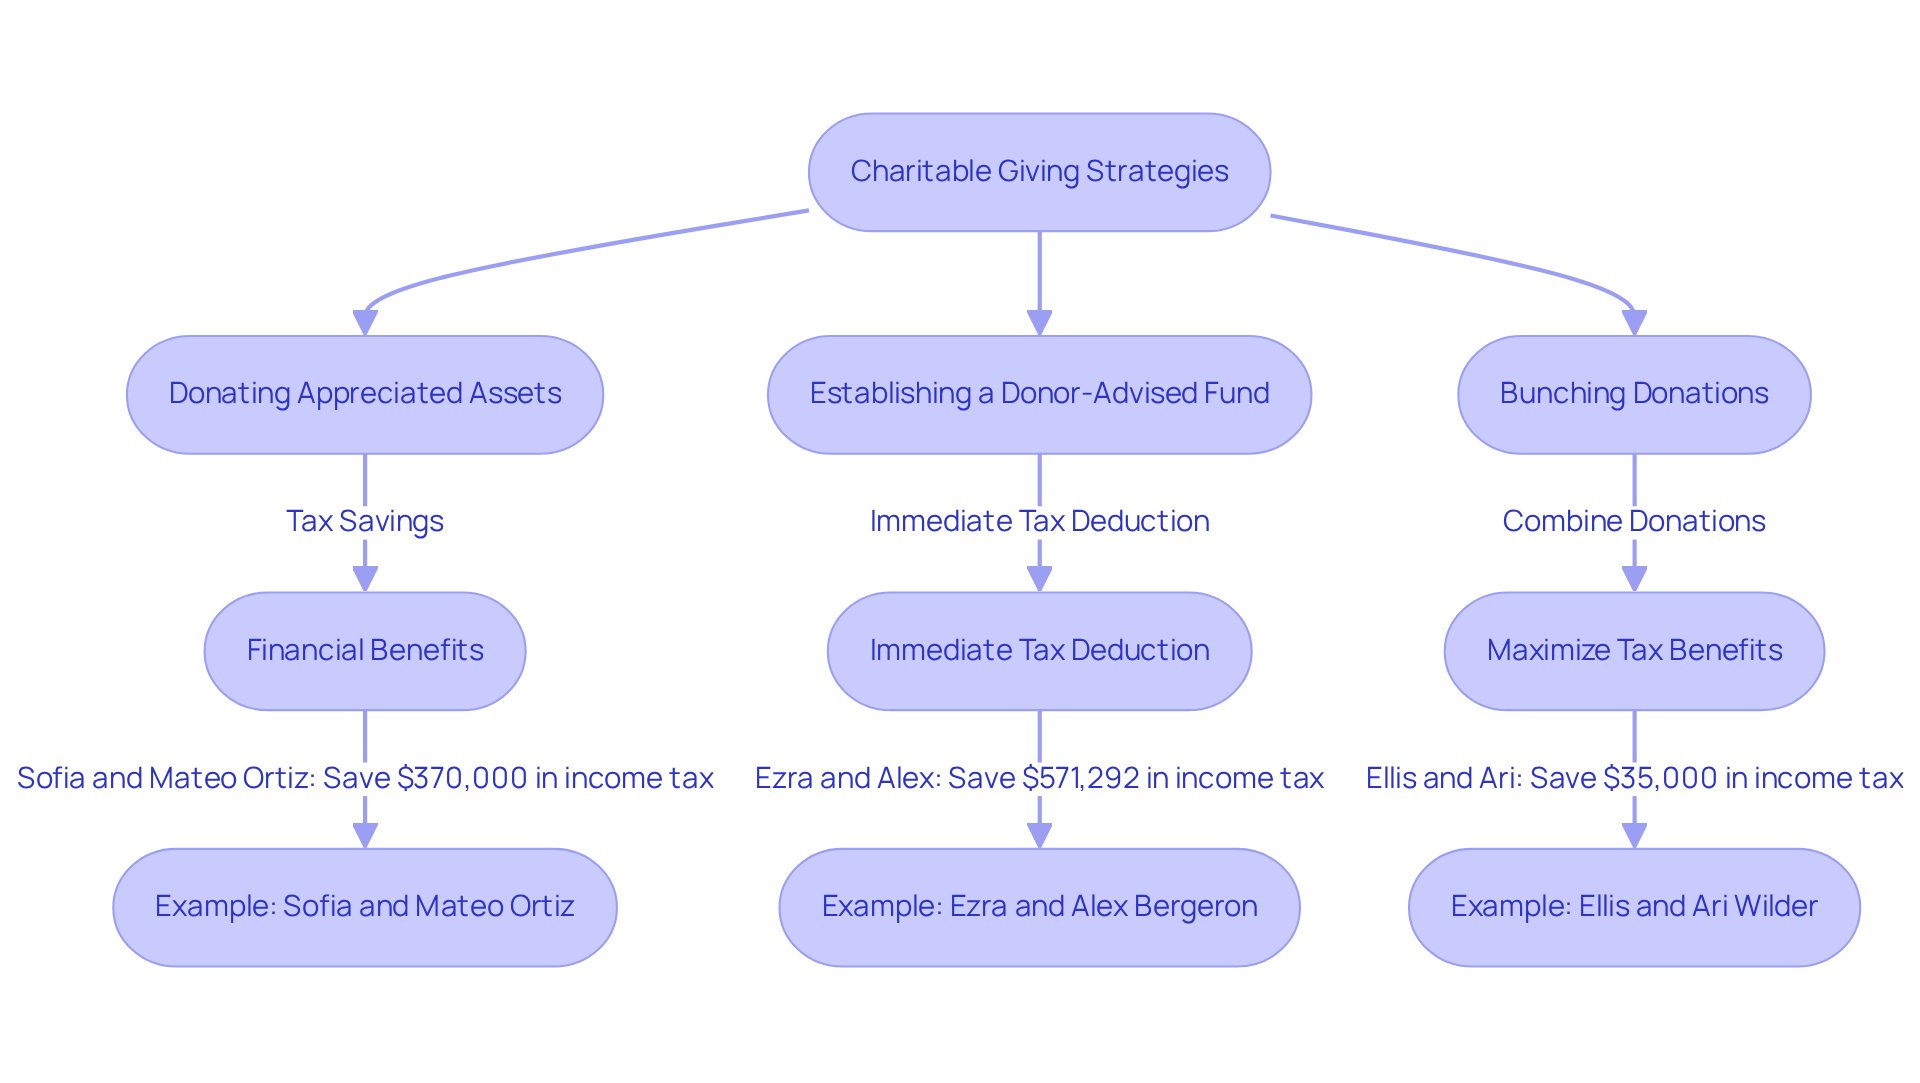
Imagine feeling the weight of tax obligations while wanting to make a difference in your community. Charitable giving can be a powerful way for families like yours to ease that burden. By donating appreciated assets, like stocks or real estate you’ve held onto, you can make a significant impact while also benefiting financially. For example, Sofia and Mateo Ortiz could save up to $370,000 in income tax and avoid $190,400 in capital gains tax by donating appreciated stock valued at $1 million, as long as they’ve held it for the required duration.
Establishing a Donor-Advised Fund (DAF) is another wonderful option. It allows you to make a charitable contribution and receive an immediate tax deduction, all while keeping the flexibility to distribute funds to charities over time. This approach not only helps causes close to your heart but also strengthens your family’s financial future. For instance, Ezra and Alex Bergeron plan to create a charitable remainder trust, which could provide an estimated income deduction of $1,491,350 and save them around $571,292 in income obligations this year, while also enabling them to avoid $1,071,000 in capital gains liability.
You might also consider ‘bunching’ your charitable donations, which means combining several years’ worth into one year to maximize your tax benefits. This tactic can help you exceed the standard deduction threshold, allowing for more impactful charitable giving. By consolidating contributions, you can significantly reduce your income taxes in high-income years with high income tax planning for executives, making a real difference in the causes you care about. Just remember, for donations over $250, a written acknowledgment from the charity is required to ensure compliance. This strategic approach not only benefits the charities involved but also aligns with your family’s financial goals, ensuring a lasting legacy of generosity. By taking these steps, you can ensure your family’s legacy of generosity thrives for generations to come.
Utilize Advanced Estate Planning Techniques
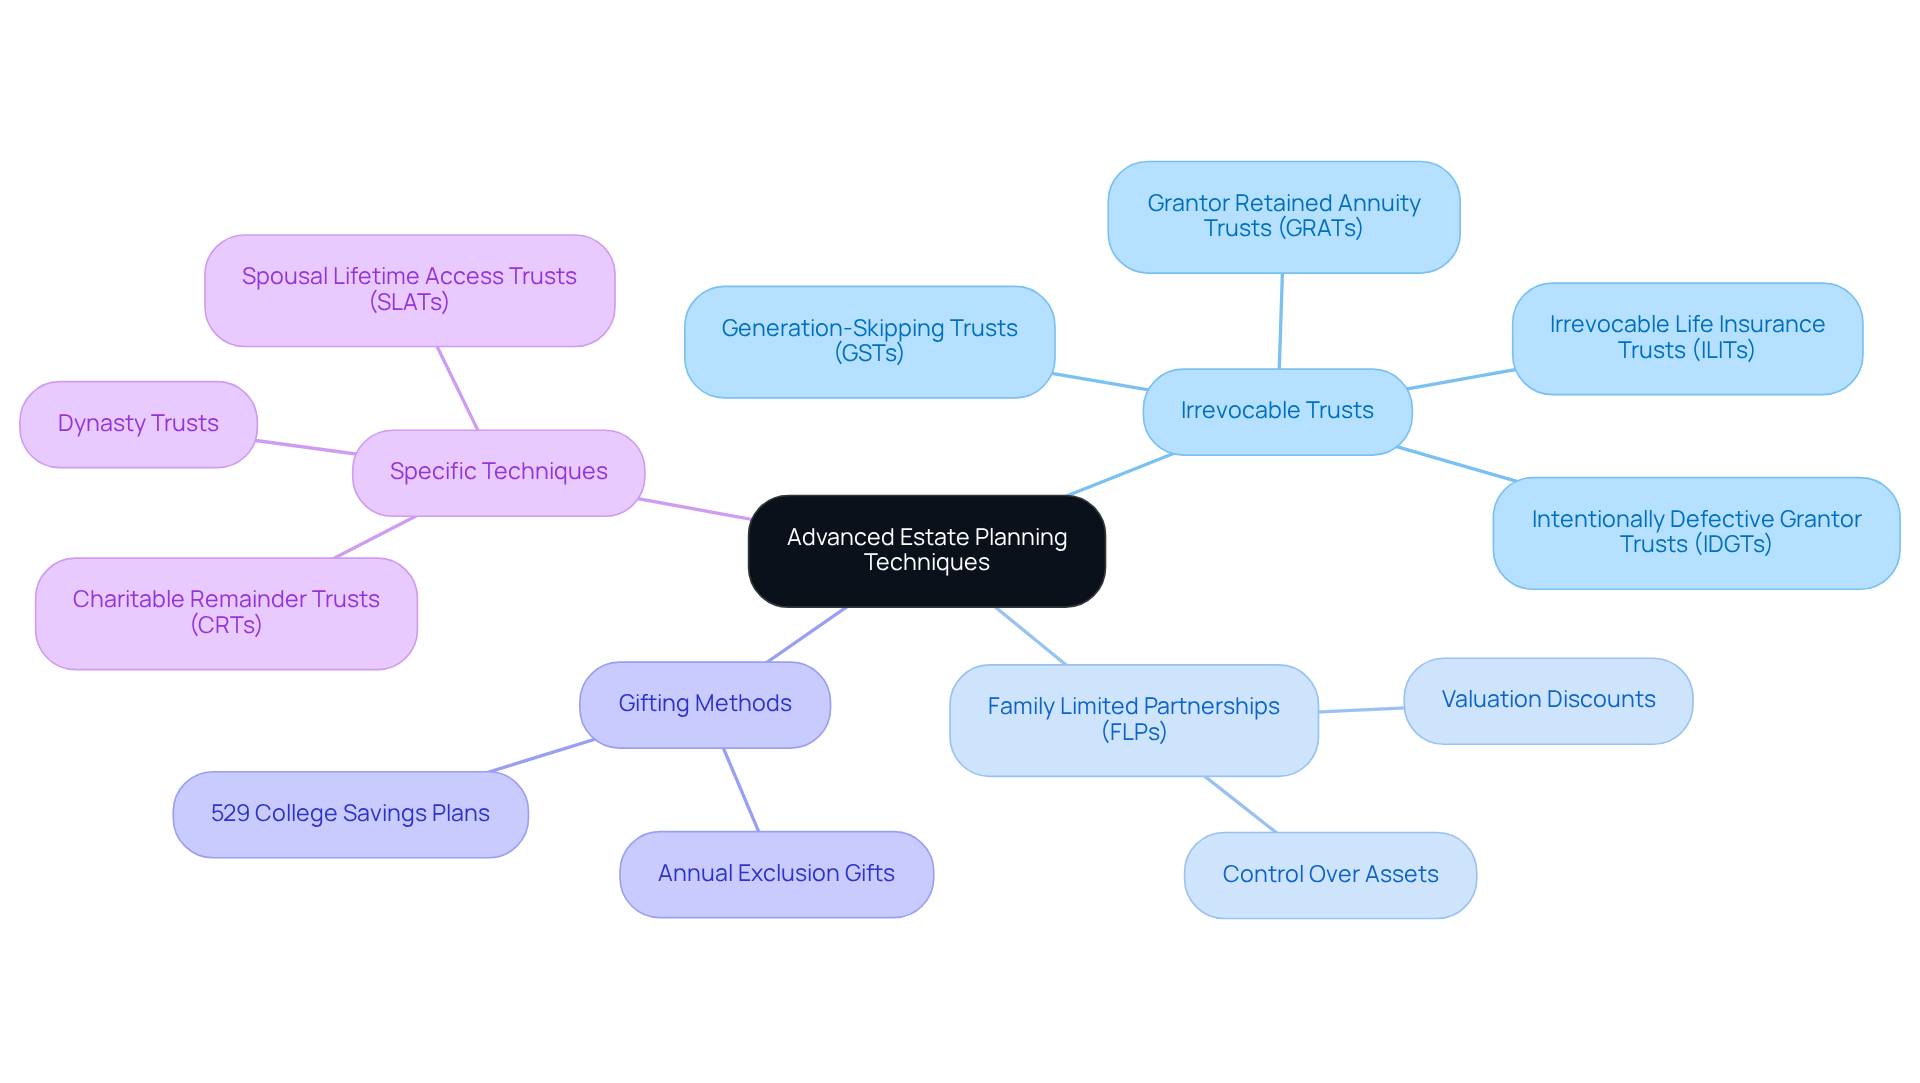
Imagine if you could secure your family’s future while minimizing tax burdens – sounds ideal, right? Advanced estate planning techniques can help high-income families like yours preserve wealth and utilize high income tax planning for executives to reduce tax exposure. One effective approach is creating irrevocable trusts. These trusts can remove assets from your taxable estate, which means lower estate levies. For example, irrevocable life insurance trusts (ILITs) can keep life insurance proceeds out of the estate, ensuring your loved ones receive the full benefit without tax implications.
Family limited partnerships (FLPs) are another valuable tool for wealth transfer. They allow families to maintain control over their assets while benefiting from valuation discounts that can lower estate taxes. Plus, gifting methods – like making annual exclusion gifts to your children or funding 529 college savings plans – can further reduce your taxable estate while providing for future generations. In fact, in 2021, about 52.7% of total gifts were made to trusts, showing how effective these strategies can be.
Consider specific advanced techniques, such as grantor retained annuity trusts (GRATs). These allow you to transfer wealth to your heirs with minimal gift tax implications, as you receive annuity payments for a set term. Similarly, generation-skipping trusts (GSTs) enable families to pass wealth directly to grandchildren, avoiding estate taxes that would typically apply to intermediate generations.
Take Allison and Brian, for example. They were just like many families, working hard but feeling overwhelmed by financial decisions. With Bright Advisers’ help, they discovered how to make their money work for them. Despite their impressive incomes, they were unaware of the financial opportunities they were missing due to insufficient high income tax planning for executives. Through their collaboration with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. By integrating tax strategies into their comprehensive financial plan, they experienced the peace of mind that comes with economic security, allowing them to enjoy more quality time with their loved ones.
By embracing these strategies, you can create a legacy that truly reflects your family’s values and aspirations.
Conclusion
Imagine feeling confident about your family’s financial future as tax changes approach in 2026. These changes can help your family keep more of what you earn, making it easier to plan for the future. But with the right strategies, you can turn these challenges into opportunities for your family’s future.
There are simple steps you can take to make tax time less stressful and more beneficial for your family:
- Think about ways to invest wisely.
- Give back to your community.
- Plan for your family’s future together.
These steps can help lighten your tax load and support your dreams for your children’s education and a secure future.
It’s so important to plan ahead for your family’s financial well-being. With these practices, you can build a future that reflects your family’s values and keeps them secure for years to come. With the right support, you can focus on what truly matters-your family and the memories you create together.
Frequently Asked Questions
What are the upcoming tax law changes for 2026 that families should be aware of?
In 2026, the standard deduction will increase to $16,100 for single filers and $32,200 for married couples filing jointly. Additionally, the state and local tax (SALT) deduction cap will rise to $40,000.
How do these changes benefit families, particularly those in high-tax states?
The increased standard deduction allows households to lower their taxable income, while the higher SALT cap makes itemizing deductions more appealing for families living in high-tax states like California and New York.
Why is it important for families to understand these tax law changes?
Understanding these adjustments is crucial for effective high income tax planning, as they can significantly influence tax liabilities and help families retain more of their income.
What should families consider when navigating these tax changes?
Families should explore ways to align their financial decisions with the new tax landscape to avoid paying more than necessary, which could impact their ability to save for future goals.
How can families prepare for the upcoming tax year in light of these changes?
With the right guidance, families can navigate the changes confidently, ensuring they keep more of what they earn for their loved ones.
List of Sources
- Understand Tax Law Changes for 2026
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Taxes 2025-2026: One Big Beautiful Bill Act Tax Law Changes and How That Impacts You (https://turbotax.intuit.com/tax-tips/general/taxes-2021-7-upcoming-tax-law-changes/L3xFucBvV)
- IRS Releases 2026 Tax Brackets, Contribution Limits, Other Tax Updates | PERA On The Issues (https://copera.org/pera-on-the-issues/irs-releases-2026-tax-brackets-contribution-limits-other-tax-updates)
- 10 tax tips for 2026 | Fidelity (https://fidelity.com/learning-center/personal-finance/tax-tips)
- Implement Tax-Efficient Investment Strategies
- Tax-Loss Harvesting Strategies: How They Work (https://am.gs.com/en-us/advisors/campaign/tax-loss-harvesting-strategies-how-they-work)
- Continuous tax-loss harvesting yields more potential for tax benefits (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/continuous-tax-loss-harvesting-yields-more-potential-for-tax-savings)
- Tax-Loss Harvesting: What Is It and How Does It Work? (https://ml.com/articles/what-is-tax-loss-harvesting.html)
- The Benefits of Tax-Loss Harvesting (https://bairdwealth.com/insights/wealth-management-perspectives/2022/10/taking-advantage-of-tax-loss-harvesting)
- Tax-Loss Harvesting Can Work Year-Round for Investors—Here’s How | Morgan Stanley (https://morganstanley.com/articles/tax-loss-harvesting)
- Leverage Charitable Giving for Tax Benefits
- Why Donating Appreciated Stock Makes Financial Sense (https://ghcf.org/articles/why-donating-appreciated-stock-makes-financial-sense)
- Tax Advantages for Donor-Advised Funds | NPTrust (https://nptrust.org/what-is-a-donor-advised-fund/daf-tax-consideration)
- How large are individual income tax incentives for charitable giving? (https://taxpolicycenter.org/briefing-book/how-large-are-individual-income-tax-incentives-charitable-giving)
- Charitable contributions: tax strategies (https://fidelitycharitable.org/guidance/charitable-tax-strategies/charitable-contributions.html)
- Utilize Advanced Estate Planning Techniques
- Irrevocable Trusts: A Deep Dive into Their Benefits and Limitations (https://sawlaw.com/blog/2025/march/irrevocable-trusts-a-deep-dive-into-their-benefi)
- Trusts: Income and Estate and Gift Tax Issues (https://congress.gov/crs-product/R48879)
- 8 Advanced Estate Planning Strategies – A Complete Guide (https://weiner.law/nj-law-blog/advanced-estate-planning-strategies)
- Four Tips for High Net Worth Estate Planning (https://elefflaw.com/blogs/4-tips-for-high-net-worth-estate-planning)
- Minimizing estate taxes with four types of trusts (https://firstcitizens.com/wealth/insights/estate-planning/how-to-minimize-estate-taxes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading