

Key Highlights
- Maximising contributions to retirement accounts like 401(k)s and IRAs is crucial for reducing taxable earnings.
- In 2026, the 401(k) contribution limit will increase to $24,500, with an additional $8,000 catch-up contribution for those aged 50 and older.
- Roth IRAs and backdoor Roth IRAs allow for tax-free growth and withdrawals, beneficial for families facing income limits.
- Health Savings Accounts (HSAs) offer triple tax benefits: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.
- Higher earners must engage in high income W2 tax planning to make catch-up contributions on a Roth basis starting in 2026.
- Tax-loss harvesting can offset capital gains, potentially saving families significant amounts on their tax bills.
- Charitable contributions of appreciated assets can avoid capital gains taxes while providing a deduction for the asset’s fair market value.
- Income shifting allows families to hire relatives in a business, reducing overall tax burdens while providing work experience.
- Professional tax guidance helps families discover deductions and strategies, ensuring compliance and enhancing savings.
- Integrating tax and estate planning is essential for high-income families to secure their financial future and minimise estate taxes.
- Gifting strategies can reduce taxable estates and allow families to share wealth with heirs during their lifetime.
Introduction
Imagine feeling overwhelmed by tax planning while trying to secure your family’s financial future. Many families feel this way, especially when the stakes are high. When you understand effective tax strategies, you can ease your worries about liabilities and help preserve your family’s wealth for generations to come.
With the right insights, you can unlock opportunities to maximize retirement contributions and integrate tax with estate planning.
So, how can you and your family make the most of these strategies to feel secure and lighten your tax load?
Maximize Retirement Account Contributions
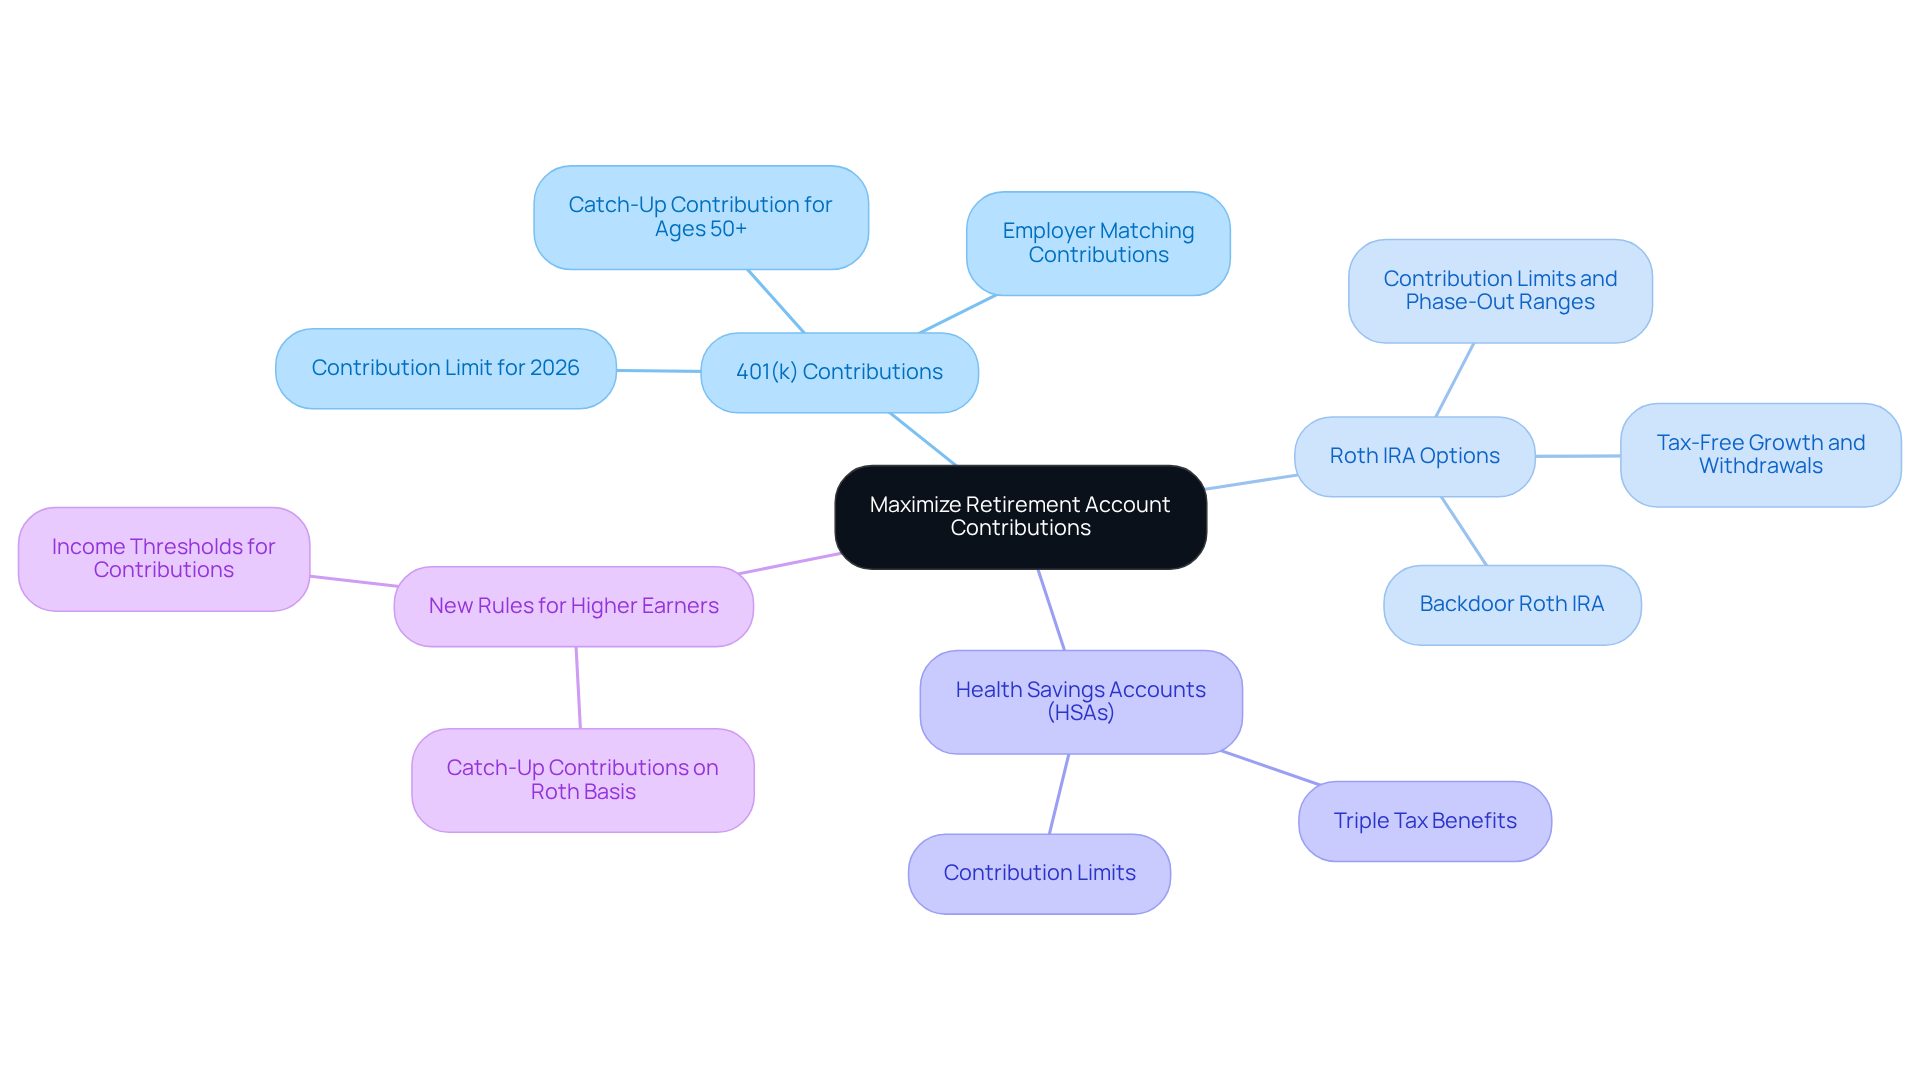
Imagine feeling secure about your family’s financial future while navigating the complexities of retirement planning. For many families, maximizing contributions to retirement accounts like 401(k)s and IRAs can feel overwhelming, but it’s a vital strategy for reducing taxable earnings. In 2026, the contribution limit for 401(k) plans is set to rise to $24,500, with an additional $8,000 catch-up contribution available for those aged 50 and older. By fully utilizing these limits, you can significantly lower your taxable earnings while preparing for a comfortable retirement.
If you find that your income limits direct contributions, consider exploring options like a Roth IRA or a backdoor Roth IRA. These accounts allow for tax-free growth and withdrawals during retirement, helping you lower current tax obligations while ensuring tax-free revenue later. Health Savings Accounts (HSAs) also present a valuable opportunity, offering triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free.
Starting in 2026, there will be new rules for higher earners that will impact high income W2 tax planning, which can feel daunting. It’s important to understand how these changes affect your savings strategy. Higher earners who made more than $150,000 in the prior year will need to engage in high income W2 tax planning to make catch-up contributions on a Roth basis. Understanding these changes can empower families to make informed decisions about their financial future.
Take Emily and Mark, for example. This high-income couple with two young children successfully maximized their 401(k) contributions as part of their high income W2 tax planning and established a backdoor Roth IRA. This method not only reduced their taxable income but also prepared them for a secure retirement, allowing them to focus on their household’s immediate needs. By applying these methods, you can improve your financial security and ensure a successful future for your family.
At Bright Advisers, we’re here to support you with personalized financial planning services, guiding you every step of the way. Please remember that past performance does not guarantee future results, and all investments carry risk. By taking these steps, you can create a brighter financial future for your family, ensuring peace of mind as you navigate life’s journey together.
Implement Advanced Tax Strategies
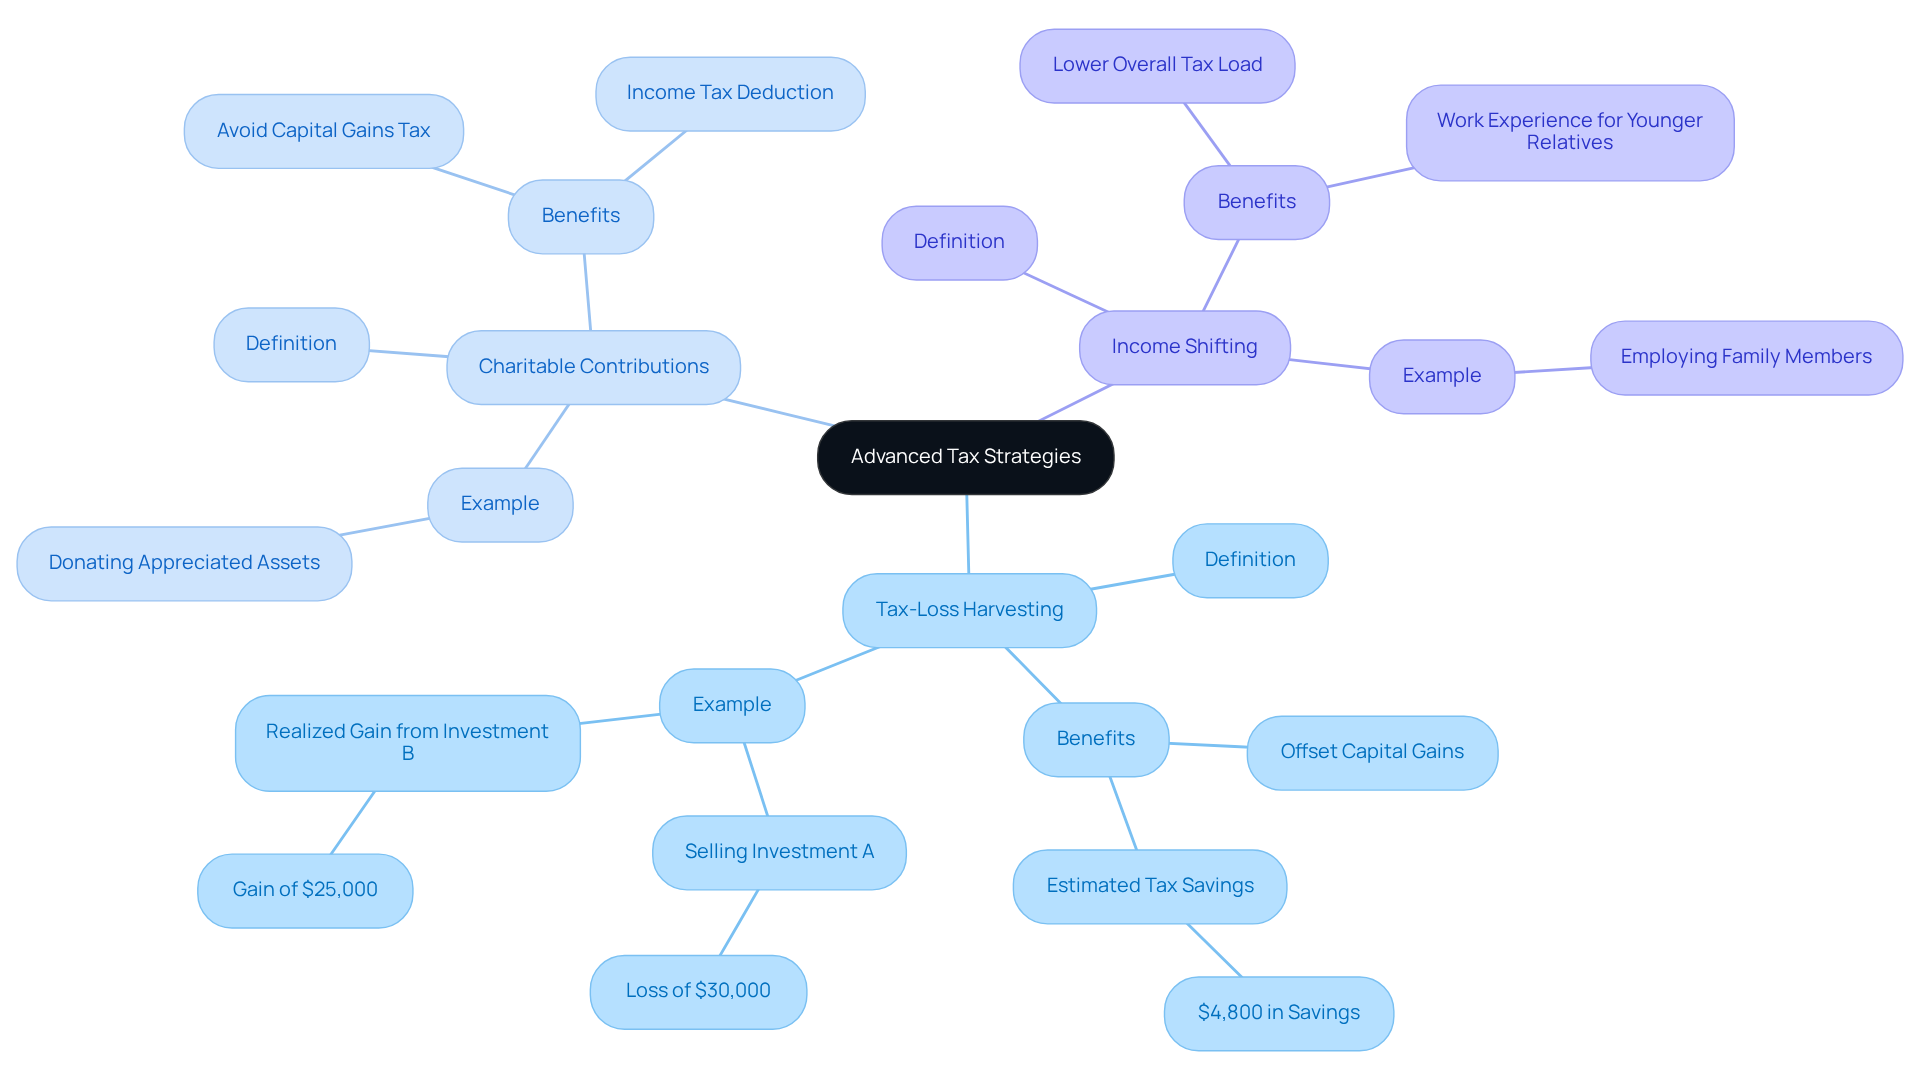
Imagine feeling overwhelmed by taxes while trying to secure your family’s future – you’re not alone in this journey. Affluent families can utilize sophisticated tax methods for high income W2 tax planning to enhance their financial effectiveness, particularly through:
- Tax-loss harvesting
- Charitable contributions
- Income shifting
Tax-loss harvesting shines during market ups and downs, helping families lower their tax bills with realized losses. For instance, if a household sells an investment at a $30,000 loss while realizing a $25,000 gain from another, they can completely offset the gain, leading to no capital gains owed. You might be surprised to learn that this method could save your family around $4,800, combining benefits from capital gains levies and reductions in regular earnings.
Charitable contributions also offer substantial tax benefits. By contributing appreciated assets instead of cash, households can avoid capital gains obligations while receiving a charitable deduction for the asset’s fair market value. This dual benefit not only supports charitable causes but also enhances overall tax efficiency. For example, contributing long-term appreciated stocks enables families to deduct the entire market value from their tax returns, potentially reducing capital gains tax obligations, which can reach as much as 20%.
Income shifting is another effective strategy. Families can hire members in a business operated by relatives, allocating earnings among those in lower tax categories. This approach not only lessens the overall tax load but also offers valuable work experience for younger relatives. For instance, Allison and Brian, who run a small business, employed their teenage children, allowing them to benefit from their lower tax rates while teaching them essential work skills.
By using these smart tax strategies, families can implement high income W2 tax planning to better manage their finances, ensuring they keep more of their hard-earned income while preparing for future generations. By embracing these strategies, you can ensure your family keeps more of what they earn, paving the way for a brighter future together.
Seek Professional Tax Guidance
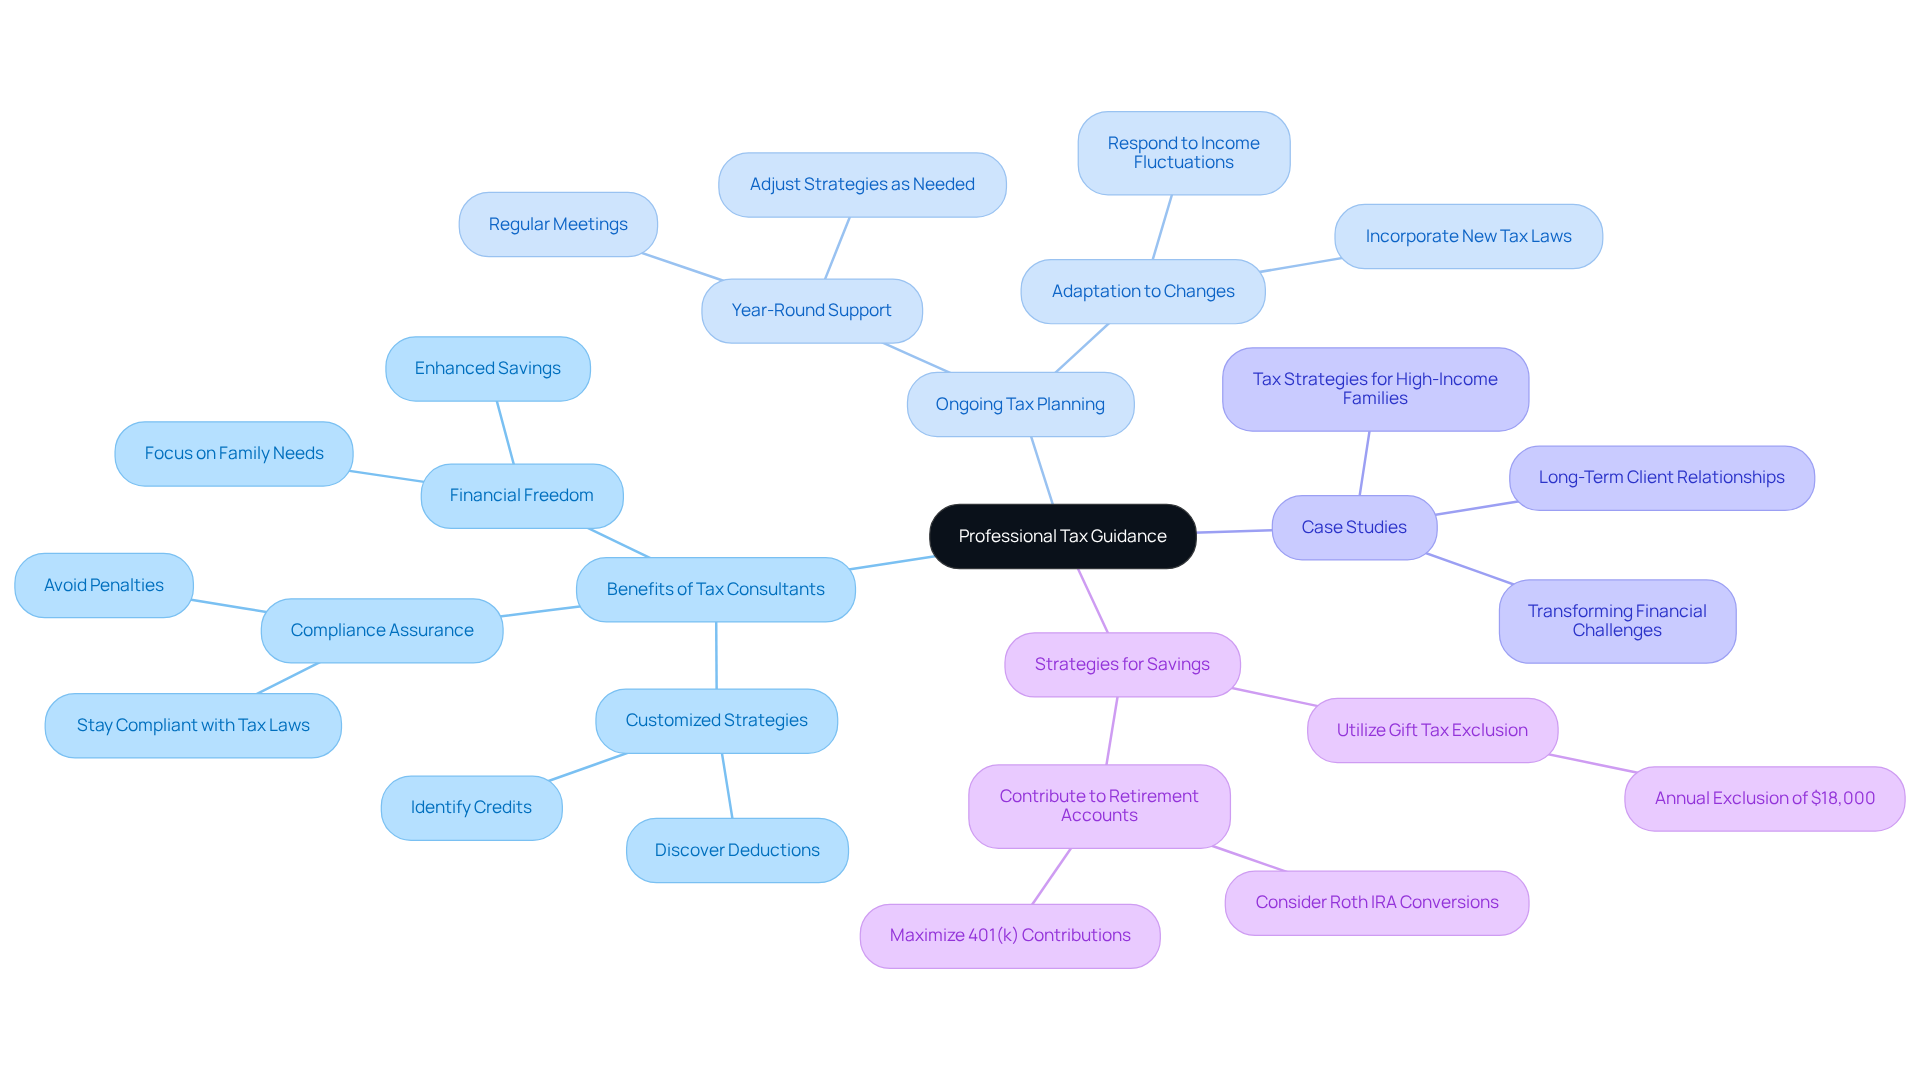
Imagine feeling lost in a sea of tax regulations, unsure of how to maximize your savings. Finding a caring tax expert can make all the difference, providing insights tailored just for your family’s needs. A tax consultant can help you discover deductions, credits, and strategies that might otherwise slip through the cracks, ensuring you stay compliant while enhancing your savings.
Tax professionals assist in year-round tax planning, not just during tax season. This proactive approach empowers you to make informed financial decisions throughout the year, adapting as your circumstances change. For instance, families like Emily and Mark benefit from regular meetings with a tax consultant, who helps them adjust their strategies based on shifts in earnings, tax laws, and family dynamics. This ongoing relationship ensures they remain compliant while fully leveraging available tax benefits.
This means more financial freedom for your family, allowing you to focus on what truly matters. Proactive tax planning enables households to take advantage of the annual gift tax exclusion of $18,000 in 2024, reducing the size of their taxable estate while providing financial support to loved ones.
Case studies further illustrate the benefits of professional tax guidance. Families who have engaged tax professionals report significant savings and improved financial management. For example, one household saved thousands through customized strategies that allowed them to enjoy their financial success with lower tax obligations. This organized method of tax planning not only helps families navigate their current financial situation but also equips them for upcoming financial challenges. With the right support, you can navigate these challenges and secure a brighter financial future for your family.
Integrate Tax and Estate Planning
Imagine the worry of leaving your loved ones with financial burdens instead of a legacy. For high-income families, high income W2 tax planning integrated with estate planning is not just a necessity; it’s a way to ensure your family’s future is secure and thriving.
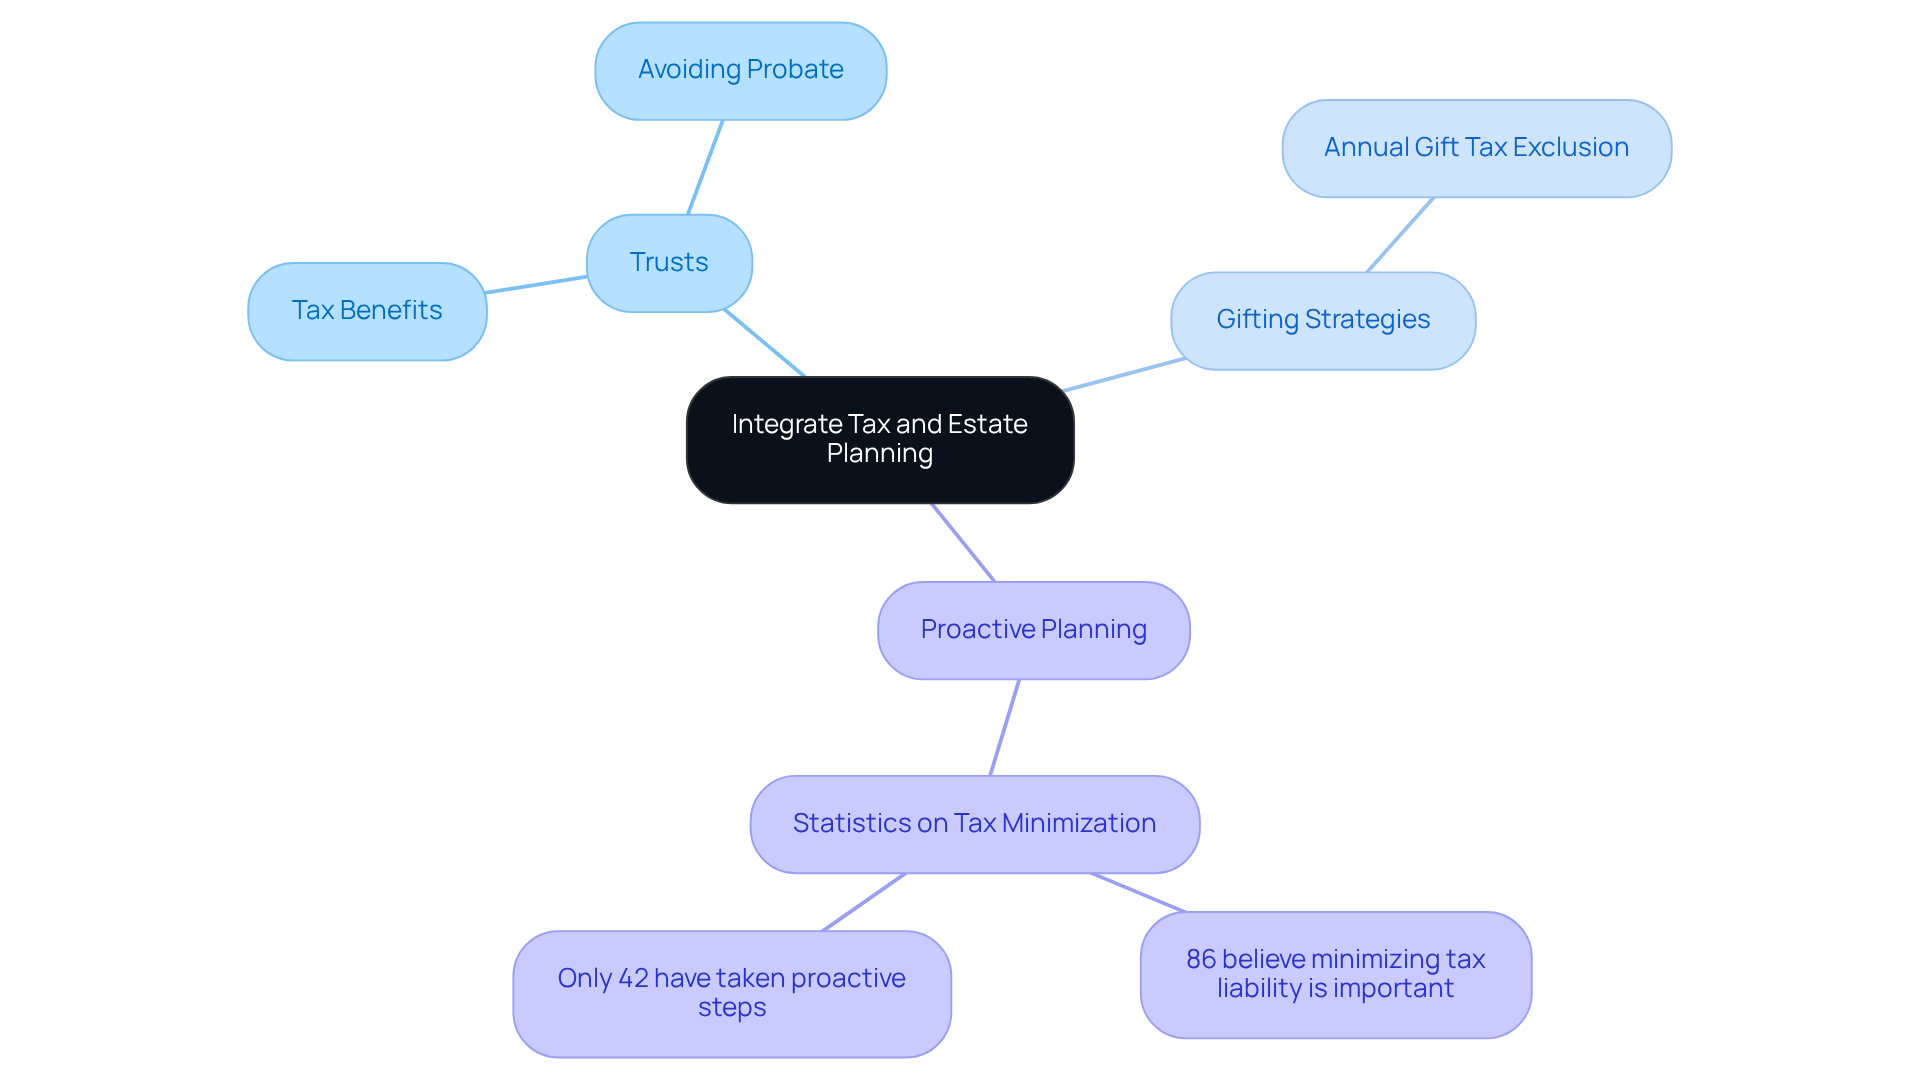
Think of trusts as a protective shield for your family’s future, offering both tax benefits and peace of mind. These trusts can help reduce estate taxes and ensure that your assets are passed on to your heirs without the hassle of probate.
You can also consider gifting strategies to lighten your taxable estate. By gifting assets to your heirs during your lifetime, you can take advantage of the annual gift tax exclusion of $15,000 per recipient. This not only lowers your estate tax burden but also allows you to share your wealth while you’re still around to see the impact.
Take Allison and Brian, for example. This high-income couple utilized high income W2 tax planning by working with Bright Advisers to set up a family trust and began gifting assets to their children. Their proactive approach not only reduced their taxable estate but also helped instill financial literacy in their kids, preparing them for future wealth management. Through their partnership with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner.
Did you know that while many people recognize the importance of minimizing taxes, only a fraction have taken action? You’re not alone in this journey. Statistics show that 86% of individuals believe minimizing tax liability is important, yet only 42% have taken proactive steps to minimize taxes through planning. With the upcoming changes to the federal estate tax exemption in 2026, it’s more important than ever for families to engage in tax and estate planning to safeguard their financial future.
With the right planning, you can ensure your family thrives, not just survives, in the future. We’re here for you, ready to help you navigate this journey together.
Conclusion
Imagine feeling secure about your family’s financial future while navigating the complexities of tax planning. Maximizing tax efficiency is essential for high-income W-2 families like yours. By implementing effective strategies – such as maximizing retirement account contributions and utilizing advanced tax techniques – you can significantly reduce your tax burdens and prepare for a prosperous future.
Many families feel overwhelmed by the complexities of tax regulations and how they impact their financial future. But there’s hope! By maximizing contributions to retirement accounts like 401(k)s and IRAs, employing strategies like tax-loss harvesting and charitable contributions, and engaging tax professionals for tailored advice, you can take control of your financial journey. Integrating tax and estate planning not only helps minimize your tax liabilities but also allows you to create a lasting legacy for your loved ones.
It’s important to understand how these practices can truly impact your family’s financial journey. As tax regulations evolve, staying informed and proactive in your planning efforts is vital. By partnering with Bright Advisers, you can navigate the complexities of tax planning with confidence, ensuring you keep more of your hard-earned income. Embrace these strategies today to pave the way for a legacy of financial well-being for your loved ones.
Frequently Asked Questions
What is the importance of maximizing retirement account contributions?
Maximizing contributions to retirement accounts like 401(k)s and IRAs is vital for reducing taxable earnings and preparing for a comfortable retirement.
What are the contribution limits for 401(k) plans in 2026?
In 2026, the contribution limit for 401(k) plans is set to rise to $24,500, with an additional $8,000 catch-up contribution available for individuals aged 50 and older.
What options are available if income limits restrict direct contributions to retirement accounts?
If income limits restrict direct contributions, options like a Roth IRA or a backdoor Roth IRA can be explored, allowing for tax-free growth and withdrawals during retirement.
What are the benefits of Health Savings Accounts (HSAs)?
HSAs offer triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free.
How will new rules in 2026 affect higher earners regarding retirement contributions?
Starting in 2026, higher earners who made more than $150,000 in the prior year will need to engage in high income W-2 tax planning to make catch-up contributions on a Roth basis.
Can you provide an example of how a family can benefit from maximizing retirement contributions?
Emily and Mark, a high-income couple with two young children, maximized their 401(k) contributions and established a backdoor Roth IRA, which reduced their taxable income and prepared them for a secure retirement.
What services does Bright Advisers offer to families regarding financial planning?
Bright Advisers provides personalized financial planning services to support families in making informed decisions about their financial future.
Are there any disclaimers regarding investment performance and risks?
Yes, it is important to remember that past performance does not guarantee future results, and all investments carry risk.
List of Sources
- Maximize Retirement Account Contributions
- IRS Increases 401(k) and IRA Contribution Limits for 2026 | Windes (https://windes.com/401k-ira-contribution-limits)
- Catch-Up Contributions 2025 and 2026 (https://schwab.com/learn/story/what-to-know-about-catch-up-contributions)
- 401(k) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- 401(k) Contribution Limits for Highly Compensated Employees in 2026 (https://epwealth.com/blog/401k-contribution-limits-for-highly-compensated-employees)
- Implement Advanced Tax Strategies
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Charitable contributions: tax strategies (https://fidelitycharitable.org/guidance/charitable-tax-strategies/charitable-contributions.html)
- What Is Tax-Loss Harvesting? | Russell Investments (https://russellinvestments.com/us/blog/what-is-tax-loss-harvesting)
- Wealthfront Tax-Loss Harvesting | Wealthfront Whitepapers (https://research.wealthfront.com/whitepapers/tax-loss-harvesting)
- Seek Professional Tax Guidance
- The Benefits of Year-Round Tax Planning (https://mccarthylebit.com/the-benefits-of-year-round-tax-planning)
- High-Income Tax Strategist vs. Tax Preparer: Which One Do You Need? (https://ratiocpa.com/high-income-tax-strategist-vs-tax-preparer-which-one-do-you-need)
- U.S. Bureau of Labor Statistics (https://bls.gov/oes/2023/may/oes132082.htm)
- Beyond Tax Season: The Value of Year-Round Tax Planning (https://mgocpa.com/perspective/year-round-tax-planning)
- High Net Worth Tax Services | High Net Worth Accountants | TPI Group (https://tpigroupinc.com/industries/high-net-worth-individuals-families)
- Integrate Tax and Estate Planning
- 50 Estate Planning Statistics and Facts You Need to Know (https://justvanilla.com/blog/estate-planning-statistics-and-facts-you-need-to-know)
- The Estate Tax After the 2017 Tax Act | Baker Institute (https://bakerinstitute.org/research/estate-tax-after-2017-tax-act)
- 18 Stats to Know from Vanilla’s 2025 State of Estate Planning Report (https://justvanilla.com/blog/estate-planning-statistics-2025)
- Estate Planning Statistics (https://stoufferlegal.com/blog/estate-planning-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading