

Key Highlights
- Age-based asset allocation adjusts investment mixes as individuals grow older, with younger investors typically favouring stocks for growth.
- As retirement approaches, it’s crucial to shift towards conservative investments, such as bonds and cash, to protect accumulated wealth.
- Risk tolerance varies among families; those with higher savings may feel more comfortable taking investment risks.
- Diversification spreads investments across various asset classes to mitigate risk and enhance returns, tailored to each family’s unique goals.
- Regular monitoring and rebalancing of portfolios are essential to maintain alignment with financial objectives, with families encouraged to review allocations every six to twelve months.
- Bright Advisers offers personalised investment plans to help families navigate financial uncertainties and achieve long-term security.
Introduction
Imagine feeling confident about your family’s financial future as you navigate the complexities of retirement planning. As you move through different stages of life, it’s important to adjust your investment strategies to match your family’s changing needs. Together, we can explore how to allocate your retirement assets wisely, ensuring your family’s financial security as you grow and change. With the right support, you can ensure your retirement plans truly reflect your family’s evolving needs.
Understand Age-Based Asset Allocation Principles
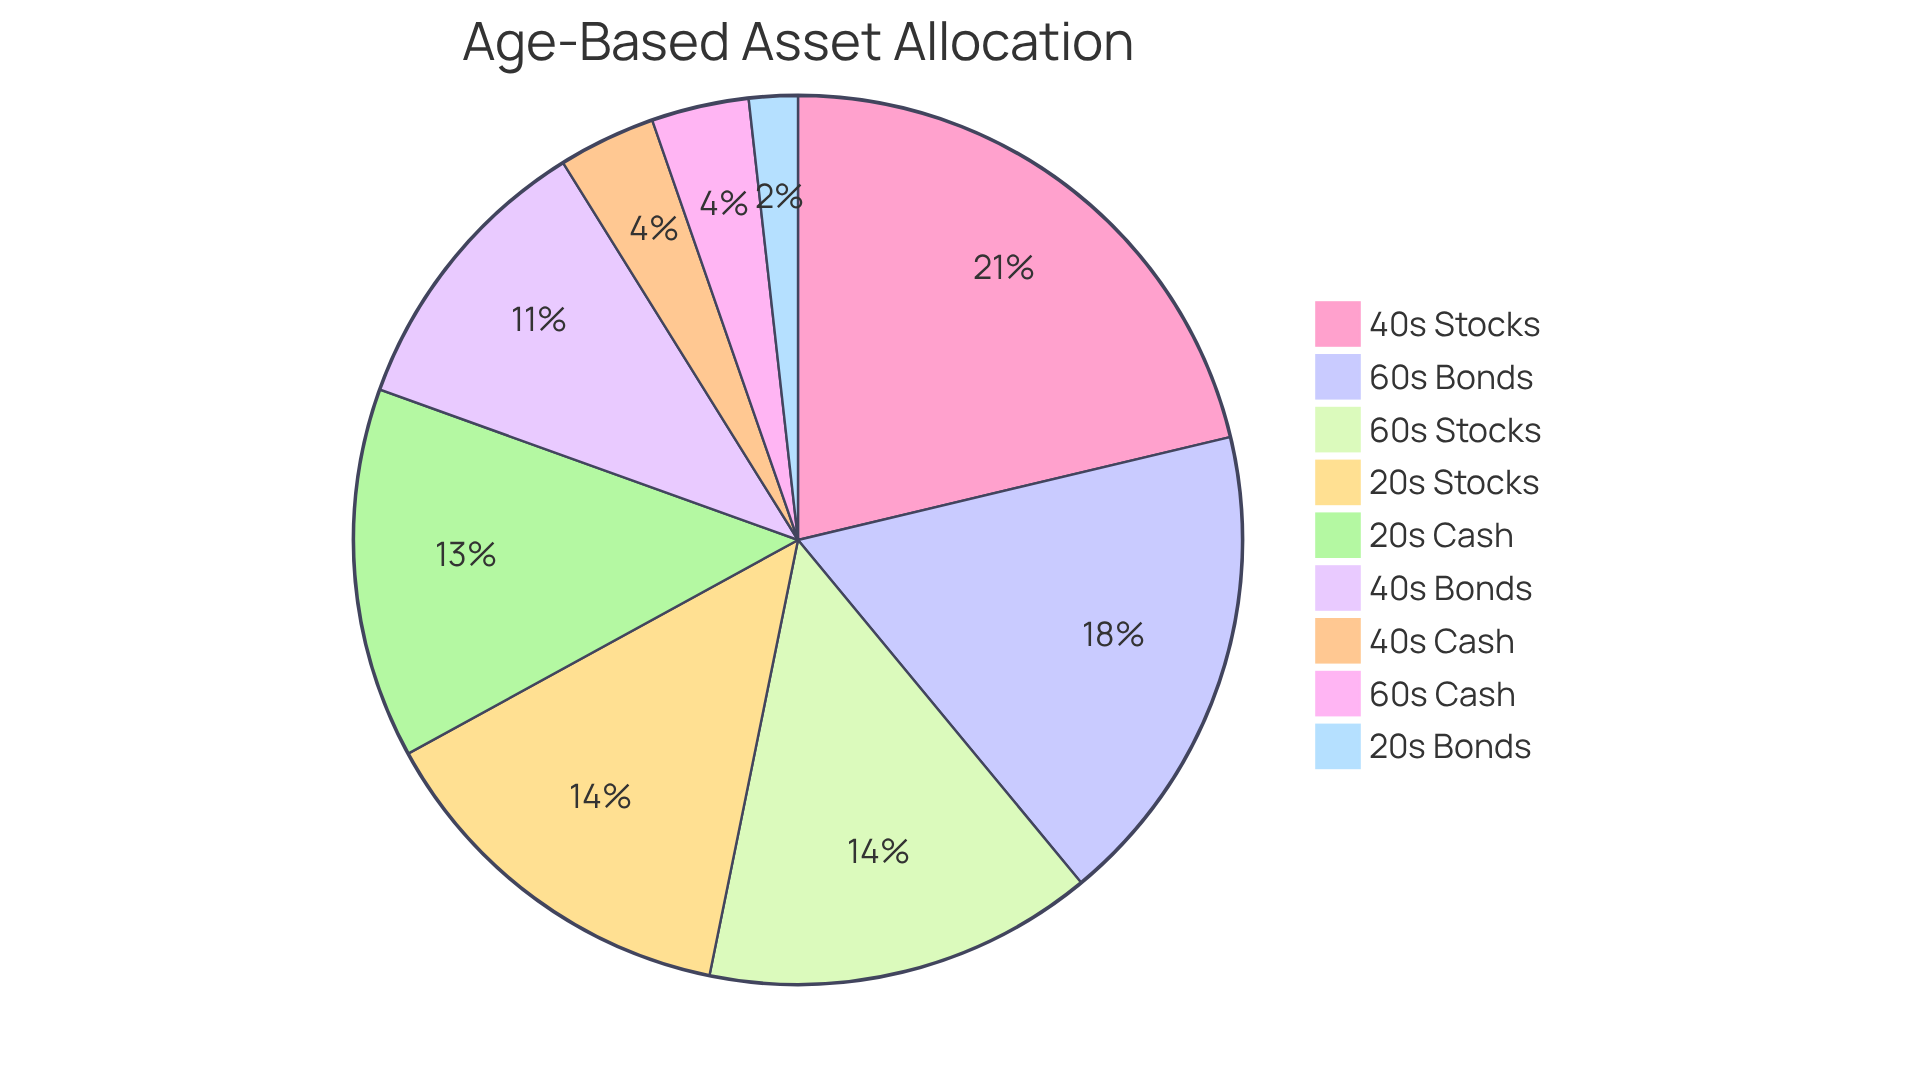
Imagine the peace of mind that comes from knowing your family’s financial future is secure, even as you navigate the challenges of parenthood. The strategy of retirement account asset allocation by age adjusts your investment mix as you grow older. For example, young investors in their 20s often choose to put 37-41% of their money into U.S. stocks, while keeping about 8% in international stocks. This approach allows them to take on more risk, aiming for growth during their longer time horizon for recovery from market fluctuations.
As you approach retirement in your 50s and 60s, it’s important to gradually shift towards more conservative investments to protect what you’ve built. For instance, a 40-year-old might consider a strategy that includes 60% bonds, 30% stocks, and 10% cash, focusing on stability and income. By the time you reach 60, the ‘100 minus age’ rule suggests that 40% of your investments should be in stocks, reflecting a more cautious approach as retirement nears.
It’s common for young parents to feel anxious about securing their family’s future in the face of financial uncertainties. Many retirees find comfort in holding around 40.5% of their assets in cash, providing a safety net as they age. This transition is crucial for managing uncertainty and ensuring that your portfolio can meet your income needs during retirement.
Consider the story of a moderate investor who allocates 60% to stocks and 35% to bonds over a decade, balancing growth with controlled exposure. In contrast, an aggressive investor might hold 95% in stocks, chasing maximum growth despite the higher volatility.
By understanding retirement account asset allocation by age, you can confidently take steps toward a secure retirement, ensuring your family’s needs are met for years to come. Together, we can navigate this journey, aligning your financial strategies with your family’s changing priorities.
Assess Risk Tolerance and Time Horizon for Effective Planning
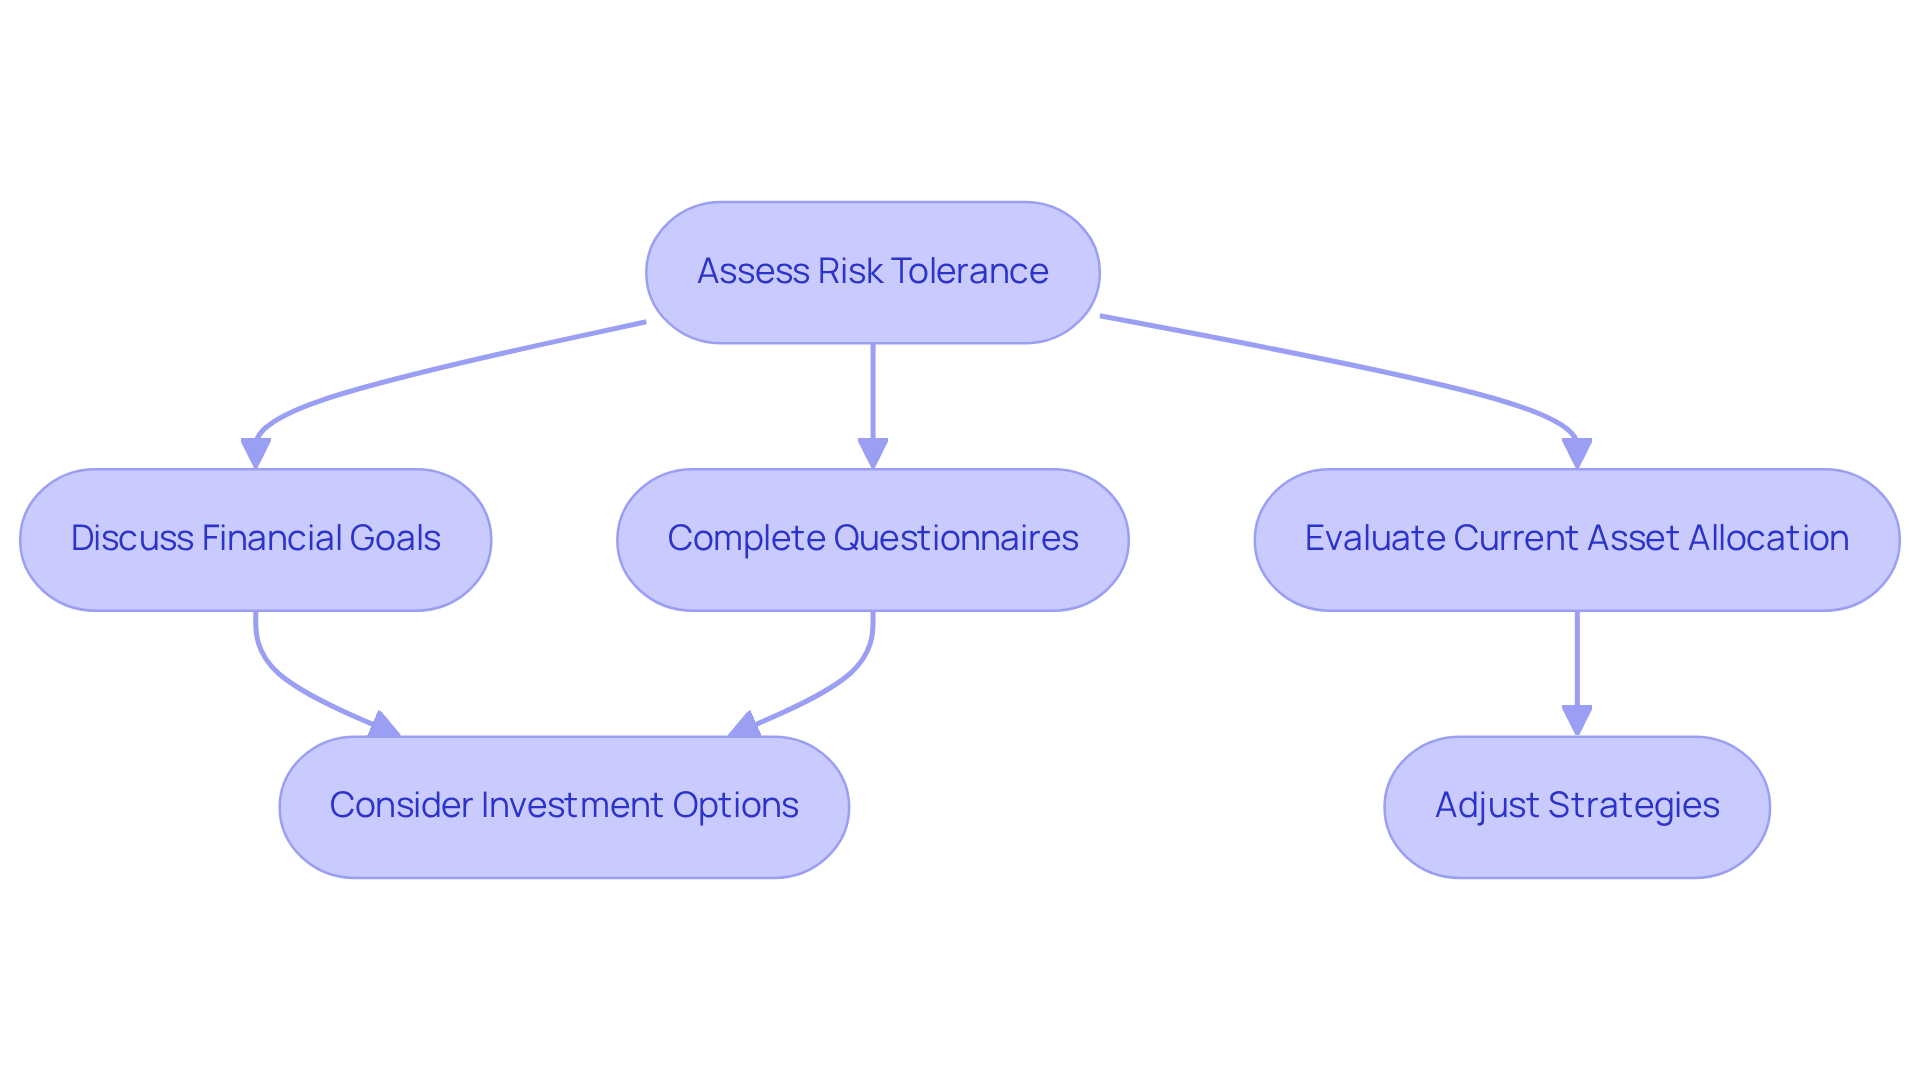
Imagine feeling uncertain about your family’s financial future as retirement approaches. It’s important to think about how much risk you’re comfortable with and how long you have until retirement. Risk tolerance is simply how much ups and downs in your investments you can handle without feeling stressed. Families with a greater willingness to accept uncertainty may choose to invest more heavily in stocks, while those who prefer a steadier approach might lean towards bonds or cash equivalents.
Talking about your financial goals and using simple questionnaires can help you figure out what feels right for your family. Did you know that only 31% of families feel good about their retirement savings? This shows that many families are feeling uncertain about their financial future, which can be stressful. It’s essential to regularly check in on your retirement account asset allocation by age and risk tolerance as your financial goals and situations change.
Interestingly, families with more savings often feel more comfortable taking risks with their investments. This means that as you build your wealth, you might find it easier to explore opportunities that could lead to greater gains. Regularly evaluating your risk tolerance and adjusting your investment strategies can help you effectively navigate the complexities of retirement account asset allocation by age.
At Bright Advisers, we create personalized investment plans that help you save on fees and make the most of your money. We invite families interested in our services to join our current client waitlist. Please remember that past performance doesn’t guarantee future results, and all financial activities come with some level of uncertainty. Our advisory services are offered through Lifeworks Advisors, a registered financial adviser, ensuring compliance and transparency.
Diversify Investments to Mitigate Risk and Enhance Returns
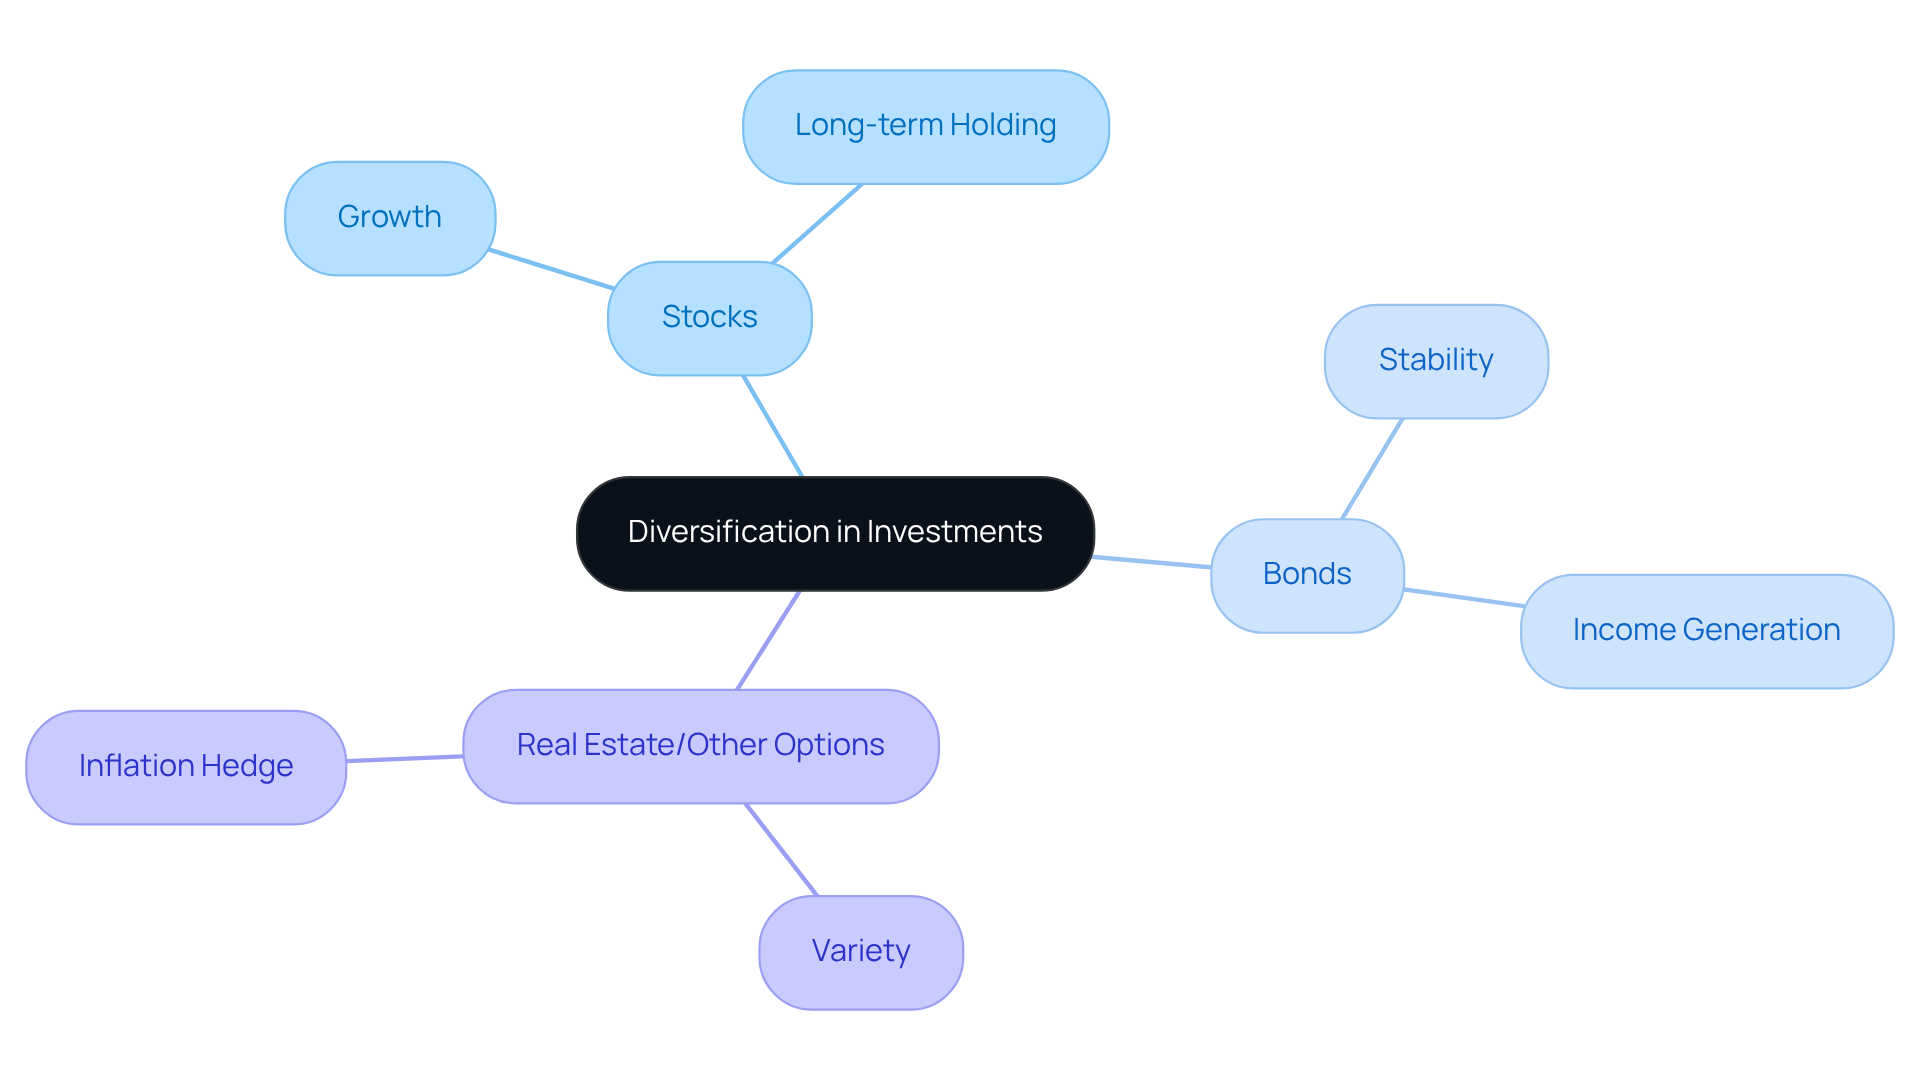
Imagine feeling overwhelmed by financial decisions, unsure of how to secure your family’s future. Diversification is like a safety net for your family’s finances, spreading your investments across various areas to help protect against unexpected downturns. Think of a balanced approach: putting a good portion into stocks for growth, some into bonds for stability, and a little into real estate or other options for variety.
At Bright Advisers, we understand that every family is unique. That’s why we create personalized portfolios that align with your household’s financial goals. Many financial experts are realizing how important it is to diversify, with more and more families choosing to spread their investments for better security. This proactive approach is especially important as families navigate the complexities of planning for the future.
Case studies show that effective diversification strategies can lead to peace of mind. For instance, families like Jay and Emma found relief from financial stress by adopting a varied approach to asset allocation. They learned that while spreading out investments is wise, too much can make things confusing and might not give the best results.
It’s crucial to regularly assess your asset distribution to ensure it aligns with your family’s goals and comfort levels. By embracing a diversified approach, families can find peace of mind and confidence in their financial journey. Together, we can navigate this journey, improving your financial resilience and preparing for future generations. By adopting these strategies, families can build a brighter financial future for generations to come, knowing they have the support of Bright Advisers every step of the way.
Monitor and Rebalance Your Portfolio Regularly
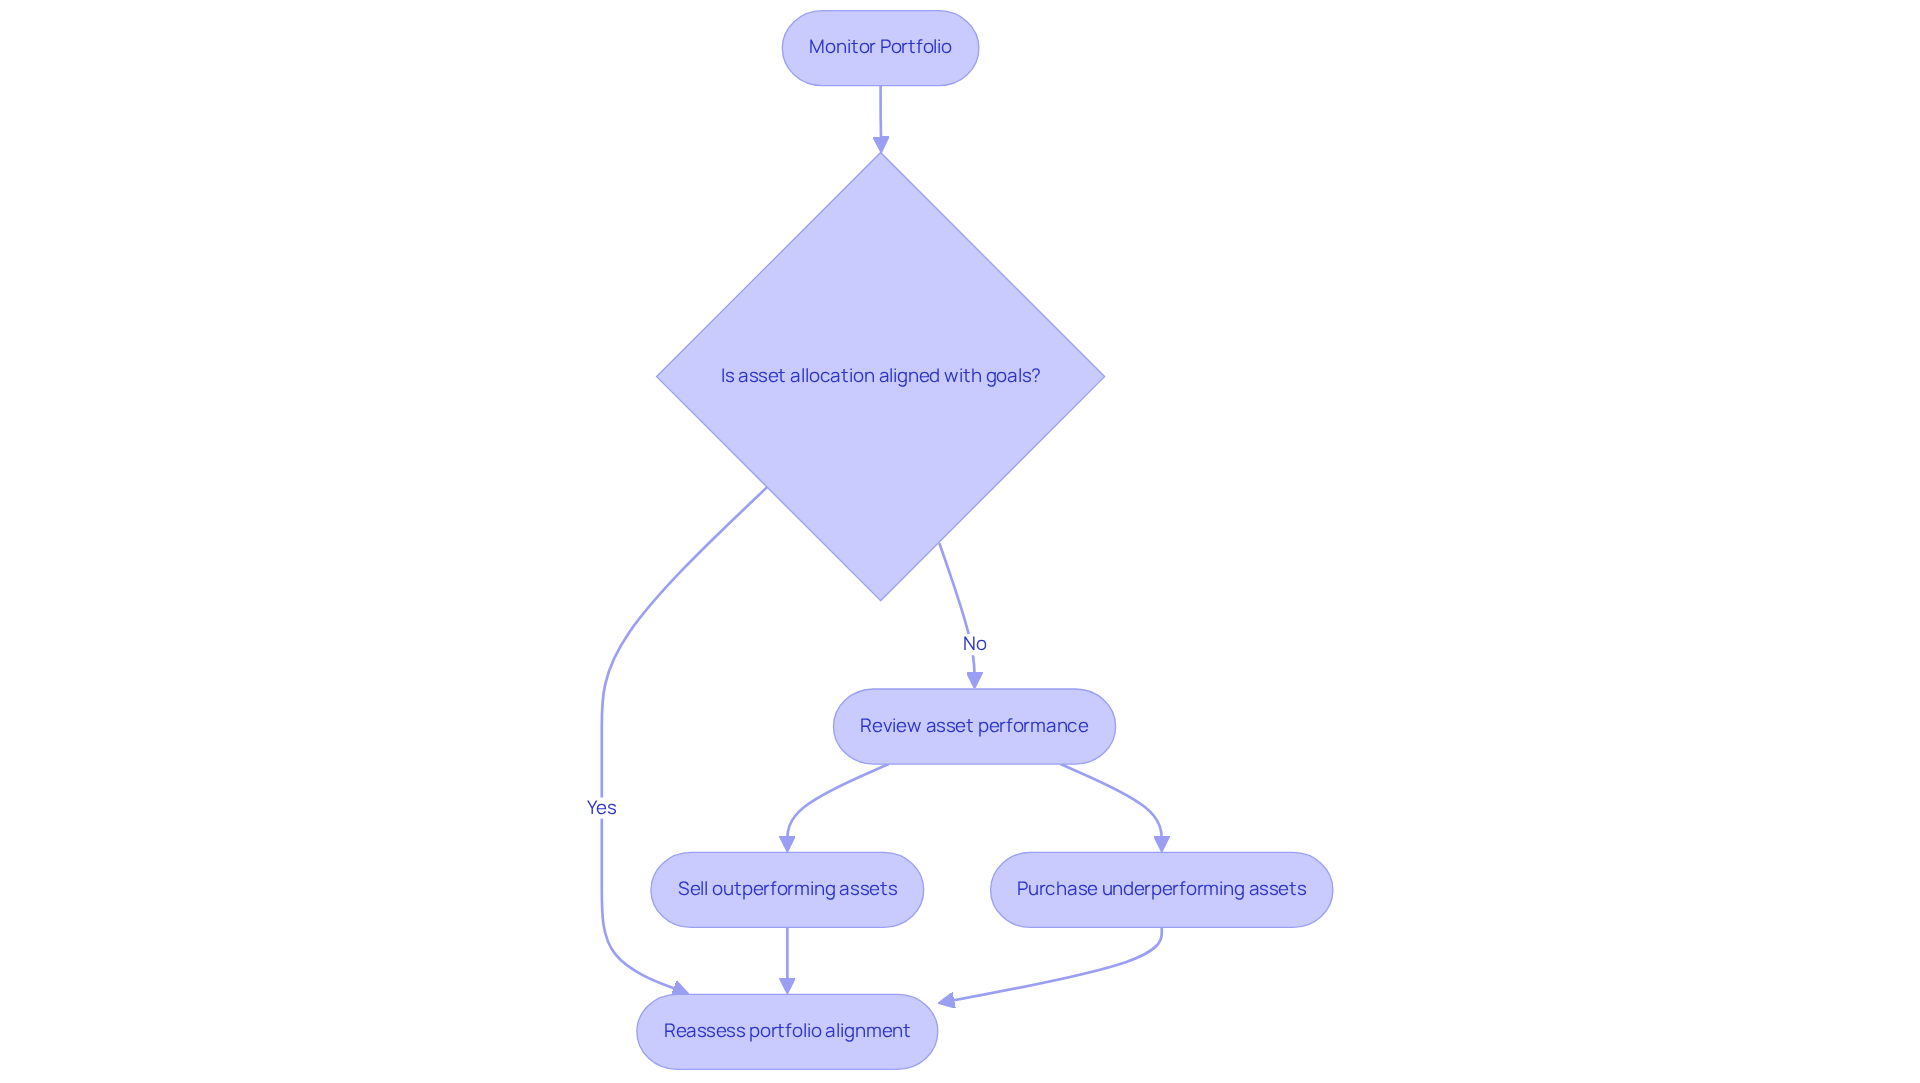
Imagine the stress of watching your investments drift away from your goals as market conditions change. Regularly checking in on your retirement account asset allocation by age is essential for families to ensure they’re still on track with their goals. Over time, certain assets may outperform others, leading to an imbalance. For instance, if stocks exceed the performance of bonds, your investment mix might become too concentrated in equities, increasing risk exposure. Families should review their retirement account asset allocation by age every six to twelve months and adjust their holdings to align with their original investment strategy. This process may involve selling some of the outperforming assets and purchasing more of the underperforming ones to restore balance.
You might be surprised to learn that families who rebalance their investments quarterly often see returns around 8.91%, while those who do it annually see slightly better at 8.97%. This highlights the potential benefits of more frequent rebalancing. Furthermore, maintaining a disciplined strategy for managing investments is crucial for long-term success. Frequent rebalancing not only helps manage uncertainty but also enables households to take advantage of emerging investment prospects as they arise.
Case studies illustrate the effectiveness of these practices. For example, households that followed a structured rebalancing timetable were able to safeguard gains and capitalize on opportunities in undervalued assets, leading to more stable growth in their investments. Together, by keeping an eye on your investments and making adjustments, you can feel more secure in reaching your family’s financial dreams.
Conclusion
Navigating retirement planning can feel overwhelming, but it doesn’t have to be a lonely journey. As families grow and change, it’s important to adapt your investment strategies to feel secure and confident in your future. This journey can nurture growth in your early years while ensuring stability and peace of mind as retirement draws near.
It’s essential to understand your comfort with risk, explore different investment options, and check in on your progress regularly. As life unfolds, your feelings about risk might shift, and that’s perfectly okay. Adjusting your strategies can help you feel more secure about your retirement.
Having a mix of investments can help protect your family from market ups and downs, and checking in on your portfolio keeps you on track with your dreams. Together, we can navigate this journey toward a secure retirement, making it a shared experience for your family.
We’re here to support you in embracing these strategies, regularly checking in on your financial situation, and finding trusted advisors who can guide you along the way. Taking these steps together can pave the way for a brighter financial future for your family.
Frequently Asked Questions
What is age-based asset allocation?
Age-based asset allocation is a strategy that adjusts your investment mix as you grow older, allowing you to manage risk and align your investments with your financial goals at different life stages.
How should young investors in their 20s allocate their assets?
Young investors in their 20s typically allocate 37-41% of their money into U.S. stocks and about 8% into international stocks, allowing them to take on more risk for potential growth.
What changes should be made to asset allocation as one approaches retirement?
As individuals approach retirement in their 50s and 60s, they should gradually shift towards more conservative investments, such as increasing the percentage of bonds and cash to protect their accumulated wealth.
What is the ‘100 minus age’ rule?
The ‘100 minus age’ rule suggests that by the time you reach 60, 40% of your investments should be in stocks, reflecting a more cautious approach as retirement nears.
How do retirees typically manage their asset allocation?
Many retirees find comfort in holding around 40.5% of their assets in cash, providing a safety net as they age and ensuring they can meet their income needs during retirement.
Can you provide an example of different investment strategies?
A moderate investor might allocate 60% to stocks and 35% to bonds for balanced growth, while an aggressive investor might hold 95% in stocks, seeking maximum growth despite higher volatility.
Why is understanding retirement account asset allocation important?
Understanding retirement account asset allocation by age helps individuals confidently take steps toward a secure retirement, ensuring their family’s financial needs are met over time.
List of Sources
- Understand Age-Based Asset Allocation Principles
- Retirement savings by age: What to do with your portfolio in 2026 (https://troweprice.com/personal-investing/resources/insights/retirement-savings-by-age-what-to-do-with-your-portfolio.html)
- What is the average asset allocation by age? (https://empower.com/the-currency/money/average-portfolio-mix-by-investor-age)
- Best Asset Allocation at Different Ages (https://boldin.com/retirement/best-asset-allocation-at-different-ages)
- The Best Investment Strategies by Age (https://navyfederal.org/makingcents/investing/investing-by-age.html)
- Retirement Portfolio Assets: Allocation by Age (https://schwab.com/learn/story/retirement-portfolio-assets-allocation-by-age)
- Assess Risk Tolerance and Time Horizon for Effective Planning
- 50+ Essential Retirement Statistics for 2026: Demographics & More (https://annuity.org/retirement/retirement-statistics)
- How Much Does Risk Tolerance Change? – PMC (https://pmc.ncbi.nlm.nih.gov/articles/PMC4276321)
- Risk tolerance and household wealth–Evidence from Chinese households (https://sciencedirect.com/science/article/abs/pii/S0264999319319868)
- What Is Risk Tolerance and How Can You Determine Yours? (https://ml.com/articles/what-is-risk-tolerance.html)
- Risk Tolerance: What It Is and How You Can Measure Yours (https://privatebank.bankofamerica.com/articles/what-is-risk-tolerance.html)
- Diversify Investments to Mitigate Risk and Enhance Returns
- 2025 Family Office Report: Trends, Statistics, and Insights (https://privatebank.bankofamerica.com/articles/family-office-report.html)
- 90 Warren Buffet Quotes to Inspire Your Investing Journey (https://sarwa.co/blog/warren-buffett-quotes)
- Family Office Statistics 2026: Key Data & Trends | TFOA (https://tfoa.info/family-office-statistics)
- Four Family Office Trends to Watch in 2025 (https://bfinance.com/us/insights/four-family-office-trends-to-watch-in-2025)
- Monitor and Rebalance Your Portfolio Regularly
- How Often Should I Rebalance My Portfolio? – Retirement Researcher (https://retirementresearcher.com/rebalancing-frequency)
- Family office portfolio rebalancing – Guides (https://andsimple.co/guides/family-office-portfolio-rebalancing)
- Importance of Monitoring & Rebalancing Your Portfolio (https://ffin.com/articles-financial-education/rebalancing-your-portfolio)
- Value of an advisor: A is for the Active Rebalancing of investment portfolios | Russell Investments (https://russellinvestments.com/us/blog/a-is-for-active-rebalancing)
- Staying on Track: The Importance of Portfolio Rebalancing | Hofer Family Wealth Advisors | Westbrook, CT | Janney (https://advisor.janney.com/hoferfamilywealthadvisors/news-and-commentary/articles/the-importance-of-portfolio-rebalancing)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading