

Key Highlights
- Maximising contributions to retirement accounts like 401(k)s and IRAs can significantly lower taxable income, with limits increasing in 2026.
- Health Savings Accounts (HSAs) offer a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for medical expenses.
- For 2026, HSA contribution limits are $4,400 for individuals and $8,750 for households, with an additional $1,000 for those aged 55 and older.
- Charitable contributions can lower taxable income, with single filers able to deduct up to $1,000 and married couples up to $2,000 in 2026.
- Tax-loss harvesting allows families to offset capital gains with losses, reducing taxable income and easing tax burdens.
- In 2026, households can offset up to $3,000 of ordinary income with capital losses, which can help manage tax liabilities.
Introduction
Imagine feeling overwhelmed by tax planning while trying to secure your family’s future. Navigating the complexities of tax planning can be daunting for young parents, but it doesn’t have to be. With the right strategies, you can significantly reduce your tax liabilities and build a solid foundation for long-term wealth.
Let’s dive into four simple strategies that can help your family thrive financially:
- Maximizing retirement contributions
- Utilizing Health Savings Accounts
- Incorporating charitable contributions
- Implementing tax-loss harvesting
These strategies not only lighten your financial load but also teach your children the value of smart financial choices. Together, we can navigate this journey toward a more secure future for your family.
Maximize Retirement Contributions to Reduce Taxable Income
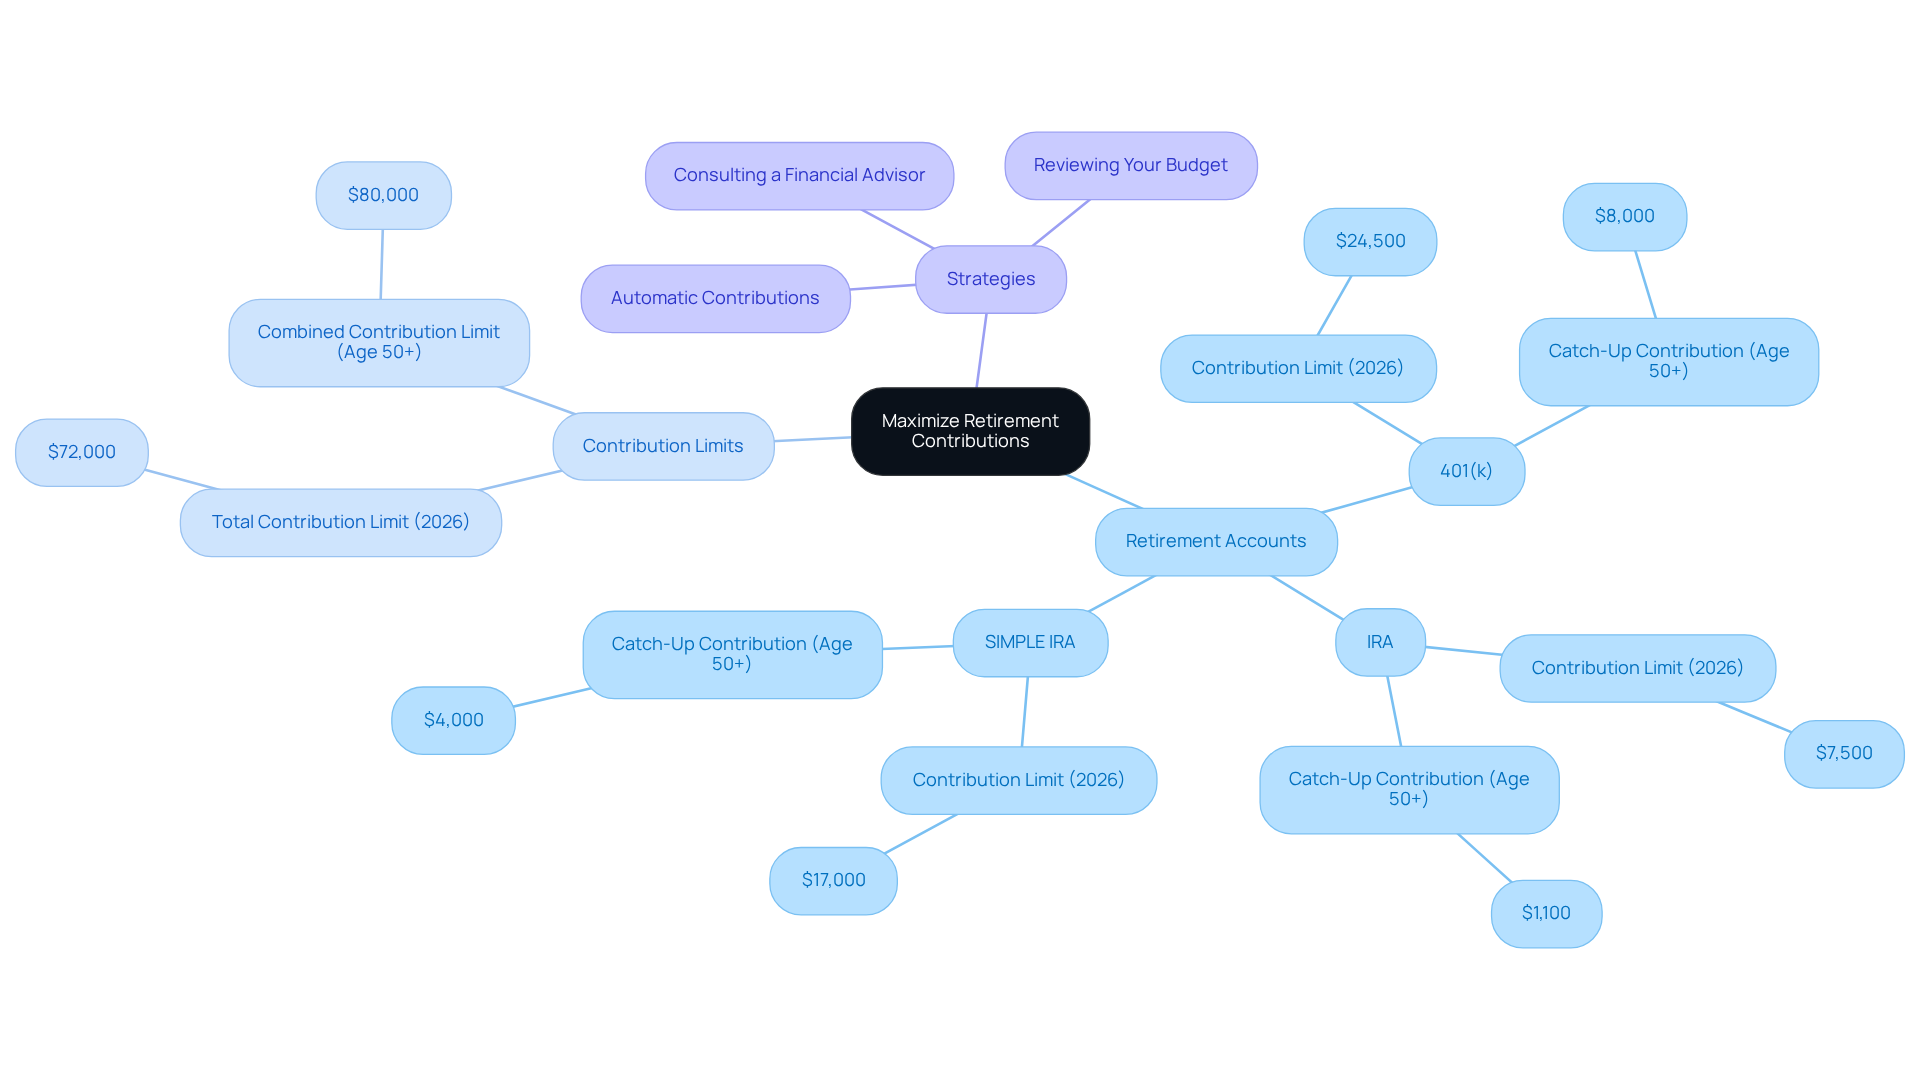
Imagine feeling secure about your family’s financial future while also easing your tax burden through retirement accounts like 401(k)s or IRAs. For young parents, increasing deposits to these accounts is a strong approach to lower taxable income. Starting in 2026, you can contribute up to $24,500 to your 401(k), plus an extra $8,000 if you’re 50 or older. And if you have a SIMPLE IRA, the catch-up limit will rise to $4,000, giving you even more ways to save for retirement.
By utilizing w2 tax planning to take full advantage of these limits, you can lower your tax bill and start building a nest egg for your family’s future. It can be tough to find room in your budget for retirement savings, especially with so many expenses to juggle. But reviewing your budget can help you see what’s possible. Setting up automatic contributions can make it easier to prioritize retirement savings each month.
Talking to a financial advisor can give you tailored advice on balancing retirement savings with other important goals, like your kids’ education or everyday expenses. At Bright Advisers, we’re here for you, dedicated to assisting households in making prudent wealth choices and safeguarding assets across generations. Together, we can navigate these financial choices to ensure a brighter future for your family.
Utilize Health Savings Accounts for Tax Efficiency and Healthcare Costs
Imagine facing unexpected medical bills while trying to provide for your family – this is where Health Savings Accounts (HSAs) can make a difference. HSAs serve as a valuable tax-advantaged resource, allowing households to save for medical costs while reducing their taxable income. Contributions to an HSA are tax-deductible, which means you can lower your taxable income for the year. For 2026, the contribution limits are set at $4,400 for individuals and $8,750 for households, with an additional $1,000 catch-up amount available for those aged 55 and older.
What makes HSAs truly appealing is their triple tax advantage: you can deduct contributions, watch your funds grow tax-free, and enjoy tax-free withdrawals for qualified medical expenses. This can be a real relief for families like Jay and Emma, who may face unforeseen healthcare expenses and are looking for ways to ease financial stress while securing their future.
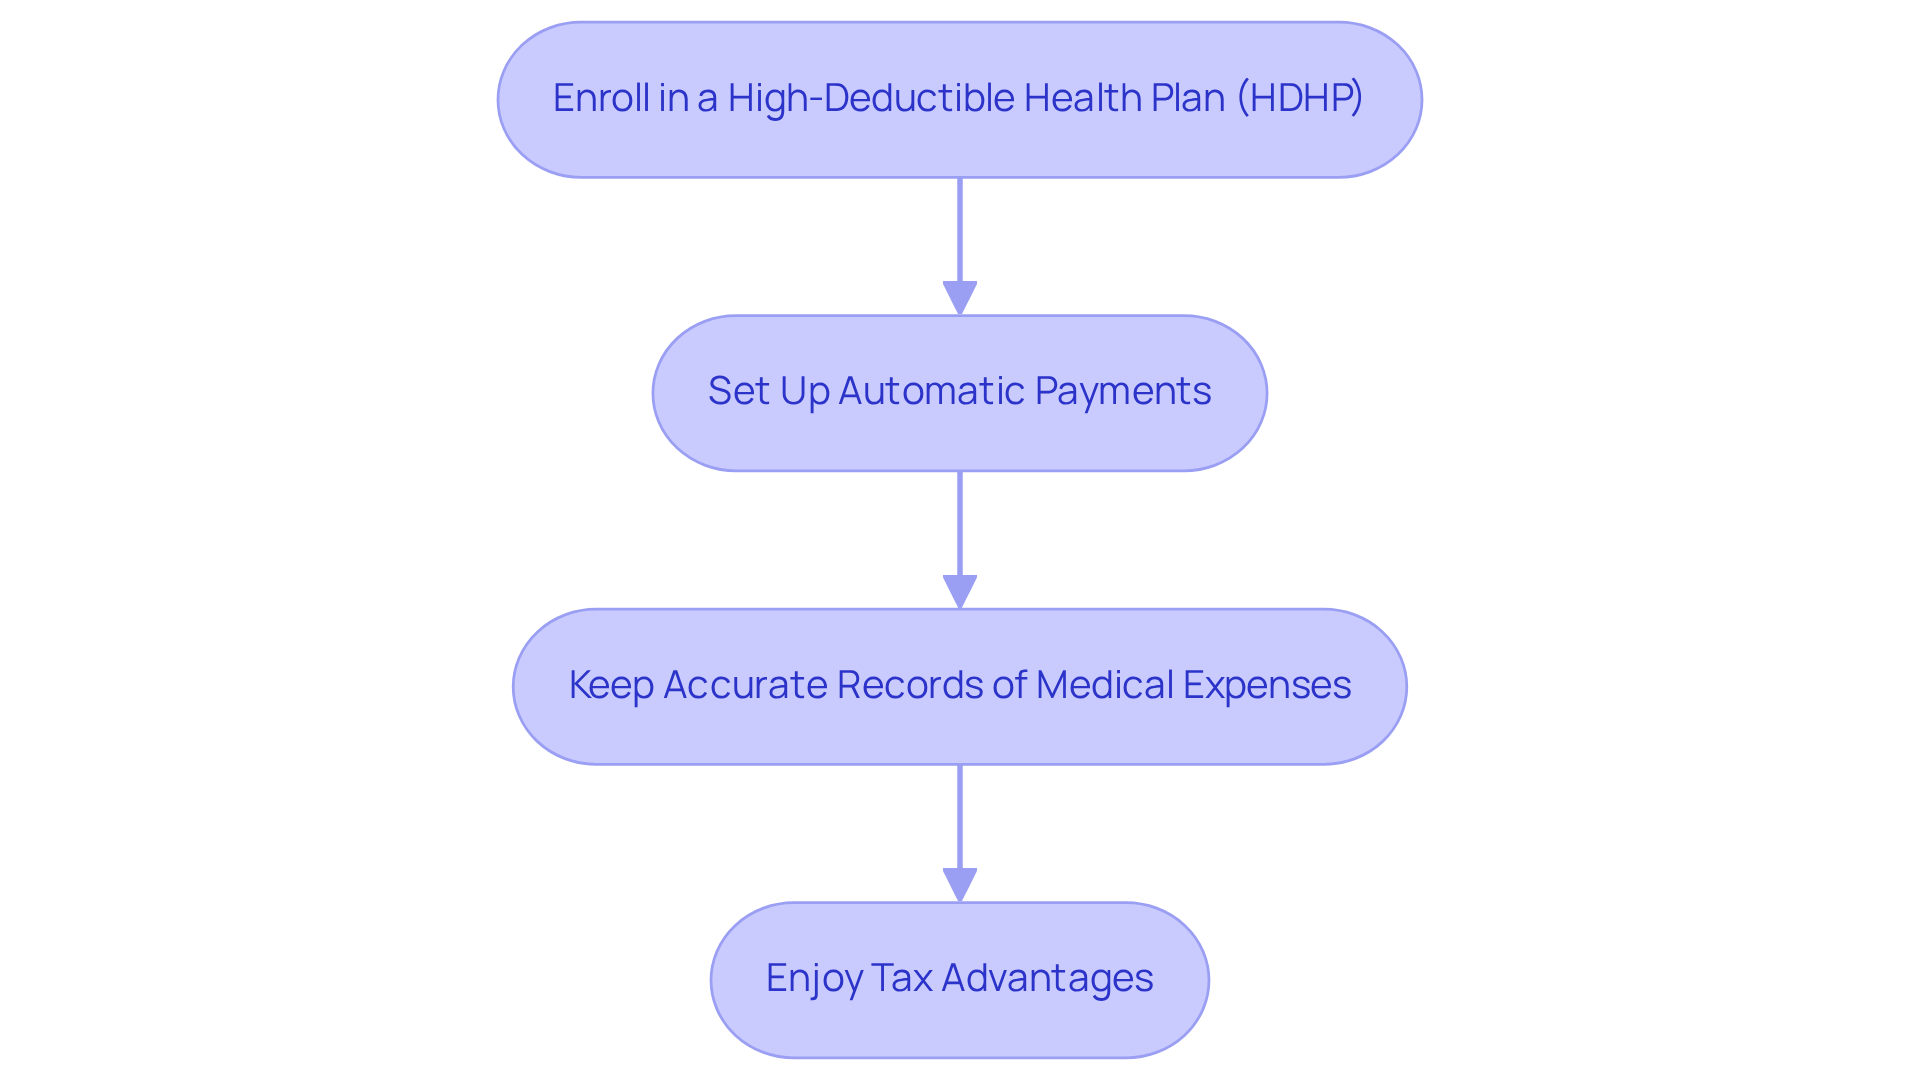
To make the most of an HSA, you first need to enroll in a high-deductible health plan (HDHP). This step is essential for HSA eligibility. Once you’re registered, setting up automatic payments can help your household consistently benefit from the tax advantages. Plus, keeping accurate records of qualified medical expenses is crucial for ensuring tax-free withdrawals when you need them. For instance, if Jay and Emma contribute $4,400 annually for 35 years, assuming a 5% annual return, they could potentially accumulate around $292,000, showcasing the long-term benefits of consistent contributions.
Consulting with a money advisor, like those at Bright Advisers, can further assist families in navigating the complexities of HSAs and incorporating them into their broader financial strategy. Bright Advisers is committed to providing clear, comprehensive fee structures, making effective planning solutions more accessible for families. With the right guidance, you can turn HSAs into a powerful tool for your family’s financial peace of mind.
Incorporate Charitable Contributions to Enhance Family Legacy and Tax Benefits
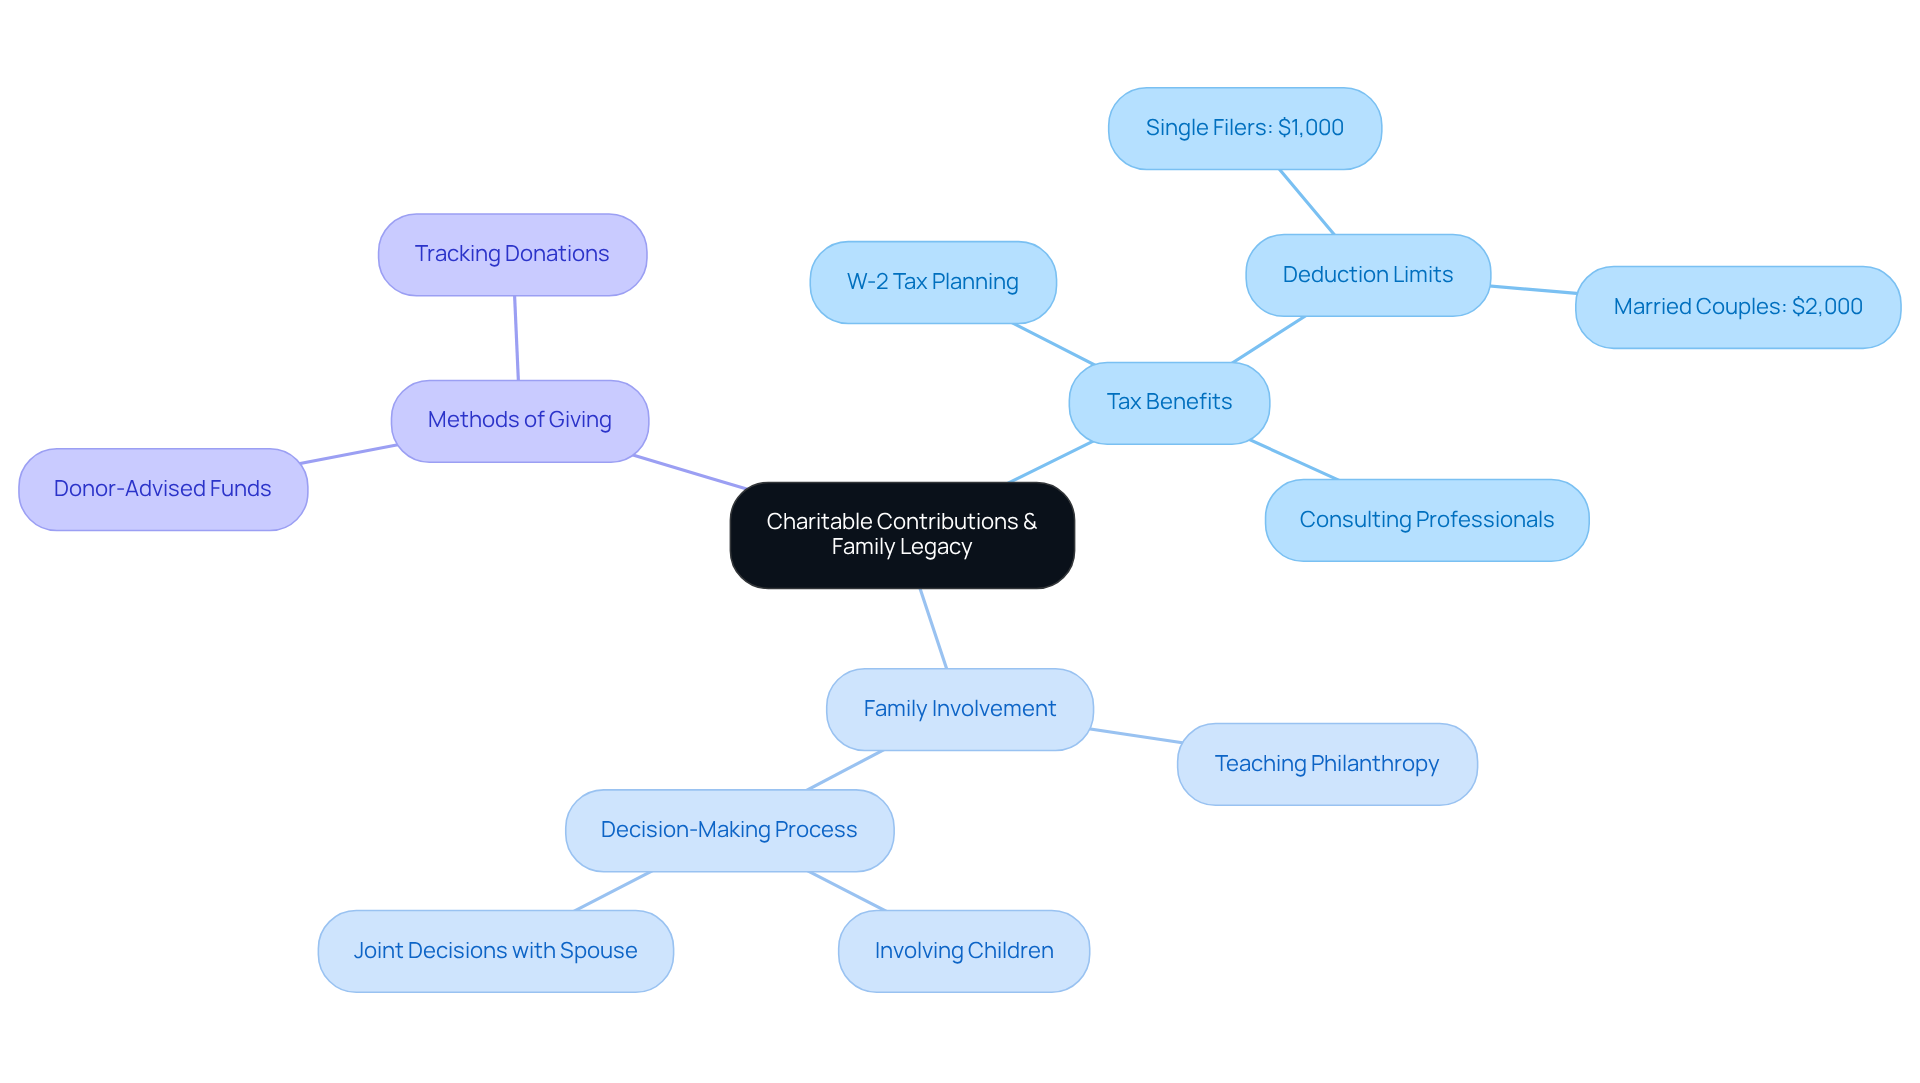
Imagine a way to teach your children the importance of giving back while also benefiting your family’s finances. Integrating charitable donations into your household’s financial plan can serve both altruistic objectives and enhance W-2 tax planning. When you participate in W-2 tax planning by donating to qualified charities, you can deduct those contributions from your taxable income, which can significantly lower your overall tax bill. For the 2026 tax year, single filers can deduct cash donations up to $1,000, while married couples filing jointly can deduct up to $2,000. This encourages families to embrace charitable giving.
This not only helps lower your taxes but also creates a lasting legacy of giving for your family. Imagine teaching your children about philanthropy and instilling values that can last a lifetime. You might consider setting up a donor-advised fund (DAF) to manage your charitable giving more effectively. This approach allows you to make larger donations in one year and then allocate those funds to different charities over time, enhancing your tax advantages.
Keeping track of your donations can feel daunting, but it’s a crucial step in making the most of your charitable efforts. It’s important to consult with a tax professional for W-2 tax planning to ensure you’re fully utilizing your deductions. When you involve your kids in choosing where to donate, you help them understand money management and the importance of giving back. By engaging them in this decision-making process, you’re equipping them for future stewardship of resources.
By involving your children in charitable decisions, you’re not just giving; you’re nurturing future stewards of generosity.
Implement Tax-Loss Harvesting to Optimize Investment Returns
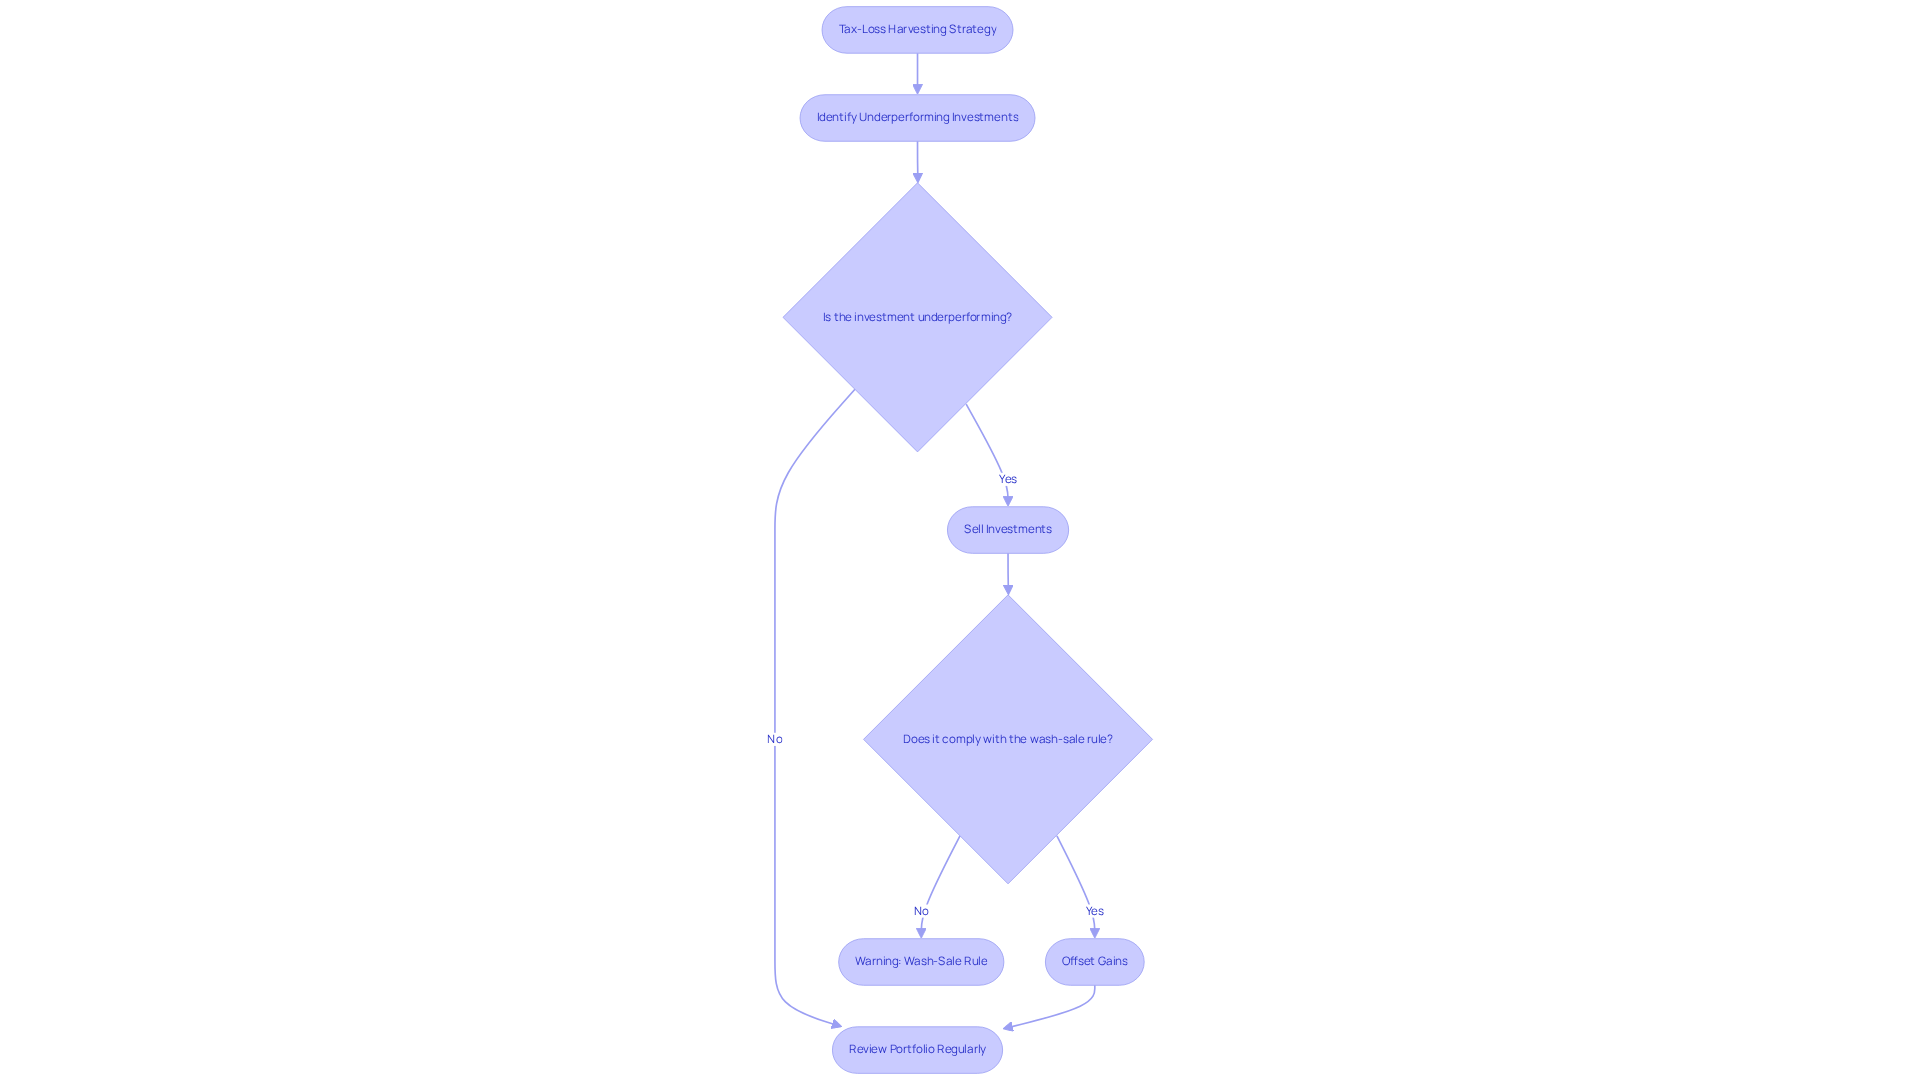
Imagine juggling your career and family while trying to secure your financial future. It can feel overwhelming, right? Tax-loss harvesting can be a helpful tool for families, allowing you to sell investments that aren’t performing well to balance out gains and lighten your tax load. For young parents like Emily and Mark, who are navigating demanding careers while seeking financial stability, this strategy can be an effective way to manage investment portfolios while minimizing tax liabilities. For instance, if your household has realized gains of $10,000 from one investment but incurs a loss of $3,000 from another, selling the losing investment can offset the gains, effectively lowering your taxable income by $3,000.
In times when the market feels unpredictable, this approach can really help you stay on track with your financial goals. By regularly reviewing your portfolio, you can spot opportunities for tax-loss harvesting throughout the year, rather than waiting until year-end. In 2026, households can offset up to $3,000 of ordinary income with capital losses, which can significantly ease your overall tax burden. For married individuals filing separately, this limit is $1,500.
To make the most of tax-loss harvesting, it’s wise to keep a variety of investments and consider reaching out to a trusted advisor who can guide you through the process. Bright Advisers, with its innovative in-house technology, helps families like Jay and Emma’s achieve their financial goals by offering personalized wealth management solutions that include tax optimization strategies. Additionally, it’s important to be aware of the wash-sale rule, which disallows the deduction of a loss if the same or substantially identical security is repurchased within 30 days. By understanding and applying tax-loss harvesting, families can enhance their investment returns while managing their tax liabilities, ultimately paving a smoother path for their family’s future.
Conclusion
Navigating the world of financial planning can feel daunting, especially for young parents trying to secure their family’s future. By using simple strategies like boosting retirement contributions, taking advantage of Health Savings Accounts, giving to charity, and managing investments wisely, families can lower their tax bills and build a secure future. These steps can ease financial stress now and help your family thrive in the long run.
Let’s explore four simple yet powerful practices designed just for families like yours, who want to make the most of their finances:
- Increasing contributions to retirement accounts can lower your taxable income.
- HSAs offer a triple tax advantage for medical expenses.
- Giving to charity not only fosters a legacy of generosity but also provides valuable tax deductions.
- Managing investments wisely through tax-loss harvesting can optimize returns and effectively manage tax liabilities.
By embracing these practices, you can feel more confident in making choices that support your family’s needs today and dreams for tomorrow. Engaging with a fiduciary advisor like Bright Advisers can provide the guidance you need to navigate these strategies effectively. Taking these steps today can pave the way for a secure and generous future for your family, ensuring that you can focus on what truly matters-your loved ones.
Frequently Asked Questions
How can increasing retirement contributions help reduce taxable income?
Increasing contributions to retirement accounts like 401(k)s or IRAs can lower your taxable income, which may ease your tax burden.
What are the contribution limits for 401(k)s starting in 2026?
Starting in 2026, you can contribute up to $24,500 to your 401(k), with an additional $8,000 allowed if you are 50 or older.
What is the catch-up contribution limit for SIMPLE IRAs?
The catch-up contribution limit for SIMPLE IRAs will rise to $4,000, providing more opportunities to save for retirement.
How can W-2 tax planning assist in maximizing retirement contributions?
W-2 tax planning can help you take full advantage of retirement contribution limits, ultimately lowering your tax bill while building savings for the future.
What strategies can help find room in the budget for retirement savings?
Reviewing your budget can help identify potential savings, and setting up automatic contributions can make it easier to prioritize retirement savings each month.
How can a financial advisor assist with retirement savings?
A financial advisor can provide tailored advice on balancing retirement savings with other important financial goals, such as children’s education and everyday expenses.
What is the mission of Bright Advisers?
Bright Advisers is dedicated to assisting families in making wise wealth decisions and preserving assets across generations.
List of Sources
- Maximize Retirement Contributions to Reduce Taxable Income
- IRA contribution limits for 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/ira-contribution-limits)
- 401(k) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/401k-contribution-limits)
- 401(k) Contribution Limits |2026, 2025 and Earlier | ADP (https://adp.com/resources/articles-and-insights/articles/4/401k-contribution-limits.aspx)
- 401k Plan Statistics and Trends For 2026 – Carry (https://carry.com/learn/401k-statistics)
- What are 2026 401(k) and individual retirement account max contribution limits? (https://principal.com/individuals/learn/what-are-2026-401k-and-ira-max-contribution-limits)
- Utilize Health Savings Accounts for Tax Efficiency and Healthcare Costs
- HSA Statistics, Facts, and Research for 2026 (https://truemed.com/blog/hsa-statistics)
- Health savings accounts and their triple tax benefits (https://natptax.com/news-insights/blog/health-savings-accounts-and-their-triple-tax-benefits?srsltid=AfmBOoo3q3Zvcp4qqTfw9aD9l4JHAzzKHNof8ibXZgqWkW3OCipWcCoG)
- HSA contribution limits 2026 and 2027 | Fidelity (https://fidelity.com/learning-center/smart-money/hsa-contribution-limits)
- What Is an HSA? A Guide to Health Savings Accounts (https://schwab.com/learn/story/is-hsa-good-deal)
- Health savings accounts triple tax advantage explained (https://instead.com/resources/blog/health-savings-accounts-triple-tax-advantage-explained)
- Incorporate Charitable Contributions to Enhance Family Legacy and Tax Benefits
- Charitable Giving Statistics | NPTrust (https://nptrust.org/philanthropic-resources/charitable-giving-statistics)
- How new charitable giving rules could affect your taxes (https://ameriprise.com/financial-goals-priorities/taxes/tax-rules-charitable-giving-deductions)
- Charitable Deduction Changes in 2026: What You Need to Know Before Year-End – Katz Baskies & Wolf PLLC (https://katzbaskies.com/blog/charitable-deduction-changes-in-2026-what-you-need-to-know)
- Affluent Charitable Giving Trends and Statistics in 2024 (https://privatebank.bankofamerica.com/articles/bank-of-america-study-of-philanthropy.html)
- What new tax rules mean for donors | Fidelity (https://fidelity.com/learning-center/wealth-management-insights/charitable-giving-tax-changes)
- Implement Tax-Loss Harvesting to Optimize Investment Returns
- Tax-loss harvesting | Capital gains and lower taxes | Fidelity (https://fidelity.com/viewpoints/personal-finance/tax-loss-harvesting)
- What is Tax-Loss Harvesting? Rules & Examples | New York Life (https://newyorklife.com/articles/what-is-tax-loss-harvesting)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading