

Key Highlights
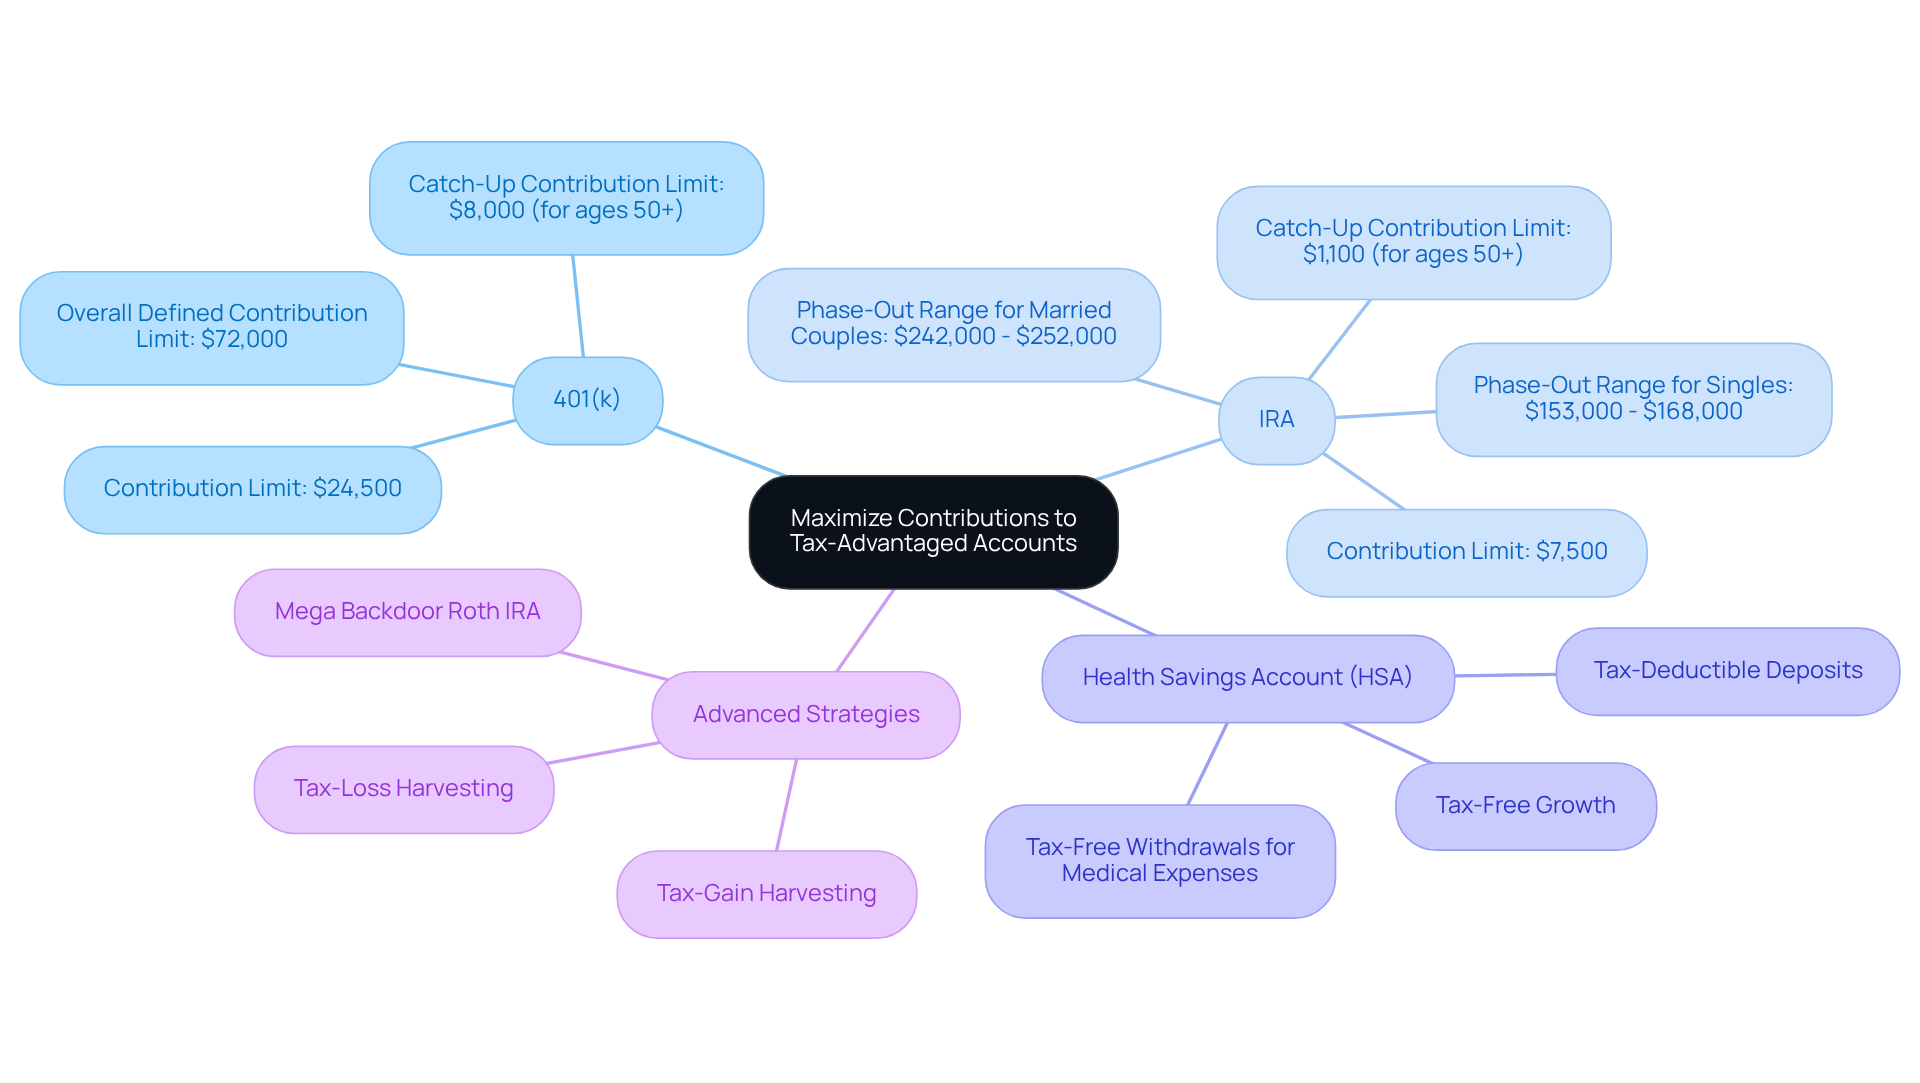
- High-income families can contribute up to $24,500 to 401(k)s and $7,500 to IRAs in 2026, aiding in tax reduction and savings.
- Health Savings Accounts (HSAs) offer tax-deductible deposits, tax-free growth, and tax-free withdrawals for medical expenses.
- The ‘mega backdoor Roth IRA’ allows for additional contributions beyond standard limits, enhancing tax efficiency.
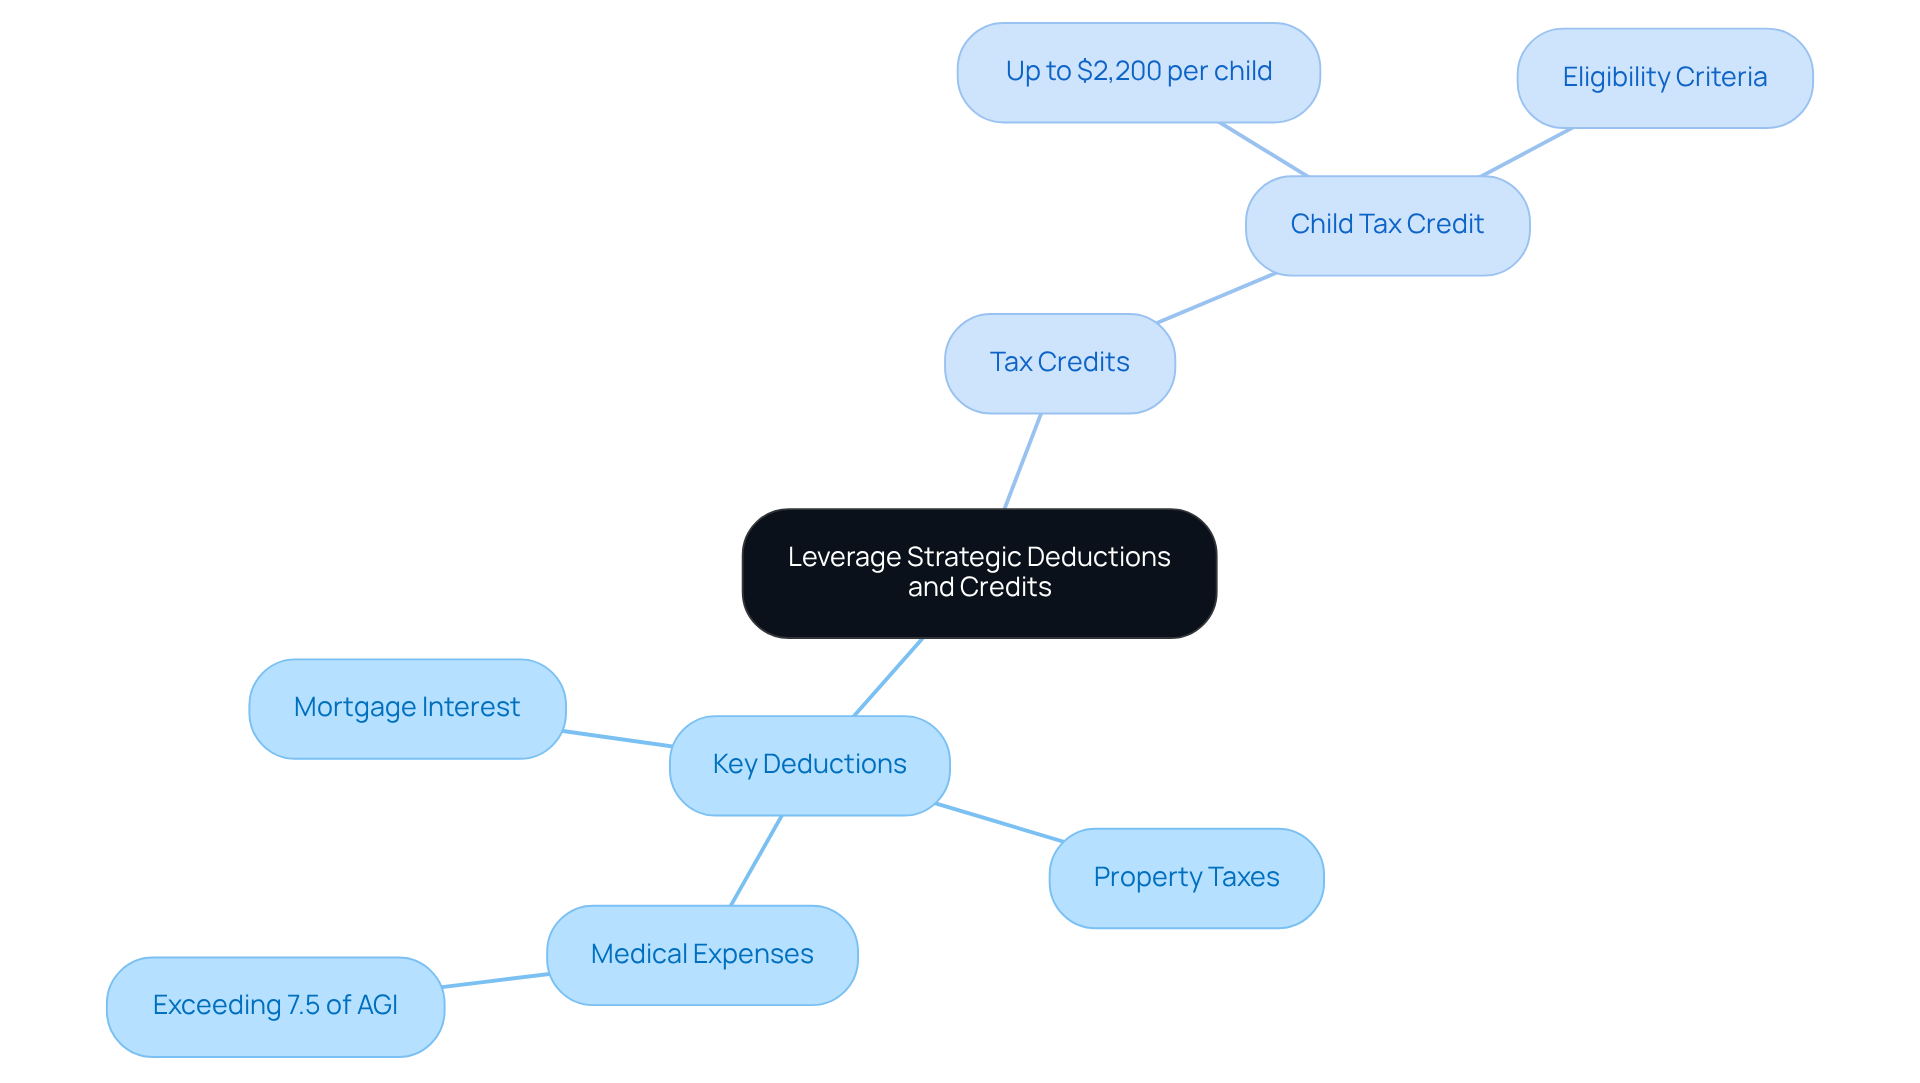
- Key tax deductions include mortgage interest, property taxes, and medical expenses exceeding 7.5% of adjusted gross income.
- The Child Tax Credit provides up to $2,200 for each qualifying child, offering significant financial support.
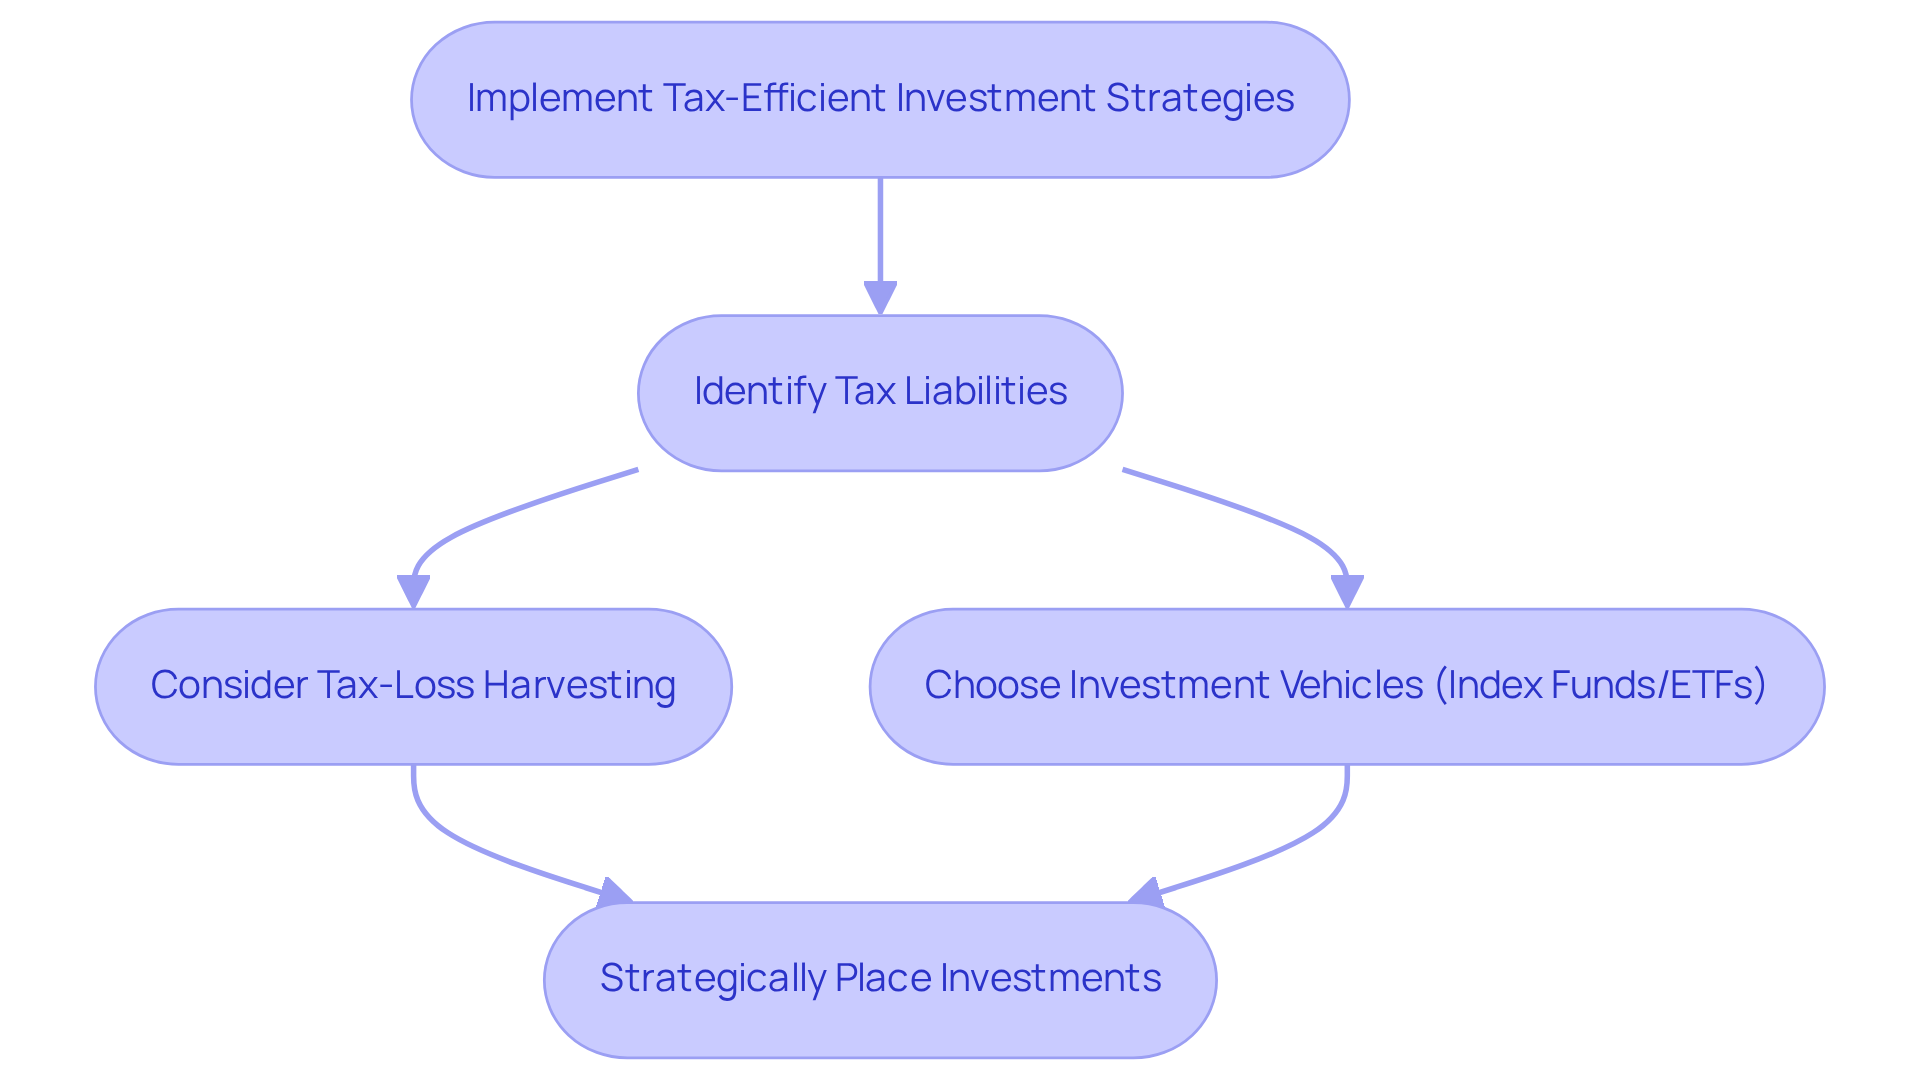
- Tax-loss harvesting can offset capital gains, providing families with more financial freedom.
- Investing in index funds or ETFs can minimise taxable events, enhancing tax efficiency.
- Placing tax-inefficient investments in tax-advantaged accounts improves overall tax efficiency.
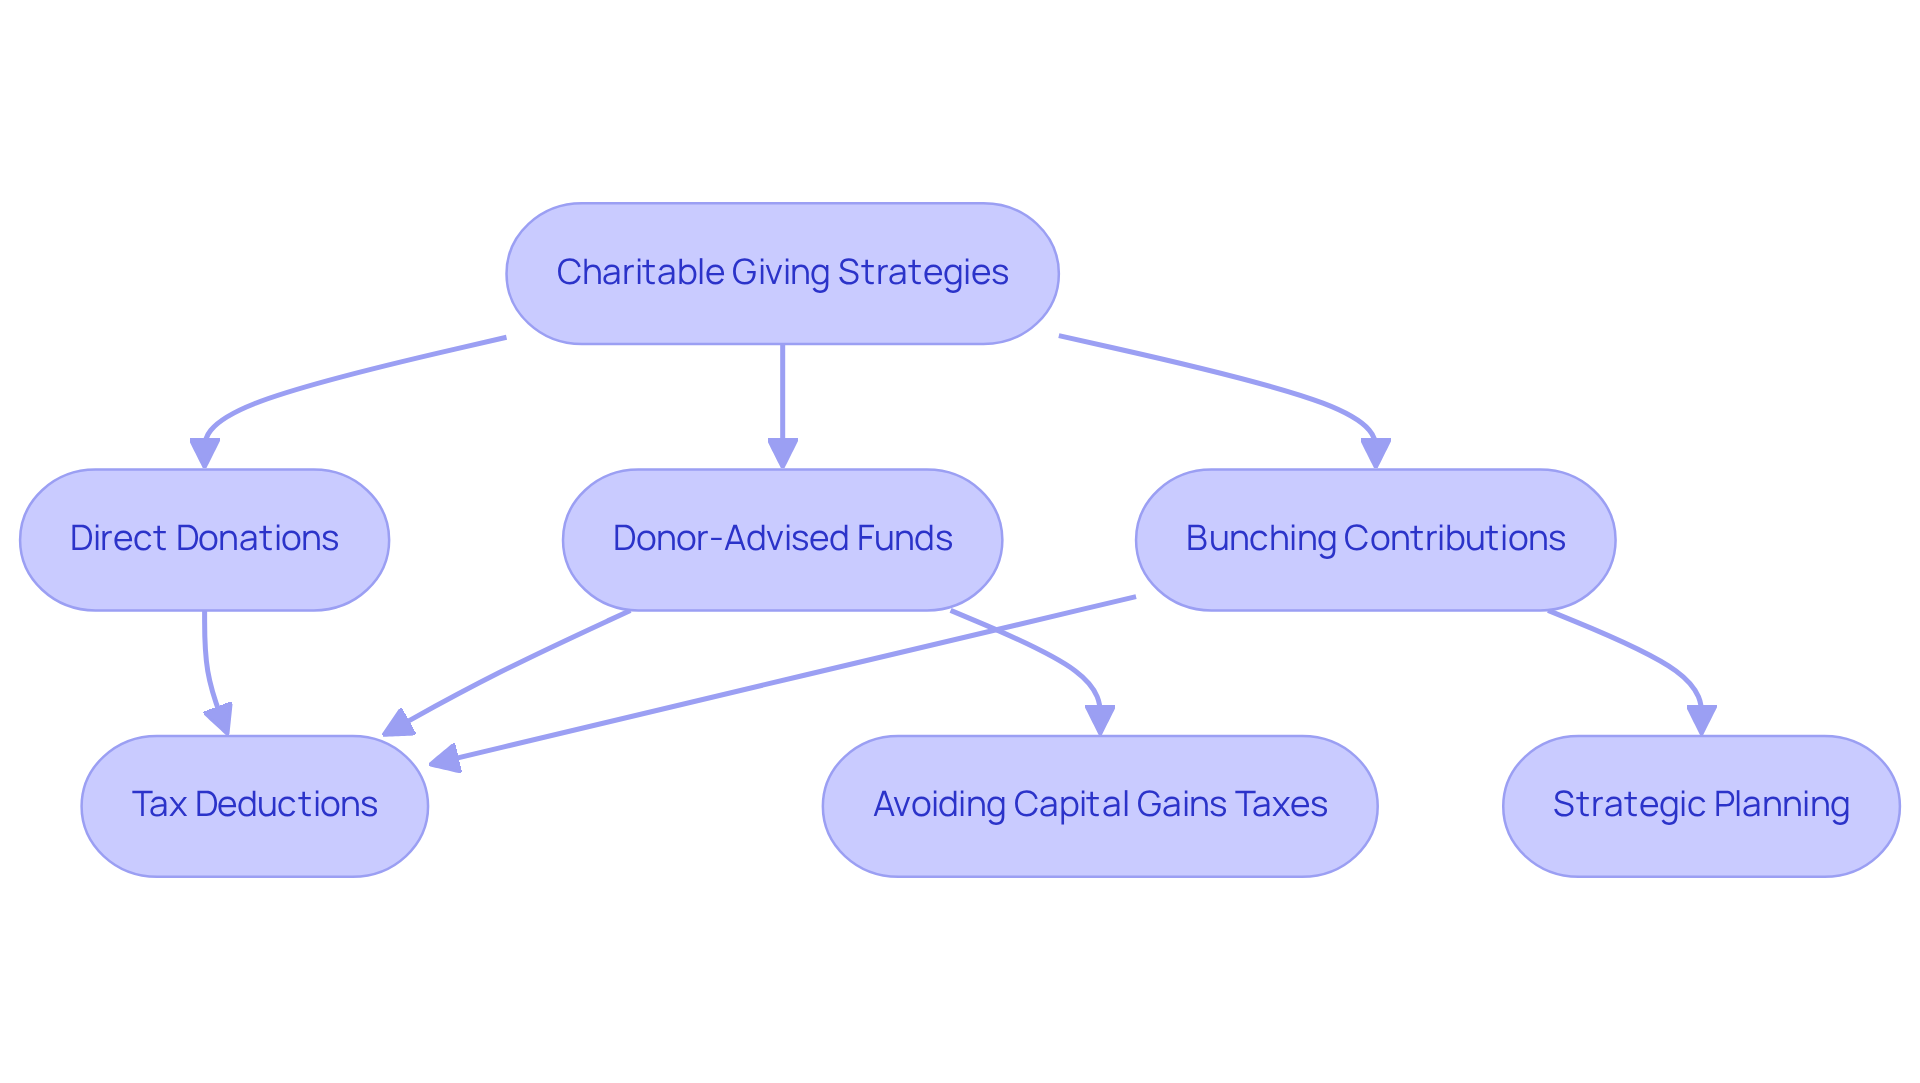
- Charitable donations to qualified nonprofits can reduce taxable income, with strategies like donating appreciated assets to avoid capital gains taxes.
- Setting up a Donor-Advised Fund allows for strategic philanthropic giving while enjoying immediate tax benefits.
Introduction
Imagine feeling overwhelmed by tax planning while trying to provide the best for your family. When you learn to manage tax liabilities, you’re not just preserving wealth; you’re building a secure future for your children.
Let’s explore four essential tax planning strategies that can help your family thrive:
- Maximizing contributions to tax-advantaged accounts
- Leveraging strategic deductions and credits
- Implementing tax-efficient investment strategies
- Utilizing charitable giving for tax benefits
How can you make sure your family isn’t leaving money on the table while securing a bright financial future?
Maximize Contributions to Tax-Advantaged Accounts
Imagine feeling secure about your family’s financial future while navigating the complexities of saving for retirement. As a high-income family, you might be wondering how high income W2 tax planning for high income earners can optimize your savings. Focusing on tax-advantaged accounts like 401(k)s and IRAs can be a great start.
For 2026, you can contribute up to $24,500 to your 401(k) and $7,500 to your IRA, which can really help your family save. By utilizing these accounts effectively, you can implement high income W2 tax planning for high income earners, which helps lower your taxable income and provides your family with more breathing room in your budget.
Plus, Health Savings Accounts (HSAs) are a fantastic option, offering you three tax benefits that can really help your family:
- Not only are your deposits tax-deductible,
- but the growth is tax-free,
- and withdrawals for eligible medical expenses are also tax-free.
You might also want to explore strategies like the ‘mega backdoor Roth IRA’ to boost your retirement savings even more. This approach allows for additional contributions beyond standard limits, paving the way for greater tax efficiency and long-term financial growth through high income W2 tax planning for high income earners.
Navigating the world of tax-advantaged accounts can feel overwhelming, especially when you’re trying to balance family needs. But by taking these steps, you can create a brighter financial future for your family, ensuring that you’re prepared for whatever life brings.
Leverage Strategic Deductions and Credits
Imagine feeling overwhelmed by taxes, unsure of how to keep more of your hard-earned money for your family. Many families like yours can benefit from exploring strategic deductions and credits to help keep more of what you earn. Key deductions include:
- Mortgage interest
- Property taxes
- Medical expenses that exceed 7.5% of adjusted gross income
For instance, the average mortgage interest deduction can significantly lighten tax obligations, especially for families with substantial home loans. Plus, don’t forget about the Child Tax Credit, which offers up to $2,200 for each qualifying child, providing essential financial support.
Now, picture this: you could turn your underperforming investments into opportunities to save on taxes, giving you more financial freedom. Tax-loss harvesting allows families to sell those investments to offset capital gains, which can be especially helpful for those facing hefty capital gains taxes. By understanding and utilizing these deductions and credits, families can ease their overall tax burden, ensuring they keep more of what they earn for future needs.
Consider the story of Allison and Brian, a couple just like you, who discovered the power of effective tax planning. Despite their impressive incomes as a medical device sales representative and a restaurant owner, they were unaware of the financial opportunities they were missing due to inadequate high income W-2 tax planning for high income earners. Through their collaboration with Bright Advisers, they optimized their tax situation, secured their children’s future through education funding, and gained the ability to retire sooner. By incorporating tax optimization into their comprehensive financial plan, they experienced the peace of mind that comes with financial security, allowing them to enjoy more quality time with their loved ones.
With the right guidance, you can transform your tax strategy into a powerful tool for your family’s future, allowing you to focus on what truly matters-your loved ones.
Implement Tax-Efficient Investment Strategies
Imagine the worry of seeing your hard-earned money diminished by taxes each year. High-income households often feel the weight of tax liabilities, but high income W2 tax planning for high income earners can help ease that burden.
What if you could turn losses into opportunities to save on taxes? Tax-loss harvesting allows you to offset gains with losses, minimizing your tax liabilities and giving you more control over your finances.
Consider investing in index funds or ETFs, which can help you keep more of what you earn for your family. These options typically have lower turnover rates, resulting in fewer taxable events and a more tax-efficient investment experience.
It’s important to understand that by strategically placing tax-inefficient investments in tax-advantaged accounts, you can enhance your overall tax efficiency, a key aspect of high income W2 tax planning for high income earners. For instance, municipal bonds, which offer tax-exempt interest, can be particularly advantageous when held in taxable accounts.
By taking control of your investments, you can feel more secure about your family’s financial future. Together, we can navigate these strategies to ensure your family’s financial future is bright and secure.
Utilize Charitable Giving for Tax Benefits
Imagine being a family that wants to give back while also easing the burden of taxes. High-income families can benefit from high income W2 tax planning for high income earners by using philanthropic giving to help reduce their taxable income. Donations to qualified nonprofit organizations allow for deductions from taxable income, leading to significant tax advantages. Consider contributing appreciated assets, like stocks or real estate. This method can help you avoid capital gains taxes while allowing you to deduct the asset’s fair market value. For instance, donating long-term appreciated assets can help you sidestep capital gains taxes, enabling you to deduct the full fair market value from your income taxes.
Think about setting up a Donor-Advised Fund, which lets you give over time while enjoying a tax break right away. This approach not only simplifies the giving process but also allows for strategic planning, like ‘bunching’ multiple years’ worth of gifts into one year to exceed the itemization threshold for deductions. By weaving these giving strategies into your financial plans, you can support causes that matter to you while also saving on taxes.
Furthermore, the average after-tax cost of philanthropic giving for the entire population in 2023 is approximately 83%, highlighting the financial impact of such donations. The federal estate and gift tax exemption of $15 million per individual in 2026 is crucial for high-income families engaged in high income W2 tax planning for high income earners and considering philanthropic donations. Additionally, the personal donation deduction is projected to cost around $51 billion in 2023, underscoring the significance of giving in the broader economic context.
For example, if your family contributes $100,000 in long-term appreciated stock, originally acquired for $10,000, you can enhance your charitable donations while reducing your tax obligations. By embracing these strategies, you can not only lighten your tax load but also make a meaningful impact on the world around you.
Conclusion
Imagine feeling confident about your family’s financial future, even amidst the complexities of tax planning. Maximizing tax efficiency is crucial for high-income families. Focusing on strategies like maximizing contributions to tax-advantaged accounts can make a big difference. By leveraging strategic deductions and credits, implementing tax-efficient investment strategies, and utilizing charitable giving, families can significantly enhance their financial well-being. These approaches not only help in reducing taxable income but also pave the way for a more secure financial future.
Throughout this article, we’ve shared key insights on managing tax obligations effectively. From the benefits of Health Savings Accounts to the importance of tax-loss harvesting and the advantages of charitable contributions, each strategy offers unique opportunities for families to keep more of their hard-earned money. Consider the story of Allison and Brian, who found success with Bright Advisers; their experience illustrates how effective tax planning can transform a family’s financial landscape.
At the end of the day, these strategies do more than just save you money; they help you focus on what really matters – creating lasting memories and securing a prosperous future for your children. Engaging with a fiduciary advisor like Bright Advisers can provide the guidance needed to navigate these complexities, ensuring that families make informed decisions that align with their financial goals. When you take the first step towards effective tax planning, you’re not just saving money; you’re investing in your family’s happiness and security.
Frequently Asked Questions
What are tax-advantaged accounts and why are they important for high-income families?
Tax-advantaged accounts, such as 401(k)s and IRAs, are investment accounts that offer tax benefits, helping high-income families lower their taxable income and save for retirement more effectively.
What are the contribution limits for 401(k)s and IRAs in 2026?
In 2026, you can contribute up to $24,500 to your 401(k) and $7,500 to your IRA.
How do Health Savings Accounts (HSAs) benefit families?
HSAs provide three tax benefits: deposits are tax-deductible, the growth is tax-free, and withdrawals for eligible medical expenses are also tax-free.
What is the ‘mega backdoor Roth IRA’ strategy?
The ‘mega backdoor Roth IRA’ strategy allows for additional contributions beyond standard limits, enhancing tax efficiency and long-term financial growth.
How can high-income W2 tax planning help families?
High-income W2 tax planning helps families optimize their savings by utilizing tax-advantaged accounts, which can lower taxable income and provide more financial flexibility.
What should families consider when navigating tax-advantaged accounts?
Families should consider their specific financial needs and goals, as navigating tax-advantaged accounts can be complex, but it is essential for creating a secure financial future.
List of Sources
- Maximize Contributions to Tax-Advantaged Accounts
- How tax-efficient investing could boost your portfolio returns in 2026 and beyond (https://cnbc.com/2026/01/12/tax-efficient-investing.html)
- IRS Increases 401(k) and IRA Contribution Limits for 2026 | Windes (https://windes.com/401k-ira-contribution-limits)
- 2026 Retirement Contribution Limits For IRAs And 401(k)s | Alliant Credit Union (https://alliantcreditunion.org/money-mentor/contribution-limits-for-iras-and-401ks)
- 2026 401(k) Contribution Limits Issued by the IRS (https://asppa-net.org/news/2025/11/2026-401k-contribution-limits-issued-by-the-irs)
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- Leverage Strategic Deductions and Credits
- The Child Tax Credit (https://cbpp.org/research/federal-tax/the-child-tax-credit)
- Child Tax Credit | Center on Poverty and Social Policy (https://povertycenter.columbia.edu/child-tax-credit)
- The Mortgage Interest Deduction: Options for Reform (https://budgetlab.yale.edu/research/mortgage-interest-deduction-options-reform)
- What is the child tax credit? (https://taxpolicycenter.org/briefing-book/what-child-tax-credit)
- Implement Tax-Efficient Investment Strategies
- Tax-efficient investing for high-income earners (https://edwardjones.com/us-en/market-news-insights/guidance-perspective/tax-efficient-investing)
- Asset location can play a key role in tax-efficient investing (https://troweprice.com/en/us/insights/asset-location-can-play-a-key-role-in-tax-efficient-investing)
- Tax efficient investing (https://advisors.vanguard.com/wealth-management/tax-efficient-investing)
- How Asset Location Can Help Save on Taxes (https://schwab.com/learn/story/how-asset-location-can-help-save-on-taxes)
- Unlocking Tax Efficiency: The Importance of Strategic Asset Allocation and Asset Location (https://am.gs.com/en-us/advisors/insights/article/2026/unlocking-tax-efficiency-asset-allocation-location)
- Utilize Charitable Giving for Tax Benefits
- How large are individual income tax incentives for charitable giving? (https://taxpolicycenter.org/briefing-book/how-large-are-individual-income-tax-incentives-charitable-giving)
- Charitable contributions: tax strategies (https://fidelitycharitable.org/guidance/charitable-tax-strategies/charitable-contributions.html)
- OBBBA Insight: Charitable Giving for High-Income Individuals – Why Give to Charity in 2025, Not 2026 (https://deandorton.com/obbba-insight-charitable-giving-for-high-income-individuals)
- Your Charity Donation Tax Deduction Guide | U.S. Bank (https://usbank.com/wealth-management/financial-perspectives/financial-planning/philanthropy-and-charitable-giving/tax-deductions-on-charitable-donations.html)
- Tax Advantages for Donor-Advised Funds | NPTrust (https://nptrust.org/what-is-a-donor-advised-fund/daf-tax-consideration)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading