

Overview
Navigating the world of taxes can feel overwhelming, especially for young parents. That’s why understanding four essential tax planning strategies can be a game changer for your family’s financial health. First, it’s important to grasp how tax brackets work. This knowledge can empower you to make informed decisions that align with your family’s needs.
Next, maximizing deductions and credits is crucial. Imagine if you could reduce your tax obligations while enhancing your family’s financial well-being. Utilizing tax credits, like the Child Tax Credit, can provide significant relief and support your family’s goals.
Selecting the right filing status is another key strategy. It’s essential to choose an option that best reflects your situation, ensuring you benefit from every possible advantage. Finally, making use of retirement contributions can optimize your finances for the future. By planning ahead, you’re not just securing your financial future; you’re also investing in your family’s dreams.
Each of these strategies is designed to help you legally reduce your tax obligations while enhancing your family’s overall financial health. Remember, we’re here for you, and together, we can navigate this journey toward a more secure financial future.
Key Highlights:
- Tax planning helps individuals legally reduce their tax obligations by examining their financial situation.
- Understanding tax brackets allows for optimization of income distribution to potentially lower overall tax burdens.
- Deductions lower taxable income, while credits directly reduce tax owed; the standard deduction for single filers will rise to $15,000 in 2025.
- Choosing the right filing status, such as married filing jointly, can influence tax rates and eligibility for credits.
- Maximising retirement contributions to accounts like 401(k)s can significantly lower taxable income.
- Tax-loss harvesting allows individuals to sell depreciated assets to offset gains, reducing tax obligations.
- Utilising available tax credits, such as the Child Tax Credit, can provide substantial tax relief for families.
- Charitable contributions offer both tax deductions and support for meaningful causes.
- Personalised tax planning involves assessing family income, utilising education savings plans, and implementing income splitting to enhance financial outcomes.
- Technology, including tax software and automated record-keeping, can streamline the tax planning process and reduce errors.
Introduction
Navigating the complexities of tax planning can feel overwhelming, but it holds the key to unlocking significant financial benefits for you and your family. By understanding essential strategies—like optimizing income distribution, maximizing deductions, and leveraging available credits—you can effectively reduce your tax obligations and enhance your overall financial well-being. Imagine if you could ease some of that financial stress and create a more secure future for your loved ones.
However, with new tax brackets and potential changes on the horizon for 2025, it’s important to consider how you can tailor your tax strategies. How can you ensure compliance with regulations while also securing a more stable financial future? The answers lie in thoughtful planning and proactive engagement.
Together, we can navigate this journey, ensuring that you have the support and resources needed to make informed decisions. We’re here for you, ready to help you explore the possibilities that lie ahead.
Understand the Fundamentals of Tax Planning
Tax planning strategies for individuals are essential as they help you examine your financial situation to legally reduce your tax obligations. Let’s explore some key concepts that can make a difference for you and your family:
-
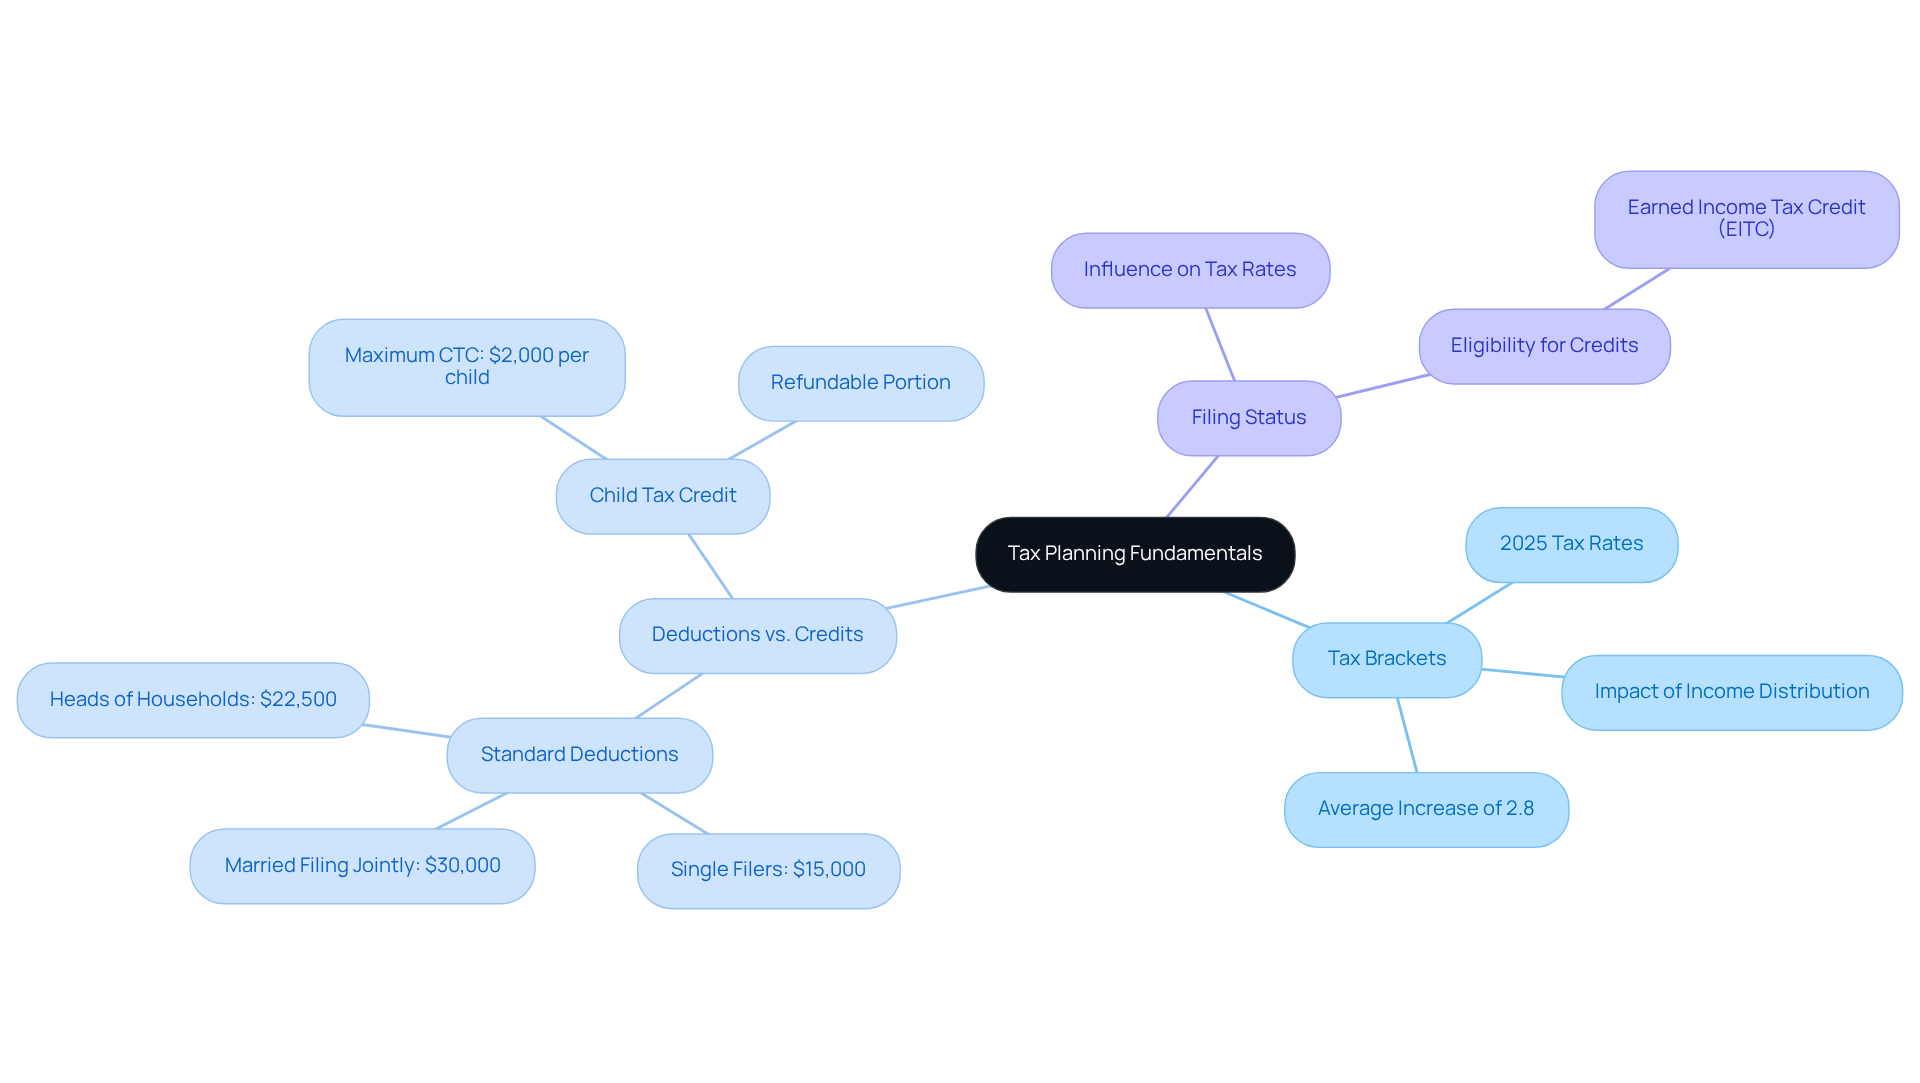
Tax Brackets: Understanding how income is taxed at different rates is crucial for strategizing your earnings and deductions. Imagine if you could optimize your income distribution across various brackets. For 2025, the IRS has announced new tax brackets with an average increase of 2.8%, reflecting adjustments due to cooled inflation. This knowledge empowers you to potentially lower your overall tax burden, giving you more resources for your family’s needs.
-
Deductions vs. Credits: It’s important to distinguish between deductions and credits. Deductions lower your taxable income, while credits directly reduce the amount of tax you owe. For instance, the standard deduction for single filers will rise to $15,000 in 2025, up $400 from the previous year. Understanding these differences can lead to significant savings, especially considering that the maximum Child Tax Credit (CTC) is $2,000 per qualifying child. This can substantially impact your family’s tax liability, allowing you to invest more in what matters most.
-
Filing Status: Choosing the right filing status—like single or married filing jointly—can greatly influence your tax rates and eligibility for various credits. For married couples filing jointly, the standard deduction will increase to $30,000 in 2025, an $800 increase from the prior year. This decision can affect your tax rate and the opportunity to claim credits such as the Earned Income Tax Credit (EITC), which is fully refundable and can provide significant financial assistance.
By mastering these fundamentals, you can build a strong foundation for tax planning strategies for individuals. Together, we can navigate the complexities of the tax system effectively, helping you enhance your family’s financial well-being. Remember, we’re here for you, guiding you every step of the way.
Explore Effective Tax Minimization Strategies
Effective tax reduction approaches are essential for enhancing financial well-being, especially for families striving to secure their future. Imagine if you could take control of your finances and create lasting stability for your loved ones. Here are some key approaches to consider:
-
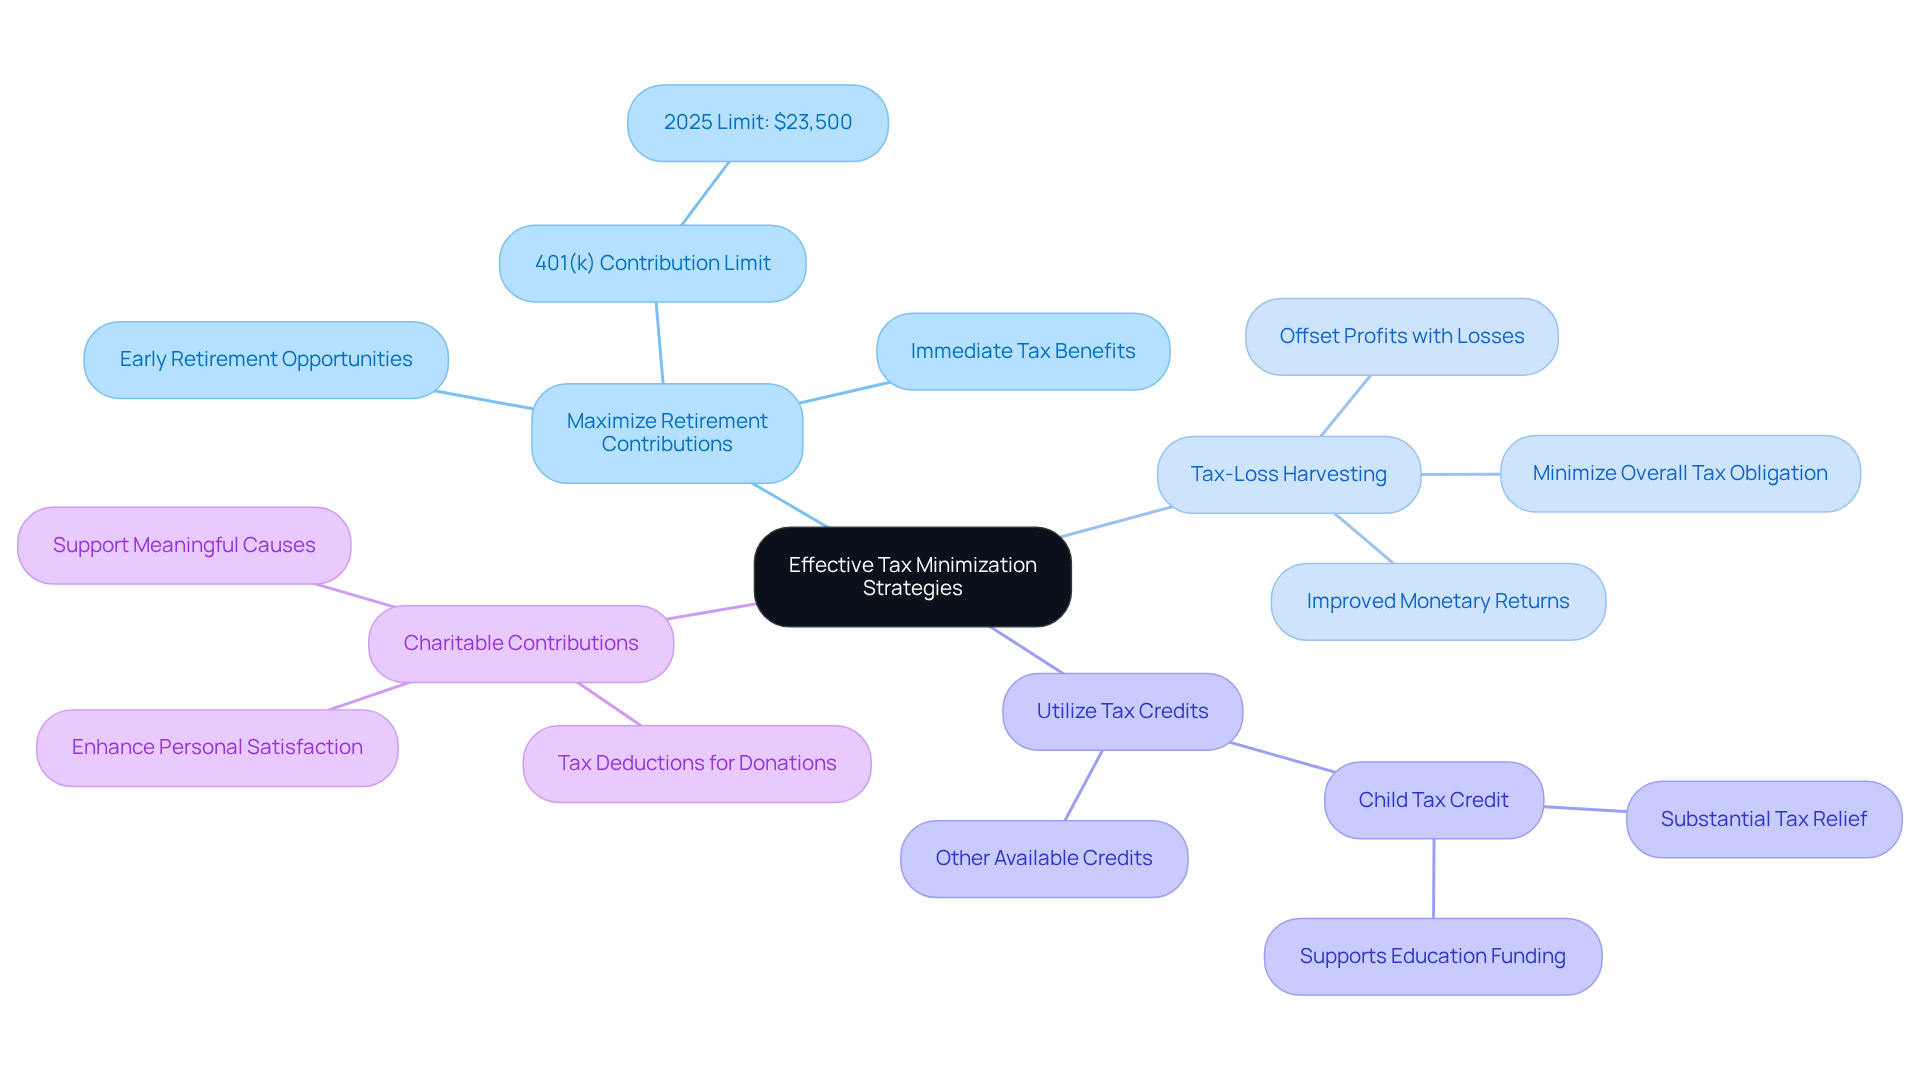
Maximize Retirement Contributions: Increasing contributions to retirement accounts like 401(k)s and IRAs can significantly lower your taxable income. For 2025, the 401(k) contribution limit will rise to $23,500, allowing you to save more while enjoying immediate tax benefits. Allison and Brian maximized their contributions, which played a crucial role in their ability to retire sooner, giving them more time to spend with family.
-
Tax-Loss Harvesting: This approach involves selling assets that have declined in value to offset profits from other investments, effectively lowering your overall tax obligation. For instance, if you sell a stock at a loss, you can use that loss to offset gains from a profitable investment, thus minimizing taxes owed. Allison and Brian successfully executed this strategy, improving their overall monetary returns and enhancing their financial security.
-
Utilize Tax Credits: Families should take full advantage of available tax credits, such as the Child Tax Credit, which can substantially decrease the amount of tax owed. By utilizing these credits, Allison and Brian ensured their children’s future through education funding, offering substantial monetary relief that supports their family’s goals.
-
Charitable Contributions: Donating to qualified charities not only supports meaningful causes but also offers tax deductions. This dual advantage can improve both personal satisfaction and economic efficiency, contributing positively to your household’s economic well-being.
By employing tax planning strategies for individuals, households like Allison and Brian can realize significant tax reductions, creating opportunities for enhanced economic well-being and stability. Together, we can navigate this journey, enabling you to spend more quality time with your loved ones.
Implement Personalized Tax Planning for Families
Personalized tax planning for families involves several key strategies that can significantly enhance financial outcomes:
-
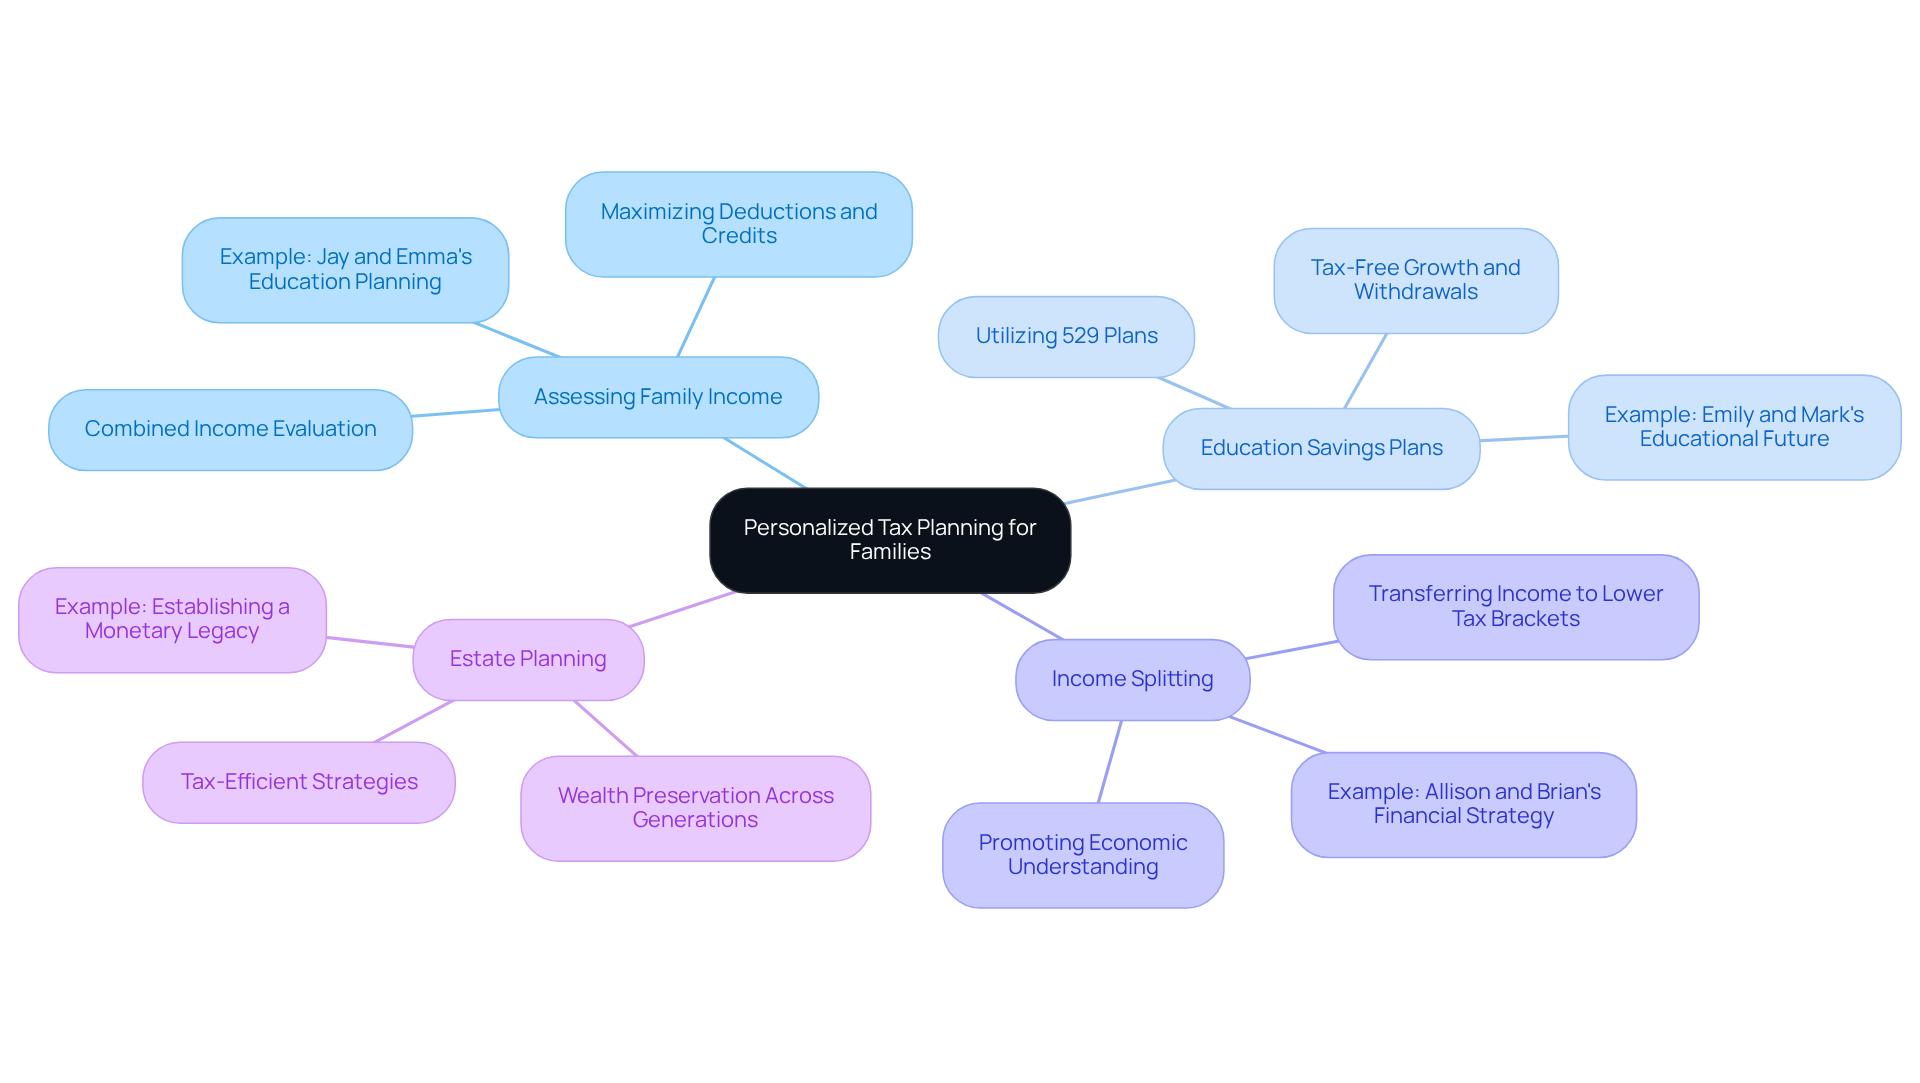
Assessing Family Income: Understanding the combined income of all family members is crucial. This evaluation allows households to effectively strategize deductions and credits, ensuring they maximize their tax benefits. Imagine Jay and Emma, who are managing economic obligations while preparing for their children’s education. A thorough income evaluation can truly enhance their tax circumstances.
-
Education Savings Plans: Utilizing 529 plans offers substantial tax advantages. Families can benefit from tax-free growth on investments within these plans, and withdrawals for qualified education expenses are also tax-exempt. This approach is especially important for Emily and Mark, who are focused on ensuring their children’s educational future while preserving economic flexibility.
-
Income Splitting: Transferring income to relatives in lower tax brackets can significantly reduce the overall tax burden. This strategy not only enhances tax obligations but also promotes economic understanding among younger family members. For instance, Allison and Brian, who aim to maximize their financial potential, can utilize income splitting to improve their overall financial plan.
-
Estate Planning: Incorporating tax-efficient estate planning strategies is essential for preserving wealth across generations. By planning in advance, households can reduce estate taxes and ensure that their assets are transferred according to their desires. This is vital for families striving to establish their monetary legacy, much like the goals of the households highlighted in our case studies.
By customizing tax planning strategies for individuals to address the specific needs of each household, individuals can enhance their tax results and ensure a more secure economic future. We’re here for you, and together, we can navigate this journey toward financial stability.
Leverage Technology for Efficient Tax Planning
Technology plays a crucial role in enhancing tax planning efficiency through several key avenues:
-
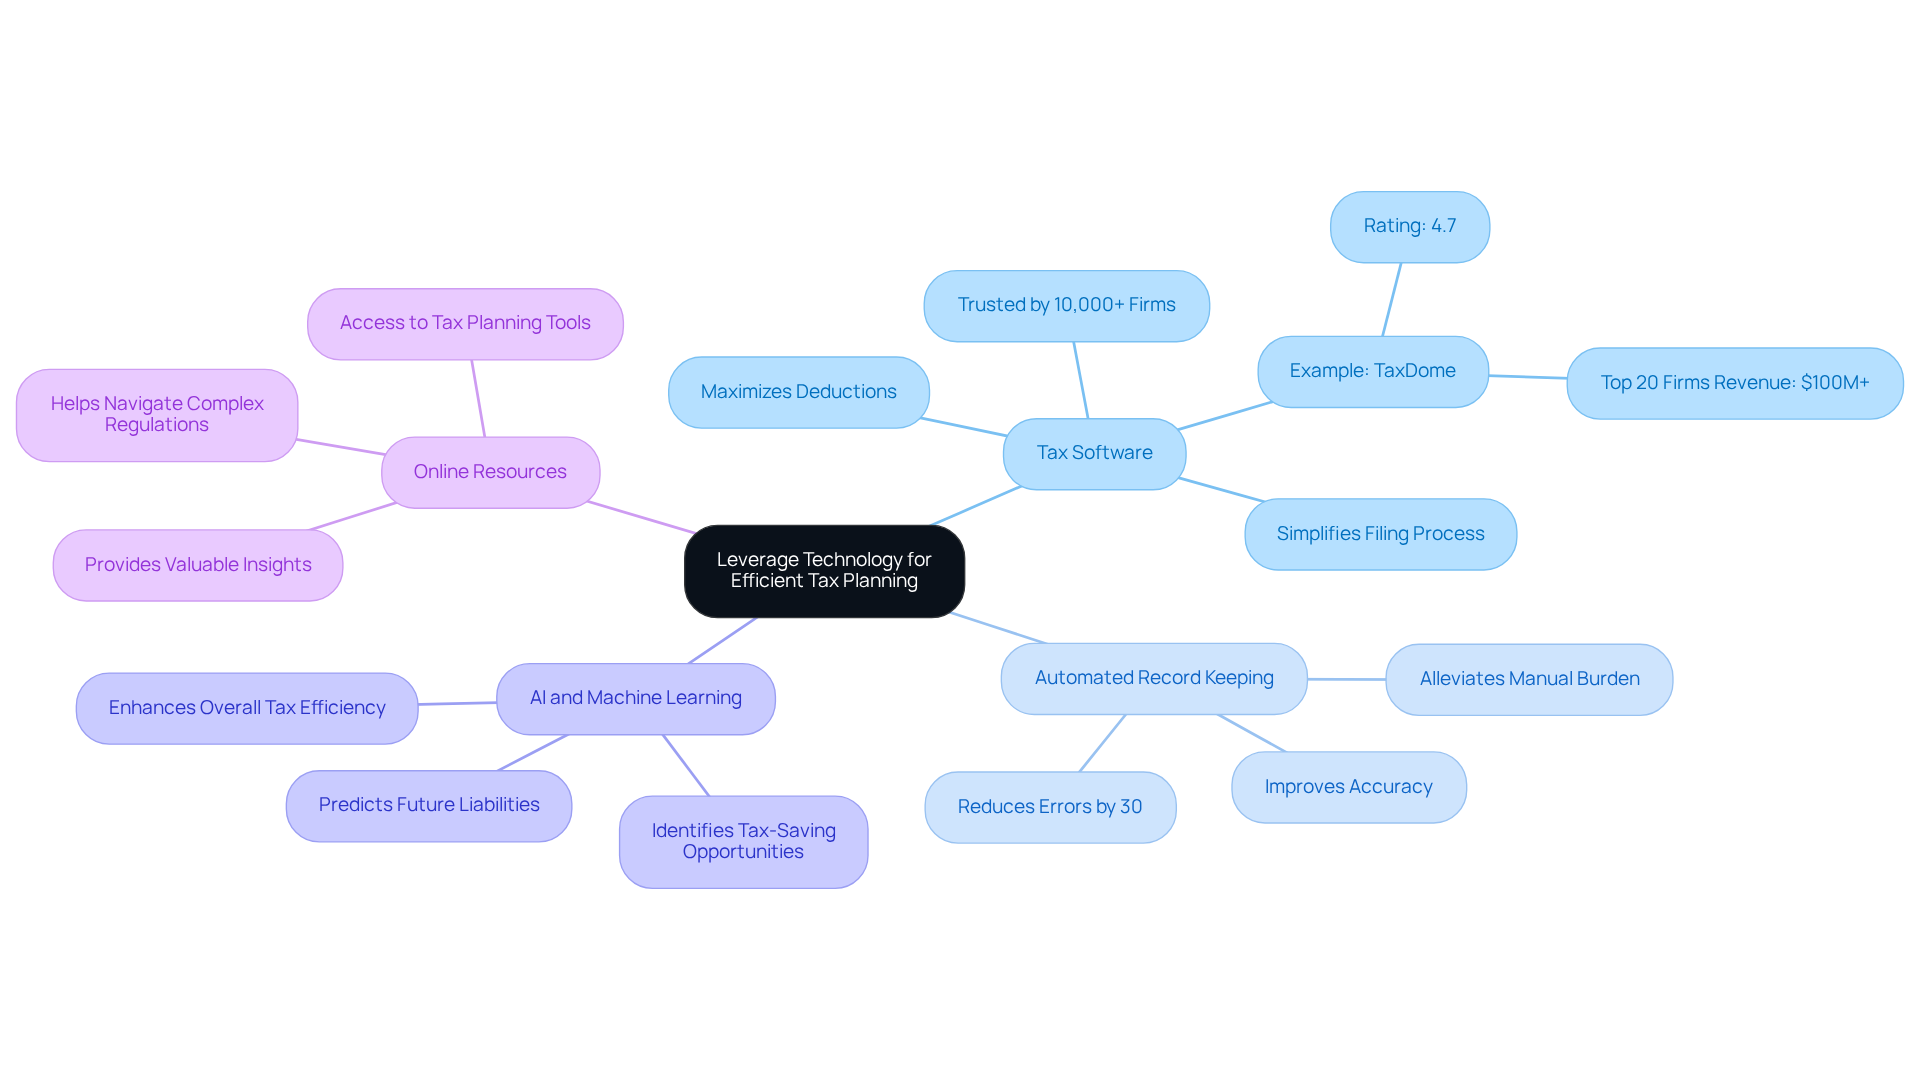
Tax Software: Imagine simplifying your filing process and ensuring compliance while maximizing deductions. In 2025, households can take advantage of top tax software alternatives tailored to their specific needs, such as TaxDome, trusted by over 10,000 accounting firms for its practice management features. This technology can assist families like Emily and Mark in streamlining their tax procedures, allowing them to focus on their financial goals. At Bright Advisers, we’re here to help you choose the right software that aligns with your monetary strategies.
-
Automated Record Keeping: It’s important to understand that digital tools for tracking expenses and income can alleviate the burden of manual record-keeping, significantly improving accuracy. Statistics show that automated record-keeping can reduce errors by up to 30%, giving families the freedom to focus on what truly matters. Bright Advisers offers guidance on effectively utilizing these tools to enhance your resource management.
-
AI and Machine Learning: Advanced technologies can analyze your financial data to uncover tax-saving opportunities and predict future liabilities. For instance, AI-driven platforms may identify spending patterns that lead to overlooked deductions, enhancing your overall tax efficiency. At Bright Advisers, we utilize these technologies to empower clients like Emily and Mark in their financial planning, ensuring you capitalize on every opportunity.
-
Online Resources: Accessing online tax planning tools and calculators enables households to make informed decisions. These resources provide valuable insights into tax strategies, helping families navigate complex regulations with ease. Bright Advisers encourages you to leverage these tools to enhance your understanding and streamline your tax filing experience.
By adopting these technological innovations, families can simplify their tax planning strategies for individuals, reduce mistakes, and ultimately save more money, ensuring a secure economic future. This approach supports not only your immediate financial needs but also aligns with long-term aspirations, as shown by the success stories of clients like Emily and Mark. Together, we can navigate this journey towards financial stability.
Conclusion
Understanding and implementing effective tax planning strategies is essential for families striving to optimize their finances. By grasping the fundamentals of tax brackets, deductions versus credits, and the significance of filing status, families can build a strong foundation for reducing their tax obligations. This knowledge empowers them to make informed financial decisions, ultimately enhancing their overall economic well-being.
Throughout this article, we’ve discussed several key strategies, such as:
- maximizing retirement contributions
- leveraging tax credits
- utilizing technology for efficient tax planning
Each of these approaches plays a vital role in minimizing tax liabilities and securing a more stable financial future. Consider the examples of families like Allison, Brian, Emily, and Mark; they demonstrate how these strategies can lead to significant savings and improved financial outcomes.
Incorporating these tax planning techniques can truly transform how families approach their finances. Imagine if, with the right knowledge and tools, you could take control of your economic destiny, ensuring you have the resources to invest in what matters most. Embracing these strategies not only fosters financial stability but also paves the way for a prosperous future.
We’re here for you, ready to support you on this important journey. Together, we can navigate the complexities of tax planning, ensuring your family thrives in every way possible.
Frequently Asked Questions
What is the importance of tax planning strategies for individuals?
Tax planning strategies help individuals examine their financial situation to legally reduce their tax obligations, ultimately enhancing their financial well-being.
How do tax brackets affect my tax planning?
Tax brackets determine how income is taxed at different rates, which is crucial for strategizing earnings and deductions. Understanding these brackets can help optimize income distribution and potentially lower overall tax burdens.
What are the new tax brackets for 2025?
For 2025, the IRS has announced new tax brackets with an average increase of 2.8%, reflecting adjustments due to cooled inflation.
What is the difference between deductions and credits?
Deductions lower your taxable income, while credits directly reduce the amount of tax you owe. Understanding this difference can lead to significant tax savings.
What is the standard deduction for single filers in 2025?
The standard deduction for single filers will rise to $15,000 in 2025, an increase of $400 from the previous year.
What is the maximum Child Tax Credit (CTC) for 2025?
The maximum Child Tax Credit (CTC) is $2,000 per qualifying child, which can significantly impact a family’s tax liability.
How does filing status influence tax rates and credits?
Choosing the right filing status, such as single or married filing jointly, can greatly influence tax rates and eligibility for various credits, affecting overall tax liability.
What will the standard deduction be for married couples filing jointly in 2025?
The standard deduction for married couples filing jointly will increase to $30,000 in 2025, an $800 increase from the prior year.
What is the Earned Income Tax Credit (EITC)?
The Earned Income Tax Credit (EITC) is a fully refundable tax credit that can provide significant financial assistance, particularly for low to moderate-income individuals and families.
List of Sources
- Understand the Fundamentals of Tax Planning
- taxfoundation.org (https://taxfoundation.org/data/all/federal/2025-tax-brackets)
- taxfoundation.org (https://taxfoundation.org/data/all/federal/latest-federal-income-tax-data-2025)
- 2025 Tax Brackets: IRS Bumps Up Income Cutoffs and Standard Deduction (https://money.com/new-tax-brackets-2025)
- 130 Inspirational Quotes About Taxes (https://inc.com/geoffrey-james/130-inspirational-quotes-about-taxes.html)
- What are tax credits and how do they differ from tax deductions? (https://taxpolicycenter.org/briefing-book/what-are-tax-credits-and-how-do-they-differ-tax-deductions)
- Explore Effective Tax Minimization Strategies
- The 13 Best Quotes about Investing – Mills Wealth Advisors (https://millswealthadvisors.com/11-best-quotes-investing)
- 9 Tax Tips That Could Save You Money on Your Taxes (https://ml.com/articles/tax-tips-that-could-save-you-money.html)
- 7 Quotes from Warren Buffett on How Retirees Should “Invest” in What Matters the Most (https://keenwealthadvisors.com/insights/7-quotes-from-warren-buffett-on-how-retirees-should-invest-in-what-matters-the-most)
- 10 brilliant compound interest quotes that will motivate you to save (https://unbiased.co.uk/discover/personal-finance/savings-investing/10-brilliant-compound-interest-quotes-that-will-motivate-you-to-save)
- Top Tax Loss Harvesting Strategies for HNW Investors 2025 (https://commonsllc.com/insights/tax-loss-harvesting-strategies)
- Implement Personalized Tax Planning for Families
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 14 Quotes From Our Favorite Money Saving Experts (https://chime.com/blog/quotes-from-money-saving-experts)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 200 Quotes About Money And Personal Finance To Inspire You (https://marriagekidsandmoney.com/20-empowering-quotes-about-money-and-personal-finance)
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- Leverage Technology for Efficient Tax Planning
- 50 funny and inspirational quotes for accountants, tax pros, and financial advisors – Blog (https://blog.taxdome.com/quotes-for-accountants)
- Making Tax Digital – HMRC Case Studies (https://stevejbicknell.com/2017/08/14/making-tax-digital-hmrc-case-studies)
- How is AI & Machine Learning revolutionizing the Tax Landscape? (https://taina.tech/resources-news-and-awards/how-is-ai-machine-learning-revolutionizing-the-tax-landscape)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading