

Key Highlights
- Understanding your tax bracket is crucial for managing finances and maximising take-home pay.
- High-tax states like California and New York significantly impact family budgets; awareness of tax implications is essential.
- Maximise contributions to retirement accounts, such as 401(k) and Roth IRA, to secure financial futures.
- Utilise employer matching contributions and Health Savings Accounts (HSAs) for additional tax benefits.
- Leverage deductions like mortgage interest, property taxes, and the Child Tax Credit to reduce taxable income.
- Consider strategic income management techniques, such as timing earnings and tax-loss harvesting, to optimise tax obligations.
- Regularly review and adjust withholding allowances to avoid overpaying taxes throughout the year.
- Stay informed about tax regulation changes that may affect financial planning and tax strategies.
Introduction
Imagine feeling overwhelmed by W-2 taxes while trying to secure your family’s future. Let’s explore four tax strategies that can help families with young children save money and find peace of mind. As tax laws change, it’s important to know how to manage your tax liabilities and maximize your benefits. By understanding these strategies, you can feel empowered to make informed decisions and be ready for the financial journey ahead.
Understand Your Tax Bracket and Implications
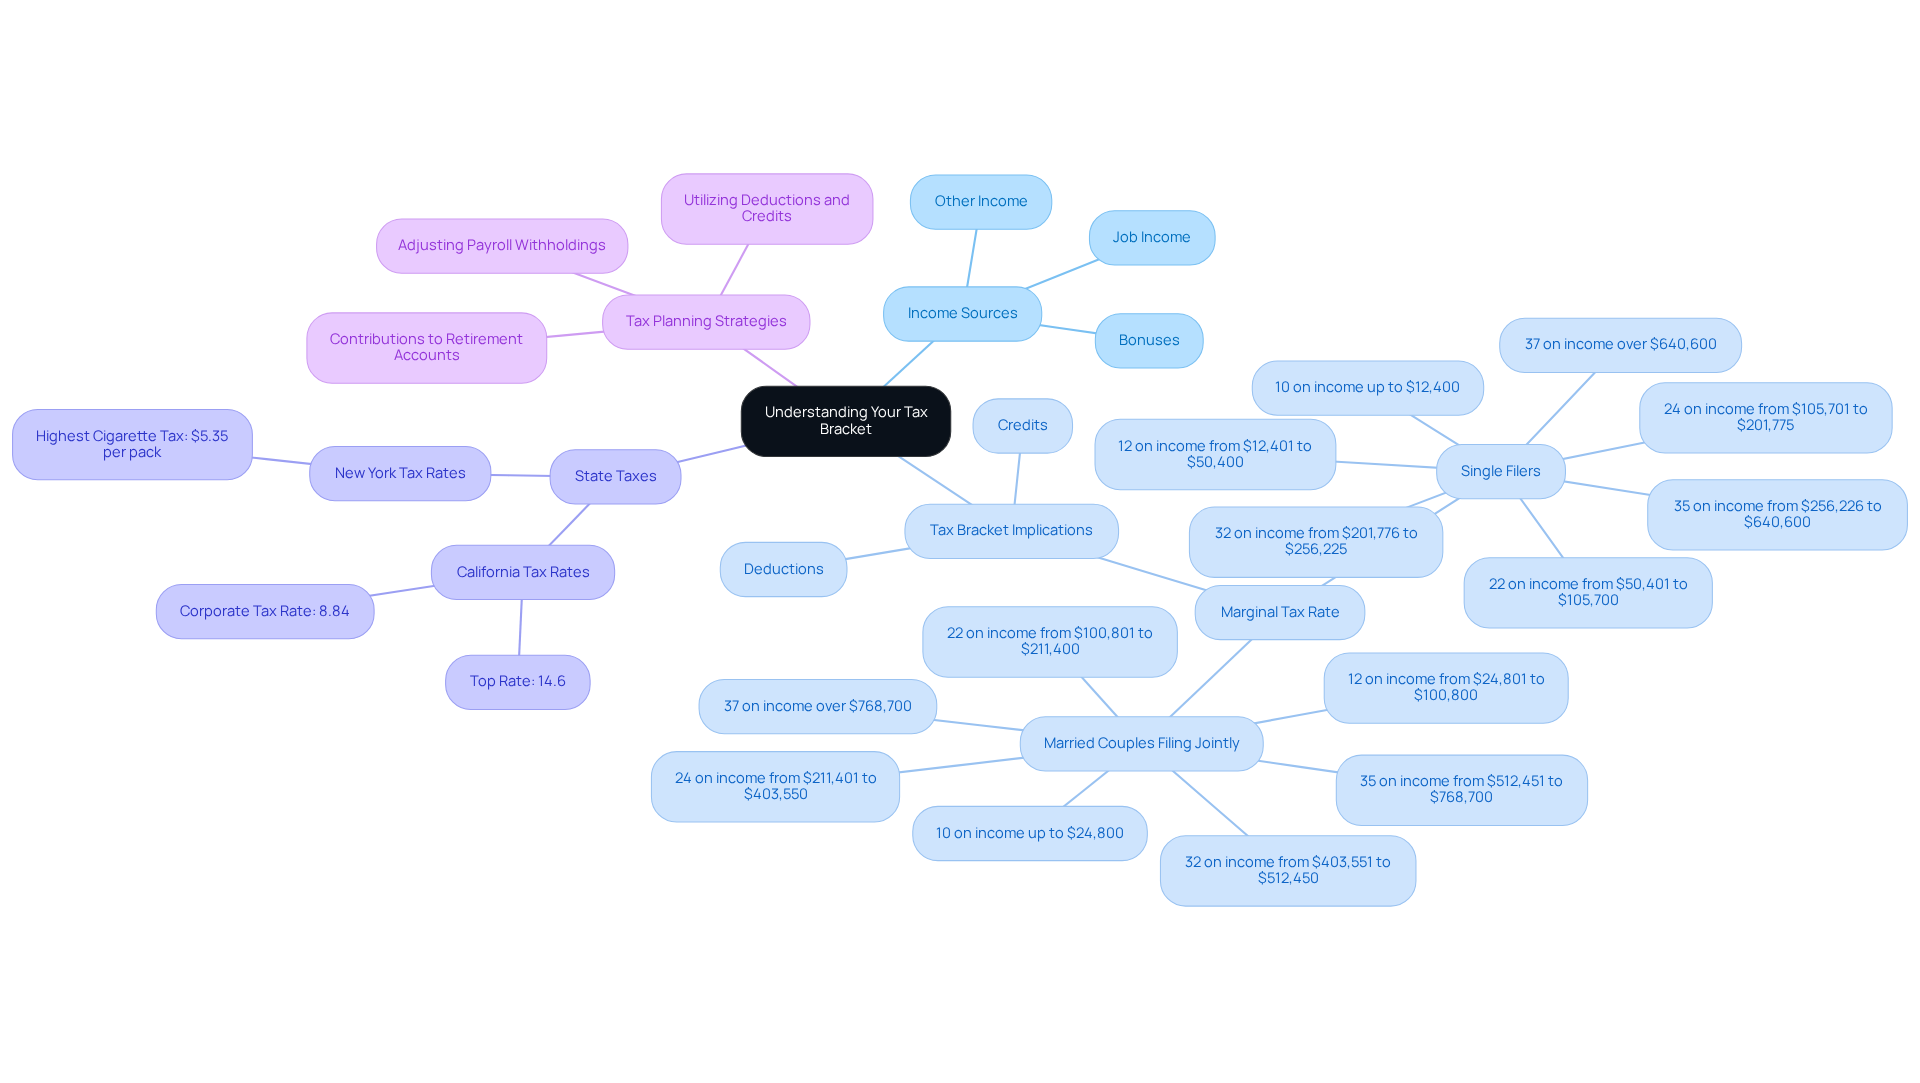
Navigating the world of taxes can feel overwhelming, especially when you’re trying to provide the best for your family. Let’s take a moment to explore your tax category based on your earnings, so you can feel more in control of your finances. It’s helpful to know your marginal tax rate, as it affects how much you keep from your hard-earned money. Think about how different income sources, like your job and bonuses, come together to shape your family’s financial landscape.
If you live in a state with high taxes, like California or New York, it’s important to understand how that impacts your family’s budget. As your earnings change, it’s good to be ready for how that might affect your tax situation and your family’s finances. Taking a yearly look at your tax bracket can help you make the most of available deductions and credits for your family. Keep in mind the AMT exemption amounts, as they can affect your overall tax picture.
Using online tax calculators can be a great way to see how different income scenarios might play out for your family’s finances. By understanding your tax situation, you can make choices that support your family’s future and peace of mind.
Maximize Contributions to Retirement Accounts
Imagine the weight of financial uncertainty as you think about your family’s future. How can you ease that burden? Enhancing deposits into retirement accounts is a gentle yet essential step for young families like Jay and Emma, who want to alleviate financial stress while preparing for what lies ahead. Let’s explore some gentle strategies that can help you on this journey:
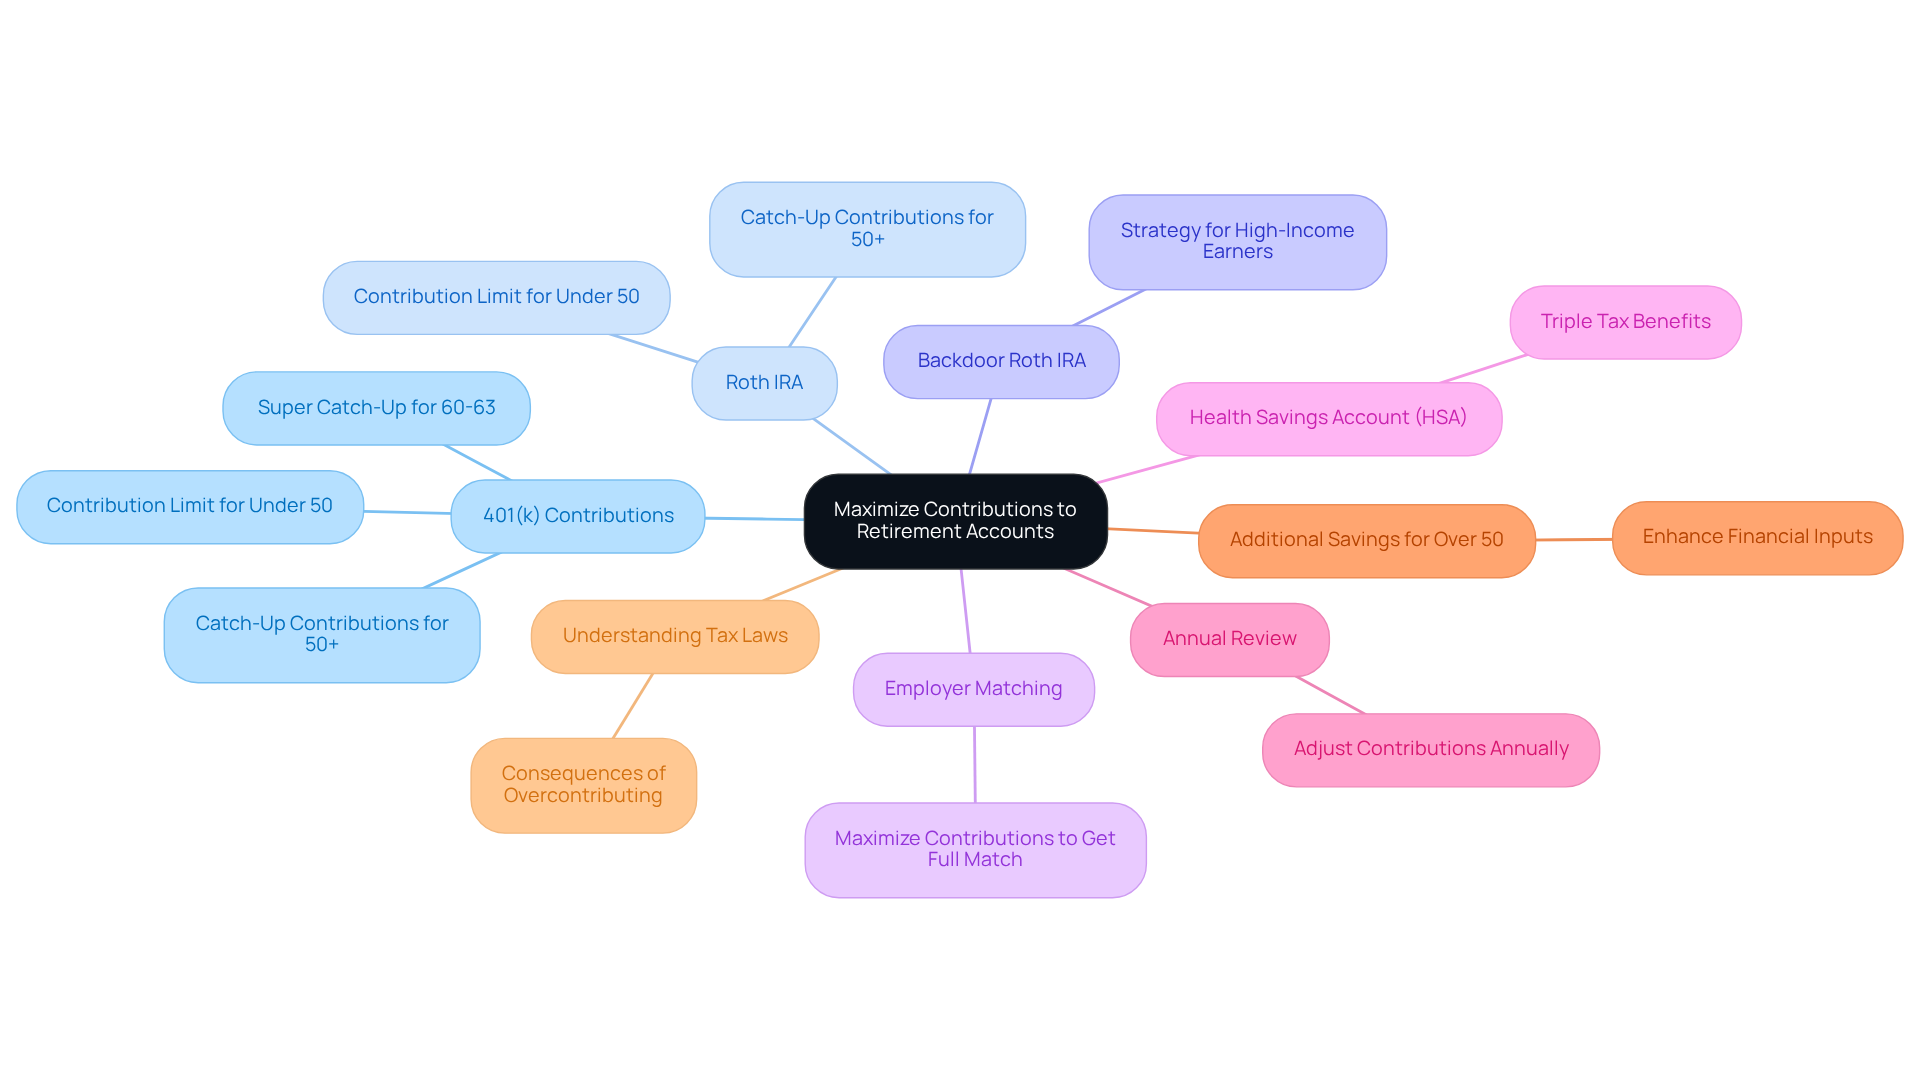
- Contribute the maximum allowable amount to your 401(k) or 403(b) plans. For 2026, the limit for these plans is set at $24,500 for individuals under age 50. If you’re 50 or older, you can add an extra $8,000 as a catch-up payment, raising your total to $32,500. And if you’re between 60 and 63, you can contribute an extra $11,250, totaling $35,750.
- Consider utilizing a Roth IRA for tax-free growth, especially if you anticipate being in a higher tax bracket during retirement. The highest allowable amount for a Roth IRA in 2026 is $7,500 for individuals under age 50, and $8,600 for those aged 50 and older, including catch-up amounts.
- Explore backdoor Roth IRA options if your income exceeds the limits for direct deposits. This W-2 tax strategy for high-income earners enables them to still benefit from tax-free growth.
- Utilize employer matching payments to enhance your retirement savings. Ensure you contribute enough to your 401(k) or 403(b) to receive the full employer match, as this is essentially free money for your retirement.
- If eligible, contribute to a Health Savings Account (HSA) for additional tax benefits. HSAs provide triple tax benefits: deposits are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are also tax-free.
- Review limits on deposits annually and adjust your payments to meet or exceed these thresholds. Staying informed about changes in funding limits can help you plan effectively.
- Consider additional savings if you are over 50 to further enhance your retirement savings. This enables you to enhance your financial inputs considerably as you near retirement.
- Understanding tax laws and regulations is crucial for effective retirement planning. Be aware of the potential consequences of overcontributing to a 403(b), which can lead to double taxation.
When families like Jay and Emma embrace these strategies, they can find peace of mind and build a brighter future for their children. Together, we can navigate these financial decisions, ensuring a secure and bright future for your family.
Leverage Deductions and Tax Credits Effectively
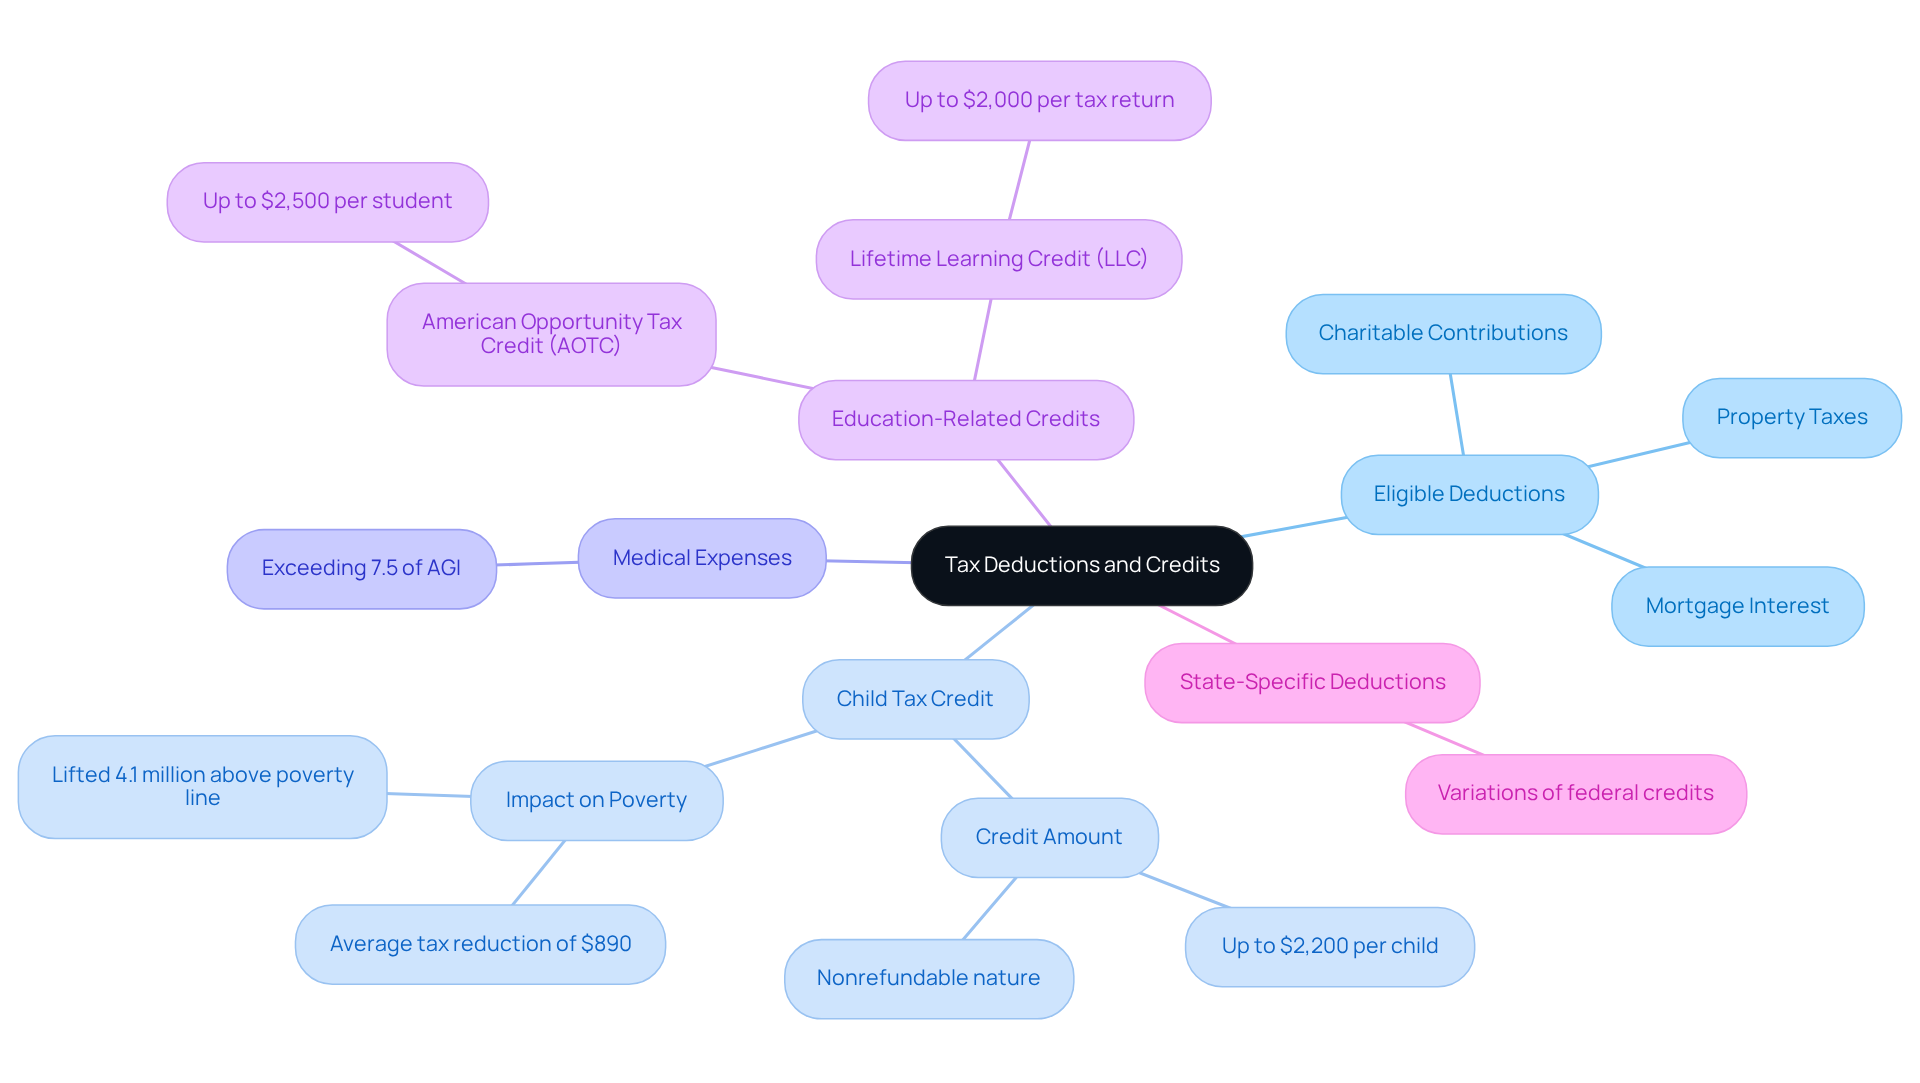
Imagine the relief of knowing you’re maximizing your family’s financial potential through smart tax deductions. Let’s explore the eligible deductions that can ease your financial burden, like:
- Mortgage interest
- Property taxes
- Charitable contributions
Don’t forget about the Child Tax Credit – it’s a wonderful way to save money for your family’s needs. If your eligible deductions are higher than the standard deduction, itemizing could be a smart choice for your family’s finances. Remember to keep an eye on medical expenses that exceed 7.5% of your adjusted gross earnings; they could lead to valuable deductions. If you’re investing in your children’s education, look into education-related tax credits that can help lighten the financial load. It’s also wise to review any state-specific deductions and credits that could benefit your family’s unique situation. And don’t hesitate to reach out to a tax professional; they can help you navigate these options and ensure you’re making the most of your deductions. With the right guidance, you can turn tax season into an opportunity for your family’s future.
Implement Strategic Income Management Techniques
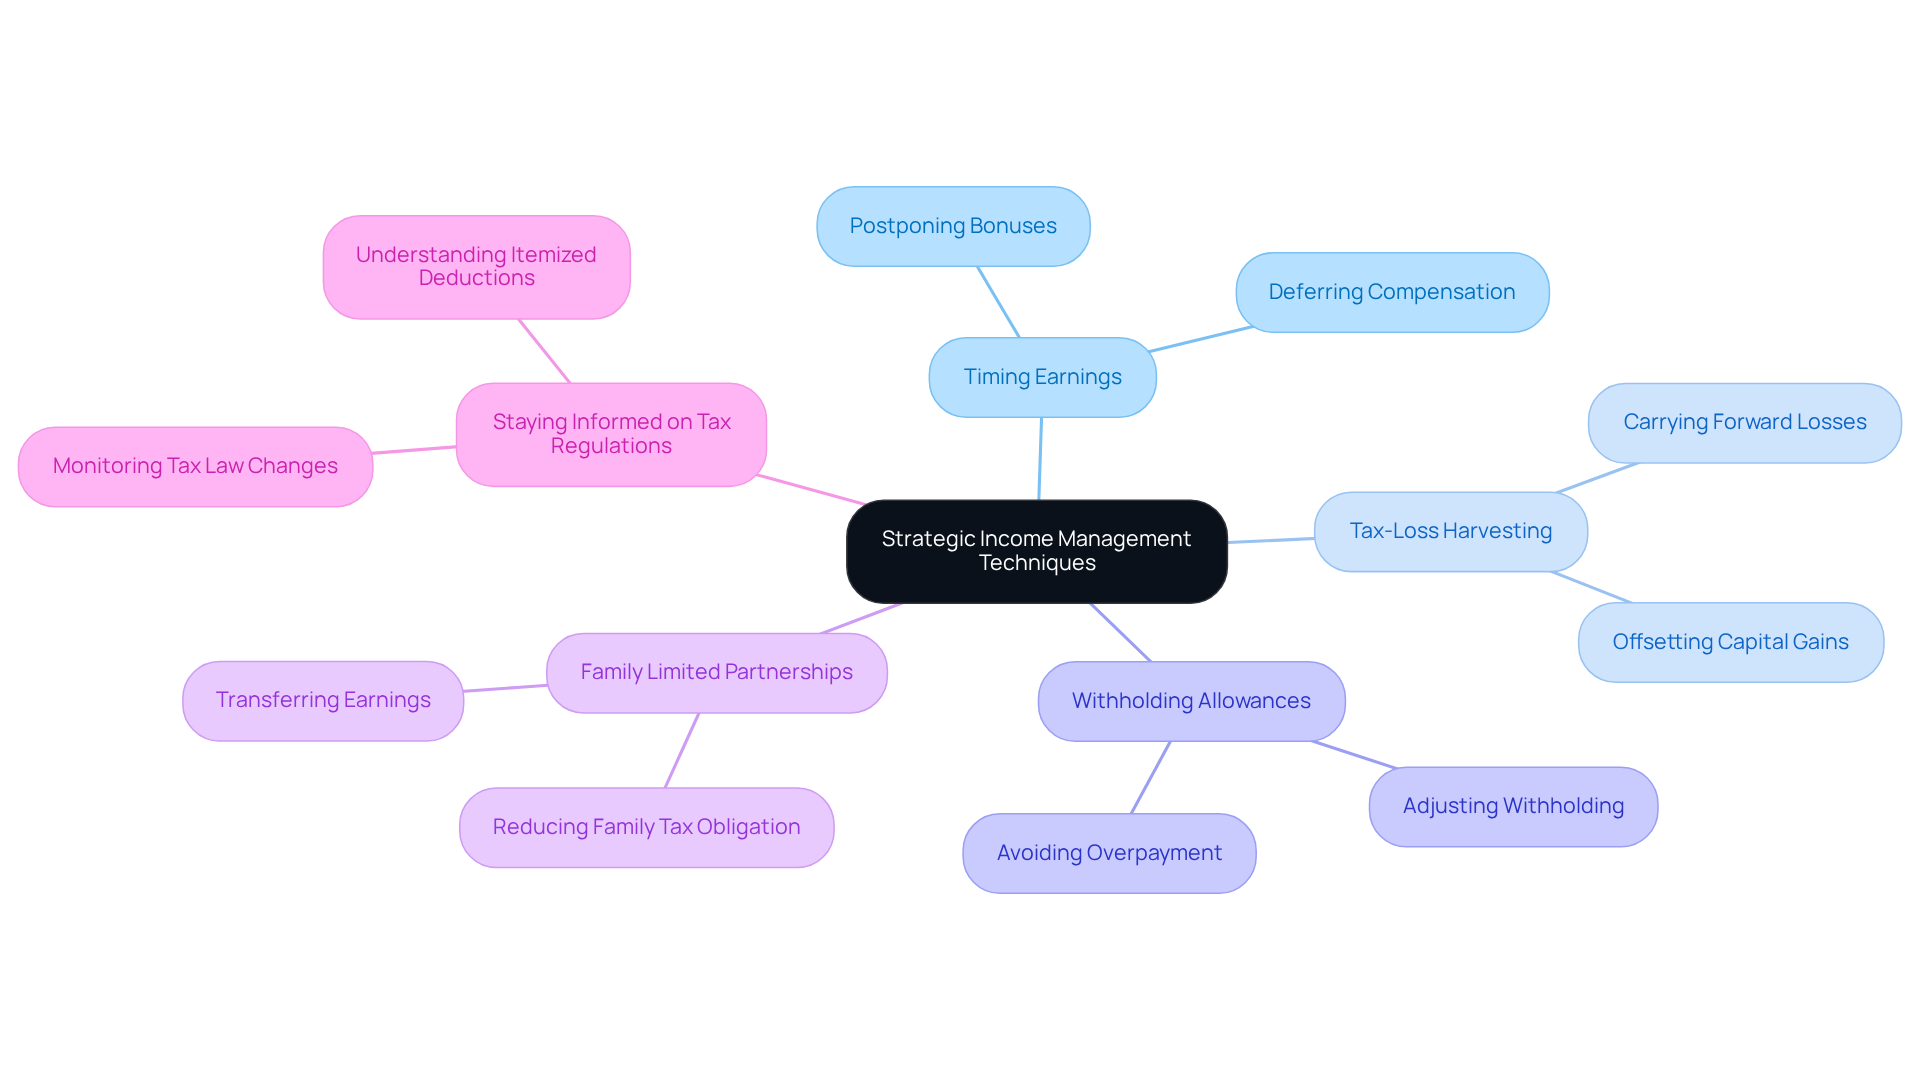
Imagine the worry of not knowing if you’re doing enough to secure your family’s future while managing your taxes effectively. Timing your earnings can be a smart way to navigate this challenge. For instance, if you expect a bonus or extra earnings, consider postponing it to a year when your total earnings may be lower. This approach can help decrease your tax obligation. With the support of Bright Advisers, Allison and Brian discovered how timing their earnings could ease their financial worries and help secure their family’s future.
Tax-loss harvesting can be a helpful tool for families, especially during those unpredictable market shifts. It’s all about finding what works best for your unique situation. By selling underperforming assets, you can offset capital gains with losses, lowering your taxable earnings. Thanks to Bright Advisers, Allison and Brian felt empowered to keep more of their hard-earned money, giving them peace of mind for their family’s future.
Have you considered postponing some of your earnings through deferred compensation plans? It could be a gentle way to manage your taxable income. The comprehensive financial plan that Bright Advisers developed for Allison and Brian included a w2 tax strategy for high income earners, enabling them to secure their children’s future through education funding.
It’s also important to review your withholding allowances to ensure you’re not overpaying taxes throughout the year. Adjusting your withholding can help you keep more of your earnings for investment or savings purposes. Bright Advisers emphasized this point to Allison and Brian, ensuring they kept more of their hard-earned money.
Creating a family limited partnership can also be beneficial for distributing earnings. This arrangement allows you to transfer earnings to family members in lower tax categories, potentially reducing the overall family tax obligation. Bright Advisers guided Allison and Brian in exploring this option, which contributed to their overall tax efficiency.
Stay informed about changes in tax regulations that may influence your financial management strategies. For example, starting in 2026, the value of itemized deductions for those in the highest tax bracket will be capped, which could influence your planning. Furthermore, the SALT deduction will return to $10,000 for earnings of $600,000 and above, which is important for implementing a w2 tax strategy for high income earners. Bright Advisers ensures families like Allison and Brian are informed and prepared for these changes.
Regularly assessing your income sources and adjusting your strategies can help align with your financial goals. Continuous monitoring can help you identify opportunities for tax efficiency and ensure that your financial plan remains effective. By incorporating tax optimization into their comprehensive financial plan, Allison and Brian experienced the peace of mind that comes with financial security, allowing them to enjoy more quality time with their loved ones.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Advisory services are provided through Lifeworks Advisors, a registered investment adviser.
Conclusion
Many parents feel overwhelmed by the complexities of tax planning, but understanding W-2 strategies can pave the way for a secure financial future. By grasping the nuances of tax brackets and maximizing retirement contributions, you can significantly reduce your tax liabilities and enhance your family’s overall well-being.
Imagine if you could leverage deductions and credits, like the Child Tax Credit, to provide substantial savings for your family. Knowing your tax bracket and its implications is essential, as it can lead to better financial decisions that resonate with your family values.
As you navigate the complexities of tax planning, remember that staying informed can empower you to secure your family’s financial future. Engaging with a fiduciary advisor can provide the necessary guidance to make informed decisions that align with your family’s unique goals. We’re here to help you navigate these decisions, ensuring they align with your family’s unique goals.
By taking these steps, you’re not just managing taxes; you’re investing in your family’s future.
Frequently Asked Questions
Why is it important to understand my tax bracket?
Understanding your tax bracket helps you know your marginal tax rate, which affects how much of your income you keep after taxes. This knowledge allows you to make informed financial decisions for your family.
How do different income sources impact my tax situation?
Different income sources, such as your job and bonuses, combine to shape your overall financial landscape. Knowing how these sources affect your tax bracket can help you plan better for your family’s finances.
What should I consider if I live in a state with high taxes?
If you live in a state with high taxes, like California or New York, it’s crucial to understand how these taxes impact your family’s budget and overall financial situation.
How often should I review my tax bracket?
It’s advisable to review your tax bracket yearly, especially as your earnings change. This can help you take advantage of available deductions and credits that may benefit your family.
What are AMT exemption amounts, and why are they important?
AMT exemption amounts can affect your overall tax picture. Being aware of these amounts is important for understanding your tax obligations and planning your finances accordingly.
How can online tax calculators assist me?
Online tax calculators can help you see how different income scenarios might affect your family’s finances, allowing you to make informed choices that support your family’s future.
List of Sources
- Understand Your Tax Bracket and Implications
- 2026 Tax Brackets (https://taxfoundation.org/data/all/federal/2026-tax-brackets)
- Tax brackets 2026 and federal income tax rates (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/2026-tax-brackets)
- 2026 individual tax brackets, and tips for understanding what you pay (https://principal.com/individuals/learn/individual-tax-brackets-understand-what-you-pay)
- Taxes in California (https://taxfoundation.org/location/california)
- 2026 Federal Income Tax Brackets and Interactive Calculator (https://bipartisanpolicy.org/explainer/2026-federal-income-tax-brackets-and-interactive-calculator)
- Maximize Contributions to Retirement Accounts
- Nationwide Retirement Plans (https://nrsforu.com/rsc-preauth/investing/irs-limits)
- 2026 retirement plan contribution limits (https://planmember.com/members/retirement-plan-contribution-limits)
- IRS Releases 2026 Limits for Benefit Plans (https://quarles.com/newsroom/publications/irs-releases-2026-limits-for-benefit-plans)
- 403(b) contribution limits 2026 | Fidelity (https://fidelity.com/learning-center/smart-money/403b-contribution-limits)
- Leverage Deductions and Tax Credits Effectively
- The Child Tax Credit (https://cbpp.org/research/federal-tax/the-child-tax-credit)
- How does the tax system subsidize child care expenses? (https://taxpolicycenter.org/briefing-book/how-does-tax-system-subsidize-child-care-expenses)
- 6 income tax breaks for parents | MassMutual (https://blog.massmutual.com/planning/tax-breaks-parents)
- Dependent Tax Deductions and Credits for Families (https://turbotax.intuit.com/tax-tips/family/tax-exemptions-and-deductions-for-families/L0Nx5Tnxi)
- How Much is My Child Tax Credit or Earned Income Tax Credit? 2026 Filing Season (https://bipartisanpolicy.org/article/how-much-is-my-child-tax-credit-or-earned-income-tax-credit-2026-filing-season)
- Implement Strategic Income Management Techniques
- Tax Planning for High Income Earners: Strategies to Preserve and Grow Wealth – Towerpoint Wealth (https://towerpointwealth.com/tax-planning-for-high-income-earners-strategies-to-preserve-and-grow-wealth)
- Advanced Tax Strategies for Shifting Income to Reduce Your Burden (https://epwealth.com/blog/advanced-tax-strategies-for-shifting-income-to-reduce-your-burden)
- 9 ways to potentially reduce your taxable income | Fidelity (https://fidelity.com/learning-center/personal-finance/how-to-reduce-taxable-income)
- Tax-loss harvesting explained | Vanguard (https://investor.vanguard.com/investor-resources-education/taxes/offset-gains-loss-harvesting)
- Continuous tax-loss harvesting yields more potential for tax benefits (https://am.jpmorgan.com/us/en/asset-management/adv/investment-strategies/separately-managed-accounts/tax-managed-solutions/continuous-tax-loss-harvesting-yields-more-potential-for-tax-savings)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading