

Overview
This article explores an important question for families: Are Restricted Stock Units (RSUs) a better financial option than cash? RSUs can provide shares delivered at vesting, offering a pathway to potential long-term wealth accumulation. Imagine if your financial decisions could align not only with your immediate needs but also with your family’s future success.
Consider the benefits of RSUs. They help to align employee interests with company success, creating a shared journey towards prosperity. This alignment can be particularly rewarding as you plan for retirement, ensuring that your financial choices support your family’s goals.
However, it’s essential to approach this with care. Managing taxes and liquidity is crucial in balancing your immediate financial needs with your long-term aspirations. Together, we can navigate this journey, ensuring that your financial strategy is as nurturing as your family values.
Ultimately, this decision is about more than just numbers; it’s about securing a brighter future for your loved ones. We’re here for you, ready to support you in making informed choices that resonate with your family’s needs and dreams.
Key Highlights:
- RSUs are equity compensation that convert into shares after vesting, offering employees ownership in the company.
- The vesting process encourages employee retention and aligns interests with company success, typically spanning several years.
- RSUs provide shares delivered at vesting, unlike stock options which require purchasing shares at a set price.
- They can enhance long-term financial planning and retirement savings, making them appealing for wealth accumulation.
- RSUs are taxed as ordinary income upon vesting, with potential capital gains tax upon sale, which requires careful financial planning.
- Strategies to mitigate tax burdens include timing sales, using tax-advantaged accounts, and charitable giving.
- Families must balance immediate financial needs with long-term goals, assessing liquidity and the potential appreciation of RSUs.
- Market volatility poses risks to RSUs, with over-concentration in company stock being a significant concern for financial security.
- Diversifying investments and selling shares upon vesting can help manage risks associated with RSUs.
Introduction
In the ever-changing world of employee compensation, Restricted Stock Units (RSUs) have become a vital resource for both companies and their employees. These equity compensation tools not only motivate employee performance but also play a significant role in long-term financial planning. Imagine if you could align your financial goals with your career—understanding RSUs is a key step toward that vision. As more organizations embrace RSUs, it’s essential for employees, especially young parents, to grasp their mechanics—from vesting schedules to tax implications—so they can optimize their financial future.
It’s important to understand that navigating the associated risks and aligning RSUs with your personal financial goals can empower families to build wealth and secure their financial stability. This journey might feel overwhelming, but remember, you’re not alone. This article delves into the intricacies of RSUs, offering insights designed to help you make informed decisions about your compensation and investments. Together, we can navigate this journey, ensuring that your family’s financial future is bright and secure.
Understand Restricted Stock Units (RSUs)
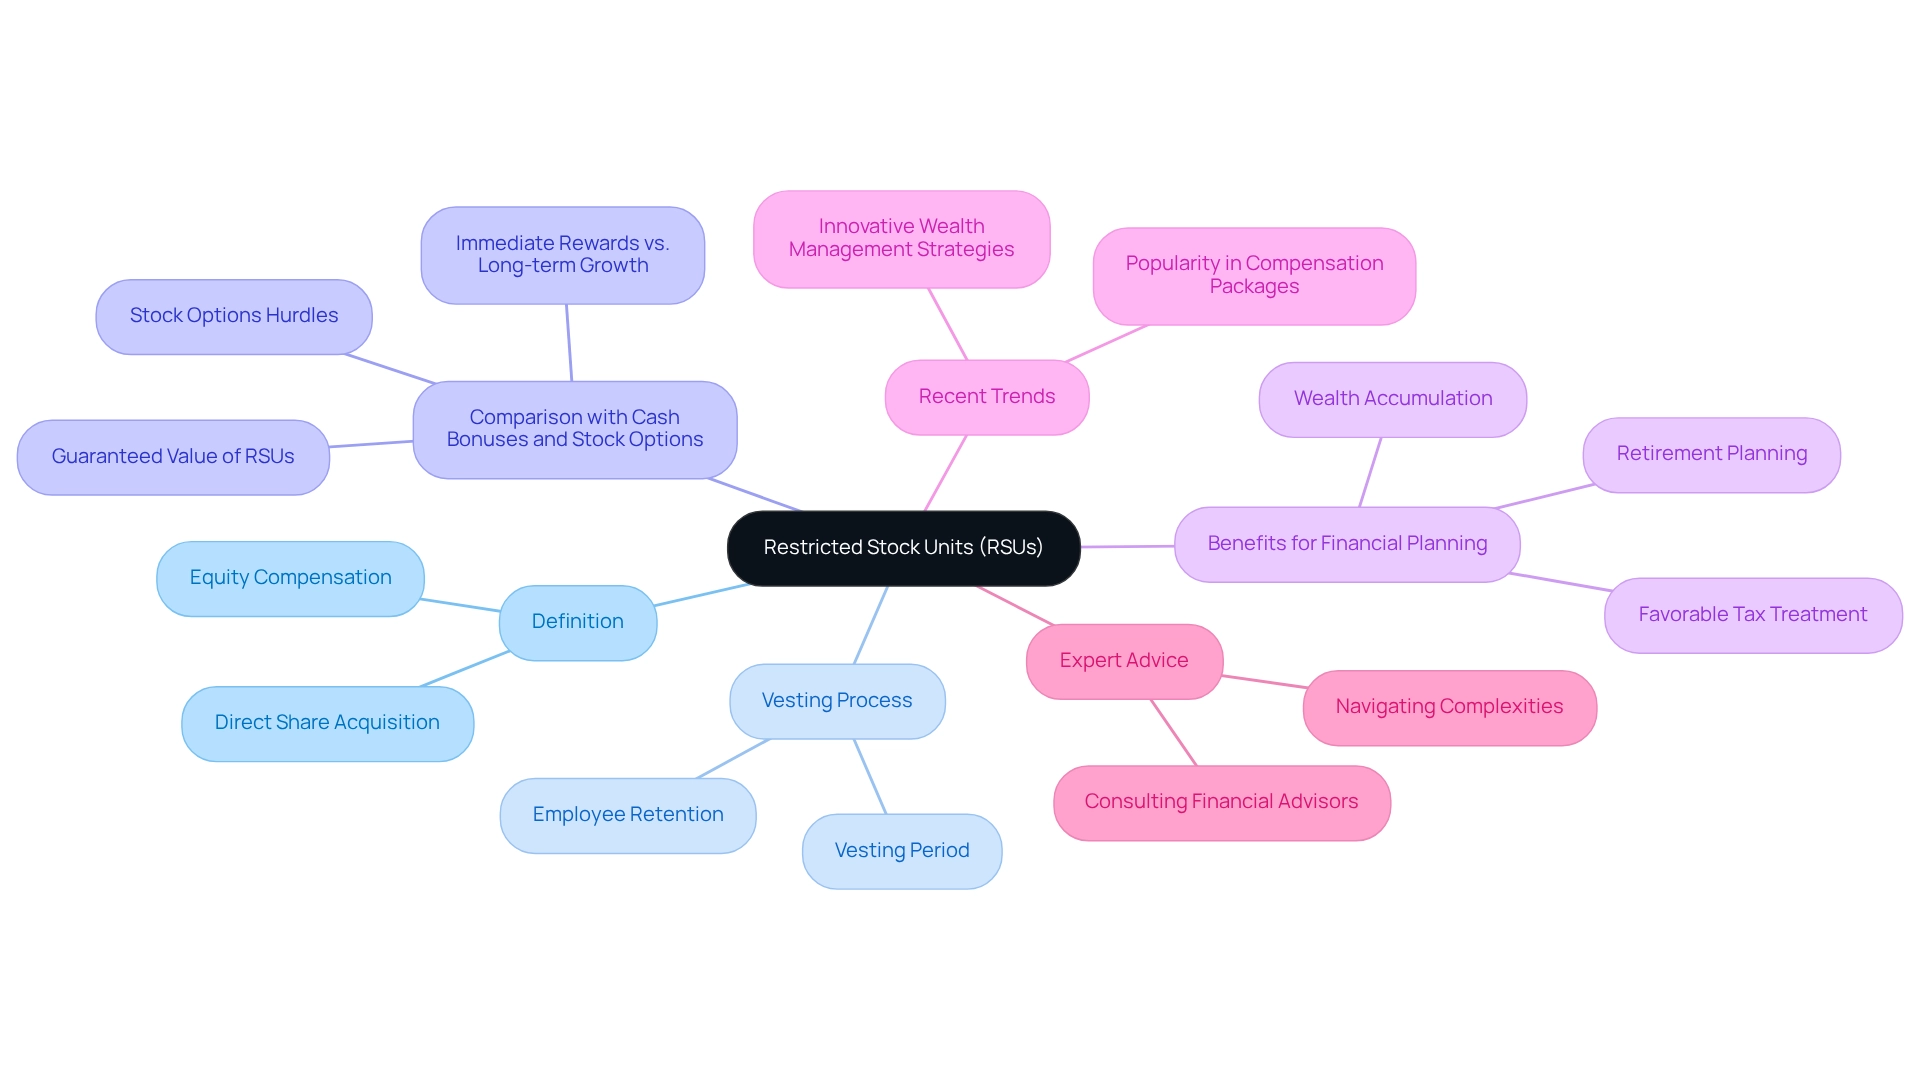
Restricted Stock Units (RSUs) are a valuable form of equity compensation that companies provide to their employees. They offer the opportunity to acquire shares of stock at a future date, typically after meeting certain conditions. Unlike stock options that allow employees to purchase shares at a predetermined price, RSUs are given directly, making them a simpler and more straightforward compensation option. Once these units vest, they convert into actual shares, granting employees ownership in the company.
The vesting process for RSUs is crucial, as it determines when employees gain full rights to their shares. Usually, RSUs vest over a specified period, often spanning several years. This approach not only encourages employee retention but also aligns their interests with the company’s long-term success. Imagine a common vesting schedule: a four-year period with annual or quarterly milestones. This structure helps employees feel invested in the company’s journey.
When considering if RSUs are better than cash bonuses or stock options, several differences come to light. While cash bonuses deliver immediate rewards, one might wonder if RSUs are better than cash when considering the potential for long-term growth associated with equity. Stock options require employees to buy shares at a set price, which can be a hurdle if the stock price doesn’t exceed that threshold. In contrast, RSUs provide a shares delivered at vesting, making them a more attractive choice for many employees.
The benefits of RSUs for long-term financial planning are significant. As more companies integrate RSUs into their compensation packages, employees can leverage this equity to build wealth over time. For instance, RSUs can play a crucial role in retirement planning, enabling employees to accumulate shares that may appreciate in value. Additionally, the favorable tax treatment of RSUs, especially when held for a longer duration, enhances their appeal as part of a comprehensive financial strategy tailored for families.
Recent statistics show that the popularity of RSUs in long-term incentive compensation is on the rise, with many companies planning to include them in their 2025 compensation packages. This trend highlights the growing recognition of RSUs as a valuable tool for employee retention and motivation, particularly in innovative wealth management strategies that focus on personalized investment portfolios, including Bright Advisers’ unique methods like smart beta and factor investing.
As the myStockOptions Editorial Team suggests, “If you are not at ease with making these decisions independently, talk about strategies with an investment consultant.” This expert advice underscores the importance of seeking professional guidance when navigating the complexities of RSUs and their impact on financial planning, especially for young families eager to enhance their wealth through Bright Advisers’ tailored investment approaches.
In summary, RSUs represent an appealing form of equity compensation that not only motivates employees but also supports them in achieving their long-term financial goals. As organizations continue to adopt RSUs, understanding their mechanics and benefits becomes essential for employees looking to secure their economic future. Together, we can navigate this journey and ensure a brighter tomorrow for your family.
Evaluate Tax Implications of RSUs
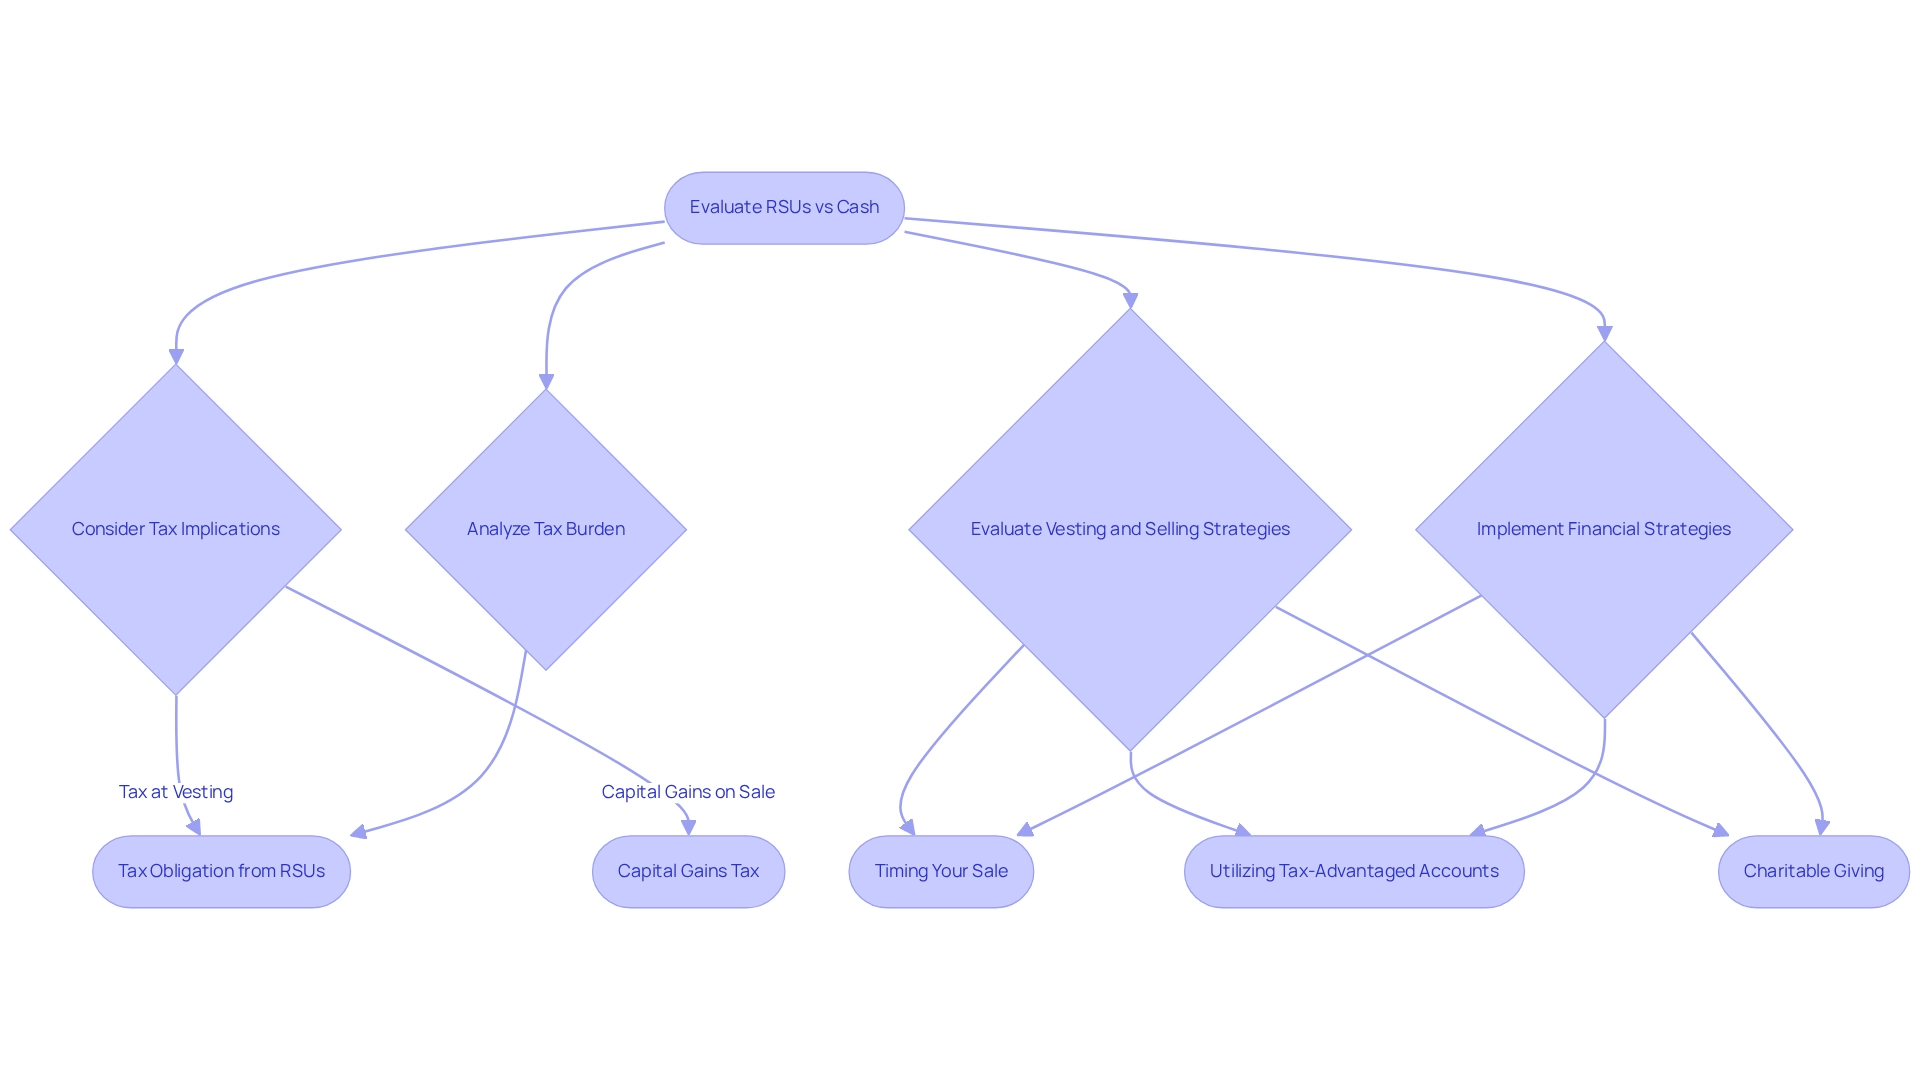
In your family’s financial planning journey, it is important to consider whether RSUs are better than cash. When these units vest, they are taxed as ordinary income, which means the fair market value of the shares at that moment is added to your taxable income. This can lead to a substantial tax obligation, especially if RSUs make up a large portion of your earnings.
Imagine if you sold your RSUs after they vested—capital gains taxes would then come into play. Any increase in value from the vesting date to the sale date is subject to capital gains tax. As of 2025, the average capital gains tax rate in the U.S. hovers around 15%, but this can vary based on your income level and how long you hold the shares post-vesting. Understanding these tax events is crucial for effective financial planning. Just like Allison and Brian, who worked with Bright Advisers to navigate their financial complexities and optimize their tax situation, you too can find support in managing these challenges.
To ease the tax burden associated with RSUs, you might want to evaluate whether RSUs are better than cash through several strategies. Timing your sale can be beneficial; for instance, selling shares in a year when your income is lower may reduce your overall tax load. Additionally, utilizing tax-advantaged accounts, such as IRAs or 401(k)s, can help defer taxes and maximize your savings. You might also think about charitable giving, which allows you to contribute appreciated stock units, lowering your taxable income while supporting meaningful causes. Furthermore, adopting a Rule 10b5-1 trading plan can help you avoid insider trading issues, providing a systematic way to sell your RSUs.
For example, if your household receives equity awards valued at $50,000 upon vesting, you could face a tax obligation of around $15,000 if you fall into the 30% tax bracket. Should you decide to sell the shares after a year, any increase in value would incur capital gains tax, complicating your financial situation further. As Nina Semczuk, a former Senior Editor, wisely notes, “employees should be aware of the vesting schedule and the tax implications once shares vest.” By understanding these implications and employing strategic planning, you can manage the complexities of RSUs more effectively, especially when considering if RSUs are better than cash, ensuring your financial choices align with your long-term goals. This journey mirrors that of Allison and Brian, who, through thoughtful tax planning with Bright Advisers, secured their financial future and maximized their wealth accumulation potential.
We’re here for you, ready to help you navigate this journey together. By grasping these concepts and utilizing the right strategies, you can empower your family’s financial future with confidence.
Assess Financial Goals and Liquidity Needs
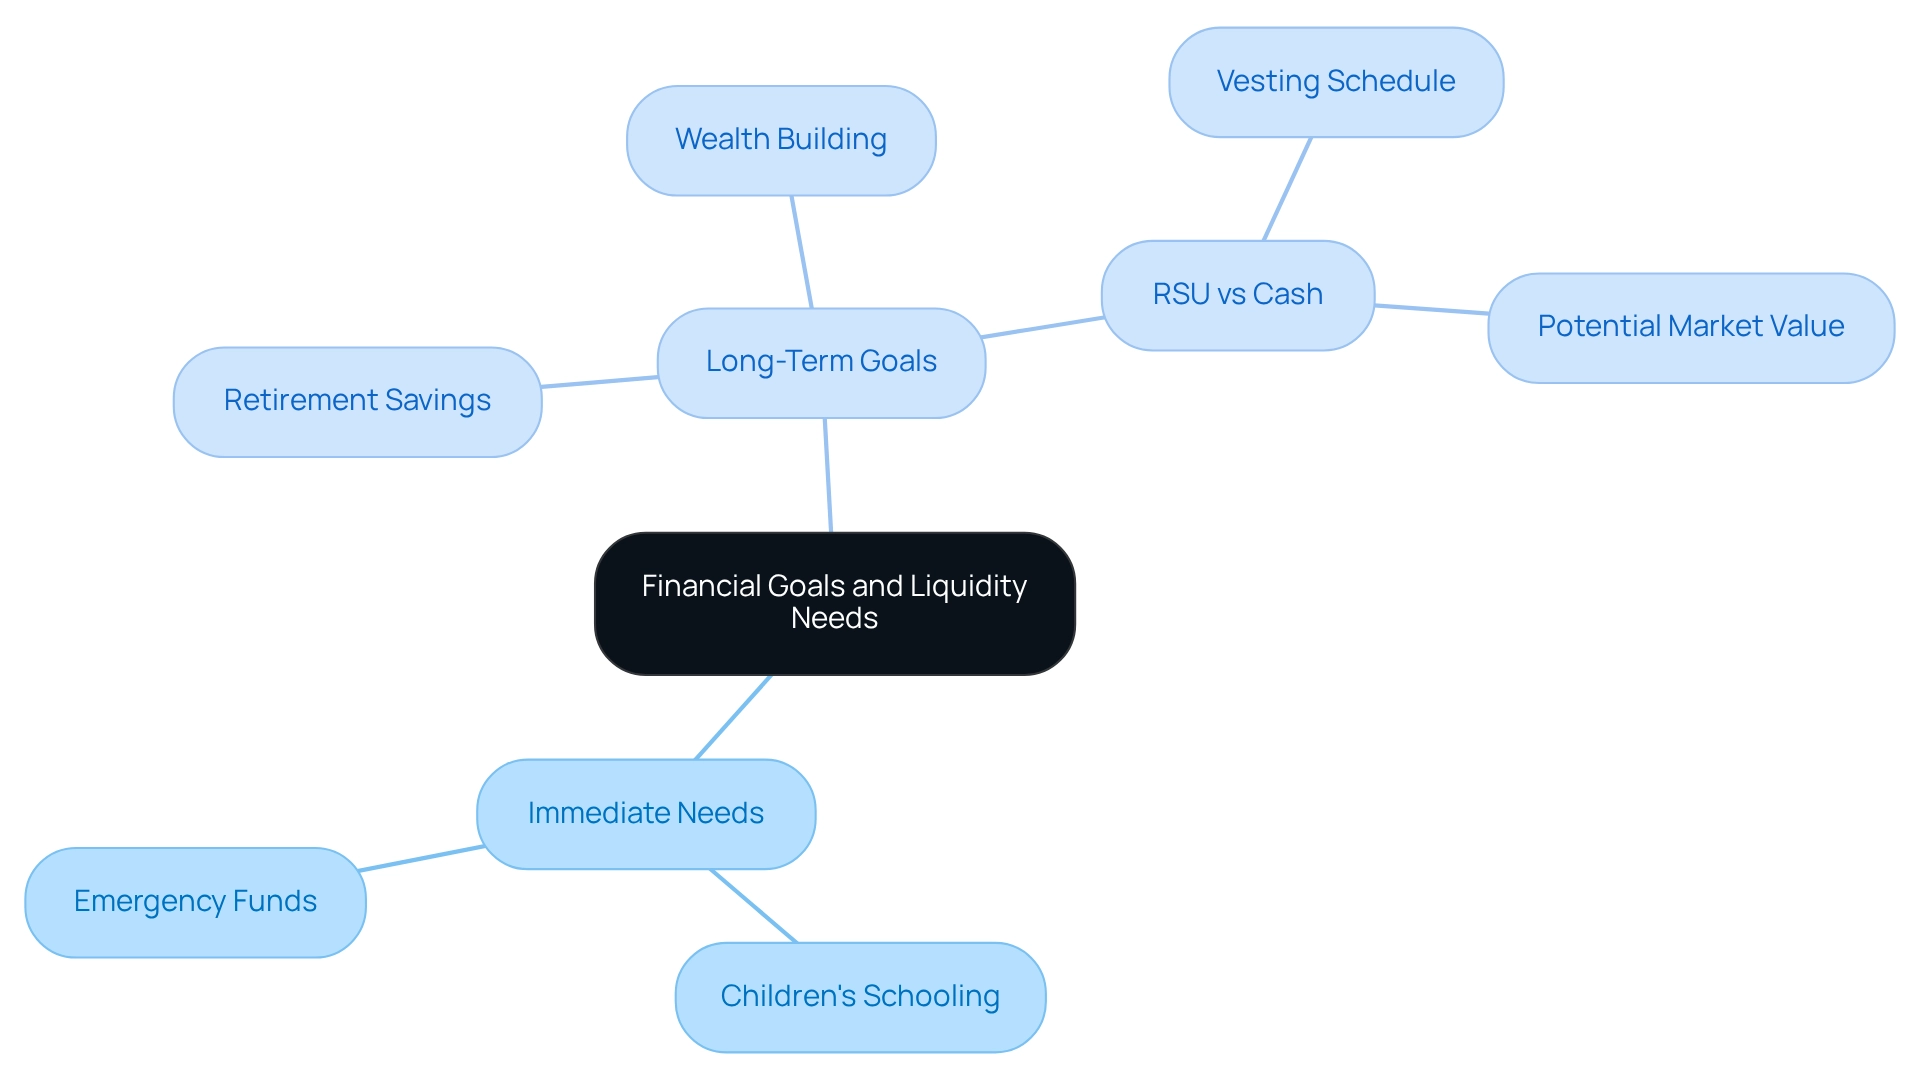
Recognizing immediate monetary needs is essential for households, especially when it comes to costs like children’s schooling and unforeseen emergencies. In 2025, many young families are facing rising living expenses, making it crucial to prioritize these urgent financial responsibilities. Statistics reveal that a significant number of consumers feel overwhelmed by their finances, highlighting the importance of effective budgeting and savings strategies. Notably, 49% of U.S. adults who are informed about personal finance learned from relatives and friends, emphasizing the value of these sources in economic education.
Long-term financial goals, such as retirement savings and wealth building, are equally important. Wealth management specialists emphasize that determining if RSU is better than cash can play a pivotal role in achieving these objectives. By utilizing restricted stock units, families can potentially enhance their retirement savings, leading to the consideration of whether RSU is better than cash, as these assets often appreciate over time, providing a valuable financial cushion for the future. According to PEW, saving money is a priority for 56% of individuals, further underscoring the need for families to focus on their savings strategies. When considering how restricted stock units can fulfill these financial goals, one must evaluate if RSU is better than cash by examining their vesting schedule and potential market value. Families should assess their liquidity needs in relation to their financial objectives, ensuring they can manage short-term expenses while also investing in long-term growth.
Imagine Emily and Mark, a young couple supported by Bright Advisers. They successfully navigated their planning by understanding their financial situation and crafting a comprehensive strategy that involved optimizing their stock options through Bright Advisers’ innovative investment approaches. This method not only focused on their immediate needs but also empowered them to make informed decisions about their future, including the question of whether RSU is better than cash. Remember, we’re here for you—together, we can navigate this journey toward financial security.
Consider Risks of Holding RSUs
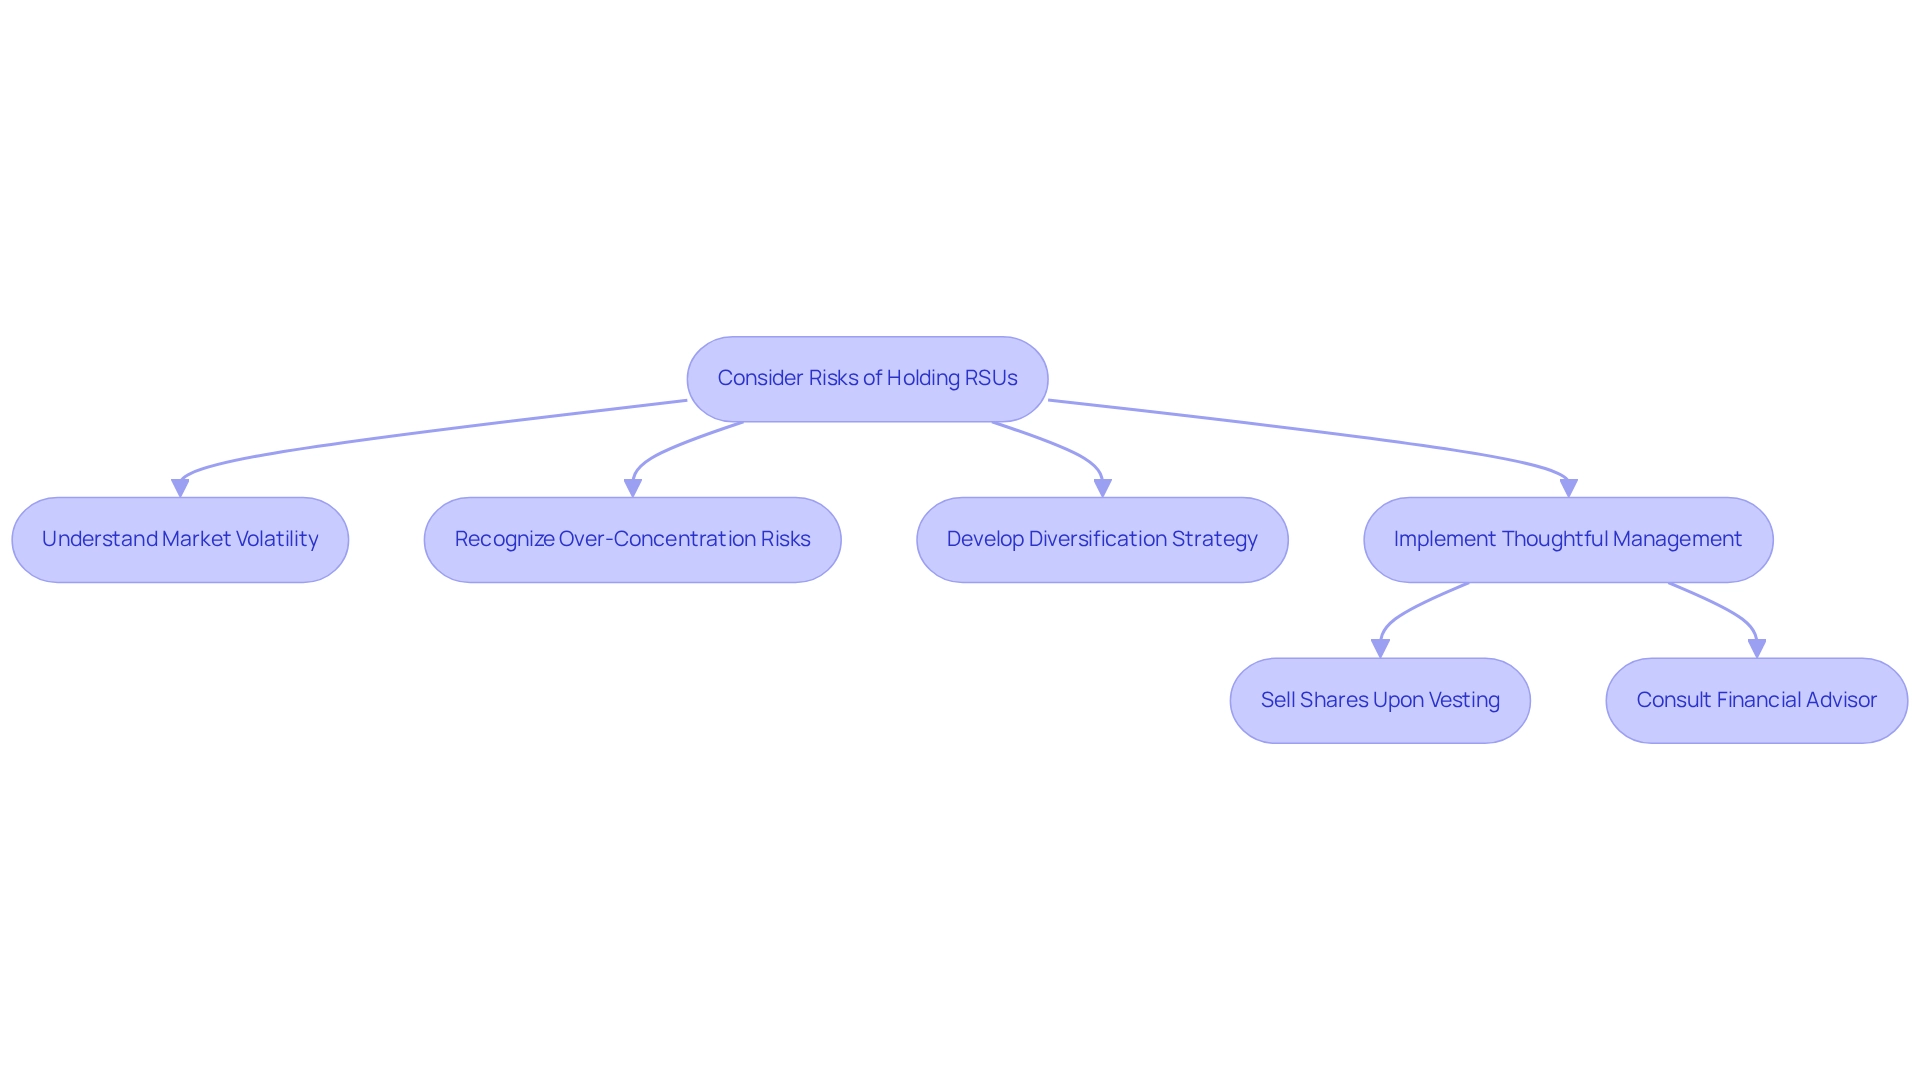
Market volatility can significantly impact the value of Restricted Stock Units (RSUs), making it crucial for families to understand the associated risks. Fluctuations in the stock market can lead to substantial changes in the worth of these units, affecting not just investment portfolios but also overall economic stability. Imagine if a family’s wealth is closely tied to their employer’s stock; a downturn could threaten their financial security, especially if they depend on these assets for future expenses like education or retirement.
Over-concentration in company stock is a serious concern. Financial advisors often suggest that no more than 10% of an investment portfolio should be allocated to employer stock, particularly for families with $1,000,000 in investable assets. This guideline is essential for reducing the risk of significant losses during market downturns. It’s important to recognize that placing a large portion of wealth in one stock may lead to inadequate diversification, increasing vulnerability to market fluctuations. Additionally, unvested RSUs can be forfeited if employment ends, adding another layer of risk. This potential loss highlights the need for a thoughtful strategy in managing RSUs effectively. Understanding the provisions and restrictions on these units is vital. To mitigate these risks, families can consider diversifying their investments across various asset classes and sectors. Selling shares upon vesting can also be a wise strategy, allowing families to realize gains while minimizing exposure to market volatility.
Consider the experiences of families who have faced these challenges. For example, Jay and Emma, a couple seeking to ease financial stress, felt considerable pressure when their employer’s stock dropped sharply, highlighting the risks of over-concentration. They worked closely with their financial consultant to develop a comprehensive plan that included improving their tax situation and exploring education savings options. In contrast, Emily and Mark, who aimed for financial independence, diversified their investments and adhered to the 10% guideline, maintaining stability despite market fluctuations. By understanding these risks and implementing thoughtful strategies, families can better protect their financial future while managing their RSUs. Together, we can navigate this journey toward financial security.
Conclusion
Restricted Stock Units (RSUs) have become an essential part of employee compensation, offering meaningful benefits for both personal and financial growth. Understanding how RSUs work, including vesting schedules and tax implications, empowers you to align your financial goals with your career path. By leveraging RSUs, you can build wealth over time, making these equity compensation tools vital for families striving to secure their financial futures.
However, navigating the complexities of RSUs requires thoughtful consideration of tax liabilities and market risks. It’s important for families to proactively assess their financial needs, both short-term and long-term, ensuring that their strategies are well-rounded and effective. The potential for capital gains taxes and the impact of market volatility highlight the importance of diversification and strategic planning. By collaborating with financial advisors and adopting sound investment strategies, families can mitigate risks and optimize their RSUs for maximum benefit.
Ultimately, as the landscape of employee compensation evolves, so too does the importance of understanding and effectively managing RSUs. This knowledge not only enhances your financial security but also facilitates informed decision-making, allowing you to focus on achieving your aspirations and building a stable financial future. Embracing this approach can transform how RSUs contribute to wealth accumulation, ensuring that you are well-equipped to navigate your financial journey with confidence. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What are Restricted Stock Units (RSUs)?
RSUs are a form of equity compensation provided by companies to employees, allowing them to acquire shares of stock in the future after meeting certain conditions. Unlike stock options, which require employees to purchase shares at a set price, RSUs are given directly.
How does the vesting process for RSUs work?
The vesting process is crucial as it determines when employees gain full rights to their shares. RSUs typically vest over a specified period, often several years, encouraging employee retention and aligning their interests with the company’s long-term success.
What is a common vesting schedule for RSUs?
A common vesting schedule for RSUs is a four-year period with annual or quarterly milestones, helping employees feel invested in the company’s journey.
How do RSUs compare to cash bonuses and stock options?
Cash bonuses provide immediate rewards, while RSUs offer potential long-term growth through equity. Unlike stock options, which require employees to buy shares at a predetermined price, RSUs have shares delivered at vesting, making them more attractive for many employees.
What are the benefits of RSUs for long-term financial planning?
RSUs can significantly contribute to long-term financial planning by enabling employees to accumulate shares that may appreciate in value, aiding in retirement planning. They also have favorable tax treatment when held for a longer duration, enhancing their appeal.
Are RSUs becoming more popular in compensation packages?
Yes, recent statistics indicate that the popularity of RSUs in long-term incentive compensation is rising, with many companies planning to include them in their 2025 compensation packages.
What should employees consider when navigating RSUs and financial planning?
Employees are encouraged to seek professional guidance from investment consultants to navigate the complexities of RSUs and their impact on financial planning, especially for young families looking to enhance their wealth.
What overall role do RSUs play in employee motivation and financial goals?
RSUs represent an appealing form of equity compensation that motivates employees and supports them in achieving their long-term financial goals, making it essential for employees to understand their mechanics and benefits.
List of Sources
- Understand Restricted Stock Units (RSUs)
- Restricted Stock Units: 10 Fast Facts (https://foley.com/insights/publications/2020/08/restricted-stock-units-10-fast-facts)
- Restricted Stock Units (RSUs): Key Points You Must Know (https://mystockoptions.com/articles/restricted-stock-units-rsus-checklist-of-key-points-to-know)
- Equity Compensation and the Rise of Restricted Stock Units (https://natlawreview.com/article/equity-compensation-and-rise-restricted-stock-units)
- Evaluate Tax Implications of RSUs
- RSU Taxes Explained + 4 Tax Strategies for 2023 (https://cordantwealth.com/rsus-tax-saving-and-hedging)
- Here’s How Restricted Stock Units (RSUs) Work | Bankrate (https://bankrate.com/investing/restricted-stock-units)
- Assess Financial Goals and Liquidity Needs
- 54 Personal Finance Statistics & Facts in 2025 [SOURCES INCLUDED] (https://moneywise.com/research/personal-finance-statistics)
- Consider Risks of Holding RSUs
- vestedfinance.com (https://vestedfinance.com/blog/us-stocks/differences-between-esops-rsus-and-espps)
- Restricted Stock Units (RSUs) Comprehensive Guide | TAN Wealth Management | Certified Financial Planner (CFP®) San Francisco | Advisor (https://tanphan.com/blog/restricted-stock-units-rsu-comprehensive-guide)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading