

Overview
When considering the sale of Employee Stock Purchase Plan (ESPP) shares, it’s important to think about key factors that can lead to financial success. These include:
- Market performance
- Your personal financial goals
- Holding periods for tax benefits
- Your diversification needs
Imagine if you could navigate these elements with confidence. Understanding them, along with strategies like timely selling and seeking advice from financial advisors, can truly help you maximize profits. This approach minimizes tax liabilities and the risks associated with holding company stock. We’re here for you as you explore these options, ensuring that your family’s financial future is secure.
Key Highlights:
- ESPPs allow employees to buy company stock at a discount (5-15%), promoting financial security.
- Key components of ESPPs include discounted purchase prices, offering periods, and qualifying dispositions for tax benefits.
- Holding shares for at least one year from purchase and two years from offering can lead to favourable tax treatment.
- Market performance and personal financial goals are critical factors in deciding when to sell ESPP shares.
- Selling ESPP shares within one year incurs ordinary income tax on the discount, while holding longer allows for lower capital gains tax.
- Qualifying dispositions offer better tax treatment compared to disqualifying dispositions, which can lead to higher taxes.
- Strategies for selling ESPP shares effectively include immediate sale after purchase, diversification, monitoring market conditions, and setting clear financial goals.
- Consulting a financial advisor can provide personalised strategies to maximise benefits from ESPPs and manage risks.
Introduction
Navigating the complexities of Employee Stock Purchase Plans (ESPPs) can feel like a transformative journey toward financial success for you and your family. These plans open up a unique opportunity for employees to acquire company stock at a discounted price, creating pathways for potential wealth accumulation.
However, it’s essential to consider when to sell these shares, as timing can significantly influence your financial outcomes. Imagine if you could optimize the sale of your ESPP shares, ensuring a secure financial future for your loved ones.
What factors should you contemplate to achieve this goal?
Understand Employee Stock Purchase Plans (ESPPs)
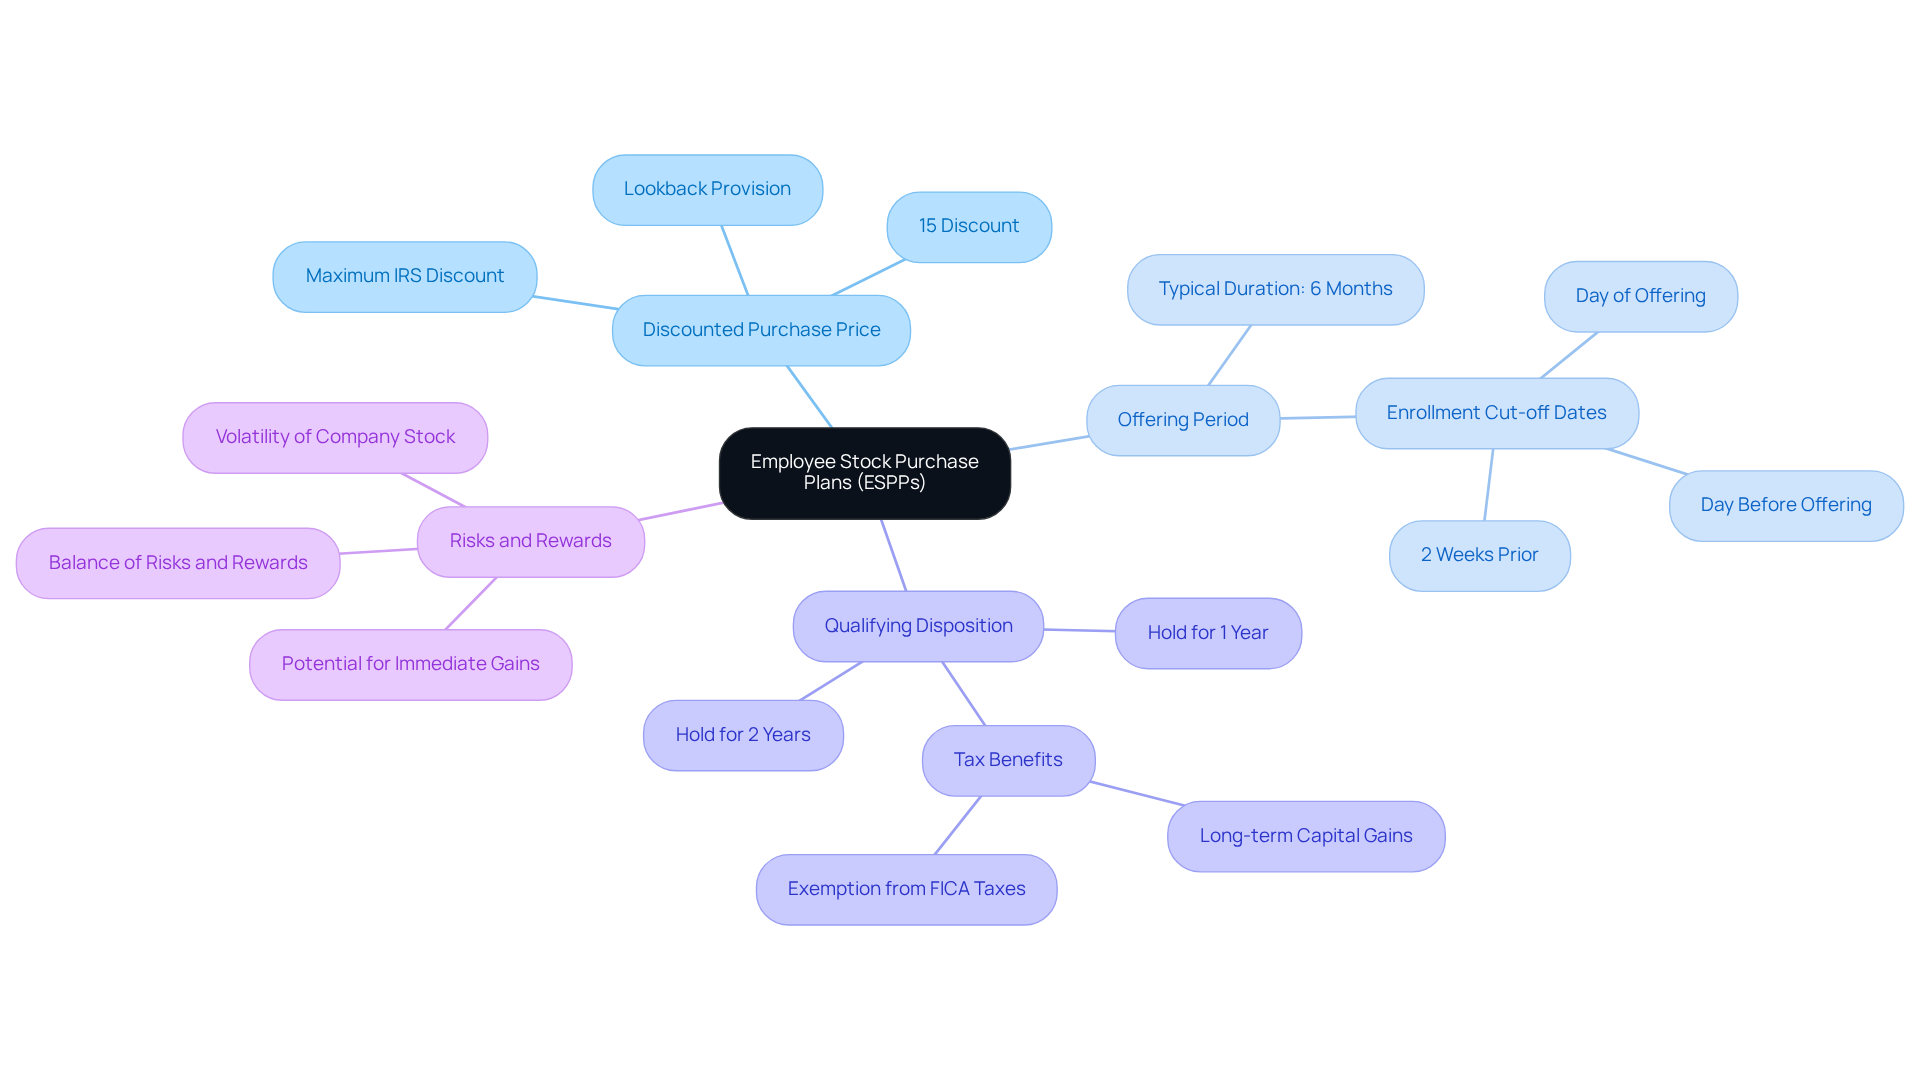
Employee Stock Purchase Plans (ESPPs) can be a wonderful opportunity for employees to invest in their future. These employer-sponsored initiatives allow you to purchase shares of your company’s stock at a reduced price, typically between 5% to 15% lower than the market value. Imagine being able to set aside a portion of your salary to acquire stocks during a specified offering period—this can be a significant step toward building your family’s financial security.
Understanding the intricacies of ESPPs is crucial for maximizing their advantages. Here are some key components to consider:
- Discounted Purchase Price: One of the most appealing aspects of ESPPs is the chance to buy shares at a lower price, which could lead to immediate financial gains. In 2025, the most common discount offered is 15%. Many plans even include a lookback provision, enhancing returns in a rising market. As Barbara Baksa, Executive Director, notes, “Among US-headquartered companies that offer an ESPP, 84% offer a Section 423-qualified plan.”
- Offering Period: This designated timeframe, usually lasting six months, allows you to enroll and contribute to the plan. Keep in mind that companies often set cut-off dates for enrollment, with 27% of firms cutting off participation two weeks prior to the offering.
- Qualifying Disposition: If you hold shares for at least one year from the purchase date and two years from the offering date, you may qualify for favorable tax treatment. This means your gains could be taxed at lower long-term capital gains rates. Plus, ordinary income from the 15% discount is exempt from FICA taxes, which can be advantageous for long-term investors. Remember, the maximum yearly contribution limit for tax-qualified ESPPs is $25,000.
- Risks and Rewards: While ESPPs can significantly enhance your overall compensation, they also expose you to the volatility of your employer’s stock performance. It’s essential to balance the potential for gains with the risks associated with holding company stock. As Emily Cervino, Head of Industry Relationships and Thought Leadership, emphasizes, “There are a lot of great employee stock purchase plan nuggets in this survey.”
By understanding these essential elements, you can make informed choices regarding your involvement in ESPPs. Together, we can navigate this journey toward creating effective plans for selling stocks and enhancing your financial results, ensuring a brighter future for you and your family.
Evaluate Timing and Conditions for Selling ESPP Shares
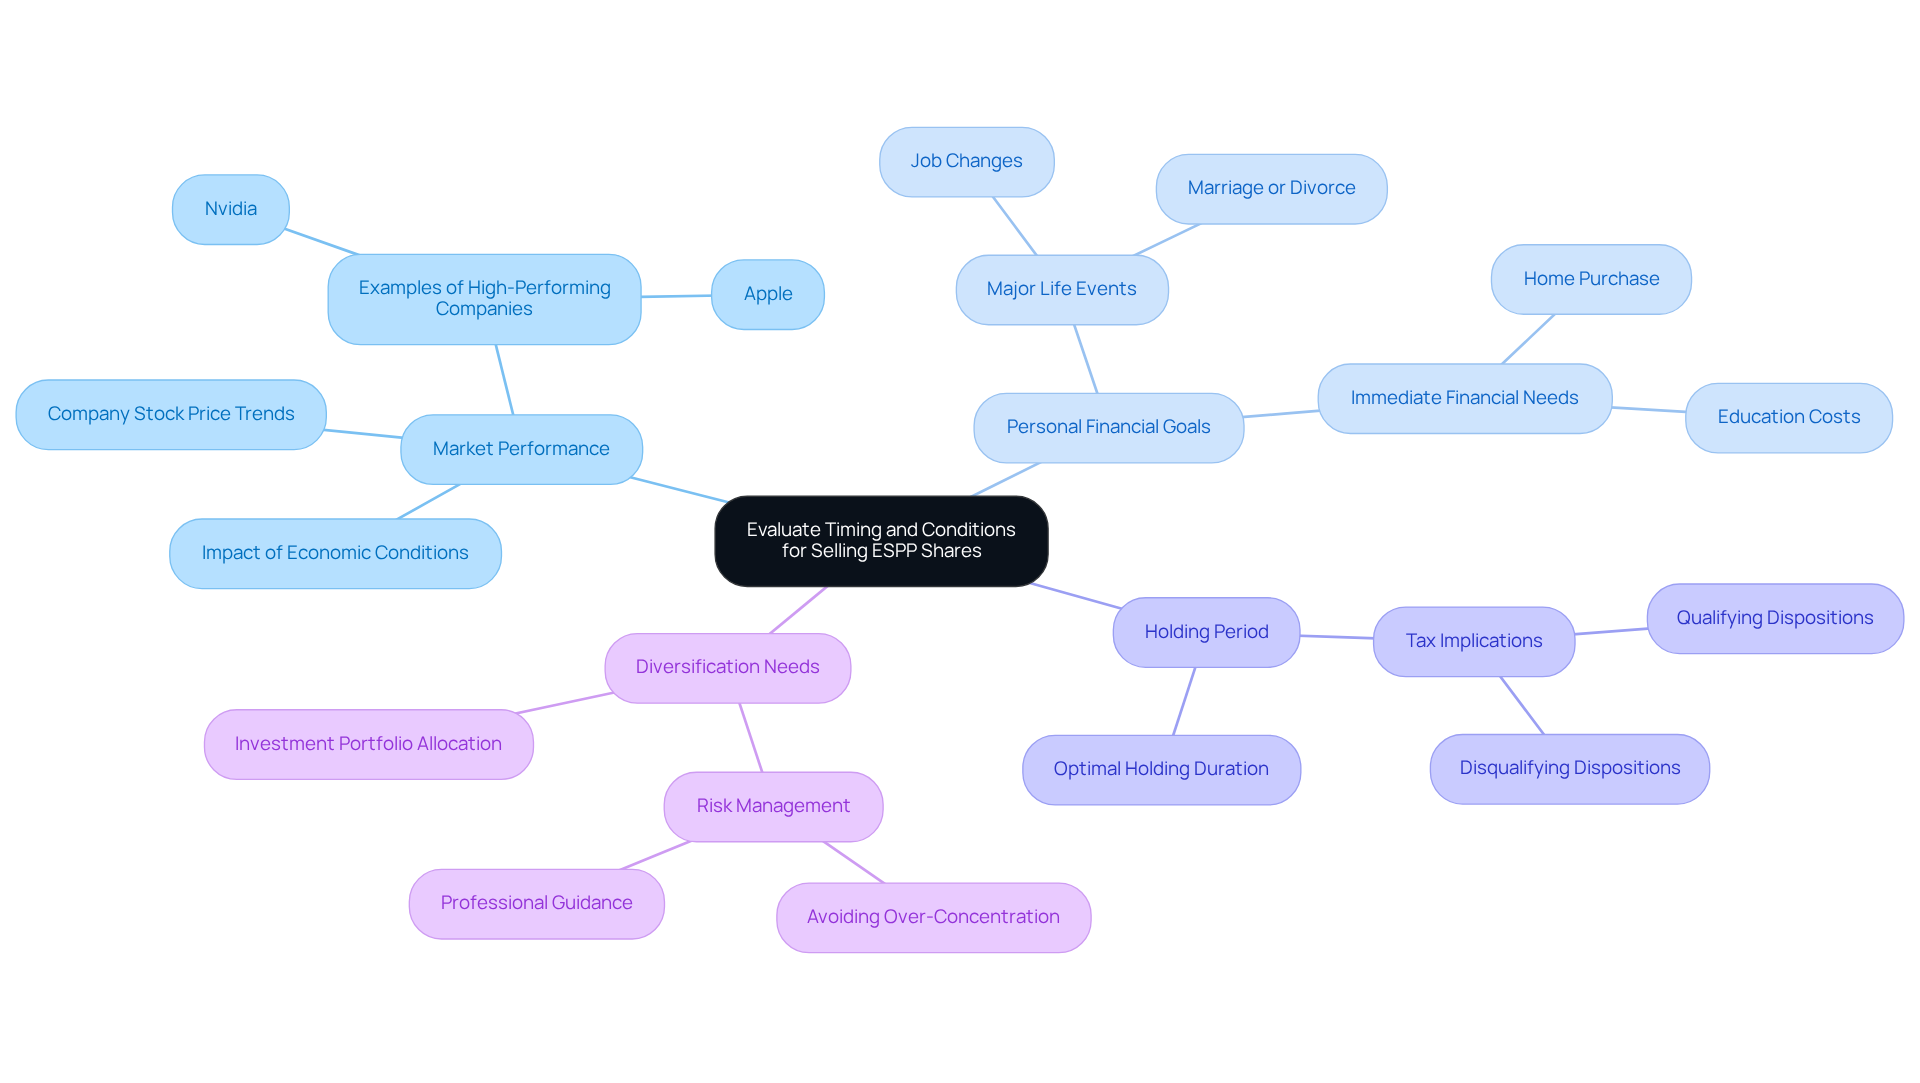
When considering when to sell ESPP units, it’s important to take a moment to evaluate both market conditions and your personal financial situation. Let’s explore some key factors together:
- Market Performance: Imagine keeping a close eye on your company’s stock price. If the stock is doing well, selling can help you secure profits for your family. For instance, companies like Nvidia and Apple have experienced significant stock price increases, making timely sales potentially rewarding. However, some employees who sold their options early may feel regret over missed opportunities, highlighting the importance of timing.
- Personal Financial Goals: Aligning your selling strategy with your financial objectives is crucial. Major life events, such as job changes, marriage, or divorce, can greatly influence your optimal ESPP strategies. If you need funds for a significant expense, like a home purchase or education costs, selling sooner might be necessary to meet those important needs.
- Holding Period: It’s essential to understand the tax implications associated with the holding period. To qualify for favorable tax treatment, stocks usually need to be held for at least two years from the offering date and one year from the acquisition date. For example, if you sell at $100 after meeting these requirements, taxes owed would be approximately $1,032. Selling too early can lead to higher tax liabilities, which can significantly affect your overall returns.
- Diversification Needs: Avoiding over-concentration in a single stock is vital for your family’s financial health. Financial advisors often recommend that no more than 5-10% of your total investment portfolio should be allocated to one stock. When employee stock purchase plan equities account for over 10% of your overall investment portfolio, seeking expert assistance can be crucial for managing risk. This strategy helps protect your family, especially in unpredictable market conditions.
By thoughtfully assessing these factors, you can make informed choices about when to sell ESPP, ultimately enhancing your financial success. Remember, we’re here for you as you navigate this journey.
Assess Tax Implications of Selling ESPP Shares
Selling your ESPP stocks can lead to significant tax consequences, and knowing when to sell ESPP can feel overwhelming. Let’s break it down together, focusing on what matters most for you and your family.
-
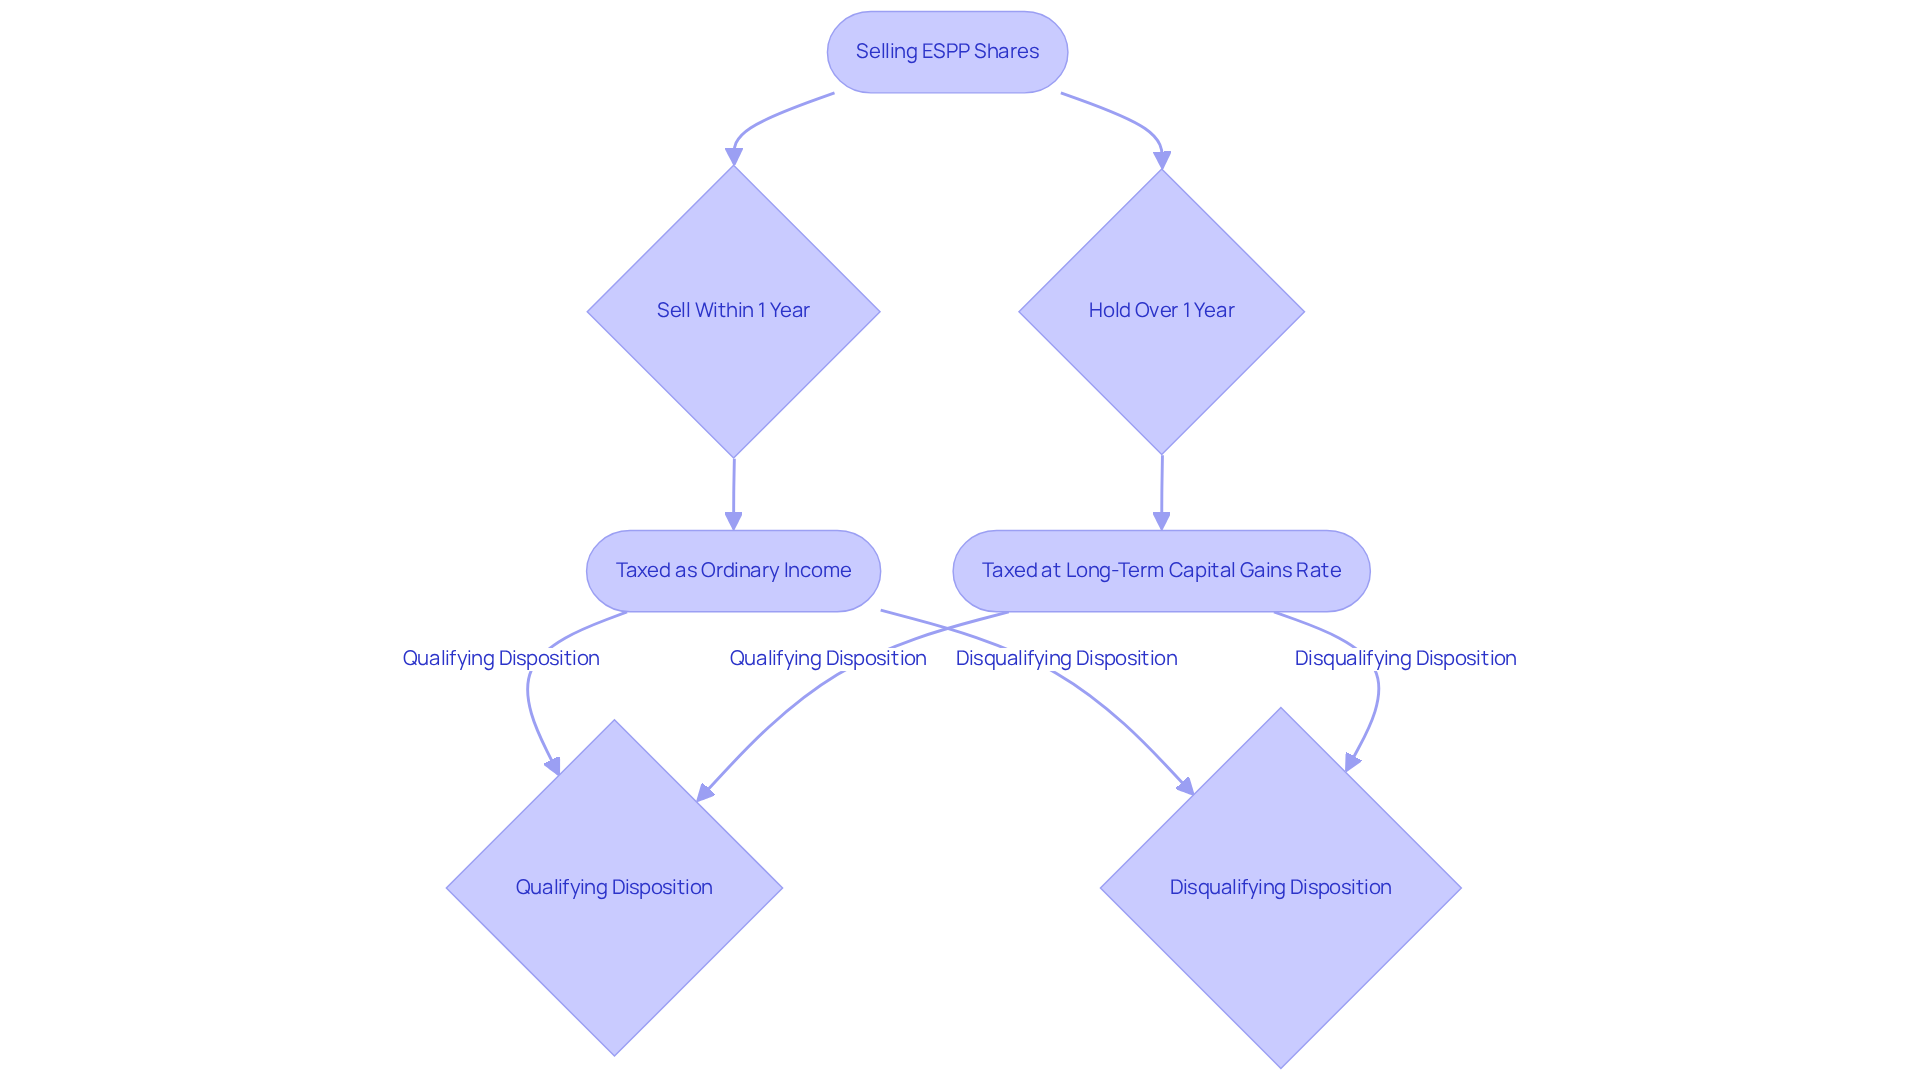
Ordinary Income Tax: If you sell your shares within one year of purchase, the discount you received will be taxed as ordinary income. This can increase your overall tax liability considerably. For example, if you received a 15% discount on assets valued at $60, that $9 deduction would be taxed at your standard income rate. It’s important to be aware of how this can impact your finances.
-
Capital Gains Tax: Holding onto your stocks for over one year allows any increase beyond the purchase price to be taxed at the long-term capital gains rate. This rate is generally lower than standard income tax rates, which can be a relief. For married couples filing jointly, the long-term capital gains tax rate may be as low as 15% for income up to $94,050. Imagine how much this could save you!
-
Qualifying vs. Disqualifying Disposition: A qualifying disposition happens when you meet specific holding period requirements—selling your assets at least two years from the offering date and one year from the purchase date. This can result in more favorable tax treatment. On the other hand, a disqualifying disposition means the discount is taxed as ordinary income, potentially leading to a higher tax bill. Understanding these distinctions can empower you to make better decisions regarding when to sell ESPP.
-
Tax Planning Strategies: To help minimize your tax burden, consider reaching out to a tax advisor who can provide tailored strategies for your situation. Understanding when to sell ESPP can help you time your sales to align with lower income years, significantly reducing your tax liability. For instance, if you anticipate a decrease in income, liquidating assets during that period may allow you to benefit from reduced capital gains tax rates. Bright Advisers offers strategies that optimize your tax situation while balancing growth potential and risk management, much like how Jay and Emma effectively managed their planning.
By grasping these tax implications and utilizing personalized financial strategies, you can make informed decisions on when to sell ESPP in relation to your employee stock plan holdings. Remember, we’re here for you, and together, we can navigate this journey to maximize your financial outcomes for your family.
Implement Strategies for Selling ESPP Shares Effectively
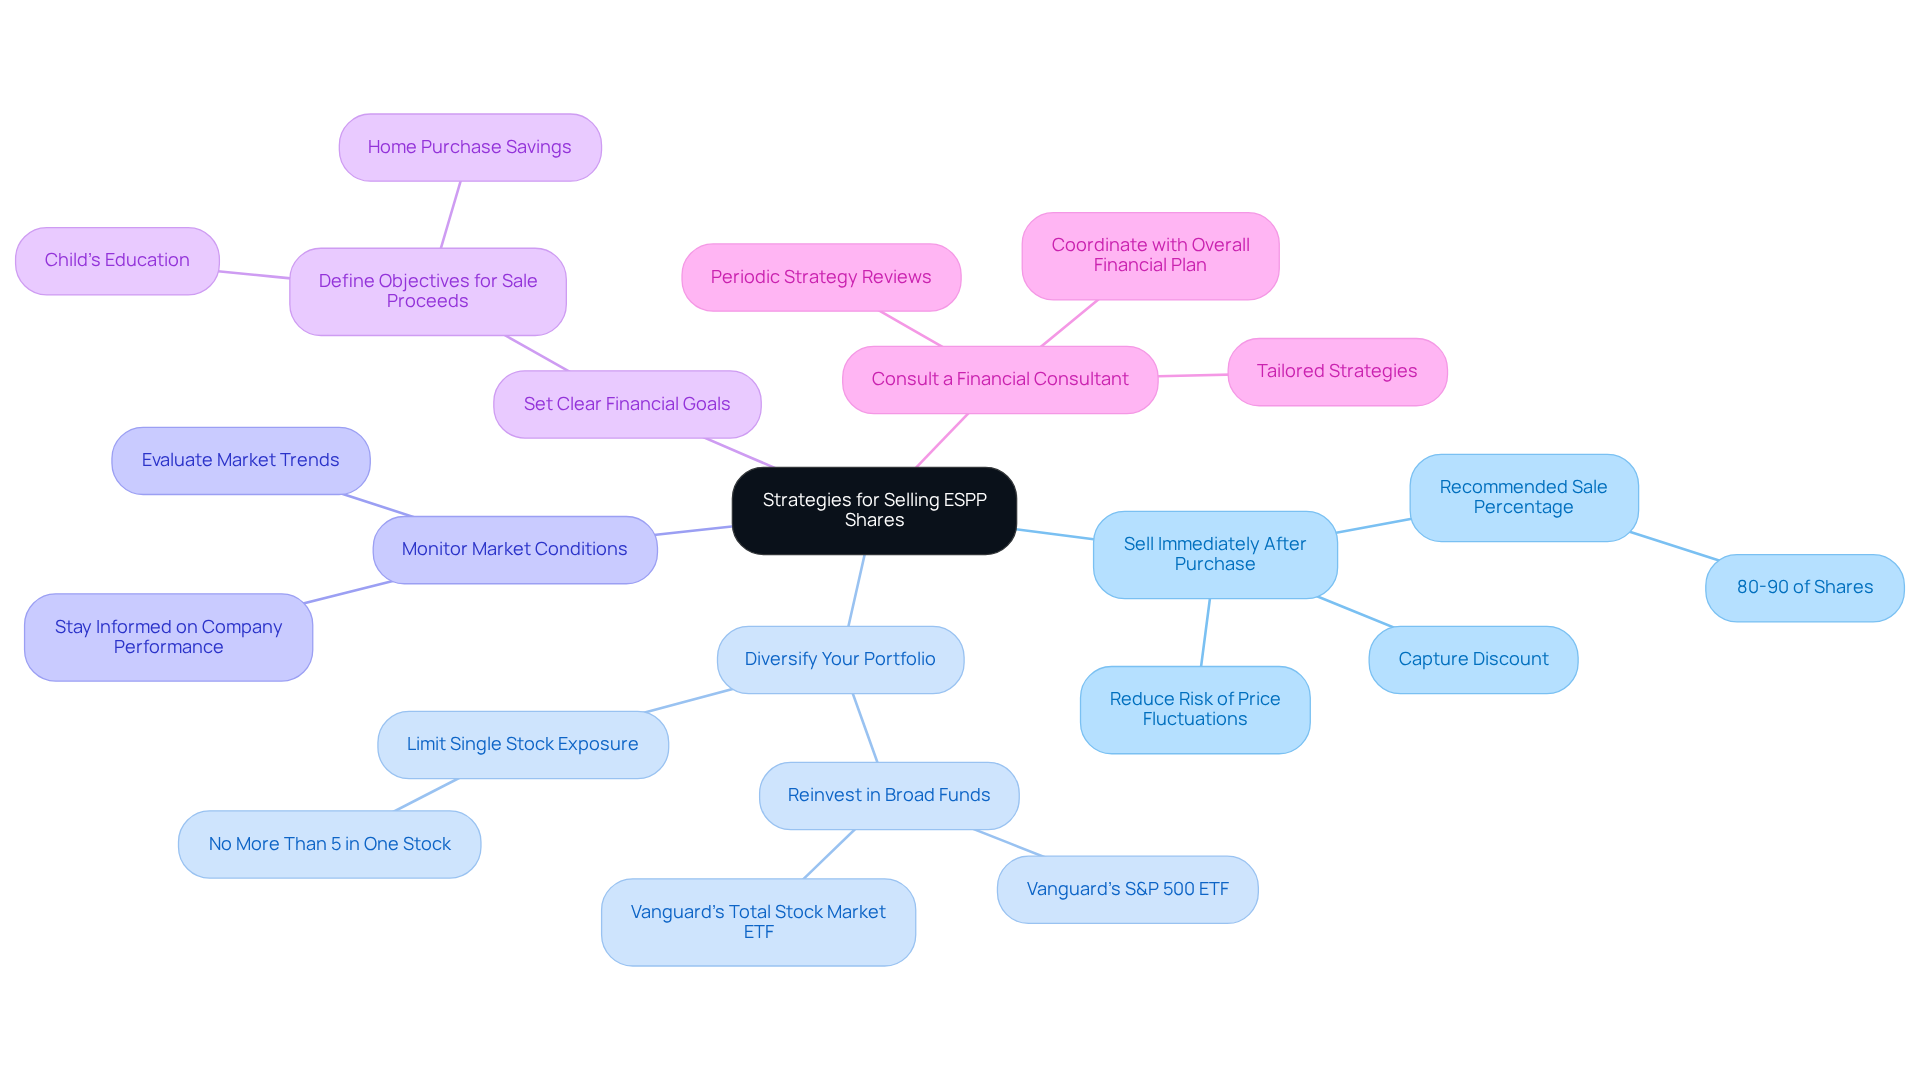
To effectively sell your ESPP shares, consider these nurturing strategies that can help you secure your family’s financial future:
-
Sell Immediately After Purchase: Imagine securing the discount and reducing the risks of stock price fluctuations. Financial consultants often recommend understanding when to sell espp by selling 80-90% of your stocks right away to take full advantage of this benefit, ensuring you can focus on what truly matters—your family’s well-being.
-
Diversify Your Portfolio: After selling, think about reinvesting the proceeds into a diversified portfolio, like Vanguard’s S&P 500 ETF. This approach can help reduce risk and enhance potential returns. Remember, holding more than 5% of your portfolio in one stock can raise economic risk, making diversification essential for peace of mind.
-
Monitor Market Conditions: It’s important to stay informed about market trends and your company’s performance. If your company’s stock is thriving, consider keeping a portion of your holdings for potential long-term benefits. However, it is important to balance this with the need for diversification, especially when to sell espp, to protect your family’s financial health.
-
Set Clear Financial Goals: Take a moment to define your objectives for the proceeds from your sale, particularly when to sell espp. Whether it’s funding your child’s education or saving for a home, having clear goals can guide your selling strategy and ensure that the funds are used effectively for your family’s future.
-
Consult a Financial Consultant: Engaging with a money planner can provide tailored strategies that align with your overall monetary plan. They can assist you in managing the intricacies of selling employee stock option units, enhancing your investment results while giving you the confidence to navigate this journey.
By implementing these caring strategies, you can maximize the benefits of your ESPP shares and enhance your family’s financial well-being. Remember, we’re here for you every step of the way.
Conclusion
Navigating the complexities of Employee Stock Purchase Plans (ESPPs) can significantly enhance your financial outcomes when selling shares. Imagine if you could make informed decisions that align with your family’s financial goals. By understanding the essential components of ESPPs—like discounted purchase prices, offering periods, and tax implications—you can take control of your financial journey. It’s crucial to recognize the importance of timing and market conditions to maximize returns while managing the risks of holding company stock.
Key factors, such as your personal financial objectives, holding periods, and diversification strategies, play a vital role in determining the best moment to sell your ESPP shares. The impact of tax implications—whether through ordinary income tax or capital gains tax—can greatly influence your overall returns. Planning effectively is essential. Consider implementing strategies like:
- Immediate selling post-purchase
- Diversifying your portfolio
- Consulting financial advisors
to secure your family’s financial stability and growth.
Ultimately, understanding when to sell ESPP shares is not just about immediate gains; it’s about creating a robust financial future for you and your loved ones. By staying informed and proactive, you can navigate the intricacies of your employee stock purchase plans, ensuring that your financial strategies are well-aligned with your long-term goals. Taking these steps not only maximizes returns from ESPP sales but also fosters a sense of financial empowerment and security. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is an Employee Stock Purchase Plan (ESPP)?
An Employee Stock Purchase Plan (ESPP) is an employer-sponsored initiative that allows employees to purchase shares of their company’s stock at a reduced price, typically between 5% to 15% lower than the market value.
How does the discounted purchase price work in ESPPs?
The discounted purchase price is one of the most appealing aspects of ESPPs, allowing employees to buy shares at a lower cost, which can lead to immediate financial gains. In 2025, the most common discount offered is 15%, and many plans include a lookback provision that enhances returns in a rising market.
What is the offering period in an ESPP?
The offering period is a designated timeframe, usually lasting six months, during which employees can enroll and contribute to the plan. Companies often set cut-off dates for enrollment, with 27% of firms cutting off participation two weeks prior to the offering.
What is a qualifying disposition in an ESPP?
A qualifying disposition occurs when shares are held for at least one year from the purchase date and two years from the offering date, potentially qualifying for favorable tax treatment. This may allow gains to be taxed at lower long-term capital gains rates, and ordinary income from the discount is exempt from FICA taxes.
What are the contribution limits for tax-qualified ESPPs?
The maximum yearly contribution limit for tax-qualified ESPPs is $25,000.
What are the risks associated with ESPPs?
While ESPPs can enhance overall compensation, they also expose employees to the volatility of their employer’s stock performance. It’s important to balance the potential for gains with the risks of holding company stock.
How can understanding ESPPs benefit employees?
By understanding the essential elements of ESPPs, employees can make informed choices regarding their involvement, navigate the journey of selling stocks, and enhance their financial results for a brighter future.
List of Sources
- Understand Employee Stock Purchase Plans (ESPPs)
- Employee Stock Purchase Plans (ESPP) | The ESOP Association (https://esopassociation.org/articles/employee-stock-purchase-plans)
- Trends in ESPP Policies and Participation (https://naspp.com/blog/espp-policies-and-participation)
- Employee stock purchase plans offer ‘free money’ — but also carry complexity and risk, experts say (https://cnbc.com/2024/04/24/what-to-know-before-opting-into-your-employee-stock-purchase-plan.html)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Benefits of Participating in Your Company’s Qualified Employee Stock Purchase Plan (https://armanino.com/articles/benefits-participating-company-qualified-employee-stock-purchase-plan)
- Evaluate Timing and Conditions for Selling ESPP Shares
- When Should You Sell ESPP Shares? — EquityFTW (https://equityftw.com/articles/when-should-you-sell-espp-shares)
- Employee Stock Purchase Programs: 2025 Guide to ESPP Risks & Benefits (https://advisorfinder.com/blog-posts/employee-stock-purchase-programs-risks-benefits-2025)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/blog/espp-tax-rules-what-you-need-to-know)
- Tax Implications Of Espp Market Values – FasterCapital (https://fastercapital.com/topics/tax-implications-of-espp-market-values.html)
- Assess Tax Implications of Selling ESPP Shares
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/blog/espp-tax-rules-what-you-need-to-know)
- 2024 and 2025 Capital Gains Tax Rates and Rules – NerdWallet (https://nerdwallet.com/article/taxes/capital-gains-tax-rates)
- 2024-2025 Long-Term Capital Gains Tax Rates | Bankrate (https://bankrate.com/investing/long-term-capital-gains-tax)
- Long-Term vs. Short-Term Capital Gains (https://investopedia.com/articles/personal-finance/101515/comparing-longterm-vs-shortterm-capital-gain-tax-rates.asp)
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- Implement Strategies for Selling ESPP Shares Effectively
- When Should You Sell ESPP Shares? — EquityFTW (https://equityftw.com/articles/when-should-you-sell-espp-shares)
- Selling Employee Stock Purchase Plan Shares (https://thebalancemoney.com/when-to-sell-espp-2388745)
- Sell ESPP Shares at Purchase: When This Strategy is Best | Equity Comp Academy (https://3040wealth.com/academy/typically-sell-espp-shares-upon-purchase)
- Employee Stock Purchase Programs: 2025 Guide to ESPP Risks & Benefits (https://advisorfinder.com/blog-posts/employee-stock-purchase-programs-risks-benefits-2025)
- Employee stock purchase plan – ESPP (https://globalshares.com/insights/employee-stock-purchase-plan-espp)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading