

Key Highlights
- Understanding financial advisor fees is crucial for young parents planning their family’s financial future.
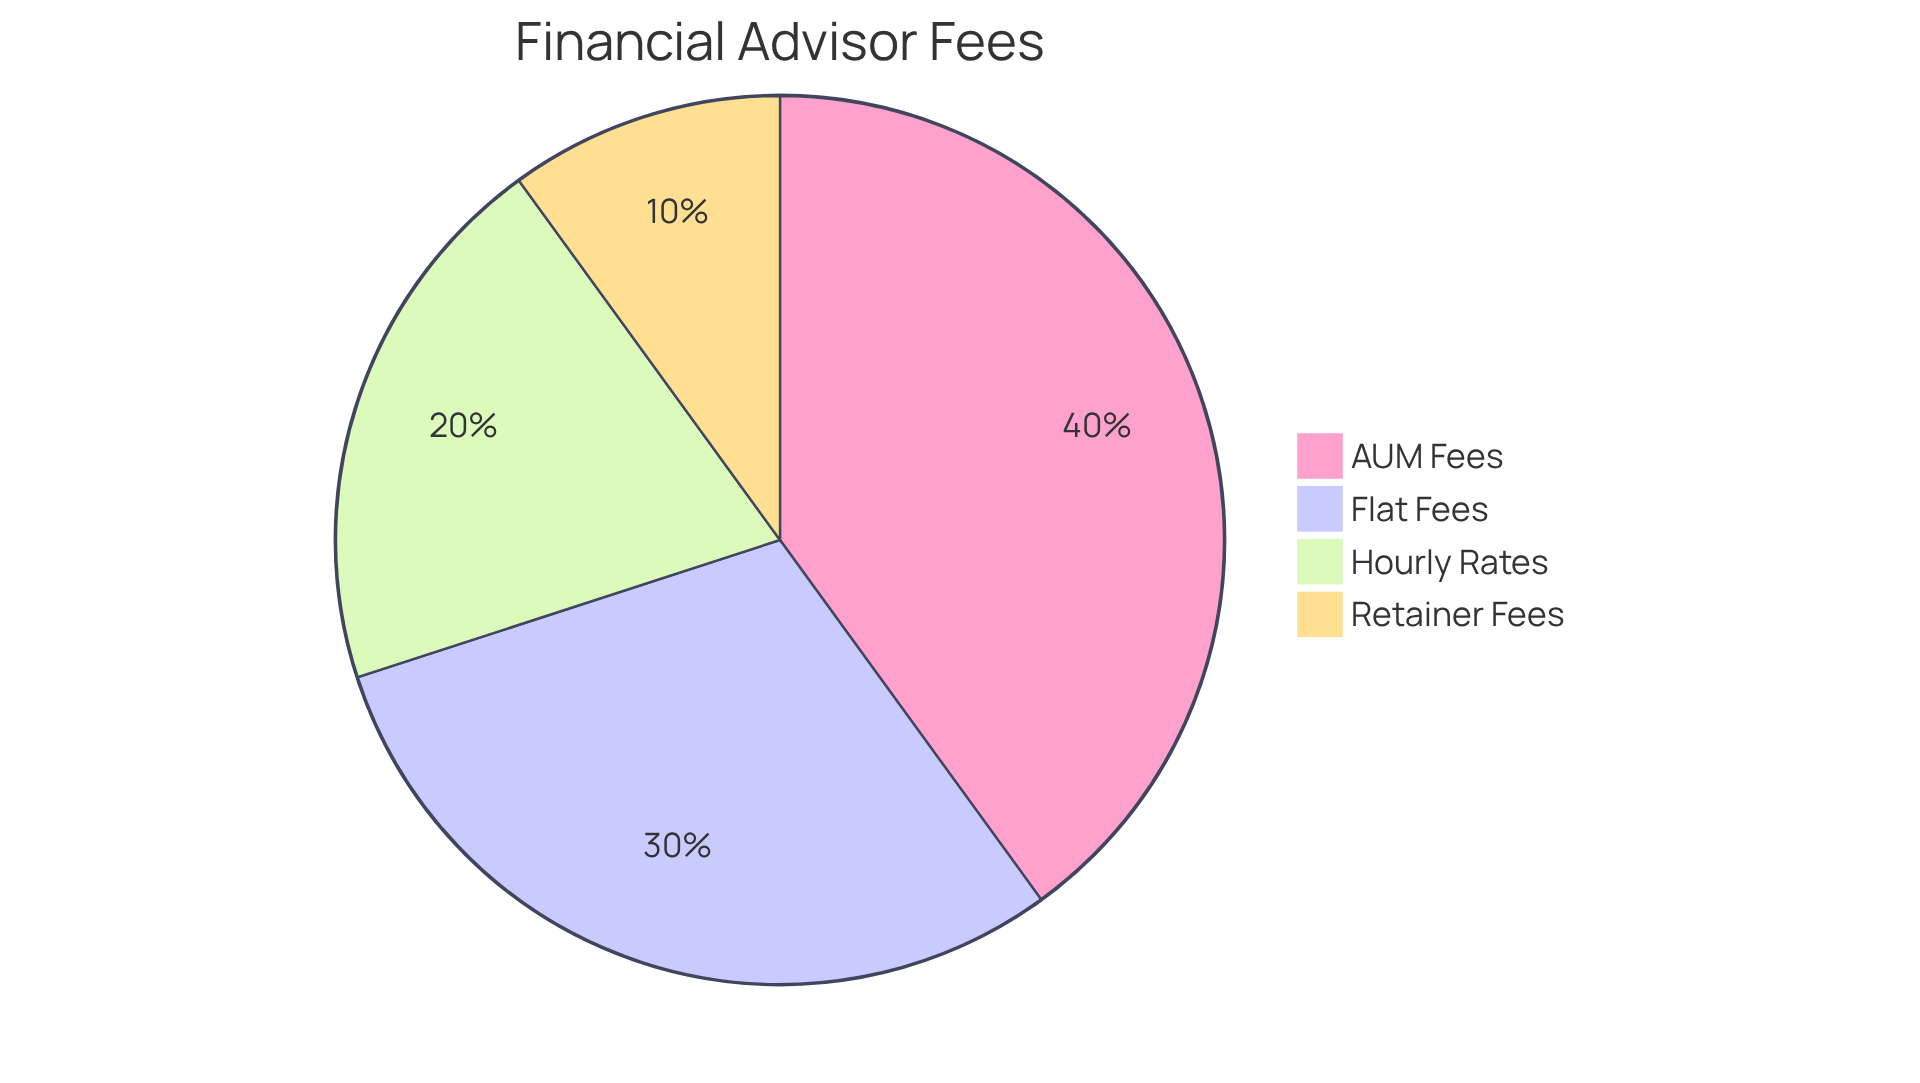
- Common fee structures include Assets Under Management (AUM), flat fees, hourly rates, and retainer fees.
- AUM fees typically range from 0.5% to 1.5% annually, impacting long-term savings significantly.
- Flat fees provide cost transparency, while hourly rates offer flexibility for specific advice.
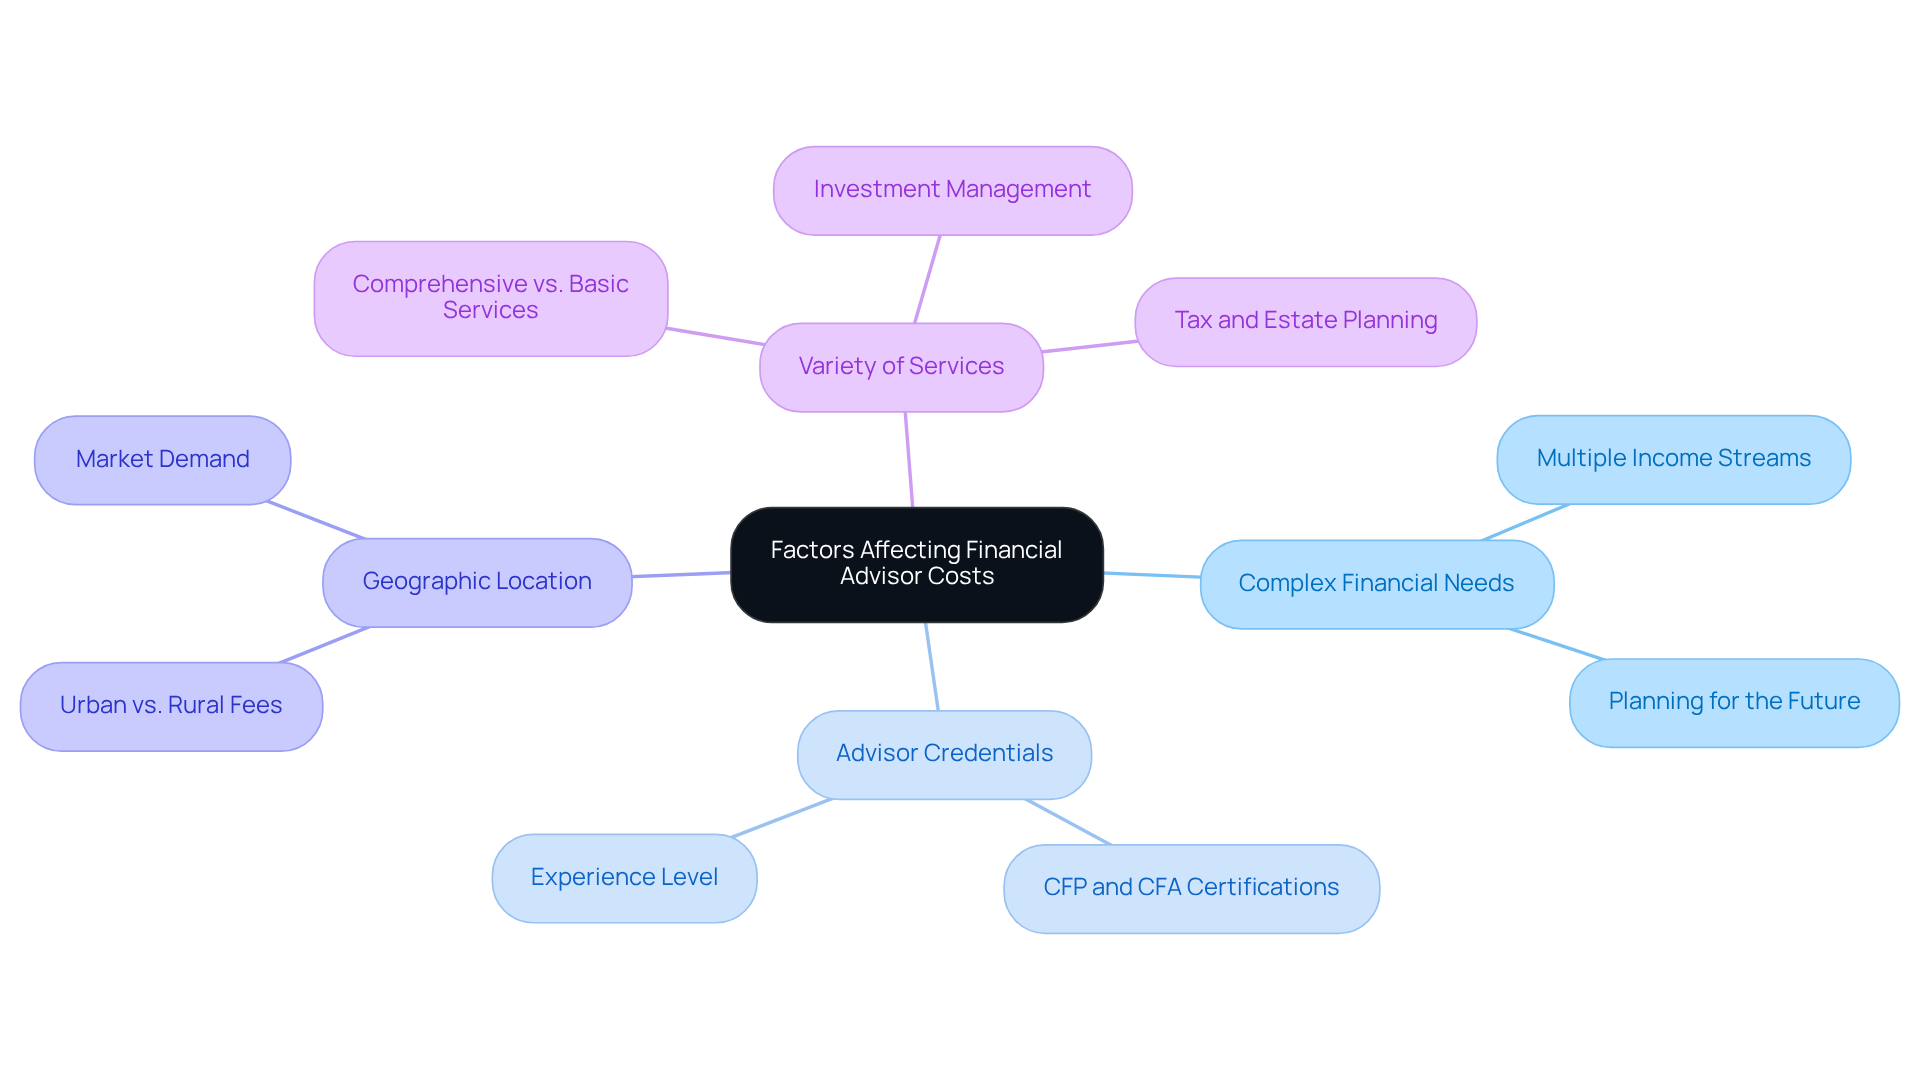
- Factors affecting advisor costs include complexity of financial needs, advisor credentials, geographic location, and range of services offered.
- Families should view advisory costs as an investment in their future, potentially leading to improved financial outcomes.
- Research indicates that working with financial advisors can enhance investment returns and provide emotional support during market fluctuations.
- A holistic approach from advisors can lead to significant long-term savings and financial security for families.
Introduction
Imagine feeling lost in a sea of financial advice while trying to secure your family’s future. It’s important to understand how financial advisor monthly fees can affect your family’s budget and future plans. What if the right support could turn confusion into clarity, helping your family thrive financially? By exploring different fee structures, you can feel empowered to make choices that truly benefit your family’s financial journey.
Define Financial Advisor Fees and Their Importance
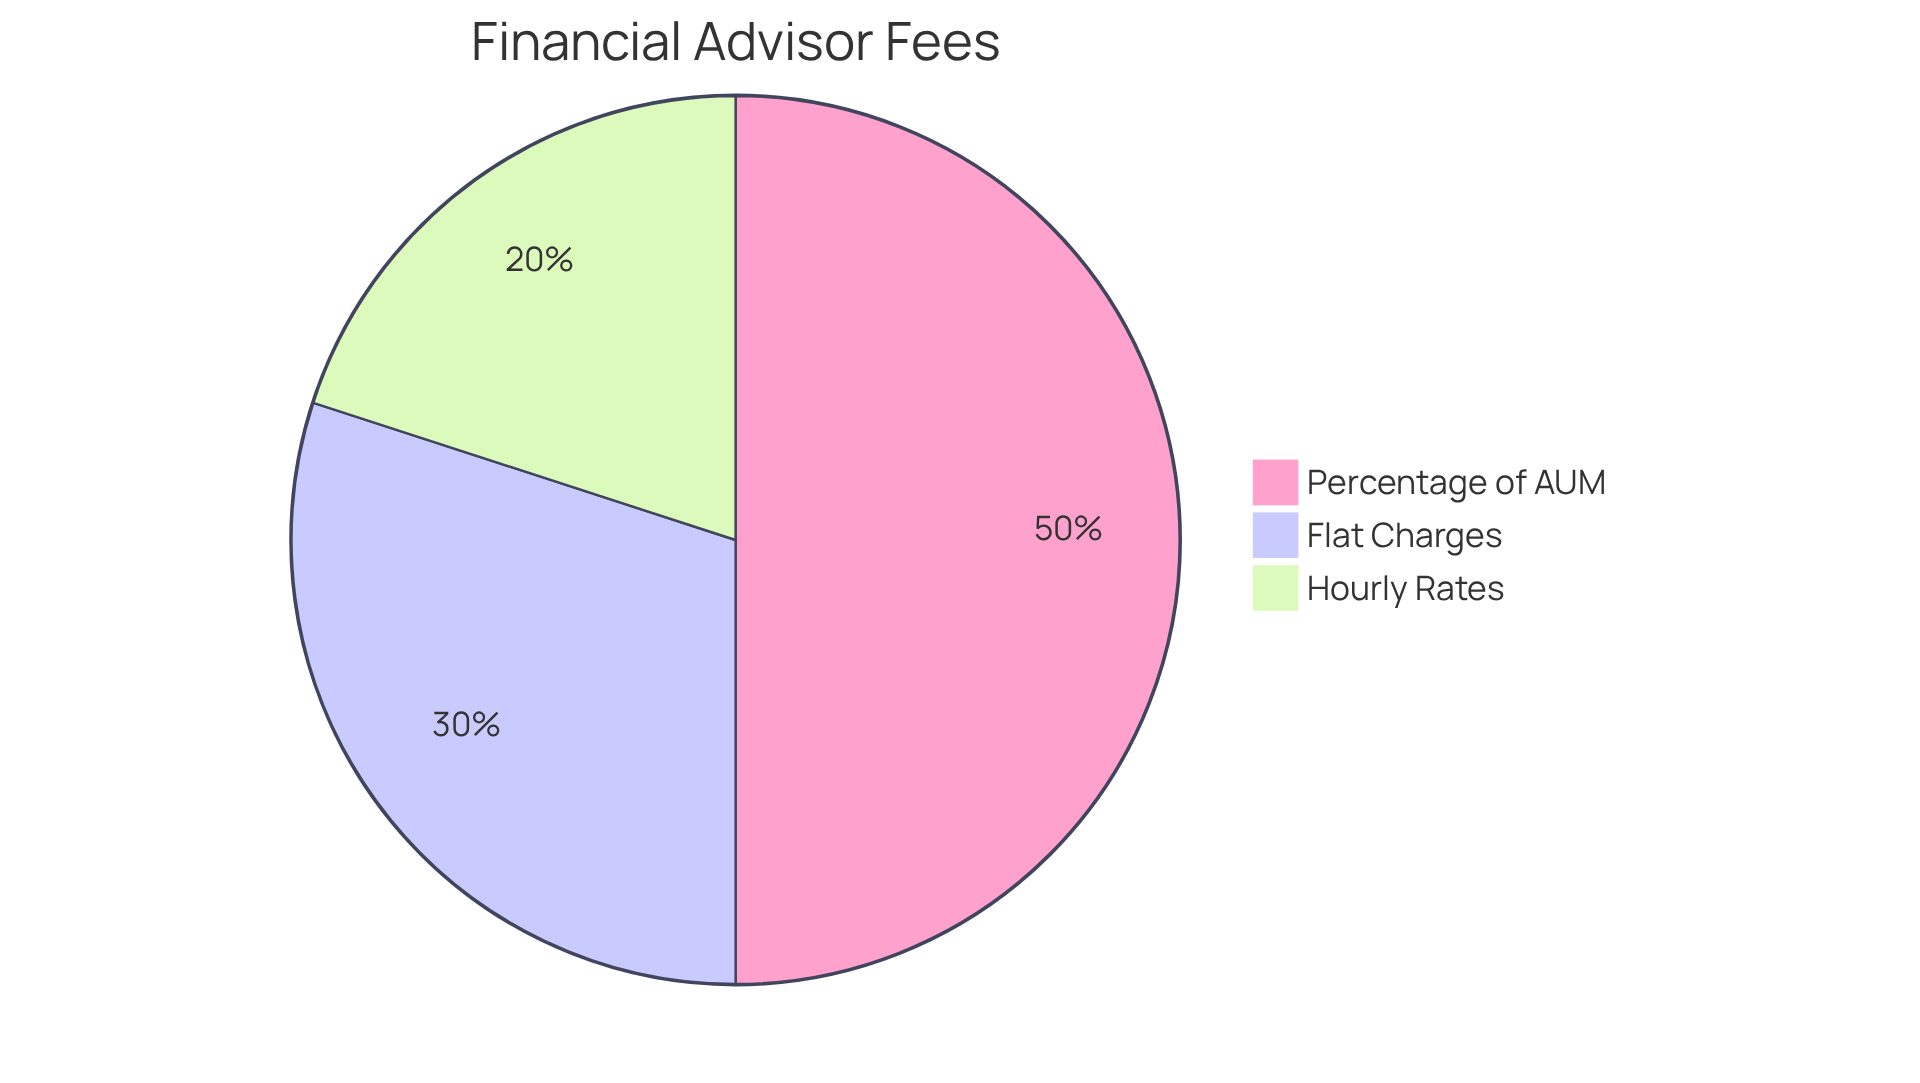
Many young parents find themselves puzzled by the costs of financial advice, unsure of how to navigate this important aspect of their family’s future. Understanding the financial advisor monthly fee can be tricky, especially since the costs of financial advice vary based on how advisors get paid. Common structures include:
- A percentage of assets under management (AUM)
- Flat charges
- Hourly rates
For young caregivers, grasping these costs is essential as they plan for their household’s financial future.
At Bright Advisers, we believe in being upfront about our pricing, so you won’t find any hidden fees or surprises. We want families to get the most value from our services. Typical AUM fees usually fall between 0.75% and 1.5% each year, and these can really add up over time, affecting your family’s savings and investments. For instance, a 1% fee on a $2 million portfolio means $20,000 annually. This highlights how important it is to understand these expenses, particularly the financial advisor monthly fee, in relation to the value we provide.
Many families find that viewing advisory costs as an investment in their future helps them make better choices. When clients see the potential for improved investment results and tax strategies, they’re more likely to find the right advisor for their needs. This perspective is especially crucial for households, as effective budgeting can lead to significant long-term benefits, validating the related expenses.
By recognizing the importance of these fees, families can confidently navigate their financial planning, ensuring they make choices that align with their goals. When families understand these fees, they empower themselves to make choices that truly benefit their financial journey together.
Explore Common Financial Advisor Fee Structures
Imagine trying to secure your family’s future while feeling lost in a sea of financial jargon. Financial advisors typically operate under several common fee structures, each designed to meet different client needs:
- Assets Under Management (AUM): Advisors charge a percentage of the assets they manage, usually between 0.5% and 1.5% annually. This means that as your portfolio grows, your advisor benefits too, creating a partnership focused on your family’s financial success. For instance, for a $1,000,000 portfolio with a 1% AUM fee, the annual cost would be $10,000.
- Flat Fees: Some consultants charge a fixed fee for specific services, such as creating a financial plan. These fees typically range from $2,500 to $10,000 annually, depending on the complexity of the services provided. This structure offers cost transparency and predictability, unaffected by market fluctuations.
- Hourly Rates: Advisors may charge by the hour, with rates typically falling between $200 and $500. This model is beneficial for clients who need specific advice without ongoing management, allowing for flexibility and cost control.
- Retainer Fees: Clients pay a regular fee for ongoing access to their advisor, which can provide peace of mind and continuous support. This structure is especially beneficial for households seeking steady direction as their monetary situations change.
Understanding the financial advisor monthly fee structures is essential for finding the right fit for your family’s financial needs. By consistently assessing consultant charges in relation to the services offered, you can prevent unnecessary expenses that might diminish your investment returns. When you choose wisely, you not only save money but also gain the peace of mind that comes from knowing your family is well-supported.
Identify Key Factors Affecting Financial Advisor Costs
Imagine feeling uncertain about the financial advisor monthly fee while trying to secure your family’s future. Several factors, including the financial advisor monthly fee, can significantly influence these costs, especially for families navigating complex financial landscapes.
Families with complex financial needs, like juggling multiple income streams or planning for the future, often find that a financial advisor monthly fee can contribute to their overall costs. This is because managing these intricacies requires more time and expertise.
It’s also important to consider the credentials associated with the financial advisor monthly fee. Advisors with advanced certifications, such as Certified Financial Planner (CFP) or Chartered Financial Analyst (CFA), typically have a higher financial advisor monthly fee. Their specialized knowledge can provide your family with tailored strategies that make the investment worthwhile.
Another factor is geographic location. Advisors in urban areas often charge more than those in rural regions, reflecting the higher living costs and market demand in cities.
Consider how the variety of services provided by an advisor can influence the financial advisor monthly fee you pay. Comprehensive financial planning, which includes investment management, tax planning, and estate planning, usually results in a higher financial advisor monthly fee compared to basic investment guidance. If your household is pursuing holistic financial strategies, you might notice that the financial advisor monthly fee has increased, indicating a rising demand for comprehensive planning.
By understanding these factors, you can better assess the value of the services you receive and feel more equipped to negotiate fees that align with your family’s financial goals. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future.
Assess the Value of Financial Advisors Against Their Fees
Imagine feeling overwhelmed by financial decisions while trying to prioritize your family’s future.
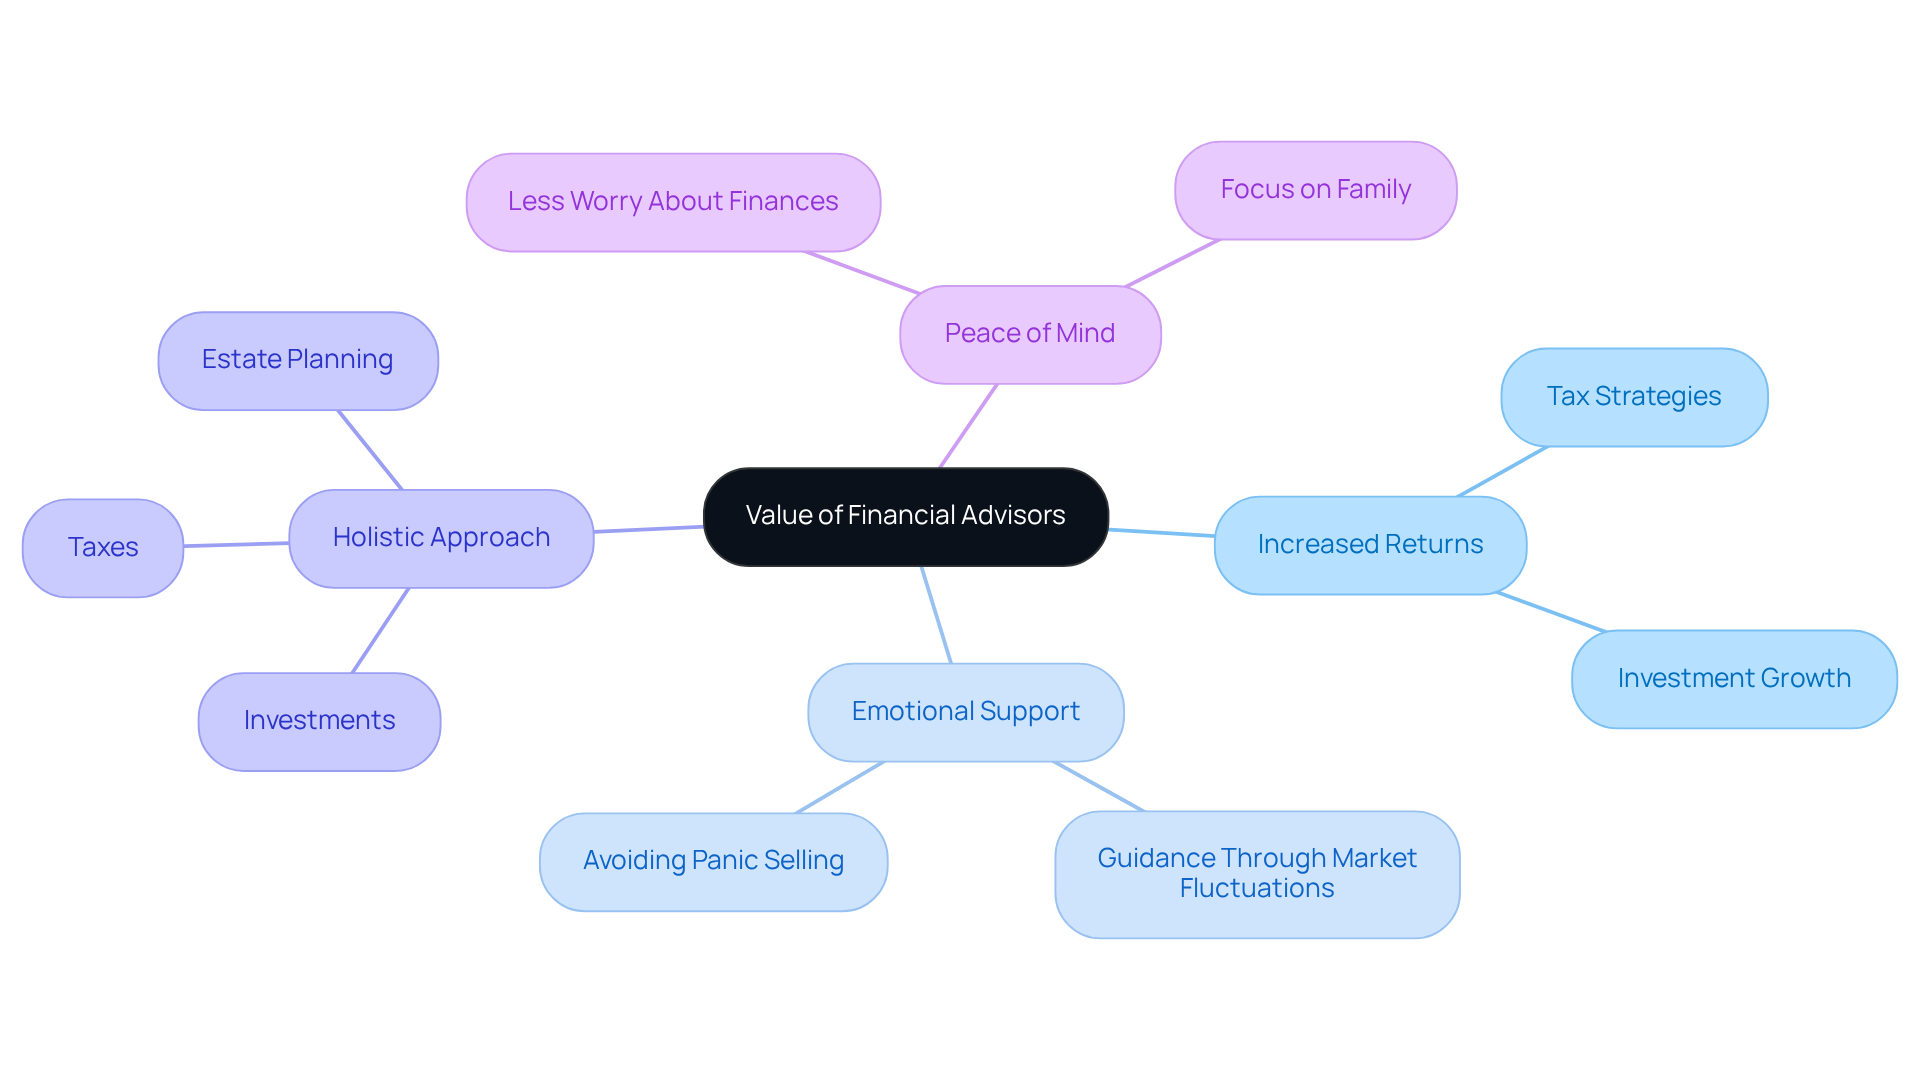
When it comes to choosing a financial advisor, families should consider a few key factors that can make a real difference. Have you ever wondered how professional guidance could help your family grow financially? Research shows that working with a financial expert can lead to increased returns on your investments. For instance, effective tax strategies can boost your returns by 2-3% each year. Just look at Allison and Brian, who optimized their financial potential with the help of Bright Advisers.
But it’s not just about numbers. This kind of support helps families feel more secure about their financial future. Financial professionals provide emotional coaching, guiding families through market ups and downs and helping them avoid common pitfalls like panic selling. Jay and Emma found confidence and empowerment through their collaboration with Bright Advisers, successfully balancing their current responsibilities with their long-term dreams.
Imagine having someone who looks at your entire financial picture, ensuring every aspect is covered. A skilled advisor offers a holistic approach to money management, addressing investments, taxes, estate planning, and more. This comprehensive service can lead to significant savings for families over time. Through their work with Bright Advisers, clients like Allison and Brian secured their children’s education funding and gained the ability to retire sooner, showcasing the transformative power of thorough planning.
When you have an expert by your side, you can truly enjoy those precious moments with your kids. In fact, 76% of advised clients reported spending less time worrying about finances. This peace of mind allows families like Jay and Emma to focus on what truly matters – nurturing their children while planning for a bright future.
By carefully assessing these factors, you can determine whether the financial advisor monthly fee is justified by the substantial value you receive. With the right support, you can turn financial uncertainty into a path toward a secure and fulfilling future for your family.
Conclusion
Navigating the world of financial advisor fees can feel overwhelming for many families. By understanding the various fee structures and their implications, you can make informed decisions that align with your long-term goals. This knowledge empowers you to view these costs not merely as expenses but as investments in your family’s well-being and financial stability.
Throughout this article, we’ve explored different types of financial advisor fees, including:
- Assets under management
- Flat fees
- Hourly rates
- Retainer fees
Each structure has its own advantages and can significantly impact your family’s budgeting and financial planning. Additionally, factors such as the advisor’s credentials, geographic location, and the complexity of services provided play a vital role in determining these costs. Recognizing these elements allows you to assess the value of the services you receive and negotiate fees that reflect your unique needs.
Ultimately, this journey is about finding a partner who understands your family’s unique needs and can help you navigate the complexities of financial planning. By investing in professional guidance, you can enhance your financial outcomes, reduce stress, and focus on what truly matters – creating lasting memories with your children. By taking this step, families can create a legacy of security and joy for their children.
Frequently Asked Questions
What are the common structures for financial advisor fees?
Common structures for financial advisor fees include a percentage of assets under management (AUM), flat charges, and hourly rates.
Why is it important for young parents to understand financial advisor fees?
Understanding financial advisor fees is essential for young parents as it helps them navigate their family’s financial future and make informed decisions regarding their investments and savings.
What are typical AUM fees for financial advisors?
Typical AUM fees usually fall between 0.75% and 1.5% each year.
How can financial advisor fees impact a family’s savings and investments?
Financial advisor fees can significantly affect a family’s savings and investments over time. For example, a 1% fee on a $2 million portfolio translates to $20,000 annually, highlighting the importance of understanding these costs.
How can families view advisory costs to make better financial choices?
Many families find that viewing advisory costs as an investment in their future helps them make better choices, as they recognize the potential for improved investment results and tax strategies.
What is the mission of Bright Advisers regarding financial advice?
Bright Advisers’ mission is to help families make wise wealth decisions and preserve wealth across generations.
How does Bright Advisers ensure transparency in their pricing?
Bright Advisers emphasizes being upfront about their pricing, ensuring there are no hidden fees or surprises, allowing families to get the most value from their services.
Who provides the advisory services mentioned in the article?
The advisory services are provided through Lifeworks Advisors, a registered investment adviser, to maintain compliance and transparency.
List of Sources
- Define Financial Advisor Fees and Their Importance
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? It Depends. – NerdWallet (https://nerdwallet.com/financial-advisors/learn/how-much-does-a-financial-advisor-cost)
- How Much Does a Financial Advisor Cost? 2026 Fee Guide (https://endeavorfg.com/feeds/blog/best-financial-advisors-flat-fee-structure-2025)
- Explore Common Financial Advisor Fee Structures
- How Much Does a Financial Advisor Cost? 2026 Fee Guide (https://endeavorfg.com/feeds/blog/best-financial-advisors-flat-fee-structure-2025)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- Identify Key Factors Affecting Financial Advisor Costs
- Pros and cons of different advisory fee models (https://envestnet.com/financial-intel/pros-and-cons-different-advisory-fee-models)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- What Is the Competition Charging? Comparing Financial Advisor Fees (https://horsesmouth.com/what-is-the-competition-charging-comparing-financial-advisor-fees)
- How Financial Advisors Actually Charge For Their Services (https://kitces.com/blog/financial-advisors-charge-services-fee-structure-advisory-firm-profession-aum-pricing-insight)
- Assess the Value of Financial Advisors Against Their Fees
- The Benefits Of Having A Financial Advisor – HB Wealth (https://hbwealth.com/insights/the-benefits-of-having-a-financial-advisor)
- Financial Advice Quotes (58 quotes) (https://goodreads.com/quotes/tag/financial-advice)
- The greatest value of financial advice: Peace of mind (https://corporate.vanguard.com/content/corporatesite/us/en/corp/articles/greatest-value-financial-advice-peace-mind.html)
- How Much Does a Financial Advisor Cost? Complete 2026 Fee Guide | Domain Money Financial Planning (https://domainmoney.com/post/how-much-does-a-financial-advisor-cost)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading