

Overview
This article presents four essential steps to help you navigate the cost of college with confidence and care.
- Understanding the total cost of attendance is crucial.
- Creating a comprehensive budget can make a significant difference in managing expenses.
- Exploring financial aid and scholarship opportunities is another vital step that can ease the financial burden.
- Regularly reviewing and adjusting your financial plan ensures you stay on track.
As you consider these steps, think about budgeting for various college expenses and the importance of the FAFSA for accessing financial aid. Engaging your children in financial discussions is also key; it prepares them for managing their educational costs and fosters a sense of responsibility. Remember, we’re here for you every step of the way as you embark on this important journey.
Key Highlights:
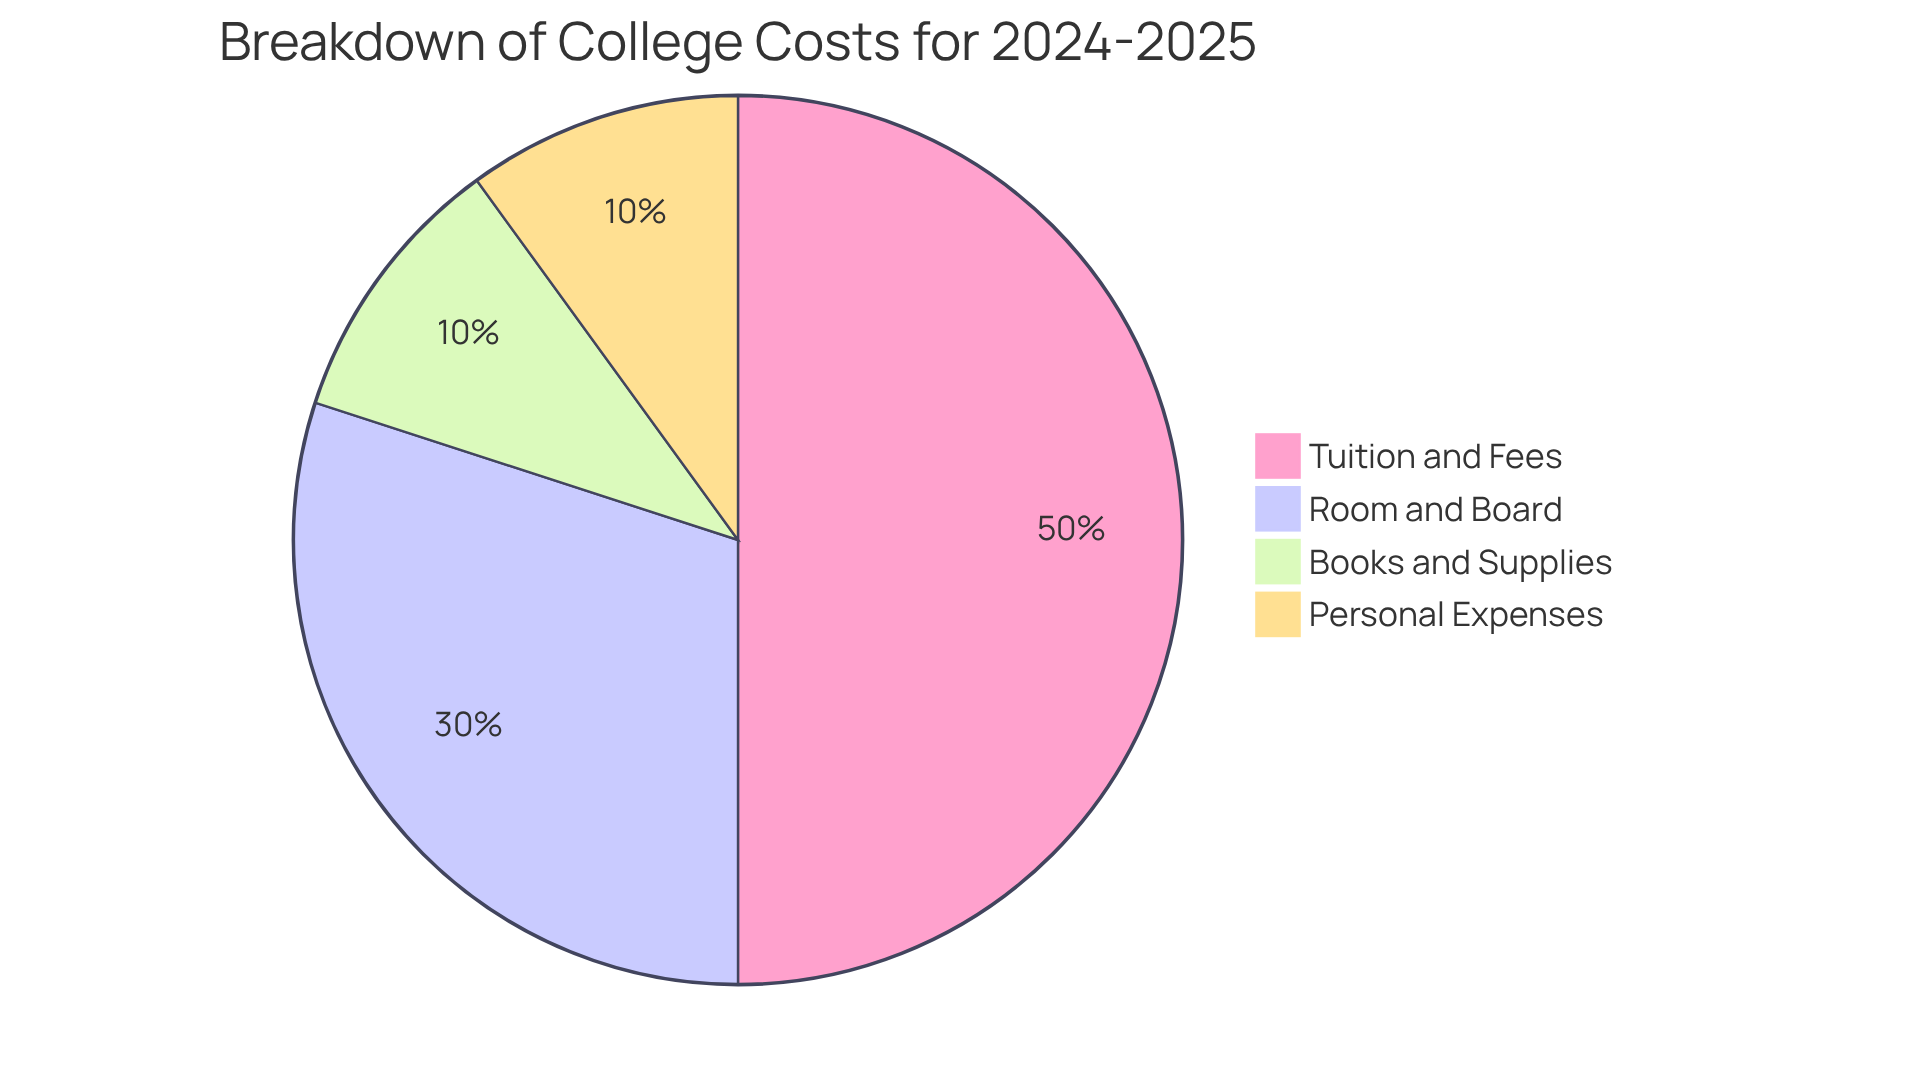
- Planning for college costs should start by understanding the total cost of attendance (COA), which includes tuition, fees, room, board, books, and personal expenses.
- For the 2024-2025 academic year, average tuition for private colleges is projected at $43,350, while public in-state tuition averages $11,610.
- It’s advisable to budget around $1,200 annually for books and supplies and $2,000 for personal expenses.
- Utilise tools like the College Cost Projector to estimate future college expenses and adjust for inflation.
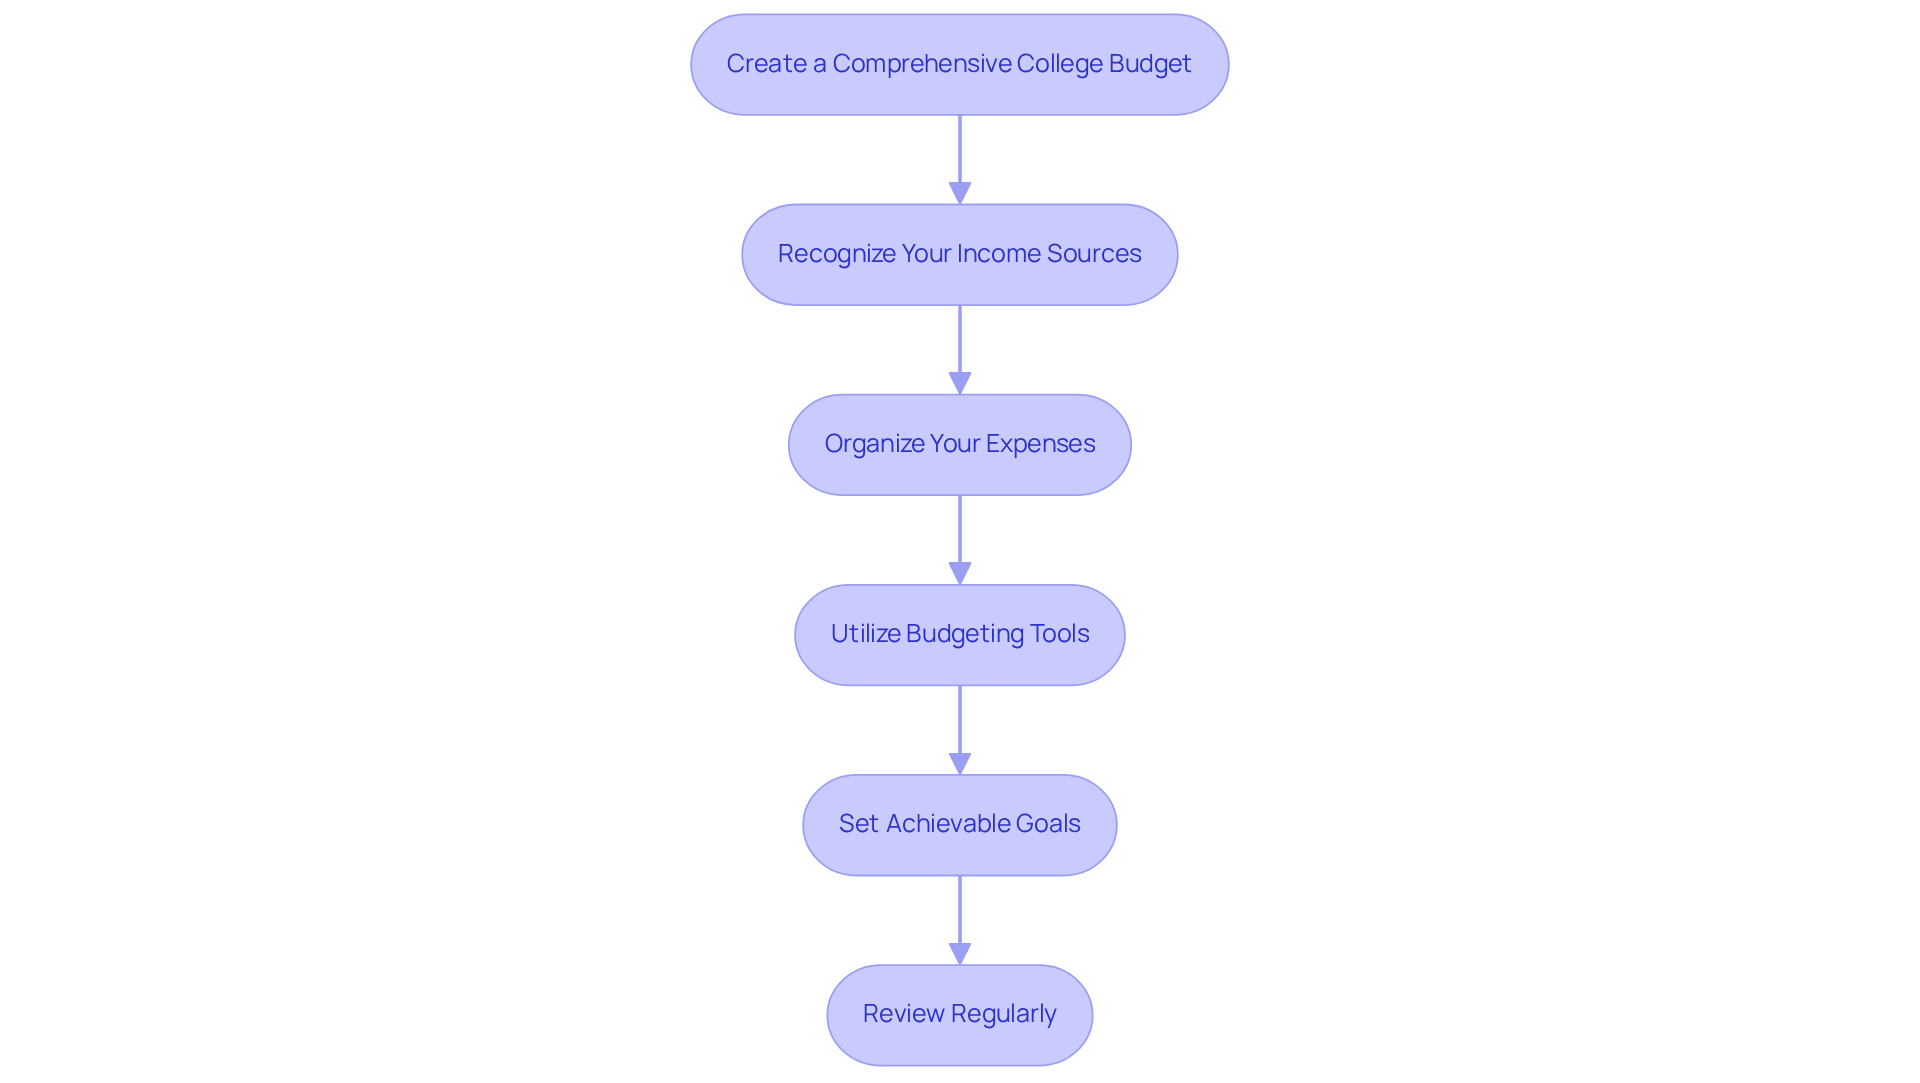
- Creating a comprehensive college budget involves recognising income sources, organising expenses, using budgeting tools, setting savings goals, and reviewing the budget regularly.
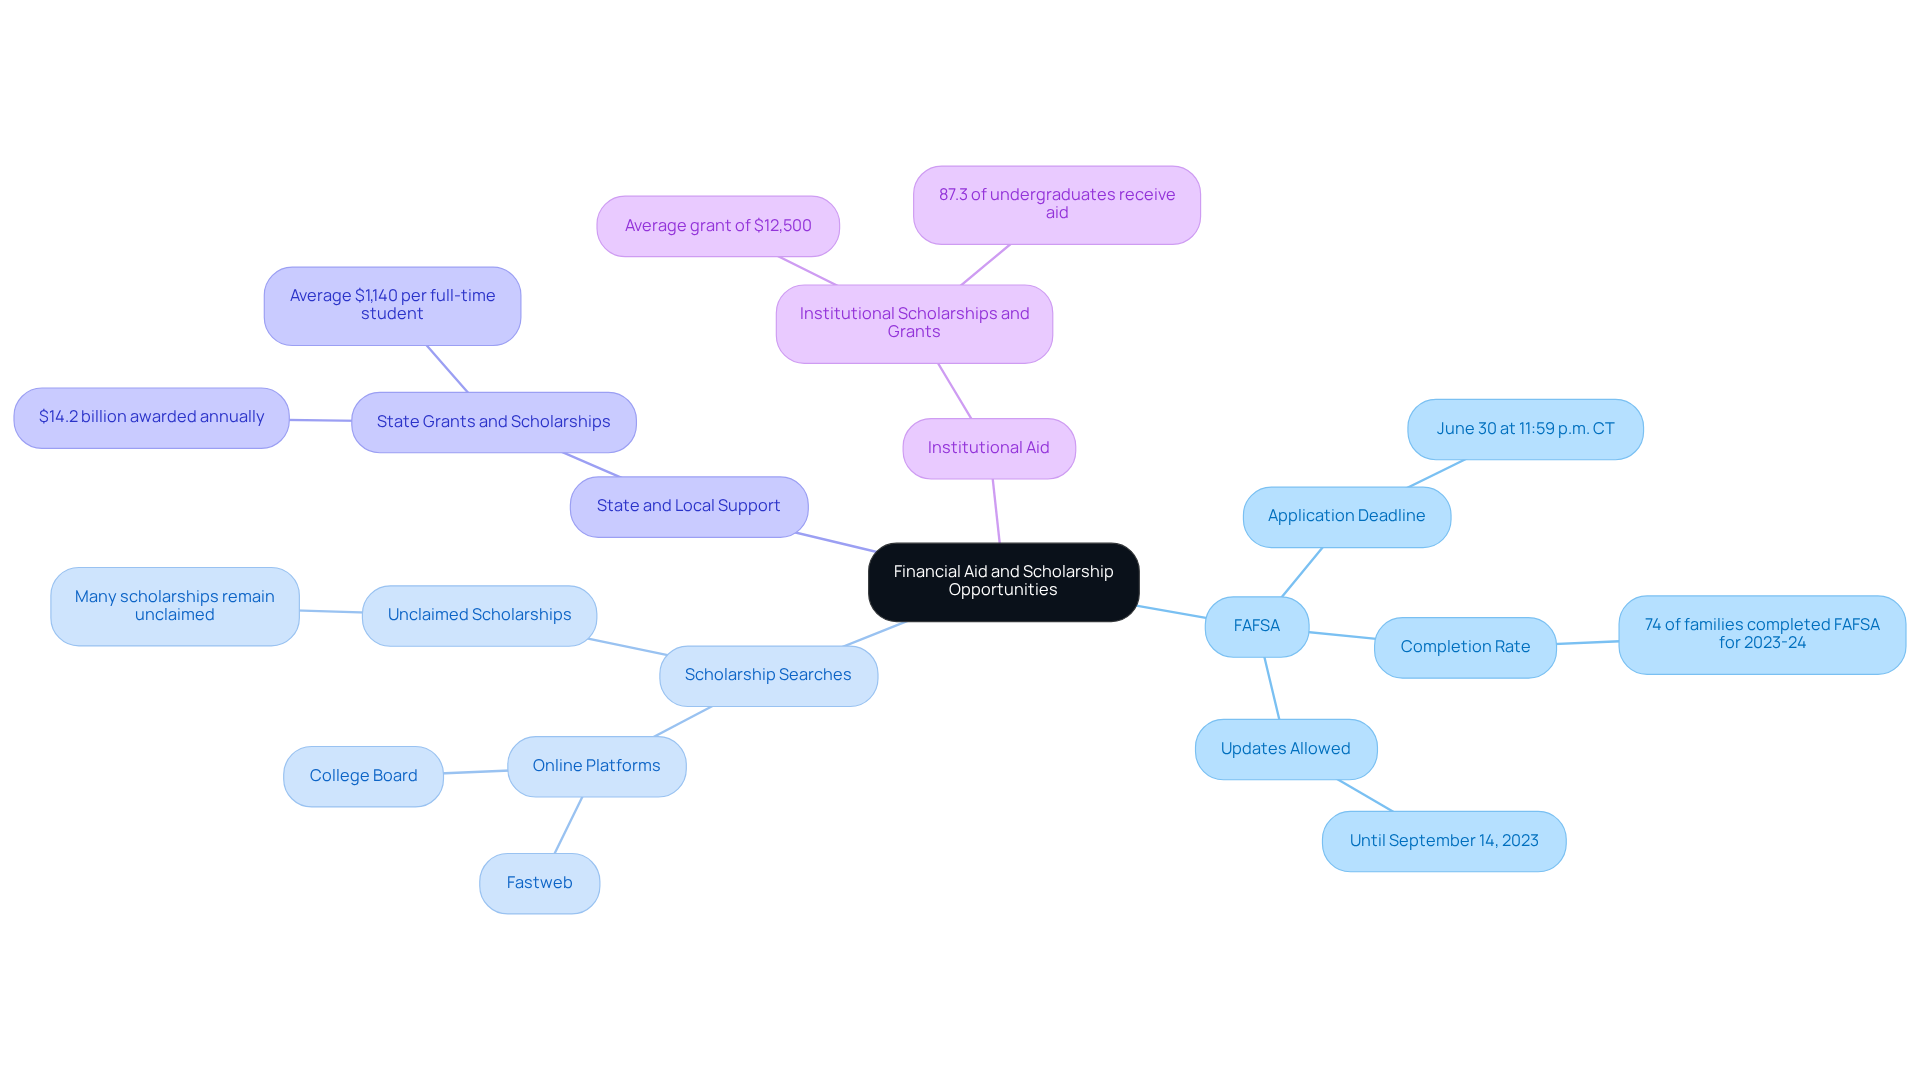
- Completing the FAFSA is crucial for accessing federal financial aid, with a deadline of June 30 for the academic year applied for.
- Scholarship opportunities can be explored through platforms like Fastweb and College Board, with many scholarships remaining unclaimed.
- State and institutional aid can significantly reduce costs, with states providing approximately $14.2 billion in assistance annually.
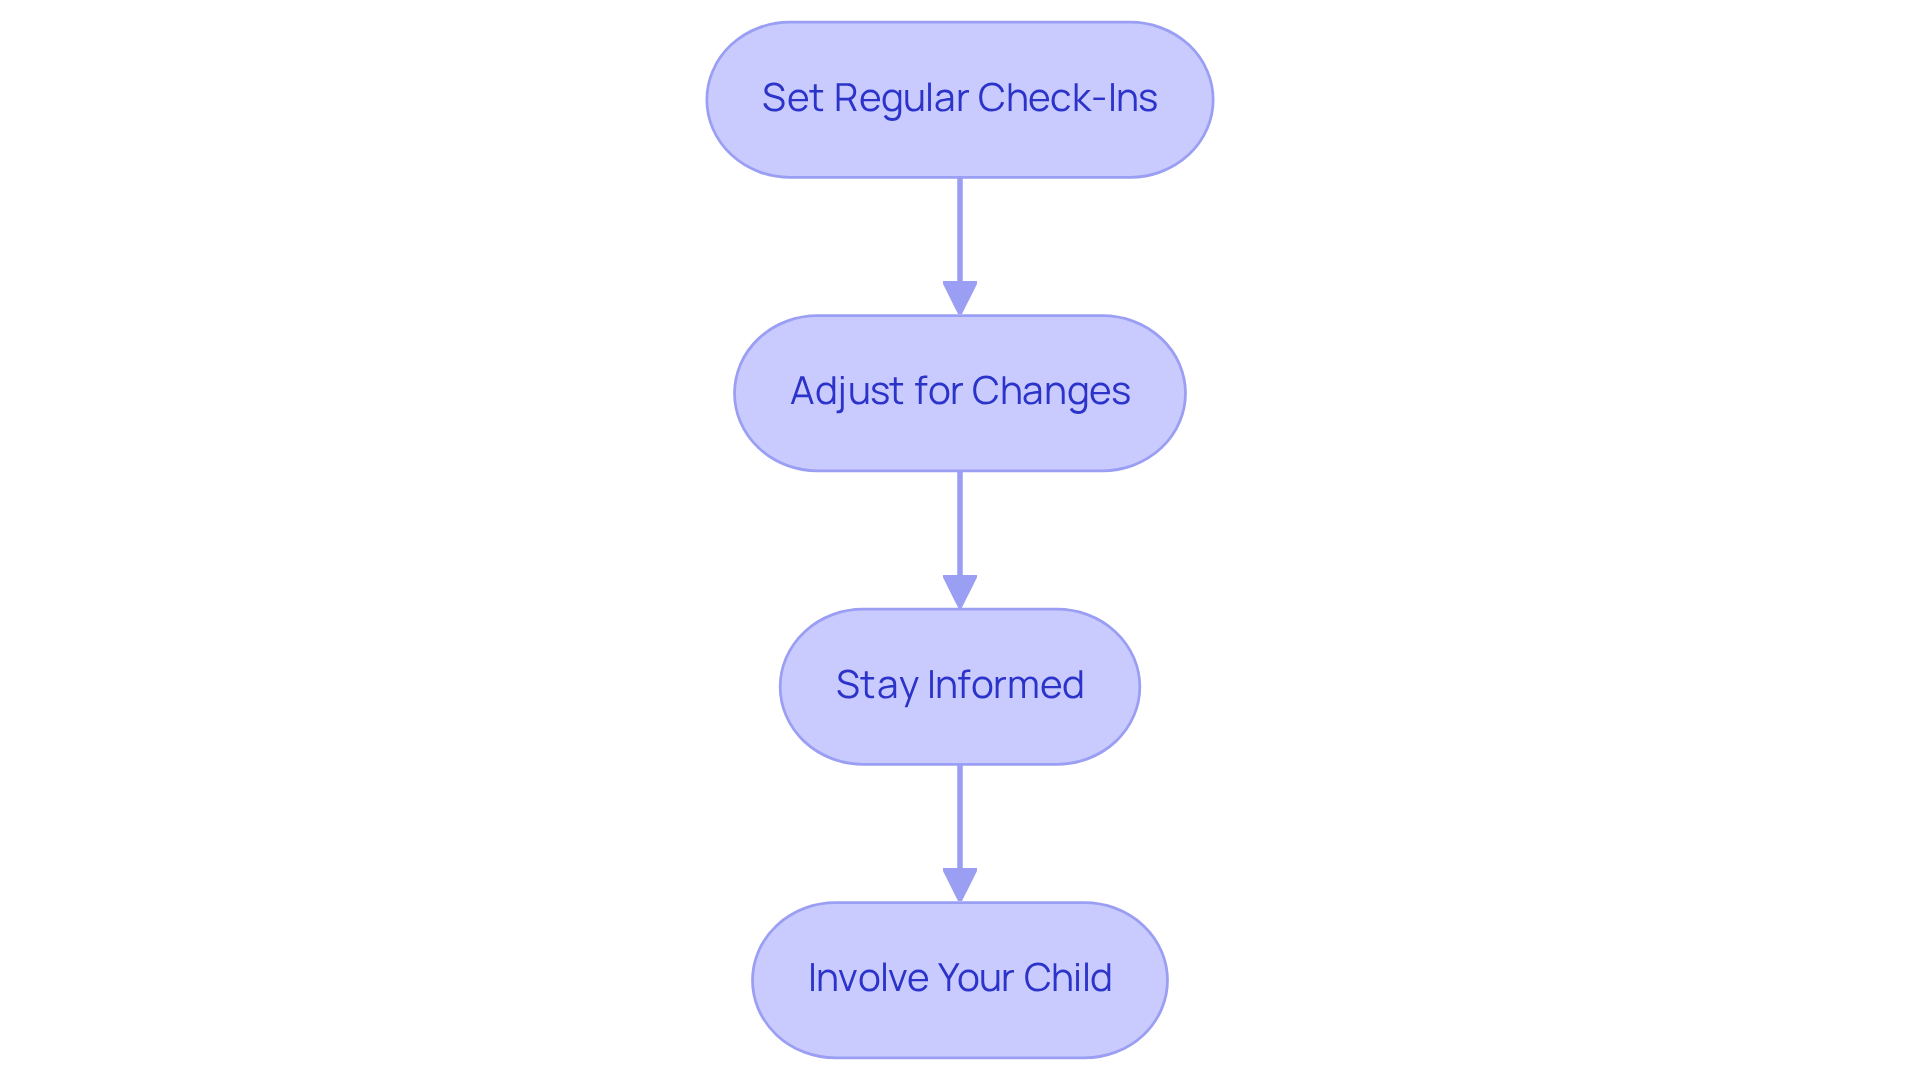
- Regular financial plan reviews help families adjust to changes in income and expenses, ensuring they stay on track to meet college funding goals.
- Engaging children in financial discussions prepares them for managing their educational expenses and fosters a sense of ownership over their funding.
Introduction
Navigating the financial landscape of higher education can often feel overwhelming for families. With college tuition costs on the rise and additional expenses lurking around every corner, understanding the true cost of college is more crucial than ever. Imagine if you had a clear roadmap to guide you through this journey.
This article offers actionable steps to help families effectively plan for college expenses, including:
- Creating a comprehensive budget
- Exploring financial aid opportunities
- Regularly reviewing financial strategies
It’s important to understand how to prepare for both the expected costs and the unexpected financial challenges that may arise. Together, we can navigate this journey with confidence.
Understand the True Cost of College
To efficiently prepare for educational expenses, planning for the cost of college is important and should start by exploring the overall costs of attendance (COA) for the schools your child is considering. This includes several key components that can significantly impact your family’s financial planning:
- Tuition and Fees: For the 2024-2025 academic year, the average tuition and fees for private nonprofit four-year colleges are projected to be around $43,350. However, it’s essential to note that students enrolled in private institutions often spend an average of $62,990 for overall expenses, which includes housing and supplies. For public four-year colleges, in-state tuition averages about $11,610, while out-of-state students can expect an average of $30,780.
- Room and Board: Living expenses can vary greatly depending on whether your child will live on-campus or off-campus. On-campus accommodation fees can differ significantly, so it’s vital to check the specific rates of the institutions you’re considering.
- Books and Supplies: It’s wise to set aside approximately $1,200 each year for textbooks and other essential materials, as these costs can add up quickly.
- Personal Expenses: Don’t forget to account for additional expenses such as transportation, meals, and personal items. A reasonable estimate would be to budget around $2,000 each year for these necessities.
Imagine having a clear picture of what to expect. Utilizing tools like the College Cost Projector can help you estimate future costs based on current data, allowing your family to adjust for inflation and potential tuition increases. Additionally, completing the FAFSA is crucial; remember, the federal deadline is June 30, but many state deadlines come earlier. By understanding these components, you can create a more precise budget while engaging in planning for the cost of college. Together, we can navigate this journey, ensuring your family is well-prepared for the future.
Create a Comprehensive College Budget
Planning for the cost of college requires creating a comprehensive budget to manage your family’s resources effectively. Let’s explore some steps together:
- Recognize Your Income Sources: Start by identifying all potential income streams—this includes your savings, earnings from a job, and any scholarships or assistance you might receive. Understanding where your money comes from is the first step toward financial security.
- Organize Your Expenses: It’s helpful to categorize your spending into fixed expenses, like tuition and housing, and variable expenses, such as food and entertainment. This way, you can clearly see where your money is going and make informed decisions.
- Utilize Budgeting Tools: Consider using budgeting apps or spreadsheets to keep track of your income and expenses. Tools like Mint and YNAB (You Need A Budget) can be invaluable for monitoring your financial situation and ensuring you stay within your means.
- Set Achievable Goals: Establish a savings goal, perhaps aiming to save 10% of your income each month. This approach helps you build a financial cushion over time, making it easier to manage educational costs.
- Review Regularly: Make it a routine to revisit your budget each month. Adjust for any changes in your income or expenses to stay on track and meet your financial goals.
By following these steps, families can effectively navigate the complexities of educational costs, which is essential for planning for the cost of college and paving the way for a financially secure future. Remember, you’re not alone in this journey—we’re here for you, and together, we can make it happen.
Explore Financial Aid and Scholarship Opportunities
To alleviate the financial burden of college, it’s important to actively seek out financial aid and scholarship opportunities:
-
FAFSA: Completing the Free Application for Federal Student Aid (FAFSA) is a crucial step in determining eligibility for federal grants, loans, and work-study programs. The 2025-26 FAFSA form is now available, and applying early is key, as funds are often allocated on a first-come, first-served basis. Remember, the FAFSA closes on June 30 at 11:59 p.m. CT for the academic year you are applying for. It’s encouraging to note that around 74% of families filled out the FAFSA for the 2023-24 academic year, highlighting the growing awareness of aid opportunities.
-
Scholarship Searches: Imagine the relief of finding scholarships that fit your child’s profile. Utilize online platforms like Fastweb or College Board to discover these opportunities. Many scholarships remain unclaimed due to a lack of applicants, so careful searching can lead to substantial financial assistance.
-
State and Local Support: Investigating state-specific grants and scholarships can uncover additional resources, as many states offer financial assistance to residents pursuing higher education. States collectively grant an estimated $14.2 billion in assistance each year, with an average of $1,140 per full-time student, providing a clearer understanding of the aid landscape.
-
Institutional Aid: It’s essential to check with the colleges your child is interested in regarding any institutional scholarships or grants they may offer. Many schools have their own assistance programs that can significantly reduce costs. In fact, the typical institutional grant awarded to undergraduate students is approximately $12,500, and with 87.3% of undergraduate students receiving aid, this support can make a meaningful difference in overall expenses.
By understanding and utilizing these resources, families can effectively navigate the economic landscape of higher education and secure the necessary funding for their children’s college journey. As we know, “The amount of aid you’ll qualify for will be influenced by several factors,” so being aware of eligibility requirements is vital. Additionally, keep in mind that updates to the FAFSA can be made until September 14, 2023, at 11:59 p.m. CT. Together, we can navigate this journey and ensure a brighter future for your children.
Review and Adjust Your Financial Plan Regularly
Effective monetary planning is an ongoing journey that requires your regular attention and thoughtful adjustments. Here are some key strategies to help you keep your college funding plan on track:
- Set Regular Check-Ins: Imagine scheduling quarterly reviews of your financial plan to evaluate how well you’re progressing toward your college funding goals. These regular assessments can help you identify areas that need adjustment and ensure you stay aligned with your objectives. Research shows that families who engage in consistent monetary planning often enjoy better outcomes; in fact, 78% of CFP® professional-advised clients maintain three-month emergency funds. For instance, Jay and Emma, a couple aiming to reduce monetary stress, benefited from regular meetings with their advisor at Bright Advisers, which guided them in optimizing their education savings choices.
- Adjust for Changes: Life can be unpredictable. If your monetary situation shifts—perhaps due to a job loss or unexpected expenses—it’s crucial to revisit your budget and aid applications. Adjusting your funding plan to reflect these changes is essential for sustaining your strategy. Emily and Mark faced challenges in managing their finances while juggling demanding careers, but their collaboration with Bright Advisers enabled them to adapt their plans effectively as their circumstances evolved.
- Stay Informed: Financial aid policies and tuition costs can vary. By staying informed—perhaps through newsletters from assistance offices or educational resources—you empower yourself to make educated decisions regarding planning for the cost of college for your child’s education funding. Allison and Brian discovered the significance of staying updated on tax planning, which greatly influenced their ability to secure their children’s future through education funding.
- Involve Your Child: As your child approaches college age, consider engaging them in discussions about money. Teaching them about budgeting and financial responsibility not only prepares them for managing their own expenses but also fosters a sense of ownership over their educational funding, which is crucial when planning for the cost of college.
Regular monetary check-ins are vital for success. As Kevin Roth, Ph.D., Managing Director of Research at CFP Board, notes, “Our initial findings demonstrate that Americans working with CFP® professionals not only have better monetary outcomes, but they also enjoy a healthier relationship with money.” By implementing these strategies, including a commitment to minimal fund fees at Bright Advisers, you can enhance your family’s financial stability and ensure a smoother transition into higher education, just as many families have successfully achieved with the support of Bright Advisers.
Conclusion
Navigating the financial complexities of higher education can feel overwhelming, but with the right strategies, families can embark on this journey with confidence. Understanding the true cost of college—tuition, room and board, books, and personal expenses—serves as a solid foundation for informed financial planning. By creating a comprehensive budget, exploring financial aid opportunities, and regularly reviewing financial strategies, families can arm themselves with the necessary tools to tackle college expenses effectively.
Key insights shared in this article highlight the importance of:
- Recognizing income sources
- Organizing expenses
- Utilizing budgeting tools to maintain financial control
Actively seeking financial aid and scholarship opportunities can significantly ease the burden of college costs. Regular check-ins and adjustments to the financial plan ensure families remain aligned with their educational funding goals. Involving children in financial discussions fosters a sense of responsibility and awareness about the costs associated with their education.
Ultimately, effective planning for college expenses is not merely about crunching numbers; it’s about preparing for a future filled with opportunities. By implementing these actionable steps, families can navigate the financial landscape with greater ease, ensuring that higher education remains an attainable goal. Taking proactive measures today will lead to a more secure financial tomorrow, empowering students to focus on their studies rather than financial stress. Together, we can navigate this journey, ensuring that the promise of higher education becomes a reality for every family.
Frequently Asked Questions
What are the main components of the cost of college (COA)?
The main components of the cost of college include tuition and fees, room and board, books and supplies, and personal expenses.
What is the average tuition for private nonprofit four-year colleges for the 2024-2025 academic year?
The average tuition and fees for private nonprofit four-year colleges are projected to be around $43,350.
What are the average overall expenses for students at private institutions?
Students enrolled in private institutions often spend an average of $62,990 for overall expenses, which includes housing and supplies.
How much is the average in-state tuition for public four-year colleges?
The average in-state tuition for public four-year colleges is about $11,610.
What is the average tuition for out-of-state students at public four-year colleges?
Out-of-state students can expect an average tuition of about $30,780.
How much should be budgeted for books and supplies each year?
It is wise to set aside approximately $1,200 each year for textbooks and other essential materials.
What is a reasonable estimate for personal expenses during college?
A reasonable estimate for personal expenses, including transportation, meals, and personal items, would be around $2,000 each year.
How can families estimate future college costs?
Families can utilize tools like the College Cost Projector to estimate future costs based on current data, adjusting for inflation and potential tuition increases.
Why is completing the FAFSA important?
Completing the FAFSA is crucial for financial aid eligibility; the federal deadline is June 30, but many state deadlines come earlier.
How can understanding the costs of college help families?
By understanding the components of college costs, families can create a more precise budget and better engage in planning for the cost of college.
List of Sources
- Understand the True Cost of College
- What You Need to Know About College Tuition Costs (https://usnews.com/education/best-colleges/paying-for-college/articles/what-you-need-to-know-about-college-tuition-costs)
- College Affordability Report: Statistics in 2025 (https://bold.org/blog/college-scholarship-statistics)
- Trends in College Pricing Highlights – College Board Research (https://research.collegeboard.org/trends/college-pricing/highlights)
- Average Cost Of College 2024-2025 | Bankrate (https://bankrate.com/loans/student-loans/average-cost-of-college)
- Create a Comprehensive College Budget
- How much to save for college (https://savingforcollege.com/article/how-much-to-save-for-college)
- College Savings Options: The Best Way to Save for College for 2025 | Research.com (https://research.com/student-loans/college-savings-options-the-best-way-to-save-for-college)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOoqrfNbNCE-kFW-NQgPZfAa3POCWjodb7YxJ-Nk2B-Hukxv61tsn)
- Explore Financial Aid and Scholarship Opportunities
- Financial Aid Statistics [2025]: Average Aid per Student (https://educationdata.org/financial-aid-statistics)
- 2023 FAFSA Statistics | Bankrate (https://bankrate.com/loans/student-loans/fafsa-statistics)
- 35 Interesting FAFSA Stats All Students Should Know | College Raptor (https://collegeraptor.com/paying-for-college/articles/financial-aid/interesting-fafsa-stats)
- Financial Aid Statistics: Average Financial Aid Packages, Federal Student Loans, and More (https://savingforcollege.com/article/financial-aid-statistics)
- Review and Adjust Your Financial Plan Regularly
- Americans Head Into 2025 With Financial Confidence: Survey (https://thinkadvisor.com/2025/01/07/americans-head-into-2025-with-financial-confidence-survey)
- 27 eye-opening financial planning statistics (https://contentsnare.com/financial-planning-statistics)
- digitaldefynd.com (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 20 + Personal Finance Statistics for 2025 | Fortunly (https://fortunly.com/statistics/personal-finance-statistics)
- Study: Americans Working With CFP® Professionals Enjoy Greater Financial Well-Being (https://cfp.net/news/2025/02/news-releases/americans-working-with-cfp-professionals-enjoy-greater-financial-well-being)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading