

Overview
Setting up a SEP IRA can be a simple yet impactful step for young parents looking to secure their family’s financial future. Imagine having a retirement plan that not only offers significant tax benefits but also allows for high contribution limits and flexibility in contributions. This straightforward process involves:
- Selecting a financial institution
- Completing IRS Form 5305-SEP
- Ensuring that all eligible employees have separate accounts
It’s important to understand that this retirement plan is more than just a financial tool; it’s a valuable resource that can help you nurture your family’s dreams. With the right support, you can navigate the complexities of financial planning with confidence. We’re here for you, ready to assist you every step of the way.
Together, we can explore how a SEP IRA can fit into your family’s goals and priorities, ensuring you have the security you deserve. Take this opportunity to invest in your family’s future and embrace the peace of mind that comes with it.
Key Highlights:
- A SEP IRA offers significant tax benefits and flexibility for self-employed individuals and small business owners.
- Contributions to a SEP IRA are tax-deductible, lowering taxable income and enhancing savings.
- In 2025, the contribution limit is up to 25% of compensation or $70,000, whichever is lower, allowing for greater retirement savings.
- Employers can adjust contributions annually based on business performance, providing financial flexibility.
- Setting up a SEP IRA involves minimal paperwork and can be completed easily through a financial institution.
- Eligibility for contributions requires employees to be at least 21, have worked for three of the last five years, and earned a minimum of $750.
- Only employers can make contributions to the SEP IRA, and all contributions are immediately vested.
- Regularly reviewing contributions and diversifying investments can enhance retirement savings and mitigate risks.
- Staying informed about tax law changes and withdrawal rules is crucial for effective SEP IRA management.
- Engaging family members in financial discussions promotes economic literacy and prepares them for future responsibilities.
Introduction
In the intricate landscape of retirement planning, the Simplified Employee Pension (SEP) IRA stands out as a powerful ally for self-employed individuals and small business owners. If you’re looking to enhance your family’s financial security, this tool offers appealing tax advantages, high contribution limits, and remarkable flexibility. Imagine being able to build a robust retirement nest egg that supports your loved ones. However, it’s important to understand the fundamental features and rules of establishing and managing this retirement plan.
This article gently guides you through the essential aspects of a SEP IRA. We’ll explore the steps to set one up, the contribution limits and regulations to consider, and effective management strategies that can ensure long-term success. As families like yours seek to secure their financial futures, understanding the potential of a SEP IRA can truly be a game-changer in wealth management. Together, we can navigate this journey toward a brighter financial future for you and your loved ones.
Understand the Basics of a SEP IRA
Setting up SEP IRA provides a thoughtful retirement savings plan designed for self-employed individuals and small business owners, offering significant tax benefits and flexibility. Let’s explore some essential features that could make a real difference for your family’s future.
- Tax Advantages: Contributions made to a SEP IRA are tax-deductible, which can effectively lower your taxable income. This means more savings in your pocket, especially for small business owners looking to enhance their financial strategies. Bright Advisers emphasizes minimal fund fees, allowing families to maximize their savings without the worry of high costs.
- High Contribution Limits: In 2025, you can contribute up to 25% of your compensation or a maximum of $70,000, whichever is lower, based on the first $350,000 of compensation. This increase of $5,000 from 2024 opens up greater retirement savings potential, particularly beneficial for those with higher earnings. With customized wealth management services from Bright Advisers, families can fully utilize these limits, improving their economic security.
- Flexibility: One of the standout features of a SEP IRA is the ability for employers to determine their contribution amounts each year. This flexibility allows you to adjust contributions based on your business’s performance, helping you manage cash flow while still prioritizing retirement savings. Bright Advisers’ innovative strategies, including scientific investment approaches and hyper-personalized portfolios, ensure families can navigate these decisions effectively, reducing anxiety about future financial stability.
- Easy Setup: Establishing a SEP IRA is a straightforward process, requiring minimal paperwork compared to other retirement plans. This simplicity makes it an appealing option for busy parents and entrepreneurs. With Bright Advisers’ advanced technology, families can easily integrate their planning with their investment strategies, ensuring a comprehensive approach to wealth accumulation.
Understanding these basics can help you identify the potential benefits of setting up SEP IRA, paving the way for a more stable economic future for your family. For self-employed individuals, careful planning is crucial to maximize contributions and avoid penalties, as contributions must be uniform for all employees, including the owner. This requires thoughtful calculation of gross income and allowable deductions. Real-world examples show how self-employed individuals can effectively save for retirement while managing their business finances, often benefiting from professional guidance to navigate these complexities. As June Sham notes, “This means that you have until October 15th to contribute for the previous tax year.” As you think about your family’s financial future, setting up a SEP IRA could serve as a valuable resource in your wealth management strategy, especially with the availability of high-quality economic services for families. Together, we can navigate this journey towards a secure financial future.
Follow Steps to Establish Your SEP IRA
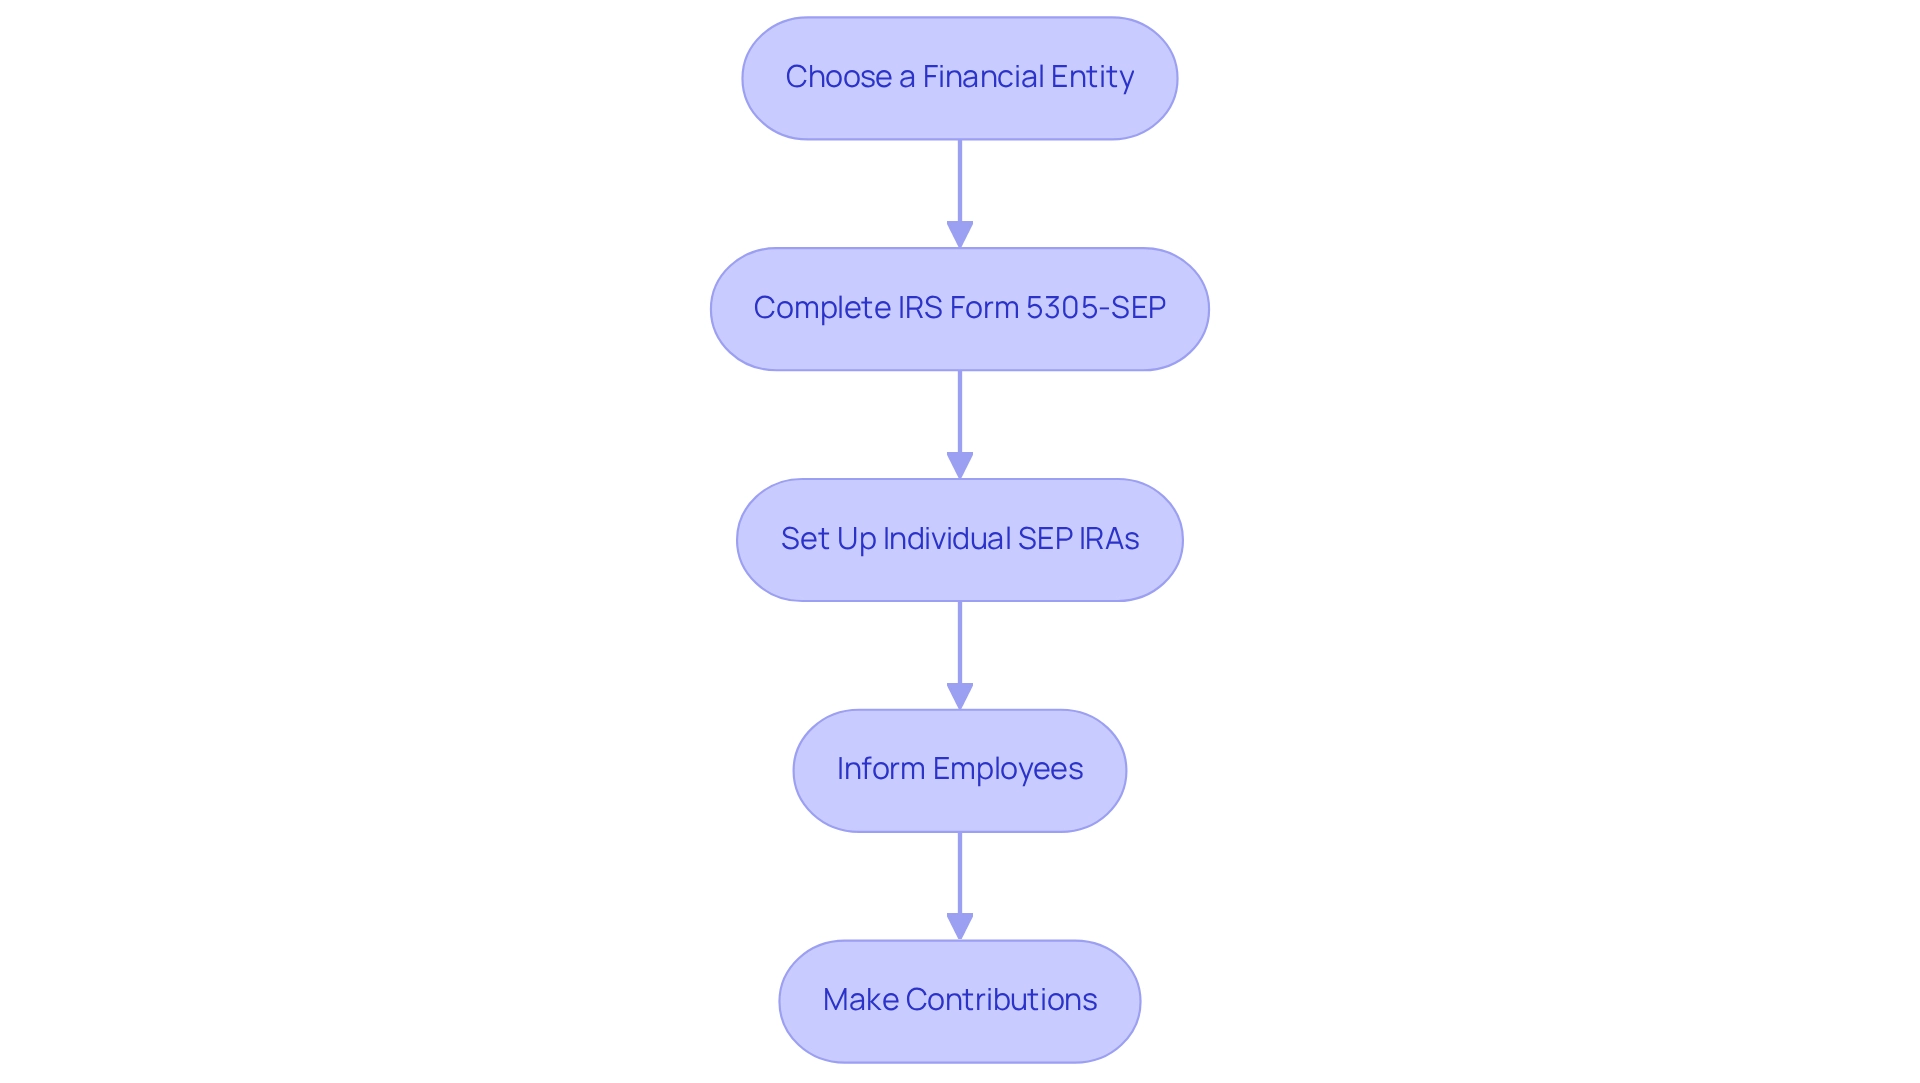
To ensure your family’s financial future, focus on setting up a SEP IRA by following these caring steps:
- Choose a Financial Entity: Begin by selecting a reputable bank, brokerage, or institution that offers SEP IRAs. Look for one that understands your needs and provides the support you deserve.
- Complete IRS Form 5305-SEP: This form serves as a written agreement to establish your SEP plan. You can easily obtain it from the IRS website or through your chosen banking institution. Recent updates in 2025 ensure it remains user-friendly and compliant with current regulations.
- Set Up Individual SEP IRAs: Each eligible employee, including yourself, must have a separate SEP IRA account. Your banking institution will be there to assist you in setting up these accounts efficiently.
- Inform Employees: If you have employees, it’s essential to share comprehensive information about the SEP plan, detailing how it operates and the benefits they will receive.
- Make Contributions: Determine your contribution amount for the year and ensure that contributions are made by the tax filing deadline, including any extensions. Remember, you can create a SEP plan up to the deadline of your business’s income tax return for that year, providing you with flexibility in your financial planning.
Case Study: Imagine a scenario where a SEP no longer meets your business’s needs. In such a case, employers can end the plan by simply informing the institution and stopping contributions. This process allows companies to adjust their retirement strategies as needed without substantial regulatory constraints, and by setting up a SEP IRA, you can effectively ensure a solid foundation for your household’s economic future. Together, we can navigate this journey toward financial stability.
Learn About Contribution Limits and Rules
When considering contributions to a SEP IRA, it’s important to understand the following limits and rules that can significantly impact your family’s financial future:
- Contribution Limits: For 2025, the maximum contribution is set at 25% of your compensation or $70,000, whichever is lower. This reflects a $1,000 increase from the 2024 limit of $69,000, making it an attractive option for self-employed individuals and small business owners who want to maximize their retirement savings. As noted by the Human Interest Team, self-employed individuals can contribute up to 25% of their annual net earnings while setting up a SEP IRA.
- Eligibility: To qualify for contributions, employees must be at least 21 years old, have worked for the employer for at least three of the last five years, and earned a minimum of $750 in compensation during the year. It’s important to ensure you meet these criteria to take advantage of this opportunity.
- Employer Contributions Only: When setting up a SEP IRA, contributions can only be made by employers; employees are not permitted to contribute on their own. This means that as a business owner, you hold the key to your employees’ retirement savings.
- Vesting: Contributions are immediately vested, granting employees full ownership of the funds as soon as they are deposited. This immediate vesting is a wonderful benefit that provides security and peace of mind.
- Tax Implications: Contributions are tax-deductible for employers, and the funds grow tax-deferred until withdrawal. However, be mindful that withdrawals made before age 59½ may incur a 10% early withdrawal penalty.
Understanding these limits and regulations will empower you to make informed choices regarding setting up a SEP IRA for your retirement contributions. After all, preparing for your family’s economic future is a journey we can navigate together.
Manage Your SEP IRA for Long-Term Success
To ensure the long-term success of your SEP IRA, consider implementing the following management strategies:
- Regularly Review Contributions: Imagine conducting an annual assessment of your business’s financial health to determine your contribution capacity. By adjusting your contributions based on profitability, you can maximize your retirement savings. This approach reflects the journey of clients like Allison and Brian, who, through effective tax planning, secured their economic future, leading to a 20% rise in their retirement savings over two years.
- It’s important to work together with your banking institution to create a varied investment strategy when setting up SEP IRA. With 58% of retirement assets in defined contribution plans managed by mutual funds in the U.S., diversification can help mitigate risks and enhance growth potential. Bright Advisers highlights this approach, assisting individuals like Allison and Brian in attaining a balanced portfolio that boosted their investment returns by 15%.
- Stay informed about changes in tax laws and contribution limits that may affect your setting up SEP IRA. Regularly checking the IRS website or connecting with a monetary advisor can ensure compliance and enhance your strategy. As Steven Bass noted, “While there is room for further improvement, that progress is cause for celebration,” emphasizing the importance of actively managing retirement accounts. This proactive method is crucial for households like Emily and Mark, who achieved clarity and control over their monetary situation through customized guidance, resulting in a 10% decrease in their total tax obligations.
- It’s essential to familiarize yourself with the rules governing withdrawals when setting up SEP IRA. While withdrawals can be made at any time, be aware that doing so before age 59½ may result in taxes and penalties. Understanding these guidelines is vital for families striving to ensure their economic future, just as Allison and Brian accomplished by planning effectively, enabling them to retire two years sooner than expected.
- Educate your family by involving your spouse and children in discussions about setting up SEP IRA and managing money overall. This engagement promotes economic literacy in your children, preparing them for future responsibilities. Bright Advisers motivates households to take an active part in their monetary education, empowering them to make informed choices, which has proven advantageous for families like Emily and Mark, who now feel more assured in managing their finances.
By actively engaging in setting up SEP IRA with these strategies, you can maximize its benefits and secure a more stable financial future for your family. The case study titled ‘The Facts Are Clear’ illustrates how IRAs and similar accounts are effectively helping U.S. households focus on long-term wealth building, reinforcing the importance of proactive management when setting up SEP IRA.
Conclusion
The Simplified Employee Pension (SEP) IRA stands as a vital ally for self-employed individuals and small business owners eager to secure their financial future. By recognizing its essential features—such as tax advantages, high contribution limits, and flexibility—families can harness this retirement savings plan to enhance their wealth management strategies. Imagine being able to contribute up to 25% of your compensation or $70,000 in 2025! With a straightforward setup process, the SEP IRA becomes an accessible option for those looking to build a robust retirement fund.
Establishing a SEP IRA involves several key steps:
- Selecting a financial institution
- Completing necessary paperwork
- Informing employees
It’s important to stay informed about contribution limits and eligibility rules to maximize benefits. The immediate vesting of contributions and the tax-deductible nature of employer contributions highlight the advantages of this retirement plan.
For long-term success, actively managing a SEP IRA is essential. Regularly reviewing contributions, diversifying investments, and planning for withdrawals can significantly enhance your retirement savings journey. Engaging family members in financial discussions not only fosters financial literacy but also prepares the next generation for future responsibilities.
In conclusion, a SEP IRA represents a powerful opportunity for families to secure their financial futures. By taking proactive steps to establish and manage this retirement plan, individuals can navigate the complexities of wealth accumulation, ensuring a stable and prosperous retirement for themselves and their loved ones. Together, we can embrace the potential of a SEP IRA, making it a game-changer in achieving long-term financial success.
Frequently Asked Questions
What is a SEP IRA and who is it designed for?
A SEP IRA is a retirement savings plan designed for self-employed individuals and small business owners, offering significant tax benefits and flexibility.
What are the tax advantages of a SEP IRA?
Contributions made to a SEP IRA are tax-deductible, which lowers your taxable income, allowing for more savings, especially beneficial for small business owners.
What are the contribution limits for a SEP IRA in 2025?
In 2025, you can contribute up to 25% of your compensation or a maximum of $70,000, whichever is lower, based on the first $350,000 of compensation.
How flexible is a SEP IRA regarding contributions?
Employers can determine their contribution amounts each year, allowing adjustments based on business performance, which helps manage cash flow while prioritizing retirement savings.
How easy is it to set up a SEP IRA?
Establishing a SEP IRA is straightforward and requires minimal paperwork compared to other retirement plans, making it appealing for busy parents and entrepreneurs.
What should self-employed individuals consider when setting up a SEP IRA?
Self-employed individuals should carefully plan to maximize contributions and avoid penalties, as contributions must be uniform for all employees, including the owner, which requires thoughtful calculation of gross income and allowable deductions.
When is the deadline for contributing to a SEP IRA for the previous tax year?
You have until October 15th to contribute to a SEP IRA for the previous tax year.
List of Sources
- Understand the Basics of a SEP IRA
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- nerdwallet.com (https://nerdwallet.com/article/investing/what-is-a-sep-ira)
- SEP-IRA Contribution Limits 2025 | Maximize Your Retirement | Human Interest (https://humaninterest.com/learn/articles/sep-ira-contribution-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Follow Steps to Establish Your SEP IRA
- Retirement plans: FAQs regarding SEPs | Internal Revenue Service (https://irs.gov/retirement-plans/retirement-plans-faqs-regarding-seps)
- SEP Retirement Plans For Small Businesses (https://dol.gov/agencies/ebsa/about-ebsa/our-activities/resource-center/publications/sep-retirement-plans-for-small-businesses)
- How to Set Up a SEP IRA (https://investopedia.com/articles/retirement/04/020404.asp)
- Learn About Contribution Limits and Rules
- SEP-IRA Contribution Limits 2025 | Maximize Your Retirement | Human Interest (https://humaninterest.com/learn/articles/sep-ira-contribution-limits)
- SEP IRA Contribution Limits for 2025 (https://kiplinger.com/retirement/sep-ira/sep-ira-limits)
- SEP IRA contribution limits for 2024 and 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/sep-ira-contribution-limits)
- Manage Your SEP IRA for Long-Term Success
- Topic: Retirement saving in the United States (https://statista.com/topics/1217/retirement-saving)
- Americans’ Retirement Savings Show Real Progress (https://ici.org/viewpoints/24-view-real-progress)
- 50+ Essential Retirement Statistics for 2025: Demographics (https://annuity.org/retirement/retirement-statistics)
- New Data Reveal Inequality in Retirement Account Ownership (https://census.gov/library/stories/2022/08/who-has-retirement-accounts.html)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin