

Overview
Imagine a future where your family’s financial security is a reality. The main focus of this article is to gently guide you through the process of converting a Simple IRA to a Roth IRA, a step that can unlock significant tax benefits for your family. This conversion can lead to tax-free withdrawals in retirement, providing peace of mind as you plan for your loved ones’ futures.
It’s important to understand the tax implications that come with this conversion. Consulting with a financial advisor can help tailor the process to your unique financial situation, ensuring that you make the best decisions for your family’s needs. Together, we can navigate this journey and find the right path for you.
Remember, you’re not alone in this. We’re here for you, offering support and guidance every step of the way. By taking this proactive step, you’re investing in a brighter future for your family, one that aligns with your values and aspirations.
Key Highlights:
- A Simple IRA is designed for small businesses and self-employed individuals, allowing contributions from both employees and employers.
- A Roth IRA allows for tax-free withdrawals during retirement, making it an attractive option for many families.
- To convert a Simple IRA to a Roth IRA, individuals must wait two years from their initial contribution to be eligible.
- The amount converted from a Simple IRA to a Roth IRA is taxed as ordinary income in the year of transfer.
- Consulting a financial advisor is recommended to tailor decisions based on individual financial circumstances.
- The conversion process involves confirming eligibility, selecting a custodian, completing necessary forms, and paying applicable taxes.
- Tax implications include the possibility of moving into a higher tax bracket due to increased taxable income from the conversion.
- Roth IRAs offer benefits such as no required minimum distributions (RMDs) during the account holder’s lifetime, providing more flexibility in retirement planning.
- Real-life examples illustrate how families have improved their financial security through effective retirement planning and tax optimization strategies.
Introduction
Navigating the complexities of retirement planning can feel overwhelming, especially when trying to understand the intricacies of various accounts. Imagine if there were a way to simplify this process and unlock significant tax advantages for you and your family. One increasingly popular strategy is converting a Simple IRA into a Roth IRA. As more individuals discover the potential of this conversion to provide tax-free growth and withdrawals in retirement, it becomes essential to understand the eligibility requirements, the conversion process, and the associated tax implications.
It’s important to recognize that this strategic financial move can play a crucial role in achieving your long-term financial goals. By delving into the essential steps and considerations involved in this conversion, we aim to equip you with the knowledge needed to make informed decisions. Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Understand Simple IRA Roth Conversions
A Simple IRA, or Savings Incentive Match Plan for Employees, is a retirement plan designed specifically for small businesses and self-employed individuals. It allows contributions from both employees and employers, making it a valuable option for those looking to secure their financial future.
On the other hand, a specific IRA is a retirement account that enables individuals to contribute after-tax income, allowing for tax-free withdrawals during retirement—an appealing prospect for many families.
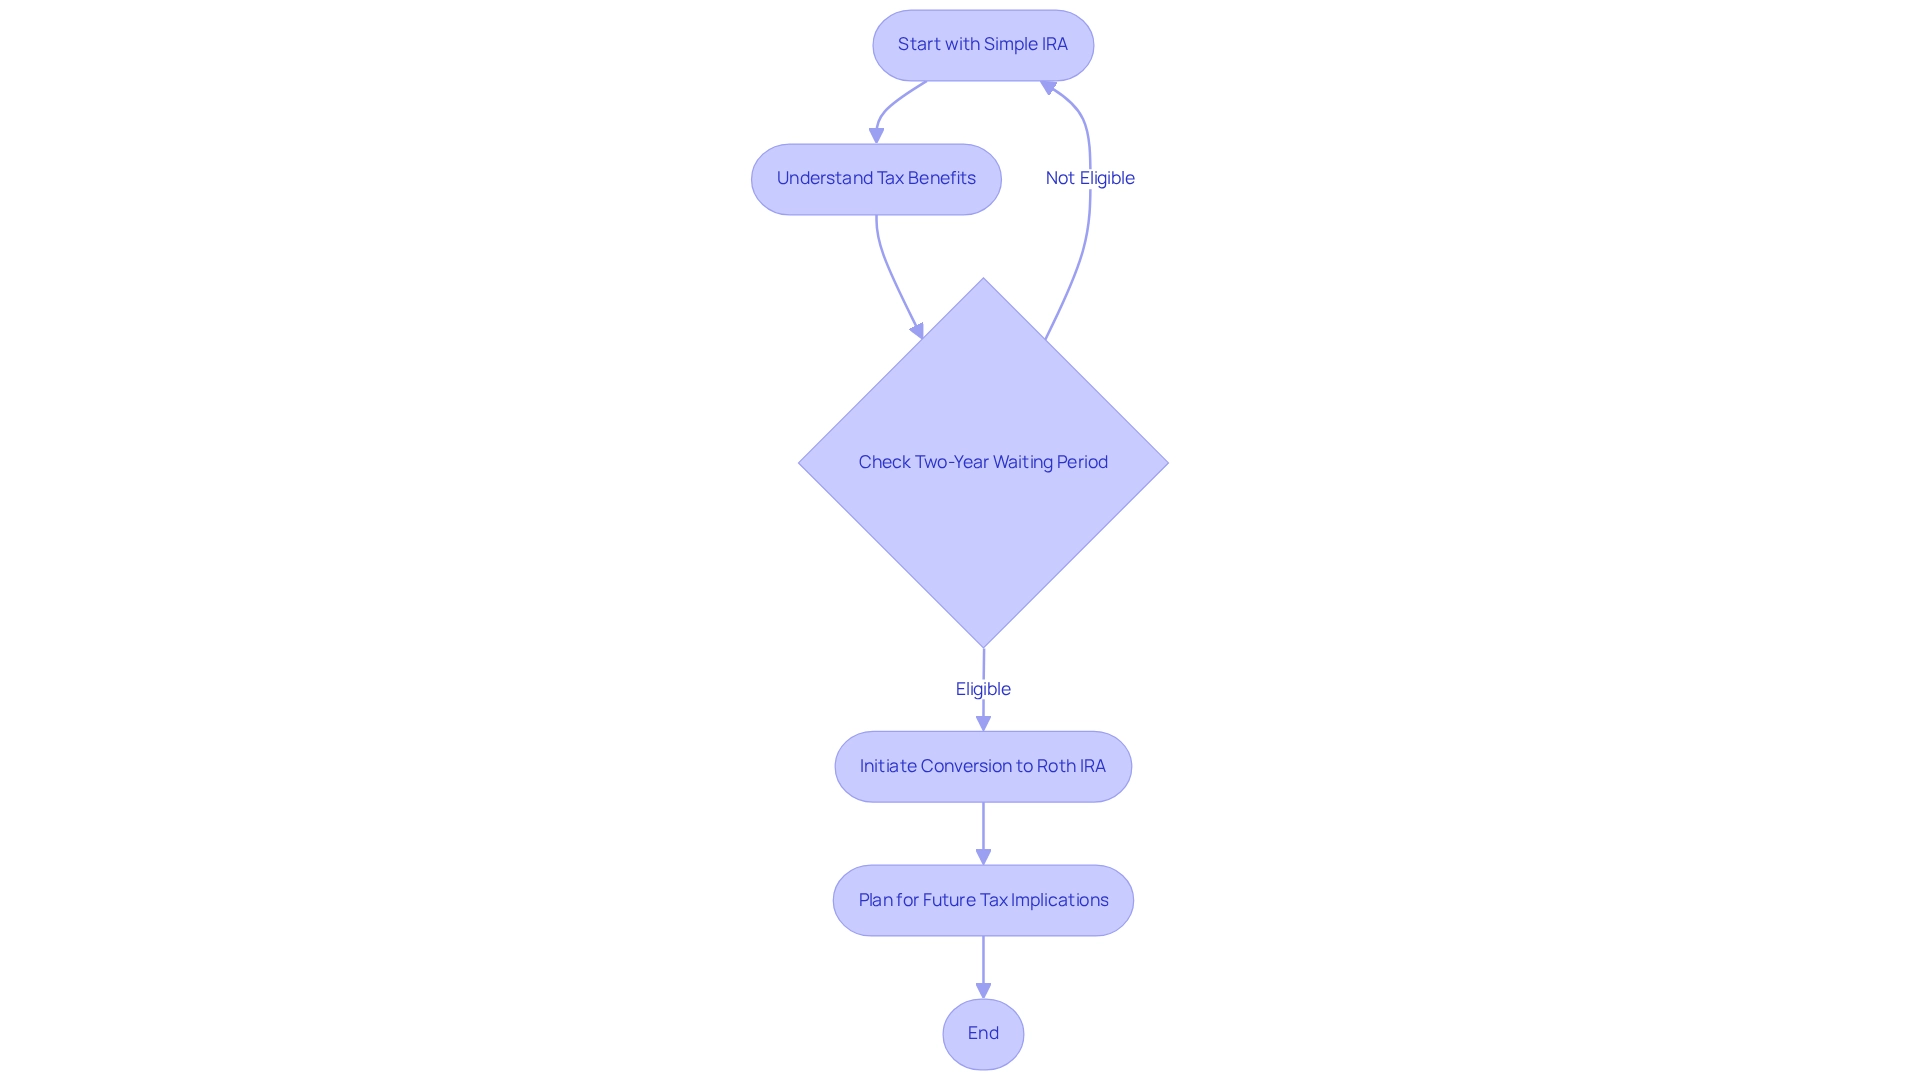
Imagine if you could make a simple IRA Roth conversion to change your individual retirement account. This process involves a simple IRA Roth conversion, which entails moving funds from the Simple IRA to the new account and can offer significant tax benefits, especially for those anticipating a higher tax category in the future. However, it’s important to understand that the IRS regulations require a two-year waiting period from the date you start participating in the Simple IRA before making such a change.
As we look ahead to 2025, more individuals are transitioning from Simple IRAs to traditional IRAs. This trend reflects a growing awareness of the advantages that come with these changes.
We’re here for you, ready to help you navigate these important decisions and ensure your family’s financial well-being. Together, we can explore the best options for your retirement planning, keeping your family’s future in mind.
Determine Eligibility for Conversion
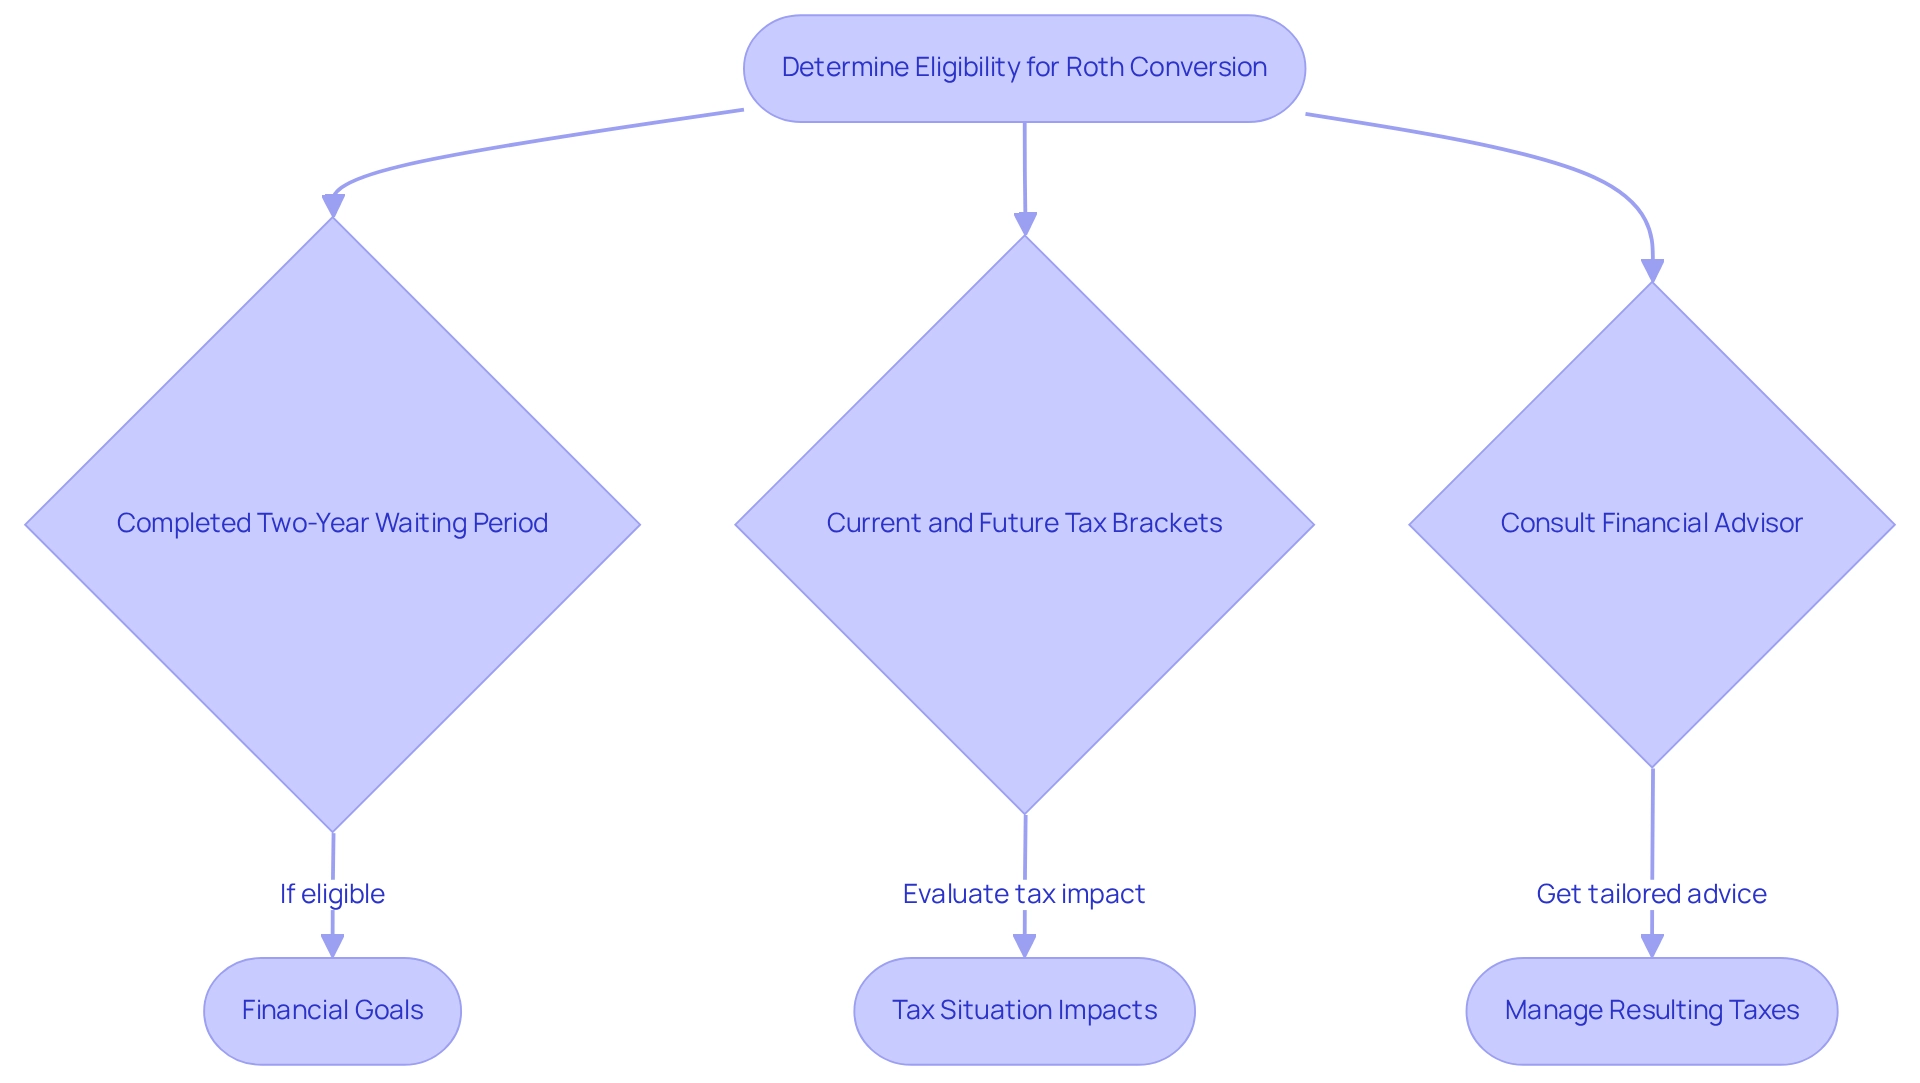
To be eligible for a simple IRA Roth conversion, you must have completed a two-year waiting period since your initial contribution to the Simple IRA. It’s important to reflect on both your current and anticipated future tax brackets, as the amount transferred will be taxed as ordinary income in the year of transfer. Imagine if understanding the financial behaviors of taxpayers with IRAs could provide valuable context for your decision. Key considerations for a simple IRA Roth conversion include:
- Your financial goals
- The potential impacts on your tax situation
- Your ability to manage the resulting taxes without impacting your retirement savings
Tim Steffen, CPA/PFS, CFP®, CPWA® Director of Advanced Planning, emphasizes, “All of this highlights the layers of considerations that should be taken before a Roth change.” Consulting with a financial advisor is highly recommended to help you navigate these complexities and tailor decisions to fit your unique financial circumstances. For instance, in the case of Allison and Brian, Bright Advisers assisted them in optimizing their tax situation, which not only secured their children’s future through education funding but also allowed them to retire sooner. This illustrates how professional guidance ensures individuals can make informed decisions tailored to their specific financial needs, maximizing the benefits of their retirement accounts.
Together, we can navigate this journey, ensuring that you make informed choices aligned with your long-term goals.
Follow the Step-by-Step Conversion Process
-
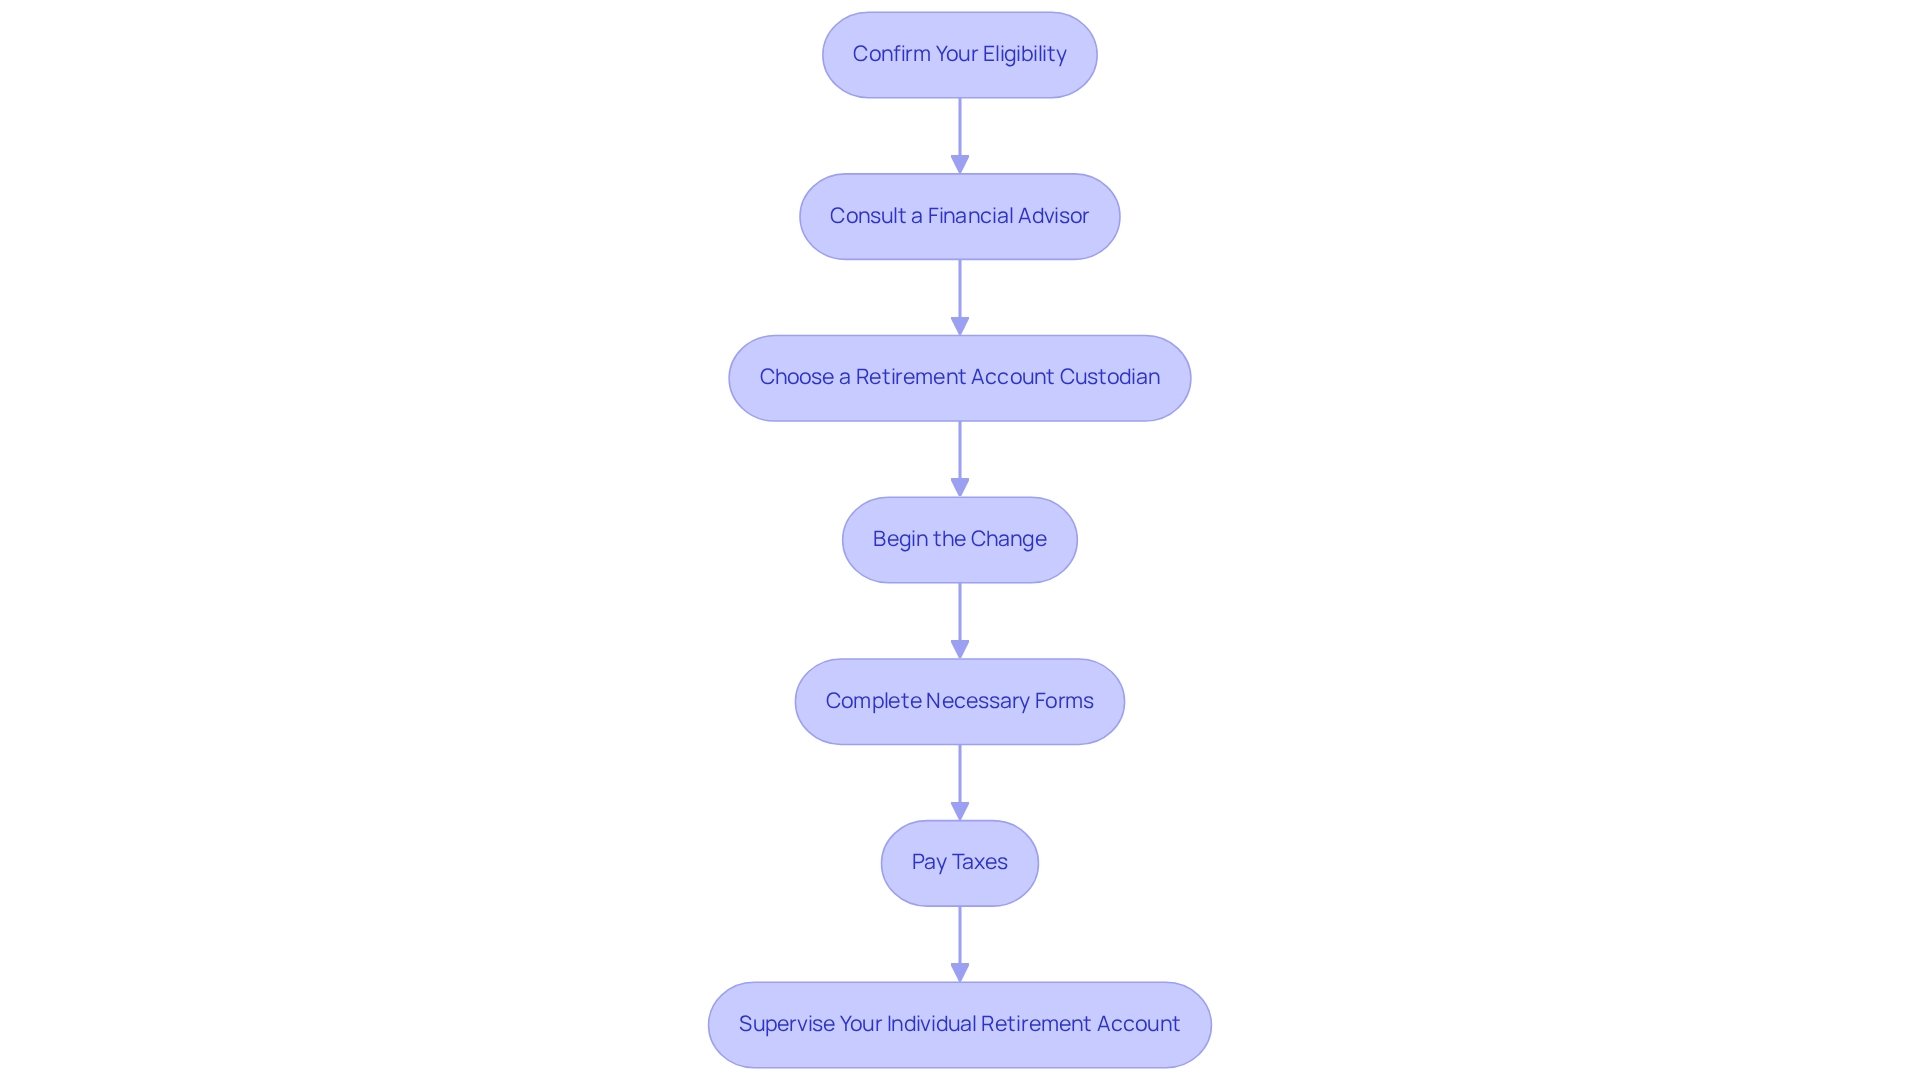
Confirm Your Eligibility: Before making any changes, take a moment to verify that you’ve completed the two-year waiting period since your first contribution to the Simple IRA. This is an important step in ensuring a smooth transition for you and your family.
-
Consult a Financial Advisor: It’s always a good idea to engage with a financial advisor who can help you assess your unique financial circumstances and objectives. This guidance ensures that any changes you consider align with your long-term family goals.
-
Choose a Retirement Account Custodian: If you don’t already have a retirement account, take the time to select a financial institution that feels right for you. Consider factors like fees and investment options that will best support your family’s future.
-
Begin the Change: When you’re ready, reach out to your Simple IRA custodian to start the change process. You can choose to execute a simple IRA Roth conversion by directly transferring funds to the Roth IRA or by taking a distribution and depositing it into the Roth IRA within 60 days. Imagine the peace of mind that comes with making informed decisions!
-
Complete Necessary Forms: Fill out all required documentation, including IRS Form 8606. This form reports the change and helps ensure compliance with tax regulations, keeping everything in line for your family’s financial future.
-
Pay Taxes: Be prepared to pay taxes on the converted amount, as it will be added to your taxable income for the year. Understanding the tax implications is crucial, especially with recent legislative changes that may affect your decision. As noted in a case study on the tax implications of simple IRA Roth conversions, it’s important to be aware of the tax liabilities associated with conversions and how employer matches in Roth 401(k)s can impact your family’s financial landscape.
-
Supervise Your Individual Retirement Account: After making the change, actively manage your individual retirement account investments to ensure they align with your financial goals and risk appetite. Regular monitoring can help you adapt to changing market conditions and personal circumstances. Remember, as expert Keihn emphasizes, you must complete the conversion by December 31 of the specific year you want it to count towards. Additionally, if you exceed income limits for direct contributions, consider exploring the Backdoor IRA strategy. Together, we can navigate this journey and secure a brighter future for your family.
Evaluate Tax Implications and Considerations
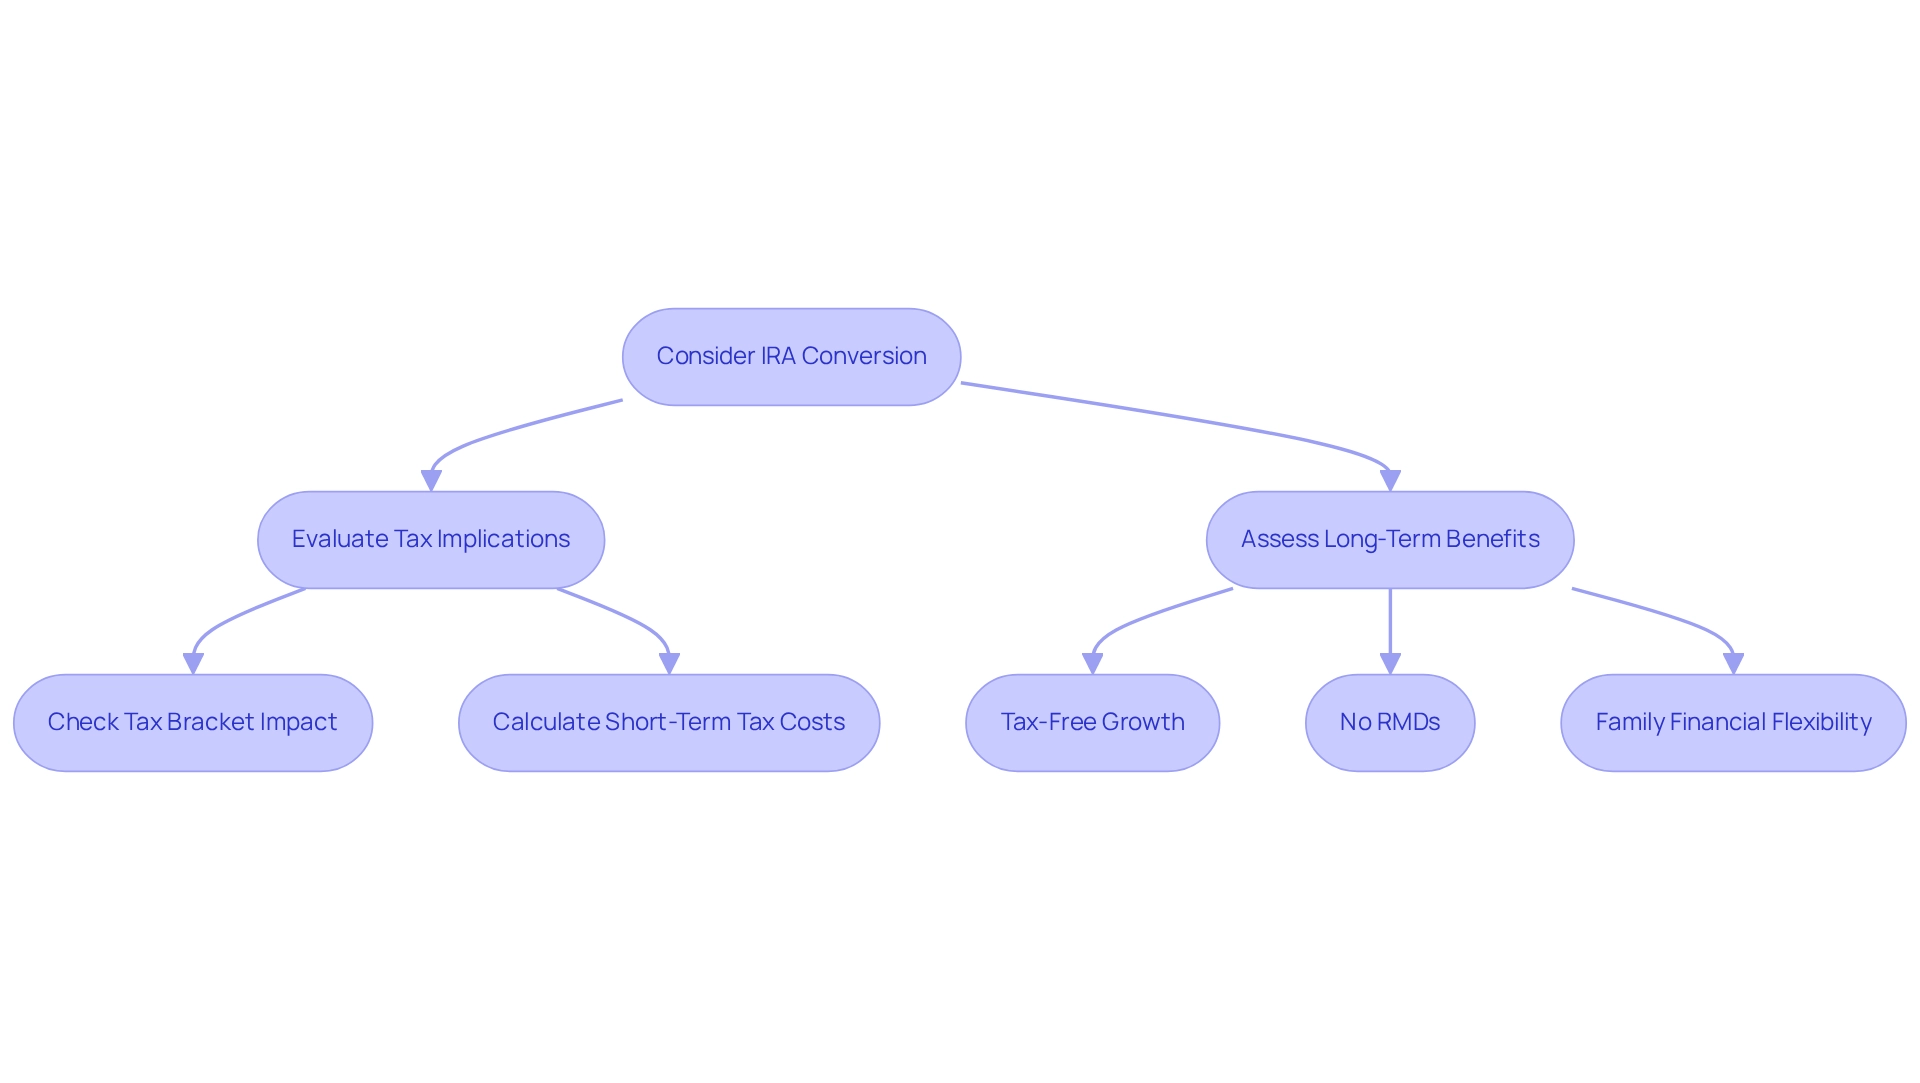
Transforming a Simple IRA through a Simple IRA Roth conversion to a different type of IRA comes with important tax implications that you should consider. When you convert, the amount added to your taxable income for the year could push you into a higher tax bracket. Yet, the benefits of having a retirement account are truly compelling. It offers tax-free growth and tax-free withdrawals in retirement, as long as you meet specific conditions.
Imagine having the freedom of not worrying about required minimum distributions (RMDs) during your lifetime with a Roth IRA. This feature provides enhanced flexibility in your retirement planning, allowing you to manage your finances with greater ease. Families can particularly benefit from this structure; tax-free withdrawals can help alleviate financial pressures during retirement, enabling better management of expenses without the added burden of taxes.
It’s important to evaluate various factors before making any changes. Balancing short-term tax expenses against long-term advantages is crucial. For instance, the increase in taxable income from a simple IRA Roth conversion can be significant, making it essential to strategize effectively.
Real-life examples show how families have successfully leveraged Roth IRAs to secure a more stable financial future. Take Emily and Mark, who partnered with Bright Advisers to develop a comprehensive financial plan. They included specific tax optimization strategies that empowered them to achieve financial freedom and make work optional.
Together, we can navigate this journey. This reinforces the value of this investment strategy, especially for young families seeking to enhance their financial security and freedom.
Conclusion
Understanding how to convert a Simple IRA to a Roth IRA is a significant step in enhancing your retirement planning strategies. This conversion opens the door to potential tax-free growth and withdrawals, offering you the flexibility to manage your retirement funds without the pressure of required minimum distributions. It’s crucial to recognize eligibility requirements, such as the two-year waiting period, as this knowledge lays the foundation for a successful conversion.
Evaluating the tax implications of this conversion is essential for making informed decisions. The converted amount is treated as ordinary income, which might push you into a higher tax bracket. However, the long-term benefits of a Roth IRA, especially for families, can outweigh the immediate tax costs. Imagine being able to enjoy tax-free withdrawals in retirement! Through real-life examples, we see how strategic planning and professional guidance can help navigate these complexities, aligning your financial objectives with your family’s retirement goals.
Ultimately, deciding to convert a Simple IRA to a Roth IRA should be approached thoughtfully, considering both your current financial situation and future aspirations. By leveraging the benefits of this conversion, you can take proactive steps toward achieving a more secure and flexible retirement. Remember, we’re here for you—together, we can navigate this journey toward a brighter financial future.
Frequently Asked Questions
What is a Simple IRA?
A Simple IRA (Savings Incentive Match Plan for Employees) is a retirement plan specifically designed for small businesses and self-employed individuals, allowing both employees and employers to contribute.
What is a Roth IRA?
A Roth IRA is a type of retirement account that enables individuals to contribute after-tax income, leading to tax-free withdrawals in retirement.
What does a Simple IRA to Roth IRA conversion involve?
A Simple IRA to Roth IRA conversion involves moving funds from a Simple IRA to a Roth IRA, which can offer significant tax benefits, particularly for individuals who expect to be in a higher tax bracket in the future.
Is there a waiting period for converting from a Simple IRA?
Yes, there is a two-year waiting period from the date of participation in the Simple IRA before any changes, such as a conversion, can occur, as outlined by IRS regulations.
What is the current IRA contribution limit?
The IRA contribution limit remains at $7,000.
How have IRA contributions changed recently?
In the third quarter of 2024, the average IRA contribution increased from $1,300 to $1,500, according to Fidelity.
How much was held in IRAs as of mid-2022?
As of mid-2022, $11.7 trillion was held in IRAs, representing a significant portion of U.S. retirement assets.
Why is it important to understand IRA changes?
Understanding IRA changes is crucial for effective long-term financial planning, as it helps individuals navigate their retirement savings strategies.
List of Sources
- Understand Simple IRA Roth Conversions
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- How Do I Roll Over a SIMPLE IRA to a Roth IRA? (https://investopedia.com/ask/answers/102714/how-do-i-roll-over-simple-ira-roth-ira.asp)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Recent IRA Statistics – Greenleaf Trust (https://greenleaftrust.com/missives/recent-ira-statistics)
- Is a Roth IRA conversion right for you? | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/ira-roth-conversion)
- Should I Do a Roth Conversion? (https://carsonallaria.com/2022/07/26/roth-conversions-good-idea)
- Determine Eligibility for Conversion
- Thinking of Converting to a Roth IRA? Consider a Partial Conversion (https://merrilledge.com/article/thinking-of-converting-to-roth-ira)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- The Three Tests of a Roth Conversion (https://bairdwealth.com/insights/wealth-management-perspectives/2023/09/the-three-tests-before-a-roth-conversion)
- None (https://bernardwealthmanagement.com/roth-conversions.htm)
- Is a Roth IRA conversion right for you? | Vanguard (https://investor.vanguard.com/investor-resources-education/iras/ira-roth-conversion)
- How Do I Roll Over a SIMPLE IRA to a Roth IRA? (https://investopedia.com/ask/answers/102714/how-do-i-roll-over-simple-ira-roth-ira.asp)
- Follow the Step-by-Step Conversion Process
- Roth IRA Conversion: Everything You Need To Know | Bankrate (https://bankrate.com/retirement/convert-to-roth-ira)
- The SIMPLE IRA Isn’t So Simple After All | Lord Abbett (https://lordabbett.com/en-us/financial-advisor/insights/retirement-planning/the-simple-ira-isn-t-so-simple-after-all.html)
- Roth Conversions: Everything You Need To Know – Capitalize (https://hicapitalize.com/resources/roth-ira-conversions)
- Roth IRA Conversion Rules (https://investopedia.com/roth-ira-conversion-rules-4770480)
- The Complete Guide to Roth Conversions | Asset Preservation (https://apsitaxes.com/blog/roth-conversions-thought-leadership)
- Evaluate Tax Implications and Considerations
- New Report Shows Strong IRA Growth — Ascensus (https://thelink.ascensus.com/articles/2021/2/17/new-report-shows-strong-ira-growth)
- Rollover IRA | Roll Over Your 401(k) and IRAs | E*TRADE (https://us.etrade.com/what-we-offer/our-accounts/rollover-ira)
- Before a Roth conversion, check this tax rate — it’s the ‘single biggest factor’ to consider, CFP says (https://cnbc.com/2025/04/30/roth-conversions-stock-market-downturn.html)
- Will a Roth Conversion Impact My Taxes on My $2,800 Monthly Social Security Benefit? (https://smartasset.com/retirement/roth-conversion-impact-2800-social-security-benefit)
- What Taxes Are Due On A Roth IRA Conversion? | Bankrate (https://bankrate.com/retirement/taxes-roth-ira-conversion)
- Roth IRA Conversion: Everything You Need To Know | Bankrate (https://bankrate.com/retirement/convert-to-roth-ira)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading