

Overview
This article presents a caring, four-step approach to transferring an IRA to another bank, designed with your family’s needs in mind. It highlights the significance of:
- Selecting a new institution
- Completing the necessary paperwork
- Keeping an eye on the transfer process
Imagine if you could navigate this transition smoothly, avoiding common pitfalls like delays or incomplete forms. By understanding these potential challenges and adopting proactive strategies, you can ensure a seamless transfer of your retirement funds without tax implications. We’re here for you, guiding you every step of the way to secure your family’s financial future.
Key Highlights:
- An Individual Retirement Account (IRA) is a tax-advantaged investment option for retirement savings.
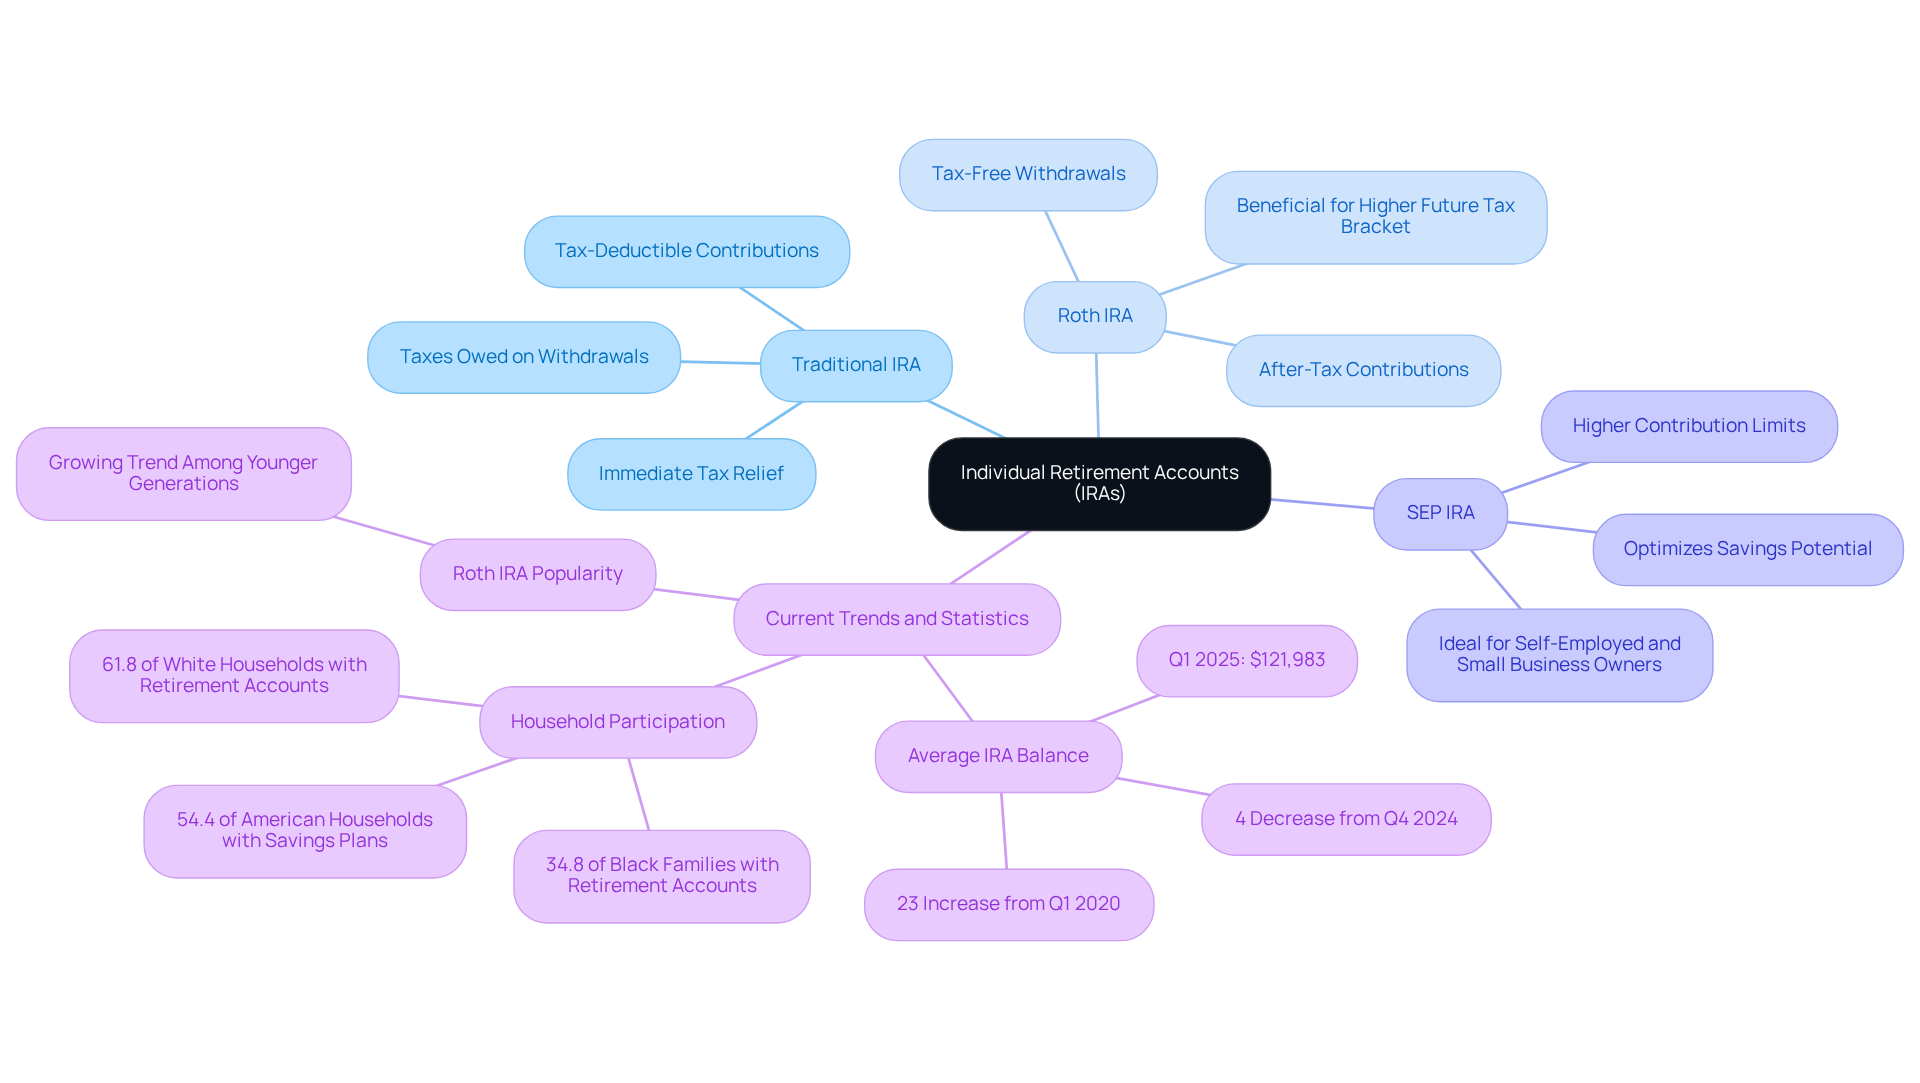
- Types of IRAs include Traditional IRA (tax-deductible contributions), Roth IRA (after-tax contributions with tax-free withdrawals), and SEP IRA (higher contribution limits for self-employed individuals).
- As of 2025, 54.4% of American households have retirement savings plans, with a trend towards Roth IRAs among younger generations.
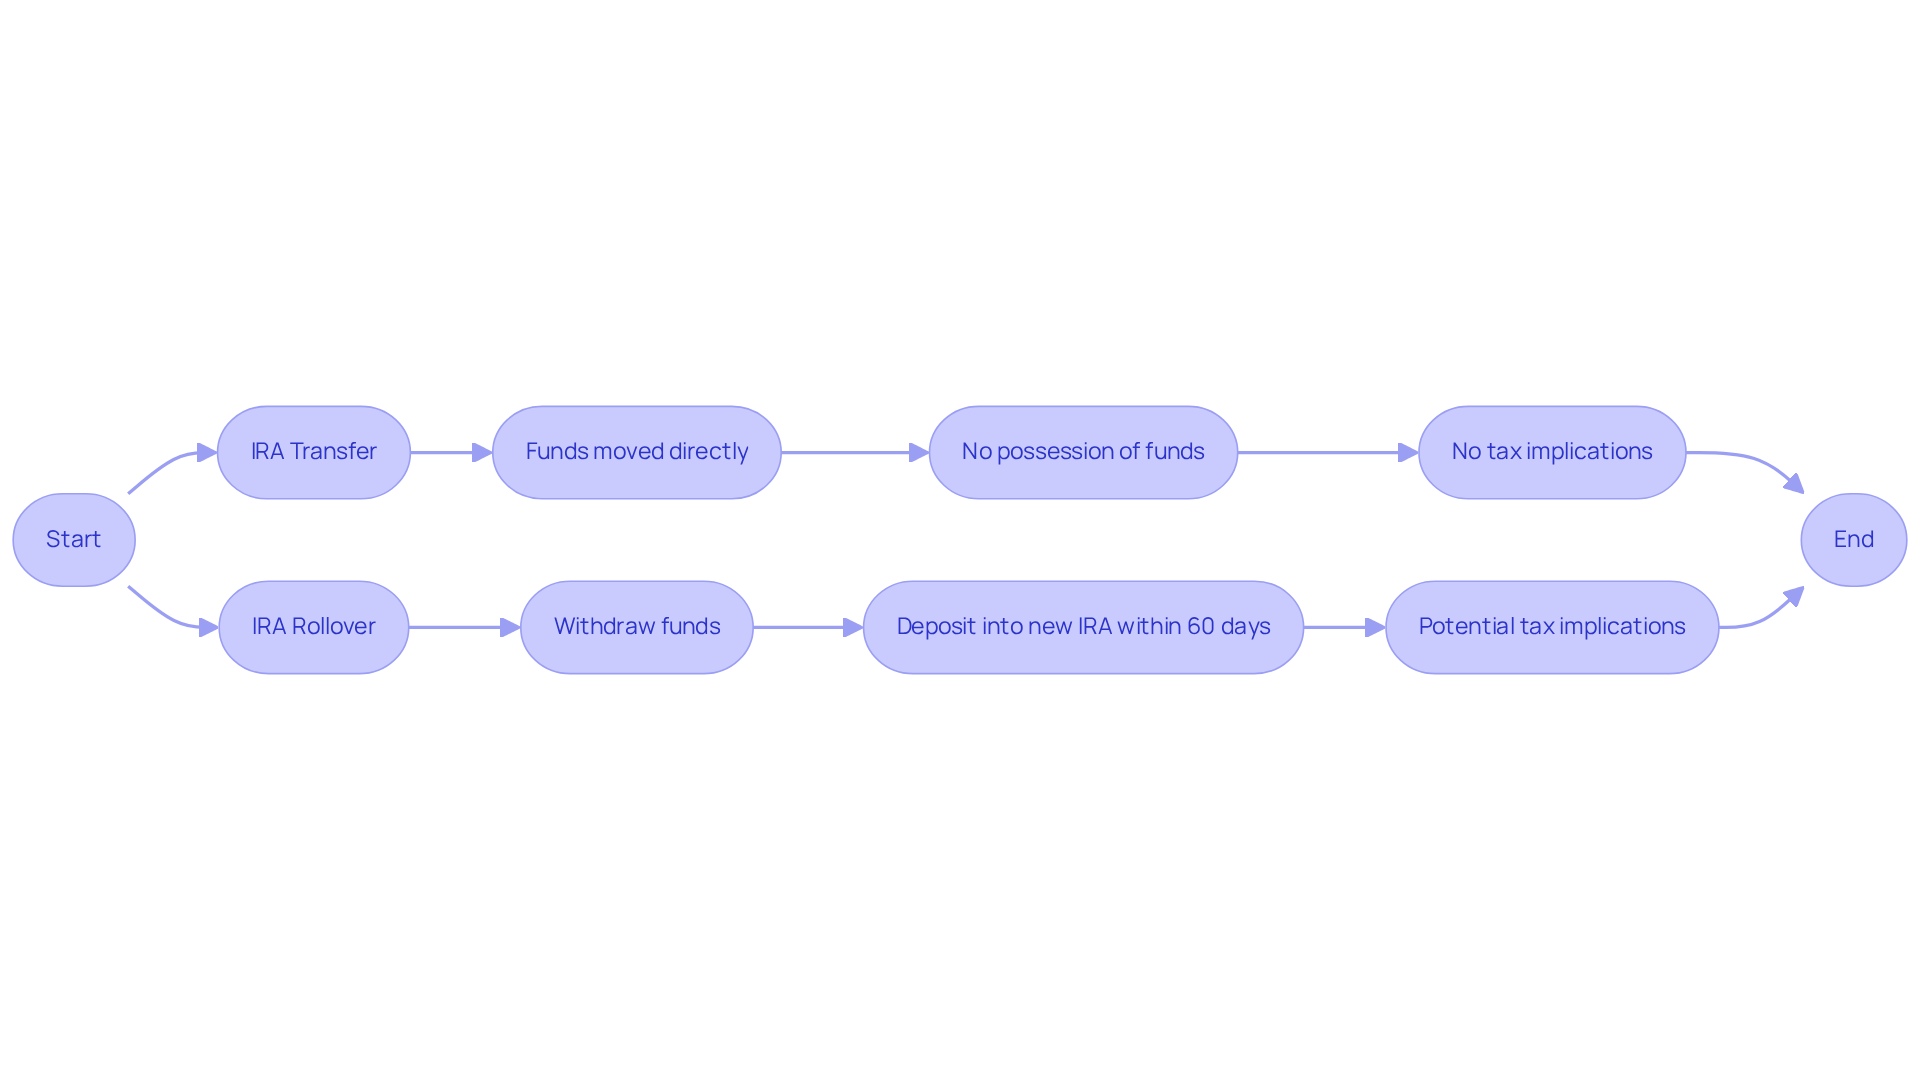
- IRA transfers move funds directly between accounts without tax implications, while rollovers involve withdrawing funds and redepositing them within 60 days, risking taxes if not done correctly.
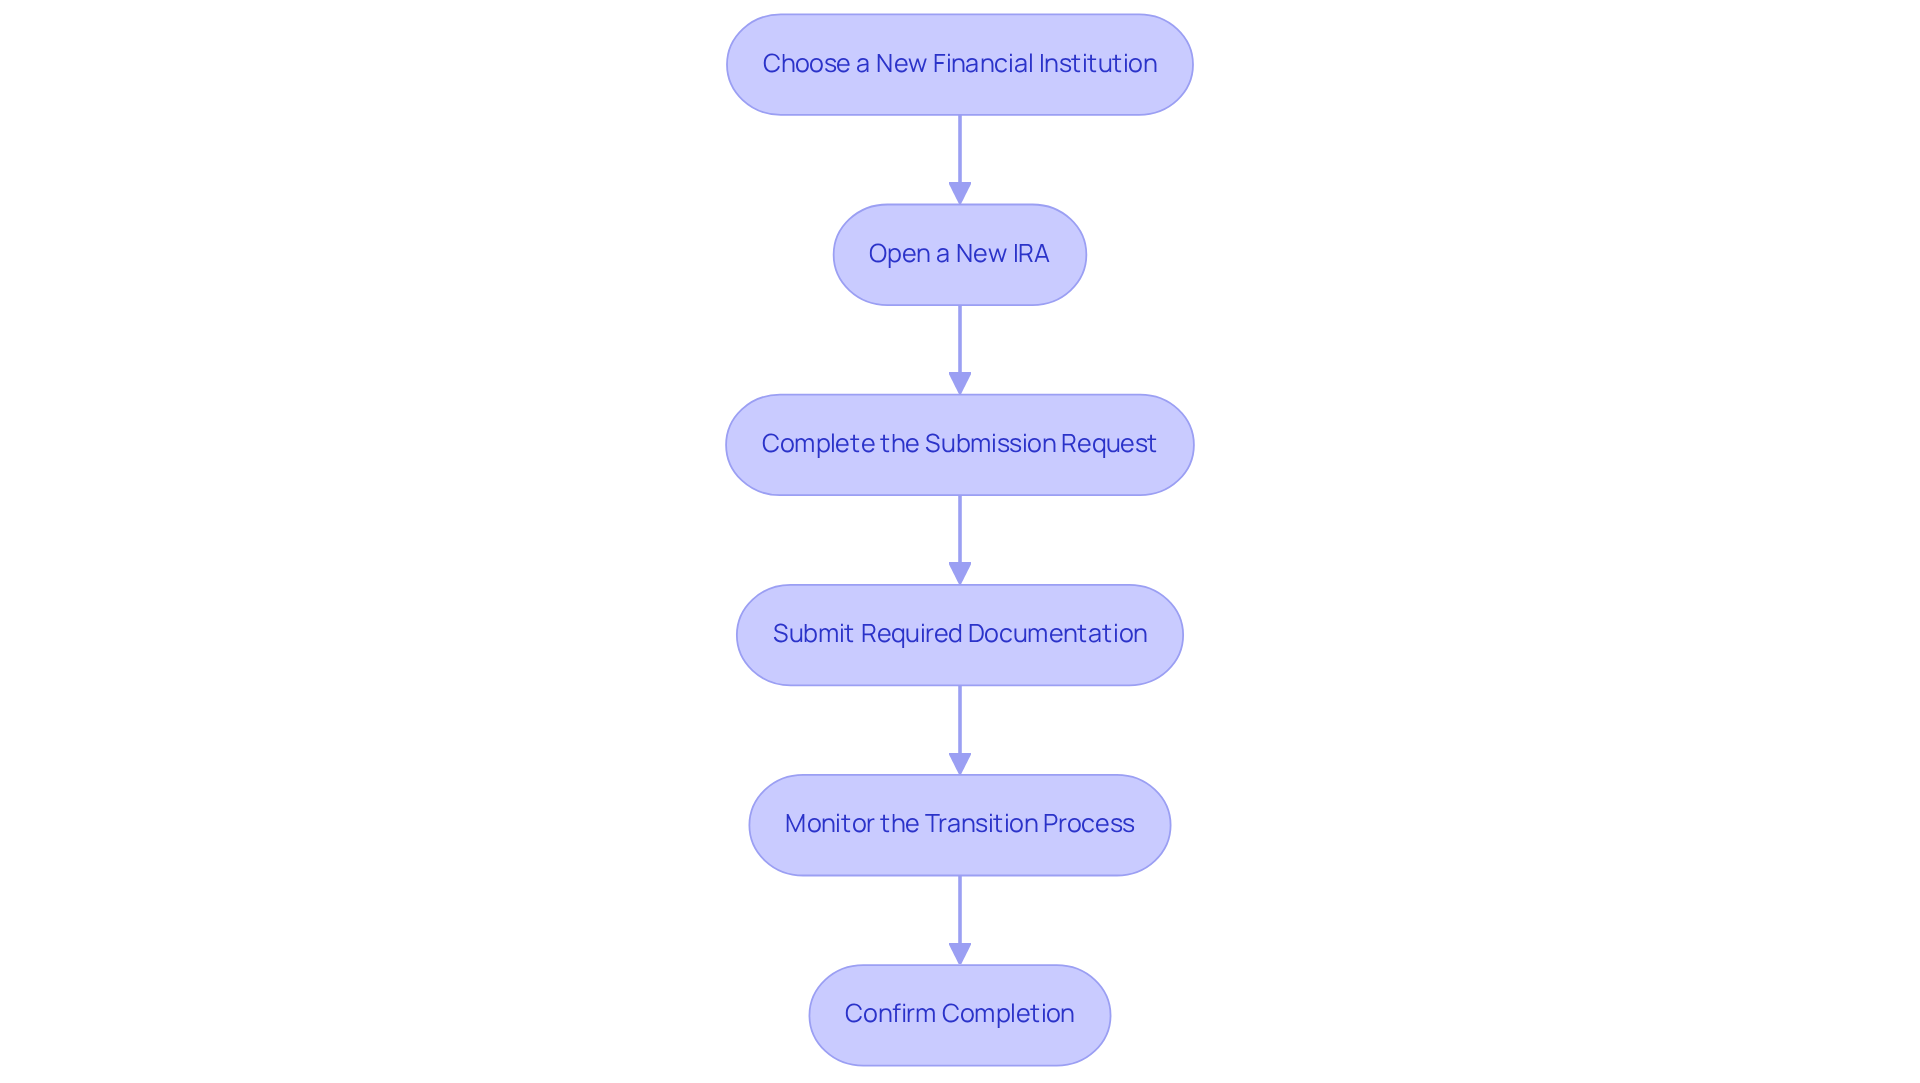
- Steps to transfer an IRA include choosing a new institution, opening a new IRA, submitting requests and documentation, monitoring the transfer, and confirming completion.
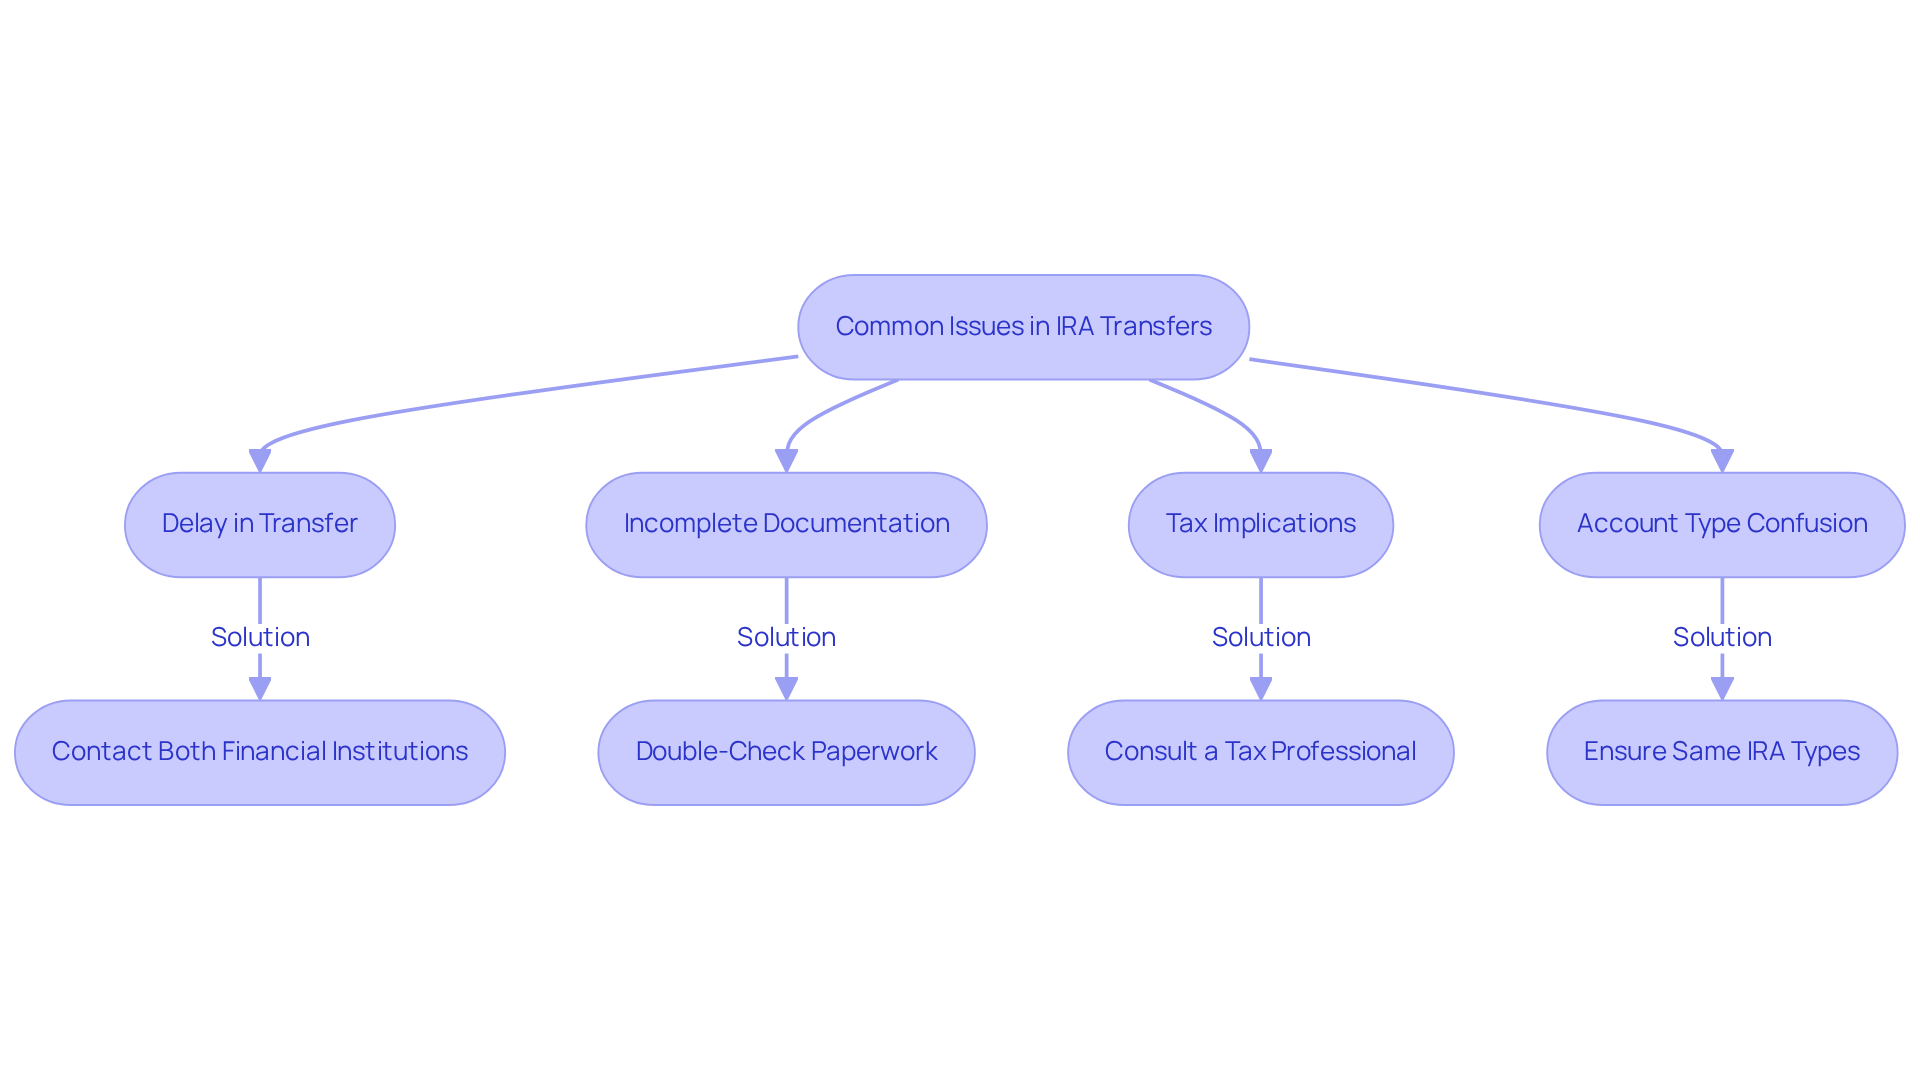
- Common issues in IRA transfers include delays, incomplete documentation, tax implications, and confusion over account types, which can be mitigated by proactive communication and careful management.
Introduction
Transferring an Individual Retirement Account (IRA) to a new bank might feel overwhelming, but it also offers a crucial chance for you to enhance your family’s financial future. By grasping the differences between various IRA types and the specific processes involved in transfers versus rollovers, you can make informed choices that align with your long-term family goals.
Imagine if unexpected delays or documentation issues arise during this process—what would that mean for you? This guide is here to illuminate the essential steps for a successful IRA transfer while addressing common challenges. Together, we can navigate this important financial transition with confidence, ensuring your family’s needs are met every step of the way.
Understand the Basics of an IRA
An Individual Retirement Account (IRA) is a wonderful tax-advantaged investment option that can help you secure a brighter future for your family. Understanding the different types of IRAs available is essential, as each offers unique benefits tailored to your needs. Let’s explore them together:
- Traditional IRA: Imagine being able to make contributions that may be tax-deductible, with taxes owed only when you withdraw funds during retirement. This option is particularly appealing for those seeking immediate tax relief, helping you invest in your family’s future today.
- Roth IRA: Picture making contributions with after-tax dollars, allowing for tax-free withdrawals when you decide to stop working. This could be especially beneficial if you anticipate being in a higher tax bracket later, ensuring that your hard-earned savings work for you and your loved ones.
- SEP IRA: If you’re self-employed or a small business owner, this plan allows for significantly higher contribution limits. It’s a fantastic choice for those looking to optimize their savings and provide a secure foundation for their family’s financial future.
It’s important to understand the specific type of IRA you hold, as this knowledge directly impacts your approach to transferring IRA to another bank and the associated tax implications. As of 2025, around 54.4% of American households have savings plans, with a notable 61.8% of white households participating. A growing trend towards Roth IRAs reflects a shift in savings strategies among younger generations, highlighting the importance of adapting to new financial landscapes.
Furthermore, the typical IRA balance was reported at $121,983 in Q1 2025, indicating a 4% decrease from Q4 2024. This underscores the need for active management of your savings accounts. By being informed and proactive, you can make empowered decisions about your family’s financial planning.
As Sarah Holden, ICI Senior Director of Retirement and Investor Research, beautifully states, “IRAs, often in conjunction with savings plans at work, are assisting millions of individuals of all ages in securing their financial future.” Remember, we’re here for you on this journey, and together, we can navigate the path to a secure and prosperous future for your family.
Differentiate Between IRA Transfers and Rollovers
When transferring an IRA to another bank, it’s essential to distinguish between an IRA transfer and a rollover.
IRA Transfer: This process involves moving funds directly from one IRA to another without the account holder taking possession of the funds. It is generally more straightforward and does not incur tax implications, making it a tax-efficient choice for managing assets for the future. This approach corresponds with the customized wealth management solutions provided by Bright Advisers, which include transferring IRA to another bank, enabling families to manage their financial challenges efficiently through services like tax planning and strategy development for future financial needs.
IRA Rollover: This occurs when the account holder withdraws funds from one IRA and deposits them into another within 60 days. If not executed correctly, rollovers can lead to taxes and a potential 10% early withdrawal penalty for those under 59.5 years old. Imagine withdrawing $50,000 from a 401(k) intending to roll it over; you may receive only $40,000 after a 20% withholding for taxes. This highlights the critical importance of redepositing the funds into the new IRA within the 60-day timeframe to avoid tax penalties.
Grasping these distinctions is essential. The decision between a shift and a rollover can greatly influence your financial circumstances and future objectives. For families like Jay and Emma, who are looking to create a comprehensive financial strategy that addresses both immediate and long-term goals, selecting the right method can streamline financial management and enhance long-term savings while avoiding potential tax liabilities. By partnering with Bright Advisers, families can develop personalized strategies that align with their aspirations for financial security and freedom. Together, we can navigate this journey with confidence.
Follow the Step-by-Step Process to Transfer Your IRA
To smoothly transfer your IRA, let’s walk through these important steps together:
-
Choose a New Financial Institution: Start by researching banks or brokerages that offer the IRA type you want. Look for factors like fees, investment options, and customer service. At Bright Advisers, we prioritize minimal fund fees, making wealth management more accessible for families. Remember, recent data shows that 54.4% of families have retirement savings, so making informed choices is crucial.
-
Open a New IRA: If you don’t have an account at your new institution yet, take the time to complete the application process. Ensure that your new profile aligns with your financial goals and investment strategy. As financial expert Robin Hartill reminds us, “In 2025, you can contribute up to $7,000 to a traditional IRA, a Roth IRA, or a combination of the two.”
-
Complete the Submission Request: Next, fill out the submission request form from your new institution. This form usually asks for details about your current IRA, including account numbers and the amount you wish to transfer for transferring IRA to another bank.
-
Submit Required Documentation: Don’t forget to provide any necessary documentation, like your current IRA statement, to help facilitate the process. This step is vital for ensuring everything goes smoothly.
-
Monitor the Transition Process: Keep an eye on the status of your transfer by regularly checking in with both your previous and new institutions. It’s important to ensure that the funds move directly into your new IRA when transferring IRA to another bank to avoid any tax implications. Financial advisors often suggest staying in touch with both institutions for a seamless transition.
-
Confirm Completion: Once the transfer is complete, verify that the funds have been accurately deposited into your new financial institution. Take a moment to review your new account details to ensure everything is in order.
By following these steps, you can navigate the process of transferring IRA to another bank with confidence, ensuring your retirement savings are effectively managed. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s financial future.
Troubleshoot Common Issues in IRA Transfers
Transferring your IRA to another bank can feel overwhelming, but you’re not alone in facing these challenges. Let’s explore some common issues together and find effective solutions that work for you and your family.
- Delay in Transfer: If your transfer takes longer than expected, it’s important to reach out to both your old and new financial institutions. They can provide updates on the status of your transfer. Typically, IRA movements can take from a few days to several weeks, depending on the institutions involved. As we approach 2025, you may notice that average transfer delays are increasing due to various factors, including market volatility, which can add to your concerns.
- Incomplete Documentation: Make sure all necessary forms and documents are filled out accurately and submitted on time. Missing information is a common cause of delays, so double-check your paperwork before sending it off. One common mistake in rollovers is unintentionally rolling over all funds to a traditional IRA, which does not apply to IRA distributions. It’s an easy oversight, but one that can lead to complications.
- Tax Implications: Be mindful of inadvertently triggering a taxable event during your transfer. If this happens, consulting a tax professional can help you explore your options and understand any potential penalties. Remember, “The IRS doesn’t offer do-overs for rollover mistakes,” as financial expert Ed Slott wisely reminds us. It’s crucial to stay informed and prepared.
- Account Type Confusion: Ensure that you are transferring between the same types of IRAs (for example, Traditional to Traditional or Roth to Roth). Mixing different types can lead to issues and setbacks, adding stress to an already complex process.
By staying proactive and informed, you can navigate these challenges with confidence, ensuring a smoother process for transferring IRA to another bank. As of Q1 2025, the average IRA balance was $121,983, underscoring the importance of managing these accounts effectively for your family’s future. Together, we can navigate this journey with care and support.
Conclusion
Transferring an Individual Retirement Account (IRA) to a new bank is not merely a task; it represents a vital step towards enhancing your family’s financial security for the future. By understanding the various types of IRAs and the distinct processes of transfers and rollovers, you can make informed decisions that align with your long-term financial objectives. This journey, while it may seem complex, offers a wonderful opportunity to optimize your retirement savings and ensure they are managed effectively.
Throughout this guide, we’ve outlined essential steps for a successful IRA transfer, from selecting the right financial institution to troubleshooting common issues that may arise during the process. We’ve also emphasized the key distinctions between IRA transfers and rollovers, highlighting the importance of avoiding tax implications and ensuring a smooth transition of funds. By following these steps and being proactive about potential challenges, you can navigate this process with confidence and clarity.
Ultimately, the significance of managing IRAs effectively cannot be overstated. As families like yours strive to secure their financial futures, taking the time to understand and execute a successful IRA transfer can lead to greater financial stability and peace of mind. Embracing this process is not just about moving funds; it’s about investing in a brighter future and ensuring that your financial goals are met. Remember, taking action today can pave the way for a more secure tomorrow. Together, we can navigate this journey, and we’re here for you every step of the way.
Frequently Asked Questions
What is an Individual Retirement Account (IRA)?
An IRA is a tax-advantaged investment option designed to help individuals save for retirement and secure a brighter financial future for their families.
What are the different types of IRAs available?
The main types of IRAs include Traditional IRA, Roth IRA, and SEP IRA. Each type offers unique benefits tailored to individual needs.
How does a Traditional IRA work?
A Traditional IRA allows you to make contributions that may be tax-deductible, with taxes owed only when you withdraw funds during retirement. This option provides immediate tax relief.
What are the benefits of a Roth IRA?
A Roth IRA involves making contributions with after-tax dollars, allowing for tax-free withdrawals during retirement. This is beneficial for individuals who anticipate being in a higher tax bracket later.
Who should consider a SEP IRA?
A SEP IRA is ideal for self-employed individuals or small business owners, as it allows for significantly higher contribution limits, helping to optimize savings for a secure financial future.
Why is it important to understand the specific type of IRA you hold?
Knowing the specific type of IRA you have is crucial because it affects your approach to transferring the IRA to another bank and the associated tax implications.
What does the trend in IRA participation among American households indicate?
As of 2025, about 54.4% of American households have savings plans, with a notable 61.8% of white households participating, indicating a growing trend towards saving for retirement.
What was the typical IRA balance reported in Q1 2025?
The typical IRA balance was reported at $121,983 in Q1 2025, reflecting a 4% decrease from Q4 2024, emphasizing the need for active management of savings accounts.
How do IRAs contribute to financial security?
IRAs, often in conjunction with workplace savings plans, assist millions of individuals in securing their financial future, as stated by Sarah Holden, ICI Senior Director of Retirement and Investor Research.
List of Sources
- Understand the Basics of an IRA
- Are you saving enough? The average IRA balance in 2025 might surprise you (https://usatoday.com/story/money/personalfinance/retirement/2025/06/13/average-ira-balance-2025/84145518007)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- IRAs Play an Increasingly Important Role in Saving for Retirement (https://ici.org/news-release/25-news-ira)
- IRA Rollovers and Contributions: Key Retirement Trends | PLANADVISER (https://planadviser.com/traditional-iras-destination-rollover-dollars-roth-iras-conversions-contributions)
- IRA Ownership, Balances Growing Steadily: CRS (https://asppa-net.org/news/2025/3/ira-ownership-balances-growing-steadily-crs)
- Differentiate Between IRA Transfers and Rollovers
- Differences Between IRA Transfer vs. Rollover (https://smartasset.com/retirement/ira-transfer-vs-rollover)
- How IRA rollovers and IRA transfers differ (https://firstcitizens.com/wealth/insights/retirement/ira-rollovers-versus-ira-transfers)
- U.S. Retirement Assets: Data in Brief (https://congress.gov/crs-product/R47699)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- IRA rollover vs. IRA transfer: Breaking down the differences (https://thrivent.com/insights/retirement-planning/ira-rollover-vs-ira-transfer-breaking-down-the-differences)
- Follow the Step-by-Step Process to Transfer Your IRA
- Release: Quarterly Retirement Market Data, Fourth Quarter 2024 (https://ici.org/statistical-report/ret_24_q4)
- These are the traditional IRA and Roth IRA limits in 2025 (https://finance.yahoo.com/personal-finance/investing/article/ira-contribution-limits-205505142.html)
- IRA Ownership Reaches Record Highs (https://ici.org/25-view-ira-ownership-reaches-record-highs)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- T. Rowe Price Personal Investor – 2025 Key Financial Numbers That You Need to Know (https://troweprice.com/personal-investing/resources/insights/key-financial-numbers.html)
- Troubleshoot Common Issues in IRA Transfers
- Are you saving enough? The average IRA balance in 2025 might surprise you (https://usatoday.com/story/money/personalfinance/retirement/2025/06/13/average-ira-balance-2025/84145518007)
- Common IRA Rollover Mistakes (https://investopedia.com/articles/retirement/06/rollovermistakes.asp)
- 10 IRA Rollover Mistakes to Avoid (https://jlsmithgroup.com/blog/10-ira-rollover-mistakes-to-avoid)
- Don’t Make These Fatal Errors With IRA Rollovers (https://morningstar.com/retirement/dont-make-these-fatal-errors-with-ira-rollovers)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading