

Key Highlights
- Incentive Stock Options (ISOs) allow employees to purchase company shares at a predetermined price, potentially benefiting their family’s financial future.
- ISOs offer favourable tax treatment, allowing capital gains tax instead of regular income tax if certain conditions are met.
- Eligibility for ISOs is limited to employees, and they must be part of a shareholder-approved plan.
- ISOs typically have a vesting period and expire 10 years from the grant date, requiring careful monitoring.
- Exercising ISOs can trigger Alternative Minimum Tax (AMT) if there is a significant difference between the purchase price and fair market value.
- To qualify for long-term capital gains tax treatment, shares must be held for at least one year after exercising and two years from the grant date.
- Timing strategies for exercising ISOs include early-year exercises, market condition assessments, income planning, and diversification of investments.
- Steps to exercise ISOs effectively include reviewing the grant agreement, calculating costs, deciding on a strategy, completing the share notice, submitting payment, keeping records, and monitoring holdings.
- Engaging with Bright Advisers can help families navigate the complexities of ISOs and optimise their financial outcomes.
Introduction
Imagine feeling confident about your financial future while navigating the complexities of Incentive Stock Options (ISOs). For many parents, understanding the essentials of ISOs can create a brighter financial future for their families. But with so many factors to consider, how can you make the best choices for your family’s future? Together, we’ll explore four essential steps that can help you master the timing of your ISOs, leading to smarter financial choices for your family.
Understand Incentive Stock Options (ISOs)
Imagine having the opportunity to secure your family’s financial future through smart investment choices like Incentive Stock Options, which allow you to buy company shares at a price that could be lower than what others pay. Let’s explore some key points that can help you understand these options better:
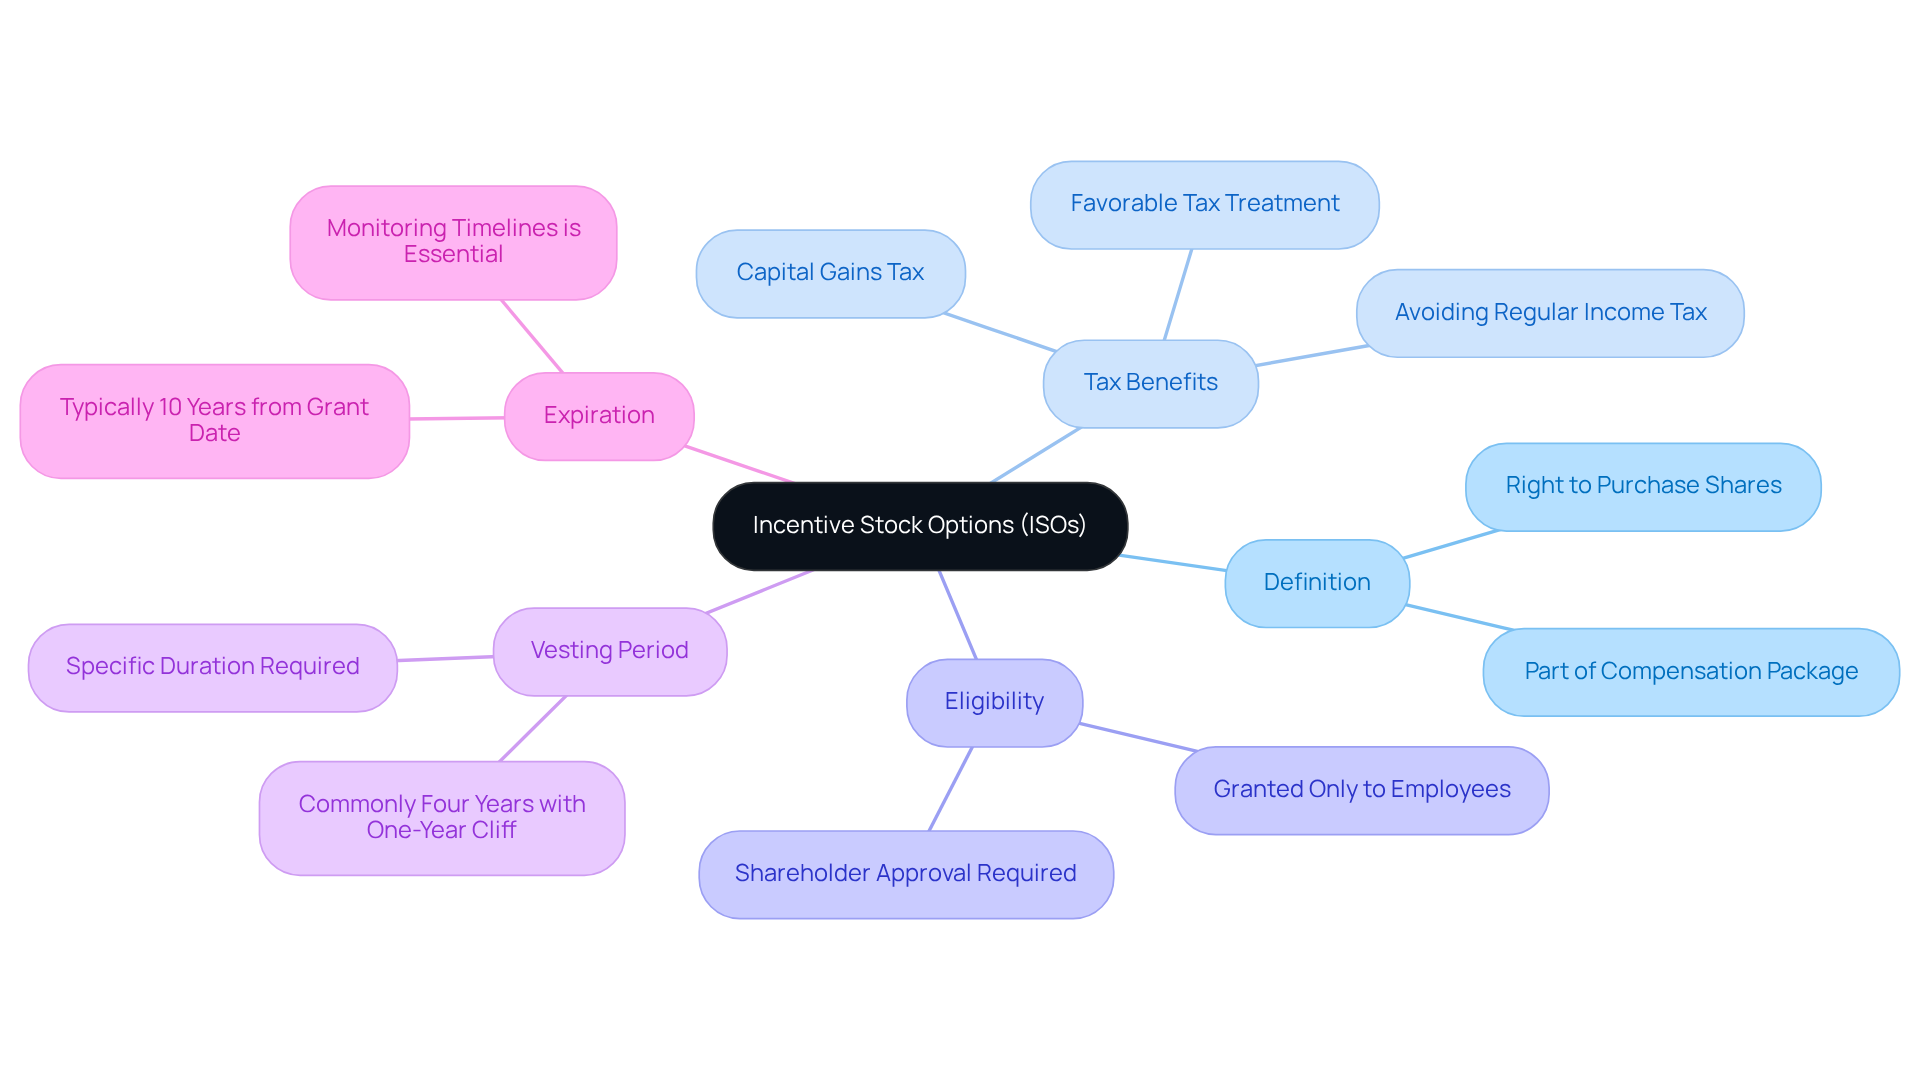
- Definition: Incentive Stock Options are part of your compensation package, giving you the right to purchase shares at a predetermined price, known as the purchase price. This can be a valuable asset for your family’s future.
- Tax Benefits: Think about the tax benefits: Incentive Stock Options can be a smart choice because they offer favorable tax treatment compared to non-qualified stock options (NSOs). If you meet certain conditions, you might avoid paying regular income tax when you realize the options, only incurring capital gains tax when you sell the shares.
- Eligibility: It’s important to know that Incentive Stock Options can only be granted to employees, not to consultants or board members. They must also be part of a plan approved by shareholders, ensuring that you’re making a sound investment.
- Vesting Period: These options usually come with a vesting period, meaning you’ll need to wait a specific duration before you can exercise them. This is a crucial step in planning your financial future.
- Expiration: Keep in mind that stock options typically expire 10 years from the grant date. Monitoring your options and their timelines is essential to make the most of this opportunity.
By understanding these basics, you’re taking a step towards making informed choices that can positively impact your family’s financial journey.
Evaluate Tax Implications of Exercising ISOs
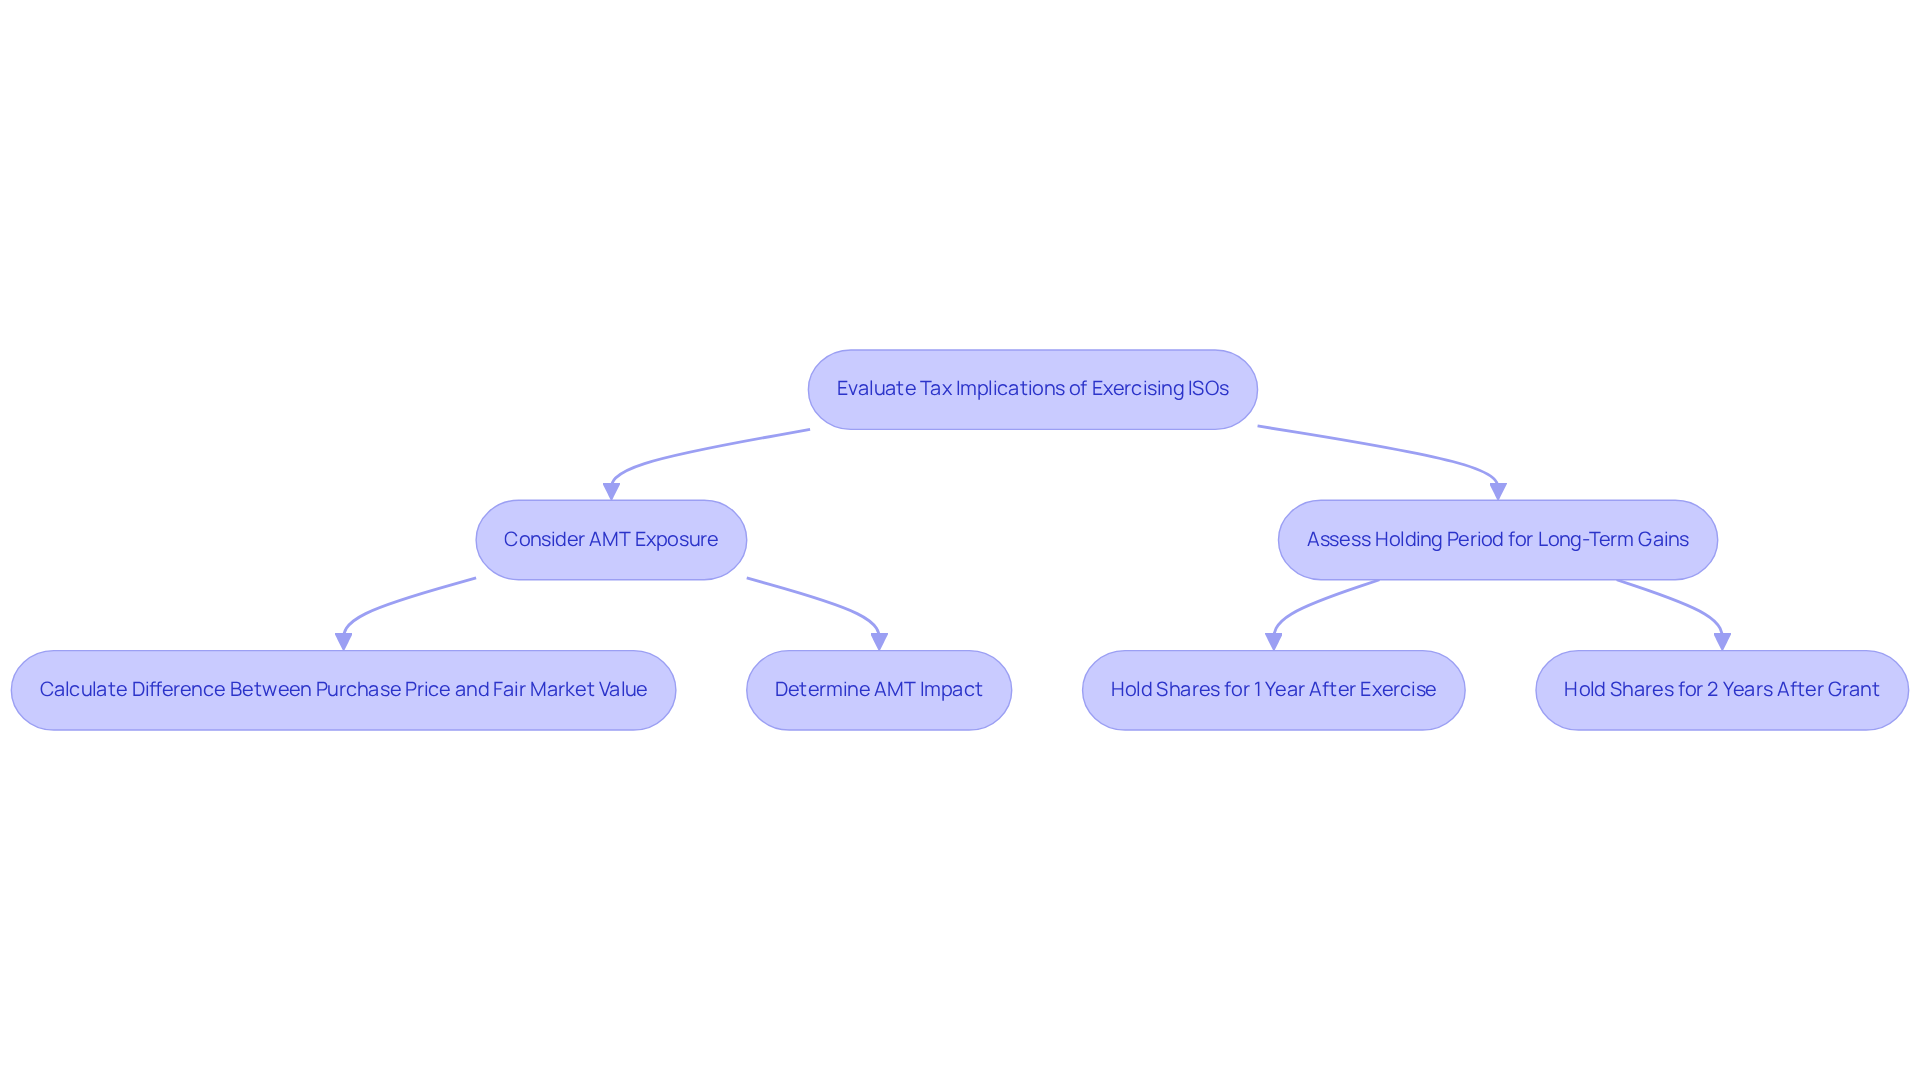
Imagine the relief of knowing your family’s financial future is secure, even when navigating the complexities of Incentive Stock Options (ISOs). You might be relieved to know that exercising ISOs usually doesn’t mean you’ll face regular income tax right away. But keep in mind, the difference between what you pay for the options and their fair market value can come into play for the Alternative Minimum Tax (AMT). If there’s a big gap between what you paid and the fair market value, you might find yourself facing AMT, which could lead to a higher tax bill than you expected. It’s really important to figure out your AMT exposure before you exercise, so you can avoid any surprises down the road.
To enjoy the benefits of long-term capital gains tax treatment, you’ll want to hold onto those shares for at least a year after exercising and two years from when they were granted. If you sell those shares before meeting the holding period, it can lead to a disqualifying disposition, meaning you’ll face ordinary income tax on the difference, which can add to your tax burden. Don’t forget to consider state-specific tax implications, as they can differ quite a bit and impact your overall strategy.
By understanding these tax implications, you can plan your exercise strategies wisely, helping to minimize tax liabilities and improve your family’s financial future.
Assess Timing Strategies for Exercising ISOs
Imagine feeling confident about your financial decisions while juggling the demands of family life. Timing is essential when it comes to the incentive stock options exercise timing for W2 employees, and there are several strategies to consider that can help ease your mind.
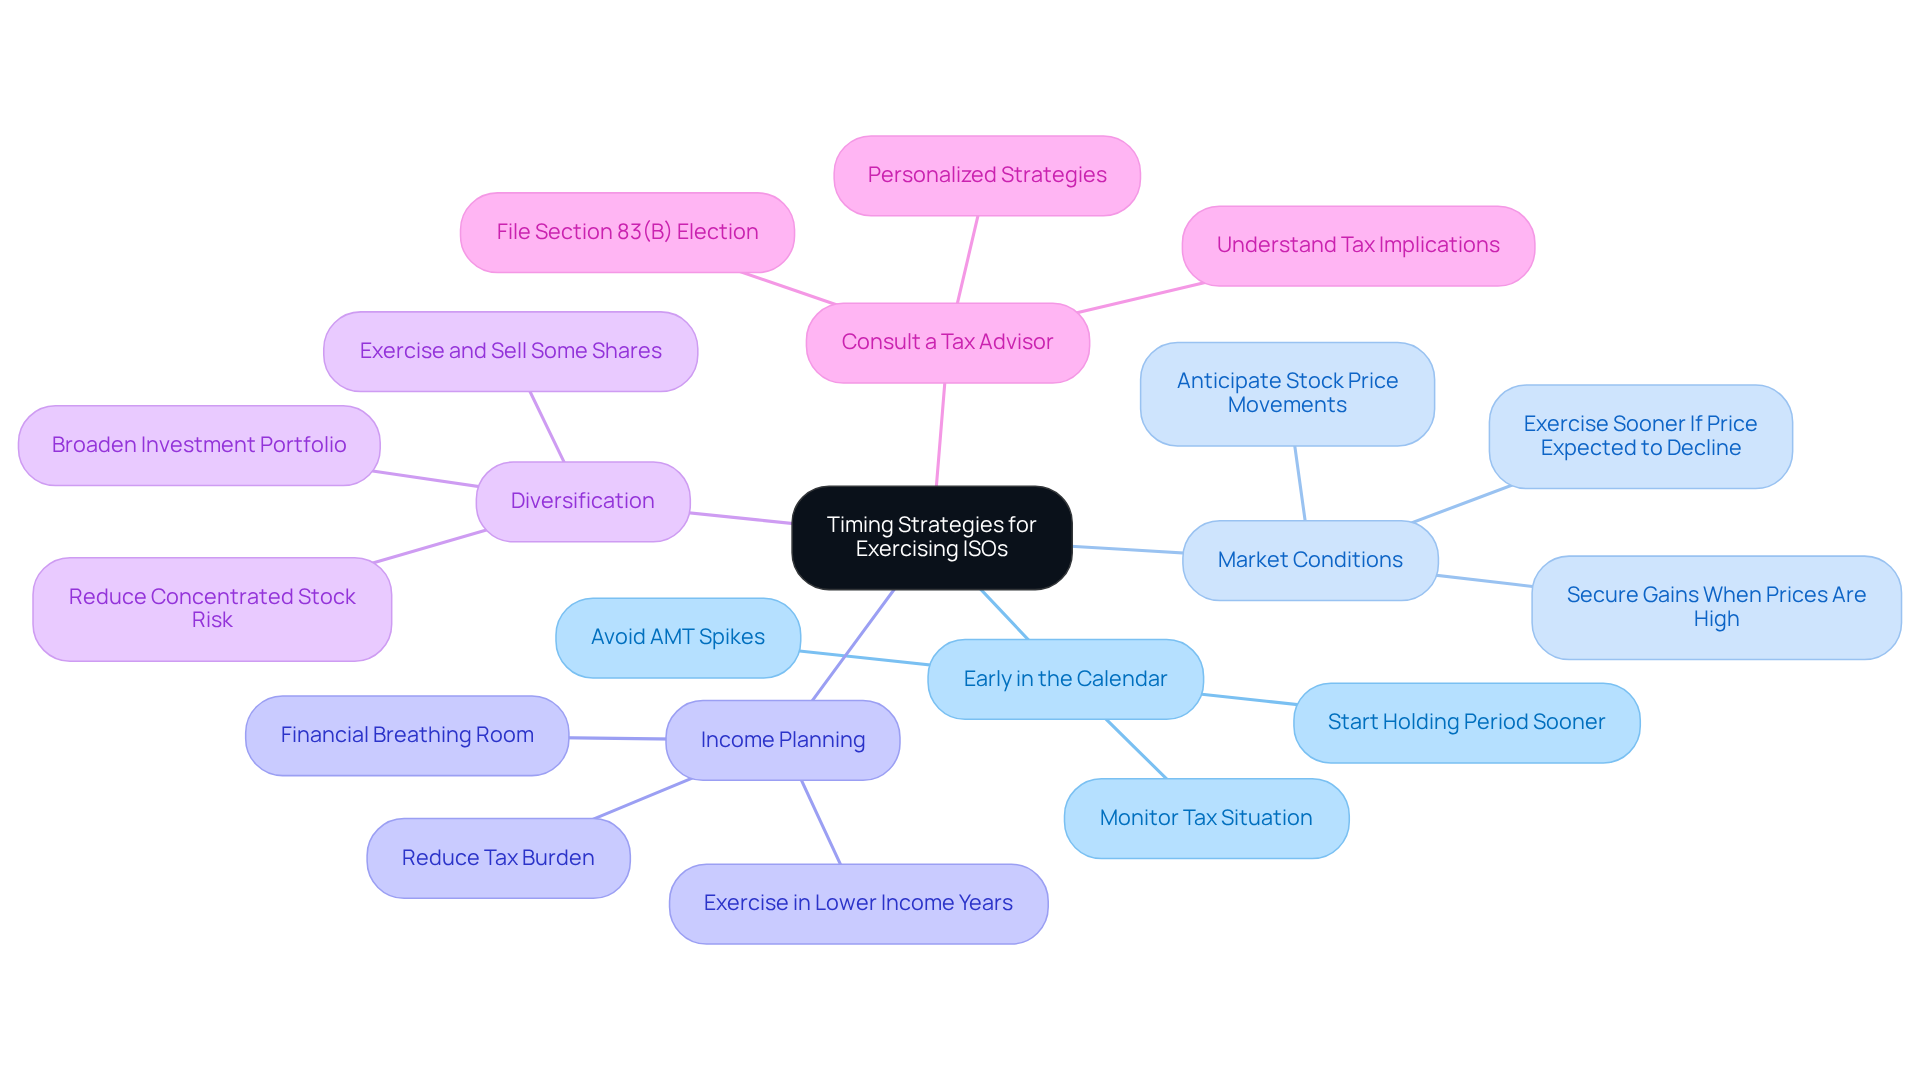
- Early in the Calendar: By choosing to exercise your options early in the year, you give yourself the chance to keep an eye on your tax situation, easing some of the stress that comes with tax season. This method allows you to start the holding period for long-term capital gains sooner and helps avoid spikes in the Alternative Minimum Tax (AMT), which can vary from 26% to 28%. Exercising in January provides almost a full cycle to monitor your tax situation before the AMT bill comes due.
- Market Conditions: Keep an eye on market conditions and stock performance. If you believe the stock price will rise, it may be beneficial to wait. Conversely, if you anticipate a decline, exercising sooner might be wise. For instance, if the current market price significantly exceeds the strike price, exercising can secure substantial gains for your family.
- Income Planning: Evaluate your total income for the duration. If you anticipate a lower income year, it may be a good time to exercise stock options to reduce your tax burden. Exercising when your income is lower can help lessen the impact of taxes on your options, giving you more financial breathing room.
- Diversification: If a significant portion of your wealth is tied up in company stock, consider exercising and selling some shares to diversify your investments. This strategy reduces risk associated with concentrated stock positions, which can pose significant financial risks for your family.
- Consult a Tax Advisor: Reaching out to a tax advisor can be a comforting step, helping you find strategies that fit your family’s unique financial journey. Given the complexities of tax implications, including the need to file a Section 83(B) election within thirty days after receiving restricted stock grants, consulting with a tax advisor can provide personalized strategies tailored to your financial situation and goals. Grasping the subtleties of tax incentives, including the possibility of AMT and the timing of tax payments, is crucial for making informed choices.
By thoroughly evaluating these timing strategies, you can enhance your approach to the incentive stock options exercise timing for W2 employees and improve your financial results. With the right timing and support, you can secure a brighter financial future for your family.
Implement Steps to Exercise ISOs Effectively
Imagine feeling confident about your financial future while ensuring your family’s needs are met through smart financial decisions. To exercise your Incentive Stock Options (ISOs) effectively, follow these steps:
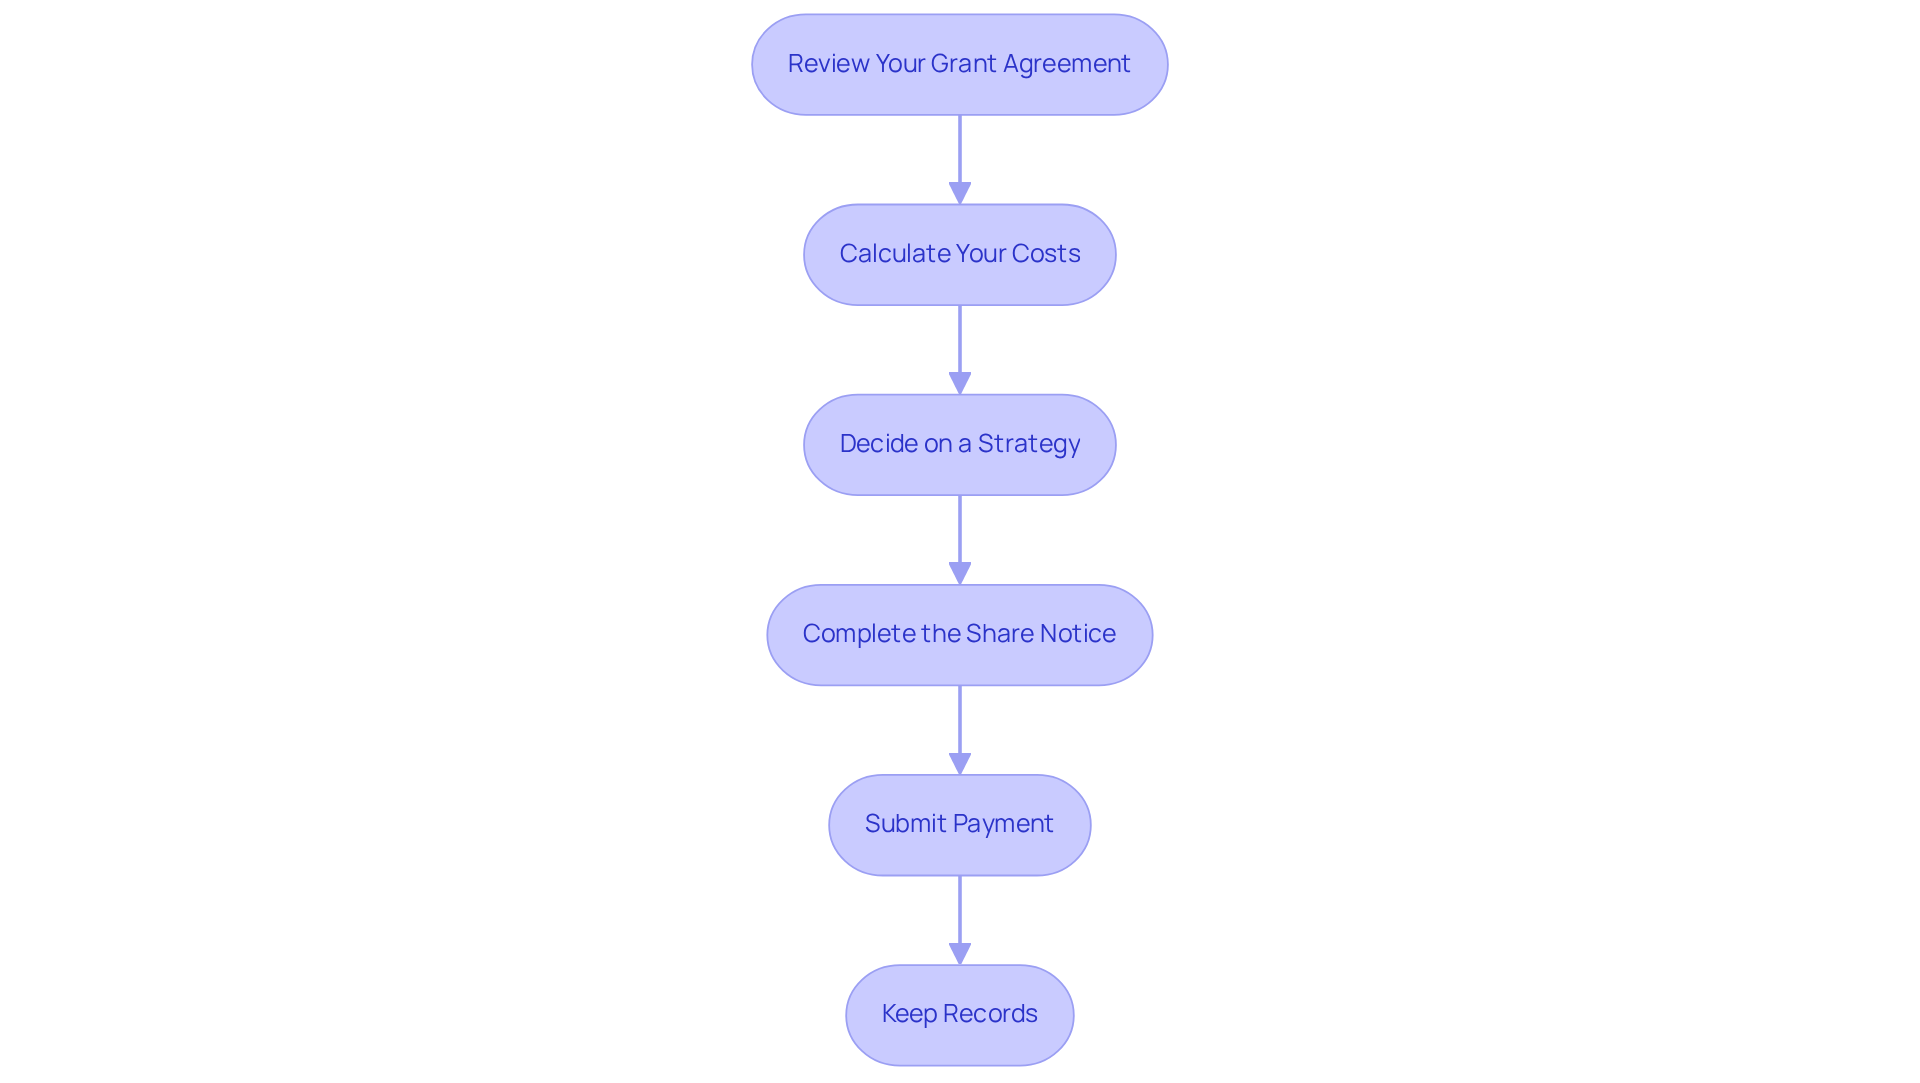
- Review Your Grant Agreement: Begin by examining your ISO grant agreement to understand key terms, including the option price, vesting schedule, and expiration date, which is typically a decade from the grant date.
- Calculate Your Costs: Calculate how much it will cost to use your options by multiplying the purchase price by the number of shares you want to buy. Make sure you have the necessary funds available, as this will be a cash outlay. Remember, the maximum dollar value of stock options an employee can receive per year cannot exceed $100,000.
- Decide on a Strategy: Choose whether to hold the shares or sell them right away. This decision should align with your financial goals and tax strategy. It’s important to understand that the incentive stock options exercise timing for W2 employees can trigger Alternative Minimum Tax (AMT) implications. For instance, in 2025, the phaseout for AMT exemption begins at $626,350 for single filers and $1,252,700 for married filing jointly. It’s easy to overlook tax implications, but understanding them can open doors to financial opportunities that benefit families like yours. Engaging with Bright Advisers can help you navigate these complexities and implement strategies such as tax-loss harvesting to optimize your financial outcomes.
- Complete the Share Notice: When you’re ready, take a moment to fill out the share notice provided by your employer. This step is important for specifying the number of shares you wish to utilize.
- Submit Payment: Make your payment for the shares, which can often be done via cash or a cashless transaction, where you sell enough shares to cover the cost.
- Keep Records: Maintain detailed documentation of your transaction, including the purchase price, fair market value (FMV) at the time of the transaction, and any tax documents received, such as Form 3921, which is essential for tax reporting. To qualify for long-term capital gains treatment on stock options, employees must adhere to the incentive stock options exercise timing for W2 employees, which requires waiting a minimum of twelve months after activity and twenty-four months following the initial grant date.
- Monitor Your Holdings: After exercising, keep an eye on your stock holdings and market conditions to make informed decisions about when to sell. Selling shares immediately after exercising can lead to disqualifying dispositions, affecting your tax treatment. If you overlook these strategies, you might miss out on significant savings that could benefit your family.
By following these steps, you can confidently navigate your ISOs, maximizing benefits while keeping your family’s financial future secure. Engaging with a professional tax planner, like Bright Advisers, can further enhance your strategy, helping you avoid unexpected tax bills and ensuring you make the most of your financial resources. For families like yours, understanding the AMT implications and other tax strategies can lead to significant wealth accumulation over time.
Disclaimer: Past performance does not guarantee future results. Securities investments are subject to risk. Bright Advisers provides advisory services through Lifeworks Advisors, a registered investment adviser.
Conclusion
Imagine feeling confident about your family’s financial future, knowing you’ve mastered the timing of your Incentive Stock Options (ISOs). Understanding ISOs can feel overwhelming, but it’s essential for making informed decisions that boost your family’s wealth. This guide has explored the essential steps to help your family navigate the complexities of ISOs with confidence, ensuring you can leverage these opportunities to your advantage.
Key insights discussed include:
- The importance of understanding the tax implications associated with exercising ISOs, such as the potential impact of the Alternative Minimum Tax (AMT) and the benefits of long-term capital gains treatment.
- Evaluating timing strategies – like exercising early in the year or considering market conditions – can significantly influence financial outcomes.
- Implementing a structured approach to exercising ISOs, from reviewing grant agreements to maintaining thorough records, empowers families to optimize their financial strategies.
When families take control of their ISOs, they open doors to financial opportunities that can last for generations. Working with a caring advisor can help you find strategies that fit your family’s unique financial goals, ensuring that you navigate the complexities of ISOs with confidence. Taking proactive steps today can pave the way for a more secure financial future, allowing your family to thrive and preserve your wealth across generations. With the right guidance, your family can thrive, ensuring a legacy of financial security for years to come.
Frequently Asked Questions
What are Incentive Stock Options (ISOs)?
Incentive Stock Options are part of an employee’s compensation package that give the right to purchase company shares at a predetermined price, known as the purchase price.
What are the tax benefits of Incentive Stock Options?
ISOs offer favorable tax treatment compared to non-qualified stock options (NSOs). If certain conditions are met, you may avoid paying regular income tax when exercising the options and only incur capital gains tax when selling the shares.
Who is eligible to receive Incentive Stock Options?
Incentive Stock Options can only be granted to employees, not to consultants or board members. They must also be part of a plan approved by shareholders.
What is a vesting period in relation to Incentive Stock Options?
A vesting period is the specific duration you must wait before you can exercise your Incentive Stock Options. This period is important for planning your financial future.
How long do Incentive Stock Options typically last?
Stock options generally expire 10 years from the grant date, so it is essential to monitor your options and their timelines to maximize this opportunity.
List of Sources
- Understand Incentive Stock Options (ISOs)
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- What are Stock Option? Types of Options & How They Work (https://carta.com/learn/equity/stock-options)
- 2022 Employee Stock Options Report | Carta (https://carta.com/data/2022-employee-stock-options-report)
- Incentive Stock Options: How ISOs Work vs NSOs – NerdWallet (https://nerdwallet.com/investing/learn/isos)
- Employee stock options: Pros & cons and how they work (https://jpmorganworkplacesolutions.com/insights/share-options-will-help-your-business-thrive)
- Evaluate Tax Implications of Exercising ISOs
- Stock Options and the Alternative Minimum Tax (AMT) (https://nceo.org/articles/stock-options-alternative-minimum-tax-amt)
- Mastering ISO and AMT Implications (https://trayecto.io/blog/mastering-isos-and-amt)
- Incentive Stock Options and AMT in 2026: Tax Rules Houston Professionals Must Know Before Exercising (https://skyboundwealthusa.com/news-and-insights/incentive-stock-options-and-amt-in-2026-tax-rules-houston-professionals-must-know-before-exercising)
- The Complete Guide to Exercising Stock Options: ISOs, NSOs, and AMT Explained — Quarry Hill Advisors (https://quarryhilladvisors.com/blog/complete-guide-exercising-stock-options-isos-nsos-amt)
- Incentive Stock Option (ISO) Taxes: A Guide (https://schwab.com/learn/story/incentive-stock-option-iso-taxes-guide)
- Assess Timing Strategies for Exercising ISOs
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- When Should I Exercise Stock Options? | Summitry (https://summitry.com/blog/when-to-exercise-stock-options)
- Exercising Options (https://insight.kellogg.northwestern.edu/article/exercising_options)
- Exercising Stock Options: Taxes, Timing & Strategies (https://jpmorganworkplacesolutions.com/insights/exercise-stock-options)
- Insights: How To Decide When To Exercise Stock Options – Forge (https://forgeglobal.com/insights/how-to-decide-when-to-exercise-your-stock-options)
- Implement Steps to Exercise ISOs Effectively
- Incentive Stock Options (ISO): How ISOs Work (https://carta.com/learn/equity/stock-options/iso)
- Understanding Incentive Stock Options and Tax-Saving Strategies – GHJ (https://ghjadvisors.com/ghj-insights/understanding-incentive-stock-options-and-tax-saving-strategies)
- 3 Strategies To Optimize Incentive Stock Options (ISOs) (https://kitces.com/blog/incentive-stock-options-iso-amt-financial-plan-taxes-portfolio)
- Stock option planning: Generating value (https://thetaxadviser.com/issues/2019/dec/stock-option-planning)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading