

Overview
This article presents a caring four-step process for withdrawing funds from life insurance, designed to help you understand your policy and the various withdrawal options available to you.
Imagine if you could navigate this journey with confidence, knowing the distinctions between partial withdrawals and complete surrenders.
It’s important to understand the implications of borrowing against cash value, as well as the potential tax consequences involved.
We encourage you to consult financial advisors who can guide you through these complexities, ensuring you make informed decisions that align with your family’s needs.
Remember, we’re here for you every step of the way.
Key Highlights:
- Understanding your life insurance policy is crucial, especially distinguishing between term and permanent coverage.
- Permanent policies, such as whole life and universal life, typically build cash value, unlike term policies.
- Key components to assess include type of policy, cash value accumulation, withdrawal limits, and surrender charges.
- Partial withdrawals allow access to cash value without losing coverage, while complete surrender results in loss of coverage and possible charges.
- Borrowing against cash value can provide funds but reduces the death benefit if loans are unpaid.
- Withdrawals up to the cost basis (total premiums paid) are usually tax-free; gains above this amount may incur taxes.
- Consulting with financial advisors is recommended to navigate withdrawal options and tax implications effectively.
- The withdrawal process includes reviewing your policy, contacting your provider, completing forms, and receiving confirmation of the transaction.
Introduction
Navigating the intricacies of life insurance can feel overwhelming, especially when it comes to accessing funds from a policy. As families increasingly turn to permanent life insurance for financial flexibility, understanding how to withdraw cash effectively becomes essential. Imagine if you could easily navigate this process with confidence. This comprehensive guide is here to illuminate the steps, ensuring that you, as a policyholder, can make informed decisions that align with your family’s financial goals.
With insights from industry experts and relatable examples, you’ll discover how to maneuver through the withdrawal landscape, all while considering tax implications and long-term consequences. It’s important to understand that embracing this knowledge empowers families to utilize their life insurance policies strategically. Together, we can pave the way for a more secure financial future for you and your loved ones.
Understand Your Life Insurance Policy
To successfully cancel your coverage, it’s essential to start by examining your documentation with care. Understanding whether you have a term or permanent coverage is crucial, as only permanent plans typically build up monetary value. Let’s explore some key components together:
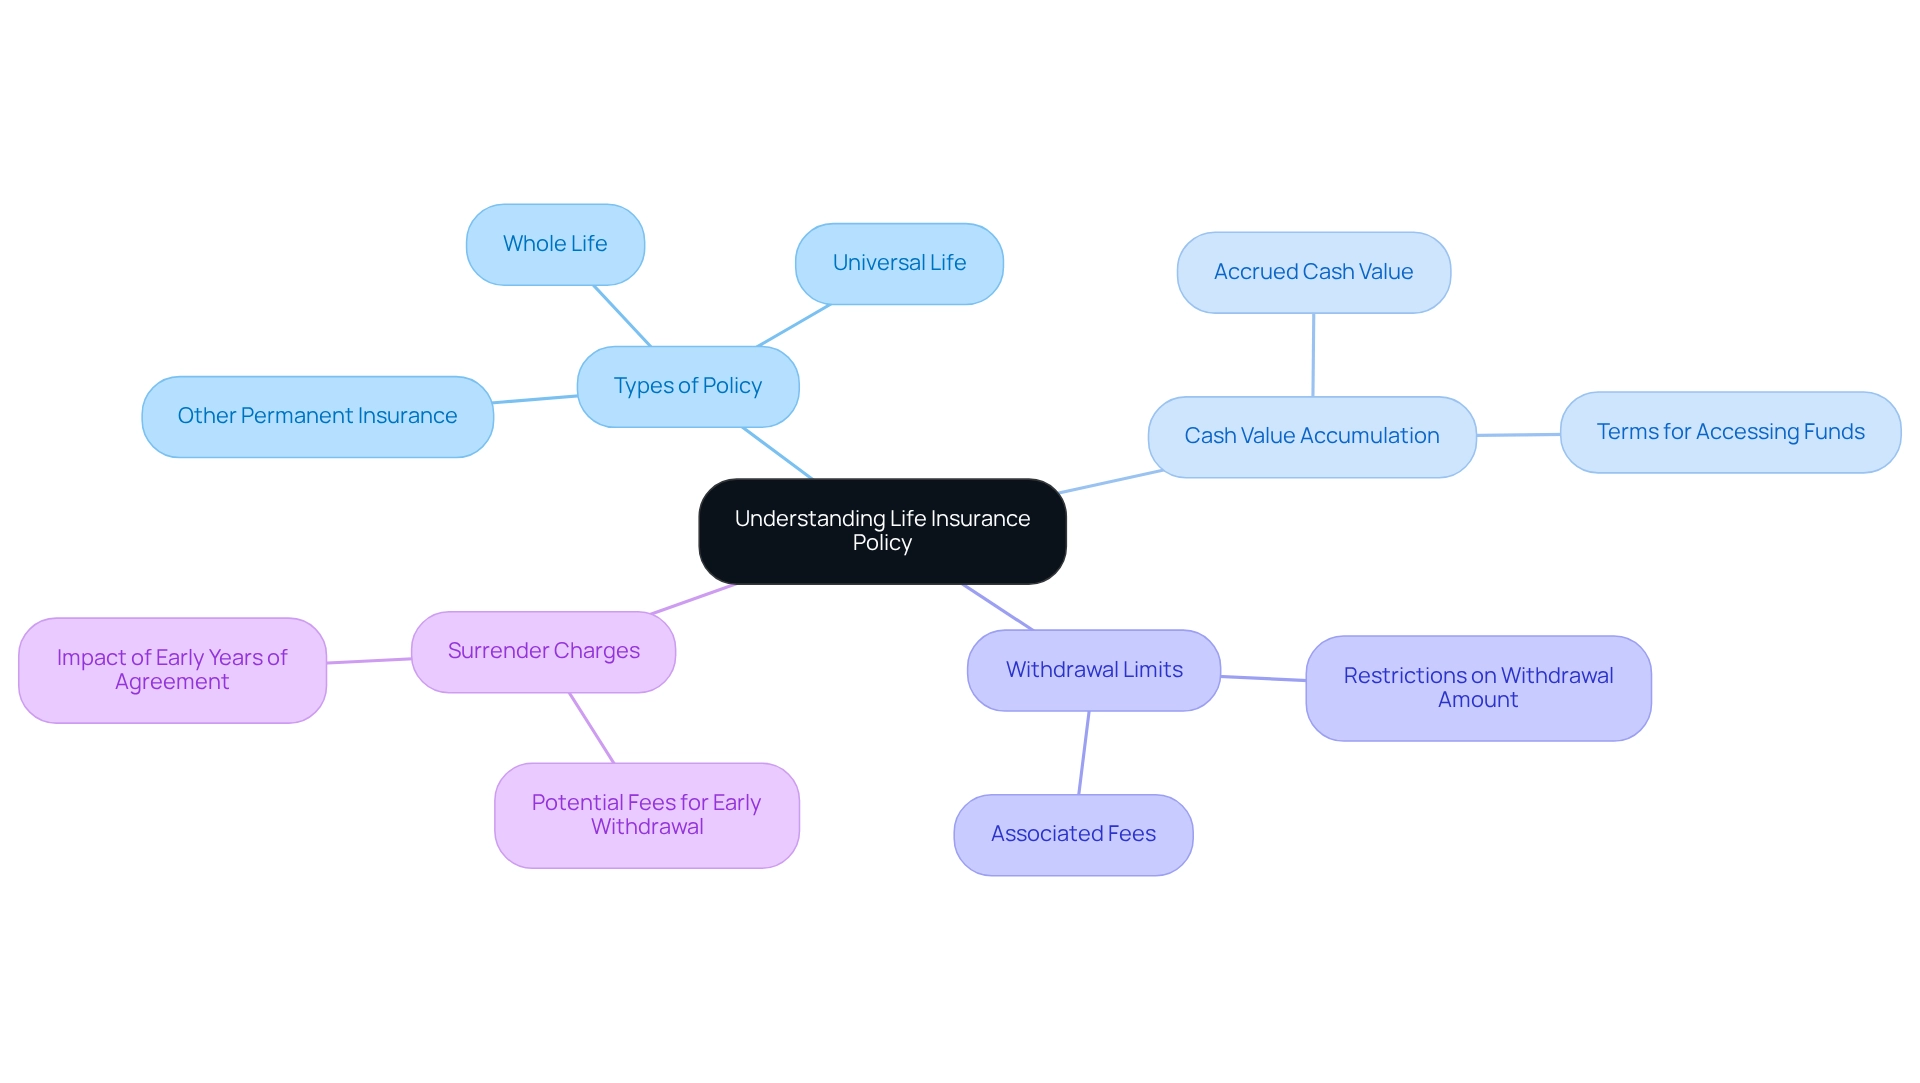
- Type of Policy: Identify if your policy is whole life, universal life, or another form of permanent insurance.
- Cash Value Accumulation: Assess how much cash value has accrued and the specific terms for accessing these funds.
- Withdrawal Limits: Familiarize yourself with any restrictions on the withdrawal amount and any associated fees.
- Surrender Charges: Be aware of potential fees for withdrawing funds, especially if it occurs during the early years of your agreement.
Understanding these elements is vital for making informed decisions regarding your withdrawal from life insurance options. With permanent coverage plans representing 60.7% of all coverage acquisitions in 2022, many families are increasingly relying on these options for financial flexibility, which includes the possibility of withdrawal from life insurance. As you navigate your choices, consider the insights from financial advisors who emphasize the importance of reviewing documentation to fully grasp the implications of your decisions.
Tori Addison, a Principal Researcher, notes, “According to data from the ACLI and our study, Delaware has the highest average payout per enforced policy, with an average amount of $4,149.” This information empowers families to make effective use of their policies, ensuring that their financial planning aligns with long-term objectives. Moreover, the growing trend towards independent agents and online research indicates that families are seeking digital platforms to better understand their coverage options.
While focusing on permanent coverage, it’s also important to mention that group policies typically offer lower premiums and simpler qualification, often available through employers as part of benefits packages. This broader context can help families make educated choices regarding the types of programs that best meet their needs. Remember, we’re here for you, and together, we can navigate this journey towards financial security.
Explore Withdrawal Options: Methods to Access Cash
Navigating the world of life coverage can feel overwhelming, but the withdrawal from life insurance can be accomplished through various means, each with its own consequences. At Bright Advisers, we are dedicated to helping families like yours explore these options effectively, ensuring minimal fund fees and tailored wealth management solutions.
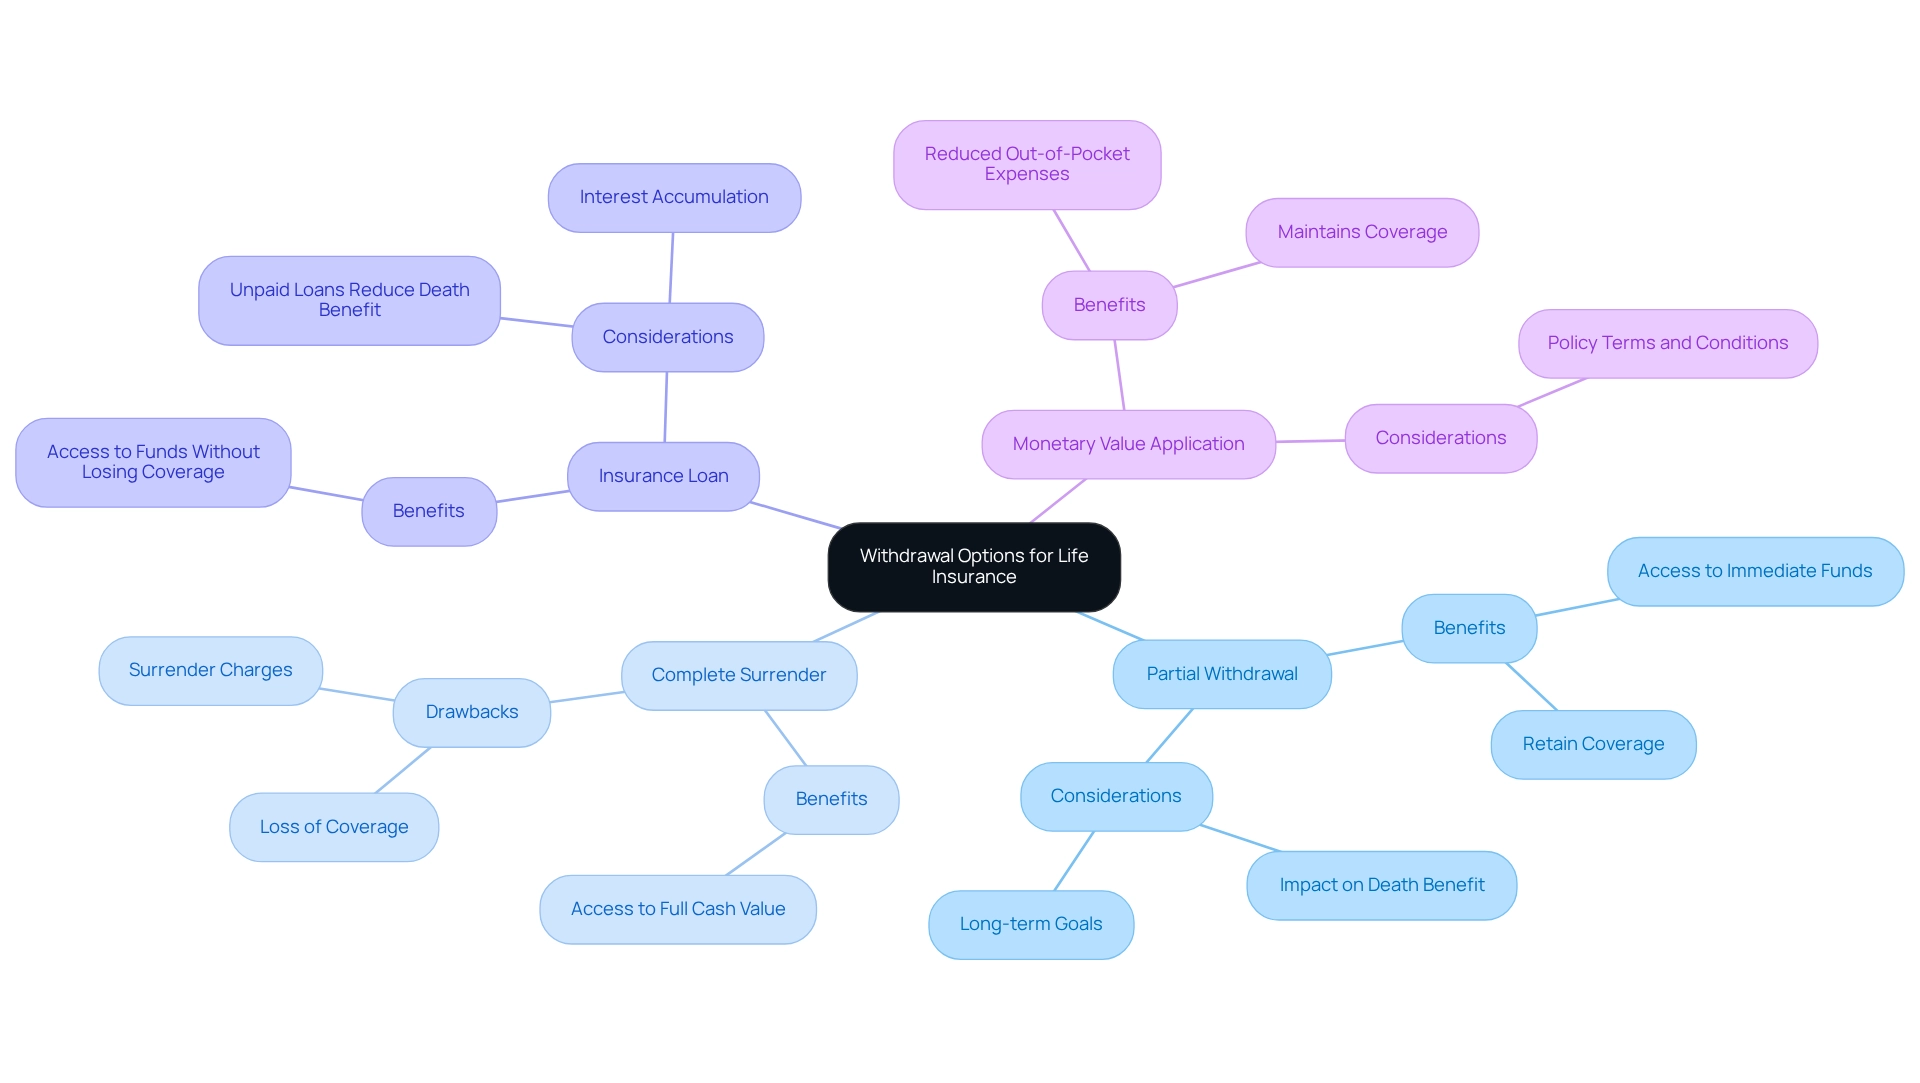
- Partial Withdrawal: Imagine needing immediate funds while still wanting to protect your loved ones. A partial withdrawal from life insurance allows you to access a portion of your policy’s monetary value without sacrificing your entire coverage. This flexible choice has gained popularity among policyholders seeking to balance their financial needs with their commitment to family protection. At Bright Advisers, we can guide you in determining the best amount to withdraw, keeping your long-term goals in mind.
- Complete Surrender: If you find that your life insurance plan no longer serves your needs, you might consider complete surrender for its monetary value. However, it’s essential to be cautious of surrender charges and the complete loss of coverage, which could leave your beneficiaries unprotected. Last year, we saw a significant rise in complete surrenders, reflecting a trend of individuals reassessing their financial strategies. Consulting with Bright Advisers can help you evaluate whether this option aligns with your family’s financial future.
- Insurance Loan: Another viable option is borrowing against the cash value of your plan. This method allows you to access funds without giving up your coverage, but it’s important to remember that any unpaid loans will reduce the death benefit, potentially impacting your loved ones’ financial security. We are here to help you understand the implications of obtaining a loan and how it fits into your overall financial strategy.
- Monetary Value Application: Some policies allow you to use the monetary value towards premium payments, effectively reducing your out-of-pocket expenses. This can be especially beneficial for families looking to manage their budgets while keeping their coverage intact. Bright Advisers can assist you in navigating this option effectively.
As you consider these choices, it’s important to weigh your immediate financial needs against your long-term aspirations. Financial advisors often suggest that a withdrawal from life insurance can be a wiser option for those wanting to access funds while still providing a safety net for their loved ones. As one financial planner noted, “Partial withdrawals allow families to access necessary funds while still providing a safety net for their loved ones.”
Real-world examples show how obtaining funds from coverage can provide essential support during challenging times. In certain situations, insured individuals have utilized settlements, transforming their contracts into substantial monetary disbursements, easing the burden of ongoing premium payments. Settlements come with specific criteria, including age, health condition, and type of coverage, making them a feasible choice for those seeking to access funds without the obligation of continuous premium payments.
Ultimately, the method you choose should align with your financial situation and future aspirations. For personalized assistance in navigating these options, we invite you to reach out to Bright Advisers today at (714) 987-2967 or hello@brightadvisers.com. Together, we can navigate this journey and find the best solutions for your family’s needs.
Follow the Step-by-Step Withdrawal Process
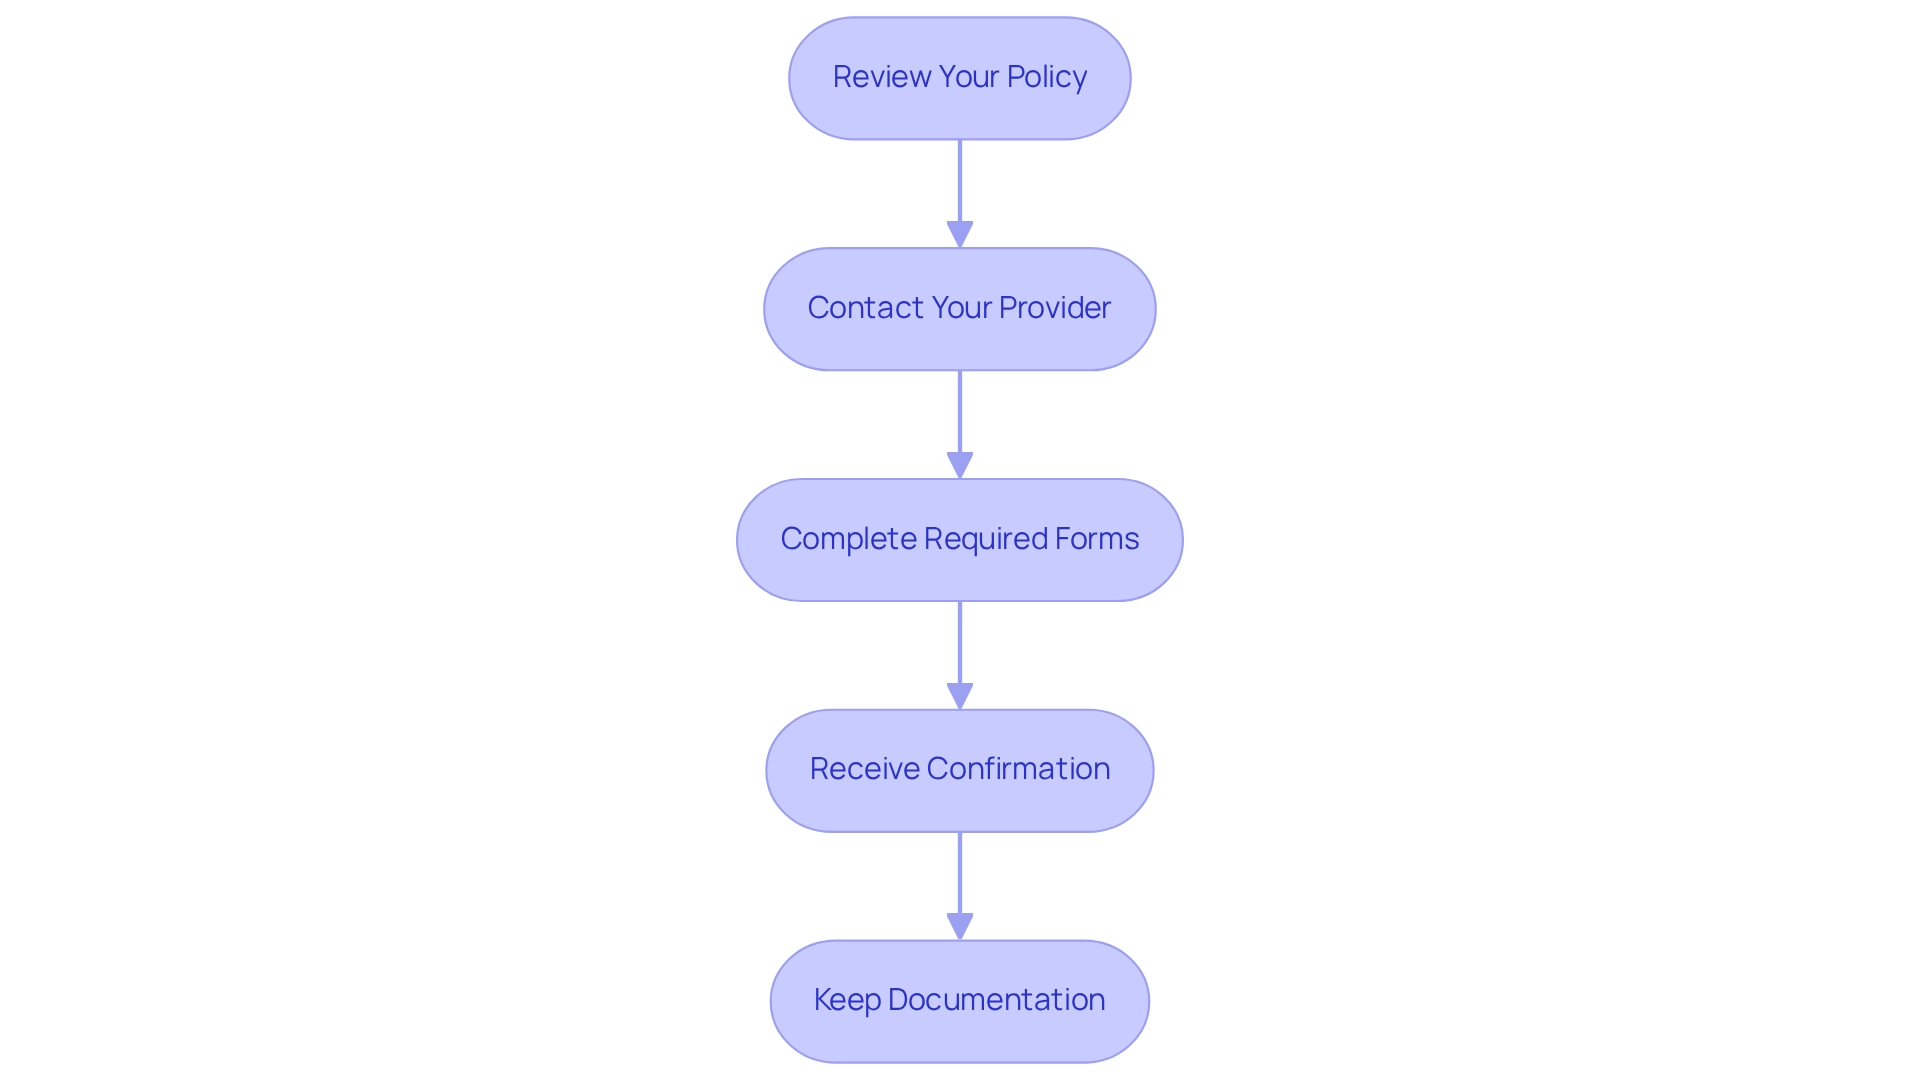
Retrieving funds through a withdrawal from life insurance can be simple if you follow these important steps:
-
Review your policy by verifying its monetary value and understanding the different options for withdrawal from life insurance that are available to you. This knowledge empowers you to make informed decisions based on your family’s financial needs.
-
Contact Your Provider: Reach out to your coverage company’s customer service or your agent. Discuss your withdrawal options and ask about any necessary forms. Imagine if effective communication with your insurer could significantly reduce the time it takes to process your request. Studies show that customers who engage proactively with their insurers experience a 30% faster processing time.
-
Complete Required Forms: Fill out all necessary forms for the withdrawal from life insurance process. This typically includes a withdrawal request form or a surrender form if you plan to cash out entirely. Be meticulous in providing accurate information to avoid delays. Coverage experts often point out that a common mistake is neglecting to verify the forms, which can lead to unnecessary complications. To make a withdrawal from life insurance, submit your request by sending the completed forms to your insurer, either online or via mail, according to their instructions. Remember to keep copies of all submitted documents for your records. It’s important to check if plan administrators need to sign forms according to plan rules.
-
Receive Confirmation: After processing, you should receive confirmation of your withdrawal and the amount disbursed. Retain this documentation, as it serves as proof of the transaction. For instance, a family who successfully navigated the withdrawal from life insurance process highlighted the importance of keeping thorough records, which ultimately helped them resolve a minor issue with their insurer. By following these steps and incorporating these insights, you can ensure a smooth and efficient withdrawal from life insurance, allowing you to access the funds you need when you need them. Remember, we’re here for you, and together, we can navigate this journey.
Consider Tax Implications and Consequences
Before making a withdrawal from life insurance, it’s important to consider the tax implications that come with it.
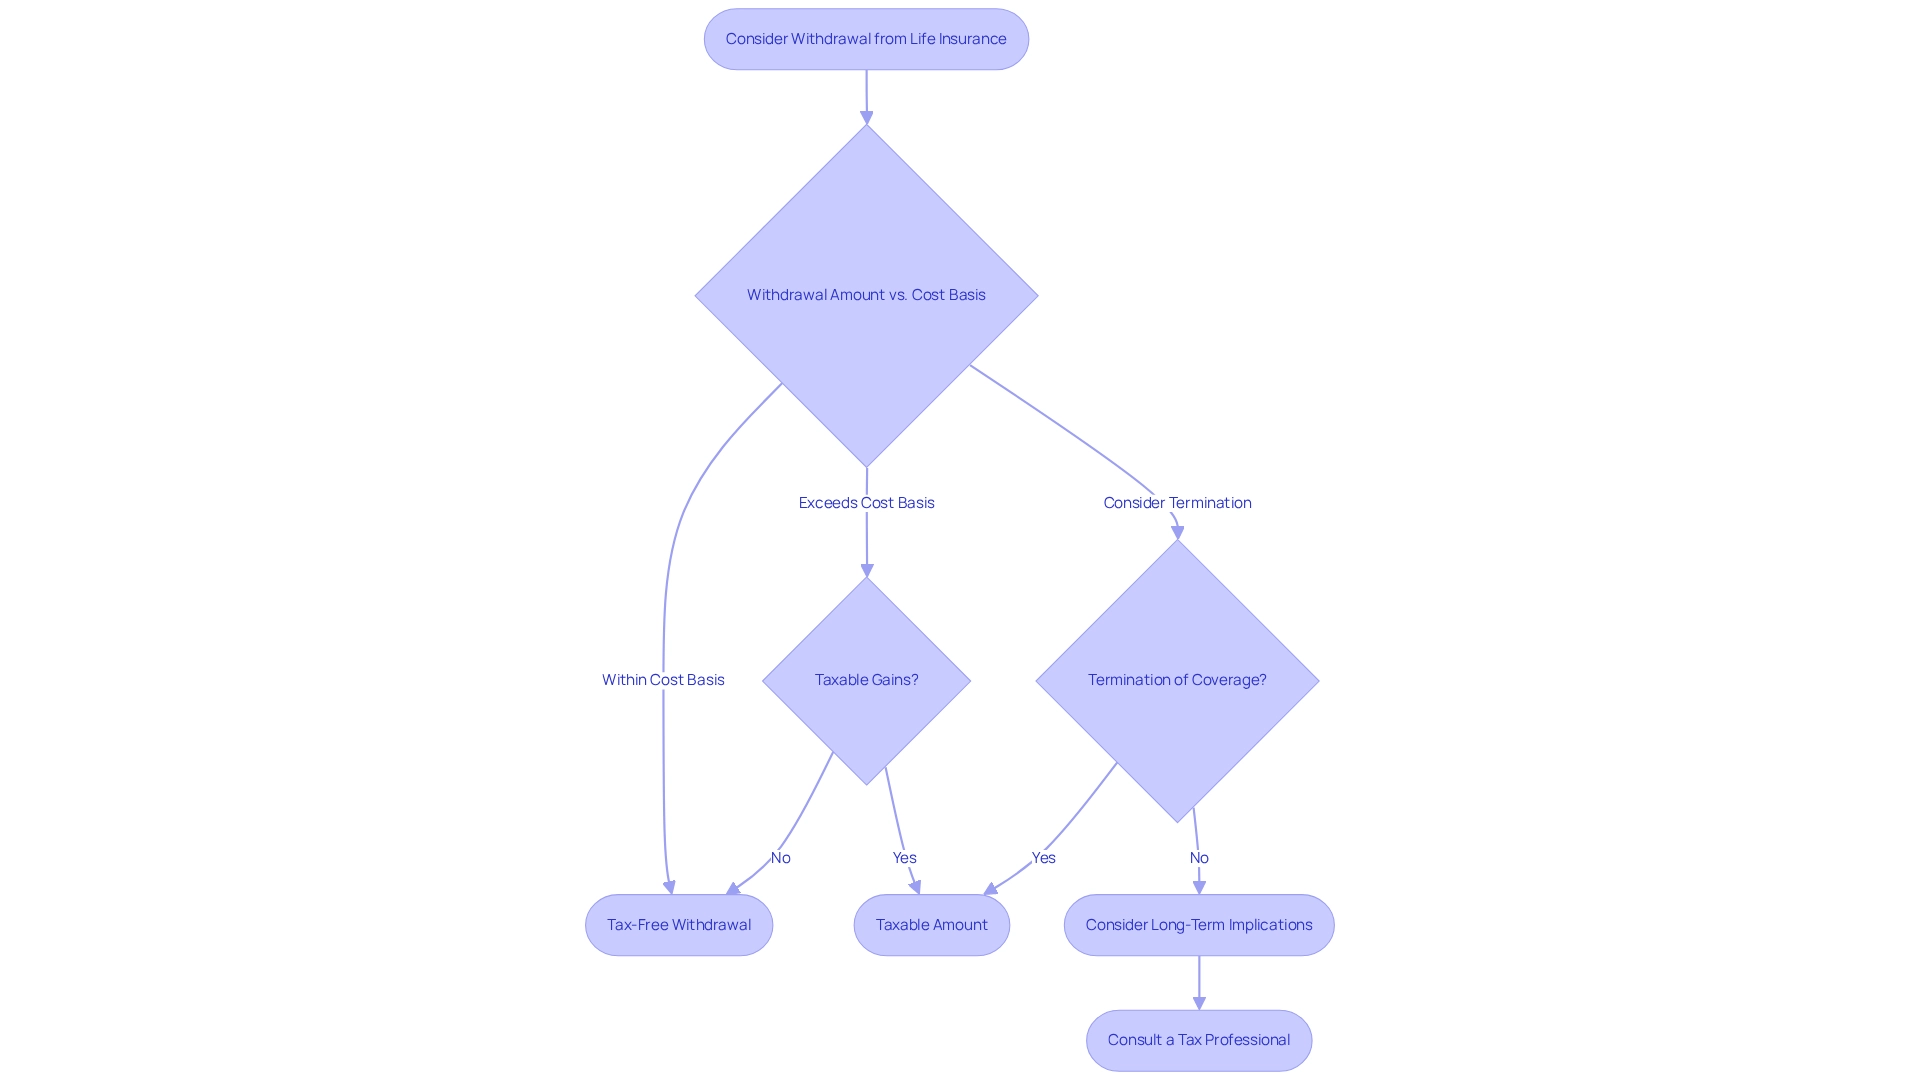
Imagine being able to access your funds without worry. You can typically make a withdrawal from life insurance up to the total amount of premiums paid into the policy, which is known as your cost basis, without incurring taxes. This means tax-free access to your money, which can be especially beneficial for families like Jay and Emma, who are striving to ease financial stress while planning for their children’s education.
However, it’s essential to be mindful of the potential taxable gains. Withdrawals that exceed your cost basis may be considered as a withdrawal from life insurance and could be subject to income tax. For example, if you withdraw $15,000 and your cost basis is $10,000, the $5,000 gain could be taxable. This emphasizes the importance of tracking your contributions to avoid unexpected tax liabilities, a lesson learned by Allison and Brian, who discovered the value of proper tax planning to maximize their financial potential.
Additionally, if you decide to terminate your coverage, be aware that any profits from the withdrawal from life insurance may also be taxed, and you could encounter surrender fees that diminish your monetary value. This can significantly affect your financial strategy, especially for families aiming to optimize their resources, much like Emily and Mark, who are focused on building a solid foundation for their future.
It’s also crucial to consider the long-term consequences of borrowing against your coverage. While loans can provide quick access to funds, they may impact your plan’s death benefit and monetary value over time. This is a concern for families like Jay and Emma, who are balancing current responsibilities with future aspirations.
Given the complexities of tax laws, consulting with a tax professional is highly advisable. They can offer tailored advice based on your specific situation, ensuring compliance and helping you navigate the intricacies of tax implications. As Michael Kitces, Head of Planning Strategy at Focus Partners Wealth, points out, “The largest by far is the straightforward fact that a death benefit from a coverage plan is completely tax free.” By carefully considering these factors, families can create a more effective strategy for withdrawal from life insurance that aligns with their long-term financial goals.
Furthermore, consider Patricia’s experience. She selected a higher premium option for her whole life insurance policy to accelerate her cash value growth. This strategy allowed her to enhance her cash value more quickly while benefiting from tax-deferred growth, optimizing her long-term financial position. For personalized guidance in navigating these complexities, reach out to Bright Advisers to explore tailored financial planning and tax optimization strategies. Together, we can navigate this journey.
Conclusion
Navigating the complexities of withdrawing cash from a life insurance policy can feel overwhelming, but understanding the details can empower you. By reviewing your policy documents, you can determine if you have a term or permanent life insurance policy and identify the cash value available for withdrawal. It’s crucial to grasp the withdrawal limits and potential surrender charges, as these factors can significantly impact both your immediate financial needs and your long-term coverage.
Imagine if you could access cash when you need it most. Several methods exist for doing so, including:
- Partial withdrawals
- Full surrenders
- Policy loans
- Applying cash value towards premium payments
Each option carries unique implications that deserve careful consideration in light of your family’s financial goals. Engaging with a financial advisor can provide invaluable guidance, ensuring that you maintain the necessary coverage while addressing your immediate needs.
It’s also important to understand the tax implications of your withdrawals. Knowing the difference between tax-free withdrawals and taxable gains can help you avoid unexpected tax liabilities. Consulting a tax professional is a wise step to navigate these complexities effectively. By taking informed steps and seeking expert advice, you can leverage your life insurance policy strategically, ultimately enhancing your financial security and aligning with your family’s long-term objectives.
In conclusion, empowering yourself with knowledge about life insurance withdrawals not only facilitates immediate access to needed funds but also strengthens your overall financial planning. By making educated decisions, you can ensure that your life insurance policy serves as a valuable asset in achieving your financial goals, providing peace of mind for your family’s future. Remember, we’re here for you, and together, we can navigate this journey.
Frequently Asked Questions
What should I examine before canceling my life insurance coverage?
You should carefully examine your documentation, including the type of policy, cash value accumulation, withdrawal limits, and surrender charges.
How can I determine the type of policy I have?
Identify if your policy is whole life, universal life, or another form of permanent insurance.
What is cash value accumulation in a life insurance policy?
Cash value accumulation refers to the amount of cash value that has accrued in permanent insurance plans, which can be accessed under specific terms.
Are there limits on how much cash I can withdraw from my policy?
Yes, it is important to familiarize yourself with any restrictions on the withdrawal amount and any associated fees.
What are surrender charges?
Surrender charges are potential fees for withdrawing funds from your policy, especially if the withdrawal occurs during the early years of your agreement.
Why is it important to understand these elements before making a decision?
Understanding these elements is vital for making informed decisions regarding your withdrawal from life insurance options.
What percentage of coverage acquisitions in 2022 were permanent coverage plans?
Permanent coverage plans represented 60.7% of all coverage acquisitions in 2022.
How do group policies differ from individual policies?
Group policies typically offer lower premiums and simpler qualification, often available through employers as part of benefits packages.
What insights do financial advisors provide regarding life insurance coverage?
Financial advisors emphasize the importance of reviewing documentation to fully grasp the implications of your decisions regarding life insurance.
List of Sources
- Understand Your Life Insurance Policy
- Top Life Insurance Statistics for 2025 (https://marketwatch.com/insurance-services/life-insurance/life-insurance-statistics)
- Life Insurance Statistics, Data and Industry Trends 2025 (https://forbes.com/advisor/life-insurance/life-insurance-statistics)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Explore Withdrawal Options: Methods to Access Cash
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)
- Partial Surrender of Life Insurance: A Strategic Financial Move (https://abramsinc.com/partial-surrender-life-insurance)
- Follow the Step-by-Step Withdrawal Process
- Idaho Power EV Information (https://idahopower.chooseev.com/commercial/case_studies)
- Withdrawal FAQs (https://corebridgefinancial.com/rs/help/faq-withdrawals)
- Consider Tax Implications and Consequences
- How Is the Cash Value of a Whole-Life Policy Taxed? | Canadian LIC (https://canadianlic.com/blog/how-is-the-cash-value-of-a-whole-life-policy-taxed)
- Life Insurance Policy Loans: Tax Rules And Risks (https://kitces.com/blog/life-insurance-loan-taxation-rules-at-death-or-lapse)
- Life Insurance Statistics in 2025 | The Zebra (https://thezebra.com/resources/research/life-insurance-statistics)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Estate Planning for high-income W-2 families at Bright Advisers.
Keep reading