

Overview
When considering moving your IRA from one bank to another, it’s essential to choose a direct trustee-to-trustee transfer. This approach not only helps you avoid tax penalties but also ensures a smooth and worry-free process. Imagine the peace of mind you’ll feel knowing that your hard-earned savings are being handled with care.
It’s important to understand the necessary steps involved in this process. Accurate documentation and diligent monitoring of the transfer can help you navigate common challenges associated with IRA transfers. Together, we can ensure that everything goes smoothly, allowing you to focus on what truly matters—your family’s future.
As you embark on this journey, remember that support is available to guide you through each step. We’re here for you, ready to help you make informed decisions that align with your family’s values and goals. Together, we can navigate this journey with confidence.
Key Highlights:
- An IRA transfer involves moving funds from one IRA to another without taking possession of the money.
- Direct movement (trustee-to-trustee transfer) is the preferred method to avoid tax penalties and streamline the process.
- A rollover requires withdrawing funds and depositing them into another IRA within 60 days, necessitating adherence to IRS regulations.
- Choosing a new IRA provider involves researching fees, investment options, and customer service quality.
- Documentation must be completed accurately to prevent delays; transfers should be monitored as they can take 1-2 weeks.
- Common challenges include delayed transfers, incomplete documentation, tax implications from improper rollovers, and confusion about account types.
- Post-transfer best practises include reviewing investment strategies, staying informed about market trends, making regular contributions, monitoring performance, and consulting a financial advisor.
Introduction
Transferring an Individual Retirement Account (IRA) might feel daunting, yet it’s a vital step for many individuals eager to enhance their retirement savings. With more than half of American families holding retirement accounts, grasping the intricacies of IRA transfers is essential for making sound financial choices.
Imagine if you could navigate this process with ease. This guide offers a straightforward pathway, from selecting a new provider to overcoming common hurdles. But what if unexpected delays or tax implications arise during your transition? It’s important to understand these challenges, as they can empower you to take control of your financial future. Together, we can ensure your retirement assets are secure and well-managed, providing peace of mind for you and your family.
Understand IRA Transfers: Key Concepts and Terminology
Before you embark on the journey of transferring your IRA, it’s important to grasp some key concepts that will guide you through this process with confidence:
- IRA Transfer: Think of this as moving your funds from one IRA to another without ever taking possession of the money yourself. You can choose to do this through a direct transaction or a rollover, both of which have their own benefits.
- Direct Movement: Also known as a trustee-to-trustee movement, this method allows your funds to shift directly from one institution to another. This ensures that you don’t have to manage the funds during the transfer, making it a seamless experience.
- Rollover: This option involves withdrawing funds from one IRA and depositing them into another within a 60-day window. It’s crucial to follow IRS regulations to avoid any taxes or penalties that can arise from improper rollovers. In fact, a Vanguard survey found that nearly 48% of individuals mistakenly thought their rollover funds were automatically invested, underscoring the importance of understanding these processes.
- Trustee: This is the financial institution that holds your IRA. Knowing how your trustee functions is essential for ensuring a smooth transition.
Understanding these terms is vital, especially since 54.4% of families have retirement accounts, highlighting the prevalence of IRA ownership. By familiarizing yourself with these concepts, you’ll be better equipped to navigate the relocation process confidently and learn how to move an IRA from one bank to another, allowing you to make informed decisions about your retirement savings. Financial advisors, like Philip Chao, emphasize that grasping these ideas can help you avoid potential tax penalties and seize valuable investment opportunities.
We’re here for you every step of the way, ensuring that you feel supported as you make these important financial decisions for your family.

Initiate the Transfer: Steps to Move Your IRA
To initiate the transfer of your IRA, let’s walk through these essential steps together:
-
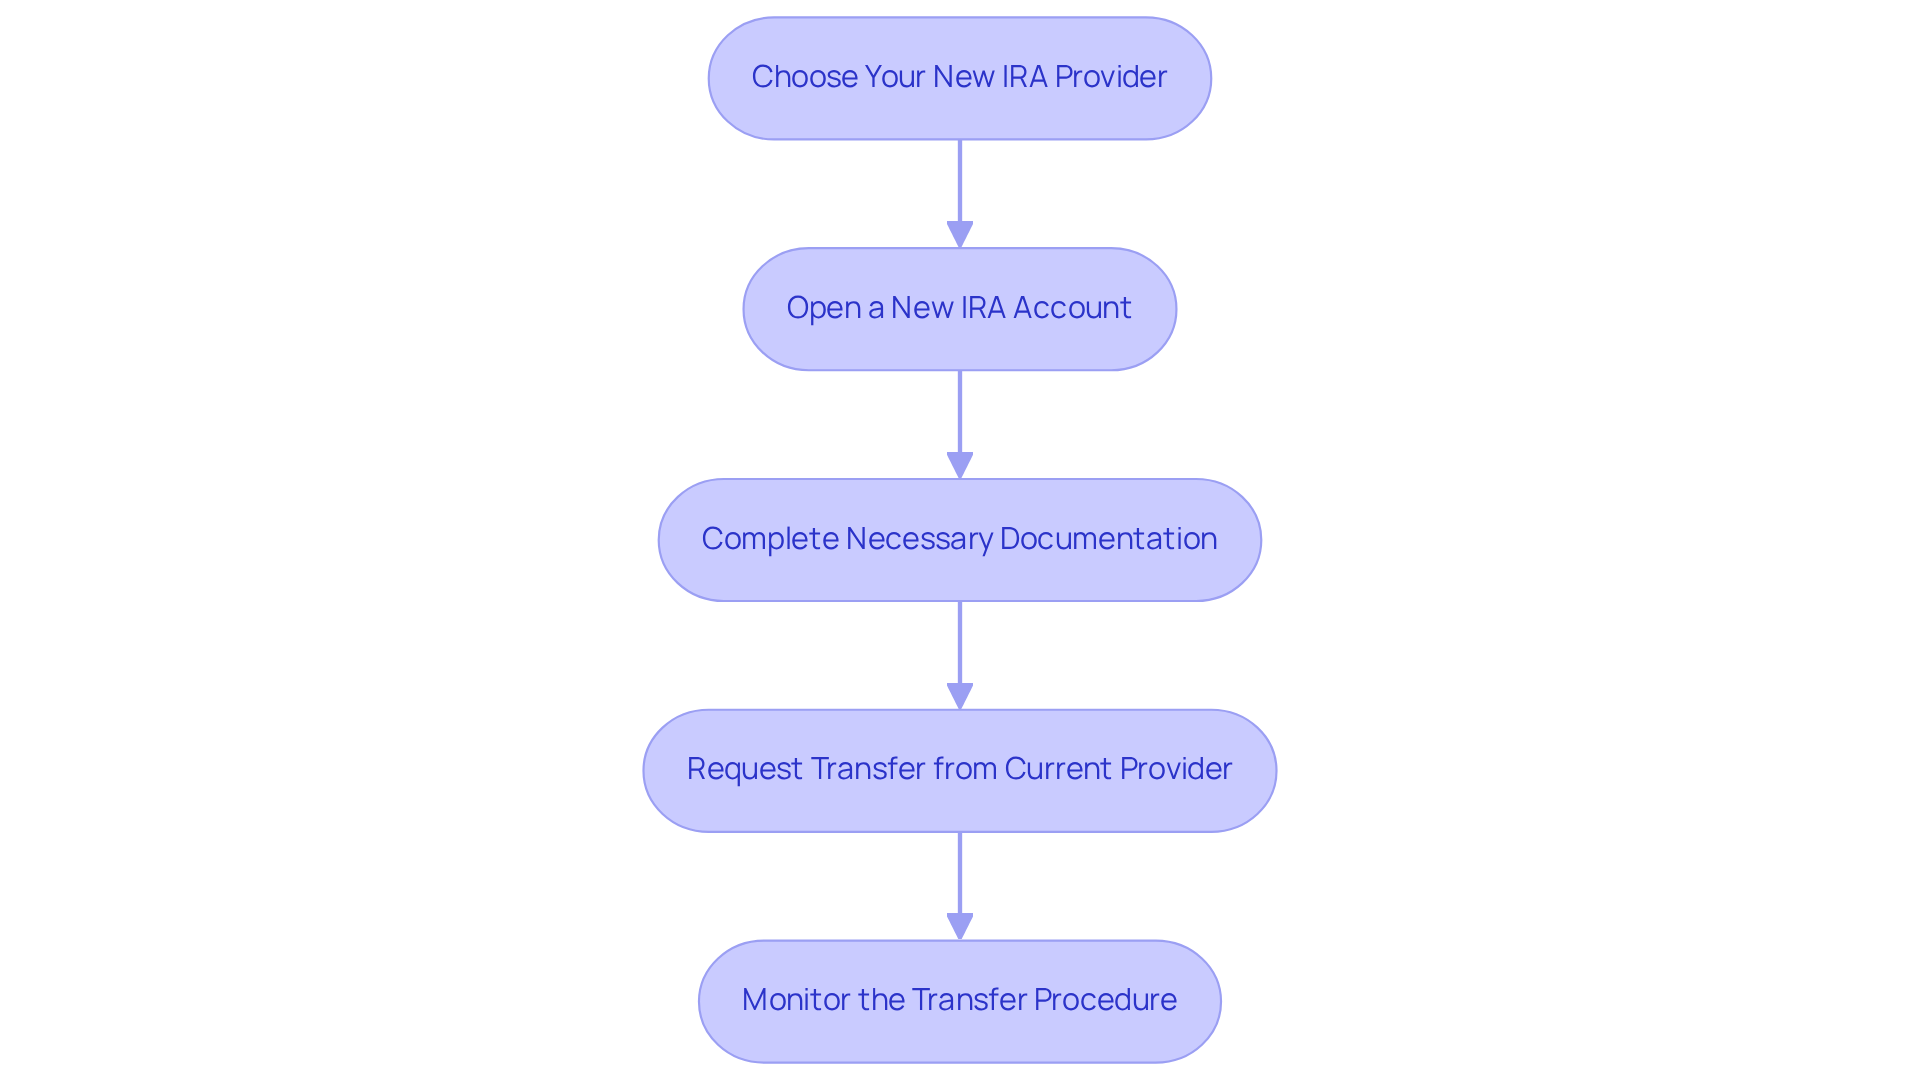
Choose Your New IRA Provider: Start by conducting thorough research to select a financial institution that truly aligns with your family’s needs. Consider key factors like fees, investment options, and the quality of customer service. Remember, 54.4% of families have retirement accounts—this highlights the importance of making informed choices that suit your unique situation.
-
Open a New IRA Account: Once you’ve chosen a provider, complete the application process, which is often available online. Be ready to share personal information and identification to help set everything up. At Bright Advisers, we are committed to ensuring that this process is transparent and seamless, guiding you every step of the way.
To understand how to move an IRA from one bank to another, it’s essential to follow the necessary steps. To learn how to move an IRA from one bank to another, request the transfer by reaching out to your current IRA provider. This usually involves filling out a request form for relocation, and your new provider can assist you with this. Keep in mind that you can only transfer your IRA once per year, making timing crucial. Our team at Bright Advisers is here to answer any questions you may have during this important transition.
-
Complete Necessary Documentation: Make sure to fill out all required forms accurately. This may include providing your new IRA account number and signing authorization forms. Remember, transfers must be completed within 60 days, so prompt action is essential to avoid penalties. As a new client, you will also have the chance to collaborate with your advisor to develop a customized investment strategy that aligns with your family’s financial goals.
-
Monitor the Transfer Procedure: Keep an eye on the status of your transfer. While it typically takes between one to two weeks for the process to finish, this duration can vary by institution. Staying proactive can help you address any potential issues quickly. At Bright Advisers, we are here to assist you throughout this journey, ensuring your retirement savings are effectively managed and aligned with your family’s vision.
By following these steps on how to move an IRA from one bank to another, you can ensure a smooth transfer of your IRA funds, thereby securing your retirement savings in good hands and effectively managing them for your family’s future.
Navigate Challenges: Common Issues and Solutions in IRA Transfers
Transferring your IRA can feel daunting, but learning how to move an IRA from one bank to another and understanding the challenges and their solutions can make the process smoother for you and your family.
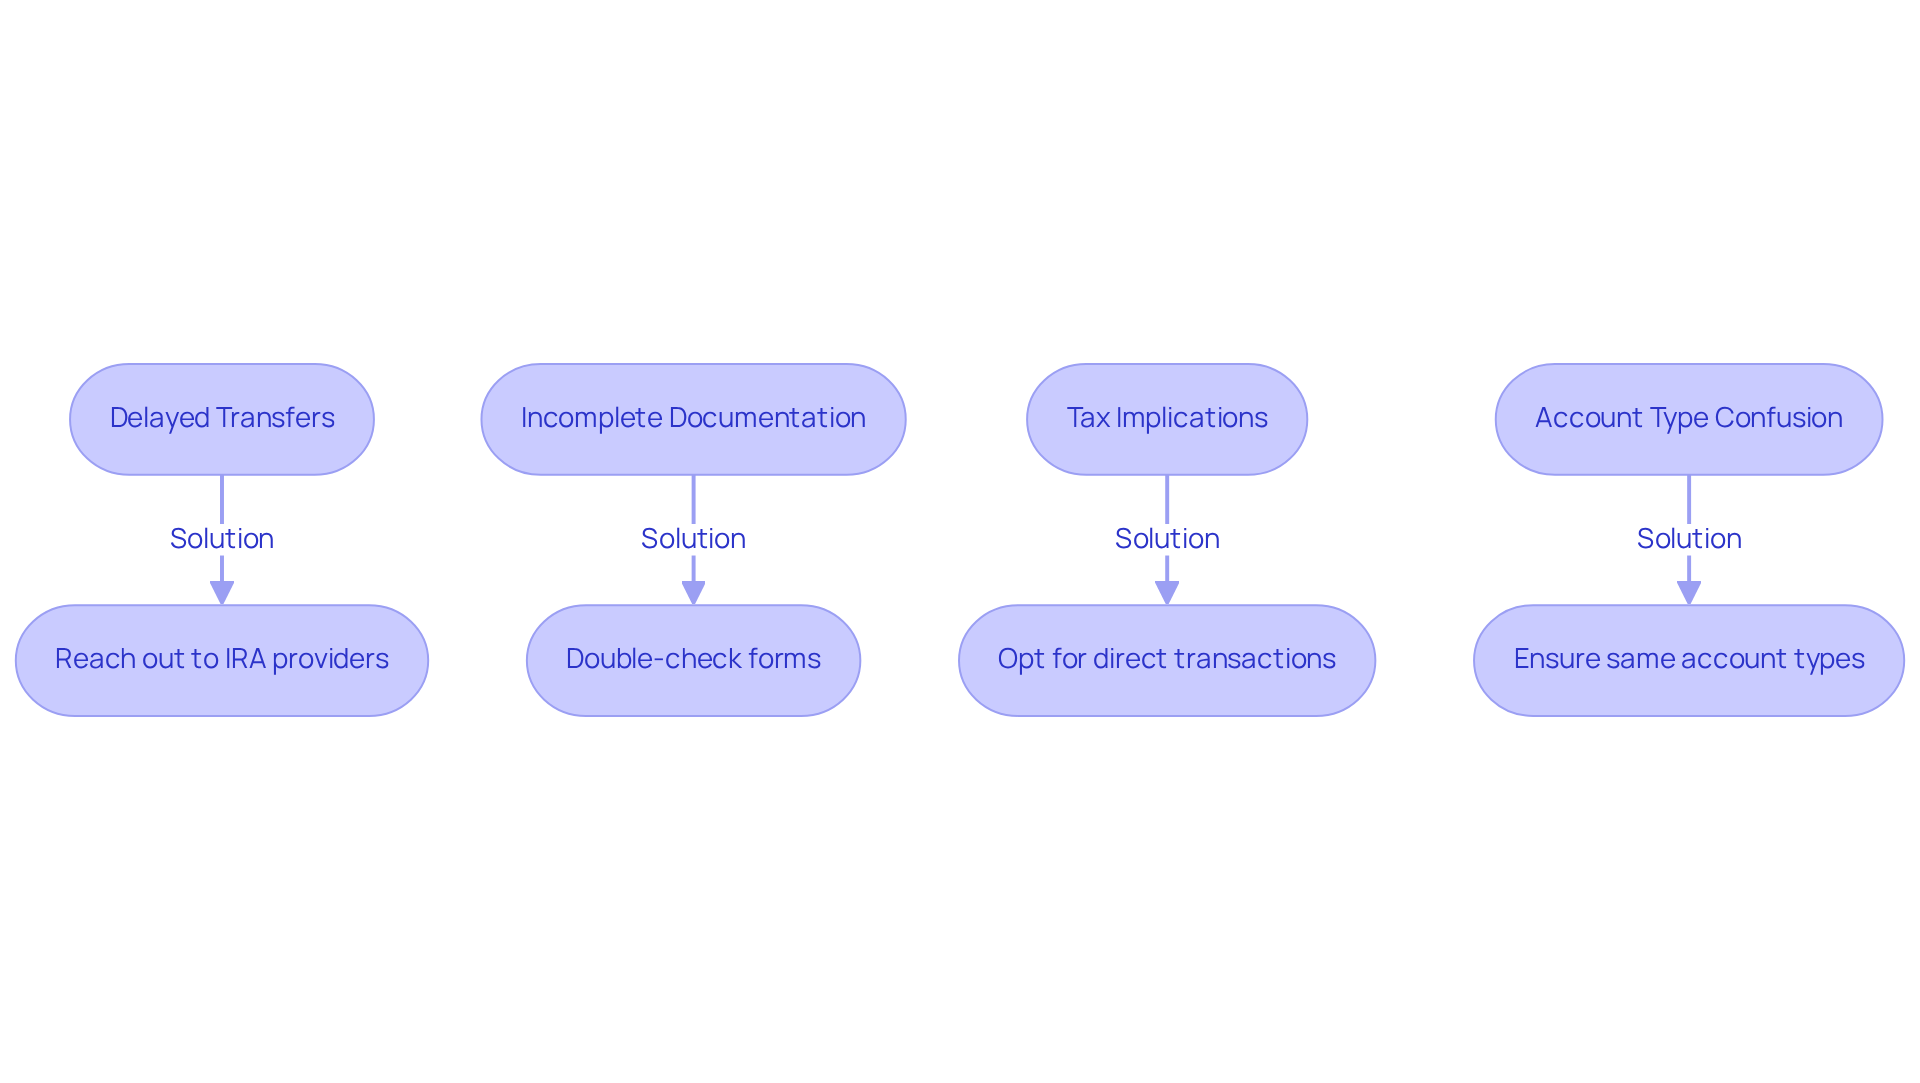
- Delayed Transfers: Sometimes, transfers take longer than expected, often stretching to 6-8 weeks. In 2022, an estimated $670 billion was rolled over from employer-sponsored plans into traditional IRAs, highlighting the importance of understanding this process. If you encounter delays, don’t hesitate to reach out to both your previous and current IRA providers to check on the status of your transfer. When learning how to move an IRA from one bank to another, a direct movement, or trustee-to-trustee transfer, is the best option as it helps you avoid common rollover mistakes and eliminates the risks associated with the 60-day rule. As Carlos Dias Jr. wisely noted, “A direct movement is the most effective solution to shift funds from one IRA to another.”
- Incomplete Documentation: It’s essential to ensure that all forms are filled out completely. Missing information can lead to frustrating delays. Take a moment to double-check your forms before submission to prevent unnecessary holdups.
- Tax Implications: If you accidentally take possession of the funds during a rollover, you may face tax penalties. To avoid this, always opt for a direct transaction, ensuring that the funds move straight between institutions without your involvement. Recent news has underscored the importance of completing rollovers within the allowed time to sidestep tax implications.
- Account Type Confusion: Moving between the same types of IRAs (for instance, traditional to traditional or Roth to Roth) is crucial to prevent complications. Misunderstanding account types can lead to tax consequences and additional delays.
By being proactive and informed about these challenges, you can better understand how to move an IRA from one bank to another, ensuring a smoother transition of your retirement assets. Remember, we’re here for you, and together, we can navigate this journey toward securing your family’s financial future.
Manage Your New IRA: Post-Transfer Best Practices
After understanding how to move an IRA from one bank to another, it’s essential to implement effective management practices to optimize your economic future. Here are some important steps to consider:
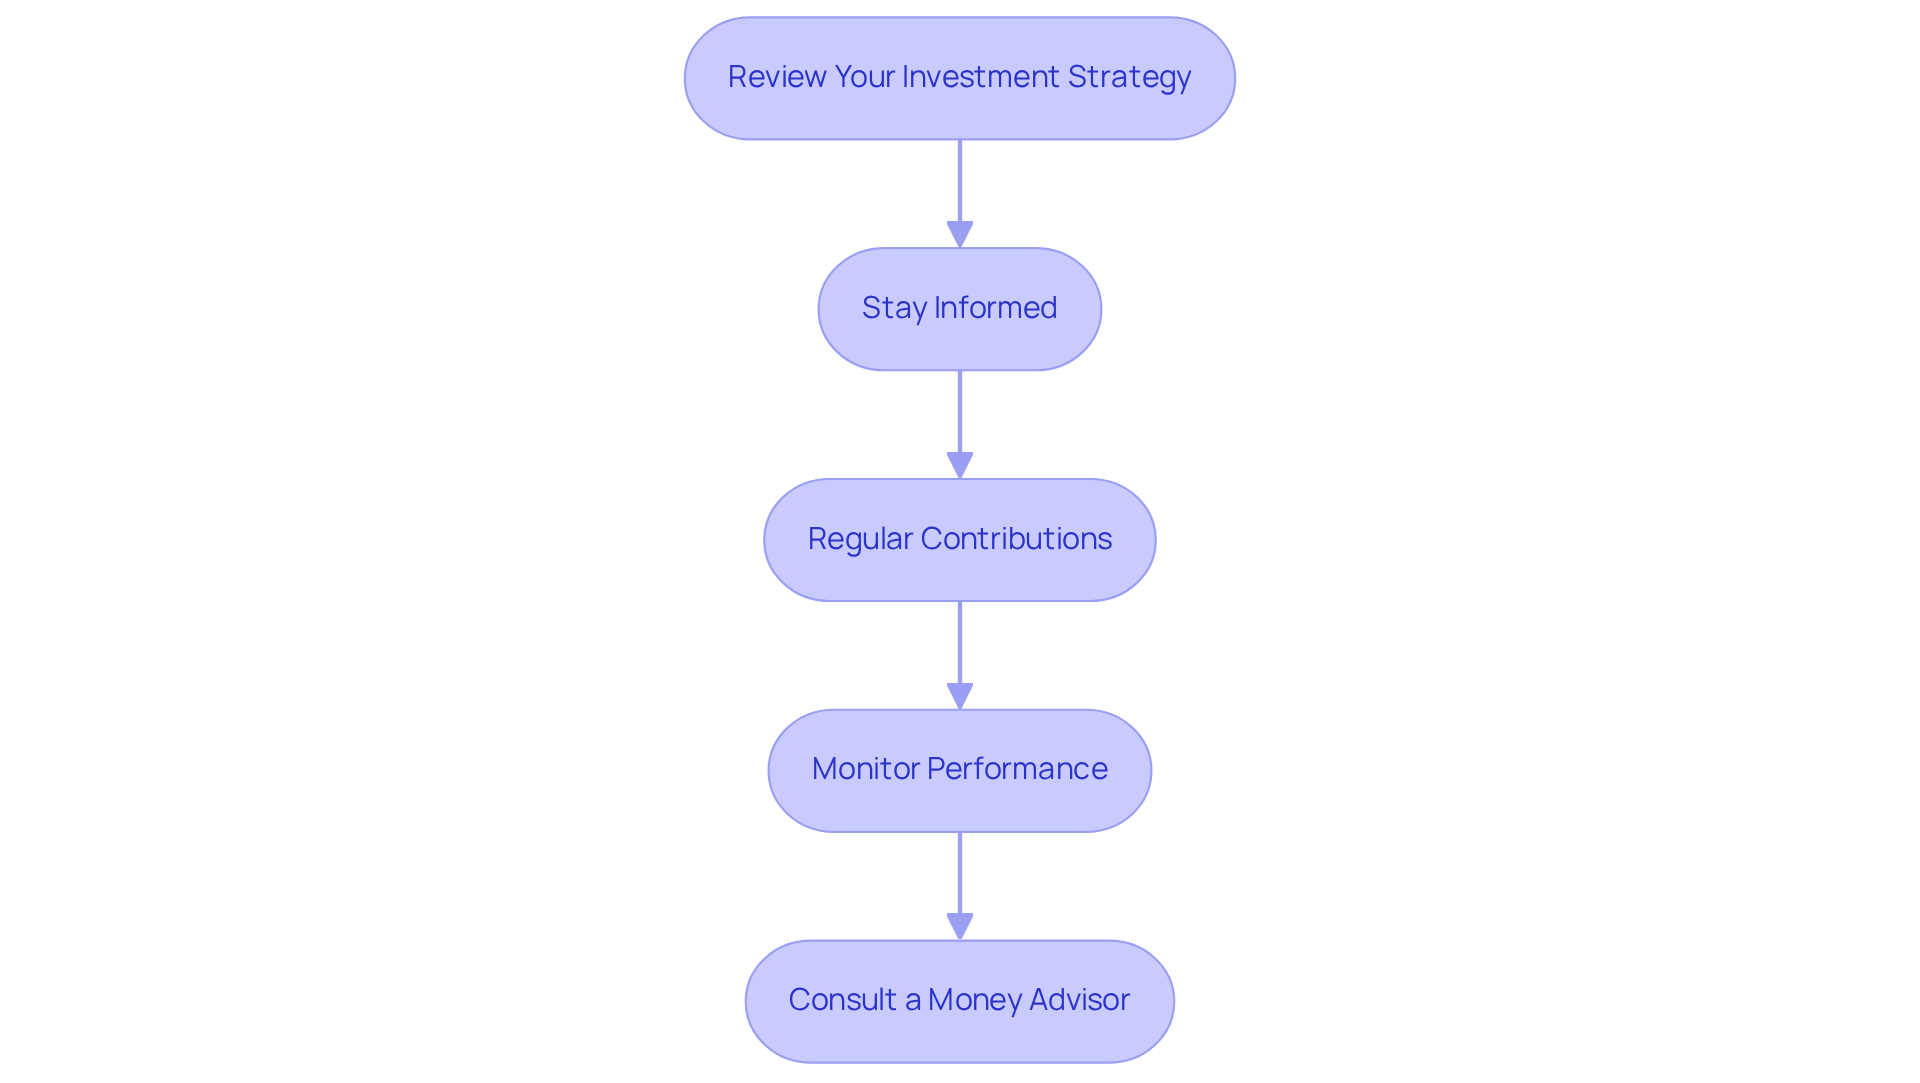
- Review Your Investment Strategy: Regularly evaluate your investment choices to ensure they align with your monetary objectives and risk tolerance. Many IRA holders overlook this crucial step, which can hinder potential growth. Adjust your portfolio as needed to reflect any changes in your economic situation or market conditions. At Bright Advisers, our compassionate team is here to help you create a lasting monetary plan that promotes growth and active management of your investment strategy, including tax-loss harvesting opportunities to enhance your returns.
- Stay Informed: Keeping up with market trends and changes in IRA regulations is vital. Being informed empowers you to make decisions about your investments that can enhance your returns. Remember, as Tony Robbins points out, market downturns can be seen as opportunities for long-term investors to buy at a discount.
- Regular Contributions: Establishing automatic contributions to your IRA can significantly boost your retirement savings over time. Experts recommend saving 12% to 15% of your salary for retirement, which is especially important for young families looking to secure their financial future. Consistent contributions can help you reach this target. Our innovative technology at Bright Advisers makes tailored monetary planning and investing accessible, ensuring you can manage your contributions effectively.
- Monitor Performance: Regularly reviewing your IRA’s performance is essential. This practice allows you to make timely adjustments to your investment strategy, keeping you on track to meet your retirement goals. The average IRA balance was reported at $129,200 in Q3 2024, underscoring the importance of proactive management. Additionally, be mindful of high fees; even a 2% annual fee can significantly reduce your retirement savings over time. At Bright Advisers, we are committed to minimizing fund fees, making wealth management more accessible for families.
- Consult a Money Advisor: If you’re feeling uncertain about your investment choices or need personalized guidance, consider consulting a planner who specializes in IRAs. A fiduciary advisor can provide tailored advice that aligns with your long-term monetary goals, helping you navigate the complexities of retirement planning. As James Royal, Ph.D., notes, working with a skilled advisor can offer comprehensive monetary guidance, ultimately assisting you in achieving your economic objectives. Bright Advisers is dedicated to empowering families through personalized planning and tax optimization.
By following these best practices, you can learn how to move an IRA from one bank to another and manage your new IRA effectively, working towards securing a stable financial future. Remember, we’re here for you every step of the way.
Conclusion
Transferring an IRA from one bank to another is more than just a financial decision; it’s a crucial step that can significantly shape your retirement savings. By familiarizing yourself with the key concepts, steps involved, and potential challenges, you can approach this process with confidence and clarity. Remember, making informed choices is essential—it lays the groundwork for a secure financial future for you and your loved ones.
In this article, we’ve outlined the essential steps for initiating an IRA transfer. This includes:
- Selecting a new provider
- Completing necessary documentation
- Closely monitoring the transfer process
We’ve also addressed common issues like:
- Delayed transfers
- Incomplete documentation
- Tax implications
Providing practical solutions to help you navigate these challenges effectively. It’s important to be proactive post-transfer; we’ve shared best practices for:
- Reviewing your investment strategies
- Staying informed
- Seeking guidance from financial advisors
Ultimately, understanding how to move an IRA from one bank to another is not just about the transfer itself; it’s about taking control of your financial destiny. By following the outlined steps and remaining vigilant throughout the process, you can ensure your retirement assets are managed effectively. Embrace this opportunity to secure a brighter financial future for your family. Remember, we’re here for you—seeking guidance from professionals can enhance your journey towards achieving long-term financial goals together.
Frequently Asked Questions
What is an IRA transfer?
An IRA transfer involves moving your funds from one IRA to another without taking possession of the money yourself. This can be done through a direct transaction or a rollover.
What is a direct movement in the context of IRA transfers?
A direct movement, also known as a trustee-to-trustee movement, allows your funds to shift directly from one financial institution to another without you managing the funds during the transfer.
What is a rollover in IRA transfers?
A rollover involves withdrawing funds from one IRA and depositing them into another IRA within a 60-day window. It’s important to follow IRS regulations to avoid taxes or penalties from improper rollovers.
What is a trustee?
A trustee is the financial institution that holds your IRA. Understanding how your trustee operates is essential for a smooth transfer process.
Why is it important to understand IRA transfer concepts?
Understanding IRA transfer concepts is vital because a significant percentage of families have retirement accounts. Familiarity with these terms helps you navigate the transfer process confidently and make informed decisions about your retirement savings.
What are the potential consequences of not properly executing a rollover?
If a rollover is not executed properly, it can lead to tax penalties. Therefore, it’s crucial to follow IRS regulations during the rollover process.
How can financial advisors assist in the IRA transfer process?
Financial advisors can provide guidance on understanding IRA transfer concepts, help you avoid potential tax penalties, and assist you in seizing valuable investment opportunities during the transfer.
List of Sources
- Understand IRA Transfers: Key Concepts and Terminology
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- This is the ‘billion-dollar blind spot’ of 401(k)-to-IRA rollovers, Vanguard finds (https://cnbc.com/2024/09/16/401k-ira-retirement-rollovers-cash-investments.html)
- IRA Ownership Reaches Record Highs (https://ici.org/25-view-ira-ownership-reaches-record-highs)
- Traditional, Roth, and Rollover Individual Retirement Account (IRA) Ownership in 2022 (https://congress.gov/crs-product/R48456)
- IRA Use Has Risen 10% Over Past Decade, ICI Study Finds (https://401kspecialistmag.com/ira-use-up-10-in-past-decade-study)
- Initiate the Transfer: Steps to Move Your IRA
- How to Transfer an IRA from One Institution to Another (https://carboncollective.co/sustainable-investing/how-to-transfer-an-ira-from-one-institution-to-another)
- 3 Ways to Transfer an IRA from One Bank to Another – wikiHow (https://wikihow.com/Transfer-an-IRA-from-One-Bank-to-Another)
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- How long do transfers from my current custodian take for my IRA? (https://learn.rocketdollar.com/hc/en-us/articles/4403919965843-How-long-do-transfers-from-my-current-custodian-take-for-my-IRA)
- Navigate Challenges: Common Issues and Solutions in IRA Transfers
- Common IRA Rollover Mistakes (https://investopedia.com/articles/retirement/06/rollovermistakes.asp)
- IRA Rollovers and Contributions: Key Retirement Trends | PLANADVISER (https://planadviser.com/traditional-iras-destination-rollover-dollars-roth-iras-conversions-contributions)
- Recent IRA Statistics – Greenleaf Trust (https://greenleaftrust.com/missives/recent-ira-statistics)
- Stuck In The Past: Why 401(k) Rollovers Remain Outdated and Painful – Capitalize (https://hicapitalize.com/resources/why-401k-rollovers-remain-outdated-white-paper)
- Most of the Money in IRAs Comes from a Surprising Source (https://kiplinger.com/retirement/iras/most-money-in-iras-comes-from-a-surprising-source)
- Manage Your New IRA: Post-Transfer Best Practices
- Retirement Account Statistics 2024 – NerdWallet (https://nerdwallet.com/article/investing/retirement-statistics)
- Tony Robbins’ Top 9 Tips For Investing Success | Bankrate (https://bankrate.com/investing/tony-robbins-top-investing-tips)
- SOI Tax Stats Accumulation and Distribution of Individual Retirement Arrangements | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-accumulation-and-distribution-of-individual-retirement-arrangements)
- None (https://fa.wellsfargoadvisors.com/todd-perry/Eight-Great-Investing-Quotes.c10271.htm)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Retirement & Employee Benefits for high-income W-2 families at Bright Advisers.
Keep reading