

Overview
To help families reduce their Modified Adjusted Gross Income (MAGI), it’s essential to maximize contributions to retirement accounts and Health Savings Accounts (HSAs). Imagine if you could utilize tax-loss harvesting and ensure you claim all available deductions. This article shares specific strategies and relatable examples that illustrate how these actions can effectively lower MAGI. By doing so, you can enhance your eligibility for valuable tax credits and improve your overall financial planning. Together, we can navigate this journey toward a more secure financial future.
Key Highlights:
- MAGI is calculated by starting with Adjusted Gross Income (AGI) and adding back specific deductions like student loan interest and IRA contributions.
- MAGI affects eligibility for tax credits, such as the Child Tax Credit, which begins to diminish at $200,000 AGI for individuals.
- Families can reduce MAGI by maximizing contributions to retirement accounts and Health Savings Accounts (HSAs), which are tax-deductible.
- Tax-loss harvesting can help offset capital gains and lower overall taxable income.
- It’s essential to maximize available deductions, including education expenses and mortgage interest, to reduce MAGI effectively.
- Common challenges in reducing MAGI include confusion over deductions, inadequate contributions, and missed deadlines, which can be addressed with professional guidance.
- Proactive financial planning and regular evaluation of income can help families manage their MAGI and optimize tax benefits.
Introduction
Navigating the complexities of Modified Adjusted Gross Income (MAGI) can feel overwhelming, especially for families striving to optimize their tax benefits. Imagine if you could unlock the financial opportunities that lie within understanding MAGI. This crucial benchmark determines eligibility for various tax credits and deductions, significantly impacting your financial planning decisions. As families with young children work to secure their financial futures, grasping the concept of MAGI becomes essential.
It’s important to understand that calculating this vital figure involves a careful examination of income sources, allowable deductions, and potential add-backs. This article delves into the intricacies of MAGI, offering insights and practical steps to empower families like yours in maximizing financial benefits while navigating the tax landscape. Together, we can navigate this journey, ensuring that your family’s financial well-being is prioritized.
Understand Modified Adjusted Gross Income (MAGI)
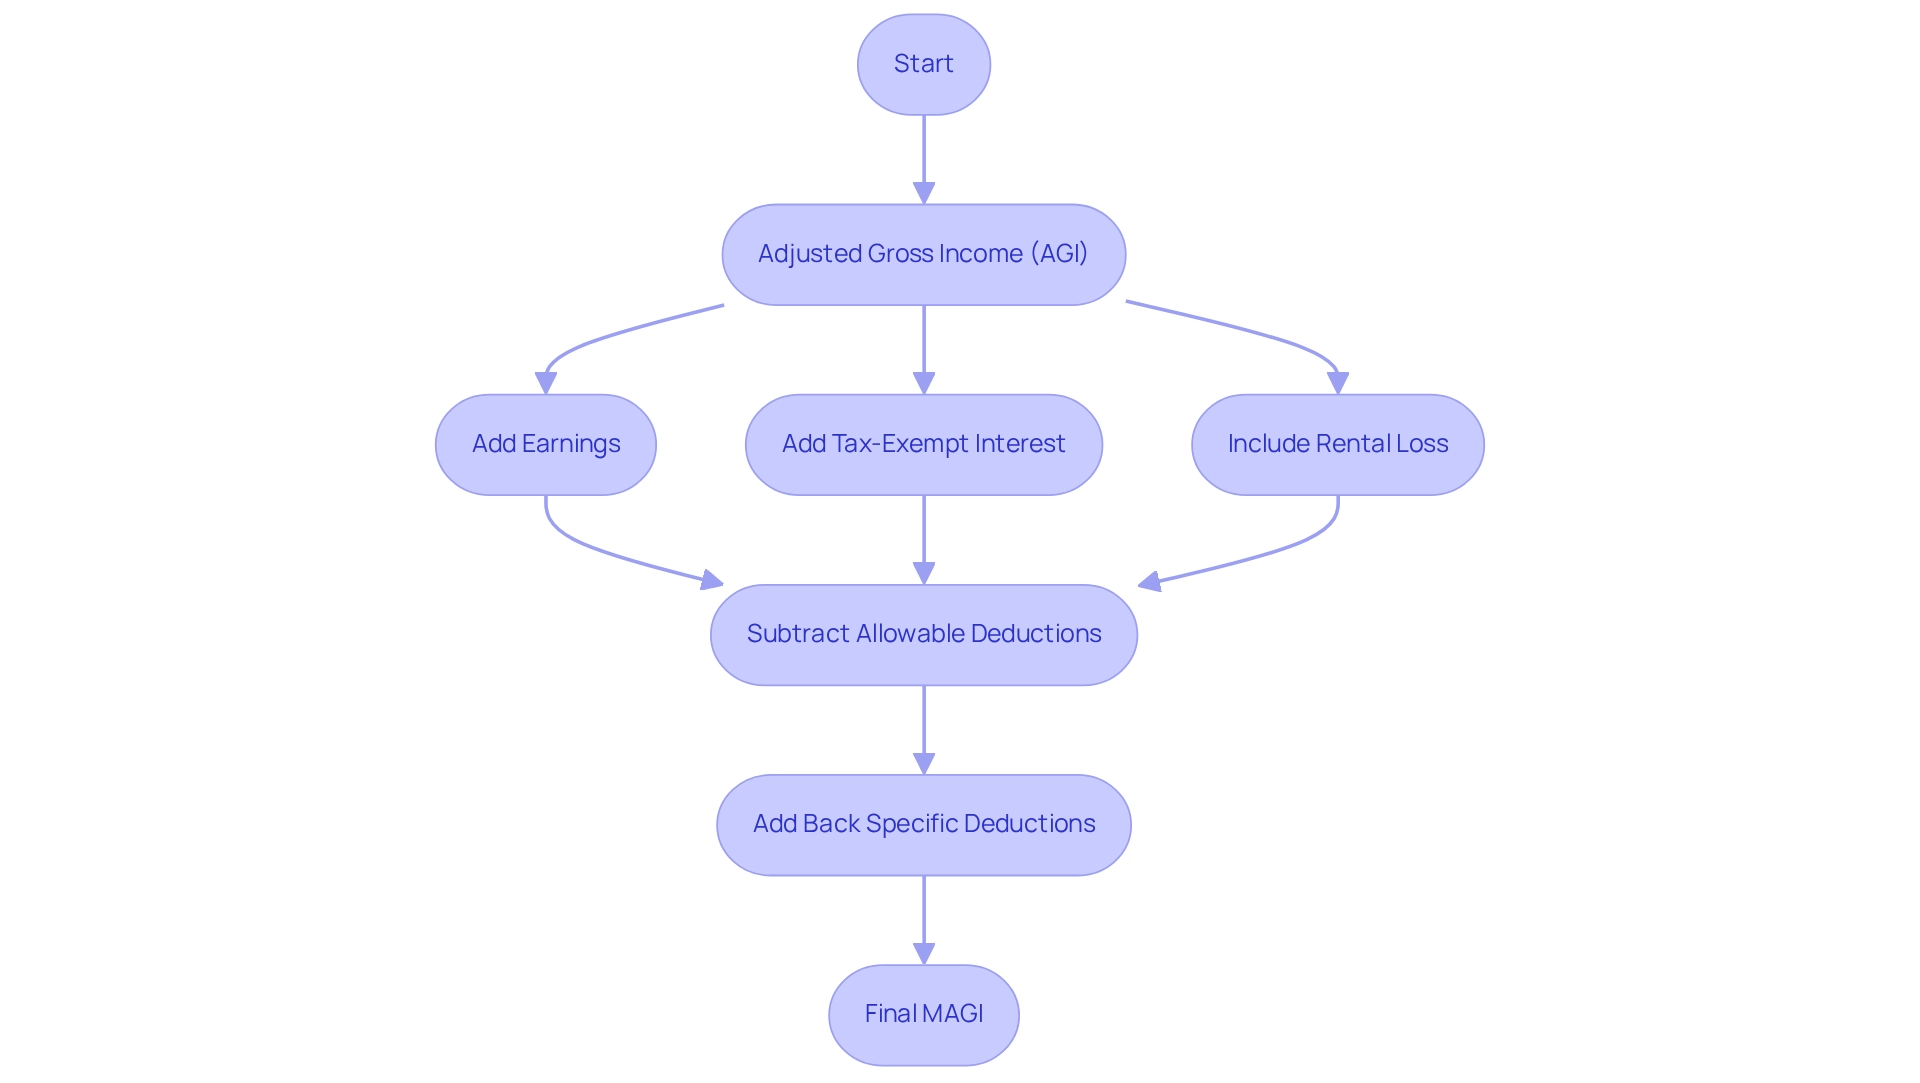
Understanding how to reduce modified adjusted gross income is vital for families navigating the complexities of tax benefits, including essential deductions and credits that can make a significant difference in their financial well-being. To calculate MAGI, begin with your Adjusted Gross Income (AGI)—this encompasses your earnings, tips, wages, taxable interest, dividends, unemployment benefits, and taxable retirement distributions. From your total income, subtract allowable deductions to determine your AGI, and then add back specific deductions, such as student loan interest and IRA contributions, as outlined by the IRS.
Imagine the impact of MAGI on families with young children. It directly influences financial planning decisions and eligibility for tax credits that can greatly support education and healthcare. For example, consider Genevieve. With an AGI of $85,000, she also has $10,000 in tax-exempt interest income and a $3,000 rental loss. After factoring in these elements, her MAGI reaches $98,000, surpassing the threshold for Medicare premium surcharges, which results in higher expenses.
Tax experts emphasize the importance of understanding how to reduce modified adjusted gross income and its implications. As Ines Zemelman, EA and founder of TFX, shares, “Understanding Modified Adjusted Gross Income is crucial for households to manage their tax advantages efficiently, particularly in maximizing credits that can assist their children’s future.” Seeking guidance from a tax consultant can provide personalized support on how to reduce modified adjusted gross income and understand its influence on tax strategies, helping families optimize their benefits.
At Bright Advisers, we are dedicated to empowering young families with tailored wealth management solutions. We provide guidance on how to reduce modified adjusted gross income while also enhancing effective tax planning strategies. By fully comprehending this concept, families can make informed decisions that align with their financial goals, ultimately securing a brighter future for their children. Plus, our commitment to minimizing fund fees ensures families can effectively manage their overall financial health.
Calculate Your MAGI Step-by-Step
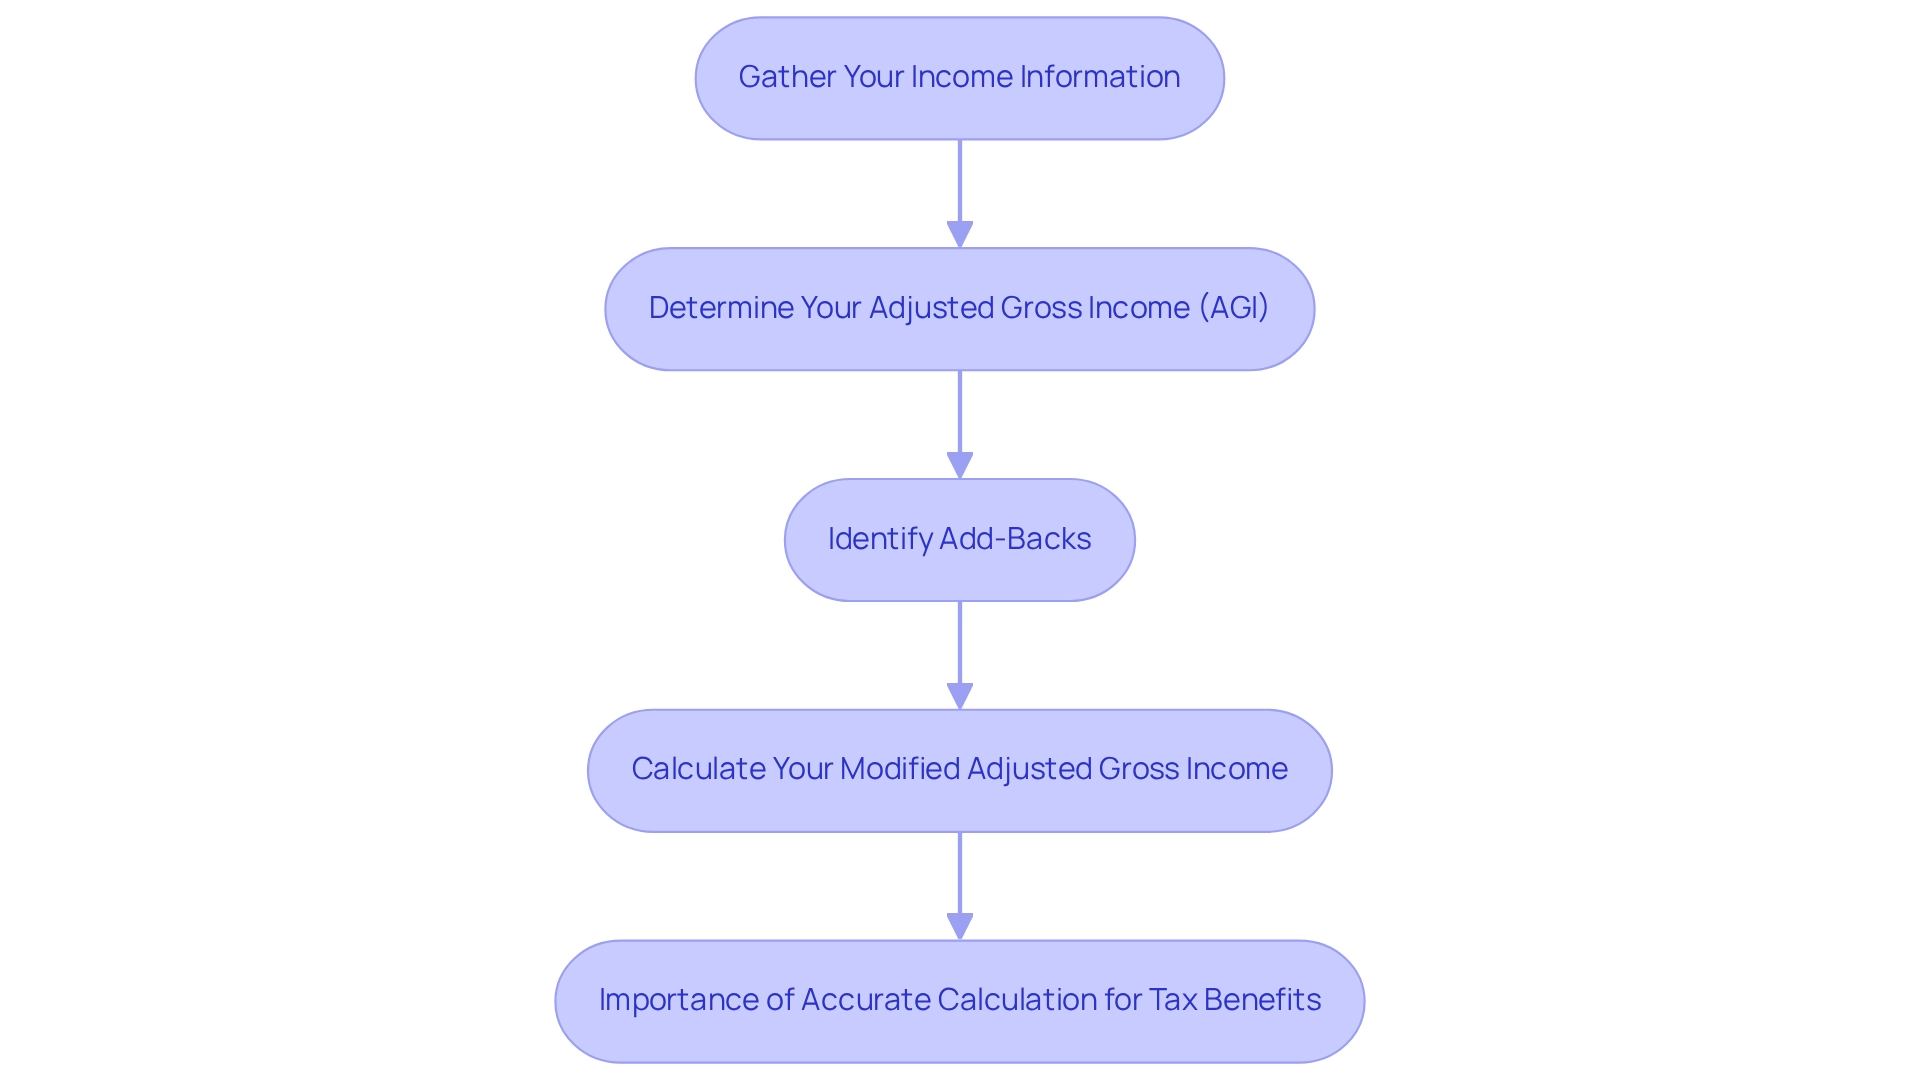
Calculating your Modified Adjusted Gross Income (MAGI) can feel daunting, but learning how to reduce modified adjusted gross income with a few simple steps can help you navigate this process with confidence. Let’s break it down together:
- Gather Your Income Information: Start by compiling all your sources of income, including wages, dividends, and any other taxable earnings. This is the foundation of your financial picture.
- Determine Your Adjusted Gross Income (AGI): Look at IRS Form 1040 to find your AGI, which is your total income minus specific deductions. You can typically find this figure on line 11 of the form. Understanding your AGI is crucial.
- Identify Add-Backs: It’s important to consult IRS guidelines to pinpoint which deductions must be added back to your AGI for the MAGI calculation. Common add-backs include:
- Traditional IRA contributions
- Student loan interest
- Foreign earned income exclusions
- Calculate Your Modified Adjusted Gross Income: Now, simply add the identified deductions back to your AGI. For instance, if your AGI is $80,000 and you have $5,000 in IRA contributions, your modified adjusted gross income would be $85,000.
By following these steps, you can learn how to reduce modified adjusted gross income, which is vital for accurately calculating your MAGI and understanding your eligibility for tax credits and deductions, including the Child Tax Credit (CTC). Remember, the CTC begins to diminish at an AGI of $200,000 for individual filers and fully diminishes at $400,000. For married couples filing together, it starts to decrease at $480,000 and completely reduces at $480,000.
As Mark Steber, Senior Vice President and Chief Tax Officer for Jackson Hewitt, wisely points out, “A Jackson Hewitt Tax Pro can provide tailored guidance and help to ensure you get every dollar you deserve.” This highlights just how crucial it is to calculate your income accurately, allowing you to maximize your tax advantages.
Together, we can navigate this journey, ensuring that you feel supported every step of the way.
Implement Strategies to Reduce Your MAGI
To effectively reduce your MAGI, consider the following compassionate strategies, successfully implemented by clients like Allison and Brian with the guidance of Bright Advisers:
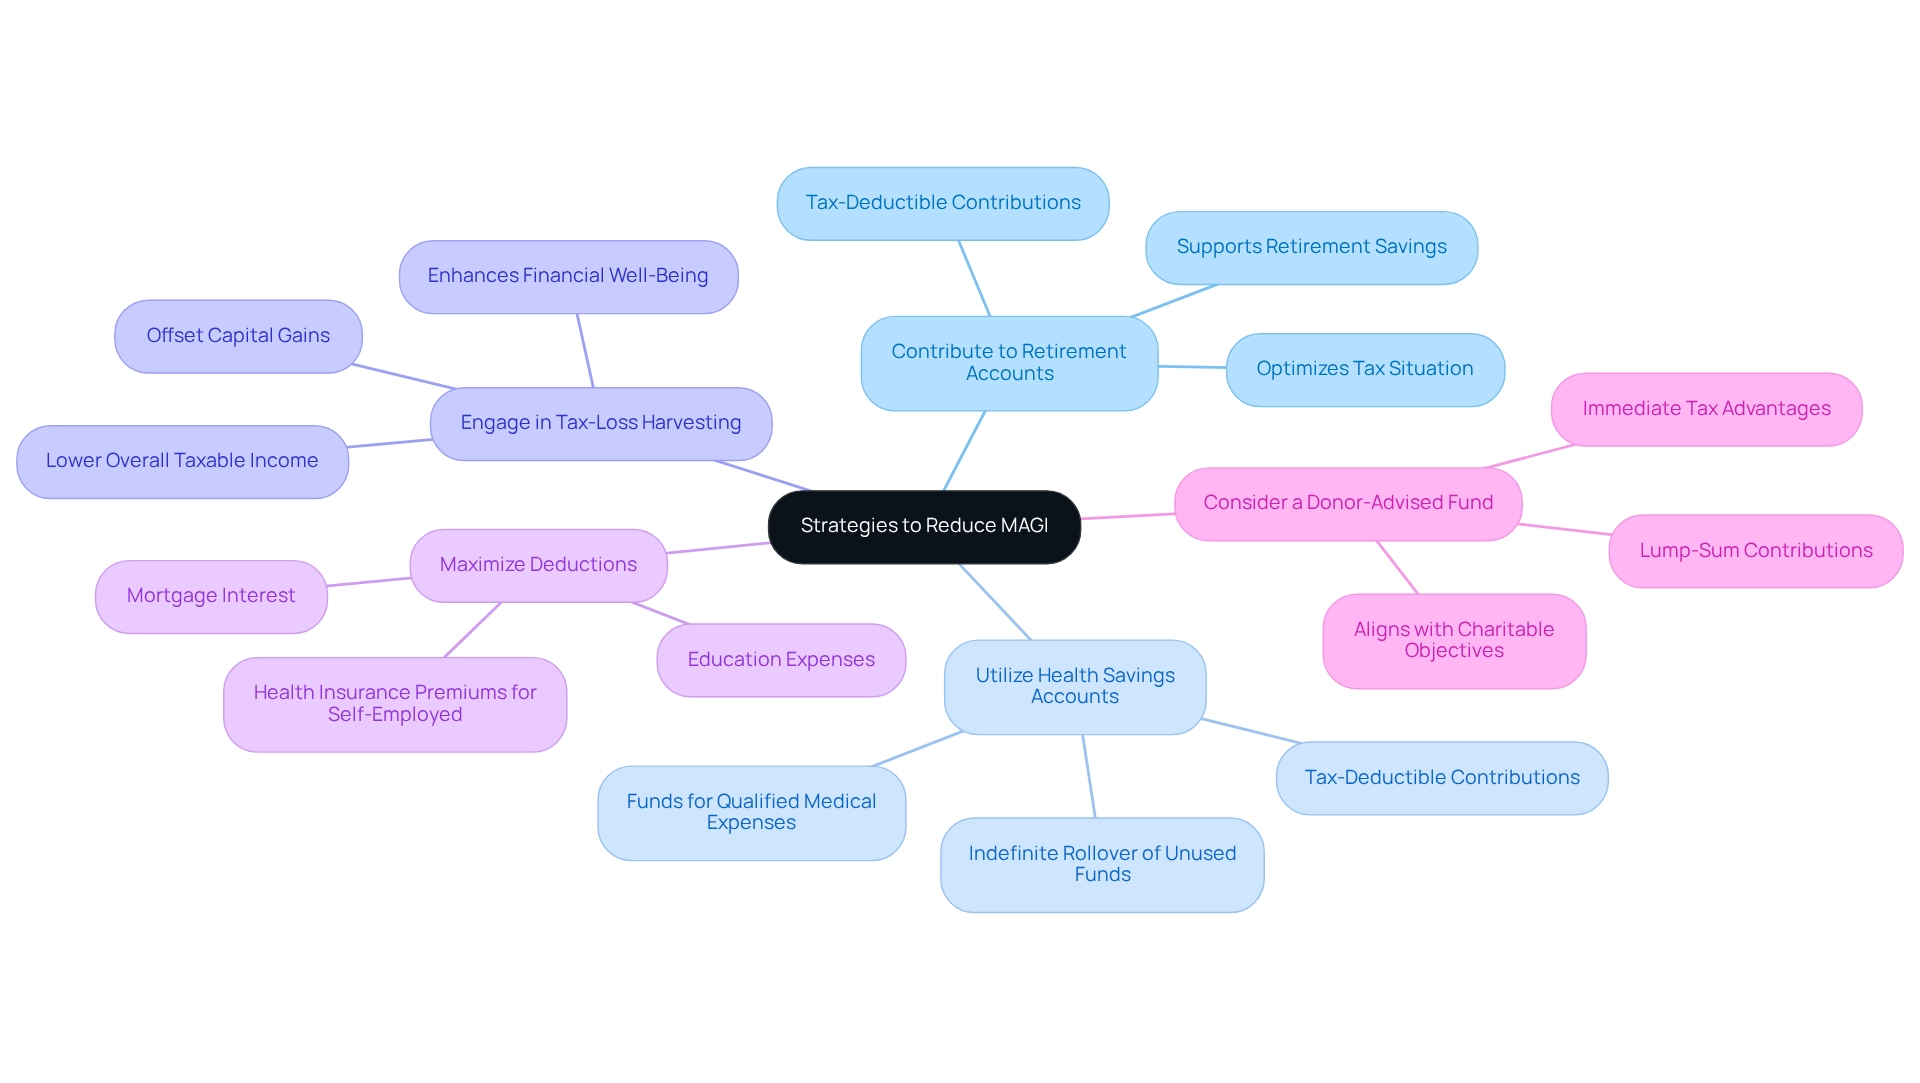
- Contribute to Retirement Accounts: Imagine maximizing your contributions to tax-advantaged retirement accounts such as 401(k)s and IRAs. These contributions are often tax-deductible, which can help to reduce modified adjusted gross income and, consequently, your AGI. Not only do these contributions support your retirement savings, but they also play a crucial role in your family’s tax planning. Allison and Brian optimized their tax situation through thoughtful contributions, resulting in a significant reduction in their taxable income.
- Utilize Health Savings Accounts (HSAs): If eligible, consider contributing to an HSA. Contributions to HSAs are tax-deductible and can help demonstrate how to reduce modified adjusted gross income while providing funds for qualified medical expenses. HSAs offer the unique advantage of allowing unused funds to roll over indefinitely, providing flexibility for future healthcare costs. A case study titled ‘Utilizing Health Savings Accounts (HSA) to Reduce MAGI’ discusses the benefits of HSAs, showcasing their tax advantages and flexibility for healthcare expenses, while also illustrating how Allison and Brian discovered how to reduce modified adjusted gross income through HSA contributions.
- Engage in Tax-Loss Harvesting: If you have investments, think about selling underperforming assets to offset capital gains. This practical approach can help lower your overall taxable income, making it an effective strategy for families looking to optimize their tax situation. Allison and Brian enhanced their financial well-being by implementing this strategy, which contributed to their overall tax efficiency.
- Maximize Deductions: It’s important to ensure you are taking advantage of all available deductions, including those for education expenses and mortgage interest. Reviewing IRS guidelines can help identify any deductions you may have overlooked, potentially leading to significant tax savings. Additionally, health insurance premiums paid for self-employed individuals can be deducted, directly reducing taxable income. Allison and Brian benefited from maximizing their deductions, contributing to their overall economic security and allowing them to save thousands in taxes.
- Consider a donor-advised fund: If charitable giving is part of your financial strategy, contributing to a donor-advised fund can enable you to make a lump-sum contribution that shows how to reduce modified adjusted gross income in the year of the donation. This approach not only aligns with your charitable objectives but also offers immediate tax advantages, resonating with the principles of families like Allison and Brian, who value both economic and social responsibility.
Implementing these strategies is an effective way to learn how to reduce modified adjusted gross income, enhancing your eligibility for various tax benefits and credits. As highlighted by tax specialists, “It’s computed using your AGI and the particular add-backs pertinent to the tax benefit you’re pursuing,” underscoring the significance of strategic planning in achieving your financial goals. Bright Advisers stands as a compassionate leader in wealth management for households with young children, making these strategies especially relevant for your financial planning.
Troubleshoot Common Issues in Reducing MAGI
Understanding how to reduce modified adjusted gross income can present several challenges, but you’re not alone in this journey. Here’s how to effectively troubleshoot these common issues:
-
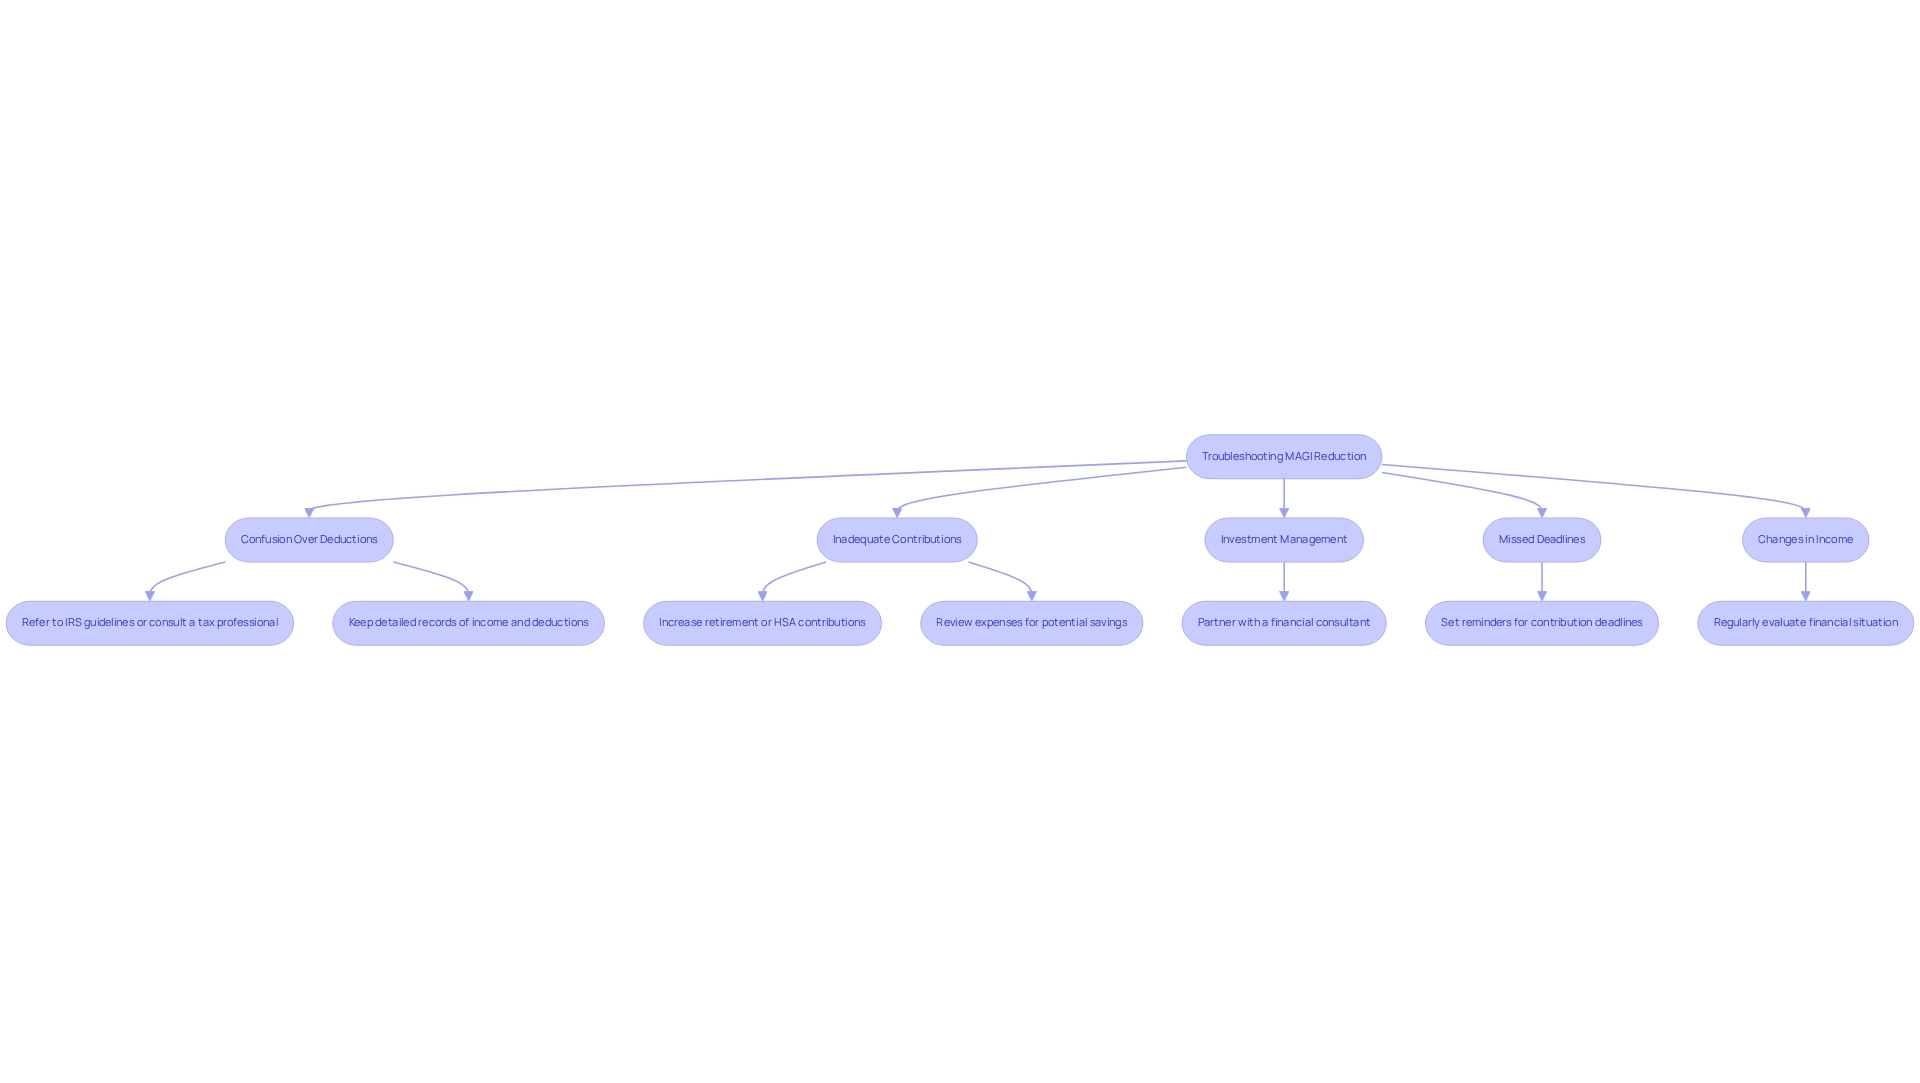
Confusion Over Deductions: Many households find themselves puzzled about which deductions to add back to their AGI. In fact, statistics reveal that 39.3% of West Virginia parents at the 90th percentile experience confusion related to income deductions. To clarify your situation, it’s important to refer to IRS guidelines or consult a tax professional. Keeping detailed records of your income and deductions can also provide clarity. Remember, understanding these deductions is a crucial part of a comprehensive financial strategy tailored to your family’s unique needs, helping you create a sustainable monetary plan.
-
Inadequate Contributions: If your retirement or Health Savings Account (HSA) contributions aren’t enough to significantly lower your MAGI, consider increasing them if your budget allows. Take a moment to review your expenses and identify areas where you can allocate a little more. For instance, Emily and Mark found that enhancing their contributions gave them the freedom to make career decisions based on their personal ambitions rather than financial constraints.
-
Investment Management: Navigating tax-loss harvesting can feel overwhelming, especially with multiple investments. Partnering with a financial consultant can help you craft a personalized plan that maximizes your tax advantages. Bright Advisers’ approach to customized wealth management ensures that families like Jay and Emma can effectively manage their investments while balancing growth potential and risk control, utilizing technology for tailored planning.
-
Missed Deadlines: It’s crucial to stay aware of contribution deadlines for retirement accounts and HSAs. Setting reminders can help you avoid missing these important dates, ensuring you maximize your contributions. Bright Advisers encourages proactive planning to assist families in staying on track with their financial goals.
-
Changes in Income: Significant fluctuations in income can affect your MAGI calculations. Regularly evaluating your financial situation allows you to adjust your strategies as needed, helping you stay on course. With the support of Bright Advisers, families can navigate these changes successfully, ensuring economic stability and peace of mind.
By proactively addressing these issues, you can streamline your efforts in learning how to reduce modified adjusted gross income and enhance your overall financial planning. As Mark Annese wisely stated, “Automated calculation of IRMAA costs is the next step in streamlining this process even further,” underscoring the importance of clear strategies and expert guidance in navigating these complexities. Remember, we’re here for you, and together, we can navigate this journey.
Conclusion
Understanding Modified Adjusted Gross Income (MAGI) is essential for families aiming to optimize their tax benefits and secure their financial futures. Imagine if you could unlock significant savings just by understanding this concept better. This article has outlined the importance of MAGI in determining eligibility for various tax credits and deductions, emphasizing its direct impact on your financial planning decisions. By calculating MAGI accurately, families can access valuable resources, particularly for children’s education and healthcare.
The step-by-step guide provided illustrates how to calculate MAGI, highlighting the significance of income sources, allowable deductions, and necessary add-backs. It’s important to understand that practical strategies can effectively reduce MAGI, such as:
- Maximizing contributions to retirement and health savings accounts
- Engaging in tax-loss harvesting
- Capitalizing on available deductions
These approaches empower families to enhance their financial well-being while navigating the complexities of tax regulations.
Addressing common challenges in reducing MAGI reinforces the need for clarity and proactive planning. By consulting tax professionals and maintaining organized financial records, families can troubleshoot potential issues that may arise during the process. Together, we can navigate this journey toward financial stability. Ultimately, a comprehensive understanding of MAGI and strategic financial planning can lead to improved eligibility for tax credits and a more secure financial future for families. Embracing these insights not only enhances financial literacy but also paves the way for smarter financial decisions that prioritize long-term stability and growth. We’re here for you, and with the right knowledge and support, you can confidently take steps toward a brighter financial future.
Frequently Asked Questions
What is modified adjusted gross income (MAGI)?
Modified adjusted gross income (MAGI) is a calculation used to determine eligibility for various tax benefits, including deductions and credits that can significantly impact financial well-being.
How do you calculate MAGI?
To calculate MAGI, start with your Adjusted Gross Income (AGI), which includes earnings, tips, wages, taxable interest, dividends, unemployment benefits, and taxable retirement distributions. Subtract allowable deductions to determine your AGI, then add back specific deductions such as student loan interest and IRA contributions.
Why is understanding MAGI important for families?
Understanding MAGI is crucial for families as it influences financial planning decisions and eligibility for tax credits, particularly those that support education and healthcare, which can greatly benefit families with young children.
Can you provide an example of how MAGI affects tax expenses?
For instance, if Genevieve has an AGI of $85,000, $10,000 in tax-exempt interest income, and a $3,000 rental loss, her MAGI would be $98,000. This amount exceeds the threshold for Medicare premium surcharges, leading to higher expenses.
How can families reduce their modified adjusted gross income?
Families can seek guidance from tax consultants who can provide personalized support on strategies to reduce MAGI and understand its implications on tax strategies, helping optimize tax benefits.
What services does Bright Advisers offer regarding MAGI and tax planning?
Bright Advisers offers tailored wealth management solutions, including guidance on reducing modified adjusted gross income and enhancing effective tax planning strategies to help families align their financial goals and secure a better future for their children.
List of Sources
- Understand Modified Adjusted Gross Income (MAGI)
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- What is MAGI or modified adjusted gross income? | healthinsurance.org (https://healthinsurance.org/glossary/modified-adjusted-gross-income-magi)
- What Is Modified Adjusted Gross Income (MAGI)? (https://smartasset.com/taxes/what-is-modified-adjusted-gross-income)
- What is modified adjusted gross income (MAGI)? | USInsuranceAgents.com (https://usinsuranceagents.com/what-is-modified-adjusted-gross-income-magi)
- Calculate Your MAGI Step-by-Step
- Modified adjusted gross income (MAGI): How to calculate MAGI (https://jacksonhewitt.com/tax-help/tax-tips-topics/filing-your-taxes/magi-modified-adjusted-gross-income)
- Modified adjusted gross income (AGI): What it is & how to calculate | Fidelity (https://fidelity.com/learning-center/personal-finance/magi-modified-adjusted-gross-income)
- Implement Strategies to Reduce Your MAGI
- What is Modified Adjusted Gross Income (MAGI) and how to calculate it? (https://taxesforexpats.com/articles/financial-planning/modified-adjusted-gross-income-magi.html)
- Effective Strategies: How to Reduce MAGI for High Earners and Lower Premiums – IRMAA Certified Planner (https://irmaacertifiedplanner.com/how-to-reduce-magi)
- Troubleshoot Common Issues in Reducing MAGI
- Modified Adjusted Gross Income (MAGI) Income Conversion Methodologies (https://aspe.hhs.gov/reports/modified-adjusted-gross-income-magi-income-conversion-methodologies-0)
- SOI tax stats – Individual statistical tables by size of adjusted gross income | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-individual-statistical-tables-by-size-of-adjusted-gross-income)
- MAGI Explained: How Modified Adjusted Gross Income Works | Facet (https://facet.com/financial-planning/modified-adjusted-gross-income-magi-what-it-is-how-to-calculate)
- Effective Strategies: How to Reduce MAGI for High Earners and Lower Premiums – IRMAA Certified Planner (https://irmaacertifiedplanner.com/how-to-reduce-magi)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading