

Overview
Understanding whether your Employee Stock Purchase Plan (ESPP) is pre-tax can feel overwhelming, but we’re here to help simplify it for you. Start by checking if your plan aligns with Section 423 of the Internal Revenue Code. Most contributions are typically made with after-tax dollars, so it’s important to know where you stand.
Imagine if you could navigate these complexities with confidence. Reviewing your ESPP documents can illuminate potential options you might have, including any pre-tax benefits. It’s crucial to consult a financial advisor who can guide you through these choices and their implications on your overall tax strategy.
By taking these steps, you can maximize the benefits of your participation in the plan, ensuring that your family’s financial future is secure. Remember, together, we can navigate this journey and make informed decisions that resonate with your family’s values and priorities.
Key Highlights:
- ESPPs allow employees to purchase company shares at a discounted price, typically 5% to 15% off market value.
- Understanding key terms like ‘offering period’ and ‘purchase price’ is crucial for effective participation in ESPPs.
- Companies with strong ESPPs experience a 3.2 times higher employee retention rate.
- Contributions to ESPPs are generally made with after-tax dollars, but some plans may offer pre-tax options.
- Effective communication and education about ESPPs can enhance employee participation and investment outcomes.
- Most ESPPs include a lookback provision, allowing for discounts based on lower stock prices from the past.
- Consulting with a financial advisor can help employees optimize their ESPP strategies and align them with financial goals.
- Holding shares for at least a year may result in returns up to 30% higher than initial investments.
Introduction
Navigating the world of Employee Stock Purchase Plans (ESPPs) can feel both rewarding and overwhelming. These company-sponsored programs offer you the chance to purchase shares at a discounted rate, creating a unique investment opportunity that can lead to significant financial benefits for your family.
However, understanding the intricacies of ESPPs—including eligibility criteria, tax implications, and strategic selling—can be daunting. Imagine if you had the right knowledge and guidance; you could maximize your participation in these plans, fostering not only personal financial growth but also a deeper loyalty to your employer.
This article delves into the essential components of ESPPs, highlighting the importance of education, strategic planning, and the value of professional financial advice. Together, we can unlock the full potential of these investment opportunities, ensuring a brighter financial future for you and your loved ones.
Understand the Basics of Employee Stock Purchase Plans (ESPPs)
Imagine a program designed just for you, where you can invest in your future while supporting your family’s needs. A worker stock acquisition plan is a company-backed initiative that allows employees to purchase shares of their employer’s equity at a reduced price, typically through convenient payroll deductions. With discounts ranging from 5% to 15% off the market price, this could be a valuable opportunity for you to grow your family’s wealth, particularly by understanding whether is espp pre tax to maximize its benefits. Familiarizing yourself with the enrollment process and purchase periods can empower you to take full advantage of this opportunity. Key terms like ‘offering period’—the timeframe during which you can acquire stocks—and ‘purchase price’—the cost at which stocks are obtained—are essential for navigating your plan effectively. For instance, if your company offers a 15% discount and the stock price is $100, you can purchase shares for just $85, providing immediate value to your investment.
Moreover, companies with robust stock purchase plans enjoy a remarkable 3.2 times greater retention rate among employees. This highlights how these programs not only benefit individual investors but also foster loyalty and engagement within the workforce. Participating in an ESPP is espp pre tax and can be a step towards securing your family’s future. Additionally, it’s reassuring to note that only 10% of firms with a qualified employee stock purchase plan impose a mandatory holding period, allowing you greater flexibility in managing your investments. By informing staff about the advantages of ESPPs, including potential discounts and contribution matches, companies can significantly enhance participation.
A case study titled ‘Understanding of Employee Stock Purchase Plan Benefits’ reveals that many employees may not fully recognize the value of such plans, especially regarding the concept of a discount. This lack of understanding can hinder participation. By improving education around these plans, companies can help their employees engage more fully and maximize their investment outcomes.
Together, we can navigate this journey towards financial stability and growth for you and your family. We’re here for you, supporting you every step of the way.
Identify Pre-Tax Eligibility Criteria for Your ESPP
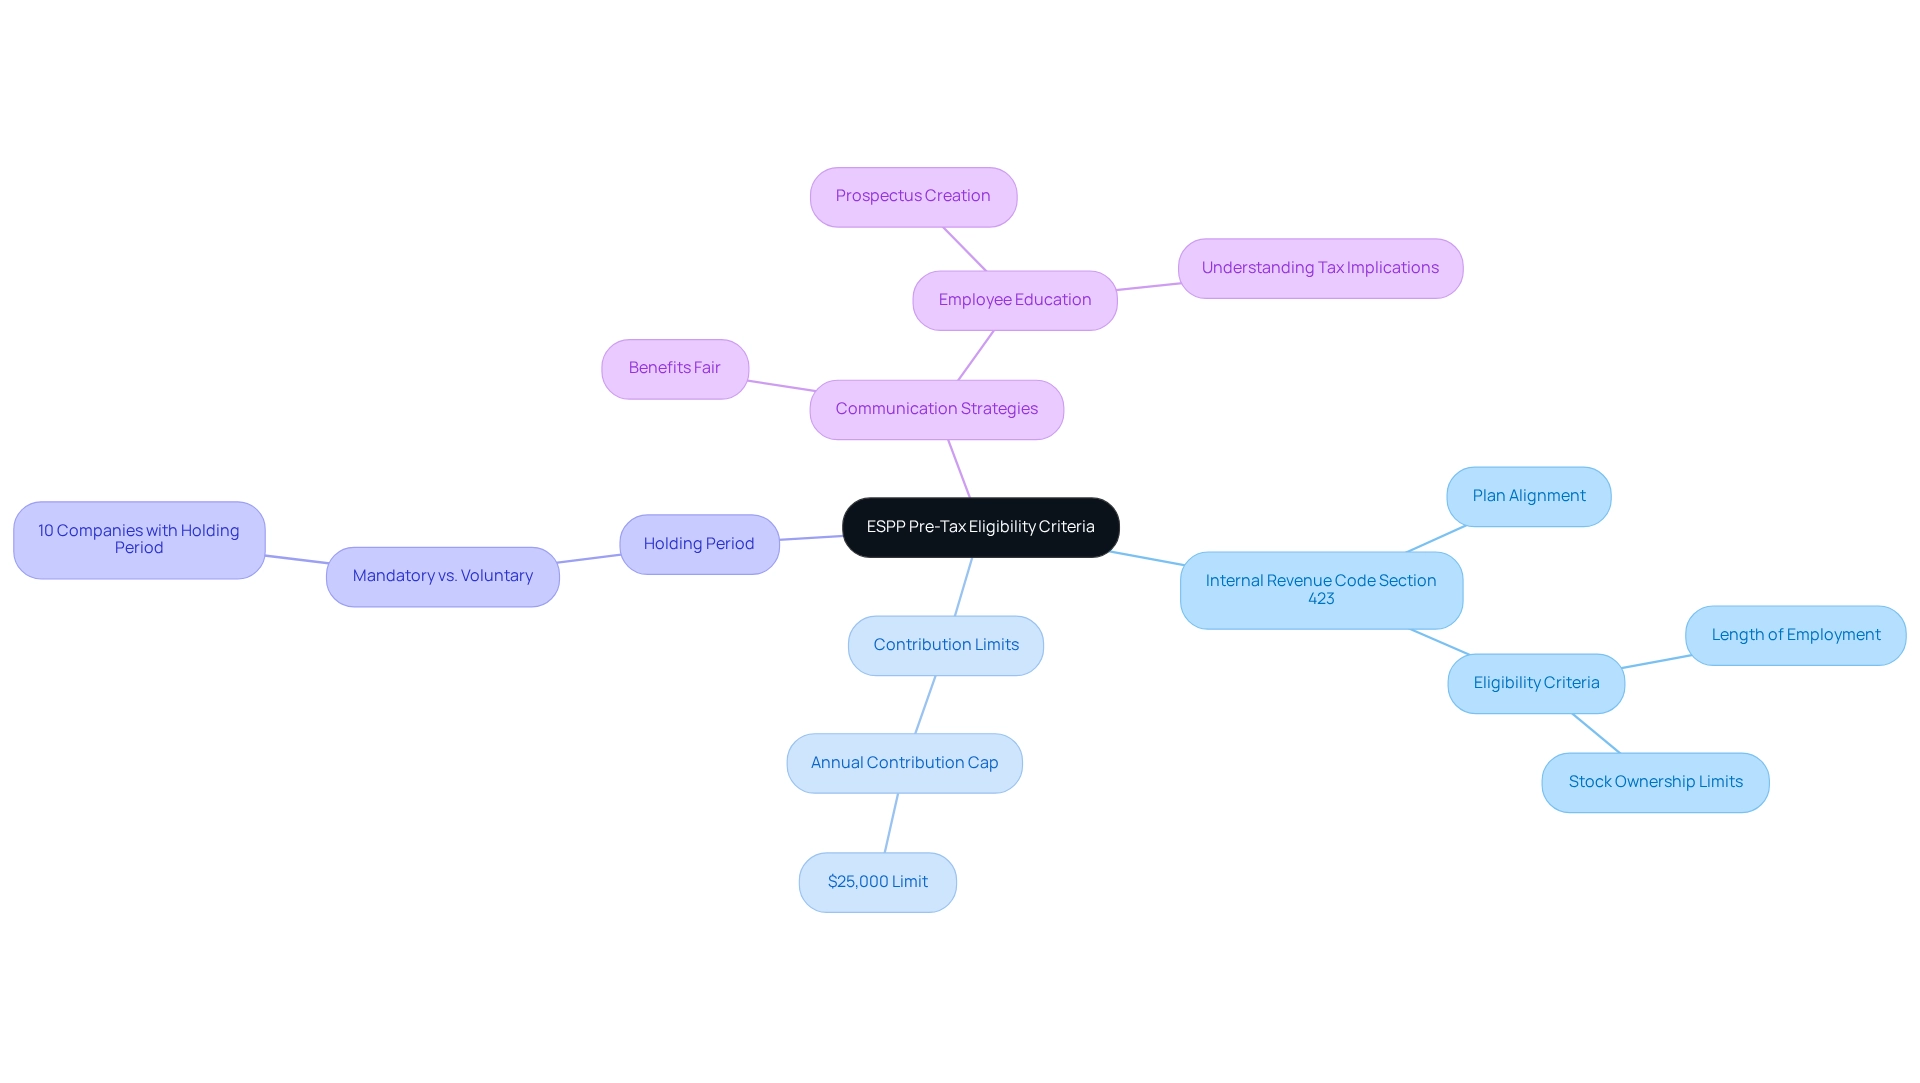
To understand if your contributions to the ESPP is espp pre tax, it’s important to first check if your plan aligns with Section 423 of the Internal Revenue Code. Typically, contributions to ESPPs are made with after-tax dollars, which means they come from your paycheck after taxes are deducted. However, some plans may offer options that is espp pre tax, so it’s worth investigating your company’s specific eligibility criteria. This can include factors like your length of employment and any stock ownership limits.
Imagine if your employer allows contributions up to $25,000 annually under a qualified plan. Understanding how this affects your taxable income is crucial for your financial planning. Significantly, only about 10% of firms with eligible ESPPs require a holding period, suggesting that many employees choose to keep their shares, which can influence tax implications.
We believe that effective communication and education about these plans can greatly improve participation rates. Hosting a benefits fair can provide a wonderful opportunity for employees to discuss plan details one-on-one and learn about ESPPs in the context of their overall benefits. As Robert W. Wood highlights, understanding the classification of workers can also clarify the complexities surrounding ESPPs.
For instance, if you decide to wait until January 2, 2026, and the price remains at $15, you would pay $1.50 of ordinary income per unit. This example illustrates the financial impact of your contributions. Remember, we’re here for you as you navigate these decisions, ensuring you have the support needed to make informed choices for your family’s future.
Review Your ESPP Plan Documents for Tax Implications
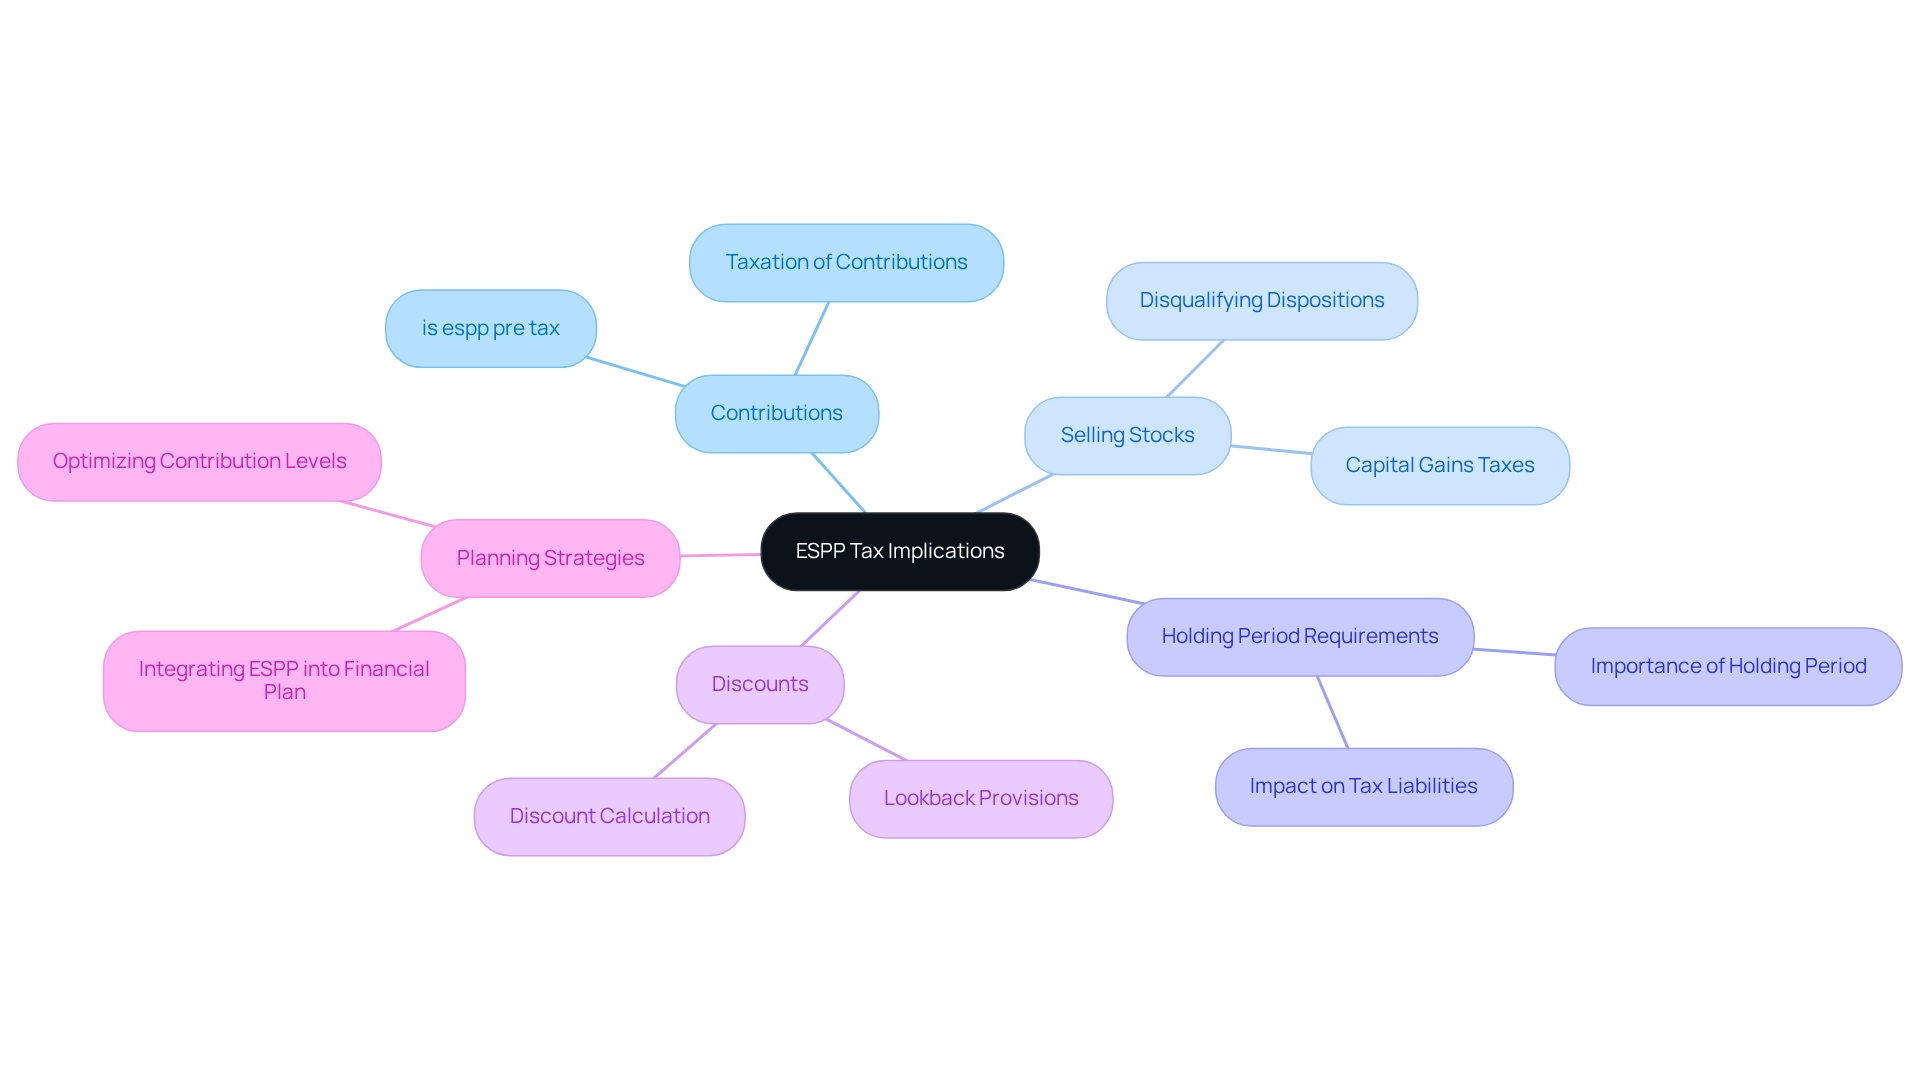
Understanding your employee stock purchase plan documents is essential for grasping whether is espp pre tax affects the tax implications of your participation. These documents typically outline how your contributions are taxed, how any discounts are handled, and whether the contributions related to is espp pre tax may affect the potential capital gains taxes that may apply when you sell your stocks.
Imagine if you were in a qualified ESPP; generally, when it comes to stock purchases, is espp pre tax, meaning you wouldn’t incur taxes at that time. However, it’s important to remember that you must report any gains upon sale, particularly because is espp pre tax, and it’s crucial to be aware of the holding period requirements. Selling shares too soon can lead to disqualifying dispositions, which may result in increased tax liabilities, particularly because is espp pre tax.
Notably, most ESPPs include a lookback provision, and it is espp pre tax, allowing discounts based on the lower of current or historical stock prices from 3-24 months ago. This can significantly impact your tax situation, particularly because is espp pre tax, and many employees are unaware of these tax implications, highlighting the need for careful review. Keeping a copy of your plan documents handy during tax season is important because is espp pre tax can help you navigate these complexities effectively.
Furthermore, incorporating strategies for an employee stock purchase plan, which is espp pre tax, into your overall monetary plan can enhance your economic circumstances. Through their collaboration with Bright Advisers, they discovered that is espp pre tax opportunities were being missed due to a lack of planning. Bright Advisers guided them in optimizing their contribution levels and timing their stock sales, as the strategy is espp pre tax to minimize tax liabilities.
This experience underscores the significance of aligning your monetary goals with your equity compensation choices, especially considering that is espp pre tax, ensuring that you maximize your potential. We’re here for you, ready to help you navigate this journey together.
Consult a Financial Advisor for Personalized Guidance
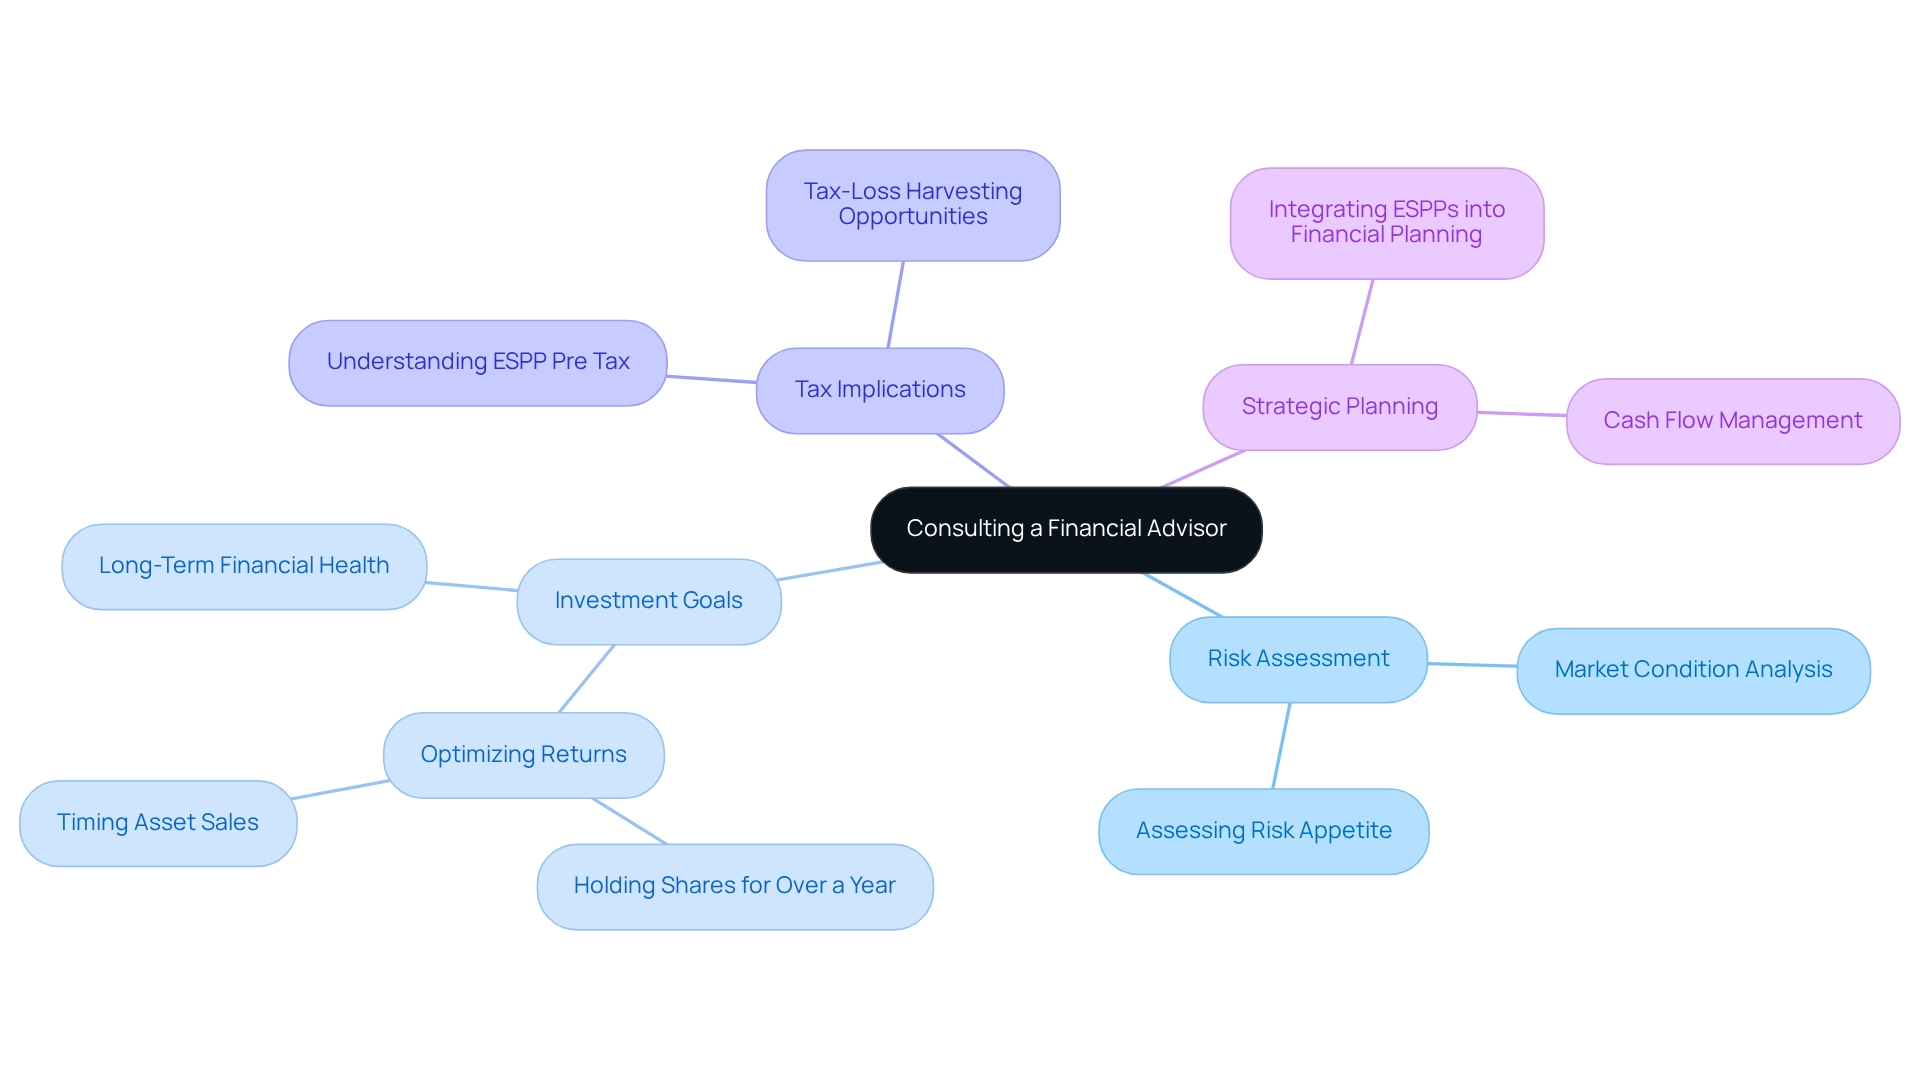
Interacting with a monetary consultant can significantly enhance your understanding of how your Employee Stock Purchase Program (ESPP) is espp pre tax and fits into your overall financial strategy. At Bright Advisers, our caring team of consultants is here to assess your risk appetite, investment goals, and tax implications. We want to ensure that your involvement in the stock purchase plan aligns with your family’s financial aspirations.
Imagine having a plan for selling your assets that takes into account market conditions and your family’s financial needs. If you anticipate a significant expense on the horizon, your advisor can help you determine the best timing to sell your ESPP holdings, optimizing your returns. Statistics show that employees who hold shares for at least a year may realize returns up to 30% higher than their initial investment. This highlights the importance of strategic planning, and our advisors are here to guide you through the complexities of market conditions to enhance your investment outcomes. Furthermore, understanding that is espp pre tax can significantly improve your financial planning and lead to better investment results.
Take, for example, Allison and Brian’s journey with Bright Advisers. They successfully optimized their tax situation through dynamic management of their investment strategy and tax-loss harvesting opportunities. By consulting a monetary advisor, you can ensure that your ESPP is espp pre tax, which not only contributes to your investment portfolio but also supports your family’s long-term financial health. This makes the role of financial advisors even more critical in this context. We’re here for you, ready to navigate this journey together and ensure your family’s financial future is secure.
Conclusion
Participating in an Employee Stock Purchase Plan (ESPP) opens up a wonderful opportunity for employees to invest in their company while enjoying significant discounts. It’s important to understand the details of these plans—like eligibility criteria, tax implications, and strategic selling—because they can greatly enhance the financial rewards for you and your family. By taking the time to learn about the mechanics of ESPPs, you can make informed decisions that not only strengthen your personal investments but also build a deeper connection with your employer.
The importance of professional guidance is something we truly believe in. Consulting with a financial advisor can provide personalized strategies that align with your individual financial goals, ensuring that your participation in an ESPP becomes an active part of a comprehensive financial plan. Advisors can help you navigate the complexities of tax implications, timing of sales, and market conditions, ultimately leading to better financial outcomes.
Imagine if engaging with ESPPs became a proactive step towards your family’s financial empowerment. By understanding the intricacies of these plans, leveraging professional advice, and making strategic decisions, you can unlock the full potential of your investment opportunities. This not only paves the way for personal financial growth but also strengthens loyalty and engagement within the workplace, contributing to a healthier financial future for you and your loved ones. Together, we can navigate this journey towards a brighter tomorrow.
Frequently Asked Questions
What is a worker stock acquisition plan?
A worker stock acquisition plan, also known as an employee stock purchase plan (ESPP), is a company-backed initiative that allows employees to purchase shares of their employer’s equity at a reduced price, typically through payroll deductions.
What discounts can employees expect from an ESPP?
Employees can expect discounts ranging from 5% to 15% off the market price when participating in an ESPP.
How does participating in an ESPP benefit employees financially?
By purchasing shares at a discounted price, employees can grow their family’s wealth. For example, if the stock price is $100 and the discount is 15%, employees can purchase shares for $85, providing immediate value.
What are key terms to understand when participating in an ESPP?
Key terms include ‘offering period,’ which is the timeframe during which stocks can be acquired, and ‘purchase price,’ which is the cost at which stocks are obtained.
How do ESPPs impact employee retention?
Companies with robust stock purchase plans enjoy a retention rate that is 3.2 times greater among employees, indicating that these programs foster loyalty and engagement.
Is participation in an ESPP pre-tax?
Yes, participating in an ESPP can be pre-tax, which can help maximize the benefits of the plan.
Are there any mandatory holding periods for ESPP shares?
Only 10% of firms with a qualified employee stock purchase plan impose a mandatory holding period, allowing greater flexibility in managing investments.
What can companies do to enhance participation in ESPPs?
Companies can inform staff about the advantages of ESPPs, including potential discounts and contribution matches, to significantly enhance participation.
Why do some employees not participate in ESPPs?
Many employees may not fully recognize the value of ESPPs, particularly the concept of a discount, which can hinder their participation. Improving education around these plans can help employees engage more fully.
List of Sources
- Understand the Basics of Employee Stock Purchase Plans (ESPPs)
- Stock Plans Increase Savings, Attract Millennials, Studies Show (https://shrm.org/topics-tools/news/benefits-compensation/stock-plans-increase-savings-attract-millennials-studies-show)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee Stock Purchase Plans (https://turbotax.intuit.com/tax-tips/investments-and-taxes/employee-stock-purchase-plans/L8NgMFpFX)
- Identify Pre-Tax Eligibility Criteria for Your ESPP
- An Overview of Qualified ESPPs (Employee Stock Purchase Plans) | Astra Wealth Partners (https://astrawp.com/an-overview-of-qualified-espps-employee-stock-purchase-plans)
- equiniti.com (https://equiniti.com/us/insights/eq-views/espps-at-a-glance-implementation-participation)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Code Sec. 423 | Tax Notes (https://taxnotes.com/lr/resolve/cq13)
- Review Your ESPP Plan Documents for Tax Implications
- Employee Stock Purchase Plans 101 | Plancorp (https://plancorp.com/employee-stock-purchase-plans-101)
- carta.com (https://carta.com/learn/equity/espp)
- ESPP Taxes Explained (https://kinetixfp.com/post/espp-taxes-explained)
- Consult a Financial Advisor for Personalized Guidance
- Maximize Wealth With Equity Compensation | Aspyre Wealth 1 (https://aspyrewealth.com/equity-compensation)
- The Long-term Payoff of Employee Ownership – FCLTGlobal (https://fcltglobal.org/resource/the-long-term-payoff-of-employee-ownership)
- Research (https://nceo.org/research)
- zajacgrp.com (https://zajacgrp.com/insights/7-things-to-know-about-your-employee-stock-purchase-plan)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading