

Overview
Imagine a secure financial future for your child. Establishing and managing a UTMA (Uniform Transfers to Minors Act) fund can be a meaningful step in that direction. Here are four essential steps to guide you:
- Selecting a custodian
- Choosing a financial institution
- Completing the application
- Funding the account
It’s important to understand that diversifying investments can significantly enhance the growth of the fund. Regularly monitoring the fund’s performance is key to ensuring it meets your family’s needs. However, you may encounter common challenges, such as navigating tax implications and transitioning control to your child when the time is right.
By addressing these aspects, you can create a nurturing environment for your child’s financial future. Remember, we’re here for you every step of the way. Together, we can navigate this journey towards securing a brighter tomorrow for your family.
Key Highlights:
- UTMA accounts allow adults to manage assets for minors until they reach legal age, offering flexibility in asset types.
- Tax benefits include lower tax rates on income generated in custodial accounts, leading to potential savings.
- Contributions to UTMA accounts are irrevocable gifts, ensuring funds are dedicated to the child’s benefit.
- Control of the funds transitions to the minor at the age defined by state law, promoting independence.
- The UTMA fund can support various purposes, including education, aligning with families’ financial goals.
- Establishing a UTMA account involves selecting a custodian, financial institution, and completing an application.
- Diversifying investments within the UTMA fund can reduce risk and increase returns, with strategies like smart beta employed.
- Regular performance monitoring and adjusting strategies are vital for effective fund management.
- Common challenges include understanding tax implications, accessing funds, transitioning control, and managing disputes.
- Bright Advisers offers tailored wealth management solutions to assist families in navigating UTMA accounts effectively.
Introduction
In the journey of financial planning for your children, UTMA (Uniform Transfers to Minors Act) accounts emerge as a valuable resource that allows caring adults to manage assets on behalf of minors until they reach adulthood. These custodial accounts not only present a variety of investment options but also offer significant tax benefits, making them an attractive choice for families dedicated to securing their children’s financial futures.
As you navigate the complexities of establishing and managing these accounts, it’s important to understand the key features, benefits, and potential challenges involved. Imagine if you could equip your family with the knowledge to make informed decisions and nurture financial responsibility in your children.
This article explores the intricacies of UTMA accounts, providing a comprehensive guide that supports you in fostering a brighter financial future for your loved ones. Together, we can navigate this journey.
Understand UTMA Accounts: Key Features and Benefits
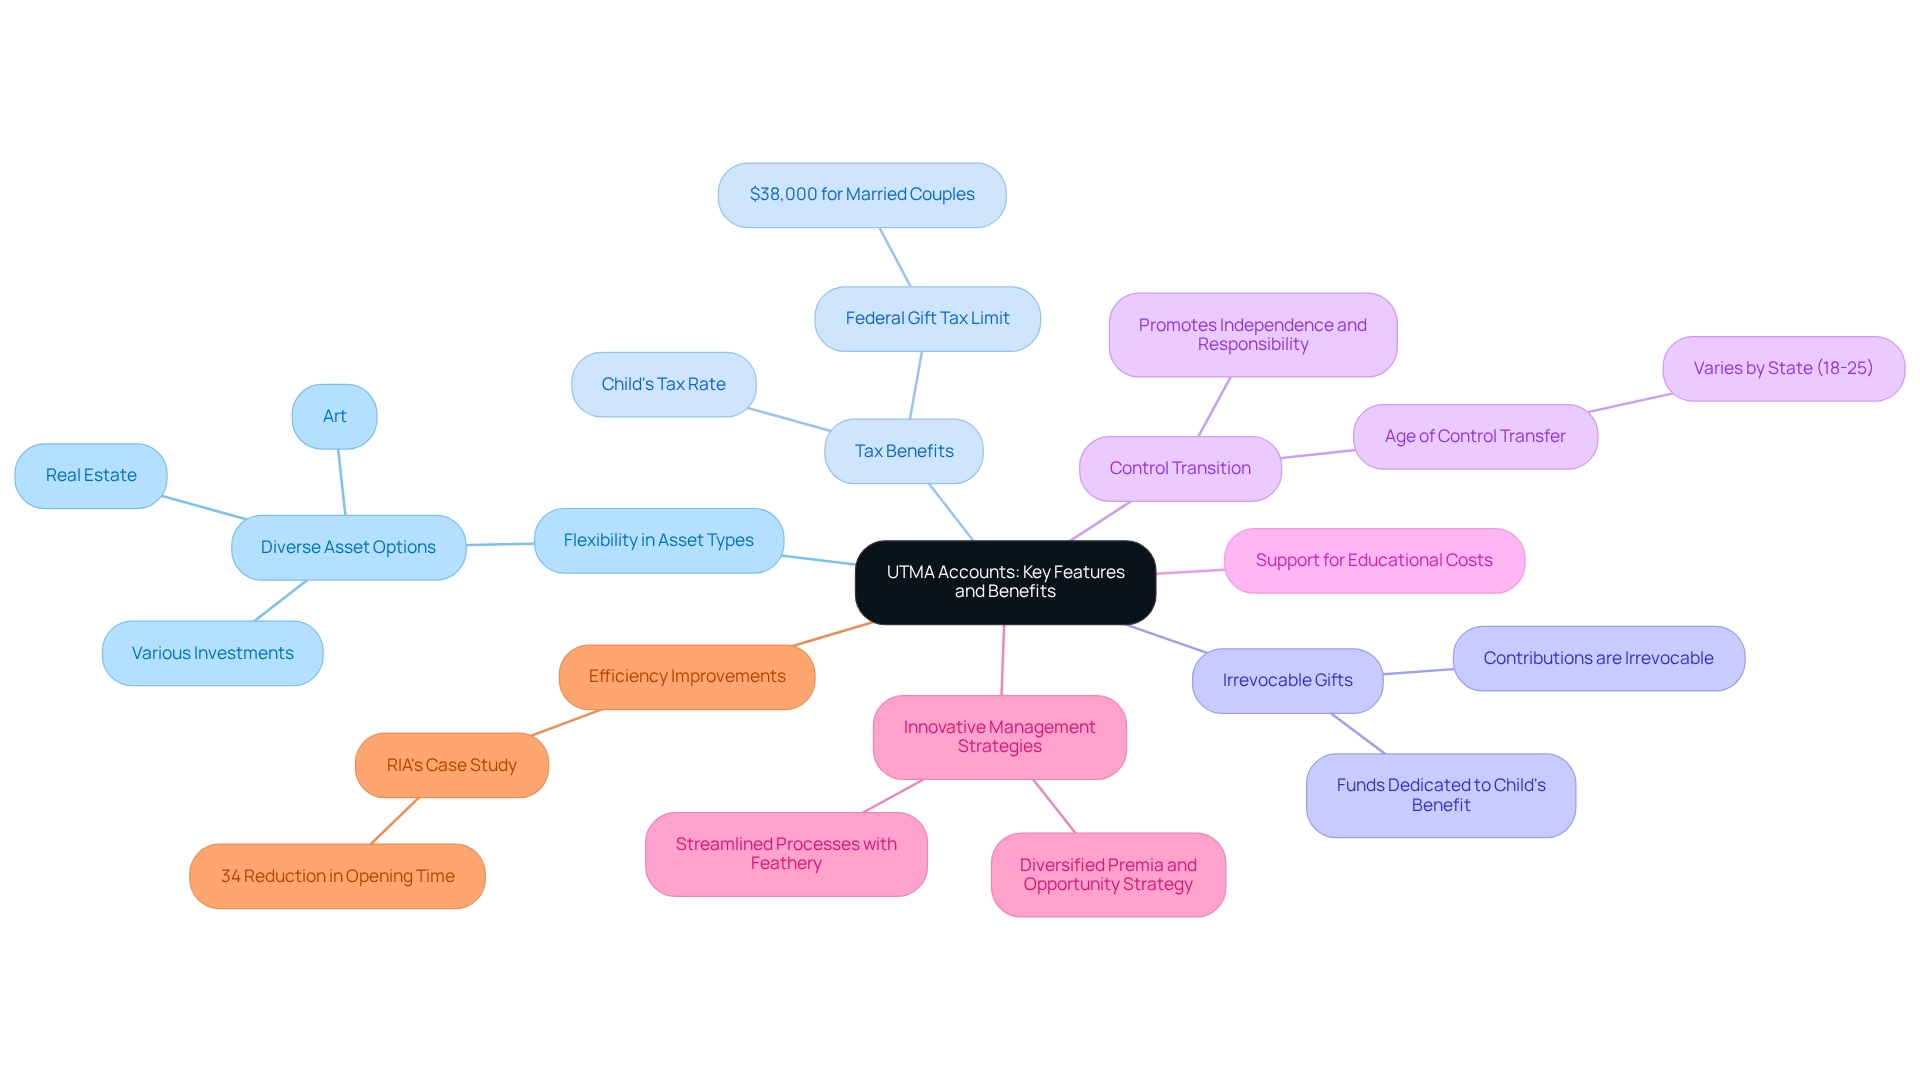
The UTMA fund custodial arrangements provide a nurturing way for adults to oversee assets for minors until they reach the legal age, which varies by state. Let’s explore some key features and benefits that can help you secure your child’s financial future.
Flexibility in asset types is a key advantage of the UTMA fund, enabling you to hold a diverse range of assets, from real estate to art and various investments. This flexibility offers you more options compared to UGMA accounts, allowing you to tailor the investment to your family’s needs.
- Tax Benefits: The income generated in a custodial savings arrangement is generally taxed at the child’s tax rate, often lower than that of the parents. This can lead to significant tax savings. For instance, a married couple can contribute up to $38,000 before facing federal gift tax, making these funds an appealing choice for wealth transfer to your children.
- Irrevocable Gifts: Contributions to a custodial fund are considered irrevocable gifts to the minor. Once the funds are deposited, they cannot be withdrawn for personal use by the contributor, ensuring that the money is dedicated to the child’s benefit and future.
- Control Transition: When the minor reaches the age defined by state law (usually between 18 and 25), they gain complete authority over the funds. This transition promotes independence and responsibility, empowering them as they step into adulthood.
The resources within a UTMA fund can support various purposes, including educational costs. This not only helps secure your child’s economic future but also aligns with our commitment at Bright Advisers to prepare children for future financial responsibilities. Take, for example, Emily and Mark, who sought to optimize their economic situation for their family’s future.
At Bright Advisers, we harness cutting-edge technology to enhance the management of custodial funds. Our innovative approach simplifies processes, allowing families to navigate financial planning with ease. This includes strategies like the Diversified Premia and Opportunity Strategy, designed to optimize the growth potential of the UTMA fund portfolios.
As our Chief Operating Officer noted, “We’ve significantly reduced back-and-forth cycles between advisors and clients, making the onboarding process more enjoyable on both sides.” This efficiency is crucial for families looking to create custodial arrangements without unnecessary delays. A recent case study highlighted how an RIA managing $8 billion in assets achieved a 34% decrease in opening time by collaborating with Feathery, allowing advisors to focus more on nurturing client relationships rather than paperwork.
These characteristics make custodial savings options especially beneficial for young families aiming to build a solid economic foundation for their children. By leveraging the tax advantages and flexibility of these options, alongside Bright Advisers’ innovative investment strategies, families can effectively plan for their children’s future while instilling valuable financial lessons. Together, we can navigate this journey and ensure a brighter tomorrow for your loved ones.
Establish a UTMA Account: Step-by-Step Process
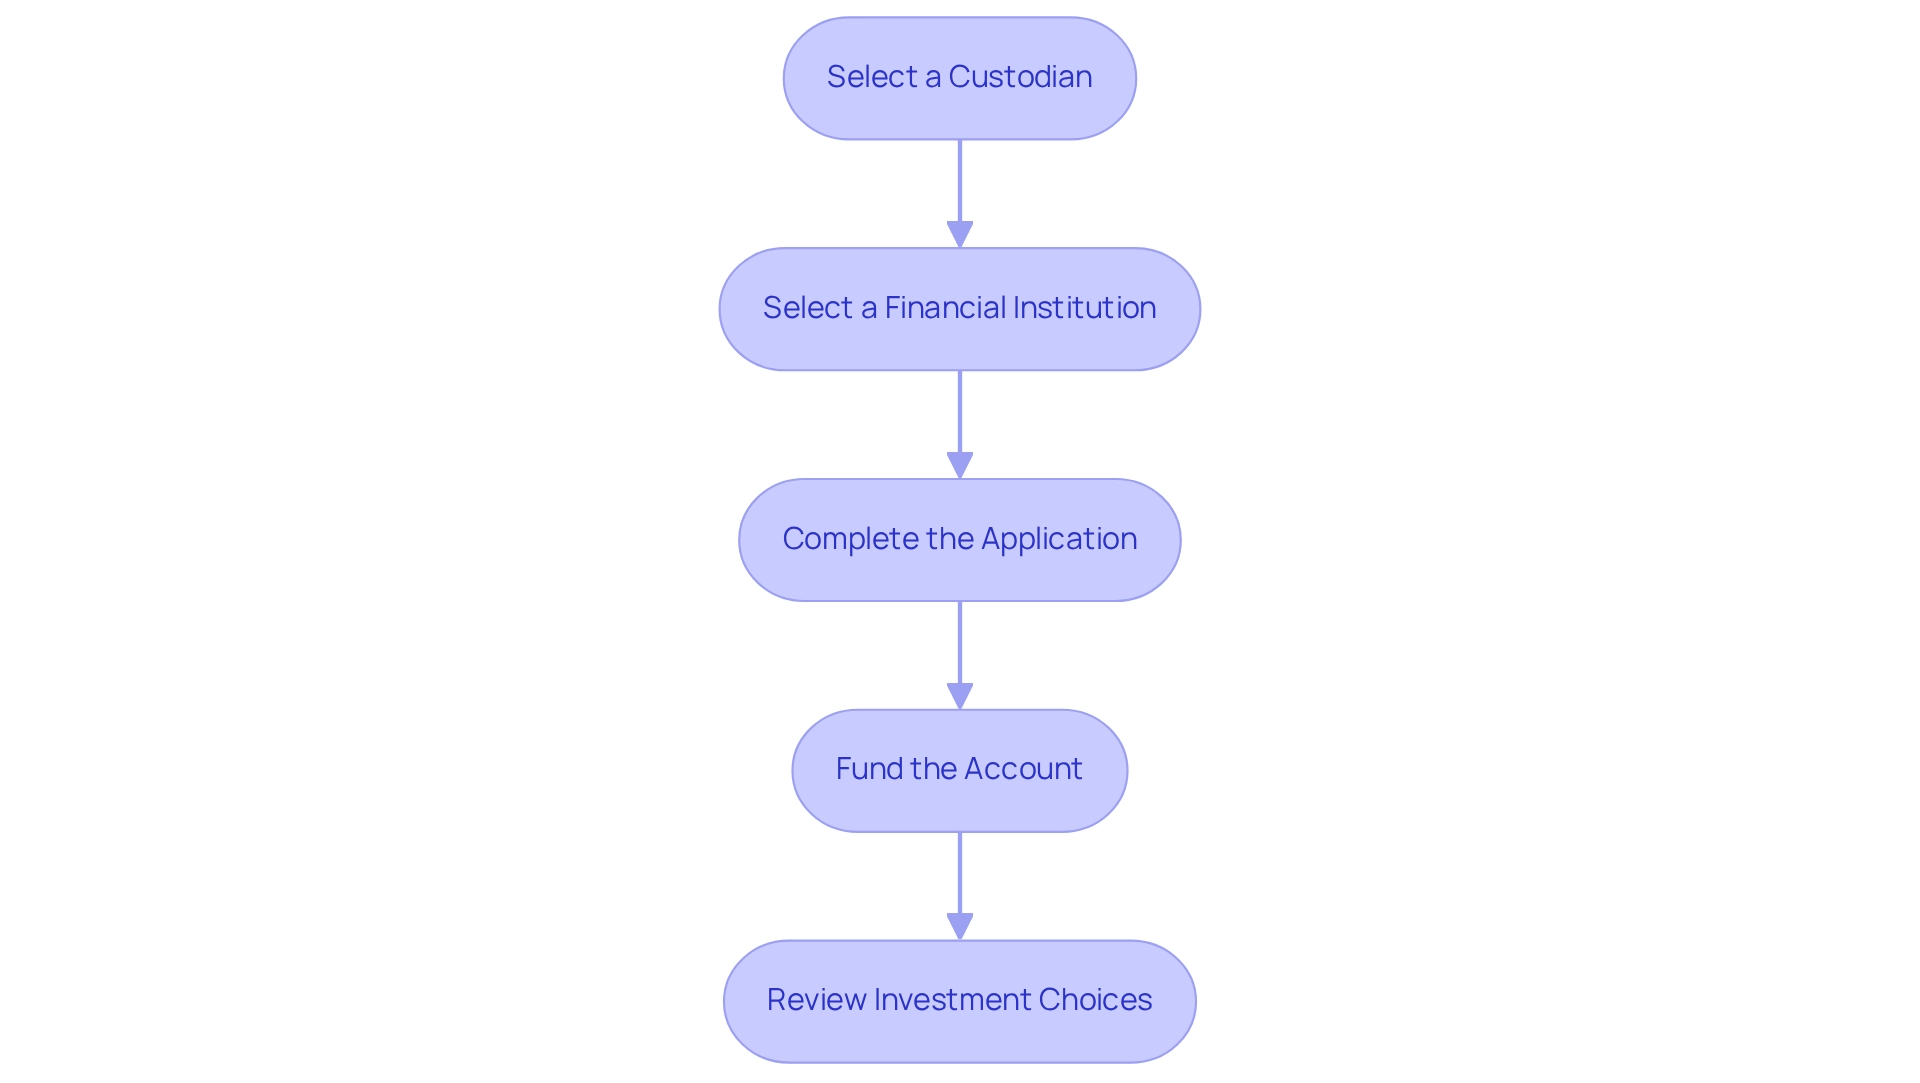
Creating a UTMA fund is a significant step towards securing your child’s financial future. Here’s how you can navigate this process with ease:
- Select a Custodian: Choose a responsible adult, typically a parent or guardian, to manage the funds until your child reaches adulthood. This person will play a vital role in guiding your child’s financial journey.
- Select a financial institution: Take the time to explore various banks or brokerages that provide UTMA fund accounts. At Bright Advisers, we prioritize minimizing fund fees to make wealth management more accessible for families. Compare aspects like fees, investment options, and customer service to find the best fit for your unique needs. Our investment advisory services are designed to support your family’s financial goals comprehensively.
- Complete the Application: Fill out the application form from your chosen bank. This will require personal details for both the custodian and the minor, including Social Security numbers, ensuring everything is in order for your child’s future.
- Fund the Account: Make an initial deposit to kickstart the UTMA fund. While there are no limits on contributions, it’s important to be mindful of potential gift tax implications if your contributions surpass the annual exclusion limit.
- Review investment choices: Engage with the institution about the investment options available within the UTMA fund framework, such as stocks, bonds, or mutual funds. At Bright Advisers, we offer tailored wealth management solutions and educational resources to empower families in making informed decisions. This step is crucial as custodial funds are considered your child’s assets, potentially affecting their eligibility for financial aid and influencing the Expected Family Contribution (EFC) when applying for college. Additionally, understanding the regulatory obligations tied to the UTMA fund arrangements is essential, as emphasized by the FINRA Rule 3110, which requires adherence to relevant securities laws and regulations. It’s also important to consider how custodial funds may impact future educational financing. For instance, a case study titled ‘Impact of Custodial Holdings on Aid Eligibility’ illustrates how these holdings can affect a student’s eligibility for assistance, as the balances are included in the EFC calculation. Should you have any questions regarding regulatory obligations, please feel free to reach out to Jeanette Wingler, Associate General Counsel, at (202) 728-8013.
By following these steps, families can establish a custodial account that serves not just as a financial tool but also as a foundation for long-term educational funding goals. Together, we can empower your family toward financial security and freedom through personalized planning. For more information or assistance, don’t hesitate to contact us at hello@brightadvisers.com or call (714) 987-2967.
Manage Your UTMA Fund: Investment Strategies and Oversight
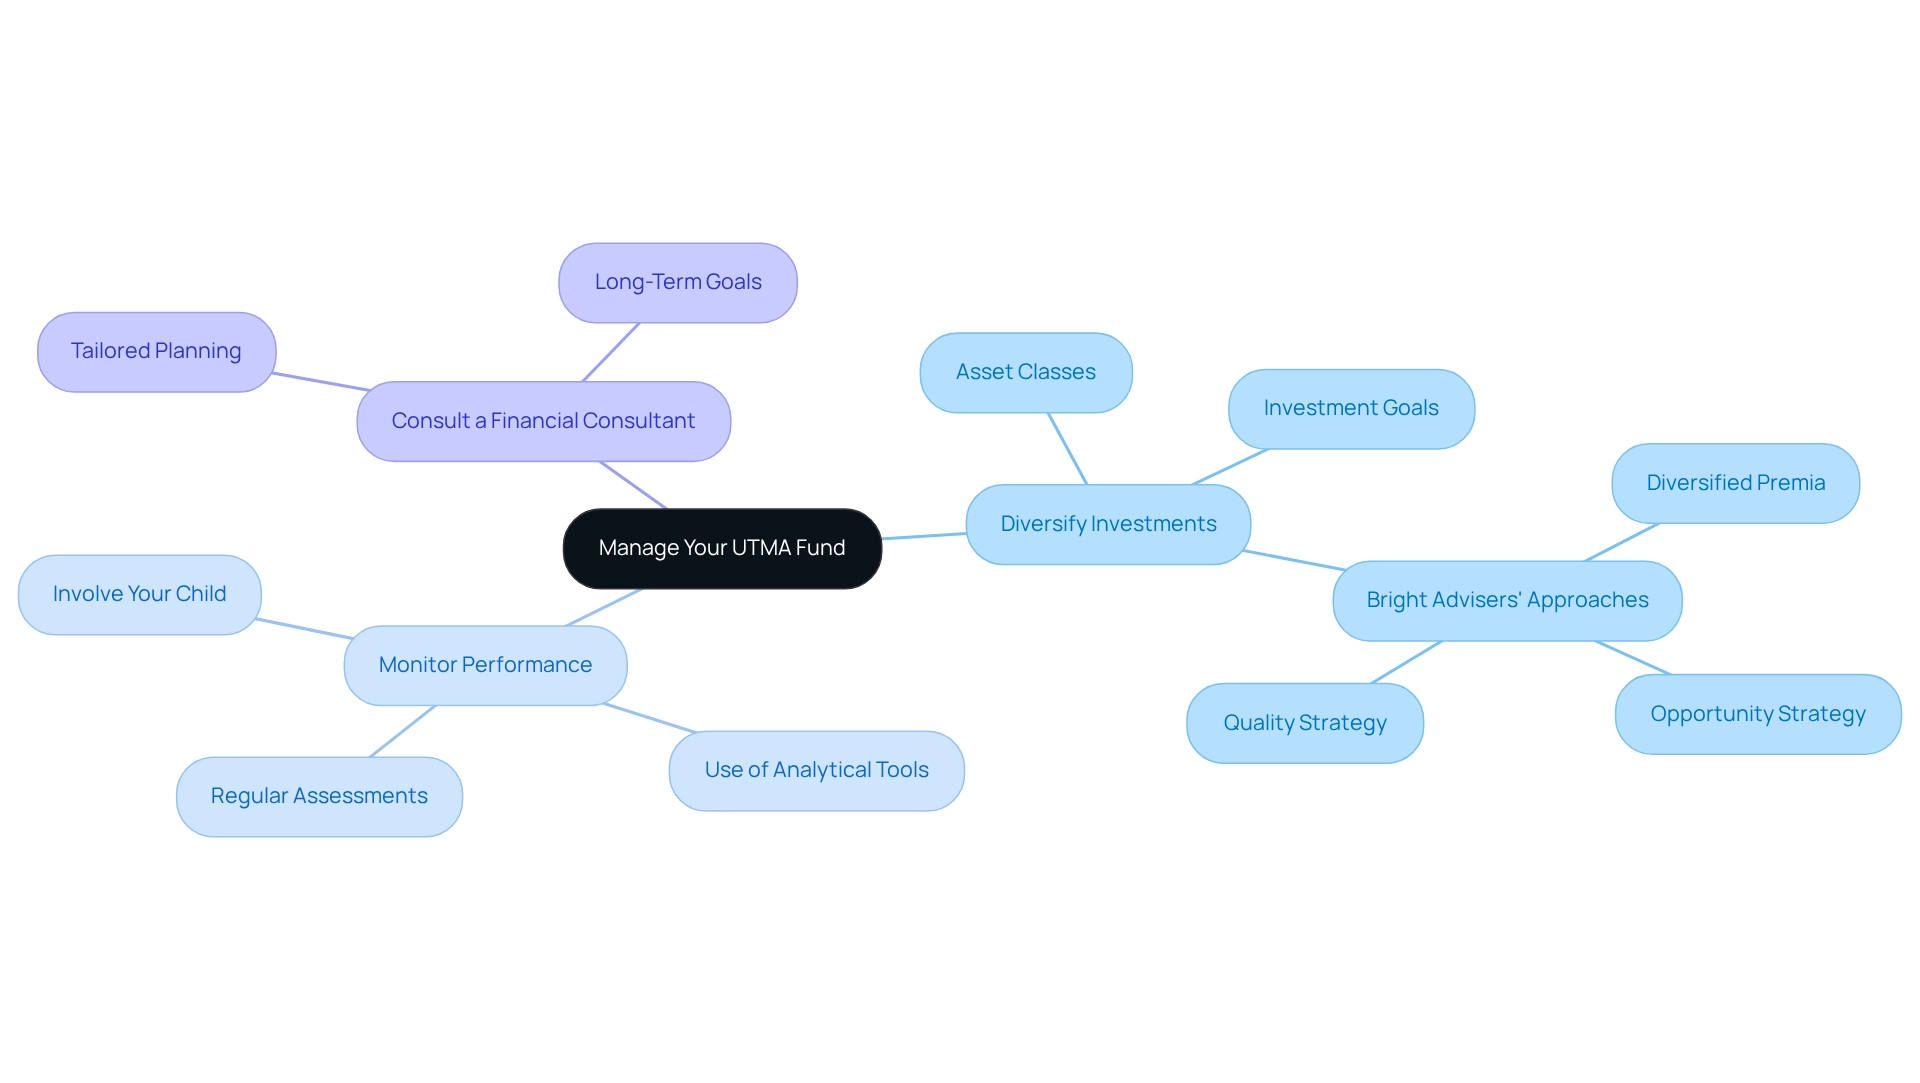
Effectively managing your UTMA fund requires a strategic approach to capital allocation and ongoing oversight. Here are some key strategies to consider:
- Diversify Investments: Imagine if you could allocate funds across various asset classes, including stocks, bonds, and mutual funds. This diversification reduces risk and increases the potential for returns, aligning with the principle that distributing resources can cushion against market volatility. Bright Advisers utilizes innovative approaches such as smart beta and factor investing, featuring their Diversified Premia, Opportunity Strategy, and Quality Strategy, to create hyper-personalized portfolios, ensuring that your assets are optimized for performance and risk management. Setting investment goals is crucial, as it’s important to clearly define the purpose of the UTMA fund—whether it is for education, a first home, or other significant milestones. Setting specific monetary goals will guide your investment choices and assist in measuring progress. Bright Advisers can help in aligning these goals with customized planning solutions that reduce anxiety and ensure your family’s future.
- Monitor Performance: Regularly assessing the account’s performance and adjusting your strategies as necessary is vital. Make use of the analytical tools provided by your financial institution to monitor growth and assess the effectiveness of your financial decisions. Bright Advisers’ advanced technology offers insights that can assist you in making informed choices, highlighting the significance of historical performance in your financial strategies and making conventional financial products outdated. As your child matures, involve them in discussions about the UTMA fund. Instructing them on money management and asset principles equips them for future economic oversight. Albert Einstein once said, “Compound interest is the eighth wonder of the world. He who understands it, earns it … he who doesn’t … pays it,” highlighting the long-term benefits of wise investing.
- Consult a Financial Consultant: If you require additional guidance, consider consulting a consultant with expertise in custodial accounts. Bright Advisers focuses on tailored planning and can help ensure that your strategy aligns with your family’s long-term monetary goals.
By applying these strategies, you can effectively oversee your custodial fund, ensuring it fulfills its intended purpose while promoting a strong financial base for your child’s future. Additionally, remember that diversification helps balance risk and reward by spreading investments across different sectors and asset classes, making it a timely strategy for 2025.
Navigate Challenges: Troubleshooting Common UTMA Issues
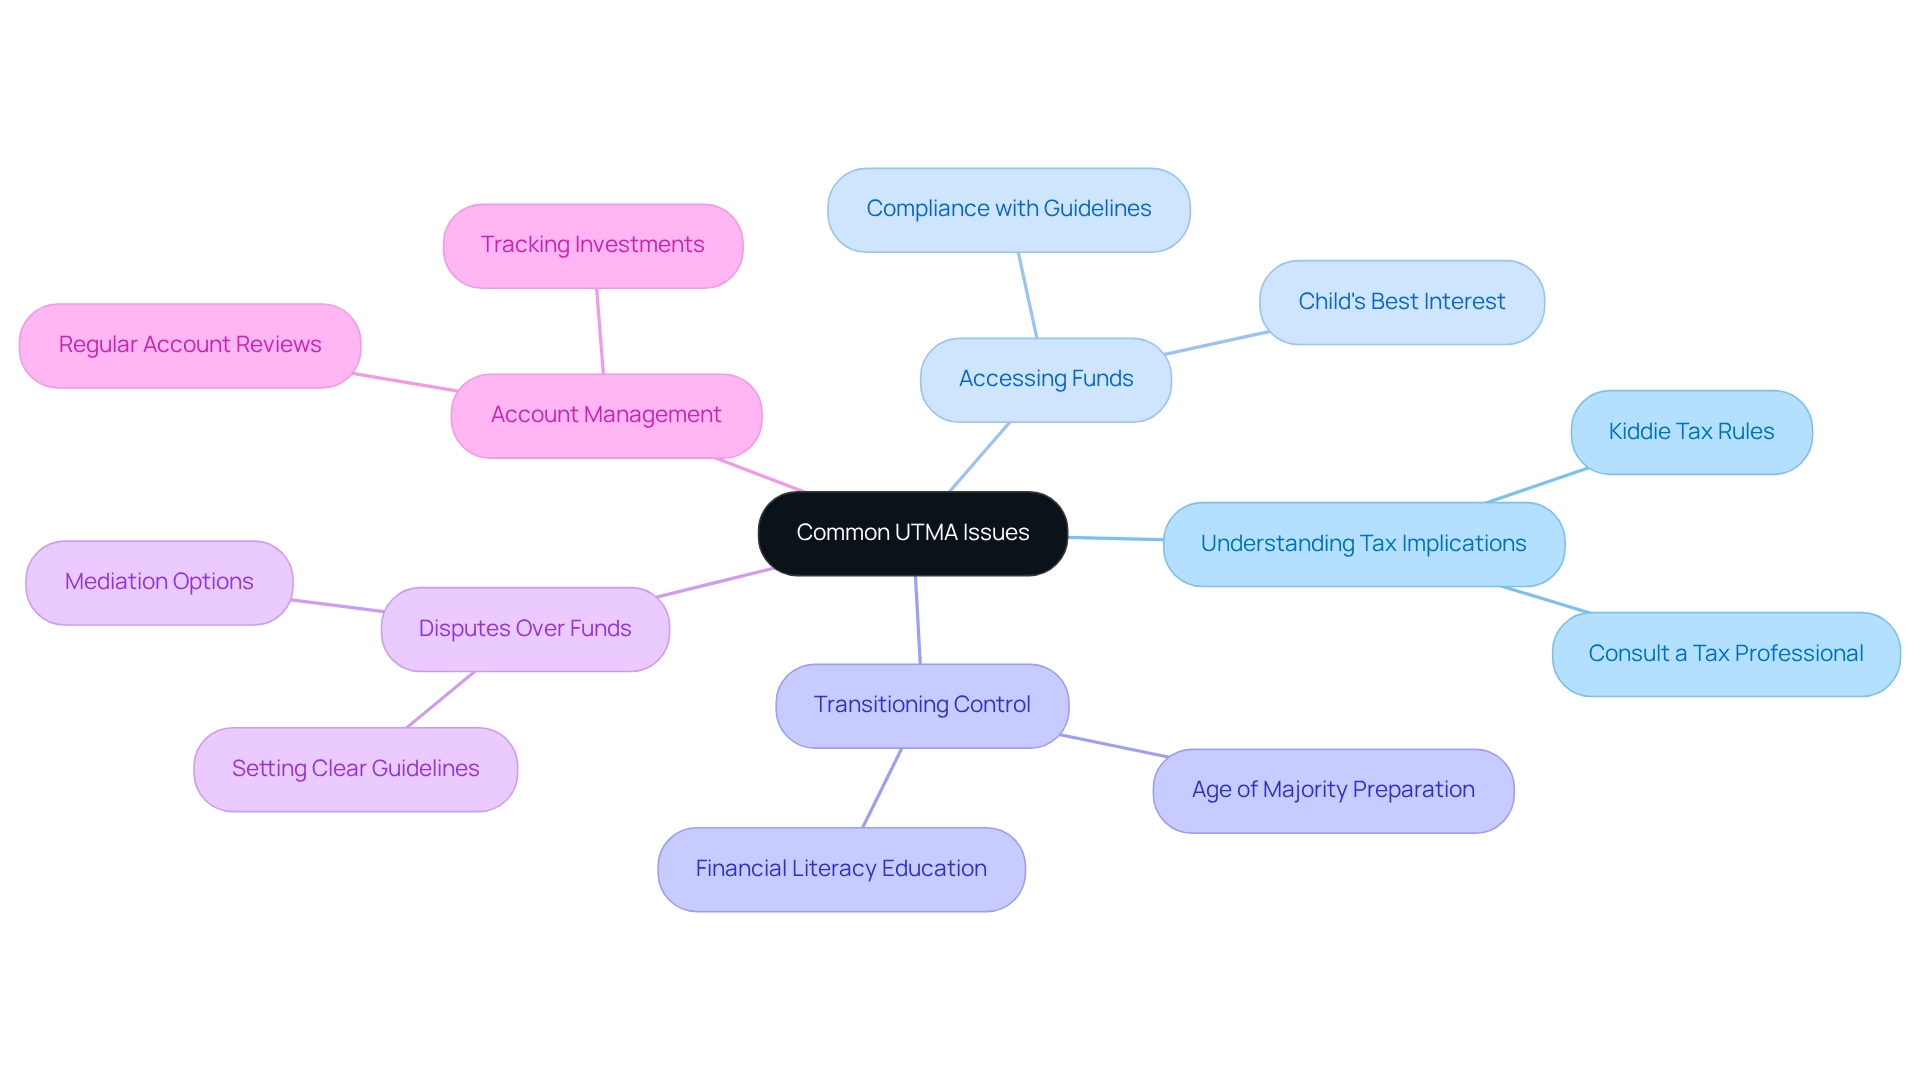
Handling a custodial investment can feel overwhelming at times, but with the right guidance, it can also be a straightforward process. Let’s explore some common challenges and thoughtful strategies to address them:
- Understanding Tax Implications: It’s essential to familiarize yourself with the ‘kiddie tax’ rules that apply to unearned income in UTMA accounts. This tax can influence how much of your child’s income is taxed at your rate. Remember, the age of majority for transferring ownership is typically 18 or 21, depending on where you live. Consulting a tax professional can help clarify any uncertainties regarding tax liabilities, ensuring you navigate these complexities with confidence.
- Accessing Funds: When it comes to withdrawing funds for your child’s benefit, it’s vital to comply with the guidelines set by your financial institution and state laws regarding permissible uses. Before establishing a UTMA fund arrangement, consider how the child’s future access to these assets may look. As Amy Danise, Editor at Forbes, emphasizes, making withdrawals in the child’s best interest is crucial. At Bright Advisers, we are dedicated to keeping fund fees low—applying to the vast majority of our models—so families can access their funds without incurring unnecessary costs, simplifying the management of these holdings.
- Transitioning Control: As your child approaches the age of majority, typically 18 or 21 depending on state laws, preparing for the transition of account control becomes essential. Engage in open discussions with your child about what this transition entails and the importance of responsible money management. A case study titled “Transitioning Accounts to Minors” highlights how custodians play a pivotal role in preparing minors for asset management, underscoring the need for education and preparation during this time. Bright Advisers offers tailored wealth management solutions, including the development of a durable financial plan, empowering families to navigate this transition smoothly, ensuring both financial security and educational readiness.
- Disputes Over Funds: Conflicts can arise among family members regarding the use of custodial funds. In such instances, consider mediation or seek legal advice to resolve disagreements amicably, always keeping the child’s best interests at heart. While the UTMA fund offers ease of use, it may also lead to future access issues that could spark disputes. Our customized monetary planning approach at Bright Advisers helps families set clear guidelines and expectations, reducing the likelihood of conflicts.
- Account Management: Regularly reviewing your account for any charges or changes in conditions is vital for effective management and maximizing benefits. Staying informed about your bank’s policies regarding the UTMA fund is essential. With Bright Advisers’ in-house technology, families can easily track their investments, ensuring they align with their financial goals while minimizing fund fees.
Together, we can navigate this journey, ensuring a secure financial future for your family.
Conclusion
UTMA accounts serve as a powerful financial tool for families eager to secure their children’s futures while nurturing a sense of financial responsibility. With their flexibility in asset types, tax advantages, and the irrevocable nature of contributions, these accounts present an appealing option for effective wealth management. Imagine being able to support your child’s educational expenses while transitioning control to them at adulthood, fostering their independence and financial literacy.
Establishing a UTMA account is a straightforward journey. From selecting a custodian to choosing a financial institution and funding the account, the process is designed to empower families. By following the necessary steps and consulting with financial advisors, you can create a robust financial foundation tailored to your family’s goals. Strategic management of these accounts, including diversification of investments and setting clear financial objectives, enhances their effectiveness, ensuring your efforts bear fruit.
While challenges may arise—such as understanding tax implications or transitioning control to your child—being prepared and informed can alleviate these concerns. Engaging in open discussions about financial management and seeking professional guidance allows families to navigate the complexities of UTMA accounts with confidence.
Ultimately, by leveraging the benefits of UTMA accounts and employing sound financial strategies, you can secure your children’s financial futures while cultivating a lifelong understanding of financial stewardship. This proactive approach lays the groundwork for a brighter tomorrow, empowering the next generation to make informed financial decisions. Remember, together, we can navigate this journey, ensuring your family’s financial well-being for years to come.
Frequently Asked Questions
What is the purpose of UTMA fund custodial arrangements?
UTMA fund custodial arrangements allow adults to oversee and manage assets for minors until they reach the legal age, which varies by state, helping to secure the child’s financial future.
What types of assets can be held in a UTMA fund?
A UTMA fund offers flexibility in asset types, enabling the holding of a diverse range of assets, including real estate, art, and various investments.
What are the tax benefits associated with a UTMA fund?
The income generated in a UTMA custodial arrangement is generally taxed at the child’s tax rate, which is often lower than that of the parents, resulting in potential tax savings. Additionally, a married couple can contribute up to $38,000 without facing federal gift tax.
Are contributions to a UTMA fund revocable?
No, contributions to a UTMA fund are considered irrevocable gifts to the minor, meaning once the funds are deposited, they cannot be withdrawn for personal use by the contributor.
When does a minor gain control over the funds in a UTMA account?
A minor gains complete authority over the funds in a UTMA account when they reach the age defined by state law, typically between 18 and 25 years old.
How can the resources within a UTMA fund be utilized?
The resources within a UTMA fund can support various purposes, including educational costs, helping to secure the child’s economic future.
What innovative approaches does Bright Advisers use for managing custodial funds?
Bright Advisers utilizes cutting-edge technology to enhance the management of custodial funds, simplifying processes and allowing families to navigate financial planning more easily.
What is the impact of Bright Advisers’ strategies on the efficiency of custodial arrangements?
Bright Advisers’ innovative strategies, such as the Diversified Premia and Opportunity Strategy, have significantly reduced the time required for onboarding and managing custodial arrangements, allowing advisors to focus more on client relationships.
Who can benefit from custodial savings options like UTMA accounts?
Custodial savings options, particularly UTMA accounts, are especially beneficial for young families aiming to build a solid economic foundation for their children through tax advantages and flexible investment strategies.
List of Sources
- Understand UTMA Accounts: Key Features and Benefits
- investor.vanguard.com (https://investor.vanguard.com/accounts-plans/ugma-utma)
- feathery.io (https://feathery.io/blog/custodial-account-vs-529)
- Establish a UTMA Account: Step-by-Step Process
- Regulatory Notice 20-07 | FINRA.org (https://finra.org/rules-guidance/notices/20-07)
- How to Open a Custodial Account for a Minor (https://smartasset.com/financial-advisor/how-to-open-a-custodial-account)
- Manage Your UTMA Fund: Investment Strategies and Oversight
- The Top 25 Investing Quotes of All Time (https://investopedia.com/financial-edge/0511/the-top-17-investing-quotes-of-all-time.aspx)
- Diversification: UGMA: Spreading Risk through Diversified Investments – FasterCapital (https://fastercapital.com/content/Diversification–UGMA–Spreading-Risk-through-Diversified-Investments.html)
- Eight Great Investing Quotes (https://texasfa.com/Eight-Great-Investing-Quotes.c10271.htm)
- Investment Strategies For Utma Assets – FasterCapital (https://fastercapital.com/topics/investment-strategies-for-utma-assets.html)
- Navigate Challenges: Troubleshooting Common UTMA Issues
- UTMA Account Taxes: What You Need to Know (https://accountinginsights.org/utma-account-taxes-what-you-need-to-know)
- Why UTMA Accounts Are Not As Simple As They Seem (https://forbes.com/sites/christinefletcher/2019/12/12/why-utma-accounts-are-not-as-simple-as-they-seem)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading