

Overview
The backdoor IRA Roth strategy offers a valuable opportunity for high-income individuals to achieve tax-free growth, which can be especially beneficial for families. By making non-deductible contributions to a traditional IRA and converting them to a Roth IRA, you can secure a brighter financial future for your loved ones.
Imagine if you could grow your savings without the burden of taxes—this strategy outlines a simple four-step process to help you do just that:
- Make a non-deductible contribution.
- Convert that amount to a Roth IRA.
- File IRS Form 8606 for tax reporting.
- Consider the tax implications, such as the Pro-Rata Rule and the Aggregation Rule, to avoid unexpected tax liabilities.
Navigating these steps may feel daunting, but remember, we’re here for you. Together, we can navigate this journey and ensure that your family’s financial goals are met with confidence and clarity.
Key Highlights:
- A backdoor Roth IRA allows individuals with high incomes to secure tax-free growth by making non-deductible contributions to a traditional IRA and converting them to a Roth IRA.
- The process involves two main steps: making a non-deductible payment to a traditional IRA and then converting that amount to a Roth IRA.
- It is essential to file IRS Form 8606 to report non-deductible contributions and conversions, ensuring accurate tax reporting.
- The Pro-Rata Rule can lead to unexpected tax liabilities if pre-tax IRAs exist; consider rolling over pre-tax IRAs to an employer-sponsored plan to minimise taxes.
- Timing the conversion shortly after making a non-deductible contribution can help maximise tax-free growth potential.
- Maintaining meticulous records of contributions and conversions is crucial for avoiding double taxation and ensuring compliance with IRS regulations.
- The Aggregation Rule treats all IRA accounts as a single entity for tax purposes, complicating tax calculations for individuals with multiple IRAs.
Introduction
Navigating the complexities of retirement savings can feel overwhelming, especially for families striving to secure their financial future. Imagine if there was a way to make this journey a little easier. The backdoor Roth IRA strategy offers a unique opportunity for high-income earners to bypass IRS restrictions and enjoy tax-free growth on their investments.
However, it’s important to understand that this process comes with its own set of challenges and intricacies. How can families effectively leverage this strategy to maximize their retirement savings while avoiding potential pitfalls? Together, we can explore this path and find the best solutions for your family’s needs.
Understand the Backdoor Roth IRA Concept
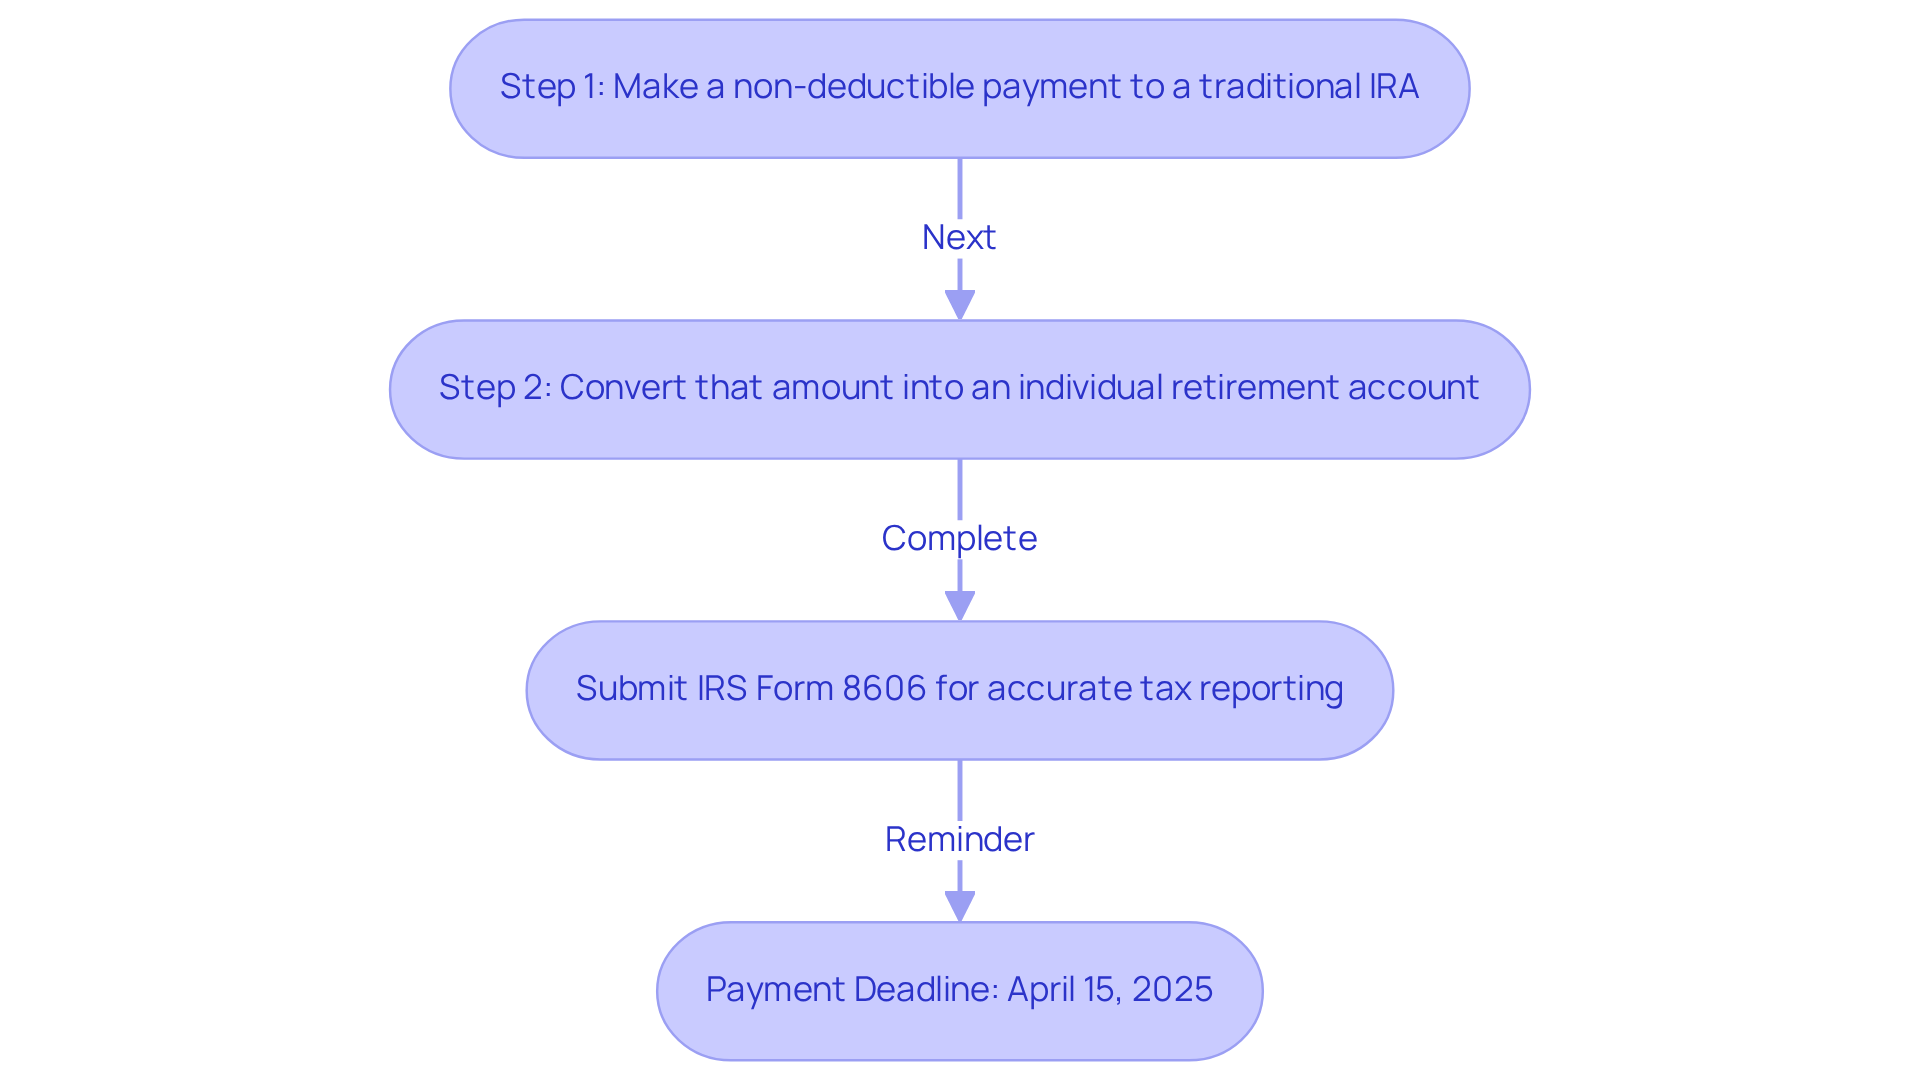
Imagine a world where you can secure your family’s financial future, even if your income exceeds IRS limits. A backdoor IRA Roth is a strategic method that allows you to do just that. This approach involves a simple two-step process:
- You make a non-deductible payment to a traditional IRA.
- You convert that amount into an individual retirement account.
This method is especially beneficial for families looking to maximize their retirement savings and enjoy tax-free growth on their investments.
Consider the peace of mind that comes with knowing your family can benefit from tax-free withdrawals in retirement, significantly boosting your financial security. Recent data shows that about 30% of families are embracing the backdoor IRA Roth strategy, recognizing its potential to enhance long-term wealth accumulation. Financial advisors highlight that this approach not only encourages tax-efficient savings but also aligns perfectly with the goal of building a strong financial foundation for future generations.
As CFP Amy Shepard wisely notes, ‘This strategy is most logical if you possess no IRA assets at the year’s conclusion and your income is too elevated for direct IRA deposits.’ By understanding the mechanics of the backdoor IRA Roth, you can navigate the complexities of retirement planning and seize this opportunity to secure your family’s financial future.
It’s also crucial to ensure accurate tax reporting by submitting IRS Form 8606 for your payments. Remember, the deadline for Roth IRA payments for the 2024 tax year is April 15, 2025. Together, we can navigate this journey, ensuring that your family’s financial goals are met with care and support.
Set Up Your Non-Deductible IRA Contribution
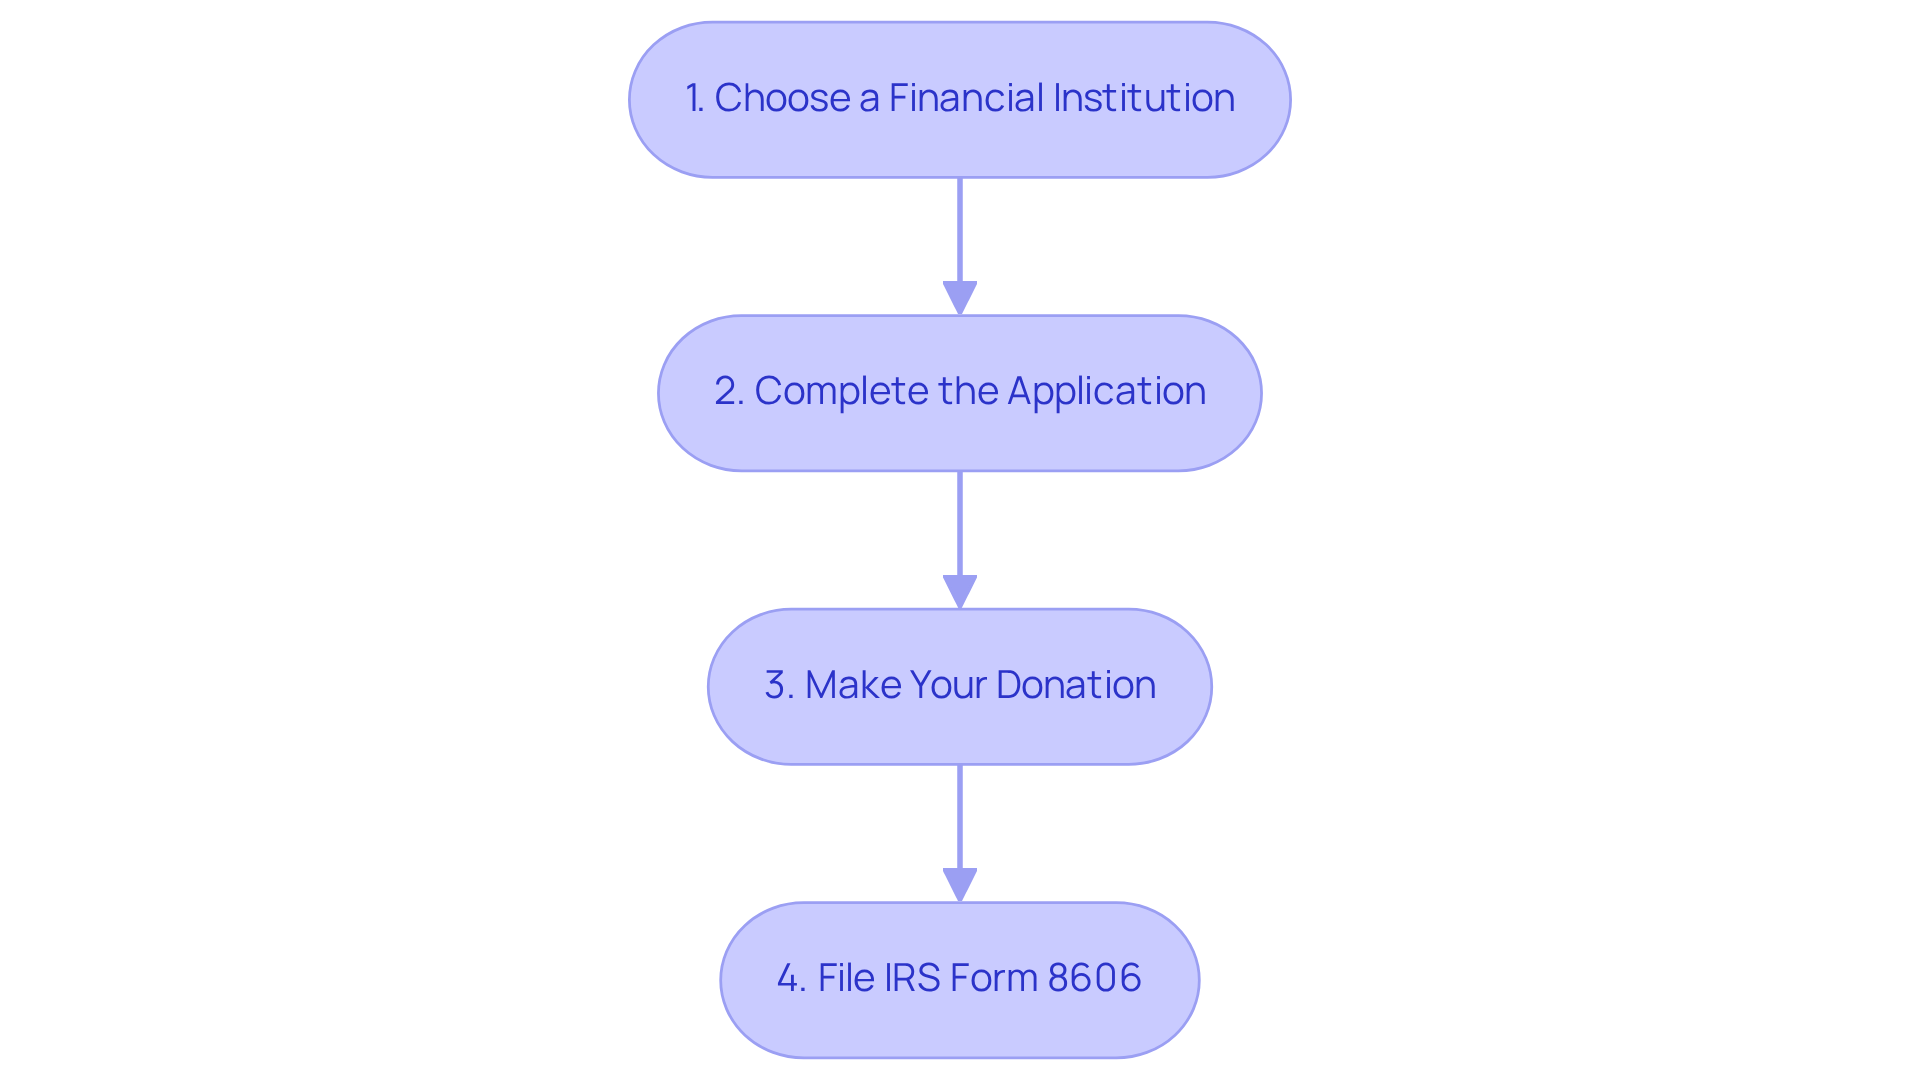
Setting up your non-deductible IRA contribution can feel daunting, but we’re here to guide you through each step with care and understanding. Let’s take this journey together:
- Choose a Financial Institution: Start by selecting a bank or brokerage that offers traditional IRAs. It’s essential to ensure they allow non-deductible payments, so you can feel confident in your choice.
- Complete the Application: Next, fill out the IRA application form, providing the necessary personal information. Be sure to indicate that you are making a non-deductible payment, which is an important detail for your future.
- Make Your Donation: Now, fund your IRA with the amount that feels right for you, keeping in mind the annual donation limits set by the IRS. For 2025, the limit is $6,500 for individuals under 50 and $7,500 for those 50 and older. Imagine the peace of mind this contribution can bring to your family’s future.
- File IRS Form 8606: Finally, when tax season comes around, remember to include Form 8606 to report your non-deductible contribution. This form is crucial for tracking your basis in the IRA, helping to prevent any unexpected taxes on the conversion later.
By following these steps, you’ll not only set up your non-deductible IRA successfully but also take a significant step in preparing for the next phase of the backdoor IRA Roth strategy. Together, we can navigate this journey toward a secure financial future for your family.
Convert to a Roth IRA
Converting your non-deductible IRA to a Roth IRA can be a significant step towards securing your family’s financial future. Here’s how to navigate this process with ease:
-
Reach Out to Your Financial Institution: Start by contacting the bank or brokerage where you set up your non-deductible IRA. Let them know you’d like to convert it to a Roth IRA. This is your first step towards a brighter financial future.
-
Complete the Necessary Forms: You’ll need to fill out some forms for the conversion. This might include specifying how much you wish to convert. Take your time with this; it’s important to get it right.
-
Choose Your Investments Wisely: Think about how you want to allocate the funds in your new Roth IRA. You have various options, such as stocks, bonds, and mutual funds. Remember, the longer your investments stay in the account, the greater the potential for tax-free growth, which can be a wonderful benefit for your family’s future.
-
Confirm the Conversion: Once you’ve submitted your request, check back with your financial institution to ensure the conversion has been processed. Keep all documentation related to this transaction, especially the significance of reporting a 2024 1099-R on your 2024 returns.
By following these steps, you can successfully transition your non-deductible IRA to a backdoor IRA Roth, which allows your investments to grow tax-free. It’s always a good idea to consult with a financial advisor who can help tailor the process to your personal situation. They can also guide you on any potential penalties for early withdrawals or the need to have cash available for taxes at the time of conversion.
Together, we can navigate this journey toward a secure financial future for your family.

Navigate Common Challenges and Considerations
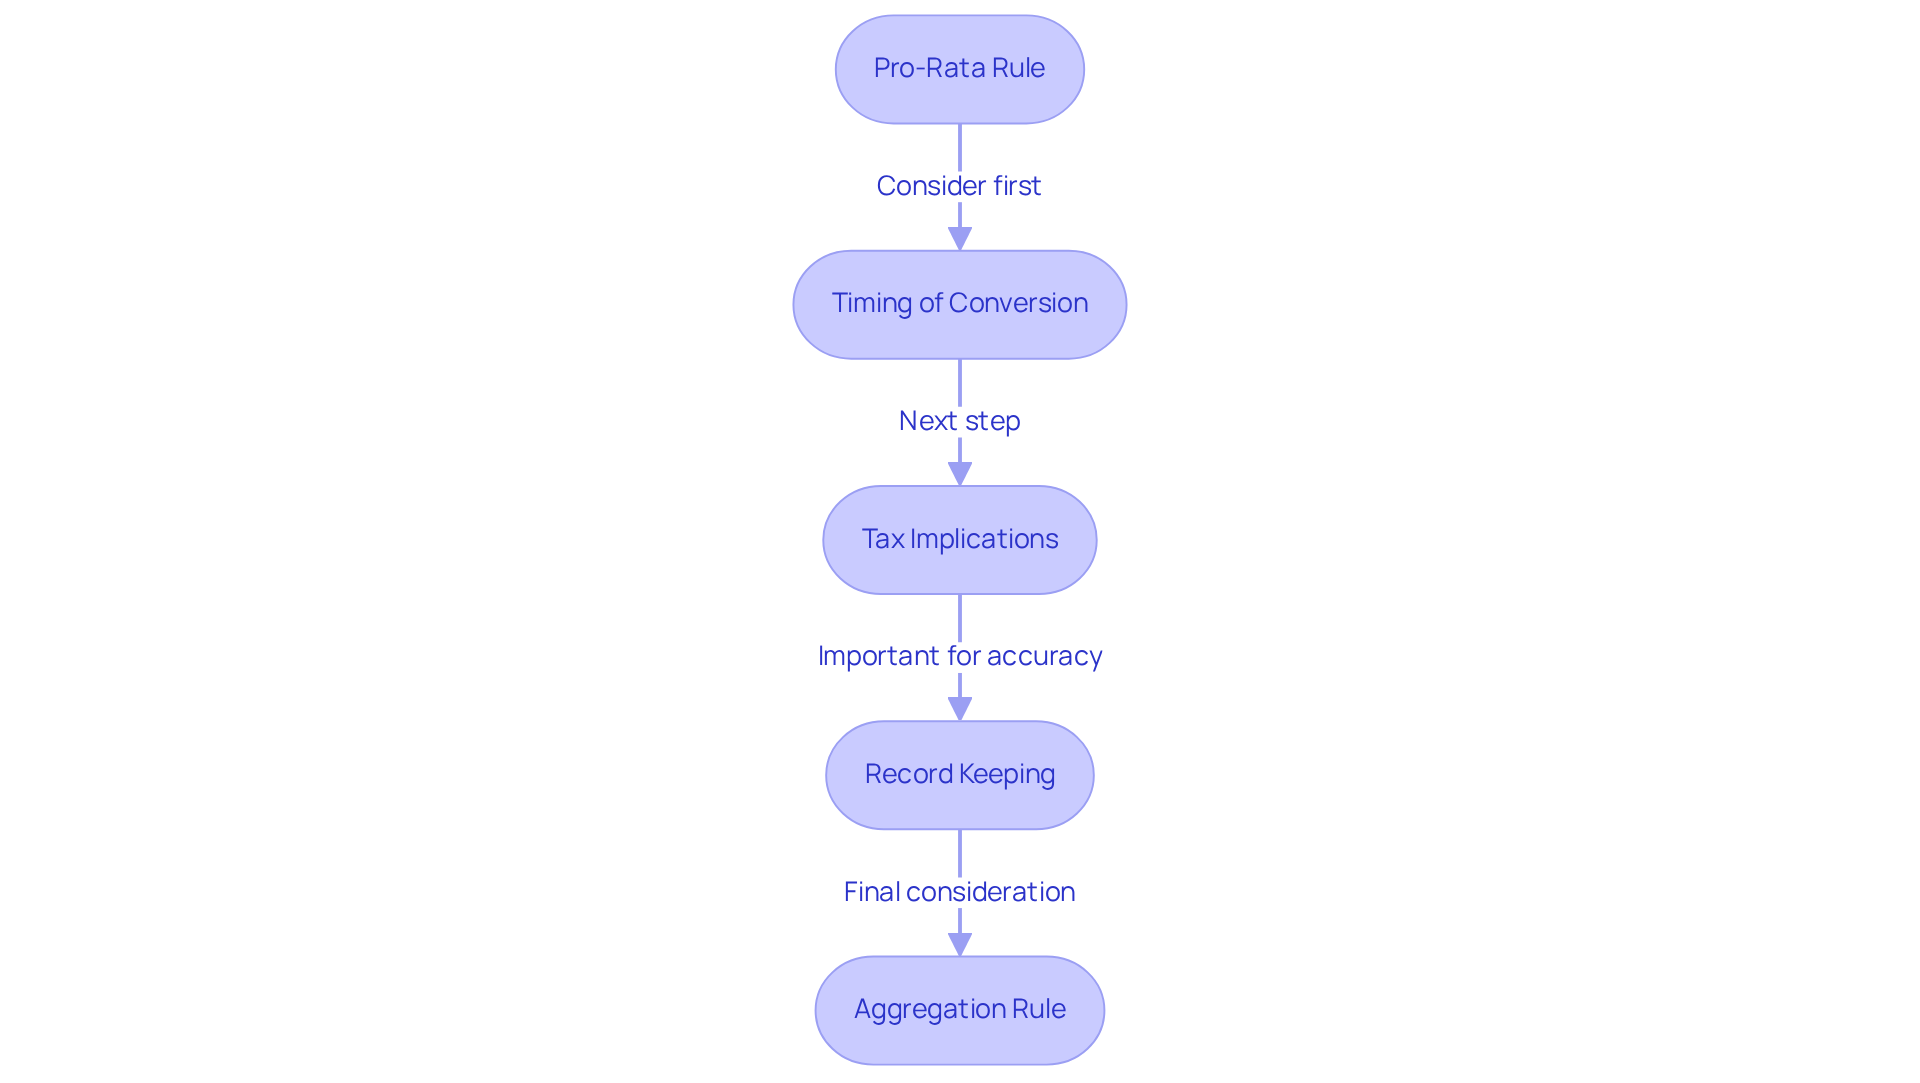
Navigating the backdoor IRA Roth strategy can feel overwhelming, especially for young parents who are focused on securing their family’s financial future. Here are some key challenges and considerations to keep in mind:
-
Pro-Rata Rule: If you have traditional IRAs with pre-tax deposits, the IRS may tax part of your conversion based on the ratio of pre-tax to post-tax funds. For instance, John encountered a tax liability of $27,000 due to this rule. To ease this burden, consider rolling over pre-tax IRAs into an employer-sponsored plan before converting. This thoughtful step can help reduce your tax liability and make the process smoother for your family.
-
Timing of Conversion: When you choose to convert your funds is crucial. To minimize potential taxable earnings, try to convert shortly after making your non-deductible contribution. This strategy can help you maximize the tax-free growth potential of your individual retirement account, paving the way for a brighter financial future.
-
Tax Implications: It’s essential to consult with a tax professional to fully grasp the implications of your conversion, especially if you hold multiple IRAs. Chad Chubb highlights that the backdoor IRA Roth strategy is especially advantageous for high-income professionals seeking to navigate income restrictions. If you have significant pre-tax assets, be mindful that the Pro-Rata Rule could result in unexpected tax bills, which can be daunting for families.
-
Record Keeping: Keeping meticulous records of your contributions and conversions is vital. Make sure to file IRS Form 8606 to accurately document your non-deductible payments and conversions. This form is your safeguard, proving that your contributions were post-tax and helping you avoid double taxation in the future.
-
Aggregation Rule: Remember that the IRS views all IRA accounts as a single entity for tax purposes. This Aggregation Rule can complicate tax calculations, particularly for those with multiple IRAs. Understanding this rule is crucial to prevent unexpected tax implications during your conversion journey.
By being aware of these challenges and considerations, you can navigate the backdoor IRA Roth process more effectively. Together, we can work towards maximizing the benefits of this strategy for your family’s financial well-being.
Conclusion
Navigating the backdoor Roth IRA strategy opens a pathway for families to secure their financial future, even when income levels exceed IRS limits. This approach not only facilitates tax-free growth on investments but also empowers individuals to maximize their retirement savings. Imagine if you could take proactive steps today to lay a strong foundation for long-term wealth accumulation for your loved ones.
Key steps in executing this strategy include:
- Setting up a non-deductible IRA contribution
- Converting that amount into a Roth IRA
- Addressing common challenges such as the pro-rata rule and the timing of conversions
Each of these elements plays a crucial role in ensuring that the backdoor Roth IRA strategy is implemented effectively, allowing for tax-efficient savings that can benefit generations to come. It’s important to understand that proper record-keeping and tax reporting are vital to avoid unexpected tax implications.
Ultimately, embracing the backdoor Roth IRA strategy is not just about immediate financial gains; it’s about fostering a legacy of financial security for future generations. By taking proactive steps and consulting with financial professionals, families can navigate this process with confidence, ensuring their financial goals are met. Together, we can navigate this journey, and engaging with this strategy today can pave the way for a more secure and prosperous tomorrow.
Frequently Asked Questions
What is a Backdoor Roth IRA?
A Backdoor Roth IRA is a strategic method that allows individuals to contribute to a Roth IRA even if their income exceeds IRS limits. It involves making a non-deductible payment to a traditional IRA and then converting that amount into a Roth IRA.
How does the Backdoor Roth IRA process work?
The process consists of two steps: first, you make a non-deductible contribution to a traditional IRA, and second, you convert that contribution into a Roth IRA.
Who can benefit from a Backdoor Roth IRA?
Families looking to maximize their retirement savings and achieve tax-free growth on their investments can benefit from a Backdoor Roth IRA, especially those with incomes too high for direct IRA contributions.
What are the advantages of using a Backdoor Roth IRA?
The advantages include the ability to secure tax-free withdrawals in retirement, enhancing long-term wealth accumulation, and promoting tax-efficient savings.
What should I consider before using a Backdoor Roth IRA?
It’s most logical to use this strategy if you have no existing IRA assets at the end of the year and your income is too high for direct IRA deposits.
What is the importance of IRS Form 8606 in this process?
IRS Form 8606 is crucial for accurate tax reporting of your non-deductible contributions and conversions related to the Backdoor Roth IRA.
When is the deadline for Roth IRA payments for the 2024 tax year?
The deadline for making Roth IRA payments for the 2024 tax year is April 15, 2025.
List of Sources
- Understand the Backdoor Roth IRA Concept
- Backdoor Roth IRA: Advantages and Tax Implications Explained (https://investopedia.com/terms/b/backdoor-roth-ira.asp)
- Backdoor Roth IRA Rules & Income Limits | Sensible Money (https://sensiblemoney.com/learn/backdoor-roth-ira-income-limits)
- Backdoor Roth IRA for High Earners | U.S. Bank (https://usbank.com/retirement-planning/financial-perspectives/backdoor-roth-ira-strategy.html)
- Backdoor Roth IRA 2025: A Step by Step Guide with Vanguard – Physician on FIRE (https://physicianonfire.com/backdoor)
- Backdoor Roth IRA | Is an IRA conversion right for you | Fidelity (https://fidelity.com/learning-center/personal-finance/backdoor-roth-ira)
- Set Up Your Non-Deductible IRA Contribution
- Effective Backdoor Roth Strategy: Rules, IRS Form 8606 (https://kitces.com/blog/backdoor-roth-conversion-strategy-traditional-ira-tax-planning)
- Publication 590-A (2024), Contributions to Individual Retirement Arrangements (IRAs) | Internal Revenue Service (https://irs.gov/publications/p590a)
- What is a non-deductible IRA? (https://empower.com/the-currency/money/non-deductible-ira)
- What Is a Non-Deductible IRA? | SoFi (https://sofi.com/learn/content/what-is-non-deductible-ira)
- Your Guide To Nondeductible IRA Contributions (https://rocketmoney.com/learn/investing/nondeductible-ira)
- Convert to a Roth IRA
- Should Your Clients Convert to a Roth Before Tax Cuts Expire? (https://asppa-net.org/news/2025/3/should-your-clients-convert-to-a-roth-before-tax-cuts-expire)
- Is Social Security Income Taxable? How to Calculate Taxes (https://ml.com/articles/roth-ira-conversion.html)
- How do I enter a backdoor Roth IRA conversion? (https://ttlc.intuit.com/turbotax-support/en-us/help-article/retirement-benefits/enter-backdoor-roth-ira-conversion/L7gGPjKVY_US_en_US)
- Backdoor Roth IRA: What it is and how to set it up | Vanguard (https://investor.vanguard.com/investor-resources-education/article/how-to-set-up-backdoor-ira)
- Navigate Common Challenges and Considerations
- The Backdoor Roth IRA and Three Mistakes to Avoid (https://wealthkeel.com/blog/the-backdoor-roth-ira-and-three-mistakes-to-avoid)
- Backdoor Roth IRA? Avoid These 5 Mistakes (https://morningstar.com/personal-finance/backdoor-roth-ira-avoid-these-5-mistakes)
- The Backdoor Roth IRA (Don’t make these conversion mistakes) (https://wealthgenadvisor.com/the-backdoor-roth-ira-dont-make-these-conversion-mistakes)
- 17 Backdoor Roth IRA Mistakes to Avoid | White Coat Investor (https://whitecoatinvestor.com/17-ways-to-screw-up-a-backdoor-roth-ira)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading