

Overview
Investing for your newborn is a heartfelt journey, and there are wonderful options to consider.
- Custodial accounts (UGMA/UTMA)
- 529 Plans for education savings
- Roth IRAs for minors with earned income
- Custodial brokerage accounts
Each offer unique benefits that can nurture long-term wealth.
Imagine starting this journey early, harnessing the power of compound interest to help your child’s future shine brighter. Each account type comes with its own set of features designed to meet your family’s needs.
As parents, it’s essential to define your financial goals. What do you envision for your child’s future? By selecting the most suitable investment option, you’re not just saving money; you’re investing in their dreams.
Remember, you’re not alone in this. Together, we can navigate this journey, ensuring that your family’s values and aspirations guide your financial choices. Let’s take this important step for your child’s future, embracing the possibilities that lie ahead.
Key Highlights:
- Investment accounts for children serve to save for education, teach financial literacy, and build wealth.
- Custodial funds (UGMA/UTMA) allow adults to manage assets for minors until they reach adulthood, with funds irrevocably designated for the beneficiary.
- 529 Plans are tax-advantaged accounts specifically for education savings, allowing tax-free growth and withdrawals for qualified expenses.
- Roth IRAs for minors can facilitate tax-free growth if the child has earned income, offering flexibility for future financial needs.
- Brokerage services enable minors to invest in stocks and bonds, promoting early engagement with financial markets.
- Starting investment accounts early can significantly enhance wealth accumulation through compound interest.
- The first $1,350 of unearned income for minors is tax-exempt, impacting the choice of investment accounts.
- Key steps for choosing an investment account include defining goals, evaluating financial situations, and researching account options.
- Common concerns include optimal investment age, tax implications, contribution amounts, and control of funds upon reaching adulthood.
Introduction
Navigating the financial landscape for your newborn can be both an exciting journey and a daunting task. Investment accounts designed specifically for children not only lay a strong foundation for future savings but also provide invaluable lessons in financial literacy. This guide explores the essential steps and options available to you, empowering you to make informed decisions that will set your child on a path to financial success.
Imagine being able to sift through the myriad of choices to uncover the best investment account that aligns with your family’s goals and aspirations. Together, we can navigate this journey toward a secure financial future.
Understand Investment Accounts for Children
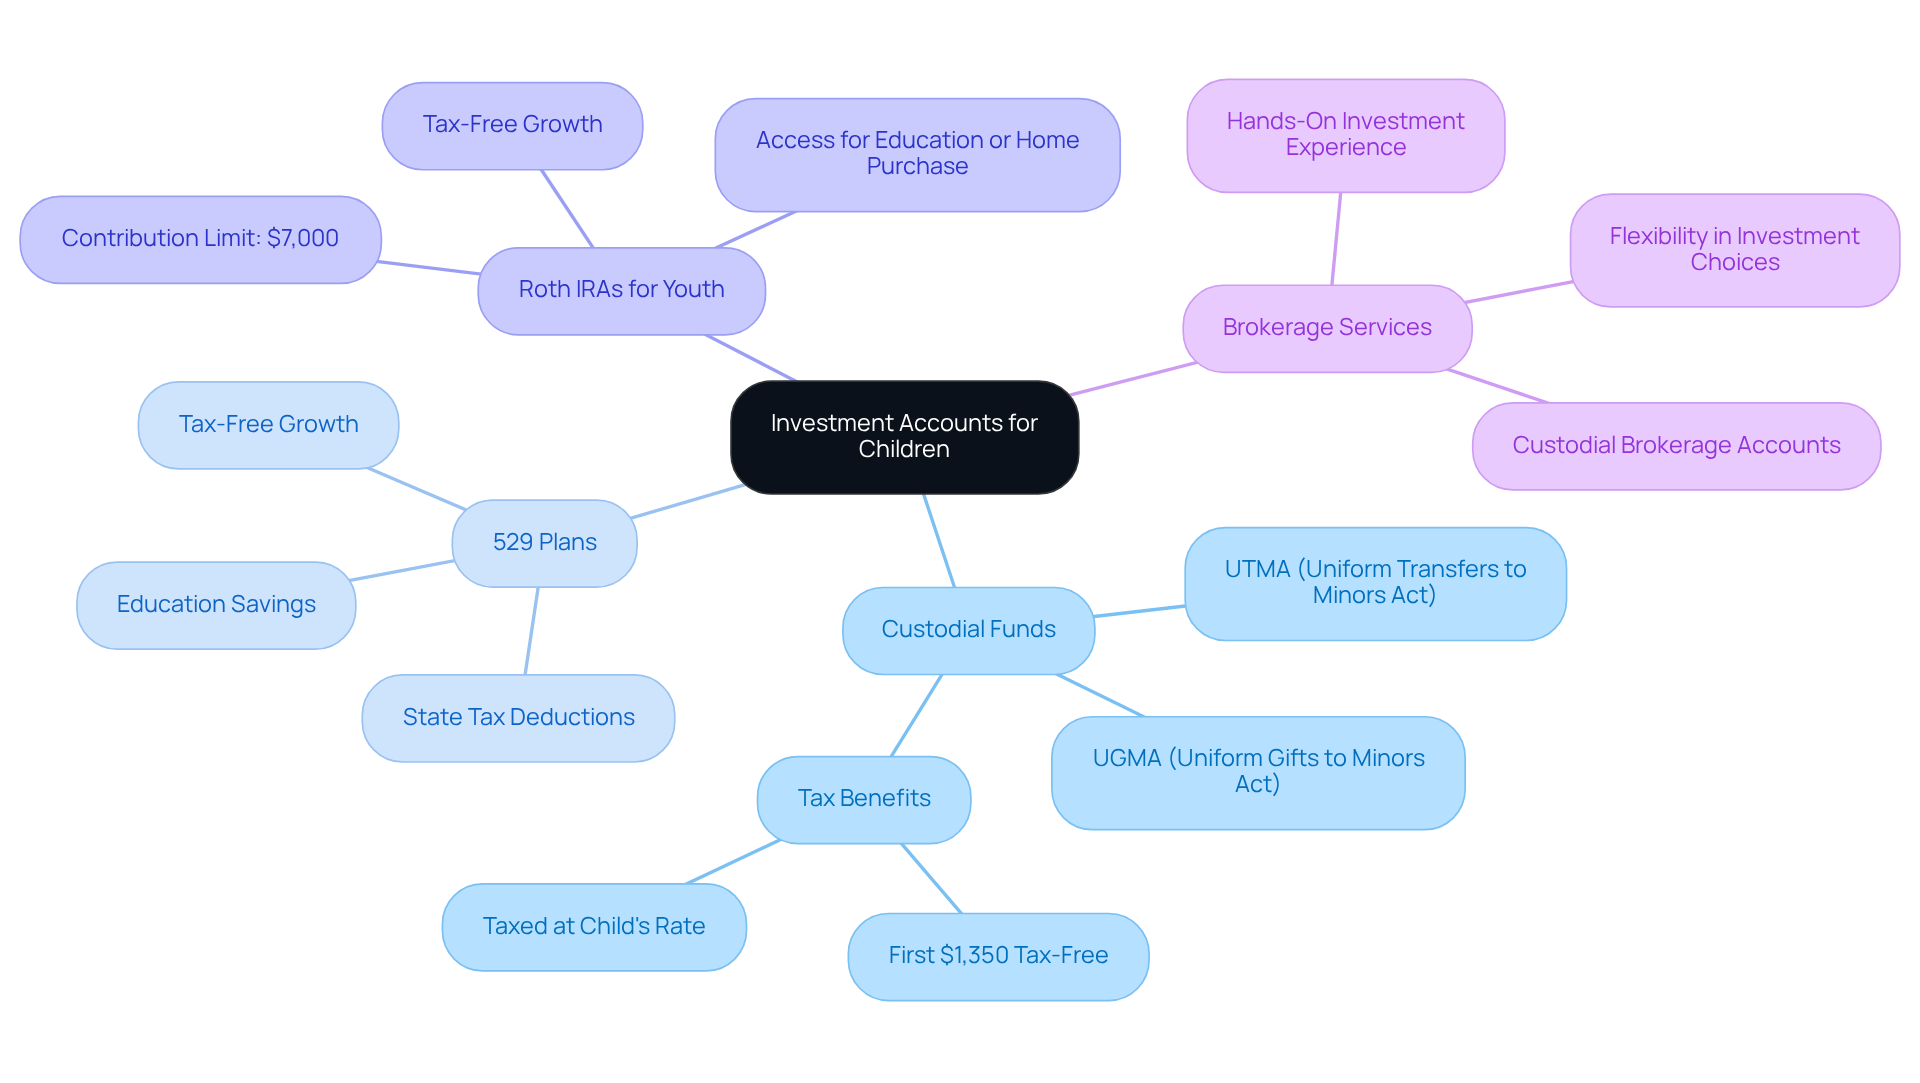
Investment plans for children, such as the best investment account for newborn, are invaluable resources for parents eager to save and invest for their kids’ futures. These financial tools can serve multiple purposes, such as education savings, teaching financial literacy, and building long-term wealth. Understanding the various types of accounts available is essential:
-
Custodial Funds: These arrangements, including UGMA (Uniform Gifts to Minors Act) and UTMA (Uniform Transfers to Minors Act), allow adults to oversee assets for minors until they reach the age of majority, typically 18 or 21, depending on state regulations. The custodian has significant discretion regarding the funds, enabling the purchase and sale of securities and making withdrawals for the minor’s benefit. Once assets are contributed, they cannot be reclaimed by the contributor, ensuring that the funds are irrevocably designated for the beneficiary.
-
529 Plans: Specifically designed for education savings, 529 plans offer considerable tax advantages when funds are used for qualified educational expenses. These funds allow for tax-free growth and withdrawals, making them a fantastic option for parents focused on financing their children’s education.
-
Roth IRAs for Youth: If a minor has earned income, a custodial Roth IRA can be a powerful way to save for retirement. Contributions grow without tax, and the funds can be utilized for specific purposes, like education or a first home, providing flexibility for future financial needs. In 2025, the contribution limit for custodial Roth IRAs is set at $7,000 or the total compensation for the year of the dependent, whichever is lower, applicable to those under 50.
-
Brokerage Services: These services offer a broader range of options for investing, including stocks, bonds, and ETFs. They can be opened in the minor’s name with a custodian, allowing for hands-on investment experience. Custodial brokerage services provide flexibility and ease, enabling young individuals to engage with markets early on, fostering economic literacy.
Real-world examples illustrate the benefits of custodial arrangements. For instance, a case study on guardianship funds for young investors highlights how these funds empower kids to learn money management and prepare for their financial futures. Additionally, investing early can harness the power of compound interest, significantly enhancing wealth accumulation over time.
The initial $1,350 of unearned income for minors is tax-exempt for the tax year 2025, while amounts exceeding $2,700 are taxed at the parent’s rate. This tax structure underscores the importance of custodial funds in educating youngsters about financial responsibility while optimizing their growth potential.
By understanding these funding options, parents can effectively navigate the world of financial planning for their children, including the best investment account for newborn, ensuring a solid foundation for their future economic success. Together, we can embark on this journey, providing the support and guidance needed to secure a brighter future for our families.
Explore Types of Investment Accounts Suitable for Newborns
When it comes to selecting the best investment account for a newborn, it’s essential to explore the best options available. Here are a few to consider:
-
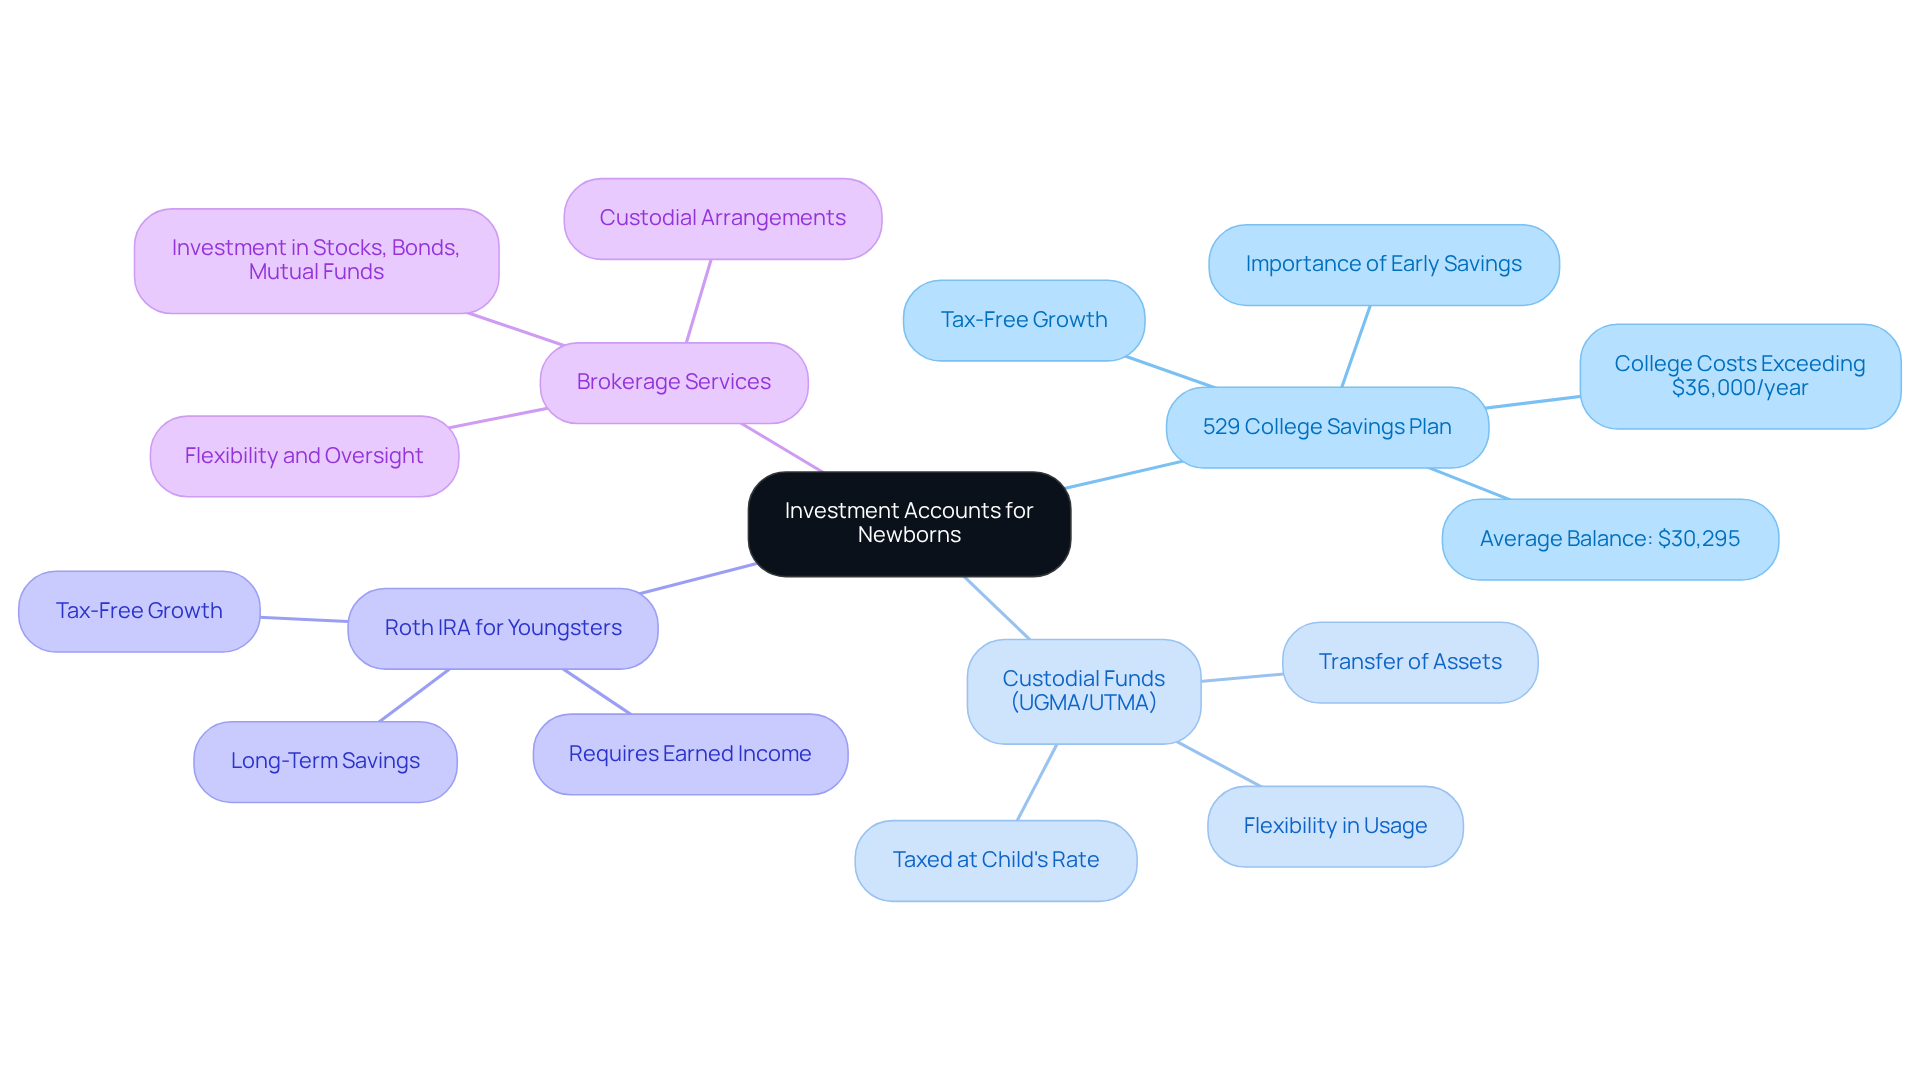
529 College Savings Plan: This plan is a wonderful choice for parents eager to save for their child’s education. Contributions grow tax-free, and withdrawals for qualified education expenses are also tax-free. Imagine starting your child’s educational journey with an average balance of approximately $30,295 in a 529 plan by 2025. As of 2018, parents saving for children aged 0-6 had set aside an average of $9,200, highlighting the importance of beginning early. With college costs exceeding $36,000 per year, starting to save now can make a significant difference.
-
Custodial Funds (UGMA/UTMA): These accounts allow you to transfer assets to your child, which can be used for any purpose once they reach adulthood. While they offer flexibility, it’s important to remember that earnings may be subject to taxes, potentially impacting overall asset growth. However, custodial funds can be taxed at your child’s rate, which may be lower than yours, presenting a possible tax benefit.
-
Roth IRA for Youngsters: If your child has earned income, such as from a part-time job, a Roth IRA can be a fantastic long-term savings option. This plan allows for tax-free growth and withdrawals during retirement, making it a strategic choice for securing your child’s financial future.
-
Brokerage Services: These services provide a wide array of opportunities for you to invest in stocks, bonds, and mutual funds. They can be set up as custodial arrangements until your child reaches the age of majority, offering both flexibility and oversight over financial options.
Each of these options presents its own unique advantages and considerations when choosing the best investment account for a newborn. It’s essential to evaluate your financial goals and your child’s future needs. Remember, we’re here for you on this journey, guiding you towards making the best decisions for your family.
Follow Steps to Choose the Right Investment Account
Choosing the right investment account for your newborn is a heartfelt journey that involves several key steps:
-
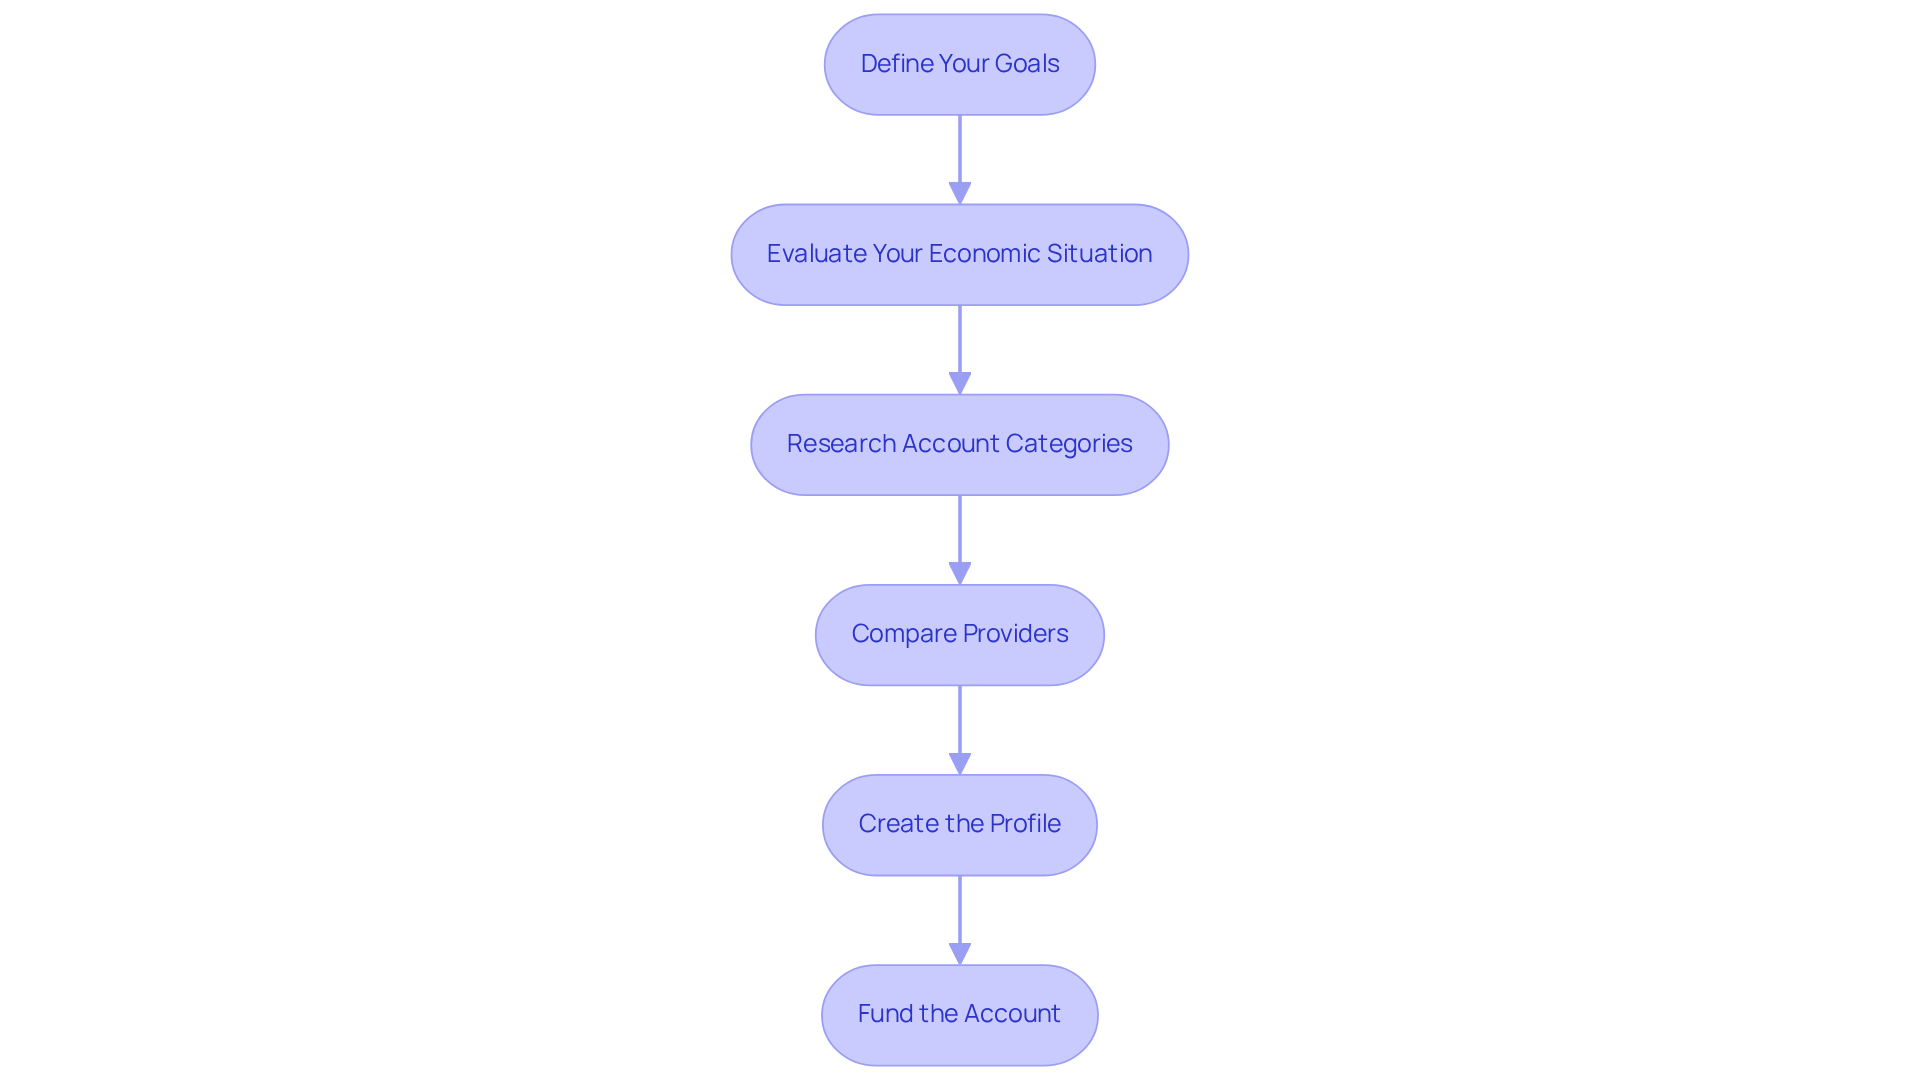
Define Your Goals: Start by envisioning what you hope to achieve with this account. Are you saving for education, nurturing general wealth, or planning for retirement? Setting clear objectives will gently guide your financial strategy, ensuring it’s aligned with your family’s dreams.
-
Evaluate Your Economic Situation: Take a moment to reflect on your current financial landscape. Consider how much you can contribute and what your risk tolerance looks like. This self-assessment will help you narrow down your options and ensure that your investment choices resonate with your financial capacity.
-
Research Account Categories: Explore the various financial arrangements available, such as 529 plans, custodial accounts, or Roth IRAs. Understanding their unique advantages and drawbacks is essential as you navigate this important decision for your family.
-
Compare Providers: Look for institutions that offer the accounts you’re interested in. Compare their fees, investment options, and customer service. It’s crucial to find a provider that understands your family’s financial needs, especially since many consumers feel that financial institutions often fall short in providing adequate support.
-
Create the Profile: Once you’ve identified the ideal account type and provider, follow their process to establish your profile. This typically involves filling out an application and providing necessary documentation, which can feel like a big step but is so important for your child’s future.
-
Fund the Account: Make that initial deposit to kick off your funding journey. Consider setting up automatic contributions to help grow the balance over time. Remember, putting aside modest sums consistently is vital for building wealth, and automatic contributions can help achieve steady growth, even during those unpredictable economic times when many are saving less.
As the saying goes, ‘The best time to plant a tree was 20 years ago. The second best time is now.’ Starting early with your financial commitments can yield significant benefits down the road. By following these steps, you can confidently select the right savings account for your newborn, knowing that you’re laying a strong foundation for their future. Together, we can navigate this journey with care and purpose.
Address Common Questions and Concerns About Investment Accounts
As parents, it’s natural to have questions and concerns about the best investment account for newborns. Here are some common inquiries that can help guide you on this journey:
-
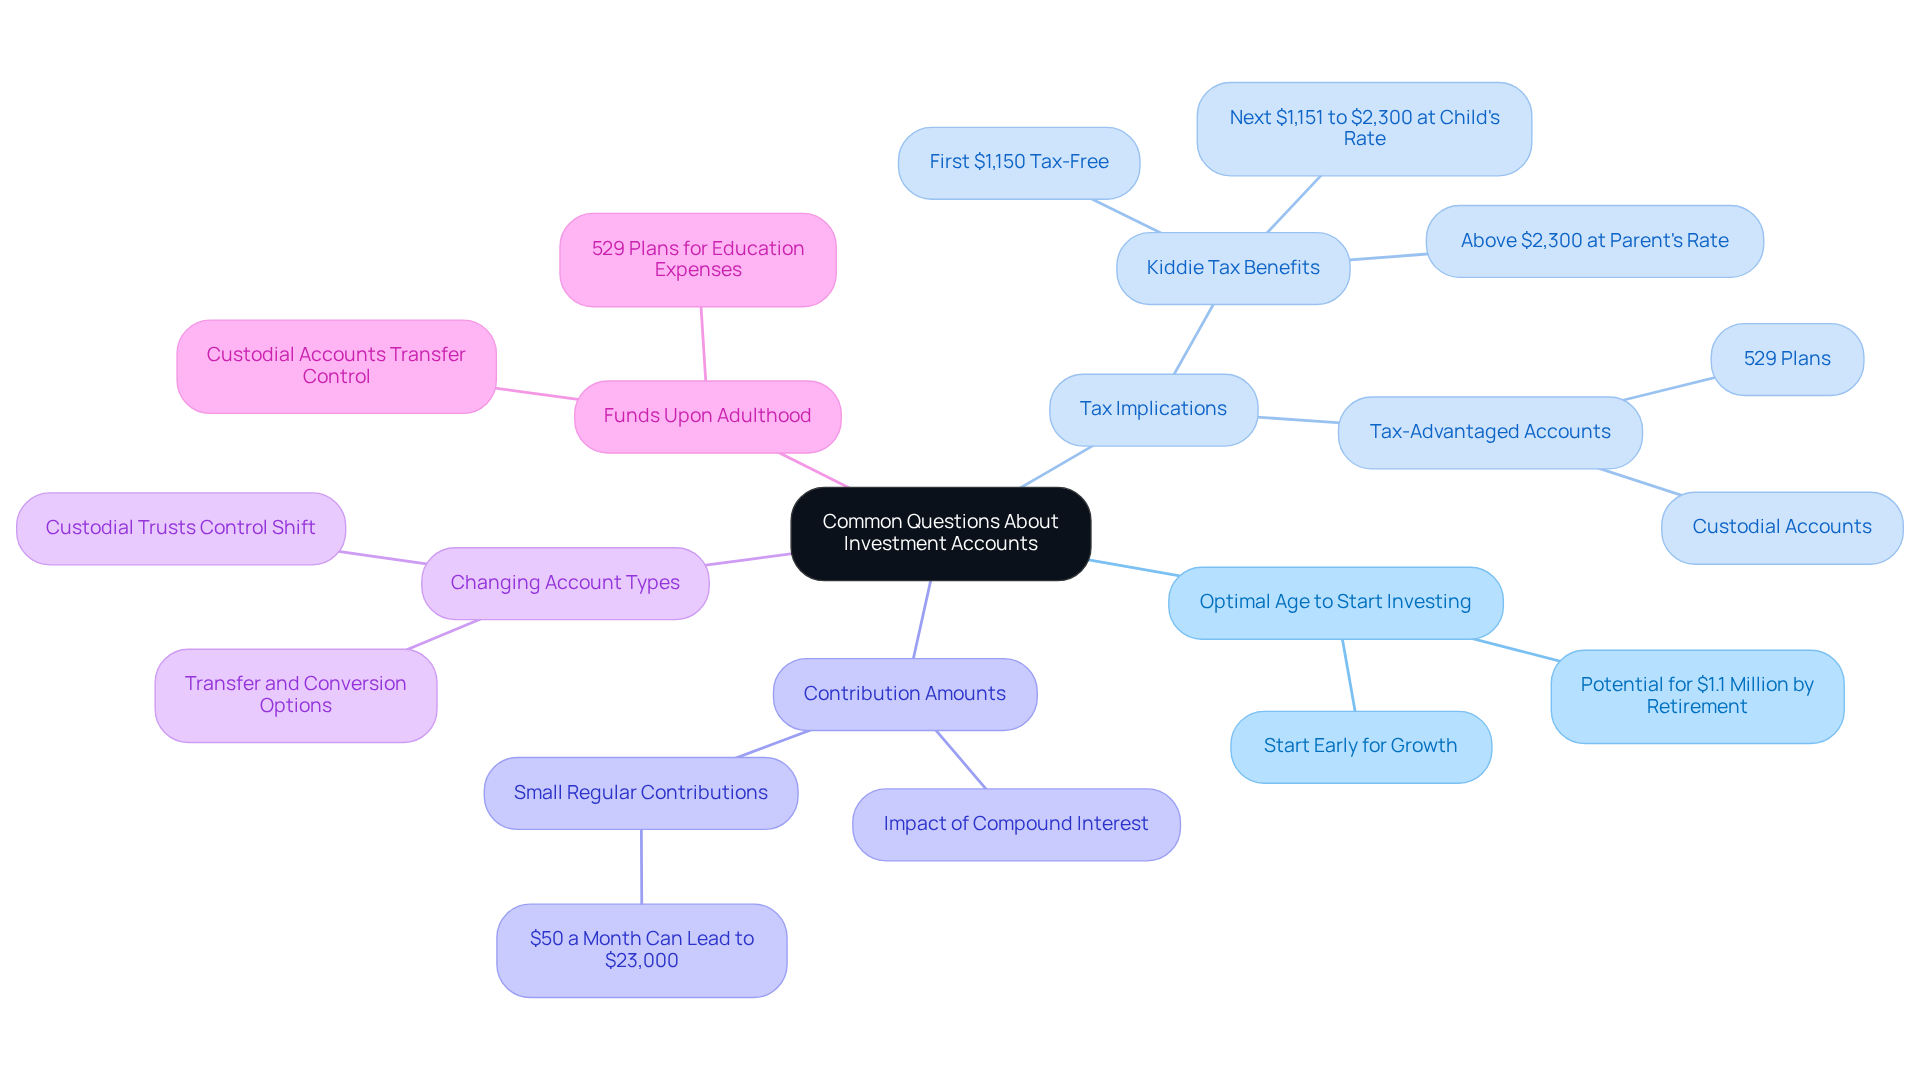
What is the optimal age to begin investing for my offspring? The earlier you start, the more time your assets have to grow. Research shows that beginning as soon as possible can lead to significant long-term benefits. Imagine your child potentially accumulating nearly $1.1 million by retirement if they invest consistently. As the saying goes, “The best time to plant a tree was 20 years ago. The second best time is now.”
-
Are there tax implications for investment portfolios? Yes, different accounts have varying tax treatments. For instance, the Kiddie Tax allows the first $1,150 of a child’s unearned income to be tax-free, while earnings between $1,151 and $2,300 are taxed at the child’s rate. Custodial funds and 529 plans also offer specific tax benefits, such as tax-free growth for education costs.
-
How much should I contribute? This really depends on your financial situation and goals. Even small, regular contributions can add up over time, thanks to the power of compound interest. For example, investing just $50 a month starting at age 5 could lead to over $23,000 by the time they head off to college.
-
Can I change the type of my profile later? Some services allow for transfers or conversions, but it’s important to understand the regulations and potential penalties associated with each type. For instance, custodial trusts generally shift control to the minor when they reach the age of majority.
-
What occurs to the funds when my offspring reaches adulthood? Most custodial accounts transfer control to the child upon reaching the age of majority, while 529 plans can continue to be used for education expenses, offering flexibility for future financial needs.
By addressing these questions, we hope you feel more informed and confident in your choice of the best investment account for newborns. Remember, we’re here for you, and together, we can navigate this journey toward a secure financial future for your family.
Conclusion
Navigating the landscape of investment accounts for newborns is a crucial step in securing a prosperous future for your child. By understanding the various options available—such as custodial funds, 529 plans, Roth IRAs, and brokerage services—you can make informed decisions that align with your financial goals and your child’s needs. Each account type offers unique benefits, allowing families to choose the best investment account tailored to their circumstances.
Throughout this journey, key insights emphasize the importance of:
- Starting early
- Setting clear financial objectives
- Evaluating the different investment vehicles
Imagine harnessing the power of compound interest, enjoying tax advantages, and experiencing the flexibility of custodial accounts. These are essential factors in fostering financial literacy and responsibility among young investors. By following a structured approach to selecting an investment account, you can lay a solid foundation for your child’s financial future.
Ultimately, investing for your newborn is not just about financial growth; it’s about empowering the next generation with the knowledge and resources needed to thrive. Taking the first steps now can yield significant benefits down the road, making it imperative for you to act with intention and foresight. Together, we can prioritize financial education and strategic planning, ensuring that your children are well-equipped to navigate the complexities of personal finance in the years to come.
Frequently Asked Questions
What are investment accounts for children?
Investment accounts for children are financial tools that help parents save and invest for their children’s futures, serving purposes such as education savings, teaching financial literacy, and building long-term wealth.
What are custodial funds?
Custodial funds, including UGMA (Uniform Gifts to Minors Act) and UTMA (Uniform Transfers to Minors Act), allow adults to manage assets for minors until they reach the age of majority (typically 18 or 21). The custodian has discretion over the funds, which can be used for the minor’s benefit.
What are 529 plans?
529 plans are specifically designed for education savings and offer significant tax advantages when funds are used for qualified educational expenses, allowing for tax-free growth and withdrawals.
How do custodial Roth IRAs work for minors?
A custodial Roth IRA allows minors with earned income to save for retirement, with contributions growing tax-free. The funds can also be used for specific purposes like education or a first home.
What is the contribution limit for custodial Roth IRAs in 2025?
In 2025, the contribution limit for custodial Roth IRAs is $7,000 or the total compensation for the year of the dependent, whichever is lower, applicable to those under 50.
What are custodial brokerage services?
Custodial brokerage services enable minors to invest in a broader range of options, including stocks, bonds, and ETFs. These accounts are managed by a custodian and allow young individuals to engage with the markets, fostering economic literacy.
How can custodial arrangements benefit children?
Custodial arrangements empower children to learn money management skills and prepare for their financial futures, while also allowing them to benefit from compound interest for wealth accumulation over time.
What is the tax structure for unearned income for minors in 2025?
For the tax year 2025, the initial $1,350 of unearned income for minors is tax-exempt, while amounts exceeding $2,700 are taxed at the parent’s rate.
Why is it important for parents to understand these investment options?
Understanding these investment options allows parents to effectively navigate financial planning for their children, ensuring a solid foundation for their future economic success.
List of Sources
- Understand Investment Accounts for Children
- Best Investment Accounts for Kids in 2025 | The Motley Fool (https://fool.com/investing/how-to-invest/investment-accounts-for-kids)
- Investing for Kids: 6 Best Investment Account Options – NerdWallet (https://nerdwallet.com/article/investing/set-kids-brokerage-account)
- Best Custodial Investment Accounts | Bankrate (https://bankrate.com/investing/best-custodial-investment-accounts)
- Child Savings Accounts: Overview and Analysis (https://congress.gov/crs-product/R48554)
- Explore Types of Investment Accounts Suitable for Newborns
- 529 College Savings Plan Statistics | BestColleges (https://bestcolleges.com/research/529-college-savings-plan-statistics)
- 529 Plan And College Savings Statistics (https://thecollegeinvestor.com/529-plan-and-college-savings-statistics?srsltid=AfmBOorC8zWnQsx9QaoVKV88TZvuYMgam_yjY–dCBnb_z25ABjE6dls)
- Average 529 plan balance: How do you compare? (https://savingforcollege.com/article/average-529-plan-balance-how-do-you-compare)
- Report: More U.S. families choosing 529 plans to save for college – Utah System of Higher Education (https://ushe.edu/report-more-u-s-families-choosing-529-plans-to-save-for-college)
- 529 Plan Program Statistics (https://ici.org/research/stats/529s)
- Follow Steps to Choose the Right Investment Account
- 5 Amazing Investing Quotes To Share With Your Kids (https://bluetreesavings.com/post/5-amazing-investing-quotes)
- 54 Personal Finance Statistics & Facts in 2025 [SOURCES INCLUDED] (https://moneywise.com/research/personal-finance-statistics)
- Consumer Financial Wellness Stats, Expectations, Graphics, and More | MX (https://mx.com/blog/financial-wellness-stats)
- Primary financial goals of Americans by generation| Statista (https://statista.com/statistics/935650/primary-financial-goals-usa-by-generation)
- Address Common Questions and Concerns About Investment Accounts
- 5 Amazing Investing Quotes To Share With Your Kids (https://bluetreesavings.com/post/5-amazing-investing-quotes)
- Why You Should Start Investing for Your Kids Right Away (https://nasdaq.com/articles/why-you-should-start-investing-for-your-kids-right-away)
- Study: 42% of Parents Aren’t Teaching Their Kids to Invest Long-Term | The Motley Fool (https://fool.com/research/parents-kids-investing)
- 90 Warren Buffett Quotes on Investing, Business, and Life (https://sarwa.co/blog/warren-buffett-quotes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading