

Overview
To meet the minimum requirements for Private Wealth Management (PWM) services, imagine starting your journey with investable assets of $250,000. Many firms, especially those focused on high-net-worth clients, often look for $2 million or more.
It’s important to:
- Evaluate your financial situation.
- Set meaningful monetary goals.
- Consult with a compassionate financial advisor.
This support ensures that your aspirations align with PWM services, guiding you and your family toward achieving your financial objectives together. Remember, we’re here for you as you navigate this journey.
Key Highlights:
- Private Wealth Management (PWM) offers tailored services for high-net-worth individuals, including investment management, monetary planning, tax optimization, and estate planning.
- Investment strategies in PWM aim for higher returns, with clients often expecting annual gains of 15.6% compared to the expert-recommended 7%.
- Minimum asset requirements for PWM services vary, typically starting at $250,000, with higher-end firms requiring $2 million or more.
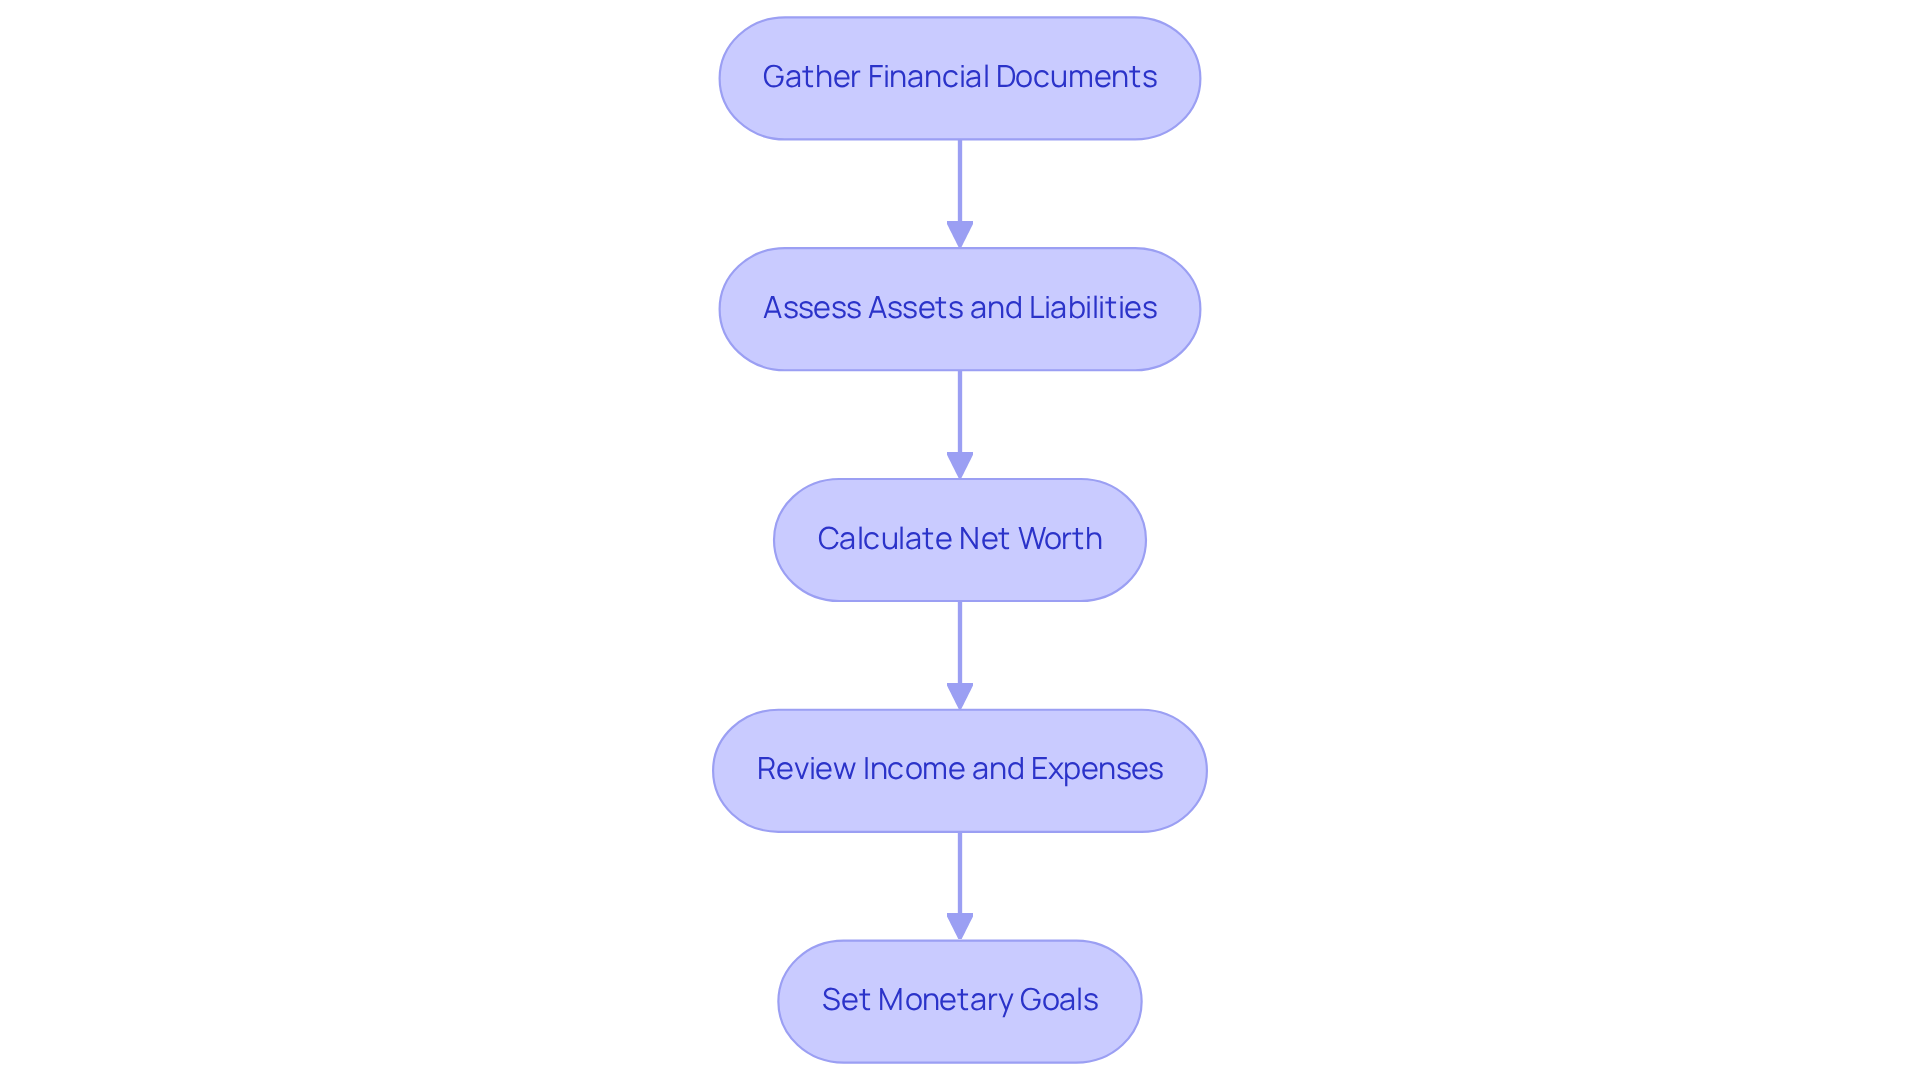
- Evaluating your financial situation involves gathering documents, assessing assets and liabilities, calculating net worth, reviewing income and expenses, and setting monetary goals.
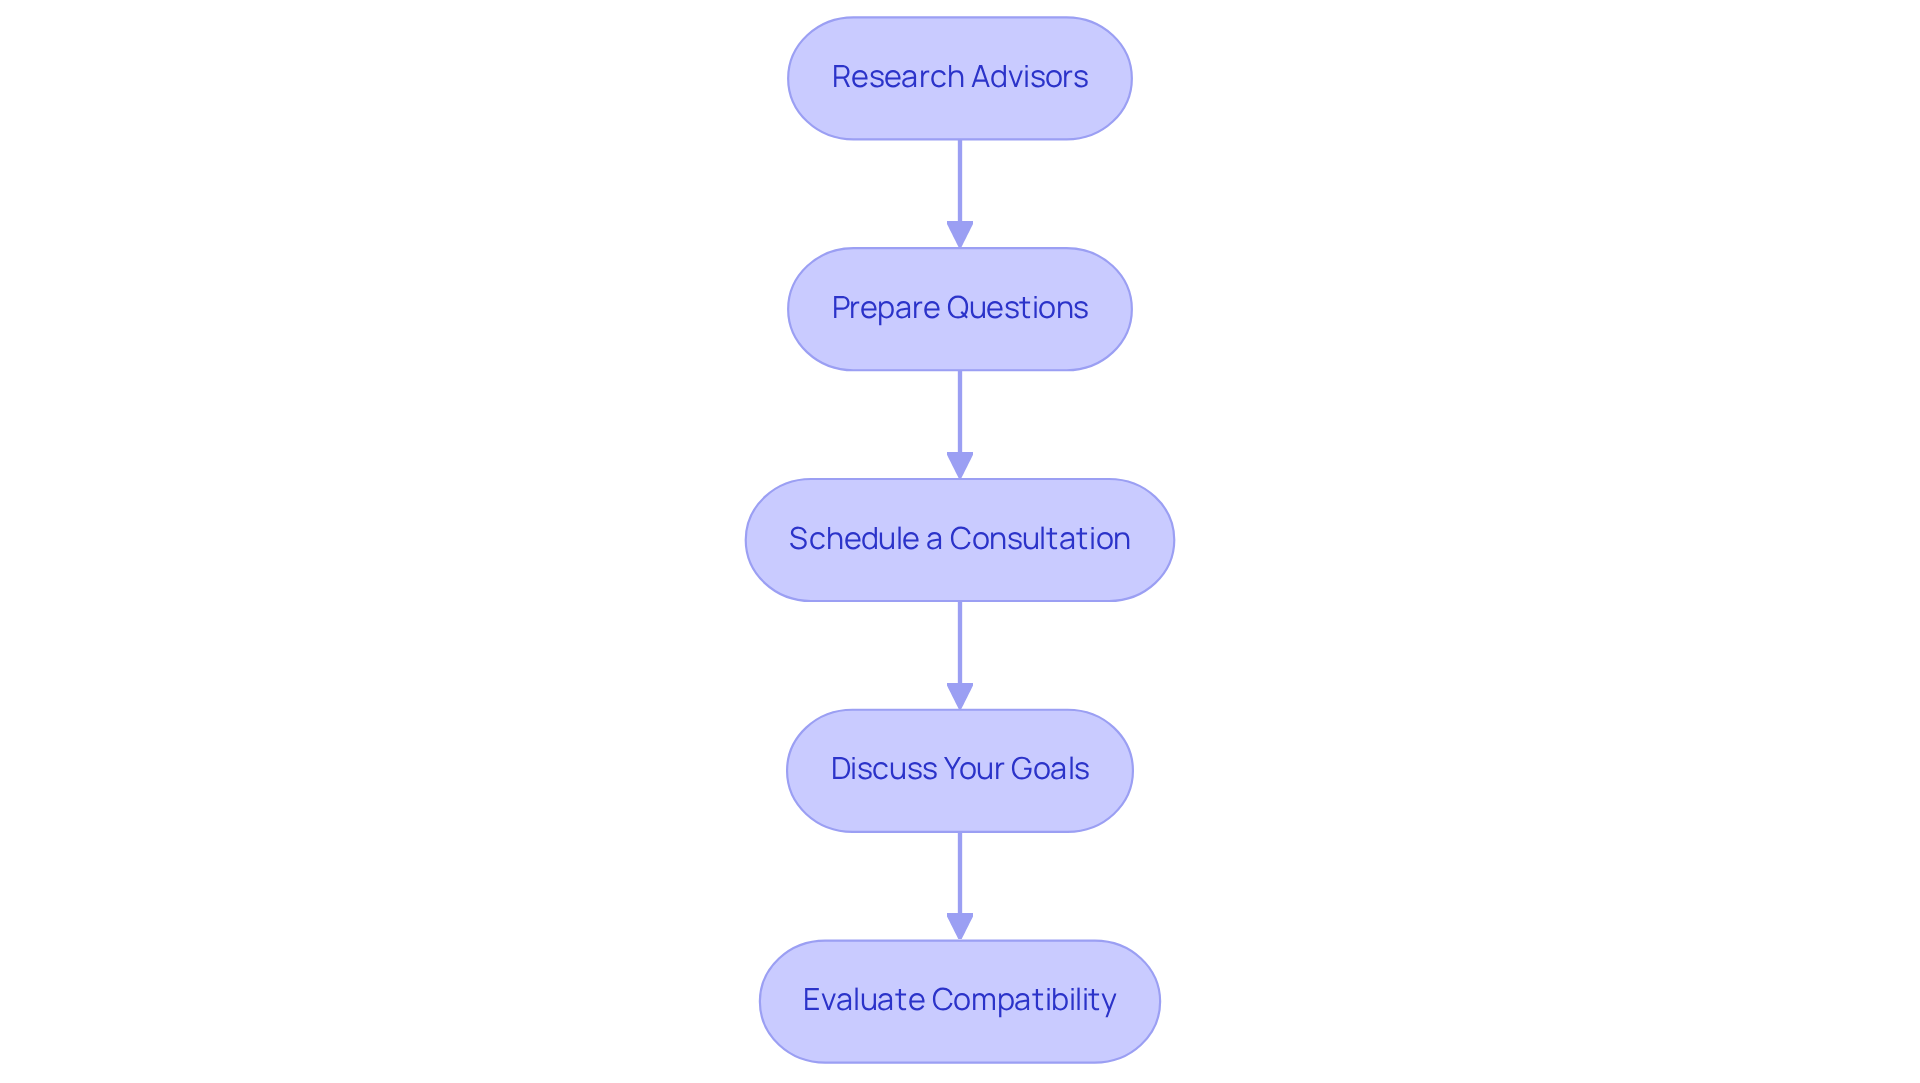
- Consulting with a financial advisor is crucial; research potential advisors, prepare questions, and assess compatibility to ensure a productive relationship.
- Working with a financial advisor can improve financial habits and outcomes, leading to greater confidence in financial decisions.
Introduction
Navigating the intricate landscape of private wealth management can feel overwhelming, especially for families striving to secure their financial futures. This specialized service, crafted for high-net-worth individuals, not only includes investment management and tax optimization but also offers personalized strategies that align with your family’s unique financial goals.
It’s important to understand the minimum asset requirements to access these services, as they can differ significantly among firms.
Imagine if you could unlock the full potential of private wealth management—what steps must your family take to meet these thresholds? Together, we can navigate this journey and ensure your family’s financial well-being.
Understand Private Wealth Management Basics
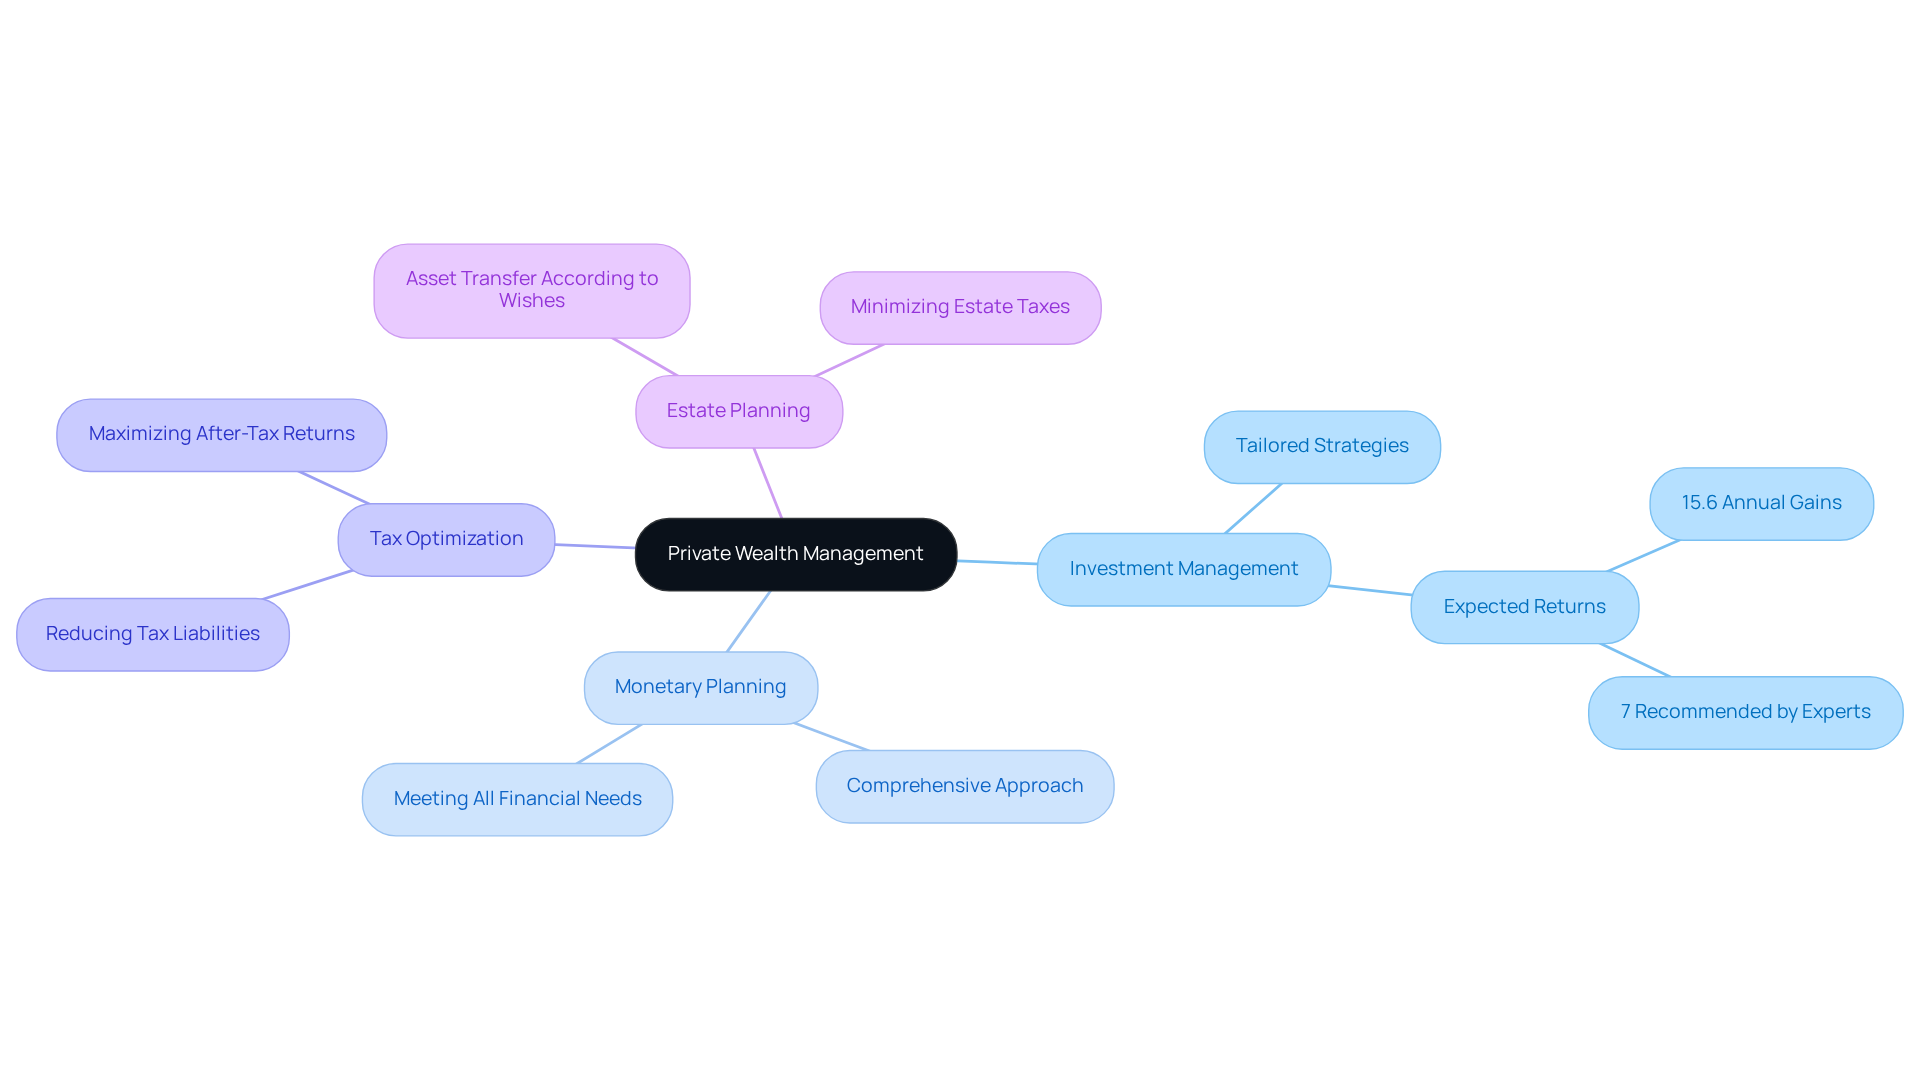
Private asset management (PWM) is a specialized service crafted for high-net-worth individuals and families, offering essential services like investment management, planning, tax optimization, and estate planning. The primary goal of PWM is to provide personalized strategies that align with your financial objectives and risk tolerance. Understanding these basics is crucial for families like yours.
Imagine having a partner who truly understands your unique financial journey. Key components of PWM include:
- Investment Management: Tailored investment strategies designed to grow and protect your wealth. Investors often expect annual gains of 15.6%, significantly higher than the 7% recommended by experts, highlighting the importance of effective investment management.
- Monetary Planning: A comprehensive approach that considers every aspect of your financial life, ensuring that all your needs are met.
- Tax Optimization: Strategic methods to reduce tax liabilities while maximizing after-tax returns, enhancing your overall financial efficiency.
- Estate Planning: Helping you transfer assets according to your wishes while minimizing estate taxes, preserving your family’s resources.
As financial experts note, “Clients seek advisors who are informed, reliable, and attentive listeners.” This underscores the importance of connecting with a money manager who truly listens to your needs. Familiarizing yourself with these concepts not only helps you meet the private wealth management minimum asset criteria often linked to PWM services but also emphasizes the significant benefits of working with a financial manager.
As families increasingly strive to secure their financial futures, grasping the fundamentals of PWM becomes essential for making informed decisions that align with your long-term goals. Bright Advisers, focusing on families with young children and committed to transparency and cost reduction, exemplifies the kind of partner you should consider in your financial journey. Together, we can navigate this path, ensuring a brighter future for your family.
Identify Minimum Asset Requirements
Navigating the world of private financial services (PWM) can feel overwhelming, especially for young parents. It’s important to understand that the private wealth management minimum asset criteria can vary significantly between firms, typically ranging from $250,000 to several million dollars in investable assets. Here are some common thresholds to consider:
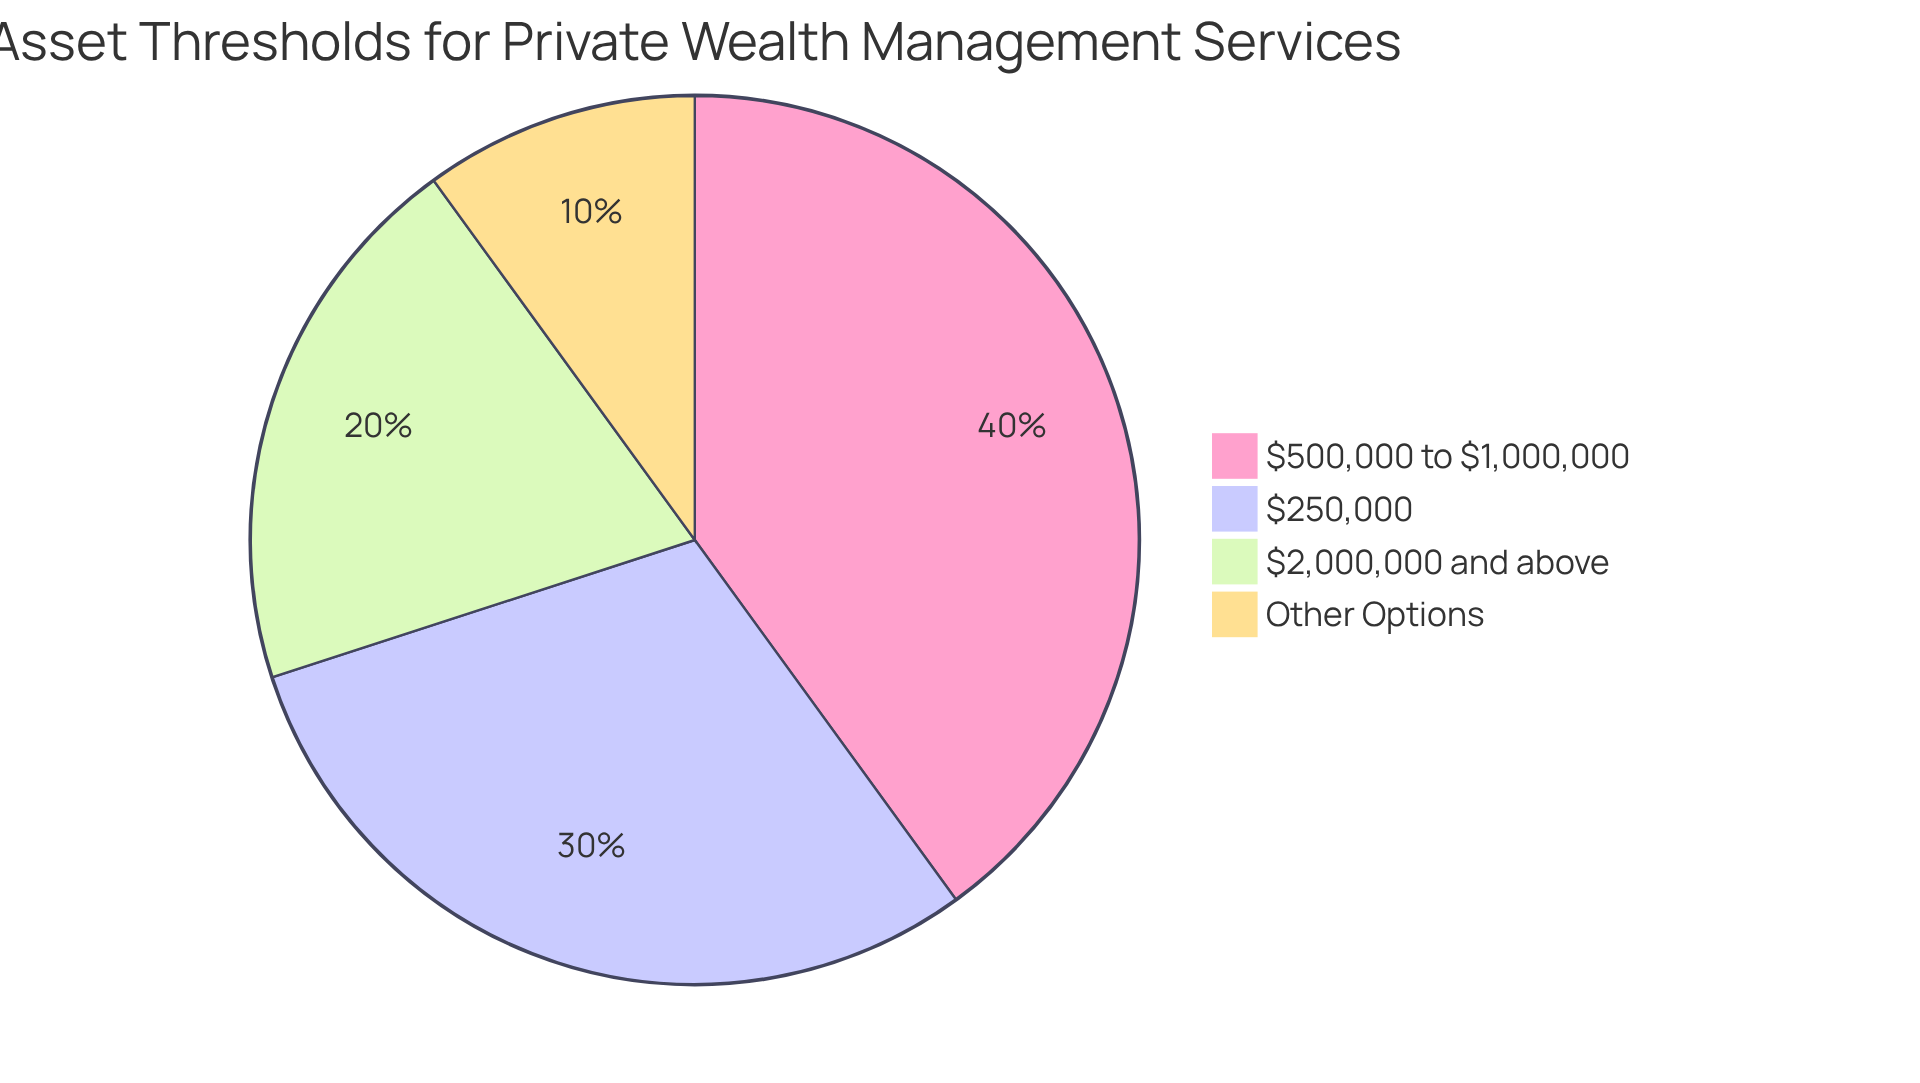
- $250,000: Some firms provide entry-level PWM services for clients with this amount, making it a great starting point for those embarking on their wealth management journey. Generally, high net worth begins around $250,000 to $500,000.
- $500,000 to $1,000,000: Many established companies set their private wealth management minimum at this range, catering to a broader audience, including families looking to build multi-generational financial security.
- $2,000,000 and above: High-end firms often set a private wealth management minimum of $2 million or more, focusing on ultra-high-net-worth individuals who seek comprehensive and tailored wealth strategies. For instance, companies like Fidelity may ask for $2 million in assets to access their ‘private financial services,’ while Vanguard might require $5 million for specialized personal consulting.
To find the right fit for your family’s needs, it’s essential to research various PWM firms and understand their private wealth management minimum requirements. This exploration will help you determine if you qualify for their services and what level of personalized attention you can expect. Additionally, keep in mind that many advisors charge fees ranging from 0.25% to 2% annually, depending on the amount of money they manage. Understanding these thresholds is crucial for families aiming to secure their financial future while navigating the complexities of wealth management.
Moreover, don’t overlook lower-cost alternatives like online platforms or robo-advisors. These options can serve as valuable entry points for individuals with fewer assets, providing accessible choices for those just starting their financial journey. Remember, we’re here for you, and together, we can navigate this journey toward financial security.
Evaluate Your Financial Situation
To effectively evaluate your financial situation, let’s walk through some essential steps together:
-
Gather Financial Documents: Begin by collecting all relevant documents, such as bank statements, investment accounts, tax returns, and debt statements. This foundational step ensures you have a complete view of your economic landscape, allowing you to understand your starting point.
-
Assess Assets and Liabilities: Take a moment to compile a detailed list of your assets—like savings, investments, and property—alongside your liabilities, including mortgages, loans, and credit card debt. Understanding this balance is crucial for a realistic monetary evaluation and can provide clarity on where you stand.
-
Calculate Net Worth: Now, determine your net worth by subtracting total liabilities from total assets. This figure is not just a number; it’s a vital indicator of your economic well-being and is often a key metric evaluated by wealth managers.
-
Review Income and Expenses: Analyze your monthly income against your expenses to identify spending patterns and potential areas for improvement. This assessment can uncover insights into your spending habits and assist you in making informed changes. Remember, the average consumer debt among Americans was nearly $17 trillion by the end of 2022, highlighting the importance of tracking your spending.
-
Set Monetary Goals: Clearly define your short-term and long-term monetary objectives, such as retirement planning, funding your children’s education, or purchasing a home. Setting these objectives offers guidance and inspiration for your monetary journey. Additionally, consider establishing automatic payments for savings, as recommended by expert Ransom-Cooper, to enhance your savings consistency.
Carrying out this comprehensive assessment not only clarifies your monetary situation but also prepares you for conversations regarding the private wealth management minimum. It’s important to note that many young parents face challenges with money management, with the median debt for Americans under 35 years being $52,200 and the median net worth for this age group at $39,040. This self-evaluation is a crucial step toward informed economic decision-making. As Ransom-Cooper wisely observes, understanding where your money goes is the first step to enhancing your economic well-being. By following these steps, you’re not just preparing yourself to interact efficiently with asset advisors; you’re also taking significant strides toward a more promising economic future. Together, we can navigate this journey with confidence.
Consult with a Financial Advisor
After evaluating your monetary circumstances, the next essential step is to seek guidance from a wealth consultant. Imagine having someone by your side to help you navigate this journey. Here’s how to effectively approach this process:
-
Research potential mentors by seeking out those who specialize in private wealth management and have a proven track record with clients facing similar financial circumstances. This ensures they understand the unique challenges you may face.
-
Prepare Questions: Before your meeting, compile a list of essential questions to ask the consultant. Inquire about their fee structure, investment philosophy, and experience with clients like you. This will help you gauge their suitability for your needs.
-
Schedule a Consultation: Contact potential advisors to arrange an initial consultation. Many provide free sessions to discuss your monetary needs and how they can help you in reaching your objectives. It’s important to take this step; you deserve the support.
-
Discuss Your Goals: During the consultation, articulate your monetary objectives, concerns, and any specific requirements you have regarding private wealth management services. This open dialogue is vital for establishing a productive relationship. Considering that 70% of people think estate planning ought to be included in wealth management, it’s important to address this element too.
-
Evaluate Compatibility: Assess whether the consultant’s method aligns with your monetary philosophy and if you feel at ease collaborating with them. A strong advisor-client relationship is essential for long-term success. As Tim Gerend, chief distribution officer at Northwestern Mutual, observes, “What we know is that individuals build long-term connections with their consultants lasting 20, 30, or 40 years.”
Consulting with a monetary consultant can provide you with customized insights and strategies that align with your economic situation, ultimately helping you meet the private wealth management minimum criteria. Engaging with an advisor can also enhance your financial habits and outcomes; studies show that Americans who work with a financial advisor have better financial habits, superior outcomes, and greater confidence in their financial decisions. Together, we can navigate this journey toward a secure financial future for your family.
Conclusion
Understanding private wealth management (PWM) is crucial for families eager to secure their financial future. By grasping the basics, identifying minimum asset requirements, evaluating personal financial situations, and consulting with a qualified financial advisor, individuals can navigate the complexities of PWM more effectively. Each of these steps is designed to empower families, ensuring they are well-prepared to meet the criteria necessary for accessing tailored wealth management services.
This article outlines critical components of PWM, including:
- investment management
- monetary planning
- tax optimization
- estate planning
It highlights the varying minimum asset thresholds across different firms, emphasizing the importance of thorough research to find the right fit. Moreover, assessing one’s financial situation through careful documentation and goal-setting is vital for establishing a strong foundation before seeking professional advice. Engaging with a financial advisor not only enhances financial literacy but also fosters better financial outcomes.
Ultimately, taking proactive steps toward understanding and managing wealth is paramount. Families are encouraged to leverage the insights shared in this article to embark on their financial journey with confidence. The path to effective private wealth management is not just about meeting minimum requirements; it’s about crafting a strategy that aligns with personal goals and values. Embracing these principles can lead to a more secure and prosperous financial future for generations to come.
Frequently Asked Questions
What is Private Wealth Management (PWM)?
Private Wealth Management is a specialized service for high-net-worth individuals and families that includes investment management, financial planning, tax optimization, and estate planning, with the goal of providing personalized strategies that align with clients’ financial objectives and risk tolerance.
What are the key components of PWM?
The key components of PWM include Investment Management, Monetary Planning, Tax Optimization, and Estate Planning. Each component is designed to address different aspects of a client’s financial life.
How does Investment Management work in PWM?
Investment Management in PWM involves creating tailored investment strategies aimed at growing and protecting wealth. Clients often expect higher annual gains, typically around 15.6%, compared to the 7% recommended by experts.
What is the purpose of Monetary Planning in PWM?
Monetary Planning provides a comprehensive approach to managing all aspects of a client’s financial life, ensuring that their various needs are addressed effectively.
How does PWM assist with Tax Optimization?
PWM employs strategic methods to reduce tax liabilities while maximizing after-tax returns, which enhances overall financial efficiency for clients.
What role does Estate Planning play in PWM?
Estate Planning helps clients transfer their assets according to their wishes while minimizing estate taxes, thus preserving family resources.
Why is it important to connect with a financial advisor in PWM?
It is crucial to connect with a financial advisor who is informed, reliable, and an attentive listener, as this ensures that the advisor understands and meets the unique needs of the client.
How can understanding PWM benefit families?
Familiarizing oneself with the fundamentals of PWM helps families meet minimum asset criteria for PWM services and empowers them to make informed decisions that align with their long-term financial goals.
Who is Bright Advisers and what do they focus on?
Bright Advisers is a financial management firm that focuses on families with young children, emphasizing transparency and cost reduction in their services to help clients secure their financial futures.
List of Sources
- Understand Private Wealth Management Basics
- Wealth Management – Worldwide | Statista Market Forecast (https://statista.com/outlook/fmo/wealth-management/worldwide)
- Topic: Private wealth management (https://statista.com/topics/2282/private-wealth-management)
- The Most Important Wealth Management Statistics To Know (https://passivesecrets.com/wealth-management-statistics)
- Industry Statistics (https://investmentadviser.org/industry-snapshots)
- Wealth Management Statistics By Market Size and AI Impact (https://electroiq.com/stats/wealth-management-statistics)
- Identify Minimum Asset Requirements
- Wealth Management: What It Is, Costs, Minimums – NerdWallet (https://nerdwallet.com/article/investing/what-is-wealth-management)
- 77 Financial Advisor Quotes to Send to Clients (https://billgoodmarketing.com/resources/financial-advisor-quotes)
- Private Wealth Management | TD Wealth (https://td.com/ca/en/investing/wealth/private-wealth-management)
- Wealth Management Minimum | Real Thresholds And Fees (https://pillarwm.com/wealth-managements/wealth-management-minimum)
- Investment Minimums of Wealth Management Firms | Finance Strategists (https://financestrategists.com/wealth-management/investment-management/investment-minimums-of-wealth-management-firms)
- Evaluate Your Financial Situation
- Average and Median Net Worth by Age in the U.S. – NerdWallet (https://nerdwallet.com/article/finance/average-net-worth-by-age)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- Average net worth by age for Americans for 2025 (https://lexingtonlaw.com/blog/finance/average-net-worth-by-age.html)
- Top 150 Financial Planning Quotes [2025] (https://digitaldefynd.com/IQ/financial-planning-quotes)
- 50 Empowering Quotes on Finances to Help Your Money Habits – Self. (https://self.inc/blog/quotes-on-finances)
- Consult with a Financial Advisor
- 35 Quotes for Financial Advisors on a Tough Day | Don Connelly & Associates (https://donconnelly.com/35-quotes-for-financial-advisors)
- 20+ Financial Advisor Statistics You Must Know in ([currentyear]) (https://upmetrics.co/blog/financial-advisor-statistics)
- Estate Planning Financial Advisor Statistics & Facts | Trust & Will (https://trustandwill.com/learn/financial-advisor-estate-planning-statistics-and-facts)
- Americans with a financial advisor expect to retire two years earlier according to Northwestern Mutual’s Planning & Progress Study (https://news.northwesternmutual.com/2024-07-09-Americans-with-a-financial-advisor-expect-to-retire-two-years-earlier-according-to-Northwestern-Mutuals-Planning-Progress-Study)
- Two-Thirds of Americans Say Their Financial Planning Needs Improvement (https://news.northwesternmutual.com/2023-07-24-Two-Thirds-of-Americans-Say-Their-Financial-Planning-Needs-Improvement)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Investment & Risk Management for high-income W-2 families at Bright Advisers.
Keep reading