

Overview
Opening a kids’ investing account can be a rewarding journey for parents, and there are several options to consider. Think about:
- Custodial Funds
- 529 College Savings Plans
- Roth IRAs for Kids
- Youth Brokerage Services
Each of these options offers unique benefits that can help manage and grow your child’s investments.
It’s important to understand the different account types available. Evaluating key factors like fees and tax implications can feel overwhelming, but you’re not alone in this. Utilizing educational resources can foster financial literacy, equipping your child with the knowledge they need for future financial independence.
Imagine if your child could learn the value of investing from an early age. By starting this journey together, you can instill important lessons that will benefit them for years to come. Remember, we’re here for you, guiding you through each step of this process. Together, we can navigate this journey towards securing a brighter financial future for your family.
Key Highlights:
- Custodial Funds (UGMA/UTMA) allow adults to manage assets for minors until they reach adulthood, holding diverse investments.
- 529 College Savings Plans offer tax advantages for education savings, making them a strong choice for families planning for college.
- Roth IRA for Kids enables tax-free growth and withdrawals for children with earned income, promoting long-term savings.
- Youth Brokerage Services provide investment accounts for minors, fostering financial literacy with parental guidance.
- Key factors for account selection include fees, funding alternatives, tax implications, child’s age, and ease of management.
- Bright Advisers emphasizes low fund fees and tailored wealth management solutions to enhance accessibility for families.
- Resources for teaching kids about investing include educational websites, investment apps, books, online courses, and financial literacy games.
- Engaging children in discussions about finances and involving them in investment decisions builds a foundation for financial independence.
Introduction
Navigating the world of investing can feel overwhelming, especially when you’re focused on securing a bright financial future for your children. As parents, you face the important task of choosing the right investment account to nurture your child’s financial literacy and growth. Picture this: custodial accounts that empower adults to manage assets on behalf of minors, alongside specialized 529 college savings plans tailored for educational expenses. Each of these options offers unique benefits and considerations that deserve your attention.
In this article, we will gently guide you through the essential factors to evaluate when selecting an investment account for your children. Imagine if you could open and manage these accounts with confidence, knowing that you’re fostering a financially savvy generation. Together, we can explore the importance of education and engagement in this journey, ensuring that your family thrives in a world of opportunities. We’re here for you, every step of the way.
Understand Types of Kids Investing Accounts
When considering an investment account for your child, it’s essential to understand the different types available:
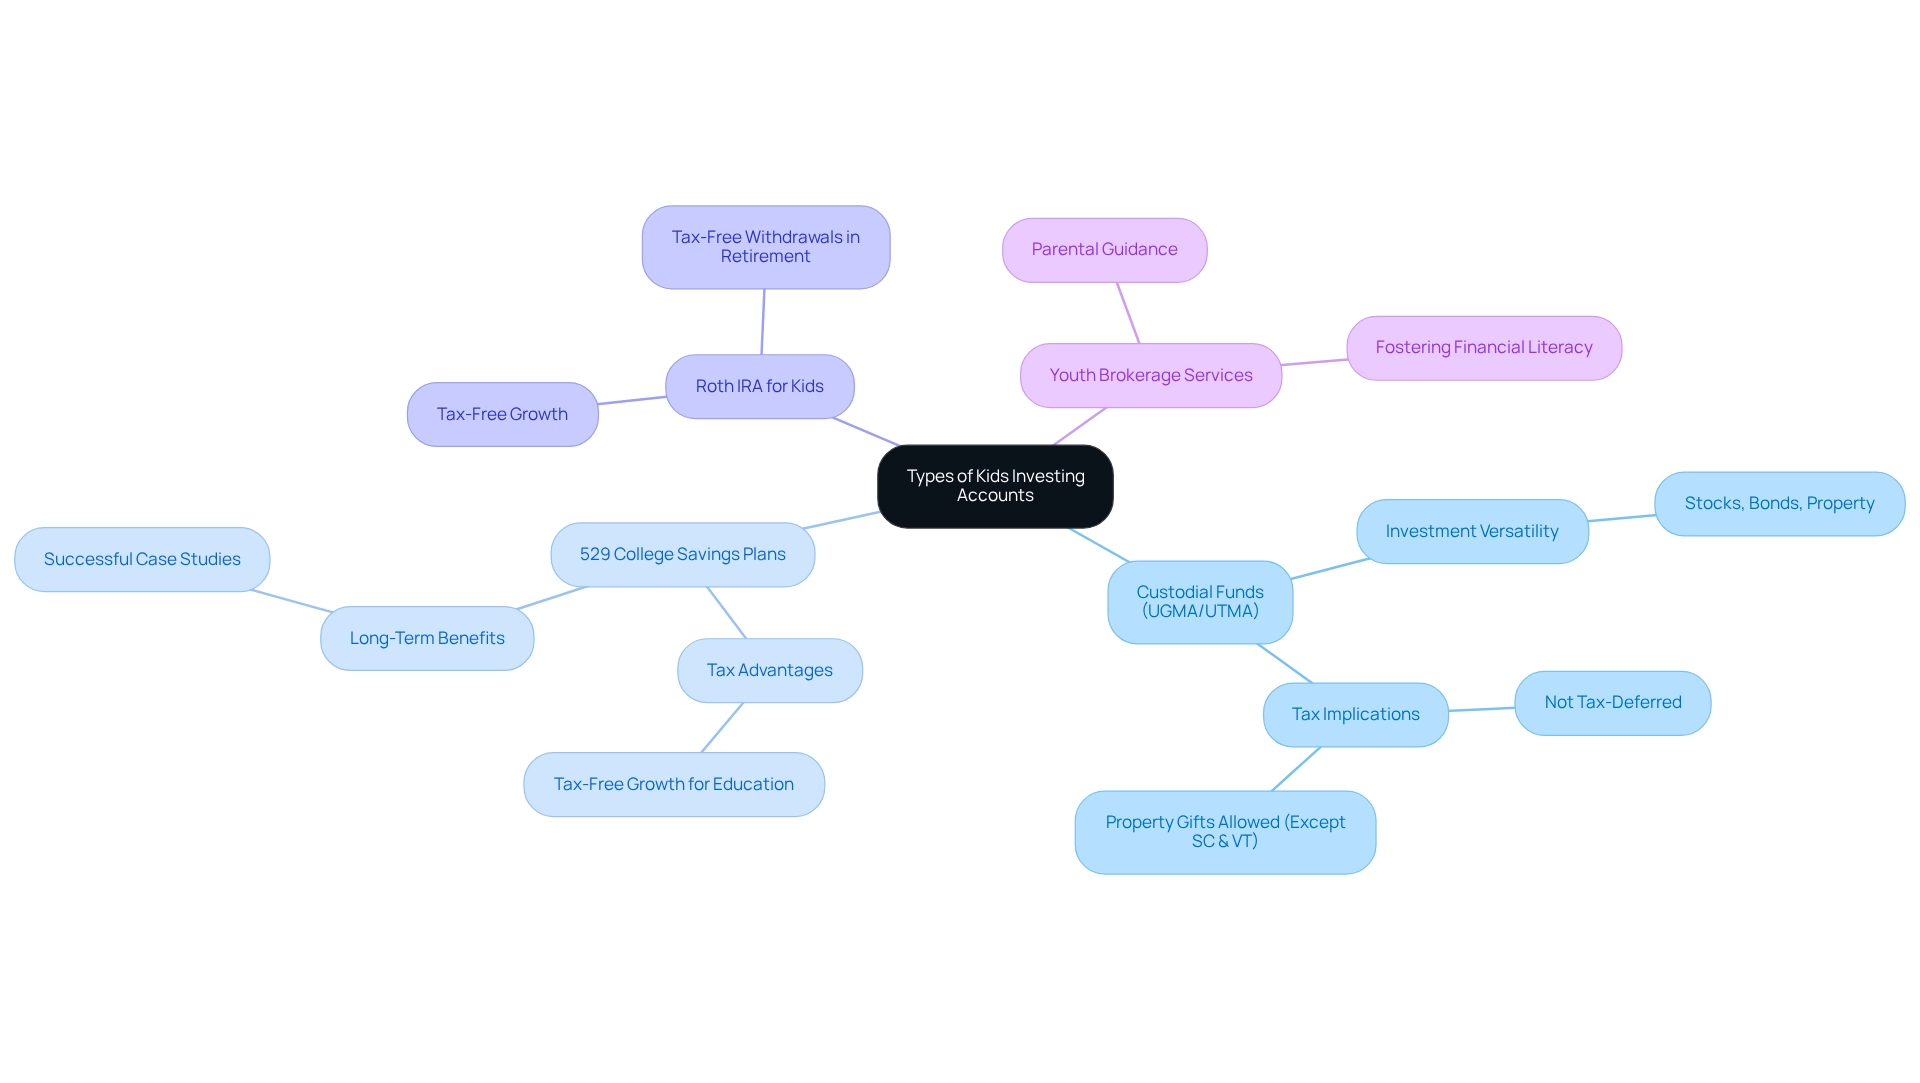
- Custodial Funds (UGMA/UTMA): These arrangements allow adults to oversee assets for a minor until they attain the age of majority. They can hold a diverse range of investments, including stocks, bonds, and even property, making them versatile options for building wealth. Notably, UTMA holdings allow gifts to include property and other transfers in all U.S. states except South Carolina and Vermont, which is a significant advantage over UGMA holdings.
- 529 College Savings Plans: Specifically designed for education savings, these accounts provide significant tax advantages when funds are used for qualified education expenses. As one specialist remarked, “529 plans provide households a valuable resource for ensuring their offspring’s educational prospects.” Successful case studies demonstrate how families have effectively utilized 529 plans, showcasing their long-term benefits and the potential for substantial growth over time.
- Roth IRA for Kids: If your child has earned income, they can contribute to a Roth IRA. This plan enables tax-free growth and tax-free withdrawals during retirement, making it a superb choice for long-term savings.
- Youth Brokerage Services: Some brokerage firms provide options designed for minors, enabling them to learn about investing with parental guidance. These kids investing accounts can help foster financial literacy from a young age, preparing children for future financial responsibilities.
At Bright Advisers, we emphasize innovative wealth management strategies that include hyper-personalized asset portfolios tailored to your family’s needs. Our innovative in-house technology improves financial outcomes, rendering traditional products functionally obsolete. Grasping these alternatives will assist you in selecting the most appropriate option based on your child’s age, financial objectives, and your overall investment approach. While custodial funds such as UGMA and UTMA offer possible tax-related advantages, they are not tax-deferred like certain college savings options. Therefore, it’s essential to consider the tax benefits of 529 plans compared to custodial accounts when choosing the appropriate account for your household.
Our dedication to reducing fund fees improves accessibility, ensuring that young households can effectively navigate financial planning challenges and secure their futures. Together, we can navigate this journey. To discover more about how we can assist you in developing a customized financial strategy for your family, reach out to Bright Advisers today.
Evaluate Key Factors for Account Selection
When selecting a kids investing account for your child, it’s essential to consider a few key factors that can significantly impact their financial future.
- Fees: Prioritize profiles with low or no fees to maximize your investment potential. Bright Advisers is dedicated to low fund fees, making wealth management more accessible for families like yours. Many financial institutions impose maintenance fees or trading commissions, which can slowly chip away at your savings over time. Low-cost financial services are becoming increasingly popular as families recognize the importance of reducing expenses to enhance their children’s economic prospects.
- Funding Alternatives: Ensure that the portfolio provides a diverse selection of funding options, including equities, debt securities, and mutual funds. A well-rounded portfolio can help mitigate risks while capitalizing on growth opportunities, setting the stage for long-term financial success. Bright Advisers offers tailored wealth management solutions to help families select the right investment options. For example, as of July 2024, the average Missouri 529 plan had $22,181 saved, reflecting a 5.20% increase from 2023, showcasing the potential for growth in these funds.
- Tax Implications: It’s important to familiarize yourself with the tax treatment of various financial arrangements. For instance, custodial funds may be subject to ‘kiddie tax’ regulations, which can affect overall returns. In contrast, 529 plans offer tax-free growth for education expenses. In Tennessee, families have saved a remarkable $366 million in 529 plans, making them a compelling option for those planning for college.
- Age of the Youngster: The age of your child plays a crucial role in your selection. Younger individuals may benefit from options focused on long-term growth, while older children might prefer a kids investing account that allows them to engage in investment decisions, which fosters financial literacy and responsibility.
- Ease of Management: Choose a platform that is user-friendly and offers educational resources to assist your child in learning about their kids investing account. Accounts that provide tools and guidance can empower young individuals to understand the importance of saving and investing from an early age. A case study from South Carolina indicates that families saved an average of $255.84 monthly in 529 plans, totaling $6.596 billion in savings, demonstrating the effectiveness of regular contributions.
As Matt Schulz, chief consumer finance analyst at LendingTree, wisely notes, “Putting your offspring in a place where they’ll be safe and nurtured is paramount.” By thoughtfully assessing these factors and considering Bright Advisers’ commitment to low fees and customized solutions, you can choose a financial plan that aligns with your goals and equips your child with the knowledge and resources necessary for a prosperous financial future. Together, we can navigate this journey.
Open and Manage Your Child’s Investment Account
Opening and managing a kids investing account can feel overwhelming, but with a few key steps, you can ensure a smooth process that sets them on the path to financial literacy and independence.
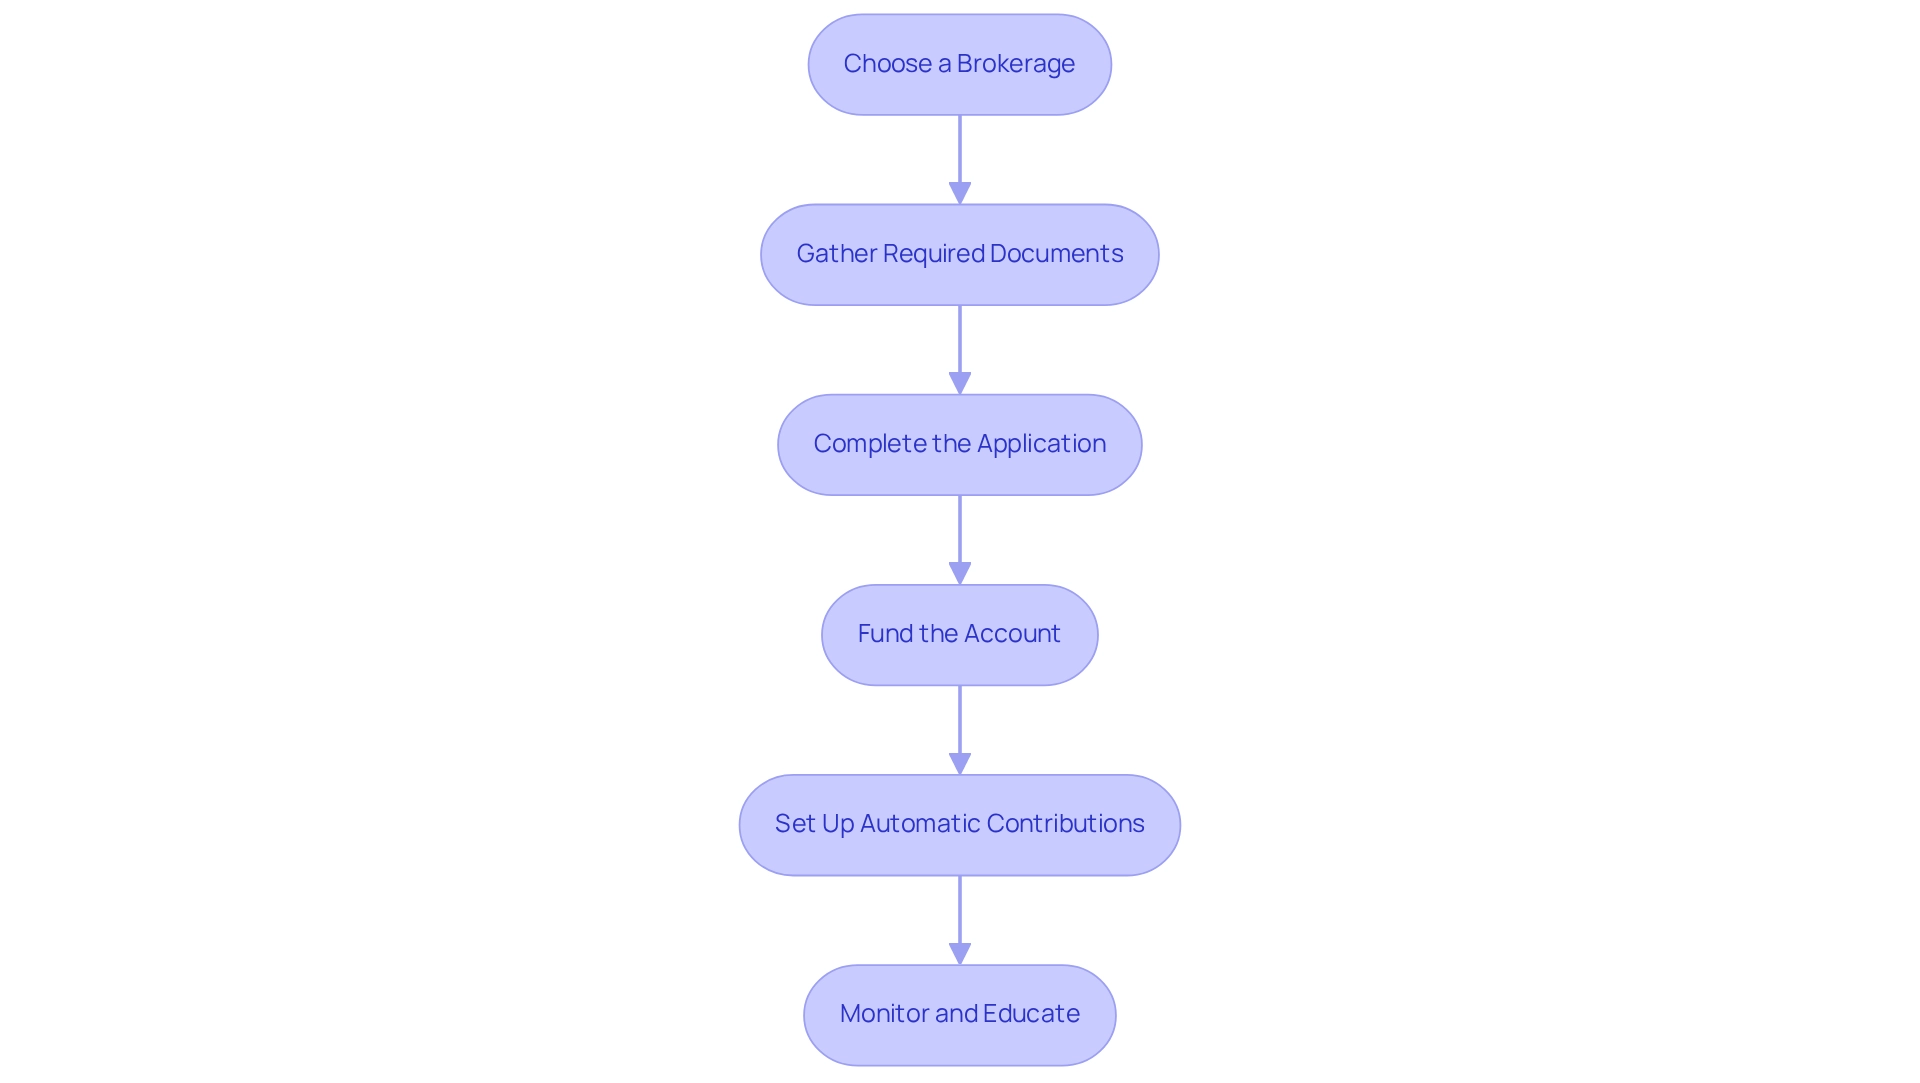
- Choose a Brokerage: Start by exploring brokerages that cater specifically to minors. Look for platforms that are user-friendly and provide robust customer support. It’s also beneficial to consider options that offer educational resources to help your child understand the world of investing. Some recommended brokerages for kids investing accounts include [Brokerage A], [Brokerage B], and [Brokerage C], known for their excellent features tailored for young investors. Bright Advisers also provides personalized wealth management solutions to guide families through this journey.
- Gather Required Documents: Collect essential documents, such as your child’s Social Security number and identification. Most brokerages will have specific forms that need to be completed, so it’s wise to check their requirements in advance. Keeping all necessary documents organized and readily accessible can make this process smoother.
- Complete the Application: Whether you choose to fill out the application form online or in person, accuracy is crucial. Double-check all information to prevent any processing delays. Remember, Bright Advisers is here to assist you in navigating this process, ensuring everything is completed correctly.
- Fund the Account: Decide on an initial deposit amount. While many options for a kids investing account do not require a minimum deposit, starting with a small amount can provide your child with practical experience in handling investments. Bright Advisers is committed to minimal fund fees, making it easier for families to start investing without high costs.
- Set Up Automatic Contributions: To cultivate a habit of saving and investing, consider setting up automatic transfers to the fund. This can help develop a consistent financial strategy over time, instilling good habits in your child.
- Monitor and Educate: Regularly review the account’s performance together with your child. Discuss investment choices and market trends to enhance their financial literacy and engagement in the investment process. Bright Advisers offers educational resources to empower families on this journey.
Statistics reveal that 49% of U.S. adults informed about personal finances gained knowledge from family and friends, highlighting the importance of involving your child in these discussions. Additionally, 56% of consumers expressed confidence in saving money, encouraging parents to focus on financial planning for their children. By prioritizing education and engagement, you can help them build a strong foundation for their financial future.
As Chris Kawashima wisely notes, “If a parent wishes to reserve funds for college costs that aren’t addressed by an ESA or 529 plan—sorority fees or vehicle repairs, for instance—a custodial arrangement may be beneficial.” This underscores the importance of considering various account types for your child’s future needs. Moreover, a case study on saving for college suggests that families should prioritize saving to avoid reliance on loans, which can lead to long-term financial burdens.
Together, we can navigate this journey, ensuring that your child is well-prepared for a bright financial future.
Access Resources and Tools for Effective Investing
To effectively support your child’s investing journey, consider utilizing resources and tools that align with Bright Advisers’ commitment to enhancing wealth management accessibility for families through a kids investing account.
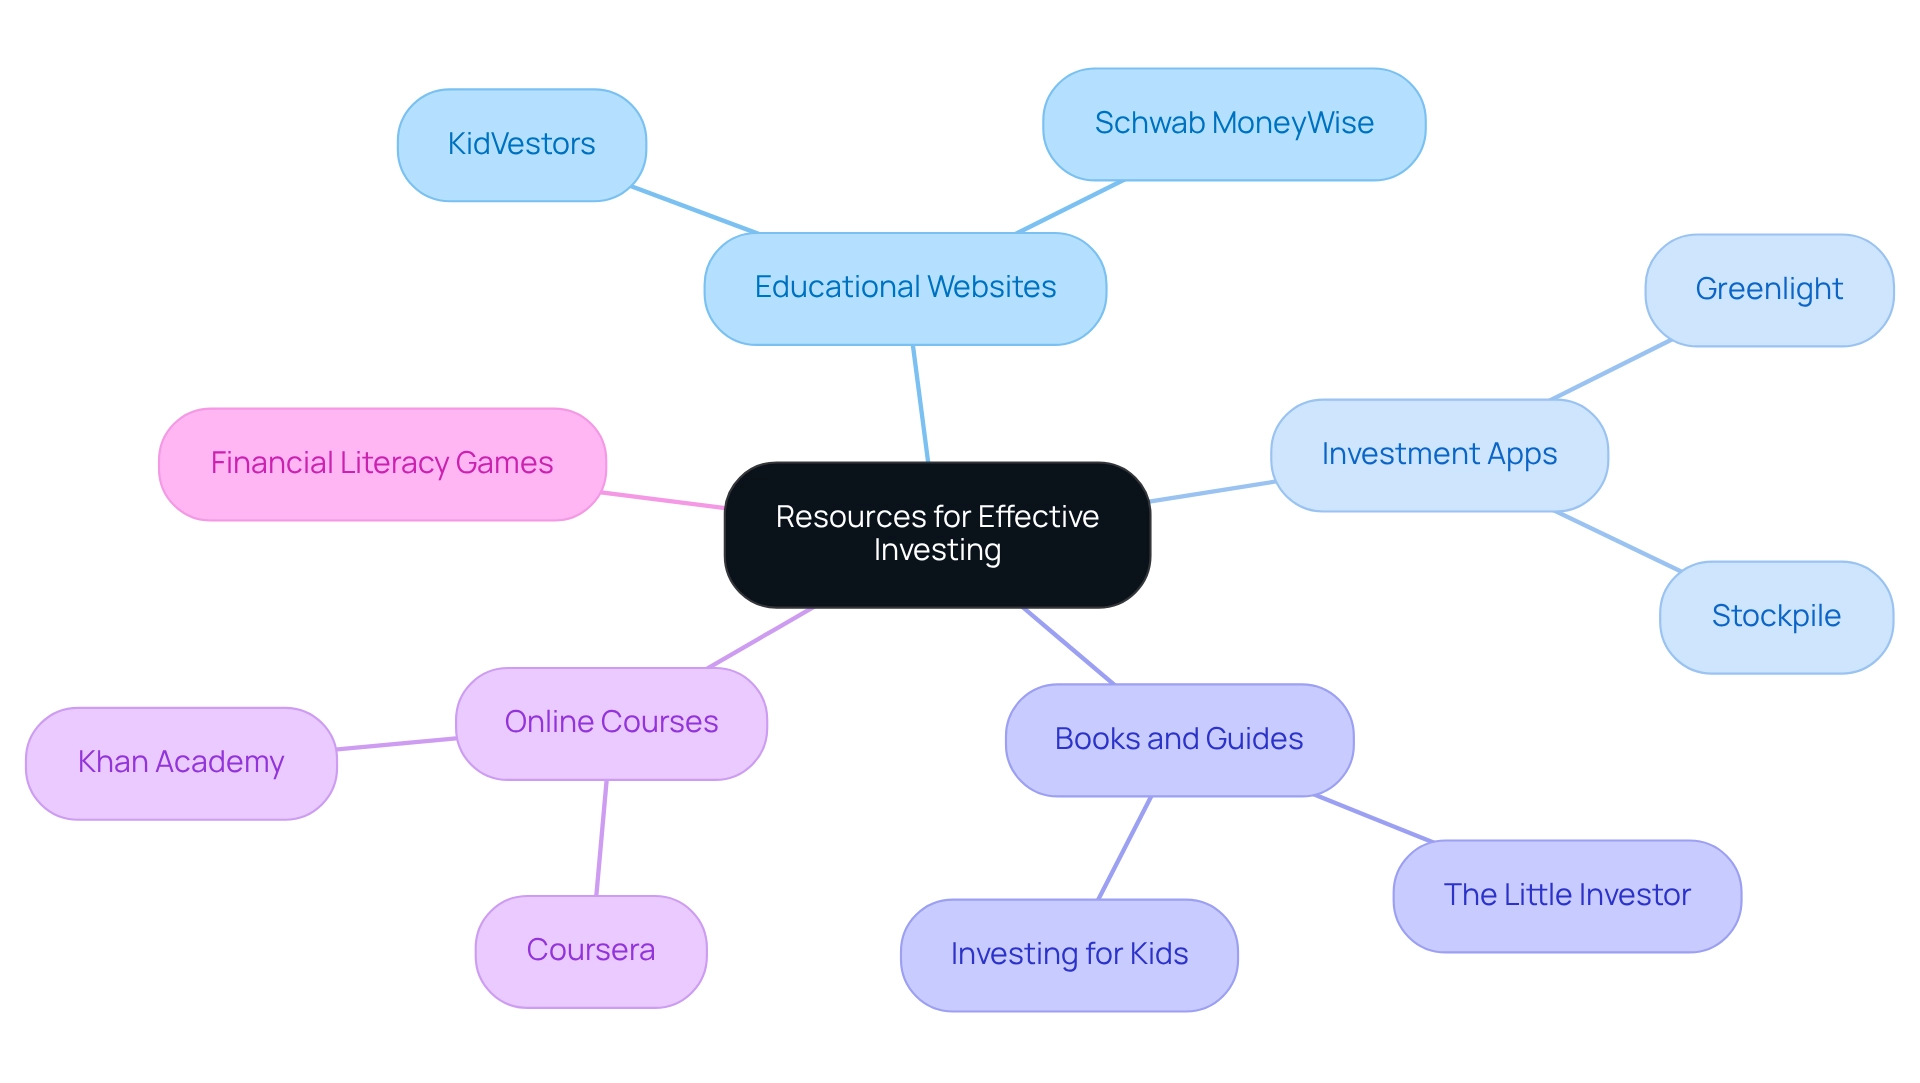
- Educational Websites: Imagine your child exploring platforms like KidVestors and Schwab MoneyWise, where engaging content is specifically crafted for young audiences. These resources foster an understanding of investing and financial literacy, particularly in relation to a kids investing account. With a 65% increase in parental preference for curriculum-aligned educational tools, these websites are particularly relevant.
- Investment Apps: Apps like Greenlight and Stockpile are important as they provide interactive experiences that enable young users to manage their kids investing account. This makes the learning process enjoyable and practical, aligning with the growing trend of integrating technology into financial education.
- Books and Guides: Seek out books that simplify investing concepts, such as ‘The Little Investor’ or ‘Investing for Kids.’ These can serve as excellent introductory materials for a kids investing account, nurturing your child’s financial knowledge.
- Online Courses: Together, you can explore free courses on personal finance and investing offered on platforms such as Coursera and Khan Academy. These resources benefit both parents and children in their financial education.
- Financial Literacy Games: Engaging games that simulate investing can assist young individuals in understanding market dynamics and the importance of saving and investing in a kids investing account.
As Tim Fries, cofounder of The Tokenist, states, ‘The best kids investing account for a young person is one that fulfills their financial purpose.’ By leveraging these resources, you can cultivate a robust foundation of financial literacy in your child, equipping them for a successful investing future.
Remember, Bright Advisers offers tailored wealth management solutions that can further enhance your family’s financial journey. We’re here for you, and if you would like more information, feel free to contact us at (714) 987-2967 or hello@brightadvisers.com. Please note that all advisory services are provided through Lifeworks Advisors, a registered investment adviser, and past performance is not indicative of future results.
Conclusion
Selecting the right investment account for your children is a crucial step in fostering their financial literacy and securing their future. By understanding various options—such as custodial accounts, 529 college savings plans, Roth IRAs for kids, and youth brokerage accounts—you empower yourself to make informed choices that align with your family’s financial goals.
When evaluating these accounts, it’s important to consider key factors like fees, investment options, tax implications, and your child’s age. Choosing low-fee accounts with diverse investment choices can enhance growth potential while encouraging financial responsibility. The process of opening and managing these accounts involves practical steps, such as selecting a suitable brokerage and setting up automatic contributions to instill saving habits early on.
Imagine the enriching experience of leveraging resources like educational websites, investment apps, and engaging literature to enhance your child’s investing journey. Involving them in discussions about their investments fosters a deeper understanding of financial concepts and prepares them for future responsibilities.
In summary, investing for your children is an empowering journey that promotes financial education and growth. By making informed decisions and creating a supportive environment, you can help your children navigate investing with confidence, ultimately paving the way for a secure financial future. Together, we can navigate this journey with care and compassion.
Frequently Asked Questions
What are custodial funds (UGMA/UTMA)?
Custodial funds are arrangements that allow adults to manage assets for a minor until they reach the age of majority. They can hold various investments, including stocks, bonds, and property, making them versatile for wealth building. UTMA holdings have the added advantage of allowing gifts to include property in all U.S. states except South Carolina and Vermont.
What are 529 College Savings Plans?
529 College Savings Plans are specifically designed for education savings and offer significant tax advantages when funds are used for qualified education expenses. They are considered a valuable resource for ensuring children’s educational prospects and have demonstrated long-term benefits and potential for substantial growth.
How does a Roth IRA for Kids work?
A Roth IRA for Kids allows children with earned income to contribute to the account. It enables tax-free growth and tax-free withdrawals during retirement, making it an excellent choice for long-term savings.
What are Youth Brokerage Services?
Youth Brokerage Services are options provided by some brokerage firms that are designed for minors. These accounts allow children to learn about investing with parental guidance, helping to foster financial literacy from a young age and preparing them for future financial responsibilities.
What should I consider when choosing an investment account for my child?
When selecting an investment account for your child, consider their age, financial objectives, and your overall investment strategy. It’s also important to weigh the tax benefits of 529 plans against custodial accounts like UGMA and UTMA, as custodial funds are not tax-deferred like certain college savings options.
How does Bright Advisers support families in financial planning?
Bright Advisers emphasizes innovative wealth management strategies, including hyper-personalized asset portfolios tailored to family needs. They focus on reducing fund fees to improve accessibility and help young households navigate financial planning challenges effectively.
List of Sources
- Understand Types of Kids Investing Accounts
- UGMA & UTMA Accounts: What They Are, Differences – NerdWallet (https://nerdwallet.com/article/investing/utma-ugma)
- merrilledge.com (https://merrilledge.com/article/5-hidden-benefits-529-college-savings-plans)
- UGMA vs. UTMA Custodial Accounts (https://smartasset.com/investing/ugma-vs-utma)
- UTMA vs. UGMA: Understanding for Investment Planning (https://westernsouthern.com/investments/utma-vs-ugma-accounts)
- Evaluate Key Factors for Account Selection
- College Saving Statistics [2025]: Average Savings & 529 Balance (https://educationdata.org/college-savings-statistics)
- It Costs $297,674 to Raise a Child Over 18 Years | LendingTree (https://lendingtree.com/debt-consolidation/raising-a-child-study)
- Open and Manage Your Child’s Investment Account
- 54 Personal Finance Statistics & Facts in 2025 [SOURCES INCLUDED] (https://moneywise.com/research/personal-finance-statistics)
- Saving for College: Custodial Accounts (https://schwab.com/learn/story/saving-college-custodial-accounts)
- Access Resources and Tools for Effective Investing
- nerdwallet.com (https://nerdwallet.com/article/investing/set-kids-brokerage-account)
- Investing for Kids (2023): Complete Parents Guide (https://tokenist.com/investing/investing-for-kids)
- Investing Apps for Teens—Top Picks for Young Investors (https://freekick.bank/investing-apps-for-teens)
- Apps for Kids Market Size, Share & Growth Analysis | 2033 (https://globalgrowthinsights.com/market-reports/apps-for-kids-market-100707)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Age Five Wealth Education for high-income W-2 families at Bright Advisers.
Keep reading