

Overview
This article gently outlines four essential steps for selling Employee Stock Purchase Plans (ESPP) or Restricted Stock Units (RSU) to help you achieve financial success. It emphasizes the importance of understanding:
- Tax implications
- Market conditions
- Monetary objectives
- Diversification needs
Imagine if you could navigate these complexities with confidence. By detailing strategic selling techniques and common mistakes to avoid, this guide aims to empower you in making informed decisions that align with your long-term financial goals. Remember, we’re here for you, and together, we can navigate this journey toward financial well-being.
Key Highlights:
- Employee Stock Purchase Plans (ESPP) allow employees to buy company stock at a discount of 5% to 15%, enhancing financial engagement.
- Participation rates in ESPPs increase significantly with higher discounts, with a 15% discount leading to a 48% participation rate.
- Restricted Stock Units (RSUs) provide equity compensation after a vesting period, with tax implications based on the fair market value at vesting.
- Key factors to consider before selling ESPP or RSU include tax implications, current market conditions, monetary objectives, and diversification needs.
- Strategic selling techniques include selling ESPP shares promptly after acquisition, establishing a scheduled selling approach for RSUs, and monitoring market trends.
- Common mistakes to avoid include neglecting tax implications, holding too much company stock, making emotional selling decisions, and ignoring market conditions.
Introduction
Navigating the complexities of Employee Stock Purchase Plans (ESPP) and Restricted Stock Units (RSU) may feel daunting, yet it can be rewarding, especially when considering the financial stability of your family. These investment vehicles present unique opportunities to acquire company stock at a discount or as part of your compensation.
However, understanding the nuances is crucial for maximizing their potential. Imagine if you could effectively decide whether to sell your ESPP or RSU first, optimizing your financial outcomes.
This article delves into strategic selling techniques and key considerations designed to empower you in enhancing your wealth while avoiding common pitfalls along the way. Together, we can navigate this journey toward a more secure financial future for your loved ones.
Understand Employee Stock Purchase Plans (ESPP) and Restricted Stock Units (RSU)
Imagine a world where you can secure your family’s financial future with smart investment choices. Employee Stock Purchase Plans (ESPP) allow you to buy company stock at a discounted price, often through convenient payroll deductions. This opportunity provides a meaningful financial advantage, enabling you to acquire shares at a lower cost than their market value, with discounts typically ranging from 5% to 15%. Companies offering a 15% discount often see participation rates soar to 48%, a notable increase from the overall median rate of 38% for all ESPPs. This highlights how attractive discounts can foster greater employee engagement.
Now, consider Restricted Stock Units (RSUs). These represent a form of compensation where you receive equity after fulfilling certain conditions, such as a vesting period. Once your RSUs vest, you’ll be taxed based on the fair market value of the shares, which can lead to complex tax implications. Strategic timing in disposing of RSUs can be beneficial, especially as you navigate the intricacies of tax consequences that vary with holding durations.
It’s important to understand these differences as they play a crucial role in your financial journey. By leveraging the benefits of ESPPs and thoughtfully managing the tax implications of RSUs, it’s important to consider whether to sell ESPP or RSU first to enhance your financial success. Together, we can navigate this journey, aligning your investment strategies with your family’s long-term goals. Remember, support is available to help you make informed choices that secure a brighter future for your loved ones.

Evaluate Key Factors Impacting Your Decision to Sell
Before selling your ESPP or RSU shares, it’s essential to consider a few key factors that can greatly influence your financial journey:
-
Tax Implications: Imagine realizing that selling your shares could significantly affect your tax situation. For ESPPs, employees can purchase company stock at a discount of up to 15%. However, immediate sales may lead to ordinary income tax on that discount. Similarly, RSUs are taxed as ordinary income upon vesting. Understanding these tax implications is vital for effectively managing your resources, especially when considering whether to sell ESPP or RSU first.
-
Market Conditions: It’s important to recognize how current market trends can impact the best time to sell. Selling during a market peak can enhance your returns, while divesting in a downturn may result in diminished profits. For instance, in 2025, fluctuating tech stock prices remind us of the necessity to stay informed about market dynamics that might affect our stock sales.
-
Monetary Objectives: Aligning your selling strategy with your long-term financial goals is crucial. Whether you’re saving for a home, funding education, or planning for retirement, your specific aspirations will guide your decisions about when and how much to sell. This alignment helps ensure that your financial actions support your broader family dreams.
-
Diversification Needs: Holding a large amount of company stock can increase your investment risk. To ease this burden, consider liquidating a portion of your investments to diversify your portfolio. This strategy not only reduces risk but also positions you for more stable long-term growth.
By thoughtfully evaluating these factors, you can make informed choices about how to sell ESPP or RSU first for managing your investments, ultimately enhancing your family’s financial well-being. Remember, we’re here for you on this journey, together navigating the complexities of wealth management.

Implement Strategic Selling Techniques for ESPP and RSU
When considering your options, you should sell ESPP or RSU first, as it can feel overwhelming, but with a few strategic techniques, you can navigate this journey with confidence and care.
-
Dispose Promptly After Acquisition (ESPP): If your company allows it, consider transferring your ESPP assets right after acquisition. This can help you secure a discount of up to 15% while minimizing exposure to market fluctuations. Many experts suggest that to enhance your financial situation, you should sell ESPP or RSU first by selling 80% to 90% of your ESPP shares immediately, while still being invested in your company’s future.
-
Scheduled Selling: Establishing a systematic approach for selling your RSUs as they vest is crucial. This strategy not only helps you manage tax implications—like immediate tax liabilities upon vesting—but also empowers you to navigate market fluctuations more effectively. Remember, it’s important to sell ESPP or RSU first, as holding onto RSUs can lead to significant tax burdens if not managed properly, so it’s important to stay proactive.
-
Use Proceeds Wisely: Once you sell your shares, think carefully about how to allocate the proceeds. Consider investing in a diversified portfolio or using the funds to meet important family goals, such as reducing debt or funding educational expenses. This approach can help you avoid the risks associated with being overly concentrated in a single stock.
-
Monitor Market Trends: Keeping a close eye on market conditions and your company’s performance is essential. Current market trends can greatly influence the value of your assets, so staying informed will empower you to make timely decisions about when to sell. Remember, understanding the broader market context is key to effective asset management.
By adopting these techniques, you can enhance your financial strategy and optimize the benefits of your ESPP and RSU holdings by understanding when to sell ESPP or RSU first. Together, we can navigate this journey and ensure your family’s financial well-being.

Avoid Common Mistakes When Selling ESPP and RSU
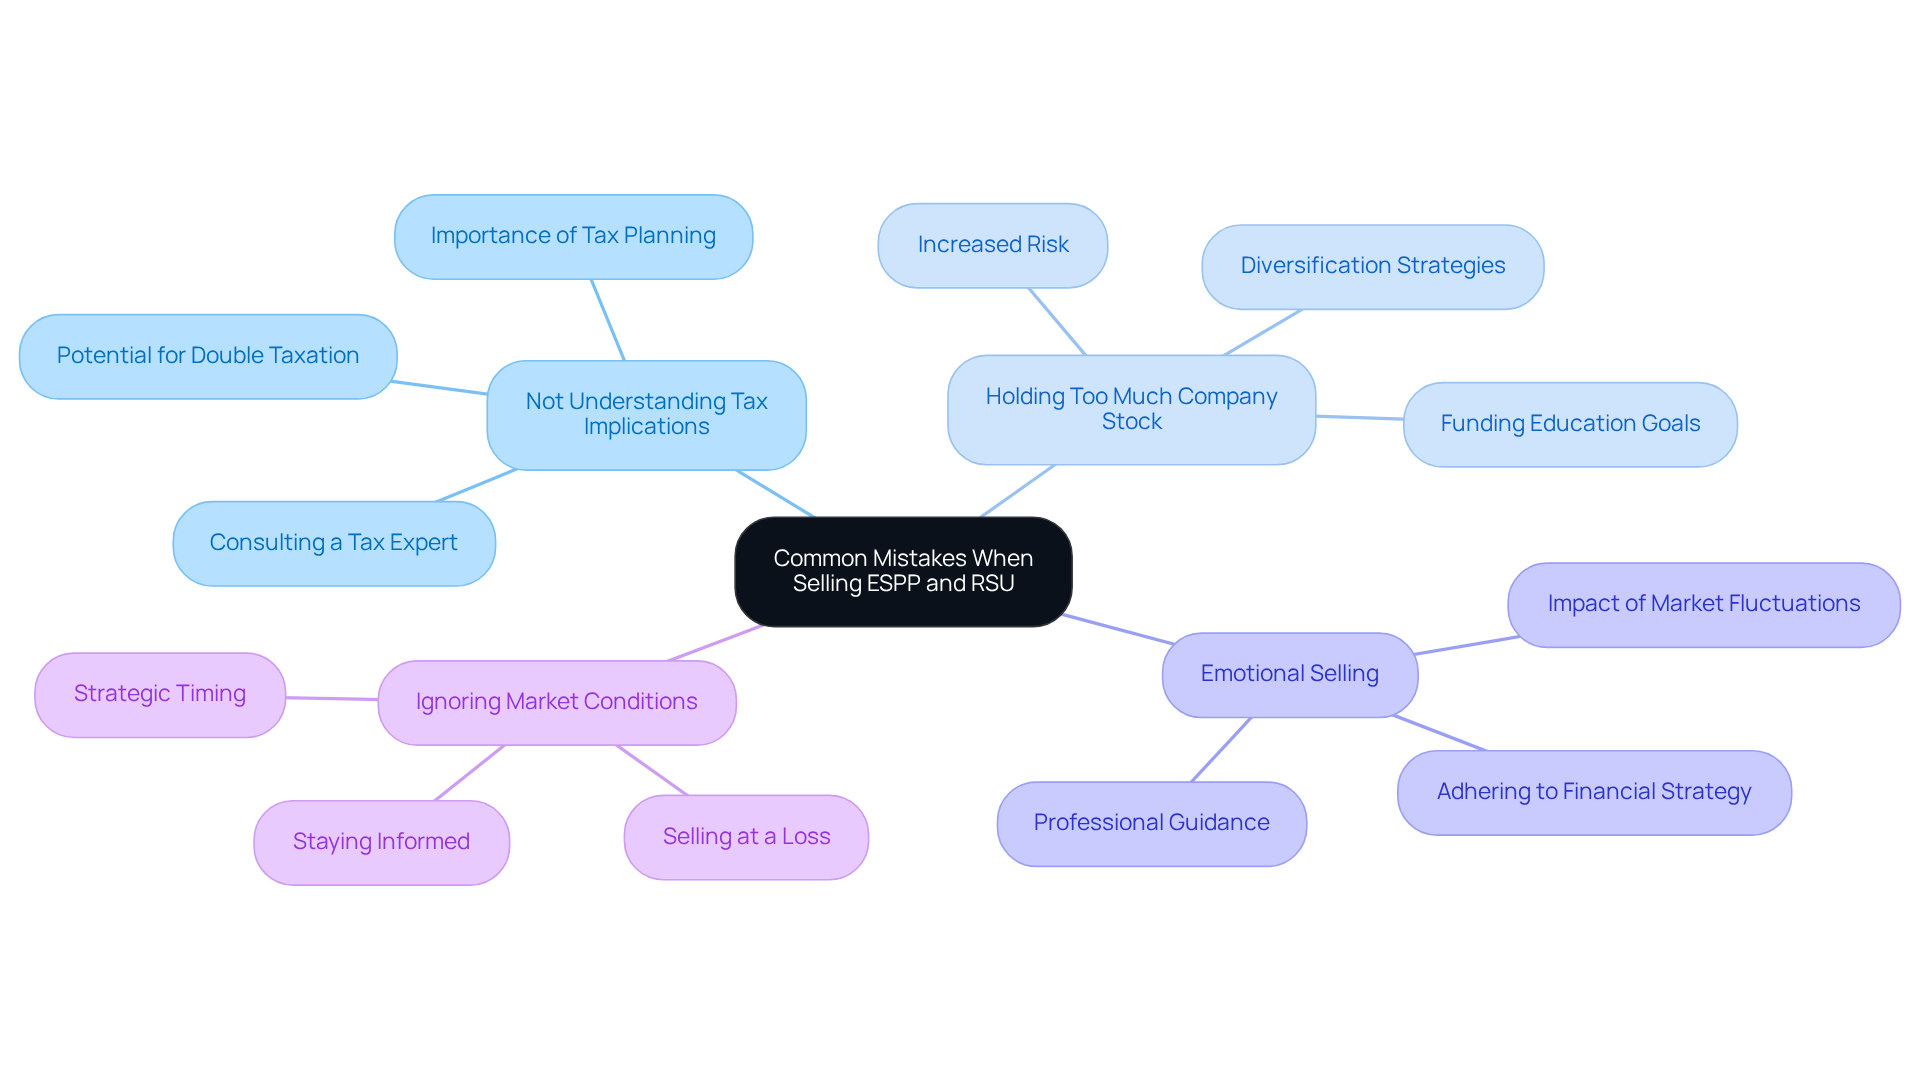
When it comes to selling your ESPP and RSU shares, it’s important to be aware of some common pitfalls that many face:
- Not Understanding Tax Implications: It’s easy to overlook how taxes can impact your sales, potentially leading to unexpected liabilities. Take, for example, Allison and Brian. They initially neglected tax planning, but after consulting a tax expert, they gained clarity on their responsibilities and maximized their financial potential. This not only helped them understand their situation better but also supported their dream of retiring earlier.
- Holding Too Much Company Stock: Placing too much of your portfolio in company stock can heighten risk. By diversifying their investments, as recommended by Bright Advisers, Allison and Brian were able to reduce this risk, providing a more secure financial future for their family, including funding their children’s education.
- Emotional Selling: Making decisions based on emotions or short-term market fluctuations can be detrimental. It’s crucial to adhere to your strategy and financial objectives, just as Allison and Brian did when they refined their plan with professional guidance.
- Ignoring Market Conditions: Failing to consider market trends might lead to selling assets at a loss. Staying informed and being strategic about your timing can ensure that your selling approach aligns with your overall financial plan.
By steering clear of these mistakes, you can improve your financial outcomes and ensure your selling strategy, including the decision to sell ESPP or RSU first, aligns with your broader financial goals. Remember, much like Allison and Brian’s successful journey with Bright Advisers, you’re not alone in this process. We’re here for you, ready to support you every step of the way.
Conclusion
Navigating the intricacies of Employee Stock Purchase Plans (ESPP) and Restricted Stock Units (RSU) is essential for achieving financial success for your family. By understanding the unique features and strategic selling techniques associated with these investment vehicles, you can make informed decisions that secure a brighter financial future for your loved ones. Imagine if you could discern whether to sell ESPP or RSU first—this choice can significantly impact your overall financial outcomes.
It’s important to consider key factors such as:
- Tax implications
- Market conditions
- Monetary objectives
- Diversification needs
These elements play a crucial role in shaping your decision-making process. Awareness of common mistakes, like emotional selling or neglecting tax planning, further highlights the importance of a well-thought-out strategy. By implementing strategic selling techniques, such as prompt disposal of ESPP shares and scheduled selling of RSUs, you can optimize your holdings and minimize risks.
Ultimately, your journey toward financial success with ESPP and RSU requires a proactive approach and a commitment to informed decision-making. By leveraging the insights provided, you can enhance your wealth management strategies and align your financial actions with long-term aspirations. Together, we can navigate this journey, fostering personal financial growth and empowering your family to achieve their dreams and secure their futures.
Frequently Asked Questions
What is an Employee Stock Purchase Plan (ESPP)?
An Employee Stock Purchase Plan (ESPP) allows employees to buy company stock at a discounted price, often through payroll deductions. Discounts typically range from 5% to 15% off the market value.
How do discounts in ESPPs affect employee participation?
Companies that offer a 15% discount often see participation rates increase significantly, with rates soaring to 48%, compared to the overall median rate of 38% for all ESPPs.
What are Restricted Stock Units (RSUs)?
Restricted Stock Units (RSUs) are a form of compensation where employees receive equity after meeting certain conditions, such as a vesting period.
What happens when RSUs vest?
Once RSUs vest, they are taxed based on the fair market value of the shares at that time, which can lead to complex tax implications.
Why is strategic timing important when disposing of RSUs?
Strategic timing is important when disposing of RSUs because the tax consequences vary depending on how long the shares are held, which can impact overall financial outcomes.
How should employees decide whether to sell ESPP or RSU shares first?
Employees should consider the tax implications and their financial goals when deciding whether to sell ESPP or RSU shares first, as this can enhance their financial success.
What support is available for employees navigating ESPPs and RSUs?
Employees can seek support to help them make informed choices regarding ESPPs and RSUs, aligning their investment strategies with their long-term financial goals.
List of Sources
- Understand Employee Stock Purchase Plans (ESPP) and Restricted Stock Units (RSU)
- Employee Stock Purchase Plans 101 | Plancorp (https://plancorp.com/employee-stock-purchase-plans-101)
- ESPP Pros and Cons: Should You Invest in Your Company’s Plan? (https://simplicitywm.com/should-you-invest-in-your-companys-employee-stock-purchase-plan-espp)
- NASPP | Trends in ESPPs: Five Facts and a Myth (https://naspp.com/blog/five-trends-in-espps)
- Employee Stock Purchase Plan (ESPPs) Trends (https://stockopter.com/employee-stock-purchase-plan-espps-trends)
- NASPP | Why Your Qualified ESPP Should Offer a 15% Discount (https://naspp.com/blog/why-15-percent-for-espp)
- Evaluate Key Factors Impacting Your Decision to Sell
- Employee Stock Purchase Plan (ESPP) Taxes: A Guide (https://schwab.com/learn/story/espp-taxes)
- Top 4 Ways to Reduce Taxes on RSU Income | Consilio Wealth Advisors (https://consiliowealth.com/insights/top-4-ways-to-reduce-taxes-on-rsu-income)
- Tax Implications for Stock-Based Compensation – Bloomberg Tax (https://pro.bloombergtax.com/insights/federal-tax/tax-implications-for-stock-based-compensation)
- Stock-based compensation: Tax forms and implications (https://thetaxadviser.com/newsletters/2024/jan/stock-based-compensation-tax-forms-and-implications)
- SOI Tax Stats – Sales of capital assets reported on individual tax returns | Internal Revenue Service (https://irs.gov/statistics/soi-tax-stats-sales-of-capital-assets-reported-on-individual-tax-returns)
- Implement Strategic Selling Techniques for ESPP and RSU
- When Should You Sell ESPP Shares? — EquityFTW (https://equityftw.com/articles/when-should-you-sell-espp-shares)
- Don’t Leave Money Behind: Proven Strategies for Selling RSUs (https://addishill.com/dont-leave-money-on-the-table-smart-strategies-for-selling-your-rsus)
- Selling Employee Stock Purchase Plan Shares (https://thebalancemoney.com/when-to-sell-espp-2388745)
- ESPP Tax Rules: What You Need to Know (https://wealthenhancement.com/s/blog/espp-tax-rules-what-you-need-to-know-MC7NEMNJHGRBD3NPLYMZUQQ23MAQ)
- MAKING THE MOST OF YOUR RSUS AND YOUR ESPP: A STRATEGIC APPROACH (https://onebridgewealth.com/blog/making-the-most-of-your-rsus-and-your-espp-a-strategic-approach-for-those)
- Avoid Common Mistakes When Selling ESPP and RSU
- 5 Employee Stock Plan Mistakes You Need To Avoid (https://forbes.com/sites/davidrae/2018/12/11/espp-mistakes)
- 3 Common ESPP Mistakes That Cost You Money (and How to Avoid Them) (https://juliemerrill.me/blog/espss-3-common-mistakes)
- Employee Stock Purchase Plans: Five Common Mistakes You Can Avoid – Summitry (https://summitry.com/blog/employee-stock-purchase-plans-five-common-mistakes-you-can-avoid)
- The Most Common RSU Mistakes — And How to Avoid Them (https://plancorp.com/blog/restricted-stock-unit-rsu-mistakes)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About KevinThis is part of how we approach Tax Management for high-income W-2 families at Bright Advisers.
Keep reading