

Overview
Setting up a Solo 401(k) S Corp plan can feel overwhelming, but we’re here to guide you through each step with care. Imagine being able to secure your family’s future while maximizing your retirement savings. To start, it’s essential to choose a provider who understands your needs. Next, completing the necessary agreements is crucial, as it lays the foundation for your plan.
It’s important to understand that obtaining an EIN is a vital step in this process. Once you have that, establishing a trust account will help you manage your contributions effectively. Funding the plan is where you can really start to see the benefits—contributing as both an employee and employer allows S Corporation owners to significantly increase their savings potential.
Maintaining compliance is key to ensuring that your plan operates smoothly, allowing you to focus on what matters most—your family. By following these steps, you not only take control of your financial future but also benefit from valuable tax advantages. Together, we can navigate this journey and help you achieve your financial goals while prioritizing your family’s well-being.
Key Highlights:
- A Solo 401(k) is a retirement savings option for self-employed individuals or S Corporation owners without employees, except for a spouse.
- S Corporation owners can contribute both as employees and employers, significantly increasing retirement savings potential.
- In 2025, individuals can contribute up to $23,500 as employees, with additional catch-up contributions for those aged 50 and over, totaling up to $79,500.
- Contributions are tax-deductible, lowering taxable income, and earnings grow tax-deferred until withdrawal.
- Solo 401(k) plans may offer loan options for liquidity during financial needs.
- Eligible S Corporation owners must have no employees (other than a spouse) and must base contributions on W-2 wages.
- To establish a Solo 401(k), choose a provider, complete an adoption agreement, obtain an EIN, establish a trust account, fund the plan, and maintain compliance.
- Contribution limits for 2025 allow up to $70,000 for individuals under 50, with an additional 25% of W-2 wages as employer contributions.
- Employee contributions must be made by December 31, while employer contributions can be made until the tax filing deadline.
Introduction
Navigating the complexities of retirement planning can feel overwhelming, particularly for S Corporation owners eager to maximize their savings. The Solo 401(k) stands out as a remarkable option, presenting unique benefits that can significantly boost retirement contributions while offering valuable tax advantages. Yet, many owners may find themselves asking:
- What are the key steps to effectively set up a Solo 401(k) plan?
- How can they truly capitalize on this opportunity?
Imagine having a clear path to a secure financial future for your family. This guide gently explores the process, eligibility requirements, and best practices to empower S Corp owners in their journey towards financial security, ensuring that you feel supported every step of the way.
Understand the Solo 401(k) and Its Benefits for S Corporations
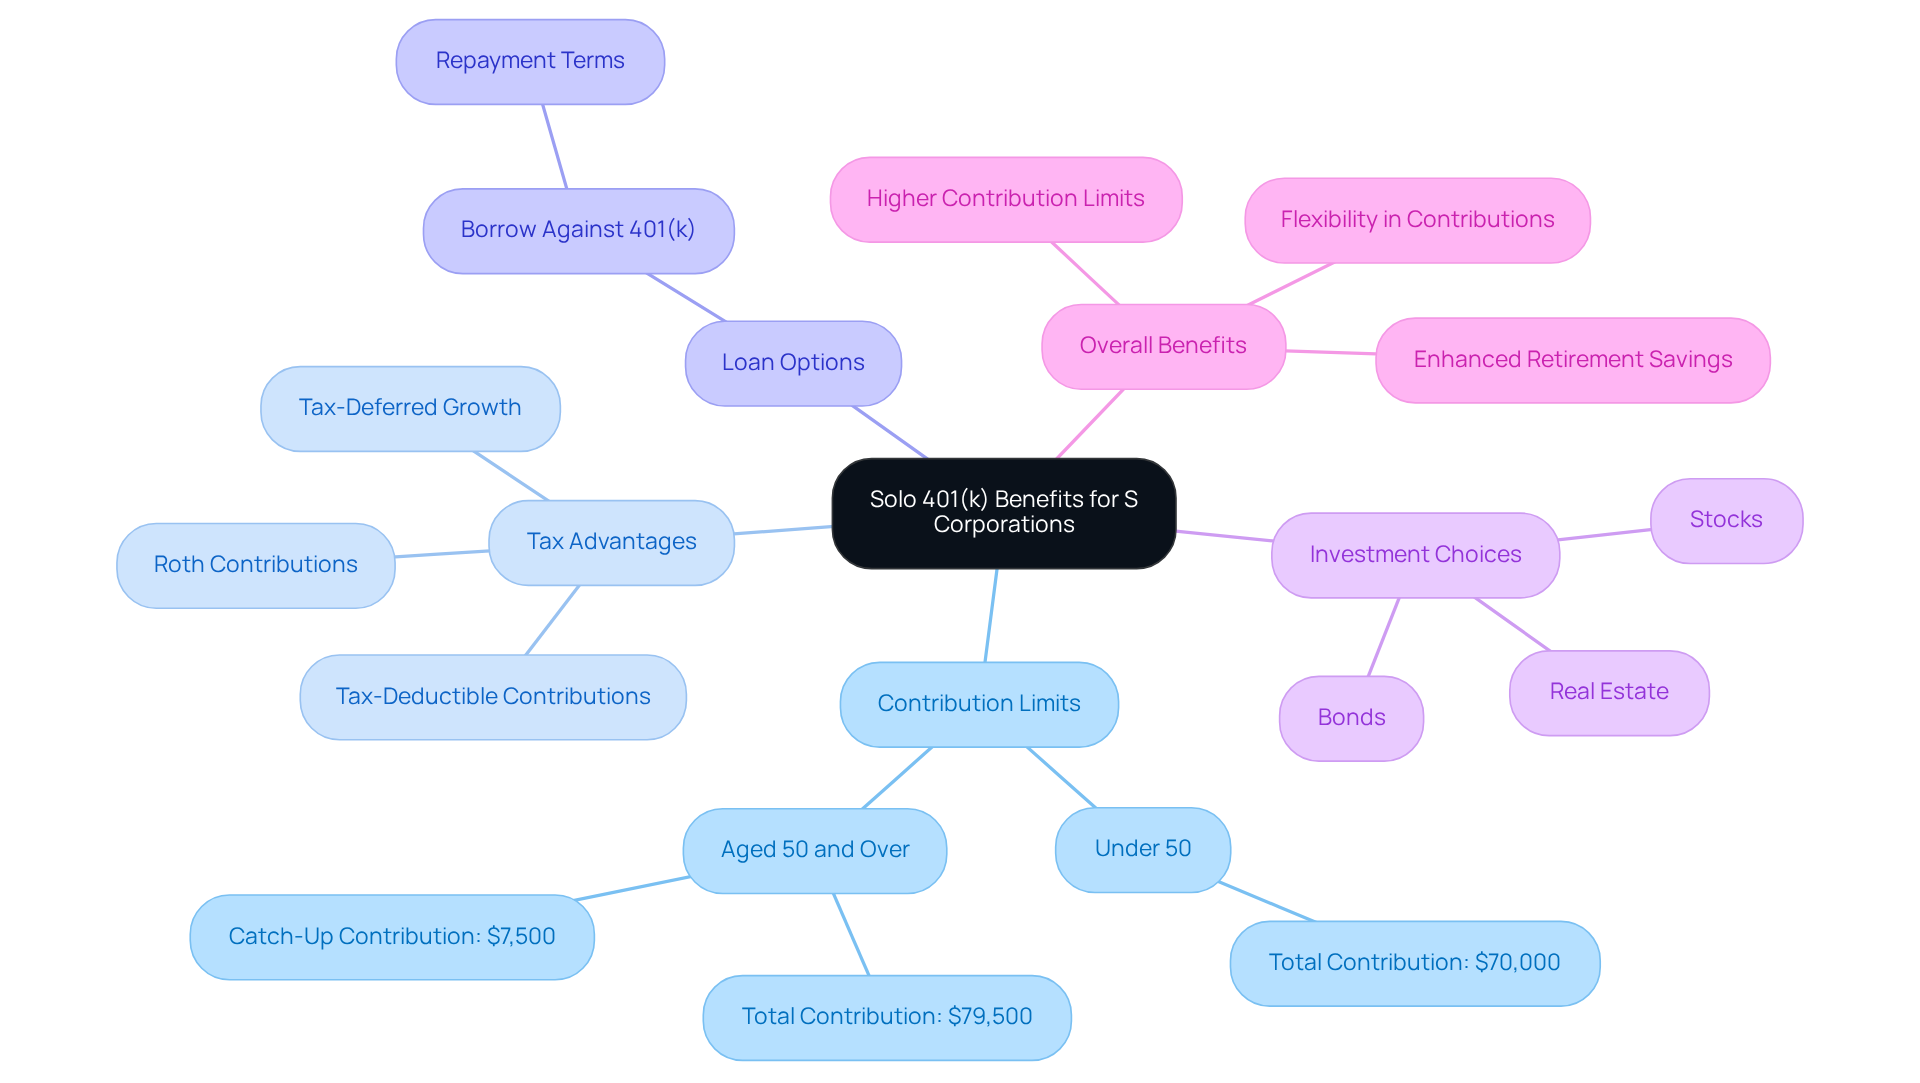
A Solo 401(k) is a thoughtful retirement savings option tailored for self-employed individuals or business owners who have no employees besides a spouse. The solo 401k s corp plan offers S Corporations a unique opportunity for owners to contribute both as employees and employers, which can significantly enhance their retirement savings potential.
Why Consider a Solo 401(k) for Your S Corporation?
Imagine having the ability to save more for your future while also benefiting from tax advantages. Solo 401(k)s provide higher funding limits compared to traditional IRAs. In 2025, individuals can contribute up to $23,500 as employees, plus an additional catch-up contribution of $7,500 for those aged 50 and over. For those aged 60 to 63, a super catch-up contribution of $11,250 is available, allowing a total contribution of up to $79,500 for those over 50. As employers, S Corporation owners can also contribute up to 25% of their W-2 wages, further enhancing their retirement savings.
It’s important to understand the tax advantages as well. Contributions to an individual 401(k) are tax-deductible, which can effectively lower your taxable income. The earnings within the account grow tax-deferred until withdrawal, allowing for greater accumulation over time.
Additionally, many individual 401(k) plans offer loan options, providing crucial liquidity during times of financial need. This flexibility can be a lifeline when unexpected expenses arise.
Participants also enjoy a wide array of investment choices, including stocks, bonds, and real estate. This variety allows you to tailor your portfolio to meet your unique financial goals and aspirations.
Grasping these benefits is essential for S Corporation owners who want to create a solo 401k s corp arrangement that aligns with their financial objectives and enhances their retirement savings. Remember, we’re here for you, and together, we can navigate this journey towards a secure financial future.
Determine Eligibility for a Solo 401(k) as an S Corp Owner
Are you an S Corporation owner interested in a solo 401k s corp to secure your financial future? To qualify for a Solo 401(k), there are a few important criteria to keep in mind:
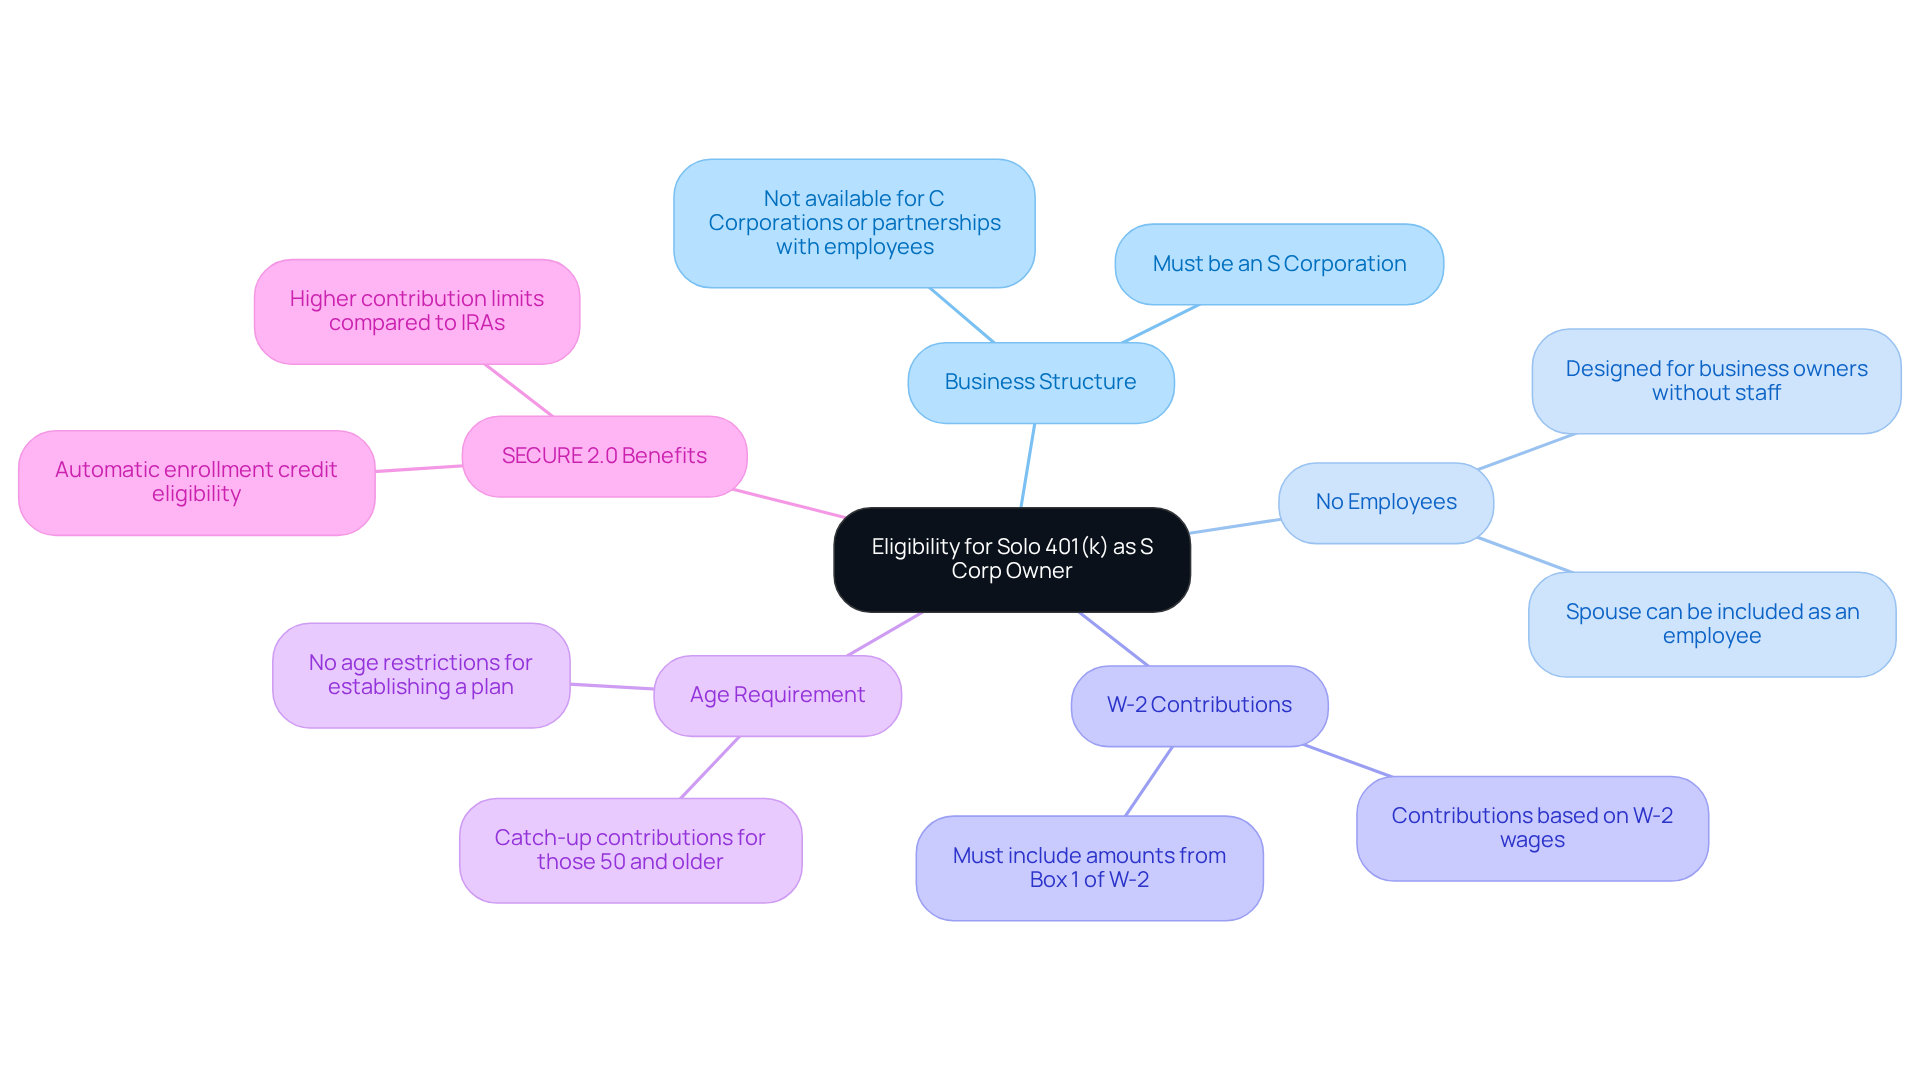
- Business Structure: You must operate as an S Corporation to establish a solo 401k s corp. This option isn’t available for C Corporations or partnerships that have employees.
- No Employees: The Solo 401(k) is designed specifically for business owners without staff, except for a spouse. If you have employees, exploring other retirement plans may be necessary.
- Contributions to your S Corporation can only come from W-2 wages earned in a solo 401k s corp. This ensures that your contributions are directly tied to your income. Specifically, contributions must be based on the total in Box 1 of your W-2, including any pre-tax amounts not shown in Box 1.
- Age Requirement: While there are no age restrictions for establishing a 401(k) plan, your age can influence contribution limits, especially for catch-up contributions for those 50 and older, which can increase your total contribution limit to $77,500.
Additionally, 401(k) plans may qualify for the automatic enrollment credit under SECURE 2.0, providing extra benefits for S Corporation owners.
As the Human Interest Team notes, “Not only does the solo 401(k) have a higher contribution limit than an IRA, but it also allows the account owner’s spouse to contribute to the same plan, provided they receive compensation from the employer.”
By verifying your eligibility, you can confidently move forward with setting up your individual 401(k) plan, which can significantly enhance your retirement savings potential. Remember, we’re here for you as you navigate this journey toward a secure financial future for your family.
Follow Steps to Establish Your Solo 401(k) Plan
To establish your Solo 401(k) plan, follow these nurturing steps:
-
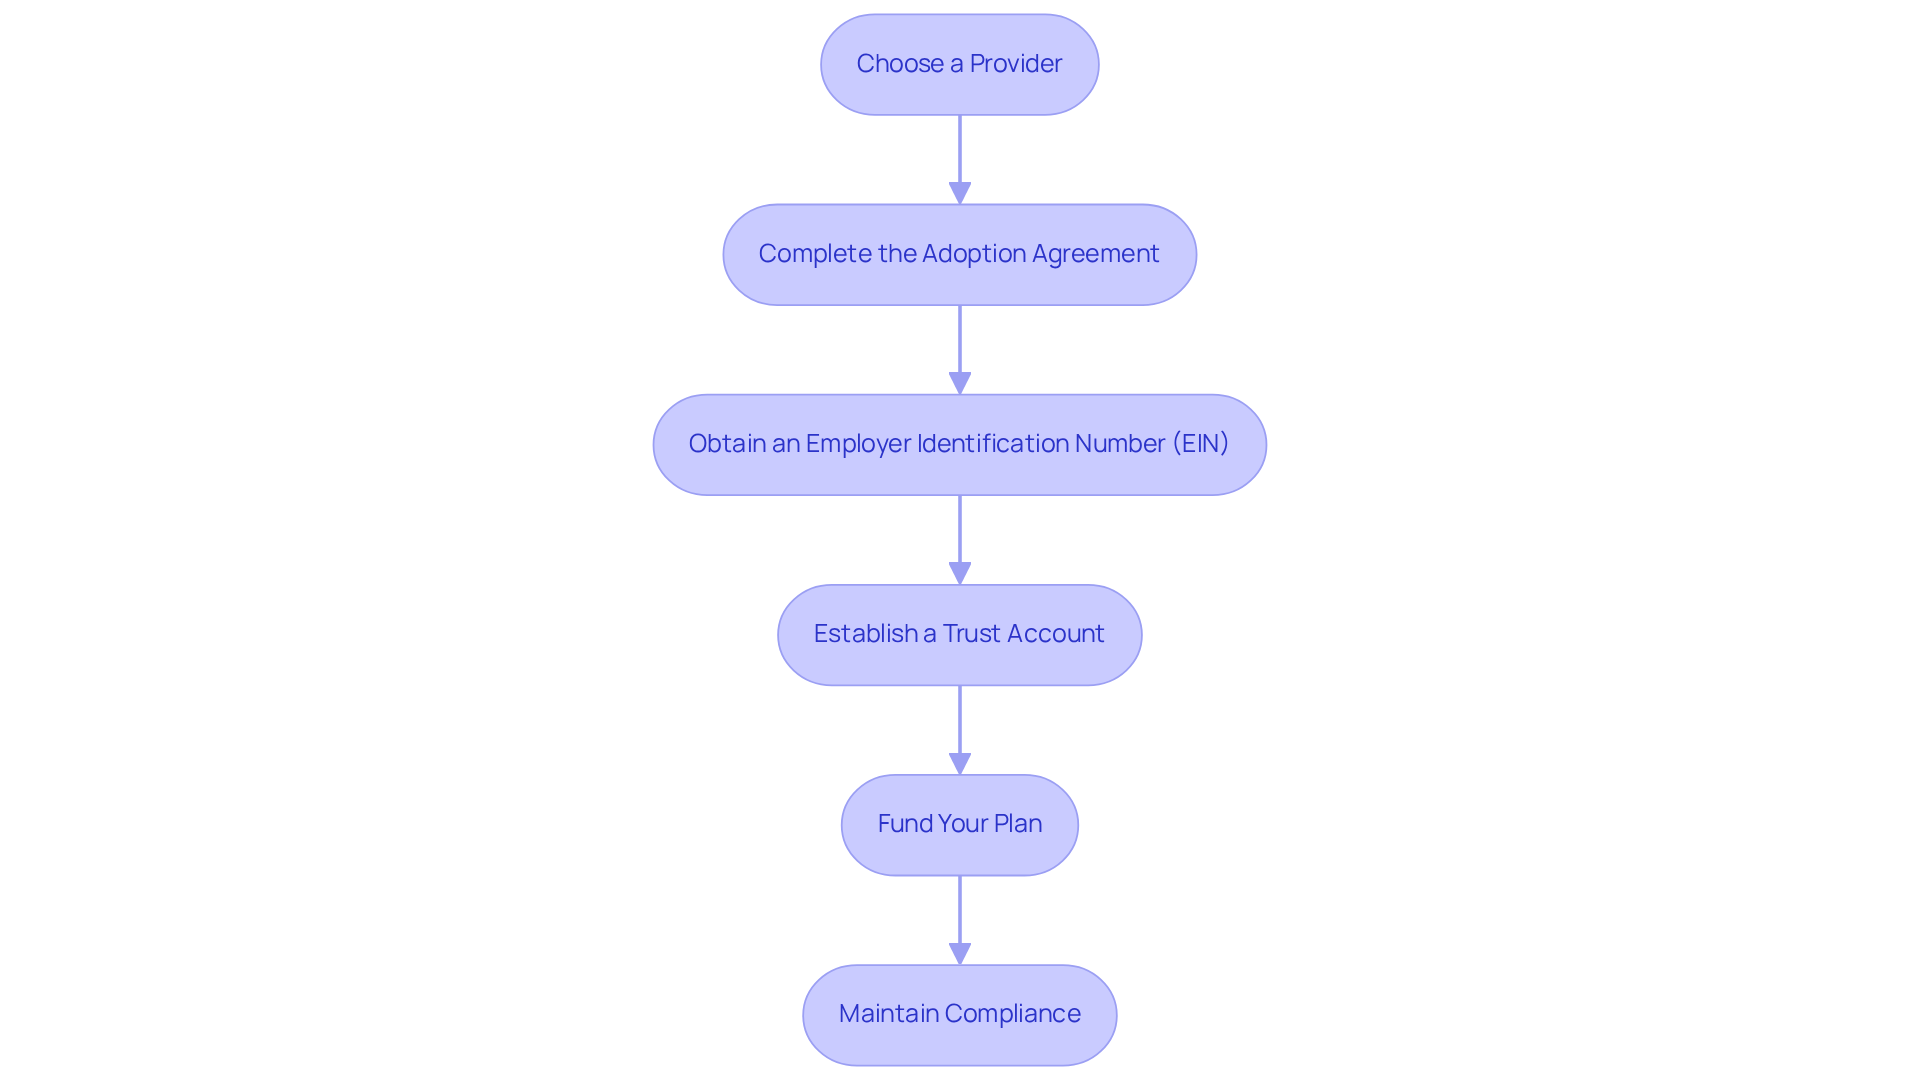
Choose a Provider: Investigate and select a financial institution that offers 401(k) options. Prioritize providers like Bright Advisers, which not only emphasizes minimal fund fees but also offers tailored solutions that cater specifically to the needs of young parents. Their diverse investment options and strong customer support can help you navigate your retirement planning effectively. Imagine having a partner in your financial journey! As David Ramirez, a CFA, recommends, consulting with a financial advisor can offer customized insights into how these strategies align with your personal financial circumstances and long-term objectives.
-
Complete the Adoption Agreement: Fill out the solo 401k s corp adoption agreement, which outlines the conditions of your arrangement. This document is essential for creating the strategy and must be signed by you as the business owner. It’s important to understand that this step lays the foundation for your financial future.
-
Obtain an Employer Identification Number (EIN): If you don’t have one, apply for an EIN from the IRS. This number is essential for tax reporting and management, ensuring that your plan is compliant and ready for success.
-
Establish a Trust Account: Open a trust account in the name of the individual 401(k) arrangement. This account will hold the plan’s assets and must be distinct from your personal or business accounts. Think of it as a safe haven for your family’s future.
-
Fund your plan by making your initial deposits to the solo 401k s corp. Be sure to comprehend the limits on deposits, which for 2025 are up to $70,000, including catch-up payments for those aged 50 and older, who can add an extra $7,500, totaling $31,000. Together, we can maximize your contributions for a brighter future.
-
Maintain Compliance: Keep detailed records of all contributions and transactions. Adhere to IRS regulations regarding reporting and compliance to avoid penalties. It’s crucial to stay organized and informed as you build your retirement savings.
By following these steps, you can successfully establish your solo 401k s corp arrangement and begin maximizing your retirement savings. The tax benefits of an individual 401(k) make it a favorable choice for self-employed individuals. Remember, discussing with a financial advisor can offer customized insights into how these strategies align with your long-term objectives. We’re here for you, ready to support you on this important journey.
Navigate Contribution Limits and Deadlines for Your Solo 401(k)
Navigating funding limits and deadlines is essential for optimizing your solo 401k S Corp plan. It’s important to understand how these factors can significantly impact your family’s future. Here’s what you need to know:
Contribution Limits:
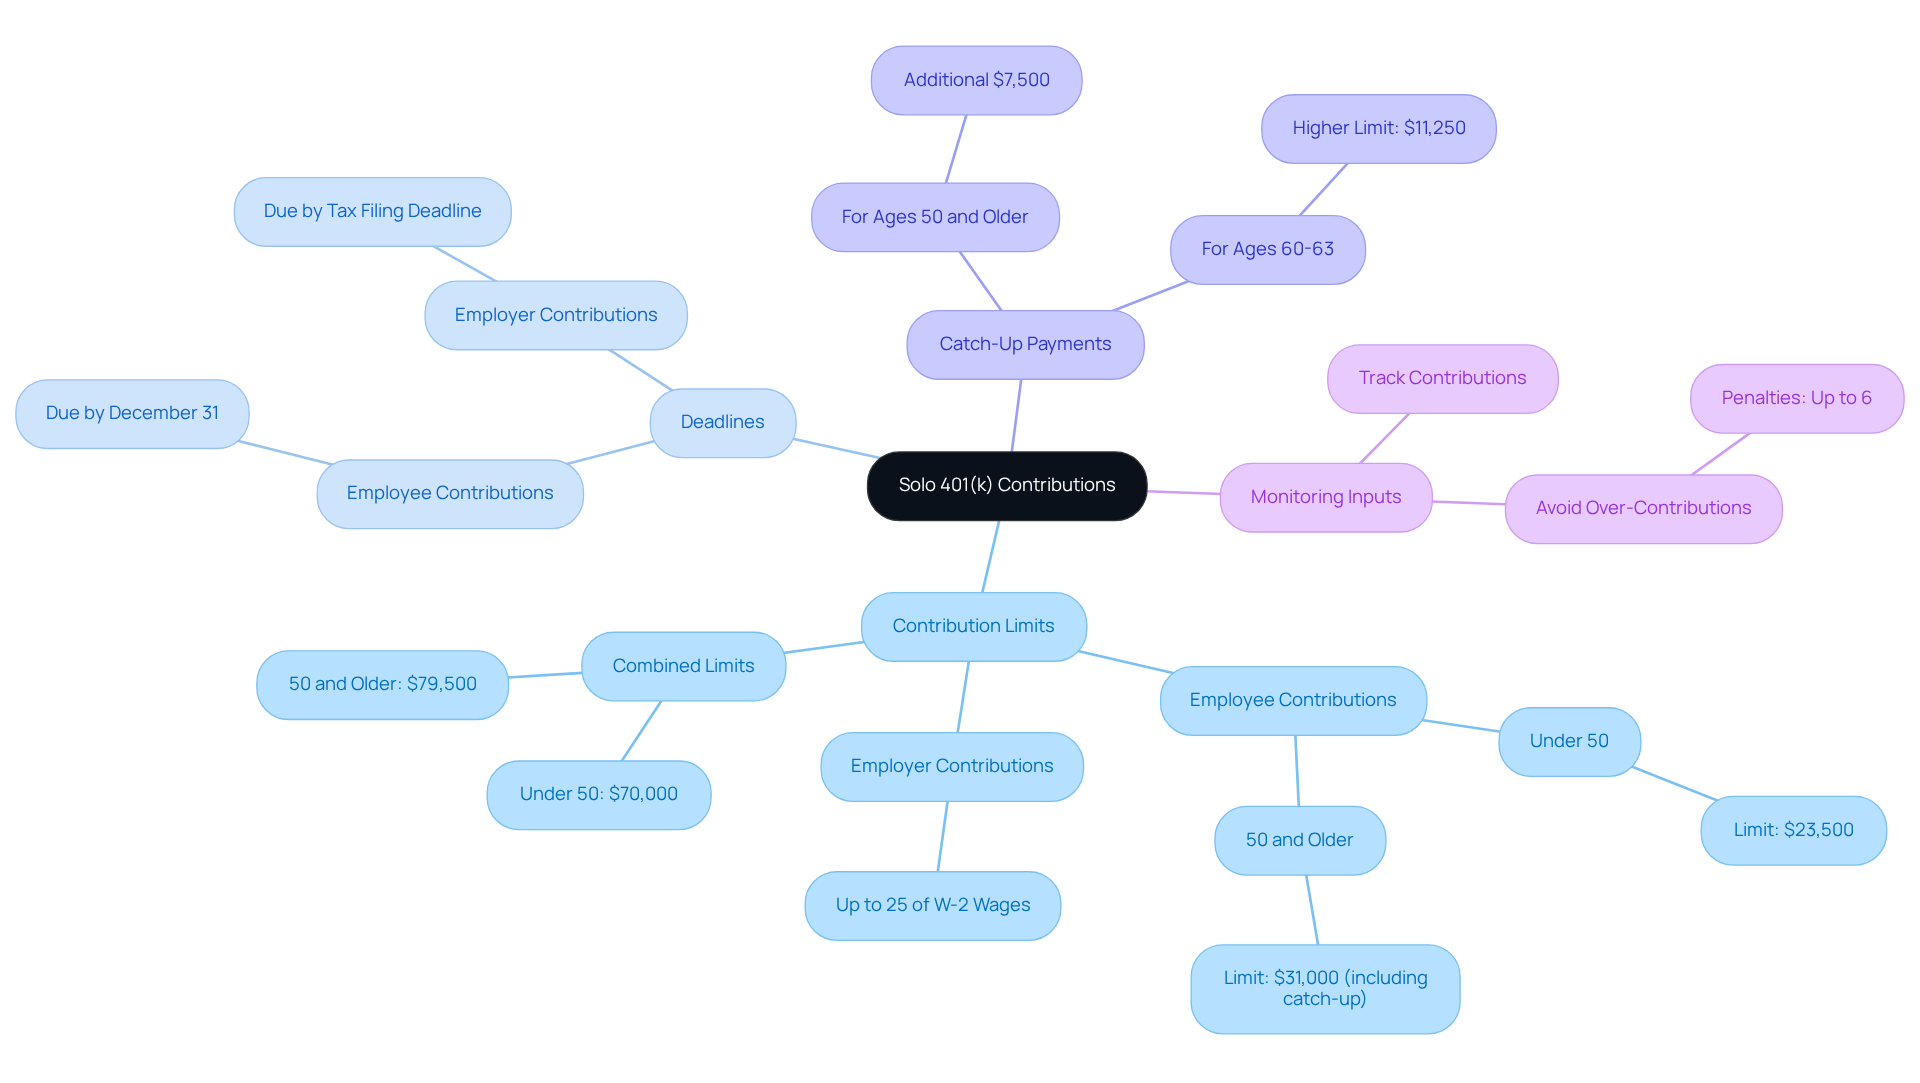
For 2025, you can contribute up to $23,500 as an employee, plus an additional $6,500 if you are age 50 or older. Imagine the peace of mind knowing that the overall combined donation limit for individuals aged 50 and above is $79,500, which includes catch-up donations. As an employer, you can also contribute up to 25% of your W-2 wages. This dual funding framework allows for considerable retirement savings, with individuals under 50 permitted to add up to $70,000.
Deadlines for Submissions:
Employee inputs must be made by December 31 of the tax year. However, employer payments can be made up until the tax filing deadline, including extensions. This flexibility enables you to optimize input based on your business’s financial condition, which is crucial for your family’s financial health.
Catch-Up Payments:
If you are 50 or older, utilizing catch-up payments can enhance your retirement savings. It’s essential to consider these extra inputs when planning your overall savings strategy, ensuring you’re providing for your family’s future.
Monitoring Inputs:
Keep track of your inputs throughout the year to ensure you do not exceed the limits. Over-contributing can result in penalties of up to 6% on the excess amount, making it crucial to stay informed. Remember, we’re here for you, and together, we can navigate this journey.
By understanding these limits and deadlines, you can effectively manage your contributions to a Solo 401k S Corp and enhance your retirement savings strategy, ensuring a secure future for you and your loved ones.
Conclusion
Establishing a Solo 401(k) for your S Corporation can be a wonderful step towards enhancing your retirement savings and enjoying valuable tax benefits. This unique retirement plan is designed specifically for self-employed individuals, allowing you to contribute as both an employee and an employer. This dual role maximizes your contribution potential, ensuring you can save more for your future. Understanding the nuances of this plan is essential for S Corporation owners who wish to secure a brighter financial future for themselves and their families.
Throughout this discussion, we’ve shared important insights that can guide you on this journey. We explored the eligibility criteria for setting up a Solo 401(k), the necessary steps to establish the plan, and the significance of adhering to contribution limits and deadlines. The dual funding structure is particularly beneficial, especially for those aged 50 and over, who can take advantage of catch-up contributions. Imagine the peace of mind that comes from knowing you have the flexibility in contribution deadlines, making it easier for you to optimize your retirement savings.
In conclusion, the Solo 401(k) stands out as an invaluable tool for S Corporation owners, paving the way for enhanced retirement savings and financial security. By understanding the benefits, eligibility requirements, and the steps to set up this plan, you can make informed decisions that align with your family’s long-term financial goals. Remember, taking action now to establish a Solo 401(k) could lead to a more secure and prosperous future, helping to turn your retirement dreams into reality. Together, we can navigate this journey towards financial well-being, ensuring that your family’s aspirations are within reach.
Frequently Asked Questions
What is a Solo 401(k)?
A Solo 401(k) is a retirement savings option designed for self-employed individuals or business owners who have no employees other than a spouse.
What are the benefits of a Solo 401(k) for S Corporations?
A Solo 401(k) allows S Corporation owners to contribute both as employees and employers, significantly enhancing their retirement savings potential and providing tax advantages.
What are the contribution limits for a Solo 401(k) in 2025?
In 2025, individuals can contribute up to $23,500 as employees, plus an additional catch-up contribution of $7,500 for those aged 50 and over. For those aged 60 to 63, a super catch-up contribution of $11,250 is available, allowing a total contribution of up to $79,500 for those over 50.
How can S Corporation owners contribute to their Solo 401(k)?
S Corporation owners can contribute up to 25% of their W-2 wages as employers, further enhancing their retirement savings.
What are the tax advantages of a Solo 401(k)?
Contributions to a Solo 401(k) are tax-deductible, reducing taxable income, and the earnings grow tax-deferred until withdrawal, allowing for greater accumulation over time.
Are there loan options available with a Solo 401(k)?
Yes, many Solo 401(k) plans offer loan options, providing liquidity during financial needs.
What investment choices are available in a Solo 401(k)?
Participants can choose from a variety of investments, including stocks, bonds, and real estate, allowing them to tailor their portfolios to meet their financial goals.
List of Sources
- Understand the Solo 401(k) and Its Benefits for S Corporations
- Contribution Limits for 401(k)s Will Have a ‘Super’ Twist Next Year (https://money.com/401k-contribution-limits-2025-irs)
- How Much Can I Contribute to a Solo 401(k) in 2025? – Bright Advisers (https://brightadvisers.com/how-much-can-i-contribute-to-a-solo-401-k-in-2025)
- What is a 401(k)? (https://empower.com/the-currency/work/what-is-a-401k)
- Master S Corp Solo 401k Contribution Limits for Financial Success – Bright Advisers (https://brightadvisers.com/master-s-corp-solo-401-k-contribution-limits-for-financial-success)
- How Much Could 401(k) Contribution Limits Rise in 2025? (https://napa-net.org/news/2024/6/how-much-could-401k-contribution-limits-rise-2025)
- Determine Eligibility for a Solo 401(k) as an S Corp Owner
- Solo 401(k) Plans – How to Maximize their Benefits (https://employeefiduciary.com/blog/solo-401k-plans-their-benefits-to-eligible-business-owners)
- Solo 401(k) contribution limits 2025 | Fidelity (https://fidelity.com/learning-center/smart-money/solo-401k-contribution-limits)
- The Ultimate Guide to Solo 401(k)s | Guideline (https://guideline.com/education/articles/the-ultimate-guide-to-solo-401ks)
- Solo 401(k) Calculator for S-Corporations: Ultimate Guide (https://emparion.com/solo-401k-calculator-s-corporation)
- Solo 401(k) Eligibility: Do You Qualify? | Human Interest (https://humaninterest.com/learn/articles/do-you-qualify-for-a-self-employed-401k)
- Follow Steps to Establish Your Solo 401(k) Plan
- The Ultimate Guide to Solo 401(k)s | Guideline (https://guideline.com/education/articles/the-ultimate-guide-to-solo-401ks)
- What Is a Solo 401(k)? Self-Employed Retirement Plans – NerdWallet (https://nerdwallet.com/article/investing/what-is-a-solo-401k)
- 12 Financial Planning Quotes for Building Wealth Wisely — Phillip James Financial (https://phillipjamesfinancial.com/blog/12-financial-planning-quotes-for-building-wealth-wisely)
- 7 Key Self Employed 401k Contribution Limits for 2025 – Bright Advisers (https://brightadvisers.com/7-key-self-employed-401-k-contribution-limits-for-2025)
- A Step-by-Step Guide to Setting Up a Solo 401(k) for Self-Employed Professionals (https://linkedin.com/pulse/step-by-step-guide-setting-up-solo-401k-self-employed-reynolds-cfp–ctacc)
- Navigate Contribution Limits and Deadlines for Your Solo 401(k)
- How Much Can I Contribute to a Solo 401(k) in 2025? – Bright Advisers (https://brightadvisers.com/how-much-can-i-contribute-to-a-solo-401-k-in-2025)
- The 401(k) Contribution Limits for 2025 Are Bigger Than Ever (https://nasdaq.com/articles/401k-contribution-limits-2025-are-bigger-ever)
- IRS Raises 401(k) Contribution Limits for 2025 | Paychex (https://paychex.com/articles/employee-benefits/annual-401k-contribution-limits)
- 401(k) Contribution Limits 2025: Maximize Savings | Human Interest (https://humaninterest.com/learn/articles/401k-contribution-limits)
- 401(k) limit increases to $23,500 for 2025, IRA limit remains $7,000 | Internal Revenue Service (https://irs.gov/newsroom/401k-limit-increases-to-23500-for-2025-ira-limit-remains-7000)

Kevin has advised high-income W-2 tech and biotech families since 2015, and leads the education-first Age Five Family Office from Brea, California.
Connect on LinkedIn → · About Kevin